A divorce doesn’t automatically mean a business must be sold or divided. What happens to a business when a couple divorces depends on factors such as when it was established, each spouse’s contribution and the family’s financial needs. The business’s value may be considered in the settlement, while ownership and control may remain with the spouse who runs it.
It’s understandable to worry that a financial claim could disrupt the business you’ve built. Including a business in the settlement doesn’t necessarily mean your spouse will receive shares or take over the company. Depending on the circumstances, its value may instead be balanced against other assets.
This article explains when a business is taken into account, how its value and ownership may be treated, and what can help protect control. It also covers practical ways to address business interests in financial arrangements, so you can understand the issues before deciding what to do next.
Key Takeaways
- A pre-nuptial or post-nuptial agreement can set out how business assets should be treated, but it isn’t always binding.
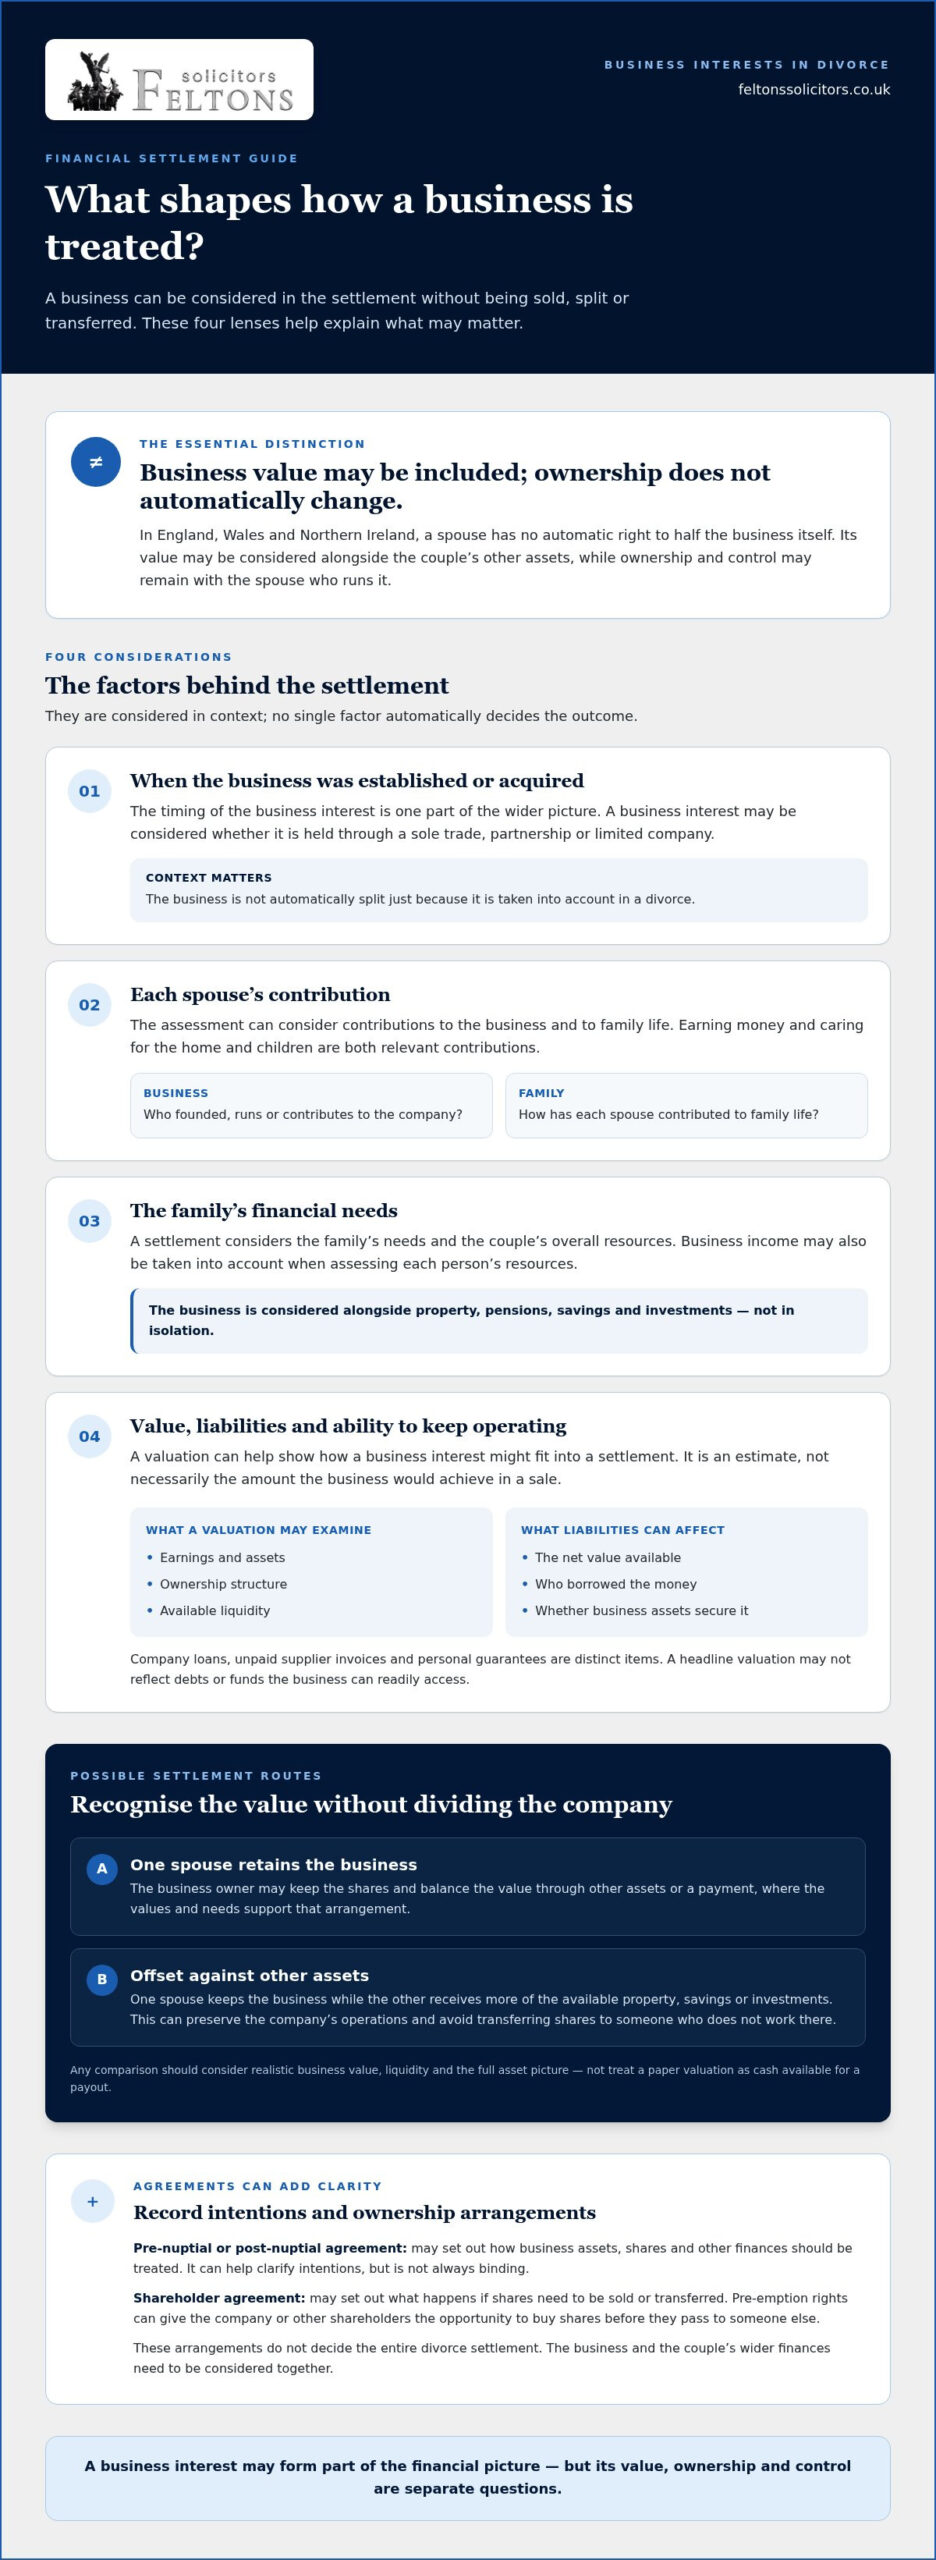
- A spouse isn’t automatically entitled to half of the business; the settlement can reflect its value alongside other assets.
- When a business is assessed, factors can include when it was established, each spouse’s contributions, the family’s needs and the business’s ability to keep operating.
- Valuation helps clarify the options, which can include one spouse retaining the business and balancing its value through other assets or a payment.
- Clear financial records and suitable business agreements can help protect ownership and control if a relationship breaks down.
Can I ringfence my business in a prenuptial agreement?
A nuptial agreement can record how a couple intends to treat business interests if they separate. It may help protect ownership, but it doesn’t guarantee that a court will follow every term.
Nuptial agreements and business protection
A pre-nuptial agreement is made before marriage; a post-nuptial agreement is made during the marriage. Either can set out how business assets, shares and other finances should be divided if the relationship ends.
For example, an agreement could record that one spouse founded and runs a company, then explain how its value should be considered alongside other assets. A nuptial agreement made before separation can help clarify intentions, but it isn’t always binding. Legal advice can help both spouses understand the terms and disclose their finances.
After separation, spouses may need to work through how to divide their finances, including property, pensions, savings and investments. A written agreement can address the business as part of that wider settlement, rather than treating it in isolation.
Shareholder agreements and pre-emption rights
A shareholder agreement sets out arrangements between a company’s shareholders, including what happens if someone needs to sell or transfer shares. It may give the company or other shareholders pre-emption rights, allowing them the opportunity to buy shares before they pass to someone else.
For example, a family company’s agreement could specify how shares are offered if an owner needs to transfer them following a divorce. These terms can help manage ownership disputes and reduce uncertainty for other shareholders. They don’t decide the entire divorce settlement, so the agreement and the couple’s wider finances need to be considered together.
Business valuation and solicitor costs
A business valuation estimates the value of an interest for financial discussions and helps show how it might fit into a settlement. How much does a business valuation or divorce solicitor cost in the UK? The price depends on the case and is given after a quote request; factors include the work required, the quality of financial records and the complexity of the valuation.
A valuation may examine earnings, assets, ownership structure and available liquidity. It is an estimate, not necessarily the amount the business would achieve in a sale. Specialist accounting work may be needed, particularly when company finances, other shareholders or several ownership interests require analysis.
Business debts and liabilities
Business debts and liabilities affect the net value available for a financial settlement. Start by identifying each obligation, its balance, who borrowed the money and whether business assets secure it.
For example, a company loan, an unpaid supplier invoice and an owner’s personal guarantee are distinct items to record. Current accounts, loan documents and guarantee terms help show how each liability relates to the business or an individual. A clear picture matters because a headline valuation may not reflect the business’s debts or the funds it can readily access.
Is my spouse entitled to half of my business?
No. In England, Wales and Northern Ireland, a spouse has no automatic right to half the business itself. Business interests and their value may be considered alongside the couple’s other assets when working out a financial settlement.
Business interests as matrimonial assets
A business interest may form part of the assets considered in a divorce, whether held through a sole trade, partnership or limited company. That doesn’t mean the company must be split: the court considers the circumstances, including when it was acquired, each spouse’s contributions and the family’s needs.
In White v White in 2000, the House of Lords rejected discrimination between earning money and caring for the home and children. Miller v Miller and McFarlane v McFarlane in 2006 addressed needs, compensation in some cases and sharing wealth built during marriage. Those principles help explain why a business owner’s work is considered alongside their spouse’s contribution to family life.
Freezing orders and business assets
A freezing order can prevent a spouse from dealing with assets when there’s a risk of disposal or devaluation that could undermine a fair financial settlement. For example, transferring company funds or selling valuable equipment could affect the assets available for division.
A freezing order is a protective measure, not a way to decide who owns the business. In England and Wales, the court must be satisfied that the risk could prejudice the applicant’s ability to obtain a fair share. If assets are being moved or depleted, prompt legal action matters because prevention can be more effective than seeking a remedy afterwards.
Offsetting business interests against other assets
Offsetting means one spouse retains the business while the other receives more of the available property, savings or investments. For example, a business owner might keep their shares while the other spouse receives a larger share of a jointly owned property, if the values and needs support that arrangement.
This approach can preserve the company’s operations and avoid transferring shares to someone who doesn’t work there. The comparison should account for realistic business value, liquidity and the full asset picture, rather than treating a paper valuation as cash available for a payout. A settlement may also take business income into account when assessing each person’s resources.
Tax considerations when dividing business assets
Selling or transferring business assets during a divorce can have tax consequences. Capital gains tax may arise when assets are sold or transferred, while stamp duty may be payable on a property transfer. These potential liabilities can change the net value each spouse receives.
For example, comparing a share transfer with a sale requires attention to the asset involved, its ownership and the proposed settlement structure. A valuation can help identify the options and their tax implications before terms are finalised. A settlement should compare what each person receives after relevant liabilities, not just the stated value of the business or property.
A business is only one part of the financial picture: pensions, property, savings and investments also matter. Financial arrangements in a divorce place business interests alongside those wider assets when considering a settlement.
Will my business be taken into account in a divorce?
Yes. A business may be included when the couple’s finances are considered, but it isn’t automatically sold or divided. The settlement looks at the business alongside other assets, income and family needs.
Accounting for a business in a settlement
A financial settlement considers the business interest as part of the couple’s wider finances. How it is treated depends on its value, income, ownership structure and the needs of each spouse and any children.
For example, a director who runs a company may keep operating it, while the settlement accounts for its value through other assets or income. The family court can consider the business’s earning capacity, underlying assets and available liquidity. These factors help distinguish a valuable but cash-poor company from one that can readily provide funds.
In England and Wales, the needs of minor children receive first priority in a financial settlement. The court also considers housing and income needs, including future earning capacity and retirement. The business is assessed in context, rather than in isolation from the family’s circumstances.
Couples can use mediation to discuss options outside court, including how to divide property, pensions, savings and business interests. A mediator can help structure those discussions, but an agreed division of money and property needs a consent order to become legally binding. HM Courts & Tribunals Service explains that the order formalises the agreement.
Separating business and household finances
Keeping company accounts separate from household and jointly held finances creates a clearer record of what belongs to the business. Separate bank accounts and properly recorded drawings, for example, can help distinguish company expenditure from personal spending.
Good records also help explain income, liabilities and transactions during financial disclosure. Both spouses must provide full financial information, including details of any business sale and its proceeds. If a company account has paid household costs, recording those transactions helps show how they should be treated in the settlement.
Current governance documents matter too. Keeping shareholder records, company accounts and ownership documents organised makes the business structure clearer during discussions. Clear separation doesn’t determine the settlement, but it helps each person understand the business assets and income being considered.
Financial claims after separation or divorce
Separation does not by itself resolve financial claims between spouses. In England and Wales, there is no time limit for a husband or wife to make a financial claim following separation or divorce, so an informal arrangement may leave finances unresolved.
A consent order records agreed terms and can bring greater finality to the division of assets. Without an order, a couple may have agreed who keeps the business but not legally concluded their financial claims. Mediation can help address outstanding matters, such as business income, pensions or property, before an application for a financial order.
If spouses cannot agree, they can ask the court to make a financial order. The court considers the available assets, each person’s needs and the business’s ability to continue functioning. For a family with children, housing and income needs are particularly important.
Keeping business ownership with the operating spouse
A spouse who established and runs a business will usually be considered to retain it where possible. A court is unlikely to order a sale if that would harm the company or its shareholders, though a Scottish court may order a sale to fund an equalising payment when other assets cannot offset its value.
Lump-sum settlements instead of ownership
A lump-sum settlement can compensate one spouse for the business’s value without giving them ownership or control. This can allow the operating spouse to keep running the company while the other receives a payment or a greater share of other assets.
For example, if a business owner has sufficient personal funds or other assets, a payment may settle the other spouse’s financial interest. The figures must reflect the business’s value and the wider settlement, including each person’s needs. If the business has limited liquidity, extracting capital could affect its ability to trade, so the payment structure matters.
A spouse may also receive a share of business income rather than part of its ownership. That can provide financial support while leaving daily decisions with the person who operates the company. The settlement needs to distinguish income from capital value, since they affect the business and each spouse differently.
Ownership structures and minority shareholdings
The legal structure affects what can be transferred. A sole trader owns the business personally, while a partnership or limited company has different ownership arrangements. In a limited company, the divorcing spouse’s shares are relevant, but transferring them can affect other shareholders and directors.
A minority shareholding in a company owned by a wider group is assessed by considering the value of that particular interest, not the whole company. A spouse holding a minority stake, for instance, doesn’t own the other shareholders’ shares. Any proposed transfer must also account for the company’s governing documents and the practical effect on its operation.
Keeping the business with one spouse doesn’t require the other to receive shares. A court can consider the business’s value alongside other assets, or the spouses may agree on a financial arrangement that avoids shared ownership.
Former spouses can sometimes continue to co-own a business, but that means their decisions and financial interests remain connected after divorce. If they jointly own a company, they need to address how each person participates, makes decisions and receives income. Separating roles may be harder if both previously worked in the business than if only one spouse operated it.
In England and Wales, a court may consider each spouse’s contribution and needs, as well as the business’s ability to continue functioning. A transfer to one spouse, a buy-out or continued joint ownership can each produce a different outcome. The choice depends on the business structure, available assets and whether the arrangement supports a workable financial settlement.
Keeping control of the business after divorce
Ownership and control are related, but they are not identical. One spouse may retain a business while the settlement recognises its value through other assets or payments. For a family business, the practical question is also who makes decisions, manages staff and maintains trading relationships after the marriage ends.
Before agreeing to transfer shares, consider the effect on other directors, shareholders and employees. A spouse receiving shares, for example, may become a shareholder without experience running the company. A transfer could also affect voting arrangements or the working relationship between existing owners. Reviewing the company’s governance documents helps identify restrictions and existing rights that may shape a workable outcome.
A shareholder agreement can set out what happens if an owner must sell or transfer shares. It may give the company or another shareholder pre-emption rights, so they have the opportunity to buy shares before they pass to someone else. In a divorce, those provisions can help manage a proposed transfer and reduce disruption for the remaining owners. They don’t determine the whole financial settlement, so the share arrangements and family finances need to be considered together.
A trust may help keep a family business within the family after divorce. Its purpose and structure need careful consideration alongside the settlement, the people involved and the business’s future needs. Insurance can also protect a business if an owner dies or becomes disabled, events that may affect its value and ownership. These measures address different risks, so neither should replace clear ownership records or suitable governance arrangements.
For businesses in Scotland, courts are unlikely to force a spouse to sell or take action that harms the business, its value or its workforce. This highlights why continuity matters when considering control after separation. In other parts of the UK, the settlement also needs to account for the company’s operation and shareholders’ interests, rather than treating shares as cash that can simply be divided.
The parties can consider who will hold shares, who will make operational decisions and how future disagreements will be managed. A family company, for example, could document decision-making responsibilities and the process for a future share sale. Clear terms can help separate the spouses’ personal financial arrangements from the company’s day-to-day management.
Discuss business control in divorce to consider how ownership, financial arrangements and the company’s ongoing operation fit together.
Feltons Solicitors LLP: Divorce and Financial Arrangements
Feltons Solicitors LLP provides Divorce and Financial Arrangements for people working through separation and business-related financial decisions. The service can help when you need to understand how business interests, property, pensions and other assets may fit into a settlement, or how to formalise agreed arrangements.
Advice can help you consider practical outcomes, such as retaining control of a company, addressing a shareholding or balancing business value against other assets. If separation also means reviewing your will or longer-term estate plans, Wills, Probate, and Estate Planning may be relevant.
For guidance on your circumstances, contact Feltons Solicitors LLP or visit feltonssolicitors.co.uk.
Prepare for a clear next step
Understanding what happens to a business when a couple divorces is useful when it helps you plan for your financial position and your company’s future. Before discussions begin, gather current accounts, ownership records, shareholder or partnership agreements, loan documents and any nuptial agreement. Note who runs key operations, which decisions require approval, and how a transfer could affect employees or co-owners. These details can focus discussions on practical options.
Feltons Solicitors LLP offers Divorce and Financial Arrangements for financial issues arising from separation. If the settlement also affects your estate plans or property, the firm offers Wills, Probate, and Estate Planning and Residential and Commercial Conveyancing. Considering these connected arrangements together can help you plan beyond the immediate ownership question.
Arrange a discussion with Feltons Solicitors LLP about your financial arrangements and business decisions. With clear records and considered advice, you can move towards a workable plan for the next chapter.
Frequently Asked Questions
What happens to the family business upon divorce?
What happens to a business when a couple divorces depends on its ownership, finances and the family’s circumstances. The business interest and its value may be considered within the wider financial arrangements, but that doesn’t automatically mean a sale. One spouse, for example, may continue running the company while the settlement addresses the other spouse’s financial position through other resources.
How is the business divided?
A business isn’t necessarily divided by transferring half its shares. The settlement may account for its value through other assets, a payment or arrangements involving business income. One spouse might, for example, retain the company while the other receives a greater share of property or savings. The practical options depend on the business structure, available liquidity and the parties’ financial needs.
Is a limited company protected from divorce?
No. A limited company’s separate legal identity doesn’t automatically exclude a spouse’s shareholding or the company’s value from divorce financial arrangements. The court may consider the owner’s shares, income, assets and ability to generate income. The company itself isn’t automatically divided or sold. Its articles and any shareholder agreement may affect share transfers, but they don’t determine the entire financial settlement.
Who conducts the business valuation for a divorce?
An independent accountant is commonly appointed to value a business, often jointly by both spouses. A specialist may review financial statements, earnings, assets, market conditions and the company’s ownership structure. The valuation may also consider liquidity and whether capital can be extracted or borrowed against business assets. It provides an estimate for settlement discussions, not necessarily the price achievable in an actual sale.
Can a business be considered a marital asset even if only one spouse owns it?
Yes. Sole legal ownership doesn’t automatically prevent a business interest from being considered in divorce proceedings. Relevant factors include when it was acquired, whether it grew during the marriage, each spouse’s contributions and the family’s needs. A spouse’s contribution to family life, for instance, may matter to the wider financial picture even without a formal role or shareholding in the company.
Can my wife take half my business in divorce?
There’s no automatic rule that a wife receives half the business or its shares. The financial settlement considers the business alongside other assets, income and needs. The spouse operating the company may retain it while the other spouse’s financial position is addressed separately. The outcome depends on the circumstances, including the marriage, each person’s contributions, children’s needs and available resources.
Divorce with a business involved, how does it work in the UK?
Understanding what happens to a business when a couple divorces in the UK starts with financial disclosure, including business interests, income, assets and liabilities. In England and Wales, spouses can negotiate or use mediation, then seek a consent order to make agreed terms legally binding. Scotland has different rules, and Northern Ireland has its own court process, so the relevant jurisdiction matters.
How is a business valued during divorce in the UK?
A valuation considers the business’s financial position and how it operates, rather than relying on turnover alone. An accountant may assess earnings, profits, underlying assets, income-generating capacity, liquidity and ownership interests. A profitable company with limited available cash, for example, may not readily fund an immediate payment. The estimate helps compare settlement options, but doesn’t necessarily represent the price the business would fetch if sold.