What Happens to a Business in Divorce and Who Keeps It

What Happens to a Business in Divorce and Who Keeps It

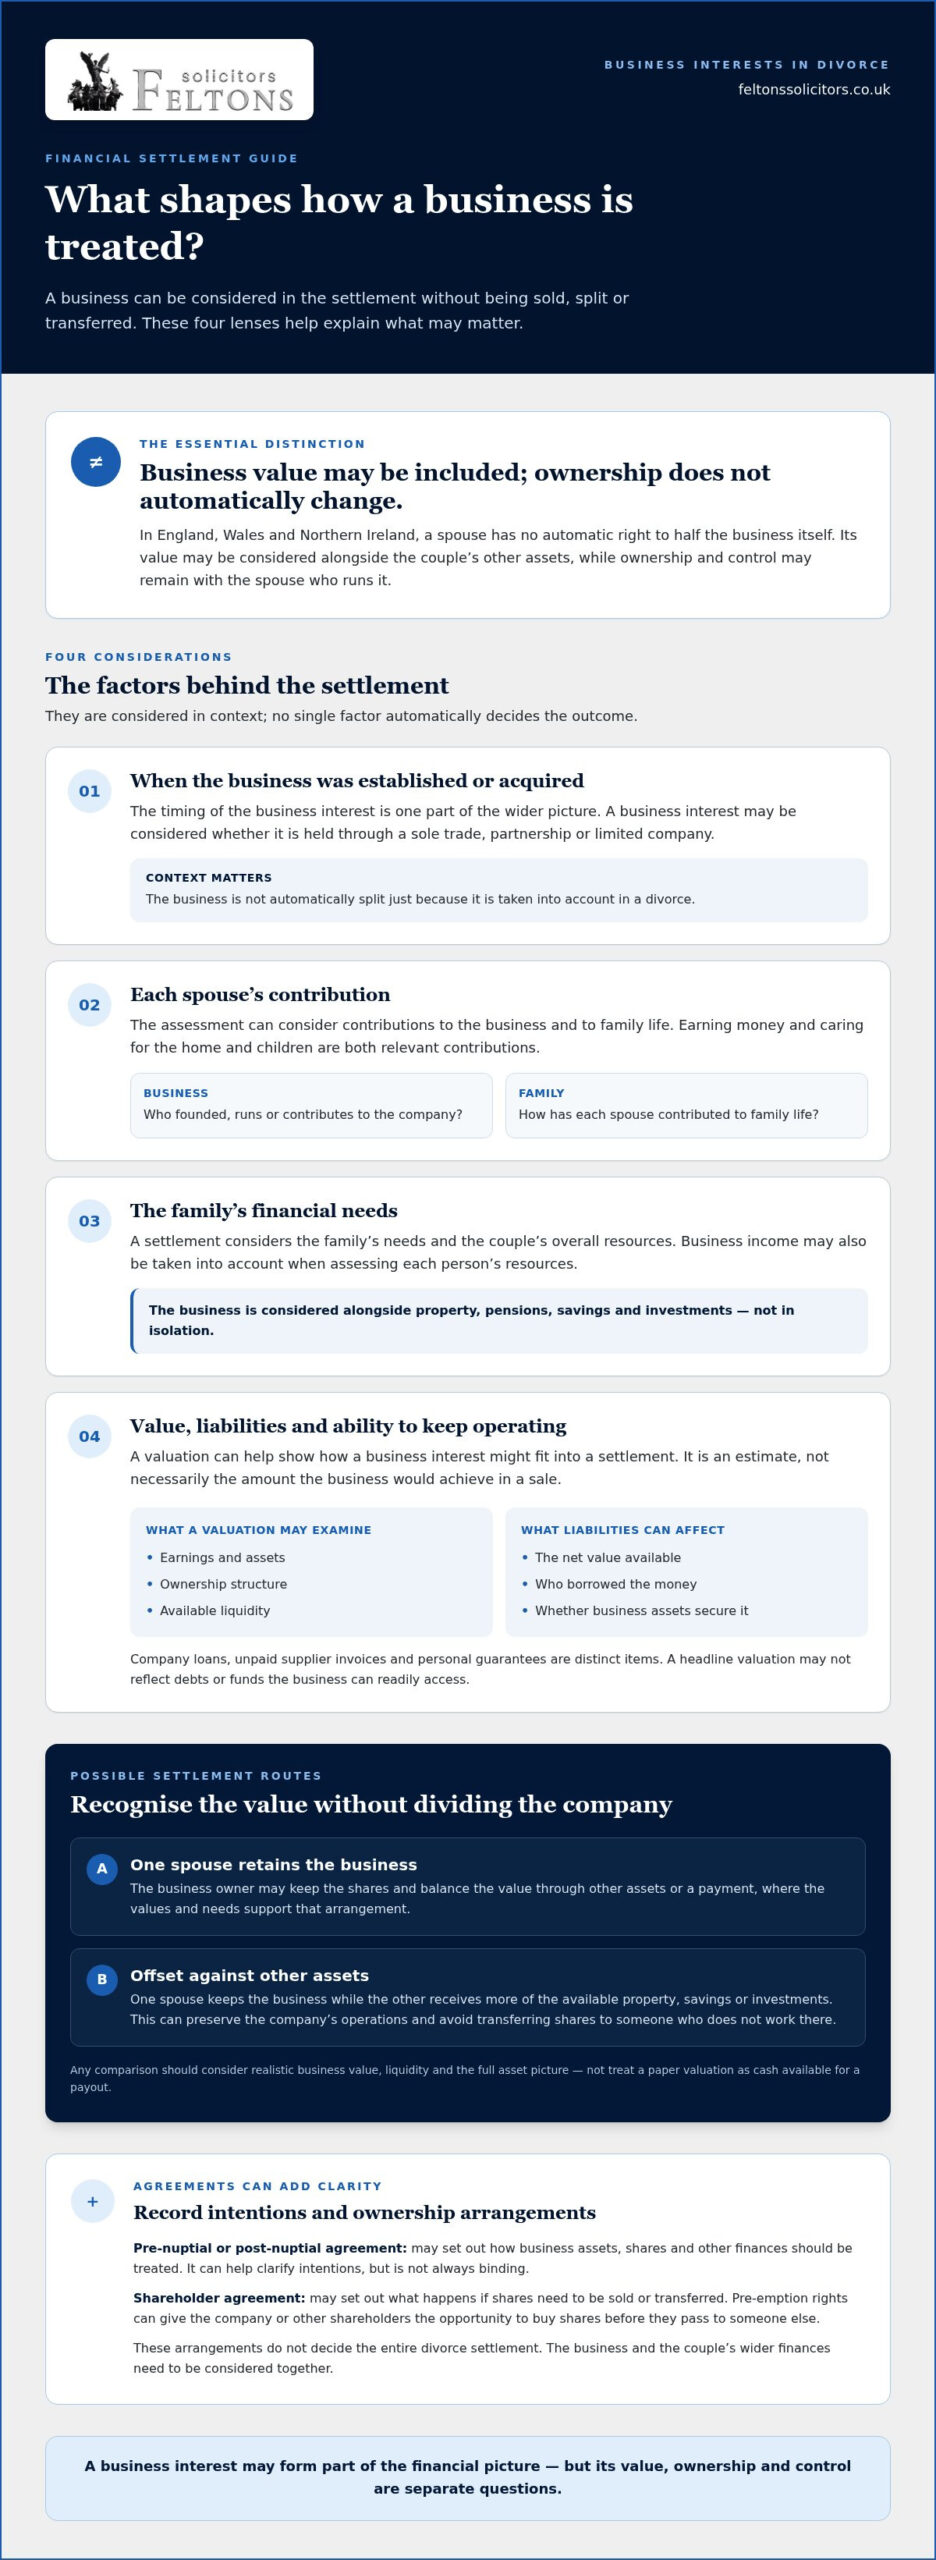
A divorce doesn’t automatically mean a business must be sold or divided. What happens to a business when a couple divorces depends on factors such as when it was established, each spouse’s contribution and the family’s financial needs. The business’s value may be considered in the settlement, while ownership and control may remain with the spouse who runs it.

It’s understandable to worry that a financial claim could disrupt the business you’ve built. Including a business in the settlement doesn’t necessarily mean your spouse will receive shares or take over the company. Depending on the circumstances, its value may instead be balanced against other assets.

This article explains when a business is taken into account, how its value and ownership may be treated, and what can help protect control. It also covers practical ways to address business interests in financial arrangements, so you can understand the issues before deciding what to do next.

Key Takeaways

  • A pre-nuptial or post-nuptial agreement can set out how business assets should be treated, but it isn’t always binding.
  • A spouse isn’t automatically entitled to half of the business; the settlement can reflect its value alongside other assets.
  • When a business is assessed, factors can include when it was established, each spouse’s contributions, the family’s needs and the business’s ability to keep operating.
  • Valuation helps clarify the options, which can include one spouse retaining the business and balancing its value through other assets or a payment.
  • Clear financial records and suitable business agreements can help protect ownership and control if a relationship breaks down.

Can I ringfence my business in a prenuptial agreement?

A nuptial agreement can record how a couple intends to treat business interests if they separate. It may help protect ownership, but it doesn’t guarantee that a court will follow every term.

Nuptial agreements and business protection

A pre-nuptial agreement is made before marriage; a post-nuptial agreement is made during the marriage. Either can set out how business assets, shares and other finances should be divided if the relationship ends.

For example, an agreement could record that one spouse founded and runs a company, then explain how its value should be considered alongside other assets. A nuptial agreement made before separation can help clarify intentions, but it isn’t always binding. Legal advice can help both spouses understand the terms and disclose their finances.

After separation, spouses may need to work through how to divide their finances, including property, pensions, savings and investments. Seeking guidance from independent wealth specialists like Her Financial Planning can help individuals evaluate the broader financial and retirement picture, ensuring a written agreement addresses the business as part of that wider settlement, rather than treating it in isolation.

Shareholder agreements and pre-emption rights

A shareholder agreement sets out arrangements between a company’s shareholders, including what happens if someone needs to sell or transfer shares. It may give the company or other shareholders pre-emption rights, allowing them the opportunity to buy shares before they pass to someone else.

For example, a family company’s agreement could specify how shares are offered if an owner needs to transfer them following a divorce. These terms can help manage ownership disputes and reduce uncertainty for other shareholders. They don’t decide the entire divorce settlement, so the agreement and the couple’s wider finances need to be considered together.

Business valuation and solicitor costs

A business valuation estimates the value of an interest for financial discussions and helps show how it might fit into a settlement. How much does a business valuation or divorce solicitor cost in the UK? The price depends on the case and is given after a quote request; factors include the work required, the quality of financial records and the complexity of the valuation.

A valuation may examine earnings, assets, ownership structure and available liquidity. It is an estimate, not necessarily the amount the business would achieve in a sale. Specialist accounting work may be needed, particularly when company finances, other shareholders or several ownership interests require analysis.

Business debts and liabilities

Business debts and liabilities affect the net value available for a financial settlement. Start by identifying each obligation, its balance, who borrowed the money and whether business assets secure it.

For example, a company loan, an unpaid supplier invoice and an owner’s personal guarantee are distinct items to record. Current accounts, loan documents and guarantee terms help show how each liability relates to the business or an individual. A clear picture matters because a headline valuation may not reflect the business’s debts or the funds it can readily access.

Is my spouse entitled to half of my business?

No. In England, Wales and Northern Ireland, a spouse has no automatic right to half the business itself. Business interests and their value may be considered alongside the couple’s other assets when working out a financial settlement.

Business interests as matrimonial assets

A business interest may form part of the assets considered in a divorce, whether held through a sole trade, partnership or limited company. That doesn’t mean the company must be split: the court considers the circumstances, including when it was acquired, each spouse’s contributions and the family’s needs.

In White v White in 2000, the House of Lords rejected discrimination between earning money and caring for the home and children. Miller v Miller and McFarlane v McFarlane in 2006 addressed needs, compensation in some cases and sharing wealth built during marriage. Those principles help explain why a business owner’s work is considered alongside their spouse’s contribution to family life.

Freezing orders and business assets

A freezing order can prevent a spouse from dealing with assets when there’s a risk of disposal or devaluation that could undermine a fair financial settlement. For example, transferring company funds or selling valuable equipment could affect the assets available for division.

A freezing order is a protective measure, not a way to decide who owns the business. In England and Wales, the court must be satisfied that the risk could prejudice the applicant’s ability to obtain a fair share. If assets are being moved or depleted, prompt legal action matters because prevention can be more effective than seeking a remedy afterwards.

Offsetting business interests against other assets

Offsetting means one spouse retains the business while the other receives more of the available property, savings or investments. For example, a business owner might keep their shares while the other spouse receives a larger share of a jointly owned property, if the values and needs support that arrangement.

This approach can preserve the company’s operations and avoid transferring shares to someone who doesn’t work there. The comparison should account for realistic business value, liquidity and the full asset picture, rather than treating a paper valuation as cash available for a payout. A settlement may also take business income into account when assessing each person’s resources.

Tax considerations when dividing business assets

Selling or transferring business assets during a divorce can have tax consequences. Capital gains tax may arise when assets are sold or transferred, while stamp duty may be payable on a property transfer. These potential liabilities can change the net value each spouse receives.

For example, comparing a share transfer with a sale requires attention to the asset involved, its ownership and the proposed settlement structure. A valuation can help identify the options and their tax implications before terms are finalised. A settlement should compare what each person receives after relevant liabilities, not just the stated value of the business or property.

A business is only one part of the financial picture: pensions, property, savings and investments also matter. Financial arrangements in a divorce place business interests alongside those wider assets when considering a settlement.

Will my business be taken into account in a divorce?

Yes. A business may be included when the couple’s finances are considered, but it isn’t automatically sold or divided. The settlement looks at the business alongside other assets, income and family needs.

Accounting for a business in a settlement

A financial settlement considers the business interest as part of the couple’s wider finances. How it is treated depends on its value, income, ownership structure and the needs of each spouse and any children.

For example, a director who runs a company may keep operating it, while the settlement accounts for its value through other assets or income. The family court can consider the business’s earning capacity, underlying assets and available liquidity. These factors help distinguish a valuable but cash-poor company from one that can readily provide funds.

In England and Wales, the needs of minor children receive first priority in a financial settlement. The court also considers housing and income needs, including future earning capacity and retirement. The business is assessed in context, rather than in isolation from the family’s circumstances.

Separating business and household finances

Keeping company accounts separate from household and jointly held finances creates a clearer record of what belongs to the business. Separate bank accounts and properly recorded drawings, for example, can help distinguish company expenditure from personal spending.

Good records also help explain income, liabilities and transactions during financial disclosure. Both spouses must provide full financial information, including details of any business sale and its proceeds. If a company account has paid household costs, recording those transactions helps show how they should be treated in the settlement.

Current governance documents matter too. Keeping shareholder records, company accounts and ownership documents organised makes the business structure clearer during discussions. Clear separation doesn’t determine the settlement, but it helps each person understand the business assets and income being considered.

Financial claims after separation or divorce

Separation does not by itself resolve financial claims between spouses. In England and Wales, there is no time limit for a husband or wife to make a financial claim following separation or divorce, so an informal arrangement may leave finances unresolved.

A consent order records agreed terms and can bring greater finality to the division of assets. Without an order, a couple may have agreed who keeps the business but not legally concluded their financial claims. Mediation can help address outstanding matters, such as business income, pensions or property, before an application for a financial order.

If spouses cannot agree, they can ask the court to make a financial order. The court considers the available assets, each person’s needs and the business’s ability to continue functioning. For a family with children, housing and income needs are particularly important.
What Happens to a Business in Divorce and Who Keeps It

Keeping business ownership with the operating spouse

A spouse who established and runs a business will usually be considered to retain it where possible. A court is unlikely to order a sale if that would harm the company or its shareholders, though a Scottish court may order a sale to fund an equalising payment when other assets cannot offset its value.

Lump-sum settlements instead of ownership

A lump-sum settlement can compensate one spouse for the business’s value without giving them ownership or control. This can allow the operating spouse to keep running the company while the other receives a payment or a greater share of other assets.

For example, if a business owner has sufficient personal funds or other assets, a payment may settle the other spouse’s financial interest. The figures must reflect the business’s value and the wider settlement, including each person’s needs. If the business has limited liquidity, extracting capital could affect its ability to trade, so the payment structure matters.

A spouse may also receive a share of business income rather than part of its ownership. That can provide financial support while leaving daily decisions with the person who operates the company. The settlement needs to distinguish income from capital value, since they affect the business and each spouse differently.

Ownership structures and minority shareholdings

The legal structure affects what can be transferred. A sole trader owns the business personally, while a partnership or limited company has different ownership arrangements. In a limited company, the divorcing spouse’s shares are relevant, but transferring them can affect other shareholders and directors.

A minority shareholding in a company owned by a wider group is assessed by considering the value of that particular interest, not the whole company. A spouse holding a minority stake, for instance, doesn’t own the other shareholders’ shares. Any proposed transfer must also account for the company’s governing documents and the practical effect on its operation.

Keeping the business with one spouse doesn’t require the other to receive shares. A court can consider the business’s value alongside other assets, or the spouses may agree on a financial arrangement that avoids shared ownership.

Former spouses can sometimes continue to co-own a business, but that means their decisions and financial interests remain connected after divorce. If they jointly own a company, they need to address how each person participates, makes decisions and receives income. Separating roles may be harder if both previously worked in the business than if only one spouse operated it.

Keeping control of the business after divorce

Ownership and control are related, but they are not identical. One spouse may retain a business while the settlement recognises its value through other assets or payments. For a family business, the practical question is also who makes decisions, manages staff and maintains trading relationships after the marriage ends.

Before agreeing to transfer shares, consider the effect on other directors, shareholders and employees. A spouse receiving shares, for example, may become a shareholder without experience running the company. A transfer could also affect voting arrangements or the working relationship between existing owners. Reviewing the company’s governance documents helps identify restrictions and existing rights that may shape a workable outcome.

A shareholder agreement can set out what happens if an owner must sell or transfer shares. It may give the company or another shareholder pre-emption rights, so they have the opportunity to buy shares before they pass to someone else. In a divorce, those provisions can help manage a proposed transfer and reduce disruption for the remaining owners. They don’t determine the whole financial settlement, so the share arrangements and family finances need to be considered together.

A trust may help keep a family business within the family after divorce. Its purpose and structure need careful consideration alongside the settlement, the people involved and the business’s future needs. Insurance can also protect a business if an owner dies or becomes disabled, events that may affect its value and ownership. These measures address different risks, so neither should replace clear ownership records or suitable governance arrangements.

For businesses in Scotland, courts are unlikely to force a spouse to sell or take action that harms the business, its value or its workforce. This highlights why continuity matters when considering control after separation. In other parts of the UK, the settlement also needs to account for the company’s operation and shareholders’ interests, rather than treating shares as cash that can simply be divided.

The parties can consider who will hold shares, who will make operational decisions and how future disagreements will be managed. A family company, for example, could document decision-making responsibilities and the process for a future share sale. Clear terms can help separate the spouses’ personal financial arrangements from the company’s day-to-day management.

Discuss business control in divorce to consider how ownership, financial arrangements and the company’s ongoing operation fit together.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP provides Divorce and Financial Arrangements for people working through separation and business-related financial decisions. The service can help when you need to understand how business interests, property, pensions and other assets may fit into a settlement, or how to formalise agreed arrangements.

Advice can help you consider practical outcomes, such as retaining control of a company, addressing a shareholding or balancing business value against other assets. If separation also means reviewing your will or longer-term estate plans, Wills, Probate, and Estate Planning may be relevant.

For guidance on your circumstances, contact Feltons Solicitors LLP or visit feltonssolicitors.co.uk.

Prepare for a clear next step

Understanding what happens to a business when a couple divorces is useful when it helps you plan for your financial position and your company’s future. Before discussions begin, gather current accounts, ownership records, shareholder or partnership agreements, loan documents and any nuptial agreement. Note who runs key operations, which decisions require approval, and how a transfer could affect employees or co-owners. These details can focus discussions on practical options.

Feltons Solicitors LLP offers Divorce and Financial Arrangements for financial issues arising from separation. If the settlement also affects your estate plans or property, the firm offers Wills, Probate, and Estate Planning and Residential and Commercial Conveyancing. Considering these connected arrangements together can help you plan beyond the immediate ownership question.

Arrange a discussion with Feltons Solicitors LLP about your financial arrangements and business decisions. With clear records and considered advice, you can move towards a workable plan for the next chapter.

Frequently Asked Questions

What happens to the family business upon divorce?

What happens to a business when a couple divorces depends on its ownership, finances and the family’s circumstances. The business interest and its value may be considered within the wider financial arrangements, but that doesn’t automatically mean a sale. One spouse, for example, may continue running the company while the settlement addresses the other spouse’s financial position through other resources.

How is the business divided?

A business isn’t necessarily divided by transferring half its shares. The settlement may account for its value through other assets, a payment or arrangements involving business income. One spouse might, for example, retain the company while the other receives a greater share of property or savings. The practical options depend on the business structure, available liquidity and the parties’ financial needs.

Is a limited company protected from divorce?

No. A limited company’s separate legal identity doesn’t automatically exclude a spouse’s shareholding or the company’s value from divorce financial arrangements. The court may consider the owner’s shares, income, assets and ability to generate income. The company itself isn’t automatically divided or sold. Its articles and any shareholder agreement may affect share transfers, but they don’t determine the entire financial settlement.

Who conducts the business valuation for a divorce?

An independent accountant is commonly appointed to value a business, often jointly by both spouses. A specialist may review financial statements, earnings, assets, market conditions and the company’s ownership structure. The valuation may also consider liquidity and whether capital can be extracted or borrowed against business assets. It provides an estimate for settlement discussions, not necessarily the price achievable in an actual sale.

Can a business be considered a marital asset even if only one spouse owns it?

Yes. Sole legal ownership doesn’t automatically prevent a business interest from being considered in divorce proceedings. Relevant factors include when it was acquired, whether it grew during the marriage, each spouse’s contributions and the family’s needs. A spouse’s contribution to family life, for instance, may matter to the wider financial picture even without a formal role or shareholding in the company.

Can my wife take half my business in divorce?

There’s no automatic rule that a wife receives half the business or its shares. The financial settlement considers the business alongside other assets, income and needs. The spouse operating the company may retain it while the other spouse’s financial position is addressed separately. The outcome depends on the circumstances, including the marriage, each person’s contributions, children’s needs and available resources.

Divorce with a business involved, how does it work in the UK?

Understanding what happens to a business when a couple divorces in the UK starts with financial disclosure, including business interests, income, assets and liabilities. In England and Wales, spouses can negotiate or use mediation, then seek a consent order to make agreed terms legally binding. Scotland has different rules, and Northern Ireland has its own court process, so the relevant jurisdiction matters.

How is a business valued during divorce in the UK?

A valuation considers the business’s financial position and how it operates, rather than relying on turnover alone. An accountant may assess earnings, profits, underlying assets, income-generating capacity, liquidity and ownership interests. A profitable company with limited available cash, for example, may not readily fund an immediate payment. The estimate helps compare settlement options, but doesn’t necessarily represent the price the business would fetch if sold.
Business Asset Valuation in Divorce: A 2026 Guide

Business Asset Valuation in Divorce: A 2026 Guide

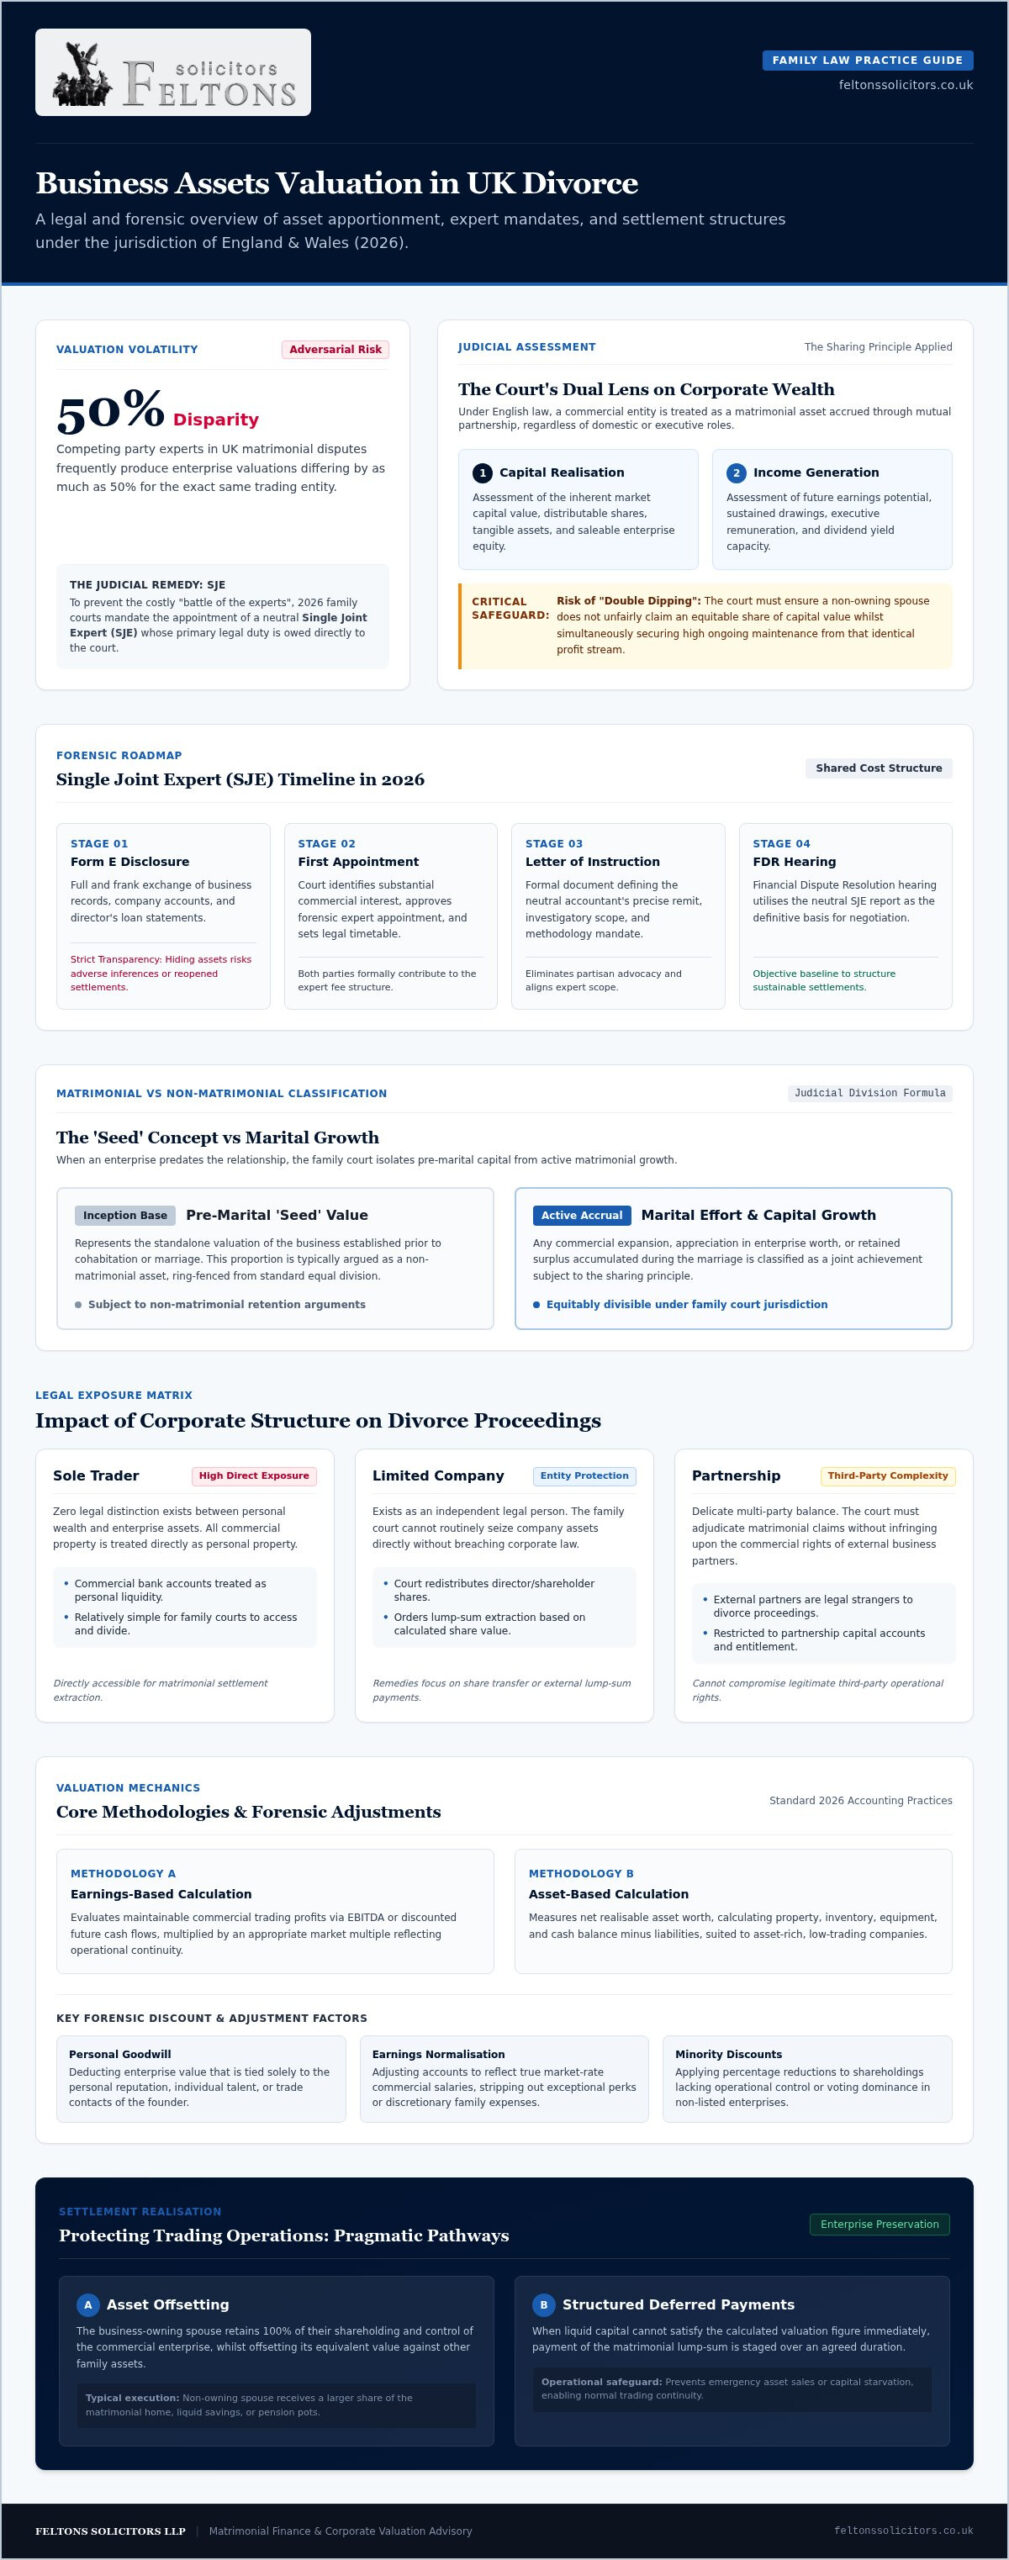
Did you know that competing valuation experts in UK matrimonial cases often produce figures that differ by as much as 50% for the same company? You’ve spent years, perhaps decades, building your enterprise from the ground up, so it’s entirely natural to feel a sense of dread that a legal process might dismantle your life’s work. The prospect of business assets valuation in divorce often brings more questions than answers, particularly when technical terms like “personal goodwill” and “earnings normalisation” enter the conversation.

We understand that you need more than just a spreadsheet; you require a strategy that respects the reality of your operations. This guide provides the clarity you need to protect your commercial interests whilst ensuring a settlement that is both fair and legally robust. We’ll explore the latest 2026 valuation methodologies, the critical role of forensic accountants, and the practical steps you can take to ensure your business continues to trade successfully long after your financial arrangements are finalised.

Key Takeaways

  • Understand why the court classifies your company as a matrimonial asset and how it balances current capital value against future income potential.
  • Navigate the role of the Single Joint Expert to ensure the business assets valuation in divorce is conducted with the forensic precision required for a fair settlement.
  • Compare earnings-based and asset-based methodologies to anticipate which calculation best reflects your firm’s commercial reality and industry standing.
  • Identify critical valuation challenges, such as minority shareholding discounts and the risk of “double dipping” into your income stream.
  • Explore pragmatic settlement options like asset offsetting and structured payments that allow you to protect your business’s continuity whilst meeting your legal obligations.

Why Business Assets Are Central to Divorce Financial Settlements

In England and Wales, the court treats a business as much more than a career; it’s a significant matrimonial asset. Whether you are a majority shareholder or a silent partner, your interest in a company is a tangible piece of the matrimonial pot. The court’s primary objective is to achieve a fair outcome, which often starts with an equal split of assets accrued during the marriage. This is known as the sharing principle. It assumes that both parties contributed equally to the family’s wealth, even if one spouse was the sole driver of the business whilst the other managed the household.

Understanding business valuation principles is vital because the court views your company through two distinct lenses. It sees a capital asset with an inherent market value and a reliable source of future income. This dual nature often complicates the business assets valuation in divorce, as the court must ensure that one spouse doesn’t receive an unfair advantage by claiming both a share of the capital and high maintenance payments based on the same profit stream.

Transparency is the foundation of this process. Every party must provide full and frank financial disclosure via Form E. This document requires you to list all business interests, including recent accounts and director’s loan statements. Attempting to obscure the true value of a company doesn’t just damage trust. It can lead to the court drawing adverse inferences or even reopening settlements years later if they discover assets were hidden.

Matrimonial vs Non-Matrimonial Business Assets

Distinguishing between assets built during the marriage and those established before the wedding is a complex task. If you started your company before you met your spouse, you might argue it’s a non-matrimonial asset. However, if the business grew significantly during your years together, the court often views that active growth as a joint achievement. The ‘seed’ of a business represents its pre-marital inception value, whereas the current valuation reflects the total marital effort and capital growth subject to court division.

The Impact of Business Structure on Divorce

Your company’s legal structure dictates how the court approaches the valuation and eventual settlement. Different entities offer different levels of protection and complexity:

  • Sole traders: There is no legal distinction between your personal finances and your business. The court treats all business assets as your personal property, making them relatively easy to access during a settlement.
  • Limited companies: The business is a separate legal entity. Whilst the court cannot usually seize company assets directly, it can redistribute your shares or order you to pay a lump sum based on their value.
  • Partnerships: These are particularly delicate. The court must balance your spouse’s claims against the legal rights of your business partners, who are considered strangers to the divorce proceedings.

The Process of Valuing a Business: How It Works in 2026

Securing an accurate valuation is rarely a matter of simple arithmetic. In the UK court system, the preferred method for establishing the worth of a company is the appointment of a Single Joint Expert (SJE). This individual is a neutral forensic accountant who owes a primary duty to the court rather than to either spouse. By 2026, the courts have become increasingly strict about the use of SJEs to prevent the “battle of the experts” that previously inflated legal costs and extended litigation timelines. This impartial approach ensures that the business assets valuation in divorce remains grounded in objective data rather than partisan advocacy.

The timeline for this process usually begins after the first exchange of financial disclosure (Form E). Once the court identifies that a business interest exists, it will set a deadline for the expert’s report, typically falling between the First Appointment and the Financial Dispute Resolution (FDR) hearing. Whilst the fees for a high-calibre forensic accountant represent a significant investment, instructing a single expert allows both parties to share the cost. It also provides a stable foundation for negotiations. If you’re concerned about how an expert might interpret your company’s books, seeking expert guidance on divorce and financial arrangements early can help you prepare for the disclosure phase.

Instructing the Single Joint Expert (SJE)

The success of a valuation depends heavily on the “Letter of Instruction.” This document defines the expert’s remit, including which valuation methods they should use and which specific assets they must investigate. Both legal teams must agree on this letter to ensure the expert has full access to the necessary financial records. If you believe the final report contains factual errors or flawed assumptions, your solicitor can submit written questions to the SJE under Part 25 of the Family Procedure Rules. However, successfully challenging an SJE’s conclusion usually requires proving a significant oversight or a departure from established business valuation principles.

Information the Valuer Will Require

A forensic accountant doesn’t just look at a single tax return. They typically require at least three to five years of statutory accounts to identify trends, along with current management accounts and future order books to assess the company’s trajectory. They will also look for “add-backs,” such as personal expenses run through the business, to determine the true maintainable earnings. A mere snapshot of today’s balance sheet is insufficient for a 2026 divorce settlement because it fails to account for the long-term sustainability of the company’s earnings or the impact of shifting market conditions on future cash flow.

Common Methodologies for Business Asset Valuation

Selecting the appropriate methodology is often the most contentious phase of the financial remedy process. In the Family Court of England and Wales, the standard applied is typically “Fair Value” rather than “Open Market Value.” Whilst market value reflects what a third party might pay in a hypothetical sale, fair value accounts for the ongoing benefit the business provides to the owner as a going concern. This distinction is vital; it ensures the valuation reflects the reality of the business’s worth to the family unit, even if there’s no immediate intention to sell.

For most trading companies, an earnings-based approach is the gold standard. This involves calculating the company’s maintainable earnings, often expressed as EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortisation), and applying a specialised “multiple” based on industry benchmarks. In contrast, for property investment firms or businesses with significant tangible holdings, an asset-based valuation is more appropriate. This focuses on the Net Asset Value (NAV), adjusting the balance sheet to reflect the current market value of all holdings minus liabilities. If you hold a minority stake, the valuer might use a dividend-based approach, focusing on the actual income stream you receive rather than the total value of a company you cannot control.

The complexity of these calculations is why business assets valuation in divorce requires such a methodical approach. It’s not just about the numbers on the page; it’s about how those numbers translate into a sustainable settlement.

Understanding Goodwill: Personal vs Corporate

Goodwill represents the value of a business beyond its tangible assets. However, the court makes a sharp distinction between corporate goodwill, which is tied to the brand and systems, and personal goodwill, which is tied to your individual reputation. If the business cannot function or be sold without your specific skills, that personal goodwill is often excluded from the divisible capital pot. A high level of personal goodwill can significantly lower the final capital valuation, as it suggests the business has limited transferable value to a third party.

Liquidity and the Ability to Pay

A high “paper value” doesn’t always translate to cash in the bank. The court is acutely aware that stripping a business of its working capital to fund a divorce settlement could cripple its future. Valuers will assess the company’s liquidity and its capacity to borrow against its assets to facilitate a buyout. Balancing these competing needs is a core part of our Guide to Divorce and Financial Arrangements, which helps business owners navigate the tension between asset division and commercial survival.

Business Asset Valuation in Divorce: A 2026 Guide

Challenges and Objections in Business Valuations

Even with the appointment of a Single Joint Expert, the path to a final financial order is often blocked by complex legal objections. A report provides a figure, but it doesn’t always provide a solution that feels equitable to both parties. One of the most significant pitfalls in business assets valuation in divorce is the “double dip.” This occurs when a spouse claims a share of the business’s capital value, which is calculated based on future earnings, and then requests spousal maintenance from those same earnings. Courts in 2026 are increasingly vigilant about this, as it effectively forces the business owner to pay out on the same profit stream twice. Successfully navigating this requires a legal team that can distinguish between capitalised income and maintainable dividends.

Beyond the double-dipping trap, the argument of “special contribution” remains a frequent but rarely successful tactic. Unless the business owner can prove they possess a “genius” quality that generated exceptional wealth, the court almost always adheres to the sharing principle. Similarly, the treatment of director’s loan accounts can create friction. If you have borrowed money from your company, that debt is an asset of the business but a liability for you personally. Forensic accountants will scrutinise these accounts to ensure they aren’t being used to artificially deflate the value of the matrimonial pot.

The Minority Shareholder Discount

A common point of confusion is why a 10% shareholding isn’t simply worth 10% of the company’s total value. In the world of private companies, a minority stake lacks “control” and “marketability,” meaning the shareholder cannot force a sale or dictate dividend policy. Forensic accountants often apply a discount, which can range from 25% to over 50% depending on the level of influence the shares provide. However, an exception often exists for “quasi-partnerships.” These are small companies that function like partnerships despite their corporate structure, where the court may decide that no discount should be applied because the parties always intended to share equally.

Addressing Allegations of Financial Non-Disclosure

Attempting to hide assets or run personal “lifestyle” expenses through the company books is a high-risk strategy that usually backfires. Forensic accountants are trained to spot anomalies, such as family holidays or school fees categorised as business expenses, and they will “add back” these sums to the company’s profit. If the court finds that you have been less than transparent, it has the power to draw “adverse inferences.” This means the judge can assume your business is worth significantly more than you claim. To ensure your disclosure is handled with the necessary precision and discretion, you should instruct a specialist solicitor for your financial arrangements at the earliest opportunity.

Protecting Your Business and Negotiating the Settlement

Once the business assets valuation in divorce is finalised, the focus shifts from calculation to implementation. The court generally follows the “Golden Egg” principle. It prefers not to kill the goose that lays the golden eggs. If a business provides the income necessary to support both parties and their children, judges are often reluctant to order a sale that would destroy that income stream. Instead, they look for creative ways to satisfy the non-owning spouse’s claims whilst ensuring the company remains a viable trading entity.

One of the most effective tools is offsetting. This involves the business owner “trading” their share of other matrimonial assets, such as the family home or liquid savings, in exchange for retaining full ownership of the company. If there isn’t enough equity elsewhere to achieve a clean break, a structured settlement may be negotiated. This allows for a lump sum to be paid in instalments over several years, protecting the company’s cash flow whilst providing the other spouse with their fair share over time. These arrangements require careful drafting to ensure they are legally binding and enforceable.

Alternatives to Selling the Business

Pension offsetting is another sophisticated route, where one party keeps their pension intact whilst the other retains the business interests. Whilst transferring shares to a spouse is technically possible, it’s often fraught with commercial risk. Becoming “accidental” business partners after a divorce can lead to operational deadlock and further litigation. For future protection, a well-drafted shareholders’ agreement or a pre-nuptial agreement can define exactly how a business should be valued and divided. This forward-thinking approach is a key part of A Complete Guide to Estate Planning, which ensures your commercial legacy remains secure.

Why Expert Legal Representation is Essential

Feltons Solicitors LLP acts as your sophisticated guide through these high-stakes negotiations. We provide the calm, steady presence needed when personal emotions collide with complex commercial interests. Our team prioritises a people-first philosophy, ensuring that whilst the technical aspects of the business assets valuation in divorce are precise, the human impact of the settlement is never forgotten.

To begin the process with professional support, your next step should be a discreet consultation to review your business structure and disclosure requirements. We’ll help you navigate the complexities of asset protection with the quiet confidence that comes from years of expertise in complex financial litigation. Protecting what you’ve built requires more than just a lawyer; it requires a partner who values your privacy and understands the nuances of your industry.

Securing Your Commercial Legacy

The complexities of business assets valuation in divorce require a balance of forensic accuracy and strategic foresight. Navigating the transition from identifying matrimonial assets to finalising a settlement involves understanding the nuances of the Single Joint Expert process and the “Golden Egg” principle. By prioritising transparency and selecting the correct valuation methodology, you can ensure your company remains a viable entity whilst meeting your legal obligations. This approach protects your life’s work from unnecessary disruption and provides a stable foundation for the future.

Feltons Solicitors provides a boutique level of care combined with national expertise in complex financial arrangements. Our specialists offer the discreet and professional legal guidance necessary to resolve high-stakes disputes with quiet confidence. We act as your sophisticated guide through every stage of the negotiation, ensuring the human impact of our work is never forgotten. Secure your business’s future with Feltons Solicitors and move forward with a resolution that respects your commercial achievements. You don’t have to navigate these complexities alone; your interests are in capable hands.

Frequently Asked Questions

Will I have to sell my business to pay my ex-spouse in a divorce?

It is rare for a court to order the sale of a business if it provides the primary income for the family. Judges prefer to keep the “golden egg” intact to ensure ongoing maintenance and financial stability. Instead, you might offset the business value against other assets like the family home or arrange a structured payout over several years. This allows the business to continue trading whilst satisfying the legal requirements of the settlement.

How long does a forensic valuation of a business usually take?

A forensic valuation typically takes between four and twelve weeks to complete once the expert has all the necessary data. This timeline depends on the complexity of your company structure and the speed at which you provide financial records. Delays often occur if there are gaps in the statutory or management accounts. It is vital to start this process early in the financial remedy proceedings to avoid pushing back your court dates.

What happens if my business is currently making a loss?

A loss-making business still has a value for divorce purposes, though it may be calculated differently. If the company is not profitable, the valuer might use an asset-based approach, focusing on the Net Asset Value (NAV) of its equipment, property, or stock. In some cases, a business might have “hope value” if it possesses unique intellectual property or a market position that suggests a return to profitability in the near future.

Can I use my own accountant to value the business for the court?

The court usually requires a Single Joint Expert (SJE) to ensure an impartial valuation that both parties can trust. Whilst your own accountant understands your books, they are not considered independent by the court. However, working with an established firm of chartered accountants like Stewart Accounting Services can help you prepare your disclosure and review the SJE’s findings. Ultimately, the formal business assets valuation in divorce must be conducted by a neutral forensic specialist appointed under a joint letter of instruction.

Is the value of my business based on what I started with or what it is worth now?

The court considers the current value of the business, but it also looks at what the business was worth at the date of marriage. Any growth that occurred during the years you were together is typically seen as a matrimonial asset. If the business was established long before the wedding, you may be able to argue that the initial “seed” value should be excluded from the pot, though this depends on the length of the marriage.

How much does a forensic business valuation cost in 2026?

Fees for a forensic accountant vary significantly based on the size and complexity of the enterprise. For a standard small-to-medium enterprise, costs generally start in the thousands and are typically shared between both parties as a joint disbursement. More complex cases involving international assets or multiple subsidiaries will naturally attract higher fees. You should discuss these costs with your solicitor early on to ensure they are proportionate to the overall value of the matrimonial estate.

What is ‘double dipping’ and how can it be avoided in my settlement?

Double dipping is a common error where the same income stream is used twice in a settlement. This happens when a business is valued based on its future earnings to create a capital lump sum, and those same earnings are then used to calculate spousal maintenance. To avoid this, your legal team must ensure that the valuation and the maintenance calculations are adjusted so the business owner isn’t paying out on the same profit twice.

Can my spouse claim a share of a business I inherited?

Inherited businesses are often viewed as non-matrimonial assets, but they aren’t automatically protected. If the business was used to fund the family’s lifestyle or if your spouse’s financial needs cannot be met by other assets, the court may choose to include it in the settlement. The longer the marriage and the more the business was integrated into your joint finances, the more likely it is that your spouse will have a valid claim.

High Net Worth Divorce Solicitors: Navigating Complex Financial Settlements in 2026

High Net Worth Divorce Solicitors: Navigating Complex Financial Settlements in 2026

The assumption that a marriage automatically entitles a spouse to half of your pre-marital wealth is no longer the legal certainty it once was. Following the landmark 2025 Supreme Court decision in Standish v Standish, the distinction between matrimonial and non-matrimonial property has become a critical battleground for wealth preservation. When your estate includes private businesses, international trusts, or overseas property, the standard administrative process of a no-fault divorce is rarely sufficient. Engaging specialised high net worth divorce solicitors is no longer just about legal representation; it’s about strategic financial protection in an era where the family courts are facing record delays and evolving precedents.

You likely feel a profound sense of responsibility to protect the assets you’ve built, whilst fearing that a public court battle could expose your private financial affairs. We understand that high-value separations require a level of discretion and technical precision that goes beyond the ordinary. This guide provides a comprehensive roadmap for securing a fair financial order that respects pre-marital contributions and manages complex international interests. You’ll learn how to navigate current Capital Gains Tax rates, the benefits of private dispute resolution, and the specific ways your business and trusts are treated under 2026 regulations.

Key Takeaways

  • Learn how recent legal precedents provide a clearer framework for ring-fencing pre-marital wealth and non-matrimonial assets during a high-value separation.
  • Understand the specific risks and protections associated with international trusts, overseas property, and the potential for the court to “pierce the corporate veil” in financial settlements.
  • Discover why high net worth divorce solicitors are vital for securing accurate valuations of private businesses whilst ensuring your financial affairs remain strictly confidential.
  • Gain insights into the mandatory disclosure process and how private dispute resolution can help you avoid the significant delays currently facing the UK family court system.
  • See how an integrated legal strategy-combining family, property, and probate expertise-provides a more robust defence for your long-term financial security.

Defining High Net Worth Divorce: Why Substantial Assets Require Specialist Expertise

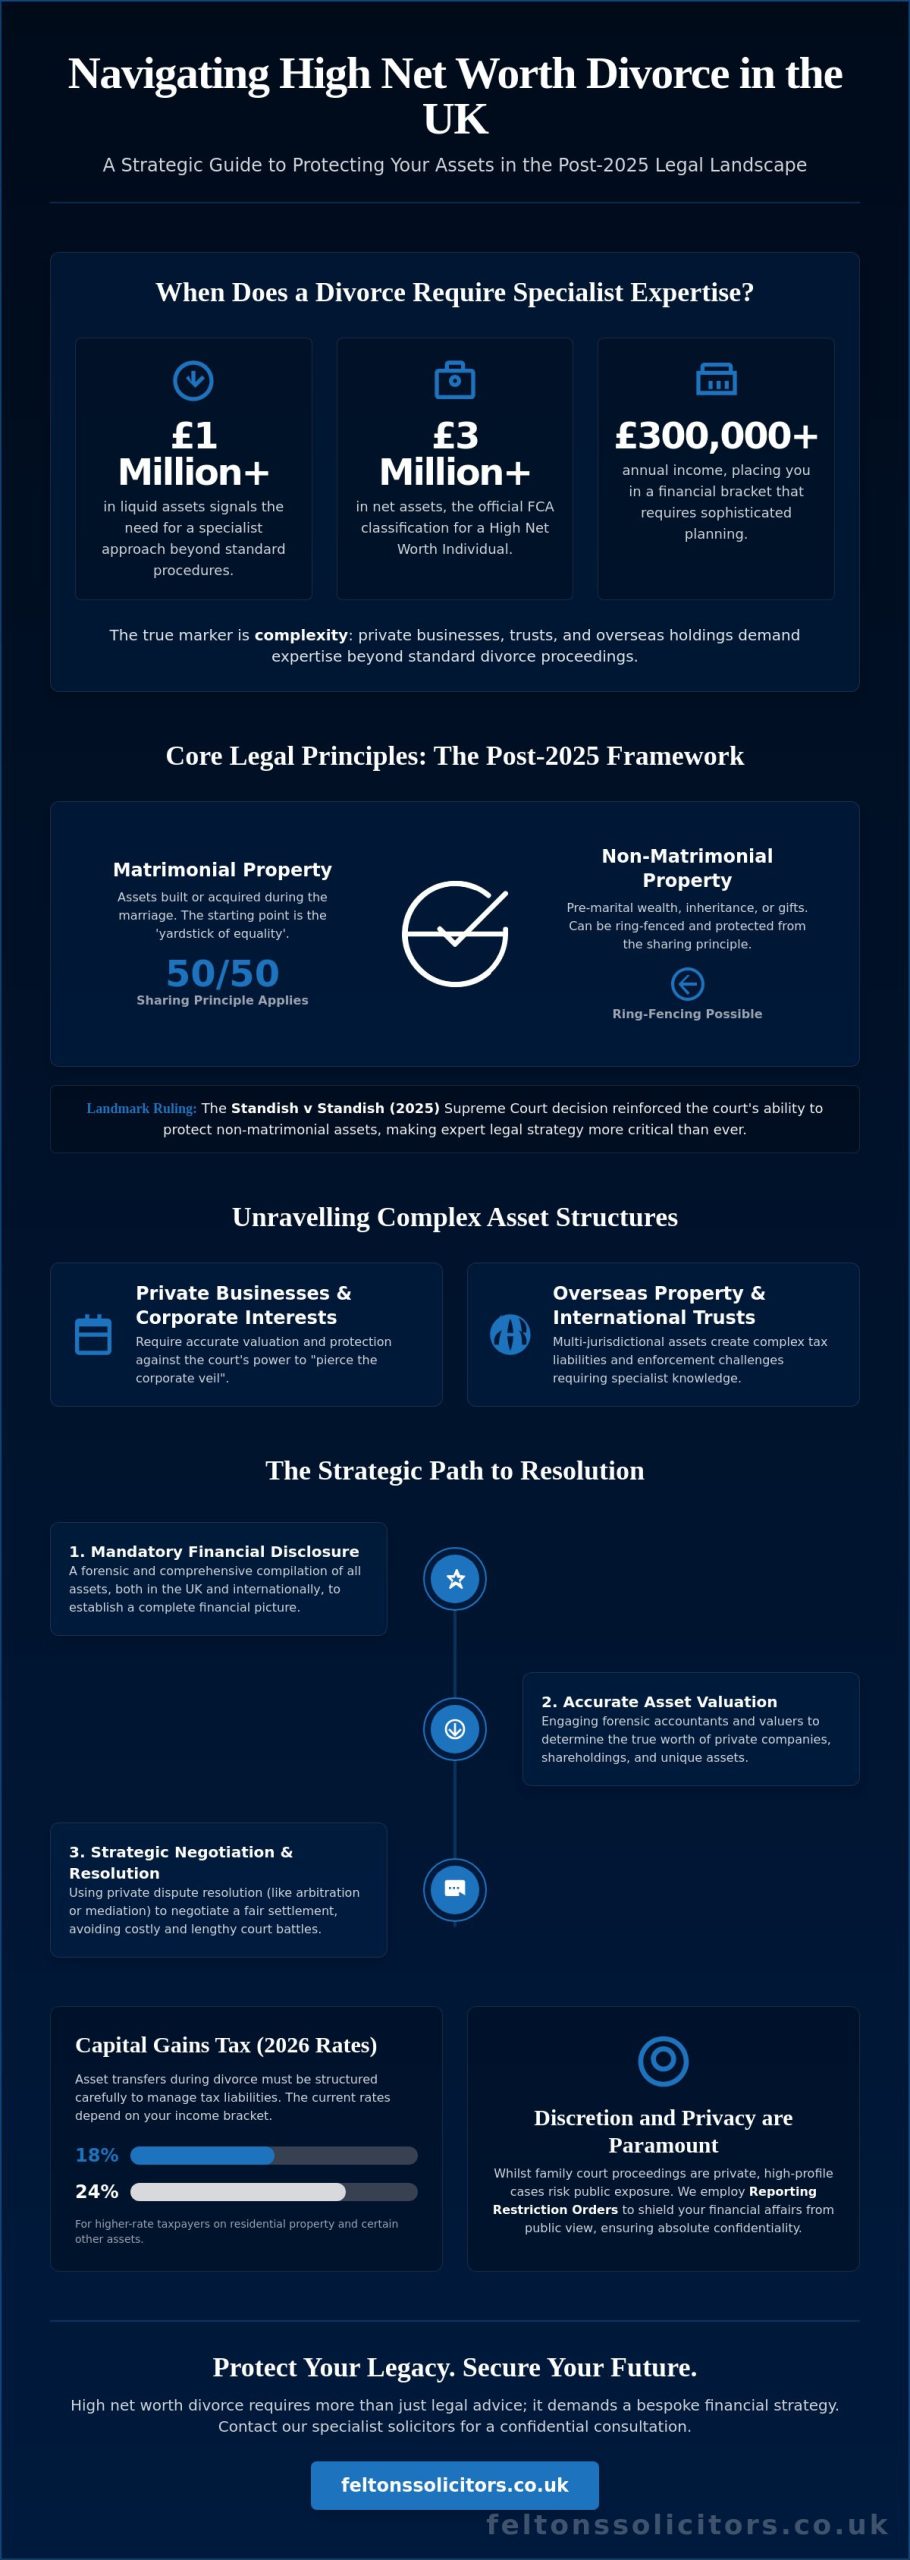
High net worth divorce is defined less by a specific figure and more by the intricate architecture of the assets involved. While the Financial Conduct Authority (FCA) categorises a high net worth individual as someone with an annual income of £300,000 or net assets exceeding £3 million, the legal reality in 2026 is that any case involving liquid assets over £1 million requires a specialist approach. Standard divorce procedures are designed for the “average” estate. They often lack the technical tools required to unpick international trusts, private equity holdings, or multi-jurisdictional tax liabilities. When your financial security depends on the valuation of a private company or the protection of inherited wealth, the standard administrative track is rarely sufficient.

In these high-value cases, the court moves beyond the basic “needs” of the parties. When assets far exceed what is required for housing and maintenance, the focus shifts to the “sharing principle.” While the “yardstick of equality” remains the starting point for matrimonial property, departures from a 50/50 split are common. This is particularly true following the 2025 Standish v Standish ruling, which reinforced the protection of non-matrimonial assets. Identifying which assets are subject to the sharing principle and which should be ring-fenced is a task that requires the steady hand of experienced high net worth divorce solicitors.

The Threshold of Complexity: When is a Divorce “High Net Worth”?

Complexity is the true marker of a high-value settlement. It isn’t just about the size of the bank balance; it’s about the presence of family trusts, offshore entities, and private business interests. Using non-specialist solicitors for such matters carries significant risk. A lack of expertise in corporate structures or the 2026 Capital Gains Tax rates, which sit at 18% or 24% depending on income, can lead to settlements that look fair on paper but are financially flawed in practice. Specialist high net worth divorce solicitors ensure that every asset is correctly categorised and valued before any negotiation begins.

The Importance of Discretion and Privacy

For many clients, the fear of public exposure is as significant as the fear of financial loss. While the UK family court system has moved toward greater transparency, financial remedy proceedings remain fundamentally private. However, the risk of sensitive details entering the public domain still exists, especially in high-profile divorce settlements where the press may take an interest. Protecting your anonymity requires a proactive strategy. We often utilise Reporting Restriction Orders to prevent the publication of identifying financial data. Boutique firms prioritise this level of discretion, acting as a shield between your private life and the public eye.

Managing Complex Asset Structures: Trusts, Overseas Entities, and Corporate Interests

High-value settlements often involve assets that exist far beyond the reach of a standard bank statement. For many clients, the bulk of their wealth is tied up in private limited companies, commercial property portfolios, or sophisticated trust arrangements. These structures require a forensic level of scrutiny. A primary challenge for high net worth divorce solicitors is determining which of these assets are truly “matrimonial” and which can be protected as non-matrimonial wealth. Whilst the 2025 Standish v Standish ruling provides clearer boundaries for ring-fencing inherited assets, the way these funds have been managed during the marriage-for example, if they were used to purchase a family home-can complicate their legal status.

Corporate interests present a unique hurdle. Under English law, a company is a separate legal person. However, the family court possesses the power to “pierce the corporate veil” in specific circumstances. If a business structure is being used as a “sham” to hide personal wealth or if one spouse maintains absolute control over the company’s liquidity, a judge may treat the business assets as personal property. Accurate valuation is essential here. We work alongside forensic accountants to ensure that the “true” value of a private limited company is established, accounting for future earnings and tax liabilities rather than just the balance sheet. If you are concerned about how your business interests will be treated, seeking advice on divorce and financial arrangements early in the process is a prudent step.

The Impact of the Register of Overseas Entities (ROE)

The intersection of property law and divorce disclosure has become increasingly complex since the introduction of the Register of Overseas Entities. Any overseas entity owning UK land must now be registered with Companies House. During a divorce, failure to comply with ROE requirements can stall a financial settlement indefinitely. If a property is held by an unregistered offshore entity, it cannot be sold or transferred to a spouse as part of a court order. Our team provides specialised expertise in the registration of overseas entities, ensuring that international property holdings are fully compliant and ready for inclusion in a final financial order.

As managing international assets often requires frequent travel, ensuring your logistics are handled with the same level of professionalism as your legal affairs is vital; you can learn more about Brighton Airport Taxis for discreet and reliable airport transfers.

Trusts: Nuptial vs. Non-Nuptial Settlements

Trusts are often the most contentious element of a high-value divorce. The court distinguishes between “nuptial” trusts, which were created for the benefit of the couple or their children, and “non-nuptial” trusts, such as those established by previous generations.

  • Nuptial Trusts: The court has broad powers to vary these settlements to meet the needs of a spouse.
  • Non-Nuptial Trusts: These are harder to reach, but the court may still consider them a “resource” if a spouse has a history of receiving regular distributions.

Protecting a family trust from being liquidated requires a strategy that demonstrates the trust was never intended to be part of the shared matrimonial pot.

Strategic Asset Protection: Balancing Fair Distribution with Wealth Preservation

Many clients approach a separation with a singular, pressing concern: the fear of losing half of everything they have spent a lifetime building. Whilst an equal division of matrimonial assets is the standard starting point in English law, it’s not an unbreakable rule. Experienced high net worth divorce solicitors focus on shifting the narrative from a simple 50/50 split to a nuanced argument for wealth preservation. This involves a rigorous analysis of the sharing principle versus the genuine financial needs of the other party. In cases of exceptional wealth, we may also explore the “special contribution” argument. This applies when the extraordinary business acumen or stellar contribution of one spouse is so significant that it justifies a departure from an equal division.

Strategic protection often rests on the validity of Pre-Nuptial and Post-Nuptial agreements. As of June 2026, the UK government is engaged in a major consultation regarding the legal status of these documents, with potential legislation on the horizon. Even before these reforms, the courts place significant weight on agreements that were entered into freely and with full financial disclosure. If an agreement is deemed fair and meets the basic needs of both parties, it serves as a powerful shield for pre-acquired wealth and inherited assets. It provides a level of certainty that the standard court process cannot guarantee.

Ringfencing Non-Matrimonial Assets

Protecting assets acquired before the marriage or through inheritance requires meticulous evidence. The primary risk in high-value cases is “mingling.” This occurs when non-matrimonial funds are transferred into joint accounts or used to purchase a shared family home. Once assets are mixed with family finances, they often lose their protected status and become part of the matrimonial pot. We assist clients in tracking the origin of their wealth through historical financial records. By clearly identifying pre-marital property and family gifts during the disclosure process, we can build a robust case for these assets to be ringfenced and excluded from the final settlement. For a comprehensive overview of the steps involved, our strategic checklist for complex financial settlement divorce provides a meticulous roadmap for safeguarding your financial future.

Business Protection Strategies

A forced sale of a family business or a mandatory transfer of shares is rarely a desirable outcome. To avoid this, we often utilise a strategy called “offsetting.” Instead of liquidating corporate interests, the other spouse may receive a larger portion of other matrimonial assets, such as liquid cash, property, or pension pots. This preserves the operational integrity of the business whilst satisfying the court’s requirement for a fair distribution. Forensic accountants are essential in this process. They provide a valuation that accounts for the illiquidity of shares and the 2026 Capital Gains Tax rates, ensuring the settlement is based on realistic, post-tax figures rather than mere book value.

High Net Worth Divorce Solicitors: Navigating Complex Financial Settlements in 2026

The Path to Resolution: Disclosure, Valuation, and Negotiated Settlements

Achieving a fair financial order depends entirely on the transparency of the information provided at the start of the process. In English law, this is known as “full and frank” financial disclosure. For clients with complex portfolios, this stage is often the most demanding. It requires a meticulous gathering of evidence for assets that may be illiquid or held in opaque structures. If a spouse attempts to hide assets or provides misleading information, the court can issue “set-aside orders” years after the divorce is finalised, effectively reopening the entire settlement. Professional high net worth divorce solicitors act as a safeguard here, ensuring that your own disclosure is unimpeachable whilst rigorously testing the validity of the information provided by your spouse. For a detailed overview of your obligations, our complete guide to financial disclosure in divorce UK covers the latest 2026 requirements in full.

The valuation of non-liquid assets, such as private equity holdings or interests in family trusts, requires more than just a cursory glance at a balance sheet. We instruct expert witnesses, including forensic accountants, tax advisors, and actuaries, to provide a precise picture of your wealth. These experts account for the 2026/27 Capital Gains Tax rates of 18% and 24%, ensuring that the net value of an asset reflects the reality of its eventual sale or transfer. Without this level of technical detail, you risk a settlement based on “paper wealth” that doesn’t account for the significant tax liabilities attached to high-value assets. This forensic approach is essential for identifying the true liquidity available for a complex financial settlement divorce.

Navigating the Form E for High Net Worth Individuals

Filling out the Form E is a complex task when your income is derived from multiple sources or offshore interests. Specific care must be taken with Section 2.13, which covers “other assets,” including digital currencies, fine art, or interests in unquoted companies. The duty of disclosure is an absolute legal obligation that remains in force until a final order is sealed. Failing to account for potential CGT liabilities or the true value of an executive pension pot can lead to a settlement that is fundamentally skewed. If you require assistance with complex filings, our team at Feltons Solicitors LLP specialises in divorce and financial arrangements for sophisticated estates.

Mediation and Arbitration: A Discreet Alternative

With family court delays currently averaging 74 weeks from application to final order, many individuals are turning to private dispute resolution. Arbitration, in particular, offers a level of discretion and efficiency that the public court system cannot match. You have the flexibility to choose an arbitrator with specific expertise in complex financial structures, ensuring your case is handled by someone who understands the nuances of HNW wealth. This private “judge” provides a binding decision in a fraction of the time, allowing you to secure a clean break without the stress of a protracted public battle. Experienced high net worth divorce solicitors facilitate these out-of-court settlements, maintaining a robust legal position whilst prioritising your privacy and time.

Feltons Solicitors LLP: A Bespoke Approach to High-Value Divorce and Financial Arrangements

Large, high-volume law firms often struggle to provide the granular attention that a multi-million pound estate demands. Feltons Solicitors LLP operates as a boutique practice, where direct partner access isn’t a luxury but a standard part of our service. This ensures that your strategy is shaped by seniority and experience from the very first consultation. As high net worth divorce solicitors, we recognise that wealth is rarely static; it’s a living entity of businesses, properties, and trusts that requires a steady, sophisticated guide to manage effectively. Established in 2010 by Paula Felton, our firm provides a calm, steady presence, ensuring that even the most stressful financial negotiations are handled with quiet confidence.

Our strength lies in our multidisciplinary strength. Because we also specialise in commercial conveyancing, litigation, and the registration of overseas entities, we don’t need to outsource the technical elements of your settlement. We understand the mechanics of property transfers and corporate structures from the inside out. This integrated perspective allows us to anticipate hurdles in asset division that a general family law firm might overlook. We pride ourselves on delivering polished, professional advice that remains accessible, favouring plain English over dense, archaic legalese.

Integrated Legal Support for HNW Families

A financial order is only the first step in securing your post-divorce life. The actual transfer of high-value property or the restructuring of corporate holdings requires precise legal execution. Our residential and commercial conveyancing teams work alongside our family department to streamline these transitions. Simultaneously, a divorce automatically alters your inheritance position. It’s vital to review your Wills and Estate Planning to ensure your assets remain protected for future generations. By managing these adjacent legal needs under one roof, we provide a seamless service that protects your interests across all sectors of the law.

Securing Your Future with Pragmatic Advice

We prioritise long-term financial stability over the fleeting satisfaction of a courtroom win. Our focus is on achieving a fair settlement that preserves your core assets and provides a clean break. We understand the human impact of these proceedings. Whilst we are robust high net worth divorce solicitors when protecting your balance sheet, we remain approachable and supportive partners throughout the process. Our national reach and experience with international complexities mean you receive elite-level representation with the personal touch of a boutique firm. If you are ready to move forward, Contact Feltons Solicitors LLP for a discreet consultation on your financial arrangements.

Securing Your Financial Legacy with Confidence

Navigating the complexities of high-value divorce in 2026 requires a legal partner who understands the intricate intersection of family law, corporate governance, and international property regulations. As we’ve explored, achieving a fair settlement involves more than just an administrative division; it requires the strategic ringfencing of non-matrimonial wealth and the precise valuation of illiquid assets. By choosing high net worth divorce solicitors who prioritise discretion and technical precision, you can navigate these challenges without sacrificing your long-term financial security or personal privacy.

Established in 2010 by Paula Felton, Feltons Solicitors LLP provides the boutique, partner-led service necessary to handle high-stakes litigation and complex overseas entity registration. We offer a calm, steady presence during a period of significant change, ensuring that your private affairs remain protected whilst you secure a clean break. Our commitment to pragmatic, “plain English” advice ensures you remain in control of the process at every stage. We are here to help you protect what you’ve built and provide a stable foundation for your future.

Secure a Discreet Consultation with Our High Net Worth Divorce Specialists

Frequently Asked Questions

What qualifies as a high net worth divorce in the UK?

High net worth divorce is defined by the complexity and scale of the marital estate rather than a single statutory figure. Whilst the Financial Conduct Authority identifies individuals with £3 million in net assets or an annual income of £300,000 as high net worth, family courts generally apply this label to cases with over £1 million in liquid assets. These cases are distinguished by the presence of diversified portfolios, including private businesses, trusts, and international property, which require a specialised legal approach beyond standard procedure.

Can I protect my business from my spouse during a divorce?

You can often protect a business from a forced sale or share transfer through a strategy known as offsetting. This involves providing your spouse with a larger share of other matrimonial assets, such as the family home or liquid cash, to preserve the operational integrity of the company. The court’s primary goal is fairness, and if a business was established before the marriage or through inherited wealth, there are strong legal arguments for ringfencing its value, provided the other party’s needs are met.

How are offshore assets and trusts treated in a UK divorce settlement?

Offshore assets and trusts are treated as financial resources and must be fully disclosed during proceedings. The family court has the power to vary “nuptial” trusts created for the benefit of the family or to treat trust distributions as an available resource if a spouse has a history of receiving funds. Compliance with the Register of Overseas Entities is also vital, as unregistered properties cannot be legally transferred or sold as part of a final financial order.

What happens if my spouse hides assets during the financial disclosure process?

Hiding assets is a serious breach of the absolute duty of “full and frank” financial disclosure in divorce UK proceedings and can lead to severe legal penalties. If non-disclosure is discovered, the court may issue “set-aside orders” to reopen a settled case, award a higher percentage of the known assets to the other spouse, or issue cost orders against the non-disclosing party. Forensic accountants are often employed to trace missing funds and ensure the settlement is based on the true extent of the marital wealth.

How long does a high net worth divorce typically take to resolve?

A high-value divorce typically takes between 12 and 18 months to reach a final financial settlement, even though the administrative divorce process has a minimum timescale of 26 weeks. Significant delays in the public court system mean that financial remedy applications currently face an average wait of 74 weeks for a final order. Experienced high net worth divorce solicitors often recommend private arbitration or mediation to bypass these delays and achieve a faster, more discreet resolution.

Is a Pre-Nuptial Agreement legally binding in a high net worth divorce?

Pre-Nuptial Agreements are not yet strictly binding in English law, but they are highly influential and often decisive if they meet specific criteria. Following the 2010 Radmacher ruling, courts will generally uphold an agreement if it was entered into freely, with full financial disclosure and independent legal advice, provided the outcome is fair. With a government consultation on the legal status of these agreements underway in 2026, their role in wealth preservation is becoming increasingly central.

Will I have to sell the family home in a high-value divorce?

Selling the family home is not a requirement if there is sufficient liquidity in the rest of the estate to satisfy both parties’ housing needs. In high net worth cases, it’s common for one spouse to retain the property whilst the other receives a balancing payment from business interests, savings, or pension pots. The court prioritises the needs of any children involved, but it also respects the practicalities of maintaining high-value assets where an alternative settlement is possible.

Why should I choose a boutique law firm over a large national practice?

Choosing a boutique firm ensures you receive a partner-led service where your financial strategy is managed by a senior expert rather than a junior associate. This model offers a level of discretion, personal rapport, and tailored attention that high-volume national practices often struggle to provide. For complex estates, high net worth divorce solicitors at boutique firms offer the technical focus and integrated property expertise required to manage sophisticated international interests effectively.