Construction Accident Claims Solicitors in the UK

Construction Accident Claims Solicitors in the UK

The deadline matters: in England and Wales, the standard time limit for a construction accident claim is three years from the date of the accident under the Limitation Act 1980. If negligence contributed to your injury, you may be able to seek compensation. Construction accident claims solicitors in the UK can help assess the circumstances and explain the steps involved.

After a construction accident, it’s understandable to be unsure what to do first, particularly when you’re dealing with treatment, time off work or uncertainty about who was responsible. Acting promptly can help preserve useful evidence and keep a potential claim on track.

This guide explains how construction accident claims work, what may amount to negligence, which time limits apply and what practical steps to take after an accident. It also explains how a solicitor can help gather evidence and progress a claim.

Key Takeaways

  • Identify whether unsafe practices, equipment or site conditions may have contributed to your injury and who was responsible.
  • Report the incident, seek medical attention and preserve useful evidence, including photographs and witness details.
  • Understand how the claims process moves from gathering evidence and assessing responsibility to negotiating a resolution.
  • A solicitor can help organise the evidence and explain the practical steps involved in pursuing a personal injury claim.

What is a construction injury compensation claim?

A construction injury compensation claim seeks damages after a worksite injury caused by someone else’s negligence. The Construction (Design and Management) Regulations 2015 are relevant to construction-site safety in England and Wales, according to The National Archives (legislation.gov.uk).

Eligibility for injury compensation

Eligibility depends on whether another party’s failure to take reasonable care caused or contributed to your injury. That party could be an employer, contractor or someone responsible for unsafe site conditions. Employees and self-employed workers may both be eligible. Consider what happened, who controlled the work and how the alleged failure led to your injury.

For example, a fall from unsafe scaffolding may raise questions about site inspections and the precautions taken. Evidence connecting the incident to a health and safety failure can help assess a compensation claim.

Injury and financial losses

Compensation may cover the injury itself and its impact on daily life. General damages reflect pain, suffering and loss of amenity, including restrictions on ordinary activities during recovery. The injury’s nature, severity and lasting effects are relevant. A wrist fracture, for example, may affect work and everyday tasks differently from a minor injury.

Special damages cover financial losses and expenses caused by the accident. Keep records linking each claimed cost or loss to your injury, such as payslips and treatment receipts.

Earnings, treatment, care and travel costs

Claimable losses may include earnings missed during recovery, private treatment, physiotherapy and travel to medical appointments. Care and assistance at home may also form part of a financial claim. Keep receipts, appointment details and records of time off work so each loss can be linked to the accident.

Future needs may also be relevant. Ongoing treatment, psychological therapy or home adaptations could affect the amount claimed, depending on the injury and its consequences.

Compensation ranges for construction injuries

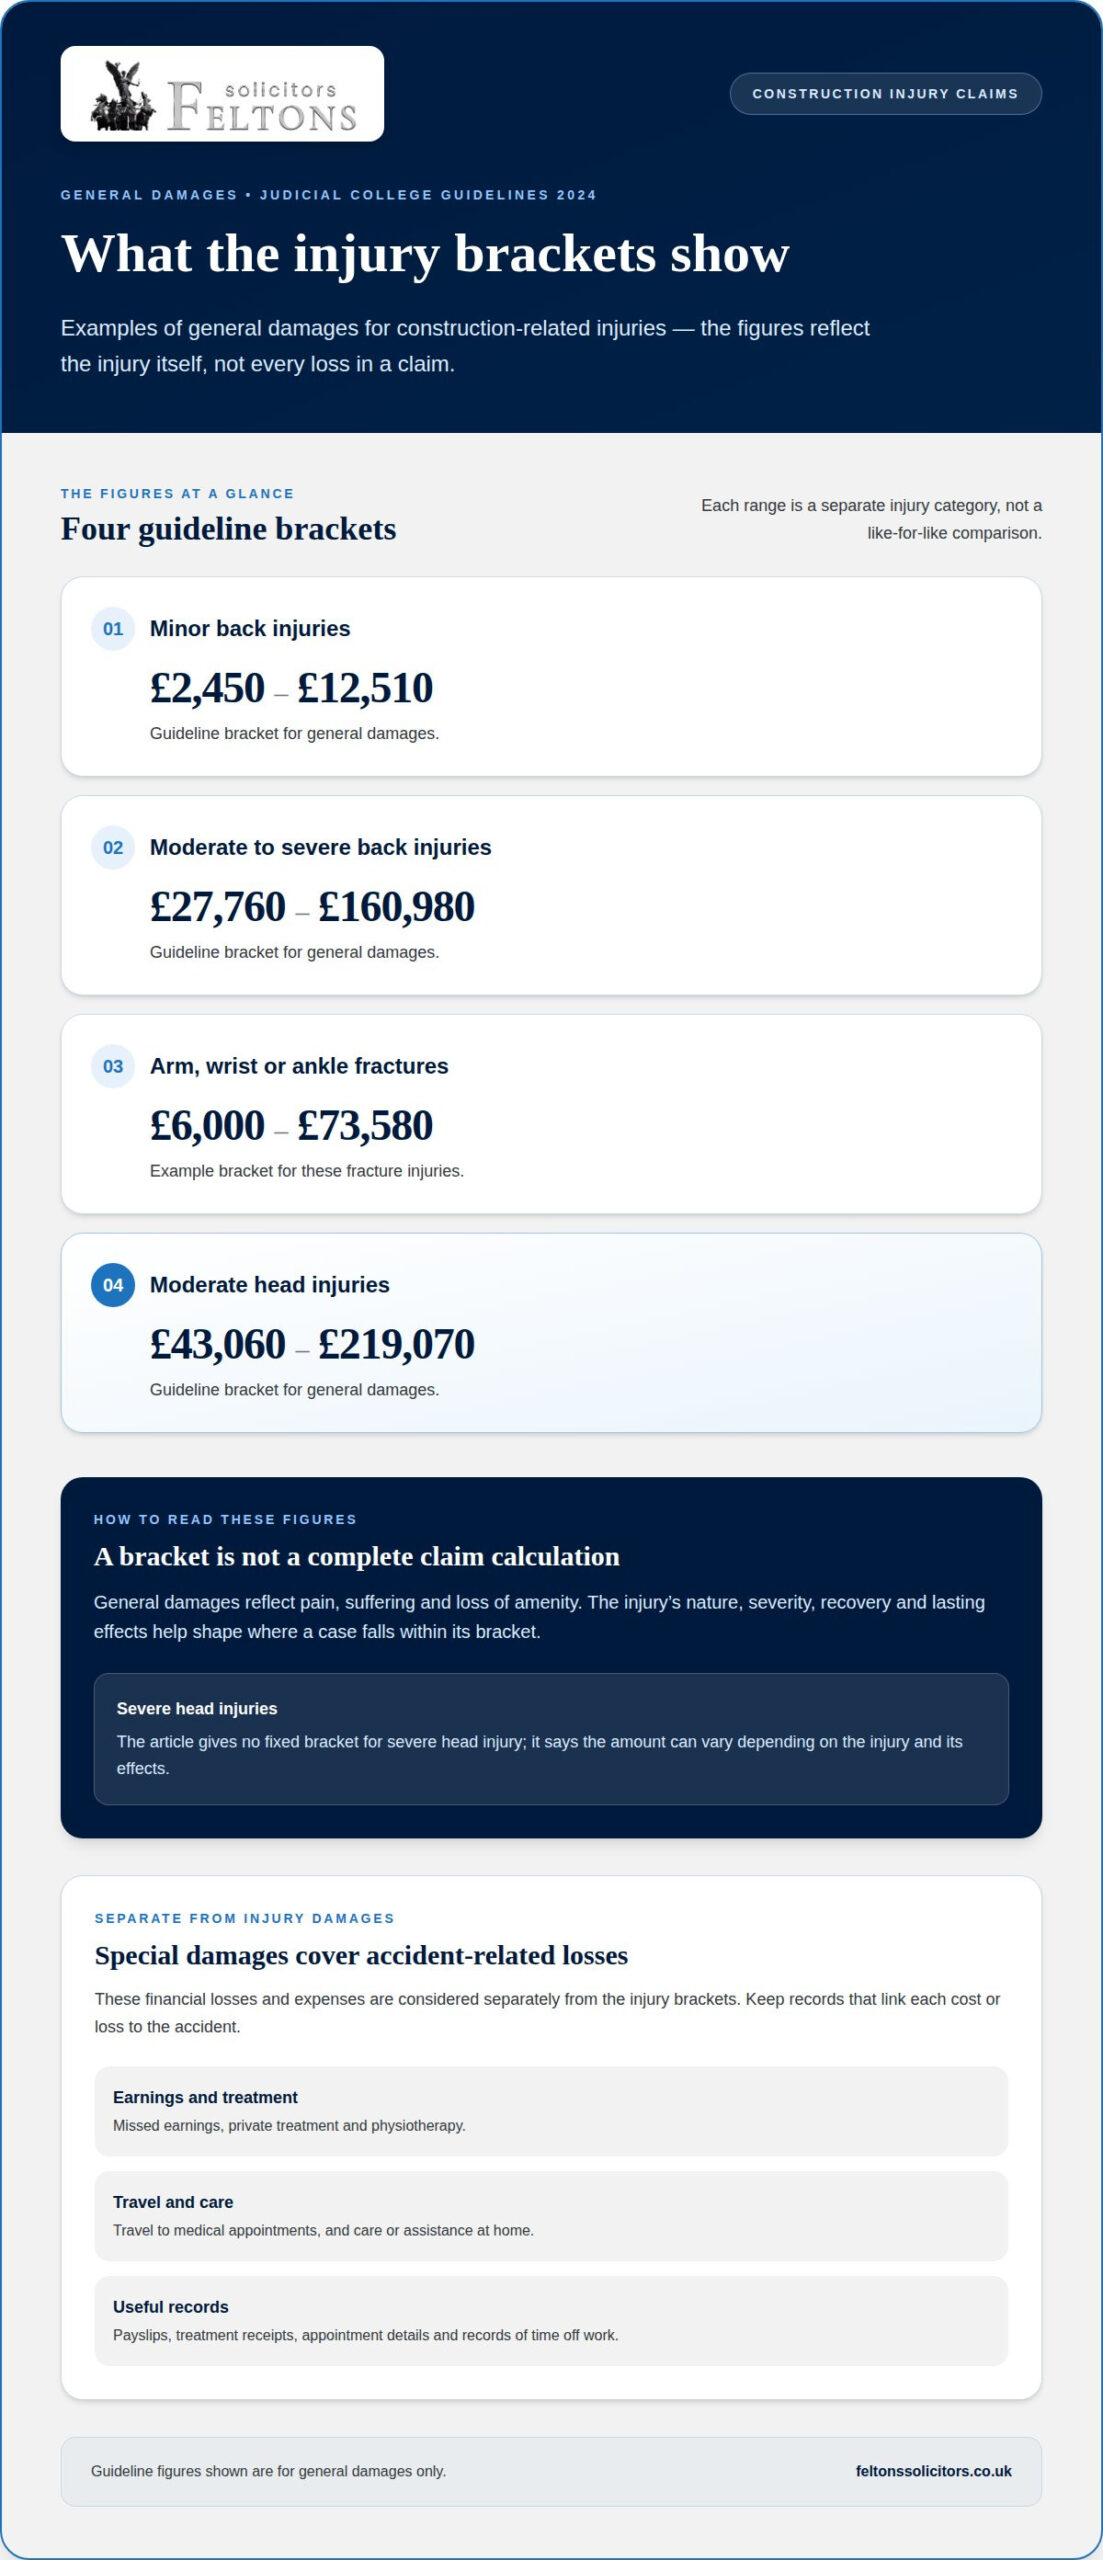
The Judicial College Guidelines 2024 provide brackets for general damages, not a complete calculation of every claim. Minor back injuries are listed at £2,450-£12,510; moderate to severe back injuries at £27,760-£160,980. These figures concern the injury itself, not earnings or treatment costs.

Other examples include £6,000-£73,580 for arm, wrist or ankle fractures and £43,060-£219,070 for moderate head injuries. The amount for a severe head injury can vary depending on the injury and its effects. Injury severity, recovery and lasting effects shape where a case falls within a bracket.

How can negligence lead to a construction accident?

When comparing construction accident claims solicitors in the UK, consider their experience with site injury claims, how they explain evidence and fees, and how they communicate about progress. Look for clear advice on responsibility, next steps and potential charges. Ask how they investigate incidents involving several contractors and how they will keep you updated.

According to The National Archives (legislation.gov.uk), the Health and Safety at Work Act 1974 requires employers and site managers in England and Wales to provide a safe working environment. The Work at Height Regulations 2005 place duties on those in control of a construction site, according to The National Archives (legislation.gov.uk). These laws are relevant when examining unsafe access, platforms or supervision.

Negligence may involve an employer, principal contractor or another contractor. Examples include failing to address a hazard, providing unsafe equipment or giving inadequate instruction. Where several businesses share a site, an investigation may need to establish who controlled the activity and whose actions contributed to the injury.

Your employment status alone doesn’t prevent a claim. Employees, agency workers, subcontractors and self-employed workers may be eligible if another party’s negligence caused their injury. For a subcontractor, evidence about site arrangements and who supplied equipment can help identify responsibility. Independent contractors must also avoid dangerous working practices that could injure others.

Visitors may have a claim if negligence caused their injury. For example, an investigation could examine whether a visitor was exposed to falling materials or unsafe access. A witness account, visitor records and photographs can help establish what happened and who may be responsible.

Investigators may also consider a worker’s actions alongside the training, instructions and equipment provided. A solicitor experienced in construction accident claims in the UK can assess how these details affect responsibility. Before proceeding, ask for a written explanation of fees and charges, and clear information about confidentiality, your interests and updates on the claim.
Construction Accident Claims Solicitors in the UK

Are there time limits for construction accident claims?

Yes, rules differ by jurisdiction. In England and Wales, the standard deadline is three years from the accident date under the Limitation Act 1980. For construction-related illness or disease, the three-year period runs from diagnosis. Don’t assume these deadlines apply elsewhere in the UK.

For an injured child, the three-year time limit begins on their 18th birthday if no claim has already been made. A parent can bring a claim on the child’s behalf before then. These time limits make early advice important, particularly where the accident date or diagnosis date may be disputed.

Evidence can disappear quickly after a site accident. Take photographs of the hazard, machinery, scaffolding or working-at-height arrangements, and note the names and contact details of witnesses. Report the incident to your employer and seek medical attention. Keep medical records, accident reports, site records and correspondence together. Construction-site CCTV footage is routinely overwritten within 14-31 days, so act promptly to preserve relevant footage.

RIDDOR is the Reporting of Injuries, Diseases and Dangerous Occurrences Regulations 2013, according to The National Archives (legislation.gov.uk). An incident report, where one exists, may help establish what happened and when. It does not replace other evidence, such as witness accounts or medical records, which can show how the accident was caused and the injuries sustained.

Evidence gathering may continue if the responsible party disputes liability. Records of treatment and income can support a claim alongside evidence about the accident itself. Organise dates, photographs and expenses in one file, and preserve original documents and messages.

Yes. The three-year deadline described here applies to England and Wales. Scotland and Northern Ireland have different rules, so don’t assume the same deadline applies there.

Steps in the construction accident claims process

A clear sequence of steps helps workers move from an initial report to a decision on responsibility and compensation. If you’ve suffered a serious workplace injury, prioritise treatment and make an accurate record of what happened.

  1. Report and record the accident. Enter the incident in the workplace accident book, including the time, place, injury details and description. Notify the employer or site manager, and keep a copy or note of the report.
  2. Get medical attention. A medical assessment supports your recovery and creates a record of the injuries. Keep appointment details and records of treatment, especially if the injury affects work or earnings.
  3. Organise evidence. Preserve photographs, witness contact details, medical records and relevant site documents. A solicitor can assess the circumstances, identify potentially responsible parties and gather further evidence where needed.
  4. Notify the responsible party. The company or contractor connected with the accident is told about the claim and asked whether liability is accepted. On a multi-contractor site, identifying who controlled the work or hazard can take investigation.
  5. Negotiate and resolve the claim. If liability is accepted, the parties can negotiate compensation using evidence of injury and losses. Interim payments may be secured during the claim in some cases where the other party accepts liability.

If liability is disputed, the evidence may need further review, including medical evidence and input from health and safety specialists. A solicitor may prepare legal documents and represent you in court if necessary. Most building site accident claims settle before a final court hearing, although the evidence and disputed issues affect how each case progresses.

Straightforward construction accident claims can take 3-9 months to settle. After an agreement, compensation is paid 14-28 days later. For practical help setting out the steps in your case, discuss your construction injury claim.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP handles personal injury and silicosis claims, so the firm can discuss a construction injury claim with you. You can talk through how your injury, evidence and resulting losses relate to a potential claim, and what steps may apply to your circumstances.

Before the discussion, organise the essentials: a brief timeline of the accident, medical records, witness details and documents showing lost earnings or treatment costs. This provides a clearer starting point for reviewing what happened and how it affected you. Advice can help you understand the claims process and what information is needed to assess your position, while recognising that every site injury has its own circumstances and outcome.

For guidance on a construction-related personal injury claim, contact Feltons Solicitors LLP.

Take the next step with clarity

Considering a claim is also an opportunity to think about the support you need while recovering. You may want help understanding how the injury has affected your work, home life or future plans, as well as guidance on the legal process. When choosing construction accident claims solicitors in the UK, look for clear communication and advice grounded in the evidence of your situation.

Before getting in touch, note the questions you want answered and gather any documents you can access. A straightforward account of what happened and what has changed since can help start a focused discussion. The strength and value of a claim depend on its circumstances, so individual advice matters.

For a measured discussion about your circumstances and possible next steps, contact Feltons Solicitors LLP. Taking that first step can help you move forward with a clearer understanding of your options.

Frequently Asked Questions

I’m self-employed or a subcontractor, can I still claim?

Yes. Self-employed workers and subcontractors may claim if another party’s negligence caused their injury; employment status alone doesn’t rule out a claim. Keep your contract, invoices and work allocation records with your accident-related documents. These may help clarify who arranged the task, supplied equipment or controlled the work area when the incident happened.

How much compensation could I receive for a construction accident?

The amount depends on the injury’s severity, its effects and the financial losses it caused. For example, the stated general damages figure for losing the little and ring fingers is around £26,620. This relates to the injury itself; lost earnings, treatment costs or care needs are assessed separately. Keep evidence of those losses to help establish their value.

Can I claim if I was visiting the construction site?

Yes, a visitor may have a claim if negligence by a responsible party caused their injury. For example, a delivery driver hurt while crossing an unsafe work area could record where the incident happened and who was present. Keep visitor sign-in details, messages arranging the visit and any photographs, as these may help establish the circumstances.

Can my employer sack me for making a claim?

Under the Employment Rights Act 1996, dismissing or penalising an employee for making a personal injury claim is automatically unfair dismissal. Keep relevant messages, meeting notes and any written warnings if your treatment at work changes after raising a claim. Record dates and what was said, so you have a clear account of events if you need advice.

How much could I get for psychological injuries after a construction accident?

The stated Judicial College Guidelines bracket for severe psychiatric damage is £66,920 to £141,240. The injury’s severity and its impact are relevant to the general damages assessment. Evidence may include treatment records and an assessment of the psychological harm. Financial losses, such as earnings lost because of the condition, are considered separately from this bracket.

How will I be able to pay for my claim?

Some UK accident claims use a No Win No Fee agreement, which generally means no payment before the case outcome. Additional expenses may still arise, and a success fee can be calculated as a percentage of compensation, subject to legal limits. Before proceeding, read the written explanation of fees and charges carefully so you understand what you may have to pay.
Fatal industrial disease compensation claims for families

Fatal industrial disease compensation claims for families

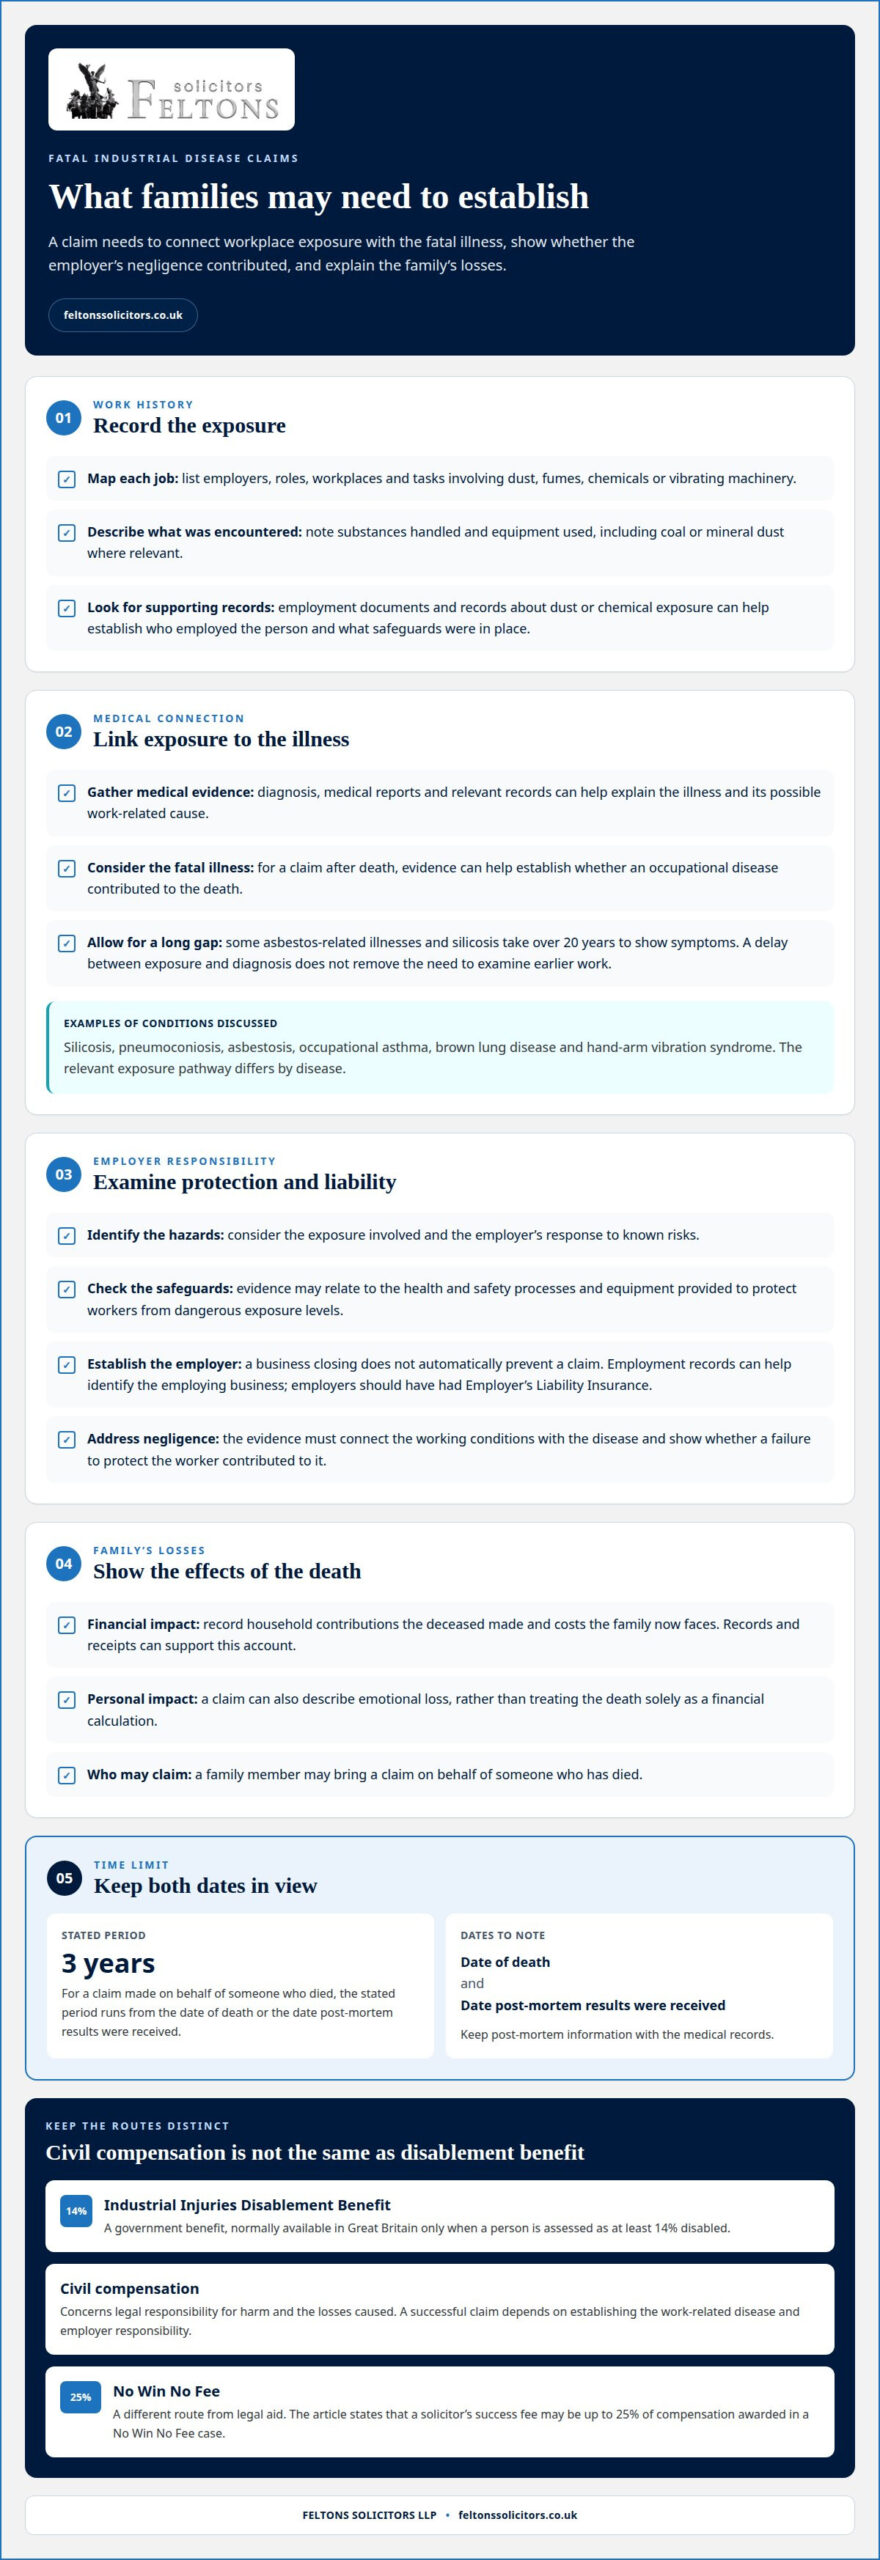
A worker’s death does not necessarily rule out a claim. Families may pursue fatal industrial disease compensation claims if workplace exposure, including coal dust, contributed to the illness that caused the death. For a claim made on behalf of someone who has died, the stated three-year time limit runs from the date of death or the date post-mortem results were received.

It can be hard to know what to do while grieving, particularly if the illness developed years after exposure or the employer has since closed. The key questions are whether the disease was work-related, who may bring a claim, and what evidence could establish responsibility and the family’s losses.

This guide explains how these claims work in the UK, including claims involving coal-dust-related lung disease. It covers who may claim, the time limit, the evidence and steps involved, and what families can expect as a claim progresses.

Key Takeaways

  • Learn who may bring a claim after a loved one’s death and when the stated three-year period begins.
  • See how workplace exposure, including coal dust, may be connected to a fatal lung disease.
  • Find out which records and evidence can help build a clearer picture of the illness and its work-related cause.
  • Understand how a compensation claim differs from Industrial Injuries Disablement Benefit, including the disability assessment threshold.

Industrial Disease Compensation Claims – How do they Work?

An industrial disease claim considers whether workplace exposure caused an illness and whether employer negligence contributed to it. Evidence must connect the working conditions with the disease and the resulting loss.

Employer health and safety responsibilities

The Health and Safety at Work Act 1974 requires UK employers to protect employees’ health at work. This includes appropriate health and safety processes and equipment to protect workers from dangerous exposure levels. Families can look at the hazards involved, the protection provided and the employer’s response to known risks. For example, records about dust or chemical exposure may help explain what safeguards were in place.

Claims against former or insolvent employers

A former employer’s closure does not automatically prevent an industrial disease claim. Employers should have had Employer’s Liability Insurance, so a claim may still be possible after a business ceases trading. If the employer is insolvent, start by identifying the employing business and gathering records of the deceased person’s work. Employment documents and medical records can help establish who employed them and what exposure they experienced.

Claims based on employer negligence

In the United Kingdom, an industrial disease claim requires evidence that the condition resulted from the employer’s negligence. This may include medical reports and information about the employer’s actions or failures. A specialist can assess how workplace exposure relates to the illness and whether suitable processes and equipment were in place. The central question is liability: whether a failure to protect the worker contributed to the disease.

Civil compensation and disablement benefit

Industrial Injuries Disablement Benefit is a government benefit, separate from civil compensation. In Great Britain, it is normally available only when a person is assessed as at least 14% disabled, according to the Department for Work and Pensions. Civil compensation instead concerns legal responsibility for harm and the losses caused. Legal aid and No Win No Fee are different routes; families can explore a No Win No Fee arrangement for solicitor help. According to the Ministry of Justice, a solicitor’s success fee may be up to 25% of compensation awarded in a No Win No Fee case.

Occupational lung disease and fatal workplace exposure

Occupational diseases can develop gradually, meaning exposure may have ended before symptoms appeared. The diagnosis and work history help link an illness to substances encountered at work.

Workplace diseases and exposures

Workplace lung diseases include silicosis, pneumoconiosis and asbestosis, all associated with underground tunnel work. Exposure to dust, fumes or chemicals can also cause respiratory conditions, skin disease or cancer. In metalworking, chrome oxide dust and Kemet fumes can cause occupational asthma. Cotton dust can cause brown lung disease through lung scarring. Vibration white finger, also known as hand-arm vibration syndrome, may be relevant if vibrating machinery was used without appropriate anti-vibration protectors. The equipment, substances and tasks involved help establish the exposure history.

Evidence of historical exposure

Build a clear work history by listing each employer, job role, workplace and task involving dust, fumes, chemicals or vibrating machinery. Note the substances handled and the equipment used, then compare those details with medical reports describing the illness. This can help show how exposure occurred, even if the worker is no longer employed there. Some asbestos-related illnesses and silicosis take over 20 years to show symptoms, so a long gap between work and diagnosis does not erase the need to examine earlier exposure.

Diseases that may qualify for compensation

Potentially relevant conditions include silicosis, pneumoconiosis, asbestosis, occupational asthma, brown lung disease and hand-arm vibration syndrome. The specific diagnosis matters: a claim needs evidence linking the illness to workplace exposure and the employer’s conduct. For a fatal claim, medical records and exposure history can help establish whether an occupational disease contributed to the death. As each disease has a different exposure pathway, distinguish, for example, coal or mineral dust from chemical fumes and machinery vibration.

Where a family is tracing a past exposure, legal guidance on occupational disease claims can help explain how the evidence fits together.

Fatal industrial disease compensation claims for families

Families may consider a civil claim if coal dust or another occupational exposure contributed to a loved one’s fatal illness. Evidence must link the exposure to the disease and resulting losses.

Who can make a claim after a death

A family member may bring a claim on behalf of someone who has died. A fatal workplace claim can set out the bereaved family’s financial and emotional losses. For example, a widow whose husband had died five years earlier asked about a claim connected to coal-dust exposure and industrial lung disease. This illustrates why families may seek advice even after time has passed, while still keeping the legal time limit in mind.

Financial and emotional losses

A claim can describe the practical and personal effects of the death. Financial evidence may include the household contributions the deceased made and costs the family now faces. Records and receipts can help explain these losses. The claim can also describe emotional loss, rather than treating the death solely as a financial calculation. A successful claim depends on establishing the work-related disease and the employer’s responsibility.

Time limits for claims after death

For a claim made on behalf of someone who died, the stated period is three years from the date of death or the date post-mortem results were received. Note both dates and keep post-mortem information with medical records. If the connection between coal dust and lung disease was recognised late, reconstructing the timeline may be harder. Record when the diagnosis and cause became known.

Civil compensation for a work-related death

Yes. Families can pursue civil compensation for a death caused by a work-related disease where evidence supports a link between occupational exposure and the fatal illness, alongside employer negligence. This differs from Industrial Injuries Disablement Benefit, which concerns assessment of disablement rather than the family’s civil claim. Dependants should distinguish an enquiry about that benefit from a civil compensation claim, which addresses liability and the losses caused by the death.

Steps in an industrial disease compensation claim

For families pursuing fatal industrial disease compensation claims, the first step is to preserve records and create a clear account of the worker’s history. Note the suspected occupational illness, workplaces, roles and substances involved. Keep medical and post-mortem papers together, and record when each document was received. This provides a useful starting point for investigating the cause of death and identifying the potentially responsible employer.

  1. Build a work history. List each employer, job role, workplace, task and known exposure. Include details such as coal dust, asbestos, chemical fumes or vibrating machinery where relevant. Add approximate employment periods if available, and note former colleagues who could describe the conditions. This chronology helps distinguish separate jobs and possible sources of exposure.
  2. Gather supporting evidence. Collect medical reports, diagnosis records, employment documents and post-mortem information. Witness accounts, photographs, messages and workplace records may clarify the conditions. Look for evidence that links the illness to specific duties, rather than relying on a diagnosis alone. Keep copies and note who supplied each item.
  3. Assess causation and responsibility. A specialist considers whether the evidence connects workplace exposure to the illness and whether employer negligence contributed. This can be difficult when symptoms appeared long after exposure or the business has closed. Records from different jobs can help identify the relevant workplace and clarify which employer’s actions need examination.
  4. Set out the family’s losses. Gather documents showing how the death affected household finances, including contributions the worker made and costs the family incurred. Describe the personal impact as well. In fatal industrial disease compensation claims, this information helps present the family’s losses alongside the evidence about illness and responsibility.

A dated file makes it easier to follow events and identify missing details. Discuss an industrial disease claim with a solicitor to consider how the available evidence may support the next steps.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP handles personal injury and silicosis claims where workplace exposure may have caused illness. If a loved one has died, the family can discuss the available evidence, suspected occupational disease and losses connected with the death. The firm also provides wills, probate and estate planning, which may be relevant to managing a deceased person’s estate. These are separate legal matters, so explain whether you need advice about a compensation claim, estate administration or both.

Before discussing the matter, gather any medical reports, employment records and post-mortem information. These give the solicitor a clearer starting point for understanding the work history and the family’s concerns.

Contact Feltons Solicitors LLP to discuss your circumstances, or visit feltonssolicitors.co.uk.

Choose a clear next step for your family

Legal advice can help your family decide what to do with the evidence and which questions to address first. For families considering fatal industrial disease compensation claims, the next step is a focused discussion of the work history, medical information and losses caused by the death. You can also raise any related legal matters that need attention as your family makes plans.

Feltons Solicitors LLP handles personal injury and silicosis claims, as well as wills, probate and estate planning. The firm also provides divorce and financial arrangements, and residential and commercial conveyancing. These are distinct matters, but a family may need advice on more than one as circumstances change.

Contact Feltons Solicitors LLP to discuss your circumstances and consider a practical way forward. A careful first conversation can help you approach the next steps with greater clarity.

Frequently Asked Questions

How much compensation will I receive?

There is no single set amount for an industrial disease claim. The assessment considers the effects of the illness and the losses supported by evidence, including how the death changed the family’s financial position. Useful records may include earnings information, household expense documents and receipts for costs linked to the illness. A solicitor can review these details and explain what losses may be included.

The employer that caused my illness has gone out of business, can I still claim?

Yes. A business closing does not automatically prevent a claim. Start by establishing the employer’s exact name and the period your relative worked there. Old payslips, contracts, pension papers and correspondence can help identify the business, even if its premises have closed. An insurer may still be relevant, so keep records that identify the employer to help trace the route for a claim.

Will I have to go to court?

Not every claim reaches a hearing. The parties may resolve a claim through settlement discussions, but court proceedings may be necessary if responsibility or the value of losses remains disputed. Before then, the evidence is gathered and the claim is presented to the party considered responsible. Keep copies of relevant records and give a clear account of the work history so the case can be assessed properly.

Am I likely to have a case to claim compensation for my occupational illness?

You may have grounds to claim if medical evidence supports an occupational illness and other evidence links it to an employer’s failure. A diagnosis alone does not establish liability. For example, a worker’s medical history can be considered alongside job records describing their duties and exposure. A solicitor can assess whether the available information supports causation, negligence and a claim for losses arising from the illness.

Can I be fired or dismissed for seeking damages against my employer for my industrial disease?

If you are concerned about how your employer may respond to a claim, keep a clear record of related communications. Employees concerned about how a claim could affect their work may wish to keep written communications about the claim or employment, including messages and letters. Keep any written communications about the claim or employment, including messages and letters, to maintain a clear record of what was said and when.

How can I be sure my illness was caused by my work?

To establish a work-related cause, compare the medical evidence with the person’s work history and exposures. Create a timeline of jobs, tasks, substances encountered, and when symptoms or diagnoses arose. Medical reports can explain the illness, while employment records, workplace documents and witness accounts may clarify the conditions. Together, this evidence can help assess whether workplace exposure caused or contributed to the disease.

Industrial asthma compensation claims for UK workers

Industrial asthma compensation claims for UK workers

A workplace asthma diagnosis can raise two separate questions: did exposure at work contribute to the condition, and might compensation or state benefits be available? In the UK, industrial asthma compensation claims generally need to be brought within three years of first knowing about the problem or of last exposure, whichever is later. Occupational asthma can develop after exposure to workplace substances, sometimes over a long period.

It’s understandable to be unsure what evidence matters, particularly if symptoms developed gradually or the employer has since closed. This guide explains occupational asthma, how medical records and workplace evidence may help link it to exposure, and what steps may matter when pursuing a claim.

It also covers tracing insurance when an employer has ceased trading and how Industrial Injuries Disablement Benefit may relate to a separate compensation claim. The overview can help you understand the issues, your options and possible next steps.

Key Takeaways

  • Occupational asthma can develop after exposure to workplace substances; consider how your work history and symptoms may be connected.
  • Medical records and workplace information can help build a clearer picture of exposure and its effects.
  • If a former employer has closed, company records and the Employers’ Liability Tracing Office may help identify its insurer.
  • Industrial Injuries Disablement Benefit and compensation are separate routes, so understand how each may apply to your circumstances.

What if my employer has ceased trading?

Yes. Workers can develop occupational asthma after leaving a job, and a former employer’s closure does not automatically prevent a claim. A claim may still be possible if evidence links the condition to workplace exposure and shows that an employer failed to take reasonable steps to protect workers.

Industrial asthma compensation claims pursued by UK workers may involve an employer’s liability insurer rather than the former business itself. UK employers are legally required to have employers’ liability insurance, and the insurer or its solicitors will handle a workplace compensation claim. The Employers’ Liability Tracing Office (ELTO) and Companies House records may help identify a former employer’s insurer.

Start by gathering employment dates, job descriptions, medical records and details of chemicals or other substances encountered at work. Safety documents, training records, incident reports and colleagues’ accounts may help show the exposure and what the employer knew. Keep evidence of when symptoms began and when a medical professional linked them to work. The usual time limit for a respiratory disease claim is three years from diagnosis by a medical professional or from the victim’s death.

Employers should assess risks from hazardous substances, provide suitable protective equipment and maintain workplace ventilation. The Control of Substances Hazardous to Health (COSHH) Regulations 2002 are relevant to occupational asthma claims, according to the UK legislation register (legislation.gov.uk). COSHH information and training duties may also help show what workers were told about asthma hazards.

Former employees may claim if evidence supports a link between their illness and past work. Contractors or subcontractors may also have a route if another party was responsible for their health and safety and they can show they did not control their working environment. A self-employed person solely responsible for that environment generally cannot claim against an employer on that basis.

In England, Wales, Scotland and Northern Ireland, begin by documenting exposure and obtaining relevant medical evidence, then identify the responsible employer or party and insurer. The legal process can depend on where the claim is brought. If a family member has died, a claim must be brought within three years of the date of death, according to the UK legislation register (legislation.gov.uk).

What is occupational asthma?

Occupational asthma develops when workplace exposure causes asthma, sometimes after a few weeks or many years. There is no single fixed compensation amount: assessment considers the condition’s severity, its effect on daily life and work, and resulting financial losses.

Workplace causes and exposures

Workplace substances may trigger allergic or irritant-induced asthma. Examples include dust, lime, chalk, sand, silica, soot, plaster and flour. With allergic asthma, exposure can prompt the body to react to a substance; irritant-induced asthma follows exposure to substances that irritate the airways. The timing and pattern of symptoms, alongside the substances present at work, can help clarify a possible connection.

Asthma caused or aggravated by work

Occupational asthma is caused by workplace exposure, while work-related aggravation means an existing asthma condition worsens at work. These are different links between a job and breathing symptoms. Consider whether asthma began after exposure or whether symptoms existed before and became more troublesome during particular tasks or shifts. Symptom patterns and exposure history can help distinguish the two.

Industries linked to occupational asthma

Occupational asthma is associated with work involving airborne allergens and irritants, rather than one specific job title. Dust and flour, for example, may be present in different working environments; silica, plaster, lime and soot are other relevant substances. Up to 3,000 people in the UK are affected each year. Record the tasks performed, materials handled and when symptoms occur, as these details can help identify workplace exposure.

Where work-related exposure may have caused or aggravated asthma, legal support for a workplace injury claim can help you consider the next steps.

Industrial asthma compensation claims for UK workers

Medical evidence linking asthma to workplace exposure

Medical evidence can help link asthma symptoms to a particular workplace exposure. A useful record combines clinical findings with a clear timeline of symptoms, tasks and substances encountered.

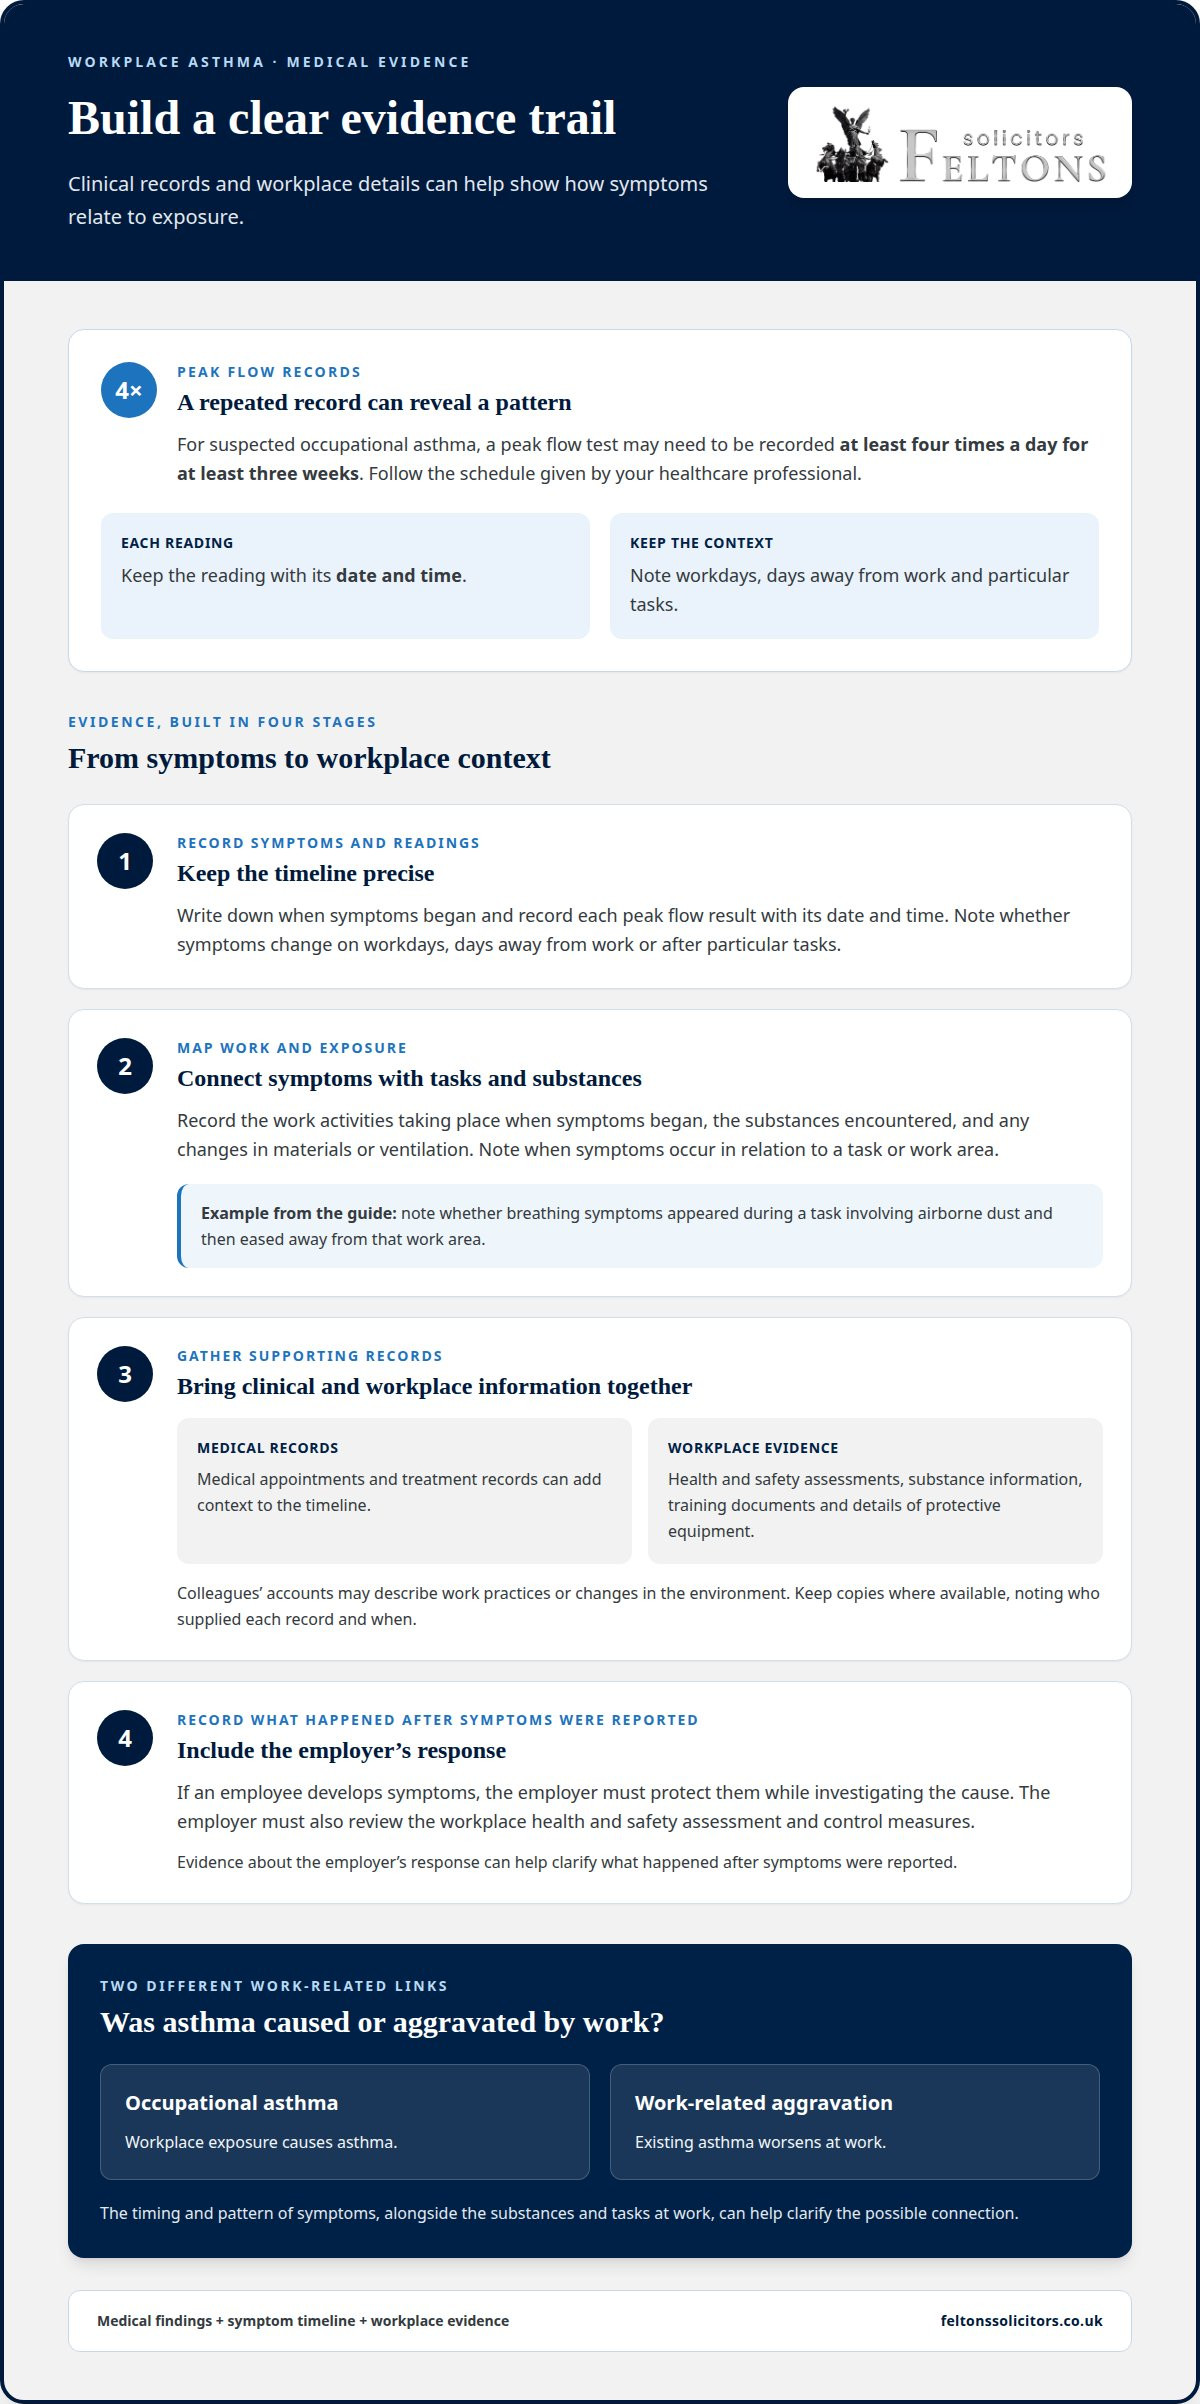
For suspected occupational asthma, a peak flow test may need to be recorded at least four times a day for at least three weeks. Follow the schedule given by your healthcare professional, and keep each reading with its date and time. Note whether symptoms change on workdays, days away from work or after particular tasks.

Build an exposure timeline alongside the test results. Record when symptoms began, what work activities were taking place, and any changes in materials or ventilation. For example, note whether breathing symptoms appeared during a task involving airborne dust and then eased away from that work area. Medical appointments and treatment records can add context.

Workplace evidence can help explain the exposure pattern. Relevant records may include health and safety assessments, substance information, training documents and details of protective equipment. Colleagues’ accounts can also describe work practices or changes in the environment. Keep copies where available, noting who supplied each record and when.

If an employee develops symptoms, the employer must protect them while investigating the cause. The employer must also review the workplace health and safety assessment and control measures. Evidence about the employer’s response can clarify what happened after symptoms were reported.

The Equality Act 2010 requires an employer to make reasonable adjustments for an employee with occupational asthma, according to the UK legislation register (legislation.gov.uk). Adjustments should address the employee’s circumstances and may relate to their duties or exposure. Keep written records of reported symptoms, discussions and any changes made at work.

Arrange the evidence in date order, from early symptoms through testing, workplace reports and treatment. This helps present a coherent account of how symptoms relate to exposure, rather than relying on one isolated reading or recollection.

State benefits and industrial disease compensation

Industrial Injuries Disablement Benefit (IIDB) and a workplace compensation claim are separate routes. IIDB may be available to people with occupational asthma, and the amount depends on how much their health has been affected. Compensation, by contrast, concerns whether a party responsible for workplace safety caused the illness by failing to protect workers. Each route has its own purpose and assessment.

Apply for IIDB as soon as possible to avoid losing benefits. A diagnosis of occupational asthma is relevant, but the benefit amount relates to the effect on your health. Keep medical records describing symptoms and treatment together with evidence of how breathing difficulties affect everyday activities. This information helps show the condition’s impact.

A compensation claim focuses on the connection between workplace exposure, the employer’s actions and the resulting disease. Evidence may include medical records, employment history and details of substances encountered at work. For example, records showing exposure to a hazardous substance alongside medical evidence linking symptoms to it can help explain the basis of a claim. The employer’s liability insurer or its solicitors handle a claim brought against the employer.

Keep the two processes organised separately. Note when you applied for IIDB, retain correspondence about the benefit, and keep compensation documents with your employment and medical records. Don’t assume that applying for one route automatically starts the other. An IIDB application addresses state support; a compensation claim addresses responsibility for workplace harm. Both may be relevant after an occupational asthma diagnosis, but each has its own evidence and purpose.

  • Record the diagnosis and its effect on your health.
  • Apply for IIDB promptly and retain the application correspondence.
  • Organise exposure evidence separately for a compensation claim.

For help considering a workplace injury claim alongside your evidence, discuss your legal options.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP handles Personal Injury and Silicosis Claims, making its personal injury service a relevant next step if you are considering a claim about workplace harm. Once you have gathered medical records and information about your exposure, legal advice can help you understand how the evidence may support a claim and what issues need attention.

This section concerns workplace illness, rather than divorce or financial arrangements. Feltons also handles those matters, alongside Wills, Probate, and Estate Planning and Residential and Commercial Conveyancing. For an asthma-related claim, focus your discussion on the workplace exposure, diagnosis and resulting impact, so the legal issues can be considered in context.

To discuss your circumstances, contact Feltons Solicitors LLP or visit feltonssolicitors.co.uk.

Take the next step with clarity

Deciding what to do after a workplace illness can feel like another burden while managing your health. A focused conversation can help you identify the questions that matter in your circumstances and consider a practical way forward. You don’t need to have every detail resolved before seeking legal guidance.

If you’re considering industrial asthma compensation claims in the UK, think about what you most need help understanding: whether your work history supports a claim, how the illness has affected your life, or what pursuing a claim may involve. Setting out your main concern gives the discussion a practical starting point and keeps the focus on your priorities.

Feltons Solicitors LLP handles Personal Injury and Silicosis Claims. For guidance about your situation, contact Feltons Solicitors LLP about your claim. Taking an informed next step can help you approach the decision with greater confidence.

Frequently Asked Questions

Who will pay the compensation?

A successful workplace compensation claim is generally handled through the employer’s liability insurer. The insurer or its solicitors deal with the claim on the employer’s behalf, so you’re not usually negotiating payment directly with an individual manager. The amount and payment arrangements depend on how the claim is resolved. Keep letters about any settlement or payment with your medical and employment records.

Will my case go to court?

Only a small percentage of industrial disease claims proceed to trial. A court hearing is therefore not the usual outcome, although this depends on whether responsibility and the claim’s value can be agreed. Keep copies of important documents and respond carefully to requests for information. If court proceedings are required, your legal representative can explain the steps and what your involvement will entail.

Can I make a claim for compensation if I’m self-employed, or a contractor?

Contractors and subcontractors may have a claim if another party was responsible for their health and safety and they can show they did not control their working environment. By contrast, someone who was self-employed and solely responsible for that environment generally cannot claim against an employer on that basis. Clarify who controlled the site, equipment and safety arrangements, and preserve any contracts or work instructions.

How much will it cost to fund my claim?

Funding costs depend on the agreement used for the claim. Funding arrangements vary, so check your agreement to understand whether you may need to pay costs if the claim does not succeed. If successful, a portion of compensation is set aside for court costs and related fees. Read the funding agreement carefully to understand what may be deducted, which expenses it covers and what happens if the claim does not succeed.

My employer has gone out of business, can I still claim?

Yes, an employer’s closure does not automatically prevent a claim. The Employers’ Liability Tracing Office and Companies House records may help identify the former employer’s insurer. Gather the employer’s exact name, trading names and employment records, as these details can help distinguish the relevant business from similarly named companies. Insurance may provide a route for pursuing a claim after the business has ceased trading.

What are the time limits on making a claim?

For a respiratory disease claim, the usual limit is three years from diagnosis by a medical professional or the victim’s death. For industrial disease claims, the limit may run from knowledge of the condition or last exposure, whichever is later. A deceased family member’s claim must be brought within three years of death, according to the UK legislation register (legislation.gov.uk). Record diagnosis and exposure dates promptly.