International Prenuptial Agreement Solicitors UK: A Guide for Global Couples in 2026

International Prenuptial Agreement Solicitors UK: A Guide for Global Couples in 2026

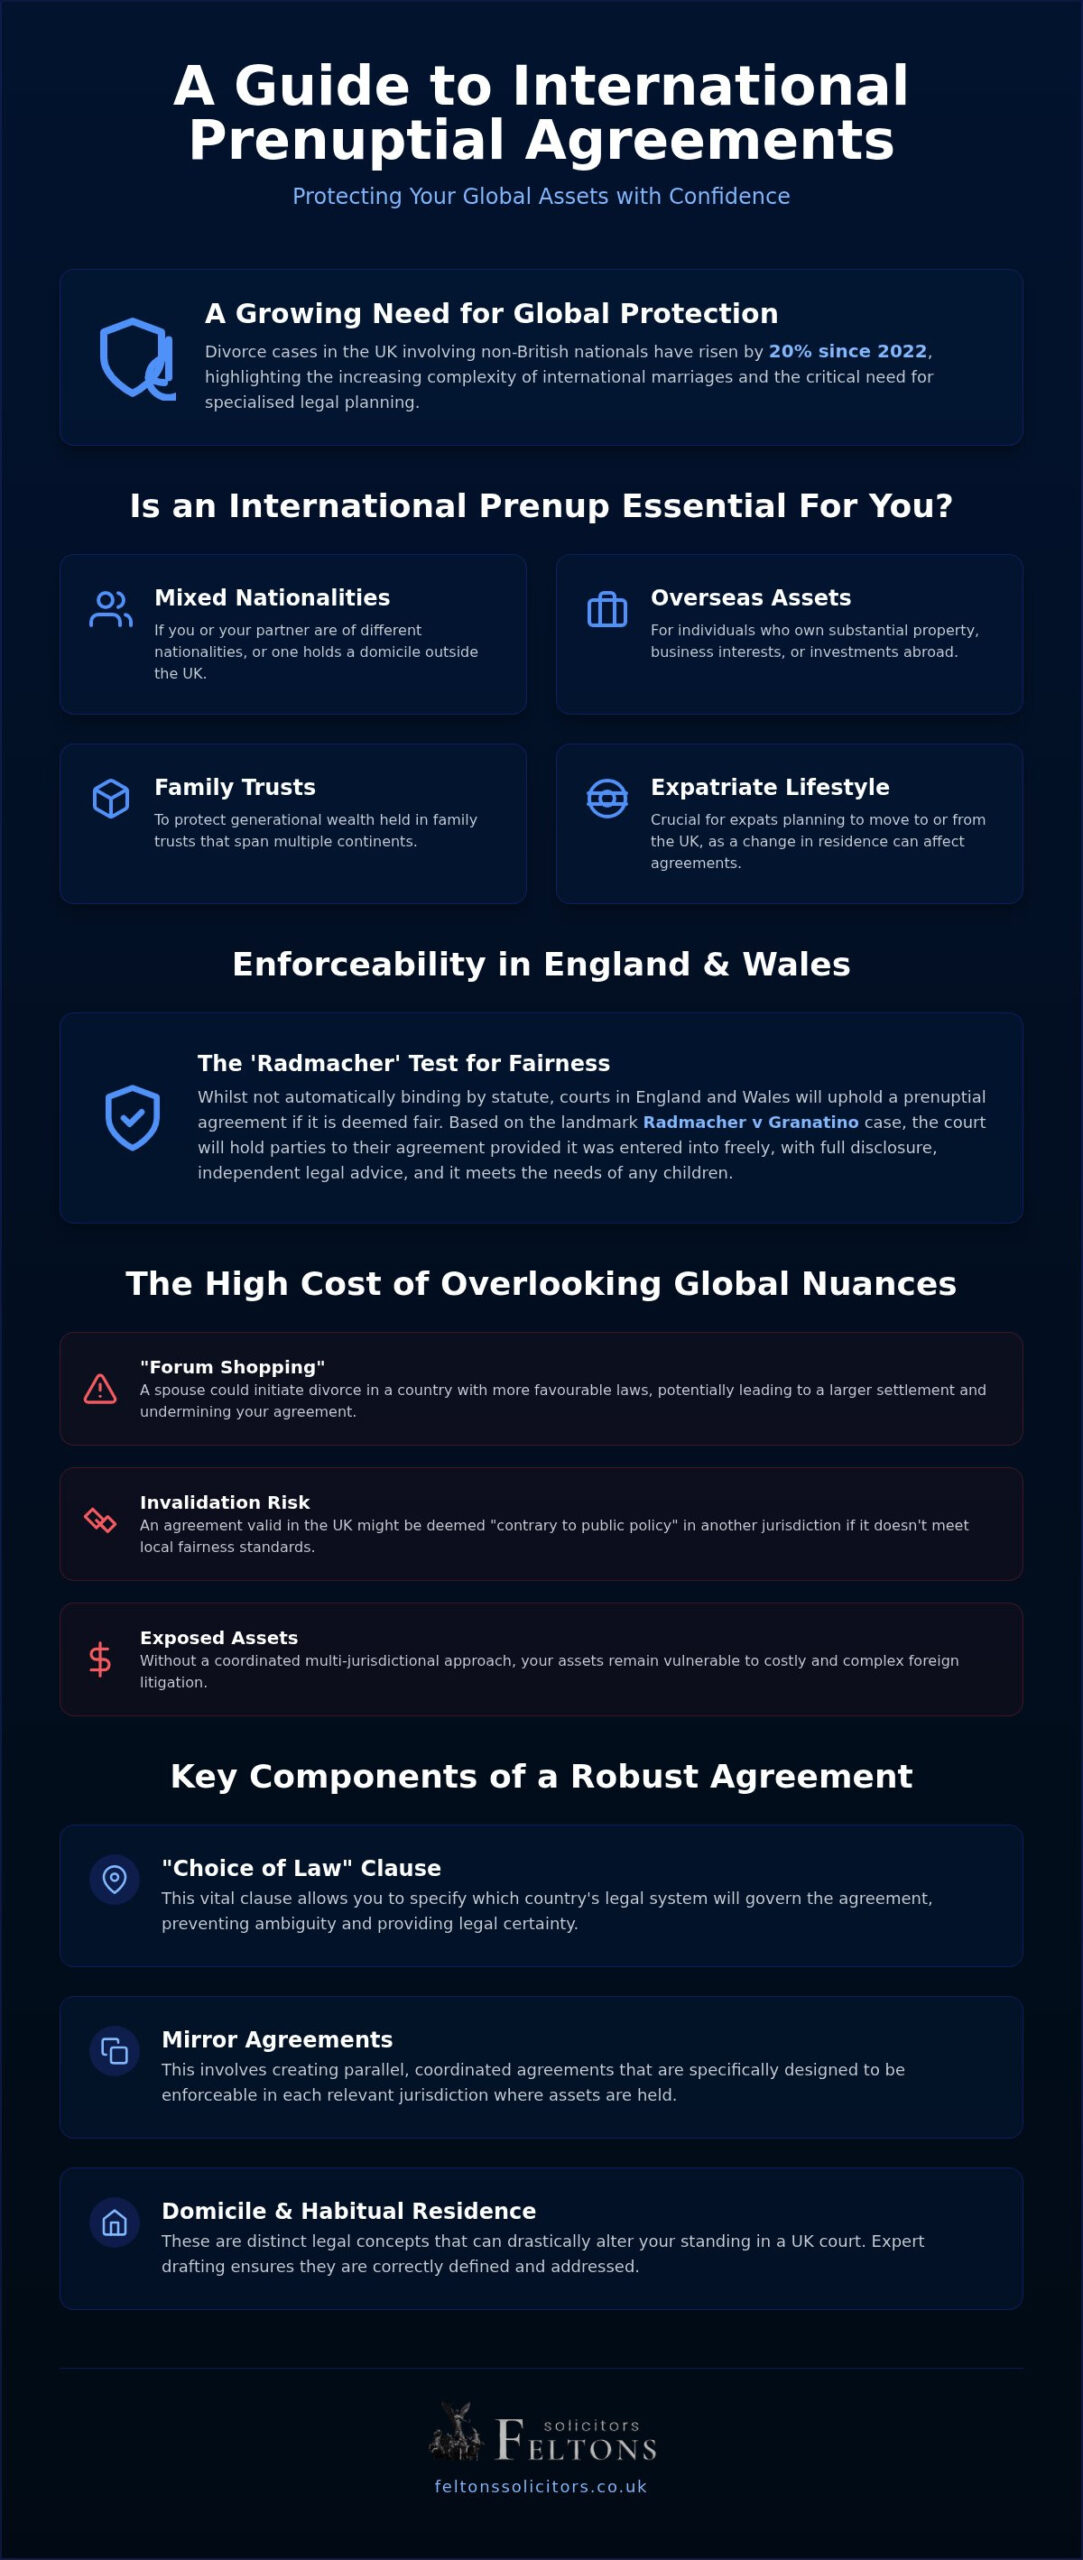
Did you know that divorce cases involving non-British nationals in the UK have risen by 20% since 2022? For couples whose lives, careers, and assets span multiple borders, the excitement of marriage often brings a unique set of logistical anxieties. You might worry about how a property in one country or a business in another would be treated under different legal systems, or feel overwhelmed by the thought of coordinating foreign lawyers. Working with specialist international prenuptial agreement solicitors uk is a pragmatic step to resolve these concerns, ensuring your financial arrangements remain predictable and secure.

This guide provides the expert insight you need to protect your global footprint with confidence. We’ll examine the 2026 proposals for Qualifying Nuptial Agreements and the enduring significance of the Radmacher v Granatino ruling. From understanding jurisdictional nuances to the practicalities of mirror agreements, you’ll learn how to establish a financial foundation that’s both discreet and dependable. Our aim is to provide you with the certainty that your future is managed with the high level of care and professional integrity your situation demands.

Key Takeaways

  • Understand the 2026 legal framework in England and Wales, including how the courts apply the Radmacher v Granatino principles to international marriages.
  • Learn why engaging specialist international prenuptial agreement solicitors uk is vital for coordinating “mirror agreements” that are enforceable across multiple jurisdictions.
  • Gain clarity on how “Choice of Law” clauses and your “Domicile” status directly impact the protection of your global property and inheritance.
  • Discover a methodical, step-by-step drafting process that ensures all foreign legal requirements are met through seamless coordination with overseas experts.
  • Establish a legally robust financial foundation that provides long-term certainty for your assets whilst prioritising discretion and personal rapport.

What is an International Prenuptial Agreement and Why is it Essential?

An international prenuptial agreement is a bespoke legal contract designed for couples whose lives and assets aren’t confined to a single country. When you’re managing a global lifestyle, a standard domestic agreement often falls short because it lacks the specific jurisdictional clauses required to protect properties, trusts, or business interests located across different borders. An international prenuptial agreement is a strategic tool for cross-border asset protection.

Standard UK agreements frequently fail to safeguard overseas property or inheritance because they don’t account for the unique “form” requirements of foreign courts. For instance, a court in France or Dubai might ignore a basic English document if it hasn’t been executed in a specific way or translated correctly. This is where What is a Prenuptial Agreement? becomes a more complex question, as the document must act as a bridge between different legal systems. Without this coordination, you risk your agreement being dismissed precisely when you need it most.

A critical component of these documents is the “Choice of Law” clause. This allows you to specify which country’s legal system should govern the agreement. Without this, you leave your future to the chance of where you happen to be living if the marriage ends. Domicile and habitual residence are distinct legal concepts that can drastically alter your standing in a UK court. Engaging experienced international prenuptial agreement solicitors uk ensures these clauses are drafted with precision, reflecting the current 2026 legal landscape and providing a calm, steady foundation for your marriage.

Who Needs an International Prenup?

Not every couple requires an international approach, but for those with a global footprint, it’s a necessity. You should consider this if you or your partner hold different nationalities or maintain a domicile outside the UK. It’s equally vital for individuals who own substantial property, business interests, or family trusts abroad. Expats planning a move to or from the United Kingdom must also consider how their change in residence affects previous agreements. Identifying these needs early allows international prenuptial agreement solicitors uk to coordinate a robust strategy before the wedding date.

The Risks of Overlooking Jurisdictional Nuances

Ignoring international nuances creates significant legal vulnerability whilst leaving your assets exposed to foreign litigation. One major risk is “forum shopping,” where a spouse might attempt to start divorce proceedings in the country most likely to grant them a larger settlement. Additionally, an agreement drafted in the UK could be deemed “contrary to public policy” in another jurisdiction if it doesn’t meet local fairness standards. For those protecting family wealth that spans generations and continents, these oversights can be incredibly costly. Expert advice on divorce and financial arrangements helps mitigate these risks by providing a coordinated, multi-country strategy.

The Supreme Court decision in Radmacher v Granatino remains the cornerstone of Enforceability in England and Wales as we move through 2026. Whilst prenuptial agreements aren’t yet automatically binding under statute, the courts will hold parties to their bargain if specific criteria are met. The judiciary’s approach is one of quiet respect for autonomy. They’ll rarely interfere with a well-drafted agreement unless it fails to meet the basic needs of a spouse or any children involved. It’s a delicate balance between personal freedom and judicial protection.

Agreements drafted under foreign laws present a unique challenge. English courts won’t simply rubber-stamp a document just because it’s valid in New York or Paris. Instead, they’ll scrutinise whether the process aligned with British standards of fairness. This makes the involvement of international prenuptial agreement solicitors uk essential. They ensure that your multi-jurisdictional strategy doesn’t inadvertently fall foul of local judicial discretion, providing a steady hand through complex cross-border requirements.

The Radmacher Criteria Explained

To carry “decisive weight,” an agreement must satisfy three primary pillars. First, it must be freely entered into. This means no last-minute pressure; ideally, the document should be finalised at least 28 days before the wedding. Second, both parties must have a full appreciation of the implications. This is only possible if each person receives independent legal advice from qualified solicitors. Finally, the agreement must be fair. A court won’t enforce a contract that leaves one party in significant financial hardship whilst the other retains vast wealth. It’s about pragmatic protection, not total exclusion of support.

Financial Disclosure Across Borders

A robust agreement relies on absolute transparency. You must provide a comprehensive schedule of all global assets, from Swiss bank accounts to Californian real estate. Valuing these interests requires a methodical approach, particularly regarding overseas entity beneficial owner registration and complex corporate structures. If you fail to disclose a material asset, the entire agreement could be set aside. This level of detail provides the certainty you need. If you’re unsure how to categorise your international holdings, seeking a discreet consultation with a specialist can help clarify your position and protect your interests.

Distinguishing between domicile and habitual residence is fundamental to your legal standing in the UK. Your domicile is generally where you consider your permanent home, whilst habitual residence is where you actually live and work. These statuses dictate which court has the power to hear a case. A “Choice of Law” clause allows you to specify which country’s rules should apply to the division of your assets, but it isn’t a silver bullet. English courts often prioritise local law if the parties are habitually resident here, especially if applying a foreign law would result in an outcome they deem unfair. This nuance is why consulting international prenuptial agreement solicitors uk is vital; they help you understand The Legal Framework for 2026 and how it impacts your specific circumstances.

A robust protection strategy doesn’t end with the marriage contract. You must integrate these arrangements with broader estate planning to ensure your global legacy remains intact across generations. Co-ordinating your prenup with your will and any existing trusts provides a seamless shield for your wealth, regardless of where your life takes you. It’s about creating a methodical, all-encompassing plan that respects both your current needs and your long-term intentions.

Jurisdiction Shopping and Forum Conveniens

Jurisdiction shopping occurs when one party rushes to file for divorce in a country that offers a more generous financial settlement. Courts use the principle of “forum conveniens” to decide the most appropriate venue for the dispute to be heard. In complex international cases, we may use anti-suit injunctions to prevent a spouse from pursuing litigation in a country that ignores the autonomy of prenuptial contracts. Strategic positioning is key. You want to select a jurisdiction that respects your agreement’s intent whilst providing a predictable, steady outcome for both parties.

Protecting Specific International Assets

Assets in civil law countries, such as France or Spain, are often governed by different marital regimes compared to the common law approach in the UK. For offshore trusts or international shareholdings, we often recommend the use of mirror agreements. These are secondary contracts drafted by local experts in the asset’s location, ensuring the protections in your primary agreement are recognised and enforced locally. Working with international prenuptial agreement solicitors uk allows for this co-ordinated, multi-jurisdictional oversight, ensuring no high-value asset is left vulnerable to foreign legal quirks.
International Prenuptial Agreement Solicitors UK: A Guide for Global Couples in 2026

The drafting process for a cross-border marriage requires a methodical approach that respects the legal nuances of every territory involved. It isn’t a single document but a coordinated strategy. Working with international prenuptial agreement solicitors uk allows you to navigate this journey with quiet confidence, knowing every detail is managed. The process typically follows five essential steps:

  • Step 1: Identify all relevant jurisdictions based on nationality, domicile, and asset location.
  • Step 2: Appoint specialist solicitors in each relevant country to ensure local compliance.
  • Step 3: Draft the primary agreement in the country where you intend to reside.
  • Step 4: Create “Mirror Agreements” that translate the intent into local legal formats.
  • Step 5: Execute and register the documents according to local formalities, such as Notarisation.

What are Mirror Agreements?

Mirror agreements are identical or complementary contracts signed in different countries to ensure your intentions are recognised globally. Relying on a single multi-jurisdictional document is risky. Foreign courts often require specific phrasing or execution methods that an English document might lack. A mirror agreement is safer because it’s drafted by a local expert to meet local standards whilst remaining consistent with your primary English agreement. This dual-layered approach provides the high-standard protection discerning couples require for their global assets.

Working with Foreign Counsel

Your UK solicitor acts as the “lead architect” of your international strategy, overseeing the entire project to ensure nothing is lost in translation. We coordinate with trusted international law firms to provide a seamless service, managing the timeline and costs of multi-jurisdictional drafting on your behalf. This boutique level of care ensures that while the technical legal work is complex, your experience remains straightforward and supportive. It’s about providing a calm, steady presence throughout the coordination of foreign legal advice. If you’re ready to secure your global assets, you can contact our team for a discreet consultation regarding your international financial arrangements.

Securing Your Future with Feltons Solicitors: Discreet International Expertise

Choosing the right legal partner is a decision that balances technical proficiency with personal rapport. At Feltons Solicitors LLP, we provide a sophisticated, boutique service tailored specifically for individuals with global interests. Our worldly experience allows us to manage international-scale matters with a “people-first” philosophy, ensuring that the human impact of your legal arrangements is never overlooked. As specialist international prenuptial agreement solicitors uk, we offer a calm, steady presence during what can often be a complex or stressful period of preparation.

We possess deep expertise in divorce and financial arrangements with a dedicated international focus. Our approach is rooted in pragmatic, discreet advice that prioritises your privacy and future security. We understand that your assets aren’t just numbers on a balance sheet; they represent your hard work, your heritage, and your family’s future legacy. By positioning ourselves as your sophisticated guide, we help you manage the nuances of cross-border law with quiet confidence and traditional professional integrity.

Why a Boutique Firm Suits International Prenups

Discerning couples often find that a boutique firm offers significant advantages over larger, more impersonal practices. You’ll benefit from greater privacy and direct access to senior partners who truly understand the intricacies of your situation. We avoid “off-the-shelf” legal templates, opting instead for bespoke drafting that reflects your unique global footprint. Our streamlined structure also allows us to move quickly and efficiently across different time zones, ensuring that your international strategy remains on track regardless of where your assets or partners are located.

Next Steps: Your Consultation

The first step in securing your financial future is a confidential discussion to review your circumstances. Before our initial meeting, it’s helpful to prepare a comprehensive list of your global assets, including property, business interests, and any existing trusts. We’ll then begin the methodical process of cross-border legal coordination, identifying necessary jurisdictions and liaising with foreign counsel on your behalf. This structured approach provides the high-end reliability you expect from international prenuptial agreement solicitors uk. We invite you to contact Feltons Solicitors LLP for a confidential discussion, where we can begin crafting a robust agreement that protects your interests across every border.

Securing Your Global Legacy for 2026 and Beyond

Navigating the complexities of cross-border marriage requires more than a simple contract. It demands a coordinated strategy that respects the legal nuances of every country where you hold assets. By prioritising procedural fairness and full financial disclosure, you ensure your agreement carries the necessary weight in British courts. Working with expert international prenuptial agreement solicitors uk provides the high-end reliability and discreet guidance essential for managing high-value, multi-jurisdictional arrangements.

We’ve explored how mirror agreements and precise choice of law clauses act as a shield for your wealth, whilst the 2026 legal landscape offers new avenues for certainty. Feltons Solicitors offers a boutique service that combines traditional integrity with modern efficiency, focusing on a personal connection that larger firms often lack. Our specialists provide pragmatic, expert advice for high-net-worth individuals facing international-scale matters with a people-first philosophy.

If you’re ready to establish a robust financial foundation, contact Feltons Solicitors for discreet international prenuptial advice. Our pragmatic approach ensures your global footprint is protected with the care and expertise it deserves. Your future stability starts with a single, confidential conversation.

Frequently Asked Questions

Is an international prenuptial agreement legally binding in the UK?

In England and Wales, prenuptial agreements aren’t yet strictly binding by law, but they carry significant weight in court. Following the Radmacher v Granatino ruling, judges will typically uphold an agreement if it was freely entered into with full financial disclosure. The 2026 proposals for Qualifying Nuptial Agreements (QNAs) aim to provide even greater certainty. Engaging international prenuptial agreement solicitors uk ensures your document meets these evolving standards of fairness and procedural integrity.

Can I include a choice of law clause in my prenuptial agreement?

You can include a choice of law clause to specify which country’s legal system should govern your assets. This is a standard feature in international agreements drafted by specialists. However, English courts retain the discretion to apply English law if you are habitually resident in the UK or if the foreign law produces an outcome deemed unfair. It’s a complex area where pragmatic, expert advice is essential to ensure your intentions are respected across borders.

What happens if we sign a prenup abroad and then move to the UK?

An agreement signed abroad isn’t automatically enforceable in the UK just because it’s valid in its country of origin. If you relocate to the UK, the English courts will scrutinise the document against local standards of fairness and disclosure. To protect your interests, it’s often advisable to have your original agreement reviewed by international prenuptial agreement solicitors uk. They may suggest a mirror agreement or a postnuptial contract to ensure your financial arrangements remain robust under English law.

Do both parties need their own solicitor for an international prenup?

Yes, it’s essential for both parties to receive independent legal advice from separate solicitors. This is a fundamental requirement for an agreement to be considered fair and enforceable in the UK courts. If one party doesn’t have their own representation, the court may conclude they didn’t fully appreciate the implications of the contract. This boutique level of care ensures that both partners are supported and that the final agreement is legally sound in every jurisdiction.

How much does an international prenuptial agreement cost in the UK?

The cost of an international prenuptial agreement varies significantly based on the complexity of your global assets and the number of jurisdictions involved. Factors such as coordinating with foreign counsel, drafting mirror agreements, and the requirement for independent legal advice for both parties will influence the total investment. Because every situation is unique, we provide a tailored approach that reflects your specific needs. We recommend a discreet consultation to discuss the scope of your requirements and obtain a clear fee estimate.

How long before the wedding should we finalise the international prenup?

You should aim to finalise and sign your agreement at least 28 days before your wedding date. This timeframe is a key pillar of enforceability in the UK, as it demonstrates that neither party was under undue pressure or time constraints. Because international agreements involve coordinating with overseas experts and translating complex documents, you should ideally begin the process several months in advance. This steady, methodical approach ensures all legal formalities are met without unnecessary stress.

Can an international prenup protect assets I haven’t acquired yet?

Yes, a well-drafted agreement can protect future assets, including expected inheritances, future business interests, or property you haven’t yet acquired. This is particularly important for high-net-worth individuals who anticipate significant growth in their global wealth. By specifying how these future acquisitions should be treated, you create long-term financial certainty. Our boutique service focuses on bespoke drafting, ensuring your agreement is flexible enough to accommodate your evolving international footprint whilst maintaining its legal integrity.

What is the difference between a prenuptial and a postnuptial agreement internationally?

The primary difference is timing; a prenuptial agreement is signed before the wedding, whilst a postnuptial agreement is executed during the marriage. Internationally, both documents are treated with similar weight by English courts, provided they meet the same criteria for fairness and disclosure. Postnups are often used by couples who move to the UK after marrying abroad or whose financial circumstances change significantly. Both serve as pragmatic tools for asset protection, providing a calm, steady foundation for your shared future.
Personal Injury Trust Solicitors: Protecting Your Compensation and Future

Personal Injury Trust Solicitors: Protecting Your Compensation and Future

What if the very compensation intended to secure your future actually placed your current financial stability at risk? Receiving a settlement after a life-changing injury should be a moment of relief, yet for many, it brings a fresh wave of anxiety regarding Universal Credit and other means-tested support. You’ve fought hard for this redress, and the fear that it might be depleted by care costs or lead to a total loss of benefits is a heavy burden to carry.

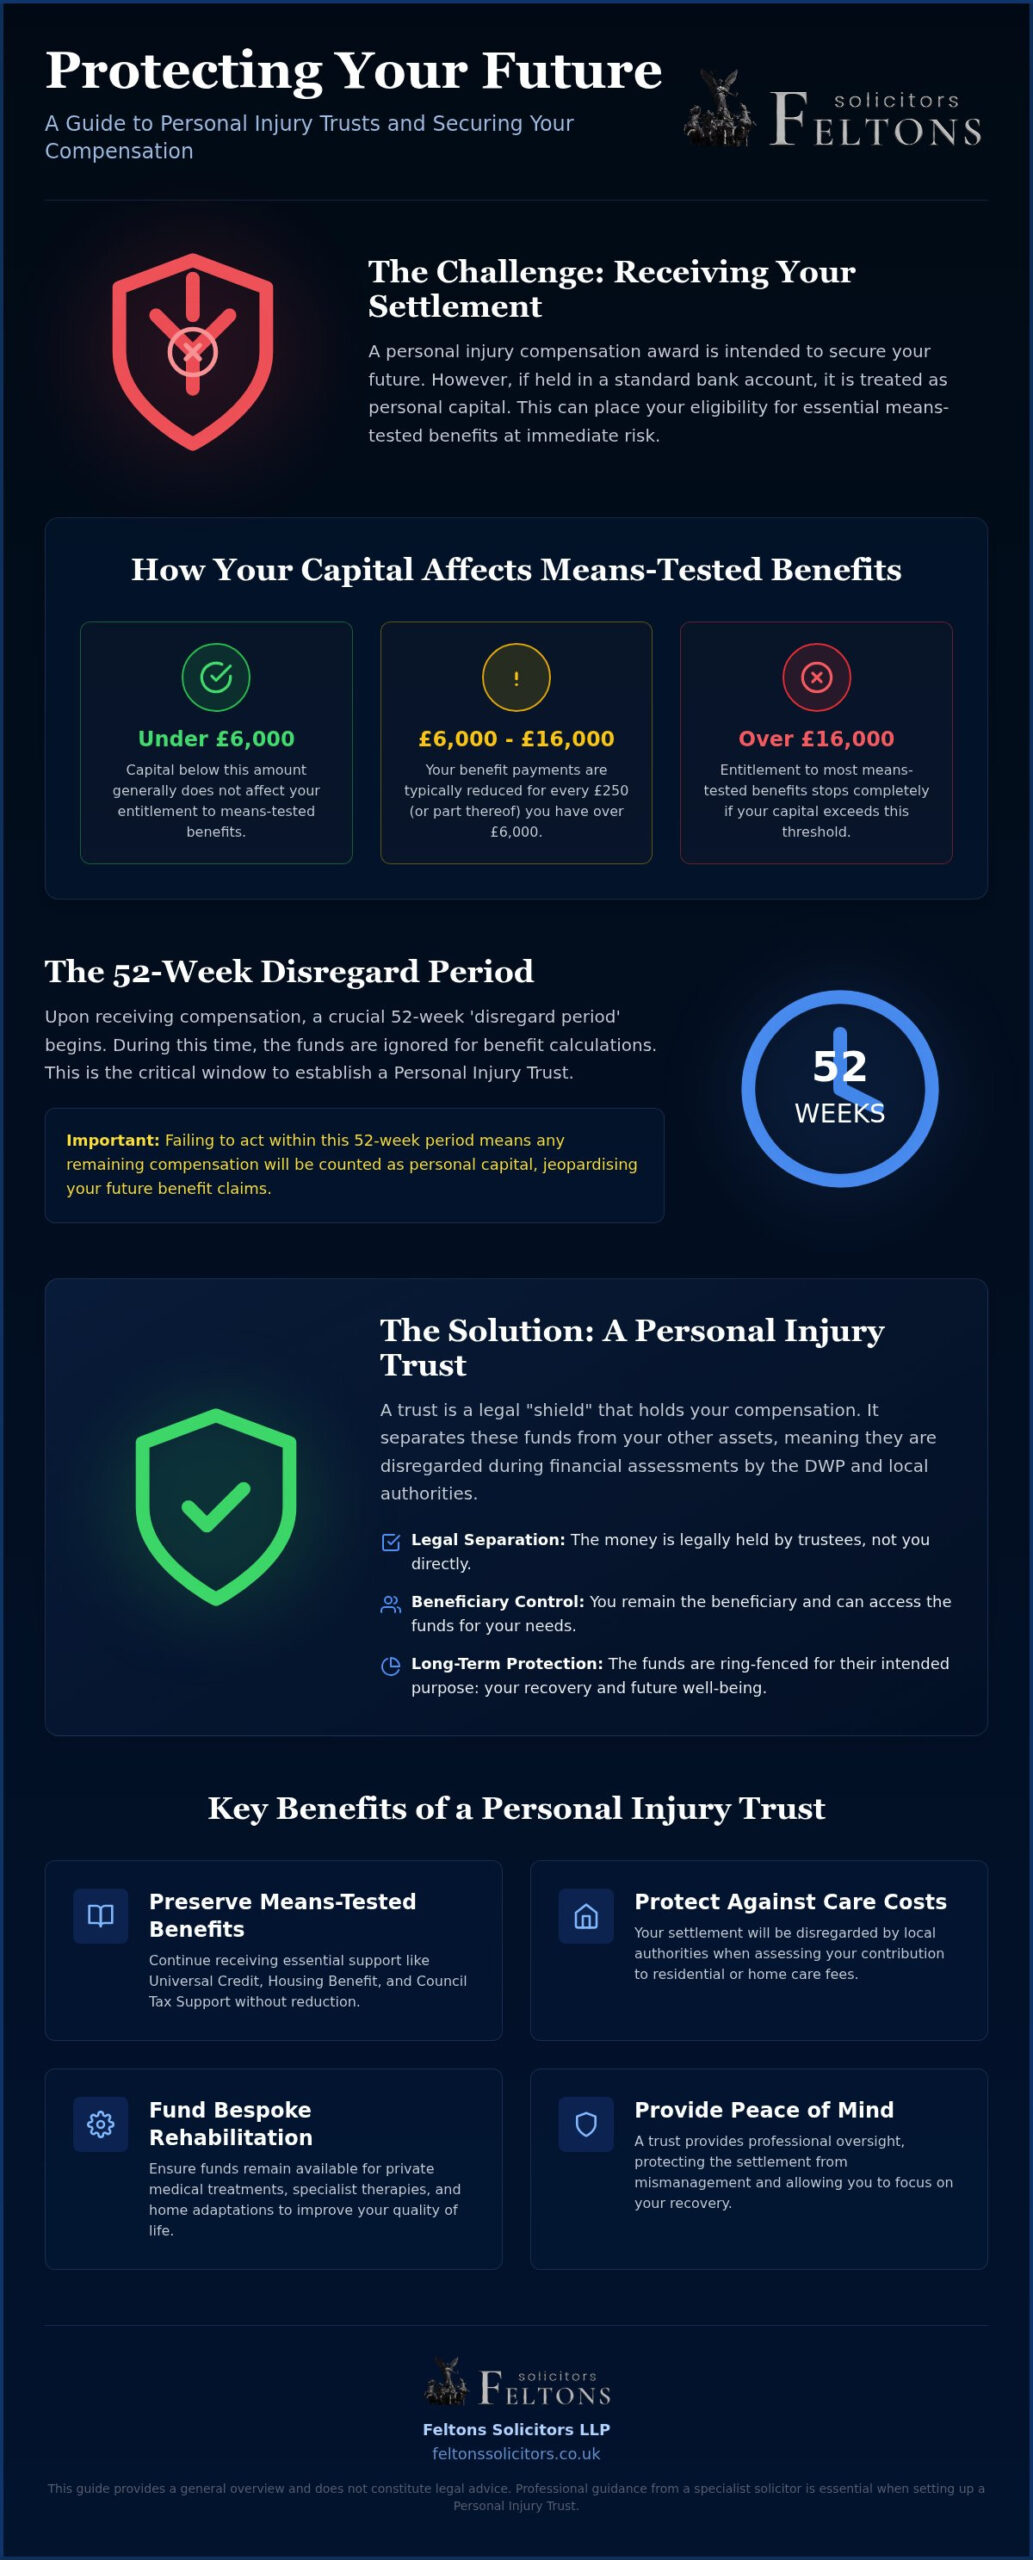
Specialist personal injury trust solicitors provide a sophisticated shield, ensuring your award is legally ring-fenced to protect your eligibility for state assistance whilst securing funds for your long-term rehabilitation. We understand that the transition from litigation to recovery is complex, and our role is to offer a calm, steady hand during this period. This guide explains how a tailored trust structure preserves your capital against the £16,000 threshold, the importance of the initial 52-week disregard period, and how a discreet legal partner simplifies the requirements of the Trust Registration Service to ensure your focus remains entirely on your recovery.

Key Takeaways

  • Learn how a personal injury trust functions as a legal shield, ring-fencing your settlement to ensure your compensation is preserved for your specific needs.
  • Understand the vital role of personal injury trust solicitors in maintaining your eligibility for means-tested benefits, such as Universal Credit, after receiving an award.
  • Discover how to protect your financial future from local authority care assessments, ensuring funds remain available for bespoke rehabilitation and private medical care.
  • Recognise why a partner-led, boutique legal service offers the discreet, high-standard expertise required for complex litigation and sensitive asset protection.
  • Gain clarity on the essential timing for establishing a trust, particularly the importance of acting before the first interim payment is received.

What is a Personal Injury Trust and Why Do You Need One?

A personal injury trust is a formal legal mechanism designed specifically to hold funds awarded as compensation following an accident or illness. It acts as a protective shield, separating your settlement from your personal capital. This distinction is vital because, without it, the Department for Work and Pensions (DWP) treats those funds as readily available assets. Engaging personal injury trust solicitors ensures this separation is legally robust. Understanding What is a Personal Injury Trust? is the first step toward long-term financial security.

Placing your settlement into a standard current or savings account is a frequent mistake. Once the money enters your personal account, it’s consolidated with your other savings. This can immediately push you over the capital limits required for state support. A trust ensures these funds are ring-fenced, meaning they’re disregarded during financial assessments by government bodies or local authorities. Whilst you remain the beneficiary, the legal title is held by trustees, which creates the necessary barrier to protect your eligibility for support.

Protecting Eligibility for Means-Tested Benefits

The DWP views personal injury settlements as capital, which can be catastrophic for your household budget. Under current 2026 regulations, capital exceeding £6,000 reduces your entitlement, while assets over £16,000 usually stop means-tested benefits entirely. By using a trust, you preserve access to essential support including:

  • Universal Credit
  • Housing Benefit
  • Council Tax Support
  • Income Support

Following the receipt of a personal injury compensation payment, there is a 52-week period where the funds are disregarded for means-tested benefit calculations. This window is a critical time to establish your trust. Failing to act before this period expires means any remaining compensation will be treated as personal capital, potentially ending your right to claim benefits.

The Role of Personal Injury Trust Solicitors

Managing the technical requirements of a Trust Deed requires precision and foresight. This is where specialist personal injury trust solicitors provide essential guidance. We help you decide between a Bare Trust, where you retain absolute control, or more complex structures if the beneficiary lacks the mental capacity to manage their own affairs. Our role is to provide a calm, steady presence during what is often a stressful financial transition. We ensure the trust is established correctly from the outset, allowing you to focus on your recovery while we handle the intricate legal documentation and compliance with the Trust Registration Service. This methodical approach ensures your settlement is managed with the high-standard care it deserves.

The Financial Benefits: Securing Your Long-Term Stability

Securing a compensation award is a significant milestone, yet it’s merely the start of ensuring your financial resilience. A settlement is often intended to last a lifetime, funding ongoing needs that may not be immediately apparent. By engaging personal injury trust solicitors, you create a formal structure that prevents this capital from being treated as personal wealth by local authorities or third parties. It transforms a lump sum into a sustainable resource.

One of the most profound advantages involves social care funding. Without a trust, a local authority can include your compensation in a means-test for residential or home care costs. This could lead to your settlement being rapidly depleted to pay for services that would otherwise be state-funded. The High Court clarified in R (CGT) v West Sussex County Council EWHC 293 (Admin) that damages held in a personal injury trust must be disregarded in these assessments. This legal protection ensures your funds remain available for private medical treatments, bespoke rehabilitation programmes, and home adaptations that enhance your quality of life.

Beyond state assessments, a trust acts as a barrier against financial mismanagement or predatory interests. Life-changing settlements can unfortunately attract unwanted attention from third parties. A trust provides a structured framework where decisions are made by trustees, offering a layer of professional oversight and psychological peace of mind. It allows you to focus on recovery, knowing your capital is ring-fenced for its intended purpose.

Trusts and Future Care Costs

Professional advice is essential to navigate the complexities of “deprivation of capital” rules. If you move funds into a trust incorrectly or after you’ve already been assessed for care, local authorities might challenge the arrangement. Our partner-led approach ensures the trust is established with the necessary precision to avoid these accusations, safeguarding your capital to maintain a higher standard of future living.

Intersections with Family Law and Estate Planning

Financial protection also extends to your domestic life. A trust can help protect your settlement in the event of divorce and financial arrangements, as the funds are clearly identified as compensation for your specific injuries. Additionally, integrating your trust with your wider estate planning ensures that any remaining capital passes to your chosen beneficiaries via a Will. If you’re concerned about how a settlement might affect your existing arrangements, our team can provide the discreet, tailored advice you need to secure your legacy.

Choosing Personal Injury Trust Solicitors: Boutique vs. Claims Factories

Selecting the right personal injury trust solicitors is a decision that carries as much weight as the litigation that secured your award. In the current legal market, many national firms operate as high-volume “claims factories” where the emphasis is on case turnover rather than individual attention. In these environments, your file is often managed by junior staff or paralegals who might lack the depth of experience required to navigate the nuanced financial needs of a life-changing injury. You deserve a partner who views your settlement not as a transaction, but as the foundation of your future security.

Personal rapport is essential when discussing sensitive financial matters and the intimate details of your recovery. A boutique firm offers a calm, steady presence, ensuring you have direct access to a senior solicitor who values privacy and personal connection. This consistency builds a deep level of trust, allowing for a more thorough understanding of your specific long-term goals. We don’t just process paperwork; we provide a methodical, orderly approach that mirrors a professional consultation, making you feel informed and supported throughout the entire process.

The Boutique Advantage for Serious Injury

Direct access to senior legal minds is the hallmark of a high-standard service. We act as sophisticated guides, providing tailored advice that considers your entire private client profile rather than just the immediate settlement. This includes coordinating with your wider estate planning and future care requirements to ensure your trust is perfectly aligned with your life. Our “people-first” philosophy means that whilst the technical legal work is paramount, the human impact of that work is never forgotten. You receive a discreet, high-end service that prioritises your peace of mind over high-volume processing.

Specialist Expertise in Niche Claims

Generalist firms often overlook the specific nuances of occupational lung disease settlements, which can lead to less robust protections. For instance, the meticulous approach required for industrial diseases like silicosis demands a deep understanding of both medical evidence and litigation strategy. Specialist knowledge translates into more effective ring-fencing of your compensation. We ensure that the unique challenges of these niche claims are reflected in how your trust is structured, providing a level of security that a volume-driven firm simply cannot match. This pragmatic, partner-led advice is essential for securing the future of bereaved families and those living with life-changing conditions.

Personal Injury Trust Solicitors: Protecting Your Compensation and Future

The Process of Setting Up a Personal Injury Trust

Establishing a trust is a methodical process that requires early intervention to be most effective. It’s a common misconception that you should wait until your final settlement is reached. In reality, the most prudent time to engage personal injury trust solicitors is before or during the receipt of your first interim payment. This ensures that compensation never consolidates with your personal capital, maintaining a clear legal boundary from the outset.

The core of this arrangement is the Trust Deed. This formal document must be drafted with absolute precision to satisfy the rigorous standards of both HMRC and the Department for Work and Pensions. It defines the rules of the trust and the powers of those managing it. Once the deed is executed, the next step involves opening a dedicated Trust Bank Account. This account remains entirely separate from your everyday banking, providing a transparent audit trail that confirms the funds are ring-fenced compensation rather than personal savings.

Selecting and Appointing Trustees

Choosing your trustees is a decision that requires sound judgment and a high degree of trust. Trustees hold “fiduciary duties”, which means they’re legally obligated to act in your best interests and manage the funds with care. Whilst many people choose close family members, it’s standard practice to appoint at least two trustees to ensure security and mutual oversight. Many of our clients find significant value in appointing a professional solicitor as a trustee. This provides a neutral, expert presence to handle complex administrative tasks and ensure that the trust’s integrity is never compromised by accidental mismanagement.

Managing the Trust Over Time

A personal injury trust is designed to be a flexible, long-term resource. You can access the funds for specific needs, such as home adaptations, specialised equipment, or private rehabilitation, without those payments being treated as personal income. Maintaining this protection requires ongoing compliance, particularly regarding the Trust Registration Service (TRS). Regular annual reviews with your legal partner ensure the trust continues to meet your evolving needs and remains compliant with current regulations. If your circumstances change, such as a need to replace a trustee or eventually dissolve the trust, your solicitor manages these transitions with the same discreet, high-standard care used during the initial setup.

To ensure your settlement is protected from the moment of your first payment, you should contact our specialist team for a partner-led consultation regarding your trust requirements.

Feltons Solicitors: Your Discreet Partner in Complex Litigation

Feltons Solicitors LLP operates as a boutique firm, providing a calm and steady presence for those facing the aftermath of life-changing injuries. We don’t believe in the high-volume model of national claims factories. Instead, we prioritise a “people-first” philosophy that combines traditional professional integrity with modern, efficient delivery. Our personal injury trust solicitors act as your sophisticated guides, ensuring that the transition from receiving a settlement to securing your future is handled with the highest level of care and precision.

Our commitment to pragmatic, expert advice is rooted in a deep understanding of the human impact behind every legal case. We recognise that behind every complex litigation file is a person or a family seeking to rebuild their lives. By positioning ourselves as a dependable advisor, we offer a level of reliability that ensures your financial interests are protected whilst you focus on your physical and emotional recovery. This methodical approach is designed to provide security in even the most stressful circumstances.

Partner-Led Expertise in Serious Injury

In complex litigation, the quality of your legal partner is paramount. At Feltons, you benefit from direct access to senior legal minds throughout every stage of your claim. We understand that the stress of litigation can be overwhelming, so we position ourselves as a steady hand to reduce that burden. Our reputation is built on handling both national and complex international matters with a level of discretion that larger firms often struggle to maintain. This partner-led approach ensures that no detail is overlooked, from the initial evidence gathering to the final execution of your trust documents.

A Holistic Approach to Private Client Law

We look beyond the immediate success of a claim to secure your entire financial landscape. Our expertise is particularly deep in niche areas such as industrial disease, where we manage complex silicosis litigation with a pragmatic and meticulous mindset. We recognise that a successful settlement is only half the battle; the other half is ensuring that those funds are managed to support your rehabilitation for decades to come. This synergy between our litigation and private client departments is what sets us apart from generalist firms.

By bridging the gap between injury litigation and asset protection, we offer bespoke trust solutions tailored to your unique personal circumstances. We don’t provide generic templates; we create legal structures that reflect your specific health needs and family situation. We invite you to a professional consultation to discuss how our personal injury trust solicitors can protect your compensation and provide the long-term stability you deserve. Our goal is to ensure you feel informed, supported, and in capable hands throughout your recovery journey.

Securing Your Financial Resilience and Peace of Mind

Reaching a settlement is a significant victory, but the work of protecting that legacy begins immediately. By ring-fencing your award within a formal trust, you ensure that your eligibility for means-tested benefits remains intact whilst your capital is preserved for future care and rehabilitation. It’s a strategic move that separates your personal savings from the compensation meant to support your long-term recovery.

Choosing the right personal injury trust solicitors is essential for navigating the complexities of DWP regulations and HMRC compliance. At Feltons Solicitors, we provide a partner-led service that prioritises discreet, high-standard care over the volume-driven approach of national firms. Our specialist expertise in complex litigation and industrial disease ensures that your advice is pragmatic and tailored to your specific financial security. We invite you to contact Feltons Solicitors for a confidential consultation regarding your Personal Injury Trust. Taking this step today ensures that your hard-won compensation remains a source of stability for years to come.

Frequently Asked Questions

What is the “52-week rule” for personal injury compensation?

The 52-week rule is a specific disregard period granted by the DWP following the receipt of your first compensation payment. During this one-year window, any money received from a personal injury claim is ignored when calculating your eligibility for means-tested benefits. It’s a vital grace period that allows you time to seek advice from personal injury trust solicitors and establish a formal trust structure before the funds are treated as personal capital.

Will I lose my Universal Credit if I receive a personal injury settlement?

You won’t necessarily lose your Universal Credit if you receive a settlement, provided you place the funds into a personal injury trust. Without a trust, the DWP treats the award as capital. Under 2026 regulations, assets exceeding £6,000 reduce your monthly entitlement, whilst holdings over £16,000 typically result in a total loss of means-tested support. Ring-fencing the money ensures it remains disregarded during these financial assessments.

Can I be a trustee of my own Personal Injury Trust?

You can certainly be a trustee of your own trust, but you cannot be the sole trustee. Most legal structures require at least two people to manage the funds to ensure transparency and security. Whilst you retain the right to the capital as the beneficiary, having a second person, such as a family member or a professional solicitor, provides the necessary oversight required by banks and government bodies to recognise the trust’s validity.

How much does it cost to set up a Personal Injury Trust in the UK?

The cost of establishing a trust varies depending on the complexity of your settlement and the specific type of trust deed required. Most firms offer a fixed-fee arrangement for standard bare trusts, whilst more intricate discretionary trusts may involve higher professional fees. It’s best to discuss your requirements with personal injury trust solicitors during an initial consultation to receive a tailored quote that reflects the level of senior expertise your specific case demands.

Can I set up a trust after I have already received my compensation?

You can set up a trust after receiving your compensation, but it’s essential to act within the 52-week disregard period. If you wait longer than a year from the date of the first payment, the DWP will likely treat the funds as personal capital, which could immediately impact your benefits. Establishing the trust as soon as the first interim payment arrives is the most effective way to avoid any disruption to your financial support.

Do I need a separate bank account for my Personal Injury Trust?

A dedicated trust bank account is a mandatory requirement for maintaining the legal separation between your compensation and your personal finances. This account must be held in the names of your trustees and should only contain funds derived from your personal injury award. Mixing these funds with your everyday savings can taint the trust, making it difficult to prove to the DWP that the capital should be disregarded during means-testing.

What can I spend my Personal Injury Trust money on?

You have the freedom to spend your trust funds on almost anything that improves your quality of life or aids your recovery. Common uses include purchasing specialised equipment, funding private rehabilitation sessions, or paying for home adaptations. However, it’s important to use the funds directly from the trust account for these purchases. Withdrawing large sums of cash into your personal account can inadvertently push you over the capital limits for benefits.

How many trustees do I need for a Personal Injury Trust?

Standard practice requires a minimum of two trustees to ensure the trust functions correctly and meets the requirements of most UK banks. Having two people provides a system of checks and balances, reducing the risk of financial mismanagement. Many individuals choose a combination of a trusted family member and a professional solicitor. This blend ensures that personal needs are understood whilst the technical and administrative duties are handled with expert precision.

Transfer of Equity Solicitors: A Strategic Guide to Reorganising Property Ownership

Transfer of Equity Solicitors: A Strategic Guide to Reorganising Property Ownership

What if the simple act of adding a partner to your property title inadvertently triggered a tax bill worth thousands of pounds? It is a common anxiety for homeowners who wish to reorganise their assets but feel overwhelmed by Stamp Duty liabilities or the technicalities of mortgage lender consent. When the stakes are this high, the guidance of experienced transfer of equity solicitors is more than a formality; it is a vital safeguard for your wealth. Whether you are managing a matrimonial breakdown or gifting a share of your home, the emotional weight is often as significant as the legal complexities.

You deserve a transition handled with both technical precision and empathy. This guide is designed to help you manage these changes, ensuring your equity remains protected and your future is secure. We understand that your property is more than just an asset; it is the foundation of your personal life. We will provide a clear roadmap through the nuances of UK property law and tax obligations. We preview the essential steps to achieve a legally robust transfer of title whilst maintaining the privacy and dignity your family dynamics require.

Key Takeaways

  • Identify the common scenarios for reorganising property interests, ranging from matrimonial settlements and new marriages to family gifting and tax planning.
  • Understand the pivotal role of mortgage lender consent and why it represents the most significant legal hurdle in the transfer process.
  • Follow a clear, step-by-step roadmap that covers everything from initial identity verification to the final registration of Title Deeds.
  • Discover how to navigate complex tax obligations, including the calculation of Stamp Duty Land Tax (SDLT) on the consideration provided.
  • Learn why engaging expert transfer of equity solicitors is vital for protecting your financial security whilst managing the sensitive human impact of property transitions.

Understanding Transfer of Equity: Why Reorganise Your Property Interests?

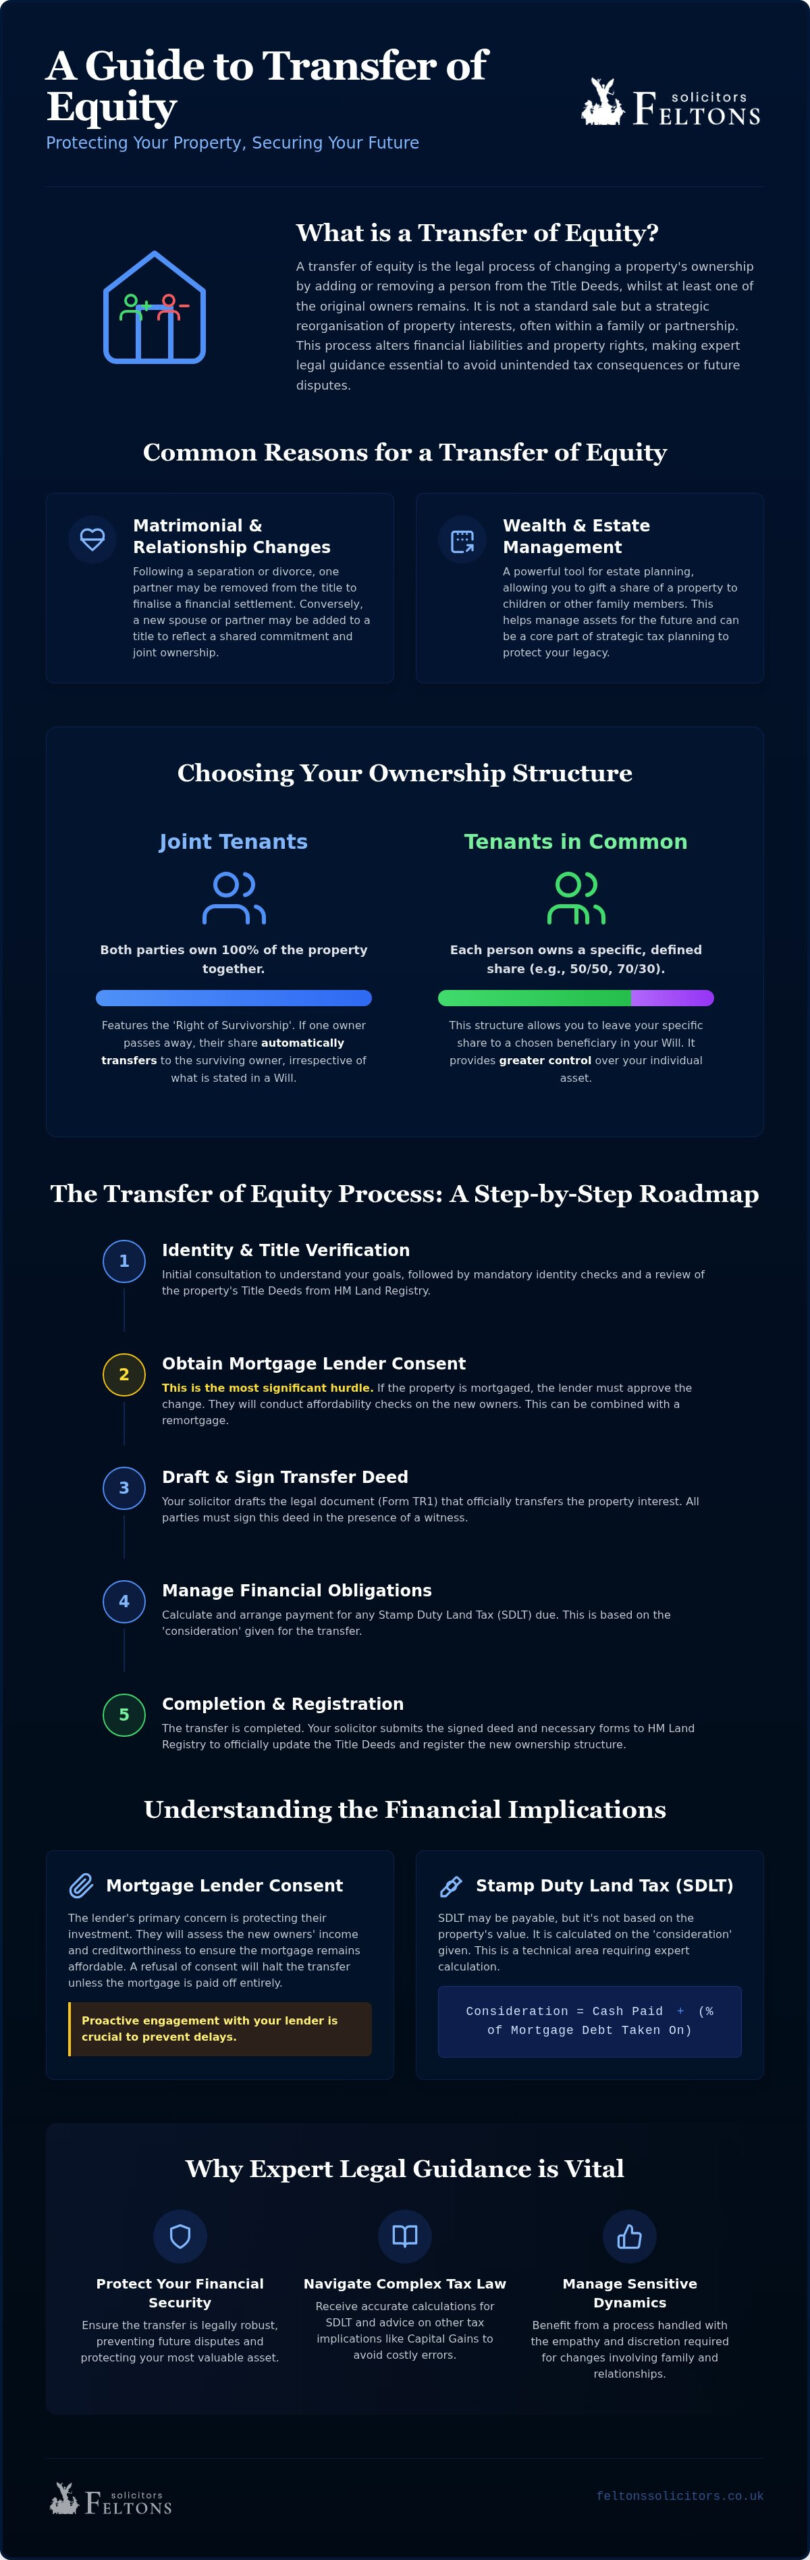
A transfer of equity occurs when the legal ownership of a property changes hands, but at least one of the original owners remains on the Title Deeds. This process differs significantly from a standard sale or purchase. In a typical market transaction, a property is sold, the mortgage is cleared, and the owners move on. A transfer of equity is instead a strategic reorganisation of existing interests. To gain a foundational perspective, one might ask, What is a transfer of equity? Simply put, it’s the legal mechanism used to add or remove individuals from a property’s title whilst keeping the property within a specific group or family unit.

Because these transitions often involve existing mortgages and significant tax implications, the expertise of a professional residential property law firm is essential. This isn’t merely an administrative update; it’s a formal legal shift that alters your financial liabilities and rights. Without precise guidance, homeowners risk future disputes or unintended tax consequences that can take years to resolve. Expert transfer of equity solicitors provide the technical accuracy needed to ensure the new ownership structure is legally robust and reflects your true intentions.

Matrimonial and Relationship Changes

Significant life transitions often necessitate a change in property holdings. Following a separation, a divorce and financial arrangements lawyer may advise removing a former partner from the title to finalise a financial settlement. Conversely, you might wish to add a new spouse or partner to the title of a home you already own to reflect a shared commitment. These moments require a delicate touch. We act as a calm, steady presence, balancing technical legal precision with the emotional sensitivity these personal changes demand.

Strategic Wealth and Estate Management

Beyond personal relationships, equity transfers are powerful tools for protecting your financial future. Gifting a share of a property to children or other family members can be a cornerstone of effective estate planning. However, the way you hold that equity is critical. You must decide between two primary structures:

  • Joint Tenants: Both parties own the whole property together. If one person passes away, their share automatically transfers to the survivor, regardless of what is written in a Will.
  • Tenants in Common: Each person owns a specific, defined percentage of the property. This allows you to leave your specific share to a chosen beneficiary in your Will.

Choosing between these options depends on your long-term goals and family dynamics. Transfer of equity solicitors help you navigate these choices, ensuring your property interests are organised in a way that respects your privacy and secures your legacy for the next generation.

If your property is subject to a mortgage, your lender is effectively a silent partner in any ownership change. Their consent is the primary hurdle in the process; without it, the transfer cannot legally proceed. Lenders view a change in ownership as a shift in their security. Whether you are removing a former partner or adding a new spouse, the bank must ensure their investment remains protected. Experienced transfer of equity solicitors act as the bridge between you and the financial institution, ensuring all criteria are met before any documents are signed.

Many homeowners choose to combine this transition with a remortgage. This synergy often makes financial sense, as it allows you to secure a better rate whilst simultaneously reorganising the title. If you stay with your current lender, they’ll conduct a full affordability assessment to ensure the remaining or new owners can comfortably meet the monthly repayments. If the bank refuses consent, usually due to a low credit score or insufficient income, the transfer will stall unless the mortgage is cleared in full. For those needing to explore alternative financing to bridge this gap, I Need Cash offers a way to compare various homeowner and personal loan products. Identifying these roadblocks early is a core part of our proactive approach.

Lenders prioritize risk management above all else. When a party is removed from a title, the bank must formally release them from their personal covenant to repay the debt. This “clean break” is vital for the outgoing individual, as it prevents them from being held liable for future arrears. For the remaining owner, the bank may require a ‘Deed of Covenant’ or a entirely new mortgage offer. They’ll scrutinise your income and outgoings with the same rigour as a fresh purchase to ensure the debt is sustainable on a single or revised set of earnings.

Coordinating with Financial Institutions

The timeline for a transfer is often dictated by the lender’s internal processing speeds. Your solicitor manages this coordination, ensuring that the mortgage offer aligns with the wider conveyancing process and Land Registry requirements. This involves significant back-and-forth communication to verify identity, confirm equity shares, and secure the final ‘letter of consent’.

Managing these moving parts requires a methodical mindset and a deep understanding of banking protocols. If you’re feeling uncertain about how your lender might react to a change in your circumstances, seeking advice from a specialist property solicitor can provide the clarity you need to move forward with confidence. We handle the technical liaisons, allowing you to focus on the personal transition at hand.

Your journey begins with a formal instruction. This stage involves rigorous Anti-Money Laundering (AML) checks, a mandatory requirement that ensures the integrity of the transaction and protects all parties from financial impropriety. Once identity is verified, we obtain the official copies of the title from the Land Registry. This review allows us to identify any existing charges, restrictions, or notices that might complicate the transition. It’s a methodical start that builds a secure foundation for the work ahead.

After reviewing the deeds, we move to the pivotal stage of securing lender consent, as discussed in our previous section. This involves a steady exchange of information with your bank to ensure the new ownership structure aligns with their lending criteria. Only when consent is in place can the formal transfer documents be prepared. Expert transfer of equity solicitors act as the primary coordinator here, ensuring that every piece of the puzzle fits perfectly before moving to execution.

Drafting the Transfer Deed (TR1)

The TR1 form is the legal instrument that effects the change in ownership. Within this document, we must clearly specify the ‘consideration’. This is the value being exchanged for the share of the property. It’s a common misconception that consideration only refers to cash; in a transfer of equity, the assumption of mortgage debt is also viewed as consideration by HMRC. We also confirm the ownership structure, whether you’ll hold the property as Joint Tenants or Tenants in Common. To prevent future ‘undue influence’ claims, transfer of equity solicitors often require the outgoing party to seek independent legal advice. This ensures they fully understand the rights they’re relinquishing, protecting the validity of the entire transaction.

Post-Completion Formalities

Once the TR1 is signed and witnessed, completion occurs. However, the legal work doesn’t end there. We must submit a Stamp Duty Land Tax (SDLT) return to HMRC, even if the transaction falls below the tax threshold and no payment is due. Following this, an application is made to the Land Registry to update the official record. Fees for this are typically submitted electronically, following the established HM Land Registry fee scales for transfers. This registration can take several weeks to process. Once finished, we provide you with the updated Title Register. This document serves as your final, definitive record of ownership, offering you the peace of mind that your property interests are correctly and securely organised.

Transfer of Equity Solicitors: A Strategic Guide to Reorganising Property Ownership

Financial Implications: SDLT, Capital Gains, and Valuation

While the legal mechanics of a transfer are vital, the financial consequences often present the most significant challenges. Many homeowners assume that if no money changes hands, no tax is due. This is a potentially costly misconception. In the UK, HM Revenue and Customs (HMRC) views the transfer of equity as a transaction with a specific value, known as ‘consideration’. Understanding how this value is calculated is where the guidance of transfer of equity solicitors becomes indispensable for protecting your long-term financial security.

An accurate property valuation is the cornerstone of this process. Whether you’re reorganising interests for tax planning or a family settlement, you must establish a fair market value. HMRC scrutinises transfers between ‘connected persons’, such as family members, and using an incorrect valuation can lead to penalties or prolonged investigations. We ensure your financial disclosures are pragmatic and robust, reflecting current market conditions whilst respecting your personal privacy.

The SDLT ‘Consideration’ Trap

Stamp Duty Land Tax (SDLT) is often triggered during a transfer because ‘consideration’ includes the value of any mortgage debt the new owner takes on. For example, if you’re added to a title for a property with a £300,000 mortgage, you’re effectively taking on responsibility for £150,000 of that debt. This £150,000 counts as consideration. Under 2026 rates, the standard SDLT threshold starts at £125,000. In this scenario, tax would be payable on the £25,000 that exceeds the 0% band. However, transfers resulting from a matrimonial breakdown or a court order are typically exempt from SDLT. We help you identify these exemptions early to avoid unnecessary payments.

Capital Gains Tax and Gifting

If the property is not your primary residence, such as a buy-to-let investment or a second home, Capital Gains Tax (CGT) may apply. For the 2026/2027 tax year, CGT rates for residential property stand at 18% for basic rate taxpayers and 24% for higher rate individuals. When gifting a share of a property to a child or family member, the ‘Market Value’ rule applies. HMRC calculates the gain based on the current value of the share being gifted, regardless of whether any money was paid. With an Annual Exempt Amount of just £3,000, these liabilities can accumulate quickly. Seeking early tax advice ensures you aren’t blindsided by a large bill months after the legal work is complete.

Managing the intersection of property law and tax obligations requires a steady, expert hand. If you’re planning to reorganise your property interests, consult our specialist property team to ensure your equity is protected and your tax liabilities are clearly understood before you proceed.

Reorganising property ownership is rarely a standalone task. It sits at the complex intersection of property law, family arrangements, and long-term tax planning. Each of these areas carries its own risks and requirements. A mistake in one can derail the others, leading to financial loss or personal friction. This is why the involvement of expert transfer of equity solicitors is vital. We don’t just process forms; we provide a strategic overview that ensures your transition is seamless and your interests remain protected.

In matrimonial transfers, the process is often emotionally charged. We act as a calm, steady presence, providing the technical precision needed whilst respecting the sensitivities of your situation. Our goal is to future-proof your property title. We ensure that every detail, from the specific wording of the Transfer Deed to the final Land Registry entry, is robust enough to withstand future scrutiny or potential disputes. By choosing a partner who understands the human impact of legal work, you ensure a transition that is as smooth as it is secure.

A Sophisticated Boutique Service

We pride ourselves on a “people-first” philosophy. Unlike high-volume firms that prioritise speed over substance, our boutique approach focuses on personal connection. We offer discreet, high-standard care that is particularly valued by high-net-worth clients who require a tailored experience. This bridges the gap between traditional professional integrity and the efficiency of modern legal delivery. You aren’t just a file number; you’re a partner in a process that values your privacy and unique circumstances. This level of individualized attention ensures that no detail is overlooked and every concern is addressed with poise and dependability.

Securing Your Property’s Future

Our expertise extends beyond simple title changes. As leasehold enfranchisement experts, we understand the nuances of complex title issues that often surface during an equity transfer. We coordinate holistically with your other professional advisors, such as accountants or surveyors, to ensure every financial and legal angle is covered. This collaborative approach provides a comprehensive service that secures the foundation of your property rights for years to come. It’s about more than the immediate change; it’s about building a legally robust future for your most valuable assets. To discuss your property ownership goals, contact our transfer of equity specialists today.

Securing Your Property Interests for the Long Term

Reorganising your property ownership is a significant legal transition that requires more than just administrative filing. It demands a strategic understanding of how mortgage lender consent, tax liabilities, and family dynamics intersect. By addressing these complexities with foresight, you ensure your equity is protected and your title remains legally robust against future challenges. Navigating the nuances of Stamp Duty and Capital Gains Tax is essential for maintaining your financial security whilst achieving your personal objectives.

At Feltons Solicitors LLP, we specialise in complex property and matrimonial transitions, providing pragmatic, professional advice tailored to your specific goals. Our discreet, boutique service ensures a human touch whilst maintaining the high-standard reliability you expect from a trusted advisor. When you engage transfer of equity solicitors who prioritise personal connection over high-volume processing, you gain a steady partner for your most valuable assets. We’re here to provide the calm, expert guidance needed to make your property reorganisation a success.

Secure your property’s future with Feltons Solicitors LLP. We look forward to guiding you through this transition with the poise and expertise your property deserves.

Frequently Asked Questions

Do I have to pay Stamp Duty when transferring equity in my home?

You may need to pay Stamp Duty Land Tax (SDLT) if the ‘consideration’ exceeds the current threshold. Consideration includes cash payments and the value of any mortgage debt the new owner takes on. For the 2026/2027 tax year, the standard threshold begins at £125,000. However, transfers resulting from a divorce or matrimonial breakdown are usually exempt. Consulting transfer of equity solicitors early ensures you don’t overlook potential exemptions or trigger unnecessary tax bills.

Can I transfer equity without my mortgage lender’s consent?

No, you cannot proceed without your mortgage lender’s formal consent. Because the lender has a legal charge over the property, they must approve any change to the ownership structure. They’ll conduct a full affordability assessment to ensure the remaining or new owners can meet the debt obligations. If consent is refused, the mortgage must be cleared in full before the transfer can occur. This is a critical hurdle that requires careful coordination.

How long does a typical transfer of equity take to complete?

A typical transfer of equity usually takes between four and eight weeks to complete. This timeline is heavily influenced by how quickly your mortgage lender provides consent and the complexity of your specific title. Whilst the legal drafting is relatively swift, external factors like HMRC filings and Land Registry registration can extend the process. We work methodically to ensure each stage is handled promptly to avoid any unnecessary delays for our clients.

Is a transfer of equity different if the property is a leasehold?

Yes, leasehold transfers involve additional administrative steps. You’ll likely need to notify the freeholder or management company of the change in ownership. There are often administrative fees for a ‘Notice of Transfer’ or ‘Notice of Charge’ as stipulated in your lease. As transfer of equity solicitors with expertise in leasehold matters, we manage these communications to ensure your lease remains compliant and your property rights are fully protected throughout the transition.

Do I need a new valuation of the property for a transfer of equity?

Yes, a formal valuation is often essential for both lender approval and tax compliance. HMRC requires the transfer to be based on a ‘fair market value’ to calculate potential Stamp Duty or Capital Gains Tax liabilities accurately. If you’re remortgaging as part of the process, your lender will also insist on an independent valuation to confirm their security. Establishing an accurate figure at the outset prevents future disputes with authorities or other parties.

What is the difference between a transfer of equity and a gift of property?

A transfer of equity involves at least one original owner remaining on the title, whilst a gift of property usually sees the entire interest transferred to someone else. Both scenarios are treated as disposals for tax purposes. If you’re gifting a share of a property that isn’t your main home, Capital Gains Tax may apply based on the market value. We provide the pragmatic advice needed to navigate these distinctions safely and securely.

Can a transfer of equity be challenged in the future by a former partner?

A transfer can be challenged if there’s evidence of ‘undue influence’ or if a party didn’t receive independent legal advice. To mitigate this risk, we ensure the process is transparent and that all parties understand the rights they’re relinquishing. A legally robust transfer, registered correctly at the Land Registry, provides the definitive record needed to protect your future interests. Our boutique approach prioritises these safeguards to ensure your property’s long-term security.

Does the outgoing person need their own solicitor for the transfer?

Yes, the outgoing person should always seek independent legal advice. Most transfer of equity solicitors and mortgage lenders require this to prevent a conflict of interest. It ensures that the individual leaving the title fully understands the financial and legal implications of their decision. This step is vital for the validity of the transfer, as it protects the transaction from future claims that the person was pressured or misinformed during the process.