Statutory Lease Extension Process: 2026 Guide

Statutory Lease Extension Process: 2026 Guide

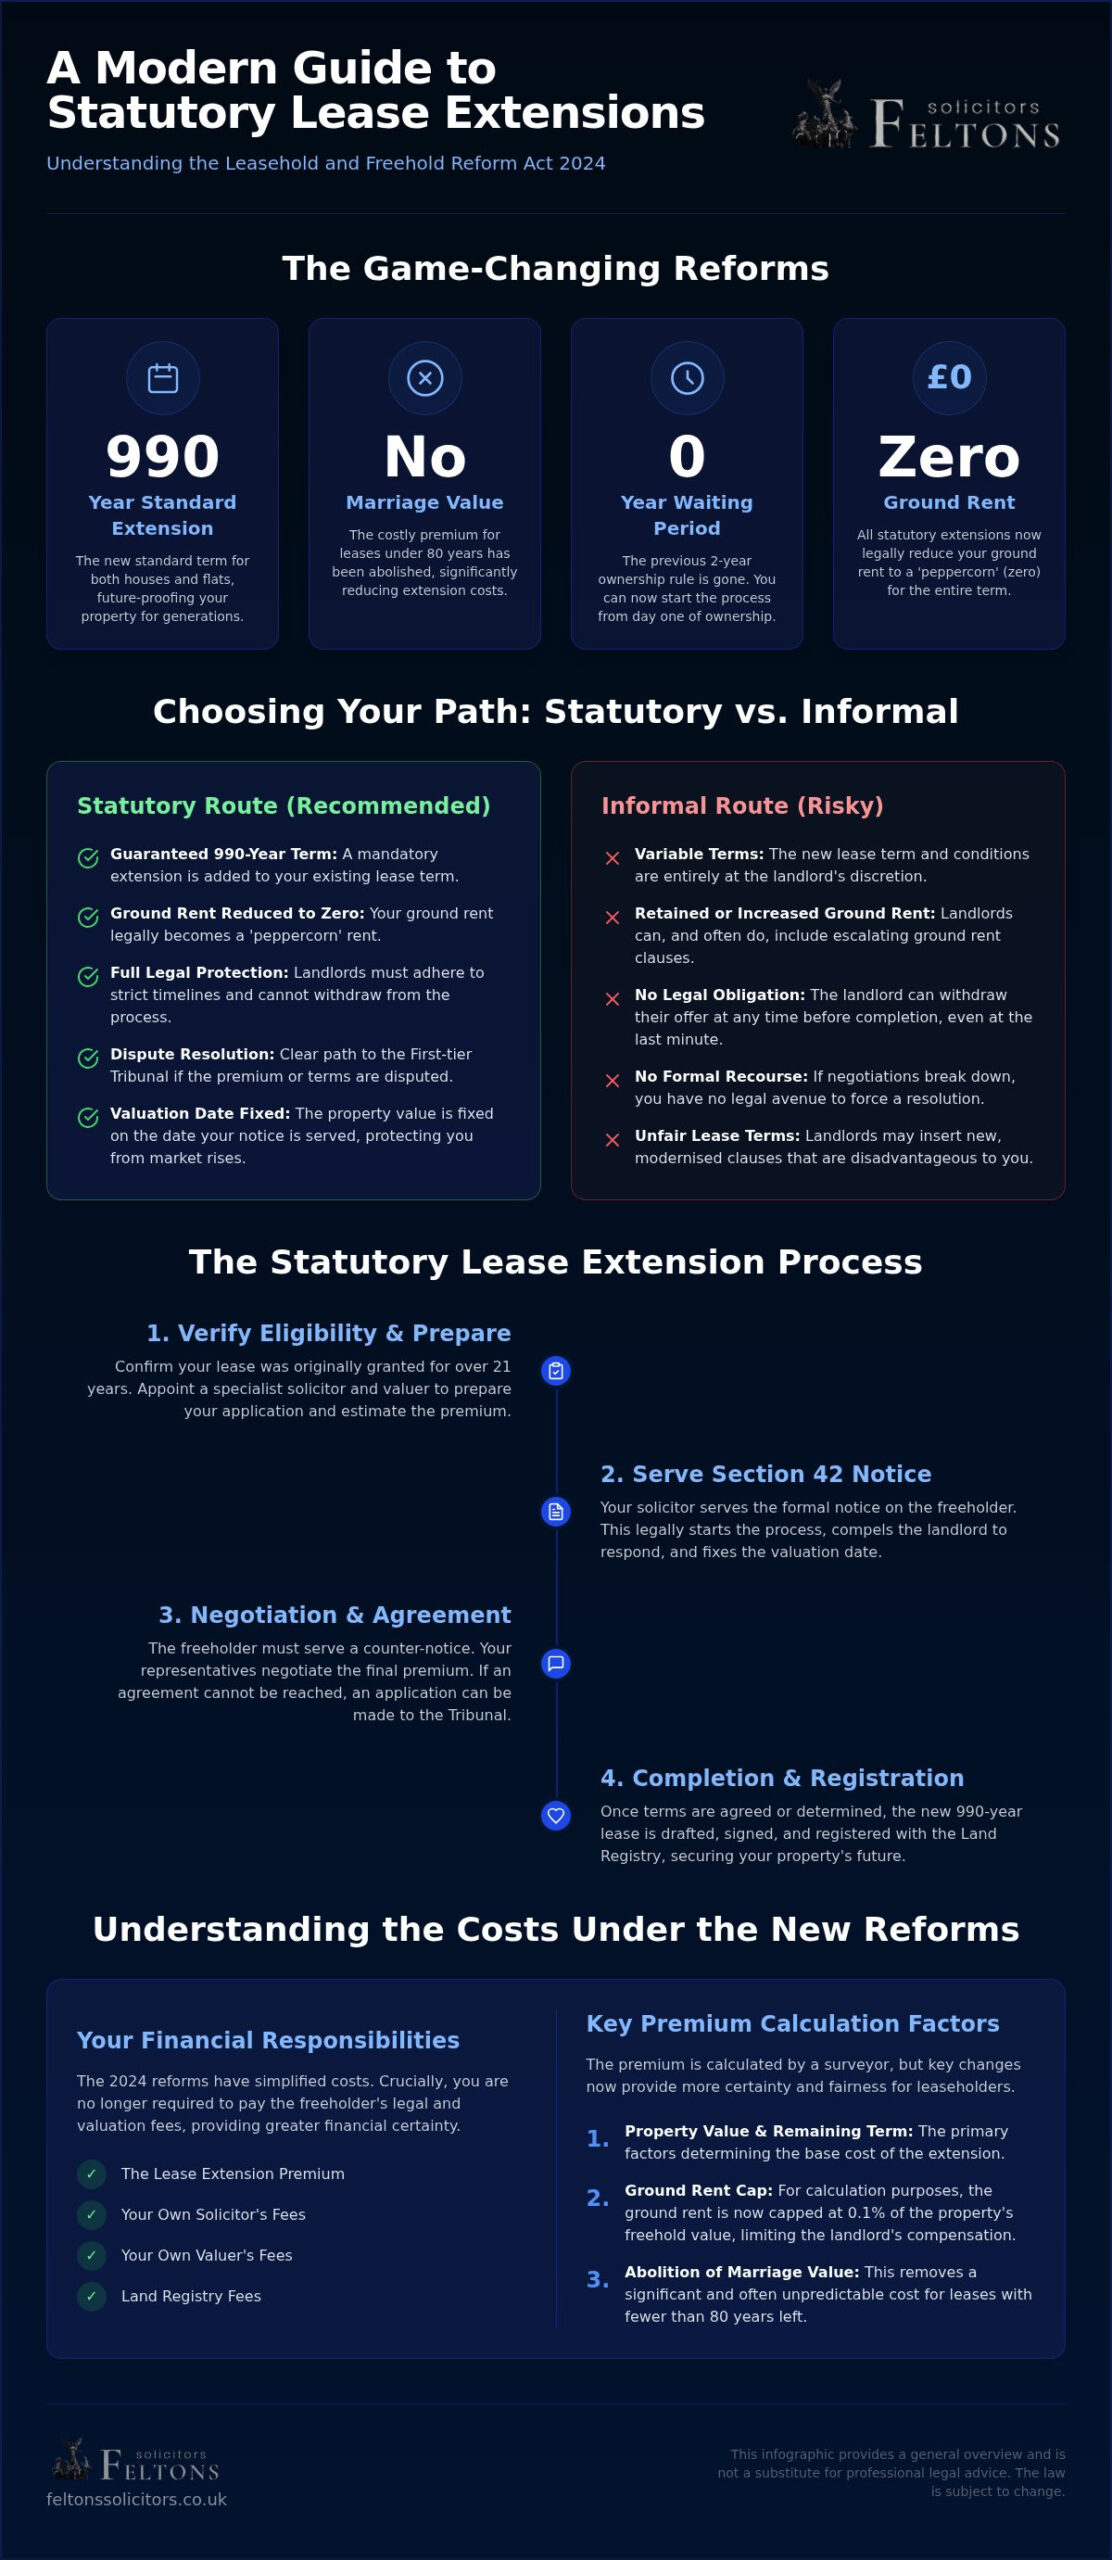
The fear of your lease dropping below eighty years and triggering eye-watering marriage value costs is finally a thing of the past. You’ve likely felt the weight of uncertainty as you watched the clock tick down on your property rights, perhaps worried that your landlord might refuse an extension or demand an extortionate premium. It’s an exhausting position to be in, especially whilst trying to keep pace with the implementation of the Leasehold and Freehold Reform Act 2024. This guide provides a definitive roadmap through the statutory lease extension process, ensuring you secure a 990-year term whilst avoiding the costly procedural errors that can derail an application.

By understanding your rights under the latest legislation, you can approach this transition with quiet confidence. We’ll explore how recent reforms have abolished the two-year ownership requirement and removed marriage value altogether. This methodical overview will show you how to navigate Section 42 notices and valuation caps, ensuring you remain in control of your property’s future without the stress of traditional legal hurdles.

Key Takeaways

  • Distinguish between informal negotiations and your formal legal right to a peppercorn ground rent under the latest reforms.
  • Navigate updated eligibility criteria, including the removal of the previous two-year ownership requirement for new leaseholders.
  • Master the technical stages of the statutory lease extension process, from serving a Section 42 notice to fixing your valuation date.
  • Capitalise on the abolition of marriage value and the introduction of the standard 990-year extension to reduce your overall costs.
  • Discover how to protect your property rights in complex scenarios, such as missing landlords or disputed counter-notices.

Understanding the Statutory Lease Extension Process vs Informal Routes

Choosing between a formal legal claim and an informal negotiation is the first critical decision any leaseholder must make. While a direct conversation with your landlord might seem like a shortcut to a quicker result, it often lacks the robust safeguards provided by the law. The statutory lease extension process is the formal legal procedure established by the Leasehold Reform, Housing and Urban Development Act 1993. It’s a powerful tool. It essentially forces a landlord to grant an extension, provided you meet the qualifying criteria, ensuring you aren’t left at the mercy of their discretion.

A Leasehold estate is, at its heart, a depleting asset. As the years on your lease diminish, the marketability and value of your home can suffer. Relying on an informal agreement to rectify this is risky; landlords are under no obligation to finish what they start and can withdraw their offer at any moment, even at the eleventh hour. By contrast, the statutory route provides a mandatory 990-year addition to your current term for both flats and houses. This effectively makes the lease future-proof for generations and removes the stress of having to extend again in your lifetime.

The Legal Framework: The 1993 Act and Beyond

The 1993 Act serves as the bedrock of your rights. It was designed to rebalance the power dynamic between leaseholders and freeholders, giving you the legal muscle to compel a lease extension. This statutory protection is vital. It ensures that your right to stay in your home is protected by a structured framework that survives even if the freehold is sold to a new owner. While the Leasehold and Freehold Reform Act 2024 has significantly updated these rights, the core principle remains the same: the law is your shield against landlord refusal.

Why the Statutory Route Offers Superior Tenant Protection

One of the most significant advantages of the formal process is the absolute guarantee of a peppercorn ground rent. Under the statutory lease extension process, your ground rent is legally reduced to zero for the entirety of the new term. Informal deals often include ground rent clauses that double every few years, which can make a property difficult to sell or remortgage later. The formal route provides a level of certainty that informal routes simply cannot match. You benefit from:

  • Strict legal timelines that prevent landlords from delaying the process.
  • A clear path to the First-tier Tribunal to resolve disputes over the premium or lease terms.
  • Protection against the inclusion of unfair or modernised clauses that benefit the landlord.
  • The ability to fix the valuation date at the moment you serve your notice, protecting you from market rises.

This methodical approach ensures you aren’t just getting more time on your lease. You are securing a cleaner, more valuable title that meets modern lending requirements and provides long-term peace of mind.

Eligibility Criteria and Essential Preparations for Leaseholders

Until recently, the most significant hurdle for many was the “two-year rule.” This required leaseholders to be registered owners for at least 24 months before they could initiate a claim. As of 31 January 2025, this barrier has been abolished. You can now begin the statutory lease extension process the day you complete your property purchase. This change has transformed the market, allowing buyers to secure their long-term interests without a stressful waiting period.

Most residential leaseholders will qualify as a “tenant” if their lease was originally granted for a term of more than 21 years. This is standard for the vast majority of flats in England and Wales. There are, however, specific exclusions to keep in mind. Business tenancies, certain shared ownership leases where the staircasing isn’t 100 per cent, and some properties owned by charitable trusts may not qualify for the statutory route. Verifying your eligibility early is essential to avoid unnecessary complications.

Preparing your finances is the next logical step. While the 2024 reforms have made extensions more affordable by removing the requirement to pay the freeholder’s legal and valuation costs, you must still budget for the premium itself and your own professional representation. For those just beginning to look at lease extension: getting started, it’s helpful to remember that the ground rent used for the calculation is now capped at 0.1 per cent of the property’s value. This cap provides much-needed certainty for your financial planning.

The Importance of an Accurate Leasehold Valuation

You must appoint a specialist valuer before serving your formal notice. Their role is to calculate the premium using the new standardised rates set by the government. In previous years, the dreaded “marriage value” added thousands to the cost for leases with less than 80 years remaining. This has been abolished, significantly reducing the premium for many. Your surveyor will focus on the “diminution” in the value of the landlord’s interest, providing a robust figure that forms the basis of your Section 42 offer.

Organising Your Professional Team

The relationship between your solicitor and valuer is symbiotic. A valuer provides the figures, but your solicitor ensures the legal paperwork is watertight. Generalist conveyancers often struggle with the technical nuances of the 1993 Act, which can lead to missed deadlines or invalid notices. Feltons Solicitors LLP offers a boutique, personalised service that manages these complexities on a national scale. If you’re ready to protect your investment, consulting with the specialist leasehold team at Feltons Solicitors LLP ensures you have a steady, expert hand guiding your application from start to finish. Our approach combines traditional professional integrity with modern efficiency, ensuring your property rights are secured without the anxiety of procedural errors.

A Step-by-Step Guide to the Section 42 Notice Procedure

Once you’ve prepared your valuation and legal strategy, the actual statutory lease extension process begins with the service of a Section 42 Initial Notice. This isn’t merely a request. It’s a formal legal trigger that compels your landlord to respond. One of the most significant benefits of this step is that it fixes the valuation date. From the moment the notice is served, the price you pay is protected against any future rises in the property market. This provides a vital layer of financial security whilst negotiations proceed.

Landlords are entitled to request evidence of your title or to inspect the property to verify its condition. While this is a standard part of the procedure, a difficult landlord might use these requests to delay progress. Having a professional team ensures these requests are handled promptly and accurately, leaving the freeholder with no grounds for procrastination. For those unfamiliar with these initial requirements, this Leasehold Advisory Service guide to getting started offers an excellent baseline for what to expect during these early exchanges.

Serving the Tenant’s Initial Notice (Section 42)

Precision is paramount when drafting your Section 42 notice. It must contain the proposed premium, any suggested modifications to the lease terms, and the names of all relevant parties. If the notice is deemed “invalid” due to a technical error, you may be barred from reapplying for six months. It’s also critical to identify any intermediate landlords who hold an interest between you and the competent landlord. Missing a party can stall the entire claim. A well-prepared notice signals to the landlord that you’re well-advised and prepared to see the matter through to its conclusion.

Managing the Landlord’s Counter-Notice and Timelines

The landlord has exactly two months from the date of service to provide their Section 45 Counter-Notice. This document will either admit your right to the extension or dispute it. More commonly, they’ll admit the right but propose a significantly higher premium. If the landlord fails to respond within this strict window, you gain a powerful advantage. You can apply to the County Court for a “Vesting Order,” which allows you to secure the extension on the terms proposed in your initial notice. This is why strict adherence to the calendar is your best defence against a recalcitrant freeholder. Managing these timelines with a methodical approach ensures you never lose your procedural momentum.
Statutory Lease Extension Process: 2026 Guide

Calculating Costs, Premiums, and the Impact of Marriage Value

Financial clarity is the cornerstone of a successful claim. For decades, the “80-year threshold” was the most significant date in a leaseholder’s calendar. Dropping even a single day below this mark traditionally triggered marriage value, an additional cost representing fifty per cent of the “profit” created by the extension. This often added tens of thousands of pounds to the premium. However, as we navigate the statutory lease extension process in 2026, the landscape has shifted fundamentally in favour of the leaseholder. The abolition of marriage value has removed one of the most punitive elements of property law, making extensions significantly more affordable for those with shorter terms.

While the premium is the largest outgoing, you must also consider Stamp Duty Land Tax (SDLT). For the majority of residential extensions, the premium falls below the threshold, but for high-value properties in prime locations, SDLT may still apply. It’s calculated on the premium paid for the new lease, and your solicitor will manage the return as part of the completion process. Precision in these calculations ensures there are no hidden surprises when the final figures are settled.

How the Leasehold and Freehold Reform Act 2024 Changes the Landscape

The 2024 Act has formalised the move towards 990-year statutory terms, replacing the old 90-year addition. This provides near-permanent security for your investment. The government has also introduced prescribed rates for the valuation calculation to reduce disputes. By capping the ground rent at 0.1 per cent of the property’s value for the purpose of the premium calculation, the law has brought a high degree of certainty to what was once a highly litigious area. These standardised rates mean that your valuer can provide a much narrower and more reliable estimate of the eventual cost.

Budgeting for Your Extension: Beyond the Premium

Your budget must account for professional fees and the procedural requirements of the 1993 Act. When you serve your Section 42 notice, you are typically required to pay a deposit of ten per cent of your proposed premium to the landlord’s solicitor. This is held as security and is deducted from the final balance. While the 2024 reforms have largely removed the requirement for leaseholders to pay the freeholder’s legal and valuation costs, some limited exceptions remain for specific, fixed amounts. You can find more detail on managing these financial nuances in our guide for Leasehold Enfranchisement Experts, which offers practical cost-saving tips for the modern leaseholder.

Appointing a specialist team is the most effective way to ensure your offer is realistic and legally sound. If you are concerned about overcharging or wish to verify your potential costs, contact Feltons Solicitors LLP for a professional consultation. We provide the steady, expert hand needed to navigate these complex financial waters, ensuring you secure your property rights whilst protecting your capital. Our boutique approach means we prioritise your personal financial outcome, treating every case with the discreet care it deserves.

Even with the legal protections of the statutory lease extension process, technical hurdles can still arise. A common complication occurs when a freeholder cannot be located or simply refuses to engage. In these instances, Feltons Solicitors LLP guides you through the “Vesting Order” process in the County Court. This allows a judge to sign the new lease on the landlord’s behalf, ensuring your extension isn’t derailed by an absent freeholder. It’s a methodical legal solution that provides a clear path to your 990-year term regardless of the landlord’s status.

Negotiation is where the value of a coordinated professional team becomes most apparent. After the Counter-Notice arrives, your solicitor and valuer work in tandem to close the gap between the valuations. Most cases are settled during this period through pragmatic, evidence-based discussion. If an agreement remains elusive after two months of negotiations, we can apply to the First-tier Tribunal (Property Chamber) for a final determination. This stage acts as a vital safety net, ensuring the premium you pay remains fair and aligned with the latest standardised rates.

The final stage involves the formal completion of the new lease and its registration at HM Land Registry. We meticulously check the final document to ensure it reflects the zero ground rent requirement and the agreed term. This registration is the definitive legal record of your extended term, providing the security future buyers and mortgage lenders require to verify your title.

Common Pitfalls in the Statutory Process and How to Avoid Them

Missing the “deemed withdrawal” deadline is a catastrophic and expensive error. If you don’t apply to the Tribunal within six months of receiving the Counter-Notice, your claim is legally cancelled. This results in significant wasted costs and a mandatory waiting period before you can start again. Identifying the “Competent Landlord” is also essential in buildings with complex head-lease structures. Serving the wrong party can render your entire notice void. The methodical approach at Feltons Solicitors LLP ensures every statutory deadline is met with absolute precision.

Why Expert Legal Representation is Essential

A sophisticated guide is vital when dealing with high-stakes property negotiations. Landlords often attempt to slip “hidden” modernisations into the new lease that favour their interests, such as new service charge triggers or restrictive covenants. We scrutinise every clause to ensure your new lease remains clean and marketable. Contact Feltons Solicitors LLP today to begin your statutory lease extension with confidence. We provide the boutique care and professional integrity required to handle complex property matters, ensuring your home remains a secure asset for the future.

Protecting Your Investment with Clarity and Confidence

The landscape for leaseholders has changed fundamentally. With the abolition of marriage value and the introduction of 990-year statutory terms, you now have a historic opportunity to secure your property’s value on much fairer terms. This guide has outlined how to navigate the technicalities of Section 42 notices whilst avoiding the procedural traps that can stall an application. You’re no longer at the mercy of landlord discretion; the law is firmly on your side.

Successfully managing the statutory lease extension process depends on a blend of meticulous legal drafting and pragmatic negotiation. Our team at Feltons Solicitors provides the boutique expertise and plain-English advice needed to handle even the most complex property litigation. We ensure that every deadline is met and every clause is scrutinised to protect your long-term interests. We maintain an established reputation for precision, ensuring your transition to a peppercorn ground rent is seamless and secure.

Don’t leave your property’s future to chance. Secure your property’s future with a statutory lease extension from Feltons Solicitors and enjoy the peace of mind that comes with expert representation. You’re in capable hands.

Frequently Asked Questions

How long does the statutory lease extension process typically take?

The statutory lease extension process typically takes between six and twelve months from the service of the Initial Notice to final registration at HM Land Registry. This timeline varies based on how quickly your landlord serves their Counter-Notice and the duration of subsequent negotiations. If an agreement cannot be reached and an application to the First-tier Tribunal becomes necessary, the timeframe may extend further.

Can I still extend my lease if my landlord is missing or unresponsive?

You can absolutely proceed if your landlord is missing or unresponsive by applying for a Vesting Order. This involves a County Court application where a judge essentially stands in for the landlord to sign the new lease. It’s a methodical legal solution that ensures your property rights aren’t held hostage by an absent freeholder or a dissolved company.

What happens to the statutory process if I decide to sell my flat midway through?

If you sell your flat midway through, you can assign the benefit of the Section 42 notice to the incoming purchaser. This is a standard procedure during conveyancing that allows the buyer to step into your shoes and complete the extension. It ensures the work you’ve started adds immediate value to the sale and provides security for the new owner from day one.

Is it possible to extend a lease for a house using the statutory route?

It is certainly possible to extend the lease of a house using the statutory route. Under the Leasehold and Freehold Reform Act 2024, house owners now have the same right to a 990-year extension as flat owners. This represents a significant shift from older legislation, providing house leaseholders with much-needed parity and the same long-term security as those owning flats.

What is the ’80-year rule’ and why is it so critical for leaseholders?

The “80-year rule” was the critical point where marriage value was triggered, significantly increasing the premium payable to the landlord. While the 2024 Act has abolished marriage value in 2026, the 80-year mark remains important for marketability. Many mortgage lenders still view leases approaching this threshold with caution, making an extension vital for maintaining your property’s liquidity and value.

Can a landlord refuse a statutory lease extension request?

A landlord cannot refuse a valid statutory request if you meet the qualifying criteria. The law grants you a mandatory right to extend, and the freeholder’s role is primarily to negotiate the premium and specific terms. Refusal is only permitted in extremely rare circumstances, such as if the landlord intends to redevelop the building within five years of the lease ending.

What are the risks of choosing an informal lease extension over the statutory route?

Choosing an informal route carries the risk of “ground rent traps” and a total lack of procedural security. Landlords can withdraw from informal negotiations at any moment, even after you’ve spent money on valuations. Informal deals often retain or increase ground rent; by contrast, the statutory lease extension process legally guarantees a peppercorn rent for the entire term.

How has the Leasehold and Freehold Reform Act 2024 affected the cost of extensions in 2026?

The 2024 Act has generally reduced the cost of extensions by abolishing marriage value and capping ground rent for valuation purposes. By removing the requirement for leaseholders to pay the landlord’s legal and valuation fees in most cases, the overall financial burden has lightened. These reforms make securing a 990-year term more accessible and affordable for millions of leaseholders across the country.
Solicitors for International Property Buyers: Navigating UK Transactions in 2026

Solicitors for International Property Buyers: Navigating UK Transactions in 2026

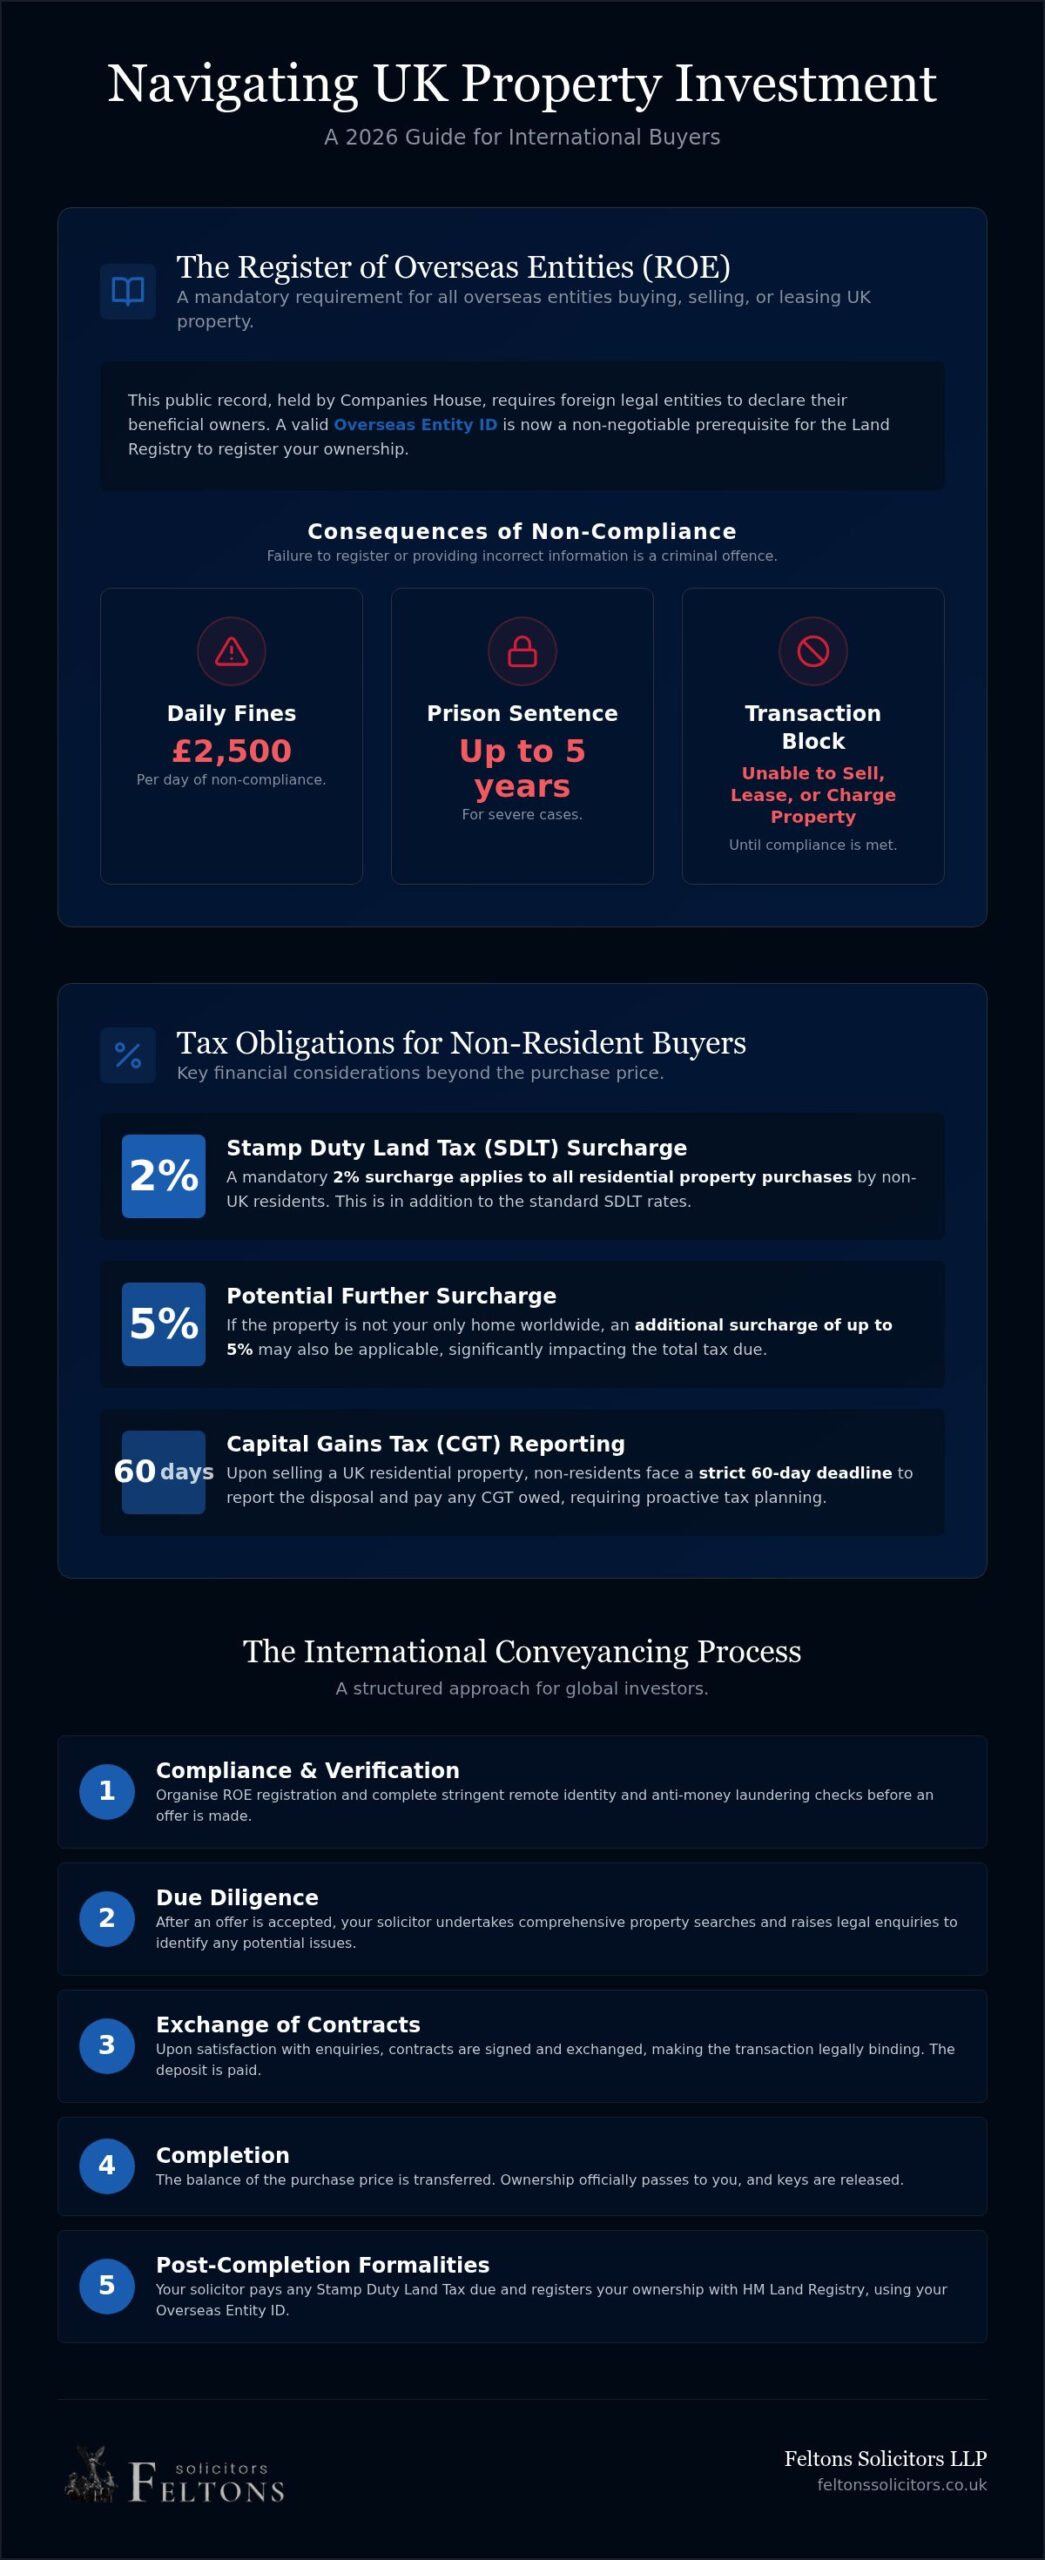
A single oversight in the Register of Overseas Entities can result in a daily fine of £2,500 or, in more severe cases, a prison sentence. It’s perfectly natural to feel a sense of trepidation when facing the UK’s increasingly rigorous transparency laws. This is particularly daunting whilst you’re managing high-value transactions from a different time zone. Finding the right solicitors for international property buyers is essential to ensuring these complexities don’t jeopardise your acquisition. You want the security of British property, but the weight of enhanced anti-money laundering checks and complex tax obligations can make the process feel unnecessarily opaque.

This guide offers a comprehensive look at the legal landscape in 2026. We cover everything from navigating the 2% non-resident Stamp Duty surcharge to meeting the latest Companies House filing requirements. We’ll outline the essential conveyancing steps and explain how a partner-led approach ensures your investment is protected with the highest standard of professional integrity. By the end of this article, you’ll have a clear understanding of your registration obligations and the confidence to move forward with your UK property goals.

Key Takeaways

  • Understand the mandatory requirements of the Register of Overseas Entities (ROE) to ensure your property acquisition remains fully compliant with 2026 transparency laws.
  • Learn how experienced solicitors for international property buyers navigate the complexities of UK conveyancing whilst managing stringent remote identity verification.
  • Identify the specific Stamp Duty Land Tax (SDLT) surcharges and tax obligations that apply to non-resident investors in both residential and commercial sectors.
  • Discover a methodical, step-by-step conveyancing process designed to accommodate global investors operating across different time zones.
  • Explore why a boutique, partner-led legal service provides the discretion and tailored expertise required for high-value international transactions.

The Landscape for International Property Buyers in 2026

The UK property market remains a beacon for global capital. Its legal system offers a level of predictability that’s rare in other jurisdictions, making it a preferred destination for those seeking long-term stability. Whilst the allure of London’s skyline or the steady yields of northern commercial hubs remains strong, the path to ownership has become more intricate for those residing outside our borders. In 2026, the primary challenge for investors isn’t just finding the right asset; it’s navigating a regulatory framework that demands absolute transparency. Instructing specialized solicitors for international property buyers is now a prerequisite for a successful acquisition. You need a legal partner who understands that a cross-border transaction is a dual exercise in property law and rigorous regulatory compliance.

Why the UK Remains a Global Investment Centre

English law continues to be the gold standard for property contracts. It provides a clear, enforceable framework that protects the interests of the buyer and seller alike. This transparency of title, managed through a robust Land Registry system, ensures that ownership is indisputable once registered. Beyond legal security, the UK offers diverse opportunities. Residential investors are drawn to consistent rental demand in major cities, whilst the commercial sector provides sophisticated assets ranging from Grade A office spaces to industrial hubs. These fundamentals haven’t changed, but the method of accessing them has evolved.

The Shift Towards Transparency and Compliance

Recent years have seen a definitive move towards greater corporate accountability. The Economic Crime (Transparency and Enforcement) Act has fundamentally altered the landscape, requiring overseas entities to disclose their beneficial owners before they can buy or sell UK land. Standard high-street firms often lack the dedicated infrastructure to handle these specific requirements. For the modern investor, proactive legal planning must begin long before an offer is made. This involves preparing for enhanced identity checks and ensuring your corporate structure is ready for scrutiny by Companies House.

Managing the conveyancing process from abroad requires a solicitor who acts as a steady, local presence. In 2026, non-resident buyers face a mandatory 2% Stamp Duty Land Tax (SDLT) surcharge on residential purchases, which applies in addition to standard rates. If the property isn’t your only home worldwide, a further 5% surcharge may also apply. These financial implications, combined with the strict 60-day reporting deadline for Capital Gains Tax on disposals, mean that your legal advisor must be as much a tax and compliance strategist as they are a conveyancer. We’ve moved past the era of “standard” transactions; every international purchase now requires a bespoke, detail-oriented approach to ensure your investment remains secure and compliant.

Understanding the Register of Overseas Entities (ROE)

The Register of Overseas Entities is a mandatory public record held by Companies House that requires foreign legal entities to identify their beneficial owners before they can buy, sell, or lease property in the UK. This isn’t a mere administrative hurdle. It’s a critical legal requirement that dictates whether a transaction can actually proceed to completion. For those seeking solicitors for international property buyers, the focus has shifted from simple title searches to complex corporate verification. Without a valid Overseas Entity ID, the Land Registry will simply refuse to register your ownership, effectively stalling your investment indefinitely.

The role of a UK-regulated agent is central to this process. You can’t simply self-certify your ownership structure. A solicitor or qualified professional must verify the information before it’s submitted to Companies House. This verification must be based on reliable, independent evidence. If the information is found to be incorrect or if you fail to register, the consequences are severe. Non-compliance is a criminal offence. You could face daily fines of up to £2,500 or even a prison sentence of up to five years. Perhaps more importantly for investors, you’ll be legally restricted from selling, leasing, or charging the property until your status is regularised.

Who Qualifies as a Beneficial Owner?

A beneficial owner is typically any individual or legal entity that holds more than 25% of the shares or voting rights. This also includes anyone who has the right to appoint or remove a majority of the board of directors. Complex trust structures and nominee arrangements require a methodical approach to peel back the layers of control. It’s not a one-time obligation. You’re required to provide annual updates to Companies House to maintain your ROE ID. Failure to file an update within 14 days of the anniversary of your registration results in an immediate breach of the law.

The Verification Process for Overseas Entities

Verification is evidence-based and exceptionally rigorous. Solicitors must review original documents, including passports, corporate registers, and trust deeds, to satisfy the 2026 transparency standards. It’s sensible to start this process long before you’ve even identified a specific property. Delays in verification are one of the most common reasons for transactions to collapse in the final stages. If you’re navigating this for the first time, you can read our detailed guide on overseas entity beneficial owner registration to prepare your documentation. Ensuring your corporate structure is transparent is the first step toward a seamless acquisition. If you need assistance with these complex filings, our team can help you register an overseas entity with the necessary precision and discretion.

Acquiring a luxury apartment in Mayfair requires a vastly different legal strategy than purchasing a logistics hub in the Midlands. Whilst both transactions demand meticulous title checks, the regulatory and tax hurdles vary significantly between the two sectors. Choosing solicitors for international property buyers who can pivot between these distinct legal landscapes is vital for a secure investment. High-value residential acquisitions often hinge on personal lifestyle requirements and long-term capital growth. Conversely, commercial units are driven by lease yields, tenant covenants, and VAT efficiency. Your legal partner must possess the versatility to handle both the personal nuances of a home and the technical rigour of a business asset.

Residential Investment: Surcharges and Leasehold Risks

Non-UK residents must account for the mandatory 2% Stamp Duty Land Tax (SDLT) surcharge on residential purchases in England. This is not a negotiable fee. It applies in addition to standard SDLT rates. If the property is an additional dwelling, such as a second home or a buy-to-let investment, a further 5% surcharge applies. This can bring the total tax burden to a significant level, making early tax planning essential. Beyond the initial purchase price, the UK’s leasehold system presents unique challenges for those unfamiliar with it. Many apartments are sold with diminishing lease terms that can eventually affect the property’s value and mortgageability.

Engaging leasehold enfranchisement experts is often necessary to extend these terms or even purchase the freehold. Managing ground rent issues and service charge disputes from abroad is notoriously difficult. A specialized residential property law firm will ensure that the lease terms are fair and sustainable before you commit your capital. They act as your eyes and ears on the ground, identifying hidden liabilities that could disrupt your long-term plans.

Commercial Property: Leases and Business Structures

Commercial acquisitions frequently involve Full Repairing and Insuring (FRI) leases. This structure typically places the entire burden of maintenance, repairs, and building insurance on the tenant. This is attractive for landlords seeking a “hands-off” investment, but it requires precise legal drafting to avoid future litigation over dilapidations. VAT is another critical factor. Many commercial properties are “opted to tax,” meaning a 20% VAT charge applies to the purchase price unless the transaction qualifies as a Transfer of a Going Concern (TOGC). Investors must also decide whether to hold the asset through a UK Special Purpose Vehicle (SPV) or an overseas company. Whilst an SPV can simplify local financing, an overseas entity triggers the mandatory ROE requirements mentioned earlier. Each structure has distinct tax and reporting implications that require careful, expert consideration.

Solicitors for International Property Buyers: Navigating UK Transactions in 2026

The International Conveyancing Process Step-by-Step

Purchasing a property in the UK from several thousand miles away requires a structured roadmap. Whilst the core principles of land law remain constant, the logistical execution for overseas investors involves specific digital hurdles and stringent verification phases. Professional solicitors for international property buyers act as your primary coordinator, ensuring that the distance doesn’t lead to delays or missed deadlines. In 2026, the average conveyancing timeline ranges between 12 and 20 weeks, though chain-free transactions can often be completed in 8 to 12 weeks with proactive management.

The process begins with initial instruction and the opening of your file. This is immediately followed by a comprehensive review of the legal pack and title deeds. Your solicitor will negotiate the contract terms and raise specific enquiries regarding the property’s history, planning permissions, and any potential liabilities. Once satisfied, you’ll move to the “Exchange of Contracts.” At this stage, a deposit, typically 10% of the purchase price, is paid, and the transaction becomes legally binding. Completion follows shortly after, involving the transfer of the remaining funds, the submission of Stamp Duty Land Tax (SDLT) returns, and the final application to the Land Registry to record your ownership.

Remote Verification and Digital Onboarding

Modern legal practice has embraced digitalisation to facilitate remote acquisitions. Solicitors now utilise secure biometric ID applications to verify your identity without requiring a physical meeting. These apps scan your passport’s NFC chip and use facial recognition to satisfy UK anti-money laundering regulations. Whilst digital signatures are increasingly common for initial documents, some Land Registry filings in 2026 still require “wet ink” signatures on specific deeds. You’ll also need to provide detailed proof of funds. UK banking regulations are exceptionally strict; you must be prepared to show a clear trail of how your investment capital was accumulated, often spanning several months of bank statements.

Managing the Transaction Timeline

Coordinating a purchase across different time zones requires a methodical approach. Delays often occur when communicating with surveyors, lenders, or estate agents who operate on UK business hours. To mitigate this, many international buyers grant a limited Power of Attorney to their solicitor or a trusted UK representative. This allows legal documents to be signed on your behalf, ensuring the “Exchange” and “Completion” phases aren’t stalled by international courier delays. If you’re ready to begin your acquisition, our team provides expert residential and commercial conveyancing services tailored to the needs of global investors.

Why International Buyers Choose Feltons Solicitors

Selecting the right solicitors for international property buyers involves more than finding a firm to process a deed. It requires a partnership with a legal team that understands the weight of your investment and the complexities of your position as a global investor. Whilst many high-volume firms treat conveyancing as a factory-style process, Feltons Solicitors LLP operates with a boutique philosophy. Since 2010, we’ve positioned ourselves as a steady, dependable presence for clients navigating the UK’s intricate property laws. We prioritise personal connection and high-end reliability, ensuring that your transaction is handled with the quiet confidence and discretion it deserves.

Our approach bridges the gap between traditional professional integrity and modern, forward-thinking methodology. We understand that for an overseas investor, the technical legal work is only one part of the equation; the human impact and the need for clear, reassuring guidance are equally paramount. Whether you’re acquiring a high-value residence or managing a commercial portfolio, our role is to act as your sophisticated guide through the regulatory landscape of 2026. We provide holistic support that extends beyond the immediate purchase, offering expert estate planning to ensure your UK assets are protected for future generations.

A Trusted Advisor for Complex Transactions

We provide a partner-led service, meaning your case is never passed down to junior staff or automated systems. An experienced solicitor oversees every detail of your transaction, providing the sound judgment necessary for complex, high-value matters. This is particularly vital when dealing with the Registration of Overseas Entities or navigating contentious property disputes. Our expertise in both residential and commercial sectors allows us to manage sophisticated portfolios with a level of individualized attention that high-volume firms simply cannot match. We value privacy and personal rapport, acting as a discreet partner for high-net-worth individuals and corporate entities alike.

National Reach with a Personal Touch

Feltons operates on a national scale, yet our service remains deeply rooted in a people-first philosophy. We’ve developed a communication rhythm that respects your schedule, regardless of your time zone. You’ll never feel like just another file number; instead, you’ll have a dedicated advisor who provides regular, methodical updates. This steady flow of information is designed to make you feel informed and supported, turning a potentially stressful international purchase into a seamless, controlled experience. By combining worldly experience with a commitment to clear, “plain English” advice, we ensure that you remain in capable hands from the initial instruction to the final registration of your title.

Securing Your UK Property Investment in 2026

The UK property market remains a premier destination for global capital, but the legal landscape in 2026 demands a higher level of transparency than ever before. Successfully navigating the Register of Overseas Entities and managing non-resident tax surcharges requires more than just a standard conveyancing service. It requires a partner who understands the nuances of cross-border transactions and the importance of meticulous compliance. By prioritising early verification and digital onboarding, you can ensure that your acquisition proceeds without the risk of daily fines or criminal liability.

Feltons Solicitors LLP has been a trusted advisor for global investors since 2010. We specialise in the Registration of Overseas Entities, providing a boutique, partner-led service that prioritises your personal objectives. Our firm offers the sophisticated guidance necessary for high-value transactions whilst maintaining the discreet, tailored care you expect. If you’re looking for dedicated solicitors for international property buyers to safeguard your UK interests, we’re here to provide a steady and calm presence throughout the process. Contact Feltons Solicitors for expert international property advice and take the first step towards a seamless, compliant acquisition.

Frequently Asked Questions

Do I need to be in the UK to buy property as an international buyer?

No, you don’t need to be physically present in the UK to complete a property purchase. Modern solicitors for international property buyers use biometric ID applications and secure digital portals to manage the entire process remotely. You can also grant a limited Power of Attorney to your legal representative, allowing them to sign specific deeds on your behalf so that completion isn’t delayed by international courier times.

What is the Register of Overseas Entities and does it apply to me?

The Register of Overseas Entities is a mandatory record held by Companies House for foreign companies or legal structures that own UK land. It applies to you if you’re purchasing property through an overseas entity rather than in your personal name. You must identify your beneficial owners and have this information verified by a UK-regulated agent before the Land Registry will record your ownership of the property.

Are there extra taxes for non-residents buying property in the UK?

Yes, non-residents are subject to a mandatory 2% Stamp Duty Land Tax (SDLT) surcharge on residential purchases in England and Northern Ireland. If the property isn’t your only home worldwide, an additional 5% surcharge for additional dwellings typically applies. You should also account for the Non-Resident Landlord Scheme, which involves a 20% withholding tax on rental income unless you’re approved to receive gross payments.

How do solicitors verify proof of funds for overseas clients?

Solicitors verify funds by reviewing an audited trail of your capital’s origin, which usually requires at least six months of bank statements. You’ll need to provide clear evidence of the source of your wealth, such as property sale completion statements, inheritance documents, or dividend vouchers. UK anti-money laundering regulations are exceptionally rigorous, so providing a transparent paper trail is the best way to avoid transaction delays.

Can an overseas company own UK residential property?

An overseas company can own UK residential property, but this triggers specific regulatory and tax obligations. Beyond the mandatory Register of Overseas Entities filing, companies owning dwellings valued at over £500,000 are subject to the Annual Tax on Enveloped Dwellings (ATED). For the 2025/26 period, these annual charges ranged from £4,400 to £287,600 depending on the specific value of the property.

How long does the UK conveyancing process take for international buyers?

The average conveyancing process for international buyers in 2026 takes between 12 and 20 weeks. If the property is chain-free and your documentation is prepared in advance, this timeline can be reduced to 8-12 weeks. Working with experienced solicitors for international property buyers helps to manage the logistical challenges of different time zones and complex overseas corporate searches that often slow down standard transactions.

What happens if I fail to register my overseas entity with Companies House?

Failure to register or update an overseas entity is a criminal offence that carries severe penalties. You could face daily fines of up to £2,500 and prison sentences of up to five years for serious non-compliance. Most importantly for investors, you’ll be legally restricted from selling, leasing, or charging the property, as the Land Registry will block any dealings involving an unregistered entity.

Can I get a UK mortgage as a non-resident?

You can obtain a UK mortgage as a non-resident, though you’ll likely need to approach specialist lenders or private banks. These lenders typically require a higher deposit, often 25% or more of the purchase price, and may charge higher interest rates than for UK residents. Your solicitor will work closely with the lender to satisfy their specific international due diligence and identity verification requirements.

UK Property Law for Foreign Nationals: A Comprehensive 2026 Guide

UK Property Law for Foreign Nationals: A Comprehensive 2026 Guide

The UK property market remains one of the most stable and attractive destinations for international capital, but the legal landscape in 2026 is far from simple. Whilst there are no restrictions on your right to buy, the reality of uk property law for foreign nationals now involves a complex web of residency tests and stringent transparency requirements. You likely recognise the prestige of a UK postcode, yet the fear of a surprise Stamp Duty bill or the anxiety of a rigorous compliance check can be daunting. It is a common concern, especially when the line between ‘resident’ and ‘tax resident’ feels increasingly blurred.

This guide offers the expert legal clarity you need to manage these complexities without the fear of unexpected tax liabilities. We’ll provide a definitive roadmap of the 2026 purchase process, from the mandatory registration of overseas entities with Companies House to the latest 60-day reporting deadlines for Capital Gains Tax. By understanding how to legally minimise your tax exposure and finding a solicitor who values discreet, high-standard service, you can secure your British assets with absolute peace of mind.

Key Takeaways

  • Confirm your legal right to own British real estate and understand the strategic differences between purchasing for personal use and commercial development.
  • Navigate the financial complexities of uk property law for foreign nationals, including the specific criteria for reclaiming the 2% non-resident Stamp Duty surcharge.
  • Streamline your purchase through remote conveyancing protocols that facilitate secure identity verification and document completion from anywhere in the world.
  • Determine the most tax-efficient ownership structure by weighing the benefits of personal title against the administrative requirements of registering an overseas entity.
  • Protect your long-term investment by mastering the unique British concepts of leasehold and freehold to mitigate the risks of rising ground rents.

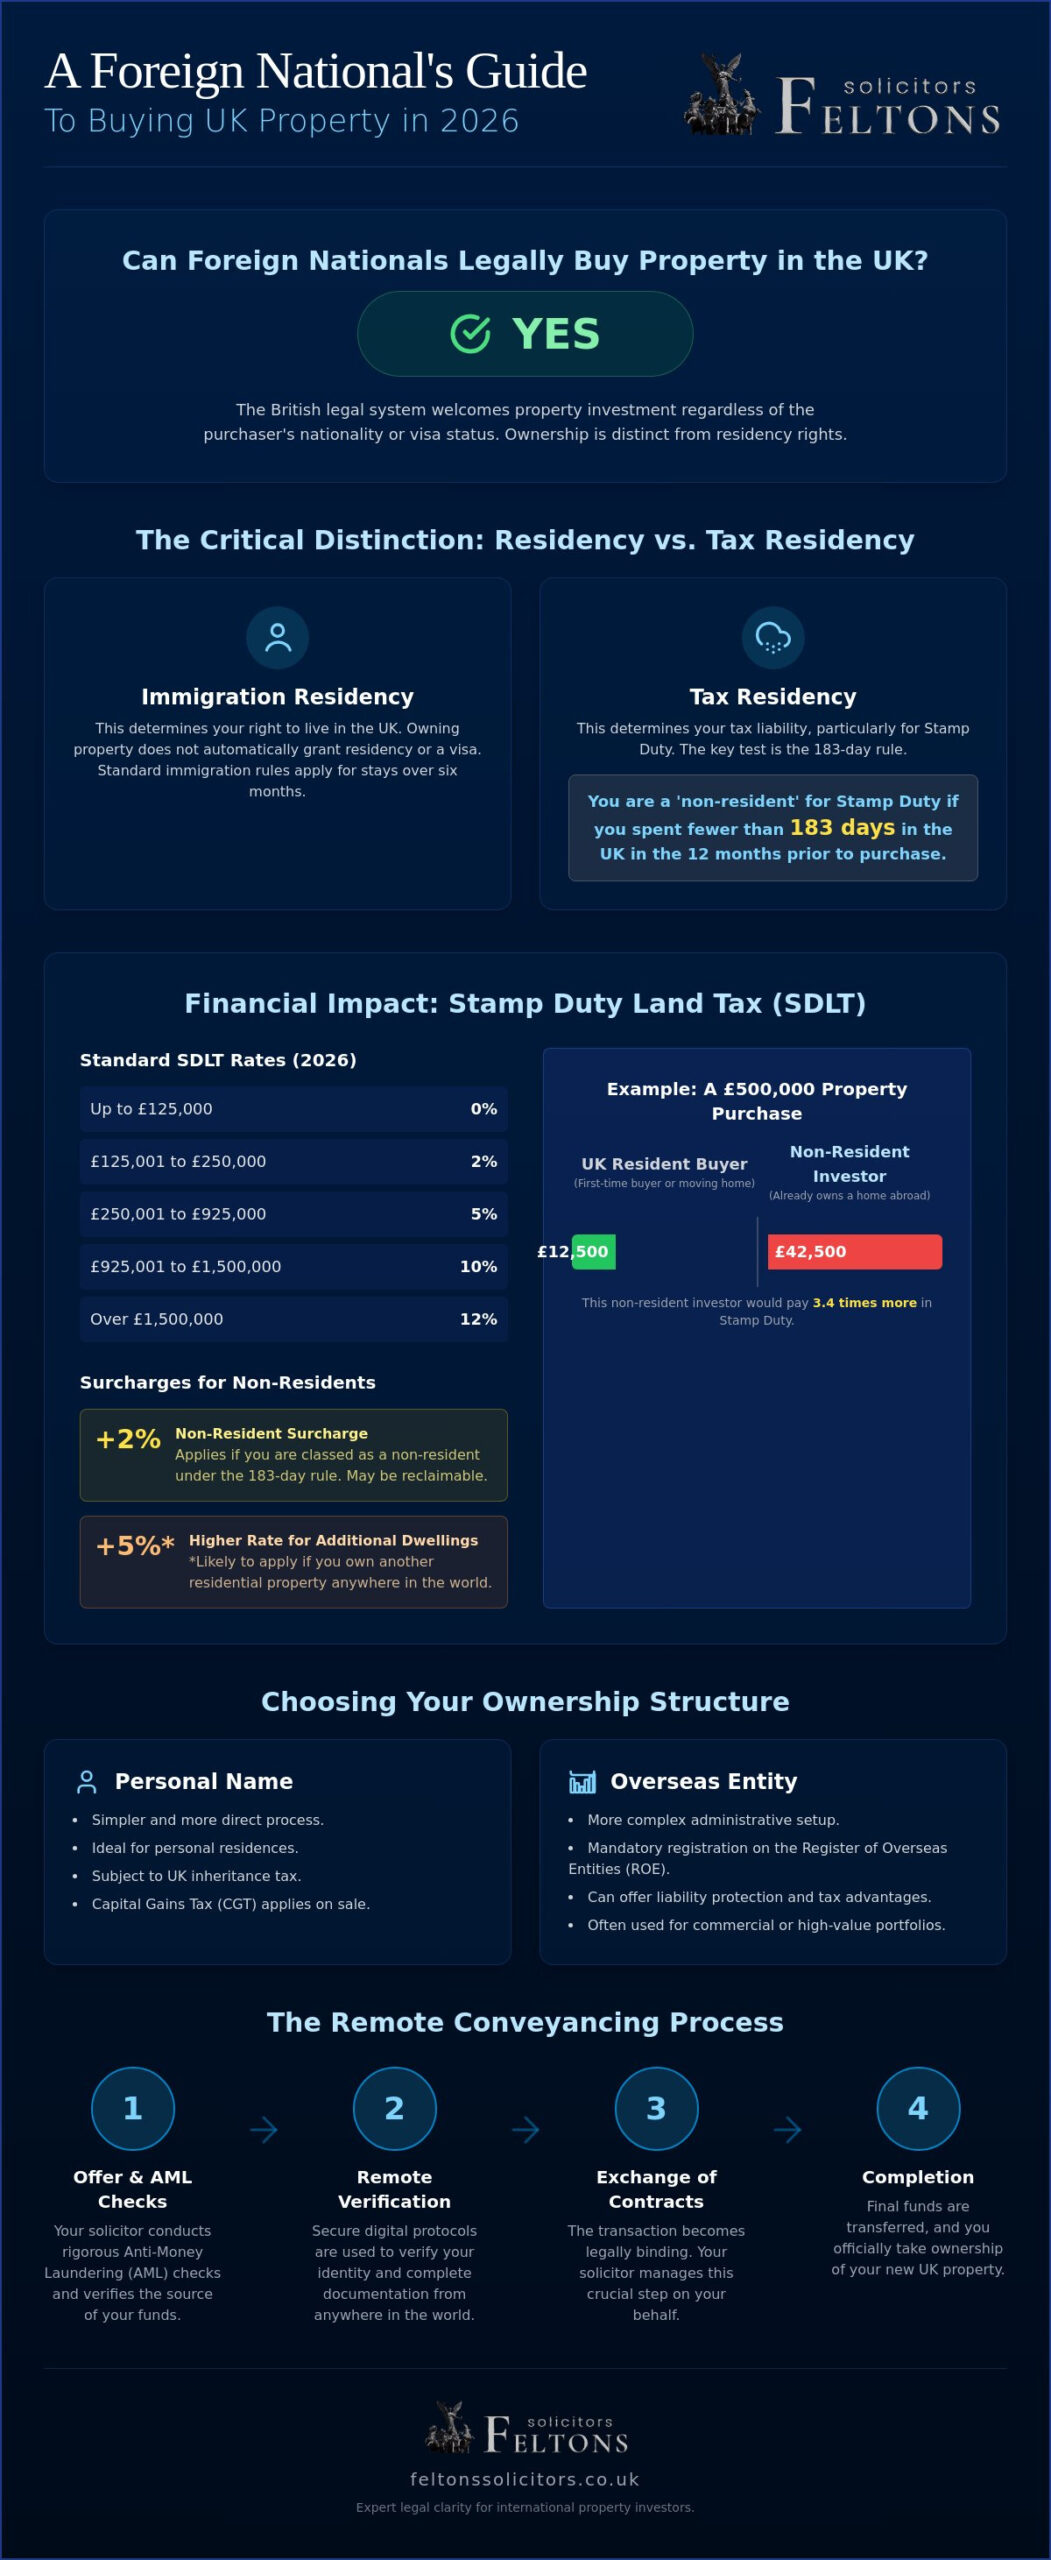
The UK remains one of the world’s most accessible property markets. Unlike many other nations that impose strict quotas or outright bans on international buyers, the British legal system welcomes investment regardless of the purchaser’s nationality. Understanding uk property law for foreign nationals is the first step toward a successful acquisition. You don’t need a UK passport or even a visa to own a piece of British soil; the market is open for personal residences, buy-to-let portfolios, and large-scale commercial developments alike.

This openness is underpinned by the stability of English land law, which provides a level of certainty and protection that few other jurisdictions can match. Even with the introduction of stricter transparency measures like the Register of Overseas Entities (ROE), the UK is still viewed as a ‘safe haven’ for international wealth. These regulations are designed to bolster market integrity rather than deter genuine investors. However, it’s vital to separate the right to own property from the right to live in it. Owning a house in London or a cottage in the Cotswolds doesn’t grant you residency rights or a path to a UK visa. You’ll still need to comply with standard immigration rules for stays exceeding six months.

Residency vs. Tax Residency: The 183-Day Rule

In 2026, the distinction between your immigration status and your tax residency is sharper than ever. For property transactions, the UK government uses a specific ‘non-resident’ test. You’re generally classed as a non-resident for Stamp Duty purposes if you’ve spent fewer than 183 days in the UK during the 12 months before your purchase. This isn’t just a technicality; it’s the trigger for a 2% surcharge on your Stamp Duty Land Tax (SDLT) bill. This rule applies even if you’re a British citizen living abroad or have a valid work visa.

The Role of the Solicitor in International Transactions

Managing a cross-border purchase requires more than just standard legal work. It demands a solicitor who understands the nuances of international wealth structures and the rigour of modern Anti-Money Laundering (AML) checks. Feltons Solicitors acts as a calm, steady guide during this process, ensuring all documentation is handled with discreet precision. We manage the ‘Exchange of Contracts’ and identity verification remotely, allowing you to secure your investment without needing to be physically present in the UK. Our role is to provide a boutique level of care, ensuring your transaction moves from offer to completion with absolute legal clarity whilst protecting your privacy at every stage.

The Financial Impact: SDLT Surcharges and Tax Residency Rules

Financial planning for a UK acquisition requires a granular understanding of the current tax regime. Whilst the market is open, the costs of entry are tiered based on your residency status and your existing global property portfolio. A fundamental pillar of uk property law for foreign nationals is the Stamp Duty Land Tax (SDLT), which is a graduated tax payable on the purchase price of a property. For residential purchases in England and Northern Ireland, the standard rates for 2026 follow a clear structure:

  • Up to £125,000: 0%
  • £125,001 to £250,000: 2%
  • £250,001 to £925,000: 5%
  • £925,001 to £1,500,000: 10%
  • Over £1,500,000: 12%

Foreign buyers must account for significant surcharges that sit atop these figures. A 2% surcharge applies to any non-UK resident purchasing a residential property costing £40,000 or more. If you already own a residential property anywhere else in the world, an additional 5% surcharge is likely to apply. This means an international investor could face a top-slice SDLT rate of 19% on the portion of the price above £1.5 million. Detailed guidance on Stamp Duty Land Tax for non-UK residents confirms that the 2% surcharge can sometimes be reclaimed if you spend more than 183 days in the UK during the year following your purchase.

Calculating Your Total Tax Liability

The total cost of your investment isn’t just the purchase price. A UK resident buying a £500,000 home might pay £12,500 in SDLT; however, a non-resident investor buying that same property as a second home could pay up to £47,500. It’s a stark difference that demands early budgeting. If a property is purchased jointly by a resident and a non-resident, the 2% surcharge is typically applied to the entire transaction value. You might find relief if the property is classed as commercial or mixed-use, as these transactions usually avoid the non-resident surcharge entirely. Engaging a firm with expertise in residential conveyancing ensures these calculations are precise from the outset.

Ongoing Tax Obligations for Foreign Landlords

Owning the asset is only the first stage of your tax journey. If you let the property, you’re subject to the Non-Resident Landlord Scheme (NRLS), where tenants or agents must withhold 20% of the rent for HMRC unless you’ve been authorised to receive gross payments. When you eventually decide to sell, you’ll need to navigate Capital Gains Tax (CGT), currently set at 18% for basic rate taxpayers and 24% for higher earners. You must report the sale and settle any CGT due within 60 days of completion, regardless of whether a tax liability actually exists. This rigorous reporting cycle reflects the UK’s commitment to transparency in uk property law for foreign nationals.

The journey from making an initial offer to receiving the keys is a structured legal process that demands meticulous attention to detail. In the context of uk property law for foreign nationals, this journey typically spans eight to twelve weeks, though complex international chains can extend this timeline. Once your offer is accepted, your solicitor begins the ‘Enquiries’ phase, scrutinising the title deeds and local authority searches to ensure no hidden liabilities exist. Whilst this happens, you should commission a comprehensive structural survey. Many British properties, particularly in historic urban centres, are sold as leaseholds. A survey is vital to identify potential maintenance issues or structural defects that could lead to significant future costs.

Remote conveyancing has become the standard for international clients. Modern legal practices use secure digital platforms for identity verification and document signing, meaning you rarely need to visit the UK in person to finalise your purchase. The most critical milestone is the ‘Exchange of Contracts’. At this point, the agreement becomes legally binding. In UK law, this is the point of no return; if you withdraw after this stage, you will likely lose your deposit and may face litigation for breach of contract. Completion follows shortly after, which is when the balance of funds is transferred and ownership officially passes to you.

Anti-Money Laundering (AML) and Source of Funds

Compliance is the most significant hurdle for many overseas buyers. UK law requires solicitors to perform exhaustive ‘Know Your Customer’ (KYC) checks to prevent financial crime. You’ll need to provide clear documentation regarding your ‘Source of Wealth’, which explains how you accumulated your total assets, and your ‘Source of Funds’ for this specific purchase. Common pitfalls include using offshore accounts without a clear audit trail or receiving gifted deposits from relatives without proper legal declarations. Providing this information early prevents delays and ensures you meet the Stamp Duty Land Tax rules for non-UK residents without administrative friction.

Securing Financing: UK Mortgages for Overseas Buyers

Securing a UK mortgage as a foreign national is entirely possible, though the criteria are stricter than for residents. Most lenders require a higher deposit, typically between 20% and 40% of the property value. Interest rates for ‘Expat’ or non-resident loans are generally higher, reflecting the lender’s perceived risk. You’ll also need to establish a UK-based bank account for monthly repayments. Navigating uk property law for foreign nationals effectively means having these financial arrangements in place before you begin your property search to demonstrate your status as a serious buyer.

UK Property Law for Foreign Nationals: A Comprehensive 2026 Guide

Ownership Structures: Personal Names vs. Registering Overseas Entities

Deciding how to hold your British assets is a choice that balances administrative simplicity against long-term tax efficiency. Buying in a personal name is the most straightforward path. It avoids the complexities of company filings and the necessity for annual accounts. However, many sophisticated investors prefer using a UK Limited Company, particularly when building a portfolio. This structure can offer significant advantages regarding mortgage interest relief and Corporation Tax rates, though it does come with higher ongoing administrative costs. This choice is a central pillar of uk property law for foreign nationals and should be made after considering your exit strategy and global tax position.

If you choose to buy through a foreign company, you must comply with the Register of Overseas Entities (ROE). This requirement, introduced under the Economic Crime (Transparency and Enforcement) Act 2022, is mandatory for any foreign entity that wants to buy, sell, or lease land in the UK. The process involves a £250 digital registration fee and an annual update statement that costs £134. Feltons Solicitors provides a bespoke service for overseas entity beneficial owner registration, ensuring your investment remains fully compliant and marketable whilst protecting your privacy where legally permitted.

The Register of Overseas Entities (ROE) Explained

Transparency is the driving force behind the ROE. Foreign companies holding UK land must declare their beneficial owners and managing officers to Companies House. A UK-regulated agent must verify this information before the entity can be registered. The consequences of non-compliance are severe. Without a valid Overseas Entity ID, you’ll be unable to register your title at the Land Registry, effectively preventing you from selling, leasing, or charging the property. Failure to update the register annually is also a criminal offence, which can lead to daily fines or even imprisonment for company officers.

Joint Ownership Options: Tenants in Common vs. Joint Tenants

For those buying with a partner or business associate, the legal structure of that partnership is vital. Joint Tenants own the property together as a single legal entity; if one owner passes away, their share automatically transfers to the survivor. Conversely, Tenants in Common own specific, defined shares, which can be passed on via a Will to anyone of their choosing. This is often the preferred route for international wealth protection, as it allows for more flexible estate planning. We strongly recommend a ‘Declaration of Trust’ to clearly define these shares and protect each party’s interests. Professional support for the Registration of Overseas Entities ensures your ownership structure is robust from the outset.

Managing Your Investment: Leasehold Rights and Estate Planning

Securing your property is only the beginning of your journey with uk property law for foreign nationals. In England and Wales, a significant portion of urban property, particularly apartments, is sold as leasehold. This means you own the right to occupy the building for a set period, whilst the ‘freeholder’ retains ownership of the land itself. It’s a unique legal concept that requires active management. You must stay vigilant regarding ground rents and service charges; if these costs rise disproportionately, they can diminish the marketability and value of your asset. Professional leasehold management ensures your rights are protected and your investment remains a stable pillar of your international portfolio.

Effective property management also involves maintaining safety standards; for investors purchasing in the Dundee area, Foster Electrical provides a local, reliable service for electrical safety checks and comprehensive rewiring.

You must also look ahead to the eventual transfer of your wealth. UK-sited assets, including all residential property, are generally subject to UK Inheritance Tax (IHT). Currently, this is charged at a rate of 40% on any value exceeding the £325,000 nil-rate band. Whilst an additional residence nil-rate band of up to £175,000 may be available if you leave a home to direct descendants, the criteria are strict. It’s also vital to note that from April 2025, the UK moved to a residency-based system for IHT. Individuals who’ve been UK residents for 10 of the previous 20 tax years may find their worldwide assets fall within the UK tax net. Relying on a foreign Will to dispose of a British home often leads to significant delays and legal friction. A dedicated UK Will ensures your property is handled according to English law with minimal administrative burden.

Lease Extensions and Enfranchisement for Overseas Owners

For those owning flats, the statutory right to extend your lease becomes available after two years of continuous ownership. This is a vital mechanism for preserving the value of your asset. Leases with fewer than 80 years remaining can become significantly more expensive to extend and difficult to remortgage. Our leasehold enfranchisement experts provide pragmatic advice on navigating these claims. We manage the entire process, including complex negotiations and dispute resolution with freeholders, ensuring your interests are represented whilst you are abroad.

Succession and Estate Planning for International Clients

UK property doesn’t exist in a vacuum; it sits within the context of your global estate. This creates a potential risk of double taxation depending on the treaties between the UK and your home jurisdiction. Integrating your British assets into a comprehensive estate planning strategy allows for the legal minimisation of tax exposure. Managing these matters requires a specialist firm that understands the nuances of international wealth structures. We act as a discreet partner, ensuring your legacy is protected and that your beneficiaries aren’t left navigating a complex legal maze without expert guidance.

Securing Your British Assets with Confidence

The UK property market remains a premier destination for global investors, yet the path to a successful acquisition in 2026 is paved with specific regulatory obligations. We’ve explored how understanding the nuances of uk property law for foreign nationals is essential, from managing the 2% non-resident Stamp Duty surcharge to ensuring your company is correctly listed on the Register of Overseas Entities. Success isn’t just about the initial purchase; it requires a proactive approach to leasehold management and robust estate planning to protect your legacy against future tax liabilities.

At Feltons Solicitors, we act as your discreet partner throughout this journey. We provide pragmatic, expert advice for international clients, specialising in the Registration of Overseas Entities and comprehensive property services. Whether you’re navigating the complexities of cross-border wealth structures or securing your assets for the next generation, our team offers the steady guidance you deserve. Contact Feltons Solicitors for expert guidance on your UK property purchase and ensure your investment is built on a foundation of absolute legal clarity. Your British property journey should be a source of security, not stress.

Frequently Asked Questions

Do I need to be in the UK to complete a property purchase?

You don’t need to be physically present in the UK to finalise your transaction. Remote conveyancing allows solicitors to manage identity verification and the exchange of contracts through secure digital platforms. Whilst you’ll need to provide certified documents, the entire process from offer to completion can be handled from your home country with ease.

Can I buy property in the UK if I have a criminal record in my home country?

Generally, yes, as there are no legal restrictions preventing those with a criminal record from owning British real estate. However, you’ll face much more rigorous Anti-Money Laundering checks during the purchase process. Mortgage lenders may also view your application with increased scrutiny, so it’s vital to be transparent with your legal team from the outset. For international buyers who need to resolve or clarify legal issues in the US, the Law Office of Kevin Bessant & Associates provides expert criminal defence representation to help clear your path for global investment.

How much is the non-resident Stamp Duty surcharge in 2026?

The non-resident surcharge remains at 2% for the 2026 tax year. This is a flat rate added to the standard Stamp Duty Land Tax (SDLT) brackets for residential properties costing £40,000 or more. It’s a critical component of uk property law for foreign nationals that applies if you haven’t been present in the UK for at least 183 days in the 12 months prior to your purchase.

Is it better to buy UK property in a company name or personal name?

The right choice depends on your long-term investment strategy and your total portfolio size. Purchasing in a personal name is simpler and avoids the costs associated with the Register of Overseas Entities. Conversely, using a UK Limited Company can be more tax-efficient for buy-to-let investors, though it involves higher administrative fees and mandatory annual filings. Navigating uk property law for foreign nationals requires weighing these administrative burdens against potential tax savings.

What documents do I need to prove my source of funds as a foreign national?

You’ll need to provide a clear audit trail showing exactly how your capital was acquired. This typically includes six months of bank statements, payslips, or tax returns from your home country. If your funds come from the sale of an asset or an inheritance, you’ll need the corresponding legal documentation to satisfy the UK’s strict ‘Know Your Customer’ requirements.

Can I get a UK mortgage if I don’t have a UK credit history?

You can secure a mortgage without a UK credit history by using specialist international or ‘Expat’ lenders. These providers assess your global wealth and income rather than just your UK credit file. You should expect to provide a larger deposit, often between 25% and 40% of the property value, and pay slightly higher interest rates than a UK resident.

Does buying a house in London or the UK give me a ‘Golden Visa’?

No, property ownership does not grant any residency or immigration rights in the UK. The British government doesn’t offer a ‘Golden Visa’ or investment-based residency through real estate purchases. You must still meet standard visa requirements if you intend to live in the property for more than six months a year, regardless of the property’s value.

What happens to my UK property if I die without a UK Will?

Your British assets will be distributed according to the UK’s intestacy rules, which may not align with your personal wishes or your home country’s laws. This process is often slow and expensive for international families, potentially leading to significant Inheritance Tax complications. Drafting a specific UK Will is the only way to ensure your property passes to your chosen beneficiaries without unnecessary legal friction.