Non-Resident Capital Gains Tax: Specialist UK Property Solicitors

Non-Resident Capital Gains Tax: Specialist UK Property Solicitors

For an international property owner, the most critical phase of a UK sale isn’t the exchange of contracts, but the sixty days that follow it. Missing this narrow window for reporting and payment can lead to immediate HMRC penalties, even if no tax is actually due. Engaging specialist non-resident capital gains tax uk property solicitors ensures that your disposal is handled with the precision required to meet these stringent deadlines. You’ve likely noticed that the UK tax landscape has become increasingly complex, moving from a relatively relaxed regime to one defined by real-time reporting and the rigorous transparency of the Register of Overseas Entities.

It’s understandable to feel a sense of trepidation when facing these evolving regulations, but with the right guidance, you can manage your obligations with confidence. This article provides a clear roadmap for navigating non-resident CGT, showing you how to minimise your liability through strategic rebasing and ensure your conveyancing process proceeds without delay. We’ll examine the current 2026-2027 tax rates, the nuances of the 60-day reporting window, and how to maintain full compliance whilst protecting your investment’s value.

Key Takeaways

  • Master the strict 60-day reporting and payment window to ensure full compliance and avoid costly HMRC penalties.
  • Explore how rebasing your property value to 2015 or 2019 levels can effectively minimise your overall tax liability.
  • Understand why registration with the Register of Overseas Entities is a mandatory prerequisite for any valid UK land transfer.
  • Discover how non-resident capital gains tax uk property solicitors provide an integrated approach to conveyancing and tax reporting.
  • Recognise the common pitfall of failing to report a disposal to HMRC, even in instances where no tax is actually payable.

Understanding Non-Resident Capital Gains Tax (NRCGT) in the UK

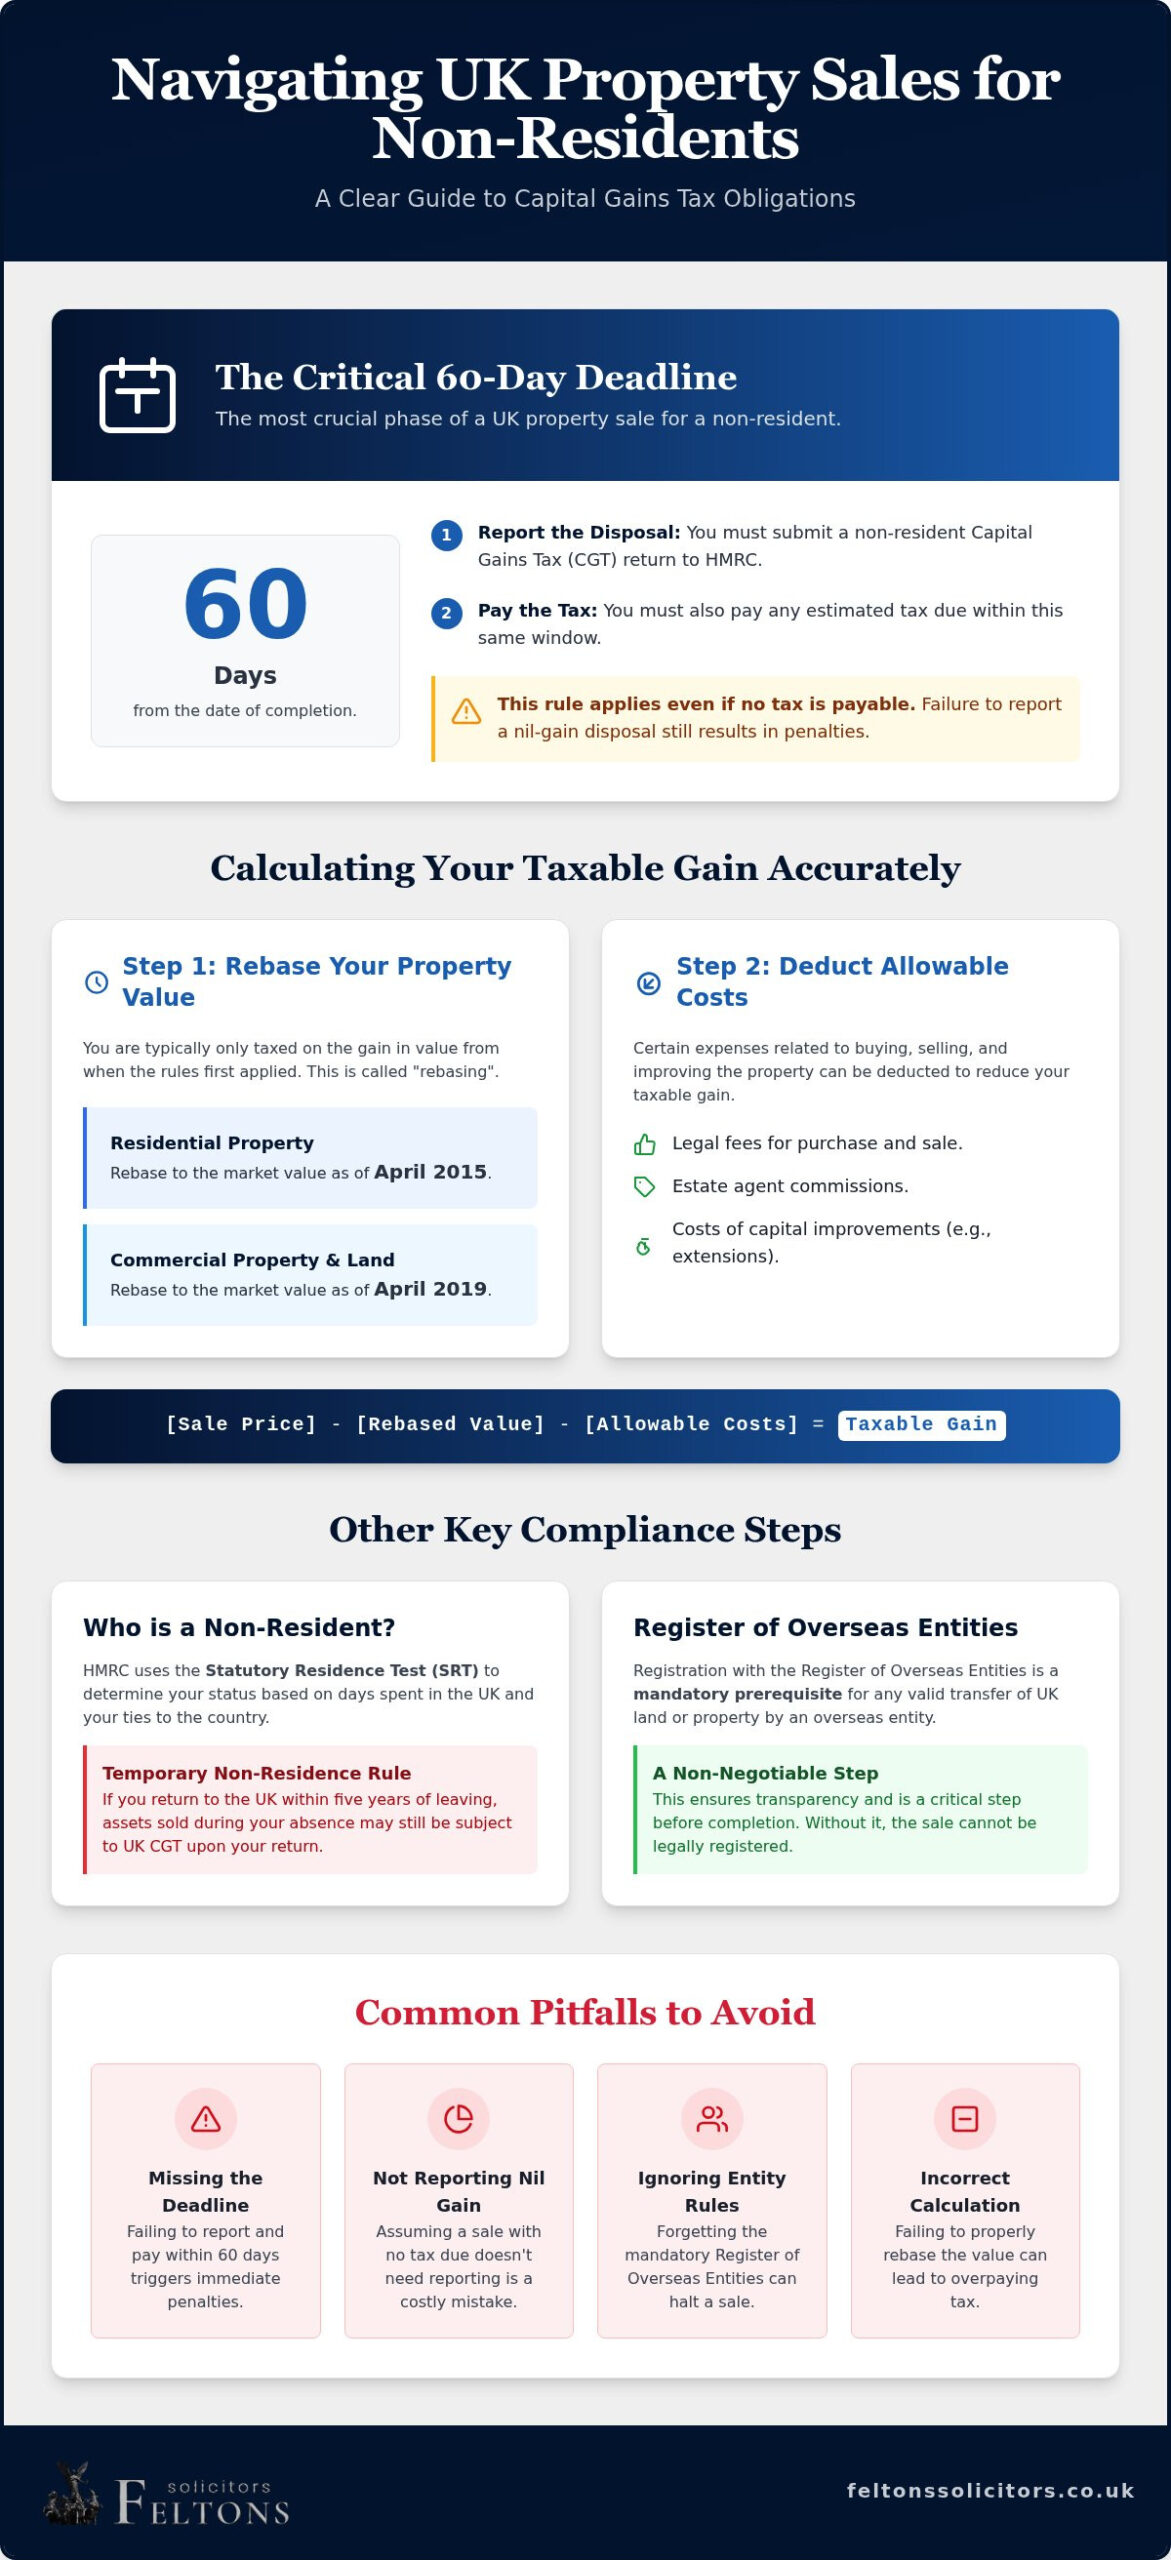
NRCGT is the tax due on profits made from disposing of UK land or property whilst living abroad. This specific branch of Capital Gains Tax in the United Kingdom has seen significant expansion over the last decade. In 2015, the UK government introduced these rules for residential assets, extending them in April 2019 to include all non-residential property and land. The logic behind this shift was to align the tax treatment of overseas owners with that of UK residents, ensuring a level playing field across the property market. Whether you’re selling a buy-to-let flat or a commercial warehouse, the profit is now firmly within the HMRC net. Engaging non-resident capital gains tax uk property solicitors early in the process is essential to understand which specific tax triggers apply to your disposal.

Who is Classified as a Non-Resident?

Determining your status isn’t always straightforward. HMRC uses the Statutory Residence Test (SRT) to assess how many days you’ve spent in the UK and the nature of your ties to the country. This classification extends beyond individuals to include trustees and personal representatives of deceased estates. A common complication arises with “temporary non-residence” rules. If you leave the UK and return within five years, assets sold during your absence might still be subject to UK tax upon your return. Because these rules are nuanced, consulting non-resident capital gains tax uk property solicitors before you list a property is the most secure way to clarify your liability and residency status.

The 60-Day Reporting and Payment Rule

The timeline for compliance is exceptionally tight. You must report the disposal and pay any tax due within 60 days of the completion date. It’s a frequent misconception that you can simply wait until your annual self-assessment return to declare the sale. This mistake is costly. Failing to file within this window triggers immediate penalties and accruing interest, even if there’s no tax to pay. For many international clients, legal experts provide the necessary oversight to ensure these filings are accurate and timely. This proactive approach prevents the stress of HMRC investigations and avoids unnecessary financial loss at the end of a transaction.

Calculating Capital Gains for Overseas Sellers

Calculating the gain on a UK property disposal is rarely as simple as subtracting the purchase price from the sale price. For international owners, the UK tax system allows for “rebasing,” which means you only pay tax on the growth in value from specific dates. For residential property, this is generally April 2015, whilst for commercial property, the date is April 2019. This provision is designed to ensure that gains accrued before these rules applied to non-residents aren’t unfairly taxed. Expert non-resident capital gains tax uk property solicitors play a vital role here, ensuring that the completion statement and acquisition data are precisely aligned for HMRC.

To establish a robust tax position, professional valuations at these rebasing dates are highly recommended. HMRC may challenge self-estimated figures, so having a formal report provides a layer of security. Additionally, some expats may still benefit from Private Residence Relief (PRR) for the period they occupied the property as their main home. This can significantly reduce the taxable gain, provided the residency criteria are strictly met. For a deeper look at the technical framework used by legal professionals, the official guidance on Non-Resident Capital Gains Tax outlines the current statutory requirements.

Residential vs Commercial Property Calculations

The distinction between residential and commercial assets is fundamental. Residential dwellings have been subject to these rules since 2015, whereas commercial property and indirect disposals, such as selling shares in a property-rich company, only fell into the scope in April 2019. It’s important to focus on the “gain” rather than just the “proceeds” of the sale. The gain is the profit remaining after accounting for the rebased value and all eligible deductions. Non-resident capital gains tax uk property solicitors can help you identify which rebasing method is most advantageous for your specific circumstances.

Deducting Costs and Professional Fees

You can effectively reduce your tax liability by deducting specific costs associated with the sale and acquisition. These include:

  • Legal fees for both the purchase and the eventual sale
  • Estate agent commissions and professional marketing costs
  • Stamp Duty Land Tax (SDLT) paid upon the initial purchase
  • Capital expenditure, such as structural extensions or significant improvements

It’s crucial to distinguish between capital improvements, which are deductible, and general maintenance or repairs, which are not. When managing a high-value disposal, having specialist property solicitors handle your conveyancing ensures that all deductible legal costs are clearly documented and evidenced for your tax filing.

The Register of Overseas Entities: A Critical Compliance Step

For corporate owners and foreign trusts, the ability to sell UK land is now inextricably linked to transparency. The Register of Overseas Entities (ROE), managed by Companies House, requires any foreign legal entity owning UK property to identify and verify its beneficial owners. This isn’t merely a reporting exercise; it’s a fundamental gatekeeper in the conveyancing process. An overseas entity cannot sell UK property without a valid Overseas Entity ID. Without this unique identifier, the Land Registry will simply refuse to register the transfer of title to a buyer, effectively freezing your assets in place. Non-resident capital gains tax uk property solicitors ensure that this registration is not only active but fully compliant with the latest 2026 regulations before a sale is even negotiated.

Maintaining your standing on the register requires constant vigilance. An annual update statement must be filed within 14 days of the anniversary of your initial registration. HMRC and Companies House use this data to ensure that the individuals profiting from UK land are clearly identified. If your registration has lapsed or the annual update is overdue, your Overseas Entity ID becomes invalid. This can lead to catastrophic delays during the final stages of a transaction, often at the very moment you are preparing to settle your capital gains tax obligations.

ROE Verification and the Role of the Solicitor

The verification process is the most rigorous aspect of the ROE. A UK-regulated professional must independently verify the identity of all registrable beneficial owners before the information is submitted. This step is designed to prevent disputes and ensure that the “people with significant control” are accurately documented. It’s a complex task, particularly when dealing with multi-layered international corporate structures or discretionary trusts. For a detailed breakdown of this process, you may find our guide on Overseas Entity Beneficial Owner Registration helpful. Specialist non-resident capital gains tax uk property solicitors provide the pragmatic oversight needed to bridge the gap between international corporate law and UK property compliance.

Consequences of Non-Compliance for Sellers

The risks of ignoring ROE obligations are severe and go beyond simple administrative hurdles. If an entity fails to register or update its details, the Land Registry places a “restriction” on the property’s title. This restriction prevents the entity from selling, leasing, or charging the land. Beyond the commercial impact, non-compliance is a criminal offence. Directors or officers of a non-compliant entity can face significant daily fines or even imprisonment. Organising your documentation well in advance of your sale date is the only way to avoid these sanctions. By integrating ROE compliance with your wider tax strategy, you ensure a smooth exit from your UK investment without the threat of legal or financial paralysis.
Non-Resident Capital Gains Tax: Specialist UK Property Solicitors

Common Pitfalls for Non-Resident Property Owners

HMRC compliance is rarely intuitive, and for international owners, the margin for error is non-existent. One of the most frequent errors involves the disposal date. Whilst the tax year of the sale is determined by the date of exchange, the 60-day reporting window begins strictly on the date of completion. Miscalculating this distinction can result in automatic penalties before you’ve even realised the deadline has passed. Additionally, properties held within corporate structures may have existing obligations under the Annual Tax on Enveloped Dwellings (ATED). The interaction between ATED-related gains and standard NRCGT is complex, often requiring non-resident capital gains tax uk property solicitors to untangle the overlapping liabilities and ensure you aren’t overpaying.

Logistical hurdles also pose a significant threat to a smooth exit. Anti-money laundering (AML) checks for international clients are now more rigorous than ever. Underestimating the time required for these checks, or for international currency transfers, can delay the entire conveyancing process. If these delays push your reporting past the sixty-day mark, HMRC will not accept bank delays or administrative friction as a valid excuse for late filing. It’s a high-stakes environment where timing is as important as the financial calculation itself.

Reporting a Sale with No Tax Due

A common HMRC trap is the belief that a loss-making sale or a break-even disposal requires no action. This is incorrect. Non-residents must file a “nil return” to declare the disposal, even if no tax is payable. Failing to submit this return within the 60-day window triggers the same penalty regime as a high-profit sale. Establishing this paper trail is not just about avoiding fines; it’s also essential for your own international tax reporting, providing clear evidence to your local tax authorities that the disposal has been handled according to UK law. For those with broader European interests, such as in Italy, professional Italian fiscal representation services can assist in ensuring that all cross-border reporting is accurately synchronised.

The UK maintains an extensive network of double taxation treaties amongst different nations to ensure that you aren’t taxed twice on the same gain. In most instances, you can claim credit for the UK CGT paid against your local tax liability in your country of residence. However, the mechanics of claiming this credit vary significantly between jurisdictions. Coordinated advice between your UK legal team and local tax advisors is the only way to ensure you aren’t left out of pocket. If you are concerned about how these pitfalls might affect your sale, you should contact our property law specialists for a comprehensive compliance review.

How Feltons Solicitors Manage Your Non-Resident Disposal

Most firms treat property law and tax compliance as separate silos, often leaving the client to coordinate between a conveyancer and an accountant. At Feltons Solicitors LLP, we provide a sophisticated, integrated service that bridges this gap. Our role as non-resident capital gains tax uk property solicitors is to manage the entire lifecycle of your disposal, from the initial legal due diligence to the final HMRC submission. We provide discreet and professional representation for high-net-worth individuals and international corporate investors, ensuring that every transaction is handled with the quiet confidence and precision it deserves. Our people-first philosophy means we prioritise your peace of mind, acting as a steady guide through the often stressful landscape of UK tax regulations.

We understand that international property owners face unique pressures, particularly when dealing with high-value estates and multi-layered corporate structures. Our team is equipped to handle the most complex matters with a boutique level of care, ensuring that your personal rapport with your solicitor remains at the heart of our service. By combining modern efficiency with traditional professional integrity, we protect your interests whilst maintaining the highest standards of HMRC compliance.

Our Proactive Approach to the 60-Day Window

The sixty-day reporting window is unforgiving, and we don’t believe in leaving compliance to the final hour. We begin preparing your NRCGT return alongside the conveyancing process, often starting the work as soon as contracts are exchanged. This proactive stance allows us to accurately capture all deductible costs, including acquisition legal fees and capital expenditure, to minimise your eventual tax liability. For those managing a broader portfolio, our guide on Navigating Residential Property Law provides essential context for maintaining residential assets in the UK. By the time completion occurs, the majority of the tax work is already finalised, allowing for a seamless transition to the reporting phase.

Specialist Support for Overseas Entities

For clients holding property through foreign companies or trusts, we manage the Register of Overseas Entities (ROE) registration and verification process entirely in-house. This ensures that your Overseas Entity ID is valid and your annual update statements are current long before they are required for a Land Registry transfer. We act as a trusted advisor for long-term UK property portfolios, providing the worldly experience necessary to handle international-scale matters with ease. If you are planning a disposal or require expert guidance on your current tax position, we invite you to contact our property team for a professional consultation.

Securing Your UK Property Exit

Successfully managing a UK property disposal as a non-resident requires a meticulous approach to timing and transparency. We have explored how the strict 60-day reporting window and the Register of Overseas Entities have transformed the compliance landscape for international owners. By leveraging rebasing rules and identifying all allowable deductions, you can significantly reduce your tax burden whilst maintaining a clear standing with HMRC.

Navigating these complexities is far simpler with the support of non-resident capital gains tax uk property solicitors who understand the intersection of conveyancing and tax law. Feltons Solicitors provides a comprehensive service. We offer pragmatic legal advice for international clients and specialist expertise in Overseas Entity Registration. You can instruct Feltons Solicitors for your UK property disposal to ensure your transaction is handled with the highest level of professional integrity and care. With the right legal partner, your exit from the UK market can be both fully compliant and commercially rewarding.

Frequently Asked Questions

Do I have to pay Capital Gains Tax if I am not a UK resident?

Yes, non-residents are liable for CGT on the disposal of all UK land and property. This includes residential dwellings, commercial buildings, and land without structures. The tax is calculated on the profit made during the period of ownership, subject to specific rebasing rules. Expert guidance from non-resident capital gains tax uk property solicitors is recommended to ensure you apply the correct rates for the 2026-2027 tax year.

What is the 60-day rule for non-resident CGT?

The 60-day rule requires non-residents to report the disposal of UK property and pay any tax due within sixty days of completion. It is a common error to assume the clock starts at the exchange of contracts. Missing this window triggers automatic penalties. Because this timeline is exceptionally tight, we prepare the necessary documentation alongside the conveyancing process to ensure you remain fully compliant with HMRC’s real-time reporting requirements.

How is CGT calculated for a non-resident selling UK property?

Calculations for non-residents typically focus on the gain accrued since April 2015 for residential property or April 2019 for commercial assets. This rebasing ensures you aren’t taxed on growth that occurred before the current rules applied to overseas owners. You subtract the rebased value and allowable expenses from the final sale price. For the 2026-2027 tax year, residential rates are 18% or 24% depending on your total UK income and gains.

Can I deduct my solicitor fees from my Capital Gains Tax bill?

Yes, you can deduct professional fees from the gain to reduce your overall tax liability. This includes the legal costs incurred during both the acquisition and the disposal of the property. Other deductible expenses include estate agent commissions, Stamp Duty Land Tax paid at purchase, and capital expenditure for structural improvements. Keeping precise records of these costs is essential for non-resident capital gains tax uk property solicitors to maximise your available tax relief.

What happens if I miss the HMRC reporting deadline?

Missing the 60-day deadline results in immediate financial penalties and accruing interest on any unpaid tax. Initial late filing penalties are usually £100, but these increase significantly if the return is more than three or six months overdue. HMRC rarely accepts administrative delays or international bank friction as a valid excuse. Proactive legal management ensures that your reporting is submitted accurately and on time, avoiding these unnecessary costs and potential investigations.

Do I need to report the sale if I made a loss on the property?

You must report the disposal to HMRC even if the sale resulted in a loss or no tax is due. This is a mandatory requirement for all non-residents disposing of UK land. Failing to submit a nil return within the 60-day window triggers the same penalty regime as a profitable sale. Reporting a loss is also beneficial, as it can often be offset against future UK capital gains to reduce your future tax liabilities.

Is commercial property treated differently for non-resident CGT?

Commercial property disposals follow the same 60-day reporting window but use a different rebasing date of April 2019. Unlike residential property, which was brought into the non-resident CGT net in 2015, commercial assets and indirect disposals only became taxable for non-residents in 2019. The calculation methods and tax rates can also differ, particularly if the property is held within a corporate structure rather than being owned by an individual.

How does the Register of Overseas Entities affect my property sale?

The Register of Overseas Entities is a mandatory compliance step for any foreign company or trust owning UK land. You cannot legally transfer the title to a buyer without a valid Overseas Entity ID from Companies House. If your registration isn’t current or your annual update is overdue, the Land Registry will block the sale. We handle the verification and registration process in-house to ensure your transaction proceeds without any regulatory delays.
Register of Overseas Entities Guidance: A Comprehensive Legal Framework for 2026

Register of Overseas Entities Guidance: A Comprehensive Legal Framework for 2026

A simple filing error on the Register of Overseas Entities is no longer just an administrative oversight; in 2026, it’s a direct path to a frozen property portfolio and potential criminal prosecution. This register of overseas entities guidance serves as your definitive roadmap through the increasingly stringent requirements of the Economic Crime Act 2022. Companies House has shifted its focus from encouraging transparency to robust enforcement, making precision more critical than ever before.

We recognise that identifying beneficial owners within multi-layered corporate structures often feels like solving a complex puzzle where the rules are constantly shifting. It’s natural to feel a sense of unease regarding the threat of heavy fines or the difficulty of securing a regulated UK verification agent whilst managing international interests. You deserve a legal partner who provides calm, expert clarity instead of added pressure.

By following this framework, you’ll master the intricacies of the new trust disclosure rules and ensure your property transactions remain seamless and secure. We will examine the registration process, the necessity of professional verification, and the strict 14-day window for your mandatory annual updates. This guide ensures you remain in full compliance, protecting both your reputation and your UK assets.

Key Takeaways

  • Identify registrable beneficial owners with precision by applying the three primary tests and the 25% control threshold.
  • Secure your property interests by obtaining expert register of overseas entities guidance to navigate mandatory verification through a regulated UK professional.
  • Protect your assets from Land Registry blocks and criminal penalties by mastering the strict 14-day filing window for annual update statements.
  • Recognise how a tailored legal approach integrates compliance into your broader property strategy to ensure seamless long-term management.

Understanding the Register of Overseas Entities (ROE) Requirements

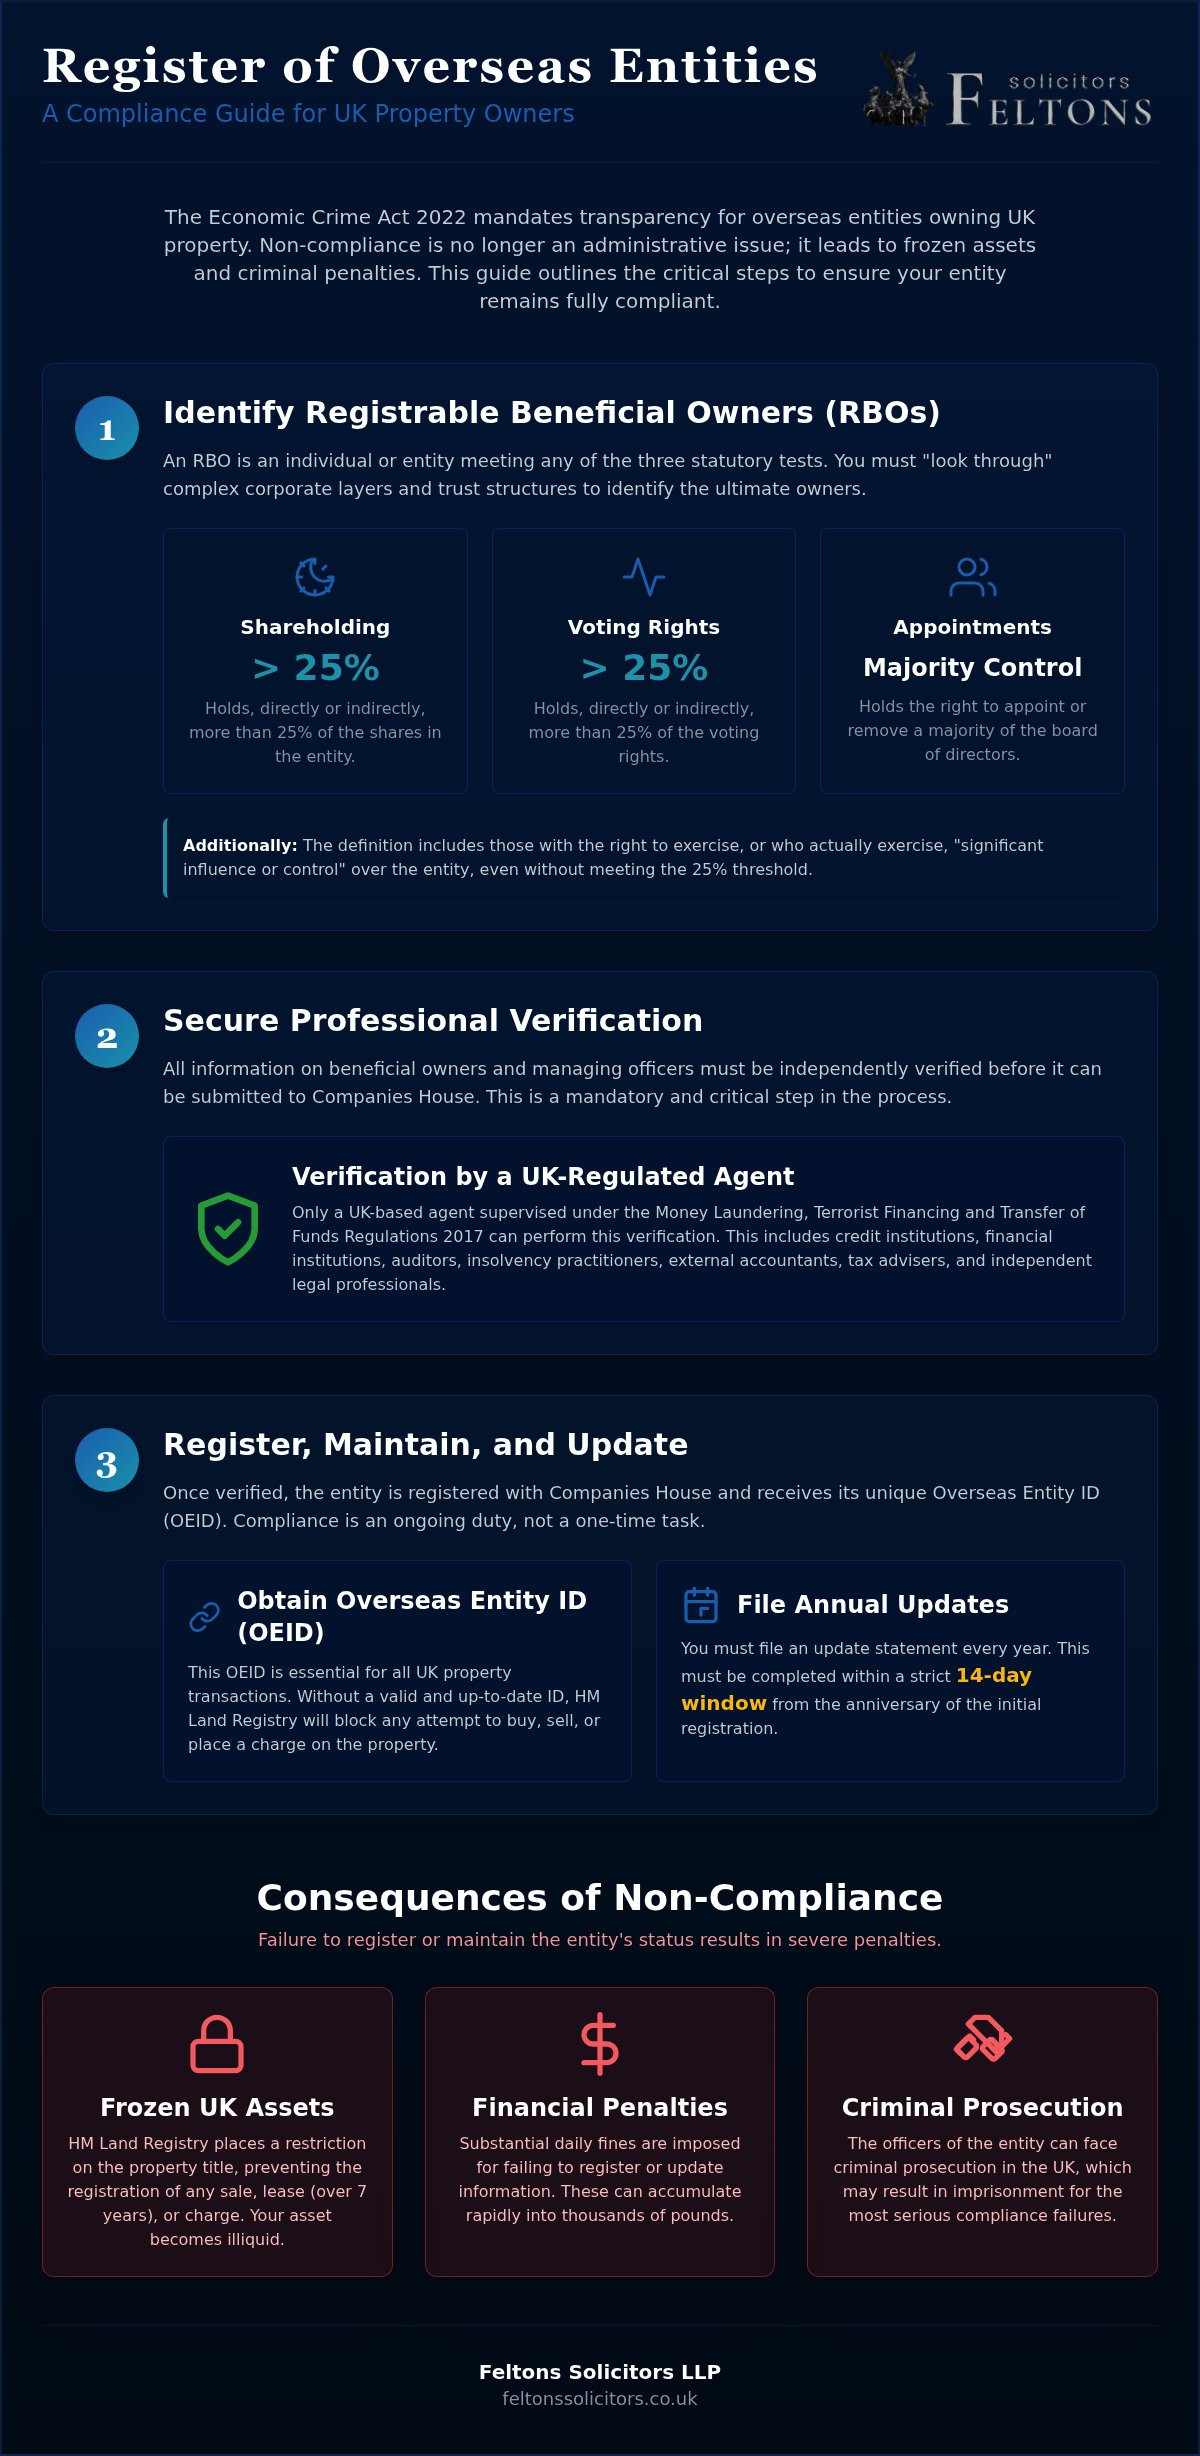
The Register of Overseas Entities (ROE) serves as a critical transparency tool within the UK’s legal system. Its primary purpose is to reveal the true owners of UK land held through foreign structures, curbing the use of anonymous offshore vehicles for illicit gains. This requirement was formalised under the Economic Crime (Transparency and Enforcement) Act 2022, which fundamentally altered the compliance obligations for international investors. By creating a public record of beneficial ownership, the government aims to foster a more accountable and secure property market.

An “overseas entity” is broadly defined as any legal person, such as a corporation or partnership, that is governed by the law of a country or territory outside the United Kingdom. If your entity owns, or intends to acquire, qualifying UK property, registration with Companies House is mandatory. Failing to adhere to this register of overseas entities guidance can lead to severe repercussions. Beyond the daily fines that can reach thousands of pounds, officers of the entity face potential imprisonment. We understand how daunting these criminal sanctions appear, yet they are avoidable with a methodical approach to your legal duties.

The Scope of the Legislation in 2026

The current framework is comprehensive, covering various legal structures including foreign companies and limited partnerships. One of the most significant aspects is its retrospective nature. In England and Wales, the rules apply to all land purchased on or after 1 January 1999. Once registered, the entity receives a unique Overseas Entity ID (OEID). This number is the “golden ticket” for any modern property transaction. Without a valid OEID, you cannot complete a purchase, sale, or lease of more than seven years. It’s a simple identifier that carries immense weight in the eyes of the law.

The Interplay with HM Land Registry

Compliance is enforced through a symbiotic relationship between Companies House and HM Land Registry. The Land Registry places a restriction on the title of any property owned by an overseas entity. This restriction effectively freezes the asset. You won’t be able to register a transfer of title, a lease, or a legal charge unless the entity is fully compliant and its registration is up to date. Proactive management is vital. Waiting until a disposal is underway to seek register of overseas entities guidance often leads to costly delays and broken chains in the conveyancing process. A clear status at the Land Registry ensures your property remains a liquid asset rather than a legal burden.

Identifying and Disclosing Registrable Beneficial Owners (RBOs)

Determining who truly holds the reins of a foreign company requires more than a glance at a share certificate. This register of overseas entities guidance prioritises the accurate identification of Registrable Beneficial Owners (RBOs), a process that involves three rigorous statutory tests. An individual or legal entity is typically registrable if they meet any of the following criteria:

  • Holding, directly or indirectly, more than 25% of the shares in the entity.
  • Holding, directly or indirectly, more than 25% of the voting rights.
  • Holding the right, directly or indirectly, to appoint or remove a majority of the board of directors.

Some individuals exert power through “significant influence or control” without holding a formal majority. This often occurs amongst family offices or private equity arrangements where veto rights or bespoke articles of association exist. If your exhaustive search yields no RBOs, you must instead provide details for every “managing officer” of the entity. Following official Companies House guidance is essential to ensure these declarations are legally sound and prevent future disputes with the registrar.

Complex Ownership and Trust Structures

Navigating chains of ownership that span multiple offshore jurisdictions is a common hurdle. You must “look through” each layer until a registrable individual or a “legal entity subject to its own disclosure requirements” is found. When trusts are part of this chain, the level of detail required increases significantly. Trustees, settlors, and even certain beneficiaries must be disclosed. If you find yourself managing a web of international interests, seeking professional legal support can clarify these opaque structures whilst ensuring your privacy is protected where the law permits.

New Rules for Trust Transparency in 2026

The landscape for trust privacy changed fundamentally on 31 August 2025, when the UK government enabled public access to trust information held on the register. Whilst this data isn’t visible on the public search by default, third parties can now apply to Companies House to view specific trust details. The Register of Overseas Entities (Protection and Trusts) Regulations 2026, which came into force in July 2026, further refined how this information is handled and protected. Under these rules, a registrable beneficial owner in the context of a trust is any person who serves as a trustee, settlor, or beneficiary, or who otherwise exercises significant control over the trust’s assets and administration.

The Critical Role of UK-Regulated Verification Agents

The integrity of the UK’s property market depends on the accuracy of the data submitted to Companies House. For this reason, the legislation strictly prohibits self-verification by the overseas entity itself. This register of overseas entities guidance emphasises that an independent, regulated professional must scrutinise every piece of information before it’s submitted. This requirement acts as a safeguard, ensuring that the transparency intended by the Economic Crime Act is actually achieved in practice.

Only “relevant persons” as defined by the Money Laundering Regulations can act as verification agents. This group primarily includes solicitors, accountants, and financial institutions regulated in the UK. Choosing the right partner is a decision that shouldn’t be taken lightly. Verification agents carry significant legal liability; providing false or misleading information is a criminal offence that can lead to unlimited fines or imprisonment. Whilst some high-volume service providers offer basic checks, a boutique law firm provides a superior level of due diligence that protects your corporate reputation and ensures absolute precision.

The Verification Process Step-by-Step

The verification journey follows a methodical three-stage path to ensure compliance. First, your agent gathers original corporate documentation, including certificates of incorporation and registers of members, to trace the ownership chain. Second, the agent conducts comprehensive “know your client” (KYC) and anti-money laundering checks on all identified beneficial owners. Finally, once satisfied, the agent issues a formal verification statement to Companies House using their unique agent assurance code. This structured approach, supported by official UK government guidance, ensures your entity receives its Overseas Entity ID without delay.

Maintaining the Integrity of the Register

Compliance is a recurring commitment rather than a one-off task. You must re-verify your information during every annual update to confirm that the beneficial ownership details remain accurate. If changes occur between filing dates, such as the transfer of shares or a change in trustees, these must be recorded and verified during the next update statement. A methodical approach prevents issues with your agent assurance code, which Companies House can revoke if they suspect negligent or fraudulent verification practices. Staying organised ensures your property assets remain liquid and your legal standing remains beyond reproach.

Register of Overseas Entities Guidance: A Comprehensive Legal Framework for 2026

Managing Annual Update Statements and Removal Procedures

Registration is the initial hurdle, but the legal race continues every year. The statutory duty to file an update statement remains one of the most overlooked aspects of the regime. This register of overseas entities guidance confirms that every entity must submit a statement once every 12 months. The filing window is surprisingly tight. You have exactly 14 days from the anniversary of your initial registration to complete the submission. Missing this deadline is a criminal offence. It can also lead to a daily fine, which accumulates rapidly and creates unnecessary financial strain.

Calculating your filing period is straightforward but requires diligence. Your “update period” is the 12 months following registration or your last update. Even if your ownership structure hasn’t changed a single percentage point, you still have a legal obligation to confirm this fact with Companies House. Staying ahead of this calendar is the only way to ensure your property interests remain protected and your corporate standing remains clear. We often find that clients feel a sense of relief once a reliable tracking system is in place, as it removes the fear of accidental non-compliance.

The Annual Update Checklist

A methodical review is the best defence against compliance failures. Before filing, you should verify that your current list of beneficial owners and managing officers is exhaustive and accurate. Ensure that all personal details, including names and residential addresses, are current. If significant changes in ownership occurred during the year, you must secure fresh verification from a UK-regulated agent before the update can be accepted. This prevents the administrative blocks that can derail future transactions. For expert assistance in managing these recurring duties, you can instruct Feltons Solicitors LLP to handle your annual compliance.

Removal from the Register of Overseas Entities

Many owners wonder what happens when they no longer hold UK property. If your entity has disposed of all qualifying land interests, you may be eligible for removal from the register. This is not an automatic process. You must submit a formal application for removal, which includes a declaration that the entity is no longer a registered owner of any relevant land. Once the application is submitted, Companies House enters a processing period to verify the claim with the Land Registry. Maintaining thorough records of your property disposals is vital during this stage. Even after removal, you should retain your compliance documentation for at least seven years to satisfy any future regulatory enquiries.

For high-net-worth property owners, the Register of Overseas Entities isn’t just an administrative hurdle; it’s a critical component of a broader wealth management and risk mitigation strategy. Large corporate firms often treat these registrations as high-volume, impersonal data entries. In contrast, a boutique firm like Feltons Solicitors LLP offers the discreet, high-standard service that complex international matters require. We provide a calm, steady presence, ensuring that your privacy is respected whilst every regulatory box is ticked with absolute precision. This register of overseas entities guidance is designed to help you move from confusion to complete confidence.

Compliance shouldn’t exist in a vacuum. By aligning your registration with broader residential property law strategies, you ensure that your assets remain liquid and ready for any future transaction. Our team specialises in the intricate details of overseas entity beneficial owner registration, allowing you to focus on your investment goals rather than administrative burdens. This integrated approach prevents the Land Registry blocks and criminal liabilities discussed earlier, providing a seamless experience from the moment of acquisition to the point of disposal.

A Tailored Approach to International Clients

We understand that our international clients operate across different time zones and diverse corporate cultures. Providing effective register of overseas entities guidance requires more than technical knowledge; it demands an appreciation for the human impact of legal work. For South African entrepreneurs, you can learn more about Express Shelf Company to ensure your domestic compliance is managed alongside your UK obligations. We act as a sophisticated guide, handling cross-border communications with the poise and dependability you expect from a trusted advisor. This people-first philosophy ensures that even the most complex or stressful property transactions feel manageable and secure under our care.

Next Steps for Your Overseas Entity

The best time to address your compliance status is before a deadline looms or a property sale is agreed. An initial consultation allows us to identify potential hurdles in your ownership structure, such as missing documentation from a foreign jurisdiction or complex trust arrangements. Whether you need to begin a new registration or submit an urgent annual update statement, our methodical process provides the security you need. Ensure your UK property assets remain secure with expert oversight by contacting our team today to discuss your specific requirements and safeguard your interests for 2026 and beyond.

Securing Your UK Property Interests for 2026

Navigating the UK property market as an international investor requires more than just capital; it demands rigorous adherence to transparency laws that are only becoming more stringent. By prioritising the accurate identification of beneficial owners and respecting the critical role of UK-regulated verification agents, you protect your assets from unnecessary freezes or legal complications. This register of overseas entities guidance provides the foundation for a compliant future, yet the practical application of these rules often requires a more personalised touch to navigate the nuances of international corporate structures.

Feltons Solicitors LLP offers the discreet, high-standard service needed to manage these complex requirements alongside your broader residential and commercial property interests. As regulated legal professionals, we provide the reassurance of absolute precision whilst maintaining the boutique level of care that high-net-worth individuals deserve. You don’t have to face these regulatory shifts alone. Instruct Feltons Solicitors LLP for your Overseas Entity Registration today to ensure your portfolio remains liquid and your reputation remains beyond reproach. We look forward to acting as your trusted advisor in these sensitive matters.

Frequently Asked Questions

What is the Register of Overseas Entities (ROE)?

The Register of Overseas Entities is a public database managed by Companies House to identify the true owners of foreign organisations holding UK property. Established under the Economic Crime Act 2022, it serves as a transparency tool to combat financial crime. Every foreign entity must register to receive a unique ID number. Without this identifier, you’ll find it impossible to buy, sell, or lease land in the United Kingdom.

Which overseas entities are required to register with Companies House?

Any legal person, such as a corporation or partnership, governed by laws outside the UK is considered an overseas entity. If your organisation owns or plans to acquire UK land, registration is a statutory requirement. This applies retrospectively to land purchased in England and Wales since January 1999. Identifying your entity type correctly is the first step in ensuring your property portfolio remains compliant with current transparency regulations.

What happens if an overseas entity fails to register its beneficial owners?

Failure to register results in a complete freeze on your property assets at HM Land Registry. You won’t be able to sell, lease, or charge the land until the entity is compliant. Beyond these civil restrictions, non-compliance is a criminal offence. The entity and its officers may face unlimited fines or prison sentences. These penalties are designed to ensure that transparency is not treated as an optional administrative task.

How often does an overseas entity need to update its registration?

Overseas entities must submit an update statement to Companies House every 12 months. This is mandatory even if your beneficial ownership structure has remained entirely unchanged since the last filing. You have a narrow 14-day window from the anniversary of your registration to complete this duty. This register of overseas entities guidance stresses the importance of punctuality, as missing this deadline can lead to immediate criminal prosecution and significant daily fines.

Can I sell my UK property if my overseas entity is not registered?

You cannot complete a property sale if your entity is not correctly registered. The Land Registry will block the transfer of title, meaning the buyer cannot become the legal owner. This often results in breached contracts and significant financial loss. It’s vital to verify your status well before a sale is agreed. Ensuring your registration is active avoids the stress of a last-minute scramble that could jeopardise your entire transaction.

Who can act as a verification agent for the Register of Overseas Entities?

Only UK-regulated professionals, such as solicitors, accountants, or financial institutions, can act as verification agents. These individuals must have a valid assurance code from Companies House to submit your data. Choosing a law firm provides a higher level of security, as solicitors are bound by strict professional standards. This ensures your data is verified with the precision required to satisfy the registrar and protect you from the consequences of inaccurate submissions.

Is information on the Register of Overseas Entities available to the public?

Most details on the register, including names and the nature of control, are visible to the public via Companies House. However, sensitive data like residential addresses and full dates of birth are kept private. Recent changes in 2025 mean that trust information is now accessible to the public upon application. If an individual faces a serious risk of harm, they can apply for their information to be protected from public disclosure entirely.

What is a “registrable beneficial owner” in the context of UK land?

A registrable beneficial owner is anyone who meets the 25% threshold for shares or voting rights in an entity. It also includes those who can appoint or remove the majority of the board of directors. This register of overseas entities guidance also covers individuals who exercise significant influence or control through other means. Correctly identifying these individuals is essential for a valid registration and requires a thorough analysis of your entity’s corporate governance.

Extending a Lease on a Flat in London: The Definitive 2026 Guide

Extending a Lease on a Flat in London: The Definitive 2026 Guide

Waiting for the “perfect” legislative moment to extend your lease could be the most expensive mistake a London property owner makes this decade. While recent reforms promise a fairer landscape, the reality of extending a lease on a flat london in 2026 remains a complex chess game of timing and technicality. You’re likely feeling the pressure of the 80-year marriage value threshold; perhaps you’re also confused by the staged implementation of the Leasehold and Freehold Reform Act 2024. It’s natural to feel anxious when your home’s future value depends on successful negotiations with a freeholder who may not share your priorities.

We understand that your property represents both your home and your financial security. This guide provides the clarity you need to move forward with quiet confidence. You’ll discover the essential steps to secure a 990-year extension, the latest updates on premium calculations, and the legal protections now available to leaseholders. We’ll walk through the entire process, from the initial valuation to the final registration, ensuring you have a steady, expert hand to guide you through this period of legal transition.

Key Takeaways

  • Identify why the 80-year threshold is the most significant factor when extending a lease on a flat london and how to time your application for maximum financial advantage.
  • Compare the statutory and informal extension routes to determine which process offers the most robust legal security for your home.
  • Gain a clear understanding of the financial requirements, including the capital premium and the professional fees necessary for a precise valuation.
  • Stay informed on the 2026 implementation of recent leasehold reforms, specifically the transition toward 990-year terms and the reduction of ground rent.
  • Learn how a methodical, expert-led negotiation strategy can safeguard your property’s future value while avoiding unnecessary legal disputes.

Why extending a lease on a flat in London and across the UK is essential

A lease extension is the formal legal process of adding additional years to your property’s remaining term. To understand the necessity of this process, one must first grasp what a leasehold property is in the context of English law. Essentially, you own the right to occupy the property for a fixed period rather than owning the land itself. As this period shortens, the value of your asset decreases. In 2026, leaseholders are increasingly prioritising these applications because the legislative environment has shifted. The Leasehold and Freehold Reform Act 2024 has introduced new standards, such as the 990-year extension term, making it a pivotal time for extending a lease on a flat london. This legal procedure is no longer just a recommendation; it’s a fundamental requirement for maintaining property liquidity.

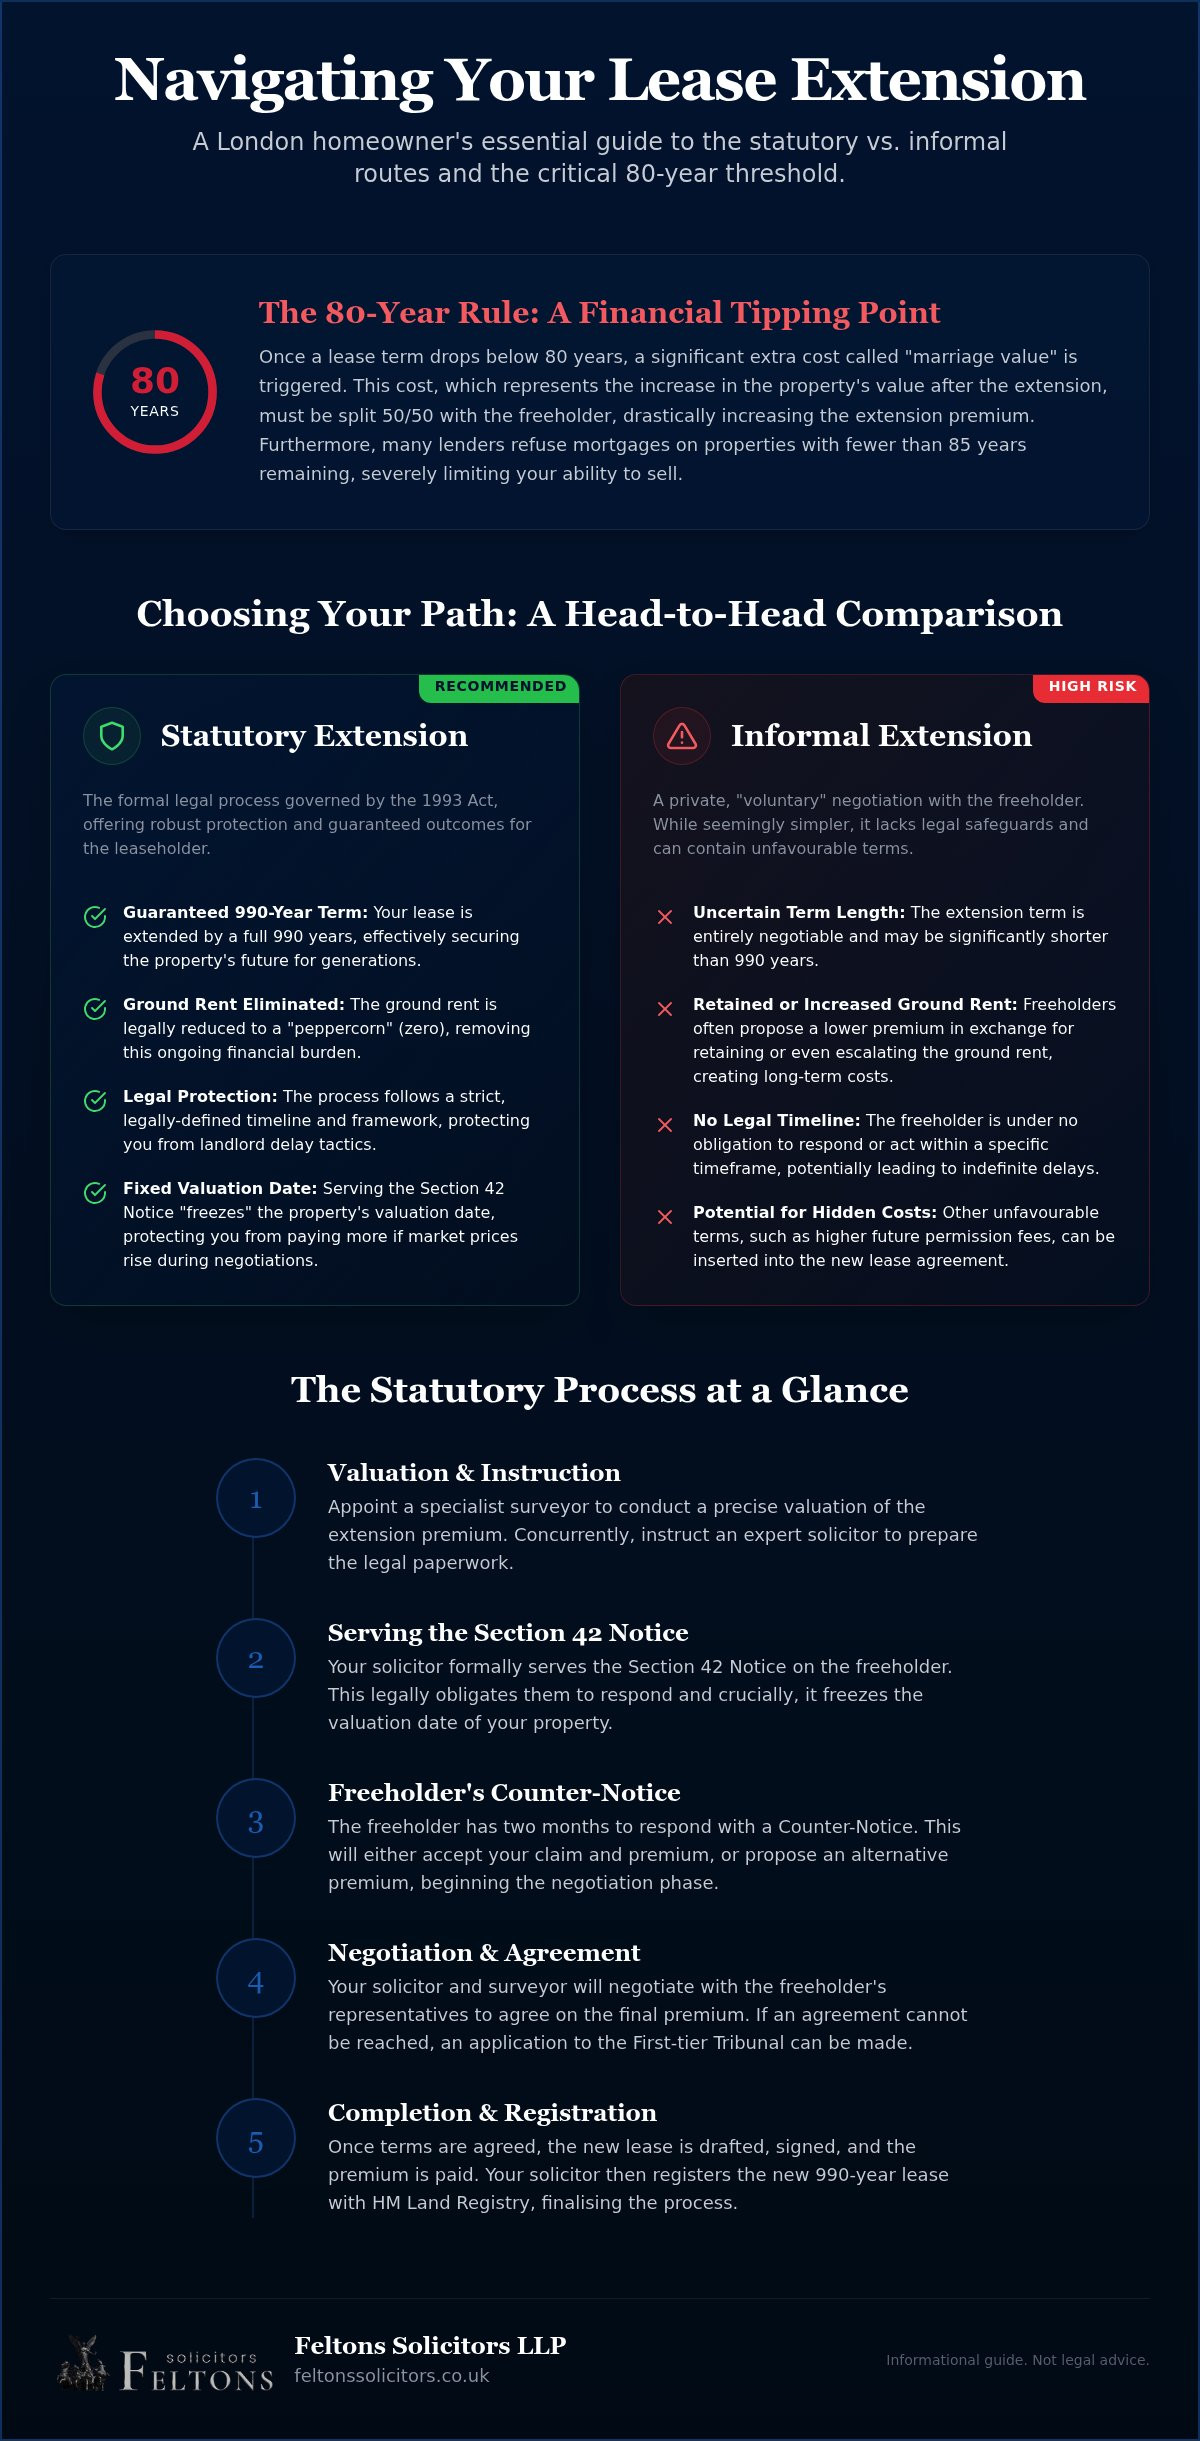
The 80-year rule: A financial turning point

The 80-year mark is widely recognised as the most critical deadline in property ownership. Once a lease drops below this threshold, a cost known as “marriage value” is triggered. Marriage value is the increase in property value following an extension. Under current rules, this profit is shared 50/50 with your freeholder, which significantly increases the premium you’re required to pay. Whilst the 2024 Act aims to eventually abolish this cost, the provision isn’t yet in force as of August 2026. Waiting for these changes carries a distinct financial risk. If the market value of your property rises whilst you delay, the eventual premium may still exceed today’s costs. Additionally, many high-street lenders now refuse to offer mortgages on properties with fewer than 85 years remaining, making it difficult to sell to anyone other than cash buyers.

Leasehold as a diminishing asset

Unlike a freehold house, a leasehold flat is a wasting asset. Its value doesn’t just plateau, it begins to accelerate downwards as the term expires. There’s a notable psychological shift amongst buyers and surveyors when a lease falls below 90 years. They often view it as a looming liability rather than a secure investment. By extending a lease on a flat london, you effectively reset the clock and protect your capital. This proactive step ensures your home remains attractive on the open market and retains its status as a high-quality asset. Securing your property’s future today provides the peace of mind that your investment is shielded from the natural erosion of time.

Statutory vs informal lease extensions: Choosing the right path

Deciding between a statutory application and an informal negotiation is the most consequential choice you’ll make when extending a lease on a flat london. The statutory route is governed by the Leasehold Reform, Housing and Urban Development Act 1993, which provides a rigid legal framework to protect your interests. In contrast, the informal route is a private agreement with your landlord. Whilst informal deals might appear simpler or faster, they often lack the strict safeguards found in official government guidance. Most professionals recommend the statutory path because it guarantees a 990-year extension and reduces ground rent to a peppercorn, providing total security for your asset.

The power of the Section 42 Notice

Serving a Section 42 Notice is a strategic move that formally initiates the statutory process. This notice is vital because it ‘freezes’ the valuation date. Even if property prices in the capital rise during negotiations, your premium is calculated based on the market value at the moment the notice is served. By 2026, the eligibility criteria have simplified; the previous requirement to have owned the property for two years was abolished in early 2025. Once served, the freeholder is legally obligated to respond with a Counter-Notice within two months. This structured timeline prevents landlords from using delay tactics to inflate costs or stall your progress.

When an informal extension might be appropriate

There are rare instances where an informal extension might be considered, particularly if you have a collaborative relationship with your freeholder and require an exceptionally fast completion. However, these “voluntary” offers frequently contain hidden traps. Landlords might propose a lower upfront premium in exchange for retaining or even increasing ground rent. Under the 2024 legislation, statutory extensions automatically eliminate ground rent, but an informal deal could include modern clauses that complicate future sales or mortgage applications. The short-term saving on professional fees is rarely worth the long-term cost of an escalating ground rent clause.

Before committing to any private offer, it’s essential to have a specialist leasehold solicitor review the terms. Our boutique approach ensures you aren’t caught by the common pitfalls of extending a lease on a flat london via the informal route. Comparing the total cost of ownership over twenty years often reveals that the statutory route is the more pragmatic financial choice, despite the initial procedural requirements.

Understanding the costs: Premium, professional fees, and taxes

Financial planning is the cornerstone of a successful property strategy. When extending a lease on a flat london, your total investment is comprised of three distinct pillars: the premium paid to the freeholder, professional fees for both parties, and potential tax obligations. The premium is the capital sum required to compensate the landlord for the loss of future ground rent and the deferment of their right to regain the property. Because this figure is based on complex valuation models, it’s the most significant variable in your budget. You can find a broader consumer perspective on these financial brackets in this guide to extending your lease, which highlights how these costs fluctuate based on market conditions.

The “Section 60” rule remains a point of frustration for many leaseholders. Under the 1993 Act, you’re generally responsible for the freeholder’s reasonable legal and valuation costs in addition to your own. Whilst this is a statutory requirement, it isn’t a blank cheque for the landlord. Furthermore, if your property is situated in a high-value area of the capital, the premium may exceed the threshold for Stamp Duty Land Tax (SDLT). It’s essential to have your solicitor calculate any potential SDLT liability early in the process to avoid late-stage surprises during the completion phase.

Factors influencing the premium

Several technical variables dictate the final price of your extension. The current market value of your flat serves as the baseline, but the remaining term of the lease and the current ground rent are equally influential. Specialist surveyors focus heavily on “yield rates” and “relativity” during negotiations. Relativity is the percentage value of the flat with its existing short lease compared to its value with an infinitely long lease. As the lease shortens, this percentage drops, causing the cost of the extension to rise sharply. Precise valuation at the start of the process is the only way to ensure your initial offer is both realistic and protective of your capital.

Managing and challenging freeholder costs

Landlords occasionally present invoices for their professional fees that appear disproportionate to the work performed. You’re only legally obligated to pay costs that are “reasonable” and “properly incurred.” If a freeholder’s solicitor or valuer charges fees that far exceed industry standards, your legal team can formally challenge them. When a mutual agreement isn’t possible, the First-tier Tribunal (Property Chamber) provides a forum to resolve these disputes. For a deeper look at how these mechanisms protect homeowners, see our article on Navigating Residential Property Law. This methodical oversight ensures that the financial burden of extending a lease on a flat london remains fair and transparent.

Extending a Lease on a Flat in London: The Definitive 2026 Guide

The step-by-step process of a formal lease extension

Following the decision to proceed, the actual mechanics of extending a lease on a flat london require a disciplined, step-by-step approach. It’s a sequence of legal and valuation milestones that must be navigated with precision to ensure your interests remain protected. The process begins with a thorough review of your current lease and title documents to identify the baseline for your claim. This initial audit allows us to confirm your eligibility and prepare the necessary information for the formal notice. By 2026, the procedural landscape has become more streamlined, yet the need for a methodical flow remains as vital as ever.

Preparation and Valuation

A professional valuation is the foundation of a successful claim. It provides the “Best Case” and “Worst Case” premium figures that anchor your entire negotiation strategy. During this stage, we also scrutinise the existing lease for “onerous” clauses, such as doubling ground rents or restrictive repair obligations, that should be varied as part of the extension. The valuation must be conducted by a surveyor with enfranchisement expertise. Their specialised knowledge of local market relativity and yield rates is what prevents you from overpaying the freeholder. This expert-led preparation ensures that the Section 42 Notice you eventually serve is robust and based on sound financial data.

From Notice to Land Registry

Serving the Section 42 Notice triggers a strict legal timetable that neither party can ignore. Once the freeholder serves their Counter-Notice, a statutory period of negotiation begins. If an agreement on the premium isn’t reached within two months, either party can apply to the First-tier Tribunal to resolve the matter. Once the premium is settled, the process enters the conveyancing stage. This involves drafting a new lease “in substitution” for the old one, effectively replacing the previous term with the new 990-year duration. It’s also the point where your mortgage lender’s formal consent is obtained and recorded to protect their security interest.

The final step is the registration of the new deed at HM Land Registry. This stage is more than just paperwork; it’s the period where the technical details of your new term are solidified and ground rent is officially reduced to a peppercorn. We ensure that the new lease follows the requirements of the 2024 Act whilst modernising any outdated language from the original deed. This final act of registration is what provides the ultimate legal certainty for your investment. If you’re ready to begin this methodical journey, you can contact our specialist leasehold team for a tailored consultation.

How Feltons Solicitors LLP secures your property rights

When you’re extending a lease on a flat london, you need more than just a legal technician; you require a sophisticated guide who understands the high stakes of the capital’s property market. Feltons Solicitors LLP positions itself as a calm, steady presence in what can often be a stressful and adversarial process. We provide pragmatic advice designed to resolve negotiations efficiently, prioritising sensible settlements over unnecessary court intervention. Our firm blends the worldly experience necessary to handle high-value London portfolios with the personalised touch of a boutique practice. This ensures that your property’s future value is protected by a team that values discretion and professional integrity above all else.

Our approach is built on the philosophy that whilst the technical legal work is paramount, the human impact of that work shouldn’t be forgotten. You’ll receive partner-led attention throughout your instruction, ensuring that your case isn’t lost in a high-volume processing system. We understand that for many of our clients, a lease extension is a vital tactical investment. By maintaining a people-first mindset, we ensure that you feel supported and informed at every milestone, from the initial title review to the final registration at HM Land Registry.

A methodical approach to leasehold law

We organise the extension process to minimise stress and provide total clarity for the leaseholder. Our methodology is highly structured, reflecting a methodical legal mindset that leaves no room for administrative error. We combine traditional professional integrity with modern delivery, using efficient systems to keep your claim moving forward without delay. As Leasehold Enfranchisement Experts, we focus on providing expert-led advice that is both grounded and current. This orderly approach allows us to manage even the most complex property disputes with quiet confidence, ensuring your rights are upheld against even the most difficult freeholders.

Protecting your interests in 2026

The legal environment in 2026 requires a partner who stays ahead of every legislative shift. We monitor the ongoing implementation of the Leasehold and Freehold Reform Act 2024 to ensure our clients benefit from the latest protections and valuation caps. Whether you’re a private homeowner or a professional property investor, we offer a high-standard service that prioritises your long-term capital security. We don’t just process paperwork; we act as your trusted advisor in a changing market. If you’re ready to secure your property’s future, Contact Feltons Solicitors LLP for a consultation on your lease extension and discover the difference that boutique, expert-led care can make.

Securing your home’s financial future

Navigating the complexities of property law requires a blend of technical precision and strategic timing. By understanding the critical 80-year threshold and the robust protections offered by the statutory route, you’re already in a stronger position to safeguard your investment. Extending a lease on a flat london isn’t merely a legal obligation; it’s a proactive financial strategy that ensures your home remains a marketable and valuable asset for decades to come.

Feltons Solicitors LLP has provided a high-standard, boutique legal service since 2010. As specialist experts in leasehold enfranchisement, we offer the pragmatic and empathetic support necessary to handle even the most intricate negotiations with freeholders. Our firm focuses on personal connection and expert-led advice, ensuring you feel supported throughout every stage of the process.

Secure your property’s value with expert legal guidance from Feltons Solicitors LLP. Taking this step today provides the long-term peace of mind that your capital is protected. We look forward to acting as your trusted advisor during this transition.

Frequently Asked Questions

Can I extend my lease if I have only owned the flat for a few months?

Yes, you can initiate the process immediately. The previous requirement to have owned the property for at least two years was abolished in January 2025. This change allows new owners to secure their property’s value without delay. It’s particularly beneficial for those who purchased a flat with a dwindling term and wish to resolve the matter before the lease shortens further, ensuring the asset remains mortgageable and attractive for future resale.

How much does it cost to extend a lease on a flat in London?

The total expenditure depends on the property’s market value, the remaining lease term, and current ground rent levels. When extending a lease on a flat london, you must budget for the capital premium paid to the freeholder and professional fees for your solicitor and surveyor. These professional costs usually fall between £2,000 and £4,000. Precise valuation is essential to ensure the opening offer is realistic and protects your capital from overpayment.

What happens if my lease has already fallen below 80 years?

If your lease is below 80 years, you currently remain liable for marriage value. Although the Leasehold and Freehold Reform Act 2024 legislates for its abolition, this specific provision isn’t yet in force as of August 2026. Delaying your application in hopes of further implementation carries risks; if property prices rise in the interim, the eventual premium may still increase. We recommend seeking specialist advice to weigh the costs of acting now versus waiting.

Do I have to pay ground rent after I extend my lease?

No, ground rent is reduced to a “peppercorn” for the entire duration of the new term. This effectively means your ground rent becomes zero. This reduction is a mandatory requirement for all statutory extensions under the 1993 Act and the 2024 reforms. Eliminating these annual payments simplifies your property ownership and removes the risk of “onerous” ground rent clauses that often deter future buyers or complicate mortgage applications from high-street lenders.

Can the freeholder refuse my request for a lease extension?

A freeholder cannot refuse a valid statutory request if you meet the basic eligibility criteria. They are legally obligated to grant a 990-year extension under the 2024 Act. Whilst they cannot block the extension itself, they have the right to dispute the proposed premium through a formal Counter-Notice. If a mutual agreement on the price isn’t reached through negotiation, the matter is referred to the First-tier Tribunal for a final, independent determination.

How long does the entire lease extension process take from start to finish?

The entire process typically takes between six and twelve months to complete. This timeline includes the initial valuation, serving the Section 42 Notice, and the subsequent period for the freeholder’s response. Negotiations regarding the premium often take several months to conclude. Once terms are agreed, the final conveyancing stage and registration at HM Land Registry add a few more months. Having a steady, expert hand to guide you ensures that strict legal deadlines are met.

What is the difference between a lease extension and buying the freehold?

A lease extension adds 990 years to your existing term, whilst buying the freehold (collective enfranchisement) gives you and your neighbours outright ownership of the building. Extending a lease on a flat london is often a more straightforward individual path to security. Buying the freehold offers more control over service charges and management but requires at least 50% of the flat owners in the block to participate, making it a more complex, collaborative legal undertaking.

Should I wait for the government’s leasehold reforms before extending?

Waiting is a calculated risk that depends on your specific lease length. Whilst the 2024 Act is law, certain provisions are still being implemented in stages throughout 2026. Additionally, a legal appeal by freeholders is expected in late 2026 or early 2027, which could impact the timeline for cheaper premiums. If your lease is approaching the 80-year mark, the cost of waiting often outweighs the potential savings, as property values continue to fluctuate.