Register of Overseas Entities Solicitors: UK Property Guidance

Register of Overseas Entities Solicitors: UK Property Guidance

Could an unresolved ownership detail complicate a UK property transaction? For an overseas entity, registration is more than a Companies House filing: it can affect the steps involved in buying, selling or holding UK property. A search for “register of overseas entities solicitors” may reflect a need to understand whether an entity falls within the regime and what its ownership structure must disclose.

It’s understandable to feel uncertain when information needs to be gathered across different jurisdictions, particularly if a property transaction is under way. This article explains the Register of Overseas Entities, the responsibilities it places on an overseas entity and the practical preparation registration may involve.

You’ll also learn how legal advice can connect registration with the wider property matter, so related steps are considered in context. Feltons Solicitors LLP provides registration of overseas entities alongside residential and commercial conveyancing, with pragmatic advice for national and international clients.

Key Takeaways

  • Learn why an overseas entity’s connection with UK land or property may bring it within the Register of Overseas Entities regime.
  • See the main stages of registration, from assessing the entity’s circumstances to organising information and maintaining its records.
  • Understand how legal advice, verification and filing are distinct parts of the process, and why it helps to clarify responsibilities.
  • Prepare for a more focused discussion by mapping the ownership structure and identifying who can provide relevant information.
  • Explore how register of overseas entities solicitors london can help connect registration advice with the wider property matter.

What is the Register of Overseas Entities and who may need to use it?

If an overseas entity owns, buys or otherwise has a relevant connection with UK land or property, establish whether the Register of Overseas Entities rules apply before a transaction progresses. The answer depends on the entity’s legal form, its ownership and control, and the nature and location of its property activity. An organisation’s everyday description may not match how it is treated under the legislation, so it is important to assess the legal structure and the property circumstances together.

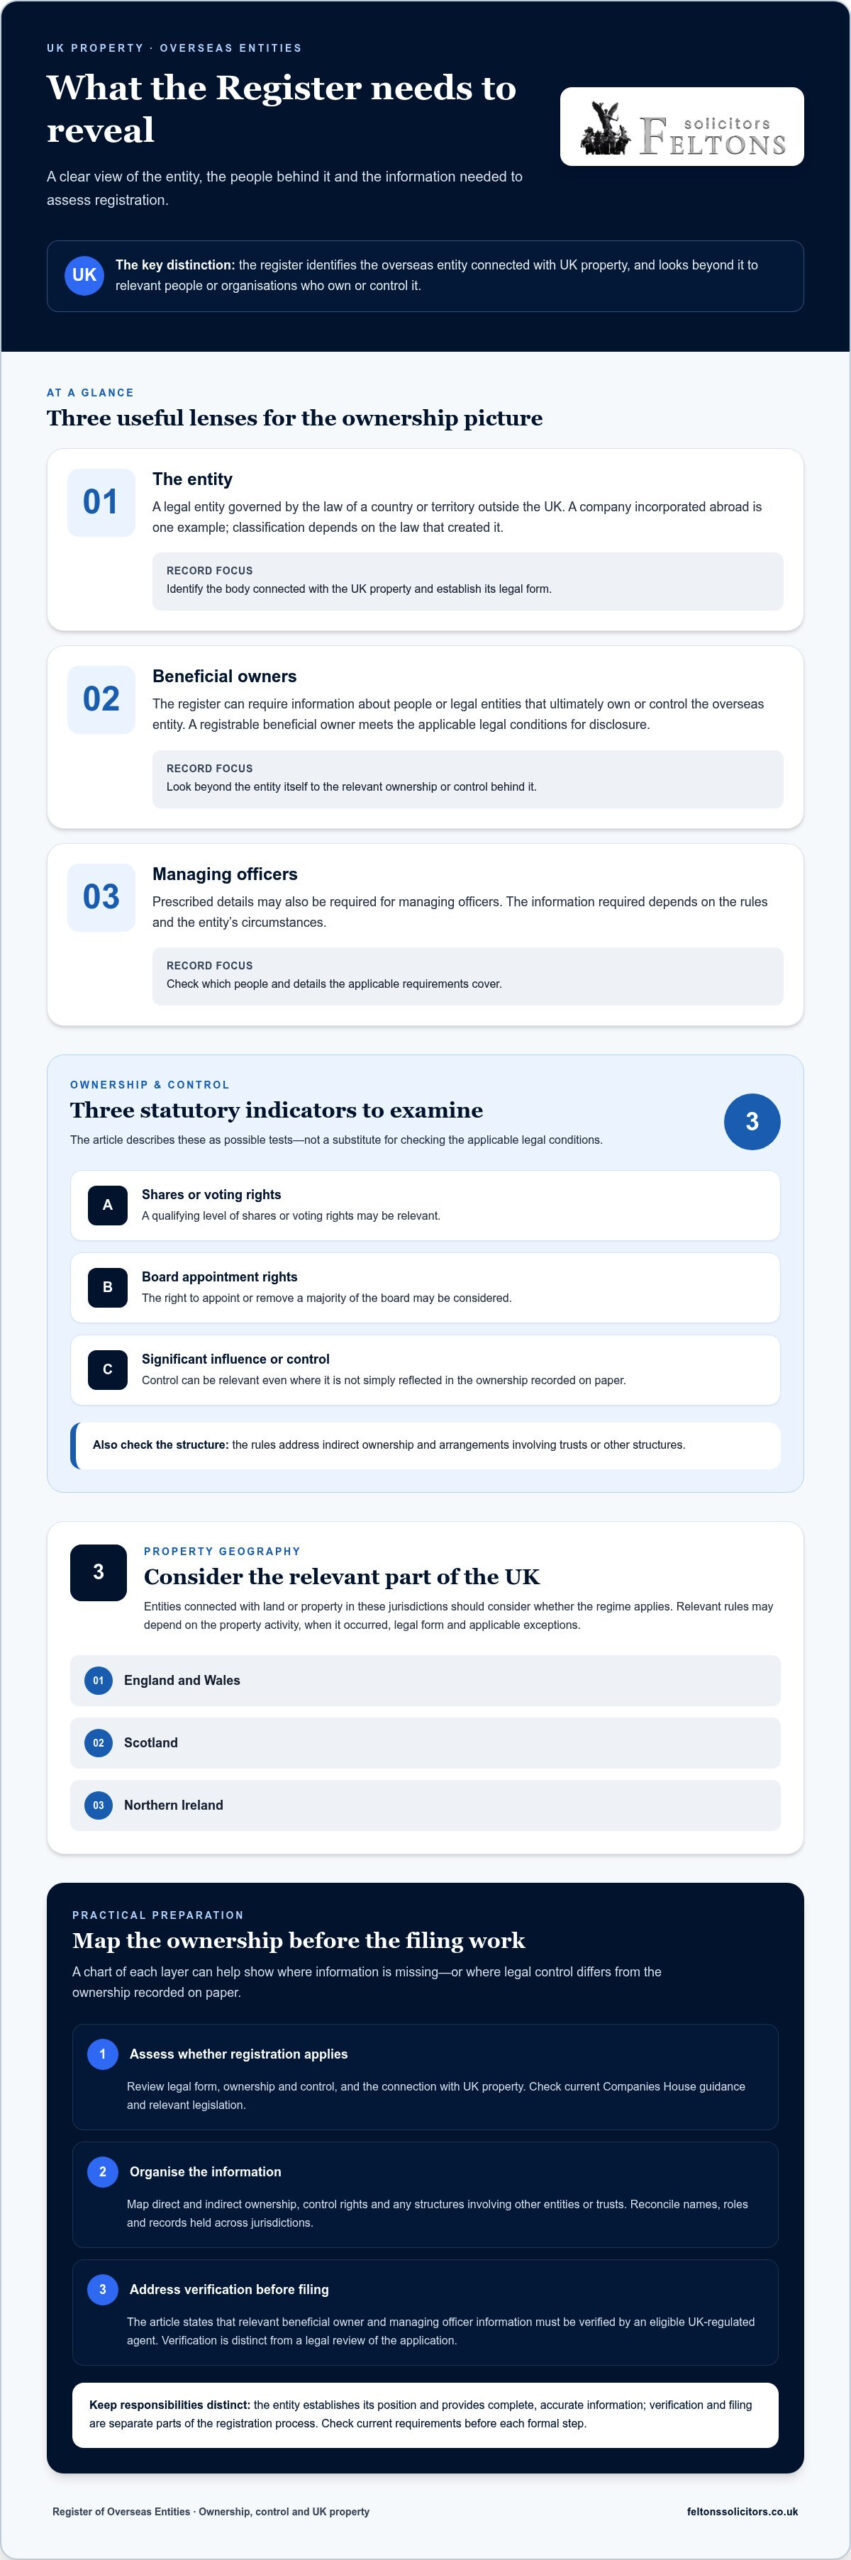
The Register of Overseas Entities is a Companies House register created to make information about overseas entities holding UK property, and the people who own or control them, more transparent. It is administered by Companies House, the UK’s registrar of companies. The register distinguishes the legal entity associated with property from the people or organisations behind its ownership and control.

What does the Register of Overseas Entities record?

An overseas entity is a legal entity governed by the law of a country or territory outside the UK. A company incorporated abroad is one example, although the precise classification depends on the entity’s legal status under the law that created it.

The register records prescribed details about the entity and information relating to its beneficial owners or managing officers, as required by the rules. A beneficial owner is, in broad terms, a person or legal entity that ultimately owns or controls the overseas entity. Statutory tests can include holding a qualifying level of shares or voting rights, having the right to appoint or remove a majority of its board, or exercising significant influence or control. Specific rules also address indirect ownership and arrangements involving trusts or other structures.

A registrable beneficial owner is someone who meets the applicable legal conditions for disclosure under the regime. The entity’s details identify the body connected with the UK property; beneficial ownership information looks beyond that body to relevant ownership or control. The two are related, but they are not interchangeable. Reviewing the structure carefully is particularly important where ownership passes through several companies or jurisdictions. A chart showing each layer can help reveal where information is missing or where legal control differs from the ownership recorded on paper.

Which overseas entities should consider their position?

Overseas entities connected with land or property in England and Wales, Scotland or Northern Ireland should consider whether the regime applies to their circumstances. The relevant rules can depend on factors such as the property activity, when it occurred, the entity’s legal form and any applicable exceptions. A foreign company’s name on property paperwork alone may not resolve every question about its reporting obligations.

Before drawing a conclusion, compare the entity’s circumstances with current Companies House guidance and the rules for the relevant part of the UK. The overseas entity beneficial owner registration guide offers further context on how ownership information connects with UK property. For advice specific to the entity, consider its legal structure, property activity and any planned transaction as one set of connected facts.

How does overseas entity registration work, from preparation to Companies House?

Registration is easier to manage when the entity first establishes what the rules require, then gathers information in a structured way. The precise filing route and evidence depend on the entity’s circumstances, so treat this as an overview rather than a substitute for current Companies House guidance. Keep a record of decisions and check the applicable requirements before each formal step. In practice, this means separating the questions of whether registration applies, what information must be disclosed, who verifies it and who submits and maintains the filing.

Accurate ownership information helps Companies House assess who ultimately owns or controls the entity and whether the application meets the regime’s requirements.

  1. Assess whether registration applies. Review the entity’s legal form, ownership and control, and its connection with UK property. The entity is responsible for establishing its position. Check current Companies House guidance and relevant legislation, including any rules or exceptions that may apply to the particular facts.
  2. Organise the entity and ownership information. Identify the details required about the overseas entity, its beneficial owners and, where relevant, managing officers. Map direct and indirect ownership, control rights and structures involving other entities or trusts. The entity is responsible for providing complete and accurate information. Where records are held across different jurisdictions, coordination may be needed to reconcile names, roles and ownership details.
  3. Address verification before filing. Current rules require relevant information about beneficial owners and managing officers to be verified by an eligible UK-regulated agent before registration. The applicable rules set who can act, the necessary supervision and authorisation, and the timing of verification. Check those requirements against current Companies House guidance. Verification is a distinct compliance function, not simply a legal review of the application.
  4. Submit and maintain the register details. The overseas entity must make the required application to Companies House, following the current filing process and requirements. After registration, it must meet the applicable update obligations, including filing an annual update statement even if there has been no change. The entity remains responsible for keeping its information accurate and meeting deadlines; confirm the current filing window and process with Companies House.

What information may be needed for an application?

Expect to organise information about the entity’s identity and legal form, its ownership and control, and relevant officers. The precise information and supporting material depend on the structure and the rules that apply. Where records are held in different jurisdictions, allow time to resolve differences in names, dates or ownership records. A useful first step is to compare the information held by the entity with records from each ownership layer, then note any gaps or inconsistencies. Don’t assume a generic document checklist will fit every entity; confirm current requirements before gathering or submitting evidence.

What role can a solicitor or verification agent play?

Legal advice can help clarify how the regime relates to the entity’s ownership and property circumstances, and identify issues that may need attention before an application. Verification is a separate formal role governed by eligibility and authorisation requirements. Filing is another distinct step, and responsibility for the application and ongoing compliance remains with the overseas entity. The roles may be handled by different parties. Feltons provides registration of overseas entities and conveyancing advice, helping clients consider the registration process alongside the property matter. You can discuss your registration and property circumstances with Feltons.

Useful legal support should make clear which parts of the matter require legal analysis, which involve formal verification and who is responsible for filing. These functions are related, but they aren’t automatically carried out by the same provider. Just as corporate organisations rely on specialist bodies like International Associates Limited for independent assessment, auditing and assurance in broader international operations, property compliance relies on clearly delineated roles. Before work begins, establish the scope of advice, the information the entity will need to provide and how registration fits alongside any property transaction. This gives the entity a practical way to understand the work involved and its own continuing responsibilities.

Why can ownership structures make the matter more involved?

For example, an overseas entity may be owned by another company, which is itself controlled by individuals or a further entity. The assessment needs to follow the relevant ownership and control through the structure, rather than stop at the first company named. Overseas records and differences in how entities are organised can affect how information is gathered. The aim is to understand and report the relevant facts accurately under the applicable rules.

Question Why it matters What legal support can address
What does the structure show? Indirect ownership or control can make it less obvious who may be reportable. Analyse the structure and identify points that need clarification.
Who is responsible for verification? Verification is a formal role subject to current eligibility and authorisation requirements. Explain how the verification step fits the process and clarify responsibilities without assuming every legal adviser can perform it.
Who will submit and maintain the information? Filing and ongoing compliance are distinct from advice and verification. Clarify the filing arrangements and the entity’s continuing responsibilities under current Companies House guidance.

How does registration relate to a property transaction?

Registration status may be relevant when an overseas entity deals with UK land or property. The effect depends on the circumstances and current legal requirements, so don’t assume a registration issue will have the same consequence in every transaction. Where a purchase, sale or other property matter is planned, considering registration alongside the conveyancing work can bring related questions into view. For example, the entity can identify how its ownership structure relates to the transaction and whether its registration position needs attention as part of the wider matter. The residential property law guide provides wider context on property matters.

Feltons Solicitors provides registration of overseas entities alongside residential and commercial conveyancing. This makes it possible to consider registration in the context of the property matter, with advice tailored to the entity’s circumstances. Focus on how ownership analysis, verification arrangements and property work relate, while keeping each party’s role distinct.
Register of Overseas Entities Solicitors: UK Property Guidance

What practical steps can an overseas entity take before seeking registration advice?

A little preparation can make an initial discussion more focused. You don’t need to resolve every legal question or assemble a definitive set of documents first. Start by organising what the entity knows, noting what remains uncertain and identifying who can help clarify the information. This avoids spending time trying to make incomplete records look consistent before their significance has been considered.

Use this checklist as a way to prepare for advice, not as a complete list of application documents or filing requirements:

  • Map ownership and control. Draw a clear outline from the overseas entity through any intermediate companies or other arrangements to the people or entities who may ultimately own or control it. Note where ownership and control differ.
  • Identify information holders. Record who can explain the entity’s structure and who holds relevant company or ownership records, including contacts in other jurisdictions. This helps show where information may need to be requested.
  • Compare key details. Check whether the entity’s name and other identifying details appear consistently across the records available to you. Flag spelling differences, incomplete information or changes in structure rather than trying to resolve their legal significance yourself.
  • Note changes and gaps. Record changes in ownership or control and any parts of the structure you can’t yet explain. A simple note of what is known, what is uncertain and who may be able to clarify it can help guide the legal review.
  • Keep sensitive information secure. Avoid sharing personal or confidential ownership details in public or unsecured channels. Organise the information privately and discuss an appropriate way to provide it as part of the legal process.

How can an entity organise its ownership information?

A simple structure chart can be a useful starting point. Show each ownership layer, the relationship between the parties and any known control rights, then annotate unclear points for discussion. If a record uses a different name or describes a structure differently, preserve the original detail and note the discrepancy. Don’t assume it is a minor issue or alter records to make them match; let a solicitor consider what the difference means under the applicable rules. This gives the legal review a clearer basis and helps distinguish confirmed information from points that still need investigation.

What should be considered alongside a property matter?

Registration and conveyancing are related when an overseas entity has a UK property matter, but they remain distinct legal tasks. Give your adviser a concise outline of the transaction and its current stage so registration questions can be considered in context. Useful details to note include:

  • Whether the matter concerns a purchase, sale or another property transaction.
  • The UK property involved and the entity’s connection to it.
  • Any key steps already taken and decisions still to be made.
  • Known timing considerations, without assuming these replace applicable filing requirements.

This context can help shape a tailored discussion of the entity’s registration position and the related property work. The overseas entity registration and beneficial ownership guide offers further background on the link between ownership information and UK property.

Feltons provides registration of overseas entities alongside residential and commercial conveyancing. A focused discussion can consider both the entity’s registration circumstances and the connected property matter, with a pragmatic approach tailored to the facts.

How can Feltons Solicitors support an overseas entity property matter?

An overseas entity’s registration and its UK property plans are closely connected, but each matter has its own legal considerations. Feltons Solicitors provides registration of overseas entities alongside residential and commercial conveyancing. The entity can discuss registration in the context of its wider property circumstances, rather than treating the register as an isolated administrative issue.

The right advice depends on the facts. An entity with a straightforward ownership structure and no active transaction may have different questions from one preparing to buy or sell property through several layers of ownership. Understanding both the entity and its property plans helps shape a practical discussion about what needs attention and which issues should be considered together.

What does a tailored legal approach bring to the matter?

Feltons takes a bespoke, pragmatic approach, helping clients consider their particular circumstances with clear, measured guidance. That may mean looking at how the entity’s structure relates to its UK property interests, or considering registration questions alongside conveyancing work. Advice is tailored to the matter, without assuming every entity’s requirements or transaction will be the same.

Feltons combines modern delivery with traditional values. The firm serves national and international clients, bringing a discreet, considered approach to matters that may involve information and interests across borders. Clear communication can help keep the legal issues understandable, especially where ownership arrangements or property plans raise questions that need careful analysis. It doesn’t remove the need to meet applicable requirements, but it can help the entity understand the issues and decisions in front of it.

When assessing legal support, consider whether the advice will address both the registration question and its relationship to the property matter. Registration, verification and filing are distinct functions, and their responsibilities should be understood clearly. Feltons provides registration and conveyancing services, while the precise steps and responsibilities in any case depend on the entity’s circumstances and current requirements.

What is a sensible next step?

To begin a focused conversation, outline the entity’s ownership structure as you currently understand it and note any areas that remain unclear. Add a brief description of the UK property matter, such as whether it involves a purchase, sale or another conveyancing issue, and where it stands. You don’t need to settle every point before seeking advice. A clear account of what is known, what needs clarification and how the property plans fit together is a helpful starting point.

Feltons can discuss the entity’s registration circumstances and any connected residential or commercial conveyancing needs. Discuss your overseas entity property matter with Feltons.

Take the next step with clarity

Before moving forward, consider what decision the entity needs to make and how its UK property plans shape that decision. A clear account of the ownership structure, any points that need clarification and the transaction’s current position can help make the first legal discussion focused and useful. You don’t need to have every answer before seeking guidance.

If you’re looking for register of overseas entities solicitors london, discuss the specific registration questions alongside any connected property requirements. Feltons can provide tailored legal advice on overseas entity registration and related conveyancing, with an approach shaped around your circumstances.

Discuss your overseas entity property matter with Feltons and take the next step with considered support.

Frequently Asked Questions

What is the Register of Overseas Entities?

It’s a Companies House register recording information about overseas entities and relevant beneficial ownership connected with UK land or property. Its purpose is to improve transparency about who owns or controls an entity. The information required depends on the entity and applicable rules. For example, a structure involving several companies may need closer analysis than a single overseas company. Use current official guidance, and seek legal advice if the ownership picture is complex.

Does an overseas entity need to register before dealing with UK property?

Not every property situation can be answered with a simple yes or no. Requirements depend on the entity’s relationship with the land, the type of dealing and the rules that apply. Before committing to a transaction, identify the property and proposed activity, then check current Companies House and land registration requirements. Legal advice can help assess the entity and transaction together.

Who can verify information for the Register of Overseas Entities?

Only a person who meets the verification requirements in force for the application may perform the formal verification role. Those rules can specify who is permitted to act and what authorisation is required, so check current Companies House guidance for the relevant filing. A solicitor may advise on the entity’s legal position without acting as its verification agent. Clarify each person’s role before relying on a verification statement in an application.

What information is needed to register an overseas entity?

An application may call for information about the overseas entity and people connected with its ownership or management. The details and supporting evidence depend on the entity’s structure and the current rules, so a general checklist can’t establish exactly what your case requires. As a practical first step, compare the entity’s records, map who owns or controls it, and note gaps or inconsistent details for legal review before preparing an application.

Can a solicitor help with both overseas entity registration and a property transaction?

Yes. Legal support can consider registration questions alongside a related property matter, although registration and conveyancing remain separate tasks with distinct requirements. Feltons Solicitors provides registration of overseas entities and residential and commercial conveyancing. For instance, if an entity is preparing for a property purchase, advice can take account of both the registration issue and the conveyancing context. The appropriate work depends on the entity’s circumstances and the rules that apply.

What happens if an overseas entity’s ownership information changes?

A change in ownership or control may affect the information the entity must keep current on the register. Keep a dated record of what changed, when it took effect and which records reflect the new position. Then check the current Companies House requirements promptly, rather than assuming the change can wait until a property transaction concludes. If a sale or purchase is also under way, raise the change as part of the legal discussion.

Is the Register of Overseas Entities the same as registering a company in the UK?

No. The Register of Overseas Entities concerns overseas entities with a relevant connection to UK land or property; it isn’t the process for incorporating a new UK company. An organisation might have separate company-law or registration obligations depending on its activities and legal status. For example, creating a UK subsidiary doesn’t by itself answer whether an overseas parent has responsibilities under the overseas entities regime. Assess each entity and obligation separately.
Overseas Corporate Property Compliance: UK Guide 2026

Overseas Corporate Property Compliance: UK Guide 2026

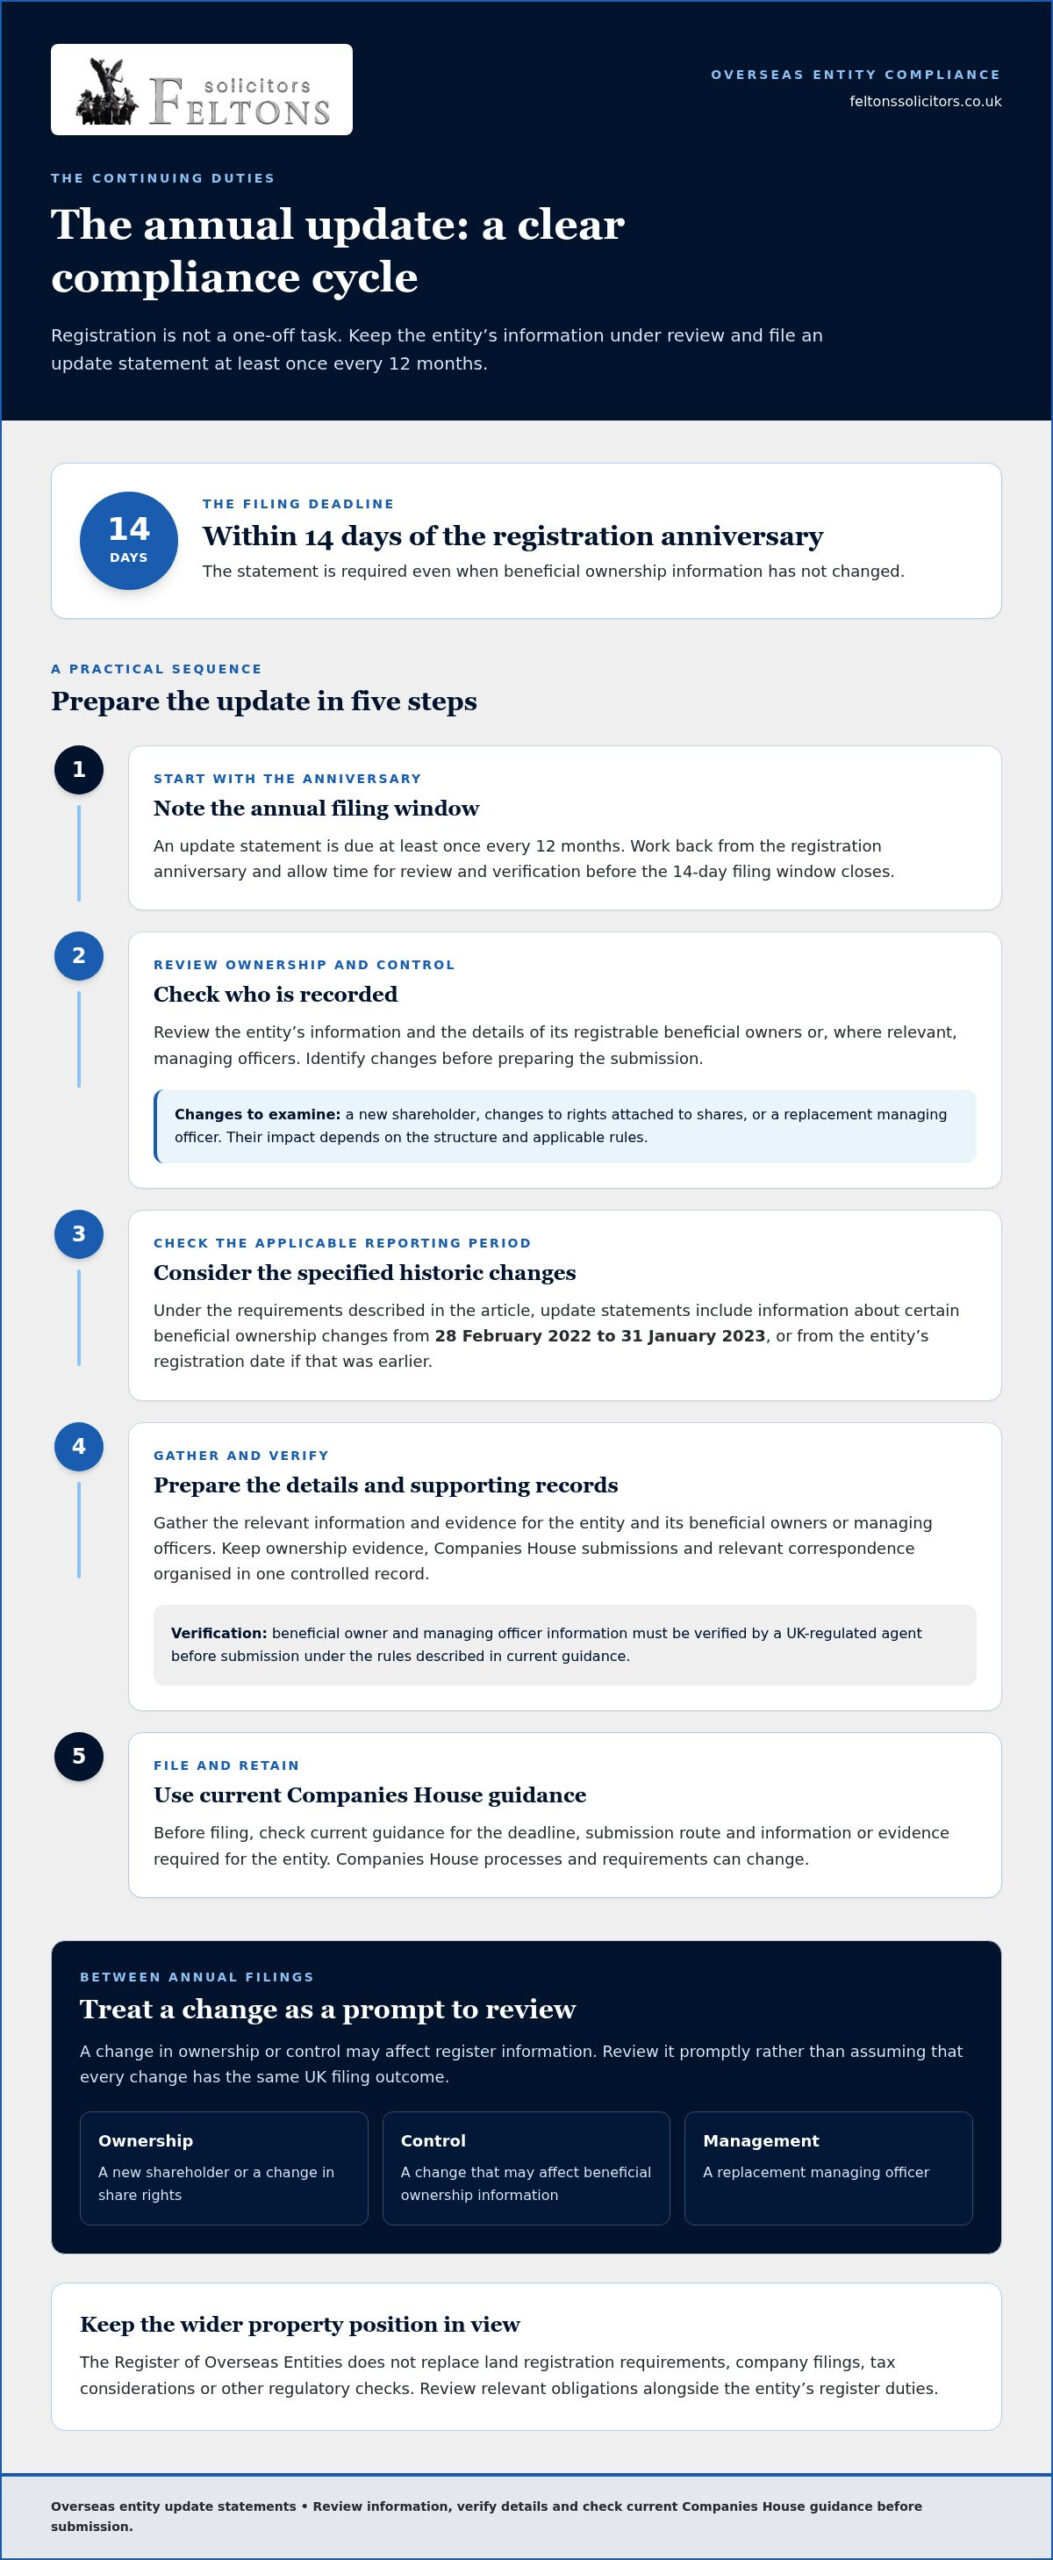
What if registering an overseas entity is only the start of its UK property compliance duties? For organisations that own UK land, overseas corporate property ownership compliance is an ongoing process. A registered entity must file an update statement with Companies House at least once every 12 months, even if its beneficial ownership hasn’t changed. The filing is due within 14 days of the registration anniversary.

It can be difficult to know which changes to report, what records to keep current and how the Register of Overseas Entities fits alongside other obligations. These duties are connected: a change in ownership or company information may require a prompt review.

This guide explains the continuing duties linked to overseas entity registration and the events that may need attention. It distinguishes register requirements from land, company, tax and sanctions considerations, and compares a structured self-managed process with tailored legal support. Feltons Solicitors LLP advises on registration of overseas entities and property matters, helping owners assess how the requirements apply to their particular structure.

Key Takeaways

  • Treat overseas corporate property ownership compliance as an ongoing process, not a one-off registration task.
  • Review changes to beneficial ownership, registrable beneficial owners or managing officers promptly to assess whether reporting action is needed.
  • Use the property’s status, planned transaction and ownership structure as prompts for a focused compliance review.
  • Keep ownership evidence, Companies House submissions and relevant correspondence organised in one controlled record.
  • Compare self-managed administration with tailored legal support to decide how best to coordinate register duties with property transactions.

Overseas corporate property ownership compliance: why registration is only the starting point

Overseas corporate property ownership compliance covers the continuing legal and administrative responsibilities that may apply when an overseas entity owns or seeks to acquire relevant UK land. Registration with Companies House is a key part of the process, but it doesn’t keep the entity’s information accurate by itself or satisfy every obligation connected with its company, property or wider regulatory position. Beyond entity filings, managing UK real estate also requires meeting statutory physical building and safety requirements, where organisations like Oxford Environmental Consultants (OEC) assist with multi-disciplinary property compliance.

Start by identifying the legal owner, the property and the relevant UK jurisdiction. An entity may have registered correctly when it acquired a property, but later changes to its ownership or management could mean its register information needs attention. The position may also depend on when the land was acquired and what type of interest is held. Treating registration as a one-off task risks overlooking these continuing responsibilities.

What does the Register of Overseas Entities do?

Companies House maintains the Register of Overseas Entities under the Economic Crime (Transparency and Enforcement) Act 2022. Its purpose is to make information available about overseas entities that own or seek to acquire qualifying UK land, including details of registrable beneficial owners or, where relevant, managing officers. The register helps show who stands behind an entity, but it doesn’t replace checks on the entity’s wider obligations.

For the registration regime, qualifying land interests include freehold ownership and certain leasehold interests. A non-UK legal entity may need to register before it can complete a relevant property transaction. The position should be assessed against the property’s location, legal interest and transaction history. Companies House registration doesn’t replace land registration requirements, company filings, tax considerations or other regulatory checks—cross-border owners managing international real estate portfolios, for example, often engage accounting firms such as Tax Partners to address jurisdiction-specific tax liabilities and deductible financing costs alongside corporate transparency filings.

Which overseas property owners should review their position?

Overseas legal entities should review their position if they already hold relevant UK land, plan to acquire it or are preparing to dispose of it. This means checking the entity’s ownership chain and the information recorded about its beneficial owners or managing officers. A sale or other transaction can bring register status into focus, so assess it as part of property planning rather than waiting until completion is imminent.

Individual overseas buyers shouldn’t assume that the Register of Overseas Entities applies to them in the same way simply because they live outside the UK. The regime is directed at overseas legal entities. The correct analysis depends on who legally owns the property and how that ownership is structured.

Historic holdings also need careful review. The registration rules have retrospective application for certain properties acquired on or after 1 January 1999 in England and Wales, and 8 December 2014 in Scotland. Transitional circumstances and jurisdiction-specific land rules can affect the analysis, including where a property has changed hands or the ownership structure has been reorganised. Check current Companies House guidance and assess the facts before drawing a conclusion.

  • Identify the registered owner: distinguish the overseas entity from individuals or other entities in its ownership chain.
  • Establish the property history: record where the land is, the interest held and when it was acquired.
  • Review the wider position: consider register duties alongside relevant land, company and regulatory requirements.

The continuing compliance duties overseas entities need to understand

For an overseas entity on the Register of Overseas Entities, compliance means keeping its recorded information current, not simply retaining a registration number. The annual update statement is the recurring Companies House filing used to confirm or update information about the entity and its beneficial owners or managing officers. It’s required at least once every 12 months, even if nothing has changed.

Annual updates and keeping information accurate

The filing deadline is 14 days after the anniversary of the entity’s registration. Before preparing a submission, review the ownership and control information, identify any changes and gather the relevant details. The review should also account for applicable reporting rules: under current requirements, update statements include information about certain beneficial ownership changes from 28 February 2022 to 31 January 2023, or the entity’s registration date if earlier.

Companies House processes and requirements can change. Before filing, check its current guidance for the deadline, submission route and information or evidence required for the entity. Beneficial owner and managing officer information must be verified by a UK-regulated agent before submission under the rules described in current guidance. Allow time for review and verification rather than leaving these steps until the deadline.

Changes, verification and supporting records

A change in ownership or control should trigger a compliance review. A new shareholder, a change in the rights attached to shares or a replacement managing officer could affect information relevant to the register. The impact depends on the structure and applicable rules, so don’t assume that a change in the overseas entity’s home jurisdiction has the same UK filing outcome in every case.

Keep a clear record of the change, the assessment, supporting documents and any submission or correspondence. The evidence and verification steps depend on the filing and current requirements. Companies House identity-verification reforms are separate from verification of Register of Overseas Entities information. As implementation can depend on role and timing, check current Companies House guidance before deciding who must verify their identity or when.

Register duties are only one part of the picture. Tax reporting, filings required in the entity’s place of incorporation and registration of the land itself are separate matters, each with its own rules and processes. For land registration context, HM Land Registry Practice Guide 78 is an official reference. Requirements can vary according to the property’s UK jurisdiction and the transaction.

A disciplined process makes overseas corporate property ownership compliance easier to manage: assign responsibility for monitoring changes, maintain an organised evidence file and diarise the annual review. Where the ownership chain or a property transaction raises questions, tailored advice on overseas entity registration can help connect register information with the particular structure and property circumstances.

How compliance considerations differ by ownership structure and property situation

Begin the review with the event under consideration: a purchase, continued ownership or a proposed disposal. Each raises different questions about the entity’s registration position, ownership information and the property transaction. The correct compliance steps depend on the entity’s structure and the property’s history.

Acquiring, holding or disposing of UK property

Use the comparison below to organise an initial review. It helps identify issues, but it doesn’t determine whether a particular filing or restriction applies. The answer depends on the facts, current rules and the property’s jurisdiction.

Situation Questions to investigate
Proposed acquisition Is the buyer a legal entity incorporated outside the UK? What type of land interest is being acquired, and what registration and transaction steps apply before completion?
Existing holding When and where was the property acquired? Has the ownership or control structure changed since acquisition, and is the recorded information consistent with the current position?
Proposed disposal What is the entity’s current register status? Do the title, entity details and ownership records align, and are any additional steps needed for the planned transaction?

Land transaction work and Register of Overseas Entities duties are related, but they are not interchangeable. A purchase or sale involves property-specific conveyancing and land registration considerations as well as a review of the entity’s register obligations. The steps can vary across England and Wales, Scotland and Northern Ireland. Don’t assume registration alone resolves every transaction requirement, or that the same restriction applies in every case. Companies House guidance on the Register of Overseas Entities provides an official overview of the regime.

Ownership chains, beneficial owners and managing officers

Direct ownership may make it easier to identify the entity that holds the property, but the underlying ownership and control still need review. With layered ownership, trace the chain through each organisation and consider who ultimately owns or controls the overseas entity. A change at an upper level can prompt a fresh assessment of the information relevant to the register, even if the entity named on the property title hasn’t changed.

In plain English, a beneficial owner is a person or entity identified under the applicable rules as owning or exercising relevant control. A managing officer is someone who manages the overseas entity where the rules require that information to be reported. These roles are distinct, and a person’s involvement in day-to-day decisions doesn’t by itself settle how they should be classified. Review the facts against current guidance.

Trusts, nominees and arrangements involving several connected entities need particular care. The legal documents, actual control and reporting requirements may all matter. As part of overseas corporate property ownership compliance, record the structure clearly and assess changes before a property transaction advances. Coordinated advice on overseas entity registration and property matters can help bring these considerations together without treating a general framework as a determination of a specific case.

Overseas Corporate Property Compliance: UK Guide 2026

A practical overseas corporate property compliance checklist

A repeatable process helps identify filing or information issues before they become urgent. For overseas corporate property ownership compliance, assign responsibility, maintain a reliable record trail and treat changes in ownership or property plans as prompts for review. Use the checklist below as a practical sequence, adapting it to the entity’s structure and circumstances.

  1. Identify the legal owner. Record the overseas entity’s full name and jurisdiction of incorporation, along with the UK property it owns or plans to acquire. Check that the entity name matches the relevant corporate and property records.
  2. Map the ownership and control structure. Set out each organisation in the ownership chain and identify the individuals or entities whose ownership or control may be relevant. Note any layers, trusts, nominees or management arrangements that need closer analysis.
  3. Confirm the registration position. Review whether the entity is registered and whether the information held is consistent with its current structure. For practical background on identifying reportable individuals, see this guide to overseas entity beneficial owner registration. For an overview of the registration process connected with UK property, consult the guide to registering an overseas entity for UK property.
  4. Monitor changes and transactions. Treat ownership restructuring, changes to beneficial owners or managing officers, acquisitions and proposed disposals as review triggers. A trigger calls for assessment; it doesn’t automatically mean register information or a filing must change.
  5. Diarise recurring reviews. Assign a named person or team to monitor relevant filing dates and review the ownership information at planned intervals. Include a handover process so responsibility doesn’t disappear when staff or advisers change.

Build a repeatable review and record-keeping process

Keep a controlled file containing ownership charts, source documents used to assess control, submitted forms, confirmation records and relevant correspondence. A dated record of who reviewed the information and what action followed can help the organisation respond consistently if questions arise. Restrict access appropriately and keep the file organised instead of relying on scattered email threads or one person’s notes.

Set retention and access practices with reference to the requirements for each record type. Don’t assume one retention period suits every document. The aim is a usable audit trail that can be updated as the entity, its ownership or its property position changes.

Recognise when a change needs legal assessment

Flag changes early, particularly when a transaction is being planned alongside a restructure or change in control. A review can establish whether the event affects reported information, requires supporting evidence or raises a separate property registration question. Feltons Solicitors LLP advises on overseas entity registration and property matters. Explore legal support for overseas entity registration for a tailored assessment of the next steps.

Some entities manage routine administration internally, using a clear ownership record and a reliable system for monitoring filing dates. This keeps the process close to the people who understand the organisation’s structure. It also requires someone with the time and knowledge to recognise when a change may affect the register or a planned property transaction.

Tailored legal support can help where ownership is layered, the property has a complex history, or an acquisition or disposal is approaching. A legal review can connect Companies House information with the entity’s ownership structure and relevant property-law questions. Neither approach suits every owner. The right level of support depends on the facts, internal resources and confidence in assessing the requirements.

What tailored legal support can help coordinate

Advice can clarify how registration and ownership information relate to the entity’s particular structure, and identify property-law questions arising from its holdings or planned transactions. This can be especially useful when a change in control occurs alongside a restructure or proposed sale, and it isn’t clear which records or obligations need review.

Feltons Solicitors LLP advises on registration of overseas entities and property matters, including conveyancing. This combined perspective helps organise a review around the entity’s circumstances rather than treating register information and property activity as unrelated tasks. Legal advice can guide the process, but the entity remains responsible for the accuracy and completeness of information it provides for its filings.

Prepare for a focused conversation about compliance

A focused discussion is easier when the relevant material is ready. Consider gathering:

  • the overseas entity’s name, jurisdiction of incorporation and registration details
  • property details, including location, ownership history and any planned transaction
  • ownership charts, relevant company records and information about beneficial owners or managing officers
  • previous Register of Overseas Entities submissions and related correspondence

Note known changes, such as a transfer of ownership interests, a new managing officer or a proposed acquisition or disposal. This gives the review a practical starting point and helps distinguish changes that need investigation from routine updates. Keep source documents organised, but don’t assume every event automatically requires a filing: its effect depends on the facts and current requirements.

For tailored guidance on overseas corporate property ownership compliance, discuss overseas entity and property compliance with Feltons Solicitors LLP. A conversation can clarify how the register, ownership structure and property plans fit together, so the next steps can be considered in context.

Make your next compliance decision with clarity

Build overseas corporate property ownership compliance into the organisation’s forward planning rather than treating it as an isolated filing task. Before an ownership change or property decision moves ahead, identify unanswered questions about the entity’s structure, register information and legal steps connected with the property. A considered review helps the organisation decide what needs attention and who should take responsibility.

Where a matter involves both register duties and a property transaction, joined-up advice can bring those considerations into one discussion. Feltons Solicitors advises on overseas entity registration and residential and commercial conveyancing, so relevant points can be considered in the context of the organisation’s property plans.

If you’d value a clear assessment of your circumstances, discuss your overseas entity and property compliance matter with Feltons Solicitors. A considered next step can make a complex issue more manageable and help you plan with confidence.

Frequently Asked Questions

Does an overseas company have to register to own property in the UK?

An overseas legal entity may need to register if it owns or intends to acquire qualifying UK land, such as a freehold or a lease exceeding seven years. The requirement depends on the entity and the property interest, so “overseas company” alone doesn’t settle the question. An individual buying in their own name shouldn’t assume the entity rules apply to them. Review the ownership documents and relevant jurisdiction before proceeding.

Is overseas entity registration a one-off requirement?

No. Registration establishes the entity’s entry on the Register of Overseas Entities, but the entity must continue to review and report its information under the applicable rules. For example, a change in who owns or controls the entity may need assessment even if the property title remains unchanged. Registration also doesn’t remove separate company, tax or land-registration responsibilities, which should be managed separately.

What changes must an overseas entity report to Companies House?

Changes to beneficial ownership, registrable beneficial owners or managing officers should prompt a review of the entity’s register information. The entity should also consider whether other recorded details have changed and what the current filing rules require. For instance, a new parent company may alter the ownership chain even though the registered property-owning entity stays the same. Assess the change against current Companies House guidance before preparing a submission.

How often must an overseas entity update its information?

An overseas entity must file an update statement at least once every 12 months, including when there’s been no change to its beneficial owners. The filing deadline is 14 days after the anniversary of its registration. Keep the anniversary and submission deadline in a central calendar, allowing time to review the information and complete any required verification. Check current Companies House filing guidance before submitting, as processes can change.

Can an overseas entity sell UK property if its register information is out of date?

It may face a restriction that prevents a property transaction from proceeding. A restriction on the title can affect an entity’s ability to sell, lease or charge the property while it remains non-compliant. The practical effect depends on the title, the property’s jurisdiction and the entity’s circumstances. If a sale is planned, review the register position early alongside the conveyancing work rather than assuming an update can wait until completion.

What is the difference between an overseas entity and a beneficial owner?

An overseas entity is the non-UK legal body that may own or acquire qualifying UK land. A beneficial owner is a person or entity identified under the applicable rules as owning or exercising relevant control over that body. For example, a property title may name an overseas company, while another organisation or individual further up its ownership chain may be relevant to beneficial ownership reporting.

Do the same overseas property ownership rules apply across the UK?

No. The Register of Overseas Entities is UK-wide, but land registration systems and property processes differ between England and Wales, Scotland, and Northern Ireland. The property’s location and acquisition history can therefore affect the review. For example, retrospective registration dates differ for some holdings in England and Wales and in Scotland. Don’t assume that a conclusion about a property in one jurisdiction applies to another.

Can a solicitor help manage overseas corporate property compliance?

Yes. A solicitor can help assess how the entity’s ownership structure, register information and property plans fit together, and advise on relevant registration and conveyancing questions. This can be particularly useful before a proposed transaction or after a change in control. Legal support can help organise the review, but the entity remains responsible for ensuring the information it provides is accurate. Feltons Solicitors LLP advises on overseas entity registration and property matters.

Land Registry Overseas Entity ID Requirements: A 2026 Checklist

Land Registry Overseas Entity ID Requirements: A 2026 Checklist

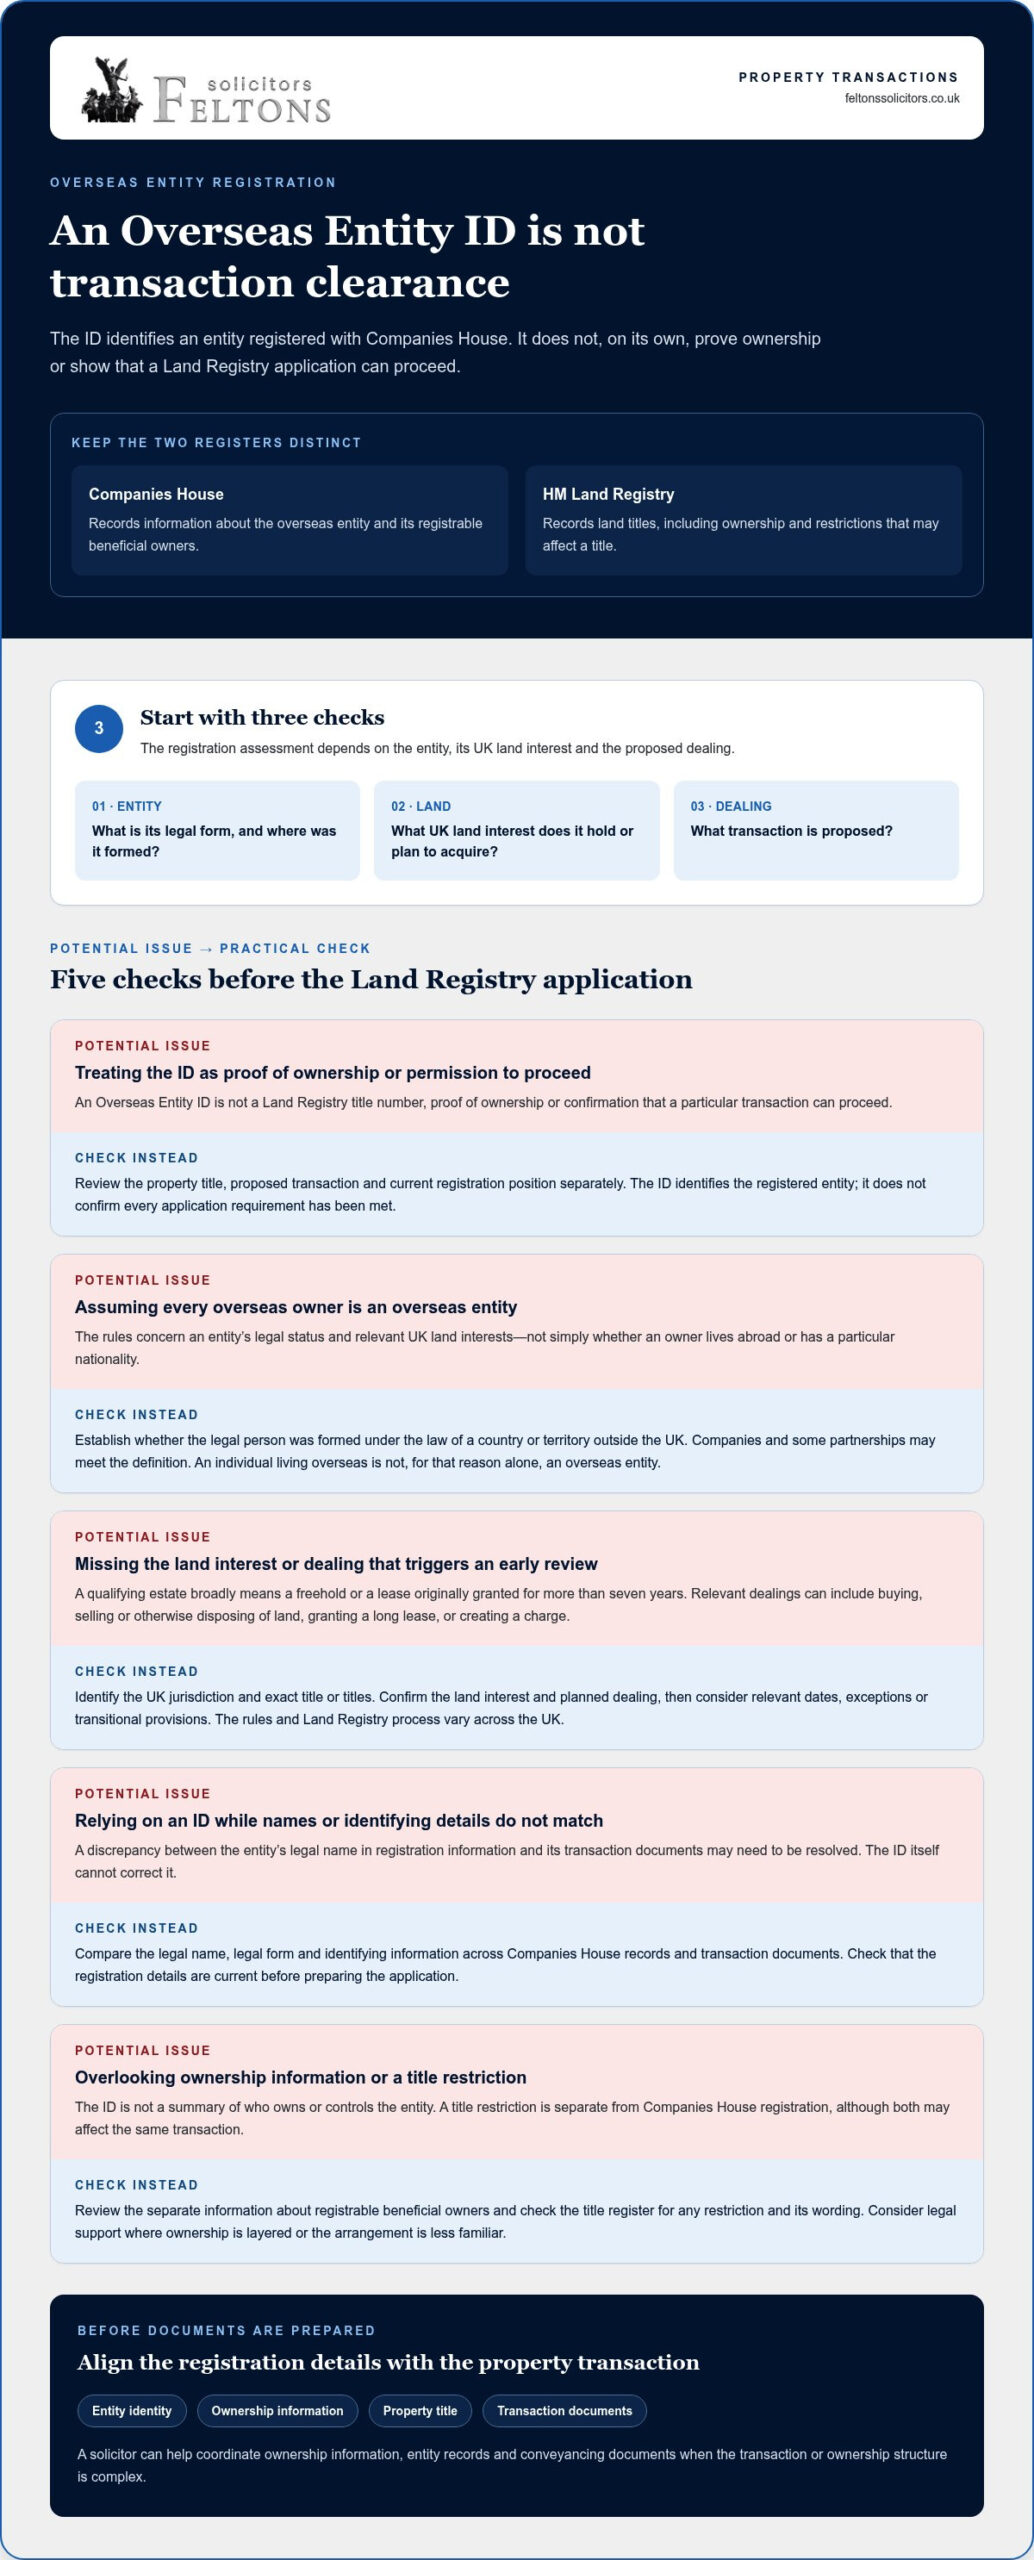
An Overseas Entity ID is a registration reference, not a green light for a UK property transaction. The land registry overseas entity ID requirements involve registering the entity with Companies House and checking that its details support the Land Registry application. An ID alone does not resolve inconsistencies or fill gaps in the information needed for a transaction.

To assess whether the rules apply, look at the entity’s legal status, its UK land interests and the activity proposed. Companies House registration and a Land Registry application are separate steps, so check that the relevant details align before documents are prepared. Doing this early can help identify issues before they affect an application.

This 2026 checklist explains when an Overseas Entity ID may be needed, what information to prepare and what to review before an application is made. It also covers how to check registration details and where legal support can help. Feltons Solicitors LLP advises on overseas entity registration and complex property transactions, helping clients coordinate registration information and conveyancing documents.

Key Takeaways

  • Start by reviewing the entity’s UK land interests and proposed transaction to establish which requirements may apply.
  • Use the land registry overseas entity ID requirements checklist to organise the registration and transaction details before applying.
  • Compare the entity’s legal name, form and identifying information across Companies House records and transaction documents.
  • Check that registration details are current, then review the property title restriction and transaction type before preparing the Land Registry application.
  • A solicitor can help coordinate ownership information, entity records and conveyancing documents when the transaction or ownership structure is complex.

What does a Land Registry overseas entity ID prove?

An Overseas Entity ID is the reference issued by Companies House when an overseas entity is entered on the Register of Overseas Entities. It identifies the registered entity. It is not a Land Registry title number, proof of ownership or confirmation that a particular property transaction can proceed.

The two registers serve different purposes. Companies House records information about the overseas entity and its registrable beneficial owners. HM Land Registry records land titles, including ownership and restrictions that may affect a title. An ID may be necessary for a property transaction, but it does not show that every registration or application requirement has been met. Check the title, proposed transaction and current registration position separately.

Which overseas entities are within the registration rules?

An overseas entity is a legal person formed under the law of a country or territory outside the UK. Companies and some partnerships may meet this definition. The rules concern the entity’s legal status and relevant UK land interests, not simply whether an owner lives abroad or has a particular nationality.

An individual who lives overseas is not, for that reason alone, an overseas entity. However, an individual may be a beneficial owner of an entity, which is a separate part of the registration analysis. The entity’s legal form and the law under which it was formed can affect whether the rules apply. Less familiar arrangements and layered ownership structures may need case-specific legal analysis before a transaction proceeds.

What is the difference between an entity ID and an owner’s details?

The ID is a reference for the registered entity. It is not a summary of the people who own or control it, and it does not replace the information required about registrable beneficial owners. Those details are assessed separately as part of the registration process.

Beneficial ownership analysis looks at relevant information about people or legal entities that own or exercise control over the overseas entity. The assessment depends on the structure and applicable rules. An ID alone does not establish that ownership information is complete, current or suitable for the transaction.

  • Entity identity: the overseas entity’s legal name and form.
  • Entity reference: the Overseas Entity ID issued after registration.
  • Ownership and control: the separate information required about registrable beneficial owners.

When checking the land registry overseas entity ID requirements, keep these elements distinct. A mismatch between the entity’s legal name in registration information and its transaction documents may need to be resolved. The ID itself cannot correct that discrepancy. Feltons Solicitors advises on overseas entity registration and complex property transactions, helping clients align ownership information with conveyancing documents.

Who needs an overseas entity ID for a UK property transaction?

Start with three questions: what kind of entity is involved, what interest in UK land does it hold or plan to acquire, and what transaction is proposed? Under the overseas entities regime, a legal entity governed by the law of a country or territory outside the UK may need to register if it owns or seeks to acquire a qualifying estate. Broadly, this means a freehold or a lease originally granted for more than seven years. The rules and Land Registry process vary across the UK, so identify the relevant jurisdiction before assessing the transaction.

This is a starting point, not a universal answer. The land registry overseas entity ID requirements can depend on the property interest, transaction date, title and applicable exemptions or transitional provisions. The regime also covers certain earlier acquisitions, with relevant dates varying across the UK. Review the transaction and title rather than relying on a general summary.

Which property dealings should prompt an early eligibility check?

Check the position early if an overseas entity is buying a qualifying estate, selling or otherwise disposing of relevant land, granting a long lease, or creating a charge over it. The effect of the rules depends on the dealing and circumstances. Having an ID does not automatically satisfy every Land Registry requirement.

Review the property title alongside the Companies House registration. A restriction on a title is a Land Registry entry that can limit registration of specified dispositions unless its stated condition is met. It is separate from registration on the Register of Overseas Entities, although both may affect the same transaction.

  • Identify the relevant UK jurisdiction and exact title or titles.
  • Confirm whether the entity owns or proposes to acquire a freehold or qualifying lease.
  • Describe the planned dealing, such as a transfer, lease or charge.
  • Review the title register for a restriction and note its wording.
  • Check relevant dates and whether an exception or transitional provision may apply.

How can ownership structures change the assessment?

Look beyond the name shown on the title. An overseas entity may be owned through several companies, or control may be exercised through arrangements that are not obvious from a simple ownership chart. Registration analysis must identify any registrable beneficial owners under the applicable tests. Shareholders and directors are not automatically decisive in every case.

Trust arrangements need particular care. Depending on the facts and rules, trustees and other people connected with a trust may be relevant to the ownership or control assessment. The treatment differs between structures. Record the chain of ownership and control, and flag trusts, intermediate entities or disputed control for legal analysis before preparing documents.

Where the structure or title raises questions, overseas entity registration and conveyancing support can help align the ownership analysis with the proposed property dealing and its Land Registry requirements.

What information should you check before relying on an overseas entity ID?

Review the details before relying on the ID in a property transaction. A valid-looking reference could be linked to the wrong entity, or the records may no longer reflect its legal name or ownership structure. The land registry overseas entity ID requirements are one part of the check: compare the Companies House record with the title and transaction documents.

Consistent records make it easier to show that the registered entity, property title and application documents refer to the same legal person. Differences in spelling, legal form or identifying details may need an explanation or correction. Deal with discrepancies early rather than waiting until the application is being prepared.

How should the entity’s registration details be checked?

Start with the Companies House Register of Overseas Entities. Find the entity and compare its record with the proposed transfer, lease or charge. Check the exact legal name and form, then confirm that the Overseas Entity ID belongs to that entity, not another group company with a similar name. Review the registration details for changes since the ID was issued.

Check the entity’s current position as well as its original registration. Overseas entities must file an annual update statement within 14 days of each registration anniversary, even if there have been no changes. Review the Companies House record for the latest filing and the next update date. Confirm the evidence and checking process required for the particular application against current Companies House and HM Land Registry guidance.

What owner and control information may need attention?

Compare the ownership and control information on the register with the entity’s current structure. Trace intermediate companies and consider whether changes in ownership, control or relevant personal details have been reflected in the required filings. Investigate missing or inconsistent entries rather than assuming they are immaterial. Trust arrangements may also require careful analysis. The people and information relevant to the disclosure depend on the circumstances and applicable rules.

  1. Match the entity: compare the exact legal name, legal form and identifying details across the Companies House record and transaction documents.
  2. Check the ID: confirm it is recorded against the entity that will be party to the transaction.
  3. Review current status: check registration details, the latest update statement and its next due date.
  4. Compare ownership: review beneficial owner and control information against the current structure, noting changes or uncertainties.
  5. Check the property records: examine the relevant HM Land Registry title information and ensure the application documents address any restriction.
  6. Organise supporting material: keep relevant records together and submit sensitive information only through the appropriate official process.

For complex structures, a solicitor can help reconcile entity records, beneficial ownership information and conveyancing documents before an application is lodged. This review can identify inconsistencies early and clarify which points need further attention under the current rules. In addition, individuals managing cross-border assets should keep abreast of broader statutory obligations, taking note of any recent hmrc tax warning regarding financial compliance and reporting.

Land Registry Overseas Entity ID Requirements: A 2026 Checklist

How do overseas entity ID requirements affect a Land Registry application?

Companies House registration and a Land Registry application are separate steps. Companies House records the overseas entity and issues its Overseas Entity ID. HM Land Registry deals with the property title and applications to register transactions. Having an ID does not, by itself, establish that an application meets the requirements for the title or the particular dealing.

The land registry overseas entity ID requirements need to be considered alongside the title register, transaction and supporting documents. A restriction on the title may specify conditions that must be satisfied before a disposition can be registered. Its wording matters. Do not assume that the same evidence or process applies to every sale, lease, charge or other dealing.

What should be checked on the title and application?

Begin with the current title information and identify any restriction referring to an overseas entity. Compare the registered proprietor and transaction parties with the Companies House details. A group may have several overseas companies with similar names, so confirm that the ID belongs to the legal entity named in the transaction and title records.

Next, establish which Land Registry application and evidence are appropriate for the transaction. Requirements can depend on the title, restriction and nature of the disposition. Check the current HM Land Registry guidance, forms and evidence standards rather than reusing documents from a different matter. The September 2026 version of Practice Guide 78 may require evidence that an overseas entity has existed continuously since it was first registered as proprietor. Assess whether that point is relevant to the title and application.

  • Read the restriction on the title and note the condition it sets.
  • Match the entity named on the title and in transaction documents to its Companies House record and ID.
  • Identify the transaction type and the application being made.
  • Check current Land Registry guidance for the applicable evidence and filing requirements.

What can happen if the ID or application details do not match?

An inconsistency may prompt HM Land Registry to raise questions or requisitions, or delay consideration of the application. The outcome depends on the issue and relevant rules. An administrative difference is not necessarily the same as a substantive eligibility or compliance problem, but it should be explained or corrected through the appropriate process.

For example, if a transfer names “Northstar Holdings Ltd” but the title or Companies House record uses a different legal name, the application may need clarification or supporting evidence. The mismatch could be a naming discrepancy, or it could indicate that the ID for a different entity has been supplied. These situations require different responses, so investigate the cause rather than making assumptions.

Where a restriction, ownership structure or supporting evidence raises questions, get legal support with your Land Registry application to coordinate registration details and conveyancing documents before submission.

A checklist helps organise the facts, but it cannot replace advice on the specific entity, title and transaction. The land registry overseas entity ID requirements involve separate Companies House and Land Registry processes. A solicitor can bring the records together, identify gaps in ownership information and assess how a title restriction applies to the proposed dealing.

Coordination is especially useful when registration details and conveyancing documents were prepared at different times or by different parties. For example, a change to an entity’s legal name or control structure may need to be reflected in relevant records and considered alongside the transaction documents. Legal review can identify what needs attention and which steps apply, without assuming a particular outcome or timetable.

When is tailored legal advice particularly useful?

Consider transaction-specific advice if ownership runs through several entities, a trust is involved, the entity’s details have changed, or the transaction is time-sensitive. These circumstances can raise questions that a general checklist cannot resolve by itself.

A solicitor can review the entity and ownership information alongside the title restriction and planned dealing. This joined-up assessment can help distinguish a record discrepancy from a wider eligibility or compliance issue, and clarify what to address before an application is prepared. Feltons Solicitors advises on overseas entity registration and complex property transactions, bringing registration and conveyancing considerations into the same discussion.

What should you have ready for an initial discussion?

You do not need to resolve every issue before seeking advice. A concise set of core details helps focus the discussion and identify what further information may be needed.

  • Entity details: the exact legal name, legal form and jurisdiction in which the entity is formed.
  • Registration reference: the Companies House Overseas Entity ID, if one has been issued, and any known update or record changes.
  • Property information: the relevant title number or title details, together with a copy of the title register if available.
  • Transaction outline: a short description of the proposed purchase, sale, lease, charge or other dealing, including any key dates.
  • Ownership and control: a simple outline of the ownership chain, any trusts, changes in control and unresolved questions.

Keep supporting documents organised, but avoid sending sensitive ownership material through informal or insecure channels. Appropriate handling depends on the information and why it is being provided.

For broader background on identifying the people connected with an overseas entity, the Overseas Entity Beneficial Owner Registration guide can help explain the ownership side of the checklist. For a UK property transaction, Feltons Solicitors can discuss how the registration position, title details and conveyancing documents fit together.

Put the next property step on a clear footing

Before the transaction moves further, turn your checklist into a working file. Record unanswered questions, identify who can provide the missing information and keep relevant documents together. This gives everyone involved a clearer basis for addressing registration and application issues as they arise.

The land registry overseas entity ID requirements can intersect with ownership structures and conveyancing documents in ways that call for a transaction-specific review. That assessment can help you identify what needs attention next, rather than relying on assumptions about how a previous matter was handled.

Feltons assists with overseas entity registration, residential and commercial conveyancing, and complex property transactions. Discuss your overseas entity and property registration requirements with Feltons to consider the appropriate next steps for your matter.

With the relevant details organised and issues identified, you can move forward with greater clarity about the registration and application requirements.

Frequently Asked Questions

What is a Land Registry overseas entity ID?

It is the reference Companies House issues after registering an overseas entity on its Register of Overseas Entities. The ID identifies the entity in that register. It is not a property title number or confirmation that every requirement for a particular transaction has been met. For example, an entity’s ID does not explain whether a restriction on a title affects a proposed transfer. Check the current rules and application requirements for the specific property and transaction.

Does an overseas entity need an ID to buy UK property?

An overseas entity may need to register and obtain an ID before a relevant property transaction can proceed, depending on its circumstances and the applicable rules. The land registry overseas entity ID requirements are not a single test that applies identically to every buyer. Establish the entity’s legal status, the property interest being acquired and whether an exception may be relevant. The title and current Companies House guidance can help identify the checks needed.

Can an overseas entity sell UK property without an ID?

That depends on the title, proposed sale and rules that apply to the entity. A restriction on the title may affect whether HM Land Registry can register a disposition, but its wording and any relevant exception need to be considered in context. Review the title register and current Land Registry guidance before progressing. A conveyancing solicitor can assess whether the entity’s registration position and sale documents address the relevant requirements.

What information is needed to apply for an overseas entity ID?

Registration generally requires information about the overseas entity and, where applicable, its registrable beneficial owners or managing officers. The details depend on the entity’s legal form and ownership arrangements. For example, a structure involving intermediate companies may require tracing ownership and control rather than considering only the immediate shareholder. Check the latest Companies House guidance before preparing the application, particularly if trusts or unusual control arrangements are involved.

Is an overseas entity ID the same as a Companies House number?

No. An Overseas Entity ID relates specifically to registration on the Register of Overseas Entities. It is distinct from other Companies House identifiers and from a Land Registry title number, which relates to a property title. For a transaction, use the precise reference requested and compare it with the entity’s official register entry. Similar names or numbers within a corporate group make this check particularly important. Do not assume one identifier can replace another.

What happens if the overseas entity ID is incorrect on a Land Registry application?

An incorrect or inconsistent ID may lead HM Land Registry to ask for clarification or raise a requisition, and could delay registration depending on the circumstances. Compare the application against the entity’s Companies House record to establish whether the error is a typing mistake or relates to a different entity. If the application has already been submitted, establish the appropriate correction process promptly. Where completion arrangements are time-sensitive, seek advice on the specific application.

Do beneficial owners need their own overseas entity ID?

No. The Overseas Entity ID identifies the registered entity, not each beneficial owner. However, registration may require information about registrable beneficial owners and other relevant people, depending on the ownership structure and applicable tests. For example, an individual who controls an entity through another organisation may need to be considered as part of the ownership analysis. Keep the entity’s reference separate from disclosure information and review complex arrangements carefully.

How long does it take to get an overseas entity ID?

There is no fixed timeframe that applies to every application. Processing can vary, and the completeness of the submission, verification requirements and complexity of the ownership structure may affect progress. Check current Companies House service information when planning, and allow time to address questions or correct information before a property transaction reaches a critical stage. If timing could affect contractual or completion arrangements, seek advice based on the transaction’s circumstances.