Could an overseas company agree terms for a UK commercial property, only to find that a registration gap prevents the transfer being registered? It’s a practical risk: an overseas entity generally needs to be registered with Companies House and hold a valid Overseas Entity ID, or the Land Registry may refuse to register the property transfer. A commercial property acquisition overseas company buyers plan therefore needs the legal and compliance steps considered together from the outset.
Registration, company records and property due diligence can all affect the transaction. Preparing early helps you identify the information needed and deal with key requirements before they become obstacles. This guide covers the main stages, including overseas-entity registration, due diligence, conveyancing and the filing duties that follow registration.
Feltons Solicitors LLP advises on commercial conveyancing and registration of overseas entities, helping national and international clients coordinate these connected matters. This guide explains what to prepare, when each step arises and how tailored legal advice can help you move the transaction forward.
Key Takeaways
- Clarify which UK jurisdiction the property is in and whether the buyer is an overseas entity, as this shapes the legal steps involved.
- Prepare beneficial-owner and managing-officer information early to address registration and disclosure requirements.
- Tailor due diligence to the property’s title, occupational arrangements, condition and intended commercial use.
- Plan the commercial property acquisition overseas company process as a connected sequence, coordinating entity checks, property enquiries and conveyancing from the outset.
- Joined-up legal advice can help organise company information, assess contractual issues and progress registration and conveyancing together.
Commercial property acquisition by an overseas company: what the transaction involves
An overseas-company acquisition is a transaction in which an entity formed outside the UK buys or holds UK commercial land. The purchaser is the company, not the directors who sign documents on its behalf, its members or shareholders, or the people who ultimately own or control it. These roles can overlap, but they are legally distinct and may call for different information and checks.
This guide focuses on UK property. Land and property law differs across England and Wales, Scotland and Northern Ireland, so the location of the asset matters. For general background on the UK market, see the UK Real Estate Market Overview. A “commercial property acquisition overseas company” transaction involves two connected workstreams: checking the overseas buyer’s identity and compliance, and investigating the property while negotiating its transfer or lease.
Which overseas-company structure is buying the property?
An overseas entity may buy property directly in its own name. Alternatively, a group might use a UK-incorporated subsidiary as the buyer, creating a separate UK legal entity within the wider corporate structure. The choice can affect how ownership is organised and may have corporate, tax and financing consequences that depend on the buyer’s circumstances. There is no single structure that suits every purchaser. Identify the intended buyer early so the entity named in the offer, contract and registration steps is consistent.
What makes a commercial acquisition different?
Commercial due diligence depends on what the buyer plans to do with the premises and whether anyone already occupies them. An office bought for the buyer’s own business raises different practical questions from a warehouse acquired with an existing tenant, for example. The title, lease terms, permitted use, repair obligations and condition can all affect the buyer’s assessment of the property and the terms needed in the contract.
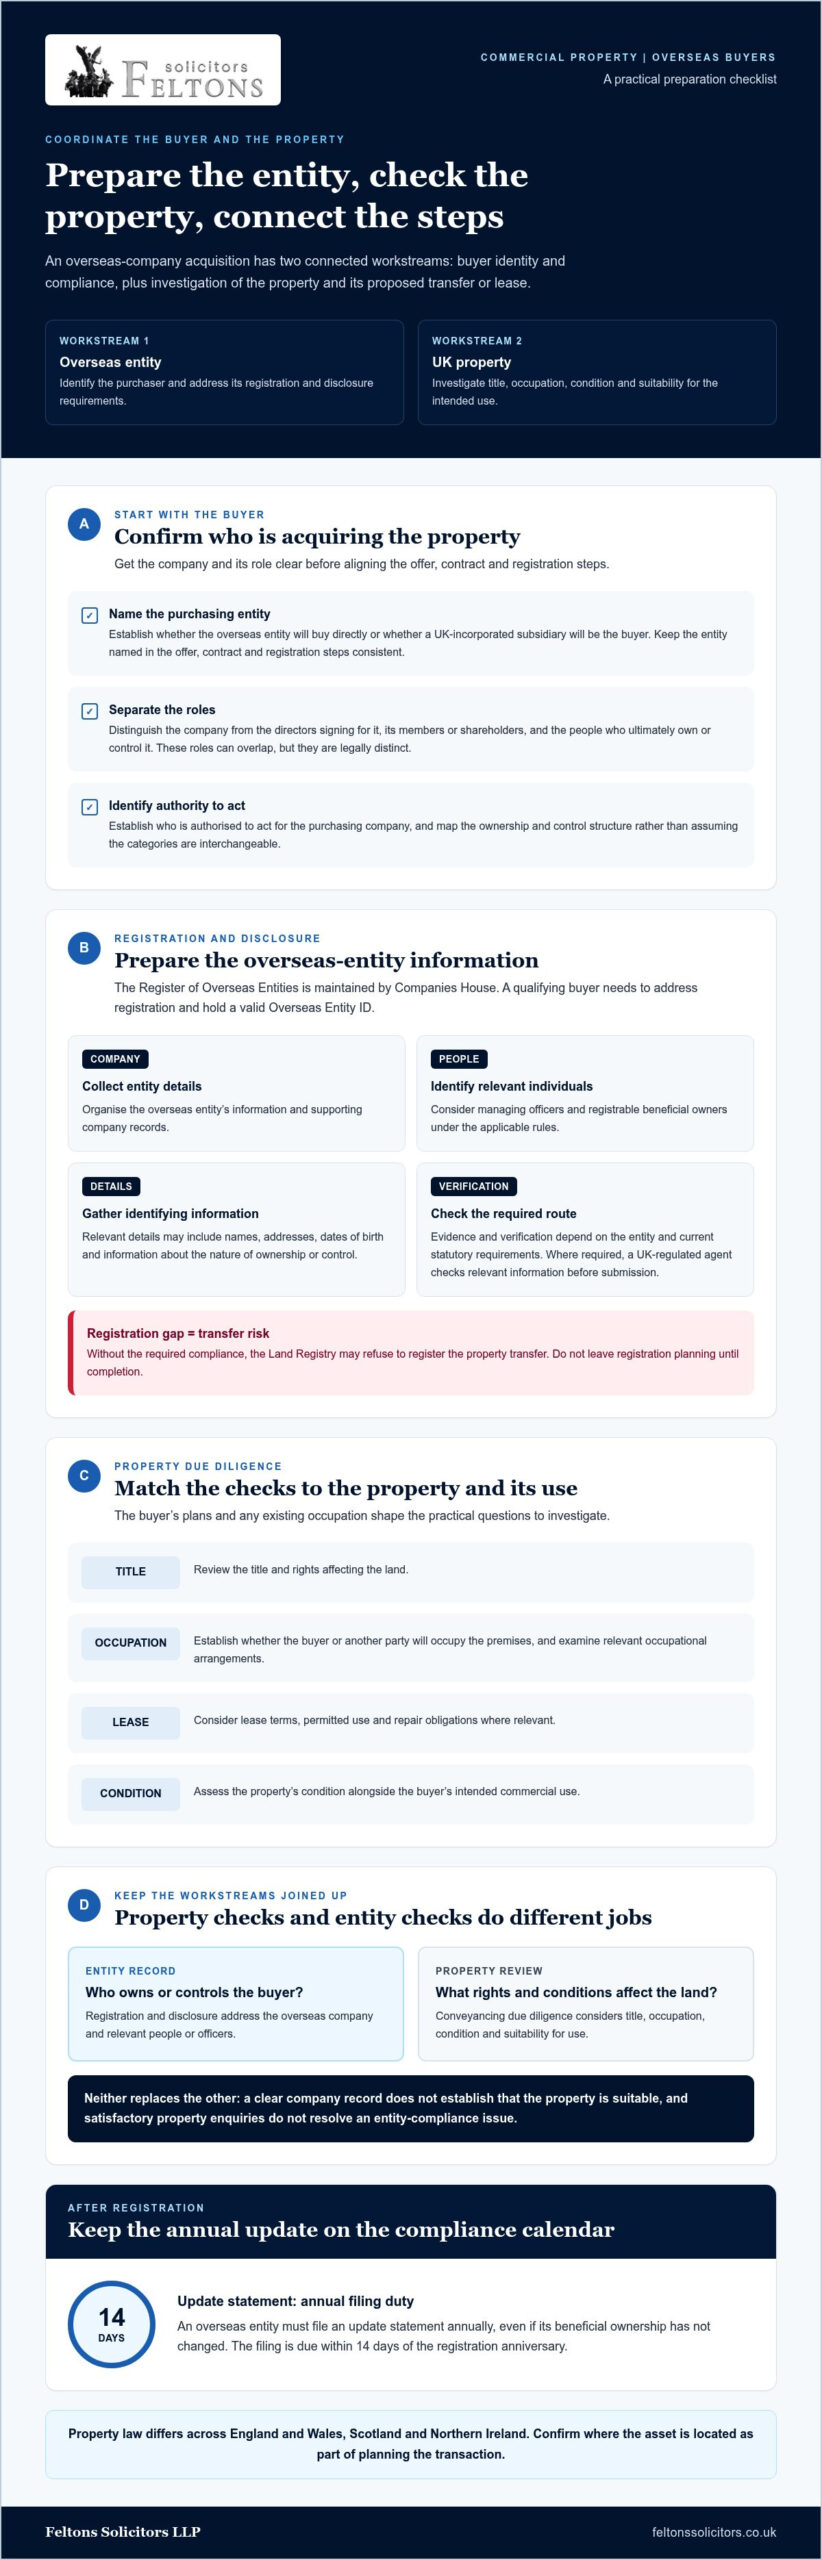
Keep these property questions separate from ownership disclosure. The property review concerns rights affecting the land, occupational arrangements and suitability for the intended use. Entity checks concern the overseas company and the people or officers relevant to its ownership and control. Neither replaces the other: a clear company record does not establish that the property is suitable, and satisfactory property enquiries do not resolve an entity-compliance issue.
- Purchasing entity: establish which company will enter into the transaction and who is authorised to act for it.
- Ownership and control: distinguish the company’s directors and members from the people who ultimately own or control it.
- Property purpose: identify the planned use and whether the premises will be occupied by the buyer or another party.
Resolve these points together to give the transaction a clearer foundation. This helps align company information, property enquiries and contract arrangements before the buyer commits to a structure or timetable.
Overseas-entity registration and disclosure: the compliance questions to resolve
The Register of Overseas Entities (ROE), maintained by Companies House, records information about overseas entities that own or seek to acquire qualifying UK land. The regime was introduced by the Economic Crime (Transparency and Enforcement) Act 2022. For a qualifying buyer, registration and a valid Overseas Entity ID are important parts of the acquisition. Without compliance, the Land Registry may refuse to register the property transfer.
Registration is not a formality to leave until completion. The buyer needs to establish which overseas entity is acquiring the property, identify the people and officers whose details must be disclosed, and organise verification in line with the rules that apply to its ownership structure. These checks sit alongside, rather than replace, conveyancing due diligence. An entity’s registration record does not establish that the property title, lease arrangements or condition are satisfactory.
What information and verification may be required?
The application generally involves information about the overseas entity, its managing officers and any registrable beneficial owners. A beneficial owner is an individual or relevant legal entity that meets the statutory tests for owning or controlling the overseas entity. A managing officer is a person who manages the entity where the rules require their details. Directors, shareholders and beneficial owners are not automatically interchangeable categories, so examine the ownership structure rather than assume they are the same.
Relevant details may include names, addresses, dates of birth or other identifying information, as well as information about the nature of ownership or control. The evidence and verification route depend on the entity and the current statutory requirements. Where verification by a UK-regulated agent is required, that agent checks the relevant information before it is submitted. Different structures can involve several lines of ownership and control, so map the group structure and collect supporting company records early.
How can registration affect the acquisition timetable?
Check registration status as soon as the proposed buyer and transaction are identified. If the entity still needs to register, gathering information across a group with several ownership layers or overseas officers may require coordination. Running this work alongside offer negotiations and property enquiries can help avoid leaving a key compliance step until the parties are preparing to complete.
The practical link is clear: an overseas entity that must comply with the ROE needs the required registration status for the Land Registry to register the relevant property transaction. The precise restriction and how it applies depend on the circumstances and current rules, so review the buyer’s status and title requirements as part of the conveyancing process.
For a commercial property acquisition overseas company, aligning registration work with conveyancing helps keep entity information, verification and title registration on the same transaction plan. Feltons advises on overseas-entity registration and commercial conveyancing, coordinating these related steps and addressing the details of the ownership structure.
Commercial property due diligence for an overseas-company buyer
Property due diligence helps you understand what is being acquired, how it can be used and which obligations may continue after completion. Shape enquiries around the buyer’s plans: a property intended for its own operations may raise different priorities from an investment property with existing tenants. Keep this review separate from checks on the purchasing entity. Company registration does not establish that the property is suitable or that its title and occupation arrangements are acceptable.
Organise the work by linking each enquiry area to the decision it informs:
| Enquiry area | What to examine | Decision it informs |
|---|---|---|
| Title and rights | Ownership, title entries, access, restrictions and third-party interests | Whether the buyer can obtain the rights and control it needs |
| Occupation | Lease terms, rent position, tenant obligations and who occupies the premises | Whether income, possession and continuing responsibilities fit the plan |
| Condition and environment | Available building information and appropriate technical investigations | Whether further assessment or contractual protection is needed |
| Intended use | Planning history, permitted use and relevant building documents | Whether the proposed activity appears compatible with the property information |
Title, rights and occupational arrangements
Title review identifies the registered owner and the rights or restrictions recorded against the land. An access route, for example, may depend on rights benefiting the property, while a title restriction may affect how it can be dealt with. Third-party interests can also shape the buyer’s practical control. Conveyancing enquiries clarify what those entries mean for the proposed transaction and whether further information or contractual provisions should be considered.
If the property is let, examine the lease rather than relying only on a summary of the rental position. Relevant points include the term, rent, review provisions, repair and insurance obligations, permitted occupation and arrangements affecting the tenant’s use. The findings may inform negotiations, contractual protections or, if a concern cannot be resolved, a decision not to proceed.
Use, condition and transaction-specific risks
Start with the intended activity. A buyer planning to operate a particular business from the premises needs enquiries into whether the recorded planning position, permitted use and available building documents align with that plan. The precise enquiries depend on the site and proposed use. Legal review can identify issues in the available documents, but cannot replace specialist technical conclusions.
Condition and environmental investigations serve a different purpose from legal due diligence. Appropriate surveys and assessments can reveal matters that need specialist evaluation. A valuation considers the asset’s value for its purpose, while tax advice addresses the buyer’s particular structure and transaction. These workstreams should inform one another without being confused.
VAT also deserves early attention. If the seller has opted to tax the property, VAT may affect the purchase price and the SDLT calculation. The position depends on the transaction, so include it in tailored tax advice before finalising the commercial assumptions. A coordinated commercial property acquisition overseas company review connects title findings, occupation, intended use and tax questions to the buyer’s decision, rather than treating each enquiry in isolation.
From offer to completion: a practical acquisition sequence
A clear sequence keeps company checks, property enquiries and contract decisions moving together. The steps below are a useful framework, not a fixed timetable. The transaction’s pace depends on the property, the buyer’s company information, the registration position and what due diligence reveals.
Before exchange: establish the buyer and investigate the asset
Before committing, confirm the exact entity that will buy the property and gather its constitutional documents, authority to act and relevant ownership information. At the same time, review the title and contract papers, arrange appropriate searches and consider the property’s commercial arrangements. Record issues that need negotiation, further investigation or specialist input so they can inform the decision to proceed.
- Identify the proposed buyer. Confirm the overseas entity’s legal name, place of incorporation and the people authorised to act for it. Make sure the proposed purchaser is consistent across the offer, company records and transaction documents.
- Review registration requirements early. Establish whether the entity needs to register with Companies House and whether it has the required Overseas Entity ID. If registration or verification is needed, coordinate that work with conveyancing rather than leaving it until the parties are ready to complete.
- Agree offer terms and obtain the papers. Clarify the proposed price, what is included in the sale, any occupation arrangements and the intended use. Request the contract pack and available property information so legal review can begin promptly.
- Investigate the property and the transaction. Review the title, searches, leases and other relevant documents, and arrange appropriate specialist enquiries. Compare the findings with the buyer’s plans, noting matters that may affect value, use, obligations or contract terms.
- Resolve key issues before exchange. Decide whether further information, contract changes or other protections are needed. Exchange is the point at which the parties enter into a binding contract on its terms, so address material concerns before making that commitment.
Exchange, completion and registration
Completion is when the transaction is carried out in accordance with the contract, including payment of the balance and transfer of the property. The conveyancer then deals with applicable post-completion filings and applies to register the transfer with the relevant land registry. Requirements depend on the property’s jurisdiction and the transaction. The sequence is straightforward in principle, but the supporting documents and compliance position must be in order.
- Prepare for completion. Confirm that contractual requirements, funds and documents are ready, and that the buyer’s registration position supports the intended transaction.
- Complete and register the transfer. Carry out the agreed completion steps, then submit the required application and supporting documents to the relevant land registry.
For more detail on ownership disclosures, the guide to overseas entity beneficial owner registration explains the information involved. Feltons coordinates registration and commercial conveyancing as part of a commercial property acquisition overseas company transaction. Speak to Feltons about your acquisition for tailored legal support with company information, property enquiries and contractual steps.
How Feltons can support an overseas-company commercial acquisition
A commercial purchase by an overseas entity brings together company information, property documents and contractual decisions. Feltons Solicitors LLP advises on commercial conveyancing and registration of overseas entities, including complex property transactions for national and international clients. Tailored legal advice can help you understand how these strands relate, identify the information to gather and focus on issues that may affect the proposed transaction.
The legal work can include considering the buyer’s entity details and registration position alongside the property papers, reviewing the contract and raising relevant conveyancing enquiries. This joined-up approach helps show where one issue may affect another. For example, proposed occupation arrangements may influence contract terms, while the identity of the purchasing entity informs registration work. The aim is pragmatic advice shaped around the transaction, not a promise of a particular outcome.
Coordinating registration and conveyancing advice
Clear responsibilities and organised documents can make a complex purchase easier to manage. The buyer’s team can identify who will provide company and ownership records, who can approve decisions, and how property enquiries and registration information will be gathered. Timely communication matters, particularly where information must come from people in different roles or jurisdictions.
The legal team can connect the entity review with the title, contract and occupational arrangements while keeping each workstream distinct. If the commercial decision involves weighing ownership against occupation under a lease, Feltons’ guide to commercial property law: buying versus leasing may help frame the issues for discussion. Tax, financing and technical questions may need input from the relevant specialists. Legal advice can identify where those questions intersect with the conveyancing process.
Preparing for an initial legal discussion
A focused first discussion is easier when the key facts are to hand. You do not need to resolve every issue in advance. A useful starting pack may include:
- Entity details: the proposed buyer’s legal name, place of incorporation and available constitutional documents.
- Ownership and authority information: a group structure or ownership chart, details of relevant officers and information about who can authorise the purchase.
- Property particulars: the address, title information if available, sales particulars, draft contract papers and details of any existing lease or occupation.
- Commercial objectives: the intended use, whether the buyer or a tenant will occupy the premises, and the key points the buyer wants the transaction to achieve.
These details help shape advice around the actual buyer and asset. They also make it easier to identify missing information, clarify priorities and organise next steps without assuming every acquisition follows the same route.
If you’re considering a commercial property acquisition overseas company structure, Feltons can advise on the proposed purchase. A discussion of the company, property and commercial objectives can help establish the appropriate conveyancing and overseas-entity registration work for your circumstances. Discuss your commercial property acquisition with Feltons.
Plan your next step with confidence
Turn your commercial objective into a clear legal plan. Consider what the property needs to achieve for your business or investment, which decisions are time-sensitive and who within your organisation can provide the required information. For a commercial property acquisition overseas company buyers pursue, this early alignment helps connect legal questions to the purpose of the purchase.
Feltons Solicitors LLP advises national and international clients on complex property matters, bringing commercial conveyancing and overseas-entity registration support together where the transaction calls for both. Advice can be tailored to the proposed buyer, property and contractual issues, while tax, finance or technical questions can be considered with the relevant specialists.
You do not need every detail resolved before seeking legal guidance. A discussion can help clarify priorities, identify useful documents and establish appropriate next steps for your circumstances. Discuss your commercial property acquisition with Feltons to understand the legal work involved.
Frequently Asked Questions
Can an overseas company obtain a UK commercial mortgage?
Does buying UK commercial property through an overseas company create UK tax obligations?
It can. The acquisition may involve property transaction taxes, and VAT can affect the price and tax calculation if the seller has opted to tax the property. Tax obligations can also arise during ownership or on disposal; non-resident companies pay UK Corporation Tax on gains from disposing of UK commercial property. The treatment depends on the transaction, structure and property location, so obtain tailored tax advice before relying on projected costs or returns.
Is beneficial ownership information on the Register of Overseas Entities publicly available?
Yes, the Register of Overseas Entities is publicly searchable and provides information about overseas entities and registrable beneficial owners. Not every personal detail is necessarily displayed: some information, such as residential addresses and full dates of birth, is treated differently from public-facing details, and protection arrangements may apply in defined circumstances. Buyers should distinguish the information that must be supplied to Companies House from what the public can view.
How often must an overseas entity update its information?
An overseas entity must file an update statement with Companies House annually, even if its beneficial ownership information has not changed. The filing is due within 14 days of the anniversary of its registration. The statement confirms or updates the relevant information for the entity. Keep a record of the registration anniversary and review ownership and officer details in good time so changes can be accurately reported through the applicable process.
Can an overseas company buy UK property through a UK subsidiary instead?
Yes. A group may choose to have a UK-incorporated subsidiary purchase the property rather than having the overseas parent acquire it directly. The subsidiary is a separate legal entity, so its authority, funding and contractual position need to be considered in their own right. Using a UK company does not automatically remove other disclosure or compliance obligations. The right structure depends on the group’s commercial, tax and financing circumstances.
Does an overseas company need a UK bank account to buy commercial property?
A UK bank account is not necessarily a legal prerequisite to owning commercial property, but the buyer needs a workable arrangement for paying the purchase funds and meeting any lender or transaction requirements. The conveyancer will need to understand the source and movement of funds as part of the transaction checks. If funds will arrive from an overseas account, agree the practical transfer arrangements early, particularly where currency conversion or several group entities are involved.
What happens if an overseas company’s ownership changes after it acquires property?
A change in ownership or control may affect the information the company must disclose to Companies House. The entity should assess whether the change makes someone a registrable beneficial owner or alters details already on the Register, then report it through the applicable update process. Keep supporting records and review the effect promptly rather than waiting for a future sale or refinancing. Changes can also have separate corporate, financing or tax implications.