Overseas Corporate Property Compliance: UK Guide 2026

Overseas Corporate Property Compliance: UK Guide 2026

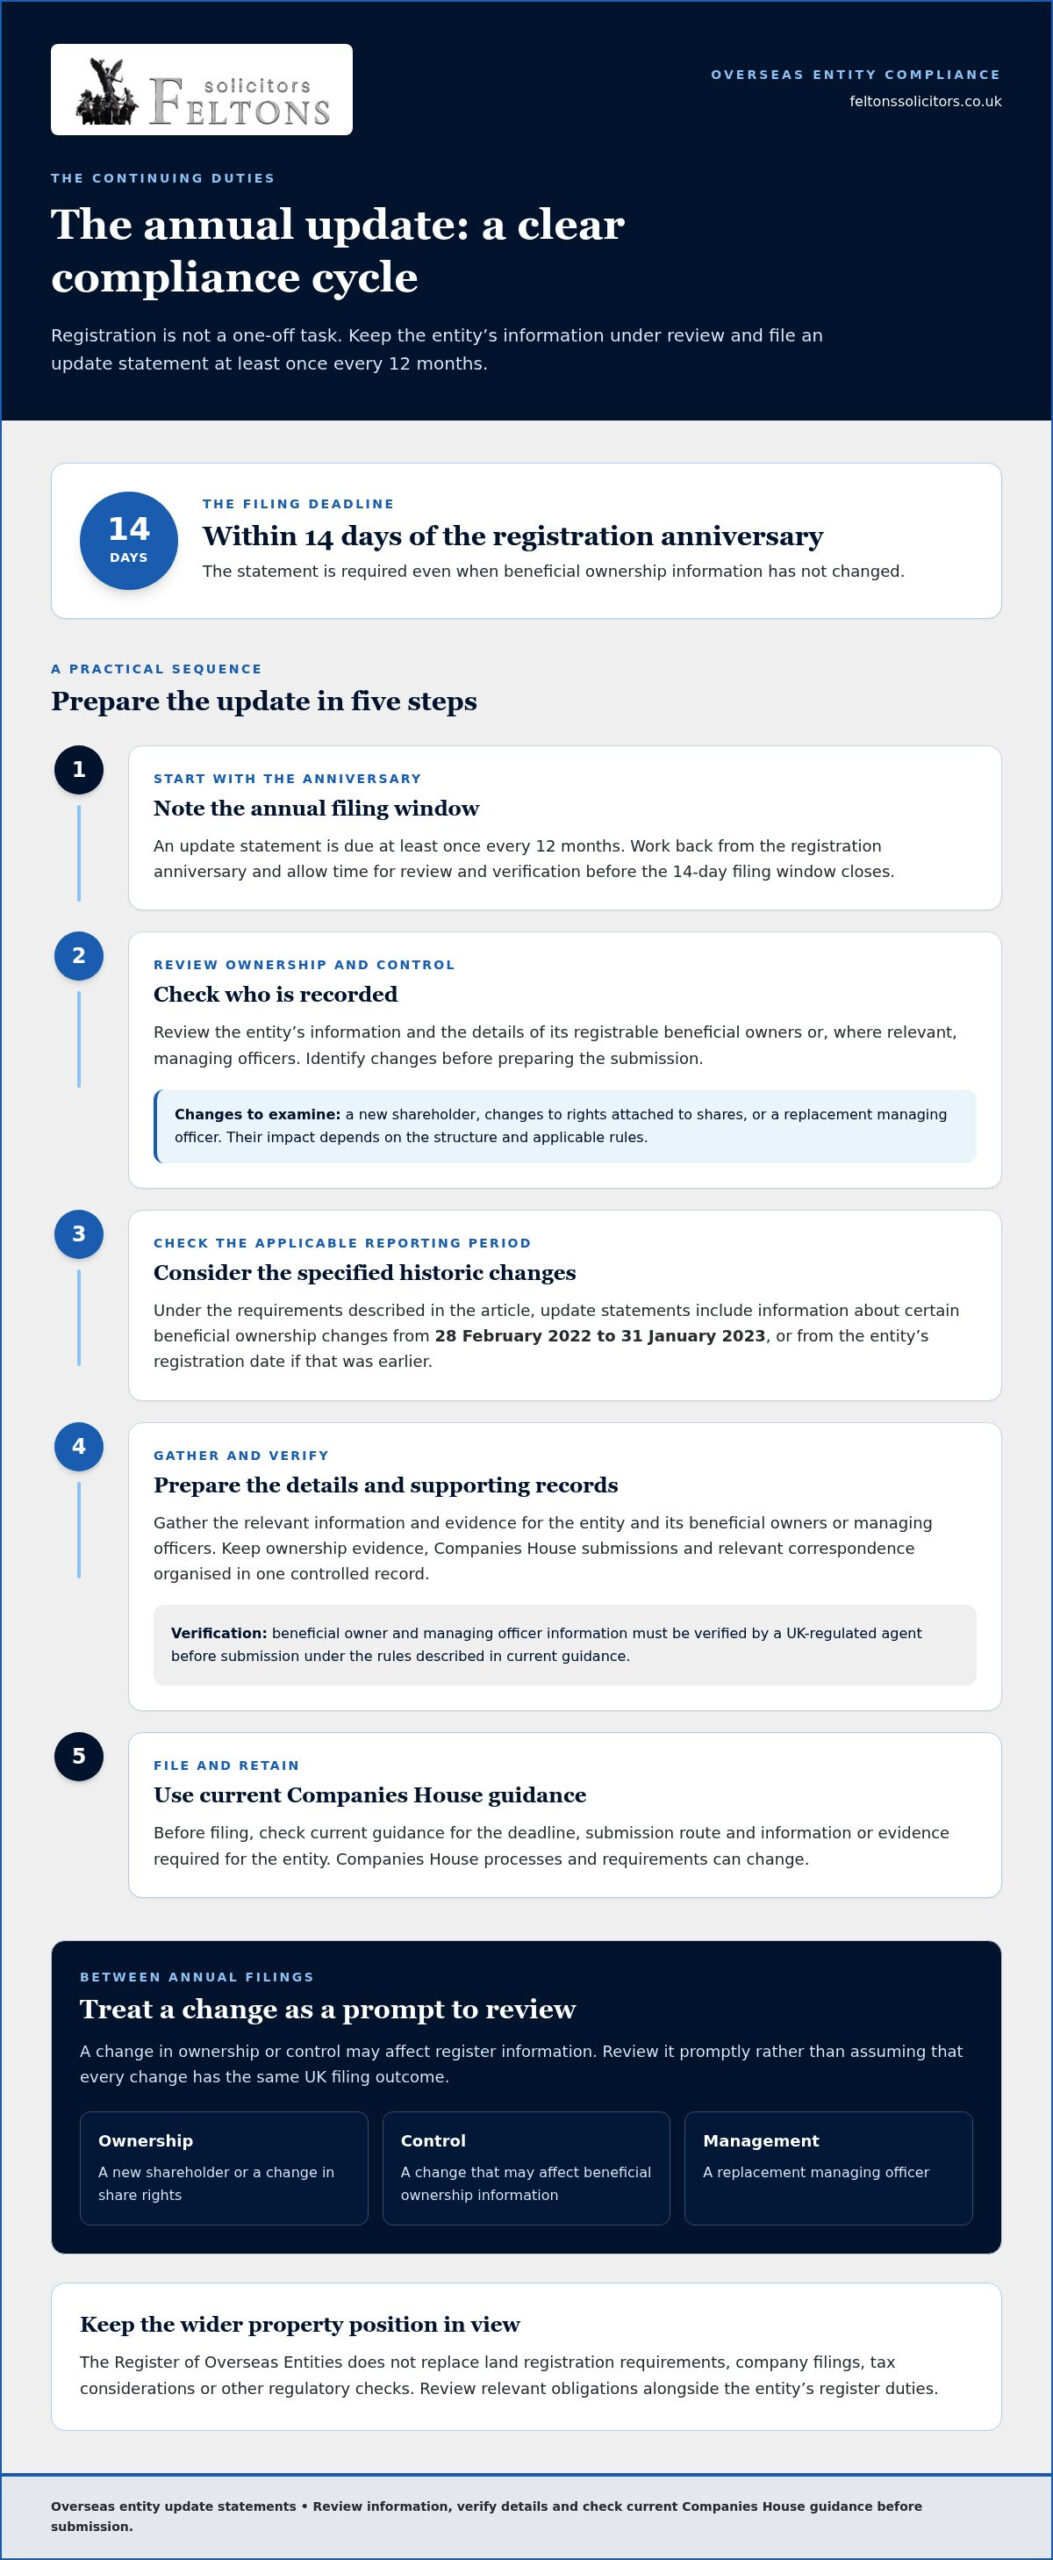
What if registering an overseas entity is only the start of its UK property compliance duties? For organisations that own UK land, overseas corporate property ownership compliance is an ongoing process. A registered entity must file an update statement with Companies House at least once every 12 months, even if its beneficial ownership hasn’t changed. The filing is due within 14 days of the registration anniversary.

It can be difficult to know which changes to report, what records to keep current and how the Register of Overseas Entities fits alongside other obligations. These duties are connected: a change in ownership or company information may require a prompt review.

This guide explains the continuing duties linked to overseas entity registration and the events that may need attention. It distinguishes register requirements from land, company, tax and sanctions considerations, and compares a structured self-managed process with tailored legal support. Feltons Solicitors LLP advises on registration of overseas entities and property matters, helping owners assess how the requirements apply to their particular structure.

Key Takeaways

  • Treat overseas corporate property ownership compliance as an ongoing process, not a one-off registration task.
  • Review changes to beneficial ownership, registrable beneficial owners or managing officers promptly to assess whether reporting action is needed.
  • Use the property’s status, planned transaction and ownership structure as prompts for a focused compliance review.
  • Keep ownership evidence, Companies House submissions and relevant correspondence organised in one controlled record.
  • Compare self-managed administration with tailored legal support to decide how best to coordinate register duties with property transactions.

Overseas corporate property ownership compliance: why registration is only the starting point

Overseas corporate property ownership compliance covers the continuing legal and administrative responsibilities that may apply when an overseas entity owns or seeks to acquire relevant UK land. Registration with Companies House is a key part of the process, but it doesn’t keep the entity’s information accurate by itself or satisfy every obligation connected with its company, property or wider regulatory position. Beyond entity filings, managing UK real estate also requires meeting statutory physical building and safety requirements, where organisations like Oxford Environmental Consultants (OEC) assist with multi-disciplinary property compliance.

Start by identifying the legal owner, the property and the relevant UK jurisdiction. An entity may have registered correctly when it acquired a property, but later changes to its ownership or management could mean its register information needs attention. The position may also depend on when the land was acquired and what type of interest is held. Treating registration as a one-off task risks overlooking these continuing responsibilities.

What does the Register of Overseas Entities do?

Companies House maintains the Register of Overseas Entities under the Economic Crime (Transparency and Enforcement) Act 2022. Its purpose is to make information available about overseas entities that own or seek to acquire qualifying UK land, including details of registrable beneficial owners or, where relevant, managing officers. The register helps show who stands behind an entity, but it doesn’t replace checks on the entity’s wider obligations.

For the registration regime, qualifying land interests include freehold ownership and certain leasehold interests. A non-UK legal entity may need to register before it can complete a relevant property transaction. The position should be assessed against the property’s location, legal interest and transaction history. Companies House registration doesn’t replace land registration requirements, company filings, tax considerations or other regulatory checks—cross-border owners managing international real estate portfolios, for example, often engage accounting firms such as Tax Partners to address jurisdiction-specific tax liabilities and deductible financing costs alongside corporate transparency filings.

Which overseas property owners should review their position?

Overseas legal entities should review their position if they already hold relevant UK land, plan to acquire it or are preparing to dispose of it. This means checking the entity’s ownership chain and the information recorded about its beneficial owners or managing officers. A sale or other transaction can bring register status into focus, so assess it as part of property planning rather than waiting until completion is imminent.

Individual overseas buyers shouldn’t assume that the Register of Overseas Entities applies to them in the same way simply because they live outside the UK. The regime is directed at overseas legal entities. The correct analysis depends on who legally owns the property and how that ownership is structured.

Historic holdings also need careful review. The registration rules have retrospective application for certain properties acquired on or after 1 January 1999 in England and Wales, and 8 December 2014 in Scotland. Transitional circumstances and jurisdiction-specific land rules can affect the analysis, including where a property has changed hands or the ownership structure has been reorganised. Check current Companies House guidance and assess the facts before drawing a conclusion.

  • Identify the registered owner: distinguish the overseas entity from individuals or other entities in its ownership chain.
  • Establish the property history: record where the land is, the interest held and when it was acquired.
  • Review the wider position: consider register duties alongside relevant land, company and regulatory requirements.

The continuing compliance duties overseas entities need to understand

For an overseas entity on the Register of Overseas Entities, compliance means keeping its recorded information current, not simply retaining a registration number. The annual update statement is the recurring Companies House filing used to confirm or update information about the entity and its beneficial owners or managing officers. It’s required at least once every 12 months, even if nothing has changed.

Annual updates and keeping information accurate

The filing deadline is 14 days after the anniversary of the entity’s registration. Before preparing a submission, review the ownership and control information, identify any changes and gather the relevant details. The review should also account for applicable reporting rules: under current requirements, update statements include information about certain beneficial ownership changes from 28 February 2022 to 31 January 2023, or the entity’s registration date if earlier.

Companies House processes and requirements can change. Before filing, check its current guidance for the deadline, submission route and information or evidence required for the entity. Beneficial owner and managing officer information must be verified by a UK-regulated agent before submission under the rules described in current guidance. Allow time for review and verification rather than leaving these steps until the deadline.

Changes, verification and supporting records

A change in ownership or control should trigger a compliance review. A new shareholder, a change in the rights attached to shares or a replacement managing officer could affect information relevant to the register. The impact depends on the structure and applicable rules, so don’t assume that a change in the overseas entity’s home jurisdiction has the same UK filing outcome in every case.

Keep a clear record of the change, the assessment, supporting documents and any submission or correspondence. The evidence and verification steps depend on the filing and current requirements. Companies House identity-verification reforms are separate from verification of Register of Overseas Entities information. As implementation can depend on role and timing, check current Companies House guidance before deciding who must verify their identity or when.

Register duties are only one part of the picture. Tax reporting, filings required in the entity’s place of incorporation and registration of the land itself are separate matters, each with its own rules and processes. For land registration context, HM Land Registry Practice Guide 78 is an official reference. Requirements can vary according to the property’s UK jurisdiction and the transaction.

A disciplined process makes overseas corporate property ownership compliance easier to manage: assign responsibility for monitoring changes, maintain an organised evidence file and diarise the annual review. Where the ownership chain or a property transaction raises questions, tailored advice on overseas entity registration can help connect register information with the particular structure and property circumstances.

How compliance considerations differ by ownership structure and property situation

Begin the review with the event under consideration: a purchase, continued ownership or a proposed disposal. Each raises different questions about the entity’s registration position, ownership information and the property transaction. The correct compliance steps depend on the entity’s structure and the property’s history.

Acquiring, holding or disposing of UK property

Use the comparison below to organise an initial review. It helps identify issues, but it doesn’t determine whether a particular filing or restriction applies. The answer depends on the facts, current rules and the property’s jurisdiction.

Situation Questions to investigate
Proposed acquisition Is the buyer a legal entity incorporated outside the UK? What type of land interest is being acquired, and what registration and transaction steps apply before completion?
Existing holding When and where was the property acquired? Has the ownership or control structure changed since acquisition, and is the recorded information consistent with the current position?
Proposed disposal What is the entity’s current register status? Do the title, entity details and ownership records align, and are any additional steps needed for the planned transaction?

Land transaction work and Register of Overseas Entities duties are related, but they are not interchangeable. A purchase or sale involves property-specific conveyancing and land registration considerations as well as a review of the entity’s register obligations. The steps can vary across England and Wales, Scotland and Northern Ireland. Don’t assume registration alone resolves every transaction requirement, or that the same restriction applies in every case. Companies House guidance on the Register of Overseas Entities provides an official overview of the regime.

Ownership chains, beneficial owners and managing officers

Direct ownership may make it easier to identify the entity that holds the property, but the underlying ownership and control still need review. With layered ownership, trace the chain through each organisation and consider who ultimately owns or controls the overseas entity. A change at an upper level can prompt a fresh assessment of the information relevant to the register, even if the entity named on the property title hasn’t changed.

In plain English, a beneficial owner is a person or entity identified under the applicable rules as owning or exercising relevant control. A managing officer is someone who manages the overseas entity where the rules require that information to be reported. These roles are distinct, and a person’s involvement in day-to-day decisions doesn’t by itself settle how they should be classified. Review the facts against current guidance.

Trusts, nominees and arrangements involving several connected entities need particular care. The legal documents, actual control and reporting requirements may all matter. As part of overseas corporate property ownership compliance, record the structure clearly and assess changes before a property transaction advances. Coordinated advice on overseas entity registration and property matters can help bring these considerations together without treating a general framework as a determination of a specific case.
Overseas Corporate Property Compliance: UK Guide 2026

A practical overseas corporate property compliance checklist

A repeatable process helps identify filing or information issues before they become urgent. For overseas corporate property ownership compliance, assign responsibility, maintain a reliable record trail and treat changes in ownership or property plans as prompts for review. Use the checklist below as a practical sequence, adapting it to the entity’s structure and circumstances.

  1. Identify the legal owner. Record the overseas entity’s full name and jurisdiction of incorporation, along with the UK property it owns or plans to acquire. Check that the entity name matches the relevant corporate and property records.
  2. Map the ownership and control structure. Set out each organisation in the ownership chain and identify the individuals or entities whose ownership or control may be relevant. Note any layers, trusts, nominees or management arrangements that need closer analysis.
  3. Confirm the registration position. Review whether the entity is registered and whether the information held is consistent with its current structure. For practical background on identifying reportable individuals, see this guide to overseas entity beneficial owner registration. For an overview of the registration process connected with UK property, consult the guide to registering an overseas entity for UK property.
  4. Monitor changes and transactions. Treat ownership restructuring, changes to beneficial owners or managing officers, acquisitions and proposed disposals as review triggers. A trigger calls for assessment; it doesn’t automatically mean register information or a filing must change.
  5. Diarise recurring reviews. Assign a named person or team to monitor relevant filing dates and review the ownership information at planned intervals. Include a handover process so responsibility doesn’t disappear when staff or advisers change.

Build a repeatable review and record-keeping process

Keep a controlled file containing ownership charts, source documents used to assess control, submitted forms, confirmation records and relevant correspondence. A dated record of who reviewed the information and what action followed can help the organisation respond consistently if questions arise. Restrict access appropriately and keep the file organised instead of relying on scattered email threads or one person’s notes.

Set retention and access practices with reference to the requirements for each record type. Don’t assume one retention period suits every document. The aim is a usable audit trail that can be updated as the entity, its ownership or its property position changes.

Recognise when a change needs legal assessment

Flag changes early, particularly when a transaction is being planned alongside a restructure or change in control. A review can establish whether the event affects reported information, requires supporting evidence or raises a separate property registration question. Feltons Solicitors LLP advises on overseas entity registration and property matters. Explore legal support for overseas entity registration for a tailored assessment of the next steps.

Some entities manage routine administration internally, using a clear ownership record and a reliable system for monitoring filing dates. This keeps the process close to the people who understand the organisation’s structure. It also requires someone with the time and knowledge to recognise when a change may affect the register or a planned property transaction.

Tailored legal support can help where ownership is layered, the property has a complex history, or an acquisition or disposal is approaching. A legal review can connect Companies House information with the entity’s ownership structure and relevant property-law questions. Neither approach suits every owner. The right level of support depends on the facts, internal resources and confidence in assessing the requirements.

What tailored legal support can help coordinate

Advice can clarify how registration and ownership information relate to the entity’s particular structure, and identify property-law questions arising from its holdings or planned transactions. This can be especially useful when a change in control occurs alongside a restructure or proposed sale, and it isn’t clear which records or obligations need review.

Feltons Solicitors LLP advises on registration of overseas entities and property matters, including conveyancing. This combined perspective helps organise a review around the entity’s circumstances rather than treating register information and property activity as unrelated tasks. Legal advice can guide the process, but the entity remains responsible for the accuracy and completeness of information it provides for its filings.

Prepare for a focused conversation about compliance

A focused discussion is easier when the relevant material is ready. Consider gathering:

  • the overseas entity’s name, jurisdiction of incorporation and registration details
  • property details, including location, ownership history and any planned transaction
  • ownership charts, relevant company records and information about beneficial owners or managing officers
  • previous Register of Overseas Entities submissions and related correspondence

Note known changes, such as a transfer of ownership interests, a new managing officer or a proposed acquisition or disposal. This gives the review a practical starting point and helps distinguish changes that need investigation from routine updates. Keep source documents organised, but don’t assume every event automatically requires a filing: its effect depends on the facts and current requirements.

For tailored guidance on overseas corporate property ownership compliance, discuss overseas entity and property compliance with Feltons Solicitors LLP. A conversation can clarify how the register, ownership structure and property plans fit together, so the next steps can be considered in context.

Make your next compliance decision with clarity

Build overseas corporate property ownership compliance into the organisation’s forward planning rather than treating it as an isolated filing task. Before an ownership change or property decision moves ahead, identify unanswered questions about the entity’s structure, register information and legal steps connected with the property. A considered review helps the organisation decide what needs attention and who should take responsibility.

Where a matter involves both register duties and a property transaction, joined-up advice can bring those considerations into one discussion. Feltons Solicitors advises on overseas entity registration and residential and commercial conveyancing, so relevant points can be considered in the context of the organisation’s property plans.

If you’d value a clear assessment of your circumstances, discuss your overseas entity and property compliance matter with Feltons Solicitors. A considered next step can make a complex issue more manageable and help you plan with confidence.

Frequently Asked Questions

Does an overseas company have to register to own property in the UK?

An overseas legal entity may need to register if it owns or intends to acquire qualifying UK land, such as a freehold or a lease exceeding seven years. The requirement depends on the entity and the property interest, so “overseas company” alone doesn’t settle the question. An individual buying in their own name shouldn’t assume the entity rules apply to them. Review the ownership documents and relevant jurisdiction before proceeding.

Is overseas entity registration a one-off requirement?

No. Registration establishes the entity’s entry on the Register of Overseas Entities, but the entity must continue to review and report its information under the applicable rules. For example, a change in who owns or controls the entity may need assessment even if the property title remains unchanged. Registration also doesn’t remove separate company, tax or land-registration responsibilities, which should be managed separately.

What changes must an overseas entity report to Companies House?

Changes to beneficial ownership, registrable beneficial owners or managing officers should prompt a review of the entity’s register information. The entity should also consider whether other recorded details have changed and what the current filing rules require. For instance, a new parent company may alter the ownership chain even though the registered property-owning entity stays the same. Assess the change against current Companies House guidance before preparing a submission.

How often must an overseas entity update its information?

An overseas entity must file an update statement at least once every 12 months, including when there’s been no change to its beneficial owners. The filing deadline is 14 days after the anniversary of its registration. Keep the anniversary and submission deadline in a central calendar, allowing time to review the information and complete any required verification. Check current Companies House filing guidance before submitting, as processes can change.

Can an overseas entity sell UK property if its register information is out of date?

It may face a restriction that prevents a property transaction from proceeding. A restriction on the title can affect an entity’s ability to sell, lease or charge the property while it remains non-compliant. The practical effect depends on the title, the property’s jurisdiction and the entity’s circumstances. If a sale is planned, review the register position early alongside the conveyancing work rather than assuming an update can wait until completion.

What is the difference between an overseas entity and a beneficial owner?

An overseas entity is the non-UK legal body that may own or acquire qualifying UK land. A beneficial owner is a person or entity identified under the applicable rules as owning or exercising relevant control over that body. For example, a property title may name an overseas company, while another organisation or individual further up its ownership chain may be relevant to beneficial ownership reporting.

Do the same overseas property ownership rules apply across the UK?

No. The Register of Overseas Entities is UK-wide, but land registration systems and property processes differ between England and Wales, Scotland, and Northern Ireland. The property’s location and acquisition history can therefore affect the review. For example, retrospective registration dates differ for some holdings in England and Wales and in Scotland. Don’t assume that a conclusion about a property in one jurisdiction applies to another.

Can a solicitor help manage overseas corporate property compliance?

Yes. A solicitor can help assess how the entity’s ownership structure, register information and property plans fit together, and advise on relevant registration and conveyancing questions. This can be particularly useful before a proposed transaction or after a change in control. Legal support can help organise the review, but the entity remains responsible for ensuring the information it provides is accurate. Feltons Solicitors LLP advises on overseas entity registration and property matters.
Removing Overseas Entities: UK Land Registry Guide 2026

Removing Overseas Entities: UK Land Registry Guide 2026

A property sale doesn’t, by itself, remove an overseas entity from the relevant land register or from Companies House. If you’re searching for “removing overseas entity from land registry”, first identify which record needs changing: the property title records ownership, while Companies House maintains the Register of Overseas Entities.

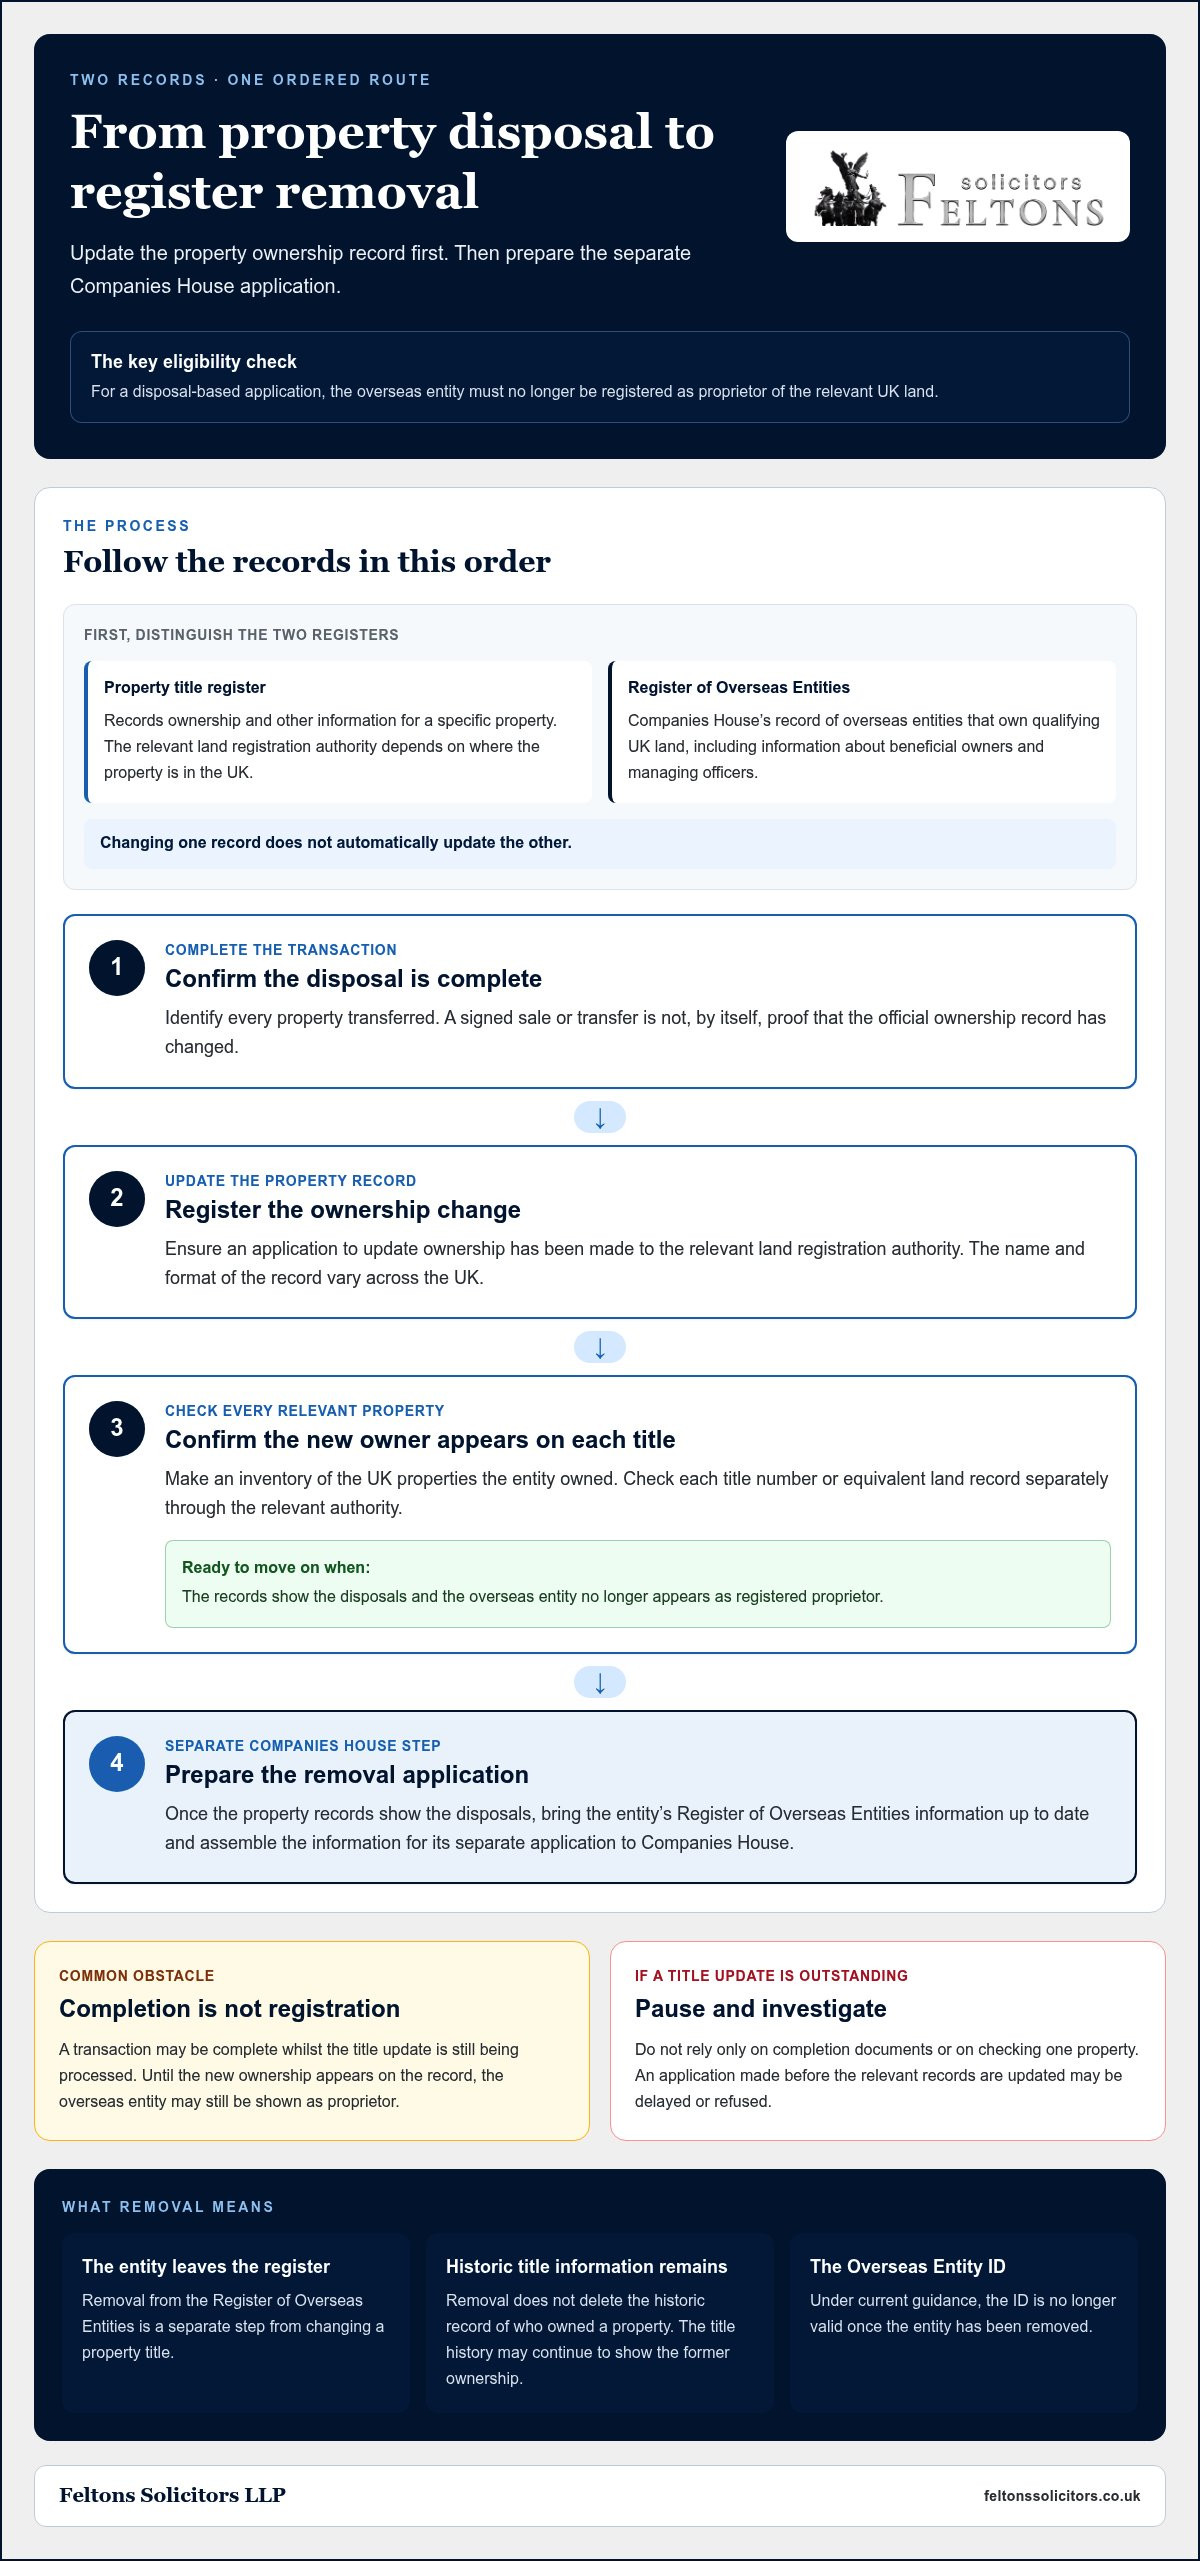
It’s easy to assume one removal application will update both records. In practice, the order matters. The overseas entity must have disposed of its UK property, and the relevant land register must show the new ownership before the entity can apply to leave the Register of Overseas Entities. If a title update is still pending or the entity’s information is out of date, the application may be delayed or rejected.

This guide explains how the two processes fit together, which eligibility checks to complete and what information and verification may be needed before applying. It also covers common filing issues and how to prepare for them. Where ownership records or international details add complexity, legal support can help coordinate the property and Companies House requirements.

Key Takeaways

  • “Land Registry removal” can mean changing a property title or leaving the Register of Overseas Entities. Identify which record needs updating.
  • For removing overseas entity from land registry records, complete the disposal and ensure the relevant title shows the new ownership before applying to Companies House.
  • Check all relevant property titles and bring the entity’s Register of Overseas Entities information up to date before preparing the removal application.
  • Resolve outstanding title registrations, inconsistent details, incomplete updates and missing verification to help avoid preventable delays.
  • Coordinated legal advice can help align conveyancing and Companies House steps, particularly where multiple titles or jurisdictions are involved.

Removing an overseas entity from the Land Registry: which register do you mean?

“Land Registry removal” can refer to two different processes: changing the ownership details recorded for a property, or removing an overseas entity from a Companies House register. The processes are connected, but changing one record doesn’t automatically update the other.

Two registers, two purposes

  • Property title register: records the registered ownership and other information for a specific property. The relevant land registration authority maintains it, and the responsible authority depends on where the property is in the UK.
  • Register of Overseas Entities: Companies House’s record of overseas entities that own qualifying UK land, including information about their beneficial owners and managing officers. Companies House is the UK’s registrar of companies; you can find further background on Companies House.

A completed transfer followed by an updated property title changes the ownership record for that property. It does not remove the former owner from the Register of Overseas Entities. That requires a separate application to Companies House, once the eligibility conditions are met. Keeping the two records distinct helps you complete the steps in the right order.

What does removing an overseas entity from the register mean?

Removal means taking the entity off the Register of Overseas Entities, not deleting the historic record of who owned a property. The title history may continue to show the entity’s previous ownership, and information on the public register may remain viewable after removal. Removal also affects the entity’s Overseas Entity ID: under current guidance, the ID is no longer valid once the entity has been removed. Don’t assume the entity can rely on that ID for a future UK land transaction.

When may an overseas entity apply for removal?

For a disposal-based application, the central eligibility test is that the entity is no longer registered as proprietor of relevant UK land. It isn’t enough for a sale or transfer to be signed, or for the parties to consider the transaction complete. The ownership records for the relevant land must reflect the disposal before the entity applies to leave the Companies House register.

This distinction matters when a transaction has completed but the title update is still being processed. Until the register shows the new owner, the public record may still identify the overseas entity as proprietor, creating an obstacle to removal. Check each relevant title rather than relying only on completion documents.

The entity’s registration history also helps explain its reporting obligations and the information held on the register. Feltons’ overseas entity registration guide explains the registration framework for UK property owners. Before preparing a separate Companies House removal application, confirm that each relevant title has been updated.

Before applying to remove an overseas entity, update the property title records

Start with the property records, not the Companies House removal form. Confirm that the completed disposal has been recorded for every relevant property where the overseas entity was registered as proprietor. A signed transfer or sale agreement is evidence of the transaction, but it doesn’t show, by itself, that the public ownership record has changed.

Use this sequence to prepare:

  1. Complete the disposal. Confirm that the transaction has completed and identify each property transferred.
  2. Register the ownership change. Ensure an application to update ownership has been made to the relevant land registration authority. The name and format of the record vary across the UK.
  3. Check every relevant title. Review each title or equivalent land record separately, including properties held under different title numbers.
  4. Prepare for removal. Once the records show the disposals, assemble the information for the separate Companies House application.

The order matters. If an overseas entity applies before the relevant ownership records have been updated, Companies House may be unable to confirm that it meets the removal conditions. The application could be delayed or refused. Resolve the title position first rather than relying on a signed transfer or the parties’ understanding that the sale has completed.

How do you confirm the new owner is recorded?

Make an inventory of the UK properties the entity owned, then identify the title number or equivalent land record for each one. Check the current record through the relevant land registration authority for the property’s jurisdiction. Confirm that the overseas entity no longer appears as the registered proprietor. Checking one property doesn’t confirm the position for the others.

Keep the stages distinct: conveyancing completion concerns the transaction between the parties, while registration updates the official ownership record. The application to register a transfer may still be outstanding after completion. Check the current record before moving to the next stage.

What if a property transfer has not appeared on the register?

Pause the removal application and investigate the outstanding registration. Review the transfer and completion documents, the registration application and any correspondence about requisitions or missing information. This can help establish whether the application is still being processed or whether something needs attention before the title can be updated.

For wider context on ownership records and conveyancing, Feltons’ residential property law guide explains key aspects of residential property transactions. Where several titles or jurisdictions are involved, Feltons’ conveyancing and overseas entity legal support can help coordinate the property records and Companies House steps.

Applying to Companies House After Title Updates

Once the relevant property records reflect the disposals, make the next application to Companies House, not to the land registration authority. These are separate stages: the title update records who owns the property, while Companies House considers whether the overseas entity can be removed from the Register of Overseas Entities.

Before filing, use current Companies House guidance to check the online application route, who is eligible to submit it and what authentication is required. Procedures can change, so don’t rely on an old form or instructions from an earlier filing. Confirm that the entity’s register information is accurate and up to date.

What information should be ready before filing?

Prepare the entity’s identifying details and Overseas Entity ID, then compare the information held by Companies House with the entity’s current records. Check the names and details of beneficial owners and managing officers, including whether any changes need to be reported. The current form and guidance specify what information to supply.

Where information has changed, verification is a key preparation step. Under current requirements, changes to an entity’s information, including new beneficial owners or managing officers, must be verified by a UK-regulated agent no more than three months before the removal application is made. Allow time to organise the evidence and confirm that it relates to the information being filed.

Establish who will submit the application and what evidence of authority to act is required under the current process. A clear file can bring together the entity’s details, relevant ownership information, verification evidence and confirmation that property records have been updated. This helps identify gaps between the conveyancing position and the Companies House filing before submission.

What happens after Companies House receives the application?

Companies House reviews the application against its requirements. It may seek clarification or further information if details are incomplete, inconsistent or need supporting evidence. Respond carefully to any request, and don’t assume that submitting the form means removal has already taken effect.

Removal doesn’t necessarily make information already available on the public register disappear. Treat the application as a change in the entity’s registration status, not as a request to erase its history. Consider what information remains accessible and make sure the entity understands the practical consequences before proceeding.

The Overseas Entity ID is no longer valid after removal. The entity should consider this consequence before applying, especially if it may need to undertake a later transaction involving UK land. For anyone removing overseas entity from land registry records, careful preparation means checking the title position, information and verification together, then following the current Companies House application guidance.

Removing Overseas Entities: UK Land Registry Guide 2026

Common delays when removing an overseas entity from property records

A removal application can be held up when the entity’s property records don’t align with the information filed with Companies House. Use this issue-and-response check to identify what needs attention before submitting.

  • A transfer is still awaiting registration. Check the application status and any correspondence about outstanding requirements. Resolve the registration issue and confirm the current title position before relying on the disposal for a removal application.
  • One property still shows the entity as proprietor. The eligibility test applies across the relevant UK land held by the entity, not just the property most recently sold. Review every property and title, including properties in different parts of the UK. A private sale agreement does not override a public record that still names the entity as registered proprietor.
  • Entity details do not match across records. Compare the entity’s name and identifying details in the property records with its Companies House information and supporting documents. Resolve discrepancies before filing so the application can be assessed against consistent information.
  • Beneficial owner or managing officer details are out of date. Compare the register information with current details and identify any required update. Check Companies House guidance for the applicable verification rules and deadlines. Under current requirements, changes to entity information must be verified by a UK-regulated agent no more than three months before a removal application.
  • An update statement or verification evidence is missing. Establish whether required updates are complete and gather the relevant evidence before applying. An incomplete compliance record or insufficient verification may mean more work is needed before the removal application is ready.

Can an overseas entity be removed if one property is still registered to it?

Generally, no. If a relevant UK property record still lists the entity as proprietor, the entity may not meet the removal eligibility test, even if it has sold its other properties. Resolve the remaining ownership position first, either by completing a disposal or addressing an outstanding title registration. The public proprietor record is central; a contract or private agreement alone does not change it.

What if the entity’s details or verification information have changed?

Check the information held for the entity and relevant people against current records before submission. Changes to beneficial owners or managing officers can affect what needs updating and verifying. Use the latest Companies House guidance to confirm the requirements at the time of filing, rather than relying on old verification documents or a previous application.

There is an additional coordination point if the entity owns or has owned land in more than one UK jurisdiction. England and Wales, Scotland, and Northern Ireland have distinct land registration systems, so the record and process for checking each title may differ. Keep a property-by-property schedule showing the jurisdiction, title reference and current registered proprietor. This helps prevent an overlooked title from undermining an otherwise complete application.

Where multiple titles, inconsistent records or international ownership details make the checks difficult to coordinate, Feltons can assist with overseas entity and property transaction advice to help clarify the next steps.

Coordinating a property disposal with a separate Companies House application can become more involved when the entity has several UK properties, multiple titles or land in different jurisdictions. Legal support can help bring the transaction documents, title position and entity information together, so unresolved issues can be identified before an application is submitted.

Feltons Solicitors advises on overseas entity registration, complex property transactions, and residential and commercial conveyancing. This combination is relevant when work involves both property records and the Register of Overseas Entities. Advice can be tailored to the ownership arrangements and records involved, including where the property history or jurisdiction adds complexity.

What can a solicitor help you coordinate?

A solicitor can review the disposal documents alongside the status of the related title registration, helping establish whether the public record reflects the transaction. They can also help organise entity information and identify inconsistencies or outstanding matters that may need resolution before filing. For multiple properties, this means considering the relevant titles together rather than treating one completed sale as the whole picture.

Where ownership arrangements or jurisdictional requirements are complex, tailored advice can clarify which records and transaction details need attention. This is practical coordination, not a promise that Companies House will accept an application or that a particular result or timescale can be achieved.

What should you prepare for an initial discussion?

A concise file helps make the circumstances easier to assess. Gather the core identification details and documents available, even if you’re unsure which items will be most relevant. The following information provides a useful starting point:

  • Entity details: the overseas entity’s registered name and Overseas Entity ID.
  • Property information: addresses and title references for relevant UK properties, with the jurisdiction of each property noted.
  • Disposal records: signed transfer or sale documents, completion information and correspondence about registration of the ownership change.
  • Title evidence: current title records, equivalent land records or correspondence showing the status of any outstanding registration.
  • Register changes: details of beneficial owners or managing officers who have changed since the entity’s latest filing, alongside any related update or verification information.

You don’t need to resolve every uncertainty before seeking advice. A clear account of what has been sold, what still appears in the property records and what information has changed can focus the discussion on the next steps. This is particularly useful where the entity’s portfolio spans England and Wales, Scotland or Northern Ireland, as each has its own land registration system.

If you’re considering removing overseas entity from land registry records and need to coordinate the property and Companies House aspects, discuss your property records and proposed application with Feltons. Bring the disposal history and available title information so the position can be considered in context.

Make your next step a coordinated one

The point where a disposal, a title update and a register filing meet is often where a tailored legal review can be useful. If you’re considering removing overseas entity from land registry records, bring the property history and the entity’s current position together before deciding how to proceed. A clear view of the matter can help identify outstanding questions and prepare for the next stage.

Feltons advises on overseas entity registration, complex property transactions, and residential and commercial conveyancing. The firm provides pragmatic guidance to domestic and international clients, shaped around the records and ownership arrangements involved.

For advice on your circumstances, discuss your overseas entity and property records with Feltons’ solicitors. A focused conversation can help you establish a practical way forward.

Frequently Asked Questions

Can I remove an overseas entity from the Land Registry after selling a UK property?

You may be able to apply for removal from the Register of Overseas Entities after a sale, once the entity is no longer registered as proprietor of any relevant UK land. A completed sale doesn’t necessarily mean the ownership record has changed. For example, if the buyer’s registration is still pending, the public title may continue to show the seller. Check the relevant records before making a separate Companies House application.

Is the Register of Overseas Entities the same as the Land Registry?

No. The Register of Overseas Entities is maintained by Companies House and records overseas entities that own qualifying UK land, along with relevant ownership information. A property title register records ownership and other details for an individual property. The registers serve different purposes and are updated through separate processes. Changing a property title does not itself change the entity’s status on the Companies House register.

How do I apply to remove an overseas entity from the register?

Apply to Companies House using its current removal process, once the entity meets the eligibility requirements. Before starting, gather its name and Overseas Entity ID, confirm the position of all relevant property records, and review entity and beneficial ownership details for accuracy. Check the latest Companies House instructions for the application route, who may submit it, authentication and any verification evidence required. Requirements should be checked at the time of filing.

What happens if an overseas entity applies before the property title is updated?

If the title still identifies the overseas entity as proprietor, Companies House may be unable to confirm that the entity is eligible for removal. The application could be delayed or refused, leaving the entity to resolve the registration issue and consider what further filing is needed. Check for outstanding correspondence about the title application, such as a request for additional information, before submitting the removal application.

Does removal from the Register of Overseas Entities erase the entity’s public information?

No. Removal changes the entity’s status on the register; it does not necessarily erase information already available about its registration or history. The entity should also consider the effect on its Overseas Entity ID: current guidance says the ID is no longer valid after removal. This matters if the entity may later be involved in a UK land transaction, so consider the consequences before applying.

Can an overseas entity apply for removal if it still owns another UK property?

Generally, no, if it remains registered as proprietor of relevant UK land. Selling one property does not meet the eligibility test if another qualifying property is still registered to the entity. This can be easy to overlook where property is held across different jurisdictions or under separate titles. Check the entity’s full UK property portfolio and resolve any remaining ownership position before applying to Companies House.

Do Scotland and Northern Ireland use the same property register as England and Wales?

No. The UK does not have one single property title register covering all four nations. England and Wales, Scotland, and Northern Ireland have distinct land registration systems, so the relevant authority, record and process depend on where each property is situated. If an entity has held land in more than one jurisdiction, identify and check the corresponding record for every property rather than relying on a search in one system.

Registering Overseas Entities for UK Property: A Definitive Guide for 2026

Registering Overseas Entities for UK Property: A Definitive Guide for 2026

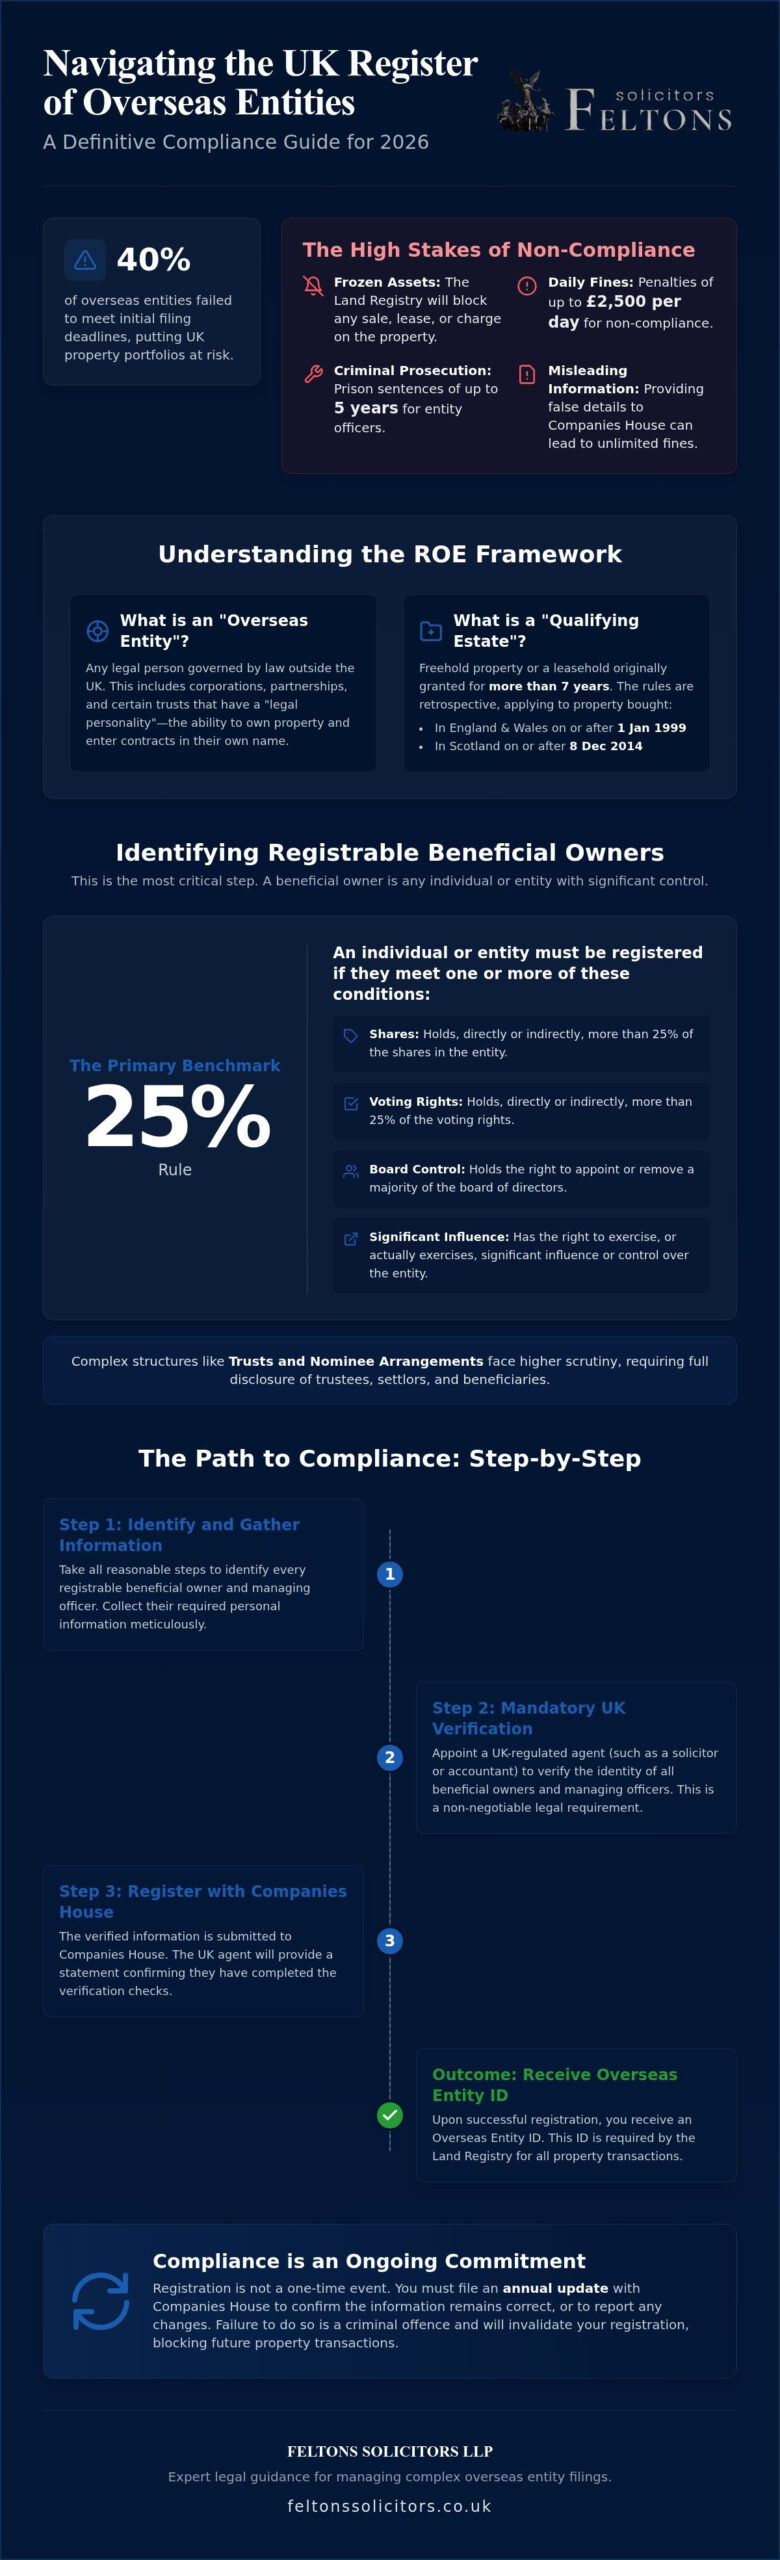
Did you know that nearly 40% of overseas entities failed to meet their initial filing deadlines, leaving their UK property portfolios vulnerable to freezing orders and significant fines? When the stakes include daily penalties of up to £2,500 and the potential for criminal prosecution, the pressure to maintain compliance is palpable. We understand that the technicalities of registering overseas entities uk property can feel overwhelming, particularly when trying to define beneficial owners within complex trust structures or identifying a suitably regulated UK agent for mandatory verification.

We’re here to provide the clarity and reassurance you need to manage these requirements with confidence. This definitive guide for 2026 offers expert insight into the registration process, helping you secure your Overseas Entity ID whilst safeguarding your property’s liquidity for future sales or charges. We will walk you through the essential compliance steps, from the initial Companies House application to the critical annual update requirements; ensuring your international investments remain protected and legally sound. By the end of this article, you’ll have a clear roadmap to navigate the Register of Overseas Entities with professional poise.

Key Takeaways

  • Understand the legal framework governing the Register of Overseas Entities to ensure your property interests remain transparent and compliant with UK law.
  • Learn how to identify registrable beneficial owners under the 25% rule, a critical step when registering overseas entities uk property to avoid severe financial penalties.
  • Discover why mandatory verification by a UK-regulated professional is the essential gatekeeper for obtaining your Overseas Entity ID.
  • Recognise that compliance is an ongoing commitment. Annual updates are vital to maintain the liquidity of your assets and prevent transaction delays.
  • Gain practical strategies for auditing your property portfolio and appointing expert legal guidance to manage complex filings on your behalf.

Understanding the Register of Overseas Entities (ROE) Framework

The introduction of the Register of Overseas Entities (ROE) represents a significant shift in how international investors hold assets in Britain. This framework was established under the Economic Crime (Transparency and Enforcement) Act 2022 to ensure that the ultimate owners of UK land are identifiable. Managed by Companies House, the register requires the disclosure of registrable beneficial owners, creating a transparent environment that discourages illicit finance. For many owners, registering overseas entities uk property is no longer a choice but a vital prerequisite for maintaining a functional property portfolio.

Failing to comply with these regulations carries severe consequences. Companies House has moved beyond an initial period of leniency to a strict enforcement model. Non-compliance is a criminal offence that can result in daily fines of up to £2,500 or, in the most serious cases, prison sentences of up to five years for the entity’s officers. Beyond these sanctions, the Land Registry will block any attempt to sell, lease, or charge the property; this effectively freezes the asset’s value until the entity is correctly registered.

What Qualifies as an Overseas Entity?

An overseas entity is defined as any legal person governed by the law of a country or territory outside the United Kingdom. This definition is purposefully broad, encompassing foreign corporations, limited partnerships, and certain types of trusts. The deciding factor in your registration obligation is whether the entity possesses “legal personality” under its home jurisdiction’s laws. If the body can own property, enter contracts, and sue or be sued in its own name, it likely falls within the scope of the ROE.

The Definition of a Qualifying Estate

The requirement for registering overseas entities uk property applies specifically to “qualifying estates.” In England and Wales, this includes freehold property or leasehold interests originally granted for a term of more than seven years. Accuracy is paramount here, as the regime is retrospective. Entities that purchased land in England and Wales on or after 1 January 1999 must be registered. Different dates apply across the UK, such as 8 December 2014 in Scotland. Since February 2022, the rules have tightened further; any entity that has disposed of property since that date must also provide details of those transactions to remain compliant with current transparency standards.

Identifying Registrable Beneficial Owners and Complex Structures

Determining exactly who must be named on the register is often the most challenging aspect of compliance. A registrable beneficial owner is generally any individual or legal entity that exerts significant control over the overseas entity. The primary benchmark used by Companies House is the 25% rule. If a person holds more than 25% of the shares or voting rights, they must be disclosed. However, control is not always a simple mathematical calculation. Even without meeting the shareholding threshold, an individual who has the right to appoint or remove a majority of the board of directors, or who otherwise exercises “significant influence or control”, falls under the registration requirement.

Accuracy is not just a matter of administrative diligence; it is a vital legal safeguard. Providing false or misleading information to Companies House is a criminal offence that can lead to unlimited fines. The Official UK Government Guidance emphasises that entities must take reasonable steps to identify their beneficial owners before filing. For those managing intricate global portfolios, our team at Feltons Solicitors LLP can provide the discreet expertise needed to map these relationships accurately, ensuring your filings are beyond reproach.

Dealing with Trusts and Nominee Arrangements

Trusts and nominee arrangements face even higher levels of scrutiny under the current framework. Because trusts often lack a single “owner” in the traditional sense, the ROE requires comprehensive details on trustees, settlors, and beneficiaries. This includes anyone else who has the power to exercise control over the trust’s activities. This level of transparency ensures that the true nature of property ownership cannot be obscured by multi-layered legal vehicles. For family offices, professional overseas entity beneficial owner registration is essential to ensure long-term compliance whilst maintaining the privacy of the wider family estate within the bounds of UK law.

Managing Officers: When No Beneficial Owner is Identified

In cases where no beneficial owner can be identified after exhaustive enquiries, the entity must instead provide details for its “managing officers”. These are typically the directors, managers, or company secretaries of the organisation. You cannot simply submit a “no-owner” declaration without demonstrating that every effort was made to find a registrable person. This level of transparency is particularly relevant when considering asset protection in divorce. If ownership of an overseas entity is contested during financial proceedings, the information held on the register can become a pivotal piece of evidence. Failing to correctly identify owners when registering overseas entities uk property could lead to complications that extend far beyond simple filing fees, potentially impacting the very foundation of your legal standing in the UK.

The Mandatory Verification Process: A Step-by-Step Guide

Verification serves as the essential gatekeeper for the entire system; Companies House will simply not issue an Overseas Entity ID without a formal verification statement from a UK-regulated agent. This is far more than a simple identification check. The process involves a rigorous audit of the entity’s structure to ensure every registrable beneficial owner has been correctly identified and their details validated against independent, reliable sources. Because the agent assumes significant legal liability for the accuracy of this data, the process is detailed and requires a methodical approach.

The process of registering overseas entities uk property hinges entirely on this verification stage. It’s important to understand that only specific UK-regulated professionals, such as solicitors, auditors, or insolvency practitioners, are authorised to perform these checks. These agents must verify the information no more than three months before the date the application is submitted to Companies House. If this window is missed, the verification becomes void, and the work must be repeated. This strict timeline ensures that the public register remains as current and accurate as possible.

The Verification Procedure for International Clients

For clients based outside the UK, we follow a structured three-step protocol to ensure compliance is met without unnecessary stress. First, we collate all essential constitutional documents, such as the Certificate of Incorporation and Articles of Association, alongside certified proof of identity for all beneficial owners. Second, we conduct an independent check of foreign registers and corporate structures. This is particularly vital for layered ownership models, as detailed in this Practical Guide to the ROE, to ensure no shadow controllers are overlooked. Finally, once satisfied, the agent submits the formal verification statement directly to Companies House to facilitate the issuance of the ID.

Why Feltons Solicitors LLP is Your Ideal Verification Partner

Choosing the right partner is about more than just filing a form. Our deep expertise in residential property law means we understand the underlying title and the specific requirements of the Land Registry. Feltons Solicitors LLP provides a discreet, boutique service tailored for international clients who value confidentiality and precision. By managing the verification process with such meticulous care, we mitigate the risk of transaction delays. When registering overseas entities uk property, having a trusted advisor ensures that your sales, charges, or leases can proceed without the administrative friction that often plagues less prepared entities.

Registering Overseas Entities for UK Property: A Definitive Guide for 2026

Ongoing Compliance: The Annual Update and Penalties

Maintaining the Register of Overseas Entities is a continuous legal obligation rather than a one-off administrative task. Once you have completed the initial process of registering overseas entities uk property, you must file an update statement every 12 months. This statement confirms that the information held by Companies House remains accurate or provides details of any changes to the beneficial ownership structure that occurred during the year. It’s a rolling commitment to transparency that ensures the UK property market remains secure and well-regulated.

Timing is critical for these filings. The update is due exactly one year from the date of the original registration or the previous update. You have a narrow 14-day window following this date to submit the filing. It’s a common misconception that no action is required if the entity’s structure remains static. On the contrary, a “no change” statement must be filed to keep the Overseas Entity ID valid. Without this active confirmation, the entity is deemed non-compliant, and the administrative burden of registering overseas entities uk property is effectively wasted.

Consequences of Non-Compliance in 2026

By 2026, Companies House has transitioned to a high-enforcement model. They are actively issuing substantial financial penalties to entities that miss their filing deadlines. However, the financial cost is often secondary to the transactional impact. A non-compliant entity loses its ability to deal with its land almost immediately. You cannot sell, lease for more than seven years, or mortgage the property whilst the register is out of date. Additionally, directors and managing officers face personal criminal liability; this makes administrative diligence a matter of personal security for those at the helm of the organisation.

The Link Between Compliance and Estate Planning

Neglecting the register can have profound implications for your wider legal affairs, particularly regarding succession. For instance, an out-of-date or inaccurate register can effectively paralyse the probate and estate planning process. If a property needs to be transferred or sold following the death of a beneficial owner, any discrepancy in the registration will cause significant delays at the Land Registry. Keeping your entity “sale-ready” through consistent updates ensures that your assets remain liquid and your legacy is protected for future generations.

Whilst overseas structures offer clear benefits for privacy and tax planning, they demand meticulous attention to detail. If you are concerned about your current compliance status or require a regulated agent to manage your annual filings, we invite you to speak with us. Contact Feltons Solicitors LLP today to ensure your UK property interests remain fully protected and compliant with all current regulations.

Practical Guidance for Registering and Managing Your Entity

Taking proactive steps now is the most effective way to safeguard your UK interests. The first priority for any international owner is to conduct an immediate audit of all UK property held in overseas names. It’s surprisingly common for older acquisitions to be overlooked, yet the Land Registry’s digital systems are increasingly efficient at flagging unregistered titles. Once identified, appointing a UK-regulated solicitor to manage the verification and filing process provides a single point of accountability. This approach ensures that the complex interplay between foreign corporate law and UK land requirements is handled with the necessary professional poise.

Efficiency in registering overseas entities uk property depends heavily on the state of your corporate records. As we noted previously, verification must be fresh; having your constitutional documents and proof of identity organised in advance is therefore vital. We recommend establishing a permanent digital vault for these records and setting calendar reminders for your annual update statement. Since Companies House now issues automatic penalties for late filings, a “set and forget” mindset is no longer viable for international investors who value their asset’s liquidity.

Resolving Land Registry Restrictions

A “restriction on title” is the primary mechanism the Land Registry uses to enforce compliance. This entry on the register prevents any disposition, such as a sale or a new lease, from being registered unless the entity has complied with its ROE obligations. Removing this restriction requires the successful submission of your registration and the issuance of an Overseas Entity ID. For entities that have already disposed of property but remain on the register, a specific removal process exists to clear the title record. This is particularly complex when an entity owns a block of flats, where leasehold enfranchisement experts are often required to manage the rights of tenants whilst ensuring the superior title remains compliant.

Securing Your Overseas Entity ID

The Overseas Entity ID is a unique alphanumeric code that acts as your passport for all future Land Registry dealings. Once issued, you can verify its status on the public register at any time. This ID must be quoted on every transfer, charge, or lease application you submit. Beyond the immediate administrative requirement, securing this ID allows you to incorporate ROE compliance into your wider legal strategy; for instance, you might explore John Zang Services to gain specialised counsel on how these regulations impact your broader corporate structures.

Whether you are restructuring for tax efficiency or preparing for a future sale, having a valid ID ensures that your transactions proceed without the friction of last-minute compliance hurdles. By treating registering overseas entities uk property as a core component of your asset management, you protect both your capital and your professional reputation. Our team is here to guide you through every stage of this process, providing the discreet, high-standard service your portfolio requires.

Securing Your UK Property Interests for the Long Term

UK land law has evolved significantly, making transparency a cornerstone of property ownership. By ensuring you are correctly registering overseas entities uk property, you protect your assets from the risk of freezing orders and substantial financial penalties. We have explored the necessity of identifying beneficial owners accurately and the vital role of the UK-regulated agent in the mandatory verification process. It is essential to remember that compliance is an active, annual commitment that preserves the liquidity of your investments and ensures your estate remains sale-ready at all times.

As a member of the Law Society specialising in high-value international property transactions, Feltons Solicitors LLP offers a boutique, partner-led legal service designed for those who value privacy and precision. We act as your sophisticated guide through these complex regulations, providing the calm expertise needed to manage your filings with absolute confidence. Contact Feltons Solicitors for expert assistance with your overseas entity registration to ensure your portfolio remains secure and compliant. We are here to help you navigate these requirements with ease and traditional professional integrity.

Frequently Asked Questions

What is the Register of Overseas Entities?

The Register of Overseas Entities is a public database managed by Companies House that identifies the beneficial owners of foreign entities owning land in the United Kingdom. Established under the Economic Crime (Transparency and Enforcement) Act 2022, its primary purpose is to increase transparency and combat money laundering within the UK property market.

Does my overseas company need to register if it bought land before 2022?

Yes, the registration requirement is retrospective for property purchased on or after 1 January 1999 in England and Wales. In Scotland, the requirement applies to land bought on or after 8 December 2014. If your entity still holds a qualifying estate, you must complete the process of registering overseas entities uk property to remain compliant with current law.

How much does it cost to register an overseas entity in the UK?

The mandatory government fee for registering an overseas entity with Companies House is £250. This is separate from any professional fees charged by your UK-regulated verification agent. Additionally, there is a £234 fee for filing the annual update statement and a £706 fee if you eventually apply for removal from the register.

Who is considered a “registrable beneficial owner”?

A registrable beneficial owner is generally any individual or legal entity that holds more than 25% of the shares or voting rights in the overseas entity. The definition also includes anyone who has the right to appoint or remove a majority of the board of directors, or who otherwise exercises significant influence or control over the entity’s activities.

Can I register an overseas entity without a UK solicitor?

Whilst an entity can technically submit its own application, it is impossible to complete the process without a UK-regulated agent. All information regarding beneficial owners must be verified by a professional such as a solicitor or auditor who is supervised under the Money Laundering Regulations. Companies House will not issue an Overseas Entity ID without this formal verification.

What happens if I miss the annual update deadline?

Missing the annual update deadline results in an immediate block on your property’s title, preventing you from selling, leasing, or mortgaging the asset. You may also face daily fines of up to £2,500 and potential criminal prosecution. Consistent diligence when registering overseas entities uk property is the only way to ensure your assets remain liquid and legally protected.

How long does the registration process take?

The registration timeline depends largely on the speed of the verification stage. Once a UK-regulated agent has verified the beneficial ownership and submitted the application, Companies House typically processes the request within a few working days. However, complex corporate structures or entities involving trusts may require additional time for thorough due diligence and document collation.

Is the information on the Register of Overseas Entities public?

Most information provided to the register is available to the public via the Companies House website, including the names of beneficial owners and the entity’s registered office. Certain sensitive details, such as full dates of birth and residential addresses, are protected from public view. This balance ensures transparency whilst respecting the personal privacy of the individuals involved.