Will Solicitors: A Comprehensive Guide to Protecting Your Estate in 2026

Will Solicitors: A Comprehensive Guide to Protecting Your Estate in 2026

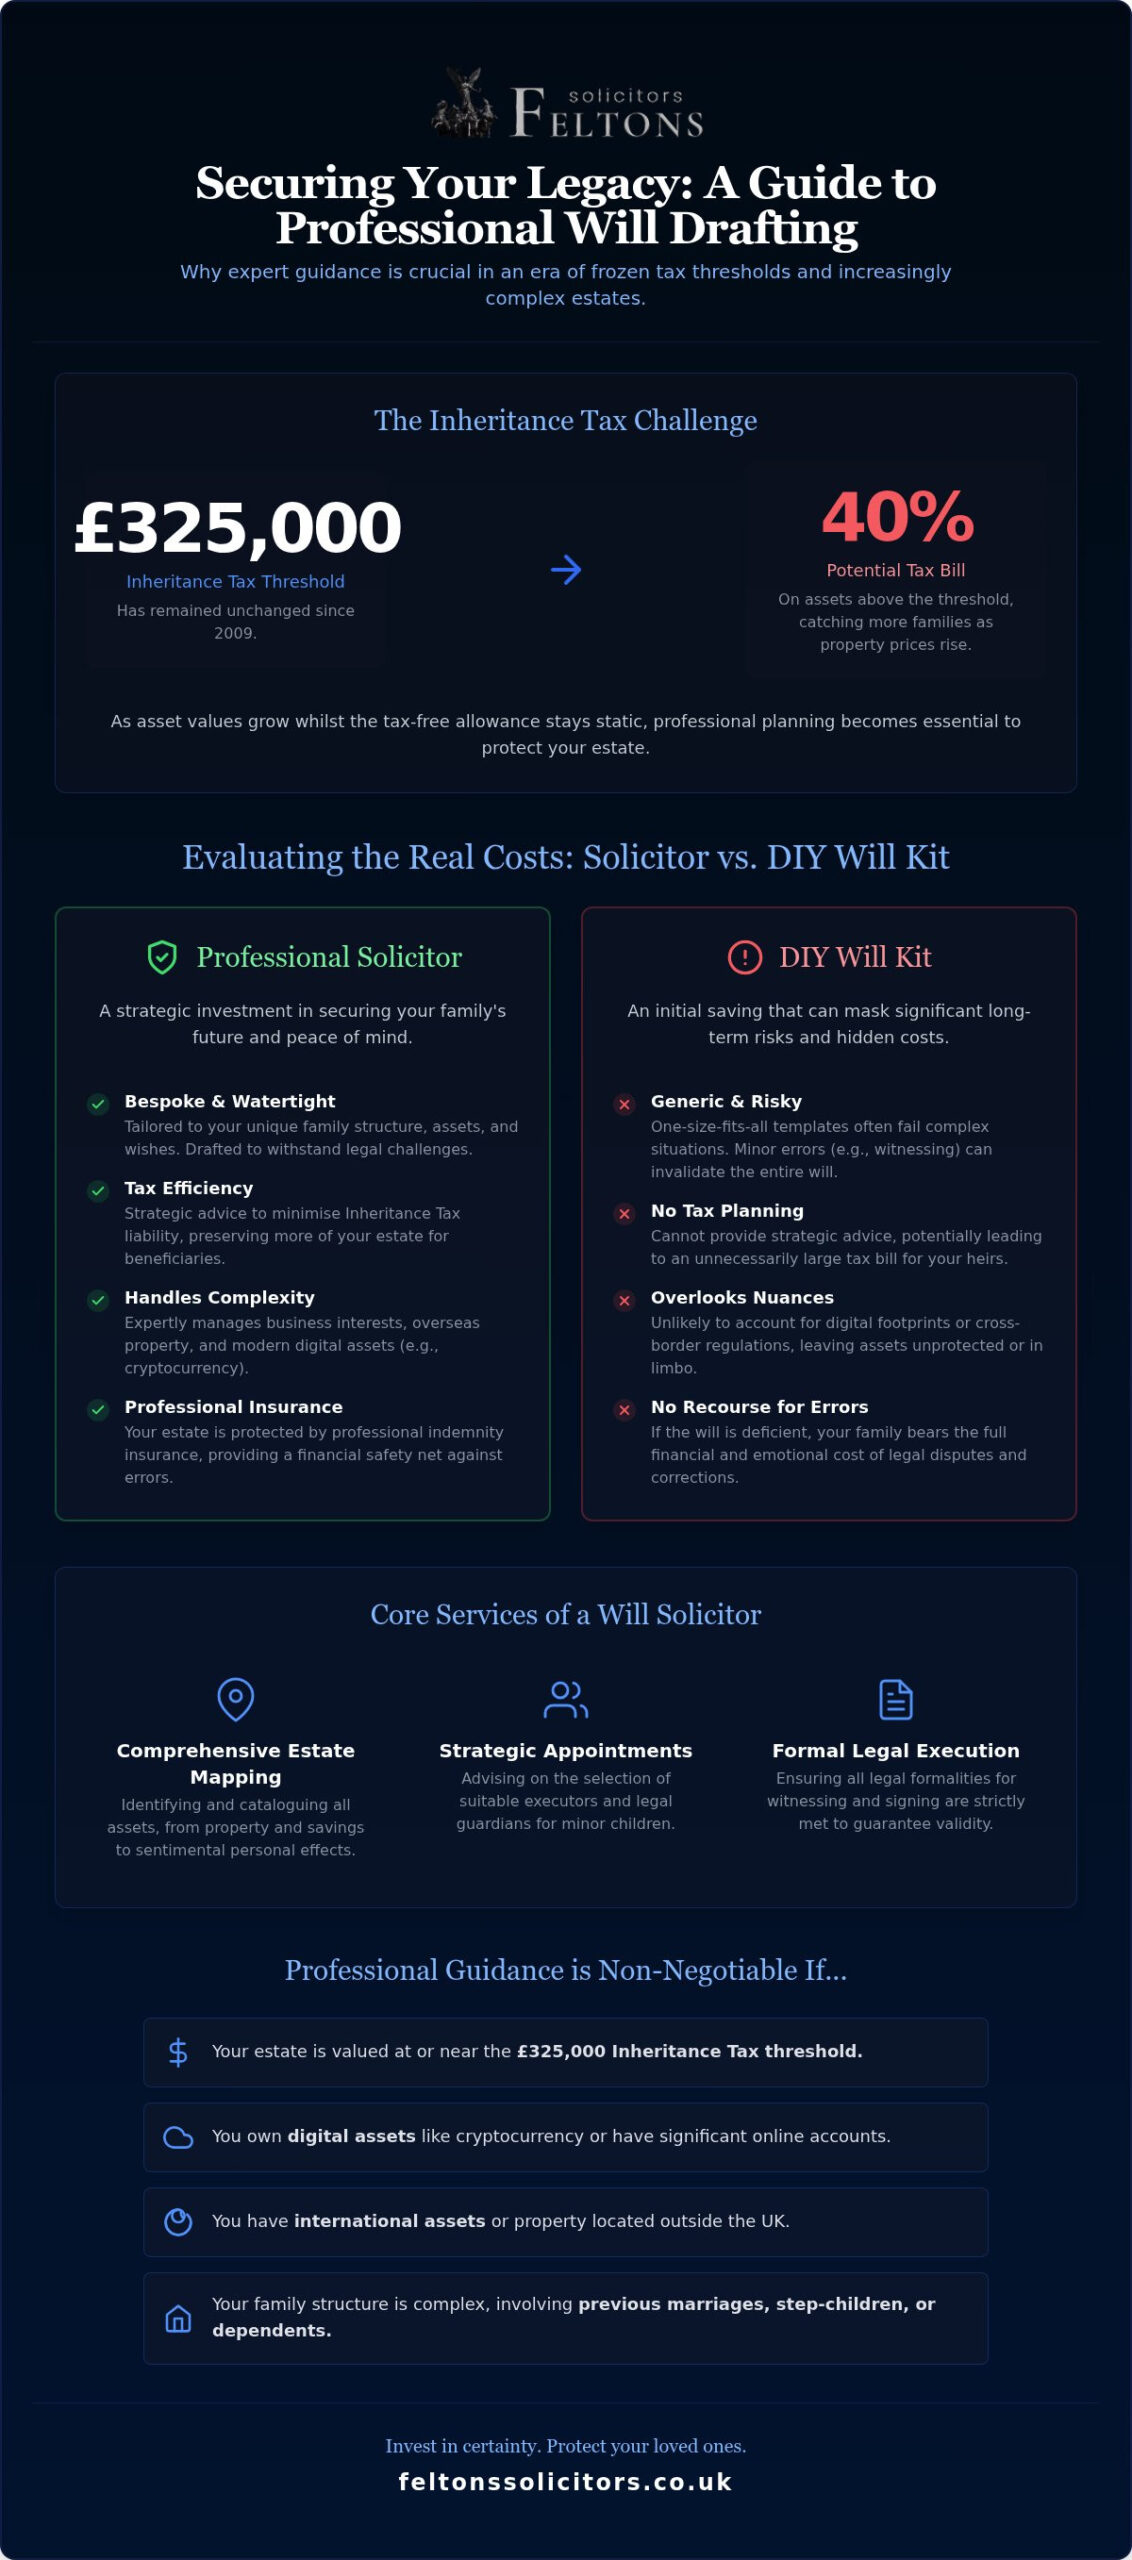
The £325,000 Inheritance Tax threshold has remained frozen since 2009. This means that as property prices continue to climb in 2026, more families find themselves unexpectedly liable for a 40% tax bill. It’s understandable to feel a sense of unease regarding the rules of intestacy or the potential invalidity of a DIY document, which is why many now seek out expert will solicitors to secure their legacy. You deserve the certainty that your life’s work will benefit the people you love most, rather than being lost to administrative errors or avoidable taxes.

Professional guidance allows you to transform a simple document into a strategic shield for your family’s future. This guide demonstrates how expert advice can help you navigate complex thresholds, protect modern digital assets, and ensure your final wishes are entirely watertight. We’ll explore the practical steps you can take today to secure your estate, provide lasting peace of mind for your beneficiaries, and establish a clear, professional plan for asset protection.

Key Takeaways

  • Understand how expert will solicitors provide more than just a document by offering strategic advice on asset distribution and legal compliance to protect your legacy.
  • Learn why the immediate savings of a DIY kit often lead to significant risks. Professional drafting ensures your estate remains tax-efficient and legally watertight.
  • Discover how to incorporate complex modern interests, such as digital assets and overseas property, into a legally binding UK framework.
  • Gain a clear roadmap of the professional consultation process, from identifying your core objectives to creating a comprehensive map of your financial world.
  • Explore how integrating your will with Lasting Powers of Attorney ensures total protection for both your assets and your personal welfare during your lifetime.

What Do Will Solicitors Do and Why Are They Essential?

Will solicitors are legal professionals who specialise in the precision-led drafting, witnessing, and execution of testamentary documents. Whilst it’s possible to write a basic expression of your wishes on a piece of paper, a solicitor ensures that those wishes are translated into a legally binding framework. They provide strategic oversight, ensuring that every asset is accounted for and that your distribution plan complies with current UK law. This professional guidance is about more than just paperwork; it’s about providing a steady presence during a complex life stage.

If you die without a valid will, your estate is subject to the rules of intestacy. This rigid legal process dictates who inherits your assets based on a strict hierarchy, often excluding unmarried partners, step-children, or close friends. By engaging a professional, you prevent the state from making these deeply personal decisions on your behalf. Expert involvement also creates a robust defence against future legal challenges. They ensure your document is resilient against claims of undue influence or lack of testamentary capacity, which are common grounds for contesting a will in the UK courts.

The Core Responsibilities of Your Legal Advisor

A trusted advisor takes a methodical approach to your affairs, ensuring no detail is overlooked. Their core responsibilities include:

  • Estate Mapping: Identifying the full scope of your estate, including property, savings, and sentimental personal effects.
  • Strategic Appointments: Advising on the selection of suitable executors and, crucially, legal guardians for minor children to ensure they’re cared for by people you trust.
  • Formal Execution: Ensuring that all legal formalities for witnessing and signing are strictly met. Even a minor technical error can render a will invalid, leading to significant distress for your loved ones.

When Professional Intervention is Non-Negotiable

Certain circumstances demand a higher level of technical expertise that a DIY kit simply cannot provide. If your family structure involves complex dynamics, such as children from previous relationships or multiple marriages, standard templates often fail to provide adequate protection for all parties. Professional intervention is equally vital for estates exceeding the £325,000 Inheritance Tax threshold. In these cases, strategic planning can significantly reduce the tax burden on your heirs. For those with business interests or international assets, will solicitors ensure that your UK will works in harmony with overseas regulations, providing a seamless transition of wealth across borders.

Solicitors vs. DIY Will Kits: Evaluating the Real Costs

The appeal of a DIY will kit is obvious: it’s inexpensive and can be completed in an afternoon. However, the immediate saving often masks a significant long-term risk. Unlike a static template, will solicitors provide a strategic shield that accounts for the nuances of your specific life circumstances. Shop-bought kits are designed for the “average” person, but few lives are truly average. When you opt for professional drafting, you’re investing in a document that is built to withstand scrutiny.

One of the most critical differences is the protection of professional indemnity insurance. If a solicitor drafts a document that is later found to be deficient, your estate has legal recourse. With a DIY document, your family is left to bear the financial burden of any errors alone. This financial safety net is a cornerstone of professional practice, providing a level of security that a simple form cannot replicate. It’s the difference between a generic product and a bespoke legal service.

The True Price of a ‘Cheap’ Will

A ‘cheap’ will often becomes an expensive legacy. Vague language, such as failing to define “personal effects” or “residuary estate” clearly, frequently leads to bitter litigation amongst beneficiaries. If the document is declared invalid due to a witnessing error, your estate falls under the rules of intestacy. Investing in professional fees now often saves your heirs tens of thousands of pounds in future legal costs. It also prevents the emotional toll of family disputes during an already difficult time.

Why Empathy and Expertise Matter

A sophisticated guide does more than fill in blanks. They act as a trusted advisor, identifying risks you might not have considered. For instance, the Property (Digital Assets etc) Act 2025 now requires specific consideration for cryptocurrency and online accounts. A template won’t ask about your digital footprint, but a specialist will.

At Feltons, we pride ourselves on delivering pragmatic, plain-English advice that prioritises your family’s unique dynamics. We understand that discussing your final wishes requires a delicate balance of technical precision and human empathy. If you’re ready to move beyond templates, you can explore our estate planning services to discuss a tailored approach to your estate. Our goal is to ensure your legacy is handled with the quiet confidence it deserves.

Managing Complex Assets: Digital Legacies and Overseas Interests

The modern estate has evolved significantly beyond physical property and traditional bank accounts. Today, your legacy likely includes a vast array of intangible assets, from cryptocurrency portfolios to professional social media presence and intellectual property. Expert will solicitors now play a vital role in ensuring these modern interests are not lost or locked away forever. Without specific provisions, your executors may find themselves legally barred from accessing essential online accounts, leading to the permanent loss of both financial value and sentimental memories.

The Rise of the Digital Estate

Digital assets encompass everything from online banking and investment platforms to digital creative works and loyalty points. To manage these effectively, your will must grant executors explicit legal authority to interact with service providers. This prevents a “digital dark age” where your online footprint becomes an inaccessible burden for your family. Under 2026 legal standards, a digital legacy is defined as the collective body of a person’s online data, digital property, and social presence that persists after their death.

Strategic planning involves more than just listing passwords; it requires a structured approach to asset discovery. We advise clients to maintain a secure, offline inventory of their digital holdings, which can be referenced in the will without compromising security. This ensures that assets like Bitcoin or NFTs, which are now formally recognised under the Property (Digital Assets etc) Act 2025, are identified and transferred according to your wishes rather than being forgotten in the depths of the blockchain.

International Assets and Overseas Entities

Owning property abroad introduces a layer of complexity that a standard UK will may not fully address. Different jurisdictions have varying rules on “forced heirship,” which can override your stated intentions if not managed correctly. Coordinating your UK arrangements with foreign legal requirements is essential to prevent conflicting instructions and protracted probate disputes. Professional drafting ensures that your global footprint is managed as a single, cohesive strategy.

For individuals with assets or interests in the United States, The Village Law Firm provides the specialised estate planning and administration expertise necessary to ensure your legacy is protected across different legal jurisdictions.

The landscape of property ownership has also been reshaped by transparency requirements. Understanding how overseas entity beneficial owner registration impacts your estate is crucial for those holding UK property through foreign structures. Failure to maintain these registrations can lead to significant delays in the transfer of property to your beneficiaries. By addressing these cross-border issues proactively, will solicitors help you mitigate the risk of international assets becoming a legal or financial liability for your heirs. We provide the discreet, worldly experience necessary to handle these intricate matters with precision.
Will Solicitors: A Comprehensive Guide to Protecting Your Estate in 2026

The Step-by-Step Process of Working with Will Solicitors

Engaging with will solicitors isn’t a mere transaction; it’s a methodical journey toward total peace of mind. The process begins with an initial consultation designed to establish trust and clarity. We don’t just ask about your assets; we seek to understand your primary objectives and the specific people you wish to protect. This isn’t a high-volume processing exercise. It’s a boutique experience where your personal connection to your legacy is prioritised from the very first meeting.

Following the consultation, we move into the vital phase of asset discovery. This is where we create a comprehensive map of your financial and personal world. We look beyond the obvious, examining property, savings, and those complex digital assets that define modern life. This methodical approach ensures that every facet of your estate is accounted for, leaving no room for ambiguity or future dispute. It’s about building a foundation that is both legally robust and personally meaningful.

Preparing for Your Consultation

To make the most of your time, it helps to gather key documents before we meet. Think about your pensions, property deeds, and life insurance policies. Consider your legacy in broader terms too. Are there charitable donations you’d like to make? Do you have specific bequests for sentimental items? Feltons’ methodical flow ensures that even the smallest detail is captured, reflecting our commitment to traditional professional integrity and modern efficiency.

Refining Your Wishes

Drafting is an iterative process. You’ll review the document with your solicitor to ensure it reflects your exact wishes with absolute precision. We’ll refine the language to ensure it’s legally watertight whilst remaining respectful to your beneficiaries. This stage also involves adjusting for tax efficiency. With the Inheritance Tax nil-rate band frozen at £325,000 until 2031, strategic drafting is essential to protect your heirs from unnecessary fiscal drag. We ensure the tone of the document remains clear, avoiding dense legalese in favour of plain English.

The final, critical step is the formal execution. The signing and witnessing ceremony must strictly adhere to legal formalities to ensure the will’s validity. Once complete, secure storage is paramount. We’ll advise on where to keep the original document and how to notify your executors of its location. A will is only effective if it can be found and verified when it’s needed most. If you’re ready to begin this methodical journey, you can contact our team of will solicitors today to discuss your requirements. We’re here to provide the calm, steady presence you need to secure your family’s future.

Beyond the Will: Integrated Asset Protection and Probate

A will shouldn’t exist in a vacuum. To achieve total protection, your testamentary wishes must be woven into a broader framework of estate planning. This integrated approach ensures that your assets are managed efficiently both during your lifetime and after you’ve passed. Whilst a will handles the distribution of your legacy, Lasting Powers of Attorney (LPA) safeguard your interests whilst you’re still alive. These documents allow you to appoint trusted individuals to make decisions about your health and finances if you ever lose the capacity to do so yourself.

Major life changes also necessitate a fresh look at your legal arrangements. If you’re navigating the end of a relationship, consulting a divorce and financial arrangements lawyer is vital. Marriage usually revokes an existing will; divorce can leave significant gaps in your estate’s protection. Expert will solicitors ensure that your updated documents reflect your new financial reality, preventing assets from inadvertently passing to an ex-partner.

Wills and Property Law

There is a powerful synergy between residential property law and the distribution of your estate. Your home is likely your most significant asset, so handling its transfer requires precision. We provide guidance on complex matters like leasehold extensions and enfranchisement, ensuring these property rights are maximised before they pass to your heirs. By using clever trust structures, we can help you protect the family home from being depleted by long-term care costs or unnecessary tax liabilities.

Probate and Estate Administration

When the time comes, the transition to probate should be as seamless as possible. Our role involves applying for a Grant of Probate, which gives executors the legal authority to manage your affairs. We handle the heavy lifting: settling outstanding debts, paying the correct amount of Inheritance Tax, and ensuring assets are distributed exactly as you intended. This methodical process provides a sense of security during a difficult time.

The practical side of estate administration often involves managing physical assets and property contents. In such cases, families may find that Clear This Ltd House Clearance Services offers a sensitive and professional way to handle house clearance throughout the Lancashire area.

Feltons’ “people-first” philosophy is particularly crucial during this stage. We act as a calm, steady presence for your family, handling the technical complexities so they can focus on their own well-being. By choosing experienced will solicitors, you ensure that the same high standard of care you received during the drafting process continues long after you’re gone. We remain your family’s discreet partner, protecting your legacy with traditional integrity and modern efficiency.

Securing Your Legacy for the Next Generation

Protecting your life’s work requires more than a simple document; it demands a strategic vision that accounts for both traditional property and modern digital assets. By moving beyond the limitations of DIY templates, you ensure your estate is resilient against legal challenges and tax inefficiencies. Expert will solicitors provide the steady, professional guidance needed to navigate these complexities with quiet confidence. Our boutique service combines national-level expertise with pragmatic, plain-English advice tailored specifically to your family’s unique dynamics.

Whether you’re managing a global asset portfolio or simply wish to provide peace of mind for your loved ones, a methodical approach is the most reliable way to safeguard your final wishes. We specialise in complex and international estate matters, ensuring that every detail is handled with discretion and integrity. It’s never too early to establish a clear plan for the future. You can book a confidential consultation with our specialist will solicitors to begin securing your legacy today. Taking this proactive step provides the certainty and security that you and your family deserve.

Frequently Asked Questions

How much do will solicitors typically charge in 2026?

Fees vary based on the complexity of your estate and the specific requirements of your family structure. A straightforward single document is generally more cost-effective than mirror wills for couples or complex arrangements involving trusts and overseas assets. We recommend discussing your needs during a consultation to receive a transparent estimate tailored to your circumstances. Investing in professional expertise ensures your document is robust, legally binding, and built to withstand future scrutiny.

Can I change my will after it has been signed and witnessed?

You can change your will at any time as long as you have the mental capacity to do so. For minor adjustments, a legal document called a codicil can be added to the existing will. However, if you wish to make significant changes, it’s usually better to draft a completely new document to avoid confusion or potential conflict. Your solicitor will ensure any updates are executed with the same formal rigour as the original.

What is the difference between an executor and a beneficiary?

An executor is the person responsible for managing your estate and carrying out the instructions in your will, whereas a beneficiary is someone who receives assets or property from the estate. It’s common for a person to be both an executor and a beneficiary, such as a spouse or adult child. Selecting an executor requires careful thought, as the role involves significant legal and financial responsibilities during the probate process.

How often should I review my will with a solicitor?

It’s advisable to review your will every three to five years to ensure it still reflects your wishes and financial situation. Certain life events make an immediate review essential, including marriage, divorce, the birth of children, or a significant change in your asset portfolio. Regular consultations with will solicitors allow you to adjust for legislative changes, such as updated tax thresholds or new regulations regarding digital property and overseas interests.

Do I need a separate will for property I own abroad?

Whether you need a separate will depends on the country where your property is located and its specific inheritance laws. Some jurisdictions have forced heirship rules that may conflict with your UK will. In many cases, having a local will in that country is the most efficient way to handle the property. Your UK solicitor will work to ensure your various testamentary documents are coordinated and don’t contain contradictory instructions.

What happens if my will is lost or destroyed?

If a will cannot be found after your death, the law may presume that you destroyed it with the intention of revoking it, which could lead to your estate being distributed under the rules of intestacy. This is why secure storage is so important. Whilst a copy may sometimes be accepted by the probate registry, the process is complex and requires significant evidence. Storing your original document with a professional firm provides a vital safety net.

Can a will be challenged in court after I die?

Yes, a will can be challenged in the UK courts on several grounds, including claims that the document was not properly executed or that the testator lacked mental capacity. Challenges can also arise under the Inheritance (Provision for Family and Dependants) Act 1975 if a close relative feels they haven’t been adequately provided for. Will solicitors use their expertise to draft robust documents that minimise the risk of these stressful and costly legal disputes.

Is a will made in 2026 valid if I move house or get married?

Moving house doesn’t invalidate your will, but getting married or entering a civil partnership usually revokes any existing document entirely unless it was made in expectation of that specific marriage. Conversely, divorce doesn’t revoke a will, but it treats your former spouse as if they had died before you, which can create unintended gaps in your distribution plan. You should always seek legal advice following these major life changes to ensure total protection.
A Comprehensive Guide to Estate Planning: Protecting Your Legacy in 2026

A Comprehensive Guide to Estate Planning: Protecting Your Legacy in 2026

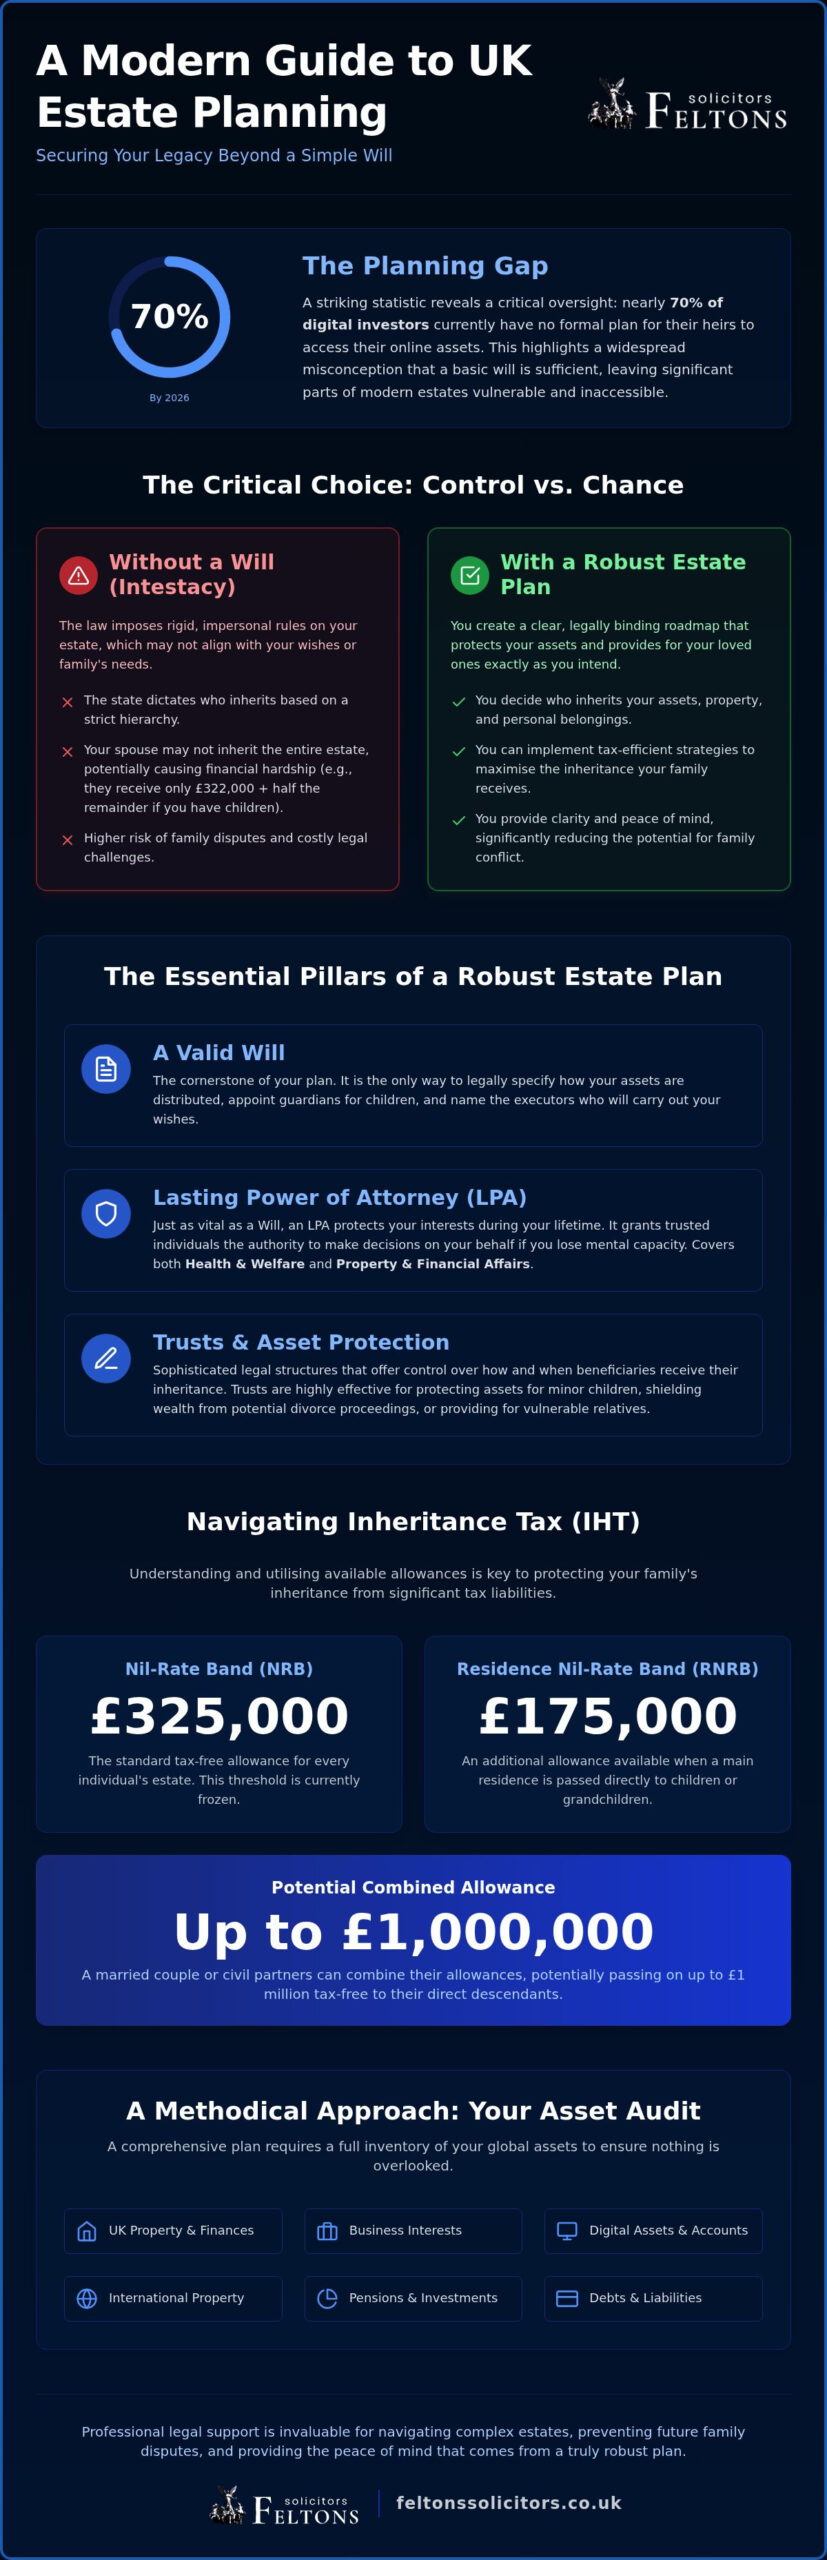
Did you know that in 2026, nearly 70% of digital investors still have no formal plan for their heirs to access their online assets? It is a striking figure that highlights a broader, more unsettling truth; many people mistakenly believe a simple will is enough to protect their life’s work. You likely feel a deep sense of responsibility to ensure your hard-earned assets reach the right hands. However, the fear of the state claiming a significant portion through Inheritance Tax remains a heavy burden. It’s natural to feel anxious about potential family disputes or confused by the technical gap between a basic will and a comprehensive estate planning strategy.

We believe your legacy is about more than just numbers. It is about the people you love and the values you have built. This guide provides a sophisticated roadmap to securing your assets and ensuring your family’s future remains legally protected. We will explore how to minimise tax liabilities under current thresholds, such as the frozen £325,000 nil-rate band, and provide clarity on protecting vulnerable beneficiaries. From the intricacies of the Residence Nil-Rate Band to the upcoming 2027 changes to pension taxation, we’ll help you find the peace of mind that comes from a truly robust plan.

Key Takeaways

  • Understand why estate planning is a comprehensive legal strategy that goes far beyond a simple will to include lifetime gifts and protective powers of attorney.
  • Identify the essential pillars of a robust plan, focusing on how a valid Will and a Lasting Power of Attorney work together to safeguard your interests.
  • Learn how to navigate the complexities of Inheritance Tax by utilising the Nil-Rate Band and the Residence Nil-Rate Band to protect your family’s inheritance.
  • Discover a methodical approach to auditing your global assets, including digital accounts and international property, to ensure nothing is overlooked.
  • Recognise the value of a boutique legal partner in managing complex estates and preventing future family disputes or costly litigation.

Defining Estate Planning in the Modern UK Context

Estate planning is a holistic legal and financial strategy designed to manage your assets during your lifetime and ensure their orderly distribution after your death. It is far more than just drafting a document; it is a methodical process that aligns your personal values with the practicalities of the law. By creating a comprehensive overview of estate planning, you establish a clear roadmap that protects your legacy from unnecessary tax burdens and legal ambiguity. Most importantly, it serves as a vital safeguard against the rigid, impersonal rules of intestacy, which apply when no valid plan is in place.

Beyond the Will: A Holistic Legal Strategy

Whilst a Will is the cornerstone of any legacy, it often isn’t enough to address the complexities of modern life. If you own a business, hold international assets, or have a blended family structure, a standard Will might leave significant gaps. Effective estate planning incorporates wider tools such as lifetime gifting, trusts, and the registration of Lasting Powers of Attorney. These mechanisms do more than just distribute wealth; they protect it. A well-structured plan can help shield assets from being depleted by care home costs or becoming entangled in divorce proceedings within the family. Because legislation evolves, having a dedicated solicitor ensures your strategy remains compliant with current tax laws and legal precedents.

The Risks of Inaction: Intestacy and Legal Uncertainty

Dying “intestate” means the state determines who inherits your estate based on a fixed hierarchy, regardless of your personal relationships or intentions. Under current rules in England and Wales, if you die without a Will and have a spouse and children, your partner is entitled to personal belongings and a statutory legacy of £322,000. They only receive half of the remaining estate, with the other half going to your children. This often creates unintended financial hardship and emotional distress. Without professional guidance, the risk of contentious probate disputes increases significantly. A clear, legally binding plan reduces this burden on grieving relatives, providing them with the certainty and peace of mind they need during a difficult time. It prevents the state from becoming the default architect of your family’s future.

The Essential Pillars of a Robust Estate Plan

A successful approach to estate planning relies on several interconnected legal instruments. Relying on a single document is like building a house without a roof; it might look complete, but it won’t withstand the elements. Beyond the Will, which acts as your primary instruction manual, you must consider tools that protect you whilst you’re still alive and others that manage your wealth long after you’ve gone. These pillars provide a framework that ensures your wishes are followed precisely, regardless of what the future holds.

The foundation is a valid Will. It is the only way to ensure your assets are distributed exactly as you intend. Without it, your estate is subject to the rigid rules of intestacy. To support this, many people also include a Letter of Wishes. This is a non-binding document that provides your executors with personal guidance on matters such as funeral arrangements or the specific distribution of sentimental items. It adds a human touch to the clinical precision of a legal Will.

Lasting Power of Attorney: Protecting Your Interests During Life

An LPA is arguably as vital as a Will. It grants a person you trust the authority to make decisions on your behalf if you lose mental capacity. There are two distinct types: Health and Welfare, and Property and Financial Affairs. Many younger professionals and business owners overlook this, assuming it’s a concern for the distant future. However, if an accident or illness leaves you unable to manage your business interests or personal bank accounts, your family could face a costly application to the Court of Protection. The legal process of registering an LPA with the Office of the Public Guardian takes time, so it’s a step that should be taken whilst you are fit and healthy. If you’re unsure where to start, you can organise your estate planning with the help of a specialist to ensure every base is covered.

Trusts and Asset Protection: Sophisticated Legacy Management

Trusts are sophisticated legal vehicles that allow you to dictate how and when beneficiaries receive their inheritance. They are particularly effective for protecting minor children or vulnerable relatives who might struggle to manage a large lump sum. For those with complex property portfolios, trusts can help manage the transition of ownership across generations whilst potentially offering protection from third-party claims. If your estate includes international property, you must also be aware of the overseas entity beneficial owner registration requirements to ensure your holdings are compliant with current UK law. Whilst your executors will eventually follow official probate guidance to settle your affairs, having these structures in place now reduces the administrative and emotional burden they will face later.

Inheritance Tax is often the most significant concern for those embarking on estate planning. It can feel like a silent partner in your financial life, waiting to claim a portion of what you have worked to build. Currently, the standard Nil-Rate Band remains frozen at £325,000 until April 2031. However, many homeowners can also benefit from the Residence Nil-Rate Band (RNRB), which provides an additional £175,000 allowance when passing a main residence to direct descendants. Understanding these Inheritance Tax thresholds and rules is the first step toward mitigation. For married couples or civil partners, these allowances are transferable, potentially creating a combined tax-free threshold of £1 million.

Reliefs and exemptions play a critical role in sophisticated planning. Transfers between spouses are generally tax-free, and leaving at least 10% of your net estate to charity can reduce your overall IHT rate from 40% to 36%. For business owners, Business Property Relief (BPR) is an essential tool. As of April 6, 2026, 100% relief for business and agricultural assets is capped at a combined £2.5 million per individual. Above this threshold, relief is reduced to 50%, making precise valuation and early advice vital for those with significant commercial interests. For estates valued at more than £2 million, the RNRB is also tapered, reducing by £1 for every £2 that the estate exceeds the threshold.

Strategic Gifting and the Seven-Year Rule

Gifting assets during your lifetime is an effective way to reduce the taxable value of your estate. Most significant gifts are considered Potentially Exempt Transfers (PETs), which only become entirely tax-free if you survive for seven years after making the gift. You must be cautious of the ‘Gift with Reservation of Benefit’ rule. You cannot, for example, gift your family home to your children whilst continuing to live there rent-free, as HMRC will still view it as part of your estate. You can, however, utilise your annual £3,000 gift allowance or make small gifts of up to £250 per person each tax year without any IHT implications.

Life Insurance and Pensions in Estate Planning

Pensions have traditionally been one of the most tax-efficient ways to pass on wealth, as they usually sit outside your estate for IHT purposes. However, from April 6, 2027, most unused defined-contribution pension pots will become subject to Inheritance Tax, a change that will affect thousands of families. Life insurance policies should also be managed with care; by writing a policy in trust, the payout goes directly to your beneficiaries rather than forming part of your legal estate. If your circumstances involve complex family dynamics or former partners, consulting a divorce and financial arrangements lawyer ensures your tax strategy doesn’t conflict with existing legal obligations.

A Comprehensive Guide to Estate Planning: Protecting Your Legacy in 2026

The Estate Planning Process: A Methodical Approach

Transitioning from understanding legal tools to implementing them requires a disciplined, step-by-step methodology. Effective estate planning begins with a comprehensive audit of your entire financial landscape. This isn’t limited to your bank balance; it includes international property holdings, business interests, and outstanding liabilities. You must also identify your primary objectives. Are you prioritising maximum tax efficiency, the protection of a vulnerable relative, or the smooth continuity of a family business? Clear goals determine which legal structures will serve you best and provide the necessary certainty for your executors.

Assessing Your Global Assets and Liabilities

We recommend creating what many call an “Estate Bible”. This is a secure, centralised record for your executors that lists every account, insurance policy, and property you own. For those with significant real estate interests, working with a residential property law firm ensures that complex title issues or leasehold extensions are resolved before they become probate problems. Don’t forget your digital legacy. With 85.6% of digital investors failing to include online assets in their Wills as of 2026, ensuring access to cryptocurrency, social media, and cloud-stored photos is a critical modern requirement that prevents your digital life from being locked away forever.

Preventing Contentious Probate and Family Disputes

The human cost of a poorly drafted plan often manifests in painful family conflict. Contentious probate is on the rise, but professional oversight can significantly reduce the likelihood of a successful challenge. Precise drafting and the inclusion of objective explanations for your decisions help manage expectations and discourage legal disputes amongst beneficiaries. We often use “no-contest” clauses or detailed solicitor’s file notes as vital evidence of your mental capacity and intentions at the time of signing. This level of detail provides a robust shield for your executors, ensuring your wishes are followed whilst protecting your loved ones from the trauma of litigation.

Once your documents are executed, your plan shouldn’t sit in a drawer gathering dust. Review your affairs at least every five years or following major life events such as marriage, divorce, or the birth of grandchildren. Legislation and personal circumstances change, and your strategy must evolve alongside them to remain effective. To begin your own methodical review and ensure your affairs are in order, you can contact our estate planning team for a discreet, professional consultation.

Feltons Solicitors LLP understands that legal documents are only as effective as the strategy behind them. Since our establishment in 2010 by Paula Felton, we’ve prioritised a boutique level of care that high-volume firms often struggle to replicate. We combine traditional professional integrity with modern efficiency to ensure your affairs are handled with the discretion they deserve. Our people-first philosophy means we never lose sight of the human impact of our work. Whether we’re drafting a simple Will or managing complex international litigation, our focus remains on providing a calm, steady presence. We act as a sophisticated guide, navigating you through the nuances of the law whilst ensuring your personal connection to the firm remains at the heart of our service.

A Discreet, Boutique Service for Complex Estates

High-net-worth individuals often face unique challenges that require more than a template-driven approach. We specialise in providing tailored solutions for those with intricate family structures or diverse asset portfolios across multiple jurisdictions. Having a single point of contact who understands your entire history is invaluable; it ensures that your estate planning remains cohesive and aligned with your long-term vision. For those seeking deeper insights into legacy protection, our complete guide to estate planning offers further details on how we safeguard complex holdings. We handle everything from residential conveyancing to the registration of overseas entities, ensuring no part of your global footprint is left exposed to unnecessary risk or tax liability.

Securing Your Future with Pragmatic Legal Advice

Choosing the right solicitor is the most important decision you’ll make in this process. We’re committed to providing pragmatic advice in plain English, avoiding the dense, archaic legalese that often leads to confusion. Our professional fees are transparent and fair, ensuring you feel in control of the process from the very first meeting. The initial consultation is designed to be a thorough yet reassuring experience where we listen to your concerns and map out a bespoke strategy. We believe that estate planning shouldn’t be a source of anxiety; it should be a source of confidence. Our firm is deeply rooted in the community yet possesses the worldly experience necessary to handle international-scale matters with ease. Take the first step towards securing your family’s future and achieving true peace of mind today.

Secure Your Legacy with Certainty and Care

Effective estate planning is about more than just wealth; it’s about providing your family with a clear, conflict-free future. By addressing the essential pillars, from robust Wills to Lasting Powers of Attorney, and navigating the frozen £325,000 Nil-Rate Band, you ensure your assets remain in the right hands. A methodical audit of your global and digital holdings prevents the state from becoming the default architect of your family’s inheritance and ensures your wishes are followed precisely.

Established in 2010 by Paula Felton, Feltons Solicitors LLP specialises in complex property and private client law. We provide pragmatic, people-first legal advice tailored to your unique circumstances. Whether you’re managing a domestic estate or intricate international interests, we act as your trusted advisor to ensure every legal detail is meticulously handled. Take the first step towards true peace of mind and contact Feltons Solicitors LLP for a discreet estate planning consultation. You’ve worked hard to build your legacy; now, let us help you protect it for the generations to come.

Frequently Asked Questions

What is the difference between a will and estate planning?

A Will is a specific legal document that dictates how your assets are distributed after death, whilst estate planning is a comprehensive strategy for managing your affairs during your lifetime and beyond. It encompasses a wider range of tools, including Lasting Powers of Attorney, trusts, and tax mitigation tactics. Whilst a Will is the foundation, a full plan ensures that your financial, legal, and personal interests are protected against unforeseen circumstances like incapacity or excessive tax liabilities.

How much can I leave to my children before they pay Inheritance Tax?

Under current 2026 rules, an individual can typically leave up to £500,000 to their children tax-free by combining the £325,000 Nil-Rate Band with the £175,000 Residence Nil-Rate Band. For married couples or civil partners, these allowances are transferable, allowing for a combined threshold of up to £1 million. Anything above these limits is generally taxed at 40%, unless specific exemptions or charitable reliefs apply to the remainder of the estate.

Do I need a solicitor for estate planning, or can I do it myself?

Whilst you can legally draft your own documents, professional legal oversight is strongly recommended for anyone with complex assets, business interests, or international property. A solicitor ensures that your documents are technically valid and structured to minimise tax liabilities effectively. Professional guidance also provides vital evidence of mental capacity and intent, which significantly reduces the likelihood of your wishes being challenged through contentious probate litigation later.

What happens to my estate if I do not have a will?

If you die without a Will, your estate is distributed according to the rigid rules of intestacy rather than your personal wishes. In England and Wales, a surviving spouse is entitled to all personal belongings, a statutory legacy of £322,000, and half of the remaining estate. The other half is divided amongst your children. This often creates financial uncertainty and may leave unmarried partners with no automatic inheritance rights at all.

Can estate planning protect my home from being sold for care home fees?

Certain legal structures, such as life interest trusts or severing a joint tenancy, can help protect a portion of your home’s value for your beneficiaries. However, you must be cautious of ‘deprivation of assets’ rules, where the local authority may challenge transfers made specifically to avoid care costs. Because this area of law is highly nuanced, it requires a bespoke approach to ensure your plan is both effective and legally compliant.

How often should I review my estate plan and will?

We recommend reviewing your estate plan and Will at least every five years to ensure they still reflect your wishes and current legislation. You should also update your documents immediately following major life events, such as marriage, divorce, or the birth of a child. Significant changes in your financial situation, such as purchasing international property or starting a business, also necessitate a professional review to maintain the plan’s effectiveness.

What is a Lasting Power of Attorney and why is it part of estate planning?

A Lasting Power of Attorney (LPA) is a legal document that appoints trusted individuals to make decisions on your behalf if you lose mental capacity. It is a vital part of estate planning because it protects your interests whilst you are still alive. Without an LPA, your family might have to undergo a costly and lengthy application to the Court of Protection to manage your bank accounts, business affairs, or health care needs.

Can I include my digital assets, like social media and cryptocurrency, in my estate plan?

Yes, you should absolutely include digital assets like cryptocurrency, social media accounts, and online photo libraries in your plan. As of 2026, a significant majority of people still haven’t made provisions for their digital legacy, which can lead to these assets being lost forever. Including a specific digital asset clause and providing your executors with clear instructions on how to access these platforms is now an essential part of modern legacy protection.

Financial Disclosure in Divorce UK: A Complete Guide for 2026

Financial Disclosure in Divorce UK: A Complete Guide for 2026

What if the most significant threat to your future financial security isn’t the divorce itself, but a single missing detail in your paperwork? It’s a common fear amongst those separating in 2026, especially when the legal landscape now includes complex digital assets and shifting pension regulations. Undertaking the financial disclosure divorce UK process often feels like an overwhelming administrative hurdle, particularly when you’re already managing the emotional weight of a relationship ending.

You’ve worked hard for your assets. The anxiety that they might be unfairly divided, or the worry that your spouse isn’t being entirely transparent about their own holdings, is a heavy burden to carry. This guide provides the calm, expert clarity you need to master these complexities, ensuring your settlement is fair, legally binding, and robust enough to withstand any future challenges. We’ll examine the latest 2026 valuation standards for pensions and cryptocurrency, the strict requirements of the current Form E, and the vital steps to achieving a final settlement with total peace of mind.

Key Takeaways

  • Understand the “full and frank” legal standard required for financial disclosure divorce UK to ensure your final settlement is protected against future legal challenges.
  • Navigate the complexities of Form E by learning the specific 2026 requirements for valuing modern assets, including digital holdings and complex pension schemes.
  • Identify exactly which assets must be declared, from the family home to individual savings accounts, to avoid the risk of court-imposed penalties.
  • Learn how the court handles non-disclosure and why being transparent is the most effective way to safeguard your long-term financial interests.
  • Discover how a tailored, people-first legal approach can transform an intrusive process into a structured path toward a fair and final resolution.

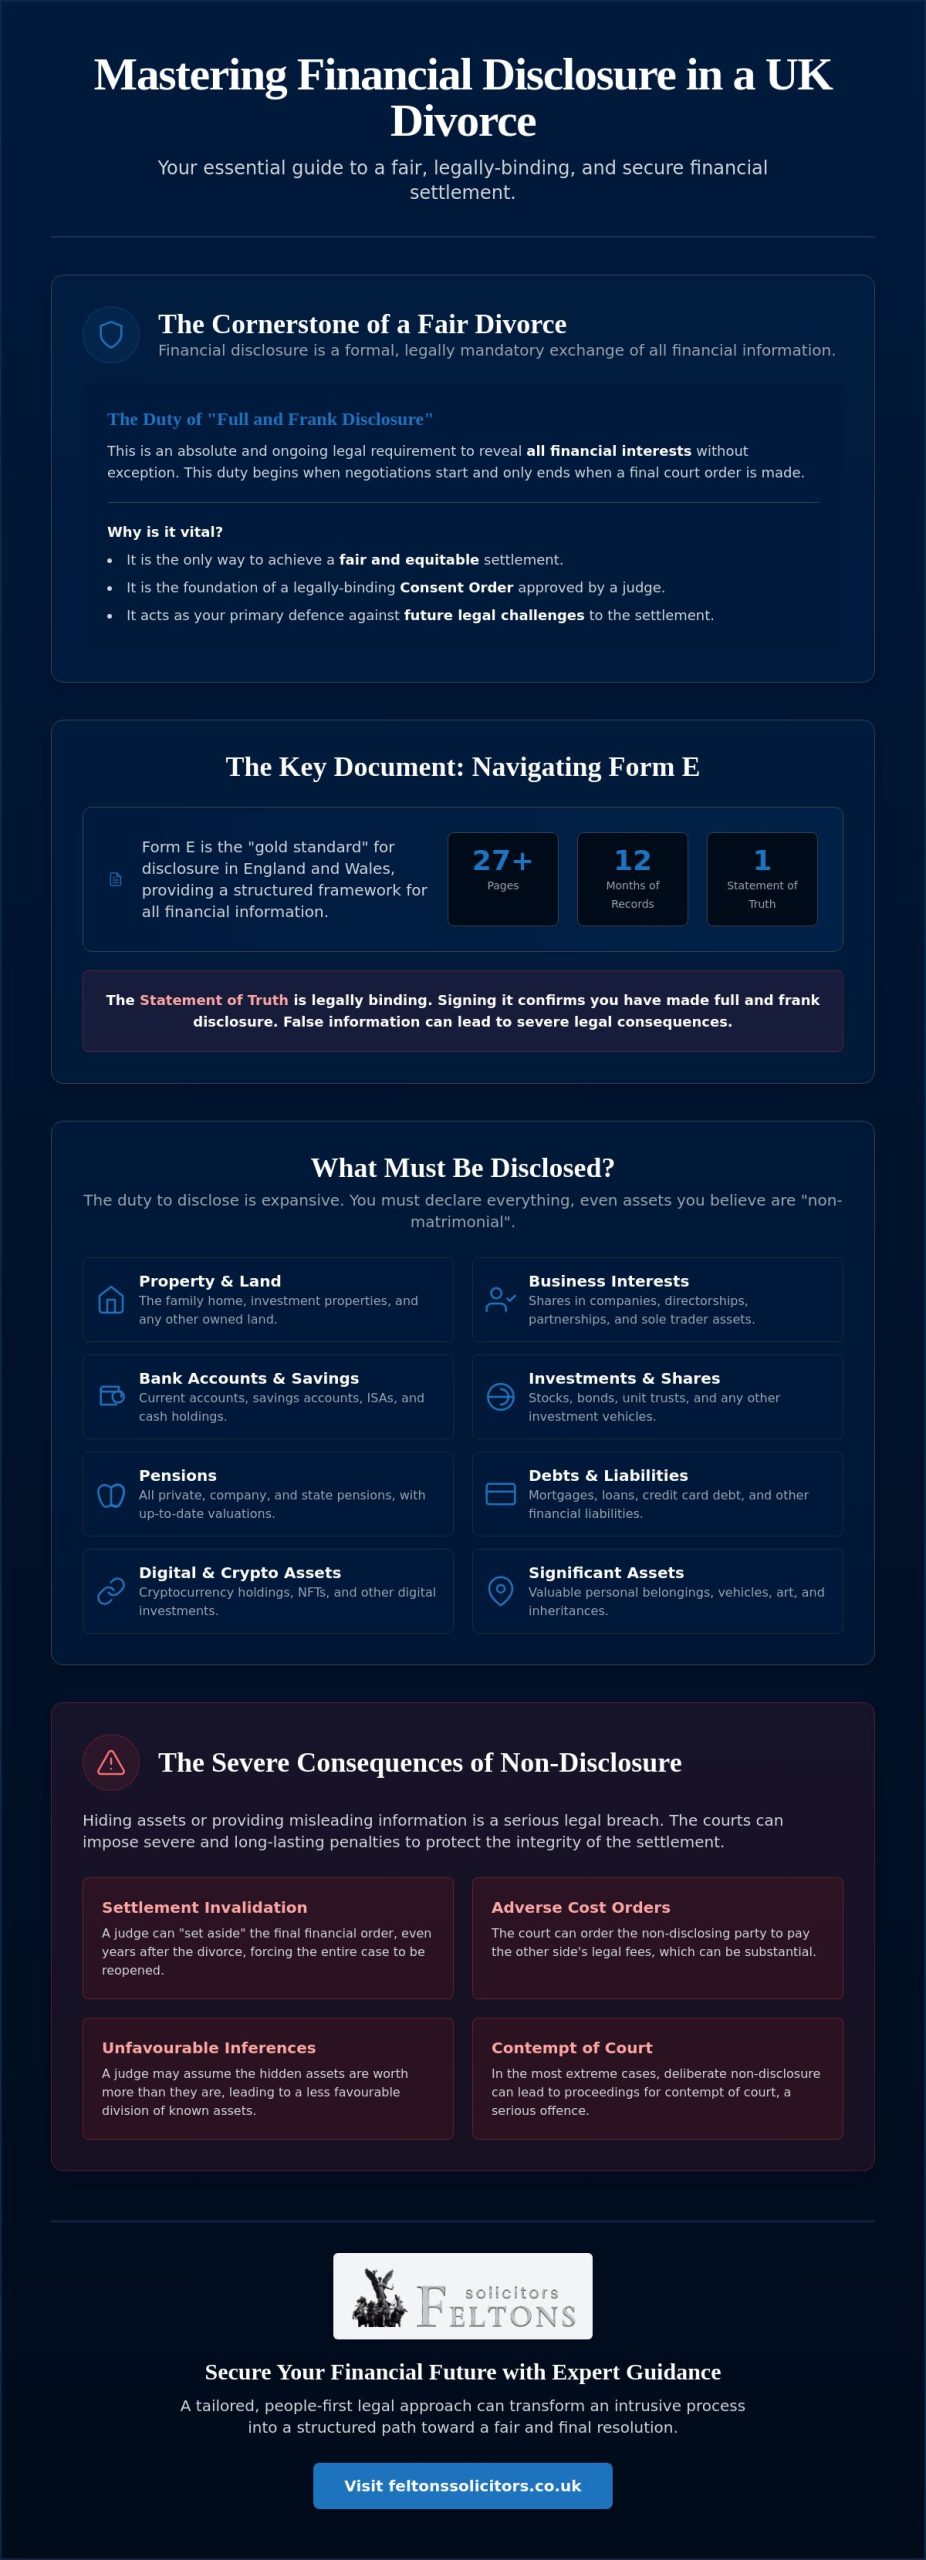
What is Financial Disclosure in a UK Divorce?

The process of financial disclosure divorce UK is often the most significant phase of a legal separation. It represents a formal exchange of information where both parties provide a comprehensive overview of their financial positions. Transparency is not merely a courtesy; it is a fundamental legal obligation. Without a clear and honest account of every asset, debt, and income stream, it is impossible to reach a settlement that the court considers fair or equitable.

This requirement exists to protect both individuals. By ensuring all cards are on the table, the law prevents one party from being disadvantaged by a lack of information. This transparency is governed primarily by the Matrimonial Causes Act 1973, which provides the framework for how the court distributes assets. Whether you are negotiating through mediation or proceeding via a court application, the standards for honesty remain identical. A final agreement only becomes legally binding when it is drafted into a Consent Order and approved by a judge, who must be satisfied that the disclosure was complete before granting the order.

Failing to be transparent carries long term risks. If a spouse discovers later that assets were hidden or undervalued, they can apply to have the original agreement “set aside.” This means the entire settlement could be reopened years after the divorce is finalised, leading to significant legal costs and emotional distress. Accurate disclosure is your primary defence against future litigation.

The Duty of Full and Frank Disclosure

Full and Frank Disclosure is the absolute legal requirement to reveal all financial interests. This duty is expansive and ongoing. It begins the moment financial negotiations start and continues until the final order is sealed by the court. You must disclose everything, including assets you might believe are “non-matrimonial,” such as an inheritance or a business you owned before the marriage. Whilst you may argue that these specific assets should not be shared, you don’t have the right to hide them from the process. The court, not the individual, determines which assets are relevant to the final division.

Voluntary vs. Court-Mandated Disclosure

Many couples choose to exchange information voluntarily at the start of their separation. This approach often saves time and reduces legal fees, as it avoids the rigid timetable of court proceedings. However, even in a voluntary exchange, most solicitors recommend using the standard Form E to ensure no details are overlooked. If one party is reluctant to share information or if there are concerns about hidden wealth, the court will intervene. In these instances, the court mandates a strict timetable for financial disclosure divorce UK, and failing to comply can result in serious penalties, including cost orders or the court making assumptions about your wealth that may not be in your favour.

The Form E Process: Navigating the Standard Financial Statement

Form E is the primary mechanism for financial disclosure divorce UK, serving as the “gold standard” for transparency in England and Wales. This document is far more than a simple list of assets; it’s a comprehensive 27-page statement that requires you to account for your entire financial life. The current version, dated 23 January 2023, is designed to leave no stone unturned, covering everything from basic income to complex business interests and digital holdings. By providing a structured framework, it ensures that both parties and the court have a clear, identical dataset from which to negotiate a fair split.

The timeline for this process is usually strict. In court proceedings, the judge sets a deadline for the simultaneous exchange of these forms, typically several weeks before the first hearing. Even in voluntary negotiations, sticking to a clear schedule prevents the process from drifting. Perhaps the most critical element of the form is the Statement of Truth. When you sign this, you’re confirming that you’ve made full and frank disclosure. Providing false information or omitting an asset isn’t just a mistake; it’s a serious legal breach that can lead to your settlement being overturned or, in extreme cases, proceedings for contempt of court.

Many people find the sheer volume of data required to be the most daunting aspect of sorting out your finances in a divorce. It’s easy to feel overwhelmed by the level of detail, but approaching the task methodically is the best way to maintain control. If you find the complexity of these requirements stressful, seeking specialist legal support can provide the steady, professional presence needed to ensure your submission is accurate and robust.

Evidence and Supporting Documentation

A Form E is only as strong as the evidence supporting it. You’re required to provide a full 12 months of statements for every bank account, building society, and ISA in your name. This “12-month rule” allows solicitors to track patterns of spending and identify any unusual transfers that might suggest assets are being moved. You’ll also need formal valuations for properties, recent mortgage statements, and up-to-date CETV (Cash Equivalent Transfer Value) figures for all pensions. Organising these documents into a clear, indexed bundle from the outset is the most effective way to minimise legal fees and avoid frustrating delays.

Questionnaires and Clarification

The exchange of Form E is rarely the end of the inquiry. Once both parties have reviewed each other’s statements, they have the right to serve a “Questionnaire.” This is a formal list of questions designed to fill gaps or clarify inconsistencies. For example, if a bank statement shows a large unexplained withdrawal, the questionnaire will ask for its destination. Whilst this back-and-forth can feel intrusive, it’s a vital part of the financial disclosure divorce UK process. It ensures that any “grey areas” are resolved before a final order is drafted, protecting the integrity of your eventual settlement.

What Must Be Disclosed? A Comprehensive Checklist for 2026

The identification of assets is the next logical step once you understand the Form E framework. In 2026, the scope of what constitutes wealth has expanded significantly. It’s no longer enough to simply list the family home and a joint savings account. The court requires a granular look at your entire financial footprint to ensure the financial disclosure divorce UK process is complete. This includes everything from traditional property to modern virtual holdings.

You must declare all matrimonial and non-matrimonial property. This encompasses the primary family home, any buy-to-let investments, and overseas holiday homes. Beyond physical bricks and mortar, every bank account, ISA, and premium bond must be listed. Business interests require particular attention; you’ll need to disclose shareholdings, directorships, and any interest in partnerships. Even if you believe a business asset is entirely separate from the marriage, it must be declared so its status can be professionally assessed. For those navigating a complex financial settlement divorce, having a clear strategic checklist in place before disclosure begins can be invaluable in ensuring no asset category is overlooked.

Pensions often represent a couple’s most valuable asset, sometimes exceeding the value of the family home. Following the Pension Advisory Group’s second report (PAG2) published in January 2024, the court’s approach to dividing occupational, private, and state pensions has become more refined. You’ll also need to account for the digital landscape. In 2026, this means providing valuations for cryptocurrency portfolios, NFTs, and even monetised online platforms like Substack or YouTube channels, which are now recognised as legitimate income streams.

Handling Complex Assets and Trusts

Assets held within a family trust must be disclosed, even if you’re only one of several beneficiaries. The court needs to understand the nature of your interest and the likelihood of you receiving future capital or income. Similarly, inheritances received before, during, or even after the separation must be documented. Whilst these are often treated differently from assets built up together, they remain part of the overall financial picture. High-value personal items also fall under the disclosure umbrella. If you own jewellery, art, or classic cars with a resale value exceeding £500, these should be professionally valued and included in your statement.

Liabilities and Financial Obligations

A fair settlement isn’t just about sharing wealth; it’s about managing debt. You must provide a full declaration of all personal loans, credit card balances, and mortgages. These liabilities are subtracted from your total assets to reach a “net” figure. The court also considers your future needs and financial obligations, such as school fees or the cost of rehousing. Whilst “conduct” or bad behaviour rarely impacts the financial split, it can become relevant during financial disclosure divorce UK if one party has deliberately squandered assets or “dissipated” funds to reduce the pot available for sharing. Understanding how spousal support obligations interact with these liabilities is essential; working with spousal maintenance solicitors UK can help you navigate these complexities and secure a financially sound Clean Break order.

Financial Disclosure in Divorce UK: A Complete Guide for 2026

The Consequences of Non-Disclosure: Protecting the Integrity of the Settlement

Attempting to circumvent the financial disclosure divorce UK process is a high-risk strategy that rarely succeeds. When a spouse is caught hiding assets or providing misleading information on Form E, the legal repercussions are severe. The court possesses the power to draw “adverse inferences,” which essentially means a judge can assume you have significantly more wealth than you’ve declared. They can then award your spouse a larger share of the known assets to compensate for this suspected hidden wealth, often leaving the non-disclosing party in a worse position than if they’d been honest.

Dishonesty also triggers significant financial penalties regarding legal costs. Usually, each party pays their own costs in financial remedy cases, but if one person behaves obstructively or dishonestly, the court can order them to pay the other party’s legal fees. This often results in a situation where the cost of the litigation far exceeds the value of the asset they were trying to hide. The landmark case of Sharland v Sharland remains the definitive authority on this matter, cementing the principle that “fraud unravels all.” In this case, the Supreme Court ruled that because a settlement was reached based on fraudulent information, it could not stand. This ensures that no person can profit from their own dishonesty during a divorce settlement.

Reopening a Divorce Settlement Years Later

A Consent Order is only as strong as the disclosure it is built upon. If a failure to disclose is discovered years later, the entire settlement can be “set aside,” effectively reopening the case. This forces both parties to restart legal proceedings from scratch, often a decade or more after the original divorce was finalised. The emotional and financial toll of restarting these negotiations is immense. Without full transparency, your settlement remains under a permanent cloud of uncertainty, leaving you vulnerable to future claims that could’ve been avoided with an honest Form E.

What to Do if You Suspect Hidden Assets

If you suspect your spouse is being untruthful, there are robust mechanisms available to uncover the truth. Forensic accountants play a vital role in these investigations, using sophisticated data analysis to identify hidden patterns in spending or undisclosed income streams. They look beyond the standard bank statements already discussed to find where money might’ve been diverted into trusts or offshore holdings. These experts provide the concrete evidence needed to request court-ordered Search Orders or Freezing Injunctions, which prevent the further movement of funds whilst the investigation continues. Feltons Solicitors LLP supports clients in protecting assets during divorce.

If you have concerns about the transparency of your partner’s finances, contact Feltons Solicitors LLP for a confidential discussion about how we can safeguard your financial future.

Expert Guidance: How Feltons Solicitors LLP Organise Your Disclosure

Managing the intricacies of financial disclosure divorce UK is a journey that requires both technical precision and emotional intelligence. At Feltons Solicitors LLP, we adopt a boutique, people-first approach that recognises the individual behind the financial data. We understand that whilst the law demands cold facts and figures, the experience of revealing your private financial life can feel intrusive and stressful. Our role is to act as a calm, steady presence, guiding you through the complexities of the 2026 legal environment with quiet confidence and professional authority.

Our team provides tailored advice for high net worth divorce, where settlements often involve international asset structures, offshore holdings, and sophisticated investment vehicles. We ensure that every aspect of your disclosure is bulletproof. By meticulously organising your financial evidence from the outset, we build a foundation for a settlement that is not only fair but also unchallengeable. This methodical preparation is the most effective way to secure a final order that protects your interests for the long term. Our worldly experience allows us to handle matters of an international scale whilst maintaining the personal rapport of a trusted advisor.

Discreet and Sophisticated Legal Support

Privacy is a cornerstone of our service. We handle sensitive financial data with the utmost discretion, ensuring your personal affairs remain protected throughout the financial disclosure divorce UK process. Our commitment to pragmatic advice means we always seek the most efficient path to a resolution, avoiding unnecessary court escalation whenever possible. We bridge the gap between traditional professional integrity and modern efficiency, using streamlined methodologies to manage complex documentation whilst maintaining the high-standard, personal service our clients expect. This approach ensures that the human impact of our work is never forgotten, even when dealing with the most technical legal requirements.

Taking the Next Step

Securing early legal advice is crucial before you start the disclosure process. This initial stage sets the tone for the entire negotiation. To prepare for your first consultation, it’s helpful to create a rough outline of your assets, liabilities, and any specific concerns you have regarding pensions or business interests. This allows us to provide immediate, focused guidance on your position. It’s often beneficial to gather your most recent bank statements and any known pension valuations to facilitate a more thorough initial discussion.

If you’re ready to move forward, we invite you to contact Feltons Solicitors LLP for a discreet discussion regarding your financial arrangements. Our solicitors are here to provide the sophisticated guidance you need to navigate this transition with security and peace of mind. You don’t have to manage the complexities of disclosure alone; we’re here to ensure you’re in capable hands from the very first step.

Securing Your Financial Independence

Navigating the intricacies of financial disclosure divorce UK is more than a procedural requirement; it’s the foundation of your future independence. By approaching the Form E process with transparency and precision, you ensure that your settlement is both fair and final. As explored throughout this guide, modern assets like digital holdings and complex pension schemes require meticulous valuation to withstand legal scrutiny. A settlement built on full and frank disclosure is the only way to achieve a clean break that remains protected for years to come, avoiding the risk of being set aside in the future.

Since 2010, Paula Felton has led Feltons Solicitors LLP in providing sophisticated, boutique legal support for those managing high net worth and complex financial arrangements. We combine national reach with international expertise to offer a calm, steady presence during life’s most challenging transitions. Secure your financial future with expert guidance from Feltons Solicitors LLP. You deserve the peace of mind that comes from knowing your affairs are in the hands of dedicated specialists who prioritise your long-term well-being and security.

Frequently Asked Questions

Do I have to disclose assets I owned before we were married?

Yes, you must disclose every asset you own, including those acquired long before the marriage took place. Whilst you might argue that these are “non-matrimonial” assets and should be excluded from the final division, they must still be visible to the court. Transparency is the only way to ensure your final settlement is legally robust and protected from future challenges.

What is the “Statement of Truth” on Form E and why does it matter?

The Statement of Truth is a formal declaration at the end of Form E confirming that the information provided is full, accurate, and complete. It carries significant legal weight. If you deliberately omit assets or provide false data, you could face proceedings for contempt of court, which may result in fines or, in extreme cases, imprisonment.

Can my ex-partner see my bank statements during financial disclosure?

Yes, your ex-partner and their legal team have a right to review all documentation provided during the financial disclosure divorce UK process. This includes the mandatory 12 months of bank statements for every account held in your name. This mutual exchange ensures that both parties are negotiating from a position of equal knowledge and transparency.

What happens if I accidentally forget to include an asset in my disclosure?

You must notify your solicitor immediately to rectify any genuine errors or omissions in your paperwork. If an asset is discovered later, it can cast doubt on the integrity of your entire disclosure. The court may choose to “set aside” the final agreement or impose cost penalties, even if the initial omission was entirely accidental.

How much does the financial disclosure process typically cost in the UK?

The cost of disclosure depends on the complexity of your financial arrangements and the level of professional support required. Whilst the court fee for a financial order application is currently £313, total costs will fluctuate if you require specialist business valuations or forensic accounting. Investing in thorough disclosure early on often prevents far more expensive legal challenges in the future.

Do I need to disclose my business accounts if I am the sole director?

Yes, you must disclose all business interests, including accounts for companies where you are the sole director. The court needs to understand the value of the business and any income or capital you could potentially draw from it. This usually involves providing the last two years of accounts and any recent business valuations.

Is financial disclosure required if we have already agreed on how to split everything?

Yes, full disclosure is still necessary even if you’ve reached an informal agreement. To turn your private arrangement into a legally binding Consent Order, a judge must review a summary of your financial positions. This ensures the financial disclosure divorce UK standards have been met and the agreement is fair to both parties.

How far back do I need to go when providing bank statements for divorce?

You are generally required to provide 12 months of statements for every bank account, building society, and ISA held in your name. This “12-month rule” is the standard for Form E. However, if there are specific concerns about unusual transactions or hidden money, the court may order you to provide statements going back much further.