An accident in a public place doesn’t automatically mean you can claim, but you may be entitled to compensation if another party’s negligence caused your injury. Public liability injury claim solicitors can assess whether the circumstances support a claim. In England and Wales, the Occupiers’ Liability Act 1957 places a duty on those responsible for public spaces to take steps to ensure visitors’ reasonable safety, according to UK Parliament.
It’s understandable to be unsure whether your injury is covered or who should be held responsible, particularly when the accident happened in a place open to the public. Personal injury claimants usually have three years from the date of injury to make a claim, according to UK Parliament.
This guide explains who may bring a public liability injury claim, which injuries may be covered and what financial losses compensation could include. It also outlines the time limit and practical steps, helping you assess whether your circumstances may justify taking the matter further.
Key Takeaways
- You may be able to claim if another party’s negligence caused your injury; responsibility for public spaces in England and Wales includes a duty to take reasonable steps to keep visitors safe.
- Personal injury claims usually have a three-year time limit from the date of injury, so understanding when the deadline applies can help you decide what to do next.
- Compensation may account for both the effects of an injury and related financial losses, such as treatment costs or lost earnings.
- Injuries from accidents in public places can vary widely; the circumstances, evidence and impact on your life all help determine whether a claim may be possible.
Who can make a claim for Public Liability Compensation?
You may be able to claim if another party’s negligence caused your injury or property damage in a public place. The key questions are whether they failed to take reasonable care and whether that failure caused the harm.
Understanding public liability injury claims
A public liability injury claim seeks compensation from a person or organisation whose activities or unsafe premises caused injury or property damage. Under the Occupiers’ Liability Act 1957, those responsible for public spaces in England and Wales have a duty to take steps to ensure visitors’ reasonable safety, according to UK Parliament. There is no fixed settlement timetable: liability, medical recovery, available evidence and negotiations affect how long resolution takes. Rules are not uniform across the UK; this Act applies to England and Wales, so the law relevant to an accident in Scotland or Northern Ireland may differ.
Accident settings and unsafe conditions
Claims may arise in shops, restaurants, leisure venues, car parks, other business premises or public spaces. Examples include slipping on an unmarked wet floor, tripping over damaged paving or being struck by falling stock. The location alone does not establish responsibility. The issue is whether an unsafe condition caused the accident and injury.
After an accident, report it promptly to the manager, owner or relevant authority. Ask for the incident to be recorded, and note the date, time and precise location. If you can, photograph the hazard and surrounding area before conditions change. For a pavement defect, a 10p or 50p coin beside the hole can help show its depth or height.
Keep details that may help explain what happened and its consequences:
- Witness names and addresses, plus any account they provide.
- Medical records and details of treatment, including a GP visit or hospital attendance.
- Receipts for prescriptions, travel to treatment and damaged belongings.
Members of the public may claim where another party’s negligence caused their harm. A court-appointed litigation friend can act for someone under 18 or someone unable to claim themselves, acting in that person’s best interests. These records help lawyers assess responsibility and support the account of the accident.
Personal injury claim time limits
For most public liability personal injury claims, the usual deadline is three years from the date of injury. The starting point can differ in some circumstances, including clinical negligence claims and claims involving children.
The time limit for making a claim
Personal injury claimants usually have three years from the date of injury to start a public liability claim, according to UK Parliament. The deadline concerns starting legal proceedings, not completing treatment or recovery. Record when the accident happened, when symptoms began and how your condition developed. If the cause of an injury became clear later, the date you became aware of it may affect the calculation.
Claim time limits and exceptions
Children have a different deadline: they have three years from their 18th birthday to make a public liability claim, according to UK Parliament. The applicable deadline for a claim made on behalf of someone who has died may depend on the circumstances. These rules make the claimant’s age and circumstances central when working out the relevant deadline.
Clinical negligence has a stated limitation period of three years from the event that caused the injury or illness, or from when the claimant became aware that the event caused harm. For example, someone may connect an ongoing injury with earlier treatment only after receiving later medical information. The event date and date of awareness are therefore important when assessing this type of claim.
Funding arrangements do not extend a limitation period, so keep the deadline in mind while considering how to fund a liability compensation claim. In England, under a conditional fee agreement, the solicitor receives no fees if the claimant loses, although the claimant may still have to pay the other side’s legal fees and expenses. If the claim succeeds, arrangements for paying the solicitor’s fees and expenses depend on the funding agreement.
Some house contents, car or travel insurance policies in England include legal expenses cover that may help with personal injury legal costs. Review the policy wording for the type of claim covered and any conditions. Personal injury claim advice can help clarify the relevant deadline and funding arrangement.
Compensation for injury and financial losses
A compensation claim may cover the injury’s effects and financial losses caused by the accident. The amount depends on the injury, recovery and evidence supporting each loss.
Compensation amounts for injuries
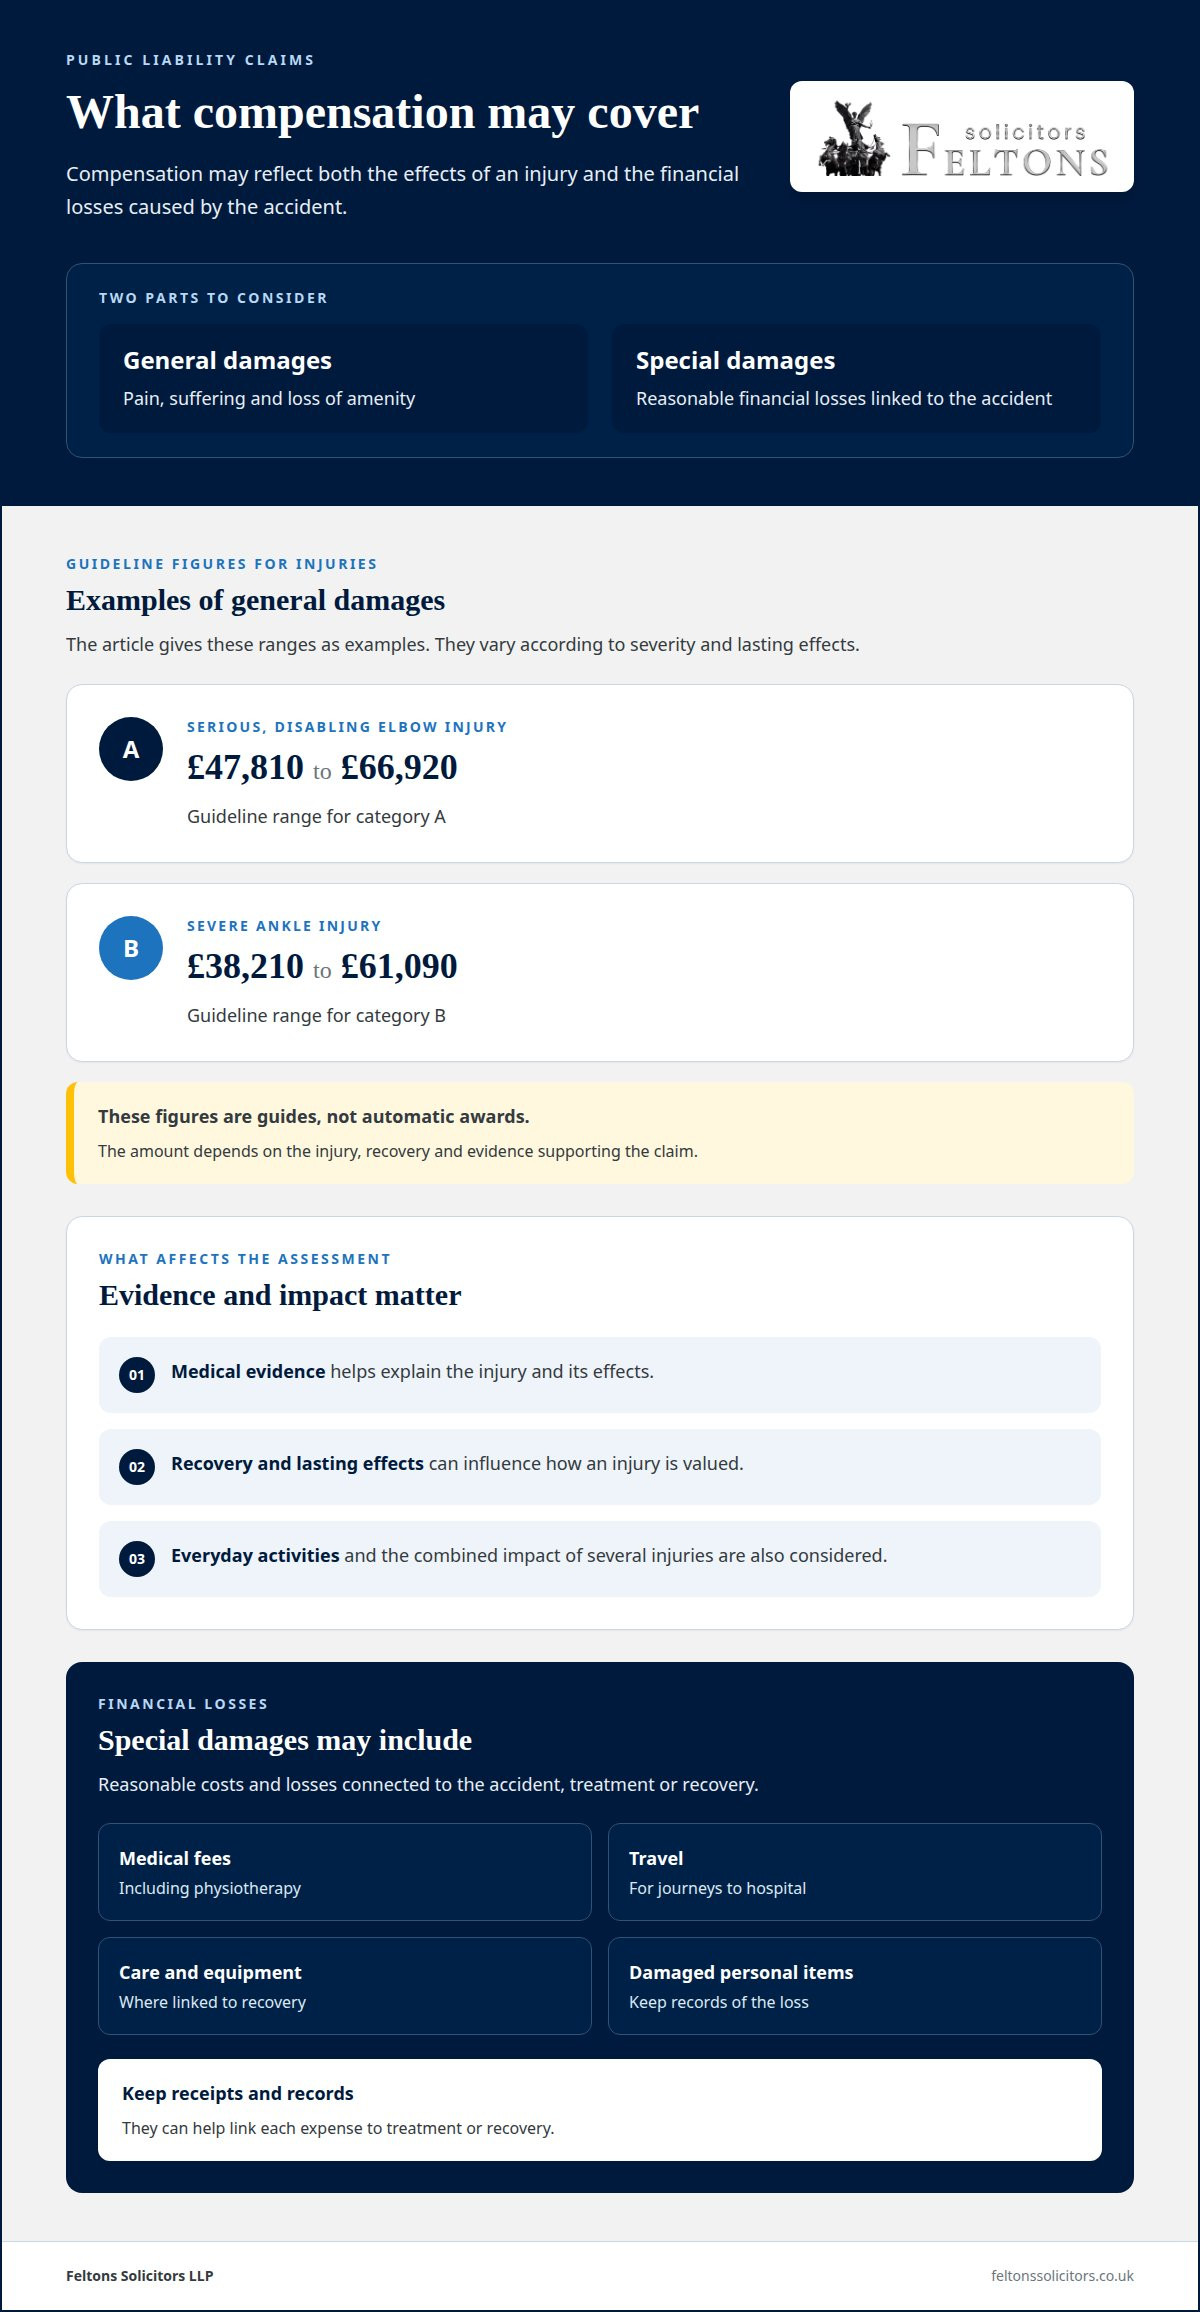
General damages reflect pain, suffering and loss of amenity. Guideline figures vary with the injury’s severity and lasting effects. For example, a serious, disabling elbow injury in category A has a guideline range of £47,810 to £66,920. A severe ankle injury in category B has a range of £38,210 to £61,090. These figures are guides, not automatic awards.
The assessment considers medical evidence, recovery and the effect on everyday activities. A fracture with continuing symptoms may be valued differently from an injury that heals fully. If several injuries occur together, their combined impact also matters.
Losses and expenses
Special damages may cover reasonable financial losses linked to the accident, such as medical fees, physiotherapy, travel to hospital, care, equipment and damaged personal items. Keep receipts and records linking each expense to treatment or recovery. For serious injuries, an assessment may also consider care needs, home adaptations and future costs.
Compensation for loss of earnings
If an injury stops you working, lost earnings may form part of your claim. Evidence could include payslips, employer records and details of time away from work. If a serious injury affects your future employment, the assessment may also consider future salary and pension losses. It looks at how the injury changed your ability to work, not simply how many days you missed.
Factors affecting compensation
The injury’s severity, recovery, treatment needs and effect on daily life all influence compensation. Evidence of expenses and earnings helps show the financial impact. Responsibility matters too: where a claimant is equally responsible for the accident or injury, the payout may be reduced by 50%. The organisation’s role, the available evidence and the connection between the accident and each loss are also relevant to the overall assessment.
Injuries covered by public liability claims
No single injury type automatically qualifies for public liability compensation. The central issue is whether another party’s negligence caused the harm and whether evidence supports that connection. A relatively minor injury can have lasting effects, while a serious diagnosis alone does not establish responsibility.
Claims may involve physical injuries suffered in shops, restaurants, car parks or public walkways. Examples include a sprained ankle after a fall, a fracture caused by a trip or a head injury from falling stock. Back, wrist, knee and elbow injuries can also affect movement, work and everyday activities. The circumstances and consequences matter as well as the medical diagnosis.
Slips and impacts can cause soft tissue injuries, bruising and strains. More serious accidents may cause brain injuries, significant fractures or lasting disability. Rest, ice, compression and elevation are often advised for minor strains, bruises and soft tissue injuries. Medical records can document the injury, treatment and recovery, showing how the harm developed after the accident.
To assess a claim, a specialist considers how the accident happened, what condition caused it and how the injury affected you. For example, evidence of a damaged step alongside medical notes recording an ankle fracture may help establish a clear sequence. Witness accounts, photographs, incident reports and treatment records can each support different parts of your account.
Evidence should capture practical consequences as well as the diagnosis. Note changes to walking, sleep, caring responsibilities or paid work, and keep receipts for treatment, travel and other related expenses. These details help explain the injury’s impact and identify associated losses. Public liability injury solicitors can assess how the available evidence supports your claim.
Discuss your public liability injury claim to understand how the injury, its cause and supporting evidence can be assessed together.
Feltons Solicitors LLP: Personal Injury and Silicosis Claims
Feltons Solicitors LLP handles personal injury and silicosis claims, including cases arising from accidents in public places or business premises. Our solicitors can assess the circumstances, available evidence and effects on your health and daily life, helping clarify the issues involved.
If you are considering whether to proceed, Feltons Solicitors LLP can explain the legal process and the information relevant to assessing your claim. This can help you weigh the next steps with a clearer understanding of your position.
For advice about a potential personal injury claim, contact Feltons Solicitors LLP.
Take the next step with a clearer picture
After an accident, uncertainty about responsibility, evidence or the effect on your future can make it difficult to decide what to do. A focused legal assessment can bring these issues together and identify practical next steps for your circumstances.
Feltons Solicitors LLP can consider how the accident occurred, the available records and the impact on your health and everyday life. This gives you a clearer basis for deciding whether to pursue a claim and what information may be relevant. The strength and value of any claim depend on its individual facts.
Feltons Solicitors LLP handles personal injury and silicosis claims. If you would like to discuss your situation and understand the options available, contact Feltons Solicitors LLP. Taking that conversation at your own pace can help you make an informed decision about what comes next.
Frequently Asked Questions
What injuries can I claim for?
You may be able to claim for a physical injury caused by another party’s negligence, but a diagnosis alone does not establish liability. A shoulder injury from an unsecured barrier or a burn caused by unsafe equipment could be considered if evidence links the hazard to your harm. The injury’s severity, duration and effects on everyday activities help shape the assessment. Medical records can document symptoms and treatment.
How are public liability accident injuries treated?
Treatment depends on the injury and its clinical needs. A healthcare professional may assess symptoms, recommend treatment and arrange follow-up. More serious injuries may need specialist care or rehabilitation. Keep appointment letters, treatment plans and records of changes in your condition. For example, notes about restricted movement after a shoulder injury can show how symptoms affected daily tasks over time.
Can I claim if the accident was partly my fault?
A claim may still be possible if you shared responsibility for the accident. Compensation may be reduced to reflect your share of fault, so evidence about each person’s actions matters. For instance, investigators may consider whether a hazard was clearly marked and whether your actions contributed to the incident. Give an accurate account, including details that may not seem favourable.
How do I find the right solicitor?
Look for a solicitor with relevant personal injury experience and a clear understanding of public liability cases. In England, the Law Society’s personal injury accreditation scheme is one relevant credential to consider. Ask how the solicitor will assess responsibility, gather evidence and keep you informed. A useful initial discussion should explain the proposed approach in plain English and identify the information needed to assess your circumstances.
How much compensation will I receive?
There is no single award for a particular accident. Compensation depends on the injury and its consequences, including medical evidence, recovery, restrictions on daily life and documented financial losses. For example, two people with similar fractures may have different claims if one quickly returns to normal activities while the other needs continuing care or can no longer do their usual work.
How much do I have to pay to pursue a claim?
What you pay depends on the funding agreement and its terms. Under a conditional fee agreement in England, a solicitor receives no fees if the claim is unsuccessful, but you may still be responsible for the other side’s legal fees and expenses. If you win, the other side will normally pay the solicitor’s fees and expenses. Read the agreement carefully to understand your position.