Public liability injury claims and who can claim compensation

Public liability injury claims and who can claim compensation

An accident in a public place doesn’t automatically mean you can claim, but you may be entitled to compensation if another party’s negligence caused your injury. Public liability injury claim solicitors can assess whether the circumstances support a claim. In England and Wales, the Occupiers’ Liability Act 1957 places a duty on those responsible for public spaces to take steps to ensure visitors’ reasonable safety, according to UK Parliament.

It’s understandable to be unsure whether your injury is covered or who should be held responsible, particularly when the accident happened in a place open to the public. Personal injury claimants usually have three years from the date of injury to make a claim, according to UK Parliament.

This guide explains who may bring a public liability injury claim, which injuries may be covered and what financial losses compensation could include. It also outlines the time limit and practical steps, helping you assess whether your circumstances may justify taking the matter further.

Key Takeaways

  • You may be able to claim if another party’s negligence caused your injury; responsibility for public spaces in England and Wales includes a duty to take reasonable steps to keep visitors safe.
  • Personal injury claims usually have a three-year time limit from the date of injury, so understanding when the deadline applies can help you decide what to do next.
  • Compensation may account for both the effects of an injury and related financial losses, such as treatment costs or lost earnings.
  • Injuries from accidents in public places can vary widely; the circumstances, evidence and impact on your life all help determine whether a claim may be possible.

Who can make a claim for Public Liability Compensation?

You may be able to claim if another party’s negligence caused your injury or property damage in a public place. The key questions are whether they failed to take reasonable care and whether that failure caused the harm.

Understanding public liability injury claims

A public liability injury claim seeks compensation from a person or organisation whose activities or unsafe premises caused injury or property damage. Under the Occupiers’ Liability Act 1957, those responsible for public spaces in England and Wales have a duty to take steps to ensure visitors’ reasonable safety, according to UK Parliament. There is no fixed settlement timetable: liability, medical recovery, available evidence and negotiations affect how long resolution takes. Rules are not uniform across the UK; this Act applies to England and Wales, so the law relevant to an accident in Scotland or Northern Ireland may differ.

Accident settings and unsafe conditions

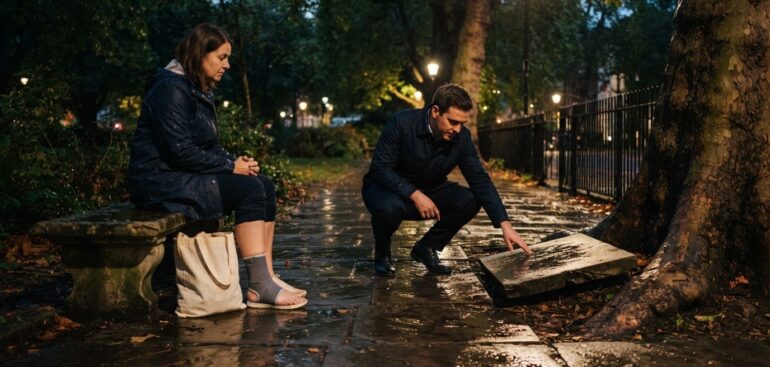
Claims may arise in shops, restaurants, leisure venues, car parks, other business premises or public spaces. Examples include slipping on an unmarked wet floor, tripping over damaged paving or being struck by falling stock. The location alone does not establish responsibility. The issue is whether an unsafe condition caused the accident and injury.

After an accident, report it promptly to the manager, owner or relevant authority. Ask for the incident to be recorded, and note the date, time and precise location. If you can, photograph the hazard and surrounding area before conditions change. For a pavement defect, a 10p or 50p coin beside the hole can help show its depth or height.

Keep details that may help explain what happened and its consequences:

  • Witness names and addresses, plus any account they provide.
  • Medical records and details of treatment, including a GP visit or hospital attendance.
  • Receipts for prescriptions, travel to treatment and damaged belongings.

Members of the public may claim where another party’s negligence caused their harm. A court-appointed litigation friend can act for someone under 18 or someone unable to claim themselves, acting in that person’s best interests. These records help lawyers assess responsibility and support the account of the accident.

Personal injury claim time limits

For most public liability personal injury claims, the usual deadline is three years from the date of injury. The starting point can differ in some circumstances, including clinical negligence claims and claims involving children.

The time limit for making a claim

Personal injury claimants usually have three years from the date of injury to start a public liability claim, according to UK Parliament. The deadline concerns starting legal proceedings, not completing treatment or recovery. Record when the accident happened, when symptoms began and how your condition developed. If the cause of an injury became clear later, the date you became aware of it may affect the calculation.

Claim time limits and exceptions

Children have a different deadline: they have three years from their 18th birthday to make a public liability claim, according to UK Parliament. The applicable deadline for a claim made on behalf of someone who has died may depend on the circumstances. These rules make the claimant’s age and circumstances central when working out the relevant deadline.

Clinical negligence has a stated limitation period of three years from the event that caused the injury or illness, or from when the claimant became aware that the event caused harm. For example, someone may connect an ongoing injury with earlier treatment only after receiving later medical information. The event date and date of awareness are therefore important when assessing this type of claim.

Funding arrangements do not extend a limitation period, so keep the deadline in mind while considering how to fund a liability compensation claim. In England, under a conditional fee agreement, the solicitor receives no fees if the claimant loses, although the claimant may still have to pay the other side’s legal fees and expenses. If the claim succeeds, arrangements for paying the solicitor’s fees and expenses depend on the funding agreement.

Some house contents, car or travel insurance policies in England include legal expenses cover that may help with personal injury legal costs. Review the policy wording for the type of claim covered and any conditions. Personal injury claim advice can help clarify the relevant deadline and funding arrangement.
Public liability injury claims and who can claim compensation

Compensation for injury and financial losses

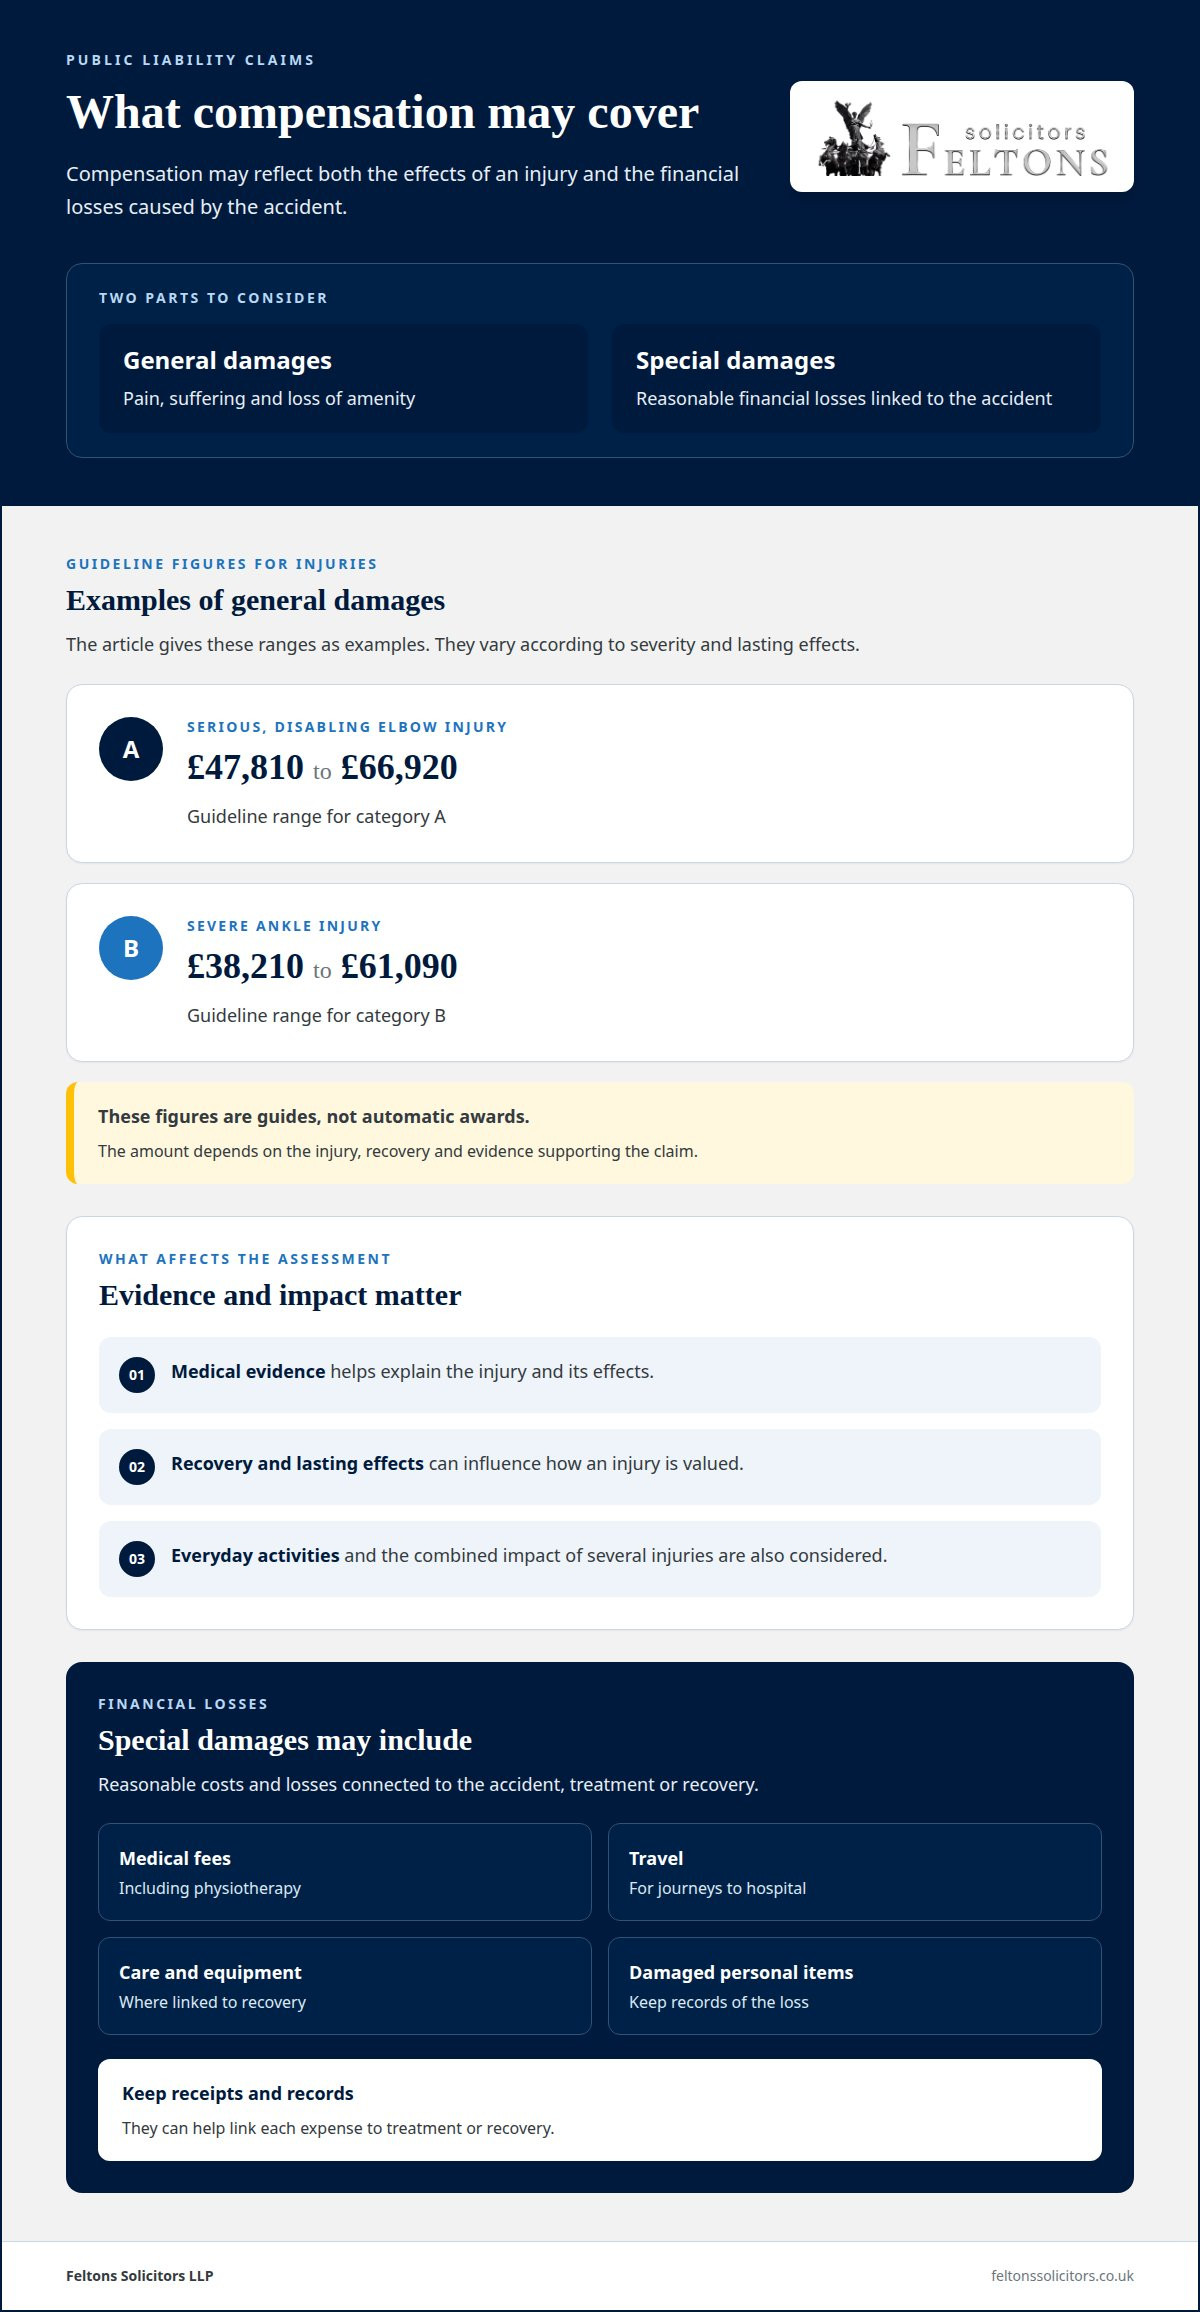
A compensation claim may cover the injury’s effects and financial losses caused by the accident. The amount depends on the injury, recovery and evidence supporting each loss.

Compensation amounts for injuries

General damages reflect pain, suffering and loss of amenity. Guideline figures vary with the injury’s severity and lasting effects. For example, a serious, disabling elbow injury in category A has a guideline range of £47,810 to £66,920. A severe ankle injury in category B has a range of £38,210 to £61,090. These figures are guides, not automatic awards.

The assessment considers medical evidence, recovery and the effect on everyday activities. A fracture with continuing symptoms may be valued differently from an injury that heals fully. If several injuries occur together, their combined impact also matters.

Losses and expenses

Special damages may cover reasonable financial losses linked to the accident, such as medical fees, physiotherapy, travel to hospital, care, equipment and damaged personal items. Keep receipts and records linking each expense to treatment or recovery. For serious injuries, an assessment may also consider care needs, home adaptations and future costs.

Compensation for loss of earnings

If an injury stops you working, lost earnings may form part of your claim. Evidence could include payslips, employer records and details of time away from work. If a serious injury affects your future employment, the assessment may also consider future salary and pension losses. It looks at how the injury changed your ability to work, not simply how many days you missed.

Factors affecting compensation

The injury’s severity, recovery, treatment needs and effect on daily life all influence compensation. Evidence of expenses and earnings helps show the financial impact. Responsibility matters too: where a claimant is equally responsible for the accident or injury, the payout may be reduced by 50%. The organisation’s role, the available evidence and the connection between the accident and each loss are also relevant to the overall assessment.

Injuries covered by public liability claims

No single injury type automatically qualifies for public liability compensation. The central issue is whether another party’s negligence caused the harm and whether evidence supports that connection. A relatively minor injury can have lasting effects, while a serious diagnosis alone does not establish responsibility.

Claims may involve physical injuries suffered in shops, restaurants, car parks or public walkways. Examples include a sprained ankle after a fall, a fracture caused by a trip or a head injury from falling stock. Back, wrist, knee and elbow injuries can also affect movement, work and everyday activities. The circumstances and consequences matter as well as the medical diagnosis.

Slips and impacts can cause soft tissue injuries, bruising and strains. More serious accidents may cause brain injuries, significant fractures or lasting disability. Rest, ice, compression and elevation are often advised for minor strains, bruises and soft tissue injuries. Medical records can document the injury, treatment and recovery, showing how the harm developed after the accident.

To assess a claim, a specialist considers how the accident happened, what condition caused it and how the injury affected you. For example, evidence of a damaged step alongside medical notes recording an ankle fracture may help establish a clear sequence. Witness accounts, photographs, incident reports and treatment records can each support different parts of your account.

Evidence should capture practical consequences as well as the diagnosis. Note changes to walking, sleep, caring responsibilities or paid work, and keep receipts for treatment, travel and other related expenses. These details help explain the injury’s impact and identify associated losses. Public liability injury solicitors can assess how the available evidence supports your claim.

Discuss your public liability injury claim to understand how the injury, its cause and supporting evidence can be assessed together.

Feltons Solicitors LLP: Personal Injury and Silicosis Claims

Feltons Solicitors LLP handles personal injury and silicosis claims, including cases arising from accidents in public places or business premises. Our solicitors can assess the circumstances, available evidence and effects on your health and daily life, helping clarify the issues involved.

If you are considering whether to proceed, Feltons Solicitors LLP can explain the legal process and the information relevant to assessing your claim. This can help you weigh the next steps with a clearer understanding of your position.

For advice about a potential personal injury claim, contact Feltons Solicitors LLP.

Take the next step with a clearer picture

After an accident, uncertainty about responsibility, evidence or the effect on your future can make it difficult to decide what to do. A focused legal assessment can bring these issues together and identify practical next steps for your circumstances.

Feltons Solicitors LLP can consider how the accident occurred, the available records and the impact on your health and everyday life. This gives you a clearer basis for deciding whether to pursue a claim and what information may be relevant. The strength and value of any claim depend on its individual facts.

Feltons Solicitors LLP handles personal injury and silicosis claims. If you would like to discuss your situation and understand the options available, contact Feltons Solicitors LLP. Taking that conversation at your own pace can help you make an informed decision about what comes next.

Frequently Asked Questions

What injuries can I claim for?

You may be able to claim for a physical injury caused by another party’s negligence, but a diagnosis alone does not establish liability. A shoulder injury from an unsecured barrier or a burn caused by unsafe equipment could be considered if evidence links the hazard to your harm. The injury’s severity, duration and effects on everyday activities help shape the assessment. Medical records can document symptoms and treatment.

How are public liability accident injuries treated?

Treatment depends on the injury and its clinical needs. A healthcare professional may assess symptoms, recommend treatment and arrange follow-up. More serious injuries may need specialist care or rehabilitation. Keep appointment letters, treatment plans and records of changes in your condition. For example, notes about restricted movement after a shoulder injury can show how symptoms affected daily tasks over time.

Can I claim if the accident was partly my fault?

A claim may still be possible if you shared responsibility for the accident. Compensation may be reduced to reflect your share of fault, so evidence about each person’s actions matters. For instance, investigators may consider whether a hazard was clearly marked and whether your actions contributed to the incident. Give an accurate account, including details that may not seem favourable.

How do I find the right solicitor?

Look for a solicitor with relevant personal injury experience and a clear understanding of public liability cases. In England, the Law Society’s personal injury accreditation scheme is one relevant credential to consider. Ask how the solicitor will assess responsibility, gather evidence and keep you informed. A useful initial discussion should explain the proposed approach in plain English and identify the information needed to assess your circumstances.

How much compensation will I receive?

There is no single award for a particular accident. Compensation depends on the injury and its consequences, including medical evidence, recovery, restrictions on daily life and documented financial losses. For example, two people with similar fractures may have different claims if one quickly returns to normal activities while the other needs continuing care or can no longer do their usual work.

How much do I have to pay to pursue a claim?

What you pay depends on the funding agreement and its terms. Under a conditional fee agreement in England, a solicitor receives no fees if the claim is unsuccessful, but you may still be responsible for the other side’s legal fees and expenses. If you win, the other side will normally pay the solicitor’s fees and expenses. Read the agreement carefully to understand your position.
How to claim compensation for a defective product injury

How to claim compensation for a defective product injury

Defective product injury compensation claims may be possible if an unsafe product caused your injury. In the UK, a personal injury claim generally must be brought within three years of the injury or of becoming aware that it was connected to a specific defective product, according to The National Archives. A product may be defective because of its design, manufacture or inadequate warnings about hazards or safe use.

After an injury, it can be difficult to tell whether a product fault caused it and what to do with the product and paperwork. The evidence you preserve can help show what went wrong, how you were injured and who may be responsible.

This guide explains when you may have a claim, what evidence can support it and how liability may depend on the circumstances. It covers product liability, negligence and personal injury claims, as well as the usual steps from an initial letter to negotiations or court proceedings.

Key Takeaways

  • Assess whether the product may have been unsafe and who could be responsible for the harm.
  • Preserve the product and gather records, photographs and witness details that may support your account.
  • Understand how the legal route can depend on whether you bought the product and the type of loss involved.
  • Learn how Feltons Solicitors LLP can assist with personal injury claims and what may happen as a claim progresses.

Can I make a product liability claim?

Start by identifying the suspected defect, the businesses connected to the product and the harm it caused. These details can help establish whether you may have a claim and who could be responsible.

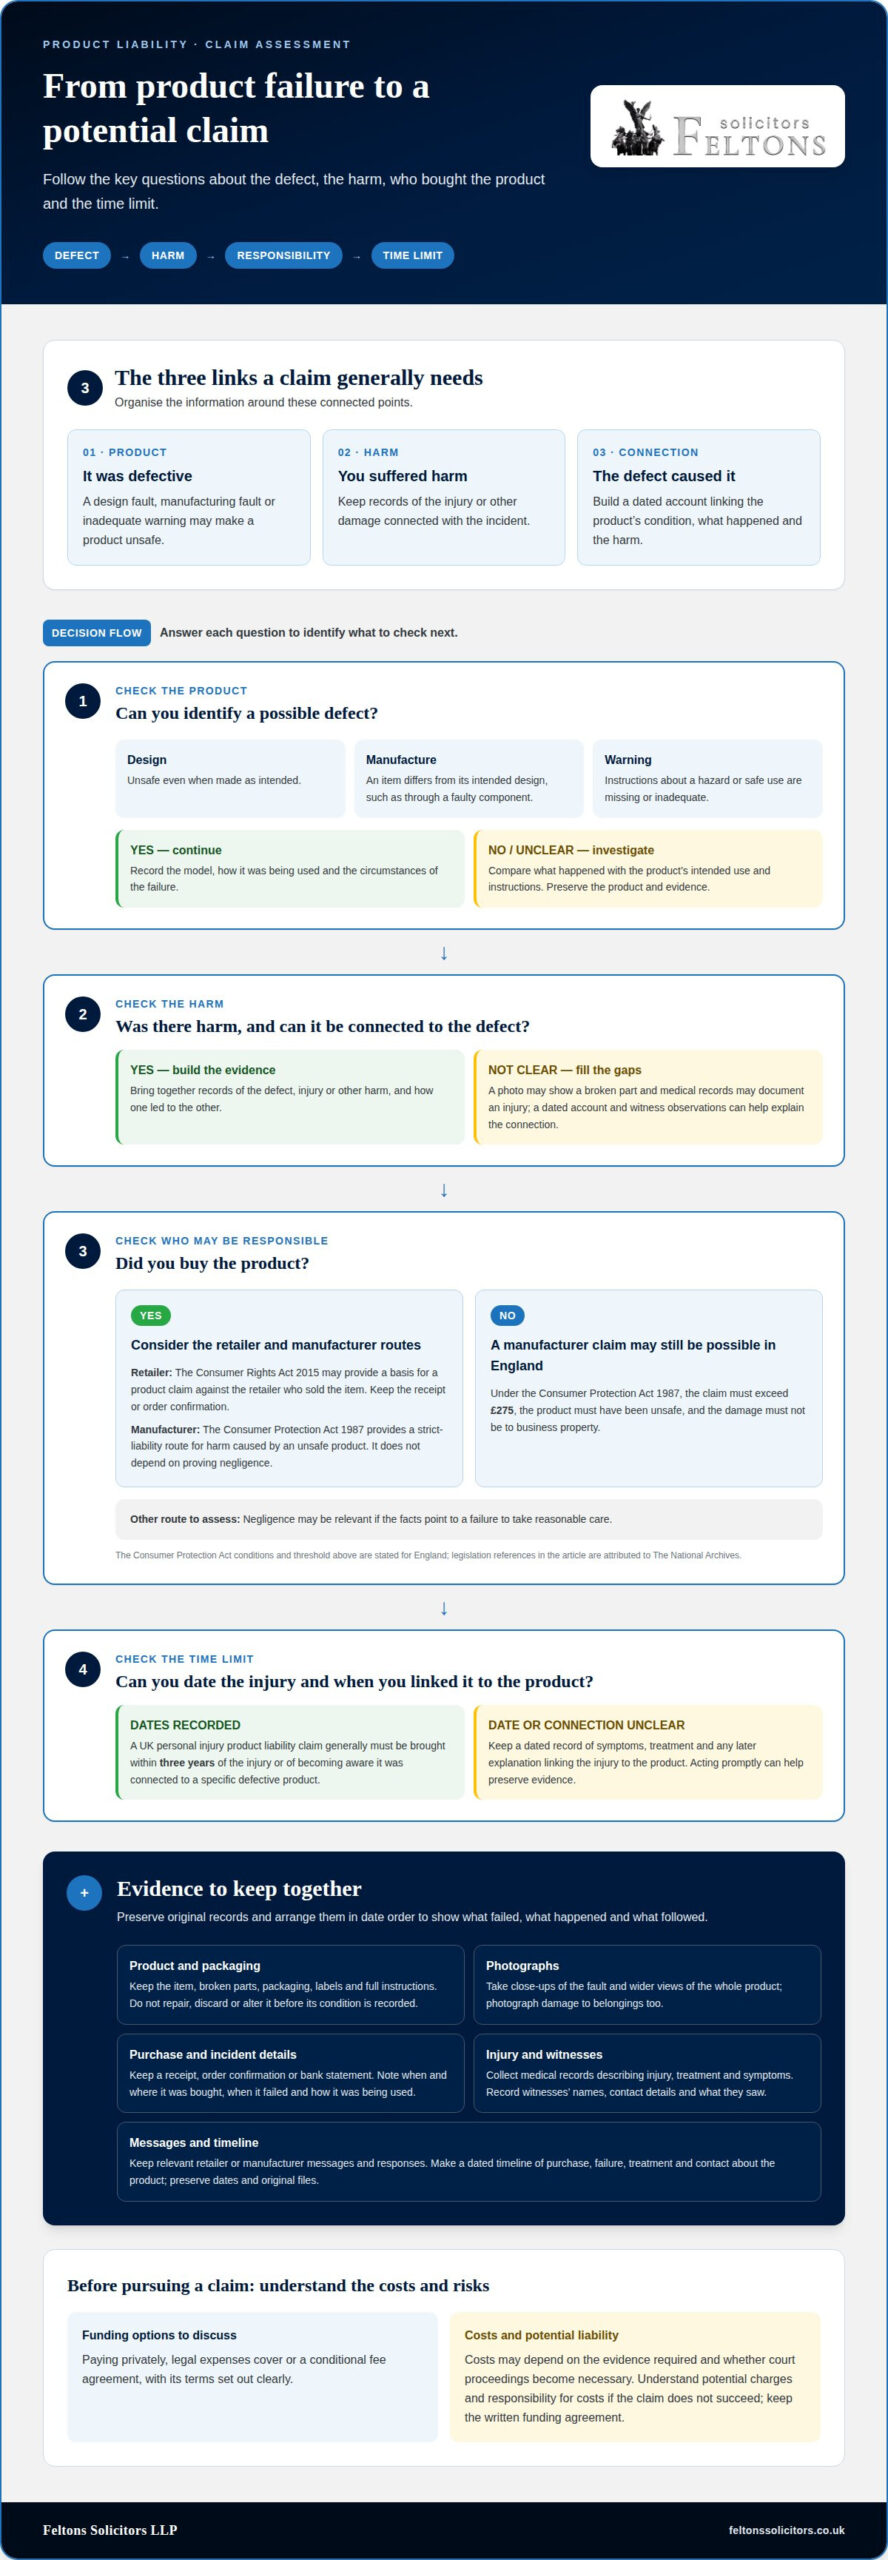
  1. Identify the type of product defect

    Describe what went wrong and compare it with how the product was intended to work. A design defect may make a product unsafe even when manufactured correctly. A manufacturing defect occurs when an individual item differs from its intended design, such as through a faulty component. A warning defect may involve missing or inadequate instructions about a hazard or safe use. Record the product model and the circumstances of the failure.

  2. Identify potentially liable manufacturers, importers or suppliers

    Trace the product’s route from maker to seller using its packaging, labels, instructions and purchase records. The manufacturer may be liable if an unsafe product caused harm. Importers and suppliers may also help identify responsible businesses and the product’s route into the UK. Keep their names and addresses where available.

    In England, a person who did not buy the product may claim compensation from its manufacturer under the Consumer Protection Act 1987 if the claim exceeds £275, the product was unsafe and the damage was not to business property, according to The National Archives (UK legislation). For consumer help in England, contact the Citizens Advice consumer helpline on 0808 223 1133.

  3. Check the claim time limit

    Note the injury date and when you first connected it to the product. A UK personal injury product liability claim generally must be brought within three years of the injury or of becoming aware that it was connected to a specific defective product, according to The National Archives. Keep a dated record of symptoms, treatment and any later explanation linking the injury to the product. Acting promptly can also help preserve evidence.

  4. Review costs, funding options and risks

    Before pursuing a claim, establish what the legal work may cost and which funding route applies. Options to discuss include paying privately, using legal expenses cover or entering a conditional fee agreement, with its terms set out clearly. Costs may depend on the evidence required and whether court proceedings become necessary.

    Consider the financial risk if the claim does not succeed, including responsibility for costs under the agreed funding terms. Ask for a clear explanation of potential charges and liabilities before authorising work, and keep the written agreement for reference.

Evidence to support a claim

Build a clear record connecting the product, the fault and your injury. A UK claim generally needs evidence that the product was defective, you suffered harm and the defect caused it.

  1. Collect evidence to support the claim

    Keep the product, packaging, instructions, labels and any broken parts. Don’t repair, discard or alter the product before its condition has been recorded. If keeping it is impractical, take clear photographs from several angles, including close-ups of the defect and wider shots showing the whole product.

    Gather proof of purchase, such as a receipt, order confirmation or bank statement. Record when and where you bought the item, when it failed and what happened next. Write down the sequence while details are fresh, including how you were using the product and any visible damage to belongings. Photograph that damage too.

    Collect medical records describing your injury, treatment and symptoms. Ask witnesses for their names and contact details, then note what each person saw. Keep relevant messages with the retailer or manufacturer, including reports of the fault and their responses. Store copies together, preserving dates and original files.

  2. Establish what must be proved

    Organise the evidence around three points: the product was defective, you suffered injury or other harm, and the defect caused that harm. A photograph of a broken component may show its condition, while medical records document an injury. Neither necessarily explains how the failure happened, so link the evidence with a dated account and witness observations.

    Compare the product’s condition with its instructions and intended use. Note, for example, whether a part failed during ordinary use or whether a warning about the hazard was missing. Keep the full instructions, as a single page may lack important context. Create a simple timeline covering purchase, failure, medical treatment and any contact about the product.

    Presenting these records in order can clarify the connection between defect and injury. For help assessing evidence for an injury claim, you can explore personal injury claims.

How to claim compensation for a defective product injury

Negligence, breach of contract and strict liability

Identify the legal route that best fits your relationship to the product, the fault and the loss. In the UK, a product claim may rely on consumer rights, strict liability or negligence.

  1. Consider a claim against the retailer under the Consumer Rights Act 2015, which The National Archives (UK legislation) identifies as a basis for a product claim against the retailer that sold the item. This route focuses on the purchase and the retailer’s obligations. Keep the receipt or order confirmation, and describe how the product failed to meet the standard you expected. For example, a newly purchased appliance that stops working because of a faulty component may raise a retailer claim.
  2. Consider strict liability under the Consumer Protection Act 1987 when an unsafe product caused harm. This route does not depend on proving that the manufacturer was negligent, but the claim still needs evidence of a defect, damage and a connection between them. A manufacturer claim may be relevant even if you were not the buyer. Whether you can include the product’s cost in a compensation claim may depend on the circumstances of the claim.
  3. Assess negligence if the facts point to a failure to take reasonable care, such as a manufacturer overlooking a safety issue during production. A negligence claim requires proof of negligence, so identify the conduct or omission and how it caused the harm. If you did not buy the product and the claim is below £275, you may claim through negligence for damage caused by it against either the manufacturer or seller. Gather evidence that connects the relevant business, its conduct and the damage.

Separate the product’s purchase cost from other losses when organising your claim. A refund or replacement affects whether you can also claim the item’s cost. The legal basis determines what must be established against the retailer, manufacturer or seller.

Personal injury claims

An injury caused by a product is pursued as a personal injury claim. Set out the physical impact separately from financial losses so each can be assessed clearly.

  1. Identify the compensation that can be claimed

    List the injury’s effects and resulting costs, including medical expenses and earnings lost because you could not work. Keep bills, appointment records and payslips together, and note how each expense relates to the injury. For example, record travel to treatment separately from a routine journey.

    In defective product injury compensation claims, include ongoing needs, such as treatment or support you still require, and explain how the injury affects everyday activities. Someone who did not buy the faulty product may claim for damage and distress, but not the product’s own cost. Keep the product price separate from injury-related losses, especially if you have received a refund or replacement.

  2. Calculate the compensation amount

    Prepare a schedule of losses listing each expense, its date and the document that supports it. Include lost earnings with records showing income before and after the injury, and distinguish actual losses from future costs. A clear breakdown explains how the injury affected your finances without relying on an unsupported total.

    An assessment considers the injury and its effects alongside related financial losses. The nature and duration of symptoms, treatment, recovery and impact on daily life help describe the injury; receipts and employment records support expenses and lost earnings. Compensation for a defective product injury depends on the evidence and consequences, so no single figure applies to every case.

    A UK product liability claim may proceed through a letter of claim, compensation negotiations and, if needed, court proceedings where a judge decides compensation. For help pursuing an injury claim, discuss your personal injury claim with a solicitor.

Feltons Solicitors LLP: Personal Injury and Silicosis Claims

Feltons Solicitors LLP handles personal injury claims, including injuries caused by defective products. If you have been hurt and need help understanding a potential claim, the evidence or the compensation process, the firm can assist with the legal aspects.

Share the key details of what happened, the injury and the product involved. Relevant records, including medical documents, photographs and proof of purchase, can help clarify the circumstances and losses claimed. A solicitor can assess how the evidence relates to liability and the next steps in pursuing a claim.

For legal support with a personal injury claim, contact Feltons Solicitors LLP to discuss your situation.

Consider your next step

After an injury, deciding whether to pursue a claim can be difficult while you manage treatment and its effects on daily life. Advice on defective product injury compensation claims can help you understand how the evidence and circumstances relate to your options, and what information may be needed to move forward.

Before speaking to a solicitor, gather the records you have and note any questions about the injury, product or impact on your work and routine. You do not need to resolve every detail before seeking guidance. A focused discussion can clarify the legal issues and practical next steps for your situation.

Feltons Solicitors LLP also assists with divorce and financial arrangements, wills, probate and estate planning, and residential and commercial conveyancing. To discuss an injury claim, contact Feltons Solicitors LLP. Taking a considered next step can help you approach the process with greater clarity.

Frequently Asked Questions

What counts as a defective product under UK law?

A product may be defective if its design, manufacture or warnings make it unsafe. The assessment concerns product safety, not simply whether an item stopped working or disappointed you. For example, a component that breaks during intended use may raise a safety issue, while ordinary wear may not. The product’s instructions, purpose and circumstances of use help explain the difference.

Who can claim compensation for an injury caused by a defective product in the UK?

A person injured by an unsafe product may be able to claim even if they did not buy it. Under the Consumer Protection Act 1987, The National Archives (UK legislation) states that a non-buyer may claim against the manufacturer where the claim exceeds £275, the product was unsafe and the damage was not to business property. The appropriate defendant and legal route depend on the facts.

What evidence is needed to support a defective product injury claim?

Useful evidence includes the product, proof of purchase, photographs of the fault, medical records and witness details. Keep digital records too, such as order confirmations, messages to the retailer and the manufacturer’s response. For example, a dated photograph alongside a treatment record may help establish when the failure happened and when the injury was documented. Preserve original files and keep copies of records.

How do you make a defective product injury claim in England and Wales, Scotland or Northern Ireland?

Start by documenting the incident, seeking medical attention and keeping evidence of the injury and product. A UK product liability claim may then proceed through a letter of claim, compensation negotiations and, if needed, court proceedings where a judge decides compensation. The legal process and rules can differ between England and Wales, Scotland, and Northern Ireland, so take advice relevant to where the claim is brought.

Can a consumer claim under the Consumer Protection Act 1987 as well as the Consumer Rights Act 2015?

These Acts provide different potential routes: the Consumer Protection Act 1987 may support a claim against a manufacturer for harm caused by an unsafe product, while the Consumer Rights Act 2015 may support a claim against the retailer that sold it. The National Archives (UK legislation) identifies the latter as a basis for a retailer claim. Which route applies depends on the product, injury and parties involved.

Construction Accident Claims Solicitors in the UK

Construction Accident Claims Solicitors in the UK

The deadline matters: in England and Wales, the standard time limit for a construction accident claim is three years from the date of the accident under the Limitation Act 1980. If negligence contributed to your injury, you may be able to seek compensation. Construction accident claims solicitors in the UK can help assess the circumstances and explain the steps involved.

After a construction accident, it’s understandable to be unsure what to do first, particularly when you’re dealing with treatment, time off work or uncertainty about who was responsible. Acting promptly can help preserve useful evidence and keep a potential claim on track.

This guide explains how construction accident claims work, what may amount to negligence, which time limits apply and what practical steps to take after an accident. It also explains how a solicitor can help gather evidence and progress a claim.

Key Takeaways

  • Identify whether unsafe practices, equipment or site conditions may have contributed to your injury and who was responsible.
  • Report the incident, seek medical attention and preserve useful evidence, including photographs and witness details.
  • Understand how the claims process moves from gathering evidence and assessing responsibility to negotiating a resolution.
  • A solicitor can help organise the evidence and explain the practical steps involved in pursuing a personal injury claim.

What is a construction injury compensation claim?

A construction injury compensation claim seeks damages after a worksite injury caused by someone else’s negligence. The Construction (Design and Management) Regulations 2015 are relevant to construction-site safety in England and Wales, according to The National Archives (legislation.gov.uk).

Eligibility for injury compensation

Eligibility depends on whether another party’s failure to take reasonable care caused or contributed to your injury. That party could be an employer, contractor or someone responsible for unsafe site conditions. Employees and self-employed workers may both be eligible. Consider what happened, who controlled the work and how the alleged failure led to your injury.

For example, a fall from unsafe scaffolding may raise questions about site inspections and the precautions taken. Evidence connecting the incident to a health and safety failure can help assess a compensation claim.

Injury and financial losses

Compensation may cover the injury itself and its impact on daily life. General damages reflect pain, suffering and loss of amenity, including restrictions on ordinary activities during recovery. The injury’s nature, severity and lasting effects are relevant. A wrist fracture, for example, may affect work and everyday tasks differently from a minor injury.

Special damages cover financial losses and expenses caused by the accident. Keep records linking each claimed cost or loss to your injury, such as payslips and treatment receipts.

Earnings, treatment, care and travel costs

Claimable losses may include earnings missed during recovery, private treatment, physiotherapy and travel to medical appointments. Care and assistance at home may also form part of a financial claim. Keep receipts, appointment details and records of time off work so each loss can be linked to the accident.

Future needs may also be relevant. Ongoing treatment, psychological therapy or home adaptations could affect the amount claimed, depending on the injury and its consequences.

Compensation ranges for construction injuries

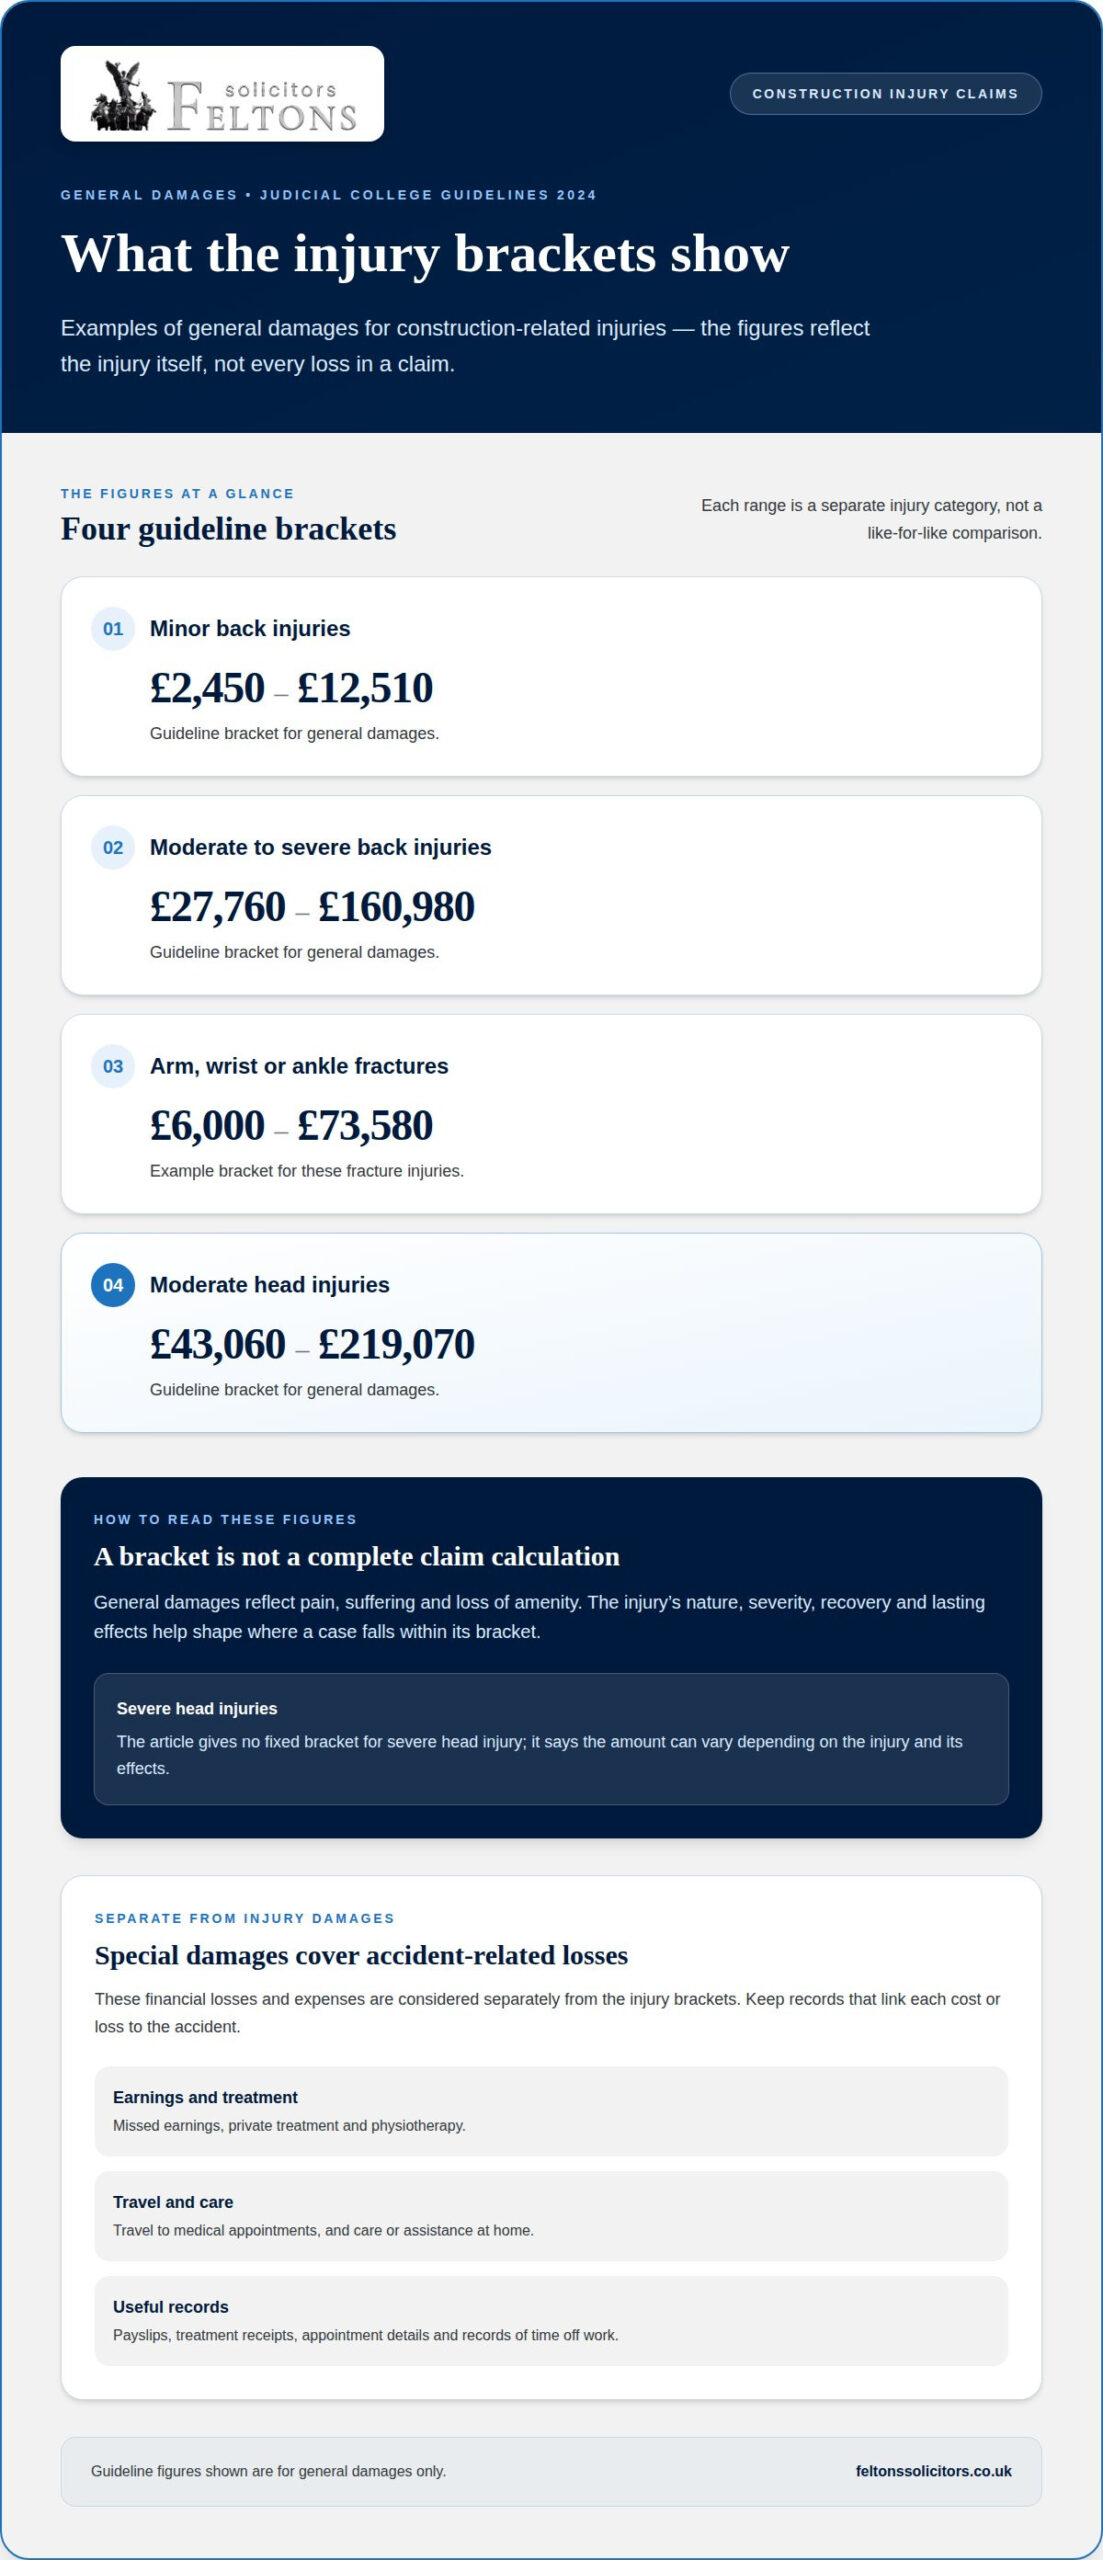
The Judicial College Guidelines 2024 provide brackets for general damages, not a complete calculation of every claim. Minor back injuries are listed at £2,450-£12,510; moderate to severe back injuries at £27,760-£160,980. These figures concern the injury itself, not earnings or treatment costs.

Other examples include £6,000-£73,580 for arm, wrist or ankle fractures and £43,060-£219,070 for moderate head injuries. The amount for a severe head injury can vary depending on the injury and its effects. Injury severity, recovery and lasting effects shape where a case falls within a bracket.

How can negligence lead to a construction accident?

When comparing construction accident claims solicitors in the UK, consider their experience with site injury claims, how they explain evidence and fees, and how they communicate about progress. Look for clear advice on responsibility, next steps and potential charges. Ask how they investigate incidents involving several contractors and how they will keep you updated.

According to The National Archives (legislation.gov.uk), the Health and Safety at Work Act 1974 requires employers and site managers in England and Wales to provide a safe working environment. The Work at Height Regulations 2005 place duties on those in control of a construction site, according to The National Archives (legislation.gov.uk). These laws are relevant when examining unsafe access, platforms or supervision.

Negligence may involve an employer, principal contractor or another contractor. Examples include failing to address a hazard, providing unsafe equipment or giving inadequate instruction. Where several businesses share a site, an investigation may need to establish who controlled the activity and whose actions contributed to the injury.

Your employment status alone doesn’t prevent a claim. Employees, agency workers, subcontractors and self-employed workers may be eligible if another party’s negligence caused their injury. For a subcontractor, evidence about site arrangements and who supplied equipment can help identify responsibility. Independent contractors must also avoid dangerous working practices that could injure others.

Visitors may have a claim if negligence caused their injury. For example, an investigation could examine whether a visitor was exposed to falling materials or unsafe access. A witness account, visitor records and photographs can help establish what happened and who may be responsible.

Investigators may also consider a worker’s actions alongside the training, instructions and equipment provided. A solicitor experienced in construction accident claims in the UK can assess how these details affect responsibility. Before proceeding, ask for a written explanation of fees and charges, and clear information about confidentiality, your interests and updates on the claim.

Construction Accident Claims Solicitors in the UK

Are there time limits for construction accident claims?

Yes, rules differ by jurisdiction. In England and Wales, the standard deadline is three years from the accident date under the Limitation Act 1980. For construction-related illness or disease, the three-year period runs from diagnosis. Don’t assume these deadlines apply elsewhere in the UK.

For an injured child, the three-year time limit begins on their 18th birthday if no claim has already been made. A parent can bring a claim on the child’s behalf before then. These time limits make early advice important, particularly where the accident date or diagnosis date may be disputed.

Evidence can disappear quickly after a site accident. Take photographs of the hazard, machinery, scaffolding or working-at-height arrangements, and note the names and contact details of witnesses. Report the incident to your employer and seek medical attention. Keep medical records, accident reports, site records and correspondence together. Construction-site CCTV footage is routinely overwritten within 14-31 days, so act promptly to preserve relevant footage.

RIDDOR is the Reporting of Injuries, Diseases and Dangerous Occurrences Regulations 2013, according to The National Archives (legislation.gov.uk). An incident report, where one exists, may help establish what happened and when. It does not replace other evidence, such as witness accounts or medical records, which can show how the accident was caused and the injuries sustained.

Evidence gathering may continue if the responsible party disputes liability. Records of treatment and income can support a claim alongside evidence about the accident itself. Organise dates, photographs and expenses in one file, and preserve original documents and messages.

Yes. The three-year deadline described here applies to England and Wales. Scotland and Northern Ireland have different rules, so don’t assume the same deadline applies there.

Steps in the construction accident claims process

A clear sequence of steps helps workers move from an initial report to a decision on responsibility and compensation. If you’ve suffered a serious workplace injury, prioritise treatment and make an accurate record of what happened.

  1. Report and record the accident. Enter the incident in the workplace accident book, including the time, place, injury details and description. Notify the employer or site manager, and keep a copy or note of the report.
  2. Get medical attention. A medical assessment supports your recovery and creates a record of the injuries. Keep appointment details and records of treatment, especially if the injury affects work or earnings.
  3. Organise evidence. Preserve photographs, witness contact details, medical records and relevant site documents. A solicitor can assess the circumstances, identify potentially responsible parties and gather further evidence where needed.
  4. Notify the responsible party. The company or contractor connected with the accident is told about the claim and asked whether liability is accepted. On a multi-contractor site, identifying who controlled the work or hazard can take investigation.
  5. Negotiate and resolve the claim. If liability is accepted, the parties can negotiate compensation using evidence of injury and losses. Interim payments may be secured during the claim in some cases where the other party accepts liability.

If liability is disputed, the evidence may need further review, including medical evidence and input from health and safety specialists. A solicitor may prepare legal documents and represent you in court if necessary. Most building site accident claims settle before a final court hearing, although the evidence and disputed issues affect how each case progresses.

Straightforward construction accident claims can take 3-9 months to settle. After an agreement, compensation is paid 14-28 days later. For practical help setting out the steps in your case, discuss your construction injury claim.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP handles personal injury and silicosis claims, so the firm can discuss a construction injury claim with you. You can talk through how your injury, evidence and resulting losses relate to a potential claim, and what steps may apply to your circumstances.

Before the discussion, organise the essentials: a brief timeline of the accident, medical records, witness details and documents showing lost earnings or treatment costs. This provides a clearer starting point for reviewing what happened and how it affected you. Advice can help you understand the claims process and what information is needed to assess your position, while recognising that every site injury has its own circumstances and outcome.

For guidance on a construction-related personal injury claim, contact Feltons Solicitors LLP.

Take the next step with clarity

Considering a claim is also an opportunity to think about the support you need while recovering. You may want help understanding how the injury has affected your work, home life or future plans, as well as guidance on the legal process. When choosing construction accident claims solicitors in the UK, look for clear communication and advice grounded in the evidence of your situation.

Before getting in touch, note the questions you want answered and gather any documents you can access. A straightforward account of what happened and what has changed since can help start a focused discussion. The strength and value of a claim depend on its circumstances, so individual advice matters.

For a measured discussion about your circumstances and possible next steps, contact Feltons Solicitors LLP. Taking that first step can help you move forward with a clearer understanding of your options.

Frequently Asked Questions

I’m self-employed or a subcontractor, can I still claim?

Yes. Self-employed workers and subcontractors may claim if another party’s negligence caused their injury; employment status alone doesn’t rule out a claim. Keep your contract, invoices and work allocation records with your accident-related documents. These may help clarify who arranged the task, supplied equipment or controlled the work area when the incident happened.

How much compensation could I receive for a construction accident?

The amount depends on the injury’s severity, its effects and the financial losses it caused. For example, the stated general damages figure for losing the little and ring fingers is around £26,620. This relates to the injury itself; lost earnings, treatment costs or care needs are assessed separately. Keep evidence of those losses to help establish their value.

Can I claim if I was visiting the construction site?

Yes, a visitor may have a claim if negligence by a responsible party caused their injury. For example, a delivery driver hurt while crossing an unsafe work area could record where the incident happened and who was present. Keep visitor sign-in details, messages arranging the visit and any photographs, as these may help establish the circumstances.

Can my employer sack me for making a claim?

Under the Employment Rights Act 1996, dismissing or penalising an employee for making a personal injury claim is automatically unfair dismissal. Keep relevant messages, meeting notes and any written warnings if your treatment at work changes after raising a claim. Record dates and what was said, so you have a clear account of events if you need advice.

How much could I get for psychological injuries after a construction accident?

The stated Judicial College Guidelines bracket for severe psychiatric damage is £66,920 to £141,240. The injury’s severity and its impact are relevant to the general damages assessment. Evidence may include treatment records and an assessment of the psychological harm. Financial losses, such as earnings lost because of the condition, are considered separately from this bracket.

How will I be able to pay for my claim?

Some UK accident claims use a No Win No Fee agreement, which generally means no payment before the case outcome. Additional expenses may still arise, and a success fee can be calculated as a percentage of compensation, subject to legal limits. Before proceeding, read the written explanation of fees and charges carefully so you understand what you may have to pay.