Silicosis Compensation Claims for Workers Exposed to Silica Dust

Silicosis Compensation Claims for Workers Exposed to Silica Dust

A silicosis diagnosis may support a compensation claim when evidence links the illness to workplace silica dust and shows that an employer failed in its duty of care. In England and Wales, the usual time limit is three years from when a person first became aware they had silicosis, according to The National Archives. Industrial dust exposure compensation claims can also involve industrial benefits, and understanding how the routes relate is an important part of deciding what to do next.

Silicosis is a long-term lung disease caused by inhaling fine crystalline silica dust. Its effects can emerge years after exposure, so it is understandable to be unsure how past work, a later diagnosis and the legal deadline fit together.

This article explains how silica exposure happens, what evidence may support a claim and how time limits apply. It also explains how a civil claim relates to industrial benefits, including when payments through one route may affect compensation through another.

Key Takeaways

  • Learn how workplace silica dust exposure and an employer’s failure to control risks may shape a compensation claim.
  • See which medical and work-history records can help connect silicosis to past employment.
  • Understand the usual three-year time limit in England and Wales, which runs from when you first become aware of the illness.
  • Explore how a civil claim may relate to industrial benefits, including a lump-sum route under the Workers Compensation Act 1979.

How does workplace silica dust exposure happen?

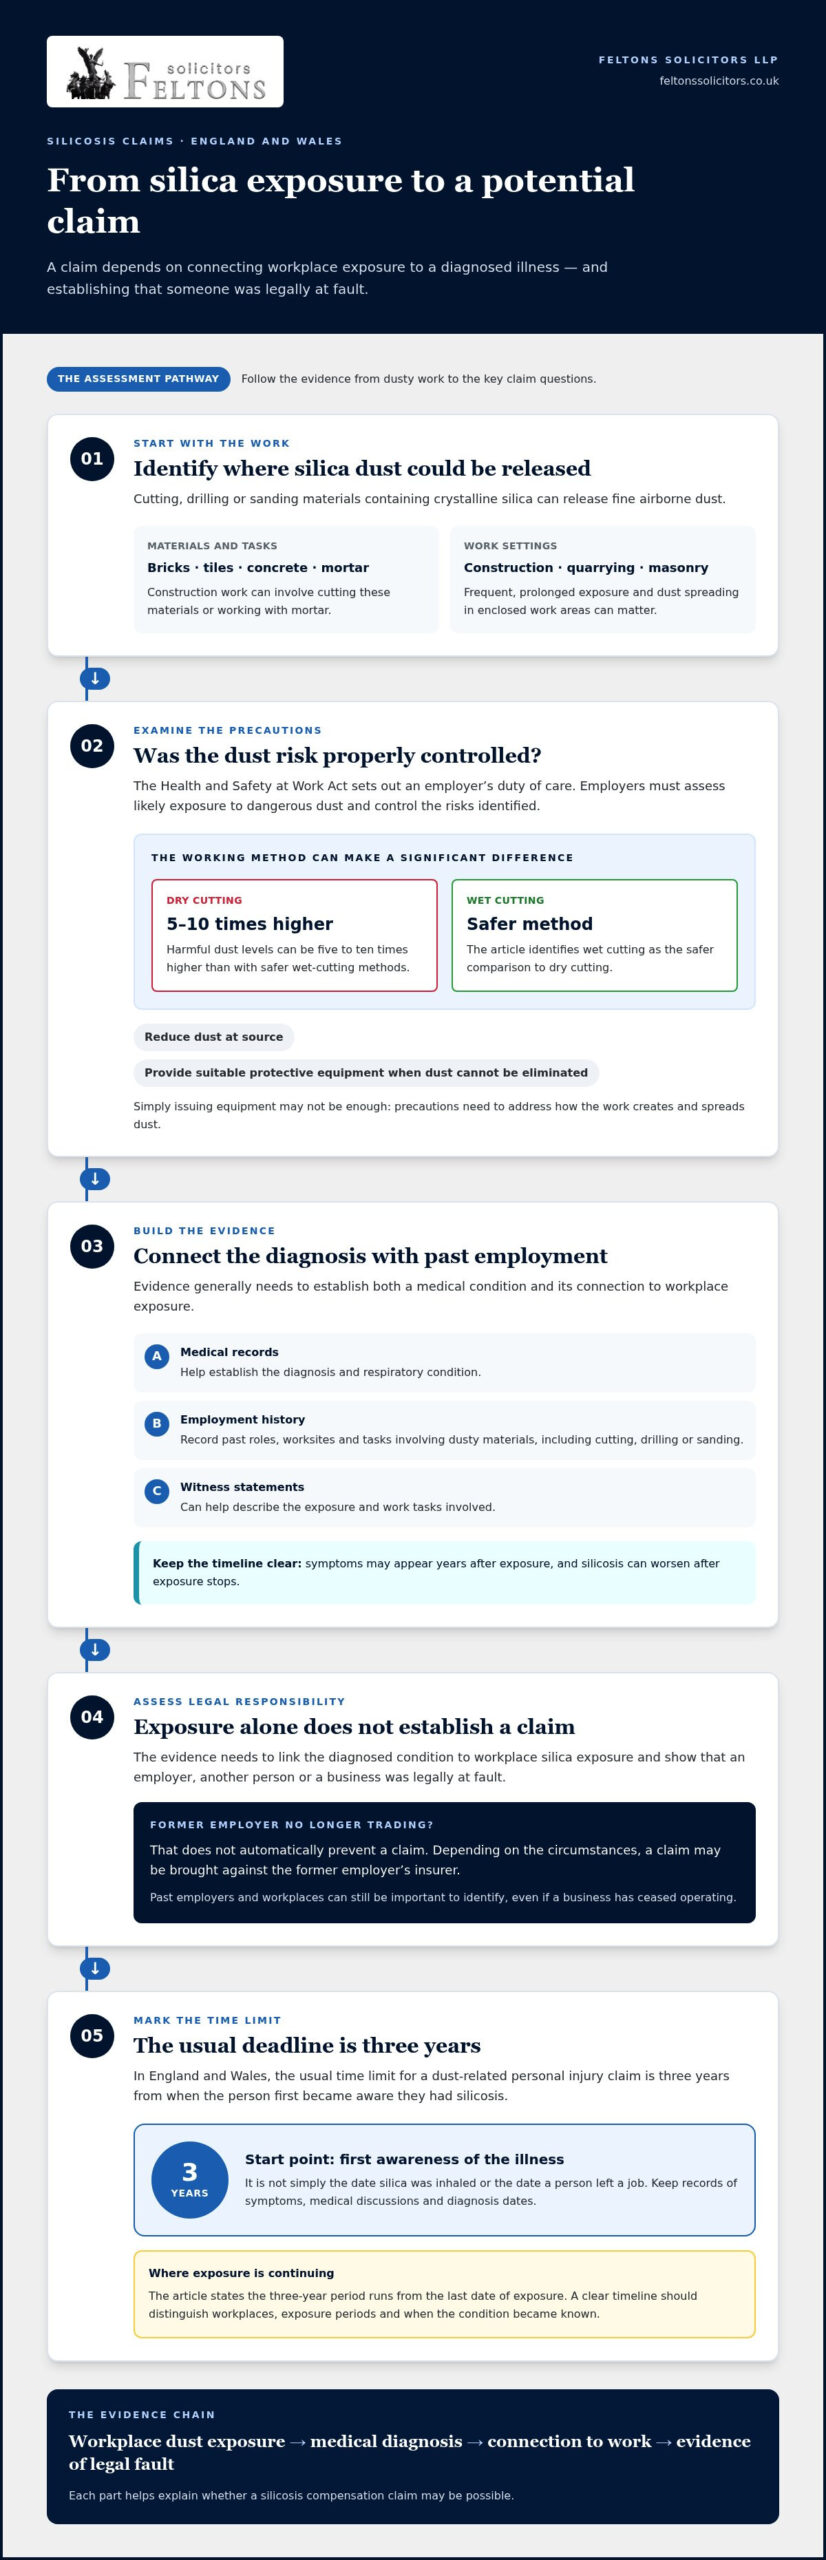
Silica dust is released when materials containing crystalline silica are cut, drilled or sanded. In construction, cutting bricks, tiles and concrete or working with mortar can release airborne dust. Construction, quarrying and masonry can involve frequent, prolonged exposure, with fine particles inhaled during routine tasks, particularly when dust spreads through an enclosed work area. Repeated workplace exposure can lead to silicosis.

The Health and Safety at Work Act sets out employers’ duty of care to protect employees from workplace harm. Employers must assess likely exposure to dangerous dust and control the risks they identify. Practical precautions include reducing dust at source and providing suitable protective equipment when dust cannot be eliminated. Simply issuing equipment is not enough: precautions must address how the work creates and spreads dust.

For example, a worker cutting engineered stone without effective dust controls may face avoidable exposure. Dry cutting can expose workers to harmful dust levels five to ten times higher than safer wet-cutting methods. This illustrates why the method of work matters when assessing whether an employer took appropriate precautions. Continued silica exposure despite avoidable risks may be relevant to whether the employer breached its duty of care.

A silicosis claim needs evidence linking the diagnosed condition to workplace silica exposure and showing that the employer failed in its duty of care. Start by recording past roles, worksites and tasks involving dusty materials. Employment records and details of cutting, drilling or sanding can help establish where exposure occurred. Medical evidence can then help connect that exposure with the respiratory condition.

A former employer’s closure does not automatically prevent a claim. In the UK, a silicosis claim may still be possible even if the employer is no longer trading. Depending on the circumstances, a claim may be brought against the former employer’s insurer. Identify past employers and workplaces, even if the business has since ceased operating.

When might a silicosis compensation claim be possible?

A claim depends on evidence linking an industrial disease to workplace exposure and establishing legal responsibility. The type of dust, medical diagnosis and work history all help explain that link.

Silicosis and lung damage

Silicosis is a long-term lung disease caused by inhaling fine crystalline silica particles. The particles scar and harden lung tissue, gradually reducing lung function. Chronic silicosis usually follows prolonged exposure, while accelerated silicosis can develop after five to 10 years of higher exposure. Acute silicosis can develop within a few weeks after exposure to very high concentrations. Cutting, drilling or sanding silica-containing materials can release the dust.

Symptoms can include persistent coughing, breathlessness during activity and chest tightness, and may appear years after exposure. Silicosis can worsen after exposure stops, and there is no known cure. Silica exposure can also be linked to lung cancer and chronic obstructive pulmonary disease (COPD). The diagnosed condition matters when assessing a claim.

Claim evidence and eligibility

Evidence generally needs to establish both a medical condition and its connection to work. Medical records, employment history and witness statements can help show the diagnosis, exposure and tasks involved. A specialist can assess how the records fit together, including whether the illness was caused by silica dust or another industrial exposure.

In the UK, compensable industrial dust exposure can include exposure to silica, asbestos and other workplace dusts, chemicals or vapours linked to respiratory illness. A claim depends on evidence that the exposure caused the condition and that an employer or another person or business was legally at fault.

Workers with a respiratory illness linked to workplace exposure can pursue a claim if legal fault is established. A claim may also be made on behalf of someone too ill to act, someone lacking mental capacity, or a person who has died from the illness.

If you have breathing difficulties, seek medical assistance, then gather medical records, employment details and witness accounts. These can help establish the diagnosis, exposure history and potential responsibility.

The risks include difficulty proving exposure, causation or fault. Industrial disease claims are often pursued through conditional fee agreements, commonly called no win no fee arrangements; the agreement’s terms explain any fees payable. For help assessing evidence, consider specialist silicosis claim advice.
Silicosis Compensation Claims for Workers Exposed to Silica Dust

Time limits for claims

In England and Wales, the usual deadline is three years from first awareness of silicosis, according to The National Archives (legislation.gov.uk). This date can matter even if symptoms develop gradually or exposure happened years earlier.

The three-year claim time limit

For a dust-related personal injury claim in England and Wales, the usual time limit is three years from when the person first became aware they had silicosis. The relevant starting point is awareness of the illness, not simply the date silica particles were inhaled or the worker left a job. Keep records of symptoms, medical discussions and diagnosis dates to help establish the timeline.

Silicosis may develop long after workplace exposure, so the gap between dusty work and diagnosis does not, by itself, determine the deadline. Where exposure is continuing, the stated period is three years from the last date of exposure. A clear timeline should distinguish each workplace, exposure period and when the condition became known.

Time limits in England and Wales

The three-year period applies to personal injury claims, including those involving silicosis. Identifying the relevant awareness date can be difficult if symptoms came before diagnosis or medical understanding developed over time. Note when you first learned that your respiratory condition was linked to workplace silica exposure, alongside diagnosis and employment records.

Do not assume the diagnosis date is decisive in every case. Records showing when the illness was identified and connected with exposure can help clarify the chronology. Delay may affect whether a claim can proceed, so it is important to review the dates and evidence promptly.

Scotland and Northern Ireland have their own limitation rules, so do not assume the England and Wales three-year period applies there. Identify where the relevant exposure and claim arose, then establish the applicable deadline before deciding what to do next.

As a practical first step, create a dated record of dusty roles, the last exposure date, symptoms and medical appointments. If silica exposure is ongoing, record when it stops. This helps distinguish the exposure timeline from the later period when an injury may develop or be diagnosed, and supports assessment of the employer’s duty of care.

Civil claims and industrial benefits

A civil claim and an industrial benefit are separate routes for people affected by occupational silicosis. Receiving a benefit does not necessarily rule out a civil claim, but payments can affect the final damages calculation. Industrial dust exposure compensation claims may therefore require consideration of both routes.

A civil claim considers whether workplace exposure caused the illness and whether an employer or another person or business was legally at fault. Compensation can reflect lung scarring and symptoms, as well as financial losses such as lost earnings, care needs, travel and medical treatment. Keep evidence of these losses with records of exposure and diagnosis.

State benefits are another consideration. Silicosis and pneumoconiosis are prescribed diseases for State benefit claims. The Workers Compensation Act 1979 provides a route to claim a lump sum for silicosis, or for a dependent whose loved one has died of silicosis, according to The National Archives (legislation.gov.uk).

Where a person receives industrial disablement benefit or a lump sum through the Workers Compensation Act, that money is deducted from compensation awarded in a civil claim under the routes described. This adjustment prevents the same loss from being compensated twice. Keep award letters and payment records so the amounts can be accurately considered alongside the civil claim.

Silicosis can progress, so evidence should also describe its current impact and possible future effects. Provisional damages may preserve the opportunity to seek further damages if a more serious condition develops later. A claim can be brought for someone too ill to act, someone lacking mental capacity, or a person who has died; a dependent may also have a lump-sum route under the 1979 Act. A person exposed while self-employed is not eligible for industrial disablement benefit under the route described here. These details can shape how industrial dust exposure compensation claims are assessed alongside benefits.

Silicosis claims can involve historic exposure, several employers and detailed medical evidence. Settlement may take up to three years, or longer depending on liability and the claimant’s condition. To discuss how a civil claim and benefits may relate, seek advice on a silicosis claim.

In Scotland and Northern Ireland, a civil claim considers whether workplace exposure caused the illness and whether an employer or another party was legally at fault; industrial benefits are a separate route. Industrial disablement benefit or a lump sum under the Workers Compensation Act 1979 may be deducted from civil damages to avoid compensating the same loss twice.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP handles Personal Injury and Silicosis Claims for people seeking advice after workplace silica exposure. The firm can advise if you have a diagnosis, questions about whether employer negligence contributed, or uncertainty about how a civil claim relates to industrial benefits. A discussion can help you understand the evidence and issues relevant to your circumstances, including past work and medical records.

Silicosis claims can involve historic exposure and more than one employer, so setting out your work history and diagnosis can help explain the situation. Feltons Solicitors LLP can advise on the legal claim; this section is distinct from its Divorce and Financial Arrangements offering.

Contact Feltons Solicitors LLP to discuss a silicosis claim.

Take a clear next step

A diagnosis can affect more than your health. It may change the work you can do, the support you need at home and the plans you make with family. Describing these practical effects can help ensure they are considered alongside medical evidence in industrial dust exposure compensation claims.

Before seeking advice, note what has changed in daily life, what assistance you need and which work or personal plans have been affected. You do not need to have every detail resolved before discussing your situation. A focused conversation can help identify the key questions and documents that may help answer them.

If you’re ready to discuss your circumstances, contact Feltons Solicitors LLP about your claim. A considered next step can help you approach the legal process with greater clarity and decide how you wish to proceed.

Frequently Asked Questions

What is silicosis?

Silicosis is an occupational lung disease caused by inhaling crystalline silica particles, which can scar lung tissue. It has chronic, accelerated and acute forms, associated with different exposure patterns. Acute silicosis can develop within a few weeks after very high exposure, while chronic disease usually follows prolonged exposure. Possible symptoms include persistent coughing, chest tightness and breathlessness; a medical diagnosis identifies the condition.

Can I claim if my former employer no longer exists?

Yes. A former employer’s closure does not automatically prevent a silicosis claim. Depending on the circumstances, a claim may be brought against the old insurer. Start by noting the employer’s name, the worksite and the tasks that created dust. Old employment papers, payslips or colleague details may help piece together your work history and identify relevant exposure periods.

Can silicosis get worse after exposure has ended?

Yes. Silicosis can continue to progress after silica exposure stops, so leaving dusty work does not necessarily end its effects. If your breathing, stamina or everyday activities change, record when the changes occur and discuss them with your medical team. These updates can help describe how the condition affects daily life, rather than relying only on an earlier account of symptoms.

How Much Compensation Can You Expect?

A claim may account for pain and suffering, lost income, care, travel and medical treatment. For example, reduced ability to work or a need for regular assistance can affect the losses assessed. There is no fixed tariff for every diagnosis.

How long do I have to make a claim?

In England and Wales, the usual limit is three years from when you first became aware of silicosis, according to The National Archives (legislation.gov.uk). Awareness may not match the date you first inhaled dust or stopped working. Note when you received information linking your condition to silica, and keep relevant medical dates together. Scotland and Northern Ireland have different limitation rules.

How might my employer be responsible?

An employer may be responsible if workplace silica exposure caused your illness and the exposure was legally their fault. For example, evidence might show dust-generating work continued without adequate measures to control the risk. The assessment considers working conditions, exposure history and the medical link, not simply whether you handled concrete. Details of tasks, sites and colleagues can help clarify what happened.
Divorce mediation for financial disputes: how it works

Divorce mediation for financial disputes: how it works

In divorce mediation for financial disputes, separating couples can work towards an agreement about money and property without asking a court to decide every issue. But mediation alone does not make an agreement legally binding. In England and Wales, the court must approve a consent order to give the agreed terms legal force. Mediation helps you shape proposals; the court provides formal approval.

It is understandable to want clarity about finances while avoiding the time, cost and pressure that contested court proceedings can bring. Mediation provides a structured way to discuss the issues, but it depends on both people sharing financial information and taking part in the discussions.

This article explains what financial mediation involves, how disclosure supports informed decisions and what happens when you reach agreement. It also compares mediation with court proceedings, explains when an agreement becomes binding and outlines the role of legal advice.

Key Takeaways

  • A MIAM helps assess whether mediation is suitable and is generally part of the route to court for a financial dispute, subject to exceptions.
  • Prepare a clear picture of income, assets, pensions, debts and expenses so discussions can focus on informed options.
  • A mediator facilitates discussion but doesn’t choose the outcome; you and your former partner retain control over whether to agree.
  • Learn how Feltons Solicitors LLP’s Divorce and Financial Arrangements service can help you consider the legal steps that follow mediation.

Are financial agreements legally binding?

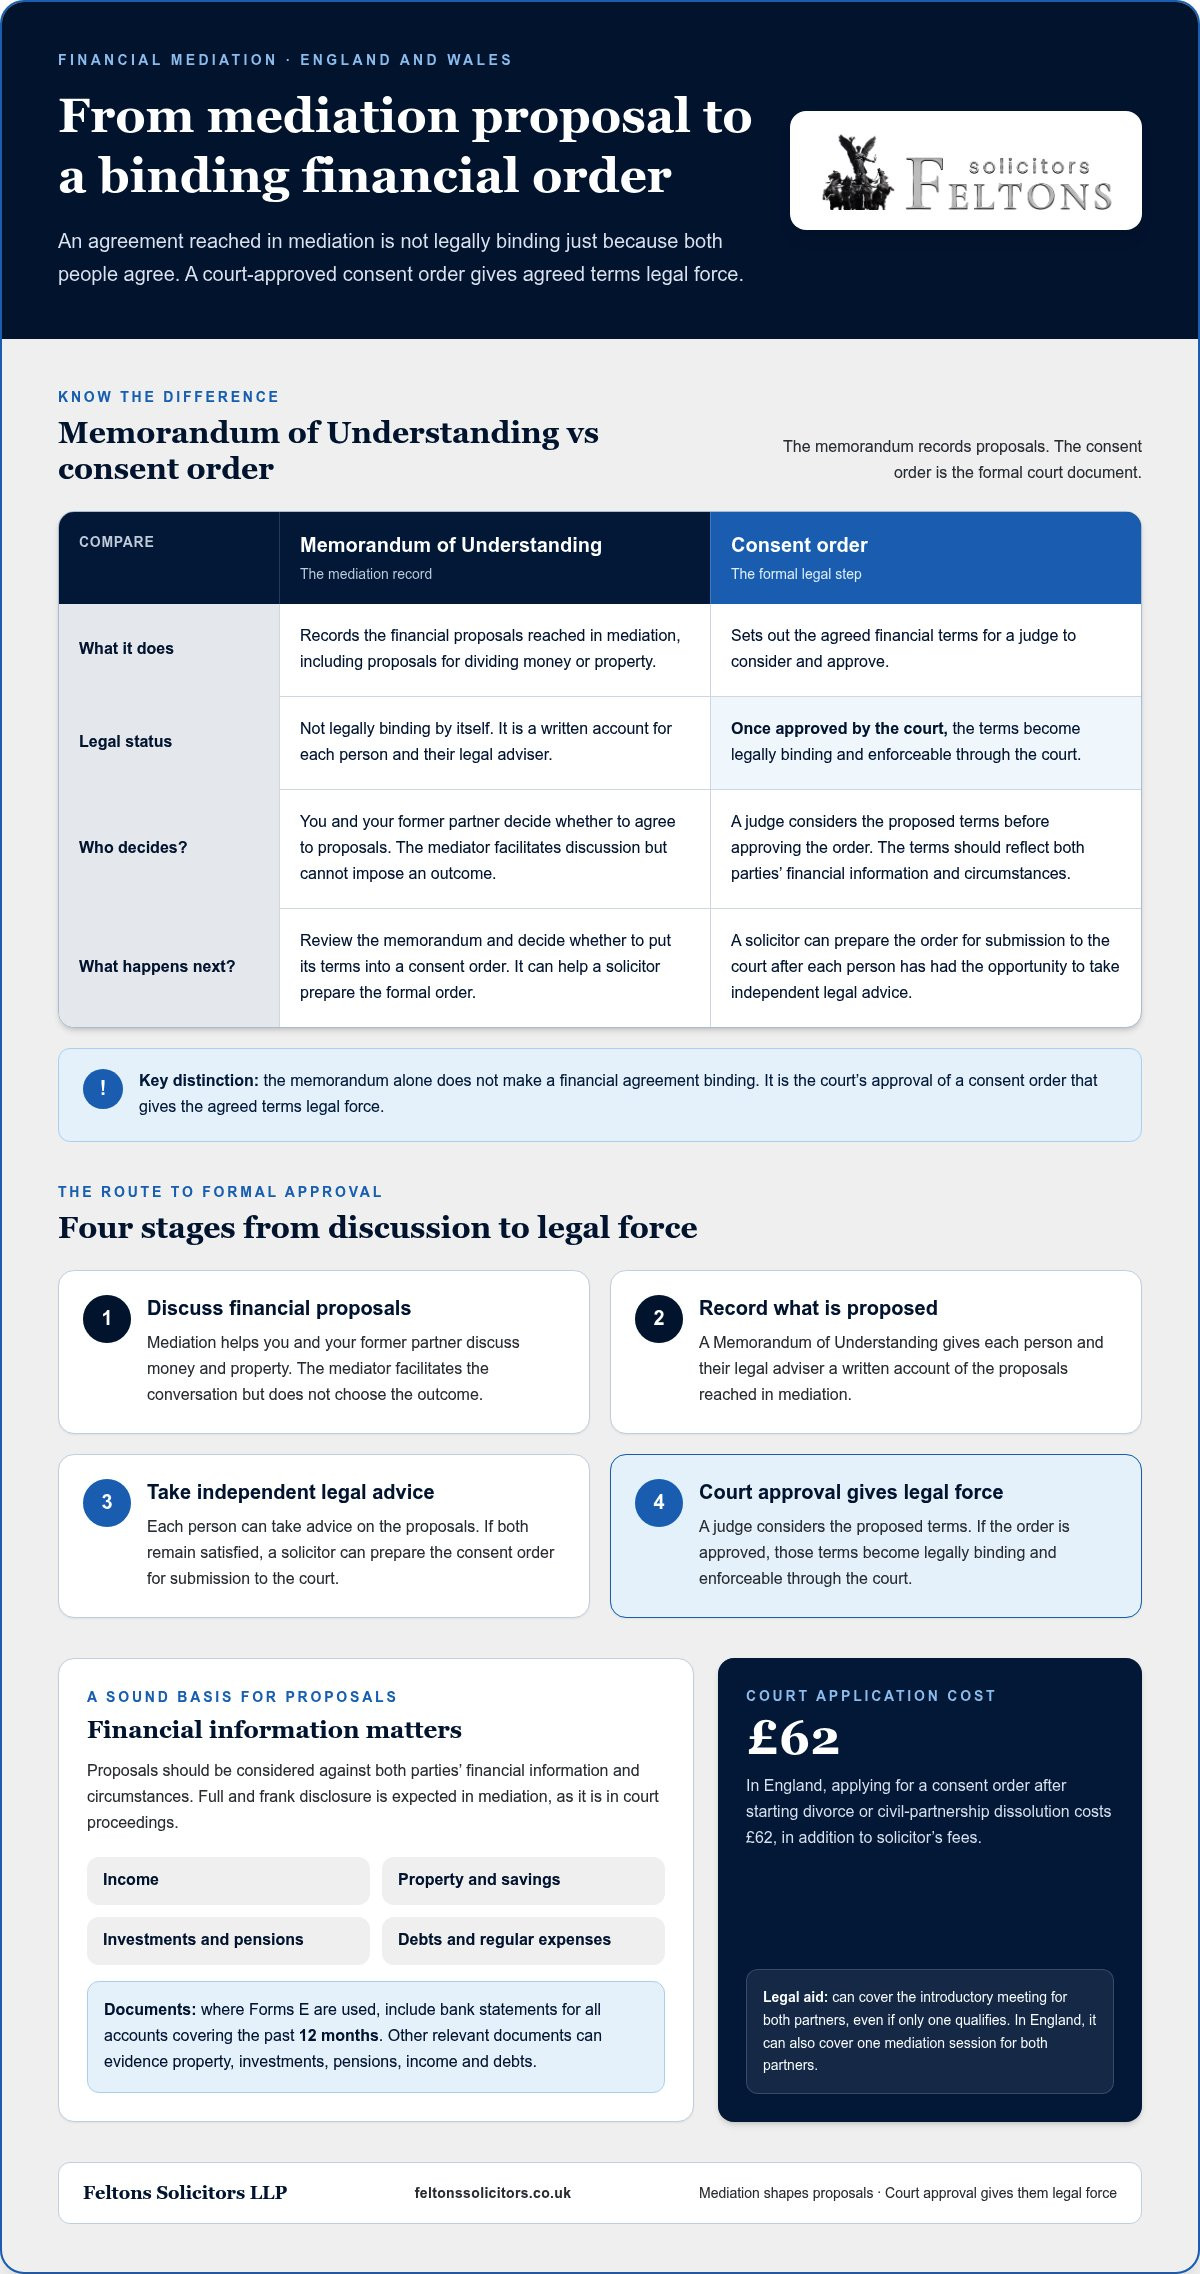
An agreement reached in mediation does not become legally binding simply because both people consent to it. In England and Wales, the formal legal step is a court-approved consent order.

Making agreements legally binding

A consent order sets out agreed financial terms for a judge to approve. Once approved, the terms become legally binding and enforceable through the court. This matters if either person later fails to meet an obligation, such as transferring property or paying maintenance. Before approving the order, the judge considers the proposed terms, which should reflect the parties’ financial information and circumstances.

After mediation, each person can take the proposals for independent legal advice. If both remain satisfied, a solicitor can prepare the consent order for submission to the court. In England, applying for a consent order after starting divorce or civil-partnership dissolution costs £62, in addition to solicitor’s fees. A financial agreement that has not been formalised and approved may not be legally binding.

Memorandums of understanding and consent orders

A Memorandum of Understanding records the financial proposals reached in mediation, but it is not itself a legally binding consent order. It gives each person and their legal adviser a written account of the agreement, including proposals for dividing money or property. That record can help a solicitor prepare the formal order, rather than leaving the terms only in discussion notes.

The next step is to review the memorandum and decide whether to put its terms into a consent order. If the judge approves the order, it becomes binding; the memorandum alone does not. If children are part of the wider separation, make clear which arrangements the financial settlement covers.

Mediation costs and court consequences

Legal aid can cover the introductory meeting for both separating partners, even if only one qualifies. In England, it can also cover one mediation session for both partners.

Refusing or leaving mediation can have cost consequences if the dispute later reaches court. A judge may order a party who withdraws to pay the other person’s legal costs if this would avoid unfairly disadvantaging someone willing to mediate. This may be relevant when mediation could have resolved the dispute but court proceedings created additional legal expense.

What is financial mediation?

Financial mediation helps separating partners discuss money and property with a neutral mediator. It can address assets, savings, pensions, debts, child support and spousal maintenance, but the mediator cannot impose an outcome or advise either partner.

Mediation information assessment meetings

A Mediation Information and Assessment Meeting (MIAM) is an initial meeting to explain mediation and assess whether it is suitable. The mediator considers each partner’s circumstances, including whether they can take part safely and communicate about the issues.

In England and Wales, applicants seeking a court decision on finances generally need to attend a MIAM first, unless an exception applies. The meeting helps you consider whether mediation could address the dispute before court proceedings begin. If someone decides not to mediate after the assessment, a mediator’s certificate is expected before proceedings start.

Mediation may be unsuitable or unsafe where there has been domestic abuse. It is voluntary, so either partner can withdraw, and unresolved issues may still need a court decision.

Financial issues mediation can address

Sessions can cover the division of property, savings, investments and other assets, as well as responsibility for debts and liabilities. Partners can also discuss pensions, spousal maintenance and child support. For example, they might consider whether one person keeps the family home while the other receives a different asset.

Income and financial commitments help shape practical proposals. The mediator facilitates negotiation but does not decide whether a proposed division is fair or require either partner to accept it. The Child Maintenance Service usually calculates child maintenance, although this does not apply in every case.

Independent legal advice can help you understand the implications of proposals before deciding whether to agree. If you need support with the legal position around a settlement, advice on financial arrangements can help you consider the next steps.

Divorce mediation for financial disputes: how it works

Financial disclosure

Financial disclosure sets out each person’s finances, including income, assets, debts and expenses. If someone hides assets or refuses to disclose information, the mediator may end mediation, leaving the parties without a reliable basis for agreement.

Disclosure before mediation

Before mediation, each person should gather a clear picture of their finances to support informed discussions. This includes income, property, savings, investments, pensions, debts and regular expenses. Preparing this information early can reveal missing details before sessions begin.

Full and frank financial disclosure is expected in mediation, as it is in court proceedings. It matters because a proposal about the family home, for example, cannot be considered fairly without understanding the wider assets and liabilities. A family law adviser can explain what information is relevant to your situation.

Financial documentation

Documents support the figures each person provides, helping both parties understand the financial position behind a proposal. Form E is the standard financial statement used in the court system; mediation participants may be asked to complete its factual and financial sections.

Where Forms E are used, include bank statements for all accounts covering the past 12 months. Other relevant documents can evidence property, investments, pensions, income and debts. Keeping records organised makes it easier to explain a figure, such as a loan balance, during discussions.

Disclosure during mediation

At the first mediation session, the mediator reviews both Forms E with the participants and identifies any gaps requiring more information. The mediator can list documents needed to verify figures and set a deadline for providing outstanding records before the next meeting.

Even if one person believes a document is unnecessary, the mediator may still require relevant financial information. If disclosure remains incomplete, the mediator may end the process rather than let discussions proceed on an unreliable picture.

Disclosure and reaching agreement

Complete disclosure gives both people a shared financial picture from which to consider proposals. It helps them compare options, such as keeping property in return for other assets, and assess how debts or pension arrangements affect the overall settlement.

A mediator may not consider disclosure full and frank, even if both people seem ready to agree. Without sufficient information, either person may misunderstand the terms or their financial effect. A lawyer can review the figures and proposed terms before the parties decide whether to agree.

Mediating divorce financial disputes instead of going to court

Mediation gives separating parties a private way to discuss financial proposals and retain control over any agreement. Court proceedings put unresolved issues before a judge to decide.

Mediation, solicitor negotiation and court

In financial mediation, a neutral mediator helps both parties negotiate. Solicitor negotiation takes place through each person’s legal adviser. Neither the mediator nor the solicitors decide the outcome, unlike a judge. This distinction matters if you want to shape arrangements around your separation, property and other financial priorities.

Mediation is voluntary and confidential, and either person can withdraw. Solicitor negotiation may suit parties who prefer legal representatives to handle discussions. If agreement remains out of reach, a court can decide the disputed issues. Contested financial proceedings can take months or even years, so the route affects both the process and who makes the final decision.

Whatever route you consider, independent legal advice can help you understand proposals before accepting them. Mediation can help identify practical options, but it does not replace advice about your legal position.

Finding a family mediator

Look for a family mediator regulated by the Family Mediation Council, which sets standards for family mediation. A mediator experienced in family law and financial disputes can help keep discussions focused on property, pensions and liabilities.

The mediator assesses whether the process is suitable for both people. Mediation may be inappropriate or unsafe where domestic abuse affects someone’s ability to take part freely. Sessions can also take place online, so the parties do not have to be in the same room.

Before deciding, consider whether you and your former partner can share information and discuss options with the mediator. If you want legal advice about your position or the available routes, discuss your financial arrangements.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP provides support with Divorce and Financial Arrangements for people considering their financial position during separation. Once mediation has clarified possible terms, legal advice can help you understand the proposals, consider their implications and decide what formal steps may be needed.

This support can help if you have reached an agreement and need advice on putting the financial terms into a consent order, or if some issues remain unresolved. A solicitor can explain how the proposed arrangements relate to your circumstances and what options are available, without taking the mediator’s role.

For advice about your divorce and financial arrangements, contact Feltons Solicitors LLP.

Take a considered next step

Choosing divorce mediation for financial disputes is part of a wider decision about how to resolve financial matters after separation. Before taking the next step, consider the outcome that matters most to you, which questions remain unanswered and whether you need advice before agreeing to proposals. Clear priorities can help make discussions more focused.

Consider how a proposed arrangement may affect your plans beyond the immediate settlement. For example, decisions involving a home or other assets may need to be weighed against your future financial commitments. Independent legal advice can help you understand the implications and decide what action is appropriate for your circumstances.

Feltons Solicitors LLP offers advice on Divorce and Financial Arrangements. Contact Feltons Solicitors LLP for advice about your next step. A well-informed decision can help you move forward with greater clarity.

Frequently Asked Questions

Can I mediate online?

Yes, family mediation can take place online, including through platforms such as MS Teams and Zoom. You can join from separate locations, which may help if travelling or meeting in person is difficult. Before the first online session, arrange a private space, test your connection and keep relevant financial documents accessible. The mediator can explain how the meetings will be organised.

How does mediation work?

Mediation gives separating partners a structured setting to identify issues, share proposals and discuss possible solutions with a neutral mediator. Sessions commonly last one to two hours, and reaching a full financial agreement may involve three to five sessions. The mediator keeps discussions focused, but each person decides whether to accept a proposal. You can seek independent legal advice during the process.

How does financial divorce mediation work in England and Wales?

In England and Wales, divorce mediation for financial disputes generally starts with a MIAM, where a mediator assesses suitability and explains the process. If mediation proceeds, both people discuss their finances and the issues they want to resolve. The mediator can help explore settlement options and summarise proposals for legal advisers. Any financial agreement needs the appropriate formal steps to become binding.

What are the steps to start financial mediation after separation?

Start by arranging a Mediation Information and Assessment Meeting, or MIAM, to discuss whether mediation is suitable. If both people are willing to proceed, organise the financial information relevant to your situation and attend sessions to discuss priorities and possible arrangements. You can take legal advice as proposals develop. If you reach agreement, ask a legal adviser about formalising its terms.

Is mediation required before applying to court for a financial order in the UK?

In England and Wales, applicants generally need to attend a MIAM before applying to court for a decision about finances, unless an exception applies. The meeting assesses whether mediation is appropriate; attending does not mean you must continue. Requirements differ across the UK, so do not assume the England and Wales process applies in Scotland or Northern Ireland.

How are pensions, property, savings and debts handled in divorce mediation?

These matters are considered as part of each person’s overall financial position. For example, a proposal involving the family home can be weighed alongside its mortgage, savings, pension interests and outstanding debts. The parties can explore different ways to divide assets or manage liabilities, using relevant information to inform their discussions. A mediator facilitates the conversation; independent legal or financial advice can help explain complex options.

Commercial lease break clause dispute solicitors

Commercial lease break clause dispute solicitors

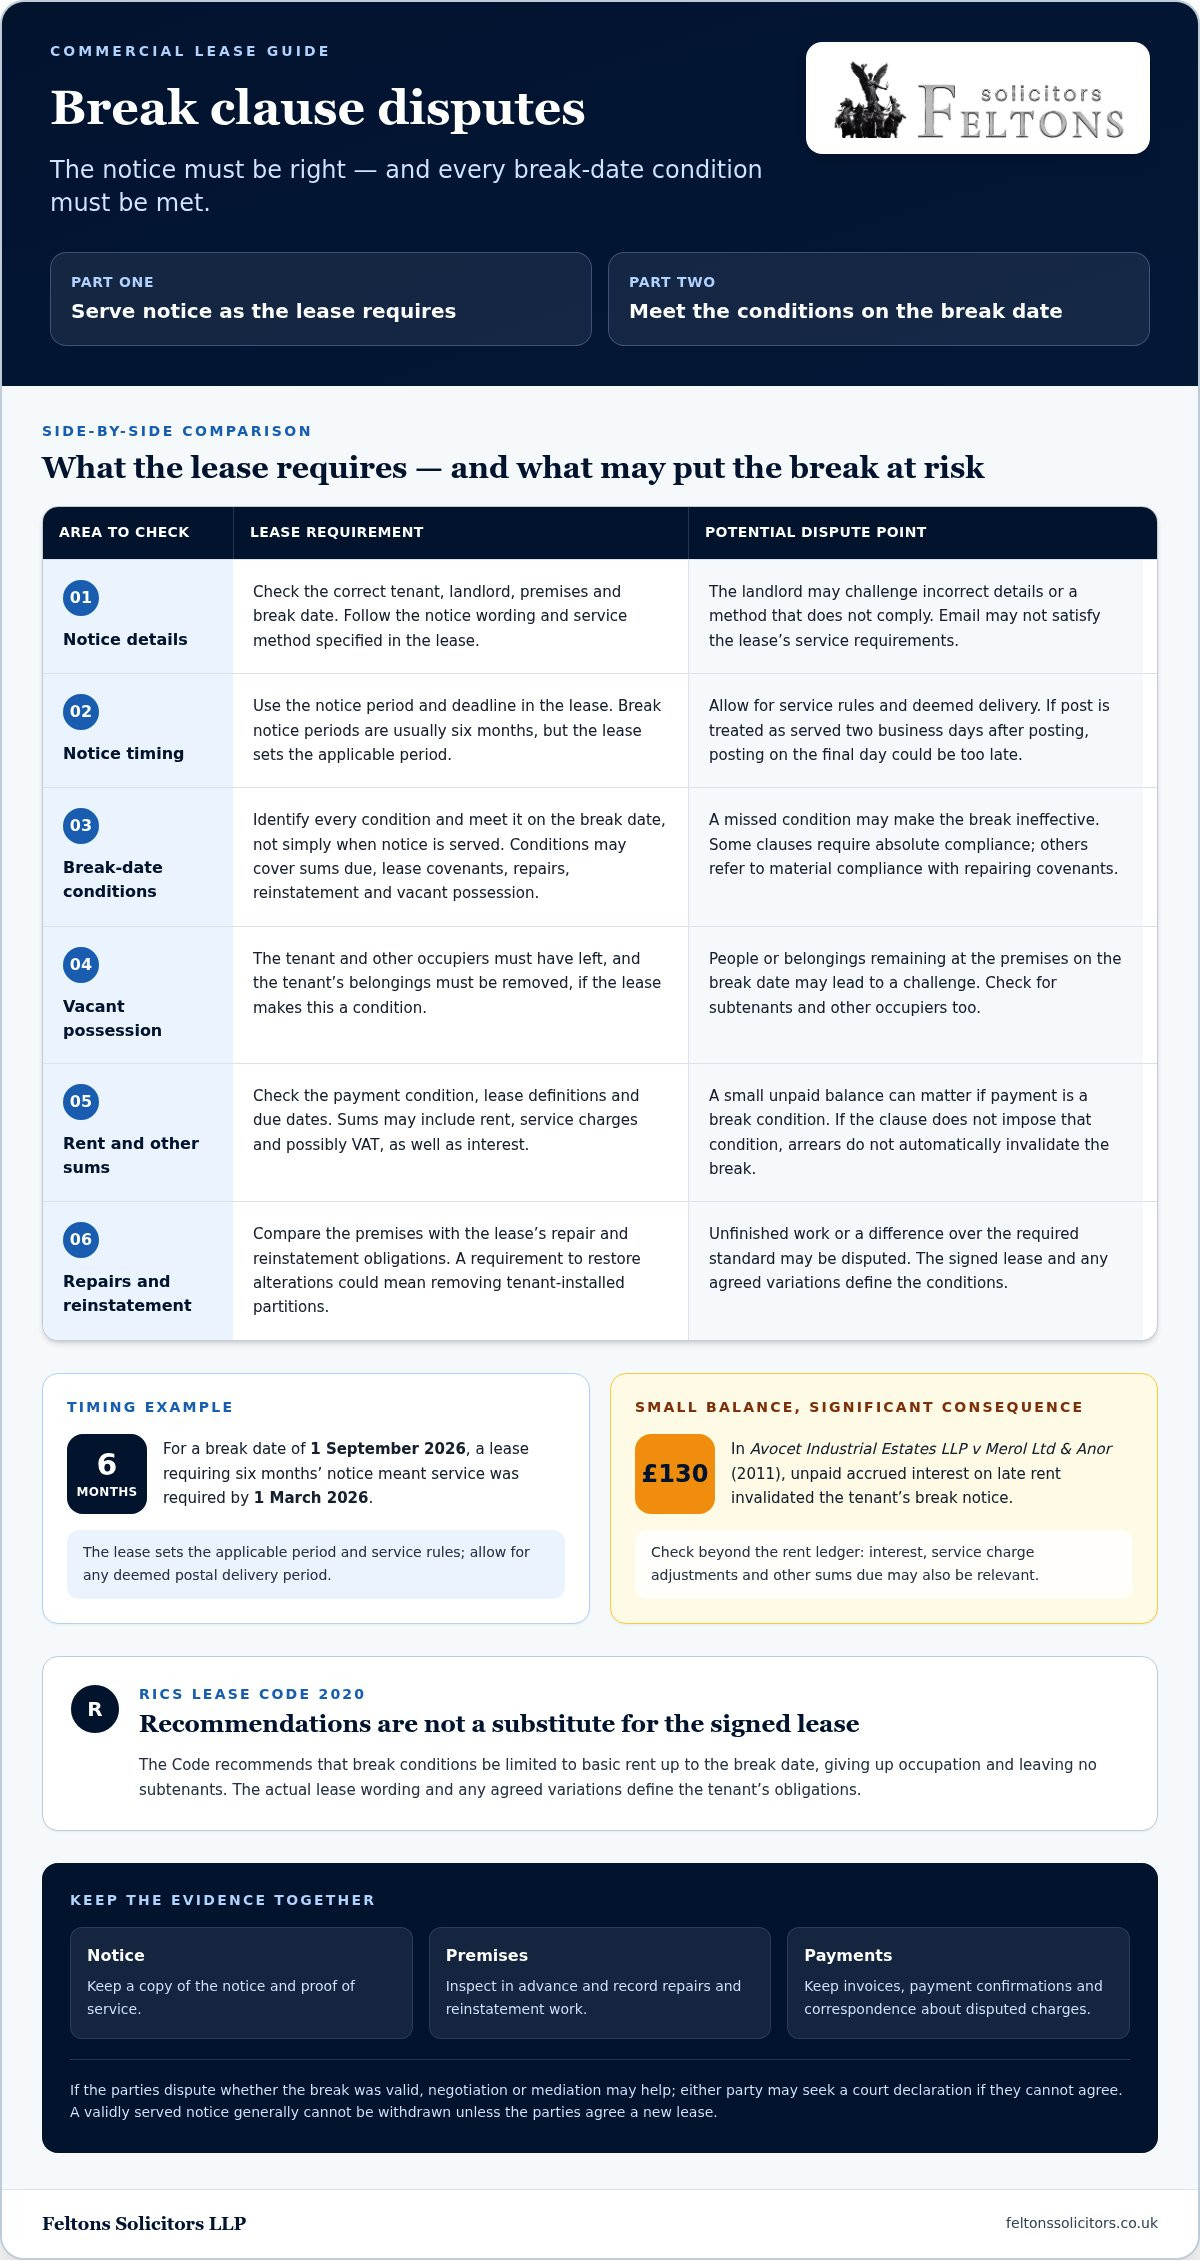
A break clause can end a commercial lease early, but only if the tenant follows the notice requirements and meets any conditions attached to the clause. Disputes often concern how notice was served, whether the tenant gave vacant possession, or whether rent and other sums were paid. Commercial lease break clause dispute solicitors assess the lease wording and the steps taken to determine whether the break was effective.

It is understandable to focus on the break date, which may seem like the key to ending the lease. But the notice process and lease conditions matter just as much. Missing a requirement may leave the tenant liable under the lease.

This guide explains what a break clause means, when a landlord may challenge a notice, and how rent, service charges and repair obligations can affect the outcome. It also covers how reviewing the clause and preparing well ahead of the break date can help identify problems before they become a dispute.

Key Takeaways

  • Read the break clause closely: the permitted notice method, recipient, wording and deadline can determine whether the notice is effective.
  • Identify every condition that must be met on the break date, including vacant possession and any repair or reinstatement obligations.
  • Review rent and other sums due, as unpaid charges or interest may put the break at risk.
  • Start reviewing the lease well in advance, inspect the premises and keep clear records of repairs and communications.

What is a break clause?

A commercial lease break clause gives the landlord, tenant or both a contractual route to end the lease before its term expires. The clause may set a fixed break date or allow a rolling break after a specified notice period. It determines who can exercise the right, when notice can be served and which conditions apply. A break is not automatic: the tenant must follow the lease wording.

Before exercising the right, identify the break date, notice period, recipient, service method and every condition. Calculate the deadline from the lease and allow for any deemed postal delivery period. Giving notice may not, by itself, be enough to end the lease. If a condition is missed, the break can be invalid, leaving the tenant bound by the lease obligations.

Conditions can cover rent and other sums, compliance with lease covenants, repairs, reinstatement of alterations and vacant possession. Some clauses demand absolute compliance; others require material compliance with repairing covenants, which may give the tenant more scope. Read each condition separately. For example, a requirement to restore alterations may mean removing tenant-installed partitions before handing back the premises.

Vacant possession means the tenant and other occupiers have left, and the tenant’s belongings have been removed. The RICS Lease Code 2020 recommends no subtenants or other occupiers as a break condition. It also recommends limiting conditions to basic rent up to the break date, giving up occupation and leaving no subtenants. These are recommendations, not a substitute for the signed lease wording.

Conditions attached to a break must be satisfied on the break date, not when notice is served. Inspect the premises in advance, compare their condition with repair and reinstatement duties, and keep records of completed work. Stricter conditions may be agreed during negotiations and set out in the Heads of Terms, as acknowledged by the RICS Code. The lease and any agreed variations define the tenant’s preconditions.

Can a landlord challenge a break notice?

Yes. A landlord may dispute a notice served incorrectly or late, or argue that a break condition was not met. Commercial lease break clause dispute solicitors can assess the notice against the lease’s contractual requirements and identify the issue in dispute.

Notice wording and timing

Check that the notice identifies the correct tenant, landlord, premises and break date. It should follow the particular wording and service method required by the lease; email may not satisfy that method. Break notice periods are usually six months, but the lease sets the applicable period. For a break date of 1 September 2026 requiring six months’ notice, service was required by 1 March 2026.

Allow for service rules as well as the deadline. A lease may deem postal service effective two business days after posting, so posting on the final day could be too late. A landlord may also challenge whether the tenant met the attached conditions. If a notice fails to meet the lease’s strict requirements, the break will usually be ineffective and the lease will continue until the next break date or the end of the term.

Dispute resolution steps and deadlines

Negotiation or mediation can help the parties resolve a dispute without asking a court to decide it. If they cannot agree, either party may seek a court declaration on whether the break was validly exercised.

In England and Wales, compare the notice, proof of service and relevant lease conditions with the contractual deadline. Then set out the disputed points and supporting records for negotiation or mediation. If agreement fails, court proceedings can determine whether the notice was valid. The lease’s notice deadline remains key to serving the break notice.

A validly served notice generally cannot be withdrawn; changing course requires the parties to agree a new lease. Commercial lease break clause dispute solicitors can help assess contested notices and dispute options. For relevant assistance, commercial property dispute resolution may be appropriate.

Commercial lease break clause dispute solicitors

Rent and other outstanding charges

A break clause may make payment of rent and other sums a strict condition of ending the lease. Depending on the wording, sums due can include service charges and possibly VAT, as well as rent. Check the payment condition against the lease’s definitions, payment dates and any separate covenants. Reconcile the account before the break date, including charges invoiced separately from rent.

Small balances can matter. In Avocet Industrial Estates LLP v Merol Ltd & Anor, decided in 2011, the tenant’s failure to pay £130 of accrued interest on late rent invalidated its break notice. The example shows why reviewing only the rent ledger may miss a sum caught by the clause. Check for interest, service charge adjustments and other sums that have become due under the lease.

If the lease makes payment a condition, an unpaid sum may mean the condition was breached and the break was ineffective. The lease may then continue, leaving the tenant responsible for its obligations until the next break date or the end of the term. If the clause does not impose that condition, arrears do not automatically invalidate the break, although the landlord may still pursue payment under the agreement.

What happens if a tenant breaches a break condition, such as payment or vacant possession? The break may fail, leaving the lease and its obligations in force; any rent or other sums due remain payable under the lease. A vacant-possession condition can also be breached if people or belongings remain at the premises on the break date.

Before the break date, compare the account with the lease and ask the landlord to clarify disputed charges in writing. Keep payment confirmations, invoices and correspondence together. If a final service charge adjustment is unresolved, establish whether the clause requires payment of sums already due or imposes a wider condition. The precise wording, payment timing and nature of the charge determine the risk.

Commercial lease break clause review

A structured review compares the break clause with the lease, notice and tenant’s actions. It can identify which conditions must be met and where evidence may be incomplete.

Evidence and document review

Gather the signed lease, any deed of variation, the break notice and proof of service. Add rent and service charge statements, payment records, repair documents, alteration approvals and correspondence about the premises. A survey or schedule of condition can help assess repair obligations and reinstatement. Reviewing these materials together shows whether the notice followed the contractual terms and whether each condition was met by the break date.

Reducing dispute risk

Tenants can identify the break date, notice period and conditions 12 months beforehand, then take advice on the clause’s drafting eight months beforehand. A property inspection nine months beforehand can reveal repair work that needs planning. Landlords can reduce uncertainty by recording concerns about the premises and communicating them clearly, rather than leaving condition issues unresolved until the break date.

For both parties, keep a dated record of notices, payments, repairs and discussions. Compare the lease with the RICS Code for Leasing Business Premises 2020, which recommends limiting break conditions to basic rent up to the break date, giving up occupation and leaving no subtenants. The signed lease remains central: a recommendation does not replace its terms.

Review the evidence against each condition separately. For example, photographs and repair invoices may help explain the premises’ condition, while a service record can establish when notice was sent. If a landlord alleges a breach, identify the exact covenant and supporting evidence. If the tenant disputes a charge, retain the account and payment records.

For tailored help assessing the lease and dispute documents, seek advice on a commercial lease dispute.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP provides commercial conveyancing and litigation and dispute resolution, relevant when a break notice or lease conditions are contested. If you are a tenant or landlord facing disagreement about notice validity, outstanding obligations or the condition of commercial premises, these legal services can help address the property and dispute issues involved.

Before seeking advice, gather the lease, any variation, the notice and evidence of service, along with relevant payment and repair records and correspondence with the landlord. These documents provide a clearer basis for discussing the disputed points and next steps. Feltons Solicitors LLP also provides Divorce and Financial Arrangements, Wills, Probate, and Estate Planning, and Personal Injury and Silicosis Claims.

Contact Feltons Solicitors LLP to discuss a commercial lease break dispute.

Take the next step with a clear plan

Your next decision is how to protect your position while the disagreement is addressed. Before taking further action, consider the outcome that matters most: ending the lease, resolving a disputed payment or clarifying responsibility for the premises. A clear account of your priorities can keep discussions focused and help identify the relevant evidence and next steps.

Speaking with commercial lease break clause dispute solicitors can help you understand the issues raised by your lease and the options available. Feltons Solicitors LLP provides residential and commercial conveyancing, as well as litigation and dispute resolution. Its wider services also include Divorce and Financial Arrangements and Wills, Probate, and Estate Planning.

For a measured discussion about your circumstances and possible next steps, contact Feltons Solicitors LLP. A considered approach can help you move forward with greater clarity.

Frequently Asked Questions

Can the break conditions be waived?

The parties can agree to change lease terms, but a tenant should not assume the landlord has waived a condition without clear agreement. A variation can record what has changed and how the break will operate; the landlord is not obliged to agree. If discussions are ongoing, keep written records and do not treat informal comments or silence as permission to disregard a condition.

How much notice do I need to give to exercise a break?

Commercial lease break notice periods are often six months, but the lease sets the required period. Check whether it runs from the date notice is served or another specified date, and follow any service provisions. For example, if the lease requires postal service, allow for any deemed delivery time. A late notice may not take effect on the intended break date.

What happens if my break notice is invalid?

An invalid notice usually leaves the lease in force, so the tenant remains responsible for its obligations until another break date or the end of the term. Do not assume a replacement notice can fix the problem: the lease may not allow another opportunity before the next break date. Review the notice and service records promptly, then consider the remaining contractual dates and obligations before deciding what to do.

What is a lease re-gear and when is it an alternative to a break?

What is a break clause in a UK commercial lease and how does it work?

A break clause is a contractual option allowing the landlord, tenant or both to end a commercial lease early. It may provide one fixed break date or a rolling right, subject to its notice period and conditions. For instance, a clause may let a tenant end the lease at the end of the third year. The clause’s exact wording determines how the option operates.

What conditions must a tenant satisfy to exercise a commercial lease break clause?

The tenant must meet the conditions set out in the lease. These may concern rent and other sums, compliance with covenants, repairs, reinstatement or the state of occupation. Check whether the clause requires absolute or material compliance, and note when each condition must be met. Keep evidence, such as repair invoices and payment records, to show how the tenant complied.