How to claim compensation for a defective product injury

How to claim compensation for a defective product injury

Defective product injury compensation claims may be possible if an unsafe product caused your injury. In the UK, a personal injury claim generally must be brought within three years of the injury or of becoming aware that it was connected to a specific defective product, according to The National Archives. A product may be defective because of its design, manufacture or inadequate warnings about hazards or safe use.

After an injury, it can be difficult to tell whether a product fault caused it and what to do with the product and paperwork. The evidence you preserve can help show what went wrong, how you were injured and who may be responsible.

This guide explains when you may have a claim, what evidence can support it and how liability may depend on the circumstances. It covers product liability, negligence and personal injury claims, as well as the usual steps from an initial letter to negotiations or court proceedings.

Key Takeaways

  • Assess whether the product may have been unsafe and who could be responsible for the harm.
  • Preserve the product and gather records, photographs and witness details that may support your account.
  • Understand how the legal route can depend on whether you bought the product and the type of loss involved.
  • Learn how Feltons Solicitors LLP can assist with personal injury claims and what may happen as a claim progresses.

Can I make a product liability claim?

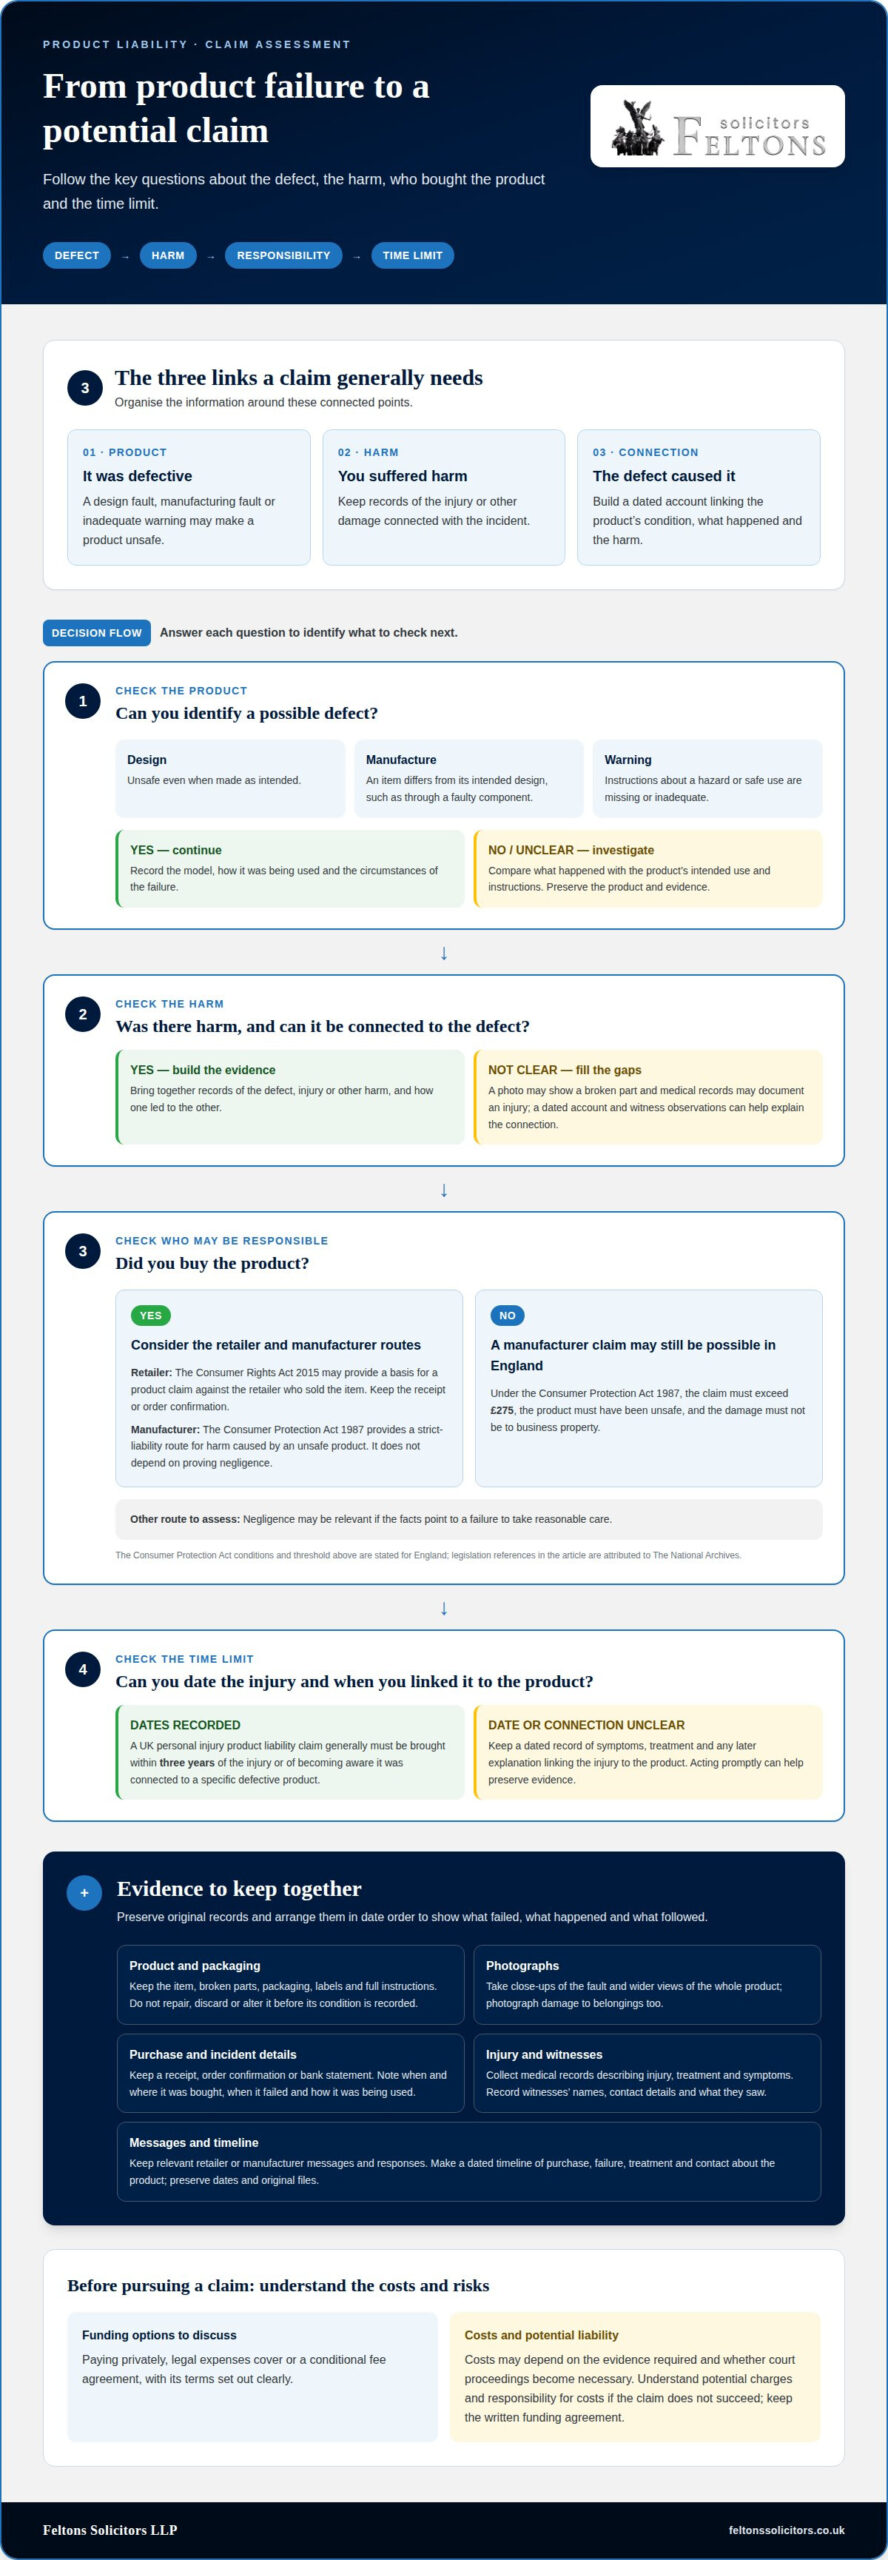
Start by identifying the suspected defect, the businesses connected to the product and the harm it caused. These details can help establish whether you may have a claim and who could be responsible.

  1. Identify the type of product defect

    Describe what went wrong and compare it with how the product was intended to work. A design defect may make a product unsafe even when manufactured correctly. A manufacturing defect occurs when an individual item differs from its intended design, such as through a faulty component. A warning defect may involve missing or inadequate instructions about a hazard or safe use. Record the product model and the circumstances of the failure.

  2. Identify potentially liable manufacturers, importers or suppliers

    Trace the product’s route from maker to seller using its packaging, labels, instructions and purchase records. The manufacturer may be liable if an unsafe product caused harm. Importers and suppliers may also help identify responsible businesses and the product’s route into the UK. Keep their names and addresses where available.

    In England, a person who did not buy the product may claim compensation from its manufacturer under the Consumer Protection Act 1987 if the claim exceeds £275, the product was unsafe and the damage was not to business property, according to The National Archives (UK legislation). For consumer help in England, contact the Citizens Advice consumer helpline on 0808 223 1133.

  3. Check the claim time limit

    Note the injury date and when you first connected it to the product. A UK personal injury product liability claim generally must be brought within three years of the injury or of becoming aware that it was connected to a specific defective product, according to The National Archives. Keep a dated record of symptoms, treatment and any later explanation linking the injury to the product. Acting promptly can also help preserve evidence.

  4. Review costs, funding options and risks

    Before pursuing a claim, establish what the legal work may cost and which funding route applies. Options to discuss include paying privately, using legal expenses cover or entering a conditional fee agreement, with its terms set out clearly. Costs may depend on the evidence required and whether court proceedings become necessary.

    Consider the financial risk if the claim does not succeed, including responsibility for costs under the agreed funding terms. Ask for a clear explanation of potential charges and liabilities before authorising work, and keep the written agreement for reference.

Evidence to support a claim

Build a clear record connecting the product, the fault and your injury. A UK claim generally needs evidence that the product was defective, you suffered harm and the defect caused it.

  1. Collect evidence to support the claim

    Keep the product, packaging, instructions, labels and any broken parts. Don’t repair, discard or alter the product before its condition has been recorded. If keeping it is impractical, take clear photographs from several angles, including close-ups of the defect and wider shots showing the whole product.

    Gather proof of purchase, such as a receipt, order confirmation or bank statement. Record when and where you bought the item, when it failed and what happened next. Write down the sequence while details are fresh, including how you were using the product and any visible damage to belongings. Photograph that damage too.

    Collect medical records describing your injury, treatment and symptoms. Ask witnesses for their names and contact details, then note what each person saw. Keep relevant messages with the retailer or manufacturer, including reports of the fault and their responses. Store copies together, preserving dates and original files.

  2. Establish what must be proved

    Organise the evidence around three points: the product was defective, you suffered injury or other harm, and the defect caused that harm. A photograph of a broken component may show its condition, while medical records document an injury. Neither necessarily explains how the failure happened, so link the evidence with a dated account and witness observations.

    Compare the product’s condition with its instructions and intended use. Note, for example, whether a part failed during ordinary use or whether a warning about the hazard was missing. Keep the full instructions, as a single page may lack important context. Create a simple timeline covering purchase, failure, medical treatment and any contact about the product.

    Presenting these records in order can clarify the connection between defect and injury. For help assessing evidence for an injury claim, you can explore personal injury claims.
How to claim compensation for a defective product injury

Negligence, breach of contract and strict liability

Identify the legal route that best fits your relationship to the product, the fault and the loss. In the UK, a product claim may rely on consumer rights, strict liability or negligence.

  1. Consider a claim against the retailer under the Consumer Rights Act 2015, which The National Archives (UK legislation) identifies as a basis for a product claim against the retailer that sold the item. This route focuses on the purchase and the retailer’s obligations. Keep the receipt or order confirmation, and describe how the product failed to meet the standard you expected. For example, a newly purchased appliance that stops working because of a faulty component may raise a retailer claim.
  2. Consider strict liability under the Consumer Protection Act 1987 when an unsafe product caused harm. This route does not depend on proving that the manufacturer was negligent, but the claim still needs evidence of a defect, damage and a connection between them. A manufacturer claim may be relevant even if you were not the buyer. Whether you can include the product’s cost in a compensation claim may depend on the circumstances of the claim.
  3. Assess negligence if the facts point to a failure to take reasonable care, such as a manufacturer overlooking a safety issue during production. A negligence claim requires proof of negligence, so identify the conduct or omission and how it caused the harm. If you did not buy the product and the claim is below £275, you may claim through negligence for damage caused by it against either the manufacturer or seller. Gather evidence that connects the relevant business, its conduct and the damage.

Separate the product’s purchase cost from other losses when organising your claim. A refund or replacement affects whether you can also claim the item’s cost. The legal basis determines what must be established against the retailer, manufacturer or seller.

Personal injury claims

An injury caused by a product is pursued as a personal injury claim. Set out the physical impact separately from financial losses so each can be assessed clearly.

  1. Identify the compensation that can be claimed

    List the injury’s effects and resulting costs, including medical expenses and earnings lost because you could not work. Keep bills, appointment records and payslips together, and note how each expense relates to the injury. For example, record travel to treatment separately from a routine journey.

    In defective product injury compensation claims, include ongoing needs, such as treatment or support you still require, and explain how the injury affects everyday activities. Someone who did not buy the faulty product may claim for damage and distress, but not the product’s own cost. Keep the product price separate from injury-related losses, especially if you have received a refund or replacement.

  2. Calculate the compensation amount

    Prepare a schedule of losses listing each expense, its date and the document that supports it. Include lost earnings with records showing income before and after the injury, and distinguish actual losses from future costs. A clear breakdown explains how the injury affected your finances without relying on an unsupported total.

    An assessment considers the injury and its effects alongside related financial losses. The nature and duration of symptoms, treatment, recovery and impact on daily life help describe the injury; receipts and employment records support expenses and lost earnings. Compensation for a defective product injury depends on the evidence and consequences, so no single figure applies to every case.

    A UK product liability claim may proceed through a letter of claim, compensation negotiations and, if needed, court proceedings where a judge decides compensation. For help pursuing an injury claim, discuss your personal injury claim with a solicitor.

Feltons Solicitors LLP: Personal Injury and Silicosis Claims

Feltons Solicitors LLP handles personal injury claims, including injuries caused by defective products. If you have been hurt and need help understanding a potential claim, the evidence or the compensation process, the firm can assist with the legal aspects.

Share the key details of what happened, the injury and the product involved. Relevant records, including medical documents, photographs and proof of purchase, can help clarify the circumstances and losses claimed. A solicitor can assess how the evidence relates to liability and the next steps in pursuing a claim.

For legal support with a personal injury claim, contact Feltons Solicitors LLP to discuss your situation.

Consider your next step

After an injury, deciding whether to pursue a claim can be difficult while you manage treatment and its effects on daily life. Advice on defective product injury compensation claims can help you understand how the evidence and circumstances relate to your options, and what information may be needed to move forward.

Before speaking to a solicitor, gather the records you have and note any questions about the injury, product or impact on your work and routine. You do not need to resolve every detail before seeking guidance. A focused discussion can clarify the legal issues and practical next steps for your situation.

Feltons Solicitors LLP also assists with divorce and financial arrangements, wills, probate and estate planning, and residential and commercial conveyancing. To discuss an injury claim, contact Feltons Solicitors LLP. Taking a considered next step can help you approach the process with greater clarity.

Frequently Asked Questions

What counts as a defective product under UK law?

A product may be defective if its design, manufacture or warnings make it unsafe. The assessment concerns product safety, not simply whether an item stopped working or disappointed you. For example, a component that breaks during intended use may raise a safety issue, while ordinary wear may not. The product’s instructions, purpose and circumstances of use help explain the difference.

Who can claim compensation for an injury caused by a defective product in the UK?

A person injured by an unsafe product may be able to claim even if they did not buy it. Under the Consumer Protection Act 1987, The National Archives (UK legislation) states that a non-buyer may claim against the manufacturer where the claim exceeds £275, the product was unsafe and the damage was not to business property. The appropriate defendant and legal route depend on the facts.

What evidence is needed to support a defective product injury claim?

Useful evidence includes the product, proof of purchase, photographs of the fault, medical records and witness details. Keep digital records too, such as order confirmations, messages to the retailer and the manufacturer’s response. For example, a dated photograph alongside a treatment record may help establish when the failure happened and when the injury was documented. Preserve original files and keep copies of records.

How do you make a defective product injury claim in England and Wales, Scotland or Northern Ireland?

Start by documenting the incident, seeking medical attention and keeping evidence of the injury and product. A UK product liability claim may then proceed through a letter of claim, compensation negotiations and, if needed, court proceedings where a judge decides compensation. The legal process and rules can differ between England and Wales, Scotland, and Northern Ireland, so take advice relevant to where the claim is brought.

Can a consumer claim under the Consumer Protection Act 1987 as well as the Consumer Rights Act 2015?

These Acts provide different potential routes: the Consumer Protection Act 1987 may support a claim against a manufacturer for harm caused by an unsafe product, while the Consumer Rights Act 2015 may support a claim against the retailer that sold it. The National Archives (UK legislation) identifies the latter as a basis for a retailer claim. Which route applies depends on the product, injury and parties involved.
Amputation injury compensation claims for injured people

Amputation injury compensation claims for injured people

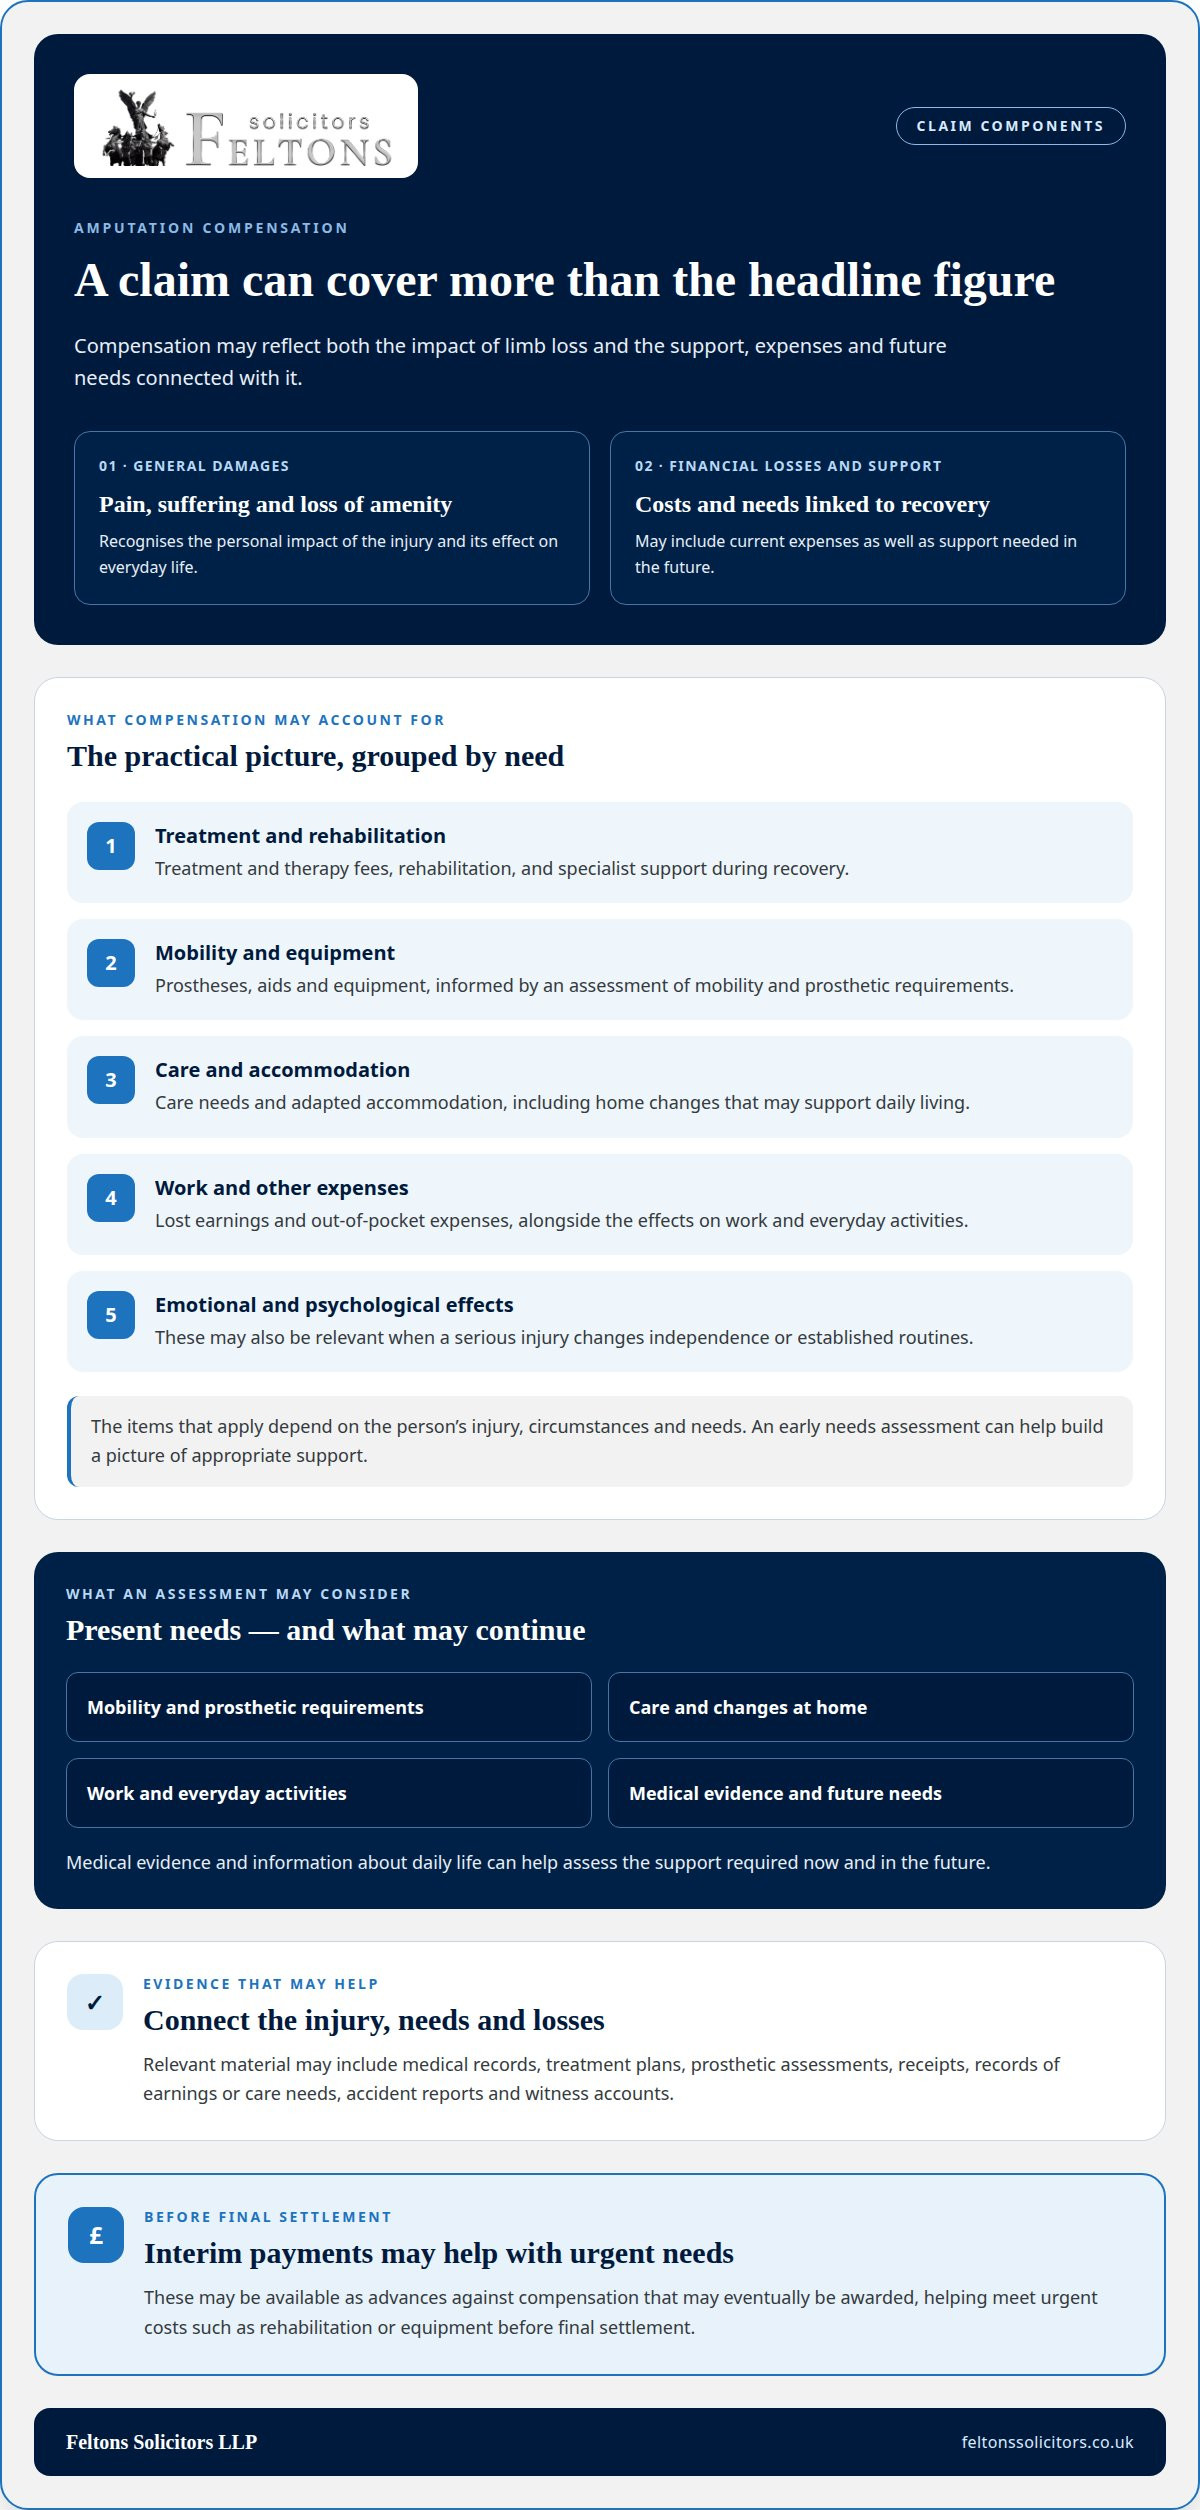
The headline figure is only part of an amputation claim. Compensation may cover pain, suffering and loss of amenity, as well as treatment, lost earnings, care, equipment, prostheses and home adaptations. Amputation injury compensation solicitors can also assess financial losses and future needs.

Time limits matter too. According to the UK Government, most personal injury and medical negligence claims must be made within 3 years of the accident or the date of knowledge. In England and Wales, compensation may be reduced if you share responsibility for the accident.

This guide explains what a claim may include, how shared responsibility and time limits can affect it, and why compensation varies by injury. It also sets out practical steps and the information that may help move a claim forward.

Key Takeaways

  • Identify when the relevant time limit starts, as the accident date and date of knowledge can both matter.
  • Build a clear picture of the support and expenses a claim may need to account for, including rehabilitation and prosthetic provision.
  • Understand how shared responsibility can affect the compensation payable, rather than assuming it automatically prevents a claim.
  • Use compensation ranges as a starting point, then consider how the injury’s location and its effect on future needs shape an individual assessment.

Is there a time limit for making an amputation claim?

In the UK, most personal injury and medical negligence claims must be made within 3 years of the accident or date of knowledge, according to the UK Government. The accident date is usually clear, such as the day a workplace machine caused an injury. The date of knowledge may matter where the connection between an earlier injury and later limb loss becomes apparent afterwards. Acting promptly helps preserve records and identify witnesses.

For an injured person who was under 18 when an accident happened in England and Wales, the usual three-year claim period does not begin until their 18th birthday. This means the adult time limit does not run during childhood. A parent or guardian can seek legal advice about a child’s circumstances before then, particularly where treatment, recovery or the cause of the amputation remains under investigation.

Amputation claims may follow workplace incidents, road traffic accidents, school accidents or playground accidents. Examples include machinery injuries at work, road collisions and serious injuries involving unsafe equipment. A medical negligence claim may arise if negligent treatment caused or worsened the injury that led to amputation. It must establish that the surgeon or practitioner was negligent. Each type of claim depends on evidence linking the responsible person’s or organisation’s actions to the limb loss.

Eligibility depends on more than the fact of amputation. A claim must show that another party was legally responsible and that their actions caused the injury or its consequences. Medical records, accident reports, witness accounts and treatment timelines can help establish what happened. For instance, records may link an accident injury to later surgery. If the injured person also contributed to the accident, a claim may still be possible, although compensation can be reduced to reflect their share of responsibility.

An amputation claim may sometimes proceed beyond the usual three-year limitation period if the original injury directly led to the later amputation. The link between the initial harm and the eventual limb loss is central. Evidence may need to show how an accident injury developed and why amputation followed. As dates and medical causation can be complex, early legal advice can help clarify the applicable time limit and what evidence supports the claim.

What does an amputation claim provide compensation for?

An amputation claim can cover both the immediate consequences of limb loss and needs that continue during recovery. Compensation may include treatment and therapy fees, rehabilitation, prostheses, aids and equipment, care, adapted accommodation, lost earnings and out-of-pocket expenses. For example, a claim may account for specialist rehabilitation and home changes needed to support daily living. General damages can also reflect pain, suffering and loss of amenity.

An early needs assessment can help identify appropriate support. It may consider mobility, prosthetic requirements, care needs and changes at home, as well as the effects on work and everyday activities. Lawyers use this information alongside medical evidence to assess present and future needs. Emotional and psychological effects may also be relevant, particularly when a serious injury changes a person’s independence or established routines.

When comparing amputation injury compensation solicitors, consider their experience with serious injury claims, rehabilitation planning and evidence of future needs. Ask how they will explain the claim’s progress and funding terms in clear language. These questions can help you understand the proposed approach before deciding how to proceed.

Fees depend on the case and are explained after a quote request. The work involved, complexity and funding arrangement affect costs. A no-win, no-fee agreement sets out how legal fees are handled if the claim succeeds or is unsuccessful. Read the terms carefully before deciding whether to proceed.

Evidence may include medical records, treatment plans, prosthetic assessments, receipts and records of earnings or care needs. Accident reports and witness accounts can help establish how the injury happened. Amputation injury compensation solicitors can review these materials to assess how they support the claim and its losses.

Interim payments may be available as advances against compensation that may eventually be awarded. They can help meet urgent needs, such as rehabilitation or equipment, before final settlement. Specialist legal support can assess how those needs relate to the claim.

For help with the legal aspects of a serious injury, explore personal injury claims support.

Amputation injury compensation claims for injured people

Contributory negligence

Contributory negligence means an injured person shares some responsibility for the accident. In England and Wales, that responsibility can reduce compensation rather than automatically prevent a claim. For example, if a claimant is found 25% responsible, they may receive 75% of the compensation otherwise payable. The reduction reflects the claimant’s share, so establishing how the accident happened remains important.

In a road traffic accident, evidence may show that another driver caused the collision while the injured person’s actions also contributed. The same principle can apply to workplace accidents involving machinery or safety procedures. Accident reports, witness accounts and relevant records help establish the sequence of events. The claimant’s conduct is considered alongside the actions of the person or organisation alleged to have caused the injury.

Medical negligence claims raise a different question: whether negligent treatment caused or worsened the injury that led to amputation. A claim must establish that the surgeon or practitioner was negligent. For example, evidence may need to show that a treatment decision or delay caused avoidable harm, rather than simply preceding the limb loss. Medical records and expert assessment can help explain the treatment, the injury’s progression and the connection to amputation.

Where negligence and the claimant’s actions both contributed, the evidence must distinguish their respective roles. A personal injury claim after an accident may involve a different chain of events from a clinical negligence claim following surgery or delayed treatment. The assessment considers what caused the harm and how each party’s conduct contributed. This can affect compensation, including payments for losses arising from the amputation.

Shared responsibility does not, by itself, determine whether a claim can proceed. The key steps are to establish the responsible party’s negligence, link it to the limb loss and assess any contribution by the claimant. Anyone who suffered an amputation after an accident or treatment should preserve relevant records and seek legal advice about how the evidence applies to their circumstances.

Amputation compensation ranges

Amputation compensation ranges offer a starting point for understanding general damages, including pain, suffering and loss of amenity. Figures vary according to the limb and level of amputation. They do not represent the full value of a claim, which may also include financial losses and the cost of future needs.

The location of the injury is only one part of the assessment. For example, ranges differ for an amputation above or below the knee. The claimant’s circumstances, recovery, ability to work and the effect on everyday activities also inform the overall claim. A settlement may therefore include general damages alongside special damages for proven financial losses and expenses.

Future needs can significantly affect the total claim. Evidence about prostheses, rehabilitation, care and necessary adaptations helps explain expected costs and practical impact. Interim payments may help meet urgent needs before final settlement. The final calculation should distinguish these expenses from the compensation range for pain and suffering, rather than treating one figure as the whole claim.

Use the ranges as a guide, then assess how the injury affects your individual circumstances and future needs. To discuss the factors relevant to your amputation compensation claim, contact the personal injury team.

Feltons Solicitors LLP: Personal Injury and Silicosis Claims

Feltons Solicitors LLP handles personal injury claims, including cases involving serious injuries such as amputation. If you are considering a claim after an accident or negligent treatment, legal advice can help clarify the evidence needed, the time limit and how compensation may reflect your losses and future needs.

A claim can involve complex medical records, questions about responsibility and an assessment of ongoing expenses. Feltons Solicitors LLP can guide you through the legal aspects of a personal injury claim and explain the next steps clearly. Early advice is particularly useful when treatment records, accident evidence or the connection between an injury and a later amputation need careful consideration.

To discuss your circumstances and possible next steps, contact Feltons Solicitors LLP.

Take the next step with a clear plan

After a serious injury, decisions about work, care and daily life can feel closely connected to the legal process. A useful next step is to list the questions that matter most to you, such as how a claim may address future needs or what evidence could explain the injury’s impact. This gives your discussion with a solicitor a practical focus.

Amputation injury compensation solicitors can assess the legal issues and explain how your circumstances may shape a claim. Feltons Solicitors LLP handles personal injury claims and can discuss your situation and the options available, recognising that every case is different.

If you’re ready to talk through your circumstances, contact Feltons Solicitors LLP. A considered conversation can help you decide what to do next, at a pace that feels manageable.

Frequently Asked Questions

How do I make a claim?

Start by obtaining legal advice about who may be responsible and whether the available evidence supports a claim. A solicitor can review relevant records, including accident reports, medical notes and correspondence about treatment. Keep documents showing expenses or changes to work and daily activities. For example, records of paid care can help explain the practical effects. The solicitor can then set out the proposed claim and its next steps.

Can I claim for “phantom limb” pain?

Yes. Pain experienced after an amputation can be included in the assessment of pain and suffering. Explain the symptoms to your treating medical professionals and describe how they affect everyday activities. Medical notes, treatment records and evidence of effects on sleep, mobility or routine can help show the impact. The claim must connect the symptoms to the injury and its consequences.

Can I claim for the psychological effects of losing a limb?

Yes. Psychological and emotional effects can be considered alongside the physical injury. Explain what has changed, such as confidence at work, social activities or independence, and discuss these effects with your healthcare team. Relevant clinical records and evidence of day-to-day impact can help document your experience. The assessment considers how amputation has affected your life, rather than treating the physical injury in isolation.

Can I claim if the accident was partly my fault?

Yes. Shared responsibility does not automatically prevent a personal injury claim, but it can reduce compensation to reflect your contribution. The circumstances and evidence are considered together, including what each person did and how that contributed to the accident. Witness accounts and accident records, for example, can help establish the sequence of events and inform the assessment of responsibility.

What does the loss of limb claims process involve?

The process typically involves investigating how the amputation occurred, gathering relevant records and assessing the injury’s effects. Medical evidence helps explain the condition and treatment, while financial documents show losses connected with the injury. The parties then consider responsibility and the claim’s value. Many amputation claims are settled out of court, although the route depends on the issues raised and whether liability and value can be agreed.

What compensation can you claim for an amputation injury in the UK?

A claim can include general damages for pain, suffering and loss of amenity, alongside special damages for financial losses and expenses. Depending on the evidence, these may cover treatment, rehabilitation, care, equipment, prostheses, home adaptations and lost income. The overall assessment considers the injury’s effects and the claimant’s needs, including future losses. Any award depends on establishing responsibility and supporting the claimed losses with relevant evidence.

Spinal cord injury compensation in the UK: claim values and care

Spinal cord injury compensation in the UK: claim values and care

Severe spinal cord injury compensation claims in the UK can reach six or seven figures. A claim may seek compensation if another party’s negligence caused the injury, including for pain and suffering, care, treatment, lost earnings and housing adaptations. The value depends on how the injury affects everyday life and the support needed over time.

It’s understandable to want a clear idea of what a claim could cover, especially when the effects may be long-lasting. A sound assessment looks beyond the injury itself to its impact on independence, finances and future care.

This guide explains what a spinal injury claim involves, how compensation for severe injuries is assessed, and what support and costs may be included. It also covers how compensation could affect means-tested benefits and practical steps to take after an accident.

Key Takeaways

  • Understand the evidence a claim needs, including how responsibility for the injury and its impact are assessed.
  • See how care, rehabilitation, lost earnings and home adaptations can contribute to a claim’s value beyond compensation for pain and suffering.
  • Learn why guideline figures don’t include lifelong care or lost earnings, and what that means when assessing severe injury compensation.
  • Find out how compensation may affect means-tested benefits and how a personal injury trust may help protect entitlement.

Can compensation cover lifelong care and support?

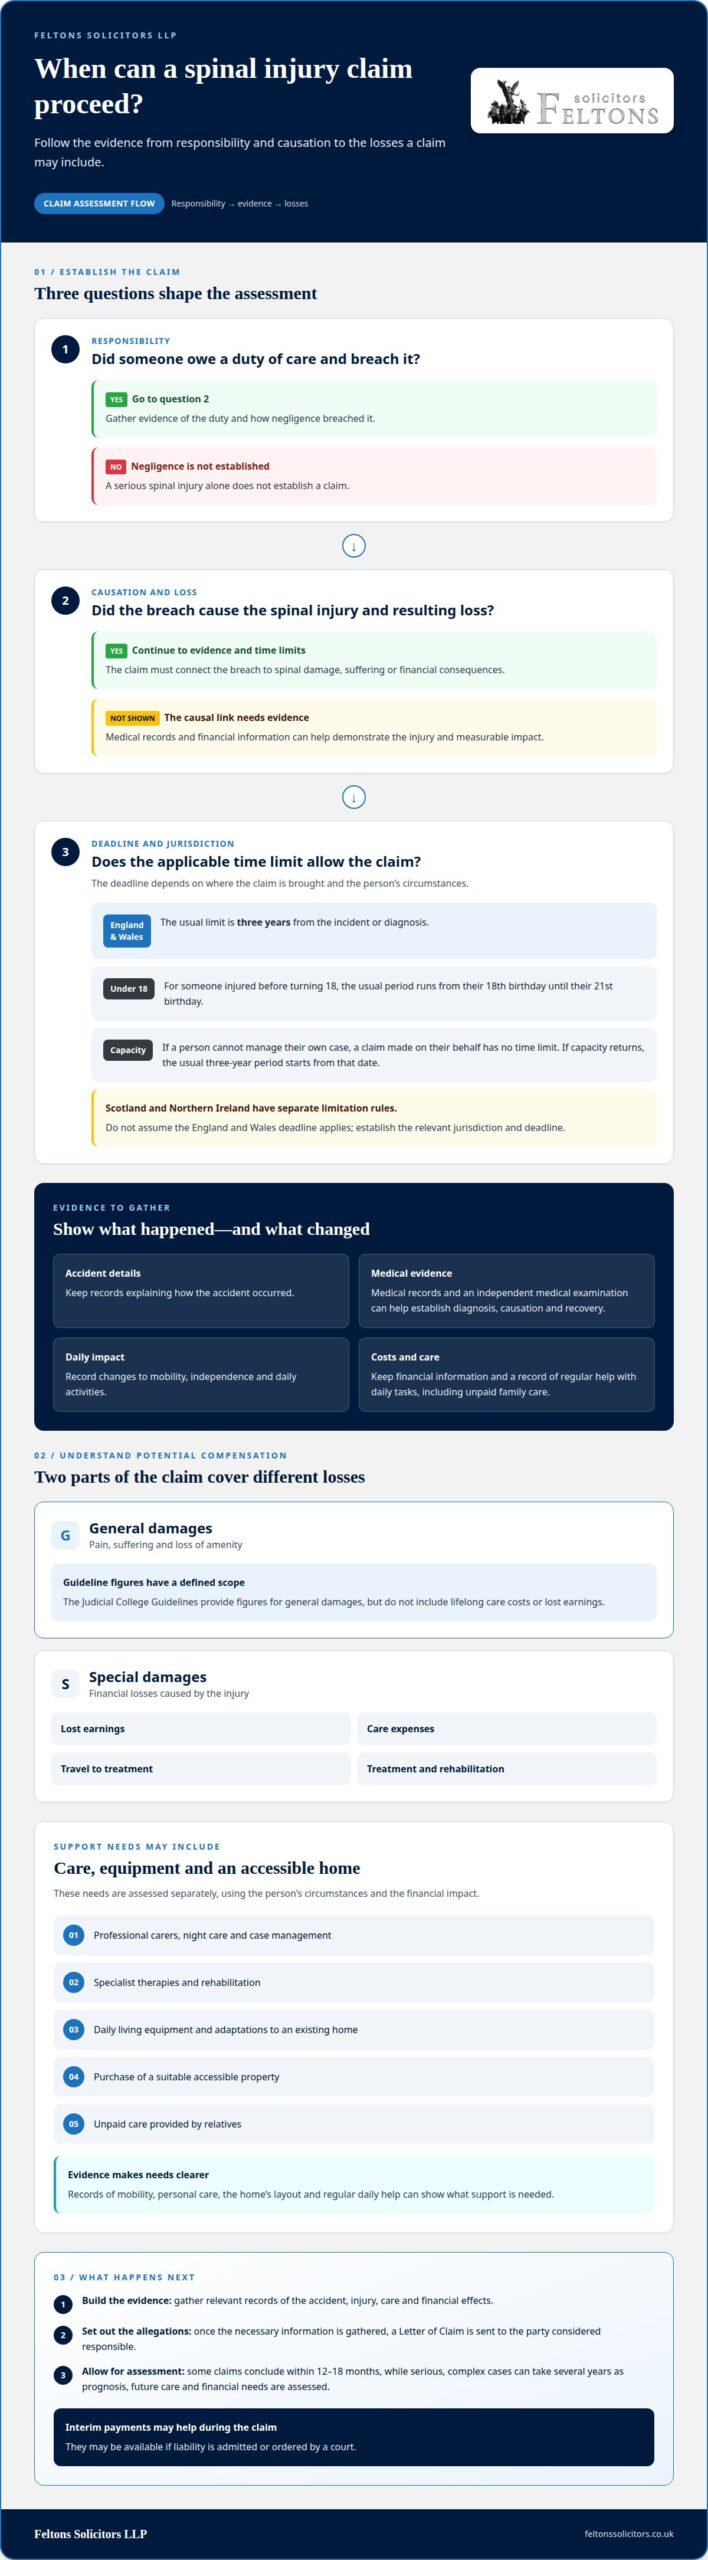
Yes. Compensation may cover care, medical treatment and rehabilitation after a spinal injury. In spinal cord injury compensation claims in the UK, special damages can include financial losses caused by the injury, such as lost earnings, care expenses and travel to treatment. General damages address pain, suffering and loss of amenity. The Judicial College Guidelines provide figures for general damages, but exclude lifelong care costs and lost earnings. These expenses need separate assessment based on the person’s needs and financial impact.

Support may include professional carers, night care, case management or specialist therapies. A claim can also cover daily living equipment, adaptations to an existing home or the purchase of a suitable accessible property. For example, evidence about mobility, personal care and the home’s layout can help demonstrate the support needed. Rehabilitation planning can identify suitable treatment and practical assistance as the person’s needs become clearer.

Care from relatives may also be valued as part of a claim. In spinal cord injury compensation claims in the UK, this can recognise unpaid help from family members rather than limiting the assessment to paid carers. A solicitor can help gather records of care, treatment and expenses, and show how the accident affects the injured person and their family. Keeping a record of regular help with daily tasks makes those needs easier to assess.

A claim must establish a duty of care, breach of duty, causation and measurable damages. It must show that someone owed a duty, negligence breached it, and the breach caused the injury and resulting loss. Evidence can include medical records and financial information. Serious spinal cord injury compensation claims in the UK often take several years, allowing time to assess the medical prognosis and long-term needs. If liability is admitted or ordered by a court, interim payments may help meet costs while the claim continues.

What should I do after an accident that causes a spinal injury?

After an accident, keep relevant records and document how the injury occurred. Eligibility depends on evidence linking someone’s negligence to the spinal injury and its effects.

Claim eligibility and negligence

A claim must show that someone owed a duty of care, breached it, and caused the injury or measurable loss. The evidence must connect the breach to the spinal damage, suffering or financial consequences. A serious injury alone does not establish negligence. In a clinical negligence claim, a healthcare provider must have failed to meet an acceptable standard of treatment, diagnosis or care, causing or materially contributing to the injury.

Starting a claim

Start by preserving records that explain the accident and its consequences. Evidence may include medical records, obtained with your permission, and an examination by an independent medical expert. These can help establish the diagnosis, the link between the accident and injury, and the effect on recovery. Once the necessary information has been gathered, a Letter of Claim is sent to the party considered responsible. An injury solicitor can assess the evidence and set out the allegations clearly.

Keep details of treatment and how the injury affects daily activities. For example, records can show whether your mobility or independence has changed since the accident.

Claim time limits

In England and Wales, the usual time limit is three years from the incident or diagnosis. For someone injured before turning 18, the period typically runs from their 18th birthday until their 21st birthday. If a person cannot manage their own case, a claim made on their behalf has no time limit. If they regain mental capacity, the usual three-year period starts from that date.

Scotland and Northern Ireland have separate limitation rules, so don’t assume the England and Wales deadline applies. Establish the relevant jurisdiction and deadline promptly. A solicitor handling a personal injury claim can help identify the applicable time limit and assess the evidence.

Spinal cord injury compensation in the UK: claim values and care

Does spinal cord injury compensation affect benefits?

Compensation can affect means-tested benefits because a damages award may change your financial circumstances. A personal injury trust may help protect benefit entitlement by holding compensation separately. The effect depends on your benefits and how the award is managed, so seek specialist advice before receiving or using damages.

Funding is another practical concern after a serious injury, particularly if earnings have fallen or care costs have increased. Many spinal injury claims use a no-win, no-fee arrangement. Under a Conditional Fee Agreement, the solicitor’s success fee is payable only if the claim succeeds. The agreement sets out how the fee works and what other costs or insurance arrangements apply.

With this funding arrangement, you don’t usually pay legal fees upfront, and no solicitor’s fee is payable if the claim fails, provided appropriate insurance is in place. Read the agreement carefully: it should explain the success fee, insurance and any costs that could remain your responsibility. A solicitor can assess the funding terms alongside the evidence and work involved, helping you understand the financial arrangements before deciding whether to proceed.

How do claims differ across the UK? The assessment considers responsibility, injury and resulting losses, but the applicable legal rules depend on the nation where the claim is brought. The time limit is a key difference: in England and Wales, the usual personal injury deadline is three years from the incident or diagnosis. Scotland and Northern Ireland have separate rules, so advice should reflect the correct jurisdiction.

How long do spinal cord injury claims take to settle? Some claims conclude within 12-18 months, while serious, complex cases can take several years. Time is needed to assess medical prognosis, future care and financial needs. An interim payment may help during the claim where liability is admitted or ordered by the court, supporting urgent needs before final damages are agreed.

Compensation ranges for severe spinal injuries

For paraplegia, the Judicial College Guidelines bracket is £267,340 to £346,890. For tetraplegia, the bracket is £396,140 to £493,000. These figures relate to pain, suffering and loss of amenity, not the entire value of a personal injury claim.

What affects compensation for paraplegia or tetraplegia? The assessment considers the injury’s severity, its effect on function and independence, and the care and support needed. Evidence about lost earnings, treatment, equipment and home adaptations can also affect the claim’s total value.

Special damages may cover financial losses caused by the injury. These can include professional care, rehabilitation, specialist equipment, lost earnings and home adaptations. For example, evidence of ongoing night care or a suitable accessible property can help explain future needs. The Judicial College Guidelines don’t include these costs, so they must be assessed separately.

Incomplete injuries can also lead to substantial claims when pain, reduced mobility or long-term support needs continue. The extent of recovery and the person’s likely future function help shape the assessment. In severe cases, spinal cord injury compensation claims may reach six or seven figures when full financial losses and care requirements are included. The amount depends on evidence of the injury’s personal and financial impact.

Before settlement, medical evidence and financial records help build a picture of ongoing needs. Serious claims can take several years to conclude while prognosis and future costs are assessed. Interim payments may be available during the claim once liability is admitted or ordered by the court. They can provide support before final damages are determined.

For a considered assessment of the injury, evidence and losses, discuss a personal injury claim.

Feltons Solicitors LLP: Personal Injury and Silicosis Claims

Feltons Solicitors LLP handles personal injury claims, including spinal injury claims. If an accident or another person’s negligence has caused a spinal cord injury, legal advice can help you understand how responsibility, medical evidence and future needs affect your claim.

For a serious injury, the assessment may need to consider more than the initial diagnosis. Care requirements, rehabilitation, changes to independence, lost earnings and adaptations can all be relevant to the losses claimed. A solicitor can explain the evidence needed and the steps involved, helping you make informed decisions about pursuing a claim.

To discuss a spinal injury claim, contact Feltons Solicitors LLP.

Choose a considered next step

After a life-changing injury, legal decisions sit alongside practical choices about family finances, housing and longer-term arrangements. For people considering spinal cord injury compensation claims in the UK, a focused conversation can help clarify which issues belong to the injury claim and which may need separate attention. You don’t need to have every detail resolved before seeking guidance.

Feltons Solicitors LLP handles Personal Injury and Silicosis Claims, Divorce and Financial Arrangements, Wills, Probate, and Estate Planning, and Residential and Commercial Conveyancing. These services may become relevant as an injury affects wider personal or property matters. Understanding how each issue is treated can help you set priorities and make informed decisions without assuming every concern forms part of a compensation claim.

A measured next step is to talk through your circumstances and identify the questions that matter most to you. Contact Feltons Solicitors LLP to discuss your next steps. With clear guidance, you can approach the decisions ahead with greater confidence.

Frequently Asked Questions

What is a spine injury claim?

A spine injury claim seeks compensation for harm caused by someone else’s negligence. It may relate to a road collision, workplace accident or negligent medical treatment. For example, a claim could address spinal damage and its effects on mobility, daily activities and finances. An injury alone isn’t enough: the claim must connect the harm and resulting losses to another party’s responsibility.

Can interim payments be claimed before the case ends?

Yes. Interim payments may be available before the final settlement if the responsible party admits liability or a court orders payment. A court may award them when it considers the claim has a high chance of succeeding. They can help meet needs during the case, such as treatment or support, while evidence about the longer-term impact is still being assessed. They are not the final damages award.

What spinal cord injury cases have settled successfully?

Reported outcomes include a roofer’s spinal injury claim after a fall, which settled for almost £2.7 million, and a catastrophic motorbike injury claim reported at £10 million. These examples show how outcomes can differ considerably; each reflects its own injury, evidence and financial losses.

Can family members be paid for providing care?

Yes. Care provided by relatives can be valued as part of a spinal injury claim, even when family members aren’t professional carers. To support this part of a claim, record the help provided, such as assistance with washing, dressing, meals or appointments, and how often it is needed. This information helps describe the care involved and its effect on family life.

How much compensation can I expect?

Judicial College Guidelines figures for pain, suffering and loss of amenity include £267,340 to £346,890 for paraplegia and £396,140 to £493,000 for tetraplegia. These figures don’t cover the whole claim. Care, lost earnings, rehabilitation, equipment and housing adaptations are assessed separately, so the overall value depends on the injury’s effects and the evidence supporting future needs.

What happens if liability is partly disputed?

If responsibility is shared, compensation may be reduced to reflect the claimant’s share of responsibility. For example, if a claimant is found 20% responsible for the accident, their compensation is reduced by 20%. The parties may negotiate over the evidence and each person’s contribution. If negotiations don’t reach agreement, the claim may go to court for a judge to decide liability and damages.