Lifetime gift tax planning and when gifts may face tax

Lifetime gift tax planning and when gifts may face tax

A lifetime gift can still affect inheritance tax, even after it has left your hands. In the UK, a gift that doesn’t qualify for another exemption is generally excluded from your estate if you survive seven years after making it. According to HMRC, taper relief applies only when the total value of gifts made in the seven years before death exceeds the £325,000 inheritance tax threshold. Sound lifetime gift tax planning legal advice starts with understanding what you gave, when you gave it and whether you continued to benefit from it.

It’s understandable to think that giving money or property away settles the tax question. The rules depend on the type of gift and the circumstances, so timing alone may not tell the whole story.

This guide explains what counts as a lifetime gift, how the seven-year rule and taper relief work, and which exemptions may apply. It also explains when lifetime gift tax planning legal advice can help you assess the effect of a gift on your estate and plan with greater clarity.

Key Takeaways

  • Identify whether a transfer is a lifetime gift, as its form and any benefit you retain can affect how it is treated for inheritance tax.
  • Use the seven-year rule to understand when a gift may still be considered in inheritance tax calculations.
  • Check whether an exemption may apply before assuming a gift will be taxable; the conditions can depend on how and when it was made.
  • Review gifts as part of your wider estate plan, particularly when making substantial transfers or giving regularly from income.

Potentially Exempt Transfers and the seven-year rule

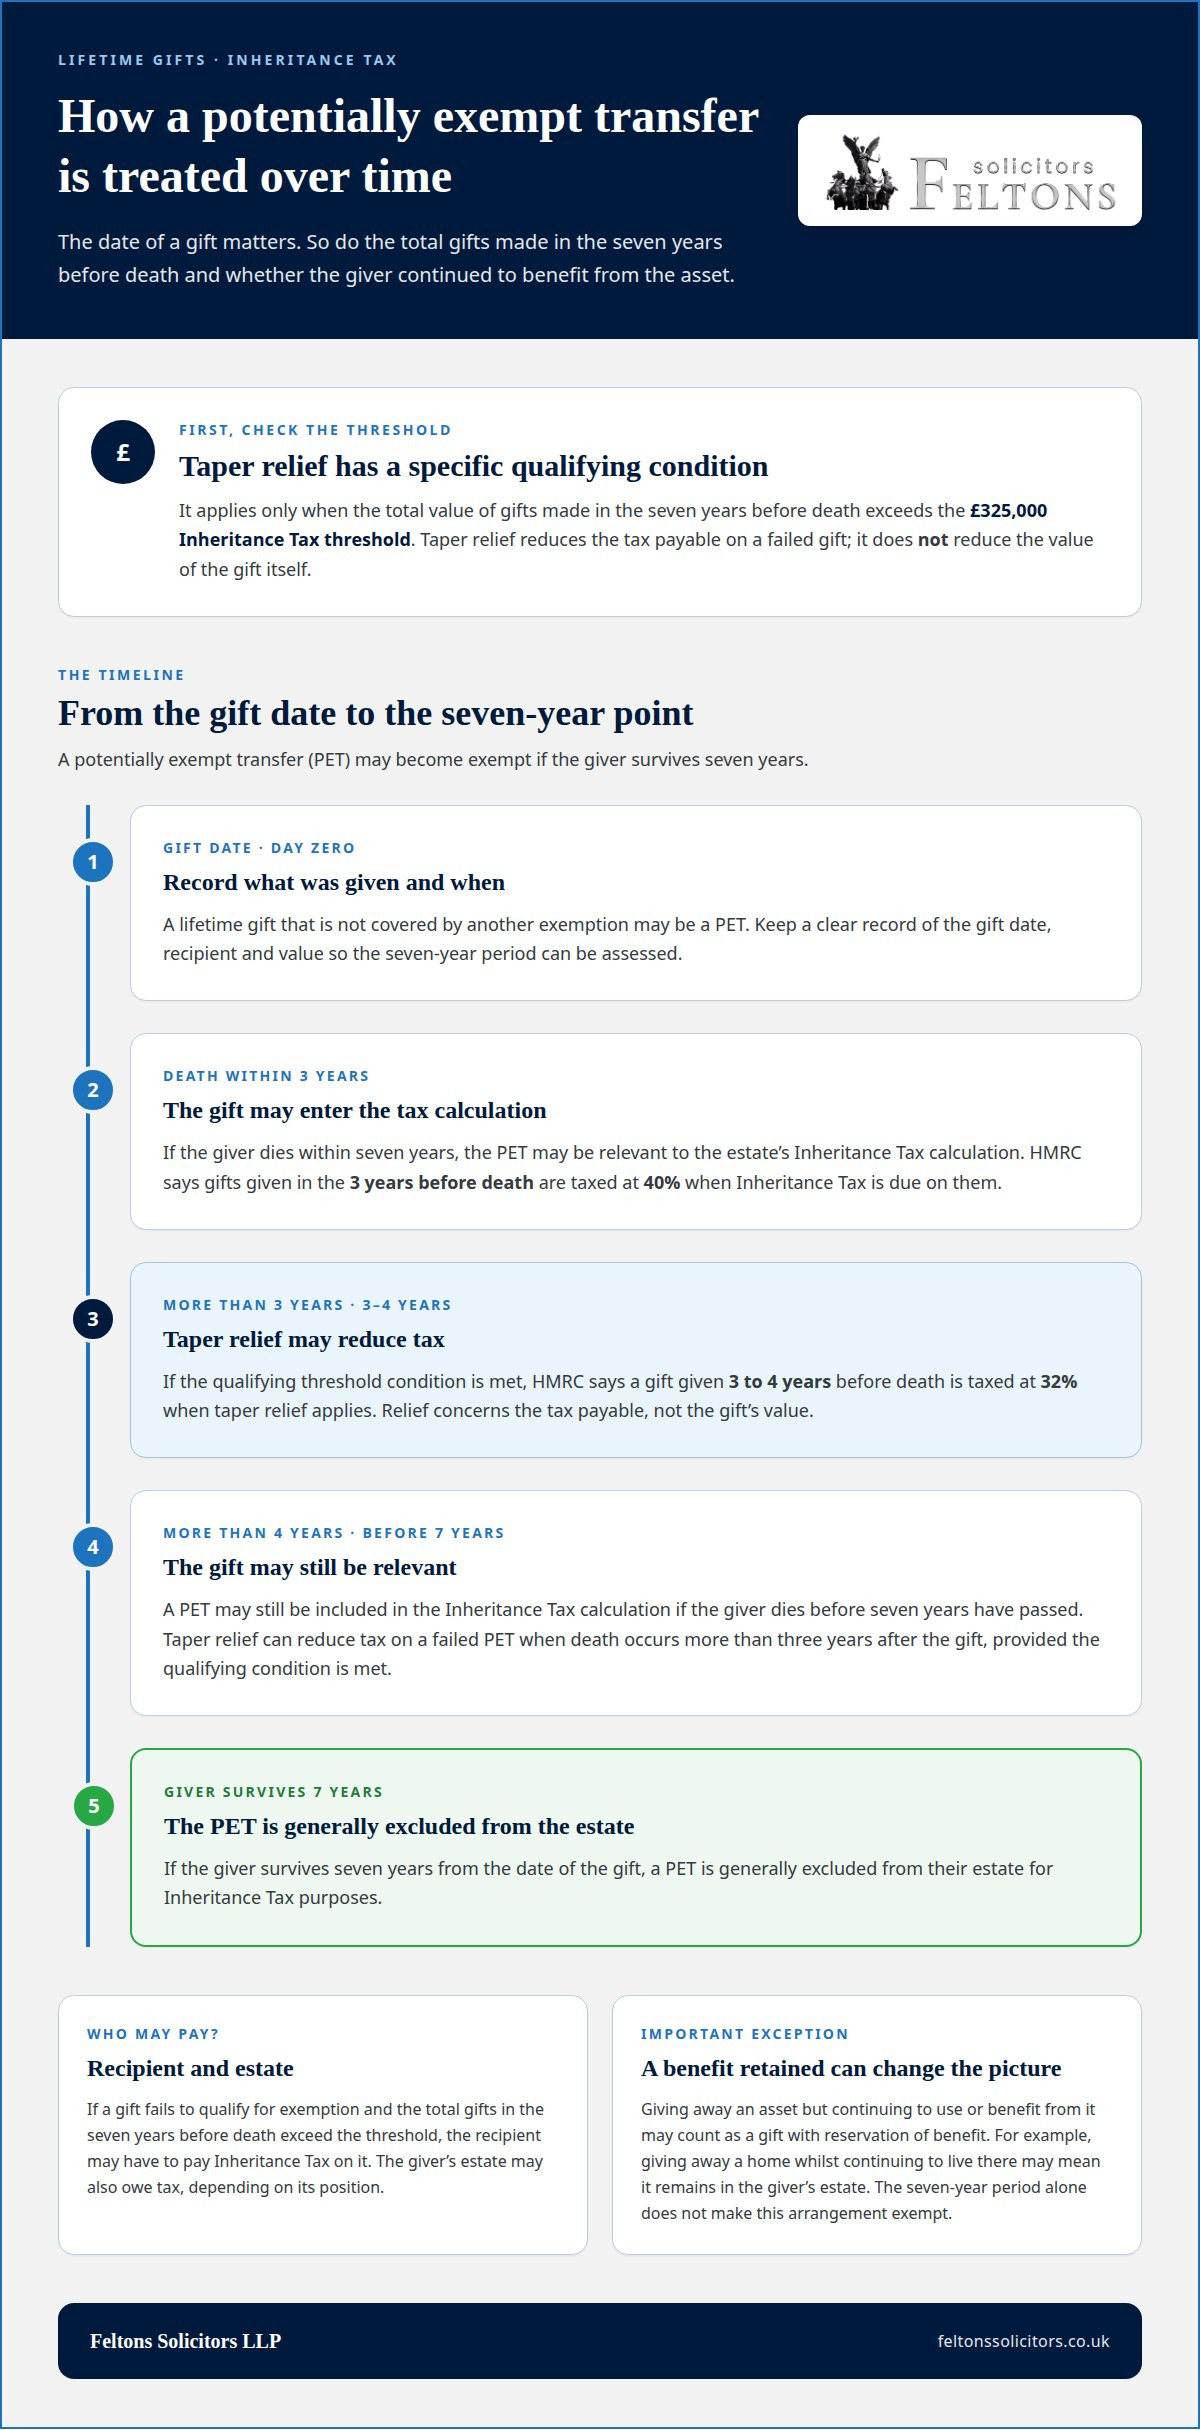
A potentially exempt transfer (PET) is a lifetime gift that may become exempt from Inheritance Tax if the giver survives seven years. If they die sooner, the gift may be included when calculating tax.

The seven-year rule

Under the seven-year rule, a PET is generally excluded from the giver’s estate if they survive seven years from the date of the gift. If they die within that period, the gift may be relevant to the estate’s Inheritance Tax calculation. A cash gift to a family member, for example, may be treated differently from a transfer covered by another exemption. Keep a clear record of the gift date when considering the seven-year period.

Taper relief and failed gifts

Taper relief reduces the Inheritance Tax payable on a failed PET when the giver dies more than three years after making it. It does not reduce the value of the gift itself. HM Revenue & Customs says taper relief applies only if gifts made in the 7 years before death exceed the £325,000 Inheritance Tax threshold. HM Revenue & Customs says taper relief taxes a gift at 32% when given 3 to 4 years before the giver’s death, if relief applies. The relevant period runs from the date of the gift to the giver’s death, not by tax year.

Inheritance tax payment responsibility

If a gift fails to qualify for exemption, the recipient may have to pay Inheritance Tax on it when the total gifts made in the seven years before death exceed the threshold. This is assessed after the giver’s death, when the estate and lifetime gifts are considered together. It may affect a family member who received a substantial gift but no funds to cover a later tax bill. The giver’s estate may also owe tax, depending on its position.

Gifts with reservation of benefit

A gift with reservation of benefit occurs when someone gives away an asset but continues to use or benefit from it. For example, giving away a home while continuing to live there may mean the property remains in the giver’s estate for Inheritance Tax purposes. Simply surviving the seven-year period does not make this arrangement exempt. A solicitor can consider how the gift works in practice, including who uses the asset and whether the giver retains a benefit. This distinction matters when a transfer is intended to reduce the estate’s taxable value.

Lifetime Giving and Inheritance Tax Planning: Is Now the Time to Act?

Lifetime gifts may reduce an estate’s value, but exemptions and the effect on your own finances also matter. Your estate plan should consider gifts, assets and future needs together.

Reducing an estate’s value

A lifetime gift transfers wealth out of your estate, which may reduce the value considered for Inheritance Tax. HM Revenue & Customs says an individual can give away £3,000 worth of gifts each tax year without those gifts being added to the value of their estate. Gifts outside an exemption may also leave the estate’s value if the giver survives seven years. Record the date, recipient and value of each transfer so the estate’s position can be established.

Gifting and inheritance tax exemptions

Exemptions allow some gifts to be made without adding them to the estate for Inheritance Tax, provided their conditions are met. HM Revenue & Customs says an individual can give as many gifts of up to £250 per person as they want each tax year, provided they haven’t used another allowance on the same person. Other exemptions may apply to qualifying gifts between spouses or civil partners, certain wedding gifts, and regular gifts from surplus income. For the last exemption, gifts must be regular, come from income rather than capital, and leave enough income to maintain the giver’s usual standard of living.

Advice from an inheritance tax solicitor

A solicitor can help assess how proposed giving fits your estate plan, including the nature of the assets and any benefit you retain. This can be particularly useful before transferring property, making substantial gifts, or relying on regular gifts from surplus income. From 6 April 2027, most unused pension funds and pension death benefits are due to be included in a person’s estate for Inheritance Tax purposes. Reviewing gifts alongside pensions and other assets helps clarify the wider picture. Estate planning advice can help you consider those connected decisions.

Inheritance tax rates and allowances

The UK nil-rate band is £325,000, and the standard Inheritance Tax rate is 40% on the part of an estate above the applicable threshold. HM Revenue & Customs says gifts given in the 3 years before the giver’s death are taxed at 40% when Inheritance Tax is due on them. The nil-rate band and Residence Nil Rate Band are fixed at their current rates until 2030. The amount due depends on the estate’s value and which allowances apply, so the figures should be considered alongside gifts and the estate’s other assets.
Lifetime gift tax planning and when gifts may face tax

An annual review helps keep gifting records and estate planning aligned as circumstances change. The tax year runs from 6 April to 5 April, so timing can affect which year an allowance applies to.

Annual and other gift exemptions

The annual exemption can be used alongside certain other exemptions, but each gift must meet the relevant conditions. Any unused annual exemption can be carried forward for one tax year only, and the current year’s allowance is used first. Reviewing your records can show whether an exemption has been used and help avoid counting the same gift twice.

Wedding or civil partnership gifts have separate limits: up to £5,000 for a child, £2,500 for a grandchild or great-grandchild, and £1,000 for another person. The gift must be made before or at the ceremony, and the event must take place for the exemption to apply. These amounts can be used alongside the annual exemption in the same tax year.

Annual and small-gift allowances

Small gifts and regular payments from income need careful records, not just a note of the amount transferred. To qualify as normal expenditure out of income, regular gifts must be made regularly, come from income rather than capital, and leave enough income for the giver to maintain their usual standard of living. Keep records of income, spending, dates and recipients. They can help executors explain the pattern to HMRC.

An annual gifting review can bring these records together, assess how each transfer fits your estate plan, and consider whether an asset has other tax consequences. Lifetime gift tax planning legal advice can help you review changes in income and expenditure and assess whether regular gifts qualify as payments from surplus income. A yearly review can also help you understand which records support your position and how your plans reflect your current circumstances.

Taper relief

Taper relief reduces Inheritance Tax on some lifetime gifts when the giver dies within seven years. Its effect depends on how long the giver survived after making the gift.

How taper relief works

Taper relief reduces the tax payable on a failed gift; it doesn’t reduce the gift’s value. It applies after the giver has survived more than three years, and the rate falls as more time passes. The relevant bands are 3 to 4 years, 4 to 5 years, 5 to 6 years, and 6 to 7 years. The rate of taper relief generally decreases as the time between the gift and the giver’s death increases. These reductions matter only where Inheritance Tax is due on the gift.

For example, the 4-to-5-year band applies a 24% rate, whilst the 6-to-7-year band applies 8%. Taper relief is therefore not an automatic exemption: the value of the gift, other gifts and available reliefs all affect whether tax is payable. A gift’s date and value are useful records when calculating the period and potential liability.

Agricultural and business property reliefs are separate from taper relief. They concern the treatment of qualifying agricultural or business assets, not the time elapsed since a gift. If a transfer involves a farm, business or partnership interest, identifying the asset and its ownership is an important step in understanding which reliefs may be relevant. The potential tax position depends on the asset and the conditions that apply.

Possible changes to taper relief

A proposal discussed in the UK could extend the seven-year Inheritance Tax rule to 10 years. This would affect the period in which lifetime gifts could be brought into account, but it is not itself a change to taper relief rates. For individuals planning transfers, the distinction matters: a longer period could alter which gifts fall within the rule, while taper relief concerns tax due on qualifying gifts. Estate planning should account for the rules that apply when a gift is made and the giver dies.

For advice on how gifts, assets and reliefs fit together, discuss estate planning with a solicitor.

Feltons Solicitors LLP: Wills, Probate, and Estate Planning

Feltons Solicitors LLP can help you consider lifetime gifts as part of your wider Wills, Probate, and Estate Planning. This may be useful when you’re weighing a substantial transfer, reviewing your estate plan or considering how gifts could affect the arrangements you want in place. Advice can bring together your wishes, assets and the practical consequences of giving, rather than treating each gift as an isolated decision.

Legal support can also help when changes in your family or finances prompt you to revisit your plans, or when you need to understand how your estate may be administered. Feltons Solicitors LLP can discuss options relevant to your circumstances and help you consider appropriate planning.

For guidance on lifetime gifts and estate planning, contact Feltons Solicitors LLP.

Make your next estate-planning decision with clarity

A useful next step is to turn your intentions into a plan that can be understood and administered. Consider who you want to benefit, which assets you may give, and how those choices fit with your wider financial and family arrangements. Clear records of your decisions can also help those responsible for your estate understand the context later.

Legal advice for lifetime gift tax planning can help you assess how a proposed transfer fits alongside your will and other arrangements. Feltons Solicitors LLP offers Wills, Probate, and Estate Planning, as well as Divorce and Financial Arrangements and Residential and Commercial Conveyancing. These services may be relevant when gifts connect with family changes, property or the wider administration of an estate.

For support considering your circumstances and next steps, contact Feltons Solicitors LLP for advice. A considered plan can help you move forward with greater confidence.

Frequently Asked Questions

What counts as a lifetime gift?

A lifetime gift is money, property or another asset you give to someone while you’re alive. It can include a cash transfer to a relative, handing over investments or transferring ownership of a home. Selling an asset for less than its full market value may also have gifting implications. If you continue to benefit from an asset after giving it away, that retained use can affect its Inheritance Tax treatment.

What allowances are available and how much can I gift?

HM Revenue & Customs says you can give away £3,000 worth of gifts each tax year without adding them to your estate’s value. You can also make as many gifts of up to £250 per person as you want each tax year, provided you haven’t used another allowance on that person. Unused annual exemption can be carried forward for one tax year only. The amount you can give is not capped, but gifts may have tax consequences.

What are the benefits of lifetime gifting?

Lifetime gifting lets you support people while you’re alive, whether by helping a family member with education costs or contributing towards a major purchase. Depending on the gift and the rules that apply, it may also reduce the value of your estate for Inheritance Tax. Giving can make your intentions clear during your lifetime, but consider your future income and financial security before transferring assets.

What can I do now?

Start by making a clear record of gifts already made, including the recipient, asset, date and value. If you make regular gifts from surplus income, gather information about your income and expenditure to show how those payments fit your finances. Then review your will and wider estate plan alongside any proposed transfer. A solicitor can help you assess how these elements work together.

What should I consider before making a gift?

Consider whether you can afford to give the asset away, whether you’ll still use or benefit from it, and whether the transfer has tax consequences beyond Inheritance Tax. Giving away a home but continuing to live there may mean it remains part of your estate for Inheritance Tax purposes. In England, a local authority may also treat a gift as deliberate deprivation of assets when assessing care-funding contributions.

Why make lifetime gifts?

People make lifetime gifts to provide practical help, pass on wealth or put estate plans into effect while they can explain their wishes. A gift may also reduce the estate’s eventual value for Inheritance Tax if the relevant conditions are met. The decision should balance the recipient’s needs with your future security. For example, regular support from income differs from giving away capital you may later need.
Trust creation and asset protection solicitors for property

Trust creation and asset protection solicitors for property

A trust is not a blanket shield for every asset. Trust creation and asset protection solicitors can explain how a trust may hold property, business interests or agricultural assets, and the practical and tax considerations involved. The right structure depends on what you own, who should benefit and how much control you want to retain.

It is understandable to want to protect assets while planning clearly for the people who may inherit or benefit from them. A trust can organise how assets are managed and passed on, but it needs careful consideration rather than being treated as a one-size-fits-all solution.

This article explains which assets may be placed in a trust, how trusts can relate to property, business and agricultural holdings, and what to consider about inheritance tax. It also outlines common trust arrangements and trustees’ roles, helping you approach the decisions with a clearer understanding of what may suit your circumstances.

Key Takeaways

  • Start by matching the assets you want to place in trust with the people who should benefit and the way they should benefit.
  • Factor in trustee responsibilities and the possibility of tax, including inheritance tax considerations, before settling on an arrangement.
  • Consider how property, business interests and agricultural assets are managed, and whether they may generate income within the trust.
  • Compare the purpose of discretionary, income-entitlement, Will, lifetime and disability trusts when considering which structure may fit your plans.

Trusts and inheritance tax considerations

Trust planning involves identifying assets, intended beneficiaries and tax considerations. Inheritance tax treatment depends on the arrangement and your circumstances.

Inheritance tax considerations

HM Revenue & Customs says trusts may have to pay tax. Tax is therefore a planning consideration, not an automatic outcome. Consider which assets would enter the trust, who could benefit and how trustees would manage them. For example, a home and an investment account need separate consideration because their uses and income differ.

Trustees manage trust assets in beneficiaries’ best interests. Before creating a trust, define its purpose and intended beneficiaries, then consider how its terms will affect asset management and future benefits. A beneficiary might receive income, inherit assets later or live in a trust property. These decisions help shape questions about inheritance tax.

Trust set-up and administration costs

There is no single charge that applies to every trust. Solicitors’ charges depend on the work and complexity involved, with a fee provided after a quote request. The trust’s assets, terms, beneficiaries and management arrangements can all affect the work required to prepare its documentation.

Administration is separate from setting up a trust. Trustees must manage its assets and act in beneficiaries’ best interests. A trust holding a rented home, for example, involves different practical management from one holding assets that produce no income. Consider the set-up and ongoing work separately.

Start by reviewing the assets and purpose. List what the trust may hold, who should benefit, and whether they need income, a future inheritance or use of a property. Then consider who will act as trustee and how decisions will be managed. The person establishing a trust may appoint themselves as trustee, while naming a successor can clarify who takes over if they die.

Finally, review the trust document against the intended arrangements. It records how a lifetime trust is to be managed. Clarifying responsibilities, beneficiaries’ needs and tax considerations before creation gives the arrangement a defined purpose. This helps frame a practical discussion about whether a trust suits your estate planning.

Trusts for property, business and agricultural assets

A trust can hold different assets, but each requires practical planning. Consider how ownership, management and beneficiaries’ needs fit together.

To compare solicitors near you, look for clear advice on the assets involved, trustee duties and trust terms. Ask how the proposed arrangement would address your aims, including ongoing management and tax considerations.

For property, consider who can use it and how it will be managed. A home held in trust might provide a place for a beneficiary to live or generate rental income. A business interest may require decisions about control and continuity. Agricultural assets may include land, buildings or business interests, each with distinct management needs.

Challenges to asset transfers

Yes, transferring assets into a trust can be challenged as deliberate deprivation. The circumstances and purpose of the transfer matter, including what was intended at the time. A trust should not be treated as a guaranteed way to prevent assets being considered in other decisions. Consider the reason for transferring each asset and record how the arrangement supports your wider plans.

Limits and risks of asset protection trusts

A trust does not remove every risk or guarantee that assets will be protected. Transferring an asset can also change who controls or manages it under the trust’s terms. Consider whether trustees can meet beneficiaries’ needs, how property or business interests will be handled, and whether the arrangement remains suitable as circumstances change.

According to the UK Government, assets held in a trust can generate income, such as rent from a home. That income and the practical work of managing the property should form part of the planning. For a business or farm, consider how trust ownership could affect day-to-day decisions and future continuity.

For property-related planning, Wills, Probate, and Estate Planning can help shape decisions about assets and beneficiaries.

Trust creation and asset protection solicitors for property

Assets that can be placed in a trust

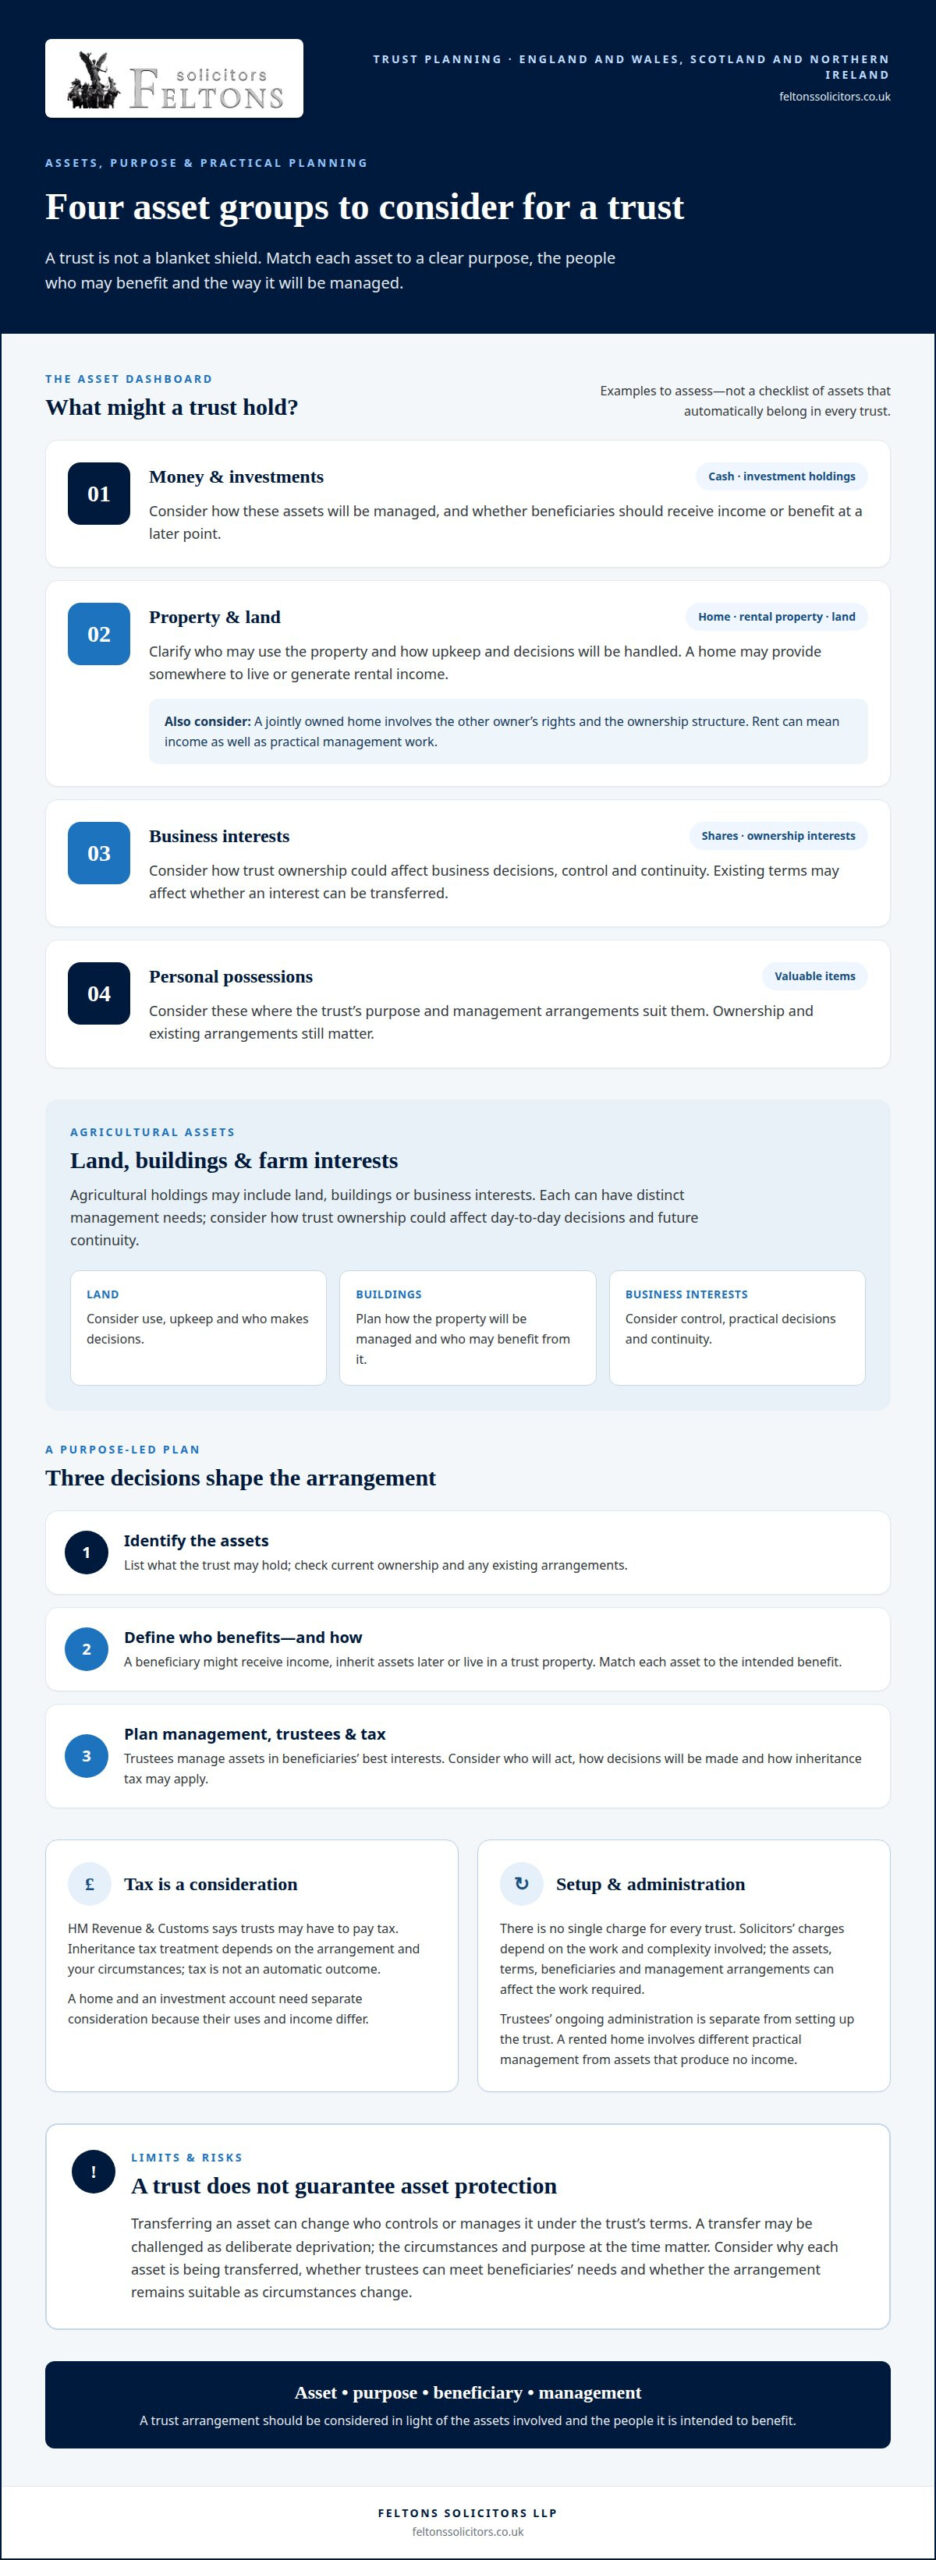
A trust can hold money or other assets for beneficiaries. Suitable assets depend on ownership, intended use and the trust’s terms. Trust creation and asset protection solicitors can help assess how each proposed asset fits your aims. Start by identifying what the trust may hold and what benefit it should provide. A cash fund, investment holding and family home each raise different management questions.

Examples of assets to consider include:

  • Money and investments: cash or investment holdings can form part of a trust. Consider how they will be managed and whether beneficiaries should receive income or benefit later.
  • Property and land: a home, rental property or land may be considered. Clarify who can use it and how decisions about its upkeep will be handled.
  • Business interests: shares or an ownership interest may be relevant. Consider how trust arrangements fit with business decisions and continuity.
  • Personal possessions: valuable items can be considered where the trust’s purpose and management arrangements suit them.

These examples are not a checklist of assets that automatically belong in every trust. Current ownership and existing arrangements matter. For a jointly owned home, for example, the other owner’s rights and the ownership structure need consideration. Business interests may also have existing terms that affect how they can be transferred.

Next, match each asset to a clear purpose. Decide whether the trust should provide income, preserve an asset for a future inheritance or allow a beneficiary to use it. Then consider who will manage it and what decisions they may need to make. This helps distinguish assets that support the trust’s purpose from those that complicate administration.

Set out the proposed assets and beneficiaries together. A home intended for a beneficiary’s use needs different management planning from cash intended to provide income. A business interest may require attention to decision-making, while land may need ongoing oversight. Trust creation and asset protection solicitors can help clarify how the proposed terms should reflect these practical responsibilities.

Finally, consider how each proposed transfer affects your wider estate plan. Reviewing an asset, its ownership and its intended role together gives you a clearer basis for deciding what to include.

What types of trusts are available in England and Wales, Scotland and Northern Ireland?

Trust options include discretionary, income-entitlement, Will, lifetime and disability trusts. For plans involving England and Wales, Scotland or Northern Ireland, establish the relevant jurisdiction before settling on a structure.

A discretionary trust gives trustees discretion over how beneficiaries benefit. This can suit plans where trustees need to consider beneficiaries’ differing needs over time. The trust document should clearly set out its purpose and management arrangements.

A trust with income entitlements gives a beneficiary an entitlement to income from trust assets. Consider who receives that income and how the underlying assets are managed. For example, both rental income and the property generating it need clear oversight.

A Will trust is created through a will and takes effect as part of estate planning. A lifetime trust is established during the settlor’s lifetime, using a trust document that records how it should be managed. Their timing and purpose distinguish these options. Consider whether the arrangement should form part of a will or begin during your lifetime.

A trust for a person with disabilities is designed around the beneficiary’s circumstances. Consider the person’s needs, the assets intended to support them and how trustees will manage those assets. The terms should connect the trust’s purpose with the support it is intended to provide.

Compare options by asking what beneficiaries need, who should make decisions and when benefits should be available. Then consider the assets involved and how trustees will manage them. A property intended for someone’s use may need different terms from investments intended to provide income. The structure should reflect the practical purpose, not rely on a trust label alone.

Since England and Wales, Scotland and Northern Ireland each form part of the UK’s trust-planning context, identify where the relevant assets and people are based. That helps frame advice on the appropriate structure and its terms. To discuss how trust choices fit your estate plans, arrange a conversation about your estate planning.

Feltons Solicitors LLP

Feltons Solicitors LLP can help you consider trust decisions within your wider estate and property plans. If you’re weighing how assets should benefit family members, its Wills, Probate, and Estate Planning service can support related planning discussions. Where property ownership forms part of your plans, Residential and Commercial Conveyancing may also be relevant.

Bring together the assets you are considering, your intended beneficiaries and the outcome you hope to achieve. This provides a clearer starting point for discussing how trust planning connects with your will, estate and property arrangements. A focused conversation about your circumstances and priorities is a practical next step.

Contact Feltons Solicitors LLP to discuss your estate planning questions.

Make your next planning decision with clarity

Before taking action, set out what you want the trust to achieve and how it fits your wider plans. Consider who should benefit, what role you want trustees to have, and whether your property or family circumstances may change. A clear outline of these priorities can make your next discussion more focused.

Trust creation and asset protection solicitors can help you consider how these decisions connect with your estate and property arrangements. Feltons Solicitors LLP’s work in Wills, Probate, and Estate Planning, Residential and Commercial Conveyancing, and Divorce and Financial Arrangements may be relevant where those matters intersect.

Bring your questions and the decisions you are weighing to a conversation. You can contact Feltons Solicitors LLP about trusts to discuss a practical next step. Thoughtful planning can help you move forward with greater confidence.

Frequently Asked Questions

Need help with a Trust?

Yes, a solicitor can help assess whether a trust fits your aims and circumstances. Prepare a brief outline of the assets involved, who you want to benefit and what you want them to receive. For example, a family home intended for a child’s future use raises different practical questions from investments intended to support someone now.

How do I set up a lifetime trust?

Begin by defining the trust’s purpose, intended beneficiaries and assets. Decide who should act as trustees, then establish how they should manage the trust and make decisions. A lifetime trust is created using a trust document that records its management arrangements. Consider how the terms will work in practice, including how trustees should respond if beneficiaries’ needs change.

What are settlors, trustees, and beneficiaries?

The settlor is the person who creates the trust and places assets into it. Trustees manage those assets under the trust’s terms, while beneficiaries receive the intended benefit. For example, a parent could establish a trust for a child, appoint trustees to manage its assets and set out how the child may benefit.

What can a family trust and asset protection solicitor do?

A solicitor can help a family understand trust options, clarify what the arrangement should achieve and consider how it fits with estate planning. They can also identify practical questions about beneficiaries, trustee roles and asset management. For instance, a family planning for a relative’s future support may need to consider who makes decisions and how those decisions are guided.

What does a trust and asset protection solicitor do in the UK?

A solicitor can explain trust structures, help consider suitable terms and discuss how a proposed arrangement fits your wider plans. This may involve considering asset ownership, beneficiaries, trustee responsibilities and tax implications. Feltons Solicitors LLP offers Wills, Probate, Trusts and Estate Planning, which can be relevant when considering how trust questions connect with your estate arrangements.

How can trusts protect assets from care fees, creditors or divorce in the UK?

A trust does not automatically protect assets from care-fee assessments, creditors or divorce-related claims. The purpose and timing of a transfer, the settlor’s control and the trust’s terms may all matter. Treat a trust as an estate-planning arrangement, not a guaranteed shield. Get advice on your circumstances before transferring assets or relying on a trust for protection.

Public liability injury claims and who can claim compensation

Public liability injury claims and who can claim compensation

An accident in a public place doesn’t automatically mean you can claim, but you may be entitled to compensation if another party’s negligence caused your injury. Public liability injury claim solicitors can assess whether the circumstances support a claim. In England and Wales, the Occupiers’ Liability Act 1957 places a duty on those responsible for public spaces to take steps to ensure visitors’ reasonable safety, according to UK Parliament.

It’s understandable to be unsure whether your injury is covered or who should be held responsible, particularly when the accident happened in a place open to the public. Personal injury claimants usually have three years from the date of injury to make a claim, according to UK Parliament.

This guide explains who may bring a public liability injury claim, which injuries may be covered and what financial losses compensation could include. It also outlines the time limit and practical steps, helping you assess whether your circumstances may justify taking the matter further.

Key Takeaways

  • You may be able to claim if another party’s negligence caused your injury; responsibility for public spaces in England and Wales includes a duty to take reasonable steps to keep visitors safe.
  • Personal injury claims usually have a three-year time limit from the date of injury, so understanding when the deadline applies can help you decide what to do next.
  • Compensation may account for both the effects of an injury and related financial losses, such as treatment costs or lost earnings.
  • Injuries from accidents in public places can vary widely; the circumstances, evidence and impact on your life all help determine whether a claim may be possible.

Who can make a claim for Public Liability Compensation?

You may be able to claim if another party’s negligence caused your injury or property damage in a public place. The key questions are whether they failed to take reasonable care and whether that failure caused the harm.

Understanding public liability injury claims

A public liability injury claim seeks compensation from a person or organisation whose activities or unsafe premises caused injury or property damage. Under the Occupiers’ Liability Act 1957, those responsible for public spaces in England and Wales have a duty to take steps to ensure visitors’ reasonable safety, according to UK Parliament. There is no fixed settlement timetable: liability, medical recovery, available evidence and negotiations affect how long resolution takes. Rules are not uniform across the UK; this Act applies to England and Wales, so the law relevant to an accident in Scotland or Northern Ireland may differ.

Accident settings and unsafe conditions

Claims may arise in shops, restaurants, leisure venues, car parks, other business premises or public spaces. Examples include slipping on an unmarked wet floor, tripping over damaged paving or being struck by falling stock. The location alone does not establish responsibility. The issue is whether an unsafe condition caused the accident and injury.

After an accident, report it promptly to the manager, owner or relevant authority. Ask for the incident to be recorded, and note the date, time and precise location. If you can, photograph the hazard and surrounding area before conditions change. For a pavement defect, a 10p or 50p coin beside the hole can help show its depth or height.

Keep details that may help explain what happened and its consequences:

  • Witness names and addresses, plus any account they provide.
  • Medical records and details of treatment, including a GP visit or hospital attendance.
  • Receipts for prescriptions, travel to treatment and damaged belongings.

Members of the public may claim where another party’s negligence caused their harm. A court-appointed litigation friend can act for someone under 18 or someone unable to claim themselves, acting in that person’s best interests. These records help lawyers assess responsibility and support the account of the accident.

Personal injury claim time limits

For most public liability personal injury claims, the usual deadline is three years from the date of injury. The starting point can differ in some circumstances, including clinical negligence claims and claims involving children.

The time limit for making a claim

Personal injury claimants usually have three years from the date of injury to start a public liability claim, according to UK Parliament. The deadline concerns starting legal proceedings, not completing treatment or recovery. Record when the accident happened, when symptoms began and how your condition developed. If the cause of an injury became clear later, the date you became aware of it may affect the calculation.

Claim time limits and exceptions

Children have a different deadline: they have three years from their 18th birthday to make a public liability claim, according to UK Parliament. The applicable deadline for a claim made on behalf of someone who has died may depend on the circumstances. These rules make the claimant’s age and circumstances central when working out the relevant deadline.

Clinical negligence has a stated limitation period of three years from the event that caused the injury or illness, or from when the claimant became aware that the event caused harm. For example, someone may connect an ongoing injury with earlier treatment only after receiving later medical information. The event date and date of awareness are therefore important when assessing this type of claim.

Funding arrangements do not extend a limitation period, so keep the deadline in mind while considering how to fund a liability compensation claim. In England, under a conditional fee agreement, the solicitor receives no fees if the claimant loses, although the claimant may still have to pay the other side’s legal fees and expenses. If the claim succeeds, arrangements for paying the solicitor’s fees and expenses depend on the funding agreement.

Some house contents, car or travel insurance policies in England include legal expenses cover that may help with personal injury legal costs. Review the policy wording for the type of claim covered and any conditions. Personal injury claim advice can help clarify the relevant deadline and funding arrangement.

Public liability injury claims and who can claim compensation

Compensation for injury and financial losses

A compensation claim may cover the injury’s effects and financial losses caused by the accident. The amount depends on the injury, recovery and evidence supporting each loss.

Compensation amounts for injuries

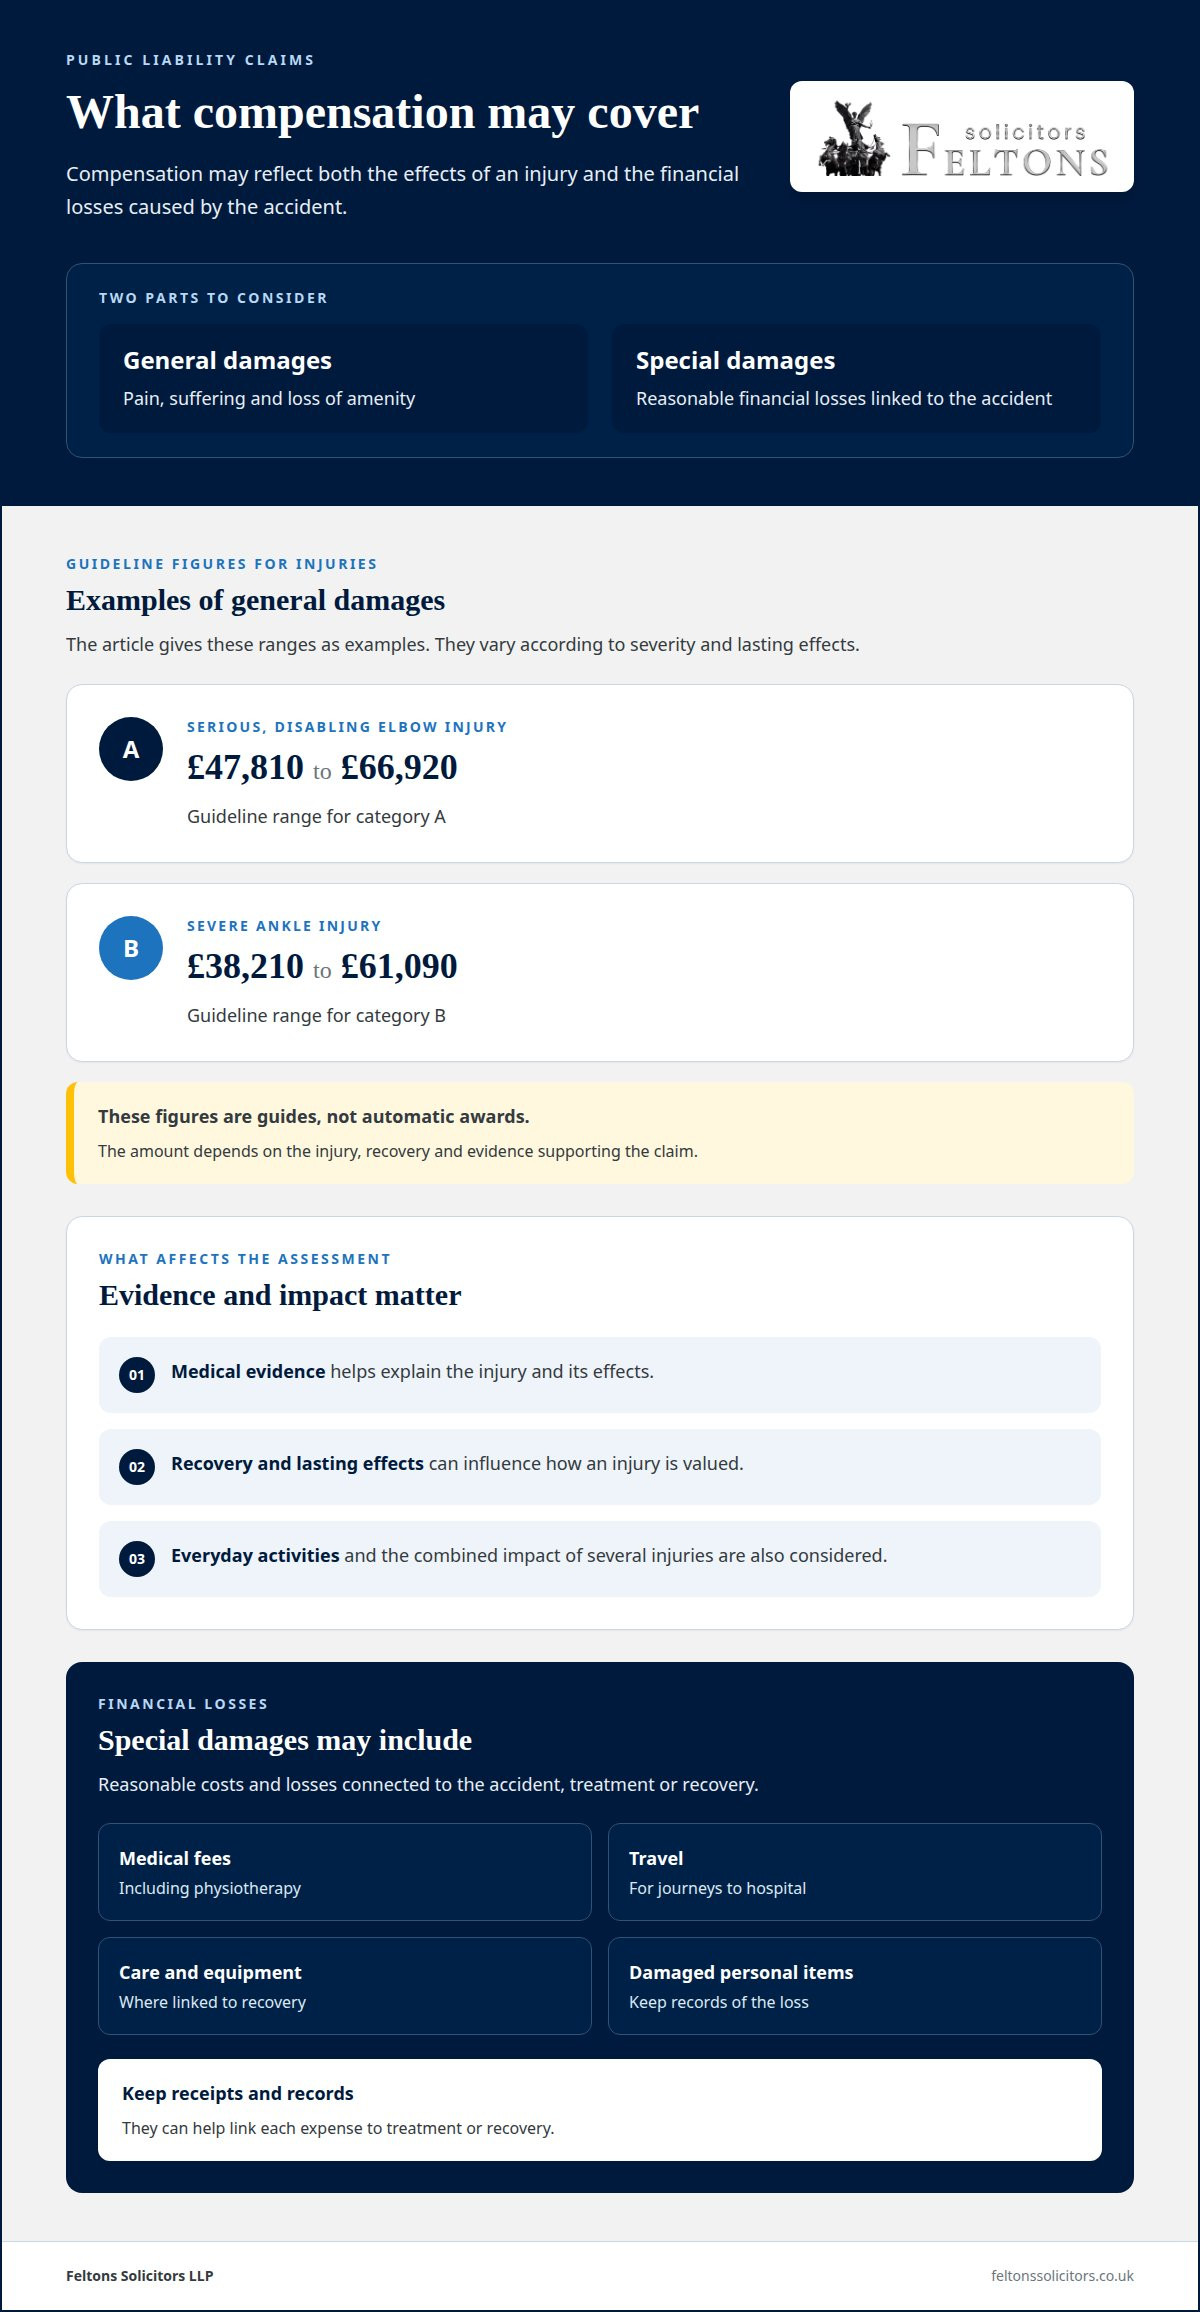
General damages reflect pain, suffering and loss of amenity. Guideline figures vary with the injury’s severity and lasting effects. For example, a serious, disabling elbow injury in category A has a guideline range of £47,810 to £66,920. A severe ankle injury in category B has a range of £38,210 to £61,090. These figures are guides, not automatic awards.

The assessment considers medical evidence, recovery and the effect on everyday activities. A fracture with continuing symptoms may be valued differently from an injury that heals fully. If several injuries occur together, their combined impact also matters.

Losses and expenses

Special damages may cover reasonable financial losses linked to the accident, such as medical fees, physiotherapy, travel to hospital, care, equipment and damaged personal items. Keep receipts and records linking each expense to treatment or recovery. For serious injuries, an assessment may also consider care needs, home adaptations and future costs.

Compensation for loss of earnings

If an injury stops you working, lost earnings may form part of your claim. Evidence could include payslips, employer records and details of time away from work. If a serious injury affects your future employment, the assessment may also consider future salary and pension losses. It looks at how the injury changed your ability to work, not simply how many days you missed.

Factors affecting compensation

The injury’s severity, recovery, treatment needs and effect on daily life all influence compensation. Evidence of expenses and earnings helps show the financial impact. Responsibility matters too: where a claimant is equally responsible for the accident or injury, the payout may be reduced by 50%. The organisation’s role, the available evidence and the connection between the accident and each loss are also relevant to the overall assessment.

Injuries covered by public liability claims

No single injury type automatically qualifies for public liability compensation. The central issue is whether another party’s negligence caused the harm and whether evidence supports that connection. A relatively minor injury can have lasting effects, while a serious diagnosis alone does not establish responsibility.

Claims may involve physical injuries suffered in shops, restaurants, car parks or public walkways. Examples include a sprained ankle after a fall, a fracture caused by a trip or a head injury from falling stock. Back, wrist, knee and elbow injuries can also affect movement, work and everyday activities. The circumstances and consequences matter as well as the medical diagnosis.

Slips and impacts can cause soft tissue injuries, bruising and strains. More serious accidents may cause brain injuries, significant fractures or lasting disability. Rest, ice, compression and elevation are often advised for minor strains, bruises and soft tissue injuries. Medical records can document the injury, treatment and recovery, showing how the harm developed after the accident.

To assess a claim, a specialist considers how the accident happened, what condition caused it and how the injury affected you. For example, evidence of a damaged step alongside medical notes recording an ankle fracture may help establish a clear sequence. Witness accounts, photographs, incident reports and treatment records can each support different parts of your account.

Evidence should capture practical consequences as well as the diagnosis. Note changes to walking, sleep, caring responsibilities or paid work, and keep receipts for treatment, travel and other related expenses. These details help explain the injury’s impact and identify associated losses. Public liability injury solicitors can assess how the available evidence supports your claim.

Discuss your public liability injury claim to understand how the injury, its cause and supporting evidence can be assessed together.

Feltons Solicitors LLP: Personal Injury and Silicosis Claims

Feltons Solicitors LLP handles personal injury and silicosis claims, including cases arising from accidents in public places or business premises. Our solicitors can assess the circumstances, available evidence and effects on your health and daily life, helping clarify the issues involved.

If you are considering whether to proceed, Feltons Solicitors LLP can explain the legal process and the information relevant to assessing your claim. This can help you weigh the next steps with a clearer understanding of your position.

For advice about a potential personal injury claim, contact Feltons Solicitors LLP.

Take the next step with a clearer picture

After an accident, uncertainty about responsibility, evidence or the effect on your future can make it difficult to decide what to do. A focused legal assessment can bring these issues together and identify practical next steps for your circumstances.

Feltons Solicitors LLP can consider how the accident occurred, the available records and the impact on your health and everyday life. This gives you a clearer basis for deciding whether to pursue a claim and what information may be relevant. The strength and value of any claim depend on its individual facts.

Feltons Solicitors LLP handles personal injury and silicosis claims. If you would like to discuss your situation and understand the options available, contact Feltons Solicitors LLP. Taking that conversation at your own pace can help you make an informed decision about what comes next.

Frequently Asked Questions

What injuries can I claim for?

You may be able to claim for a physical injury caused by another party’s negligence, but a diagnosis alone does not establish liability. A shoulder injury from an unsecured barrier or a burn caused by unsafe equipment could be considered if evidence links the hazard to your harm. The injury’s severity, duration and effects on everyday activities help shape the assessment. Medical records can document symptoms and treatment.

How are public liability accident injuries treated?

Treatment depends on the injury and its clinical needs. A healthcare professional may assess symptoms, recommend treatment and arrange follow-up. More serious injuries may need specialist care or rehabilitation. Keep appointment letters, treatment plans and records of changes in your condition. For example, notes about restricted movement after a shoulder injury can show how symptoms affected daily tasks over time.

Can I claim if the accident was partly my fault?

A claim may still be possible if you shared responsibility for the accident. Compensation may be reduced to reflect your share of fault, so evidence about each person’s actions matters. For instance, investigators may consider whether a hazard was clearly marked and whether your actions contributed to the incident. Give an accurate account, including details that may not seem favourable.

How do I find the right solicitor?

Look for a solicitor with relevant personal injury experience and a clear understanding of public liability cases. In England, the Law Society’s personal injury accreditation scheme is one relevant credential to consider. Ask how the solicitor will assess responsibility, gather evidence and keep you informed. A useful initial discussion should explain the proposed approach in plain English and identify the information needed to assess your circumstances.

How much compensation will I receive?

There is no single award for a particular accident. Compensation depends on the injury and its consequences, including medical evidence, recovery, restrictions on daily life and documented financial losses. For example, two people with similar fractures may have different claims if one quickly returns to normal activities while the other needs continuing care or can no longer do their usual work.

How much do I have to pay to pursue a claim?

What you pay depends on the funding agreement and its terms. Under a conditional fee agreement in England, a solicitor receives no fees if the claim is unsuccessful, but you may still be responsible for the other side’s legal fees and expenses. If you win, the other side will normally pay the solicitor’s fees and expenses. Read the agreement carefully to understand your position.