Restrictive Covenant Discharge Solicitors: A UK Property Owner’s Guide

Restrictive Covenant Discharge Solicitors: A UK Property Owner’s Guide

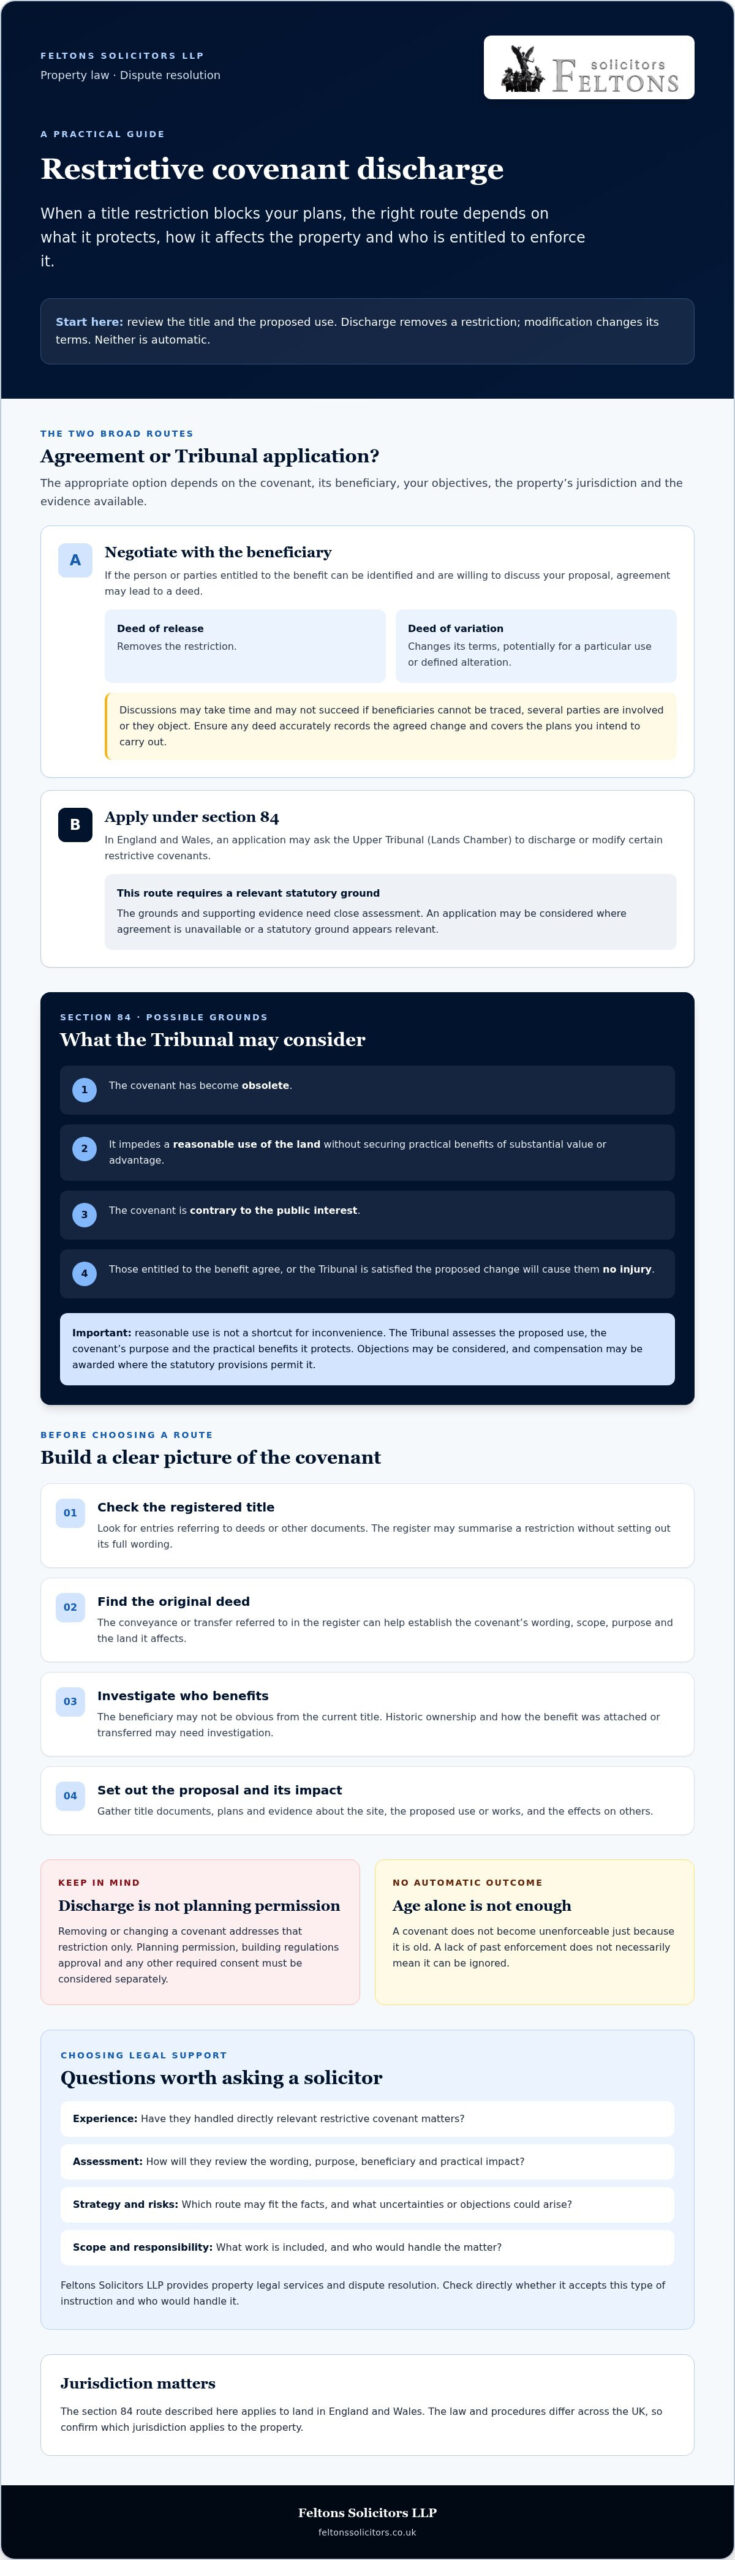
Could a covenant that blocks your plans be changed without a lengthy dispute? The right route depends on what the restriction protects, how it affects your property and whether the person entitled to enforce it can be found. Restrictive covenant discharge solicitors can help assess those points, but the first step is a careful review of the title and your proposed use.

It’s understandable to feel stuck when a title restriction appears to rule out an extension, change of use or development. In some cases, negotiation with the beneficiary may lead to a deed of release or modification. For land in England and Wales, an application under section 84 of the Law of Property Act 1925 may be another option. The relevant legal grounds and supporting evidence need close assessment.

This guide explains the available routes, the factors that may influence an application and why identifying the beneficiary matters. You’ll also find out which title documents and evidence to gather, and what to ask a solicitor about directly relevant experience and who would handle your matter. This can help you choose a proportionate next step.

Key Takeaways

  • Understand how a restrictive covenant can limit the use of land, and why it may not be straightforward to identify who benefits from it.
  • Compare a negotiated deed of release or variation with an application to the Upper Tribunal (Lands Chamber) under section 84.
  • Assess the covenant’s wording, purpose and practical impact, then gather title documents, plans and evidence about the site.
  • Use restrictive covenant discharge solicitors to help evaluate the possible route, and ask about relevant experience, strategy, scope and risks.
  • Feltons Solicitors LLP provides property legal services and dispute resolution. Check directly whether it accepts this type of instruction and who would handle it.

Restrictive covenant discharge: what it means for your property

A restrictive covenant is a legally binding promise that limits how land can be used. For example, a deed might prevent a property owner from building anything other than a single dwelling. The land subject to the restriction is the burdened land. Another property, person or organisation may have the benefit and be entitled to enforce it. The benefit is not always easy to identify from the current title. The general principles are outlined in Covenant (law).

Discharge removes the restriction, whilst modification changes its terms, perhaps to allow a particular use or a defined alteration. Neither is automatic. In England and Wales, section 84 of the Law of Property Act 1925 provides a route to ask the Upper Tribunal (Lands Chamber) to discharge or modify certain restrictive covenants, if the relevant statutory grounds are made out. The law and procedures differ across the UK, so the property’s jurisdiction matters.

How to identify a restrictive covenant in your title documents

Start with the registered title, including any entries that refer to deeds or other documents. The register may summarise a restriction without setting out its full wording. The original conveyance or transfer referred to in the register can provide important detail about the covenant’s scope, purpose and the land it affects. If that document is not readily available, further investigation may be needed. Tracing who can enforce the covenant may also require research into historic ownership and how the benefit was attached or transferred.

What discharge can and cannot achieve

Removing or changing a covenant addresses that restriction only. It does not grant planning permission, building regulations approval or any other consent your project may require. Those matters need to be considered separately.

Age alone does not make a covenant unenforceable, and a lack of past enforcement does not necessarily mean it can be ignored. Its wording, purpose, the land affected and the evidence available all matter. If you seek advice from restrictive covenant discharge solicitors, be ready to explain the intended use or works and provide the relevant title documents. A solicitor can assess possible routes, but no outcome should be assumed before the facts and applicable legal tests have been examined.

How restrictive covenants may be discharged or modified

There are two broad routes: reach an agreement with the person or parties entitled to the covenant’s benefit, or apply to the Upper Tribunal (Lands Chamber) in England and Wales. A negotiated deed of release removes the restriction, while a deed of variation changes its terms. An application under section 84 of the Law of Property Act 1925 asks the Tribunal to discharge or modify it. The appropriate route depends on the covenant’s wording, who benefits, the property’s jurisdiction, your objectives and the evidence available.

Section 84 provides several grounds for an application. These include that the covenant has become obsolete, that it impedes a reasonable use of the land without securing practical benefits of substantial value or advantage, or that it is contrary to the public interest. An application may also be possible where those entitled to the benefit agree, or where the Tribunal is satisfied that the proposed discharge or modification will cause no injury to them. The distinct framework for conservation covenants discussed in the Law Commission report illustrates why the legal treatment of covenants depends on their type and context.

When negotiation with the beneficiary may be considered

Negotiation may be a practical first route if the beneficiary can be identified and is willing to discuss your proposal. A solicitor can investigate the title and relevant historic documents to establish who may hold the benefit. If agreement is reached, make sure the deed accurately records what is being released or varied and covers the plans you intend to carry out. Discussions can take time and may not succeed if beneficiaries cannot be traced, several parties are involved or they object.

When a section 84 application may be relevant

An application may be worth considering where agreement is unavailable or the statutory grounds appear relevant. The reasonable-use ground is not a shortcut for inconvenience. The Tribunal assesses the proposed use alongside the covenant’s purpose and the practical benefits it protects. Evidence about the land, the proposed change and its effects on others will be important. The Tribunal can consider objections and may award compensation where the statutory provisions permit it. Check the current procedure before preparing an application.

Before choosing a route, clarify what you need the covenant to allow and assemble the title documents and plans. Restrictive covenant discharge solicitors can help assess the evidence and explain the risks of negotiation and a Tribunal application. If you are considering advice, you can review Feltons’ property and dispute-resolution services and ask whether the firm accepts this type of instruction and who would handle it.

How to assess your prospects and compare solicitors

There’s no reliable shortcut to judging whether a covenant can be changed. Prospects depend on its exact wording and purpose, when it was created, which land it affects and how your proposal would alter the position of those who may benefit. A covenant’s age may be relevant, but age alone does not establish that it is obsolete or unenforceable.

Consider the practical impact on both sides. Even a modest alteration may affect a neighbour’s property or an amenity the covenant was intended to protect. Objections, uncertainty over who can enforce the restriction, questions about its enforceability and possible compensation may all influence the route, evidence needed and level of risk. The UK Government guidance on discharging covenants outlines the Upper Tribunal application process and can help you understand what information may be required.

What evidence may support an application

Gather the registered title, historic transfers or conveyances, plans referred to in those documents and any correspondence about the covenant. Then describe exactly what you want to do. Drawings showing a proposed extension or development can make your request clearer than a general description. Depending on the proposal and any issues in dispute, ask whether planning, valuation or other professional evidence would help explain the land’s context, practical effects or potential impact on others.

Questions to ask restrictive covenant discharge solicitors

Compare advice by its relevance and clarity, not just by confidence of tone. Ask who would handle the matter and what directly relevant experience they can confirm, including experience with section 84 applications if that route is being considered. You can also ask:

  • Which routes may be available, and what facts could strengthen or weaken each?
  • How might objections, enforceability issues or compensation affect the strategy?
  • What evidence and procedural steps may be needed, and who will manage them?
  • What work is included in the proposed scope, how will fees be explained, and how will you be kept informed?

A careful adviser should explain uncertainties as well as possible next steps. Restrictive covenant discharge solicitors should assess your specific documents and objectives before suggesting a route, rather than treating every restriction as the same problem.
Restrictive Covenant Discharge Solicitors: A UK Property Owner’s Guide

What the discharge process involves and what can affect it

A measured process starts with the documents and your practical objective, not with an assumption that a Tribunal application is necessary. Typically, the work proceeds through these stages:

  • Review the title: check the register and the deeds it refers to for the covenant’s wording and context.
  • Define the objective: clarify the specific use, alteration or development you want to carry out.
  • Assess the route: consider whether discussion with the beneficiary, a formal application or another option is appropriate.
  • Prepare the evidence: assemble plans, relevant correspondence and supporting material for the chosen route.
  • Act: negotiate and document any agreement, or follow the applicable Tribunal procedure.

Negotiation and Tribunal proceedings involve different people and uncertainties. A negotiated release or variation depends on locating the relevant beneficiary and reaching agreement on terms. A Tribunal application follows formal procedural steps and may draw objections from people claiming the covenant’s benefit. The evidence required, number of parties involved, complexity of the title and need to respond to objections can all affect progress and legal fees. Ask for a clear explanation of what the proposed work includes and how additional steps may be handled. No timetable or outcome should be assumed before the circumstances are assessed.

Preparing for an initial legal discussion

Bring the registered title, the deeds referred to in it, relevant plans and correspondence about the restriction. Write down exactly what you hope to do, who you understand may benefit, any previous approaches or objections, and relevant project or transaction dates. Separate the result you need, such as permission for a defined extension, from your assumption about the legal route. This helps the solicitor assess the options against your objective.

Understanding risks, objections, and alternatives

An unsuccessful application may leave the covenant in place, affecting or preventing your plans. Ask the solicitor to explain the risk of objections, possible compensation, potential adverse-party costs and procedural issues that may apply to your case. Consider practical alternatives too: a revised design, negotiated consent or another arrangement may meet your needs with less uncertainty. Early assessment gives you a clearer basis for weighing those choices.

Before instructing restrictive covenant discharge solicitors, confirm who will handle the matter, what directly relevant experience they can demonstrate, and how they will explain risks and fees as the case develops. Feltons provides property legal services and dispute resolution. Contact Feltons to ask whether it accepts instructions of this kind and who would manage the work.

The right legal support should combine careful property-document review with a clear, proportionate strategy. A solicitor should explain what can be established from the title, what remains uncertain and which options fit your intended use, rather than implying that discharge is assured.

When comparing restrictive covenant discharge solicitors, look for relevant property-law experience, a reasoned assessment of the available routes, a transparent scope of work and considered advice about risks. Ask how the solicitor will address potential objections, what evidence may be needed and how you’ll be kept informed. Clear communication matters, particularly if the matter involves several beneficiaries or a formal application.

What a tailored legal assessment should cover

A useful initial assessment should consider the covenant’s wording and purpose, the title history, the land affected and your specific plans. Ask the solicitor to explain which routes may be available, what evidence could support them and what might weaken your position. The advice should consider objections and practical alternatives, not just your preferred legal route. Before proceeding, clarify the proposed scope, likely stages, communication arrangements and how fees will be explained as the matter develops.

A measured next step with Feltons Solicitors

Feltons Solicitors provides residential and commercial property legal services, alongside litigation and dispute resolution. These services may be relevant when assessing a property restriction and the possibility of a dispute, but the firm’s specific experience with restrictive covenant discharge is not confirmed in the information available for this guide. Ask directly whether the firm can advise on your matter.

In particular, confirm whether the solicitor handling your case has experience with the covenant in question and, if relevant, section 84 applications and Upper Tribunal proceedings. Ask what documents are needed for an initial review. The registered title, deeds referred to in it, relevant plans and a concise description of your intended use can help frame that discussion.

If you’re ready to take a measured next step, discuss your property law requirements with Feltons Solicitors. A conversation about the restriction and your plans can help establish whether the firm accepts this type of instruction and what further information it would need to assess the options.

Take a considered next step with your property plans

A restrictive covenant may not have to prevent your plans, but the right option depends on its wording, purpose, the land affected and the evidence available. Negotiation, a deed of release or variation, and an application to the Tribunal each involve different considerations. A careful review of the title and your intended use can help clarify realistic routes and risks before you commit to a course of action.

When speaking with restrictive covenant discharge solicitors, ask about directly relevant experience, who will handle the matter, what evidence may be needed and how the scope and fees will be explained. Feltons Solicitors, established in 2010, provides property and conveyancing legal services, as well as litigation and dispute resolution. Confirm the firm’s specific experience with covenant discharge directly.

Discuss your property law requirements with Feltons Solicitors, including the title restriction and the use you have in mind. A measured first conversation can help you decide what to do next with greater clarity.

Frequently Asked Questions

Can a restrictive covenant be discharged without the beneficiary’s consent?

Yes. In England and Wales, you can apply to the Upper Tribunal (Lands Chamber) under section 84 of the Law of Property Act 1925 without the beneficiary’s agreement. You’ll need to establish a relevant statutory ground with supporting evidence. The Tribunal may consider objections and the effect of the proposed change on those entitled to the covenant’s benefit. The outcome isn’t guaranteed, so assess the evidence and risks before applying.

What are the grounds for discharging a restrictive covenant?

In England and Wales, section 84 includes grounds such as the covenant having become obsolete, impeding reasonable use of the land or being contrary to the public interest. An application may also be possible if those entitled to the benefit agree, or if the Tribunal considers that discharge or modification would cause them no injury. The legal test depends on the ground relied on, and the applicant must support it with relevant evidence.

How do I find out who can enforce a restrictive covenant?

Start with the registered title and any deeds or transfers referred to in it. The wording may identify land that benefits from the covenant, but it may not name a current person entitled to enforce it. Historic conveyances, ownership records and the way the covenant’s benefit was transferred may need investigation. A solicitor can review these documents and help trace potential beneficiaries, though the answer may not be immediately clear.

How long does it take to discharge a restrictive covenant?

There’s no single timetable. A negotiated release may depend on identifying all relevant beneficiaries, reaching agreement and preparing appropriate documents. A Tribunal application follows formal steps, and progress can be affected by the evidence required, objections, the number of parties and whether a hearing is needed. Ask your solicitor for a case-specific estimate and what could cause delay. Treat any early timeframe as an estimate, not a guarantee.

Can I build on my property while a restrictive covenant is in place?

Don’t assume you can build simply because you have planning permission or the covenant is old. Planning permission and compliance with a private covenant are separate issues. If the proposed work breaches an enforceable restriction, proceeding without consent or a legal resolution may expose you to a dispute and affect your plans. Check the covenant’s wording and obtain advice before starting work. A Tribunal application or agreement may be relevant, but neither is automatic.

What documents should I give a solicitor about a restrictive covenant?

Provide the registered title, the conveyance or transfer containing the covenant, and any other deeds referred to in the register. Include relevant plans, correspondence with potential beneficiaries, previous requests for consent or objections, and drawings showing your proposed works or use. A clear note of your objective and any project or transaction dates is useful too. Restrictive covenant discharge solicitors can then assess what further documents or professional evidence may be needed.

Can a restrictive covenant be modified rather than discharged?

Yes. Modification changes the covenant’s terms, while discharge removes it. For example, an owner might seek permission for a defined alteration rather than removing the restriction in full. In England and Wales, section 84 allows the Upper Tribunal to consider modification as well as discharge, subject to the relevant statutory ground and evidence. A negotiated variation may also be possible if the beneficiary agrees. The appropriate scope depends on your plans and circumstances.
Equity Release Legal Advice: How to Choose a Solicitor

Equity Release Legal Advice: How to Choose a Solicitor

What if the person checking your equity release paperwork isn’t the person advising whether the plan is financially right for you? If you’re comparing equity release legal advice solicitors, it’s understandable to want clear answers about long-term costs, your partner’s position and what may remain in your estate.

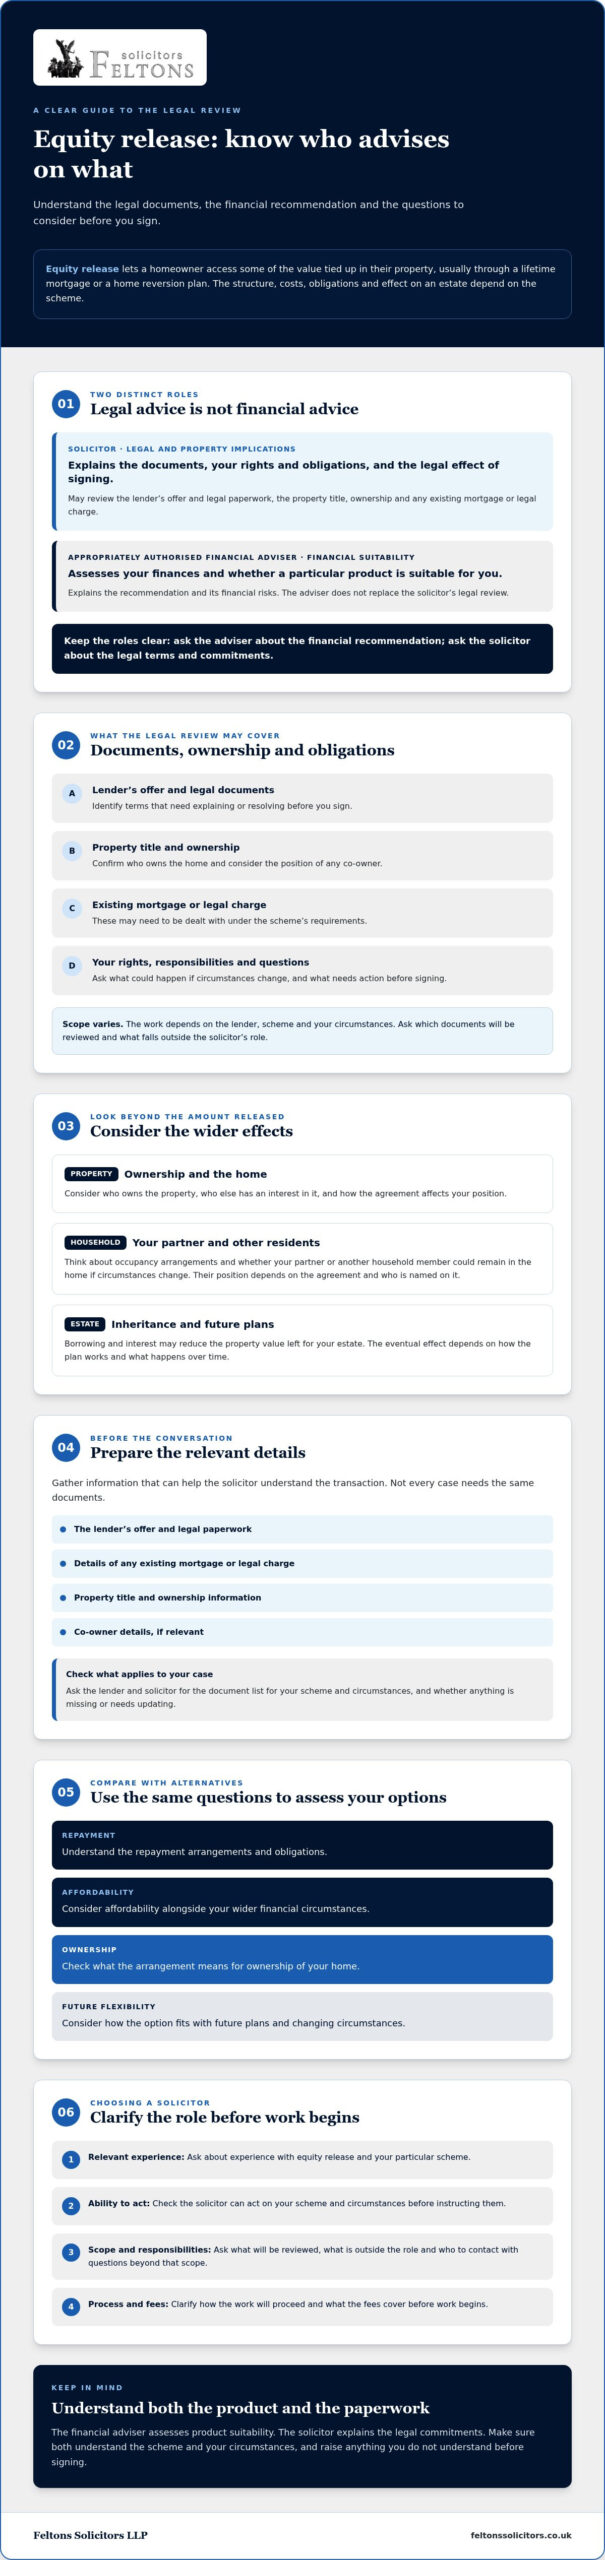
Legal advice and regulated financial advice have different purposes. A solicitor can explain the legal documents and property implications, while an appropriately authorised financial adviser assesses the financial product and its suitability for you. Understanding the distinction can help you make a considered decision and know who to ask when questions arise.

This guide explains what a solicitor may review, what to ask and which details to prepare before a conversation. It also considers how equity release could affect family members and estate plans. Feltons Solicitors LLP provides property and estate-planning legal services. An enquiry can help establish whether the firm is able to assist with your circumstances.

Key Takeaways

  • Equity release legal advice solicitors review a plan’s legal and property implications, but don’t recommend which financial product is right for you.
  • Ask how the agreement could affect ownership, your partner and your estate. The details depend on your circumstances and the scheme terms.
  • Compare equity release with alternatives by considering repayment, affordability, ownership and future flexibility.
  • Prepare information about your property and proposed scheme, then clarify the solicitor’s role, process, responsibilities and fees before work begins.
  • Check that the solicitor has relevant experience and can act on your particular scheme and circumstances before instructing them.

Equity release lets a homeowner access some of the value tied up in their property, usually through a product such as a lifetime mortgage or a home reversion plan. The structure, costs, obligations and effect on your estate depend on the scheme. The Equity release overview offers background on different forms and risks, but your own documents need to be considered in context.

In brief: a solicitor explains the legal effect of the documents and your obligations. A regulated financial adviser assesses and recommends a suitable financial product. Keeping these roles distinct helps you understand both what you’re agreeing to and why the proposed plan may or may not fit your financial circumstances.

What does an equity release solicitor check?

A solicitor’s review may cover the lender’s offer and legal documents, the property title and who owns the home. They can identify terms or details that need explaining or resolving before you sign. For example, an existing mortgage or legal charge may need to be dealt with under the scheme’s requirements. If someone else owns the property with you, their interest and position may also need consideration.

The work depends on the lender, the scheme and your circumstances. Ask which documents the solicitor will review, what is outside their scope and what happens if something needs clarification. Their role is to help you understand the legal commitments, not to tell you which product to choose.

How legal advice differs from financial advice

Legal advice and financial advice answer different questions. An appropriately authorised financial adviser considers your finances and whether a particular product is suitable, then explains the recommendation and its financial risks. The solicitor focuses on the legal documents, your rights and obligations, and whether you understand the legal effect of signing.

An independent legal review matters because lender documents may create binding commitments. Before signing, raise anything you don’t understand, including what could happen if your circumstances change, how the arrangement affects a co-owner and what it may mean for your estate. Don’t assume one professional’s advice covers the other’s role.

  • Ask the adviser to explain the financial recommendation and its risks.
  • Ask the solicitor to explain the legal terms, obligations and any points requiring action.
  • Check that both professionals understand the scheme and your circumstances. Ask who to contact with questions outside their remit.

Choosing between equity release legal advice solicitors is about more than finding someone to process paperwork. Look for a clear explanation of scope and responsibilities, and confirm the solicitor can act on your specific scheme before instructing them.

Financial advice doesn’t replace an independent legal review. The adviser considers the financial product and its suitability; the solicitor examines the legal documents and explains the obligations they create. The role of an equity release solicitor includes helping you understand the legal commitment before you sign. The work and possible consequences depend on the contract, scheme terms and your household circumstances.

Read the documents with your own plans in mind, not just the amount you could release. Borrowing and interest may reduce the property value left for your estate, but the eventual effect depends on how the plan works and what happens over time. If you share your home, consider whether your partner or another household member could remain there if circumstances change. Their position depends on the agreement and who is named on it, so ask the solicitor to explain the relevant terms.

Which documents and details may the solicitor need?

To help the solicitor understand the transaction, gather the lender’s offer and legal paperwork, details of any existing mortgage or legal charge, and information about property ownership. Title details and co-owner information may also be relevant. Not every case needs the same documents. Ask the lender and solicitor for the list that applies to your scheme and circumstances, and check whether anything is missing or needs updating.

Consider your partner, estate and future plans

Think through your occupancy arrangements, inheritance wishes and the needs of anyone who lives with you. Ask what the contract says if you move home or your living arrangements change, and whether your partner’s position is affected. Equity release legal advice solicitors can explain the legal effect of the documents, but they don’t determine whether the financial arrangement is suitable for you.

Before signing, understand exactly what events trigger repayment. The timing and consequences depend on the agreement. Ask the solicitor to explain relevant triggers in plain English, including what happens if the home is sold or the borrower’s circumstances change, where those situations are covered by the contract.

Tax, means-tested benefits and care-fee treatment depend on individual circumstances and current rules. Don’t rely on general information to predict the result; seek appropriate specialist advice before making a decision. If your decision raises wider property or estate-planning questions, you can enquire about property and estate-planning legal services and confirm whether the firm can assist with your circumstances.

Compare equity release with alternatives before choosing a solicitor

Equity release is one way to access money tied up in your home, but it isn’t the only option to explore. Downsizing, another type of loan, using savings or investments, or receiving family support may raise different questions about ownership, repayment, affordability and future plans. None is suitable for everyone. What’s available and appropriate depends on your circumstances and current product terms.

Discuss financial suitability and affordability with an appropriately authorised financial adviser. A solicitor can explain the legal implications of a proposed arrangement, including how it affects the property and the people connected to it. Comparing options first can help you identify the right questions for both professionals.

Compare the questions each option raises

Option Questions to consider
Equity release How does interest build, when is repayment due, and what do the terms say about moving home or changes in circumstances?
Downsizing Would selling and buying a different property suit your housing needs, and what would happen to ownership and the proceeds?
Other borrowing Can repayments remain affordable, what security is required, and how flexible are the repayment and early repayment terms?
Savings, investments or family support What assets could be used without undermining other plans? If a relative helps, is the arrangement a gift or a loan, and should it be recorded clearly?

This is a starting point, not a recommendation. Discuss family support openly with everyone involved and consider recording any agreed terms. The right approach depends on individual finances, property needs and family relationships.

Questions to resolve before deciding

Ask the adviser to explain how interest, repayments and any early repayment charges work under the specific offer. Ask the solicitor to clarify the legal terms and any obligations that could affect your plans. Check what the contract says if you move, your circumstances change or a borrower enters long-term care. Don’t assume the same outcome applies across all schemes.

Write down unanswered questions and take them to the relevant professional. Keep financial suitability questions for your adviser and legal-document questions for your solicitor. Ask each to clarify where their role ends. Comparing options before selecting equity release legal advice solicitors can help you focus on the expertise you need, rather than treating the choice of solicitor as a decision about which financial route to take.

Equity Release Legal Advice: How to Choose a Solicitor

How to prepare for an equity release solicitor consultation

A little preparation can make your first conversation more focused. You don’t need every document ready, but a clear picture of the proposed plan, your property and your priorities can help the solicitor identify what needs checking. Be open about relevant household and estate-planning circumstances, including details that may feel personal. They can affect which questions need to be considered.

Gather information and agree the next steps

  • 1. Collect the paperwork. Bring any proposed plan documents or lender correspondence, property ownership and title information, and details of an existing mortgage or other charge, if applicable. Ask the lender and solicitor which documents they need for your case.
  • 2. Note your circumstances and questions. Record who lives in the property, whether there are co-owners or dependants, and any concerns about a partner’s housing position or your inheritance intentions. Consider possible future changes, such as moving home.
  • 3. Bring relevant estate-planning papers. If you have a will or other documents that may relate to your plans, ask whether they would help the solicitor understand your concerns. Don’t assume they’ll all be required.
  • 4. Clarify the retainer before instructing. Ask what legal work is included, what falls outside the scope, who will handle the matter, how you’ll receive updates and what the next steps are.
  • 5. Confirm fees and process. Request clear information about fees and how any additional work would be discussed. Check your understanding before agreeing to proceed.

Questions to ask your solicitor

Use the conversation to establish practical expectations, not just whether the firm can review documents. Ask: “Which parts of the proposed arrangement will you examine?”, “What issues might require further information?” and “Who should I contact if I have a question about financial suitability?” A solicitor should explain the boundaries of their role, the process they propose and how they’ll raise matters that need your decision.

Timing and required steps vary according to the lender, transaction and your circumstances. Ask what sequence to expect and whether anything is needed from you before the review can progress. Don’t instruct a firm before you understand its scope and fees. If you’re considering equity release legal advice solicitors and have wider property or estate-planning questions, you can enquire with Feltons Solicitors LLP to establish whether the firm can assist with your circumstances.

A suitable solicitor should make the legal process clear, explain what they will review and give you space to raise concerns. Before instructing anyone, confirm they can act on the lender’s scheme and your particular circumstances. Experience with property and private client matters can be relevant, but ask specifically about the documents and requirements involved in your proposed transaction.

How to assess a solicitor’s suitability

Use your first conversation to check the fit rather than assuming a general property background covers every equity release arrangement. Ask whether the solicitor has experience with the relevant lender, scheme documents and transaction requirements, and what they would do if the paperwork raises an issue. Their role should be independent of the financial product recommendation. Ask how they’ll explain the legal obligations and check your understanding.

  • Relevant experience: Can they act on this scheme and explain the legal review it requires?
  • Clear scope: Which documents and issues are included, and what falls outside the work?
  • Communication: Who will handle your matter, how will updates be provided, and how can you raise questions?
  • Transparent fees: What will you be charged, and how will any additional work be discussed?
  • Your circumstances: Will the review take account of ownership, co-owners, household arrangements and your stated concerns?

Equity release legal advice solicitors should explain the legal position in language you understand, without presenting their review as a recommendation about financial suitability. If anything remains unclear, ask for an explanation before you sign or agree to proceed.

What to expect when you contact Feltons Solicitors LLP

Feltons Solicitors LLP provides private client and property legal services, including wills, probate, estate planning and residential conveyancing. The firm’s information does not confirm a specialist equity release service. An enquiry is a practical way to establish whether the firm currently accepts this type of matter, can act on your scheme and circumstances, and what the scope of any advice could be.

If your questions connect with wider inheritance planning, you may find the estate planning guide helpful. For questions about property ownership and transactions, see the residential property law guide. These resources provide background, but they don’t replace advice on your specific documents and circumstances.

To establish whether the firm can assist and discuss an appropriate next step, contact Feltons Solicitors LLP to discuss your circumstances. You can ask about availability, the applicable jurisdiction, the proposed scope of work and fees before deciding whether to instruct.

Take a considered next step

Choosing equity release legal advice solicitors means checking that the legal review is distinct from financial product advice, that the solicitor can act on your particular scheme, and that the documents and obligations are explained in language you understand. Weigh alternatives and consider how the decision may affect your household and estate plans before committing.

Feltons Solicitors LLP provides property law and conveyancing services alongside private client services, including wills and estate planning. The firm’s information doesn’t confirm whether it currently accepts equity release matters, so check availability, scope and whether it can assist with your circumstances before instructing.

Contact Feltons Solicitors to ask whether the firm can assist with your circumstances.

Frequently Asked Questions

What does an equity release solicitor do?

An equity release solicitor reviews the transaction’s legal paperwork and explains the obligations, risks and steps relevant to your case. They may check title ownership, co-owners, any existing mortgage and whether lender requirements appear to have been met. Their role isn’t to recommend a financial product. Ask which documents they’ll review, what falls outside their agreed scope and whether they can act on your particular scheme.

Do I need a solicitor for equity release?

Equity release transactions commonly involve legal work, but the process and requirements depend on the lender, product and your circumstances. A solicitor can explain the documents and commitments so you can understand them before signing. Ask the lender and solicitor to confirm the steps required for your case. Legal advice doesn’t replace regulated financial advice about whether a product is suitable for you.

Can an equity release solicitor give financial advice?

A solicitor’s legal advice is separate from a regulated recommendation about whether an equity release product suits you. Within the agreed scope, the solicitor can explain legal documents, obligations and relevant transaction steps. For product recommendations and financial suitability, speak to an appropriately authorised financial adviser. If you’re unsure who should answer a particular question, ask both professionals to explain their responsibilities before you proceed.

What should I ask an equity release solicitor before instructing them?

Ask whether they can act on your specific scheme, what the legal work includes and who will handle your matter. Clarify the expected steps, how updates will be given, the fees and how additional work would be discussed. You can also ask how the review will address property ownership, your partner’s position and estate-planning concerns. Request clear answers before deciding whether to instruct the firm.

Will equity release affect my inheritance or my family?

It may reduce the property value remaining for your estate after borrowing and interest are repaid, though the eventual effect depends on the agreement and future circumstances. Consider how the arrangement could relate to your partner’s housing position, other household members and inheritance wishes. Ask your financial adviser about the financial implications and your solicitor about the legal terms. You may also wish to review your will or wider estate plans.

Can I compare equity release with other options before signing?

Yes. You can discuss alternatives such as downsizing, other borrowing or using other assets with an appropriately authorised financial adviser. Compare each route by considering ownership, repayment, affordability and flexibility, rather than relying on one feature alone. Availability and suitability depend on your circumstances and current terms. If you’re considering equity release, a solicitor can explain the legal documents and identify points that need clarification before you sign.

What documents should I take to an equity release solicitor?

Useful starting points may include the proposed plan documents, property ownership or title information, and details of any existing mortgage. A will or other estate-planning papers may help if they relate to your concerns. Prepare questions about your household and future plans, too. Requirements vary, so ask the solicitor for their document list before your meeting. Only send sensitive paperwork through a channel you’ve verified with the firm.

New Build Property Purchase Legal Advice: The 2026 Buyer’s Guide

New Build Property Purchase Legal Advice: The 2026 Buyer's Guide

The legal conveyancer your developer urgently recommends might seem like the most convenient choice, but handing them your file could be the costliest mistake of your property journey. Securing specialist new build property purchase legal advice is essential when you are facing high-pressure sales tactics, complex off-plan specifications, and vague completion schedules.

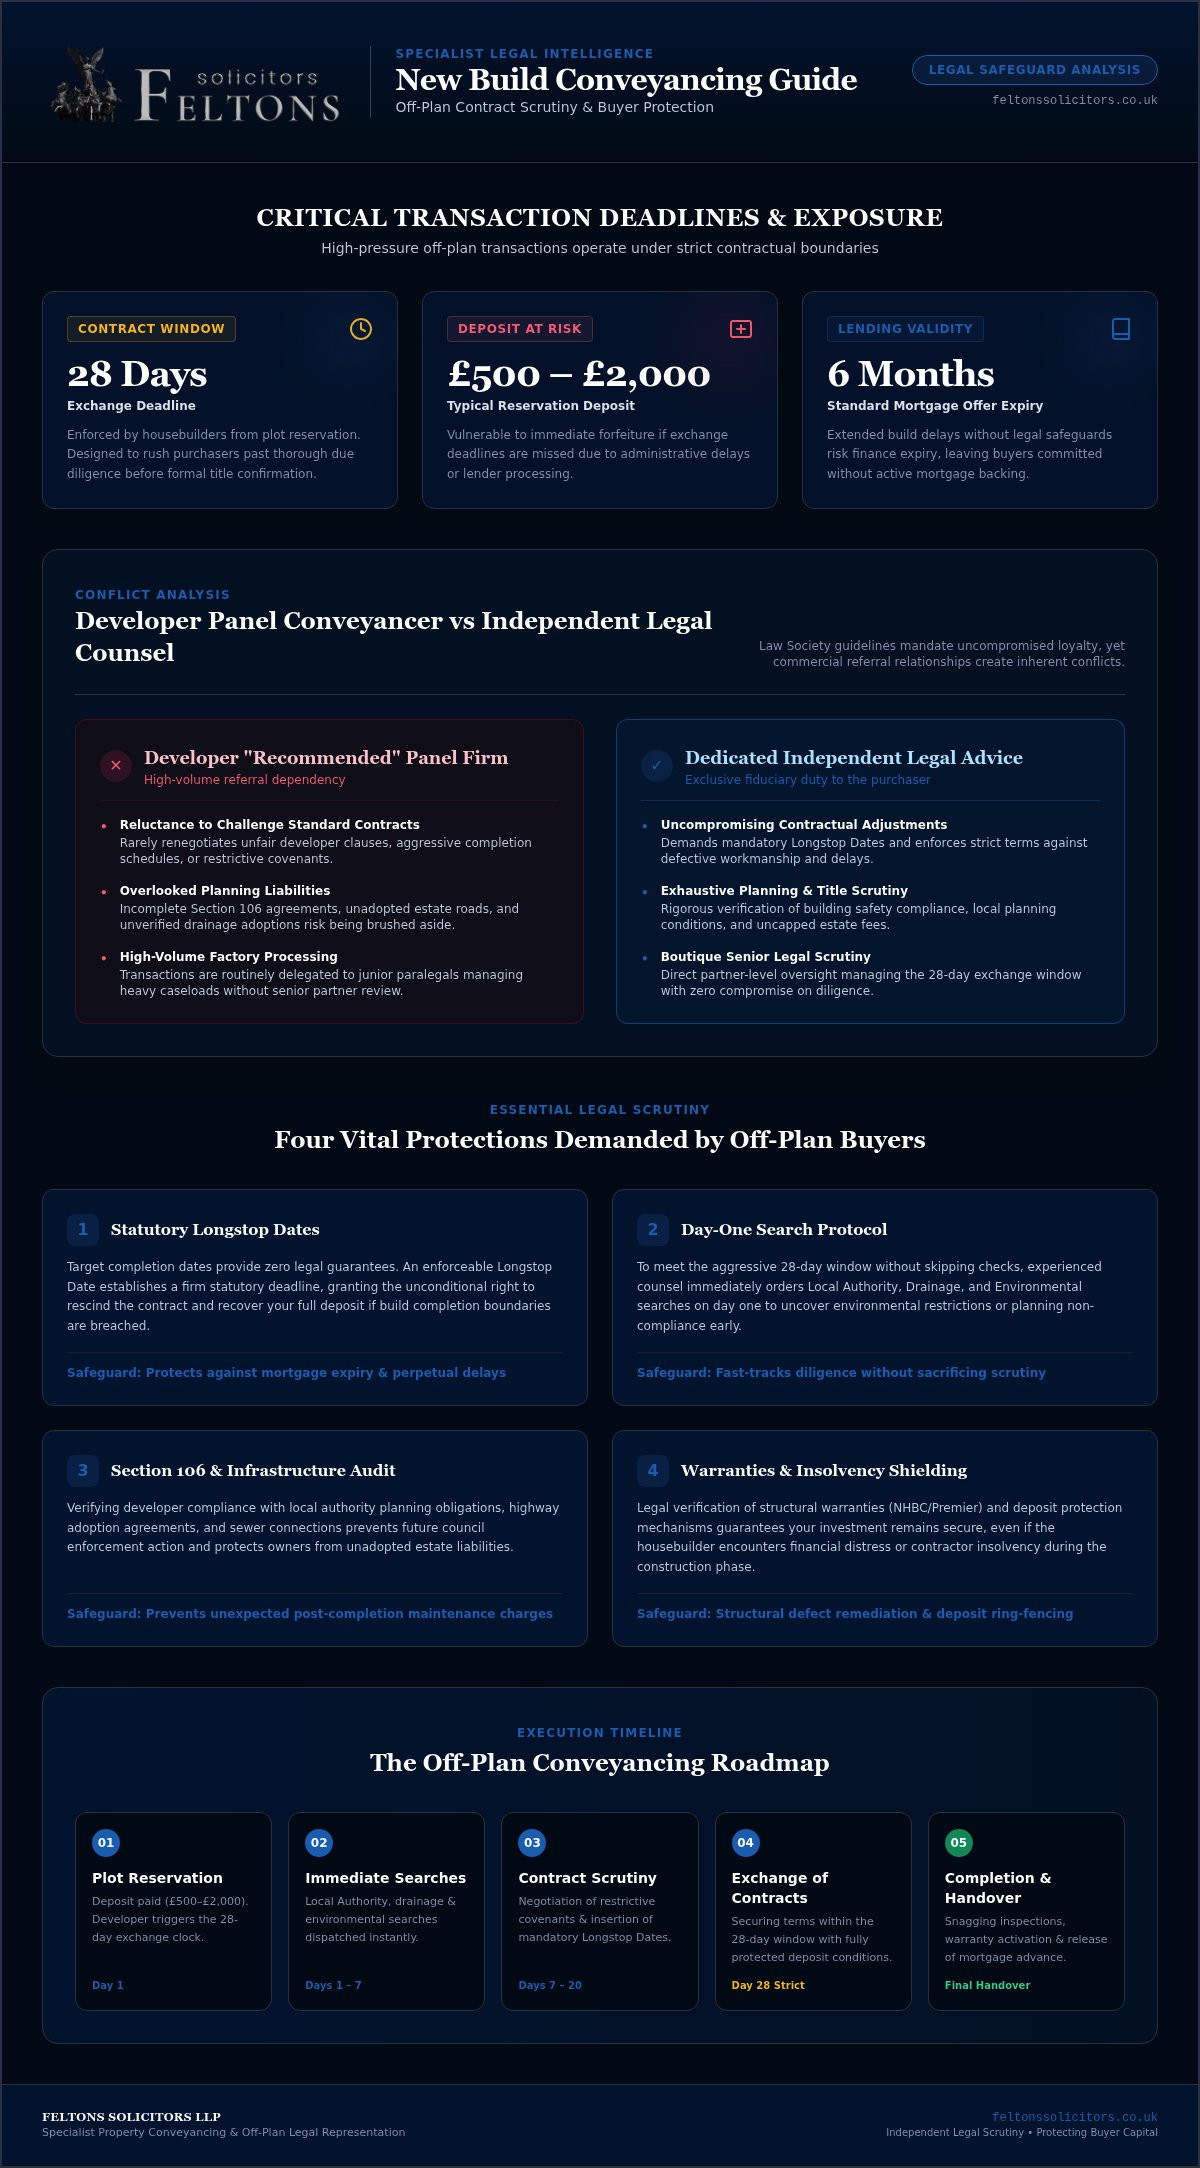
It is entirely natural to feel anxious under the weight of an unyielding 28-day exchange deadline, particularly when you worry that challenging hidden estate management charges or incomplete planning conditions could forfeit your reservation deposit. You shouldn’t have to compromise your legal protection just to meet a housebuilder’s arbitrary timeline. In this 2026 guide, you will discover how to safeguard your deposit, bypass restrictive developer clauses, and secure ironclad terms against construction delays and defective workmanship. We will walk you through the entire conveyancing process, showing you how dedicated, independent legal scrutiny keeps you in control from reservation through to final completion.

Key Takeaways

  • Securing independent new build property purchase legal advice shields your financial interests against biased contracts and protects your reservation deposit from aggressive housebuilder tactics.
  • Rigorous contract scrutiny ensures essential longstop dates are inserted, granting you the statutory right to walk away with your full deposit if construction runs past agreed completion boundaries.
  • Understanding the strict requirements around local planning agreements, building safety compliance, and unadopted estate charges prevents unexpected post-completion liabilities.
  • Partnering with a boutique legal practice guarantees direct access to an experienced solicitor who manages the swift 28-day exchange process without cutting critical corners.
  • A structured conveyancing roadmap synchronises mortgage expiry dates, snagging inspections, and warranty registrations to ensure a protected, orderly handover.

Purchasing a home off-plan bears little resemblance to buying an established, pre-owned residence. When you buy an existing house, you inspect physical bricks and mortar with decades of visible structural history. With a new build, you commit hundreds of thousands of pounds to architectural plans, developer promises, and unfinished sites. This fundamental difference introduces legal, financial, and planning risks that standard property transactions simply do not face. Navigating these unique hurdles requires dedicated, highly specialised conveyancing insight to ensure your contract properly protects your hard-earned capital.

Without bespoke representation, buyers risk signing standard-form developer agreements packed with onerous covenants, unrestricted completion leeway, and uncapped estate management liabilities. Expert guidance shields your deposit from developer insolvency, enforces structural warranties, and establishes explicit contractual boundaries before exchange takes place.

The Reality of Strict 28-Day Exchange Deadlines

Housebuilders routinely enforce an aggressive 28-day exchange window from the moment you reserve a plot. This compressed timetable isn’t accidental; developers intentionally create urgency to rush buyers past comprehensive due diligence. If your mortgage lender delays an administrative sign-off or valuation, the developer may threaten to cancel your reservation and forfeit your initial deposit, which typically ranges between £500 and £2,000.

A proactive legal ally mitigates this manufactured pressure immediately. Experienced legal counsel orders local authority, drainage, and environmental searches on day one, managing tight deadlines while maintaining uncompromised scrutiny of the site’s title.

Developer Panel Solicitors vs Independent Legal Representation

Sales suites frequently push “recommended” panel conveyancers, offering attractive incentives or discounted legal fees if you accept. You should approach these recommendations with extreme caution. While Law Society guidelines strictly mandate that all solicitors act with uncompromised independence and client loyalty, panel firms operate under an undeniable commercial conflict. They rely on high-volume referral pipelines from the housebuilder to sustain their business models.

This reliant relationship creates tangible vulnerabilities for buyers:

  • Reluctance to challenge standard contracts: Panel firms rarely push back vigorously against unfair developer clauses or aggressive completion terms.
  • Overlooked planning restrictions: Incomplete Section 106 agreements, unadopted road liabilities, or unverified drainage adoptions can easily be brushed aside.
  • Factory processing: Cases are routinely handed down to junior paralegals working under high caseloads, eliminating meaningful partner-level analysis.

Securing fully independent new build property purchase legal advice ensures your solicitor answers exclusively to you. An autonomous conveyancer will unreservedly challenge unacceptable draft terms, dispute unreasonable build delays, and safeguard your deposit without worrying about upsetting the developer’s sales team.

Critical Contractual Risks in New Build Purchases: What Your Solicitor Must Scrutinise

Housebuilder sale agreements are drafted by institutional commercial lawyers to protect developer balance sheets rather than private buyers. Without targeted legal adjustments, standard off-plan contracts transfer substantial commercial risk onto your shoulders. Securing specialised new build property purchase legal advice ensures onerous covenants are identified and renegotiated before you commit your funds.

Longstop Dates and Protection Against Construction Delays

Off-plan contracts typically state an estimated completion date alongside an enforceable “longstop date”. The estimated target merely guides expectations; the longstop date establishes a definitive legal boundary. Because standard UK mortgage offers expire after six months, substantial site delays can leave you without valid financing. Your conveyancer must draft an enforceable longstop clause granting an unconditional right to rescind the contract and recover your full deposit if building work stalls indefinitely.

Uncapped Estate Rentcharges and Maintenance Obligations

Modern housing developments frequently feature unadopted roads, drainage infrastructure, and communal play areas managed by private property companies. If your transfer deed contains an estate rentcharge, any payment dispute can trigger draconian statutory remedies under Section 121 of the Law of Property Act 1925, allowing rentcharge owners to place a lease over your home. Your legal counsel must negotiate deed clauses that exclude these statutory remedies, whilst establishing clear caps on annual maintenance fee hikes.

Planning Permissions, Section 106 Obligations, and Structural Warranties

Your conveyancer must confirm that the developer has formally discharged all pre-commencement and pre-occupation local planning conditions. They must also verify statutory infrastructure agreements, including Section 38 highway bonds and Section 104 sewer adoptions, preventing local authorities from billing homeowners for unfinished roads. Crucially, your 10-year structural warranty from providers such as NHBC, Premier Guarantee, or LABC must align with consumer protections under the New Homes Quality Code before completion funds are transferred. For bespoke guidance on dismantling aggressive developer covenants, turning to an independent specialist at Feltons Solicitors ensures your legal footing remains completely secure throughout the purchase.

Choosing the right legal professional determines whether your transaction progresses smoothly or fractures under intense developer pressure. Off-plan acquisitions involve unique contractual mechanisms, complex infrastructure agreements, and strict planning triggers that standard domestic conveyancing rarely encounters. Selecting an inexperienced firm or relying on automated conveyancing platforms can leave critical title flaws unnoticed until it is too late to rectify them.

Securing dedicated new build property purchase legal advice from a specialist practice gives you the confidence that every developer clause has been scrutinised by an expert working solely on your behalf.

Dedicated Solicitor Attention vs High-Volume Factory Conveyancing

High-volume conveyancing factories rely on call-centre setups where files pass between rotating junior clerks and administrative assistants. This fragmented workflow often causes administrative bottlenecks, unreturned calls, and missed reservation deadlines. Conversely, boutique practices provide direct, continuous access to a qualified solicitor. Partner-led oversight ensures intricate planning conditions, boundary easements, and warranty certifications receive rigorous, personal scrutiny rather than superficial checklist reviews.

Essential Questions to Ask Before Instructing Legal Counsel

Before committing to a law firm, take the time to evaluate their technical background in handling housebuilder negotiations. You need absolute certainty that your representative can handle aggressive timescales without sacrificing comprehensive due diligence.

Pose these targeted questions during your initial enquiry:

  • Are you approved on all major UK mortgage lender panels? If your chosen firm lacks panel approval for your specific lender, separate representation will be required, generating substantial delays and duplicate legal costs.
  • Who will have day-to-day conduct of my file? Demand direct confirmation that a dedicated solicitor will personally review the contract pack and handle developer negotiations.
  • How do you handle rapid exchange deadlines? Enquire about their systems for ordering searches immediately and expediting preliminary enquiries before reservation periods elapse.
  • What is your proven track record with off-plan properties? Look for comprehensive expertise across all aspects of residential property law to ensure complex development covenants are correctly interpreted.

Partnering with an independent, partner-led firm guarantees that your legal defence remains robust, transparent, and entirely aligned with your financial safety.

New Build Property Purchase Legal Advice: The 2026 Buyer's Guide

The New Build Conveyancing Roadmap: From Reservation to Completion

Managing an off-plan acquisition requires a methodical approach that keeps pace with construction milestones without bypassing essential legal safeguards. Securing specialist new build property purchase legal advice transforms what can feel like a chaotic process into an orderly, five-stage progression:

  1. Reservation and immediate instruction: You pay the reservation fee, secure the developer’s draft contract pack, and instruct an independent legal representative immediately.
  2. Due diligence and search enquiries: Your solicitor scrutinises planning consents, highway adoptions, and local authority searches whilst synchronising your mortgage terms.
  3. Contract negotiation and exchange: Critical amendments regarding longstops and defect remedies are inserted before exchanging contracts and paying your deposit.
  4. Practical completion and snagging: The developer concludes physical works, serves formal completion notice, and permits independent pre-completion inspections.
  5. Legal handover and registration: Balance purchase monies are transferred, structural warranties are activated, and your title is registered at HM Land Registry.

Reservation, Search Inquiries, and Mortgage Offer Alignment

The reservation period moves quickly. Your conveyancer must order local authority, drainage, and environmental searches on day one to prevent developer deadlines from slipping. Concurrently, your legal team cross-references your mortgage offer against realistic build projections. Because most UK mortgage offers expire after six months, aligning your finance validity with anticipated construction phases prevents costly reassessments if bad weather or supply chain disruptions delay the site.

Exchange on Notice, Pre-Completion Inspections, and Snagging Retentions

Off-plan contracts rarely include a fixed completion calendar date. Instead, exchange occurs “on notice”. Once building control and warranty inspectors confirm the property is structurally sound, the developer serves a formal notice to complete, typically giving you ten working days to transfer final funds.

During this brief window, you have the legal right to commission an independent pre-completion snagging inspection before moving in. Wherever feasible, an experienced solicitor will push to incorporate retention clauses into the contract. These provisions allow you to withhold a defined portion of final completion funds until the developer satisfactorily rectifies identified snags.

To ensure your rights remain protected throughout every stage of development, speak to our specialist property solicitors to secure proactive, partner-led legal representation from day one.

Safeguarding Your Property Investment with Feltons Solicitors LLP

Established in 2010 by Paula Felton, Feltons Solicitors LLP delivers residential conveyancing founded on partner-led oversight, genuine accessibility, and uncompromising legal rigour. We represent buyers nationally across the United Kingdom, cutting through dense developer contracts to deliver pragmatic, plain-English guidance. When large housebuilders apply intense sales pressure, our solicitors act as an independent shield, protecting your deposit against unilateral contract variations and unfair site terms.

Securing specialist new build property purchase legal advice ensures your financial interests remain paramount. Rather than processing your transaction on an assembly line, we maintain direct lines of communication so you always know the exact standing of your file.

Boutique Legal Standards for Modern Property Purchases

Our boutique structure deliberately rejects the high-volume pressures of factory conveyancing practices. By maintaining manageable caseloads, our solicitors dedicate the time required to interrogate complex site masterplans, drainage adoption agreements, and planning obligations thoroughly. If you are purchasing an apartment, our dedicated capabilities in leasehold property matters ensure that service charge mechanics, management company covenants, and statutory building safety requirements are comprehensively audited before you commit.

Instructing Feltons Solicitors for Your New Build Purchase

Engaging our conveyancing team before you sign a reservation form gives you an immediate strategic advantage. Our onboarding process is entirely frictionless:

  • Immediate file opening: We contact the developer’s legal team directly on day one to request the comprehensive contract pack and planning schedules.
  • Expedited search orders: We commission local authority, environmental, and drainage searches instantly to prevent developer deadlines from slipping.
  • Robust contract amendments: We draft explicit longstop protections and delete disproportionate estate management clauses before presentation for signature.

We understand how challenging a developer’s 28-day exchange deadline feels. Our methodical, partner-led approach ensures you meet those strict commercial timetables without forfeiting your statutory buyer rights or compromising on due diligence. Contact our property team before paying your reservation deposit, and let us protect your home investment from the very outset.

Secure Your Investment with Confident, Independent Representation

Purchasing an off-plan home should be an inspiring milestone rather than a stressful gamble against developer deadlines. Securing specialist new build property purchase legal advice ensures your deposit remains ring-fenced, enforceable longstop dates are secured, and unadopted estate charges are challenged before you sign. Stepping away from developer-recommended panel conveyancers restores your negotiating power and puts your legal interests first.

Established in 2010, Feltons Solicitors LLP delivers partner-led residential conveyancing across the United Kingdom, combining high-value property experience with meticulous, personal attention. Our boutique practice gives you direct access to senior solicitors who challenge complex developer paperwork with uncompromised independence, keeping your transaction on track without cutting critical legal corners. You don’t have to navigate intense sales suites alone. Instruct Feltons Solicitors for your new build purchase today, and step into your new home with complete peace of mind.

Frequently Asked Questions

Can I use the developer’s recommended solicitor when buying a new build property?

Yes, you can legally instruct them, but doing so compromises your legal protection. Recommended panel conveyancers often rely on repeat referrals from the housebuilder, which creates an inherent conflict of commercial interest. Choosing independent legal representation guarantees your solicitor investigates planning agreements, contract variations, and site covenants without outside commercial pressure. Securing independent new build property purchase legal advice ensures your financial deposit and contractual interests remain the absolute priority throughout the transaction.

What happens if the developer fails to complete the build by the agreed date?

Your remedies depend entirely on whether an enforceable longstop clause was negotiated before contract exchange. Without this protection, you remain legally tied to the purchase even if construction delays stretch past your mortgage offer expiry date. If your contract incorporates explicit longstop provisions, exceeding the agreed date allows you to rescind the agreement, cancel your purchase obligations, and recover your full reservation and exchange deposits without financial penalty.

Why is a 28-day exchange deadline common for new build property purchases?

Housebuilders impose 28-day deadlines to lock buyers into legally binding contracts as quickly as possible. This commercial tactic secures non-refundable deposits and confirms development cash flow for the builder’s lenders. It intentionally narrows the window for comprehensive scrutiny, making it essential to instruct a proactive conveyancer on day one. An experienced legal team orders environmental, drainage, and local authority searches immediately to meet the deadline without sacrificing vital due diligence.

What are estate rentcharges and why do solicitors warn buyers about them?

Estate rentcharges are mandatory annual contributions levied on freehold homeowners to fund private development infrastructure, such as unadopted roads, drainage basins, and communal gardens. Conveyancers warn buyers about them because failure to pay, even over a disputed minor sum, can grant rentcharge owners statutory power under Section 121 of the Law of Property Act 1925 to create a lease over your home. Experienced solicitors negotiate modifications to exclude these draconian statutory remedies.

What is a longstop date in an off-plan property purchase contract?

A longstop date is the absolute final deadline by which a housebuilder must legally finish construction and achieve practical completion. Unlike standard estimated target dates, which are merely projections, the longstop date establishes a hard contractual boundary. If the housebuilder fails to deliver the property by this specified longstop point, you gain the statutory contractual right to terminate the agreement and receive an immediate refund of your deposit.

Can I legally delay completion if significant defects are discovered during snagging?

Generally, you cannot refuse to complete over minor snagging issues once the developer serves formal notice to complete. Standard contracts consider practical completion achieved once building control signs off the property. However, specialist new build property purchase legal advice can secure bespoke contractual retention clauses during pre-exchange negotiations. These provisions legally permit you to withhold a defined portion of final completion funds until the developer inspects and rectifies all major documented defects.

How do structural warranties like NHBC protect my new build purchase?

Structural warranties, such as those provided by NHBC, Premier Guarantee, or LABC, offer a 10-year policy covering major structural defects. During the initial two years, the housebuilder is legally obliged to repair any defects in materials and workmanship. In years three to ten, the warranty provider handles severe physical damage to core structural elements, including foundations, roofs, and load-bearing walls. Your solicitor verifies that warranty certificates are active prior to legal completion.