New Build Property Purchase Legal Advice: The 2026 Buyer’s Guide

New Build Property Purchase Legal Advice: The 2026 Buyer's Guide

The legal conveyancer your developer urgently recommends might seem like the most convenient choice, but handing them your file could be the costliest mistake of your property journey. Securing specialist new build property purchase legal advice is essential when you are facing high-pressure sales tactics, complex off-plan specifications, and vague completion schedules.

It is entirely natural to feel anxious under the weight of an unyielding 28-day exchange deadline, particularly when you worry that challenging hidden estate management charges or incomplete planning conditions could forfeit your reservation deposit. You shouldn’t have to compromise your legal protection just to meet a housebuilder’s arbitrary timeline. In this 2026 guide, you will discover how to safeguard your deposit, bypass restrictive developer clauses, and secure ironclad terms against construction delays and defective workmanship. We will walk you through the entire conveyancing process, showing you how dedicated, independent legal scrutiny keeps you in control from reservation through to final completion.

Key Takeaways

  • Securing independent new build property purchase legal advice shields your financial interests against biased contracts and protects your reservation deposit from aggressive housebuilder tactics.
  • Rigorous contract scrutiny ensures essential longstop dates are inserted, granting you the statutory right to walk away with your full deposit if construction runs past agreed completion boundaries.
  • Understanding the strict requirements around local planning agreements, building safety compliance, and unadopted estate charges prevents unexpected post-completion liabilities.
  • Partnering with a boutique legal practice guarantees direct access to an experienced solicitor who manages the swift 28-day exchange process without cutting critical corners.
  • A structured conveyancing roadmap synchronises mortgage expiry dates, snagging inspections, and warranty registrations to ensure a protected, orderly handover.

Purchasing a home off-plan bears little resemblance to buying an established, pre-owned residence. When you buy an existing house, you inspect physical bricks and mortar with decades of visible structural history. With a new build, you commit hundreds of thousands of pounds to architectural plans, developer promises, and unfinished sites. This fundamental difference introduces legal, financial, and planning risks that standard property transactions simply do not face. Navigating these unique hurdles requires dedicated, highly specialised conveyancing insight to ensure your contract properly protects your hard-earned capital.

Without bespoke representation, buyers risk signing standard-form developer agreements packed with onerous covenants, unrestricted completion leeway, and uncapped estate management liabilities. Expert guidance shields your deposit from developer insolvency, enforces structural warranties, and establishes explicit contractual boundaries before exchange takes place.

The Reality of Strict 28-Day Exchange Deadlines

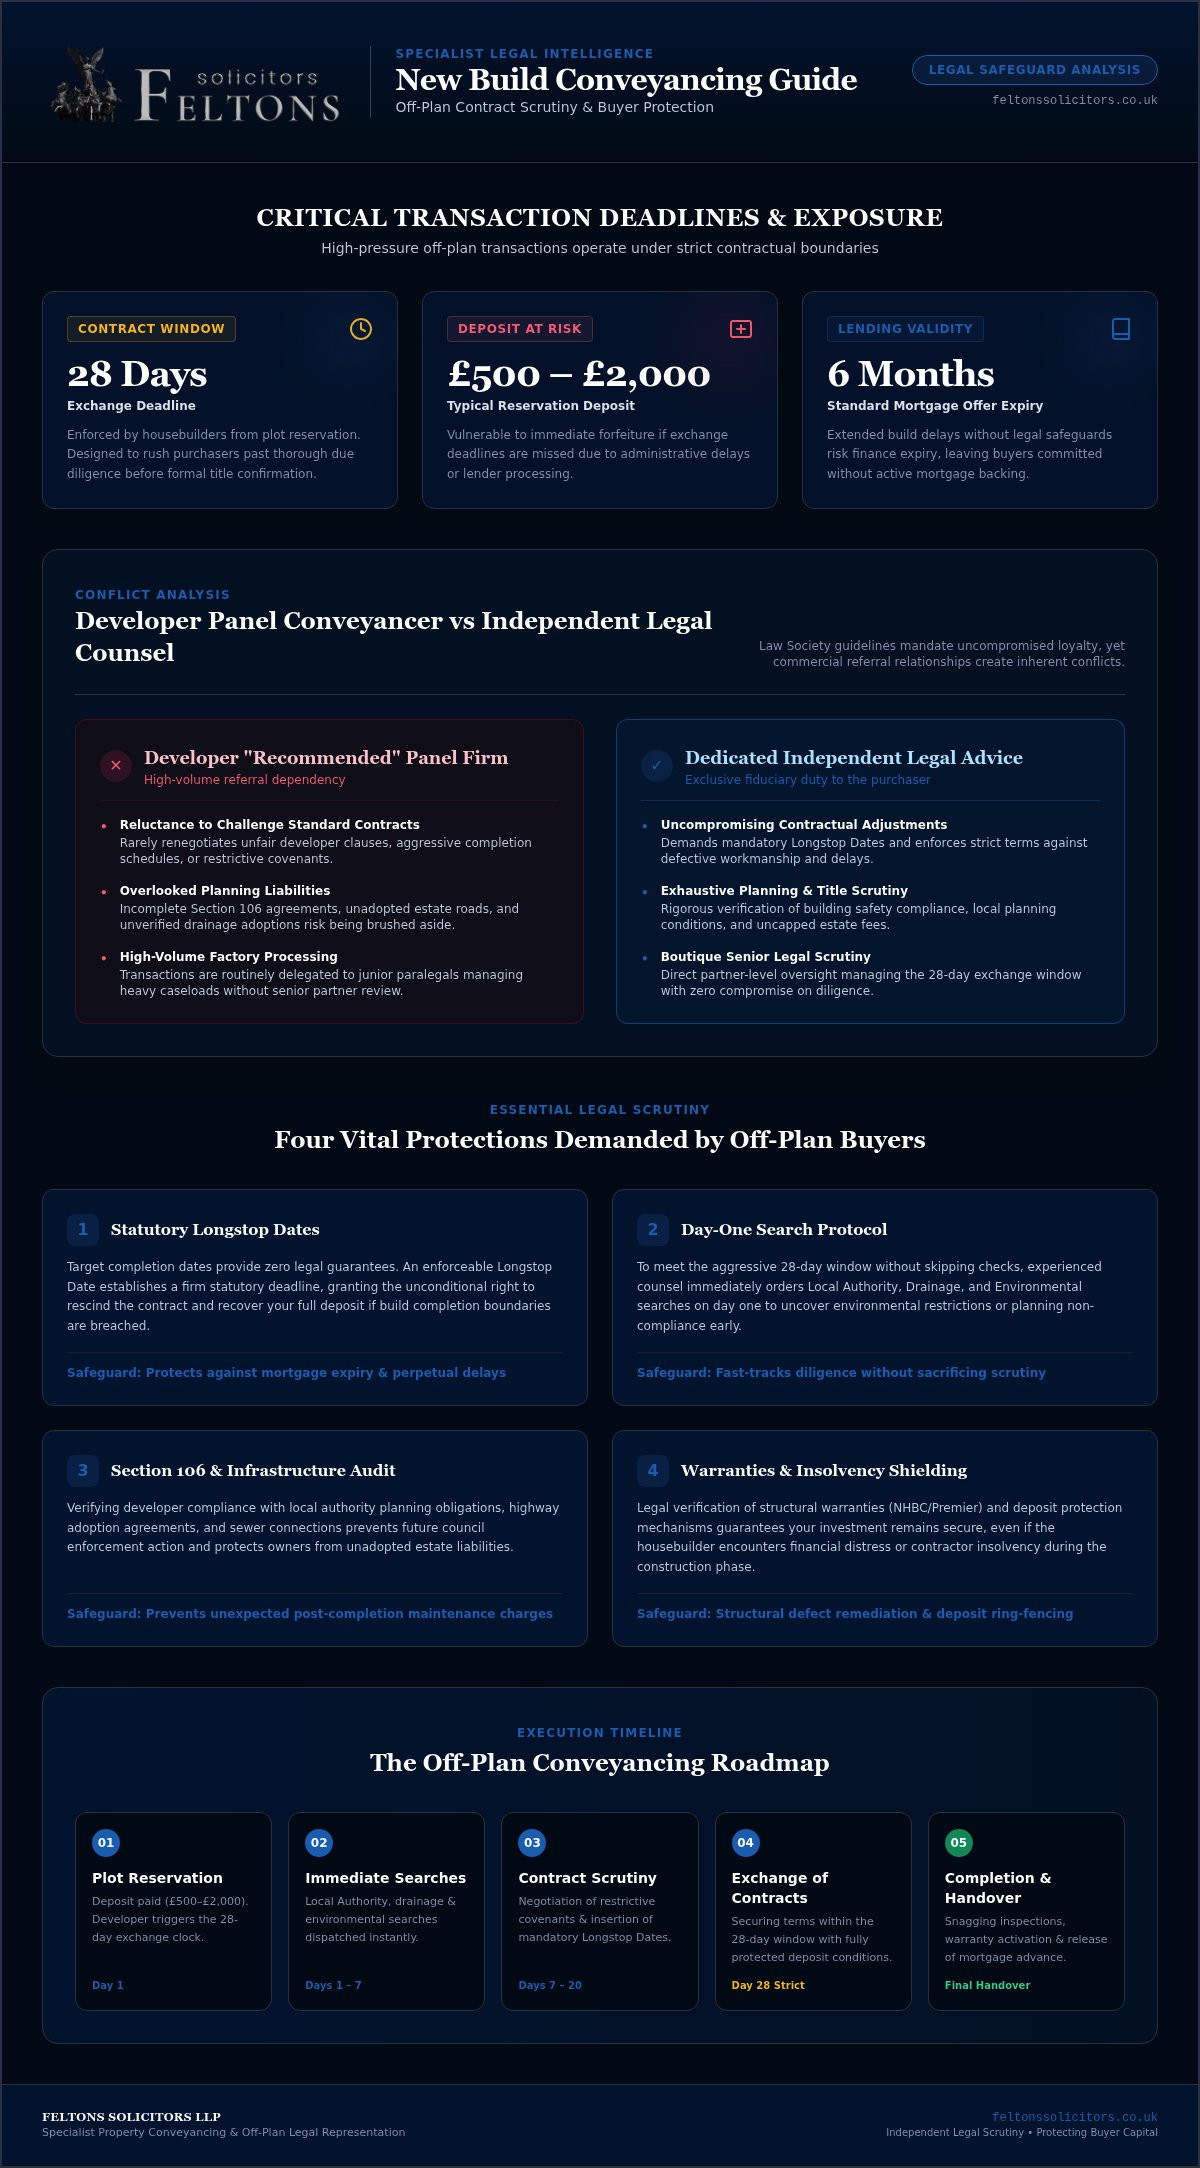
Housebuilders routinely enforce an aggressive 28-day exchange window from the moment you reserve a plot. This compressed timetable isn’t accidental; developers intentionally create urgency to rush buyers past comprehensive due diligence. If your mortgage lender delays an administrative sign-off or valuation, the developer may threaten to cancel your reservation and forfeit your initial deposit, which typically ranges between £500 and £2,000.

A proactive legal ally mitigates this manufactured pressure immediately. Experienced legal counsel orders local authority, drainage, and environmental searches on day one, managing tight deadlines while maintaining uncompromised scrutiny of the site’s title.

Developer Panel Solicitors vs Independent Legal Representation

Sales suites frequently push “recommended” panel conveyancers, offering attractive incentives or discounted legal fees if you accept. You should approach these recommendations with extreme caution. While Law Society guidelines strictly mandate that all solicitors act with uncompromised independence and client loyalty, panel firms operate under an undeniable commercial conflict. They rely on high-volume referral pipelines from the housebuilder to sustain their business models.

This reliant relationship creates tangible vulnerabilities for buyers:

  • Reluctance to challenge standard contracts: Panel firms rarely push back vigorously against unfair developer clauses or aggressive completion terms.
  • Overlooked planning restrictions: Incomplete Section 106 agreements, unadopted road liabilities, or unverified drainage adoptions can easily be brushed aside.
  • Factory processing: Cases are routinely handed down to junior paralegals working under high caseloads, eliminating meaningful partner-level analysis.

Securing fully independent new build property purchase legal advice ensures your solicitor answers exclusively to you. An autonomous conveyancer will unreservedly challenge unacceptable draft terms, dispute unreasonable build delays, and safeguard your deposit without worrying about upsetting the developer’s sales team.

Critical Contractual Risks in New Build Purchases: What Your Solicitor Must Scrutinise

Housebuilder sale agreements are drafted by institutional commercial lawyers to protect developer balance sheets rather than private buyers. Without targeted legal adjustments, standard off-plan contracts transfer substantial commercial risk onto your shoulders. Securing specialised new build property purchase legal advice ensures onerous covenants are identified and renegotiated before you commit your funds.

Longstop Dates and Protection Against Construction Delays

Off-plan contracts typically state an estimated completion date alongside an enforceable “longstop date”. The estimated target merely guides expectations; the longstop date establishes a definitive legal boundary. Because standard UK mortgage offers expire after six months, substantial site delays can leave you without valid financing. Your conveyancer must draft an enforceable longstop clause granting an unconditional right to rescind the contract and recover your full deposit if building work stalls indefinitely.

Uncapped Estate Rentcharges and Maintenance Obligations

Modern housing developments frequently feature unadopted roads, drainage infrastructure, and communal play areas managed by private property companies. If your transfer deed contains an estate rentcharge, any payment dispute can trigger draconian statutory remedies under Section 121 of the Law of Property Act 1925, allowing rentcharge owners to place a lease over your home. Your legal counsel must negotiate deed clauses that exclude these statutory remedies, whilst establishing clear caps on annual maintenance fee hikes.

Planning Permissions, Section 106 Obligations, and Structural Warranties

Your conveyancer must confirm that the developer has formally discharged all pre-commencement and pre-occupation local planning conditions. They must also verify statutory infrastructure agreements, including Section 38 highway bonds and Section 104 sewer adoptions, preventing local authorities from billing homeowners for unfinished roads. Crucially, your 10-year structural warranty from providers such as NHBC, Premier Guarantee, or LABC must align with consumer protections under the New Homes Quality Code before completion funds are transferred. For bespoke guidance on dismantling aggressive developer covenants, turning to an independent specialist at Feltons Solicitors ensures your legal footing remains completely secure throughout the purchase.

Choosing the right legal professional determines whether your transaction progresses smoothly or fractures under intense developer pressure. Off-plan acquisitions involve unique contractual mechanisms, complex infrastructure agreements, and strict planning triggers that standard domestic conveyancing rarely encounters. Selecting an inexperienced firm or relying on automated conveyancing platforms can leave critical title flaws unnoticed until it is too late to rectify them.

Securing dedicated new build property purchase legal advice from a specialist practice gives you the confidence that every developer clause has been scrutinised by an expert working solely on your behalf.

Dedicated Solicitor Attention vs High-Volume Factory Conveyancing

High-volume conveyancing factories rely on call-centre setups where files pass between rotating junior clerks and administrative assistants. This fragmented workflow often causes administrative bottlenecks, unreturned calls, and missed reservation deadlines. Conversely, boutique practices provide direct, continuous access to a qualified solicitor. Partner-led oversight ensures intricate planning conditions, boundary easements, and warranty certifications receive rigorous, personal scrutiny rather than superficial checklist reviews.

Essential Questions to Ask Before Instructing Legal Counsel

Before committing to a law firm, take the time to evaluate their technical background in handling housebuilder negotiations. You need absolute certainty that your representative can handle aggressive timescales without sacrificing comprehensive due diligence.

Pose these targeted questions during your initial enquiry:

  • Are you approved on all major UK mortgage lender panels? If your chosen firm lacks panel approval for your specific lender, separate representation will be required, generating substantial delays and duplicate legal costs.
  • Who will have day-to-day conduct of my file? Demand direct confirmation that a dedicated solicitor will personally review the contract pack and handle developer negotiations.
  • How do you handle rapid exchange deadlines? Enquire about their systems for ordering searches immediately and expediting preliminary enquiries before reservation periods elapse.
  • What is your proven track record with off-plan properties? Look for comprehensive expertise across all aspects of residential property law to ensure complex development covenants are correctly interpreted.

Partnering with an independent, partner-led firm guarantees that your legal defence remains robust, transparent, and entirely aligned with your financial safety.
New Build Property Purchase Legal Advice: The 2026 Buyer's Guide

The New Build Conveyancing Roadmap: From Reservation to Completion

Managing an off-plan acquisition requires a methodical approach that keeps pace with construction milestones without bypassing essential legal safeguards. Securing specialist new build property purchase legal advice transforms what can feel like a chaotic process into an orderly, five-stage progression:

  1. Reservation and immediate instruction: You pay the reservation fee, secure the developer’s draft contract pack, and instruct an independent legal representative immediately.
  2. Due diligence and search enquiries: Your solicitor scrutinises planning consents, highway adoptions, and local authority searches whilst synchronising your mortgage terms.
  3. Contract negotiation and exchange: Critical amendments regarding longstops and defect remedies are inserted before exchanging contracts and paying your deposit.
  4. Practical completion and snagging: The developer concludes physical works, serves formal completion notice, and permits independent pre-completion inspections.
  5. Legal handover and registration: Balance purchase monies are transferred, structural warranties are activated, and your title is registered at HM Land Registry.

Reservation, Search Inquiries, and Mortgage Offer Alignment

The reservation period moves quickly. Your conveyancer must order local authority, drainage, and environmental searches on day one to prevent developer deadlines from slipping. Concurrently, your legal team cross-references your mortgage offer against realistic build projections. Because most UK mortgage offers expire after six months, aligning your finance validity with anticipated construction phases prevents costly reassessments if bad weather or supply chain disruptions delay the site.

Exchange on Notice, Pre-Completion Inspections, and Snagging Retentions

Off-plan contracts rarely include a fixed completion calendar date. Instead, exchange occurs “on notice”. Once building control and warranty inspectors confirm the property is structurally sound, the developer serves a formal notice to complete, typically giving you ten working days to transfer final funds.

During this brief window, you have the legal right to commission an independent pre-completion snagging inspection before moving in. Wherever feasible, an experienced solicitor will push to incorporate retention clauses into the contract. These provisions allow you to withhold a defined portion of final completion funds until the developer satisfactorily rectifies identified snags.

To ensure your rights remain protected throughout every stage of development, speak to our specialist property solicitors to secure proactive, partner-led legal representation from day one.

Safeguarding Your Property Investment with Feltons Solicitors LLP

Established in 2010 by Paula Felton, Feltons Solicitors LLP delivers residential conveyancing founded on partner-led oversight, genuine accessibility, and uncompromising legal rigour. We represent buyers nationally across the United Kingdom, cutting through dense developer contracts to deliver pragmatic, plain-English guidance. When large housebuilders apply intense sales pressure, our solicitors act as an independent shield, protecting your deposit against unilateral contract variations and unfair site terms.

Securing specialist new build property purchase legal advice ensures your financial interests remain paramount. Rather than processing your transaction on an assembly line, we maintain direct lines of communication so you always know the exact standing of your file.

Boutique Legal Standards for Modern Property Purchases

Our boutique structure deliberately rejects the high-volume pressures of factory conveyancing practices. By maintaining manageable caseloads, our solicitors dedicate the time required to interrogate complex site masterplans, drainage adoption agreements, and planning obligations thoroughly. If you are purchasing an apartment, our dedicated capabilities in leasehold property matters ensure that service charge mechanics, management company covenants, and statutory building safety requirements are comprehensively audited before you commit.

Instructing Feltons Solicitors for Your New Build Purchase

Engaging our conveyancing team before you sign a reservation form gives you an immediate strategic advantage. Our onboarding process is entirely frictionless:

  • Immediate file opening: We contact the developer’s legal team directly on day one to request the comprehensive contract pack and planning schedules.
  • Expedited search orders: We commission local authority, environmental, and drainage searches instantly to prevent developer deadlines from slipping.
  • Robust contract amendments: We draft explicit longstop protections and delete disproportionate estate management clauses before presentation for signature.

We understand how challenging a developer’s 28-day exchange deadline feels. Our methodical, partner-led approach ensures you meet those strict commercial timetables without forfeiting your statutory buyer rights or compromising on due diligence. Contact our property team before paying your reservation deposit, and let us protect your home investment from the very outset.

Secure Your Investment with Confident, Independent Representation

Purchasing an off-plan home should be an inspiring milestone rather than a stressful gamble against developer deadlines. Securing specialist new build property purchase legal advice ensures your deposit remains ring-fenced, enforceable longstop dates are secured, and unadopted estate charges are challenged before you sign. Stepping away from developer-recommended panel conveyancers restores your negotiating power and puts your legal interests first.

Established in 2010, Feltons Solicitors LLP delivers partner-led residential conveyancing across the United Kingdom, combining high-value property experience with meticulous, personal attention. Our boutique practice gives you direct access to senior solicitors who challenge complex developer paperwork with uncompromised independence, keeping your transaction on track without cutting critical legal corners. You don’t have to navigate intense sales suites alone. Instruct Feltons Solicitors for your new build purchase today, and step into your new home with complete peace of mind.

Frequently Asked Questions

Can I use the developer’s recommended solicitor when buying a new build property?

Yes, you can legally instruct them, but doing so compromises your legal protection. Recommended panel conveyancers often rely on repeat referrals from the housebuilder, which creates an inherent conflict of commercial interest. Choosing independent legal representation guarantees your solicitor investigates planning agreements, contract variations, and site covenants without outside commercial pressure. Securing independent new build property purchase legal advice ensures your financial deposit and contractual interests remain the absolute priority throughout the transaction.

What happens if the developer fails to complete the build by the agreed date?

Your remedies depend entirely on whether an enforceable longstop clause was negotiated before contract exchange. Without this protection, you remain legally tied to the purchase even if construction delays stretch past your mortgage offer expiry date. If your contract incorporates explicit longstop provisions, exceeding the agreed date allows you to rescind the agreement, cancel your purchase obligations, and recover your full reservation and exchange deposits without financial penalty.

Why is a 28-day exchange deadline common for new build property purchases?

Housebuilders impose 28-day deadlines to lock buyers into legally binding contracts as quickly as possible. This commercial tactic secures non-refundable deposits and confirms development cash flow for the builder’s lenders. It intentionally narrows the window for comprehensive scrutiny, making it essential to instruct a proactive conveyancer on day one. An experienced legal team orders environmental, drainage, and local authority searches immediately to meet the deadline without sacrificing vital due diligence.

What are estate rentcharges and why do solicitors warn buyers about them?

Estate rentcharges are mandatory annual contributions levied on freehold homeowners to fund private development infrastructure, such as unadopted roads, drainage basins, and communal gardens. Conveyancers warn buyers about them because failure to pay, even over a disputed minor sum, can grant rentcharge owners statutory power under Section 121 of the Law of Property Act 1925 to create a lease over your home. Experienced solicitors negotiate modifications to exclude these draconian statutory remedies.

What is a longstop date in an off-plan property purchase contract?

A longstop date is the absolute final deadline by which a housebuilder must legally finish construction and achieve practical completion. Unlike standard estimated target dates, which are merely projections, the longstop date establishes a hard contractual boundary. If the housebuilder fails to deliver the property by this specified longstop point, you gain the statutory contractual right to terminate the agreement and receive an immediate refund of your deposit.

Can I legally delay completion if significant defects are discovered during snagging?

Generally, you cannot refuse to complete over minor snagging issues once the developer serves formal notice to complete. Standard contracts consider practical completion achieved once building control signs off the property. However, specialist new build property purchase legal advice can secure bespoke contractual retention clauses during pre-exchange negotiations. These provisions legally permit you to withhold a defined portion of final completion funds until the developer inspects and rectifies all major documented defects.

How do structural warranties like NHBC protect my new build purchase?

Structural warranties, such as those provided by NHBC, Premier Guarantee, or LABC, offer a 10-year policy covering major structural defects. During the initial two years, the housebuilder is legally obliged to repair any defects in materials and workmanship. In years three to ten, the warranty provider handles severe physical damage to core structural elements, including foundations, roofs, and load-bearing walls. Your solicitor verifies that warranty certificates are active prior to legal completion.
Transfer of Equity Solicitors: A Strategic Guide to Reorganising Property Ownership

Transfer of Equity Solicitors: A Strategic Guide to Reorganising Property Ownership

What if the simple act of adding a partner to your property title inadvertently triggered a tax bill worth thousands of pounds? It is a common anxiety for homeowners who wish to reorganise their assets but feel overwhelmed by Stamp Duty liabilities or the technicalities of mortgage lender consent. When the stakes are this high, the guidance of experienced transfer of equity solicitors is more than a formality; it is a vital safeguard for your wealth. Whether you are managing a matrimonial breakdown or gifting a share of your home, the emotional weight is often as significant as the legal complexities.

You deserve a transition handled with both technical precision and empathy. This guide is designed to help you manage these changes, ensuring your equity remains protected and your future is secure. We understand that your property is more than just an asset; it is the foundation of your personal life. We will provide a clear roadmap through the nuances of UK property law and tax obligations. We preview the essential steps to achieve a legally robust transfer of title whilst maintaining the privacy and dignity your family dynamics require.

Key Takeaways

  • Identify the common scenarios for reorganising property interests, ranging from matrimonial settlements and new marriages to family gifting and tax planning.
  • Understand the pivotal role of mortgage lender consent and why it represents the most significant legal hurdle in the transfer process.
  • Follow a clear, step-by-step roadmap that covers everything from initial identity verification to the final registration of Title Deeds.
  • Discover how to navigate complex tax obligations, including the calculation of Stamp Duty Land Tax (SDLT) on the consideration provided.
  • Learn why engaging expert transfer of equity solicitors is vital for protecting your financial security whilst managing the sensitive human impact of property transitions.

Understanding Transfer of Equity: Why Reorganise Your Property Interests?

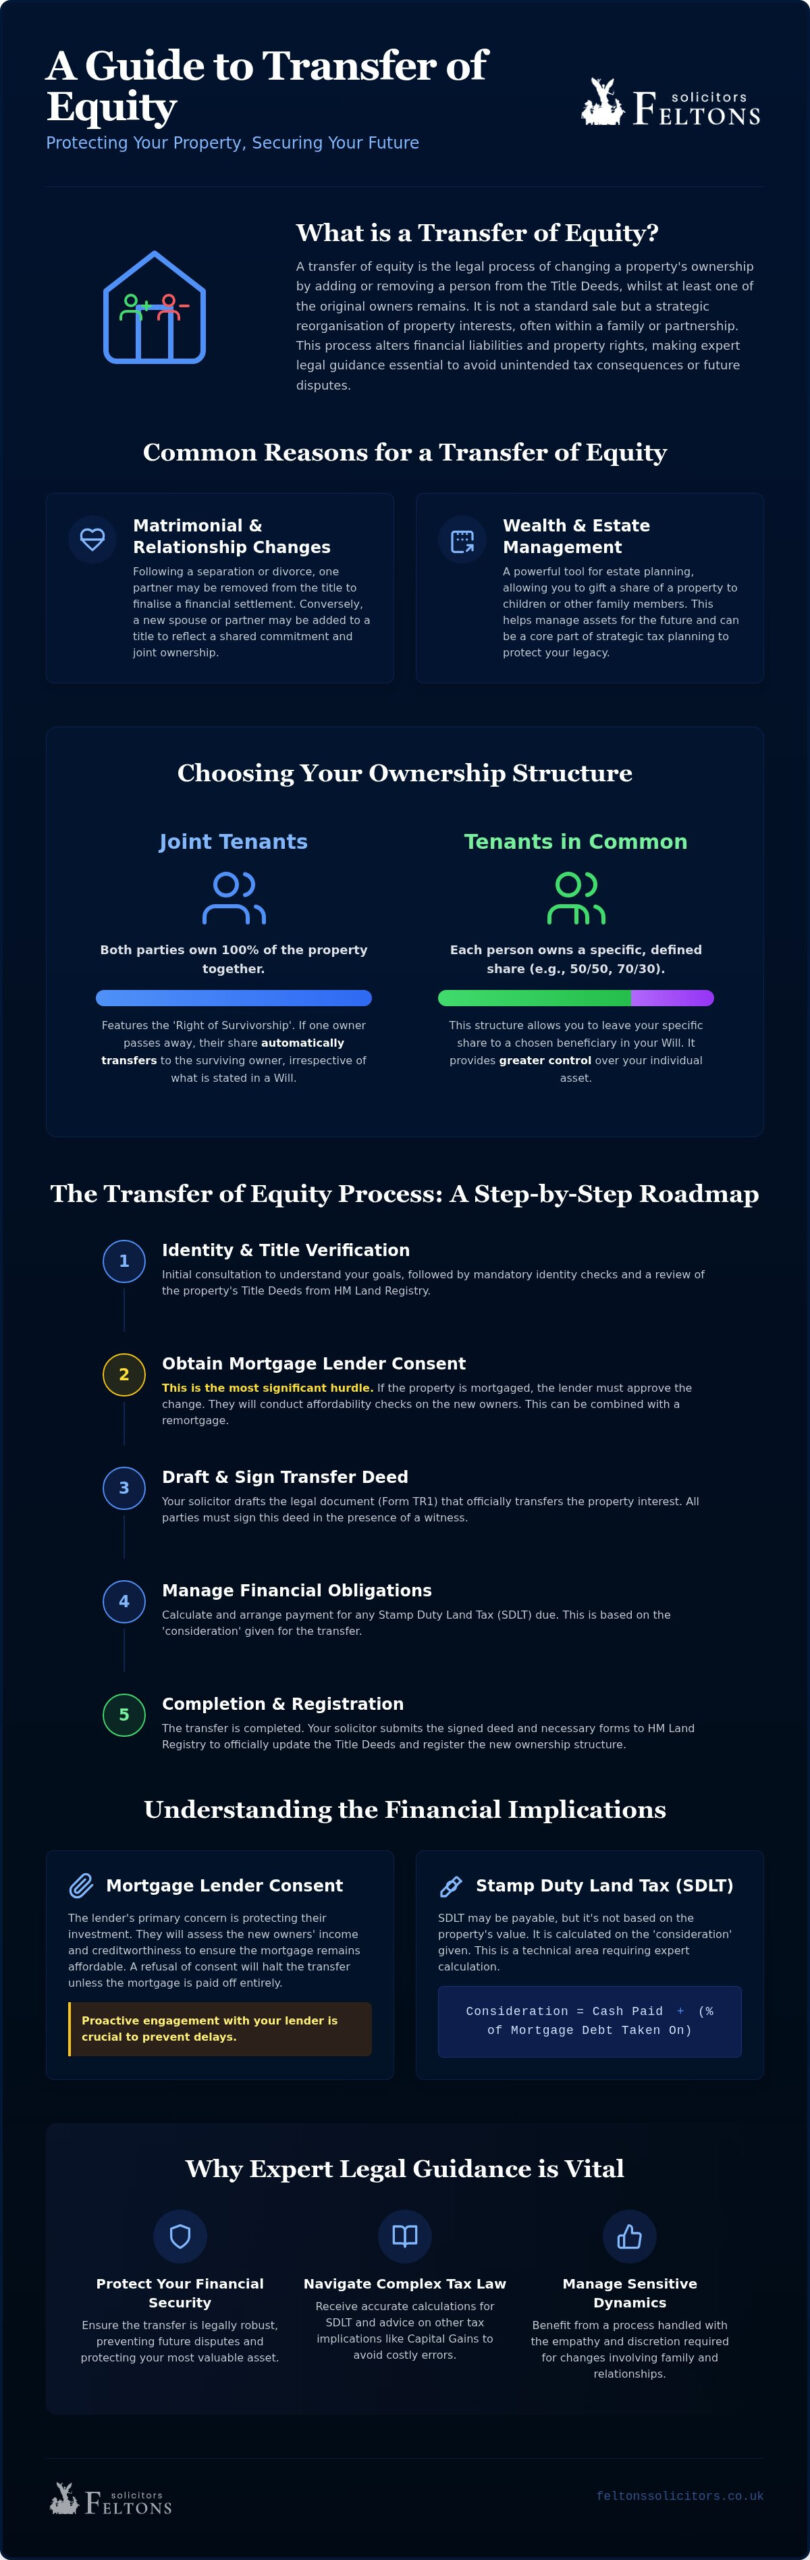
A transfer of equity occurs when the legal ownership of a property changes hands, but at least one of the original owners remains on the Title Deeds. This process differs significantly from a standard sale or purchase. In a typical market transaction, a property is sold, the mortgage is cleared, and the owners move on. A transfer of equity is instead a strategic reorganisation of existing interests. To gain a foundational perspective, one might ask, What is a transfer of equity? Simply put, it’s the legal mechanism used to add or remove individuals from a property’s title whilst keeping the property within a specific group or family unit.

Because these transitions often involve existing mortgages and significant tax implications, the expertise of a professional residential property law firm is essential. This isn’t merely an administrative update; it’s a formal legal shift that alters your financial liabilities and rights. Without precise guidance, homeowners risk future disputes or unintended tax consequences that can take years to resolve. Expert transfer of equity solicitors provide the technical accuracy needed to ensure the new ownership structure is legally robust and reflects your true intentions.

Matrimonial and Relationship Changes

Significant life transitions often necessitate a change in property holdings. Following a separation, a divorce and financial arrangements lawyer may advise removing a former partner from the title to finalise a financial settlement. Conversely, you might wish to add a new spouse or partner to the title of a home you already own to reflect a shared commitment. These moments require a delicate touch. We act as a calm, steady presence, balancing technical legal precision with the emotional sensitivity these personal changes demand.

Strategic Wealth and Estate Management

Beyond personal relationships, equity transfers are powerful tools for protecting your financial future. Gifting a share of a property to children or other family members can be a cornerstone of effective estate planning. However, the way you hold that equity is critical. You must decide between two primary structures:

  • Joint Tenants: Both parties own the whole property together. If one person passes away, their share automatically transfers to the survivor, regardless of what is written in a Will.
  • Tenants in Common: Each person owns a specific, defined percentage of the property. This allows you to leave your specific share to a chosen beneficiary in your Will.

Choosing between these options depends on your long-term goals and family dynamics. Transfer of equity solicitors help you navigate these choices, ensuring your property interests are organised in a way that respects your privacy and secures your legacy for the next generation.

If your property is subject to a mortgage, your lender is effectively a silent partner in any ownership change. Their consent is the primary hurdle in the process; without it, the transfer cannot legally proceed. Lenders view a change in ownership as a shift in their security. Whether you are removing a former partner or adding a new spouse, the bank must ensure their investment remains protected. Experienced transfer of equity solicitors act as the bridge between you and the financial institution, ensuring all criteria are met before any documents are signed.

Many homeowners choose to combine this transition with a remortgage. This synergy often makes financial sense, as it allows you to secure a better rate whilst simultaneously reorganising the title. If you stay with your current lender, they’ll conduct a full affordability assessment to ensure the remaining or new owners can comfortably meet the monthly repayments. If the bank refuses consent, usually due to a low credit score or insufficient income, the transfer will stall unless the mortgage is cleared in full. For those needing to explore alternative financing to bridge this gap, I Need Cash offers a way to compare various homeowner and personal loan products. Identifying these roadblocks early is a core part of our proactive approach.

Lenders prioritize risk management above all else. When a party is removed from a title, the bank must formally release them from their personal covenant to repay the debt. This “clean break” is vital for the outgoing individual, as it prevents them from being held liable for future arrears. For the remaining owner, the bank may require a ‘Deed of Covenant’ or a entirely new mortgage offer. They’ll scrutinise your income and outgoings with the same rigour as a fresh purchase; in such cases, Lee Tonks: Mortgage Guru can provide the independent advice needed to ensure the debt is sustainable on a single or revised set of earnings.

Coordinating with Financial Institutions

The timeline for a transfer is often dictated by the lender’s internal processing speeds. Your solicitor manages this coordination, ensuring that the mortgage offer aligns with the wider conveyancing process and Land Registry requirements. This involves significant back-and-forth communication to verify identity, confirm equity shares, and secure the final ‘letter of consent’.

Managing these moving parts requires a methodical mindset and a deep understanding of banking protocols. If you’re feeling uncertain about how your lender might react to a change in your circumstances, seeking advice from a specialist property solicitor can provide the clarity you need to move forward with confidence. We handle the technical liaisons, allowing you to focus on the personal transition at hand.

Your journey begins with a formal instruction. This stage involves rigorous Anti-Money Laundering (AML) checks, a mandatory requirement that ensures the integrity of the transaction and protects all parties from financial impropriety. Once identity is verified, we obtain the official copies of the title from the Land Registry. This review allows us to identify any existing charges, restrictions, or notices that might complicate the transition. It’s a methodical start that builds a secure foundation for the work ahead.

After reviewing the deeds, we move to the pivotal stage of securing lender consent, as discussed in our previous section. This involves a steady exchange of information with your bank to ensure the new ownership structure aligns with their lending criteria. Only when consent is in place can the formal transfer documents be prepared. Expert transfer of equity solicitors act as the primary coordinator here, ensuring that every piece of the puzzle fits perfectly before moving to execution.

Drafting the Transfer Deed (TR1)

The TR1 form is the legal instrument that effects the change in ownership. Within this document, we must clearly specify the ‘consideration’. This is the value being exchanged for the share of the property. It’s a common misconception that consideration only refers to cash; in a transfer of equity, the assumption of mortgage debt is also viewed as consideration by HMRC. We also confirm the ownership structure, whether you’ll hold the property as Joint Tenants or Tenants in Common. To prevent future ‘undue influence’ claims, transfer of equity solicitors often require the outgoing party to seek independent legal advice. This ensures they fully understand the rights they’re relinquishing, protecting the validity of the entire transaction.

Post-Completion Formalities

Once the TR1 is signed and witnessed, completion occurs. However, the legal work doesn’t end there. We must submit a Stamp Duty Land Tax (SDLT) return to HMRC, even if the transaction falls below the tax threshold and no payment is due. Following this, an application is made to the Land Registry to update the official record. Fees for this are typically submitted electronically, following the established HM Land Registry fee scales for transfers. This registration can take several weeks to process. Once finished, we provide you with the updated Title Register. This document serves as your final, definitive record of ownership, offering you the peace of mind that your property interests are correctly and securely organised.

Transfer of Equity Solicitors: A Strategic Guide to Reorganising Property Ownership

Financial Implications: SDLT, Capital Gains, and Valuation

While the legal mechanics of a transfer are vital, the financial consequences often present the most significant challenges. Many homeowners assume that if no money changes hands, no tax is due. This is a potentially costly misconception. In the UK, HM Revenue and Customs (HMRC) views the transfer of equity as a transaction with a specific value, known as ‘consideration’. Understanding how this value is calculated is where the guidance of transfer of equity solicitors becomes indispensable for protecting your long-term financial security.

An accurate property valuation is the cornerstone of this process. Whether you’re reorganising interests for tax planning or a family settlement, you must establish a fair market value. HMRC scrutinises transfers between ‘connected persons’, such as family members, and using an incorrect valuation can lead to penalties or prolonged investigations. We ensure your financial disclosures are pragmatic and robust, reflecting current market conditions whilst respecting your personal privacy.

The SDLT ‘Consideration’ Trap

Stamp Duty Land Tax (SDLT) is often triggered during a transfer because ‘consideration’ includes the value of any mortgage debt the new owner takes on. For example, if you’re added to a title for a property with a £300,000 mortgage, you’re effectively taking on responsibility for £150,000 of that debt. This £150,000 counts as consideration. Under 2026 rates, the standard SDLT threshold starts at £125,000. In this scenario, tax would be payable on the £25,000 that exceeds the 0% band. However, transfers resulting from a matrimonial breakdown or a court order are typically exempt from SDLT. We help you identify these exemptions early to avoid unnecessary payments.

Capital Gains Tax and Gifting

If the property is not your primary residence, such as a buy-to-let investment or a second home, Capital Gains Tax (CGT) may apply. For the 2026/2027 tax year, CGT rates for residential property stand at 18% for basic rate taxpayers and 24% for higher rate individuals. When gifting a share of a property to a child or family member, the ‘Market Value’ rule applies. HMRC calculates the gain based on the current value of the share being gifted, regardless of whether any money was paid. With an Annual Exempt Amount of just £3,000, these liabilities can accumulate quickly. Seeking early tax advice ensures you aren’t blindsided by a large bill months after the legal work is complete.

Managing the intersection of property law and tax obligations requires a steady, expert hand. If you’re planning to reorganise your property interests, consult our specialist property team to ensure your equity is protected and your tax liabilities are clearly understood before you proceed.

Reorganising property ownership is rarely a standalone task. It sits at the complex intersection of property law, family arrangements, and long-term tax planning. Each of these areas carries its own risks and requirements. A mistake in one can derail the others, leading to financial loss or personal friction. This is why the involvement of expert transfer of equity solicitors is vital. We don’t just process forms; we provide a strategic overview that ensures your transition is seamless and your interests remain protected.

In matrimonial transfers, the process is often emotionally charged. We act as a calm, steady presence, providing the technical precision needed whilst respecting the sensitivities of your situation. Our goal is to future-proof your property title. We ensure that every detail, from the specific wording of the Transfer Deed to the final Land Registry entry, is robust enough to withstand future scrutiny or potential disputes. By choosing a partner who understands the human impact of legal work, you ensure a transition that is as smooth as it is secure.

A Sophisticated Boutique Service

We pride ourselves on a “people-first” philosophy. Unlike high-volume firms that prioritise speed over substance, our boutique approach focuses on personal connection. We offer discreet, high-standard care that is particularly valued by high-net-worth clients who require a tailored experience. This bridges the gap between traditional professional integrity and the efficiency of modern legal delivery. You aren’t just a file number; you’re a partner in a process that values your privacy and unique circumstances. This level of individualized attention ensures that no detail is overlooked and every concern is addressed with poise and dependability.

Securing Your Property’s Future

Our expertise extends beyond simple title changes. As leasehold enfranchisement experts, we understand the nuances of complex title issues that often surface during an equity transfer. We coordinate holistically with your other professional advisors, such as accountants or surveyors, to ensure every financial and legal angle is covered. This collaborative approach provides a comprehensive service that secures the foundation of your property rights for years to come. It’s about more than the immediate change; it’s about building a legally robust future for your most valuable assets. To discuss your property ownership goals, contact our transfer of equity specialists today.

Securing Your Property Interests for the Long Term

Reorganising your property ownership is a significant legal transition that requires more than just administrative filing. It demands a strategic understanding of how mortgage lender consent, tax liabilities, and family dynamics intersect. By addressing these complexities with foresight, you ensure your equity is protected and your title remains legally robust against future challenges. Navigating the nuances of Stamp Duty and Capital Gains Tax is essential for maintaining your financial security whilst achieving your personal objectives.

At Feltons Solicitors LLP, we specialise in complex property and matrimonial transitions, providing pragmatic, professional advice tailored to your specific goals. Our discreet, boutique service ensures a human touch whilst maintaining the high-standard reliability you expect from a trusted advisor. When you engage transfer of equity solicitors who prioritise personal connection over high-volume processing, you gain a steady partner for your most valuable assets. We’re here to provide the calm, expert guidance needed to make your property reorganisation a success.

Secure your property’s future with Feltons Solicitors LLP. We look forward to guiding you through this transition with the poise and expertise your property deserves.

Frequently Asked Questions

Do I have to pay Stamp Duty when transferring equity in my home?

You may need to pay Stamp Duty Land Tax (SDLT) if the ‘consideration’ exceeds the current threshold. Consideration includes cash payments and the value of any mortgage debt the new owner takes on. For the 2026/2027 tax year, the standard threshold begins at £125,000. However, transfers resulting from a divorce or matrimonial breakdown are usually exempt. Consulting transfer of equity solicitors early ensures you don’t overlook potential exemptions or trigger unnecessary tax bills.

Can I transfer equity without my mortgage lender’s consent?

No, you cannot proceed without your mortgage lender’s formal consent. Because the lender has a legal charge over the property, they must approve any change to the ownership structure. They’ll conduct a full affordability assessment to ensure the remaining or new owners can meet the debt obligations. If consent is refused, the mortgage must be cleared in full before the transfer can occur. This is a critical hurdle that requires careful coordination.

How long does a typical transfer of equity take to complete?

A typical transfer of equity usually takes between four and eight weeks to complete. This timeline is heavily influenced by how quickly your mortgage lender provides consent and the complexity of your specific title. Whilst the legal drafting is relatively swift, external factors like HMRC filings and Land Registry registration can extend the process. We work methodically to ensure each stage is handled promptly to avoid any unnecessary delays for our clients.

Is a transfer of equity different if the property is a leasehold?

Yes, leasehold transfers involve additional administrative steps. You’ll likely need to notify the freeholder or management company of the change in ownership. There are often administrative fees for a ‘Notice of Transfer’ or ‘Notice of Charge’ as stipulated in your lease. As transfer of equity solicitors with expertise in leasehold matters, we manage these communications to ensure your lease remains compliant and your property rights are fully protected throughout the transition.

Do I need a new valuation of the property for a transfer of equity?

Yes, a formal valuation is often essential for both lender approval and tax compliance. HMRC requires the transfer to be based on a ‘fair market value’ to calculate potential Stamp Duty or Capital Gains Tax liabilities accurately. If you’re remortgaging as part of the process, your lender will also insist on an independent valuation to confirm their security. Establishing an accurate figure at the outset prevents future disputes with authorities or other parties.

What is the difference between a transfer of equity and a gift of property?

A transfer of equity involves at least one original owner remaining on the title, whilst a gift of property usually sees the entire interest transferred to someone else. Both scenarios are treated as disposals for tax purposes. If you’re gifting a share of a property that isn’t your main home, Capital Gains Tax may apply based on the market value. We provide the pragmatic advice needed to navigate these distinctions safely and securely.

Can a transfer of equity be challenged in the future by a former partner?

A transfer can be challenged if there’s evidence of ‘undue influence’ or if a party didn’t receive independent legal advice. To mitigate this risk, we ensure the process is transparent and that all parties understand the rights they’re relinquishing. A legally robust transfer, registered correctly at the Land Registry, provides the definitive record needed to protect your future interests. Our boutique approach prioritises these safeguards to ensure your property’s long-term security.

Does the outgoing person need their own solicitor for the transfer?

Yes, the outgoing person should always seek independent legal advice. Most transfer of equity solicitors and mortgage lenders require this to prevent a conflict of interest. It ensures that the individual leaving the title fully understands the financial and legal implications of their decision. This step is vital for the validity of the transfer, as it protects the transaction from future claims that the person was pressured or misinformed during the process.

Leasehold Enfranchisement Solicitors: A Strategic Guide to Securing Your Freehold in 2026

Leasehold Enfranchisement Solicitors: A Strategic Guide to Securing Your Freehold in 2026

What if the most significant obstacle to your property’s value isn’t the market, but the very lease you’re holding? With approximately 4.90 million leasehold dwellings in England, many owners feel trapped by rising ground rents and the legislative shifts of 2026. Partnering with expert leasehold enfranchisement solicitors is no longer just a legal formality. It’s a strategic move to reclaim control over your home’s future. We recognise that the anxiety of aggressive freeholders or complex valuation disputes can be exhausting, especially whilst the government continues to refine the 2024 Reform Act’s implementation.

This guide explains how to manage these complexities and secure your freehold with pragmatic legal advice tailored to your property goals. You’ll learn about the latest statutory updates, including the abolition of the two-year ownership rule and the proposed ground rent caps. We’ll provide a clear roadmap toward full ownership and increased marketability, ensuring you feel supported and informed throughout the entire process. By aligning modern methodology with traditional professional integrity, you can move forward with quiet confidence.

Key Takeaways

  • Learn how to distinguish between statutory lease extensions and collective enfranchisement to choose the most cost-effective route for your property.
  • Understand the 2026 impact of the Leasehold and Freehold Reform Act, specifically regarding the abolition of marriage value for leases under 80 years.
  • Master the statutory timeline, including how to correctly serve an Initial Notice and navigate the subsequent negotiation period with your freeholder.
  • Find out how specialist leasehold enfranchisement solicitors provide the partner-led, pragmatic advice needed to handle complex valuation disputes and aggressive freeholders.
  • Discover how to transform a “wasting” leasehold asset into a secure freehold, significantly increasing your property’s long-term marketability and value.

Understanding Leasehold Enfranchisement: Taking Control of Your Property Rights

Leasehold enfranchisement is the statutory right for leaseholders to purchase the freehold of their property. It transforms the legal relationship between you and the building, moving you from a tenant with a finite interest to an absolute owner. For many, this process is a financial necessity. A lease is a “wasting asset”; its value diminishes as the remaining term grows shorter. By engaging specialist leasehold enfranchisement solicitors, you can halt this depreciation and secure the long-term equity of your home.

The shift from leaseholder to freeholder is both psychological and financial. You’re no longer subject to the whims of a landlord or a management company’s escalating fees. Whilst the process for houses usually involves an individual claim, flat owners often act together. Understanding Collective Enfranchisement is vital here, as it allows a group of neighbours to gain total control over their building’s management and future. This collective approach often results in a more harmonious living environment and a shared commitment to the property’s upkeep.

The Core Benefits of Enfranchisement

Choosing to enfranchise offers immediate practical advantages that extend beyond mere ownership. You’re effectively future-proofing your investment against market volatility and legislative changes. Key benefits include:

  • Eliminating Ground Rent: Once you own the freehold, ground rent obligations cease entirely. This is particularly relevant given the 2026 proposals to cap existing ground rents at £250 per year.
  • Control Over Service Charges: You and your fellow freeholders decide who manages the building and how much is spent on maintenance, removing the risk of inflated third-party costs.
  • Increased Marketability: Properties with a share of freehold or a significantly extended lease are far more attractive to lenders and future buyers.
  • 999-Year Lease Extensions: As a freeholder, you can grant yourself a lease of up to 999 years at a “peppercorn” rent, effectively removing lease length as a concern for generations.

Who is Eligible? The Qualifying Tenant Criteria

To start this process, you must be a “qualifying tenant.” Traditionally, this required a “long lease” originally granted for more than 21 years. In the past, leaseholders also had to wait two years before they could serve a formal notice. However, a significant reform as of 31 January 2025 abolished this two-year ownership requirement. This change allows new buyers to begin their claim immediately after completion. Some exclusions still apply, such as properties owned by the National Trust or certain charitable interests. Our leasehold enfranchisement solicitors ensure these technical details are verified early, providing you with a clear, pragmatic path forward.

Extending Your Lease vs. Buying the Freehold: Choosing the Right Path

Deciding between extending your lease or purchasing the freehold is a pivotal moment for any property owner. Whilst both options protect your investment, they serve different strategic goals. A lease extension is often a swifter, individual path to security. Collective enfranchisement, however, offers the ultimate prize: total autonomy over your building’s management. Expert leasehold enfranchisement solicitors can help you weigh these options against your long-term objectives and the specific nuances of your building’s structure.

The Statutory Lease Extension Route

The formal route under the Leasehold Reform, Housing and Urban Development Act 1993 allows you to add 90 years to your current term. This process is initiated by serving a Section 42 notice on your landlord. Once completed, your ground rent is reduced to a “peppercorn” (zero) for the duration of the lease. This is often the most pragmatic choice if your neighbours aren’t interested in a joint purchase. Be wary of “informal” or voluntary extensions offered by landlords. These often include hidden traps like escalating ground rents or unfavourable terms that don’t offer the same statutory protections as the formal route.

Collective Enfranchisement: Buying the Freehold of a Block

If you live in a block of flats, you might prefer to join forces with your neighbours. To trigger this claim, at least 50% of the qualifying tenants in the building must participate. This “50% rule” is the gateway to removing a third-party landlord from the equation entirely. Beyond the financial uplift, the management benefits are significant. You can appoint your own agents and set service budgets that reflect your building’s actual needs. For a broader look at your rights as a property owner, see our guide on Navigating Residential Property Law: A Comprehensive Guide for UK Homeowners.

Evaluating the costs is essential. The premium for a freehold is usually higher than a lease extension, but the added value and control often justify the expense. The 2026 Leasehold Reforms are currently addressing how these costs are shared, with consultations focusing on whether each party should bear their own legal expenses. This is a complex landscape where the right advice pays for itself in avoided disputes. If you’re unsure which path fits your circumstances, consulting with a boutique firm can provide the clarity you need to proceed with quiet confidence.

The legislative environment in 2026 is one of significant transition. While the Leasehold and Freehold Reform Act 2024 set the stage, the full implementation of its enfranchisement provisions remains tied to the Commonhold and Leasehold Reform Bill. Many leaseholders have adopted a cautious approach, waiting for the secondary legislation that will finally standardise the cost of buying their freehold. The Law Commission’s Review was instrumental in identifying the need for these changes, aiming to replace complex, litigious calculations with a more transparent methodology. For those navigating this shift, leasehold enfranchisement solicitors provide the necessary foresight to determine whether to act now or wait for the new valuation rates to be finalised following the current government consultations.

The End of Marriage Value: A Game Changer for Leaseholders

Historically, the 80-year mark was a financial cliff edge. Once a lease fell below this point, the premium skyrocketed due to “marriage value.” Marriage value represents the potential increase in the property’s value created by combining the leasehold and freehold interests, with half of this uplift traditionally paid to the landlord. The 2026 landscape looks far more favourable for tenants, as the abolition of this requirement is a central pillar of the new reforms. This change removes the urgent pressure to extend before the 80-year deadline, though the exact timing of its implementation depends on the prescribed rates currently being debated in Parliament.

Standardised Rates and Capped Ground Rents

Valuation is becoming less of a negotiation and more of a calculation. The shift toward a standardised “valuation tool” aims to eliminate the aggressive “hope value” claims often made by freeholders. Ground rent also plays a critical role; the proposed cap of £250 per year in the draft bill significantly reduces the capitalised value of the landlord’s interest. However, technical disputes still arise. Our leasehold enfranchisement solicitors work closely with RICS surveyors who specialise in this niche field to ensure that deferment and capitalisation rates are applied fairly. Ensuring your valuation is grounded in current 2026 data is vital, as the government’s consultation on these rates closes on 21 October 2026. This methodical approach protects you from overpaying whilst securing your property’s future.

Leasehold Enfranchisement Solicitors: A Strategic Guide to Securing Your Freehold in 2026

The Statutory Process: A Step-by-Step Guide to Successful Enfranchisement

The statutory route is a procedural journey that requires precision and a steady hand. It’s not merely about filling out forms; it’s about adhering to a strict legal timeline that leaves no room for error. Working with experienced leasehold enfranchisement solicitors ensures that every milestone, from the initial valuation to the final transfer of title, is handled with the methodical care your property deserves. This process provides a structured path to ownership, protecting you from the uncertainties of informal negotiations that often lack statutory safeguards.

Preparing Your Claim: Valuation and Participation

Success begins long before any formal notice is served. You must gather accurate data regarding the building’s structure, the existing leases, and the current ground rent schedules. For collective claims, participation agreements are essential. These legally binding documents ensure that all involved leaseholders remain committed to the purchase, preventing the claim from collapsing if one party wavers. For more detail on these early stages, see our guide on Leasehold Enfranchisement Experts: A Guide to Securing Your Property Rights in 2026.

Once your preparation is complete, you serve an Initial Notice. This is a Section 13 notice for collective enfranchisement or a Section 42 notice for a lease extension. The freeholder then has two months to serve a Counter-Notice. This is often where the real work begins. Freeholders may attempt to inflate the premium or delay the process to force a “deemed withdrawal.” If a claim is withdrawn because a deadline is missed, you’re usually barred from re-applying for 12 months, making expert management of the timeline vital.

Negotiation and Tribunal Protection

A specialist solicitor acts as a calm buffer during these negotiations. We maintain a professional dialogue whilst robustly defending your valuation. If terms cannot be agreed within the statutory period, the matter moves to the First-tier Tribunal (Property Chamber). As of July 2026, the fee framework is clearly defined; many common leasehold applications involve an application fee of £114 and a hearing fee of £227. The Tribunal provides a fair, independent resolution, ensuring that freeholders cannot hold you to ransom with unreasonable demands.

After terms are finally agreed or determined by the Tribunal, the legal transfer of the freehold or the grant of the new lease takes place. This final stage involves updating the Land Registry to reflect your new status as a freeholder or a long-lease owner. To ensure your claim is handled with boutique-level care and partner-led expertise, instructing specialist solicitors early in the process is the most strategic way to secure your property goals.

Selecting the right legal partner is the most critical decision in your enfranchisement journey. Whilst many generalist conveyancers may offer to assist, the technicality of the Leasehold Reform Act 1993 and the 2024 Act’s ongoing implementation requires a specialist hand. Enfranchisement isn’t a standard administrative task. It involves complex valuation disputes, the navigation of intermediate head leases, and the management of mixed-use building requirements. Generalists often overlook these nuances, potentially leading to costly delays or even the “deemed withdrawal” of your claim.

Engaging specialist leasehold enfranchisement solicitors ensures that your new lease or freehold transfer is drafted to modern standards. This protects you from outdated clauses that could hinder future mortgageability. At Feltons Solicitors, we provide a boutique, partner-led alternative to large, high-volume firms. This means your case isn’t passed to a junior assistant; it receives the focused attention of an experienced advisor who understands the strategic weight of your investment. We ensure that every document reflects the current 2026 legislative landscape, providing you with a secure, long-term asset.

A Tailored Approach to Property Rights

We prioritise personal connection and steady guidance throughout what can often be a stressful period. Our firm has deep experience in handling both national and international property portfolios, ensuring that whether you own a single flat or a complex block, the approach is bespoke. We combine traditional professional integrity with modern delivery, ensuring that your rights are robustly defended without sacrificing the human element of the service. This people-first philosophy allows us to manage aggressive freeholders whilst keeping you informed and at ease. You’re not just another file; you’re a partner in a strategic legal process.

Next Steps: Securing Your Property’s Future

Beginning your enfranchisement journey starts with a professional consultation to assess your eligibility and the likely premium. Our pragmatic advice focuses on achieving your goals with the least amount of friction. We believe that legal expertise should be accessible and supportive, providing a clear roadmap through the 2026 reforms. Taking control of your freehold is a significant step toward financial independence and property security. By acting now, you can capitalise on the abolition of marriage value and the shifting valuation methodology.

Contact Feltons Solicitors for expert guidance on your enfranchisement claim and discover how our specialist team can simplify the complex for you.

Taking the Next Step Toward Property Autonomy

Securing your freehold in 2026 is a strategic investment that requires a calm, methodical approach. The legislative shift, particularly the abolition of marriage value, has removed the financial “cliff edge” for many, but the technical demands of the statutory process remain as rigorous as ever. By understanding the timeline and preparing your valuation data early, you can avoid common pitfalls like inflated premiums or missed deadlines. This process is about more than just ownership; it’s about future-proofing your home and reclaiming control over your property rights.

Partnering with specialist leasehold enfranchisement solicitors ensures your interests are protected by experts who understand the nuances of complex property litigation. At Feltons Solicitors, we provide pragmatic, plain-English advice delivered with the personal touch of a boutique firm. Our partner-led approach ensures that your property goals are met with quiet confidence and professional integrity. We bridge the gap between established heritage and forward-thinking methodology to deliver a high-standard service.

Instruct Feltons Solicitors for your leasehold enfranchisement today to begin your journey toward full ownership. We’re here to guide you through every stage of the process with care and expertise.

Frequently Asked Questions

How much does leasehold enfranchisement cost in 2026?

The total cost comprises the premium paid to the freeholder, valuation fees, and legal costs for both parties. Whilst the 2026 reforms aim to reduce these expenses, current government consultations on valuation rates and legal costs are ongoing. You should also account for First-tier Tribunal fees; for instance, many applications now incur a £114 application fee and a £227 hearing fee. Expert leasehold enfranchisement solicitors can provide a clearer estimate based on your property’s specific valuation.

Can I buy the freehold of my flat if some neighbours do not want to join?

Yes, you can proceed as long as at least 50% of the qualifying tenants in the building agree to participate. This “50% rule” is a statutory requirement for collective enfranchisement claims. If your block has only two flats, both owners must usually participate. For larger buildings, organising a committed group is essential. If you cannot reach the 50% threshold, an individual statutory lease extension remains a viable alternative to protect your investment and property value.

What is the difference between a statutory and an informal lease extension?

A statutory extension follows the formal legal process under the 1993 Act, granting you an additional 90 years and reducing ground rent to a peppercorn. This route offers legal protection against unreasonable terms. Conversely, an informal extension is a private agreement with the landlord. Whilst it might seem quicker, landlords often include clauses for escalating ground rents or shorter terms. Specialist leasehold enfranchisement solicitors generally recommend the statutory route to ensure long-term mortgageability and security.

Do the 2026 reforms make it cheaper to extend a lease under 80 years?

The Leasehold and Freehold Reform Act 2024 provides for the abolition of marriage value, which historically made extending leases under 80 years significantly more expensive. In 2026, this reform is a central focus of the transition toward a fairer valuation methodology. By removing the requirement to share the “uplift” in property value with the landlord, the premium for shorter leases should decrease. However, the exact impact depends on the final prescribed valuation rates currently being debated.

How long does the leasehold enfranchisement process typically take?

The process typically takes between eight and twelve months from the service of the Initial Notice to final completion. This timeline accounts for the two-month period the freeholder has to serve a Counter-Notice and the subsequent months required for premium negotiations. If the parties cannot agree and the matter moves to a Tribunal, the duration may extend further. Maintaining a methodical approach and adhering to statutory deadlines is vital to prevent the claim from being deemed withdrawn.

Can a freeholder refuse to sell the freehold or extend the lease?

A freeholder cannot refuse a valid statutory claim if you meet the qualifying criteria. As a qualifying tenant, you have a legal right to buy the freehold or extend your lease. The freeholder can only challenge the claim on technical grounds, such as if the building doesn’t qualify or if the notice is incorrectly served. This is why instructing expert leasehold enfranchisement solicitors is critical; they ensure your notice is robust and legally sound from the very beginning.

What happens to my ground rent after I extend my lease statutory?

Once a statutory lease extension is completed, your ground rent is legally reduced to a “peppercorn,” which effectively means it becomes zero for the remainder of the term. This applies to both the existing years and the new 90-year addition. This reduction is a major benefit of the formal route, providing immediate relief from rising costs. It also aligns with 2026 draft legislation aiming to cap existing ground rents at £250 per year for leaseholders.

Is an executor of an estate able to start a lease extension claim?

Yes, an executor can initiate a lease extension claim on behalf of a deceased person’s estate. This right is often exercised to increase the property’s marketability before a sale. The executor must usually start the process within two years of the grant of probate. Following the 2025 reforms that abolished the two-year ownership rule for individuals, the process has become more accessible. Our solicitors can guide executors through the specific documentation required to prove their standing.