Equity Release Legal Advice: How to Choose a Solicitor

Equity Release Legal Advice: How to Choose a Solicitor

What if the person checking your equity release paperwork isn’t the person advising whether the plan is financially right for you? If you’re comparing equity release legal advice solicitors, it’s understandable to want clear answers about long-term costs, your partner’s position and what may remain in your estate.

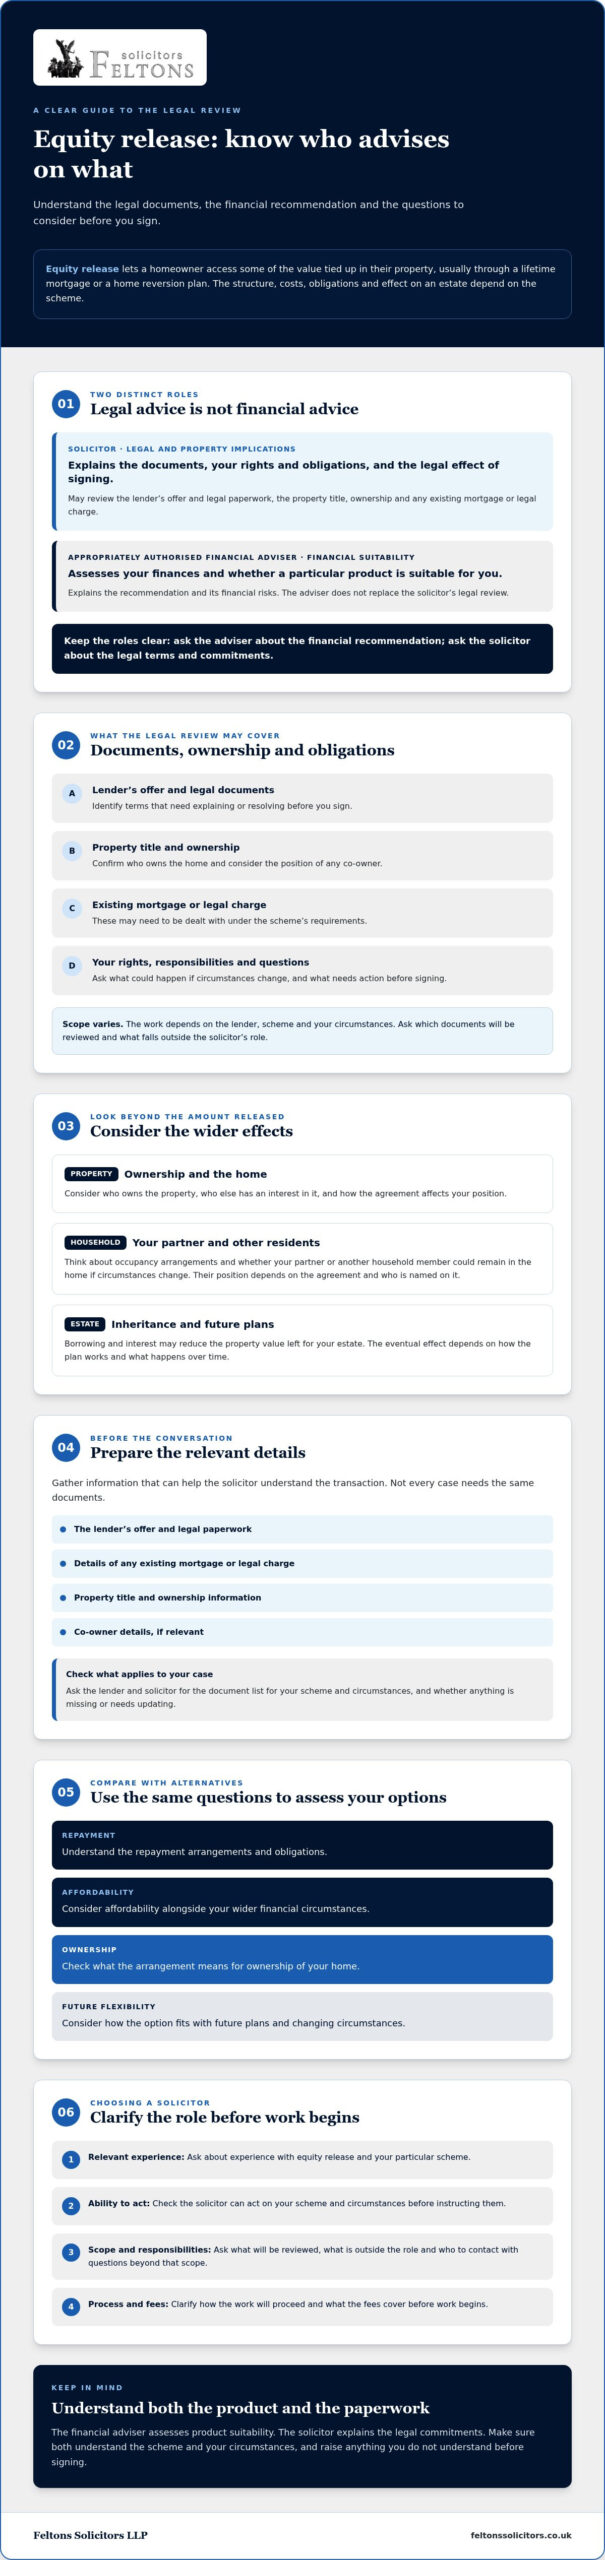
Legal advice and regulated financial advice have different purposes. A solicitor can explain the legal documents and property implications, while an appropriately authorised financial adviser assesses the financial product and its suitability for you. Understanding the distinction can help you make a considered decision and know who to ask when questions arise.

This guide explains what a solicitor may review, what to ask and which details to prepare before a conversation. It also considers how equity release could affect family members and estate plans. Feltons Solicitors LLP provides property and estate-planning legal services. An enquiry can help establish whether the firm is able to assist with your circumstances.

Key Takeaways

  • Equity release legal advice solicitors review a plan’s legal and property implications, but don’t recommend which financial product is right for you.
  • Ask how the agreement could affect ownership, your partner and your estate. The details depend on your circumstances and the scheme terms.
  • Compare equity release with alternatives by considering repayment, affordability, ownership and future flexibility.
  • Prepare information about your property and proposed scheme, then clarify the solicitor’s role, process, responsibilities and fees before work begins.
  • Check that the solicitor has relevant experience and can act on your particular scheme and circumstances before instructing them.

Equity release lets a homeowner access some of the value tied up in their property, usually through a product such as a lifetime mortgage or a home reversion plan. The structure, costs, obligations and effect on your estate depend on the scheme. The Equity release overview offers background on different forms and risks, but your own documents need to be considered in context.

In brief: a solicitor explains the legal effect of the documents and your obligations. A regulated financial adviser assesses and recommends a suitable financial product. Keeping these roles distinct helps you understand both what you’re agreeing to and why the proposed plan may or may not fit your financial circumstances.

What does an equity release solicitor check?

A solicitor’s review may cover the lender’s offer and legal documents, the property title and who owns the home. They can identify terms or details that need explaining or resolving before you sign. For example, an existing mortgage or legal charge may need to be dealt with under the scheme’s requirements. If someone else owns the property with you, their interest and position may also need consideration.

The work depends on the lender, the scheme and your circumstances. Ask which documents the solicitor will review, what is outside their scope and what happens if something needs clarification. Their role is to help you understand the legal commitments, not to tell you which product to choose.

How legal advice differs from financial advice

Legal advice and financial advice answer different questions. An appropriately authorised financial adviser considers your finances and whether a particular product is suitable, then explains the recommendation and its financial risks. The solicitor focuses on the legal documents, your rights and obligations, and whether you understand the legal effect of signing.

An independent legal review matters because lender documents may create binding commitments. Before signing, raise anything you don’t understand, including what could happen if your circumstances change, how the arrangement affects a co-owner and what it may mean for your estate. Don’t assume one professional’s advice covers the other’s role.

  • Ask the adviser to explain the financial recommendation and its risks.
  • Ask the solicitor to explain the legal terms, obligations and any points requiring action.
  • Check that both professionals understand the scheme and your circumstances. Ask who to contact with questions outside their remit.

Choosing between equity release legal advice solicitors is about more than finding someone to process paperwork. Look for a clear explanation of scope and responsibilities, and confirm the solicitor can act on your specific scheme before instructing them.

Financial advice doesn’t replace an independent legal review. The adviser considers the financial product and its suitability; the solicitor examines the legal documents and explains the obligations they create. The role of an equity release solicitor includes helping you understand the legal commitment before you sign. The work and possible consequences depend on the contract, scheme terms and your household circumstances.

Read the documents with your own plans in mind, not just the amount you could release. Borrowing and interest may reduce the property value left for your estate, but the eventual effect depends on how the plan works and what happens over time. If you share your home, consider whether your partner or another household member could remain there if circumstances change. Their position depends on the agreement and who is named on it, so ask the solicitor to explain the relevant terms.

Which documents and details may the solicitor need?

To help the solicitor understand the transaction, gather the lender’s offer and legal paperwork, details of any existing mortgage or legal charge, and information about property ownership. Title details and co-owner information may also be relevant. Not every case needs the same documents. Ask the lender and solicitor for the list that applies to your scheme and circumstances, and check whether anything is missing or needs updating.

Consider your partner, estate and future plans

Think through your occupancy arrangements, inheritance wishes and the needs of anyone who lives with you. Ask what the contract says if you move home or your living arrangements change, and whether your partner’s position is affected. Equity release legal advice solicitors can explain the legal effect of the documents, but they don’t determine whether the financial arrangement is suitable for you.

Before signing, understand exactly what events trigger repayment. The timing and consequences depend on the agreement. Ask the solicitor to explain relevant triggers in plain English, including what happens if the home is sold or the borrower’s circumstances change, where those situations are covered by the contract.

Tax, means-tested benefits and care-fee treatment depend on individual circumstances and current rules. Don’t rely on general information to predict the result; seek appropriate specialist advice before making a decision. If your decision raises wider property or estate-planning questions, you can enquire about property and estate-planning legal services and confirm whether the firm can assist with your circumstances.

Compare equity release with alternatives before choosing a solicitor

Equity release is one way to access money tied up in your home, but it isn’t the only option to explore. Downsizing, another type of loan, using savings or investments, or receiving family support may raise different questions about ownership, repayment, affordability and future plans. None is suitable for everyone. What’s available and appropriate depends on your circumstances and current product terms.

Discuss financial suitability and affordability with an appropriately authorised financial adviser. A solicitor can explain the legal implications of a proposed arrangement, including how it affects the property and the people connected to it. Comparing options first can help you identify the right questions for both professionals.

Compare the questions each option raises

Option Questions to consider
Equity release How does interest build, when is repayment due, and what do the terms say about moving home or changes in circumstances?
Downsizing Would selling and buying a different property suit your housing needs, and what would happen to ownership and the proceeds?
Other borrowing Can repayments remain affordable, what security is required, and how flexible are the repayment and early repayment terms?
Savings, investments or family support What assets could be used without undermining other plans? If a relative helps, is the arrangement a gift or a loan, and should it be recorded clearly?

This is a starting point, not a recommendation. Discuss family support openly with everyone involved and consider recording any agreed terms. The right approach depends on individual finances, property needs and family relationships.

Questions to resolve before deciding

Ask the adviser to explain how interest, repayments and any early repayment charges work under the specific offer. Ask the solicitor to clarify the legal terms and any obligations that could affect your plans. Check what the contract says if you move, your circumstances change or a borrower enters long-term care. Don’t assume the same outcome applies across all schemes.

Write down unanswered questions and take them to the relevant professional. Keep financial suitability questions for your adviser and legal-document questions for your solicitor. Ask each to clarify where their role ends. Comparing options before selecting equity release legal advice solicitors can help you focus on the expertise you need, rather than treating the choice of solicitor as a decision about which financial route to take.
Equity Release Legal Advice: How to Choose a Solicitor

How to prepare for an equity release solicitor consultation

A little preparation can make your first conversation more focused. You don’t need every document ready, but a clear picture of the proposed plan, your property and your priorities can help the solicitor identify what needs checking. Be open about relevant household and estate-planning circumstances, including details that may feel personal. They can affect which questions need to be considered.

Gather information and agree the next steps

  • 1. Collect the paperwork. Bring any proposed plan documents or lender correspondence, property ownership and title information, and details of an existing mortgage or other charge, if applicable. Ask the lender and solicitor which documents they need for your case.
  • 2. Note your circumstances and questions. Record who lives in the property, whether there are co-owners or dependants, and any concerns about a partner’s housing position or your inheritance intentions. Consider possible future changes, such as moving home.
  • 3. Bring relevant estate-planning papers. If you have a will or other documents that may relate to your plans, ask whether they would help the solicitor understand your concerns. Don’t assume they’ll all be required.
  • 4. Clarify the retainer before instructing. Ask what legal work is included, what falls outside the scope, who will handle the matter, how you’ll receive updates and what the next steps are.
  • 5. Confirm fees and process. Request clear information about fees and how any additional work would be discussed. Check your understanding before agreeing to proceed.

Questions to ask your solicitor

Use the conversation to establish practical expectations, not just whether the firm can review documents. Ask: “Which parts of the proposed arrangement will you examine?”, “What issues might require further information?” and “Who should I contact if I have a question about financial suitability?” A solicitor should explain the boundaries of their role, the process they propose and how they’ll raise matters that need your decision.

Timing and required steps vary according to the lender, transaction and your circumstances. Ask what sequence to expect and whether anything is needed from you before the review can progress. Don’t instruct a firm before you understand its scope and fees. If you’re considering equity release legal advice solicitors and have wider property or estate-planning questions, you can enquire with Feltons Solicitors LLP to establish whether the firm can assist with your circumstances.

A suitable solicitor should make the legal process clear, explain what they will review and give you space to raise concerns. Before instructing anyone, confirm they can act on the lender’s scheme and your particular circumstances. Experience with property and private client matters can be relevant, but ask specifically about the documents and requirements involved in your proposed transaction.

How to assess a solicitor’s suitability

Use your first conversation to check the fit rather than assuming a general property background covers every equity release arrangement. Ask whether the solicitor has experience with the relevant lender, scheme documents and transaction requirements, and what they would do if the paperwork raises an issue. Their role should be independent of the financial product recommendation. Ask how they’ll explain the legal obligations and check your understanding.

  • Relevant experience: Can they act on this scheme and explain the legal review it requires?
  • Clear scope: Which documents and issues are included, and what falls outside the work?
  • Communication: Who will handle your matter, how will updates be provided, and how can you raise questions?
  • Transparent fees: What will you be charged, and how will any additional work be discussed?
  • Your circumstances: Will the review take account of ownership, co-owners, household arrangements and your stated concerns?

Equity release legal advice solicitors should explain the legal position in language you understand, without presenting their review as a recommendation about financial suitability. If anything remains unclear, ask for an explanation before you sign or agree to proceed.

What to expect when you contact Feltons Solicitors LLP

Feltons Solicitors LLP provides private client and property legal services, including wills, probate, estate planning and residential conveyancing. The firm’s information does not confirm a specialist equity release service. An enquiry is a practical way to establish whether the firm currently accepts this type of matter, can act on your scheme and circumstances, and what the scope of any advice could be.

If your questions connect with wider inheritance planning, you may find the estate planning guide helpful. For questions about property ownership and transactions, see the residential property law guide. These resources provide background, but they don’t replace advice on your specific documents and circumstances.

To establish whether the firm can assist and discuss an appropriate next step, contact Feltons Solicitors LLP to discuss your circumstances. You can ask about availability, the applicable jurisdiction, the proposed scope of work and fees before deciding whether to instruct.

Take a considered next step

Choosing equity release legal advice solicitors means checking that the legal review is distinct from financial product advice, that the solicitor can act on your particular scheme, and that the documents and obligations are explained in language you understand. Weigh alternatives and consider how the decision may affect your household and estate plans before committing.

Feltons Solicitors LLP provides property law and conveyancing services alongside private client services, including wills and estate planning. The firm’s information doesn’t confirm whether it currently accepts equity release matters, so check availability, scope and whether it can assist with your circumstances before instructing.

Contact Feltons Solicitors to ask whether the firm can assist with your circumstances.

Frequently Asked Questions

What does an equity release solicitor do?

An equity release solicitor reviews the transaction’s legal paperwork and explains the obligations, risks and steps relevant to your case. They may check title ownership, co-owners, any existing mortgage and whether lender requirements appear to have been met. Their role isn’t to recommend a financial product. Ask which documents they’ll review, what falls outside their agreed scope and whether they can act on your particular scheme.

Do I need a solicitor for equity release?

Equity release transactions commonly involve legal work, but the process and requirements depend on the lender, product and your circumstances. A solicitor can explain the documents and commitments so you can understand them before signing. Ask the lender and solicitor to confirm the steps required for your case. Legal advice doesn’t replace regulated financial advice about whether a product is suitable for you.

Can an equity release solicitor give financial advice?

A solicitor’s legal advice is separate from a regulated recommendation about whether an equity release product suits you. Within the agreed scope, the solicitor can explain legal documents, obligations and relevant transaction steps. For product recommendations and financial suitability, speak to an appropriately authorised financial adviser. If you’re unsure who should answer a particular question, ask both professionals to explain their responsibilities before you proceed.

What should I ask an equity release solicitor before instructing them?

Ask whether they can act on your specific scheme, what the legal work includes and who will handle your matter. Clarify the expected steps, how updates will be given, the fees and how additional work would be discussed. You can also ask how the review will address property ownership, your partner’s position and estate-planning concerns. Request clear answers before deciding whether to instruct the firm.

Will equity release affect my inheritance or my family?

It may reduce the property value remaining for your estate after borrowing and interest are repaid, though the eventual effect depends on the agreement and future circumstances. Consider how the arrangement could relate to your partner’s housing position, other household members and inheritance wishes. Ask your financial adviser about the financial implications and your solicitor about the legal terms. You may also wish to review your will or wider estate plans.

Can I compare equity release with other options before signing?

Yes. You can discuss alternatives such as downsizing, other borrowing or using other assets with an appropriately authorised financial adviser. Compare each route by considering ownership, repayment, affordability and flexibility, rather than relying on one feature alone. Availability and suitability depend on your circumstances and current terms. If you’re considering equity release, a solicitor can explain the legal documents and identify points that need clarification before you sign.

What documents should I take to an equity release solicitor?

Useful starting points may include the proposed plan documents, property ownership or title information, and details of any existing mortgage. A will or other estate-planning papers may help if they relate to your concerns. Prepare questions about your household and future plans, too. Requirements vary, so ask the solicitor for their document list before your meeting. Only send sensitive paperwork through a channel you’ve verified with the firm.
Non-Resident Capital Gains Tax: Specialist UK Property Solicitors

Non-Resident Capital Gains Tax: Specialist UK Property Solicitors

For an international property owner, the most critical phase of a UK sale isn’t the exchange of contracts, but the sixty days that follow it. Missing this narrow window for reporting and payment can lead to immediate HMRC penalties, even if no tax is actually due. Engaging specialist non-resident capital gains tax uk property solicitors ensures that your disposal is handled with the precision required to meet these stringent deadlines. You’ve likely noticed that the UK tax landscape has become increasingly complex, moving from a relatively relaxed regime to one defined by real-time reporting and the rigorous transparency of the Register of Overseas Entities.

It’s understandable to feel a sense of trepidation when facing these evolving regulations, but with the right guidance, you can manage your obligations with confidence. This article provides a clear roadmap for navigating non-resident CGT, showing you how to minimise your liability through strategic rebasing and ensure your conveyancing process proceeds without delay. We’ll examine the current 2026-2027 tax rates, the nuances of the 60-day reporting window, and how to maintain full compliance whilst protecting your investment’s value.

Key Takeaways

  • Master the strict 60-day reporting and payment window to ensure full compliance and avoid costly HMRC penalties.
  • Explore how rebasing your property value to 2015 or 2019 levels can effectively minimise your overall tax liability.
  • Understand why registration with the Register of Overseas Entities is a mandatory prerequisite for any valid UK land transfer.
  • Discover how non-resident capital gains tax uk property solicitors provide an integrated approach to conveyancing and tax reporting.
  • Recognise the common pitfall of failing to report a disposal to HMRC, even in instances where no tax is actually payable.

Understanding Non-Resident Capital Gains Tax (NRCGT) in the UK

NRCGT is the tax due on profits made from disposing of UK land or property whilst living abroad. This specific branch of Capital Gains Tax in the United Kingdom has seen significant expansion over the last decade. In 2015, the UK government introduced these rules for residential assets, extending them in April 2019 to include all non-residential property and land. The logic behind this shift was to align the tax treatment of overseas owners with that of UK residents, ensuring a level playing field across the property market. Whether you’re selling a buy-to-let flat or a commercial warehouse, the profit is now firmly within the HMRC net. Engaging non-resident capital gains tax uk property solicitors early in the process is essential to understand which specific tax triggers apply to your disposal.

Who is Classified as a Non-Resident?

Determining your status isn’t always straightforward. HMRC uses the Statutory Residence Test (SRT) to assess how many days you’ve spent in the UK and the nature of your ties to the country. This classification extends beyond individuals to include trustees and personal representatives of deceased estates. A common complication arises with “temporary non-residence” rules. If you leave the UK and return within five years, assets sold during your absence might still be subject to UK tax upon your return. Because these rules are nuanced, consulting non-resident capital gains tax uk property solicitors before you list a property is the most secure way to clarify your liability and residency status.

The 60-Day Reporting and Payment Rule

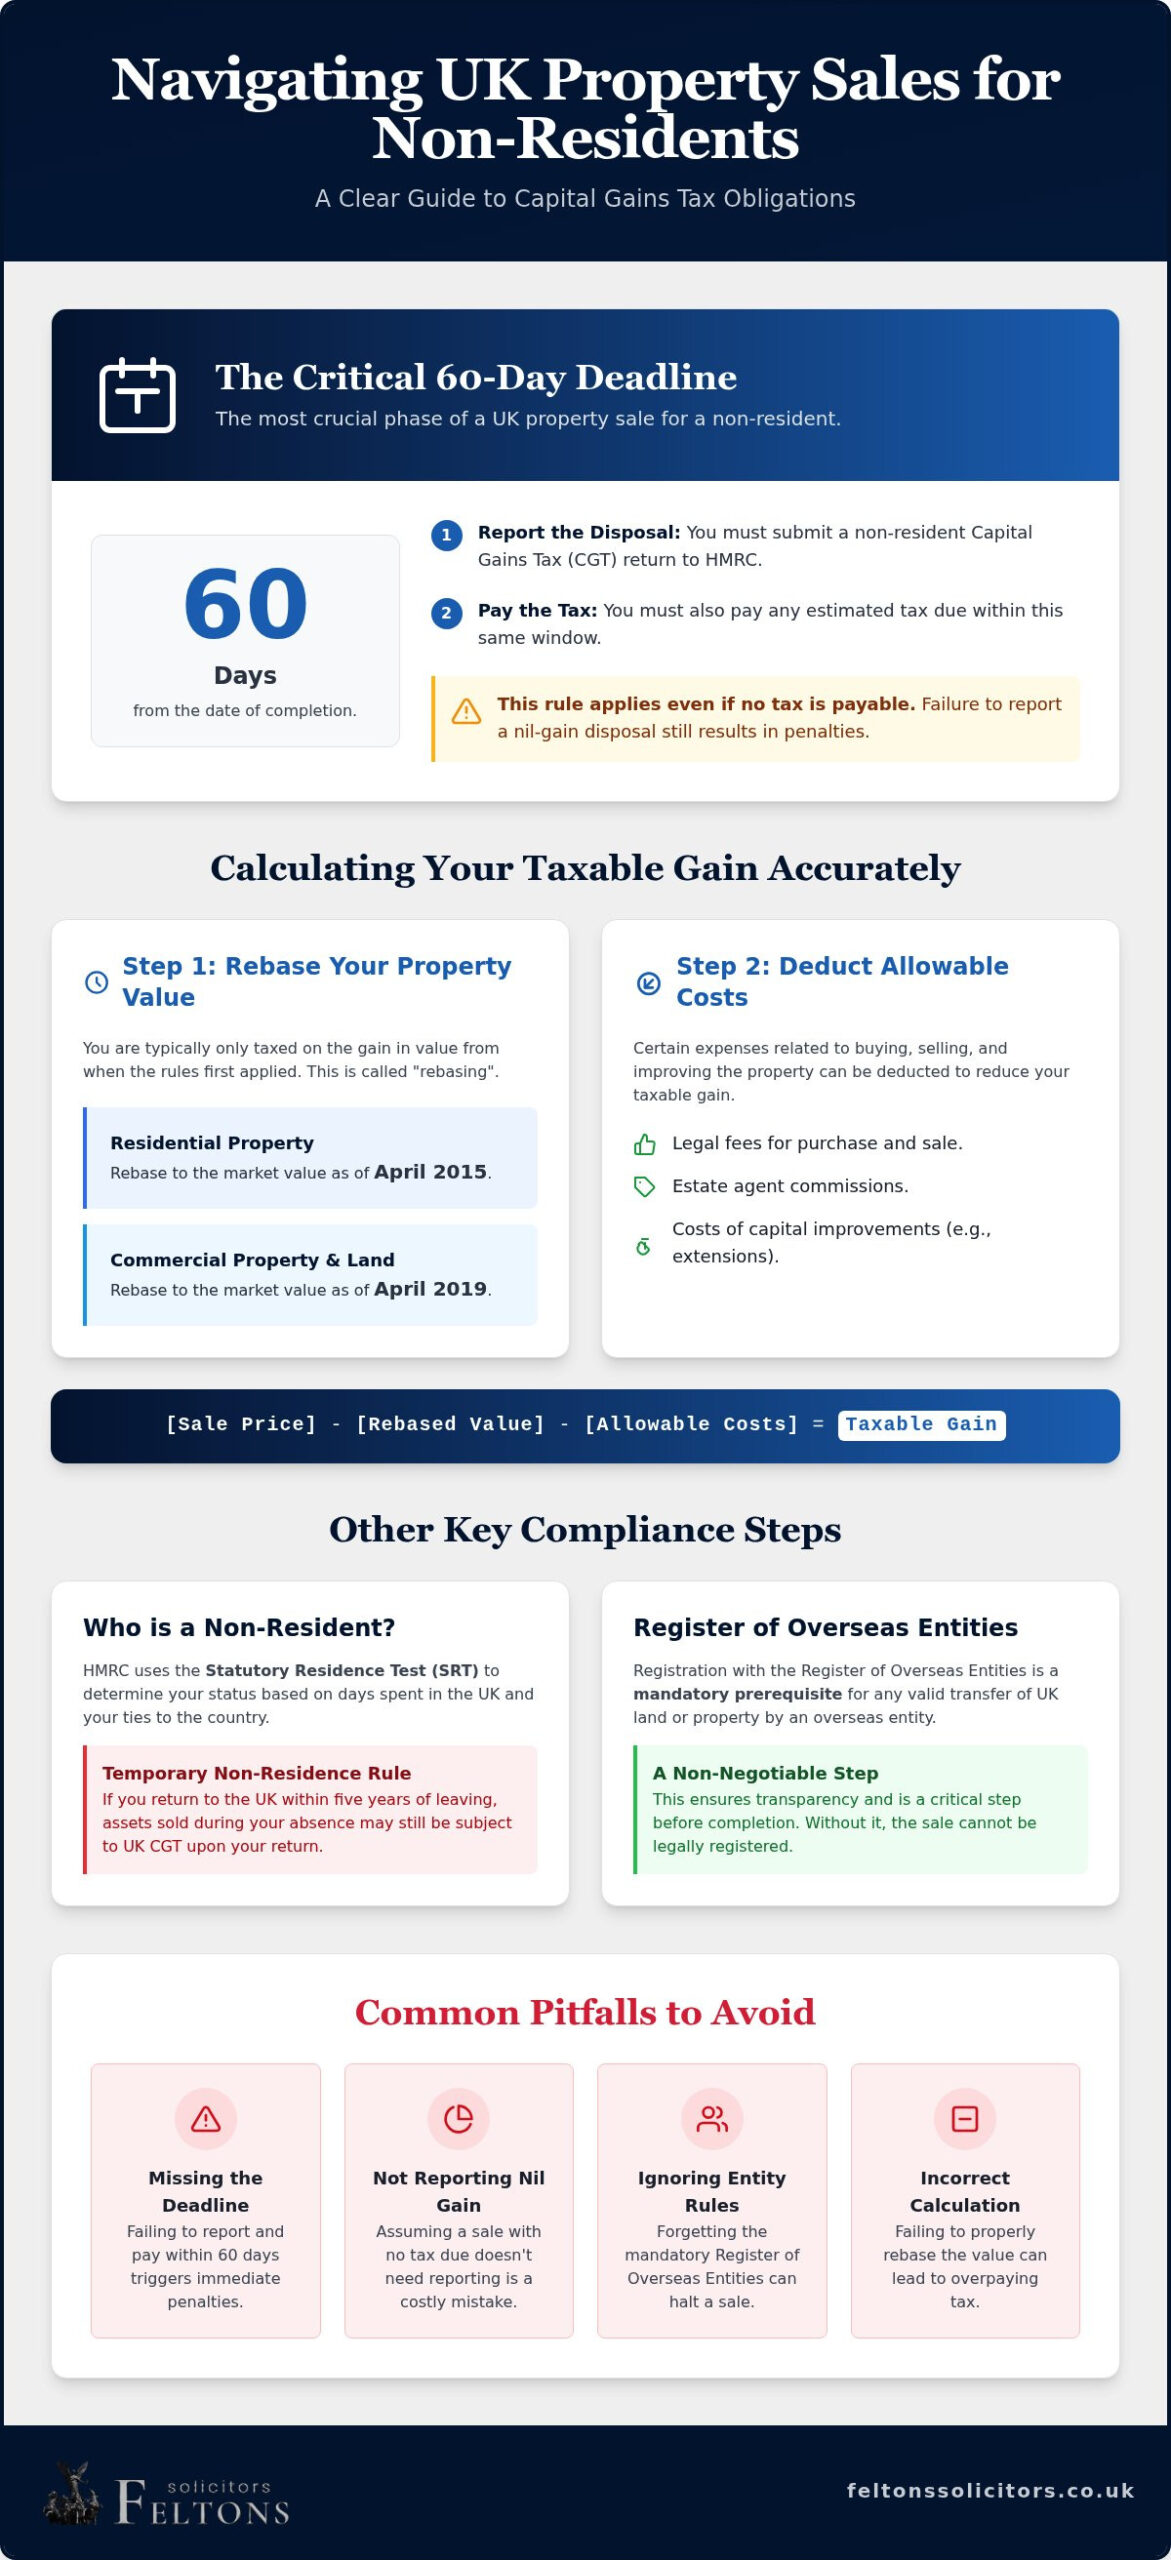
The timeline for compliance is exceptionally tight. You must report the disposal and pay any tax due within 60 days of the completion date. It’s a frequent misconception that you can simply wait until your annual self-assessment return to declare the sale. This mistake is costly. Failing to file within this window triggers immediate penalties and accruing interest, even if there’s no tax to pay. For many international clients, legal experts provide the necessary oversight to ensure these filings are accurate and timely. This proactive approach prevents the stress of HMRC investigations and avoids unnecessary financial loss at the end of a transaction.

Calculating Capital Gains for Overseas Sellers

Calculating the gain on a UK property disposal is rarely as simple as subtracting the purchase price from the sale price. For international owners, the UK tax system allows for “rebasing,” which means you only pay tax on the growth in value from specific dates. For residential property, this is generally April 2015, whilst for commercial property, the date is April 2019. This provision is designed to ensure that gains accrued before these rules applied to non-residents aren’t unfairly taxed. Expert non-resident capital gains tax uk property solicitors play a vital role here, ensuring that the completion statement and acquisition data are precisely aligned for HMRC.

To establish a robust tax position, professional valuations at these rebasing dates are highly recommended. HMRC may challenge self-estimated figures, so having a formal report provides a layer of security. Additionally, some expats may still benefit from Private Residence Relief (PRR) for the period they occupied the property as their main home. This can significantly reduce the taxable gain, provided the residency criteria are strictly met. For a deeper look at the technical framework used by legal professionals, the official guidance on Non-Resident Capital Gains Tax outlines the current statutory requirements.

Residential vs Commercial Property Calculations

The distinction between residential and commercial assets is fundamental. Residential dwellings have been subject to these rules since 2015, whereas commercial property and indirect disposals, such as selling shares in a property-rich company, only fell into the scope in April 2019. It’s important to focus on the “gain” rather than just the “proceeds” of the sale. The gain is the profit remaining after accounting for the rebased value and all eligible deductions. Non-resident capital gains tax uk property solicitors can help you identify which rebasing method is most advantageous for your specific circumstances.

Deducting Costs and Professional Fees

You can effectively reduce your tax liability by deducting specific costs associated with the sale and acquisition. These include:

  • Legal fees for both the purchase and the eventual sale
  • Estate agent commissions and professional marketing costs
  • Stamp Duty Land Tax (SDLT) paid upon the initial purchase
  • Capital expenditure, such as structural extensions or significant improvements

It’s crucial to distinguish between capital improvements, which are deductible, and general maintenance or repairs, which are not. When managing a high-value disposal, having specialist property solicitors handle your conveyancing ensures that all deductible legal costs are clearly documented and evidenced for your tax filing.

The Register of Overseas Entities: A Critical Compliance Step

For corporate owners and foreign trusts, the ability to sell UK land is now inextricably linked to transparency. The Register of Overseas Entities (ROE), managed by Companies House, requires any foreign legal entity owning UK property to identify and verify its beneficial owners. This isn’t merely a reporting exercise; it’s a fundamental gatekeeper in the conveyancing process. An overseas entity cannot sell UK property without a valid Overseas Entity ID. Without this unique identifier, the Land Registry will simply refuse to register the transfer of title to a buyer, effectively freezing your assets in place. Non-resident capital gains tax uk property solicitors ensure that this registration is not only active but fully compliant with the latest 2026 regulations before a sale is even negotiated.

Maintaining your standing on the register requires constant vigilance. An annual update statement must be filed within 14 days of the anniversary of your initial registration. HMRC and Companies House use this data to ensure that the individuals profiting from UK land are clearly identified. If your registration has lapsed or the annual update is overdue, your Overseas Entity ID becomes invalid. This can lead to catastrophic delays during the final stages of a transaction, often at the very moment you are preparing to settle your capital gains tax obligations.

ROE Verification and the Role of the Solicitor

The verification process is the most rigorous aspect of the ROE. A UK-regulated professional must independently verify the identity of all registrable beneficial owners before the information is submitted. This step is designed to prevent disputes and ensure that the “people with significant control” are accurately documented. It’s a complex task, particularly when dealing with multi-layered international corporate structures or discretionary trusts. For a detailed breakdown of this process, you may find our guide on Overseas Entity Beneficial Owner Registration helpful. Specialist non-resident capital gains tax uk property solicitors provide the pragmatic oversight needed to bridge the gap between international corporate law and UK property compliance.

Consequences of Non-Compliance for Sellers

The risks of ignoring ROE obligations are severe and go beyond simple administrative hurdles. If an entity fails to register or update its details, the Land Registry places a “restriction” on the property’s title. This restriction prevents the entity from selling, leasing, or charging the land. Beyond the commercial impact, non-compliance is a criminal offence. Directors or officers of a non-compliant entity can face significant daily fines or even imprisonment. Organising your documentation well in advance of your sale date is the only way to avoid these sanctions. By integrating ROE compliance with your wider tax strategy, you ensure a smooth exit from your UK investment without the threat of legal or financial paralysis.

Non-Resident Capital Gains Tax: Specialist UK Property Solicitors

Common Pitfalls for Non-Resident Property Owners

HMRC compliance is rarely intuitive, and for international owners, the margin for error is non-existent. One of the most frequent errors involves the disposal date. Whilst the tax year of the sale is determined by the date of exchange, the 60-day reporting window begins strictly on the date of completion. Miscalculating this distinction can result in automatic penalties before you’ve even realised the deadline has passed. Additionally, properties held within corporate structures may have existing obligations under the Annual Tax on Enveloped Dwellings (ATED). The interaction between ATED-related gains and standard NRCGT is complex, often requiring non-resident capital gains tax uk property solicitors to untangle the overlapping liabilities and ensure you aren’t overpaying.

Logistical hurdles also pose a significant threat to a smooth exit. Anti-money laundering (AML) checks for international clients are now more rigorous than ever. Underestimating the time required for these checks, or for international currency transfers, can delay the entire conveyancing process. If these delays push your reporting past the sixty-day mark, HMRC will not accept bank delays or administrative friction as a valid excuse for late filing. It’s a high-stakes environment where timing is as important as the financial calculation itself.

Reporting a Sale with No Tax Due

A common HMRC trap is the belief that a loss-making sale or a break-even disposal requires no action. This is incorrect. Non-residents must file a “nil return” to declare the disposal, even if no tax is payable. Failing to submit this return within the 60-day window triggers the same penalty regime as a high-profit sale. Establishing this paper trail is not just about avoiding fines; it’s also essential for your own international tax reporting, providing clear evidence to your local tax authorities that the disposal has been handled according to UK law. For those with broader European interests, such as in Italy, professional Italian fiscal representation services can assist in ensuring that all cross-border reporting is accurately synchronised.

The UK maintains an extensive network of double taxation treaties amongst different nations to ensure that you aren’t taxed twice on the same gain. In most instances, you can claim credit for the UK CGT paid against your local tax liability in your country of residence. However, the mechanics of claiming this credit vary significantly between jurisdictions. Coordinated advice between your UK legal team and local tax advisors is the only way to ensure you aren’t left out of pocket. If you are concerned about how these pitfalls might affect your sale, you should contact our property law specialists for a comprehensive compliance review.

How Feltons Solicitors Manage Your Non-Resident Disposal

Most firms treat property law and tax compliance as separate silos, often leaving the client to coordinate between a conveyancer and an accountant. At Feltons Solicitors LLP, we provide a sophisticated, integrated service that bridges this gap. Our role as non-resident capital gains tax uk property solicitors is to manage the entire lifecycle of your disposal, from the initial legal due diligence to the final HMRC submission. We provide discreet and professional representation for high-net-worth individuals and international corporate investors, ensuring that every transaction is handled with the quiet confidence and precision it deserves. Our people-first philosophy means we prioritise your peace of mind, acting as a steady guide through the often stressful landscape of UK tax regulations.

We understand that international property owners face unique pressures, particularly when dealing with high-value estates and multi-layered corporate structures. Our team is equipped to handle the most complex matters with a boutique level of care, ensuring that your personal rapport with your solicitor remains at the heart of our service. By combining modern efficiency with traditional professional integrity, we protect your interests whilst maintaining the highest standards of HMRC compliance.

Our Proactive Approach to the 60-Day Window

The sixty-day reporting window is unforgiving, and we don’t believe in leaving compliance to the final hour. We begin preparing your NRCGT return alongside the conveyancing process, often starting the work as soon as contracts are exchanged. This proactive stance allows us to accurately capture all deductible costs, including acquisition legal fees and capital expenditure, to minimise your eventual tax liability. For those managing a broader portfolio, our guide on Navigating Residential Property Law provides essential context for maintaining residential assets in the UK. By the time completion occurs, the majority of the tax work is already finalised, allowing for a seamless transition to the reporting phase.

Specialist Support for Overseas Entities

For clients holding property through foreign companies or trusts, we manage the Register of Overseas Entities (ROE) registration and verification process entirely in-house. This ensures that your Overseas Entity ID is valid and your annual update statements are current long before they are required for a Land Registry transfer. We act as a trusted advisor for long-term UK property portfolios, providing the worldly experience necessary to handle international-scale matters with ease. If you are planning a disposal or require expert guidance on your current tax position, we invite you to contact our property team for a professional consultation.

Securing Your UK Property Exit

Successfully managing a UK property disposal as a non-resident requires a meticulous approach to timing and transparency. We have explored how the strict 60-day reporting window and the Register of Overseas Entities have transformed the compliance landscape for international owners. By leveraging rebasing rules and identifying all allowable deductions, you can significantly reduce your tax burden whilst maintaining a clear standing with HMRC.

Navigating these complexities is far simpler with the support of non-resident capital gains tax uk property solicitors who understand the intersection of conveyancing and tax law. Feltons Solicitors provides a comprehensive service. We offer pragmatic legal advice for international clients and specialist expertise in Overseas Entity Registration. You can instruct Feltons Solicitors for your UK property disposal to ensure your transaction is handled with the highest level of professional integrity and care. With the right legal partner, your exit from the UK market can be both fully compliant and commercially rewarding.

Frequently Asked Questions

Do I have to pay Capital Gains Tax if I am not a UK resident?

Yes, non-residents are liable for CGT on the disposal of all UK land and property. This includes residential dwellings, commercial buildings, and land without structures. The tax is calculated on the profit made during the period of ownership, subject to specific rebasing rules. Expert guidance from non-resident capital gains tax uk property solicitors is recommended to ensure you apply the correct rates for the 2026-2027 tax year.

What is the 60-day rule for non-resident CGT?

The 60-day rule requires non-residents to report the disposal of UK property and pay any tax due within sixty days of completion. It is a common error to assume the clock starts at the exchange of contracts. Missing this window triggers automatic penalties. Because this timeline is exceptionally tight, we prepare the necessary documentation alongside the conveyancing process to ensure you remain fully compliant with HMRC’s real-time reporting requirements.

How is CGT calculated for a non-resident selling UK property?

Calculations for non-residents typically focus on the gain accrued since April 2015 for residential property or April 2019 for commercial assets. This rebasing ensures you aren’t taxed on growth that occurred before the current rules applied to overseas owners. You subtract the rebased value and allowable expenses from the final sale price. For the 2026-2027 tax year, residential rates are 18% or 24% depending on your total UK income and gains.

Can I deduct my solicitor fees from my Capital Gains Tax bill?

Yes, you can deduct professional fees from the gain to reduce your overall tax liability. This includes the legal costs incurred during both the acquisition and the disposal of the property. Other deductible expenses include estate agent commissions, Stamp Duty Land Tax paid at purchase, and capital expenditure for structural improvements. Keeping precise records of these costs is essential for non-resident capital gains tax uk property solicitors to maximise your available tax relief.

What happens if I miss the HMRC reporting deadline?

Missing the 60-day deadline results in immediate financial penalties and accruing interest on any unpaid tax. Initial late filing penalties are usually £100, but these increase significantly if the return is more than three or six months overdue. HMRC rarely accepts administrative delays or international bank friction as a valid excuse. Proactive legal management ensures that your reporting is submitted accurately and on time, avoiding these unnecessary costs and potential investigations.

Do I need to report the sale if I made a loss on the property?

You must report the disposal to HMRC even if the sale resulted in a loss or no tax is due. This is a mandatory requirement for all non-residents disposing of UK land. Failing to submit a nil return within the 60-day window triggers the same penalty regime as a profitable sale. Reporting a loss is also beneficial, as it can often be offset against future UK capital gains to reduce your future tax liabilities.

Is commercial property treated differently for non-resident CGT?

Commercial property disposals follow the same 60-day reporting window but use a different rebasing date of April 2019. Unlike residential property, which was brought into the non-resident CGT net in 2015, commercial assets and indirect disposals only became taxable for non-residents in 2019. The calculation methods and tax rates can also differ, particularly if the property is held within a corporate structure rather than being owned by an individual.

How does the Register of Overseas Entities affect my property sale?

The Register of Overseas Entities is a mandatory compliance step for any foreign company or trust owning UK land. You cannot legally transfer the title to a buyer without a valid Overseas Entity ID from Companies House. If your registration isn’t current or your annual update is overdue, the Land Registry will block the sale. We handle the verification and registration process in-house to ensure your transaction proceeds without any regulatory delays.

Transfer of Equity Solicitors: A Strategic Guide to Reorganising Property Ownership

Transfer of Equity Solicitors: A Strategic Guide to Reorganising Property Ownership

What if the simple act of adding a partner to your property title inadvertently triggered a tax bill worth thousands of pounds? It is a common anxiety for homeowners who wish to reorganise their assets but feel overwhelmed by Stamp Duty liabilities or the technicalities of mortgage lender consent. When the stakes are this high, the guidance of experienced transfer of equity solicitors is more than a formality; it is a vital safeguard for your wealth. Whether you are managing a matrimonial breakdown or gifting a share of your home, the emotional weight is often as significant as the legal complexities.

You deserve a transition handled with both technical precision and empathy. This guide is designed to help you manage these changes, ensuring your equity remains protected and your future is secure. We understand that your property is more than just an asset; it is the foundation of your personal life. We will provide a clear roadmap through the nuances of UK property law and tax obligations. We preview the essential steps to achieve a legally robust transfer of title whilst maintaining the privacy and dignity your family dynamics require.

Key Takeaways

  • Identify the common scenarios for reorganising property interests, ranging from matrimonial settlements and new marriages to family gifting and tax planning.
  • Understand the pivotal role of mortgage lender consent and why it represents the most significant legal hurdle in the transfer process.
  • Follow a clear, step-by-step roadmap that covers everything from initial identity verification to the final registration of Title Deeds.
  • Discover how to navigate complex tax obligations, including the calculation of Stamp Duty Land Tax (SDLT) on the consideration provided.
  • Learn why engaging expert transfer of equity solicitors is vital for protecting your financial security whilst managing the sensitive human impact of property transitions.

Understanding Transfer of Equity: Why Reorganise Your Property Interests?

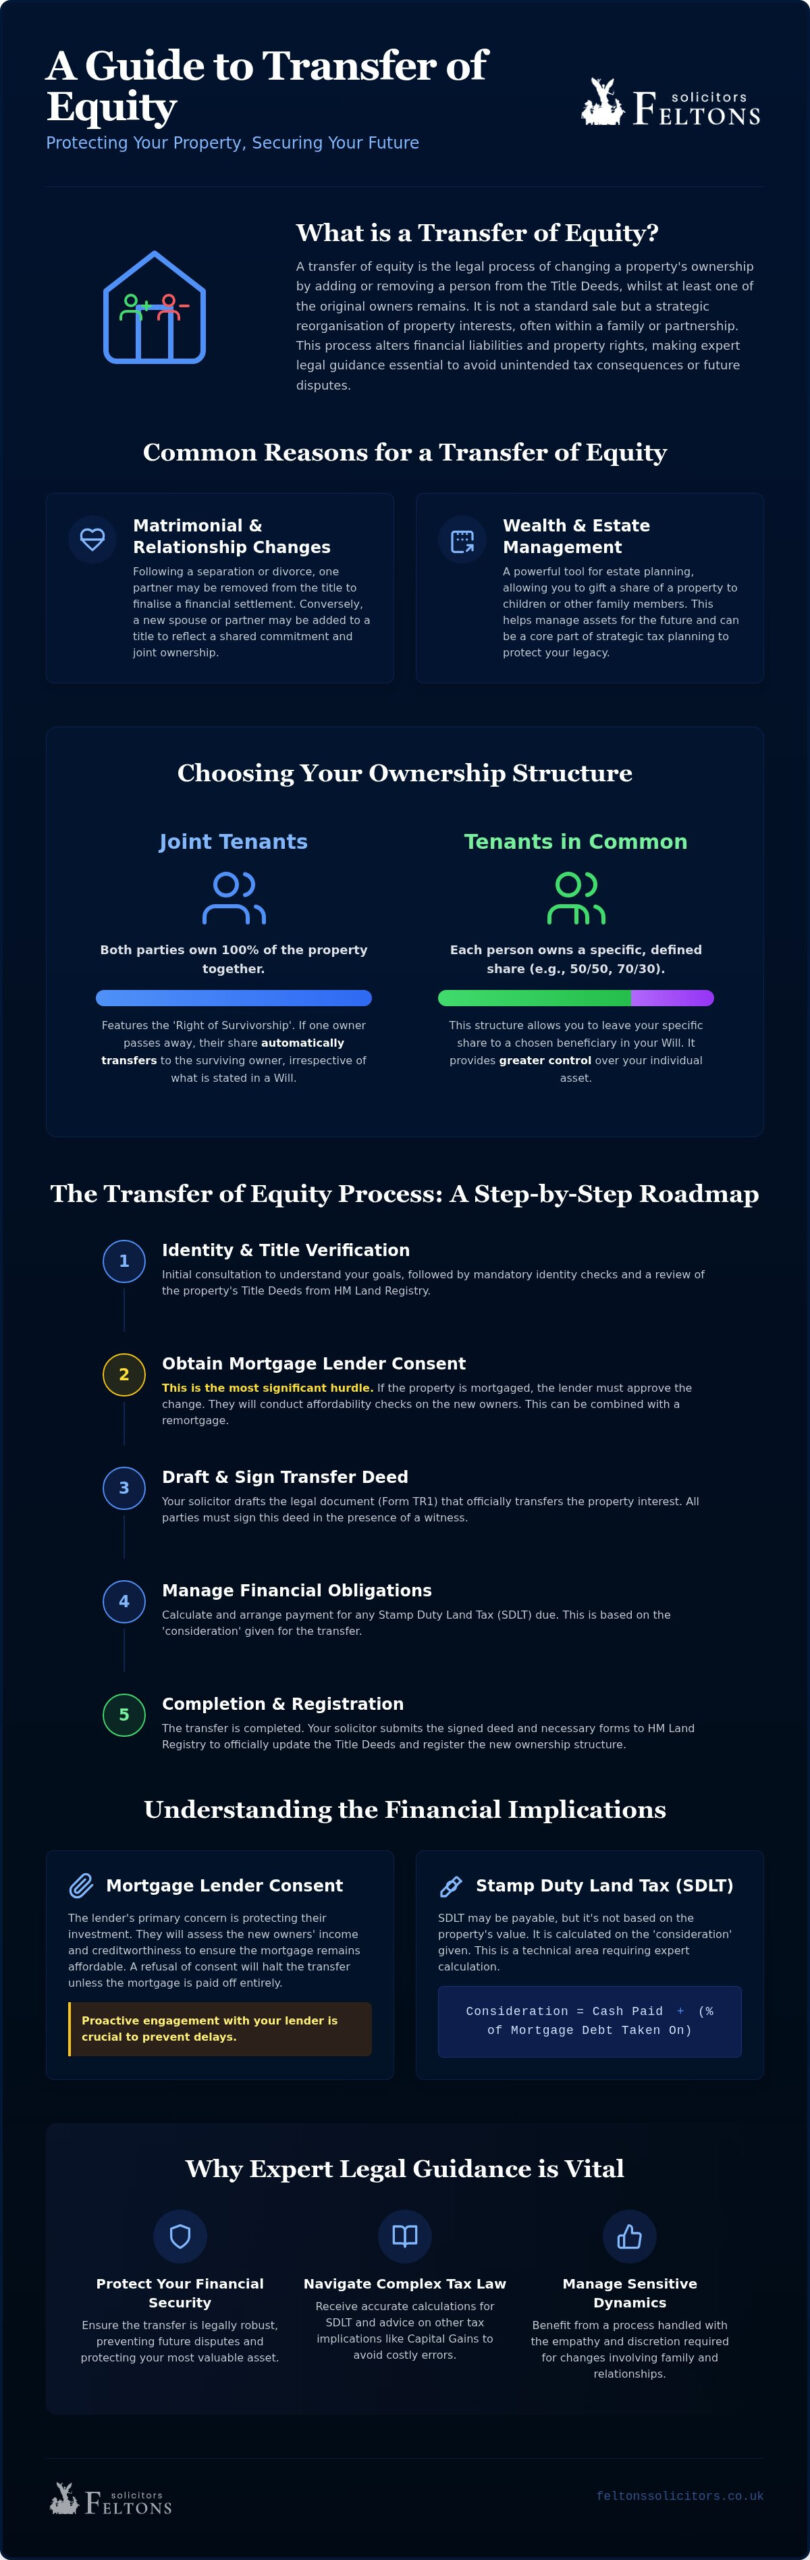
A transfer of equity occurs when the legal ownership of a property changes hands, but at least one of the original owners remains on the Title Deeds. This process differs significantly from a standard sale or purchase. In a typical market transaction, a property is sold, the mortgage is cleared, and the owners move on. A transfer of equity is instead a strategic reorganisation of existing interests. To gain a foundational perspective, one might ask, What is a transfer of equity? Simply put, it’s the legal mechanism used to add or remove individuals from a property’s title whilst keeping the property within a specific group or family unit.

Because these transitions often involve existing mortgages and significant tax implications, the expertise of a professional residential property law firm is essential. This isn’t merely an administrative update; it’s a formal legal shift that alters your financial liabilities and rights. Without precise guidance, homeowners risk future disputes or unintended tax consequences that can take years to resolve. Expert transfer of equity solicitors provide the technical accuracy needed to ensure the new ownership structure is legally robust and reflects your true intentions.

Matrimonial and Relationship Changes

Significant life transitions often necessitate a change in property holdings. Following a separation, a divorce and financial arrangements lawyer may advise removing a former partner from the title to finalise a financial settlement. Conversely, you might wish to add a new spouse or partner to the title of a home you already own to reflect a shared commitment. These moments require a delicate touch. We act as a calm, steady presence, balancing technical legal precision with the emotional sensitivity these personal changes demand.

Strategic Wealth and Estate Management

Beyond personal relationships, equity transfers are powerful tools for protecting your financial future. Gifting a share of a property to children or other family members can be a cornerstone of effective estate planning. However, the way you hold that equity is critical. You must decide between two primary structures:

  • Joint Tenants: Both parties own the whole property together. If one person passes away, their share automatically transfers to the survivor, regardless of what is written in a Will.
  • Tenants in Common: Each person owns a specific, defined percentage of the property. This allows you to leave your specific share to a chosen beneficiary in your Will.

Choosing between these options depends on your long-term goals and family dynamics. Transfer of equity solicitors help you navigate these choices, ensuring your property interests are organised in a way that respects your privacy and secures your legacy for the next generation.

If your property is subject to a mortgage, your lender is effectively a silent partner in any ownership change. Their consent is the primary hurdle in the process; without it, the transfer cannot legally proceed. Lenders view a change in ownership as a shift in their security. Whether you are removing a former partner or adding a new spouse, the bank must ensure their investment remains protected. Experienced transfer of equity solicitors act as the bridge between you and the financial institution, ensuring all criteria are met before any documents are signed.

Many homeowners choose to combine this transition with a remortgage. This synergy often makes financial sense, as it allows you to secure a better rate whilst simultaneously reorganising the title. If you stay with your current lender, they’ll conduct a full affordability assessment to ensure the remaining or new owners can comfortably meet the monthly repayments. If the bank refuses consent, usually due to a low credit score or insufficient income, the transfer will stall unless the mortgage is cleared in full. For those needing to explore alternative financing to bridge this gap, I Need Cash offers a way to compare various homeowner and personal loan products. Identifying these roadblocks early is a core part of our proactive approach.

Lenders prioritize risk management above all else. When a party is removed from a title, the bank must formally release them from their personal covenant to repay the debt. This “clean break” is vital for the outgoing individual, as it prevents them from being held liable for future arrears. For the remaining owner, the bank may require a ‘Deed of Covenant’ or a entirely new mortgage offer. They’ll scrutinise your income and outgoings with the same rigour as a fresh purchase; in such cases, Lee Tonks: Mortgage Guru can provide the independent advice needed to ensure the debt is sustainable on a single or revised set of earnings.

Coordinating with Financial Institutions

The timeline for a transfer is often dictated by the lender’s internal processing speeds. Your solicitor manages this coordination, ensuring that the mortgage offer aligns with the wider conveyancing process and Land Registry requirements. This involves significant back-and-forth communication to verify identity, confirm equity shares, and secure the final ‘letter of consent’.

Managing these moving parts requires a methodical mindset and a deep understanding of banking protocols. If you’re feeling uncertain about how your lender might react to a change in your circumstances, seeking advice from a specialist property solicitor can provide the clarity you need to move forward with confidence. We handle the technical liaisons, allowing you to focus on the personal transition at hand.

Your journey begins with a formal instruction. This stage involves rigorous Anti-Money Laundering (AML) checks, a mandatory requirement that ensures the integrity of the transaction and protects all parties from financial impropriety. Once identity is verified, we obtain the official copies of the title from the Land Registry. This review allows us to identify any existing charges, restrictions, or notices that might complicate the transition. It’s a methodical start that builds a secure foundation for the work ahead.

After reviewing the deeds, we move to the pivotal stage of securing lender consent, as discussed in our previous section. This involves a steady exchange of information with your bank to ensure the new ownership structure aligns with their lending criteria. Only when consent is in place can the formal transfer documents be prepared. Expert transfer of equity solicitors act as the primary coordinator here, ensuring that every piece of the puzzle fits perfectly before moving to execution.

Drafting the Transfer Deed (TR1)

The TR1 form is the legal instrument that effects the change in ownership. Within this document, we must clearly specify the ‘consideration’. This is the value being exchanged for the share of the property. It’s a common misconception that consideration only refers to cash; in a transfer of equity, the assumption of mortgage debt is also viewed as consideration by HMRC. We also confirm the ownership structure, whether you’ll hold the property as Joint Tenants or Tenants in Common. To prevent future ‘undue influence’ claims, transfer of equity solicitors often require the outgoing party to seek independent legal advice. This ensures they fully understand the rights they’re relinquishing, protecting the validity of the entire transaction.

Post-Completion Formalities

Once the TR1 is signed and witnessed, completion occurs. However, the legal work doesn’t end there. We must submit a Stamp Duty Land Tax (SDLT) return to HMRC, even if the transaction falls below the tax threshold and no payment is due. Following this, an application is made to the Land Registry to update the official record. Fees for this are typically submitted electronically, following the established HM Land Registry fee scales for transfers. This registration can take several weeks to process. Once finished, we provide you with the updated Title Register. This document serves as your final, definitive record of ownership, offering you the peace of mind that your property interests are correctly and securely organised.

Transfer of Equity Solicitors: A Strategic Guide to Reorganising Property Ownership

Financial Implications: SDLT, Capital Gains, and Valuation

While the legal mechanics of a transfer are vital, the financial consequences often present the most significant challenges. Many homeowners assume that if no money changes hands, no tax is due. This is a potentially costly misconception. In the UK, HM Revenue and Customs (HMRC) views the transfer of equity as a transaction with a specific value, known as ‘consideration’. Understanding how this value is calculated is where the guidance of transfer of equity solicitors becomes indispensable for protecting your long-term financial security.

An accurate property valuation is the cornerstone of this process. Whether you’re reorganising interests for tax planning or a family settlement, you must establish a fair market value. HMRC scrutinises transfers between ‘connected persons’, such as family members, and using an incorrect valuation can lead to penalties or prolonged investigations. We ensure your financial disclosures are pragmatic and robust, reflecting current market conditions whilst respecting your personal privacy.

The SDLT ‘Consideration’ Trap

Stamp Duty Land Tax (SDLT) is often triggered during a transfer because ‘consideration’ includes the value of any mortgage debt the new owner takes on. For example, if you’re added to a title for a property with a £300,000 mortgage, you’re effectively taking on responsibility for £150,000 of that debt. This £150,000 counts as consideration. Under 2026 rates, the standard SDLT threshold starts at £125,000. In this scenario, tax would be payable on the £25,000 that exceeds the 0% band. However, transfers resulting from a matrimonial breakdown or a court order are typically exempt from SDLT. We help you identify these exemptions early to avoid unnecessary payments.

Capital Gains Tax and Gifting

If the property is not your primary residence, such as a buy-to-let investment or a second home, Capital Gains Tax (CGT) may apply. For the 2026/2027 tax year, CGT rates for residential property stand at 18% for basic rate taxpayers and 24% for higher rate individuals. When gifting a share of a property to a child or family member, the ‘Market Value’ rule applies. HMRC calculates the gain based on the current value of the share being gifted, regardless of whether any money was paid. With an Annual Exempt Amount of just £3,000, these liabilities can accumulate quickly. Seeking early tax advice ensures you aren’t blindsided by a large bill months after the legal work is complete.

Managing the intersection of property law and tax obligations requires a steady, expert hand. If you’re planning to reorganise your property interests, consult our specialist property team to ensure your equity is protected and your tax liabilities are clearly understood before you proceed.

Reorganising property ownership is rarely a standalone task. It sits at the complex intersection of property law, family arrangements, and long-term tax planning. Each of these areas carries its own risks and requirements. A mistake in one can derail the others, leading to financial loss or personal friction. This is why the involvement of expert transfer of equity solicitors is vital. We don’t just process forms; we provide a strategic overview that ensures your transition is seamless and your interests remain protected.

In matrimonial transfers, the process is often emotionally charged. We act as a calm, steady presence, providing the technical precision needed whilst respecting the sensitivities of your situation. Our goal is to future-proof your property title. We ensure that every detail, from the specific wording of the Transfer Deed to the final Land Registry entry, is robust enough to withstand future scrutiny or potential disputes. By choosing a partner who understands the human impact of legal work, you ensure a transition that is as smooth as it is secure.

A Sophisticated Boutique Service

We pride ourselves on a “people-first” philosophy. Unlike high-volume firms that prioritise speed over substance, our boutique approach focuses on personal connection. We offer discreet, high-standard care that is particularly valued by high-net-worth clients who require a tailored experience. This bridges the gap between traditional professional integrity and the efficiency of modern legal delivery. You aren’t just a file number; you’re a partner in a process that values your privacy and unique circumstances. This level of individualized attention ensures that no detail is overlooked and every concern is addressed with poise and dependability.

Securing Your Property’s Future

Our expertise extends beyond simple title changes. As leasehold enfranchisement experts, we understand the nuances of complex title issues that often surface during an equity transfer. We coordinate holistically with your other professional advisors, such as accountants or surveyors, to ensure every financial and legal angle is covered. This collaborative approach provides a comprehensive service that secures the foundation of your property rights for years to come. It’s about more than the immediate change; it’s about building a legally robust future for your most valuable assets. To discuss your property ownership goals, contact our transfer of equity specialists today.

Securing Your Property Interests for the Long Term

Reorganising your property ownership is a significant legal transition that requires more than just administrative filing. It demands a strategic understanding of how mortgage lender consent, tax liabilities, and family dynamics intersect. By addressing these complexities with foresight, you ensure your equity is protected and your title remains legally robust against future challenges. Navigating the nuances of Stamp Duty and Capital Gains Tax is essential for maintaining your financial security whilst achieving your personal objectives.

At Feltons Solicitors LLP, we specialise in complex property and matrimonial transitions, providing pragmatic, professional advice tailored to your specific goals. Our discreet, boutique service ensures a human touch whilst maintaining the high-standard reliability you expect from a trusted advisor. When you engage transfer of equity solicitors who prioritise personal connection over high-volume processing, you gain a steady partner for your most valuable assets. We’re here to provide the calm, expert guidance needed to make your property reorganisation a success.

Secure your property’s future with Feltons Solicitors LLP. We look forward to guiding you through this transition with the poise and expertise your property deserves.

Frequently Asked Questions

Do I have to pay Stamp Duty when transferring equity in my home?

You may need to pay Stamp Duty Land Tax (SDLT) if the ‘consideration’ exceeds the current threshold. Consideration includes cash payments and the value of any mortgage debt the new owner takes on. For the 2026/2027 tax year, the standard threshold begins at £125,000. However, transfers resulting from a divorce or matrimonial breakdown are usually exempt. Consulting transfer of equity solicitors early ensures you don’t overlook potential exemptions or trigger unnecessary tax bills.

Can I transfer equity without my mortgage lender’s consent?

No, you cannot proceed without your mortgage lender’s formal consent. Because the lender has a legal charge over the property, they must approve any change to the ownership structure. They’ll conduct a full affordability assessment to ensure the remaining or new owners can meet the debt obligations. If consent is refused, the mortgage must be cleared in full before the transfer can occur. This is a critical hurdle that requires careful coordination.

How long does a typical transfer of equity take to complete?

A typical transfer of equity usually takes between four and eight weeks to complete. This timeline is heavily influenced by how quickly your mortgage lender provides consent and the complexity of your specific title. Whilst the legal drafting is relatively swift, external factors like HMRC filings and Land Registry registration can extend the process. We work methodically to ensure each stage is handled promptly to avoid any unnecessary delays for our clients.

Is a transfer of equity different if the property is a leasehold?

Yes, leasehold transfers involve additional administrative steps. You’ll likely need to notify the freeholder or management company of the change in ownership. There are often administrative fees for a ‘Notice of Transfer’ or ‘Notice of Charge’ as stipulated in your lease. As transfer of equity solicitors with expertise in leasehold matters, we manage these communications to ensure your lease remains compliant and your property rights are fully protected throughout the transition.

Do I need a new valuation of the property for a transfer of equity?

Yes, a formal valuation is often essential for both lender approval and tax compliance. HMRC requires the transfer to be based on a ‘fair market value’ to calculate potential Stamp Duty or Capital Gains Tax liabilities accurately. If you’re remortgaging as part of the process, your lender will also insist on an independent valuation to confirm their security. Establishing an accurate figure at the outset prevents future disputes with authorities or other parties.

What is the difference between a transfer of equity and a gift of property?

A transfer of equity involves at least one original owner remaining on the title, whilst a gift of property usually sees the entire interest transferred to someone else. Both scenarios are treated as disposals for tax purposes. If you’re gifting a share of a property that isn’t your main home, Capital Gains Tax may apply based on the market value. We provide the pragmatic advice needed to navigate these distinctions safely and securely.

Can a transfer of equity be challenged in the future by a former partner?

A transfer can be challenged if there’s evidence of ‘undue influence’ or if a party didn’t receive independent legal advice. To mitigate this risk, we ensure the process is transparent and that all parties understand the rights they’re relinquishing. A legally robust transfer, registered correctly at the Land Registry, provides the definitive record needed to protect your future interests. Our boutique approach prioritises these safeguards to ensure your property’s long-term security.

Does the outgoing person need their own solicitor for the transfer?

Yes, the outgoing person should always seek independent legal advice. Most transfer of equity solicitors and mortgage lenders require this to prevent a conflict of interest. It ensures that the individual leaving the title fully understands the financial and legal implications of their decision. This step is vital for the validity of the transfer, as it protects the transaction from future claims that the person was pressured or misinformed during the process.