Non-Resident Capital Gains Tax: Specialist UK Property Solicitors

Non-Resident Capital Gains Tax: Specialist UK Property Solicitors

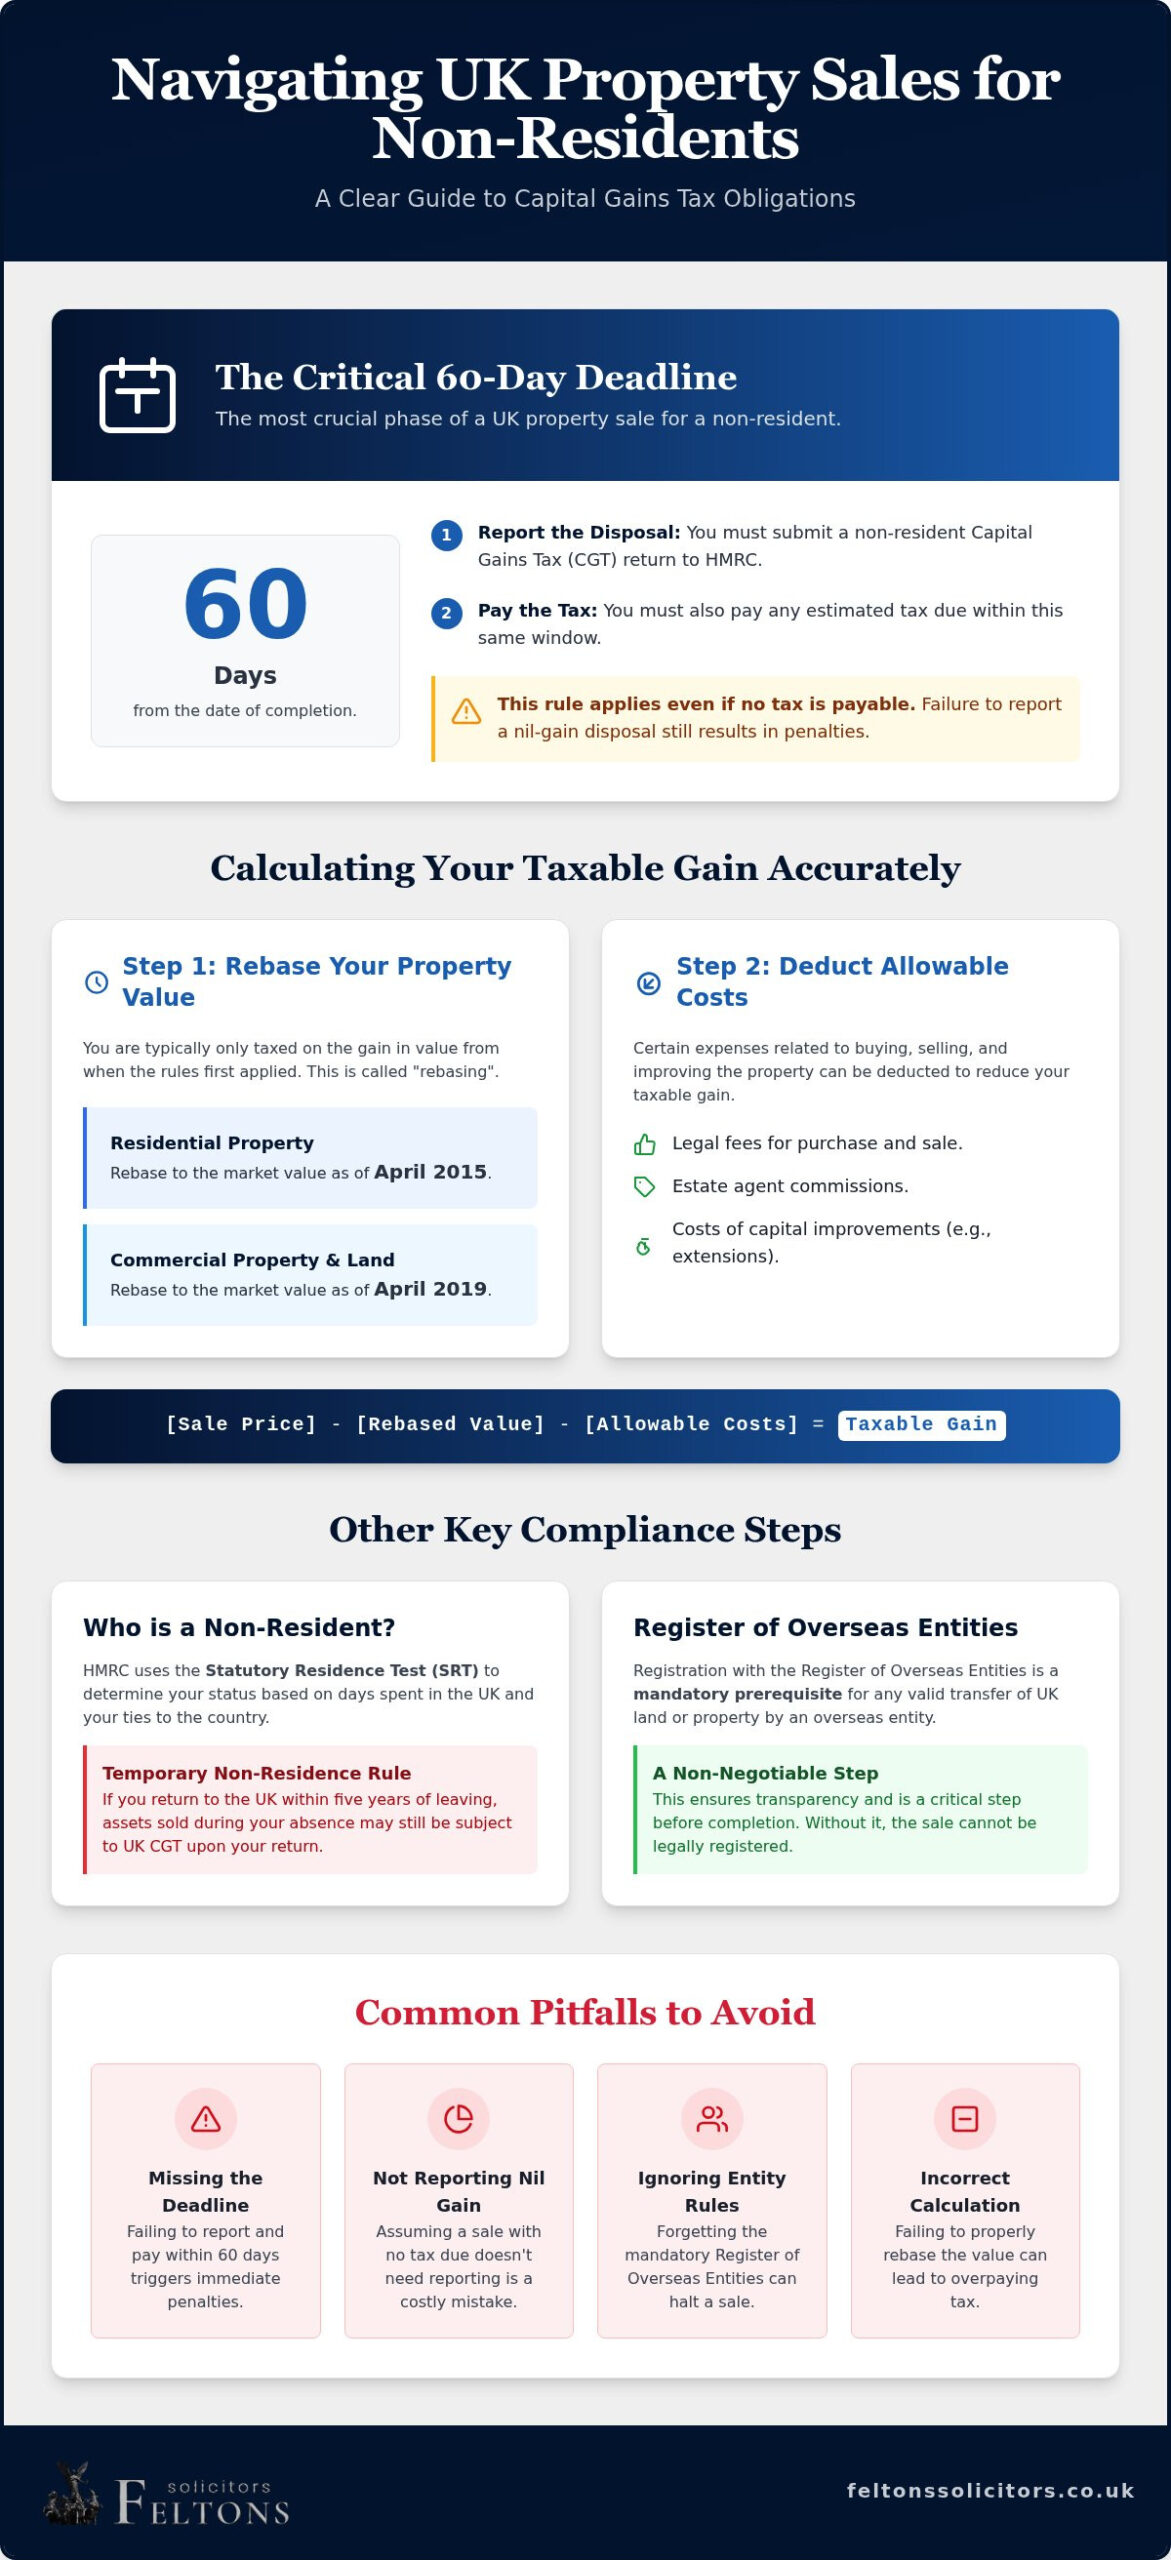
For an international property owner, the most critical phase of a UK sale isn’t the exchange of contracts, but the sixty days that follow it. Missing this narrow window for reporting and payment can lead to immediate HMRC penalties, even if no tax is actually due. Engaging specialist non-resident capital gains tax uk property solicitors ensures that your disposal is handled with the precision required to meet these stringent deadlines. You’ve likely noticed that the UK tax landscape has become increasingly complex, moving from a relatively relaxed regime to one defined by real-time reporting and the rigorous transparency of the Register of Overseas Entities.

It’s understandable to feel a sense of trepidation when facing these evolving regulations, but with the right guidance, you can manage your obligations with confidence. This article provides a clear roadmap for navigating non-resident CGT, showing you how to minimise your liability through strategic rebasing and ensure your conveyancing process proceeds without delay. We’ll examine the current 2026-2027 tax rates, the nuances of the 60-day reporting window, and how to maintain full compliance whilst protecting your investment’s value.

Key Takeaways

  • Master the strict 60-day reporting and payment window to ensure full compliance and avoid costly HMRC penalties.
  • Explore how rebasing your property value to 2015 or 2019 levels can effectively minimise your overall tax liability.
  • Understand why registration with the Register of Overseas Entities is a mandatory prerequisite for any valid UK land transfer.
  • Discover how non-resident capital gains tax uk property solicitors provide an integrated approach to conveyancing and tax reporting.
  • Recognise the common pitfall of failing to report a disposal to HMRC, even in instances where no tax is actually payable.

Understanding Non-Resident Capital Gains Tax (NRCGT) in the UK

NRCGT is the tax due on profits made from disposing of UK land or property whilst living abroad. This specific branch of Capital Gains Tax in the United Kingdom has seen significant expansion over the last decade. In 2015, the UK government introduced these rules for residential assets, extending them in April 2019 to include all non-residential property and land. The logic behind this shift was to align the tax treatment of overseas owners with that of UK residents, ensuring a level playing field across the property market. Whether you’re selling a buy-to-let flat or a commercial warehouse, the profit is now firmly within the HMRC net. Engaging non-resident capital gains tax uk property solicitors early in the process is essential to understand which specific tax triggers apply to your disposal.

Who is Classified as a Non-Resident?

Determining your status isn’t always straightforward. HMRC uses the Statutory Residence Test (SRT) to assess how many days you’ve spent in the UK and the nature of your ties to the country. This classification extends beyond individuals to include trustees and personal representatives of deceased estates. A common complication arises with “temporary non-residence” rules. If you leave the UK and return within five years, assets sold during your absence might still be subject to UK tax upon your return. Because these rules are nuanced, consulting non-resident capital gains tax uk property solicitors before you list a property is the most secure way to clarify your liability and residency status.

The 60-Day Reporting and Payment Rule

The timeline for compliance is exceptionally tight. You must report the disposal and pay any tax due within 60 days of the completion date. It’s a frequent misconception that you can simply wait until your annual self-assessment return to declare the sale. This mistake is costly. Failing to file within this window triggers immediate penalties and accruing interest, even if there’s no tax to pay. For many international clients, legal experts provide the necessary oversight to ensure these filings are accurate and timely. This proactive approach prevents the stress of HMRC investigations and avoids unnecessary financial loss at the end of a transaction.

Calculating Capital Gains for Overseas Sellers

Calculating the gain on a UK property disposal is rarely as simple as subtracting the purchase price from the sale price. For international owners, the UK tax system allows for “rebasing,” which means you only pay tax on the growth in value from specific dates. For residential property, this is generally April 2015, whilst for commercial property, the date is April 2019. This provision is designed to ensure that gains accrued before these rules applied to non-residents aren’t unfairly taxed. Expert non-resident capital gains tax uk property solicitors play a vital role here, ensuring that the completion statement and acquisition data are precisely aligned for HMRC.

To establish a robust tax position, professional valuations at these rebasing dates are highly recommended. HMRC may challenge self-estimated figures, so having a formal report provides a layer of security. Additionally, some expats may still benefit from Private Residence Relief (PRR) for the period they occupied the property as their main home. This can significantly reduce the taxable gain, provided the residency criteria are strictly met. For a deeper look at the technical framework used by legal professionals, the official guidance on Non-Resident Capital Gains Tax outlines the current statutory requirements.

Residential vs Commercial Property Calculations

The distinction between residential and commercial assets is fundamental. Residential dwellings have been subject to these rules since 2015, whereas commercial property and indirect disposals, such as selling shares in a property-rich company, only fell into the scope in April 2019. It’s important to focus on the “gain” rather than just the “proceeds” of the sale. The gain is the profit remaining after accounting for the rebased value and all eligible deductions. Non-resident capital gains tax uk property solicitors can help you identify which rebasing method is most advantageous for your specific circumstances.

Deducting Costs and Professional Fees

You can effectively reduce your tax liability by deducting specific costs associated with the sale and acquisition. These include:

  • Legal fees for both the purchase and the eventual sale
  • Estate agent commissions and professional marketing costs
  • Stamp Duty Land Tax (SDLT) paid upon the initial purchase
  • Capital expenditure, such as structural extensions or significant improvements

It’s crucial to distinguish between capital improvements, which are deductible, and general maintenance or repairs, which are not. When managing a high-value disposal, having specialist property solicitors handle your conveyancing ensures that all deductible legal costs are clearly documented and evidenced for your tax filing.

The Register of Overseas Entities: A Critical Compliance Step

For corporate owners and foreign trusts, the ability to sell UK land is now inextricably linked to transparency. The Register of Overseas Entities (ROE), managed by Companies House, requires any foreign legal entity owning UK property to identify and verify its beneficial owners. This isn’t merely a reporting exercise; it’s a fundamental gatekeeper in the conveyancing process. An overseas entity cannot sell UK property without a valid Overseas Entity ID. Without this unique identifier, the Land Registry will simply refuse to register the transfer of title to a buyer, effectively freezing your assets in place. Non-resident capital gains tax uk property solicitors ensure that this registration is not only active but fully compliant with the latest 2026 regulations before a sale is even negotiated.

Maintaining your standing on the register requires constant vigilance. An annual update statement must be filed within 14 days of the anniversary of your initial registration. HMRC and Companies House use this data to ensure that the individuals profiting from UK land are clearly identified. If your registration has lapsed or the annual update is overdue, your Overseas Entity ID becomes invalid. This can lead to catastrophic delays during the final stages of a transaction, often at the very moment you are preparing to settle your capital gains tax obligations.

ROE Verification and the Role of the Solicitor

The verification process is the most rigorous aspect of the ROE. A UK-regulated professional must independently verify the identity of all registrable beneficial owners before the information is submitted. This step is designed to prevent disputes and ensure that the “people with significant control” are accurately documented. It’s a complex task, particularly when dealing with multi-layered international corporate structures or discretionary trusts. For a detailed breakdown of this process, you may find our guide on Overseas Entity Beneficial Owner Registration helpful. Specialist non-resident capital gains tax uk property solicitors provide the pragmatic oversight needed to bridge the gap between international corporate law and UK property compliance.

Consequences of Non-Compliance for Sellers

The risks of ignoring ROE obligations are severe and go beyond simple administrative hurdles. If an entity fails to register or update its details, the Land Registry places a “restriction” on the property’s title. This restriction prevents the entity from selling, leasing, or charging the land. Beyond the commercial impact, non-compliance is a criminal offence. Directors or officers of a non-compliant entity can face significant daily fines or even imprisonment. Organising your documentation well in advance of your sale date is the only way to avoid these sanctions. By integrating ROE compliance with your wider tax strategy, you ensure a smooth exit from your UK investment without the threat of legal or financial paralysis.
Non-Resident Capital Gains Tax: Specialist UK Property Solicitors

Common Pitfalls for Non-Resident Property Owners

HMRC compliance is rarely intuitive, and for international owners, the margin for error is non-existent. One of the most frequent errors involves the disposal date. Whilst the tax year of the sale is determined by the date of exchange, the 60-day reporting window begins strictly on the date of completion. Miscalculating this distinction can result in automatic penalties before you’ve even realised the deadline has passed. Additionally, properties held within corporate structures may have existing obligations under the Annual Tax on Enveloped Dwellings (ATED). The interaction between ATED-related gains and standard NRCGT is complex, often requiring non-resident capital gains tax uk property solicitors to untangle the overlapping liabilities and ensure you aren’t overpaying.

Logistical hurdles also pose a significant threat to a smooth exit. Anti-money laundering (AML) checks for international clients are now more rigorous than ever. Underestimating the time required for these checks, or for international currency transfers, can delay the entire conveyancing process. If these delays push your reporting past the sixty-day mark, HMRC will not accept bank delays or administrative friction as a valid excuse for late filing. It’s a high-stakes environment where timing is as important as the financial calculation itself.

Reporting a Sale with No Tax Due

A common HMRC trap is the belief that a loss-making sale or a break-even disposal requires no action. This is incorrect. Non-residents must file a “nil return” to declare the disposal, even if no tax is payable. Failing to submit this return within the 60-day window triggers the same penalty regime as a high-profit sale. Establishing this paper trail is not just about avoiding fines; it’s also essential for your own international tax reporting, providing clear evidence to your local tax authorities that the disposal has been handled according to UK law. For those with broader European interests, such as in Italy, professional Italian fiscal representation services can assist in ensuring that all cross-border reporting is accurately synchronised.

The UK maintains an extensive network of double taxation treaties amongst different nations to ensure that you aren’t taxed twice on the same gain. In most instances, you can claim credit for the UK CGT paid against your local tax liability in your country of residence. However, the mechanics of claiming this credit vary significantly between jurisdictions. Coordinated advice between your UK legal team and local tax advisors is the only way to ensure you aren’t left out of pocket. If you are concerned about how these pitfalls might affect your sale, you should contact our property law specialists for a comprehensive compliance review.

How Feltons Solicitors Manage Your Non-Resident Disposal

Most firms treat property law and tax compliance as separate silos, often leaving the client to coordinate between a conveyancer and an accountant. At Feltons Solicitors LLP, we provide a sophisticated, integrated service that bridges this gap. Our role as non-resident capital gains tax uk property solicitors is to manage the entire lifecycle of your disposal, from the initial legal due diligence to the final HMRC submission. We provide discreet and professional representation for high-net-worth individuals and international corporate investors, ensuring that every transaction is handled with the quiet confidence and precision it deserves. Our people-first philosophy means we prioritise your peace of mind, acting as a steady guide through the often stressful landscape of UK tax regulations.

We understand that international property owners face unique pressures, particularly when dealing with high-value estates and multi-layered corporate structures. Our team is equipped to handle the most complex matters with a boutique level of care, ensuring that your personal rapport with your solicitor remains at the heart of our service. By combining modern efficiency with traditional professional integrity, we protect your interests whilst maintaining the highest standards of HMRC compliance.

Our Proactive Approach to the 60-Day Window

The sixty-day reporting window is unforgiving, and we don’t believe in leaving compliance to the final hour. We begin preparing your NRCGT return alongside the conveyancing process, often starting the work as soon as contracts are exchanged. This proactive stance allows us to accurately capture all deductible costs, including acquisition legal fees and capital expenditure, to minimise your eventual tax liability. For those managing a broader portfolio, our guide on Navigating Residential Property Law provides essential context for maintaining residential assets in the UK. By the time completion occurs, the majority of the tax work is already finalised, allowing for a seamless transition to the reporting phase.

Specialist Support for Overseas Entities

For clients holding property through foreign companies or trusts, we manage the Register of Overseas Entities (ROE) registration and verification process entirely in-house. This ensures that your Overseas Entity ID is valid and your annual update statements are current long before they are required for a Land Registry transfer. We act as a trusted advisor for long-term UK property portfolios, providing the worldly experience necessary to handle international-scale matters with ease. If you are planning a disposal or require expert guidance on your current tax position, we invite you to contact our property team for a professional consultation.

Securing Your UK Property Exit

Successfully managing a UK property disposal as a non-resident requires a meticulous approach to timing and transparency. We have explored how the strict 60-day reporting window and the Register of Overseas Entities have transformed the compliance landscape for international owners. By leveraging rebasing rules and identifying all allowable deductions, you can significantly reduce your tax burden whilst maintaining a clear standing with HMRC.

Navigating these complexities is far simpler with the support of non-resident capital gains tax uk property solicitors who understand the intersection of conveyancing and tax law. Feltons Solicitors provides a comprehensive service. We offer pragmatic legal advice for international clients and specialist expertise in Overseas Entity Registration. You can instruct Feltons Solicitors for your UK property disposal to ensure your transaction is handled with the highest level of professional integrity and care. With the right legal partner, your exit from the UK market can be both fully compliant and commercially rewarding.

Frequently Asked Questions

Do I have to pay Capital Gains Tax if I am not a UK resident?

Yes, non-residents are liable for CGT on the disposal of all UK land and property. This includes residential dwellings, commercial buildings, and land without structures. The tax is calculated on the profit made during the period of ownership, subject to specific rebasing rules. Expert guidance from non-resident capital gains tax uk property solicitors is recommended to ensure you apply the correct rates for the 2026-2027 tax year.

What is the 60-day rule for non-resident CGT?

The 60-day rule requires non-residents to report the disposal of UK property and pay any tax due within sixty days of completion. It is a common error to assume the clock starts at the exchange of contracts. Missing this window triggers automatic penalties. Because this timeline is exceptionally tight, we prepare the necessary documentation alongside the conveyancing process to ensure you remain fully compliant with HMRC’s real-time reporting requirements.

How is CGT calculated for a non-resident selling UK property?

Calculations for non-residents typically focus on the gain accrued since April 2015 for residential property or April 2019 for commercial assets. This rebasing ensures you aren’t taxed on growth that occurred before the current rules applied to overseas owners. You subtract the rebased value and allowable expenses from the final sale price. For the 2026-2027 tax year, residential rates are 18% or 24% depending on your total UK income and gains.

Can I deduct my solicitor fees from my Capital Gains Tax bill?

Yes, you can deduct professional fees from the gain to reduce your overall tax liability. This includes the legal costs incurred during both the acquisition and the disposal of the property. Other deductible expenses include estate agent commissions, Stamp Duty Land Tax paid at purchase, and capital expenditure for structural improvements. Keeping precise records of these costs is essential for non-resident capital gains tax uk property solicitors to maximise your available tax relief.

What happens if I miss the HMRC reporting deadline?

Missing the 60-day deadline results in immediate financial penalties and accruing interest on any unpaid tax. Initial late filing penalties are usually £100, but these increase significantly if the return is more than three or six months overdue. HMRC rarely accepts administrative delays or international bank friction as a valid excuse. Proactive legal management ensures that your reporting is submitted accurately and on time, avoiding these unnecessary costs and potential investigations.

Do I need to report the sale if I made a loss on the property?

You must report the disposal to HMRC even if the sale resulted in a loss or no tax is due. This is a mandatory requirement for all non-residents disposing of UK land. Failing to submit a nil return within the 60-day window triggers the same penalty regime as a profitable sale. Reporting a loss is also beneficial, as it can often be offset against future UK capital gains to reduce your future tax liabilities.

Is commercial property treated differently for non-resident CGT?

Commercial property disposals follow the same 60-day reporting window but use a different rebasing date of April 2019. Unlike residential property, which was brought into the non-resident CGT net in 2015, commercial assets and indirect disposals only became taxable for non-residents in 2019. The calculation methods and tax rates can also differ, particularly if the property is held within a corporate structure rather than being owned by an individual.

How does the Register of Overseas Entities affect my property sale?

The Register of Overseas Entities is a mandatory compliance step for any foreign company or trust owning UK land. You cannot legally transfer the title to a buyer without a valid Overseas Entity ID from Companies House. If your registration isn’t current or your annual update is overdue, the Land Registry will block the sale. We handle the verification and registration process in-house to ensure your transaction proceeds without any regulatory delays.
International Prenuptial Agreement Solicitors UK: A Guide for Global Couples in 2026

International Prenuptial Agreement Solicitors UK: A Guide for Global Couples in 2026

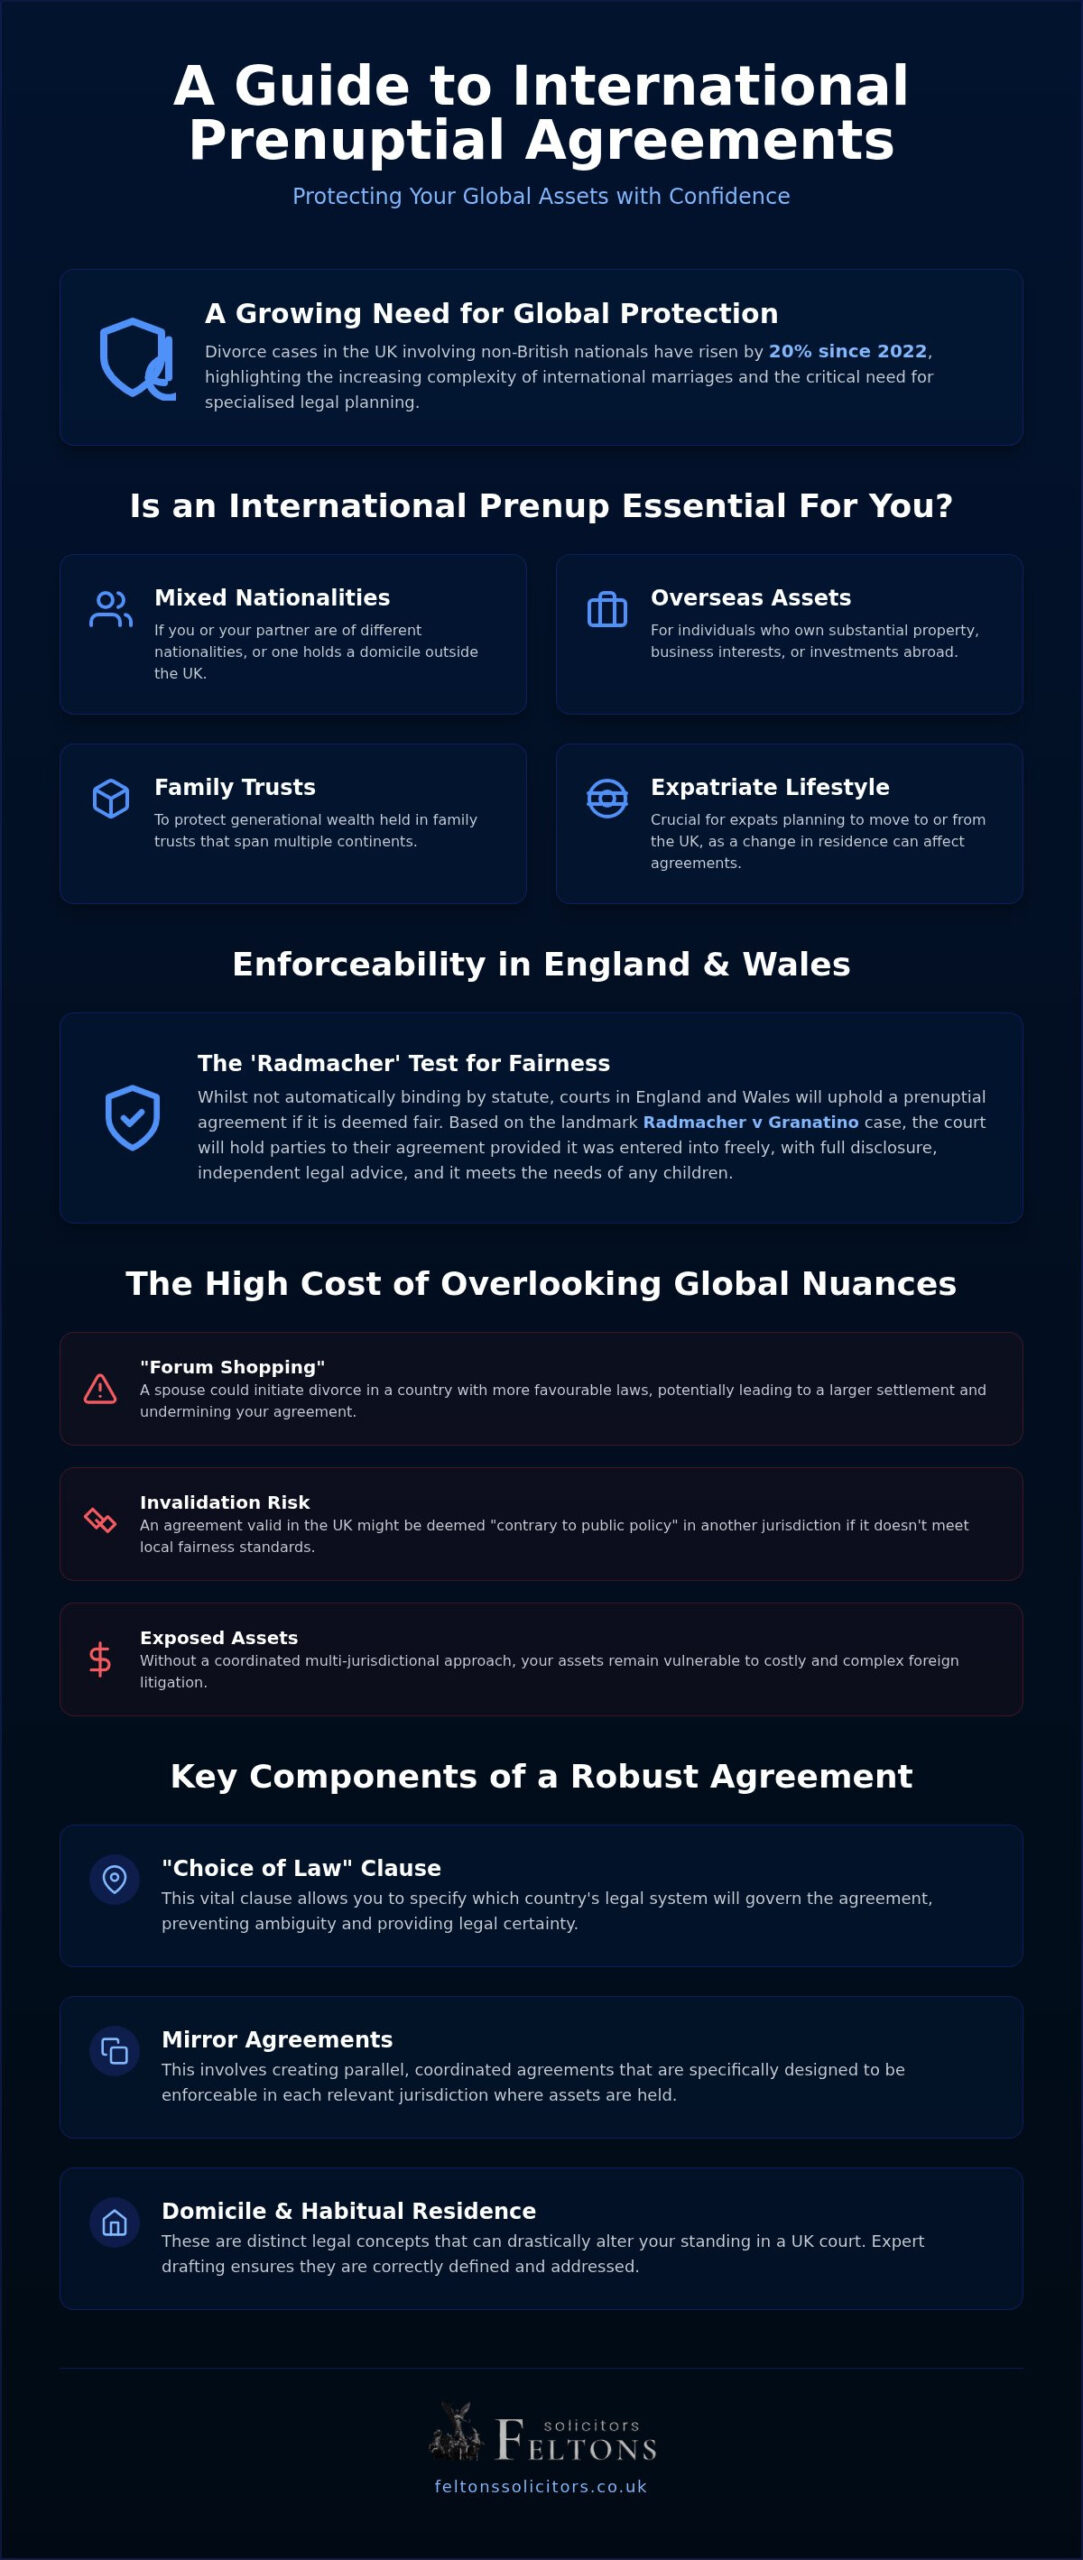
Did you know that divorce cases involving non-British nationals in the UK have risen by 20% since 2022? For couples whose lives, careers, and assets span multiple borders, the excitement of marriage often brings a unique set of logistical anxieties. You might worry about how a property in one country or a business in another would be treated under different legal systems, or feel overwhelmed by the thought of coordinating foreign lawyers. Working with specialist international prenuptial agreement solicitors uk is a pragmatic step to resolve these concerns, ensuring your financial arrangements remain predictable and secure.

This guide provides the expert insight you need to protect your global footprint with confidence. We’ll examine the 2026 proposals for Qualifying Nuptial Agreements and the enduring significance of the Radmacher v Granatino ruling. From understanding jurisdictional nuances to the practicalities of mirror agreements, you’ll learn how to establish a financial foundation that’s both discreet and dependable. Our aim is to provide you with the certainty that your future is managed with the high level of care and professional integrity your situation demands.

Key Takeaways

  • Understand the 2026 legal framework in England and Wales, including how the courts apply the Radmacher v Granatino principles to international marriages.
  • Learn why engaging specialist international prenuptial agreement solicitors uk is vital for coordinating “mirror agreements” that are enforceable across multiple jurisdictions.
  • Gain clarity on how “Choice of Law” clauses and your “Domicile” status directly impact the protection of your global property and inheritance.
  • Discover a methodical, step-by-step drafting process that ensures all foreign legal requirements are met through seamless coordination with overseas experts.
  • Establish a legally robust financial foundation that provides long-term certainty for your assets whilst prioritising discretion and personal rapport.

What is an International Prenuptial Agreement and Why is it Essential?

An international prenuptial agreement is a bespoke legal contract designed for couples whose lives and assets aren’t confined to a single country. When you’re managing a global lifestyle, a standard domestic agreement often falls short because it lacks the specific jurisdictional clauses required to protect properties, trusts, or business interests located across different borders. An international prenuptial agreement is a strategic tool for cross-border asset protection.

Standard UK agreements frequently fail to safeguard overseas property or inheritance because they don’t account for the unique “form” requirements of foreign courts. For instance, a court in France or Dubai might ignore a basic English document if it hasn’t been executed in a specific way or translated correctly. This is where What is a Prenuptial Agreement? becomes a more complex question, as the document must act as a bridge between different legal systems. Without this coordination, you risk your agreement being dismissed precisely when you need it most.

A critical component of these documents is the “Choice of Law” clause. This allows you to specify which country’s legal system should govern the agreement. Without this, you leave your future to the chance of where you happen to be living if the marriage ends. Domicile and habitual residence are distinct legal concepts that can drastically alter your standing in a UK court. Engaging experienced international prenuptial agreement solicitors uk ensures these clauses are drafted with precision, reflecting the current 2026 legal landscape and providing a calm, steady foundation for your marriage.

Who Needs an International Prenup?

Not every couple requires an international approach, but for those with a global footprint, it’s a necessity. You should consider this if you or your partner hold different nationalities or maintain a domicile outside the UK. It’s equally vital for individuals who own substantial property, business interests, or family trusts abroad. Expats planning a move to or from the United Kingdom must also consider how their change in residence affects previous agreements. Identifying these needs early allows international prenuptial agreement solicitors uk to coordinate a robust strategy before the wedding date.

The Risks of Overlooking Jurisdictional Nuances

Ignoring international nuances creates significant legal vulnerability whilst leaving your assets exposed to foreign litigation. One major risk is “forum shopping,” where a spouse might attempt to start divorce proceedings in the country most likely to grant them a larger settlement. Additionally, an agreement drafted in the UK could be deemed “contrary to public policy” in another jurisdiction if it doesn’t meet local fairness standards. For those protecting family wealth that spans generations and continents, these oversights can be incredibly costly. Expert advice on divorce and financial arrangements helps mitigate these risks by providing a coordinated, multi-country strategy.

The Supreme Court decision in Radmacher v Granatino remains the cornerstone of Enforceability in England and Wales as we move through 2026. Whilst prenuptial agreements aren’t yet automatically binding under statute, the courts will hold parties to their bargain if specific criteria are met. The judiciary’s approach is one of quiet respect for autonomy. They’ll rarely interfere with a well-drafted agreement unless it fails to meet the basic needs of a spouse or any children involved. It’s a delicate balance between personal freedom and judicial protection.

Agreements drafted under foreign laws present a unique challenge. English courts won’t simply rubber-stamp a document just because it’s valid in New York or Paris. Instead, they’ll scrutinise whether the process aligned with British standards of fairness. This makes the involvement of international prenuptial agreement solicitors uk essential. They ensure that your multi-jurisdictional strategy doesn’t inadvertently fall foul of local judicial discretion, providing a steady hand through complex cross-border requirements.

The Radmacher Criteria Explained

To carry “decisive weight,” an agreement must satisfy three primary pillars. First, it must be freely entered into. This means no last-minute pressure; ideally, the document should be finalised at least 28 days before the wedding. Second, both parties must have a full appreciation of the implications. This is only possible if each person receives independent legal advice from qualified solicitors. Finally, the agreement must be fair. A court won’t enforce a contract that leaves one party in significant financial hardship whilst the other retains vast wealth. It’s about pragmatic protection, not total exclusion of support.

Financial Disclosure Across Borders

A robust agreement relies on absolute transparency. You must provide a comprehensive schedule of all global assets, from Swiss bank accounts to Californian real estate. Valuing these interests requires a methodical approach, particularly regarding overseas entity beneficial owner registration and complex corporate structures. If you fail to disclose a material asset, the entire agreement could be set aside. This level of detail provides the certainty you need. If you’re unsure how to categorise your international holdings, seeking a discreet consultation with a specialist can help clarify your position and protect your interests.

Distinguishing between domicile and habitual residence is fundamental to your legal standing in the UK. Your domicile is generally where you consider your permanent home, whilst habitual residence is where you actually live and work. These statuses dictate which court has the power to hear a case. A “Choice of Law” clause allows you to specify which country’s rules should apply to the division of your assets, but it isn’t a silver bullet. English courts often prioritise local law if the parties are habitually resident here, especially if applying a foreign law would result in an outcome they deem unfair. This nuance is why consulting international prenuptial agreement solicitors uk is vital; they help you understand The Legal Framework for 2026 and how it impacts your specific circumstances.

A robust protection strategy doesn’t end with the marriage contract. You must integrate these arrangements with broader estate planning to ensure your global legacy remains intact across generations. Co-ordinating your prenup with your will and any existing trusts provides a seamless shield for your wealth, regardless of where your life takes you. It’s about creating a methodical, all-encompassing plan that respects both your current needs and your long-term intentions.

Jurisdiction Shopping and Forum Conveniens

Jurisdiction shopping occurs when one party rushes to file for divorce in a country that offers a more generous financial settlement. Courts use the principle of “forum conveniens” to decide the most appropriate venue for the dispute to be heard. In complex international cases, we may use anti-suit injunctions to prevent a spouse from pursuing litigation in a country that ignores the autonomy of prenuptial contracts. Strategic positioning is key. You want to select a jurisdiction that respects your agreement’s intent whilst providing a predictable, steady outcome for both parties.

Protecting Specific International Assets

Assets in civil law countries, such as France or Spain, are often governed by different marital regimes compared to the common law approach in the UK. For offshore trusts or international shareholdings, we often recommend the use of mirror agreements. These are secondary contracts drafted by local experts in the asset’s location, ensuring the protections in your primary agreement are recognised and enforced locally. Working with international prenuptial agreement solicitors uk allows for this co-ordinated, multi-jurisdictional oversight, ensuring no high-value asset is left vulnerable to foreign legal quirks.

International Prenuptial Agreement Solicitors UK: A Guide for Global Couples in 2026

The drafting process for a cross-border marriage requires a methodical approach that respects the legal nuances of every territory involved. It isn’t a single document but a coordinated strategy. Working with international prenuptial agreement solicitors uk allows you to navigate this journey with quiet confidence, knowing every detail is managed. The process typically follows five essential steps:

  • Step 1: Identify all relevant jurisdictions based on nationality, domicile, and asset location.
  • Step 2: Appoint specialist solicitors in each relevant country to ensure local compliance.
  • Step 3: Draft the primary agreement in the country where you intend to reside.
  • Step 4: Create “Mirror Agreements” that translate the intent into local legal formats.
  • Step 5: Execute and register the documents according to local formalities, such as Notarisation.

What are Mirror Agreements?

Mirror agreements are identical or complementary contracts signed in different countries to ensure your intentions are recognised globally. Relying on a single multi-jurisdictional document is risky. Foreign courts often require specific phrasing or execution methods that an English document might lack. A mirror agreement is safer because it’s drafted by a local expert to meet local standards whilst remaining consistent with your primary English agreement. This dual-layered approach provides the high-standard protection discerning couples require for their global assets.

Working with Foreign Counsel

Your UK solicitor acts as the “lead architect” of your international strategy, overseeing the entire project to ensure nothing is lost in translation. We coordinate with trusted international law firms to provide a seamless service, managing the timeline and costs of multi-jurisdictional drafting on your behalf. This boutique level of care ensures that while the technical legal work is complex, your experience remains straightforward and supportive. It’s about providing a calm, steady presence throughout the coordination of foreign legal advice. If you’re ready to secure your global assets, you can contact our team for a discreet consultation regarding your international financial arrangements.

Securing Your Future with Feltons Solicitors: Discreet International Expertise

Choosing the right legal partner is a decision that balances technical proficiency with personal rapport. At Feltons Solicitors LLP, we provide a sophisticated, boutique service tailored specifically for individuals with global interests. Our worldly experience allows us to manage international-scale matters with a “people-first” philosophy, ensuring that the human impact of your legal arrangements is never overlooked. As specialist international prenuptial agreement solicitors uk, we offer a calm, steady presence during what can often be a complex or stressful period of preparation.

We possess deep expertise in divorce and financial arrangements with a dedicated international focus. Our approach is rooted in pragmatic, discreet advice that prioritises your privacy and future security. We understand that your assets aren’t just numbers on a balance sheet; they represent your hard work, your heritage, and your family’s future legacy. By positioning ourselves as your sophisticated guide, we help you manage the nuances of cross-border law with quiet confidence and traditional professional integrity.

Why a Boutique Firm Suits International Prenups

Discerning couples often find that a boutique firm offers significant advantages over larger, more impersonal practices. You’ll benefit from greater privacy and direct access to senior partners who truly understand the intricacies of your situation. We avoid “off-the-shelf” legal templates, opting instead for bespoke drafting that reflects your unique global footprint. Our streamlined structure also allows us to move quickly and efficiently across different time zones, ensuring that your international strategy remains on track regardless of where your assets or partners are located.

Next Steps: Your Consultation

The first step in securing your financial future is a confidential discussion to review your circumstances. Before our initial meeting, it’s helpful to prepare a comprehensive list of your global assets, including property, business interests, and any existing trusts. We’ll then begin the methodical process of cross-border legal coordination, identifying necessary jurisdictions and liaising with foreign counsel on your behalf. This structured approach provides the high-end reliability you expect from international prenuptial agreement solicitors uk. We invite you to contact Feltons Solicitors LLP for a confidential discussion, where we can begin crafting a robust agreement that protects your interests across every border.

Securing Your Global Legacy for 2026 and Beyond

Navigating the complexities of cross-border marriage requires more than a simple contract. It demands a coordinated strategy that respects the legal nuances of every country where you hold assets. By prioritising procedural fairness and full financial disclosure, you ensure your agreement carries the necessary weight in British courts. Working with expert international prenuptial agreement solicitors uk provides the high-end reliability and discreet guidance essential for managing high-value, multi-jurisdictional arrangements.

We’ve explored how mirror agreements and precise choice of law clauses act as a shield for your wealth, whilst the 2026 legal landscape offers new avenues for certainty. Feltons Solicitors offers a boutique service that combines traditional integrity with modern efficiency, focusing on a personal connection that larger firms often lack. Our specialists provide pragmatic, expert advice for high-net-worth individuals facing international-scale matters with a people-first philosophy.

If you’re ready to establish a robust financial foundation, contact Feltons Solicitors for discreet international prenuptial advice. Our pragmatic approach ensures your global footprint is protected with the care and expertise it deserves. Your future stability starts with a single, confidential conversation.

Frequently Asked Questions

Is an international prenuptial agreement legally binding in the UK?

In England and Wales, prenuptial agreements aren’t yet strictly binding by law, but they carry significant weight in court. Following the Radmacher v Granatino ruling, judges will typically uphold an agreement if it was freely entered into with full financial disclosure. The 2026 proposals for Qualifying Nuptial Agreements (QNAs) aim to provide even greater certainty. Engaging international prenuptial agreement solicitors uk ensures your document meets these evolving standards of fairness and procedural integrity.

Can I include a choice of law clause in my prenuptial agreement?

You can include a choice of law clause to specify which country’s legal system should govern your assets. This is a standard feature in international agreements drafted by specialists. However, English courts retain the discretion to apply English law if you are habitually resident in the UK or if the foreign law produces an outcome deemed unfair. It’s a complex area where pragmatic, expert advice is essential to ensure your intentions are respected across borders.

What happens if we sign a prenup abroad and then move to the UK?

An agreement signed abroad isn’t automatically enforceable in the UK just because it’s valid in its country of origin. If you relocate to the UK, the English courts will scrutinise the document against local standards of fairness and disclosure. To protect your interests, it’s often advisable to have your original agreement reviewed by international prenuptial agreement solicitors uk. They may suggest a mirror agreement or a postnuptial contract to ensure your financial arrangements remain robust under English law.

Do both parties need their own solicitor for an international prenup?

Yes, it’s essential for both parties to receive independent legal advice from separate solicitors. This is a fundamental requirement for an agreement to be considered fair and enforceable in the UK courts. If one party doesn’t have their own representation, the court may conclude they didn’t fully appreciate the implications of the contract. This boutique level of care ensures that both partners are supported and that the final agreement is legally sound in every jurisdiction.

How much does an international prenuptial agreement cost in the UK?

The cost of an international prenuptial agreement varies significantly based on the complexity of your global assets and the number of jurisdictions involved. Factors such as coordinating with foreign counsel, drafting mirror agreements, and the requirement for independent legal advice for both parties will influence the total investment. Because every situation is unique, we provide a tailored approach that reflects your specific needs. We recommend a discreet consultation to discuss the scope of your requirements and obtain a clear fee estimate.

How long before the wedding should we finalise the international prenup?

You should aim to finalise and sign your agreement at least 28 days before your wedding date. This timeframe is a key pillar of enforceability in the UK, as it demonstrates that neither party was under undue pressure or time constraints. Because international agreements involve coordinating with overseas experts and translating complex documents, you should ideally begin the process several months in advance. This steady, methodical approach ensures all legal formalities are met without unnecessary stress.

Can an international prenup protect assets I haven’t acquired yet?

Yes, a well-drafted agreement can protect future assets, including expected inheritances, future business interests, or property you haven’t yet acquired. This is particularly important for high-net-worth individuals who anticipate significant growth in their global wealth. By specifying how these future acquisitions should be treated, you create long-term financial certainty. Our boutique service focuses on bespoke drafting, ensuring your agreement is flexible enough to accommodate your evolving international footprint whilst maintaining its legal integrity.

What is the difference between a prenuptial and a postnuptial agreement internationally?

The primary difference is timing; a prenuptial agreement is signed before the wedding, whilst a postnuptial agreement is executed during the marriage. Internationally, both documents are treated with similar weight by English courts, provided they meet the same criteria for fairness and disclosure. Postnups are often used by couples who move to the UK after marrying abroad or whose financial circumstances change significantly. Both serve as pragmatic tools for asset protection, providing a calm, steady foundation for your shared future.

Personal Injury Trust Solicitors: Protecting Your Compensation and Future

Personal Injury Trust Solicitors: Protecting Your Compensation and Future

What if the very compensation intended to secure your future actually placed your current financial stability at risk? Receiving a settlement after a life-changing injury should be a moment of relief, yet for many, it brings a fresh wave of anxiety regarding Universal Credit and other means-tested support. You’ve fought hard for this redress, and the fear that it might be depleted by care costs or lead to a total loss of benefits is a heavy burden to carry.

Specialist personal injury trust solicitors provide a sophisticated shield, ensuring your award is legally ring-fenced to protect your eligibility for state assistance whilst securing funds for your long-term rehabilitation. We understand that the transition from litigation to recovery is complex, and our role is to offer a calm, steady hand during this period. This guide explains how a tailored trust structure preserves your capital against the £16,000 threshold, the importance of the initial 52-week disregard period, and how a discreet legal partner simplifies the requirements of the Trust Registration Service to ensure your focus remains entirely on your recovery.

Key Takeaways

  • Learn how a personal injury trust functions as a legal shield, ring-fencing your settlement to ensure your compensation is preserved for your specific needs.
  • Understand the vital role of personal injury trust solicitors in maintaining your eligibility for means-tested benefits, such as Universal Credit, after receiving an award.
  • Discover how to protect your financial future from local authority care assessments, ensuring funds remain available for bespoke rehabilitation and private medical care.
  • Recognise why a partner-led, boutique legal service offers the discreet, high-standard expertise required for complex litigation and sensitive asset protection.
  • Gain clarity on the essential timing for establishing a trust, particularly the importance of acting before the first interim payment is received.

What is a Personal Injury Trust and Why Do You Need One?

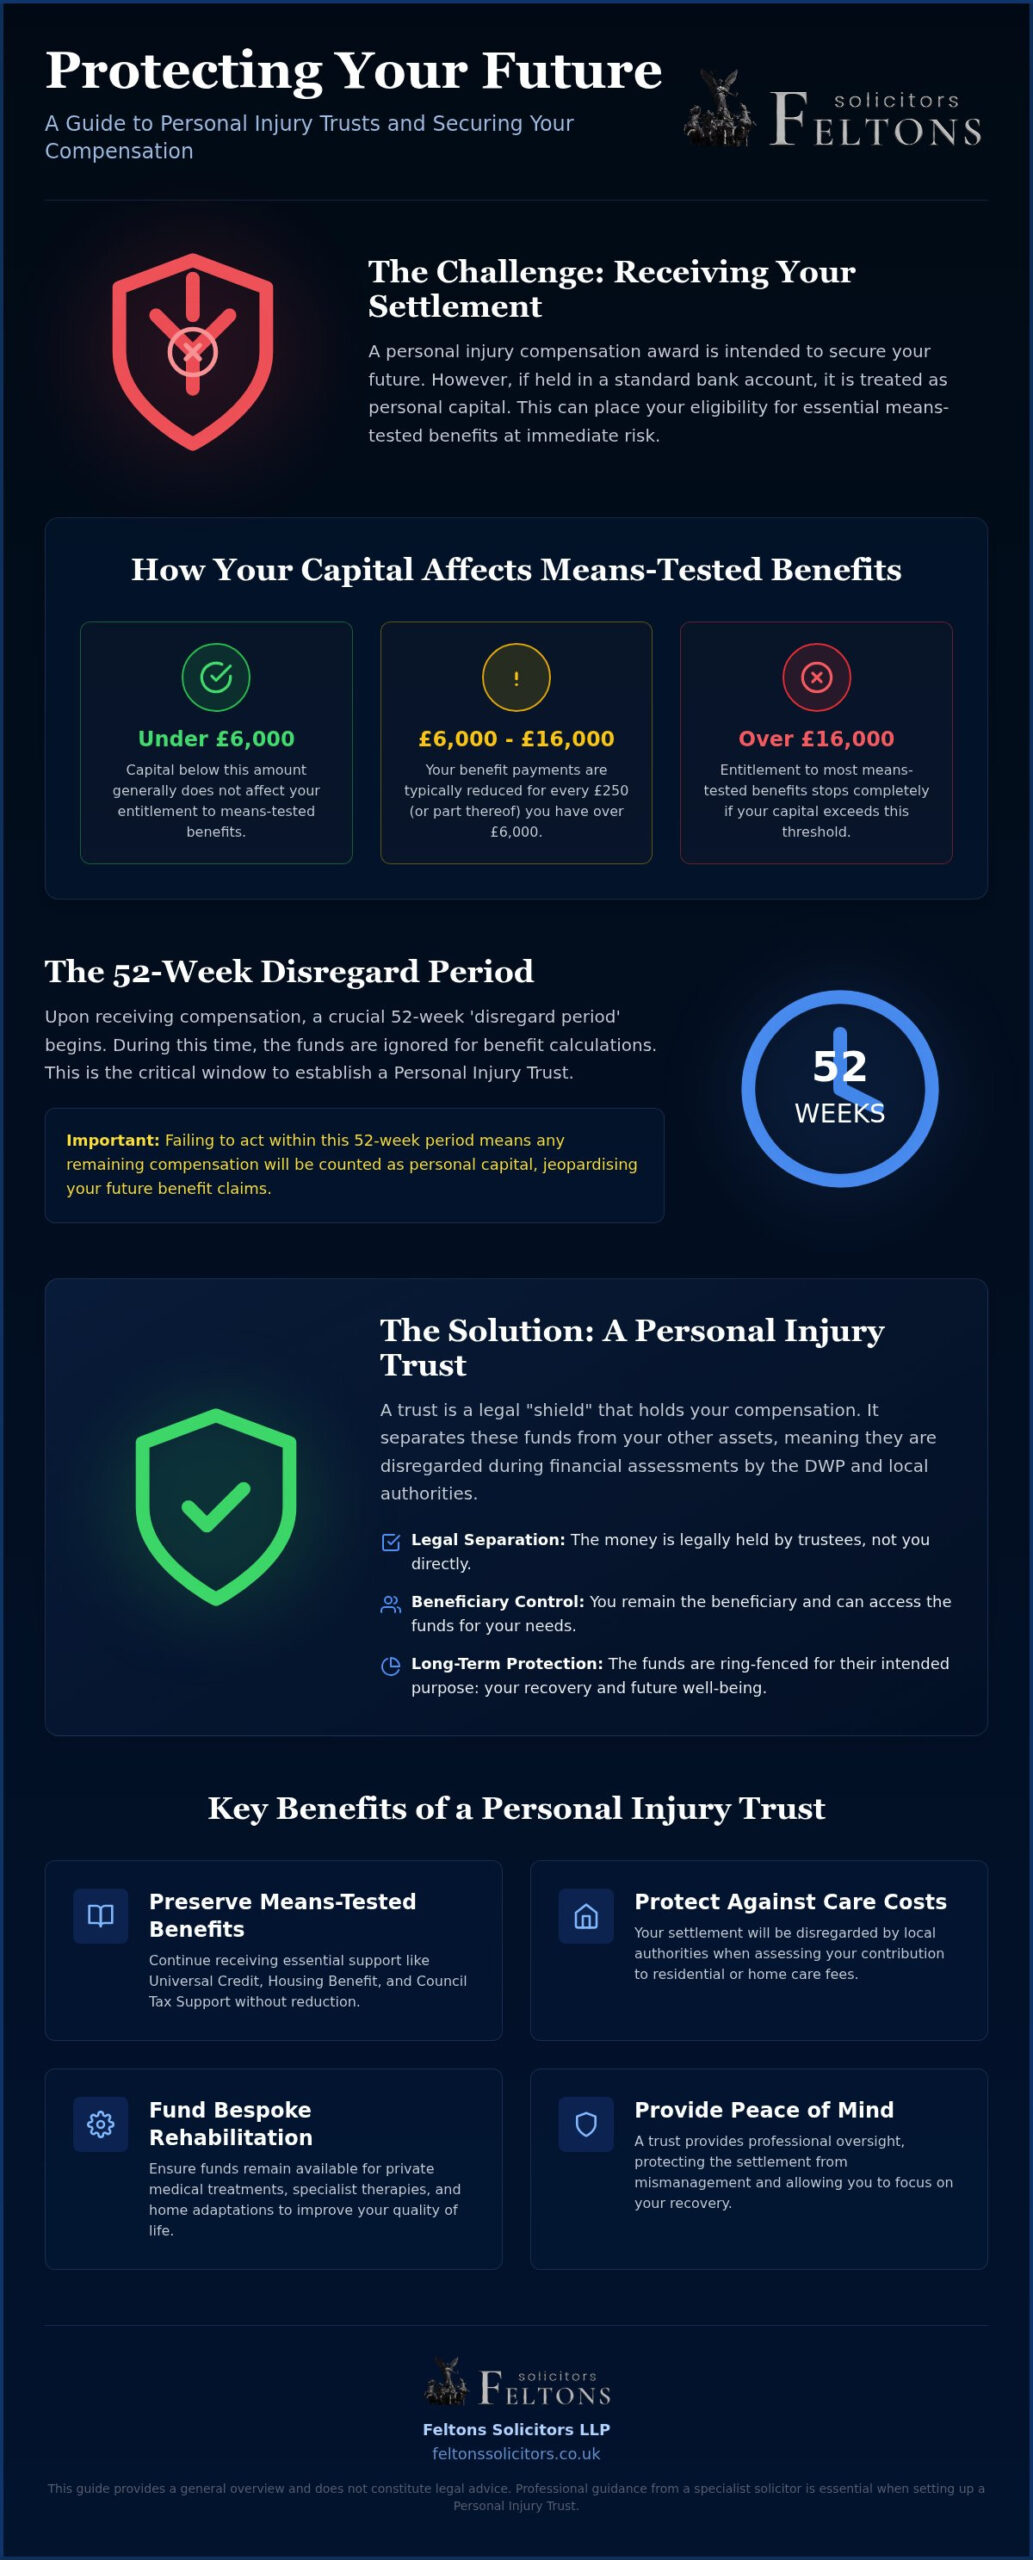
A personal injury trust is a formal legal mechanism designed specifically to hold funds awarded as compensation following an accident or illness. It acts as a protective shield, separating your settlement from your personal capital. This distinction is vital because, without it, the Department for Work and Pensions (DWP) treats those funds as readily available assets. Engaging personal injury trust solicitors ensures this separation is legally robust. Understanding What is a Personal Injury Trust? is the first step toward long-term financial security.

Placing your settlement into a standard current or savings account is a frequent mistake. Once the money enters your personal account, it’s consolidated with your other savings. This can immediately push you over the capital limits required for state support. A trust ensures these funds are ring-fenced, meaning they’re disregarded during financial assessments by government bodies or local authorities. Whilst you remain the beneficiary, the legal title is held by trustees, which creates the necessary barrier to protect your eligibility for support.

Protecting Eligibility for Means-Tested Benefits

The DWP views personal injury settlements as capital, which can be catastrophic for your household budget. Under current 2026 regulations, capital exceeding £6,000 reduces your entitlement, while assets over £16,000 usually stop means-tested benefits entirely. By using a trust, you preserve access to essential support including:

  • Universal Credit
  • Housing Benefit
  • Council Tax Support
  • Income Support

Following the receipt of a personal injury compensation payment, there is a 52-week period where the funds are disregarded for means-tested benefit calculations. This window is a critical time to establish your trust. Failing to act before this period expires means any remaining compensation will be treated as personal capital, potentially ending your right to claim benefits.

The Role of Personal Injury Trust Solicitors

Managing the technical requirements of a Trust Deed requires precision and foresight. This is where specialist personal injury trust solicitors provide essential guidance. We help you decide between a Bare Trust, where you retain absolute control, or more complex structures if the beneficiary lacks the mental capacity to manage their own affairs. Our role is to provide a calm, steady presence during what is often a stressful financial transition. We ensure the trust is established correctly from the outset, allowing you to focus on your recovery while we handle the intricate legal documentation and compliance with the Trust Registration Service. This methodical approach ensures your settlement is managed with the high-standard care it deserves.

The Financial Benefits: Securing Your Long-Term Stability

Securing a compensation award is a significant milestone, yet it’s merely the start of ensuring your financial resilience. A settlement is often intended to last a lifetime, funding ongoing needs that may not be immediately apparent. By engaging personal injury trust solicitors, you create a formal structure that prevents this capital from being treated as personal wealth by local authorities or third parties. It transforms a lump sum into a sustainable resource.

One of the most profound advantages involves social care funding. Without a trust, a local authority can include your compensation in a means-test for residential or home care costs. This could lead to your settlement being rapidly depleted to pay for services that would otherwise be state-funded. The High Court clarified in R (CGT) v West Sussex County Council EWHC 293 (Admin) that damages held in a personal injury trust must be disregarded in these assessments. This legal protection ensures your funds remain available for private medical treatments, bespoke rehabilitation programmes, and home adaptations that enhance your quality of life.

Beyond state assessments, a trust acts as a barrier against financial mismanagement or predatory interests. Life-changing settlements can unfortunately attract unwanted attention from third parties. A trust provides a structured framework where decisions are made by trustees, offering a layer of professional oversight and psychological peace of mind. It allows you to focus on recovery, knowing your capital is ring-fenced for its intended purpose.

Trusts and Future Care Costs

Professional advice is essential to navigate the complexities of “deprivation of capital” rules. If you move funds into a trust incorrectly or after you’ve already been assessed for care, local authorities might challenge the arrangement. Our partner-led approach ensures the trust is established with the necessary precision to avoid these accusations, safeguarding your capital to maintain a higher standard of future living.

Intersections with Family Law and Estate Planning

Financial protection also extends to your domestic life. A trust can help protect your settlement in the event of divorce and financial arrangements, as the funds are clearly identified as compensation for your specific injuries. Additionally, integrating your trust with your wider estate planning ensures that any remaining capital passes to your chosen beneficiaries via a Will. If you’re concerned about how a settlement might affect your existing arrangements, our team can provide the discreet, tailored advice you need to secure your legacy.

Choosing Personal Injury Trust Solicitors: Boutique vs. Claims Factories

Selecting the right personal injury trust solicitors is a decision that carries as much weight as the litigation that secured your award. In the current legal market, many national firms operate as high-volume “claims factories” where the emphasis is on case turnover rather than individual attention. In these environments, your file is often managed by junior staff or paralegals who might lack the depth of experience required to navigate the nuanced financial needs of a life-changing injury. You deserve a partner who views your settlement not as a transaction, but as the foundation of your future security.

Personal rapport is essential when discussing sensitive financial matters and the intimate details of your recovery. A boutique firm offers a calm, steady presence, ensuring you have direct access to a senior solicitor who values privacy and personal connection. This consistency builds a deep level of trust, allowing for a more thorough understanding of your specific long-term goals. We don’t just process paperwork; we provide a methodical, orderly approach that mirrors a professional consultation, making you feel informed and supported throughout the entire process.

The Boutique Advantage for Serious Injury

Direct access to senior legal minds is the hallmark of a high-standard service. We act as sophisticated guides, providing tailored advice that considers your entire private client profile rather than just the immediate settlement. This includes coordinating with your wider estate planning and future care requirements to ensure your trust is perfectly aligned with your life. Our “people-first” philosophy means that whilst the technical legal work is paramount, the human impact of that work is never forgotten. You receive a discreet, high-end service that prioritises your peace of mind over high-volume processing.

Specialist Expertise in Niche Claims

Generalist firms often overlook the specific nuances of occupational lung disease settlements, which can lead to less robust protections. For instance, the meticulous approach required for industrial diseases like silicosis demands a deep understanding of both medical evidence and litigation strategy. Specialist knowledge translates into more effective ring-fencing of your compensation. We ensure that the unique challenges of these niche claims are reflected in how your trust is structured, providing a level of security that a volume-driven firm simply cannot match. This pragmatic, partner-led advice is essential for securing the future of bereaved families and those living with life-changing conditions.

Personal Injury Trust Solicitors: Protecting Your Compensation and Future

The Process of Setting Up a Personal Injury Trust

Establishing a trust is a methodical process that requires early intervention to be most effective. It’s a common misconception that you should wait until your final settlement is reached. In reality, the most prudent time to engage personal injury trust solicitors is before or during the receipt of your first interim payment. This ensures that compensation never consolidates with your personal capital, maintaining a clear legal boundary from the outset.

The core of this arrangement is the Trust Deed. This formal document must be drafted with absolute precision to satisfy the rigorous standards of both HMRC and the Department for Work and Pensions. It defines the rules of the trust and the powers of those managing it. Once the deed is executed, the next step involves opening a dedicated Trust Bank Account. This account remains entirely separate from your everyday banking, providing a transparent audit trail that confirms the funds are ring-fenced compensation rather than personal savings.

Selecting and Appointing Trustees

Choosing your trustees is a decision that requires sound judgment and a high degree of trust. Trustees hold “fiduciary duties”, which means they’re legally obligated to act in your best interests and manage the funds with care. Whilst many people choose close family members, it’s standard practice to appoint at least two trustees to ensure security and mutual oversight. Many of our clients find significant value in appointing a professional solicitor as a trustee. This provides a neutral, expert presence to handle complex administrative tasks and ensure that the trust’s integrity is never compromised by accidental mismanagement.

Managing the Trust Over Time

A personal injury trust is designed to be a flexible, long-term resource. You can access the funds for specific needs, such as home adaptations, specialised equipment, or private rehabilitation, without those payments being treated as personal income. Maintaining this protection requires ongoing compliance, particularly regarding the Trust Registration Service (TRS). Regular annual reviews with your legal partner ensure the trust continues to meet your evolving needs and remains compliant with current regulations. If your circumstances change, such as a need to replace a trustee or eventually dissolve the trust, your solicitor manages these transitions with the same discreet, high-standard care used during the initial setup.

To ensure your settlement is protected from the moment of your first payment, you should contact our specialist team for a partner-led consultation regarding your trust requirements.

Feltons Solicitors: Your Discreet Partner in Complex Litigation

Feltons Solicitors LLP operates as a boutique firm, providing a calm and steady presence for those facing the aftermath of life-changing injuries. We don’t believe in the high-volume model of national claims factories. Instead, we prioritise a “people-first” philosophy that combines traditional professional integrity with modern, efficient delivery. Our personal injury trust solicitors act as your sophisticated guides, ensuring that the transition from receiving a settlement to securing your future is handled with the highest level of care and precision.

Our commitment to pragmatic, expert advice is rooted in a deep understanding of the human impact behind every legal case. We recognise that behind every complex litigation file is a person or a family seeking to rebuild their lives. By positioning ourselves as a dependable advisor, we offer a level of reliability that ensures your financial interests are protected whilst you focus on your physical and emotional recovery. This methodical approach is designed to provide security in even the most stressful circumstances.

Partner-Led Expertise in Serious Injury

In complex litigation, the quality of your legal partner is paramount. At Feltons, you benefit from direct access to senior legal minds throughout every stage of your claim. We understand that the stress of litigation can be overwhelming, so we position ourselves as a steady hand to reduce that burden. Our reputation is built on handling both national and complex international matters with a level of discretion that larger firms often struggle to maintain. This partner-led approach ensures that no detail is overlooked, from the initial evidence gathering to the final execution of your trust documents.

A Holistic Approach to Private Client Law

We look beyond the immediate success of a claim to secure your entire financial landscape. Our expertise is particularly deep in niche areas such as industrial disease, where we manage complex silicosis litigation with a pragmatic and meticulous mindset. We recognise that a successful settlement is only half the battle; the other half is ensuring that those funds are managed to support your rehabilitation for decades to come. This synergy between our litigation and private client departments is what sets us apart from generalist firms.

By bridging the gap between injury litigation and asset protection, we offer bespoke trust solutions tailored to your unique personal circumstances. We don’t provide generic templates; we create legal structures that reflect your specific health needs and family situation. We invite you to a professional consultation to discuss how our personal injury trust solicitors can protect your compensation and provide the long-term stability you deserve. Our goal is to ensure you feel informed, supported, and in capable hands throughout your recovery journey.

Securing Your Financial Resilience and Peace of Mind

Reaching a settlement is a significant victory, but the work of protecting that legacy begins immediately. By ring-fencing your award within a formal trust, you ensure that your eligibility for means-tested benefits remains intact whilst your capital is preserved for future care and rehabilitation. It’s a strategic move that separates your personal savings from the compensation meant to support your long-term recovery.

Choosing the right personal injury trust solicitors is essential for navigating the complexities of DWP regulations and HMRC compliance. At Feltons Solicitors, we provide a partner-led service that prioritises discreet, high-standard care over the volume-driven approach of national firms. Our specialist expertise in complex litigation and industrial disease ensures that your advice is pragmatic and tailored to your specific financial security. We invite you to contact Feltons Solicitors for a confidential consultation regarding your Personal Injury Trust. Taking this step today ensures that your hard-won compensation remains a source of stability for years to come.

Frequently Asked Questions

What is the “52-week rule” for personal injury compensation?

The 52-week rule is a specific disregard period granted by the DWP following the receipt of your first compensation payment. During this one-year window, any money received from a personal injury claim is ignored when calculating your eligibility for means-tested benefits. It’s a vital grace period that allows you time to seek advice from personal injury trust solicitors and establish a formal trust structure before the funds are treated as personal capital.

Will I lose my Universal Credit if I receive a personal injury settlement?

You won’t necessarily lose your Universal Credit if you receive a settlement, provided you place the funds into a personal injury trust. Without a trust, the DWP treats the award as capital. Under 2026 regulations, assets exceeding £6,000 reduce your monthly entitlement, whilst holdings over £16,000 typically result in a total loss of means-tested support. Ring-fencing the money ensures it remains disregarded during these financial assessments.

Can I be a trustee of my own Personal Injury Trust?

You can certainly be a trustee of your own trust, but you cannot be the sole trustee. Most legal structures require at least two people to manage the funds to ensure transparency and security. Whilst you retain the right to the capital as the beneficiary, having a second person, such as a family member or a professional solicitor, provides the necessary oversight required by banks and government bodies to recognise the trust’s validity.

How much does it cost to set up a Personal Injury Trust in the UK?

The cost of establishing a trust varies depending on the complexity of your settlement and the specific type of trust deed required. Most firms offer a fixed-fee arrangement for standard bare trusts, whilst more intricate discretionary trusts may involve higher professional fees. It’s best to discuss your requirements with personal injury trust solicitors during an initial consultation to receive a tailored quote that reflects the level of senior expertise your specific case demands.

Can I set up a trust after I have already received my compensation?

You can set up a trust after receiving your compensation, but it’s essential to act within the 52-week disregard period. If you wait longer than a year from the date of the first payment, the DWP will likely treat the funds as personal capital, which could immediately impact your benefits. Establishing the trust as soon as the first interim payment arrives is the most effective way to avoid any disruption to your financial support.

Do I need a separate bank account for my Personal Injury Trust?

A dedicated trust bank account is a mandatory requirement for maintaining the legal separation between your compensation and your personal finances. This account must be held in the names of your trustees and should only contain funds derived from your personal injury award. Mixing these funds with your everyday savings can taint the trust, making it difficult to prove to the DWP that the capital should be disregarded during means-testing.

What can I spend my Personal Injury Trust money on?

You have the freedom to spend your trust funds on almost anything that improves your quality of life or aids your recovery. Common uses include purchasing specialised equipment, funding private rehabilitation sessions, or paying for home adaptations. However, it’s important to use the funds directly from the trust account for these purchases. Withdrawing large sums of cash into your personal account can inadvertently push you over the capital limits for benefits.

How many trustees do I need for a Personal Injury Trust?

Standard practice requires a minimum of two trustees to ensure the trust functions correctly and meets the requirements of most UK banks. Having two people provides a system of checks and balances, reducing the risk of financial mismanagement. Many individuals choose a combination of a trusted family member and a professional solicitor. This blend ensures that personal needs are understood whilst the technical and administrative duties are handled with expert precision.