Leasehold Reform Valuation Tribunal Solicitors: A Practical Guide

Leasehold Reform Valuation Tribunal Solicitors: A Practical Guide

A strong tribunal strategy starts by defining the valuation issue, not simply arguing that a proposed premium is too high. If you’re considering leasehold reform valuation tribunal solicitors, first identify which parts of the valuation are genuinely in dispute and whether the tribunal can determine them.

When a premium, valuation evidence and formal procedure are all in play, it can be difficult to know whether to challenge a figure, continue negotiating or prepare for a formal determination. The First-tier Tribunal can decide certain statutory leasehold valuation disputes, but it does not determine every disagreement between a leaseholder and a landlord. A focused assessment can help clarify the evidence, procedural options and practical demands of proceeding.

This guide explains the tribunal’s role and limits, the documents and valuation evidence that may be relevant, and how the process can unfold. It also considers how a solicitor can work alongside a specialist valuer to clarify your options, prepare your case and assess legal costs. Feltons Solicitors LLP advises on leasehold enfranchisement, extensions and property disputes, helping you make an informed decision about your next step.

Key Takeaways

  • Pinpoint the statutory valuation issue before deciding whether to challenge or defend a proposed premium.
  • Understand the First-tier Tribunal’s role and why not every leasehold disagreement falls within its remit.
  • Use the lease, notices, valuation material and correspondence to organise relevant evidence for the specific route and issue.
  • Consider whether leasehold reform valuation tribunal solicitors could help clarify procedural options, evidence and the demands of handling the matter yourself.
  • See how Feltons’ experience in leasehold enfranchisement, extensions and dispute resolution can inform a tailored assessment of next steps.

Leasehold reform valuation disputes: when can the tribunal help?

A disputed premium can make an important leasehold decision difficult: accept the figure, keep negotiating or seek a formal determination? The right forum depends on the legal route and the precise question in dispute. A disagreement about a statutory lease-extension premium is not automatically the same as a complaint about a landlord’s conduct or a service charge.

In England, the First-tier Tribunal (Property Chamber) determines particular property disputes assigned to it by legislation. In leasehold enfranchisement and extension cases, it may decide disputed valuation terms or other matters referred to it under the applicable statutory procedure. The tribunal decides specified leasehold questions that legislation places within its jurisdiction; it does not resolve every disagreement between a leaseholder and a landlord.

The name can cause confusion. The former Leasehold Valuation Tribunal’s functions in England transferred to the First-tier Tribunal, and the Leasehold Valuation Tribunal (LVT) entry offers historical context. Wales has a separate tribunal system, so the appropriate forum and procedure depend on where the property is and which statutory route applies.

Which leasehold valuation issues may reach the tribunal?

In a qualifying lease extension or enfranchisement process, the parties may disagree about the premium or a component of the statutory valuation. The tribunal may be able to determine the issue where legislation provides for it and the matter is properly referred. Define the disagreement precisely: challenging an assumption in a valuation is different from objecting to the whole process or the other party’s conduct.

The statutory route shapes what can be decided, what evidence matters and how the issue reaches the tribunal. Relevant rights and valuation rules can also change as leasehold reforms take effect. Leasehold reform valuation tribunal solicitors can help clarify whether the point falls within the tribunal’s remit and what procedural options may be available. A hearing is not necessarily the only route to consider.

What the tribunal does not decide automatically

A valuation determination is not a general landlord-and-tenant complaint service. A dispute about repairs, management conduct or service charges may involve different legal provisions, procedures or forums. Nor does the tribunal simply settle negotiations because the parties cannot agree: its authority is limited to questions assigned to it by law. The Housing Ombudsman is not the decision-maker for leasehold valuation disputes.

Related concerns should be considered on their own facts and legal basis. An unsatisfactory premium does not mean every connected complaint belongs in the same proceedings. A broader understanding of leasehold enfranchisement and extensions can help you identify the statutory choices, while tailored legal advice can assess how those choices apply to the property and dispute.

How leasehold reform valuation proceedings examine the disputed figure

A persuasive tribunal case identifies the legal question and explains why the proposed figure should differ. Saying a premium feels unfair does not show which assumption is disputed or how the evidence supports another view. Connect the figure to the applicable statutory framework and the facts of the property.

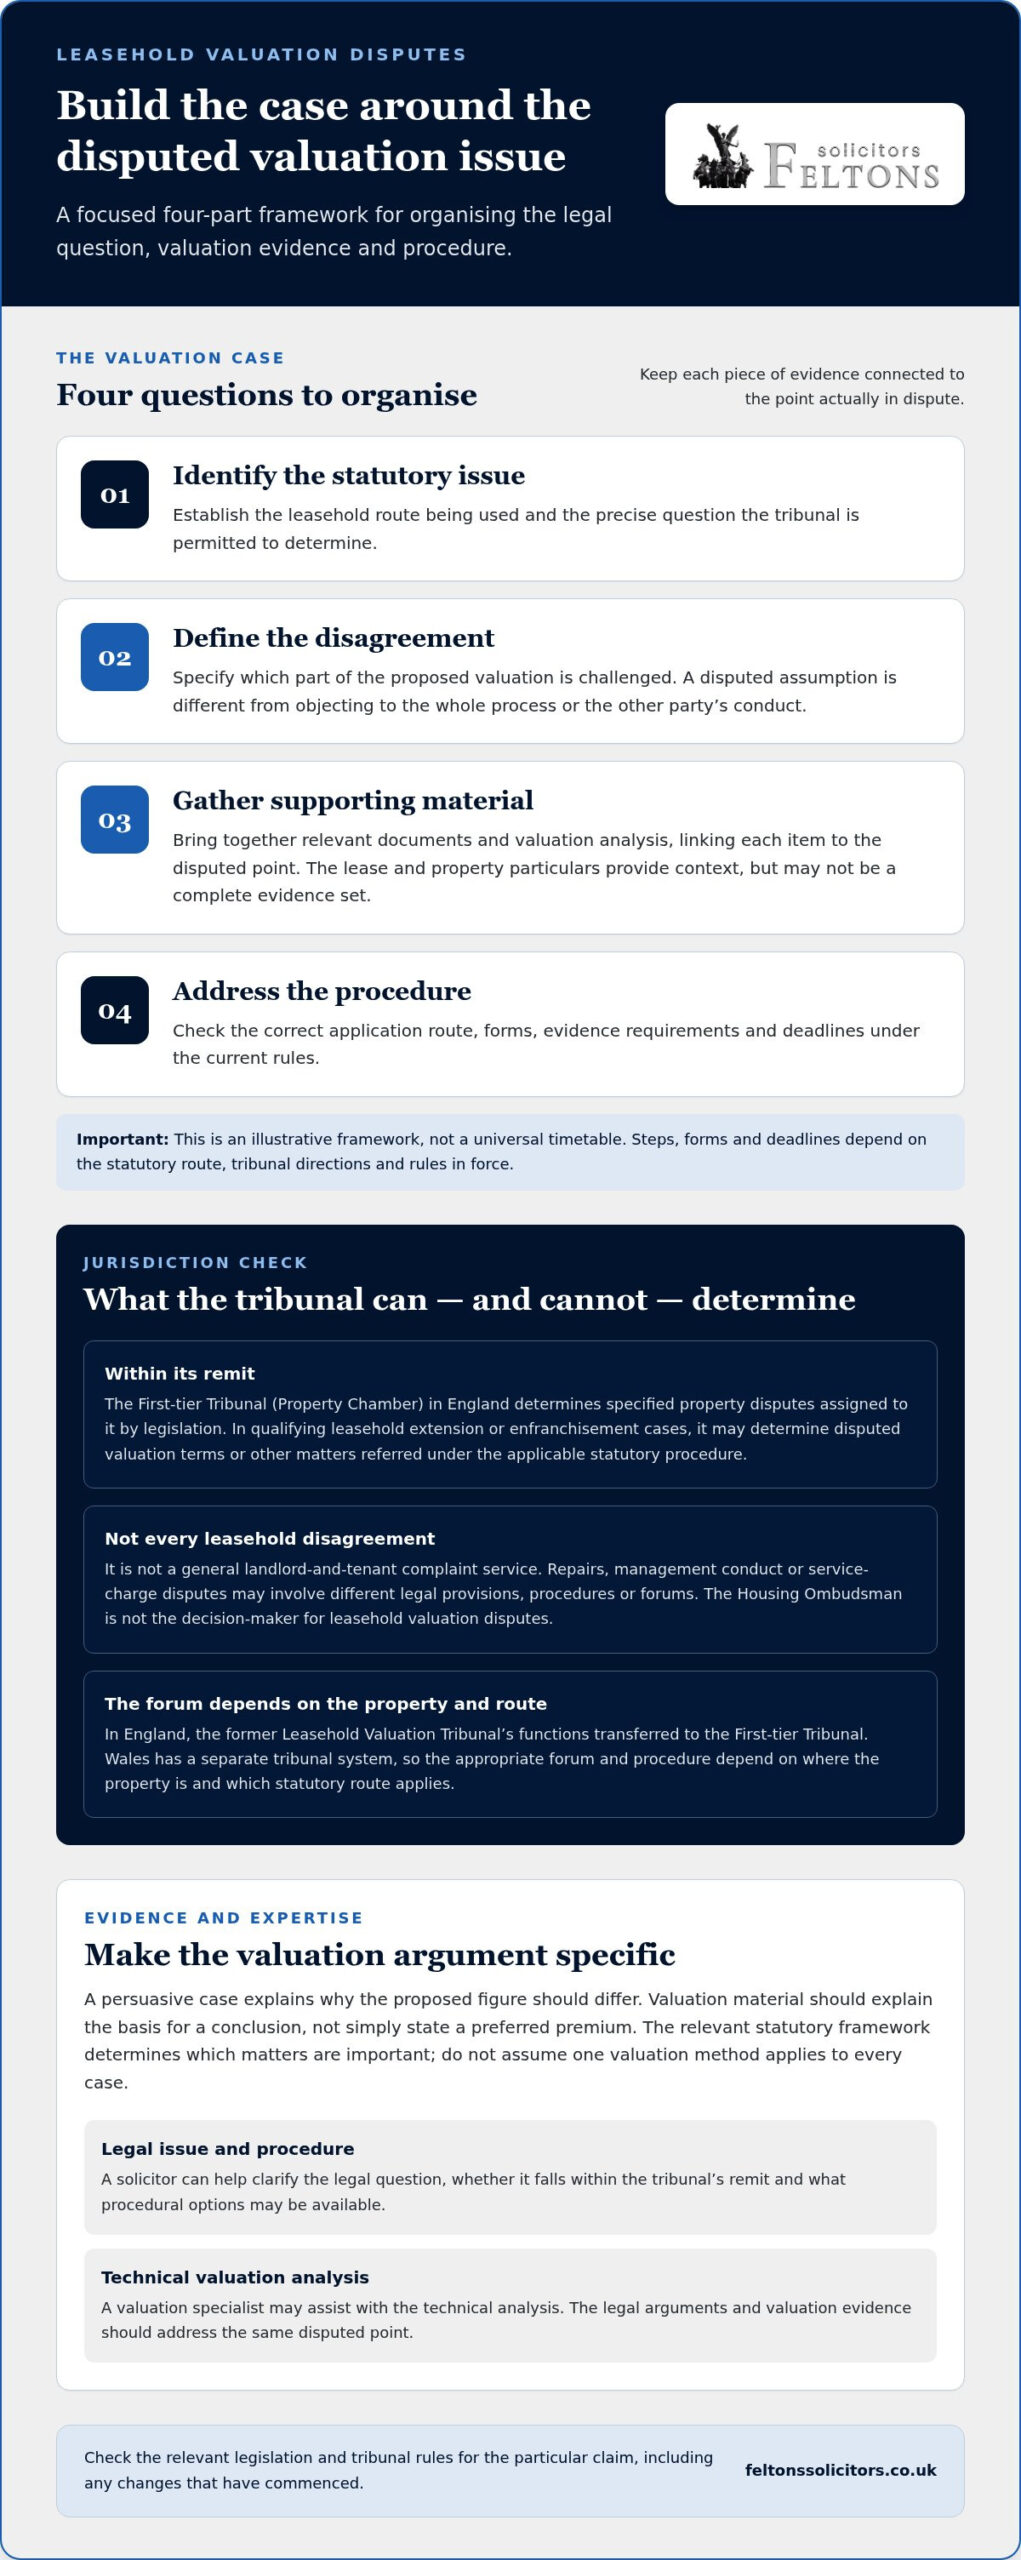
In England, the First-tier Tribunal (Property Chamber) considers matters within its statutory jurisdiction. Check the relevant legislation and tribunal rules against the particular claim, including any changes that have commenced. A practical way to organise the issues is:

  1. Identify the statutory issue. Establish the leasehold route being used and the question the tribunal is permitted to determine.
  2. Define the disagreement. Specify which part of the proposed valuation is challenged, rather than treating the whole figure as one unexplained difference.
  3. Gather supporting material. Assemble relevant documents and valuation analysis, linking each item to the disputed point.
  4. Address the procedure. Check the correct application route, forms, evidence requirements and deadlines under the current rules.

This is an illustrative framework, not a universal timetable. The steps, forms and deadlines depend on the statutory route, tribunal directions and rules in force. A solicitor can help clarify the legal issue and procedural options, while a valuation specialist may assist with the technical analysis. Leasehold reform valuation tribunal solicitors can also help ensure the legal arguments and valuation evidence address the same point.

How valuation evidence can support each party’s position

Valuation material should explain the basis for a conclusion, not simply state a preferred premium. Depending on the issue, the analysis may address assumptions or property characteristics that affect the calculation. The lease and property particulars provide important context, but may not be a complete evidence set. Other documents or expert analysis may be needed to address the specific disagreement. The statutory framework determines which matters are relevant, so do not assume one valuation method applies to every case.

For example, if the parties rely on different assumptions about a feature of the property or the lease, identify the difference, explain why it matters and support your position with relevant material. This gives the tribunal a reasoned comparison rather than a bare assertion that one figure is too high or too low.

Why statutory changes need careful checking

The Leasehold and Freehold Reform Act 2024 received Royal Assent on 24 May 2024, but enactment does not mean every provision applies immediately. As at October 2026, the reforms are being implemented in stages, and some key provisions require secondary legislation. Check the applicable valuation framework against commencement provisions and any relevant transitional rules before relying on a changed calculation.

An Act may be on the statute book before the provisions relevant to a particular valuation are in force. This can affect both the legal route and the valuation arguments. A tailored review can help establish which rules apply to the matter. Leasehold valuation legal support can help clarify the issue and the next procedural step.

Solicitor or direct representation: choosing support for a valuation tribunal dispute

There is no single right choice between handling a tribunal matter yourself and seeking solicitor input. Consider the legal and valuation issues, the evidence available, the procedural work involved and how confident you feel presenting your position. A focused review can clarify your options without assuming full representation is necessary.

Use these considerations as a starting point, then assess your particular case:

Factor Handling it directly Solicitor input
Issue complexity May feel manageable where the point is clearly defined and the route is understood. Can help clarify how the statutory route applies and frame the legal issue.
Evidence You organise the documents and explain how they support your position. A solicitor can help identify gaps, organise the case and liaise with valuation expertise where appropriate.
Procedure You take responsibility for understanding the relevant process and meeting its requirements. Legal advice can help interpret the applicable procedure and identify dates or steps that need attention.
Your confidence May suit someone comfortable communicating their case and managing formal correspondence. Can provide structure and support if the process or opposing arguments feel difficult to manage.

Legal advice can help you test the strengths and weaknesses of each position, consider the risks of continuing and assess whether further negotiation is sensible. It cannot guarantee a particular tribunal decision or ensure that representation reduces the overall cost. The scope of advice can vary, so understand what work is proposed and how it relates to your priorities before deciding how to proceed.

When tailored solicitor advice may be particularly useful

Advice may be especially useful if the statutory route is unclear, the valuation turns on contested assumptions or you’re unsure how to meet a procedural requirement. You may need help separating a legal disagreement from a technical valuation question, or assessing whether the evidence answers the other party’s case. These are examples, not legal tests. The benefit of an assessment is that it considers your circumstances before you commit to a course of action.

Questions to resolve before deciding on representation

Before choosing how much support you need, write down the precise issue, the other party’s stated position and any dates or directions that could affect the next step. Consider whether you need help with an initial case assessment, particular documents, negotiation or the tribunal process as a whole. Asking what the advice will cover and what work it involves helps you make a considered decision. A guide to leasehold enfranchisement and property rights can provide context for the statutory process.

Feltons Solicitors LLP advises on leasehold enfranchisement and extensions, alongside litigation and dispute resolution. A tailored assessment can clarify the issue, procedural options and a proportionate level of support. For leasehold valuation legal advice, provide the key documents and explain where the disagreement stands.
Leasehold Reform Valuation Tribunal Solicitors: A Practical Guide

Preparing documents and decisions for a leasehold valuation dispute

An organised record helps show how the disagreement developed and which evidence relates to the question the tribunal may need to decide. Gather the documents that appear relevant, then check them against the statutory route and the particular valuation issue. Not every item will matter in every case.

Depending on the circumstances, your starting file may include:

  • The lease and any relevant variations or related documents.
  • Formal notices and responses exchanged as part of the lease extension or enfranchisement process.
  • Valuation reports, calculations, supporting material and any revised figures.
  • Correspondence recording negotiations, explanations or points of disagreement.
  • Procedural documents, such as applications, directions or other tribunal communications, if proceedings have begun.

Organise evidence around the question the tribunal must determine. For each disputed figure or assumption, note what the other party says, your response and the documents that support it. A clear chronology makes changes in position easier to follow and helps distinguish agreed facts from matters still in dispute.

Organising the valuation record

Keep dated correspondence and copies of key documents together and in order. A simple index can identify each document, its date and the issue it relates to. Separate agreed facts, such as a recorded lease term, from contested valuation assumptions or calculations. Preserve original records and present material fairly: selective extracts or overstated conclusions can obscure the point you need to explain. If a document seems relevant, note why rather than assuming its significance is self-evident.

Assessing procedure, risk and possible resolution

Good preparation includes checking what must happen next. Filing requirements, forms, deadlines and costs rules can depend on the statutory route and current tribunal rules. Use current authoritative guidance for the relevant procedure. Do not rely on a date or process mentioned in an older document without checking that it applies to your case. If directions have been issued, make sure your working chronology reflects them.

Negotiation may remain practical while a dispute is being prepared, and a clearer record can help the parties understand where their positions differ. However, discussions should not be assumed to pause or replace a procedural requirement. Before taking an irreversible step, consider the possible consequences of proceeding, settling or changing course. Early legal advice can clarify the issue, evidence and options. Leasehold reform valuation tribunal solicitors may also help assess how the legal position relates to the valuation material, without promising a particular result or lower overall costs.

Feltons Solicitors LLP advises on leasehold enfranchisement and extensions, as well as litigation and dispute resolution. A measured assessment can help identify the key disagreement and practical next steps. Read about support for your leasehold valuation dispute.

How Feltons Solicitors can support leasehold reform valuation disputes

A leasehold valuation disagreement can affect important decisions about your home or property interests. Feltons Solicitors LLP advises on leasehold enfranchisement and extensions, property matters, litigation and dispute resolution. This experience can help bring the legal route and the practical dispute into focus, without assuming that every disagreement should proceed to a tribunal.

For those looking for leasehold reform valuation tribunal solicitors, support starts with understanding the specific matter. An assessment can consider the property issue, the figure or assumption in dispute, the other party’s position and the stage the matter has reached. The aim is to clarify available options and next steps, not to promise a particular outcome.

A pragmatic assessment of the dispute

Property law and dispute-resolution experience can inform a measured review of the relevant facts and documents. Depending on the circumstances, advice may consider whether the issue fits the statutory route, how the valuation arguments are framed, what evidence may be relevant and which procedural requirements need attention. The assessment can also consider whether further discussion with the other party remains practical alongside any formal steps that apply.

Property decisions often carry personal as well as financial weight. A clear explanation of strengths, uncertainties and possible routes forward can help you decide with a better understanding of the risks. Advice is tailored to the facts, available records, applicable law and procedural position. The right approach depends on those details; neither a tribunal application nor legal representation can guarantee a particular result.

Taking the next step with Feltons

To make an initial discussion more focused, explain the valuation issue, what the other party has said and whether you know of any important procedural dates or tribunal directions. Relevant documents may include the lease, valuation correspondence and formal notices, where applicable. You do not need to resolve every point in advance. A clear account of what you understand and what remains uncertain is a useful starting point.

For wider context, Feltons’ residential property law guide may help explain how a valuation question sits alongside other property rights and responsibilities. The guide cannot determine how the law applies to your particular dispute, but it may help you identify questions for a tailored assessment.

Feltons takes a pragmatic, supportive approach to leasehold and property disputes. Speak to Feltons about leasehold valuation legal support and explain the issue and documents you have available.

Choose your next step with a clearer view

A tribunal should be a considered route, not simply the next move when negotiations become difficult. Before acting, decide what you need to understand: whether the disputed point falls within the tribunal’s role, what evidence could address it, or which procedural choices remain open. That focus can make a conversation with leasehold reform valuation tribunal solicitors more useful, whether you’re weighing up advice or preparing to proceed.

Feltons’ work in leasehold enfranchisement and extensions, alongside litigation and dispute resolution, brings property and dispute experience to an individual assessment. The aim is pragmatic, tailored guidance that helps you understand your position and choose a course suited to the facts, without promising a particular outcome.

If you’re ready to discuss the issue, explain what you disagree with and what you hope to resolve. Discuss your leasehold valuation dispute with Feltons to get a clearer view of your next step.

Frequently Asked Questions

What does a leasehold valuation tribunal solicitor do?

A solicitor helps you understand the legal route, frame the issue and manage the legal aspects of a valuation dispute. They may review the claim and response, identify arguments that need evidence, explain procedural obligations and advise on possible settlement discussions. The specialist valuation assessment itself may require input from a valuer. The solicitor connects the legal case with the facts and helps you make informed decisions, but cannot guarantee a result.

Can the First-tier Tribunal decide a lease extension premium?

In England, the First-tier Tribunal (Property Chamber) may determine a disputed premium where the applicable statutory lease-extension route gives it jurisdiction and the matter is properly brought before it. The answer depends on the type of claim and the specific point in dispute. The tribunal’s role may differ depending on whether the parties disagree about the premium itself or another issue under the statutory process. Wales has a separate tribunal system.

Do I need a solicitor for a leasehold valuation tribunal?

No. Having a solicitor is not automatically required, and some people choose to present their own case. Whether that is practical depends on your understanding of the statutory process, the valuation dispute and the evidence. You might seek limited legal advice to assess a draft position or clarify a procedural question without asking a solicitor to handle every aspect. Consider the work involved and your confidence before deciding what support you need.

What evidence is needed for a leasehold valuation tribunal?

There is no single evidence bundle that suits every application. The material should relate to the specific valuation question and may include documents showing the basis of each party’s position, such as relevant lease provisions, formal notices, valuation reports or calculations. If a report relies on an assumption you dispute, identify that assumption and the material that supports your response. The tribunal’s directions and the applicable route determine what must be filed.

How long does a leasehold valuation tribunal case take?

There is no reliable fixed timeframe for every case. The duration can depend on the application route, the issues raised, the evidence required, tribunal directions and whether the parties reach agreement before a hearing. A case involving a narrow point may require different preparation from one with several disputed issues. Check current tribunal guidance and any directions in your proceedings for case-specific timings, and seek advice promptly if a date is unclear.

Can a leasehold valuation dispute be settled without a tribunal hearing?

Yes. Parties may reach agreement through negotiation, including after a formal application has been made. A settlement should clearly record what has been agreed and how it affects any ongoing tribunal steps. Do not assume discussions suspend a deadline or remove a procedural requirement; check the applicable rules and directions. Legal advice can help you assess proposed terms and understand the practical consequences before accepting them.

Can I appeal a First-tier Tribunal leasehold valuation decision?

An appeal may be possible, but it is not simply a chance to ask another tribunal to reconsider the valuation because you disagree with the result. The appeal route, grounds, permission requirements and time limits depend on the applicable rules and decision. Read the decision notice carefully, as it should explain relevant next steps. If you are considering an appeal, obtain advice promptly so the potential grounds and any deadline can be assessed.
Commercial Property Acquisition by an Overseas Company: UK Legal Guide

Commercial Property Acquisition by an Overseas Company: UK Legal Guide

Could an overseas company agree terms for a UK commercial property, only to find that a registration gap prevents the transfer being registered? It’s a practical risk: an overseas entity generally needs to be registered with Companies House and hold a valid Overseas Entity ID, or the Land Registry may refuse to register the property transfer. A commercial property acquisition overseas company buyers plan therefore needs the legal and compliance steps considered together from the outset.

Registration, company records and property due diligence can all affect the transaction. Preparing early helps you identify the information needed and deal with key requirements before they become obstacles. This guide covers the main stages, including overseas-entity registration, due diligence, conveyancing and the filing duties that follow registration.

Feltons Solicitors LLP advises on commercial conveyancing and registration of overseas entities, helping national and international clients coordinate these connected matters. This guide explains what to prepare, when each step arises and how tailored legal advice can help you move the transaction forward.

Key Takeaways

  • Clarify which UK jurisdiction the property is in and whether the buyer is an overseas entity, as this shapes the legal steps involved.
  • Prepare beneficial-owner and managing-officer information early to address registration and disclosure requirements.
  • Tailor due diligence to the property’s title, occupational arrangements, condition and intended commercial use.
  • Plan the commercial property acquisition overseas company process as a connected sequence, coordinating entity checks, property enquiries and conveyancing from the outset.
  • Joined-up legal advice can help organise company information, assess contractual issues and progress registration and conveyancing together.

Commercial property acquisition by an overseas company: what the transaction involves

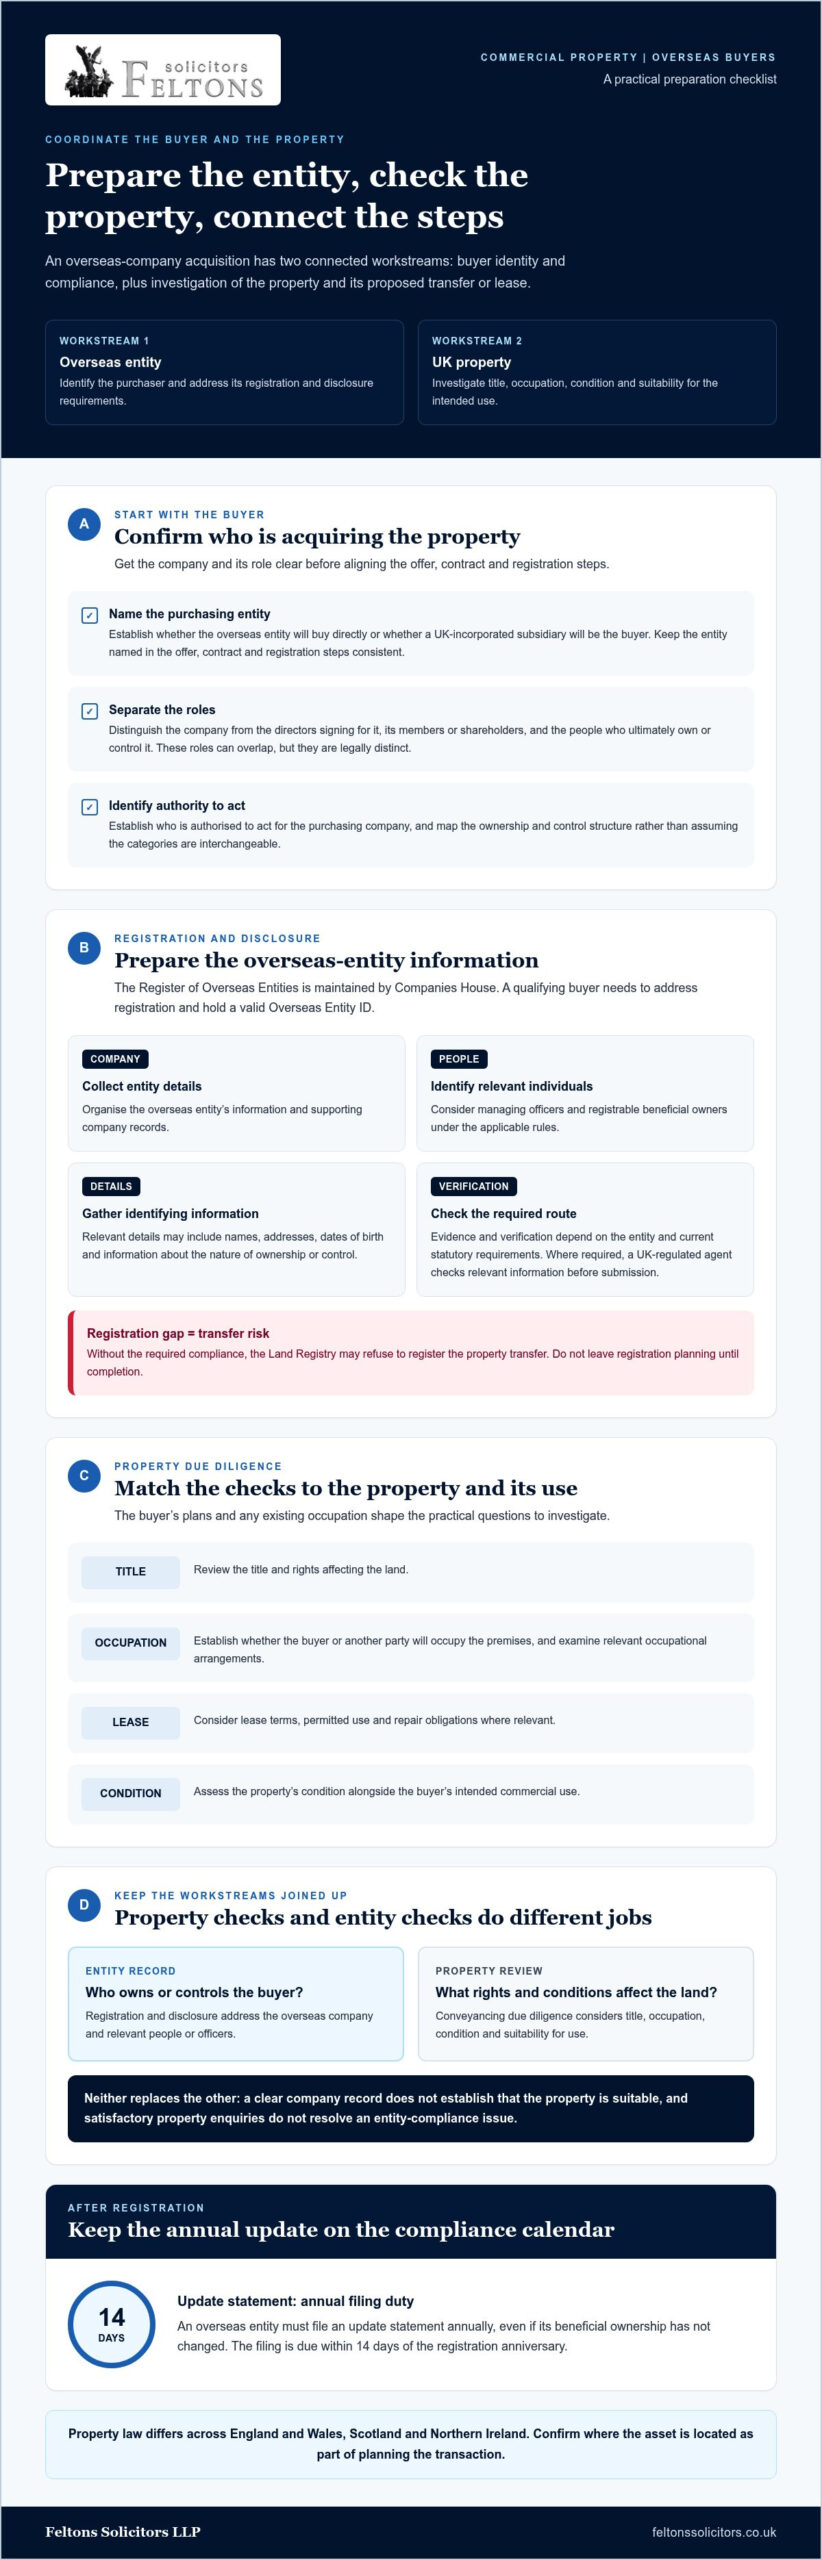
An overseas-company acquisition is a transaction in which an entity formed outside the UK buys or holds UK commercial land. The purchaser is the company, not the directors who sign documents on its behalf, its members or shareholders, or the people who ultimately own or control it. These roles can overlap, but they are legally distinct and may call for different information and checks.

This guide focuses on UK property. Land and property law differs across England and Wales, Scotland and Northern Ireland, so the location of the asset matters. For general background on the UK market, see the UK Real Estate Market Overview. A “commercial property acquisition overseas company” transaction involves two connected workstreams: checking the overseas buyer’s identity and compliance, and investigating the property while negotiating its transfer or lease.

Which overseas-company structure is buying the property?

An overseas entity may buy property directly in its own name. Alternatively, a group might use a UK-incorporated subsidiary as the buyer, creating a separate UK legal entity within the wider corporate structure. The choice can affect how ownership is organised and may have corporate, tax and financing consequences that depend on the buyer’s circumstances. There is no single structure that suits every purchaser. Identify the intended buyer early so the entity named in the offer, contract and registration steps is consistent.

What makes a commercial acquisition different?

Commercial due diligence depends on what the buyer plans to do with the premises and whether anyone already occupies them. An office bought for the buyer’s own business raises different practical questions from a warehouse acquired with an existing tenant, for example. The title, lease terms, permitted use, repair obligations and condition can all affect the buyer’s assessment of the property and the terms needed in the contract.

Keep these property questions separate from ownership disclosure. The property review concerns rights affecting the land, occupational arrangements and suitability for the intended use. Entity checks concern the overseas company and the people or officers relevant to its ownership and control. Neither replaces the other: a clear company record does not establish that the property is suitable, and satisfactory property enquiries do not resolve an entity-compliance issue.

  • Purchasing entity: establish which company will enter into the transaction and who is authorised to act for it.
  • Ownership and control: distinguish the company’s directors and members from the people who ultimately own or control it.
  • Property purpose: identify the planned use and whether the premises will be occupied by the buyer or another party.

Resolve these points together to give the transaction a clearer foundation. This helps align company information, property enquiries and contract arrangements before the buyer commits to a structure or timetable.

Overseas-entity registration and disclosure: the compliance questions to resolve

The Register of Overseas Entities (ROE), maintained by Companies House, records information about overseas entities that own or seek to acquire qualifying UK land. The regime was introduced by the Economic Crime (Transparency and Enforcement) Act 2022. For a qualifying buyer, registration and a valid Overseas Entity ID are important parts of the acquisition. Without compliance, the Land Registry may refuse to register the property transfer.

Registration is not a formality to leave until completion. The buyer needs to establish which overseas entity is acquiring the property, identify the people and officers whose details must be disclosed, and organise verification in line with the rules that apply to its ownership structure. These checks sit alongside, rather than replace, conveyancing due diligence. An entity’s registration record does not establish that the property title, lease arrangements or condition are satisfactory.

What information and verification may be required?

The application generally involves information about the overseas entity, its managing officers and any registrable beneficial owners. A beneficial owner is an individual or relevant legal entity that meets the statutory tests for owning or controlling the overseas entity. A managing officer is a person who manages the entity where the rules require their details. Directors, shareholders and beneficial owners are not automatically interchangeable categories, so examine the ownership structure rather than assume they are the same.

Relevant details may include names, addresses, dates of birth or other identifying information, as well as information about the nature of ownership or control. The evidence and verification route depend on the entity and the current statutory requirements. Where verification by a UK-regulated agent is required, that agent checks the relevant information before it is submitted. Different structures can involve several lines of ownership and control, so map the group structure and collect supporting company records early.

How can registration affect the acquisition timetable?

Check registration status as soon as the proposed buyer and transaction are identified. If the entity still needs to register, gathering information across a group with several ownership layers or overseas officers may require coordination. Running this work alongside offer negotiations and property enquiries can help avoid leaving a key compliance step until the parties are preparing to complete.

The practical link is clear: an overseas entity that must comply with the ROE needs the required registration status for the Land Registry to register the relevant property transaction. The precise restriction and how it applies depend on the circumstances and current rules, so review the buyer’s status and title requirements as part of the conveyancing process.

For a commercial property acquisition overseas company, aligning registration work with conveyancing helps keep entity information, verification and title registration on the same transaction plan. Feltons advises on overseas-entity registration and commercial conveyancing, coordinating these related steps and addressing the details of the ownership structure.

Commercial property due diligence for an overseas-company buyer

Property due diligence helps you understand what is being acquired, how it can be used and which obligations may continue after completion. Shape enquiries around the buyer’s plans: a property intended for its own operations may raise different priorities from an investment property with existing tenants. Keep this review separate from checks on the purchasing entity. Company registration does not establish that the property is suitable or that its title and occupation arrangements are acceptable.

Organise the work by linking each enquiry area to the decision it informs:

Enquiry area What to examine Decision it informs
Title and rights Ownership, title entries, access, restrictions and third-party interests Whether the buyer can obtain the rights and control it needs
Occupation Lease terms, rent position, tenant obligations and who occupies the premises Whether income, possession and continuing responsibilities fit the plan
Condition and environment Available building information and appropriate technical investigations Whether further assessment or contractual protection is needed
Intended use Planning history, permitted use and relevant building documents Whether the proposed activity appears compatible with the property information

Title, rights and occupational arrangements

Title review identifies the registered owner and the rights or restrictions recorded against the land. An access route, for example, may depend on rights benefiting the property, while a title restriction may affect how it can be dealt with. Third-party interests can also shape the buyer’s practical control. Conveyancing enquiries clarify what those entries mean for the proposed transaction and whether further information or contractual provisions should be considered.

If the property is let, examine the lease rather than relying only on a summary of the rental position. Relevant points include the term, rent, review provisions, repair and insurance obligations, permitted occupation and arrangements affecting the tenant’s use. The findings may inform negotiations, contractual protections or, if a concern cannot be resolved, a decision not to proceed.

Use, condition and transaction-specific risks

Start with the intended activity. A buyer planning to operate a particular business from the premises needs enquiries into whether the recorded planning position, permitted use and available building documents align with that plan. The precise enquiries depend on the site and proposed use. Legal review can identify issues in the available documents, but cannot replace specialist technical conclusions.

Condition and environmental investigations serve a different purpose from legal due diligence. Appropriate surveys and assessments can reveal matters that need specialist evaluation. A valuation considers the asset’s value for its purpose, while tax advice addresses the buyer’s particular structure and transaction. These workstreams should inform one another without being confused.

VAT also deserves early attention. If the seller has opted to tax the property, VAT may affect the purchase price and the SDLT calculation. The position depends on the transaction, so include it in tailored tax advice before finalising the commercial assumptions. A coordinated commercial property acquisition overseas company review connects title findings, occupation, intended use and tax questions to the buyer’s decision, rather than treating each enquiry in isolation.

Commercial Property Acquisition by an Overseas Company: UK Legal Guide

From offer to completion: a practical acquisition sequence

A clear sequence keeps company checks, property enquiries and contract decisions moving together. The steps below are a useful framework, not a fixed timetable. The transaction’s pace depends on the property, the buyer’s company information, the registration position and what due diligence reveals.

Before exchange: establish the buyer and investigate the asset

Before committing, confirm the exact entity that will buy the property and gather its constitutional documents, authority to act and relevant ownership information. At the same time, review the title and contract papers, arrange appropriate searches and consider the property’s commercial arrangements. Record issues that need negotiation, further investigation or specialist input so they can inform the decision to proceed.

  1. Identify the proposed buyer. Confirm the overseas entity’s legal name, place of incorporation and the people authorised to act for it. Make sure the proposed purchaser is consistent across the offer, company records and transaction documents.
  2. Review registration requirements early. Establish whether the entity needs to register with Companies House and whether it has the required Overseas Entity ID. If registration or verification is needed, coordinate that work with conveyancing rather than leaving it until the parties are ready to complete.
  3. Agree offer terms and obtain the papers. Clarify the proposed price, what is included in the sale, any occupation arrangements and the intended use. Request the contract pack and available property information so legal review can begin promptly.
  4. Investigate the property and the transaction. Review the title, searches, leases and other relevant documents, and arrange appropriate specialist enquiries. Compare the findings with the buyer’s plans, noting matters that may affect value, use, obligations or contract terms.
  5. Resolve key issues before exchange. Decide whether further information, contract changes or other protections are needed. Exchange is the point at which the parties enter into a binding contract on its terms, so address material concerns before making that commitment.

Exchange, completion and registration

Completion is when the transaction is carried out in accordance with the contract, including payment of the balance and transfer of the property. The conveyancer then deals with applicable post-completion filings and applies to register the transfer with the relevant land registry. Requirements depend on the property’s jurisdiction and the transaction. The sequence is straightforward in principle, but the supporting documents and compliance position must be in order.

  1. Prepare for completion. Confirm that contractual requirements, funds and documents are ready, and that the buyer’s registration position supports the intended transaction.
  2. Complete and register the transfer. Carry out the agreed completion steps, then submit the required application and supporting documents to the relevant land registry.

For more detail on ownership disclosures, the guide to overseas entity beneficial owner registration explains the information involved. Feltons coordinates registration and commercial conveyancing as part of a commercial property acquisition overseas company transaction. Speak to Feltons about your acquisition for tailored legal support with company information, property enquiries and contractual steps.

How Feltons can support an overseas-company commercial acquisition

A commercial purchase by an overseas entity brings together company information, property documents and contractual decisions. Feltons Solicitors LLP advises on commercial conveyancing and registration of overseas entities, including complex property transactions for national and international clients. Tailored legal advice can help you understand how these strands relate, identify the information to gather and focus on issues that may affect the proposed transaction.

The legal work can include considering the buyer’s entity details and registration position alongside the property papers, reviewing the contract and raising relevant conveyancing enquiries. This joined-up approach helps show where one issue may affect another. For example, proposed occupation arrangements may influence contract terms, while the identity of the purchasing entity informs registration work. The aim is pragmatic advice shaped around the transaction, not a promise of a particular outcome.

Coordinating registration and conveyancing advice

Clear responsibilities and organised documents can make a complex purchase easier to manage. The buyer’s team can identify who will provide company and ownership records, who can approve decisions, and how property enquiries and registration information will be gathered. Timely communication matters, particularly where information must come from people in different roles or jurisdictions.

The legal team can connect the entity review with the title, contract and occupational arrangements while keeping each workstream distinct. If the commercial decision involves weighing ownership against occupation under a lease, Feltons’ guide to commercial property law: buying versus leasing may help frame the issues for discussion. Tax, financing and technical questions may need input from the relevant specialists. Legal advice can identify where those questions intersect with the conveyancing process.

Preparing for an initial legal discussion

A focused first discussion is easier when the key facts are to hand. You do not need to resolve every issue in advance. A useful starting pack may include:

  • Entity details: the proposed buyer’s legal name, place of incorporation and available constitutional documents.
  • Ownership and authority information: a group structure or ownership chart, details of relevant officers and information about who can authorise the purchase.
  • Property particulars: the address, title information if available, sales particulars, draft contract papers and details of any existing lease or occupation.
  • Commercial objectives: the intended use, whether the buyer or a tenant will occupy the premises, and the key points the buyer wants the transaction to achieve.

These details help shape advice around the actual buyer and asset. They also make it easier to identify missing information, clarify priorities and organise next steps without assuming every acquisition follows the same route.

If you’re considering a commercial property acquisition overseas company structure, Feltons can advise on the proposed purchase. A discussion of the company, property and commercial objectives can help establish the appropriate conveyancing and overseas-entity registration work for your circumstances. Discuss your commercial property acquisition with Feltons.

Plan your next step with confidence

Turn your commercial objective into a clear legal plan. Consider what the property needs to achieve for your business or investment, which decisions are time-sensitive and who within your organisation can provide the required information. For a commercial property acquisition overseas company buyers pursue, this early alignment helps connect legal questions to the purpose of the purchase.

Feltons Solicitors LLP advises national and international clients on complex property matters, bringing commercial conveyancing and overseas-entity registration support together where the transaction calls for both. Advice can be tailored to the proposed buyer, property and contractual issues, while tax, finance or technical questions can be considered with the relevant specialists.

You do not need every detail resolved before seeking legal guidance. A discussion can help clarify priorities, identify useful documents and establish appropriate next steps for your circumstances. Discuss your commercial property acquisition with Feltons to understand the legal work involved.

Frequently Asked Questions

Can an overseas company obtain a UK commercial mortgage?

Does buying UK commercial property through an overseas company create UK tax obligations?

It can. The acquisition may involve property transaction taxes, and VAT can affect the price and tax calculation if the seller has opted to tax the property. Tax obligations can also arise during ownership or on disposal; non-resident companies pay UK Corporation Tax on gains from disposing of UK commercial property. The treatment depends on the transaction, structure and property location, so obtain tailored tax advice before relying on projected costs or returns.

Is beneficial ownership information on the Register of Overseas Entities publicly available?

Yes, the Register of Overseas Entities is publicly searchable and provides information about overseas entities and registrable beneficial owners. Not every personal detail is necessarily displayed: some information, such as residential addresses and full dates of birth, is treated differently from public-facing details, and protection arrangements may apply in defined circumstances. Buyers should distinguish the information that must be supplied to Companies House from what the public can view.

How often must an overseas entity update its information?

An overseas entity must file an update statement with Companies House annually, even if its beneficial ownership information has not changed. The filing is due within 14 days of the anniversary of its registration. The statement confirms or updates the relevant information for the entity. Keep a record of the registration anniversary and review ownership and officer details in good time so changes can be accurately reported through the applicable process.

Can an overseas company buy UK property through a UK subsidiary instead?

Yes. A group may choose to have a UK-incorporated subsidiary purchase the property rather than having the overseas parent acquire it directly. The subsidiary is a separate legal entity, so its authority, funding and contractual position need to be considered in their own right. Using a UK company does not automatically remove other disclosure or compliance obligations. The right structure depends on the group’s commercial, tax and financing circumstances.

Does an overseas company need a UK bank account to buy commercial property?

A UK bank account is not necessarily a legal prerequisite to owning commercial property, but the buyer needs a workable arrangement for paying the purchase funds and meeting any lender or transaction requirements. The conveyancer will need to understand the source and movement of funds as part of the transaction checks. If funds will arrive from an overseas account, agree the practical transfer arrangements early, particularly where currency conversion or several group entities are involved.

What happens if an overseas company’s ownership changes after it acquires property?

A change in ownership or control may affect the information the company must disclose to Companies House. The entity should assess whether the change makes someone a registrable beneficial owner or alters details already on the Register, then report it through the applicable update process. Keep supporting records and review the effect promptly rather than waiting for a future sale or refinancing. Changes can also have separate corporate, financing or tax implications.

Overseas Corporate Property Compliance: UK Guide 2026

Overseas Corporate Property Compliance: UK Guide 2026

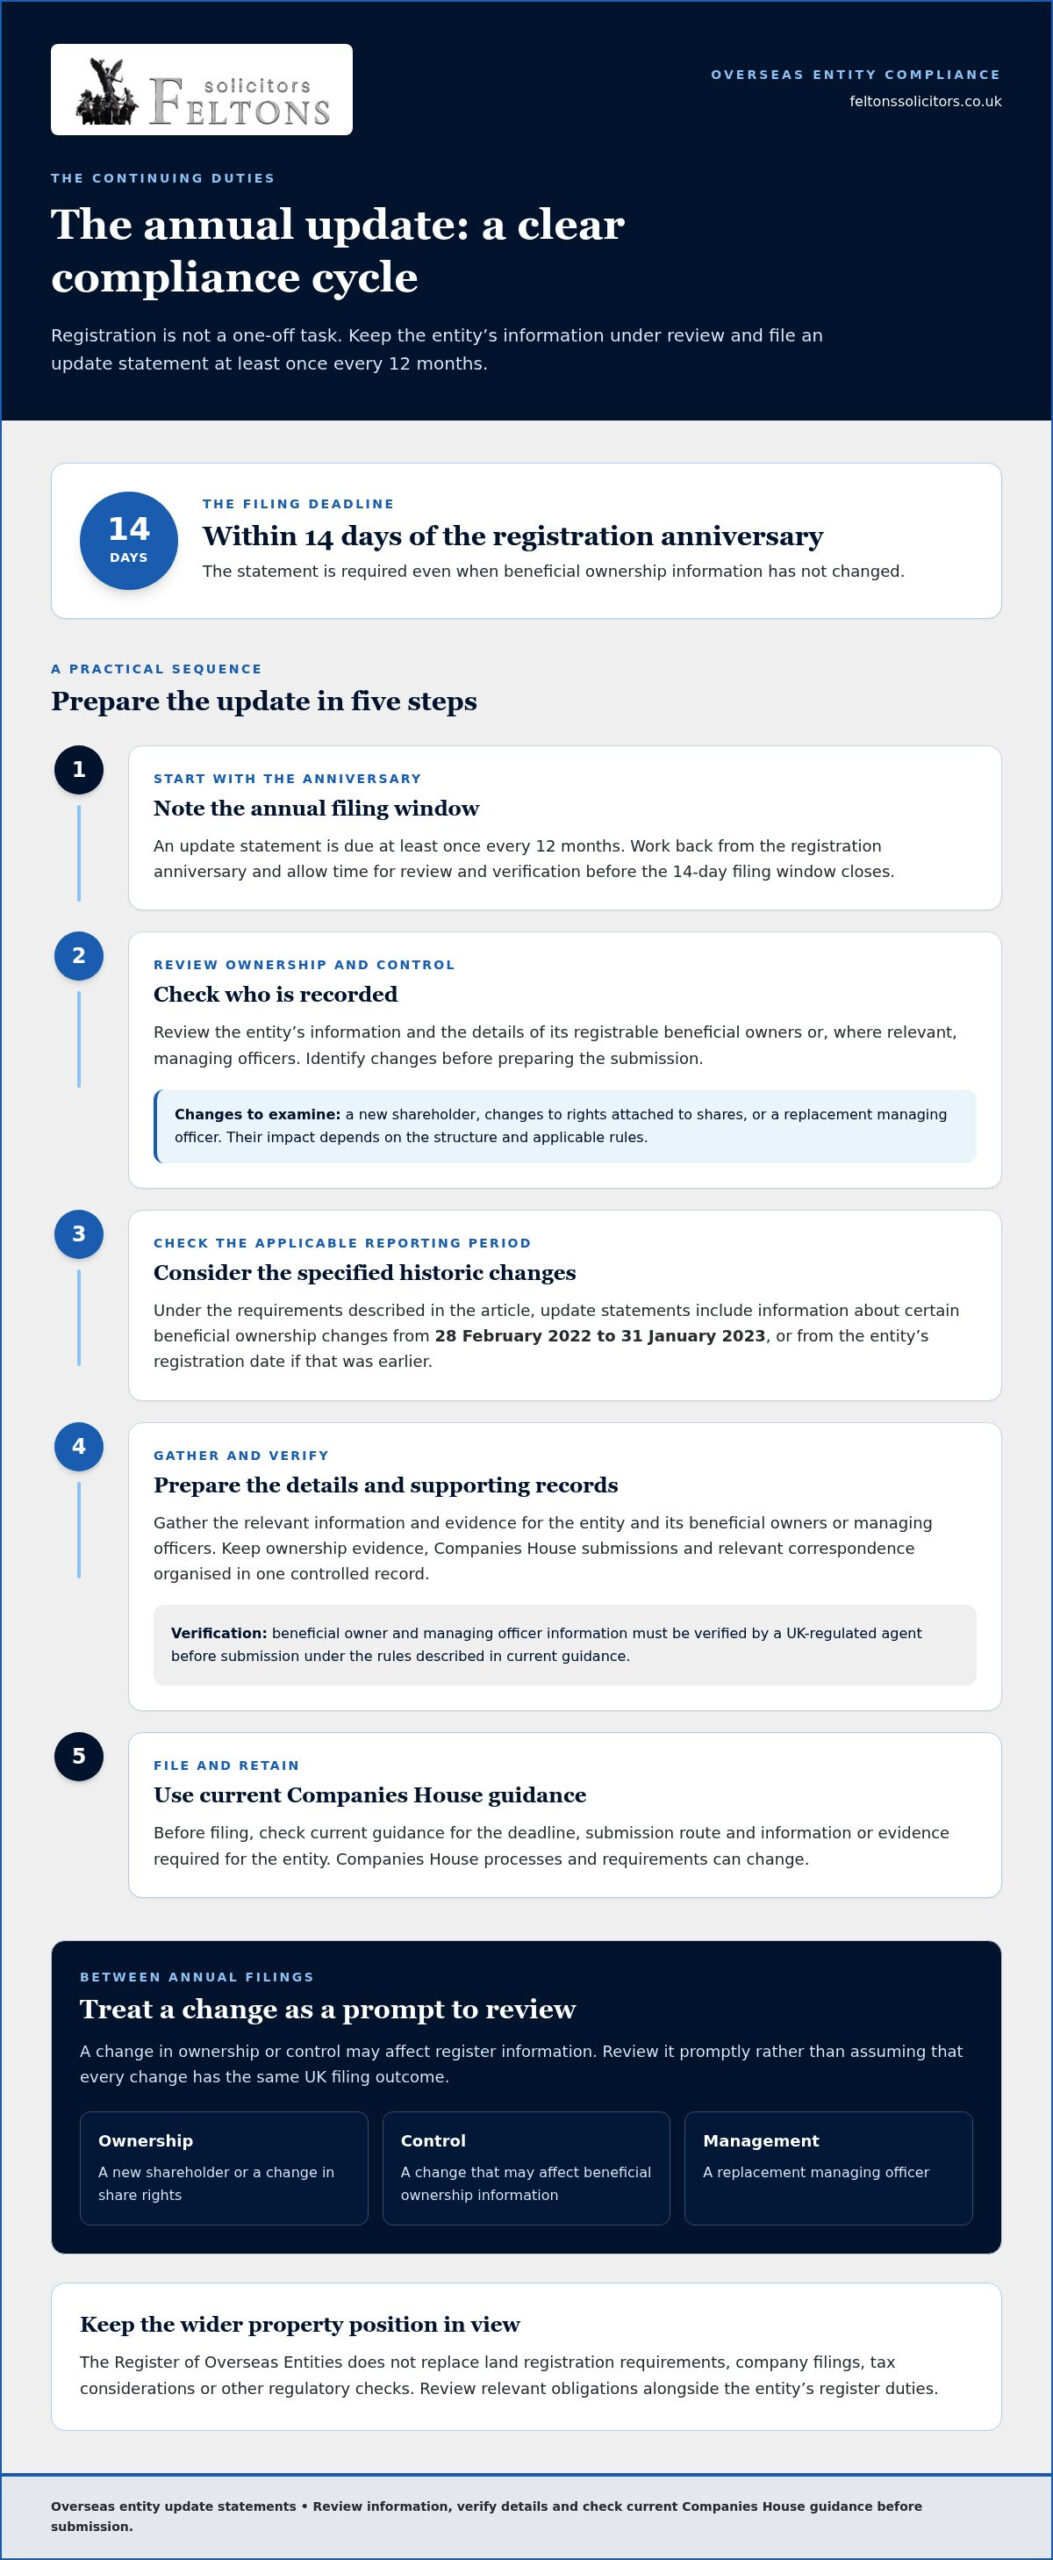
What if registering an overseas entity is only the start of its UK property compliance duties? For organisations that own UK land, overseas corporate property ownership compliance is an ongoing process. A registered entity must file an update statement with Companies House at least once every 12 months, even if its beneficial ownership hasn’t changed. The filing is due within 14 days of the registration anniversary.

It can be difficult to know which changes to report, what records to keep current and how the Register of Overseas Entities fits alongside other obligations. These duties are connected: a change in ownership or company information may require a prompt review.

This guide explains the continuing duties linked to overseas entity registration and the events that may need attention. It distinguishes register requirements from land, company, tax and sanctions considerations, and compares a structured self-managed process with tailored legal support. Feltons Solicitors LLP advises on registration of overseas entities and property matters, helping owners assess how the requirements apply to their particular structure.

Key Takeaways

  • Treat overseas corporate property ownership compliance as an ongoing process, not a one-off registration task.
  • Review changes to beneficial ownership, registrable beneficial owners or managing officers promptly to assess whether reporting action is needed.
  • Use the property’s status, planned transaction and ownership structure as prompts for a focused compliance review.
  • Keep ownership evidence, Companies House submissions and relevant correspondence organised in one controlled record.
  • Compare self-managed administration with tailored legal support to decide how best to coordinate register duties with property transactions.

Overseas corporate property ownership compliance: why registration is only the starting point

Overseas corporate property ownership compliance covers the continuing legal and administrative responsibilities that may apply when an overseas entity owns or seeks to acquire relevant UK land. Registration with Companies House is a key part of the process, but it doesn’t keep the entity’s information accurate by itself or satisfy every obligation connected with its company, property or wider regulatory position. Beyond entity filings, managing UK real estate also requires meeting statutory physical building and safety requirements, where organisations like Oxford Environmental Consultants (OEC) assist with multi-disciplinary property compliance.

Start by identifying the legal owner, the property and the relevant UK jurisdiction. An entity may have registered correctly when it acquired a property, but later changes to its ownership or management could mean its register information needs attention. The position may also depend on when the land was acquired and what type of interest is held. Treating registration as a one-off task risks overlooking these continuing responsibilities.

What does the Register of Overseas Entities do?

Companies House maintains the Register of Overseas Entities under the Economic Crime (Transparency and Enforcement) Act 2022. Its purpose is to make information available about overseas entities that own or seek to acquire qualifying UK land, including details of registrable beneficial owners or, where relevant, managing officers. The register helps show who stands behind an entity, but it doesn’t replace checks on the entity’s wider obligations.

For the registration regime, qualifying land interests include freehold ownership and certain leasehold interests. A non-UK legal entity may need to register before it can complete a relevant property transaction. The position should be assessed against the property’s location, legal interest and transaction history. Companies House registration doesn’t replace land registration requirements, company filings, tax considerations or other regulatory checks—cross-border owners managing international real estate portfolios, for example, often engage accounting firms such as Tax Partners to address jurisdiction-specific tax liabilities and deductible financing costs alongside corporate transparency filings.

Which overseas property owners should review their position?

Overseas legal entities should review their position if they already hold relevant UK land, plan to acquire it or are preparing to dispose of it. This means checking the entity’s ownership chain and the information recorded about its beneficial owners or managing officers. A sale or other transaction can bring register status into focus, so assess it as part of property planning rather than waiting until completion is imminent.

Individual overseas buyers shouldn’t assume that the Register of Overseas Entities applies to them in the same way simply because they live outside the UK. The regime is directed at overseas legal entities. The correct analysis depends on who legally owns the property and how that ownership is structured.

Historic holdings also need careful review. The registration rules have retrospective application for certain properties acquired on or after 1 January 1999 in England and Wales, and 8 December 2014 in Scotland. Transitional circumstances and jurisdiction-specific land rules can affect the analysis, including where a property has changed hands or the ownership structure has been reorganised. Check current Companies House guidance and assess the facts before drawing a conclusion.

  • Identify the registered owner: distinguish the overseas entity from individuals or other entities in its ownership chain.
  • Establish the property history: record where the land is, the interest held and when it was acquired.
  • Review the wider position: consider register duties alongside relevant land, company and regulatory requirements.

The continuing compliance duties overseas entities need to understand

For an overseas entity on the Register of Overseas Entities, compliance means keeping its recorded information current, not simply retaining a registration number. The annual update statement is the recurring Companies House filing used to confirm or update information about the entity and its beneficial owners or managing officers. It’s required at least once every 12 months, even if nothing has changed.

Annual updates and keeping information accurate

The filing deadline is 14 days after the anniversary of the entity’s registration. Before preparing a submission, review the ownership and control information, identify any changes and gather the relevant details. The review should also account for applicable reporting rules: under current requirements, update statements include information about certain beneficial ownership changes from 28 February 2022 to 31 January 2023, or the entity’s registration date if earlier.

Companies House processes and requirements can change. Before filing, check its current guidance for the deadline, submission route and information or evidence required for the entity. Beneficial owner and managing officer information must be verified by a UK-regulated agent before submission under the rules described in current guidance. Allow time for review and verification rather than leaving these steps until the deadline.

Changes, verification and supporting records

A change in ownership or control should trigger a compliance review. A new shareholder, a change in the rights attached to shares or a replacement managing officer could affect information relevant to the register. The impact depends on the structure and applicable rules, so don’t assume that a change in the overseas entity’s home jurisdiction has the same UK filing outcome in every case.

Keep a clear record of the change, the assessment, supporting documents and any submission or correspondence. The evidence and verification steps depend on the filing and current requirements. Companies House identity-verification reforms are separate from verification of Register of Overseas Entities information. As implementation can depend on role and timing, check current Companies House guidance before deciding who must verify their identity or when.

Register duties are only one part of the picture. Tax reporting, filings required in the entity’s place of incorporation and registration of the land itself are separate matters, each with its own rules and processes. For land registration context, HM Land Registry Practice Guide 78 is an official reference. Requirements can vary according to the property’s UK jurisdiction and the transaction.

A disciplined process makes overseas corporate property ownership compliance easier to manage: assign responsibility for monitoring changes, maintain an organised evidence file and diarise the annual review. Where the ownership chain or a property transaction raises questions, tailored advice on overseas entity registration can help connect register information with the particular structure and property circumstances.

How compliance considerations differ by ownership structure and property situation

Begin the review with the event under consideration: a purchase, continued ownership or a proposed disposal. Each raises different questions about the entity’s registration position, ownership information and the property transaction. The correct compliance steps depend on the entity’s structure and the property’s history.

Acquiring, holding or disposing of UK property

Use the comparison below to organise an initial review. It helps identify issues, but it doesn’t determine whether a particular filing or restriction applies. The answer depends on the facts, current rules and the property’s jurisdiction.

Situation Questions to investigate
Proposed acquisition Is the buyer a legal entity incorporated outside the UK? What type of land interest is being acquired, and what registration and transaction steps apply before completion?
Existing holding When and where was the property acquired? Has the ownership or control structure changed since acquisition, and is the recorded information consistent with the current position?
Proposed disposal What is the entity’s current register status? Do the title, entity details and ownership records align, and are any additional steps needed for the planned transaction?

Land transaction work and Register of Overseas Entities duties are related, but they are not interchangeable. A purchase or sale involves property-specific conveyancing and land registration considerations as well as a review of the entity’s register obligations. The steps can vary across England and Wales, Scotland and Northern Ireland. Don’t assume registration alone resolves every transaction requirement, or that the same restriction applies in every case. Companies House guidance on the Register of Overseas Entities provides an official overview of the regime.

Ownership chains, beneficial owners and managing officers

Direct ownership may make it easier to identify the entity that holds the property, but the underlying ownership and control still need review. With layered ownership, trace the chain through each organisation and consider who ultimately owns or controls the overseas entity. A change at an upper level can prompt a fresh assessment of the information relevant to the register, even if the entity named on the property title hasn’t changed.

In plain English, a beneficial owner is a person or entity identified under the applicable rules as owning or exercising relevant control. A managing officer is someone who manages the overseas entity where the rules require that information to be reported. These roles are distinct, and a person’s involvement in day-to-day decisions doesn’t by itself settle how they should be classified. Review the facts against current guidance.

Trusts, nominees and arrangements involving several connected entities need particular care. The legal documents, actual control and reporting requirements may all matter. As part of overseas corporate property ownership compliance, record the structure clearly and assess changes before a property transaction advances. Coordinated advice on overseas entity registration and property matters can help bring these considerations together without treating a general framework as a determination of a specific case.

Overseas Corporate Property Compliance: UK Guide 2026

A practical overseas corporate property compliance checklist

A repeatable process helps identify filing or information issues before they become urgent. For overseas corporate property ownership compliance, assign responsibility, maintain a reliable record trail and treat changes in ownership or property plans as prompts for review. Use the checklist below as a practical sequence, adapting it to the entity’s structure and circumstances.

  1. Identify the legal owner. Record the overseas entity’s full name and jurisdiction of incorporation, along with the UK property it owns or plans to acquire. Check that the entity name matches the relevant corporate and property records.
  2. Map the ownership and control structure. Set out each organisation in the ownership chain and identify the individuals or entities whose ownership or control may be relevant. Note any layers, trusts, nominees or management arrangements that need closer analysis.
  3. Confirm the registration position. Review whether the entity is registered and whether the information held is consistent with its current structure. For practical background on identifying reportable individuals, see this guide to overseas entity beneficial owner registration. For an overview of the registration process connected with UK property, consult the guide to registering an overseas entity for UK property.
  4. Monitor changes and transactions. Treat ownership restructuring, changes to beneficial owners or managing officers, acquisitions and proposed disposals as review triggers. A trigger calls for assessment; it doesn’t automatically mean register information or a filing must change.
  5. Diarise recurring reviews. Assign a named person or team to monitor relevant filing dates and review the ownership information at planned intervals. Include a handover process so responsibility doesn’t disappear when staff or advisers change.

Build a repeatable review and record-keeping process

Keep a controlled file containing ownership charts, source documents used to assess control, submitted forms, confirmation records and relevant correspondence. A dated record of who reviewed the information and what action followed can help the organisation respond consistently if questions arise. Restrict access appropriately and keep the file organised instead of relying on scattered email threads or one person’s notes.

Set retention and access practices with reference to the requirements for each record type. Don’t assume one retention period suits every document. The aim is a usable audit trail that can be updated as the entity, its ownership or its property position changes.

Recognise when a change needs legal assessment

Flag changes early, particularly when a transaction is being planned alongside a restructure or change in control. A review can establish whether the event affects reported information, requires supporting evidence or raises a separate property registration question. Feltons Solicitors LLP advises on overseas entity registration and property matters. Explore legal support for overseas entity registration for a tailored assessment of the next steps.

Some entities manage routine administration internally, using a clear ownership record and a reliable system for monitoring filing dates. This keeps the process close to the people who understand the organisation’s structure. It also requires someone with the time and knowledge to recognise when a change may affect the register or a planned property transaction.

Tailored legal support can help where ownership is layered, the property has a complex history, or an acquisition or disposal is approaching. A legal review can connect Companies House information with the entity’s ownership structure and relevant property-law questions. Neither approach suits every owner. The right level of support depends on the facts, internal resources and confidence in assessing the requirements.

What tailored legal support can help coordinate

Advice can clarify how registration and ownership information relate to the entity’s particular structure, and identify property-law questions arising from its holdings or planned transactions. This can be especially useful when a change in control occurs alongside a restructure or proposed sale, and it isn’t clear which records or obligations need review.

Feltons Solicitors LLP advises on registration of overseas entities and property matters, including conveyancing. This combined perspective helps organise a review around the entity’s circumstances rather than treating register information and property activity as unrelated tasks. Legal advice can guide the process, but the entity remains responsible for the accuracy and completeness of information it provides for its filings.

Prepare for a focused conversation about compliance

A focused discussion is easier when the relevant material is ready. Consider gathering:

  • the overseas entity’s name, jurisdiction of incorporation and registration details
  • property details, including location, ownership history and any planned transaction
  • ownership charts, relevant company records and information about beneficial owners or managing officers
  • previous Register of Overseas Entities submissions and related correspondence

Note known changes, such as a transfer of ownership interests, a new managing officer or a proposed acquisition or disposal. This gives the review a practical starting point and helps distinguish changes that need investigation from routine updates. Keep source documents organised, but don’t assume every event automatically requires a filing: its effect depends on the facts and current requirements.

For tailored guidance on overseas corporate property ownership compliance, discuss overseas entity and property compliance with Feltons Solicitors LLP. A conversation can clarify how the register, ownership structure and property plans fit together, so the next steps can be considered in context.

Make your next compliance decision with clarity

Build overseas corporate property ownership compliance into the organisation’s forward planning rather than treating it as an isolated filing task. Before an ownership change or property decision moves ahead, identify unanswered questions about the entity’s structure, register information and legal steps connected with the property. A considered review helps the organisation decide what needs attention and who should take responsibility.

Where a matter involves both register duties and a property transaction, joined-up advice can bring those considerations into one discussion. Feltons Solicitors advises on overseas entity registration and residential and commercial conveyancing, so relevant points can be considered in the context of the organisation’s property plans.

If you’d value a clear assessment of your circumstances, discuss your overseas entity and property compliance matter with Feltons Solicitors. A considered next step can make a complex issue more manageable and help you plan with confidence.

Frequently Asked Questions

Does an overseas company have to register to own property in the UK?

An overseas legal entity may need to register if it owns or intends to acquire qualifying UK land, such as a freehold or a lease exceeding seven years. The requirement depends on the entity and the property interest, so “overseas company” alone doesn’t settle the question. An individual buying in their own name shouldn’t assume the entity rules apply to them. Review the ownership documents and relevant jurisdiction before proceeding.

Is overseas entity registration a one-off requirement?

No. Registration establishes the entity’s entry on the Register of Overseas Entities, but the entity must continue to review and report its information under the applicable rules. For example, a change in who owns or controls the entity may need assessment even if the property title remains unchanged. Registration also doesn’t remove separate company, tax or land-registration responsibilities, which should be managed separately.

What changes must an overseas entity report to Companies House?

Changes to beneficial ownership, registrable beneficial owners or managing officers should prompt a review of the entity’s register information. The entity should also consider whether other recorded details have changed and what the current filing rules require. For instance, a new parent company may alter the ownership chain even though the registered property-owning entity stays the same. Assess the change against current Companies House guidance before preparing a submission.

How often must an overseas entity update its information?

An overseas entity must file an update statement at least once every 12 months, including when there’s been no change to its beneficial owners. The filing deadline is 14 days after the anniversary of its registration. Keep the anniversary and submission deadline in a central calendar, allowing time to review the information and complete any required verification. Check current Companies House filing guidance before submitting, as processes can change.

Can an overseas entity sell UK property if its register information is out of date?

It may face a restriction that prevents a property transaction from proceeding. A restriction on the title can affect an entity’s ability to sell, lease or charge the property while it remains non-compliant. The practical effect depends on the title, the property’s jurisdiction and the entity’s circumstances. If a sale is planned, review the register position early alongside the conveyancing work rather than assuming an update can wait until completion.

What is the difference between an overseas entity and a beneficial owner?

An overseas entity is the non-UK legal body that may own or acquire qualifying UK land. A beneficial owner is a person or entity identified under the applicable rules as owning or exercising relevant control over that body. For example, a property title may name an overseas company, while another organisation or individual further up its ownership chain may be relevant to beneficial ownership reporting.

Do the same overseas property ownership rules apply across the UK?

No. The Register of Overseas Entities is UK-wide, but land registration systems and property processes differ between England and Wales, Scotland, and Northern Ireland. The property’s location and acquisition history can therefore affect the review. For example, retrospective registration dates differ for some holdings in England and Wales and in Scotland. Don’t assume that a conclusion about a property in one jurisdiction applies to another.

Can a solicitor help manage overseas corporate property compliance?

Yes. A solicitor can help assess how the entity’s ownership structure, register information and property plans fit together, and advise on relevant registration and conveyancing questions. This can be particularly useful before a proposed transaction or after a change in control. Legal support can help organise the review, but the entity remains responsible for ensuring the information it provides is accurate. Feltons Solicitors LLP advises on overseas entity registration and property matters.