
What if the most expensive bill your family ever receives is the one that arrives after you’re gone? With the Treasury projected to collect over £9 billion in inheritance tax by the 2026/27 tax year, the “death tax” is no longer a concern reserved solely for the ultra-wealthy. Frozen thresholds and recent reforms to business reliefs mean that many more family homes and hard-earned savings are now falling into the 40% tax net. Partnering with experienced inheritance tax planning solicitors is no longer just a financial precaution; it’s a vital step in ensuring your life’s work isn’t dismantled by HMRC.
It’s natural to feel a sense of unease when faced with complex HMRC rules and the fear of losing a legacy you’ve spent decades building. We believe that your estate should benefit those you love most, rather than being unnecessarily eroded by tax liabilities. This article explores how expert planning can safeguard your assets, providing a clear strategy to minimise tax and protect the family home. We will preview the latest 2026 legislative changes, from business property relief caps to upcoming shifts in pension treatment, giving you the peace of mind that your family legacy remains secure and intact.
Key Takeaways
- Understand how frozen thresholds and rising property values are placing more family homes within the 40% tax bracket than in previous decades.
- Learn to navigate the specific rules surrounding the Nil Rate Band and Residence Nil Rate Band to protect up to £1 million of your joint estate.
- Discover the strategic benefits of the “Seven-Year Rule” and trusts to gift assets whilst ensuring your beneficiaries receive the maximum possible benefit.
- Identify why engaging expert inheritance tax planning solicitors is essential for conducting a comprehensive audit of your property, pensions, and global interests.
- Explore how a boutique, people-first approach to estate planning provides the discreet and tailored guidance necessary to secure a complex family legacy.
Understanding Inheritance Tax: The “Silent” Threat to Your Estate
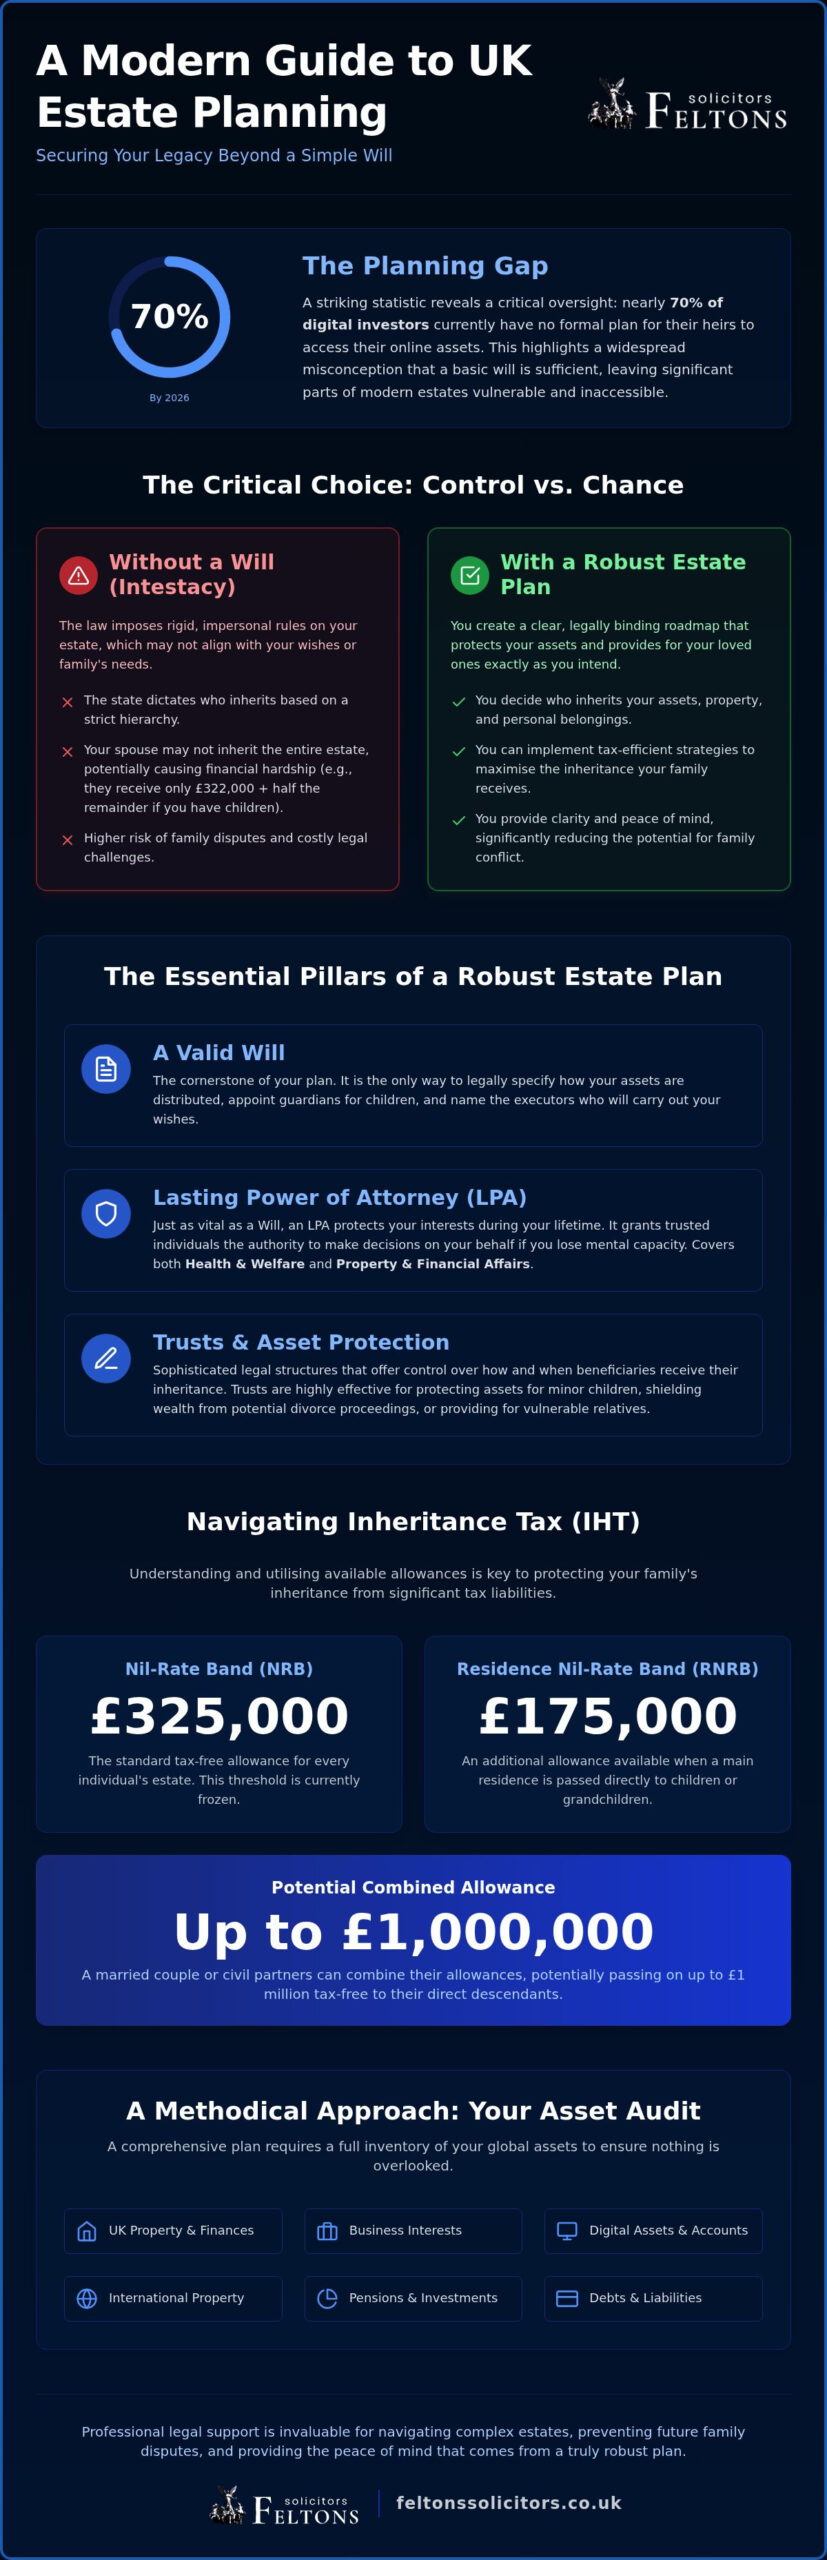
Inheritance tax is often described as a voluntary levy because, with the right guidance from inheritance tax planning solicitors, its impact can be significantly mitigated. At its core, Inheritance Tax in the United Kingdom is a 40% charge on the portion of an estate that exceeds specific thresholds. While it was once perceived as a tax for the wealthy, rising property values combined with frozen tax-free bands have created a “fiscal drag” that pulls many more families into the net. This isn’t just a financial burden; it’s a source of profound emotional stress. Without a clear plan, beneficiaries may face difficult decisions or even disputes amongst themselves during an already painful time. The Nil Rate Band is the foundational tax-free allowance in the UK, providing a baseline of £325,000 that can be passed on without triggering a tax charge.
The 40% Factor: Why Doing Nothing is Costly
The 40% rate is one of the highest tax figures in the UK, yet it only applies to the value above your available allowances. For many, the most significant allowance is the Residence Nil Rate Band (RNRB), which provides an additional £175,000 when a main residence is left to direct descendants. However, if your estate’s value exceeds these combined limits, the tax bill can be staggering. We often see families forced into a “fire sale” of the family home or cherished assets simply to satisfy HMRC within the required six-month window. This pressure is entirely avoidable with proactive organisation. It’s about protecting the liquidity of your estate so your loved ones aren’t left with a debt they can’t afford to pay.
Common Misconceptions About Estate Planning
A frequent mistake is the belief that inheritance tax only affects the super-rich. With the average UK house price rising, many modest estates now exceed the thresholds. Another misconception is that a basic Will is enough. While a Will is vital for stating who gets what, it rarely addresses the complex tax structures needed to preserve wealth over generations. Finally, many assume that gifting assets is a simple, immediate solution. In reality, gifts are subject to strict rules and can lead to unexpected tax charges if not handled with professional care. Engaging inheritance tax planning solicitors ensures these nuances are managed, protecting your legacy from avoidable erosion whilst giving you the confidence that your affairs are in order.
Key Thresholds and Reliefs: The Framework of UK Tax Planning
Effective tax planning begins with a clear understanding of the allowances available to you. Every individual in the UK currently benefits from a Nil Rate Band (NRB) of £325,000. This is the amount you can pass on to your beneficiaries entirely tax-free amongst other potential exemptions. When a main residence is involved, the Residence Nil Rate Band (RNRB) provides an additional £175,000 allowance, provided the property is left to direct descendants like children or grandchildren. For married couples and civil partners, these allowances are even more powerful. Any unused portion of a deceased partner’s NRB or RNRB can be transferred to the survivor, effectively doubling the tax-free threshold. You can find the most recent updates on these figures in the official government IHT guidance.
Accurate valuation is the cornerstone of a robust estate plan. This is particularly true for complex assets such as property with leasehold interests. The value of a leasehold property can fluctuate significantly based on the remaining term of the lease, making it essential to obtain professional valuations that HMRC will accept. Our inheritance tax planning solicitors work closely with property experts to ensure every asset is accounted for at its true market value, preventing overpayment or future disputes with the tax office whilst ensuring full compliance.
The Role of the Family Home in Your Estate
The family home is often a person’s most valuable asset. By combining both the NRB and the RNRB, a couple can potentially pass on up to £1 million without triggering an inheritance tax bill. It’s vital to be aware of the tapering rules; for estates valued at more than £2 million, the RNRB is reduced by £1 for every £2 the estate’s value exceeds this threshold. If your estate includes significant property holdings, you might find our residential property law guide helpful for understanding how ownership structures impact your tax position.
Specialist Reliefs for Business and Agricultural Assets
For business owners and farmers, the landscape changed significantly in April 2026. Business Property Relief (BPR) and Agricultural Property Relief (APR) can provide up to 100% relief on qualifying assets, but this is now capped at a combined £2.5 million per person. Value exceeding this cap generally receives 50% relief. To qualify, assets must meet strict criteria, such as being a trading business rather than an investment company. Meticulous documentation is required to satisfy HMRC that these reliefs apply. If you’re concerned about how these caps affect your commercial interests, it’s wise to review your estate planning with a specialist who understands both the legal and commercial nuances.
Bespoke Strategies: Gifts, Trusts, and Lifetime Planning
Lifetime planning is about taking proactive steps today to ensure your family’s future is unburdened by tax liabilities. One of the most effective tools used by inheritance tax planning solicitors is the Potentially Exempt Transfer (PET). This allows you to gift assets of any value, which then become exempt from tax if you survive for seven years from the date of the transfer. Beyond simple gifts, you might consider leaving at least 10% of your net estate to a qualifying charity. This altruistic choice reduces the standard 40% inheritance tax rate to 36% across your entire taxable estate, potentially saving your family a significant sum whilst supporting a cause you value. For many, life insurance remains a cornerstone of a robust strategy. When a policy is written into a Trust, the payout doesn’t form part of your taxable estate; instead, it provides immediate liquidity for your beneficiaries to settle any IHT bill without the need to sell the family home.
Utilising Trusts to Protect Assets and Control Distribution
Trusts offer a sophisticated way to remove assets from your estate whilst maintaining a level of influence over how and when they are distributed. A Discretionary Trust allows you to appoint trustees who decide which beneficiaries receive funds, providing flexibility for changing family circumstances. Alternatively, a Life Interest Trust can protect a spouse’s right to live in a property whilst ensuring the capital eventually passes to children. You can find more detail on these structures in our guide to estate planning. These arrangements require precise legal drafting to ensure they remain compliant with HMRC’s evolving rules and provide the protection your family needs.
The Nuances of Gifting and Taper Relief
Not all gifts are subject to the seven-year rule. Every individual has an annual exemption of £3,000, which can be carried forward for one year if unused. Small gifts of up to £250 to any number of people and specific wedding gifts are also immediately exempt. When larger gifts are made, Taper Relief applies if you survive between three and seven years. This relief reduces the tax rate on the gift itself on a sliding scale, though it’s a common misconception that it reduces the value of the gift for the purposes of the nil-rate band. The UK government’s guide to Inheritance Tax provides the specific percentage breakdowns for these periods. It’s vital to avoid a “Gift with Reservation of Benefit” (GROB). This occurs if you give an asset away, such as your home, but continue to use it without paying a full market rent. HMRC will treat such assets as if they never left your estate, potentially negating your entire planning strategy. Our inheritance tax planning solicitors ensure your gifts are structured correctly to avoid these common pitfalls.

The Planning Process: How Inheritance Tax Solicitors Organise Your Affairs
Organising a complex estate requires a methodical approach that balances technical legal requirements with your personal family values. Expert inheritance tax planning solicitors act as a sophisticated guide, leading you through a structured process designed to provide clarity and security. This journey begins with a comprehensive audit of your global estate. We examine everything from residential and commercial property holdings to pension funds and interests in overseas entities. By understanding the full scope of your assets, we can identify potential tax exposures that a more superficial review might miss, which is why the involvement of inheritance tax planning solicitors is so vital.
Once the audit is complete, the focus shifts to your specific family goals. This people-first philosophy ensures the resulting strategy reflects your priorities, whether that’s protecting a business for the next generation or ensuring a spouse is provided for. The planning then moves through three critical implementation phases:
- Drafting and Updating: We refine your Will to incorporate tax-efficient structures, such as the trusts discussed in previous sections.
- Active Implementation: This involves setting up lifetime gift programmes or establishing trusts to remove assets from the taxable estate whilst retaining necessary control.
- Continual Oversight: A legacy is not static. We schedule regular reviews to ensure your plan remains effective as tax laws evolve or your personal circumstances change.
Collaborating with Financial Advisors
We believe the best results are achieved through professional synergy. Whilst our role focuses on legal asset protection and the drafting of complex documents, financial advisors provide the investment strategy and product selection. We frequently collaborate with a client’s existing professional network to ensure the legal framework and financial investments work in perfect harmony. This holistic approach ensures that no aspect of your wealth is left vulnerable to avoidable tax “bites.” If you’re ready to begin this process, you can contact our specialist team today for a discreet consultation.
Reviewing Your Plan: Adapting to Change
Life rarely follows a linear path. Major milestones such as marriage, the birth of grandchildren, or a change in business ownership necessitate an immediate review of your IHT strategy. Significant life events like separation also require careful handling to protect assets from being unnecessarily depleted. In such cases, consulting a divorce and financial arrangements lawyer ensures that your estate plan remains robust even during periods of personal transition. Regular reviews also safeguard your legacy against shifts in government policy, ensuring that your tax-mitigation strategies remain fully compliant with the latest HMRC rules.
Why Choose Feltons Solicitors for Your IHT Planning?
Choosing the right inheritance tax planning solicitors is a decision that impacts generations. Since our establishment in 2010, Feltons Solicitors LLP has positioned itself as a sophisticated guide for families seeking to protect their wealth. We offer a boutique service level that prioritises personal connection over high-volume processing. This means you aren’t just another file; you’re a partner whose legacy we are committed to safeguarding. Our national service handles complex, international-scale matters with the same quiet confidence we bring to every consultation. We take pride in our “plain English” approach. We believe that professional authority shouldn’t be inaccessible. By stripping away unnecessary legalese, we ensure you feel informed and in control of your financial future.
A unique advantage of our firm is the synergy between our private client work and our deep expertise in residential and commercial property law. Most inheritance tax liabilities are tied to property value. Our background in conveyancing and leasehold matters allows us to provide pragmatic, high-standard advice that other firms might overlook. We understand the nuances of valuation and the legal structures required to protect property assets effectively. This dual expertise ensures that your most valuable assets are managed with precision and care.
A People-First Philosophy to Legal Care
Legal work is essentially about human impact. We adopt a people-first philosophy, recognising that estate planning can be a sensitive or stressful process. Our team acts as a calm, steady presence, guiding you through the technicalities with empathetic reassurance. We value traditional professional integrity, yet we embrace modern efficiency to deliver results that are both thorough and timely. Building a personal rapport is central to our method. It allows us to understand the specific goals of your family, ensuring the strategy we build is truly bespoke. You deserve a solicitor who listens as much as they advise.
A Discreet Partner for High-Net-Worth Individuals
For high-net-worth individuals, privacy is paramount. We act as a discreet partner, handling high-value estates with the utmost confidentiality. Our experience extends to complex matters such as overseas entity beneficial owner registration, ensuring that international property interests are fully compliant and tax-efficient. We handle the intricacies of global assets so you don’t have to. Protecting your legacy is a serious responsibility. We invite you to begin this journey with a confidential consultation, where we can discuss your priorities in a secure and professional environment. Your peace of mind is our primary objective.
Securing Your Legacy for the Generations to Come
Protecting your hard-earned assets from the 40% inheritance tax levy requires more than just a simple Will; it demands a proactive and highly organised strategy. We’ve explored how frozen thresholds and rising property values have made expert planning essential for modern families. By utilising bespoke tools such as lifetime gifting and carefully structured trusts, you can ensure your beneficiaries receive the maximum benefit from your estate whilst maintaining your family’s financial harmony.
As a firm established in 2010, Feltons Solicitors LLP provides a boutique service that combines national expertise with a deeply personal touch. We specialise in property-linked estate planning, ensuring that the unique complexities of your home and commercial interests are fully addressed. Choosing the right inheritance tax planning solicitors is the first step towards achieving lasting peace of mind. Our team is here to act as your sophisticated guide, providing the discreet and pragmatic advice you need to navigate HMRC’s evolving rules.
Secure your family’s future—contact Feltons Solicitors LLP today for bespoke inheritance tax advice. You’ve spent a lifetime building your legacy; let us help you ensure it is protected for those who matter most.
Frequently Asked Questions
Is inheritance tax planning legal and compliant with HMRC?
Yes, inheritance tax planning is entirely legal and compliant with HMRC when it focuses on legitimate tax mitigation. This involves utilising statutory reliefs and exemptions, such as the nil-rate bands or business property relief, to reduce the tax burden on your estate. It’s fundamentally different from tax evasion, which is illegal. Our inheritance tax planning solicitors ensure that every strategy implemented is transparent, professionally documented, and adheres strictly to the latest UK legislation.
Can I avoid inheritance tax by giving my house to my children now?
Gifting your home to your children whilst you continue to live there is usually ineffective for tax purposes. HMRC views this as a “Gift with Reservation of Benefit.” Unless you pay a full market rent to your children, the property remains part of your estate for tax calculations. This rule prevents individuals from artificially reducing their estate’s value whilst still enjoying the benefits of the asset. Proper planning requires more sophisticated legal structures.
What is the seven-year rule for inheritance tax?
The seven-year rule applies to Potentially Exempt Transfers, which are lifetime gifts that fall outside your estate if you survive for seven years. If you die within this period, the gift is added back into your estate’s value. Taper relief may reduce the tax rate on the gift if you survive at least three years, but it doesn’t reduce the value of the gift itself. It’s a complex sliding scale that requires meticulous record-keeping.
How much can I leave to my children tax-free in 2026?
In 2026, an individual can typically pass on up to £500,000 tax-free, provided their estate includes a main residence left to direct descendants. This total includes the £325,000 Nil Rate Band and the £175,000 Residence Nil Rate Band. For married couples or civil partners, these allowances can be combined to allow up to £1 million to be passed on without triggering a tax charge. However, these thresholds are subject to tapering for larger estates.
Do I need a solicitor for inheritance tax planning or can I do it myself?
Whilst it’s possible to attempt estate planning yourself, the risks of costly errors are exceptionally high. HMRC’s rules are intricate, and a single mistake in a trust deed or gift record can negate your entire strategy. Engaging inheritance tax planning solicitors provides the security of professional indemnity and ensures your plan is bespoke to your family’s needs. We provide the sophisticated guidance necessary to navigate these complex legal frameworks whilst prioritising your family’s harmony.
What happens if I die without a Will or an inheritance tax plan?
Dying without a Will or plan means your estate is distributed according to the laws of intestacy. This often results in assets passing to people you didn’t intend to benefit and can lead to a much higher tax bill. Without professional organisation, your family may lose out on valuable reliefs like the Residence Nil Rate Band, potentially forcing the sale of the family home to pay HMRC. It leaves your legacy to chance.
Can business owners claim relief on their company assets?
Yes, business owners can claim Business Property Relief on qualifying trading assets. However, as of April 2026, 100% relief is capped at a combined £2.5 million per person for business and agricultural property. Any value exceeding this threshold only receives 50% relief. This change makes it essential for business owners to review their succession plans to ensure their commercial interests remain protected under the new rules. Proactive restructuring may be necessary to preserve value.
How does the Residence Nil Rate Band work if I sell my home to move into care?
If you sell your home to move into care or a smaller property, you may still be eligible for “downsizing additions” to the Residence Nil Rate Band. This relief ensures you aren’t penalised for moving to a less valuable home later in life. Provided the original property was your main residence and you leave assets of equivalent value to your direct descendants, you can often still claim the full allowance. It provides vital flexibility for elderly homeowners.