Inheritance Tax Planning Solicitors: Protecting Your Family Legacy in 2026

Inheritance Tax Planning Solicitors: Protecting Your Family Legacy in 2026

What if the most expensive bill your family ever receives is the one that arrives after you’re gone? With the Treasury projected to collect over £9 billion in inheritance tax by the 2026/27 tax year, the “death tax” is no longer a concern reserved solely for the ultra-wealthy. Frozen thresholds and recent reforms to business reliefs mean that many more family homes and hard-earned savings are now falling into the 40% tax net. Partnering with experienced inheritance tax planning solicitors is no longer just a financial precaution; it’s a vital step in ensuring your life’s work isn’t dismantled by HMRC.

It’s natural to feel a sense of unease when faced with complex HMRC rules and the fear of losing a legacy you’ve spent decades building. We believe that your estate should benefit those you love most, rather than being unnecessarily eroded by tax liabilities. This article explores how expert planning can safeguard your assets, providing a clear strategy to minimise tax and protect the family home. We will preview the latest 2026 legislative changes, from business property relief caps to upcoming shifts in pension treatment, giving you the peace of mind that your family legacy remains secure and intact.

Key Takeaways

  • Understand how frozen thresholds and rising property values are placing more family homes within the 40% tax bracket than in previous decades.
  • Learn to navigate the specific rules surrounding the Nil Rate Band and Residence Nil Rate Band to protect up to £1 million of your joint estate.
  • Discover the strategic benefits of the “Seven-Year Rule” and trusts to gift assets whilst ensuring your beneficiaries receive the maximum possible benefit.
  • Identify why engaging expert inheritance tax planning solicitors is essential for conducting a comprehensive audit of your property, pensions, and global interests.
  • Explore how a boutique, people-first approach to estate planning provides the discreet and tailored guidance necessary to secure a complex family legacy.

Understanding Inheritance Tax: The “Silent” Threat to Your Estate

Inheritance tax is often described as a voluntary levy because, with the right guidance from inheritance tax planning solicitors, its impact can be significantly mitigated. At its core, Inheritance Tax in the United Kingdom is a 40% charge on the portion of an estate that exceeds specific thresholds. While it was once perceived as a tax for the wealthy, rising property values combined with frozen tax-free bands have created a “fiscal drag” that pulls many more families into the net. This isn’t just a financial burden; it’s a source of profound emotional stress. Without a clear plan, beneficiaries may face difficult decisions or even disputes amongst themselves during an already painful time. The Nil Rate Band is the foundational tax-free allowance in the UK, providing a baseline of £325,000 that can be passed on without triggering a tax charge.

The 40% Factor: Why Doing Nothing is Costly

The 40% rate is one of the highest tax figures in the UK, yet it only applies to the value above your available allowances. For many, the most significant allowance is the Residence Nil Rate Band (RNRB), which provides an additional £175,000 when a main residence is left to direct descendants. However, if your estate’s value exceeds these combined limits, the tax bill can be staggering. We often see families forced into a “fire sale” of the family home or cherished assets simply to satisfy HMRC within the required six-month window. This pressure is entirely avoidable with proactive organisation. It’s about protecting the liquidity of your estate so your loved ones aren’t left with a debt they can’t afford to pay.

Common Misconceptions About Estate Planning

A frequent mistake is the belief that inheritance tax only affects the super-rich. With the average UK house price rising, many modest estates now exceed the thresholds. Another misconception is that a basic Will is enough. While a Will is vital for stating who gets what, it rarely addresses the complex tax structures needed to preserve wealth over generations. Finally, many assume that gifting assets is a simple, immediate solution. In reality, gifts are subject to strict rules and can lead to unexpected tax charges if not handled with professional care. Engaging inheritance tax planning solicitors ensures these nuances are managed, protecting your legacy from avoidable erosion whilst giving you the confidence that your affairs are in order.

Key Thresholds and Reliefs: The Framework of UK Tax Planning

Effective tax planning begins with a clear understanding of the allowances available to you. Every individual in the UK currently benefits from a Nil Rate Band (NRB) of £325,000. This is the amount you can pass on to your beneficiaries entirely tax-free amongst other potential exemptions. When a main residence is involved, the Residence Nil Rate Band (RNRB) provides an additional £175,000 allowance, provided the property is left to direct descendants like children or grandchildren. For married couples and civil partners, these allowances are even more powerful. Any unused portion of a deceased partner’s NRB or RNRB can be transferred to the survivor, effectively doubling the tax-free threshold. You can find the most recent updates on these figures in the official government IHT guidance.

Accurate valuation is the cornerstone of a robust estate plan. This is particularly true for complex assets such as property with leasehold interests. The value of a leasehold property can fluctuate significantly based on the remaining term of the lease, making it essential to obtain professional valuations that HMRC will accept. Our inheritance tax planning solicitors work closely with property experts to ensure every asset is accounted for at its true market value, preventing overpayment or future disputes with the tax office whilst ensuring full compliance.

The Role of the Family Home in Your Estate

The family home is often a person’s most valuable asset. By combining both the NRB and the RNRB, a couple can potentially pass on up to £1 million without triggering an inheritance tax bill. It’s vital to be aware of the tapering rules; for estates valued at more than £2 million, the RNRB is reduced by £1 for every £2 the estate’s value exceeds this threshold. If your estate includes significant property holdings, you might find our residential property law guide helpful for understanding how ownership structures impact your tax position.

Specialist Reliefs for Business and Agricultural Assets

For business owners and farmers, the landscape changed significantly in April 2026. Business Property Relief (BPR) and Agricultural Property Relief (APR) can provide up to 100% relief on qualifying assets, but this is now capped at a combined £2.5 million per person. Value exceeding this cap generally receives 50% relief. To qualify, assets must meet strict criteria, such as being a trading business rather than an investment company. Meticulous documentation is required to satisfy HMRC that these reliefs apply. If you’re concerned about how these caps affect your commercial interests, it’s wise to review your estate planning with a specialist who understands both the legal and commercial nuances.

Bespoke Strategies: Gifts, Trusts, and Lifetime Planning

Lifetime planning is about taking proactive steps today to ensure your family’s future is unburdened by tax liabilities. One of the most effective tools used by inheritance tax planning solicitors is the Potentially Exempt Transfer (PET). This allows you to gift assets of any value, which then become exempt from tax if you survive for seven years from the date of the transfer. Beyond simple gifts, you might consider leaving at least 10% of your net estate to a qualifying charity. This altruistic choice reduces the standard 40% inheritance tax rate to 36% across your entire taxable estate, potentially saving your family a significant sum whilst supporting a cause you value. For many, life insurance remains a cornerstone of a robust strategy. When a policy is written into a Trust, the payout doesn’t form part of your taxable estate; instead, it provides immediate liquidity for your beneficiaries to settle any IHT bill without the need to sell the family home.

Utilising Trusts to Protect Assets and Control Distribution

Trusts offer a sophisticated way to remove assets from your estate whilst maintaining a level of influence over how and when they are distributed. A Discretionary Trust allows you to appoint trustees who decide which beneficiaries receive funds, providing flexibility for changing family circumstances. Alternatively, a Life Interest Trust can protect a spouse’s right to live in a property whilst ensuring the capital eventually passes to children. You can find more detail on these structures in our guide to estate planning. These arrangements require precise legal drafting to ensure they remain compliant with HMRC’s evolving rules and provide the protection your family needs.

The Nuances of Gifting and Taper Relief

Not all gifts are subject to the seven-year rule. Every individual has an annual exemption of £3,000, which can be carried forward for one year if unused. Small gifts of up to £250 to any number of people and specific wedding gifts are also immediately exempt. When larger gifts are made, Taper Relief applies if you survive between three and seven years. This relief reduces the tax rate on the gift itself on a sliding scale, though it’s a common misconception that it reduces the value of the gift for the purposes of the nil-rate band. The UK government’s guide to Inheritance Tax provides the specific percentage breakdowns for these periods. It’s vital to avoid a “Gift with Reservation of Benefit” (GROB). This occurs if you give an asset away, such as your home, but continue to use it without paying a full market rent. HMRC will treat such assets as if they never left your estate, potentially negating your entire planning strategy. Our inheritance tax planning solicitors ensure your gifts are structured correctly to avoid these common pitfalls.

Inheritance Tax Planning Solicitors: Protecting Your Family Legacy in 2026

The Planning Process: How Inheritance Tax Solicitors Organise Your Affairs

Organising a complex estate requires a methodical approach that balances technical legal requirements with your personal family values. Expert inheritance tax planning solicitors act as a sophisticated guide, leading you through a structured process designed to provide clarity and security. This journey begins with a comprehensive audit of your global estate. We examine everything from residential and commercial property holdings to pension funds and interests in overseas entities. By understanding the full scope of your assets, we can identify potential tax exposures that a more superficial review might miss, which is why the involvement of inheritance tax planning solicitors is so vital.

Once the audit is complete, the focus shifts to your specific family goals. This people-first philosophy ensures the resulting strategy reflects your priorities, whether that’s protecting a business for the next generation or ensuring a spouse is provided for. The planning then moves through three critical implementation phases:

  • Drafting and Updating: We refine your Will to incorporate tax-efficient structures, such as the trusts discussed in previous sections.
  • Active Implementation: This involves setting up lifetime gift programmes or establishing trusts to remove assets from the taxable estate whilst retaining necessary control.
  • Continual Oversight: A legacy is not static. We schedule regular reviews to ensure your plan remains effective as tax laws evolve or your personal circumstances change.

Collaborating with Financial Advisors

We believe the best results are achieved through professional synergy. Whilst our role focuses on legal asset protection and the drafting of complex documents, financial advisors provide the investment strategy and product selection. We frequently collaborate with a client’s existing professional network to ensure the legal framework and financial investments work in perfect harmony. This holistic approach ensures that no aspect of your wealth is left vulnerable to avoidable tax “bites.” If you’re ready to begin this process, you can contact our specialist team today for a discreet consultation.

Reviewing Your Plan: Adapting to Change

Life rarely follows a linear path. Major milestones such as marriage, the birth of grandchildren, or a change in business ownership necessitate an immediate review of your IHT strategy. Significant life events like separation also require careful handling to protect assets from being unnecessarily depleted. In such cases, consulting a divorce and financial arrangements lawyer ensures that your estate plan remains robust even during periods of personal transition. Regular reviews also safeguard your legacy against shifts in government policy, ensuring that your tax-mitigation strategies remain fully compliant with the latest HMRC rules.

Why Choose Feltons Solicitors for Your IHT Planning?

Choosing the right inheritance tax planning solicitors is a decision that impacts generations. Since our establishment in 2010, Feltons Solicitors LLP has positioned itself as a sophisticated guide for families seeking to protect their wealth. We offer a boutique service level that prioritises personal connection over high-volume processing. This means you aren’t just another file; you’re a partner whose legacy we are committed to safeguarding. Our national service handles complex, international-scale matters with the same quiet confidence we bring to every consultation. We take pride in our “plain English” approach. We believe that professional authority shouldn’t be inaccessible. By stripping away unnecessary legalese, we ensure you feel informed and in control of your financial future.

A unique advantage of our firm is the synergy between our private client work and our deep expertise in residential and commercial property law. Most inheritance tax liabilities are tied to property value. Our background in conveyancing and leasehold matters allows us to provide pragmatic, high-standard advice that other firms might overlook. We understand the nuances of valuation and the legal structures required to protect property assets effectively. This dual expertise ensures that your most valuable assets are managed with precision and care.

A People-First Philosophy to Legal Care

Legal work is essentially about human impact. We adopt a people-first philosophy, recognising that estate planning can be a sensitive or stressful process. Our team acts as a calm, steady presence, guiding you through the technicalities with empathetic reassurance. We value traditional professional integrity, yet we embrace modern efficiency to deliver results that are both thorough and timely. Building a personal rapport is central to our method. It allows us to understand the specific goals of your family, ensuring the strategy we build is truly bespoke. You deserve a solicitor who listens as much as they advise.

A Discreet Partner for High-Net-Worth Individuals

For high-net-worth individuals, privacy is paramount. We act as a discreet partner, handling high-value estates with the utmost confidentiality. Our experience extends to complex matters such as overseas entity beneficial owner registration, ensuring that international property interests are fully compliant and tax-efficient. We handle the intricacies of global assets so you don’t have to. Protecting your legacy is a serious responsibility. We invite you to begin this journey with a confidential consultation, where we can discuss your priorities in a secure and professional environment. Your peace of mind is our primary objective.

Securing Your Legacy for the Generations to Come

Protecting your hard-earned assets from the 40% inheritance tax levy requires more than just a simple Will; it demands a proactive and highly organised strategy. We’ve explored how frozen thresholds and rising property values have made expert planning essential for modern families. By utilising bespoke tools such as lifetime gifting and carefully structured trusts, you can ensure your beneficiaries receive the maximum benefit from your estate whilst maintaining your family’s financial harmony.

As a firm established in 2010, Feltons Solicitors LLP provides a boutique service that combines national expertise with a deeply personal touch. We specialise in property-linked estate planning, ensuring that the unique complexities of your home and commercial interests are fully addressed. Choosing the right inheritance tax planning solicitors is the first step towards achieving lasting peace of mind. Our team is here to act as your sophisticated guide, providing the discreet and pragmatic advice you need to navigate HMRC’s evolving rules.

Secure your family’s future—contact Feltons Solicitors LLP today for bespoke inheritance tax advice. You’ve spent a lifetime building your legacy; let us help you ensure it is protected for those who matter most.

Frequently Asked Questions

Is inheritance tax planning legal and compliant with HMRC?

Yes, inheritance tax planning is entirely legal and compliant with HMRC when it focuses on legitimate tax mitigation. This involves utilising statutory reliefs and exemptions, such as the nil-rate bands or business property relief, to reduce the tax burden on your estate. It’s fundamentally different from tax evasion, which is illegal. Our inheritance tax planning solicitors ensure that every strategy implemented is transparent, professionally documented, and adheres strictly to the latest UK legislation.

Can I avoid inheritance tax by giving my house to my children now?

Gifting your home to your children whilst you continue to live there is usually ineffective for tax purposes. HMRC views this as a “Gift with Reservation of Benefit.” Unless you pay a full market rent to your children, the property remains part of your estate for tax calculations. This rule prevents individuals from artificially reducing their estate’s value whilst still enjoying the benefits of the asset. Proper planning requires more sophisticated legal structures.

What is the seven-year rule for inheritance tax?

The seven-year rule applies to Potentially Exempt Transfers, which are lifetime gifts that fall outside your estate if you survive for seven years. If you die within this period, the gift is added back into your estate’s value. Taper relief may reduce the tax rate on the gift if you survive at least three years, but it doesn’t reduce the value of the gift itself. It’s a complex sliding scale that requires meticulous record-keeping.

How much can I leave to my children tax-free in 2026?

In 2026, an individual can typically pass on up to £500,000 tax-free, provided their estate includes a main residence left to direct descendants. This total includes the £325,000 Nil Rate Band and the £175,000 Residence Nil Rate Band. For married couples or civil partners, these allowances can be combined to allow up to £1 million to be passed on without triggering a tax charge. However, these thresholds are subject to tapering for larger estates.

Do I need a solicitor for inheritance tax planning or can I do it myself?

Whilst it’s possible to attempt estate planning yourself, the risks of costly errors are exceptionally high. HMRC’s rules are intricate, and a single mistake in a trust deed or gift record can negate your entire strategy. Engaging inheritance tax planning solicitors provides the security of professional indemnity and ensures your plan is bespoke to your family’s needs. We provide the sophisticated guidance necessary to navigate these complex legal frameworks whilst prioritising your family’s harmony.

What happens if I die without a Will or an inheritance tax plan?

Dying without a Will or plan means your estate is distributed according to the laws of intestacy. This often results in assets passing to people you didn’t intend to benefit and can lead to a much higher tax bill. Without professional organisation, your family may lose out on valuable reliefs like the Residence Nil Rate Band, potentially forcing the sale of the family home to pay HMRC. It leaves your legacy to chance.

Can business owners claim relief on their company assets?

Yes, business owners can claim Business Property Relief on qualifying trading assets. However, as of April 2026, 100% relief is capped at a combined £2.5 million per person for business and agricultural property. Any value exceeding this threshold only receives 50% relief. This change makes it essential for business owners to review their succession plans to ensure their commercial interests remain protected under the new rules. Proactive restructuring may be necessary to preserve value.

How does the Residence Nil Rate Band work if I sell my home to move into care?

If you sell your home to move into care or a smaller property, you may still be eligible for “downsizing additions” to the Residence Nil Rate Band. This relief ensures you aren’t penalised for moving to a less valuable home later in life. Provided the original property was your main residence and you leave assets of equivalent value to your direct descendants, you can often still claim the full allowance. It provides vital flexibility for elderly homeowners.
What is a Family Trust? A Comprehensive Guide to Protecting Your Legacy in 2026

What is a Family Trust? A Comprehensive Guide to Protecting Your Legacy in 2026

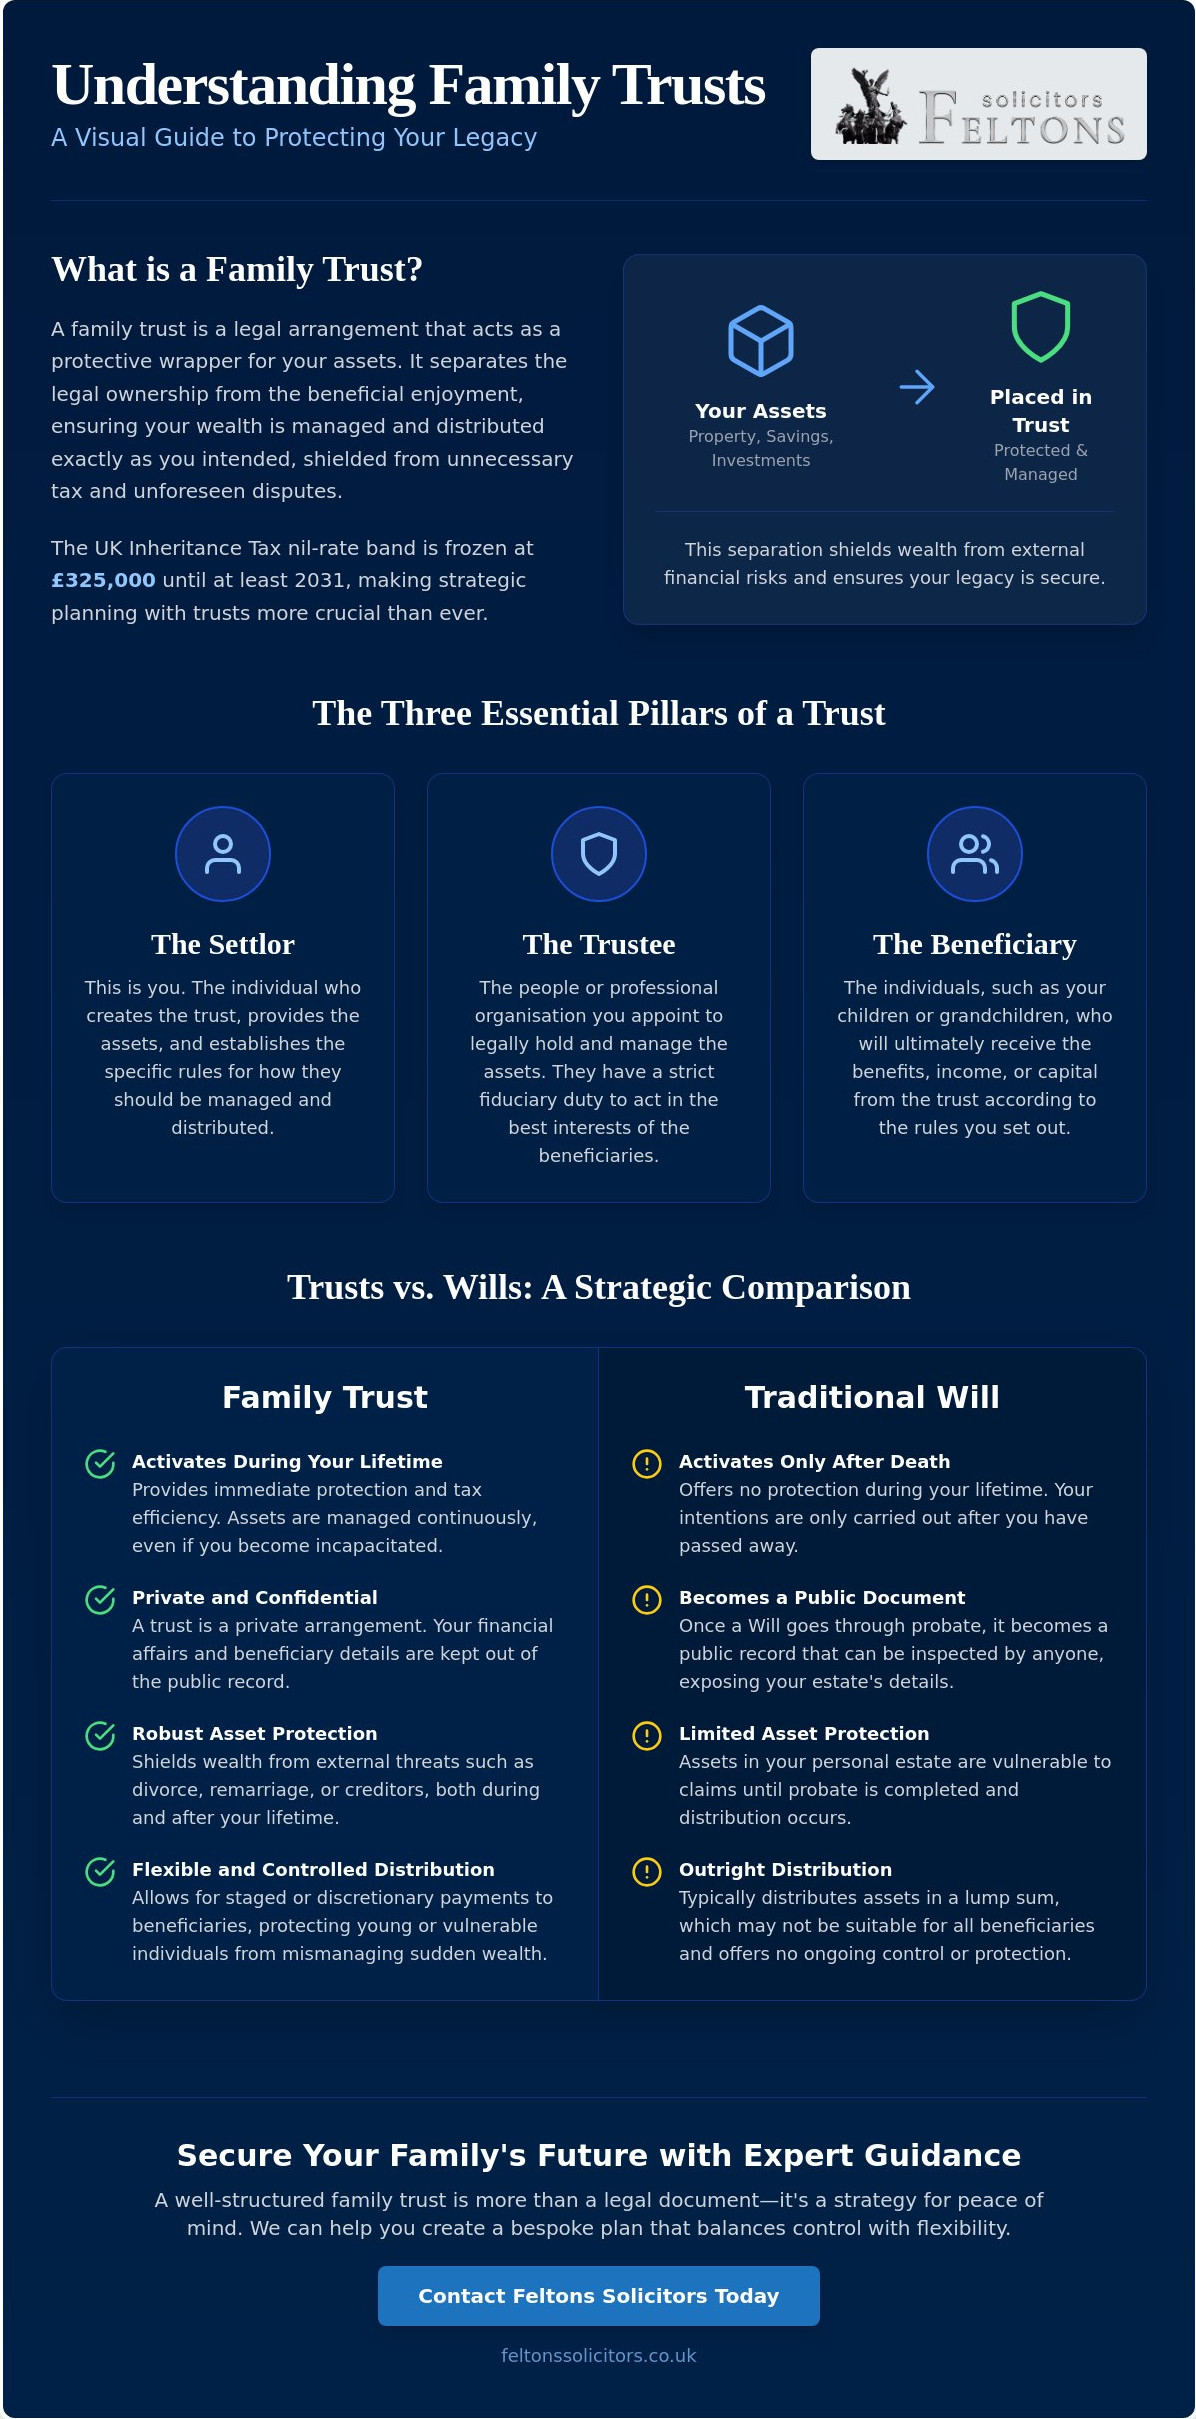
If your family home and savings have grown in value whilst the tax thresholds have remained frozen, how much of your hard-earned legacy will actually reach your children? Many people begin their estate planning journey by asking what is a family trust when they realise that the standard Inheritance Tax nil-rate band is staying at £325,000 until at least 2031. It’s a valid concern. You’ve worked hard to build your wealth, and the thought of it being diminished by tax or mismanaged by future generations is understandably unsettling.

We believe that protecting your family’s future requires more than just a simple document; it requires a strategy that balances control with flexibility. This guide will help you discover how a family trust can safeguard your assets, manage inheritance tax, and provide for your loved ones with professional legal clarity. We’ll examine the specific roles within a trust, how to shield assets from external threats, and provide a clear framework to help you choose between a Will and a Trust for your estate.

Key Takeaways

  • Understand the fundamental legal structure of a trust and the crucial distinction between holding a legal title and possessing a beneficial interest.
  • Gain clear insight into what is a family trust by exploring how a bespoke Trust Deed serves as a precise rulebook for your family legacy.
  • Compare the flexibility of Discretionary Trusts with the structured security of Interest in Possession Trusts to determine the most suitable path for your beneficiaries.
  • Learn how a robust trust structure can shield your family wealth from external threats such as divorce, remarriage, or the risks of managing sudden wealth.
  • Follow a methodical framework to audit your current assets and align your estate planning with your specific long-term protection goals.

Understanding the Core Concept: What is a Family Trust in the UK?

At its most fundamental level, a family trust is a legal arrangement where assets are held by individuals or a professional body for the benefit of others. Whilst it might sound complex, the core principle is straightforward: it’s a way to ensure your wealth is managed exactly as you intended, even when you’re no longer there to oversee it. For those exploring what is a family trust, it’s helpful to view it as a protective wrapper that sits around your assets, shielding them from unnecessary tax or unforeseen family disputes. Understanding the Core Concept of trusts requires looking at how English law distinguishes between legal and beneficial ownership.

When you transfer an asset into a trust, you separate the “legal title” from the “beneficial interest”. The trustees hold the legal title; they’re the registered owners on paper and responsible for the day-to-day administration. However, they don’t own the assets for themselves. The beneficial interest belongs to your beneficiaries, who have the right to enjoy the income or capital according to the rules you’ve set out. This distinction is the engine that drives asset protection, as the assets are no longer technically part of your personal estate.

The Three Essential Pillars of a Trust

Every trust relies on three distinct roles to function effectively and provide the security your family deserves:

  • The Settlor: This is you. You’re the individual who provides the assets, whether that’s property, cash, or investments, and establishes the specific rules for how they should be handled.
  • The Trustee: These are the people or professional organisations you appoint to manage the trust. They have a fiduciary duty to act in the best interests of the beneficiaries and must follow the instructions in your Trust Deed.
  • The Beneficiary: These are the individuals, such as your children or grandchildren, who will ultimately receive the benefits, income, or assets from the trust.

Trusts vs Wills: Which is Right for Your Estate?

Understanding what is a family trust involves comparing it to other legal instruments. Choosing between a Will and a trust often depends on when you want your legacy plan to begin. A traditional Will only takes effect upon your death, whereas a trust can be established during your lifetime to provide immediate protection and tax efficiency. Because trusts can operate whilst you’re still alive, they offer a level of continuity that a Will simply cannot match.

Privacy is another significant factor. When a Will goes through probate, it becomes a public document that anyone can inspect. In contrast, a family trust is a private arrangement, keeping your financial affairs and the details of your beneficiaries away from the public eye. Integrating these structures into your broader estate planning strategy ensures that your family remains supported through a discreet, high-standard service that values both modern efficiency and traditional integrity.

The Mechanics of Asset Protection: How a Trust Structure Operates

Establishing the legal boundaries of a trust requires more than just intent; it requires a formal Trust Deed. This document serves as the precise rulebook for your family legacy, detailing how assets are administered, managed, and eventually distributed. Once this framework is in place, the process of conveyance begins, where assets move from your individual name into the trust’s legal title. This transition is what creates the protective barrier, ensuring that when people ask what is a family trust, they see it as a functional entity separate from their personal estate. This separation is the primary mechanism that shields your wealth from various forms of financial risk.

Trustees are bound by a strict fiduciary duty, requiring them to act with absolute integrity and in the best interests of the beneficiaries at all times. This legal obligation is the cornerstone of the trust’s reliability, ensuring that the assets are managed with sound judgment and professional care. Whilst the Trust Deed acts as the rigid legal instrument, a “letter of wishes” provides the necessary nuance. This confidential document offers personal guidance to your trustees, helping them understand your values and the specific needs of your loved ones. It is a vital tool for ensuring that the human side of your legacy remains intact, even within a formal, highly organised legal structure.

Choosing Your Trustees Wisely

Selecting the right individuals to manage these assets is a decision that requires careful thought and a long-term perspective. Many settlors opt for a combination of trusted family members and professional advisors who understand the specific Tax Implications in 2026. Professional trustees bring an objective perspective that can prevent family friction during stressful times, whilst family members provide continuity and personal context. At Feltons Solicitors LLP, we often recommend this balanced approach to maintain both personal connection and high-standard professional integrity. If you are uncertain about the right choice for your family, our estate planning specialists can provide a tailored consultation.

Managing Trust Assets

A family trust can hold a diverse range of assets, from investment portfolios and cash savings to the family home itself. When a primary residence is involved, the transfer process must align perfectly with residential property law to ensure the asset protection is legally absolute and compliant with Land Registry requirements. Beyond the initial setup, understanding what is a family trust requires a commitment to ongoing administration. Trustees are responsible for annual reporting and must ensure the trust is registered with the HMRC Trust Registration Service (TRS) within 90 days of creation. This methodical oversight is essential for maintaining the trust’s validity and protecting the assets from external threats over the coming decades.

Common Types of Family Trusts and Their Tax Implications in 2026

Selecting the right structure is as important as understanding what is a family trust in the first place. For families in 2026, the choice usually settles on one of three main vehicles, each offering a different balance of control, protection, and tax efficiency. With the Inheritance Tax (IHT) nil-rate band frozen at £325,000 until April 2031, your choice of trust type will significantly impact how much of your estate is subject to the 20% entry charge on transfers exceeding this threshold. Following official guidance on trusts is essential to ensure your chosen path aligns with HMRC’s evolving regulations.

Discretionary Trusts: Flexibility and Control

This is arguably the most versatile option for families with complex or changing needs. In a discretionary trust, the trustees have the power to decide which beneficiaries receive income or capital, how often payments are made, and what conditions must be met. It’s a powerful tool for protecting wealth from a beneficiary’s potential divorce or bankruptcy, as the assets don’t technically belong to the individual until the trustees make a distribution. When people ask what is a family trust, they’re often looking for the specific flexibility provided by this discretionary structure.

This flexibility comes with specific tax considerations. Most discretionary trusts are subject to the “relevant property” regime, which includes a periodic charge of up to 6% on the trust’s value above the nil-rate band every 10 years, alongside “exit charges” when assets are distributed. From April 6, 2026, families with business interests must also account for the new £1 million cap on Business Property Relief (BPR). For trusts created on or after October 30, 2024, this cap applies immediately from April 2026, potentially increasing the tax burden on high-value business assets.

Interest in Possession: Balancing Immediate Needs

Often used in the context of second marriages, an Interest in Possession trust allows a “Life Tenant” (often a surviving spouse) to receive income from the trust assets for the rest of their life. Upon their death, the capital passes to the “Remainderman”, who is typically a child from a first marriage. This ensures the spouse is provided for whilst the underlying inheritance is legally ring-fenced for the next generation. In 2026, these trusts remain a popular choice for those wanting to manage immediate family requirements without losing control over the final destination of the family’s wealth.

Bare Trusts: Direct and Simple

A Bare Trust is the most straightforward arrangement. The assets are held in the name of a trustee, but the beneficiary has an absolute right to both the capital and income. These are frequently used for minor children or grandchildren, where assets are held until the child reaches 18. Once the beneficiary reaches the age of majority, they can demand the assets be transferred to them directly. Whilst they lack the long-term protection of other structures, they’re often favoured for their simplicity and the fact that they’re generally treated as the beneficiary’s own assets for tax purposes.

What is a Family Trust? A Comprehensive Guide to Protecting Your Legacy in 2026

Strategic Benefits: Why Families Choose Trusts Over Simple Wills

Whilst a Will is a foundational document, it often lacks the protective depth required for modern family structures. Many families now look beyond simple probate planning to ask what is a family trust because they require a solution that manages assets across generations with more flexibility. In 2026, the notion that trusts are reserved for the elite is outdated. As property values rise against frozen tax thresholds, these structures have become a pragmatic tool for any homeowner seeking to preserve control over their hard-earned legacy and ensure high-end reliability for their heirs.

When exploring what is a family trust, many families prioritise the concept of “bloodline protection”. If an estate is left directly to a spouse via a Will, those assets are technically at risk if that spouse later remarries or faces legal claims. A trust ensures that whilst the survivor is fully supported, the underlying capital is ring-fenced for your children or grandchildren. This prevents your wealth from being inadvertently diverted to a new partner’s family, providing a sense of security and continuity that a standard Will cannot offer in a blended family scenario. For estates where disputes arise during administration, engaging complex probate solicitors can provide the specialist guidance needed to resolve contentious matters and protect beneficiaries’ interests.

Asset Protection in Divorce and Litigation

A robust trust structure acts as a discreet shield, separating family wealth from the personal liabilities of beneficiaries. Because the assets are managed by trustees, they are often less vulnerable to claims during a beneficiary’s relationship breakdown or personal litigation. As a specialist divorce and financial arrangements lawyer at Feltons Solicitors LLP can confirm, it is always best to establish these protections proactively. Setting up a trust during a period of stability ensures your family’s future remains secure and dependable, rather than reacting to a crisis after it has already begun.

Providing for Vulnerable Beneficiaries

Trusts are also essential for supporting family members who may be unable to manage a large inheritance independently. This includes individuals with disabilities, where a direct gift might affect their eligibility for essential state support. By using a trust, you ensure they receive tailored care and financial stability managed by responsible trustees. Similarly, this structure protects beneficiaries who may struggle with financial management or addiction issues. This people-first approach ensures your wealth serves its true purpose: providing a stable future amongst unpredictable life events. A comprehensive estate plan should also consider appointing a lasting power of attorney solicitor London families trust to ensure that, should you lose mental capacity, your chosen trustees and attorneys can act seamlessly without interruption to your family’s financial arrangements. To begin your journey, contact Feltons Solicitors LLP for a consultation focused on your unique family dynamics.

Establishing Your Legacy: The Path to Creating a Family Trust

Moving from the theoretical understanding of what is a family trust to the practical implementation of one requires a clear, methodical roadmap. The journey begins with identifying your primary objectives, which often involve a sophisticated blend of tax mitigation, asset ring-fencing, and long-term control. At Feltons Solicitors LLP, we start by helping you define exactly what success looks like for your family. Whether you are focused on the upcoming 2026 changes to Business Property Relief or seeking to protect a vulnerable relative, your goals will dictate the specific architecture of the trust structure.

The second stage involves a comprehensive audit of your assets to identify which holdings are suitable for transfer. This is a delicate balancing act that requires professional insight into your current liquidity and future needs. Once the assets are identified, the focus shifts to drafting the Trust Deed with absolute legal precision. This document is the definitive authority on how your wealth is managed, and it must be robust enough to withstand future scrutiny. The final step is the formal conveyance of assets into the trust and ensuring the arrangement is registered with the HMRC Trust Registration Service (TRS), a vital compliance step for modern estate management. Where an estate involves significant business interests or cross-border assets, the expertise of complex probate solicitors may also be required to navigate the intricate administration process alongside your trust structure.

The Importance of Professional Drafting

Attempting to use generic DIY templates for such a complex legal arrangement carries significant risks, including the potential for costly litigation or unintended tax consequences. Feltons Solicitors LLP provides the specialised expertise necessary to ensure your trust is resilient and tailored to your family’s specific nuances. We ensure that your trust works in perfect harmony with your broader estate plan, which often involves finding a will for other family members to eliminate any contradictions. A cohesive strategy also means ensuring that a professionally appointed lasting power of attorney solicitor in London has documented your wishes regarding financial and health decisions, so your trustees can act with full legal authority if you lose capacity before the trust is fully administered. A cohesive strategy is the only way to guarantee that your last wishes are carried out with high-end reliability and professional integrity.

Next Steps with Feltons Solicitors LLP

When you are ready to move forward, our initial consultation provides a calm, steady space to discuss your financial landscape. We take a boutique, people-first approach, ensuring that your family’s unique dynamics are respected throughout the process. You can expect clear, pragmatic advice that avoids dense legalese in favour of practical solutions tailored to your national requirements. Our role as your trusted advisor is to guide you through the complexities of what is a family trust whilst providing the worldly experience necessary to handle even the most intricate estate matters. By choosing a partner that values both modern efficiency and traditional professional integrity, you can secure a legacy that truly stands the test of time.

Securing Your Family Legacy for 2026 and Beyond

Protecting your wealth requires a shift from static planning to a more dynamic, protective framework. You’ve seen how trusts safeguard assets against divorce, manage complex inheritance tax rules, and provide for vulnerable beneficiaries with absolute precision. Deciding what is a family trust for your specific needs is the first step toward ensuring your children and grandchildren are truly provided for. A well-structured trust doesn’t just manage money; it preserves your family values across generations, which often includes the lifelong care of family pets; to prepare for their future health needs, you can check out London Veterinary Surgeries for expert advice on feline healthcare costs.

At Feltons Solicitors, we’ve been helping families since 2010. We blend traditional values with modern delivery to provide boutique, people-first legal expertise. As specialists in complex estate planning and financial arrangements, we ensure your legacy remains robust against future challenges. We’re here to act as your calm, steady presence through every stage of the planning process.

Secure your family’s future with a bespoke trust consultation at Feltons Solicitors. Your legacy is more than just a list of assets; it’s the foundation for your family’s future. We look forward to helping you build it with confidence and care.

Frequently Asked Questions

Is a family trust better than a Will for inheritance tax?

A family trust can be more effective than a Will for Inheritance Tax (IHT) planning because it allows you to remove assets from your personal estate whilst you’re still alive. With the nil-rate band frozen at £325,000 until April 2031, placing assets in trust can mitigate the impact of fiscal drag on your wealth. However, you must consider the 20% entry charge on transfers exceeding your available allowance and potential periodic charges every ten years.

Can I be a trustee of my own family trust in the UK?

You can certainly be a trustee of your own family trust in the UK, and many settlors choose this path to maintain direct involvement in management. Acting as a trustee allows you to oversee the distribution of assets according to your original intent. We often suggest appointing at least one other trustee, perhaps a professional body, to provide continuity and impartial judgment if your circumstances change.

What assets can I put into a family trust?

You can place a wide variety of assets into a trust, including your residential home, cash savings, stocks, shares, and land. When considering what is a family trust for business owners, it’s vital to note that from April 6, 2026, a £1 million cap applies to 100% Business Property Relief. Assets exceeding this value will only receive 50% relief, making the timing of your transfer a critical factor in your strategy.

How much does it cost to maintain a family trust annually?

The annual maintenance costs for a trust depend on its complexity and the type of assets held within the structure. You should account for the cost of preparing annual accounts, filing trust tax returns with HMRC, and periodic legal reviews to ensure compliance with changing regulations. Professional fees for these administrative tasks are a necessary investment to maintain the trust’s protective wrapper and ensure high-end reliability.

Can a family trust be challenged in court after I die?

A family trust can be challenged in court, though it’s generally more difficult to overturn than a traditional Will. Challenges usually arise from claims of mental incapacity, undue influence, or under the Inheritance (Provision for Family and Dependants) Act 1975. Using a professionally drafted Trust Deed and a clear letter of wishes provides a robust defence, ensuring your legacy remains exactly as you intended.

Do I still have control over my house if I put it in a trust?

You can still live in and manage your home if it’s placed in a trust, provided the Trust Deed is drafted with a right to occupy or an Interest in Possession. Whilst the legal title moves to the trustees, your beneficial interest allows you to remain in the property. This arrangement provides security for your residence whilst ensuring the capital is legally ring-fenced for the next generation.

What is the Trust Registration Service (TRS) and do I need to register?

The Trust Registration Service (TRS) is a central HMRC register designed to improve transparency, and most UK trusts must register within 90 days of being established. Failing to register can lead to financial penalties and administrative complications for your trustees. Understanding what is a family trust in 2026 involves recognising these ongoing compliance duties as a standard part of modern, methodical estate management.

Can a family trust protect my assets from care home fees?

A family trust can protect assets from care home fee assessments, but only if it’s established for genuine estate planning reasons well in advance of needing care. If a local authority deems the transfer was made primarily to avoid fees, they may invoke deliberate deprivation of assets rules. Timing and intent are the two most critical factors, which is why we recommend establishing these structures whilst you’re in good health.

A Complete Guide to Estate Planning: Protecting Your Legacy in 2026

A Complete Guide to Estate Planning: Protecting Your Legacy in 2026

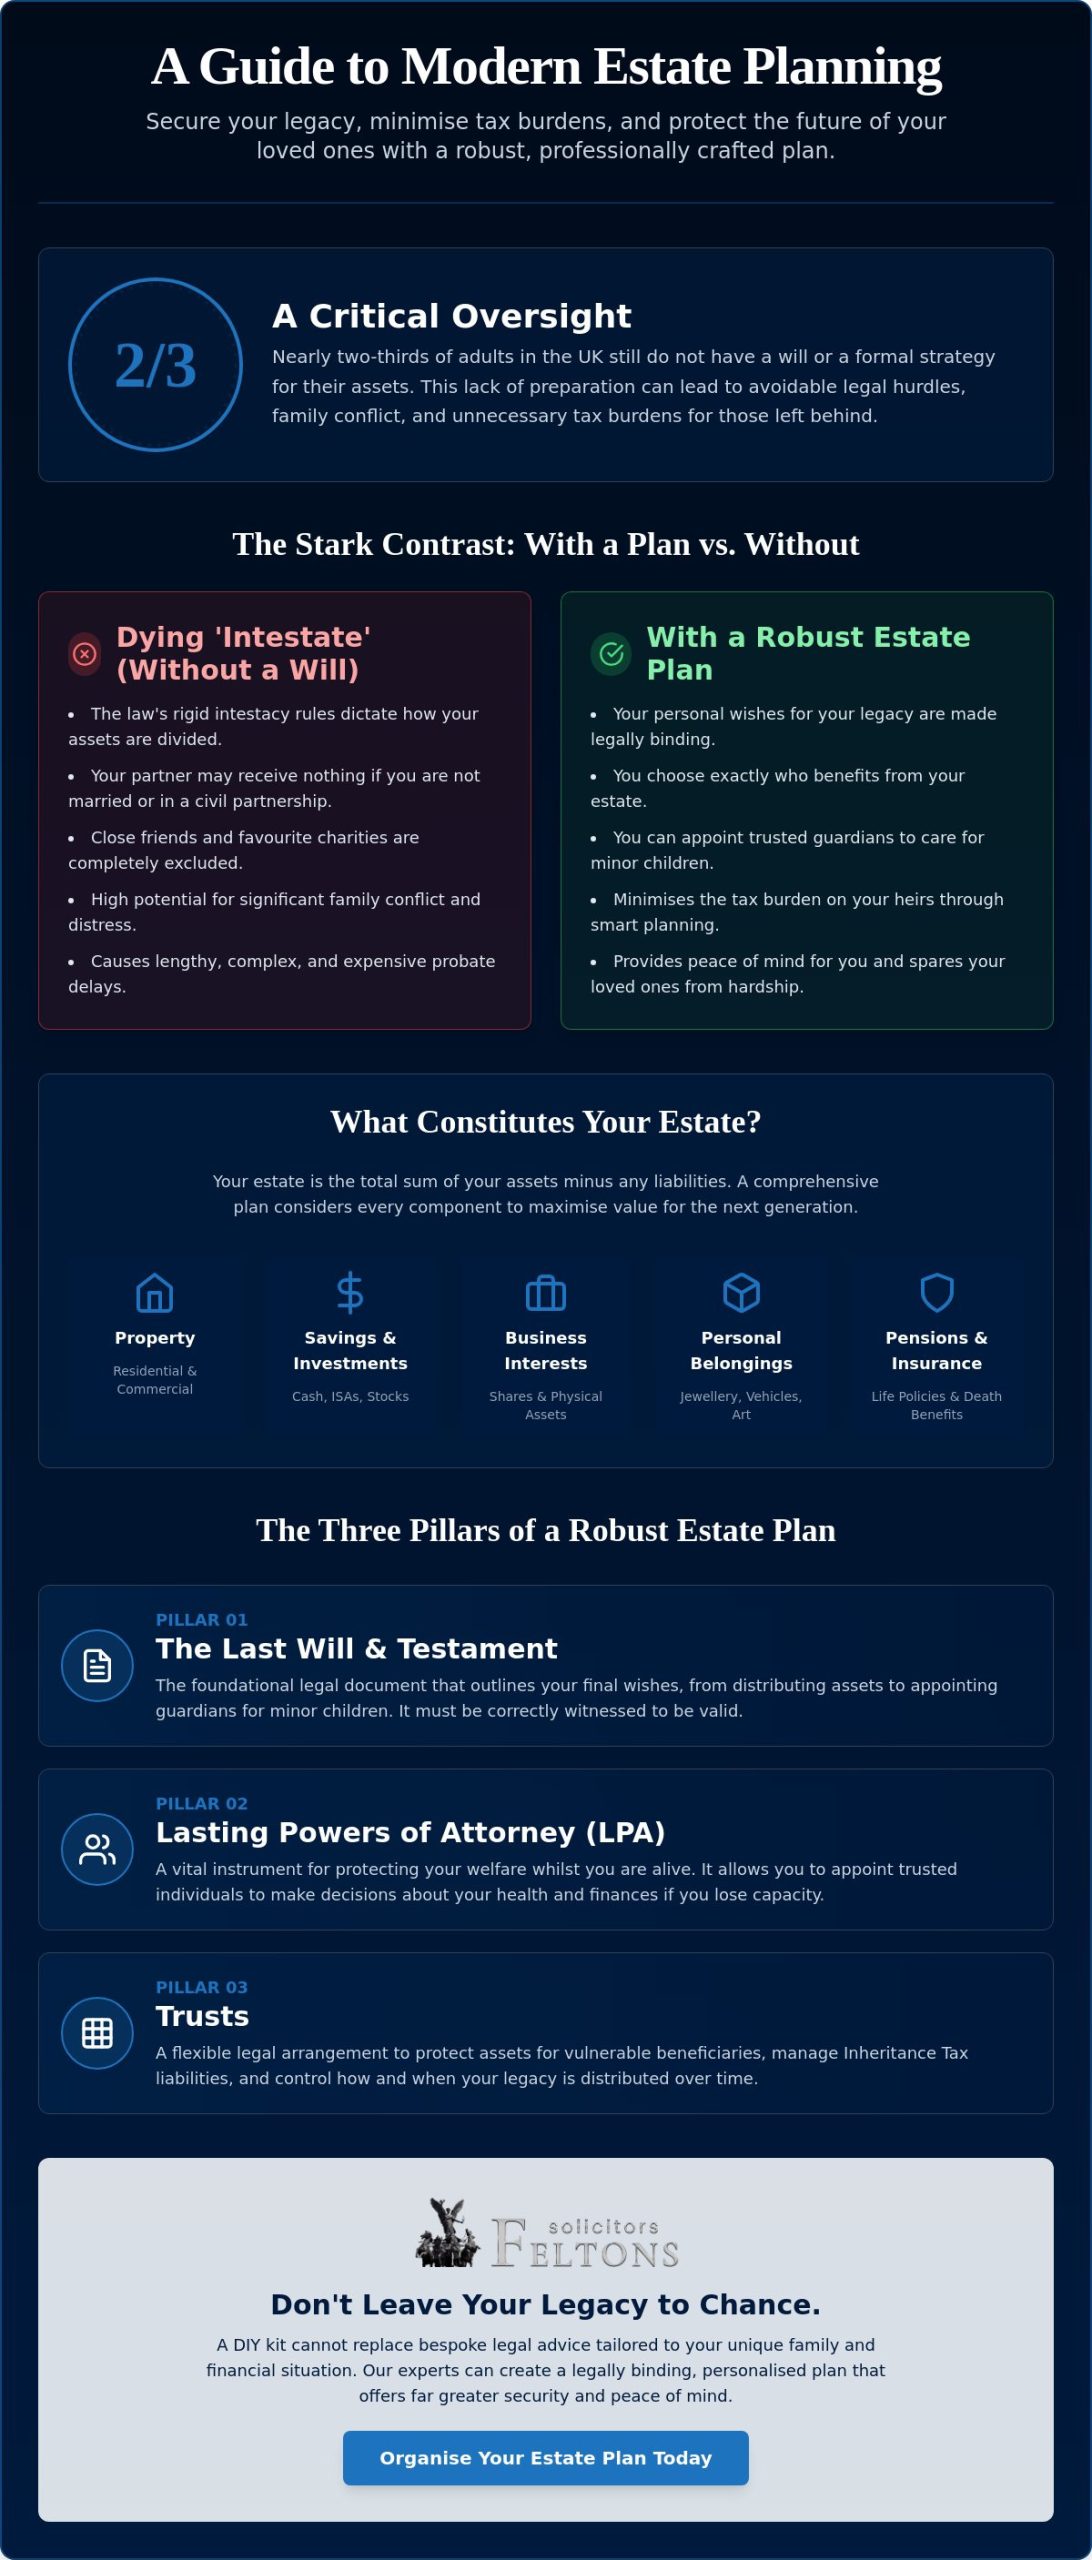
Nearly two-thirds of adults in the UK still do not have a will or a formal strategy for their assets. It’s a striking figure, especially when you consider that a lack of preparation often leaves families facing avoidable legal hurdles and unnecessary tax burdens. You likely want to ensure your hard-earned legacy reaches the right people without causing friction or confusion. Effective estate planning is about more than just drafting a document; it’s a process of securing your family’s future and ensuring your wishes remain legally binding.

We understand that the complexity of Inheritance Tax (IHT) rules and the anxiety of losing control can feel daunting. This guide provides a clear roadmap to help you organise your assets, minimise tax liabilities, and protect your loved ones. We’ll examine the 2026 landscape, including the nuances of nil-rate bands and the emerging role of digital executors. By the end, you’ll have the clarity needed to build a plan that offers both modern efficiency and traditional professional integrity.

Key Takeaways

  • Understand why estate planning is a vital legal strategy for everyone, moving beyond a simple Will to provide a comprehensive roadmap for your assets.
  • Identify the three essential pillars, consisting of Wills, Lasting Powers of Attorney, and Trusts, which create a robust shield for your financial and personal interests.
  • Learn how to navigate complex Inheritance Tax rules and nil-rate bands to protect your family home and minimise the tax burden for your heirs.
  • Discover how to adapt your strategy for modern life, including the management of digital assets and the nuances of blended family arrangements.
  • Recognise the value of bespoke legal advice in creating a legally binding, personalised plan that offers far greater security than standard DIY kits.

Understanding Estate Planning: More than Just a Will

Estate planning is often mistakenly viewed as a task reserved for the exceptionally wealthy. In reality, it’s a proactive, life-long strategy designed to manage your affairs whilst you’re alive and ensure your legacy is handled exactly as you wish after you’re gone. Whilst a Will is a vital component, it’s only one piece of the puzzle. A truly robust approach involves a comprehensive overview of estate planning, covering everything from tax efficiency to the protection of vulnerable beneficiaries.

The primary objectives of this process are clear and practical. You’re looking to protect your assets from unnecessary erosion, ensure the taxman takes no more than is legally required, and provide a secure future for those who depend on you. It’s about maintaining control. Without a structured plan, you leave these critical decisions to chance or to rigid legal frameworks that may not reflect your personal values or modern family dynamics.

What constitutes your “Estate” in 2026?

Your estate is essentially the sum of everything you own, minus any debts or liabilities. In the current environment, this encompasses a diverse range of assets that require careful consideration:

  • Residential and commercial property interests.
  • Cash savings, ISAs, and traditional investments.
  • Business interests, including shares and physical assets.
  • Personal belongings, such as jewellery, vehicles, or art.
  • Life insurance policies and pension death benefits.

Calculating your net worth is the first step in understanding your potential tax exposure. It’s a methodical process that brings clarity to your financial standing and highlights where protection is most needed. By identifying these assets early, we can help you organise them in a way that maximises their value for the next generation.

The consequences of dying intestate

Dying without a valid Will or estate planning strategy, known as dying “intestate,” can be a distressing experience for those left behind. When this happens, the law dictates how your assets are divided through strict UK intestacy rules. These rules are often inflexible. They don’t account for the nuances of modern life.

If you aren’t married or in a civil partnership, your partner may receive nothing at all, regardless of how long you’ve been together. Similarly, favourite charities or close friends are completely excluded under these regulations. This lack of direction often leads to significant family conflict and lengthy, expensive probate delays. Professional estate planning removes this uncertainty. It provides peace of mind that your wishes are legally binding and your loved ones are spared unnecessary hardship during a difficult time.

The Essential Components of a Robust Estate Plan

To build a truly resilient legacy, you must look beyond a single document. A 360-degree approach to estate planning relies on three distinct yet interconnected pillars. These components work in harmony to protect your interests, your assets, and your loved ones through every stage of life. When viewed through the legal framework of estate planning, these instruments form a unified shield that ensures your intentions are respected regardless of what the future holds.

Choosing the right people to uphold these instructions is just as critical as the documents themselves. Executors and trustees carry significant legal and emotional responsibility. Their role is to navigate the technical requirements of your plan with diligence and integrity. However, even the most meticulously drafted plan is only effective if it can be located when needed. A lost document is a silent one.

The Last Will and Testament

For a Will to be valid in England and Wales, it must be made by a person of sound mind, voluntarily, and signed in the presence of two witnesses. Beyond simple asset distribution, it’s the primary legal tool for appointing guardians for minor children. This ensures your children are cared for by people you trust rather than being left to the discretion of the courts. Professional storage is essential to prevent loss or damage. You should also ensure your family knows how to find a Will to avoid unnecessary stress during probate.

Lasting Powers of Attorney (LPA)

Lasting Powers of Attorney are vital for protecting your welfare whilst you’re still alive. There are two specific types: Health and Welfare, and Property and Financial Affairs. A common misconception is that these documents only “kick in” during old age. In reality, they offer vital protection if you temporarily lose capacity due to a sudden accident or illness. Without an LPA in place, your family may have to endure a costly, lengthy application to the Court of Protection just to manage your daily expenses or make medical decisions on your behalf.

Utilising Trusts for Asset Protection

Trusts offer a sophisticated layer of control by separating legal ownership from beneficial enjoyment. A Discretionary Trust provides flexibility, allowing trustees to decide how and when assets are distributed to beneficiaries based on their needs. Alternatively, a Bare Trust offers a more direct route for assets to pass to a specific person. These structures are particularly effective at preventing “sideways disinheritance,” which often occurs if a surviving spouse remarries and original family assets are diverted away from your children. If you would like to understand what is a family trust and how it can safeguard your assets for future generations, our detailed guide covers the specific roles, tax implications, and protections available. If you are considering these protections, our team can guide you through the Estate Planning process with the personal care your legacy deserves.

Protecting your legacy involves more than just listing your assets; it requires a proactive approach to tax efficiency. Estate planning serves as your primary defence against the erosion of your wealth by Inheritance Tax (IHT). In 2026, the tax landscape continues to rely on the “nil-rate band” as a cornerstone. This threshold allows a specific portion of your estate to pass to beneficiaries tax-free. For many homeowners, the residence nil-rate band provides an additional allowance when a family home is left to direct descendants, potentially increasing the total tax-free threshold significantly. Working with a specialist residential property law firm can help ensure your home is correctly valued and structured within your estate plan to maximise these reliefs.

Accurate professional valuation is a critical part of this process. It isn’t enough to rely on rough estimates. Overvaluing assets can lead to your beneficiaries overpaying tax, whilst undervaluing them can invite unwanted scrutiny from HMRC. By ensuring your essential estate planning documents are supported by current, professional appraisals, you provide a clear and defensible record of your estate’s worth. This methodical approach ensures that every available relief is utilised effectively.

Strategic Gifting and Exemptions

Lifetime gifting is a powerful tool for reducing the eventual tax burden on your estate. Most gifts to individuals fall under the category of a “potentially exempt transfer” (PET). These gifts only become fully tax-free if you survive for seven years after making the transfer. If you pass away within this timeframe, the value of the gift may still be counted towards your estate, though taper relief may apply after three years.

You can also take advantage of smaller, immediate exemptions. The annual gift allowance remains a popular choice, allowing you to give away up to £3,000 each year without it being added to the value of your estate. Other allowances include gifts in consideration of a marriage or civil partnership, and small gifts of up to £250 per person, provided they haven’t received part of your £3,000 allowance. Organising these gifts early can make a substantial difference over time.

Business and Agricultural Reliefs

For those with commercial or farming interests, specific reliefs are available to ensure that family businesses can continue without being liquidated to pay tax bills. Business Property Relief (BPR) can reduce the value of a business or its assets by either 50% or 100% for IHT purposes, provided the assets qualify and have been owned for at least two years. Agricultural Property Relief (APR) works similarly for land or buildings used for farming.

These reliefs are not guaranteed. They require regular reviews to ensure the assets continue to meet the strict qualifying criteria. Changes in how a business is structured or how land is used can inadvertently disqualify you from these protections. We recommend a discreet, professional review of your holdings to confirm that your estate planning strategy remains aligned with current legislation and your long-term family goals.

A Complete Guide to Estate Planning: Protecting Your Legacy in 2026

Addressing Modern Complexity: From Digital Assets to International Interests

Life in 2026 is inherently more complex than it was for previous generations. Our assets are no longer confined to physical folders or domestic borders. Effective estate planning must now account for intangible wealth and global footprints to remain relevant. A modern strategy doesn’t just look at what you own; it considers where it’s held and who possesses the legal authority to access it.

Family structures have also evolved significantly. With the rise of blended families and international careers, the traditional “one size fits all” approach is often inadequate. Failing to address these nuances can lead to assets being frozen or distributed in ways you never intended. It’s about ensuring your plan reflects the reality of your life today whilst providing a steady foundation for tomorrow.

Managing Your Digital Legacy

Our digital footprint is often more extensive than we realise. It includes cryptocurrency, NFTs, social media accounts, cloud storage, and intellectual property. Industry research indicates that whilst the perceived value of digital holdings is rising, approximately 76% of individuals report having little or no knowledge of digital estate planning. Executors face significant hurdles when attempting to access password-protected accounts due to strict privacy laws and platform terms. We recommend creating a secure digital asset log. This should list your accounts and instructions for your “digital executor” without including sensitive passwords in the Will itself, as Wills become public documents.

Estate Planning After Divorce or Remarriage

If you’ve recently divorced, your existing Will remains valid, but the law treats your ex-spouse as if they had predeceased you. This can leave significant gaps in your distribution plan. Conversely, many are unaware of the “marriage trap”: entering a new marriage or civil partnership automatically revokes any existing Will unless it was specifically made in contemplation of that marriage. For those in blended families, protecting children from a previous relationship whilst providing for a new spouse requires careful balancing. You can find more detail on asset protection in our guide to Divorce and Financial Arrangements.

International Property and Overseas Entities

Owning property abroad introduces the concept of “Situs,” where the location of an asset determines which country’s laws apply. This can lead to conflicting legal requirements and unexpected tax liabilities. There are also strict requirements for the registration of overseas entities that own UK property, a factor that has become increasingly important for transparency. To ensure your wishes are carried out, you might require separate Wills in different jurisdictions, each drafted to work in harmony. If your circumstances involve international interests or complex family dynamics, contact our team for bespoke Estate Planning advice tailored to your unique situation.

Implementing a strategy of this magnitude requires more than just filling in the blanks on a standard form. Whilst DIY kits are readily available, they often lack the technical precision needed to address the modern complexities we’ve discussed, such as the management of digital assets or international property interests. A single oversight in wording or a failure to follow strict signing protocols can render a document invalid, leaving your family in the exact position you sought to avoid. Professional estate planning provides a level of security that off-the-shelf solutions simply cannot match.

Choosing a boutique legal partner like Feltons Solicitors LLP ensures your plan is crafted with a deep understanding of your unique circumstances. We operate with a people-first philosophy, recognising that behind every asset list is a human story. Our work is backed by professional indemnity insurance and strict regulation, offering you the quiet confidence that your legacy is in capable, protected hands. It’s about more than just wealth distribution; it’s about providing a steady presence for your loved ones when they need it most.

Choosing a Specialist Private Client Solicitor

Finding a trusted advisor is about more than technical skill; it’s about building a personal rapport. You need an expert who understands your family dynamic and can anticipate potential friction before it arises. A specialist solicitor offers a holistic view, often managing related matters such as Residential and Commercial Conveyancing if your plan involves property transfers or restructuring business interests. If disputes do occur, having an advisor with experience in Litigation and Dispute Resolution ensures your interests remain defended. This integrated approach ensures every facet of your legal life works in harmony.

Reviewing and Updating Your Plan

Legislative changes can also impact your strategy. As thresholds shift and new digital asset rules emerge, a plan that was perfect a few years ago may be obsolete by 2026. Regular consultations allow us to refine your approach, ensuring your protections remain as effective as the day they were first drafted. If you’re ready to secure your future, contact us today to organise a discreet consultation and begin your estate planning journey with confidence.

Securing Your Family’s Future with Confidence

Effective estate planning is a profound act of care for those you leave behind. It transforms a complex array of assets into a clear, legally binding legacy that respects your wishes and provides for your family’s needs. By integrating robust Wills, Lasting Powers of Attorney, and strategic Trusts, you create a shield against modern uncertainties and unnecessary tax burdens. Whether you’re managing a traditional family home or complex international interests, a proactive approach ensures your hard-earned wealth remains protected.

At Feltons Solicitors, we believe in a boutique, people-first approach. Established in 2010 by Paula Felton, our firm offers specialist expertise in complex probate and property matters. We provide a bespoke, discreet service for both national and international clients, ensuring every detail is handled with professional integrity. You don’t have to face these technical hurdles alone. Our team is here to guide you through every step with quiet confidence and tailored advice. Begin your estate planning journey with Feltons Solicitors today and find the peace of mind that comes from knowing your legacy is secure.

Frequently Asked Questions

What is the difference between a Will and estate planning?

A Will is a single legal document that specifies how your assets are distributed after your death. In contrast, estate planning is a comprehensive, ongoing strategy that encompasses your Will, tax mitigation, trusts, and lifetime protections like Lasting Powers of Attorney. It’s about managing your affairs whilst you’re alive as much as it is about protecting your legacy later. This holistic approach ensures every facet of your financial and personal life is coordinated.

Do I need to pay Inheritance Tax on my family home?

Whether you pay Inheritance Tax (IHT) on your home depends on the total value of your estate and your chosen beneficiaries. Most individuals benefit from a standard nil-rate band, but you may also qualify for the “residence nil-rate band” if you leave your property to direct descendants like children or grandchildren. This can significantly increase your tax-free threshold, provided your estate stays within specific valuation limits set by HMRC.

Can I write my own estate plan without a solicitor?

Whilst you can technically draft your own documents, DIY kits often lack the sophistication required for modern family or financial situations. Small errors in wording or witnessing can lead to documents being contested or declared invalid in court. Professional guidance ensures your plan is legally robust and that you haven’t overlooked critical tax-saving opportunities or the complex requirements of digital asset management.

How often should I update my estate planning documents?

We recommend reviewing your estate planning documents every three to five years to ensure they remain aligned with current legislation and your personal wishes. You should also trigger an immediate review after major life events. These include marriage, divorce, the birth of children, or significant changes in your financial circumstances, such as buying a new property or starting a business.

What happens to my digital assets like social media and crypto when I die?

Digital assets are governed by a combination of legal instructions and practical access planning. Unlike physical property, crypto-assets and social media accounts are protected by strict encryption and terms of service that can block executors. You should maintain a secure, private record of your digital presence and consider appointing a digital executor. This person can handle the technical aspects of managing these assets according to your specific wishes.

Is a Lasting Power of Attorney only for the elderly?

Lasting Powers of Attorney (LPAs) are essential for any adult over the age of 18. Sudden illness or accidents can happen at any stage of life, potentially leaving you unable to manage your finances or make medical decisions. If you don’t have an LPA in place, your family might be forced to apply to the Court of Protection for a Deputyship order. This is a significantly more expensive and intrusive process than proactive planning.

How can I protect my children’s inheritance if I remarry?

You can protect your children’s interests by using specific trust structures within your Will, such as a Life Interest Trust. This allows a new spouse to live in a property or receive income during their lifetime whilst ensuring the capital eventually passes to your children. Without these protections, your assets could unintentionally pass to a new spouse’s own heirs through “sideways disinheritance” if you pass away first. Our comprehensive guide on what is a family trust explains how these structures can be tailored to balance the needs of a new spouse with the long-term interests of your children.

What are the costs involved in professional estate planning?

The investment required for professional assistance varies based on the complexity of your family dynamics and the diversity of your assets. A straightforward Will involves a different level of work than a comprehensive strategy involving multiple trusts, business interests, or international property. Our focus is on providing a transparent, boutique service where the true value lies in the long-term tax savings and the absolute legal security provided to your beneficiaries. If your family has also been affected by an industrial illness, you may wish to explore whether you are entitled to pursue a silicosis claim after death to secure the compensation your loved one was owed. Where an estate involves disputed assets, contested beneficiaries, or significant business holdings, engaging complex probate solicitors from the outset can help prevent costly delays and protect the estate’s full value for your beneficiaries.