Inheritance Tax Planning Solicitors: Protecting Your Family Legacy in 2026

Inheritance Tax Planning Solicitors: Protecting Your Family Legacy in 2026

What if the most expensive bill your family ever receives is the one that arrives after you’re gone? With the Treasury projected to collect over £9 billion in inheritance tax by the 2026/27 tax year, the “death tax” is no longer a concern reserved solely for the ultra-wealthy. Frozen thresholds and recent reforms to business reliefs mean that many more family homes and hard-earned savings are now falling into the 40% tax net. Partnering with experienced inheritance tax planning solicitors is no longer just a financial precaution; it’s a vital step in ensuring your life’s work isn’t dismantled by HMRC.

It’s natural to feel a sense of unease when faced with complex HMRC rules and the fear of losing a legacy you’ve spent decades building. We believe that your estate should benefit those you love most, rather than being unnecessarily eroded by tax liabilities. This article explores how expert planning can safeguard your assets, providing a clear strategy to minimise tax and protect the family home. We will preview the latest 2026 legislative changes, from business property relief caps to upcoming shifts in pension treatment, giving you the peace of mind that your family legacy remains secure and intact.

Key Takeaways

  • Understand how frozen thresholds and rising property values are placing more family homes within the 40% tax bracket than in previous decades.
  • Learn to navigate the specific rules surrounding the Nil Rate Band and Residence Nil Rate Band to protect up to £1 million of your joint estate.
  • Discover the strategic benefits of the “Seven-Year Rule” and trusts to gift assets whilst ensuring your beneficiaries receive the maximum possible benefit.
  • Identify why engaging expert inheritance tax planning solicitors is essential for conducting a comprehensive audit of your property, pensions, and global interests.
  • Explore how a boutique, people-first approach to estate planning provides the discreet and tailored guidance necessary to secure a complex family legacy.

Understanding Inheritance Tax: The “Silent” Threat to Your Estate

Inheritance tax is often described as a voluntary levy because, with the right guidance from inheritance tax planning solicitors, its impact can be significantly mitigated. At its core, Inheritance Tax in the United Kingdom is a 40% charge on the portion of an estate that exceeds specific thresholds. While it was once perceived as a tax for the wealthy, rising property values combined with frozen tax-free bands have created a “fiscal drag” that pulls many more families into the net. This isn’t just a financial burden; it’s a source of profound emotional stress. Without a clear plan, beneficiaries may face difficult decisions or even disputes amongst themselves during an already painful time. The Nil Rate Band is the foundational tax-free allowance in the UK, providing a baseline of £325,000 that can be passed on without triggering a tax charge.

The 40% Factor: Why Doing Nothing is Costly

The 40% rate is one of the highest tax figures in the UK, yet it only applies to the value above your available allowances. For many, the most significant allowance is the Residence Nil Rate Band (RNRB), which provides an additional £175,000 when a main residence is left to direct descendants. However, if your estate’s value exceeds these combined limits, the tax bill can be staggering. We often see families forced into a “fire sale” of the family home or cherished assets simply to satisfy HMRC within the required six-month window. This pressure is entirely avoidable with proactive organisation. It’s about protecting the liquidity of your estate so your loved ones aren’t left with a debt they can’t afford to pay.

Common Misconceptions About Estate Planning

A frequent mistake is the belief that inheritance tax only affects the super-rich. With the average UK house price rising, many modest estates now exceed the thresholds. Another misconception is that a basic Will is enough. While a Will is vital for stating who gets what, it rarely addresses the complex tax structures needed to preserve wealth over generations. Finally, many assume that gifting assets is a simple, immediate solution. In reality, gifts are subject to strict rules and can lead to unexpected tax charges if not handled with professional care. Engaging inheritance tax planning solicitors ensures these nuances are managed, protecting your legacy from avoidable erosion whilst giving you the confidence that your affairs are in order.

Key Thresholds and Reliefs: The Framework of UK Tax Planning

Effective tax planning begins with a clear understanding of the allowances available to you. Every individual in the UK currently benefits from a Nil Rate Band (NRB) of £325,000. This is the amount you can pass on to your beneficiaries entirely tax-free amongst other potential exemptions. When a main residence is involved, the Residence Nil Rate Band (RNRB) provides an additional £175,000 allowance, provided the property is left to direct descendants like children or grandchildren. For married couples and civil partners, these allowances are even more powerful. Any unused portion of a deceased partner’s NRB or RNRB can be transferred to the survivor, effectively doubling the tax-free threshold. You can find the most recent updates on these figures in the official government IHT guidance.

Accurate valuation is the cornerstone of a robust estate plan. This is particularly true for complex assets such as property with leasehold interests. The value of a leasehold property can fluctuate significantly based on the remaining term of the lease, making it essential to obtain professional valuations that HMRC will accept. Our inheritance tax planning solicitors work closely with property experts to ensure every asset is accounted for at its true market value, preventing overpayment or future disputes with the tax office whilst ensuring full compliance.

The Role of the Family Home in Your Estate

The family home is often a person’s most valuable asset. By combining both the NRB and the RNRB, a couple can potentially pass on up to £1 million without triggering an inheritance tax bill. It’s vital to be aware of the tapering rules; for estates valued at more than £2 million, the RNRB is reduced by £1 for every £2 the estate’s value exceeds this threshold. If your estate includes significant property holdings, you might find our residential property law guide helpful for understanding how ownership structures impact your tax position.

Specialist Reliefs for Business and Agricultural Assets

For business owners and farmers, the landscape changed significantly in April 2026. Business Property Relief (BPR) and Agricultural Property Relief (APR) can provide up to 100% relief on qualifying assets, but this is now capped at a combined £2.5 million per person. Value exceeding this cap generally receives 50% relief. To qualify, assets must meet strict criteria, such as being a trading business rather than an investment company. Meticulous documentation is required to satisfy HMRC that these reliefs apply. If you’re concerned about how these caps affect your commercial interests, it’s wise to review your estate planning with a specialist who understands both the legal and commercial nuances.

Bespoke Strategies: Gifts, Trusts, and Lifetime Planning

Lifetime planning is about taking proactive steps today to ensure your family’s future is unburdened by tax liabilities. One of the most effective tools used by inheritance tax planning solicitors is the Potentially Exempt Transfer (PET). This allows you to gift assets of any value, which then become exempt from tax if you survive for seven years from the date of the transfer. Beyond simple gifts, you might consider leaving at least 10% of your net estate to a qualifying charity. This altruistic choice reduces the standard 40% inheritance tax rate to 36% across your entire taxable estate, potentially saving your family a significant sum whilst supporting a cause you value. For many, life insurance remains a cornerstone of a robust strategy. When a policy is written into a Trust, the payout doesn’t form part of your taxable estate; instead, it provides immediate liquidity for your beneficiaries to settle any IHT bill without the need to sell the family home.

Utilising Trusts to Protect Assets and Control Distribution

Trusts offer a sophisticated way to remove assets from your estate whilst maintaining a level of influence over how and when they are distributed. A Discretionary Trust allows you to appoint trustees who decide which beneficiaries receive funds, providing flexibility for changing family circumstances. Alternatively, a Life Interest Trust can protect a spouse’s right to live in a property whilst ensuring the capital eventually passes to children. You can find more detail on these structures in our guide to estate planning. These arrangements require precise legal drafting to ensure they remain compliant with HMRC’s evolving rules and provide the protection your family needs.

The Nuances of Gifting and Taper Relief

Not all gifts are subject to the seven-year rule. Every individual has an annual exemption of £3,000, which can be carried forward for one year if unused. Small gifts of up to £250 to any number of people and specific wedding gifts are also immediately exempt. When larger gifts are made, Taper Relief applies if you survive between three and seven years. This relief reduces the tax rate on the gift itself on a sliding scale, though it’s a common misconception that it reduces the value of the gift for the purposes of the nil-rate band. The UK government’s guide to Inheritance Tax provides the specific percentage breakdowns for these periods. It’s vital to avoid a “Gift with Reservation of Benefit” (GROB). This occurs if you give an asset away, such as your home, but continue to use it without paying a full market rent. HMRC will treat such assets as if they never left your estate, potentially negating your entire planning strategy. Our inheritance tax planning solicitors ensure your gifts are structured correctly to avoid these common pitfalls.

Inheritance Tax Planning Solicitors: Protecting Your Family Legacy in 2026

The Planning Process: How Inheritance Tax Solicitors Organise Your Affairs

Organising a complex estate requires a methodical approach that balances technical legal requirements with your personal family values. Expert inheritance tax planning solicitors act as a sophisticated guide, leading you through a structured process designed to provide clarity and security. This journey begins with a comprehensive audit of your global estate. We examine everything from residential and commercial property holdings to pension funds and interests in overseas entities. By understanding the full scope of your assets, we can identify potential tax exposures that a more superficial review might miss, which is why the involvement of inheritance tax planning solicitors is so vital.

Once the audit is complete, the focus shifts to your specific family goals. This people-first philosophy ensures the resulting strategy reflects your priorities, whether that’s protecting a business for the next generation or ensuring a spouse is provided for. The planning then moves through three critical implementation phases:

  • Drafting and Updating: We refine your Will to incorporate tax-efficient structures, such as the trusts discussed in previous sections.
  • Active Implementation: This involves setting up lifetime gift programmes or establishing trusts to remove assets from the taxable estate whilst retaining necessary control.
  • Continual Oversight: A legacy is not static. We schedule regular reviews to ensure your plan remains effective as tax laws evolve or your personal circumstances change.

Collaborating with Financial Advisors

We believe the best results are achieved through professional synergy. Whilst our role focuses on legal asset protection and the drafting of complex documents, financial advisors provide the investment strategy and product selection. We frequently collaborate with a client’s existing professional network to ensure the legal framework and financial investments work in perfect harmony. This holistic approach ensures that no aspect of your wealth is left vulnerable to avoidable tax “bites.” If you’re ready to begin this process, you can contact our specialist team today for a discreet consultation.

Reviewing Your Plan: Adapting to Change

Life rarely follows a linear path. Major milestones such as marriage, the birth of grandchildren, or a change in business ownership necessitate an immediate review of your IHT strategy. Significant life events like separation also require careful handling to protect assets from being unnecessarily depleted. In such cases, consulting a divorce and financial arrangements lawyer ensures that your estate plan remains robust even during periods of personal transition. Regular reviews also safeguard your legacy against shifts in government policy, ensuring that your tax-mitigation strategies remain fully compliant with the latest HMRC rules.

Why Choose Feltons Solicitors for Your IHT Planning?

Choosing the right inheritance tax planning solicitors is a decision that impacts generations. Since our establishment in 2010, Feltons Solicitors LLP has positioned itself as a sophisticated guide for families seeking to protect their wealth. We offer a boutique service level that prioritises personal connection over high-volume processing. This means you aren’t just another file; you’re a partner whose legacy we are committed to safeguarding. Our national service handles complex, international-scale matters with the same quiet confidence we bring to every consultation. We take pride in our “plain English” approach. We believe that professional authority shouldn’t be inaccessible. By stripping away unnecessary legalese, we ensure you feel informed and in control of your financial future.

A unique advantage of our firm is the synergy between our private client work and our deep expertise in residential and commercial property law. Most inheritance tax liabilities are tied to property value. Our background in conveyancing and leasehold matters allows us to provide pragmatic, high-standard advice that other firms might overlook. We understand the nuances of valuation and the legal structures required to protect property assets effectively. This dual expertise ensures that your most valuable assets are managed with precision and care.

A People-First Philosophy to Legal Care

Legal work is essentially about human impact. We adopt a people-first philosophy, recognising that estate planning can be a sensitive or stressful process. Our team acts as a calm, steady presence, guiding you through the technicalities with empathetic reassurance. We value traditional professional integrity, yet we embrace modern efficiency to deliver results that are both thorough and timely. Building a personal rapport is central to our method. It allows us to understand the specific goals of your family, ensuring the strategy we build is truly bespoke. You deserve a solicitor who listens as much as they advise.

A Discreet Partner for High-Net-Worth Individuals

For high-net-worth individuals, privacy is paramount. We act as a discreet partner, handling high-value estates with the utmost confidentiality. Our experience extends to complex matters such as overseas entity beneficial owner registration, ensuring that international property interests are fully compliant and tax-efficient. We handle the intricacies of global assets so you don’t have to. Protecting your legacy is a serious responsibility. We invite you to begin this journey with a confidential consultation, where we can discuss your priorities in a secure and professional environment. Your peace of mind is our primary objective.

Securing Your Legacy for the Generations to Come

Protecting your hard-earned assets from the 40% inheritance tax levy requires more than just a simple Will; it demands a proactive and highly organised strategy. We’ve explored how frozen thresholds and rising property values have made expert planning essential for modern families. By utilising bespoke tools such as lifetime gifting and carefully structured trusts, you can ensure your beneficiaries receive the maximum benefit from your estate whilst maintaining your family’s financial harmony.

As a firm established in 2010, Feltons Solicitors LLP provides a boutique service that combines national expertise with a deeply personal touch. We specialise in property-linked estate planning, ensuring that the unique complexities of your home and commercial interests are fully addressed. Choosing the right inheritance tax planning solicitors is the first step towards achieving lasting peace of mind. Our team is here to act as your sophisticated guide, providing the discreet and pragmatic advice you need to navigate HMRC’s evolving rules.

Secure your family’s future—contact Feltons Solicitors LLP today for bespoke inheritance tax advice. You’ve spent a lifetime building your legacy; let us help you ensure it is protected for those who matter most.

Frequently Asked Questions

Is inheritance tax planning legal and compliant with HMRC?

Yes, inheritance tax planning is entirely legal and compliant with HMRC when it focuses on legitimate tax mitigation. This involves utilising statutory reliefs and exemptions, such as the nil-rate bands or business property relief, to reduce the tax burden on your estate. It’s fundamentally different from tax evasion, which is illegal. Our inheritance tax planning solicitors ensure that every strategy implemented is transparent, professionally documented, and adheres strictly to the latest UK legislation.

Can I avoid inheritance tax by giving my house to my children now?

Gifting your home to your children whilst you continue to live there is usually ineffective for tax purposes. HMRC views this as a “Gift with Reservation of Benefit.” Unless you pay a full market rent to your children, the property remains part of your estate for tax calculations. This rule prevents individuals from artificially reducing their estate’s value whilst still enjoying the benefits of the asset. Proper planning requires more sophisticated legal structures.

What is the seven-year rule for inheritance tax?

The seven-year rule applies to Potentially Exempt Transfers, which are lifetime gifts that fall outside your estate if you survive for seven years. If you die within this period, the gift is added back into your estate’s value. Taper relief may reduce the tax rate on the gift if you survive at least three years, but it doesn’t reduce the value of the gift itself. It’s a complex sliding scale that requires meticulous record-keeping.

How much can I leave to my children tax-free in 2026?

In 2026, an individual can typically pass on up to £500,000 tax-free, provided their estate includes a main residence left to direct descendants. This total includes the £325,000 Nil Rate Band and the £175,000 Residence Nil Rate Band. For married couples or civil partners, these allowances can be combined to allow up to £1 million to be passed on without triggering a tax charge. However, these thresholds are subject to tapering for larger estates.

Do I need a solicitor for inheritance tax planning or can I do it myself?

Whilst it’s possible to attempt estate planning yourself, the risks of costly errors are exceptionally high. HMRC’s rules are intricate, and a single mistake in a trust deed or gift record can negate your entire strategy. Engaging inheritance tax planning solicitors provides the security of professional indemnity and ensures your plan is bespoke to your family’s needs. We provide the sophisticated guidance necessary to navigate these complex legal frameworks whilst prioritising your family’s harmony.

What happens if I die without a Will or an inheritance tax plan?

Dying without a Will or plan means your estate is distributed according to the laws of intestacy. This often results in assets passing to people you didn’t intend to benefit and can lead to a much higher tax bill. Without professional organisation, your family may lose out on valuable reliefs like the Residence Nil Rate Band, potentially forcing the sale of the family home to pay HMRC. It leaves your legacy to chance.

Can business owners claim relief on their company assets?

Yes, business owners can claim Business Property Relief on qualifying trading assets. However, as of April 2026, 100% relief is capped at a combined £2.5 million per person for business and agricultural property. Any value exceeding this threshold only receives 50% relief. This change makes it essential for business owners to review their succession plans to ensure their commercial interests remain protected under the new rules. Proactive restructuring may be necessary to preserve value.

How does the Residence Nil Rate Band work if I sell my home to move into care?

If you sell your home to move into care or a smaller property, you may still be eligible for “downsizing additions” to the Residence Nil Rate Band. This relief ensures you aren’t penalised for moving to a less valuable home later in life. Provided the original property was your main residence and you leave assets of equivalent value to your direct descendants, you can often still claim the full allowance. It provides vital flexibility for elderly homeowners.
Complex Personal Injury Claims Solicitor: Navigating Life-Changing Litigation in 2026

Complex Personal Injury Claims Solicitor: Navigating Life-Changing Litigation in 2026

A life-changing injury often brings a sense of profound isolation, particularly when you’re faced with the daunting task of proving liability in a non-standard accident. You might worry that your case will be processed by a large legal firm where personal connection is sacrificed for volume. Choosing the right complex personal injury claims solicitor is about finding a sophisticated guide who views your recovery as a priority rather than a statistic.

Your future shouldn’t be a gamble. It’s natural to feel anxious about the rising costs of specialist care or the complexities of the 2026 legal landscape, including updated court fees and evolving liability standards. You deserve a partner who provides a calm, steady presence whilst navigating the intricate details of your claim. This guide explains how a specialist solicitor secures essential interim payments for immediate rehabilitation and builds cases for settlements that reflect your true long-term needs. We’ll examine the senior-led strategies required to manage high-value disputes and how a boutique approach ensures you’re never just another file in a system.

Key Takeaways

  • Identify the factors that elevate a case to high-value litigation and how forensic experts establish negligence in intricate accident scenarios.
  • See how a complex personal injury claims solicitor prioritises your long-term security by navigating disputes involving multiple parties or non-standard liability.
  • Gain insight into the resurgence of occupational diseases like silicosis and the critical steps required to hold employers accountable for respiratory protection failures.
  • Learn how to accurately quantify both immediate medical bills and lifelong needs, such as home adaptations, to ensure your settlement provides total financial stability.
  • Discover the benefits of a senior-led, boutique legal approach that values personal rapport and pragmatic advice over high-volume processing.

What Defines a Complex Personal Injury Claim?

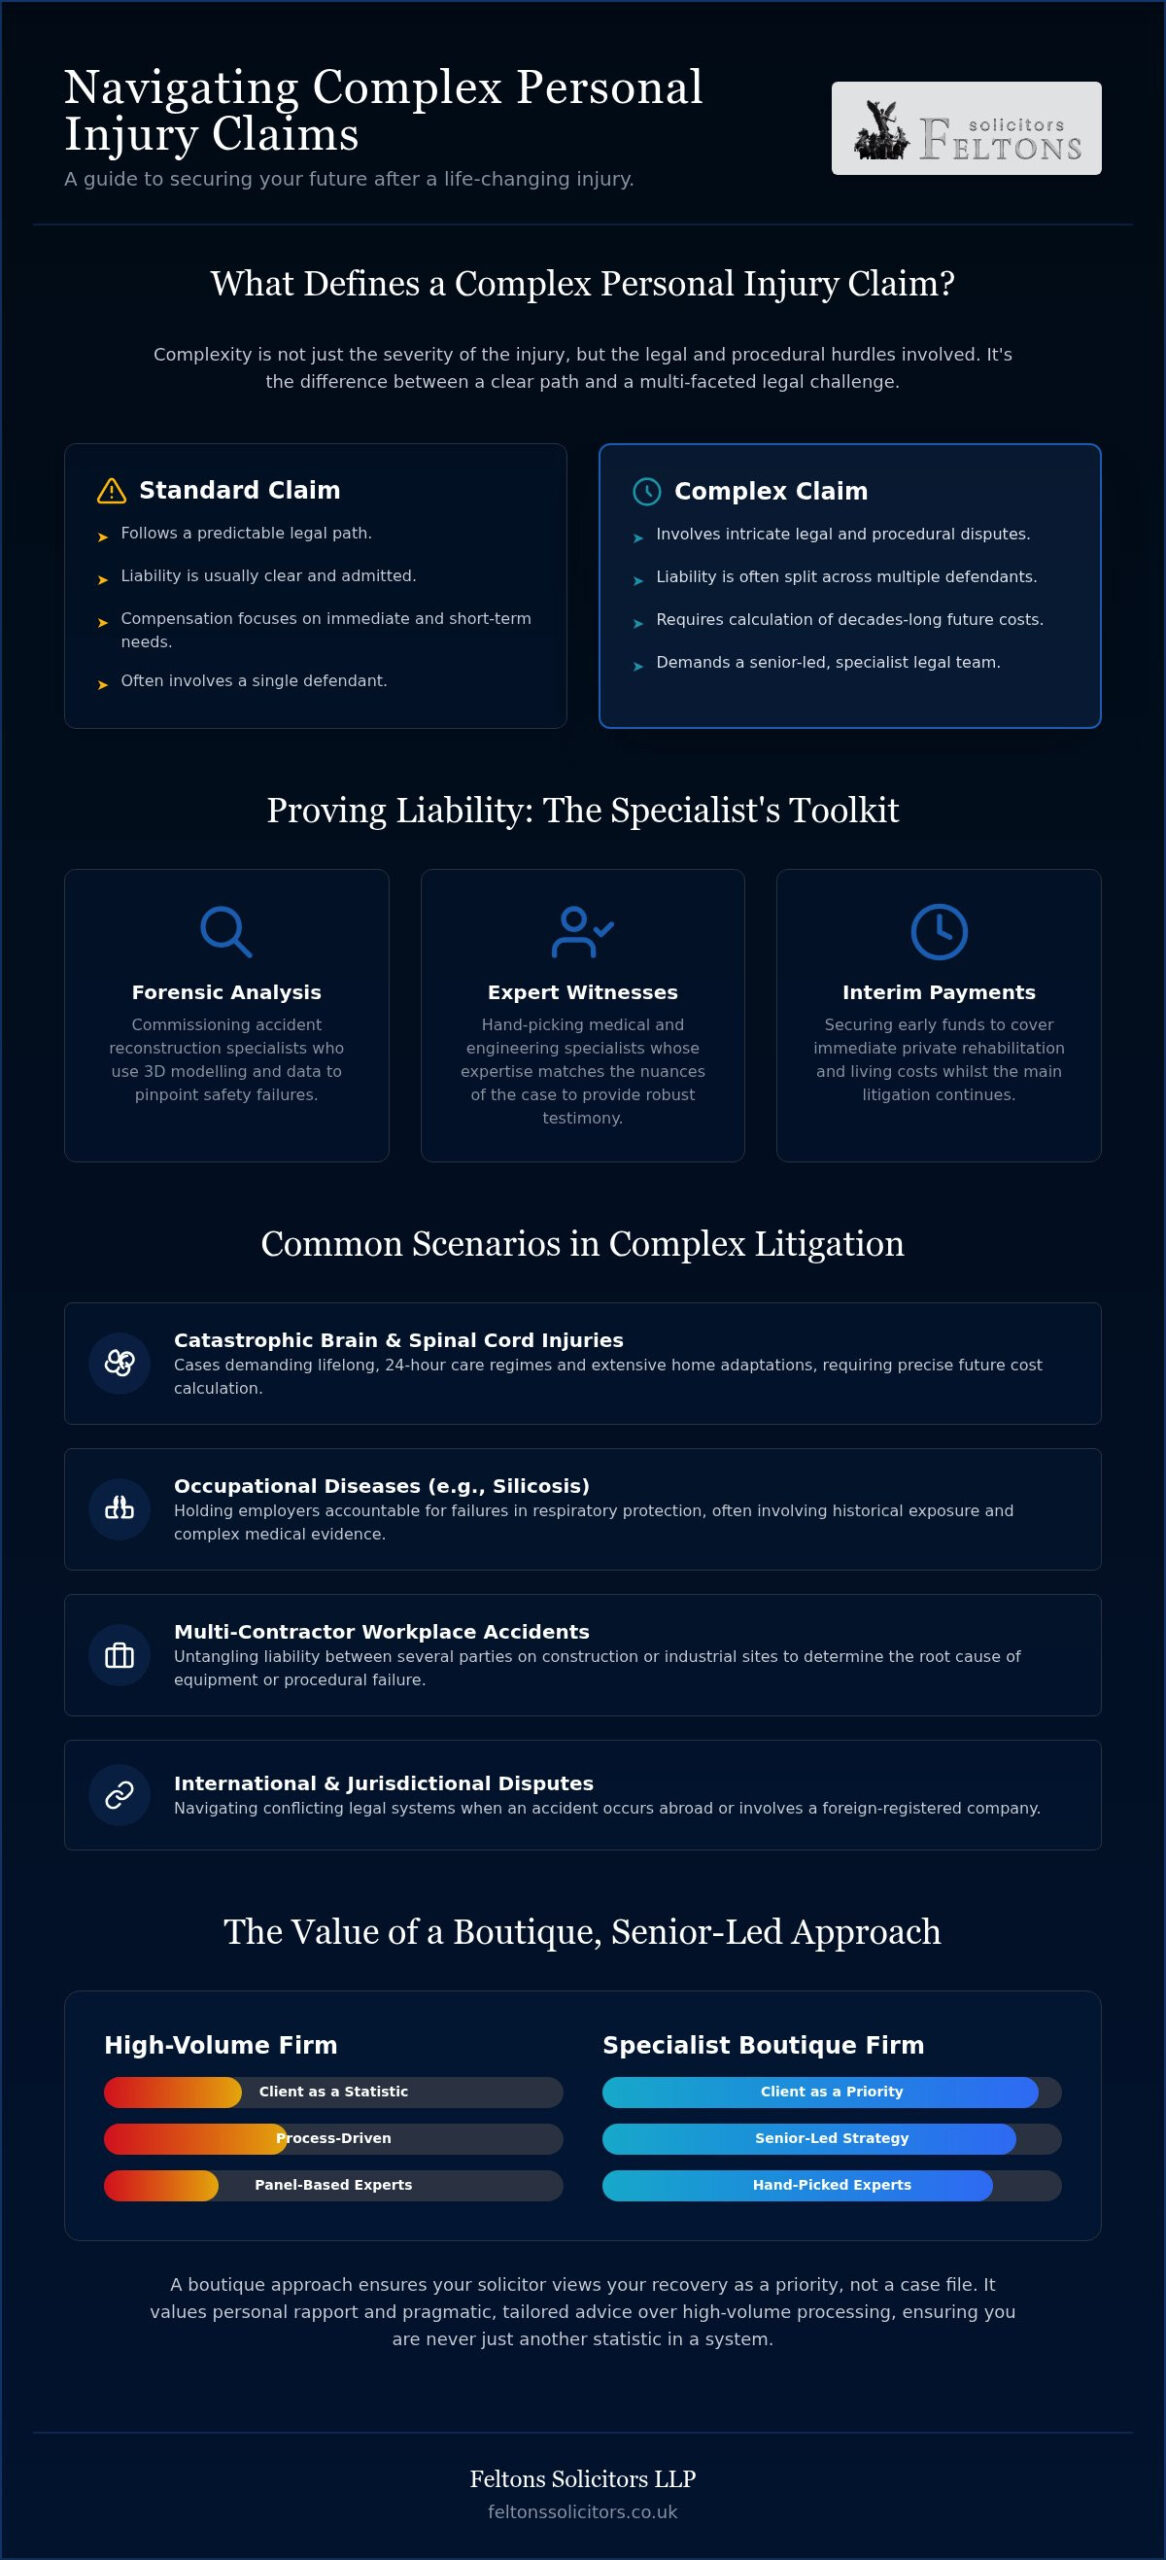
Complexity isn’t just about the scale of the injury. It describes the legal and procedural hurdles that stand between a claimant and their recovery. Whilst a standard claim might follow a predictable path, a complex case involves layers of dispute that require a senior-led approach. It’s the difference between a straightforward admission of fault and a multi-year battle over intricate liability.

A complex personal injury claims solicitor often deals with cases where liability is split across multiple defendants. This is common in large-scale construction accidents or multi-vehicle collisions. In these instances, the difficulty lies in untangling who is responsible for what percentage of the harm. When several parties are involved, each with their own legal team and insurers, the litigation becomes a sophisticated exercise in coordination and forensic evidence gathering.

High-value claims also introduce the challenge of predicting the future. When an injury is life-changing, the legal team must account for decades of lost earnings and care costs. This process of calculating compensation requires a deep understanding of the Personal Injury Discount Rate, which stands at +0.5% as of 2026, and how it affects lump-sum payments for future losses. Without this specialist expertise, there’s a risk that a settlement won’t cover the claimant’s lifelong needs.

The Difference Between Serious and Complex Injuries

A serious injury, such as a compound fracture, is physically devastating but legally straightforward if the cause is clear. Complexity arises when the medical prognosis is unstable or when the injury affects multiple aspects of a person’s life over many years. This is why a complex personal injury claims solicitor looks beyond the immediate diagnosis. They coordinate with multi-disciplinary experts to understand how an injury will evolve, ensuring the claim doesn’t settle prematurely for an inadequate sum. It’s about protecting your interests for the next thirty years, not just the next three.

Common Scenarios Requiring Specialist Complex Litigation

Certain environments naturally produce more intricate legal disputes. These often include catastrophic brain and spinal cord injuries that demand lifelong, 24-hour care regimes. Workplace accidents involving several contractors are equally challenging, as equipment failure must be forensically analysed to determine the root cause of the incident. Fatal accident enquiries also fall into this category, where the solicitor represents bereaved families during inquests and subsequent dependency claims. In modern litigation, international elements add another layer of difficulty. If an accident occurs abroad or involves a foreign-registered entity, jurisdictional challenges require a solicitor with worldly experience to navigate conflicting legal systems.

Proving liability in a standard slip-and-trip is one thing; establishing negligence in a high-stakes industrial environment or a multi-vehicle pile-up is quite another. In these non-standard settings, the burden of proof rests heavily on the claimant. A complex personal injury claims solicitor must meticulously organise evidence to transform a collection of facts into a robust, undeniable narrative. This often involves commissioning accident reconstruction specialists who use 3D modelling and forensic data to pinpoint the exact moment a safety protocol failed. It isn’t just about what happened; it’s about proving exactly why it was avoidable.

For those facing life-altering injuries, waiting years for a final settlement isn’t an option. Senior solicitors prioritise securing interim payments. These funds provide immediate relief for private rehabilitation, medical equipment, and daily living costs whilst the main litigation continues. It’s a pragmatic approach that ensures your recovery starts now, not when the court process concludes. Securing these payments early provides a sense of financial security that allows you to focus entirely on your physical and emotional wellbeing without the constant pressure of mounting bills.

The Role of Expert Witnesses in Complex Claims

Expert testimony is the bridge between a physical injury and legal compensation. Choosing the right medical or engineering specialists is a nuanced task. Whilst larger firms might rely on high-volume panels, a boutique firm hand-picks advisors whose expertise matches the specific nuances of your case. These party-specific advisors provide detailed reports that withstand intense cross-examination. In some instances, your legal strategy might also consider state-level support like the Industrial Injuries Disablement Benefit, though this is separate from the civil damages pursued by your solicitor. The goal is to create a comprehensive picture of your future needs that the court cannot ignore.

Managing Multi-Party Liability and Contributory Negligence

Complexity often peaks when liability is shared amongst multiple defendants, and a complex personal injury claims solicitor must ensure no party evades their responsibility. This requires a methodical, orderly legal mindset to ensure every potential defendant is correctly identified and served. Defendants frequently attempt to reduce their payout by alleging contributory negligence, arguing that the claimant was partly at fault for their own injuries. Defending against these tactics requires a solicitor who is both a sophisticated guide and a firm advocate. If you’re concerned about the intricacy of your accident, seeking senior-led litigation advice can help clarify the path forward and protect the full value of your claim.

Specialist Focus: Silicosis and Occupational Lung Diseases

The UK stone masonry sector is currently witnessing a troubling resurgence of respiratory conditions, largely driven by the popularity of engineered stone. In May 2026, the Health and Safety Executive (HSE) launched a concentrated programme of over 1,000 inspections to address the unacceptable practice of dry cutting, which puts an estimated 600,000 workers at risk of silica exposure annually. For a complex personal injury claims solicitor, these cases represent a unique intersection of medical science and statutory duty. Silicosis is a preventable but incurable occupational disease caused by silica dust. This condition, along with other Silicosis and Occupational Lung Diseases, often goes undetected for decades due to its long latency period.

Unlike a sudden traumatic accident, the “date of knowledge” for a disease claim might occur years after the initial exposure. This delay creates evidentiary challenges that require a methodical legal mind to overcome. A specialist solicitor must trace historical employment records and safety protocols to prove that the exposure was significant and attributable to a specific workplace environment. It’s about building a bridge between past negligence and current suffering.

Employer Negligence and Statutory Breach

Employers have a clear legal duty to maintain the workplace exposure limit for respirable crystalline silica at or below 0.1 mg/m³. Proving a breach involves demonstrating that an employer failed to implement dust controls that were “as low as reasonably practicable.” This includes providing high-standard respiratory protective equipment and ensuring adequate ventilation. If an original employer has ceased trading, your legal team will work to trace their historical insurers to ensure the claim can still proceed. This persistence is vital for securing the financial security needed to manage a progressive illness.

Legal Support for Bereaved Families

The impact of occupational disease often extends beyond the individual, affecting entire families. Pursuing a claim on behalf of a deceased loved one involves a sensitive but rigorous process of quantifying loss. This includes securing dependency payments for spouses and children who have lost financial support. For those navigating this difficult path, our silicosis claim after death guide provides a detailed roadmap for fatal accident litigation. A complex personal injury claims solicitor acts as a discreet partner during these times, ensuring the human impact of the loss is fully recognised by the court whilst handling the technical complexities of the litigation.

Complex Personal Injury Claims Solicitor: Navigating Life-Changing Litigation in 2026

Calculating Compensation: Securing Your Future

General damages compensate you for pain, suffering, and loss of amenity (PSLA). These figures are based on established judicial guidelines, but a complex personal injury claims solicitor ensures that every nuanced impact on your quality of life is professionally documented. Special damages cover your quantifiable financial losses. These include immediate medical bills, travel expenses, and the significant cost of home adaptations required to accommodate a disability. A settlement is not just a payout, but a financial blueprint for the rest of your life.

For younger claimants, calculating the loss of future earnings involves a “multiplier” effect. This process uses the Ogden Tables to estimate what you would have earned had the accident not occurred, accounting for career progression and pension contributions. As of 2026, the personal injury discount rate for England and Wales remains at +0.5%. This rate is used to calculate lump-sum compensation for future losses, and even a small percentage shift can significantly alter the final settlement. It’s a precise, mathematical exercise that requires a solicitor with a methodical and orderly legal mindset.

Future Care and Rehabilitation Needs

Securing your future involves assessing the lifelong costs of private nursing, specialised physiotherapy, and psychological support. In many high-value cases, we may advocate for Periodical Payment Orders (PPOs). These provide a guaranteed, tax-free income for life, which is adjusted annually for inflation. This approach offers a level of security that a single lump sum cannot always match, particularly when care needs are expected to increase as you age. A solicitor who looks beyond the immediate litigation will prioritise these structures to ensure you never run out of funds for essential care.

Personal Injury Trusts and Estate Planning

A successful claim often results in a significant sum that can inadvertently disqualify you from means-tested state benefits. We advise on the creation of Personal Injury Trusts to ring-fence your settlement, ensuring you maintain access to essential support whilst protecting your capital. This synergy between litigation and estate planning ensures your legacy and financial security are protected for the long term. If you are ready to discuss your case with a trusted advisor, you can speak with our senior solicitors to begin building your financial recovery plan.

The Feltons Approach: Boutique Care for Complex Needs

Choosing a complex personal injury claims solicitor is a decision that extends far beyond technical competence. It’s about finding a sophisticated guide who understands that behind every high-value dispute is a life that has been fundamentally altered. Feltons Solicitors LLP was established in 2010 with a commitment to providing discreet, high-standard service that prioritises personal connection over high-volume processing. We don’t believe in the “legal factory” model where cases are passed down to junior staff; instead, we provide senior-led attention for every complex matter we undertake.

Our approach bridges the gap between traditional professional integrity and modern efficiency. We provide pragmatic, plain-English advice that cuts through dense legalese, ensuring you remain fully informed at every stage of the litigation. This methodical flow mirrors a professional consultation, where information is presented in a highly organised manner to provide a sense of security and comprehensive care. By acting as a discreet partner, we value your privacy and personal rapport, ensuring that the human impact of your injury is never forgotten amongst the technical legal work.

A People-First Philosophy in Litigation

We believe that the technical success of a claim is only half the battle. A truly successful outcome is one where the claimant feels supported and empowered throughout the process. Our methodical and orderly approach to resolving high-stakes disputes ensures that every detail is captured, from the forensic evidence of the accident to the long-term psychological impact on the family. We prioritise the human element, recognising that the ultimate goal is your long-term rehabilitation and financial security. If you’re facing the challenges of life-changing litigation, we invite you to a confidential consultation to discuss your unique circumstances and explore how we can support your recovery.

National Expertise with a Personal Touch

Whilst we maintain the worldly experience necessary to handle complex, international-scale matters, we remain deeply rooted in our commitment to personalised care. We handle complex claims for clients across the United Kingdom, providing the strategic depth of a large firm with the tailored attention of a boutique practice. This combination allows us to manage intricate liability disputes and high-value compensation calculations with quiet confidence. Whether you require assistance with a catastrophic injury or a specialist silicosis claim, our team acts as a trusted advisor to secure the settlement you deserve. If you’re seeking a partner who values your future as much as you do, contact our senior solicitors to begin your journey toward financial stability and peace of mind.

Navigating the aftermath of a catastrophic injury requires more than just legal representation; it demands a partnership with a trusted advisor who understands the lifelong implications of your claim. We’ve explored how identifying the nuances of liability and precisely calculating future care costs are essential steps in protecting your long-term wellbeing. Whether you are managing the challenges of a specialist occupational disease or a life-changing accident, the right complex personal injury claims solicitor provides the steady, methodical guidance necessary to build a robust case.

Feltons Solicitors LLP offers senior-led expertise with a national reach, ensuring you receive boutique levels of care without sacrificing the worldly experience required for high-value litigation. We prioritise personal connection and traditional professional integrity to help you move forward with confidence. If you are ready to protect your future, speak with a specialist complex personal injury solicitor at Feltons Solicitors today. You don’t have to navigate these intricate challenges alone.

Frequently Asked Questions

What makes a personal injury claim “complex” in the eyes of the law?

Complexity is defined by legal, medical, or procedural hurdles rather than physical severity alone. It typically involves cases with multiple defendants, international jurisdictional issues, or intricate liability disputes where fault is contested. High-value claims requiring decades of future loss calculations also fall into this category. A complex personal injury claims solicitor manages these layers of difficulty to ensure that the litigation narrative is forensically sound and addresses all multi-disciplinary hurdles.

How long do I have to start a complex personal injury claim in the UK?

You generally have three years from the date of the accident or the “date of knowledge” of the injury to begin legal proceedings. This limit is governed by the Limitation Act 1980. For occupational diseases like silicosis, the three-year clock starts when you reasonably knew your illness was significant and caused by your work. It’s vital to seek senior-led advice early to ensure evidence is preserved and court deadlines are met.

Can I change my solicitor if I am unhappy with how my complex claim is being handled?

Yes, you have the right to transfer your case to a different firm at any stage of the litigation. Many claimants move from high-volume “legal factories” to a boutique complex personal injury claims solicitor to receive more personal, senior-led attention. Your new solicitor will coordinate the transfer of your file and handle the lien on your costs, ensuring the transition is smooth and your case remains on track for success.

What are interim payments, and can I receive them before my case is settled?

Interim payments are advance sums paid out of the final settlement to cover immediate needs like private rehabilitation, medical equipment, or lost earnings. You can receive them once the defendant has admitted liability or if the court is satisfied you will win. These payments are crucial for maintaining financial security during long-running disputes. They ensure you don’t have to wait years to access the care and home adaptations you need right now.

Will my complex personal injury claim have to go to court?

Most claims are settled through negotiation, with approximately 97% of personal injury cases in England and Wales concluding without a full trial. Whilst your solicitor will prepare every case as if it’s going to court to maintain a position of strength, a settlement is often reached during mediation. If a trial is necessary, your senior solicitor will provide a steady, calm presence to guide you through the process and represent your interests.

How is compensation calculated for life-changing injuries?

Compensation is split into general damages for pain and suffering and special damages for quantifiable financial losses. For life-changing injuries, we use the Personal Injury Discount Rate, currently +0.5%, to calculate lump-sum payments for future care and lost earnings. We also consider the “multiplier” effect for younger claimants. This methodical approach ensures your settlement acts as a comprehensive financial blueprint for your lifelong needs and provides long-term security.

What is a Personal Injury Trust, and do I need one?

A Personal Injury Trust is a legal arrangement that holds your compensation separately from your personal finances. This is often necessary to ensure your settlement isn’t “means-tested,” allowing you to remain eligible for certain state benefits. By ring-fencing these funds, you protect your capital for its intended purpose: your long-term care and rehabilitation. Your solicitor can advise on the synergy between litigation and estate planning to protect your legacy and future support.

Can I claim for silicosis if I was exposed to silica dust many years ago?

Yes, you can claim for silicosis even if exposure occurred decades ago, provided you are within three years of your “date of knowledge.” Because occupational lung diseases have long latency periods, the law allows for claims to proceed once symptoms are diagnosed. We trace historical insurers for companies that may have ceased trading, ensuring that the human impact of past negligence is addressed through contemporary legal action and financial support.

Will Solicitors: A Comprehensive Guide to Protecting Your Estate in 2026

Will Solicitors: A Comprehensive Guide to Protecting Your Estate in 2026

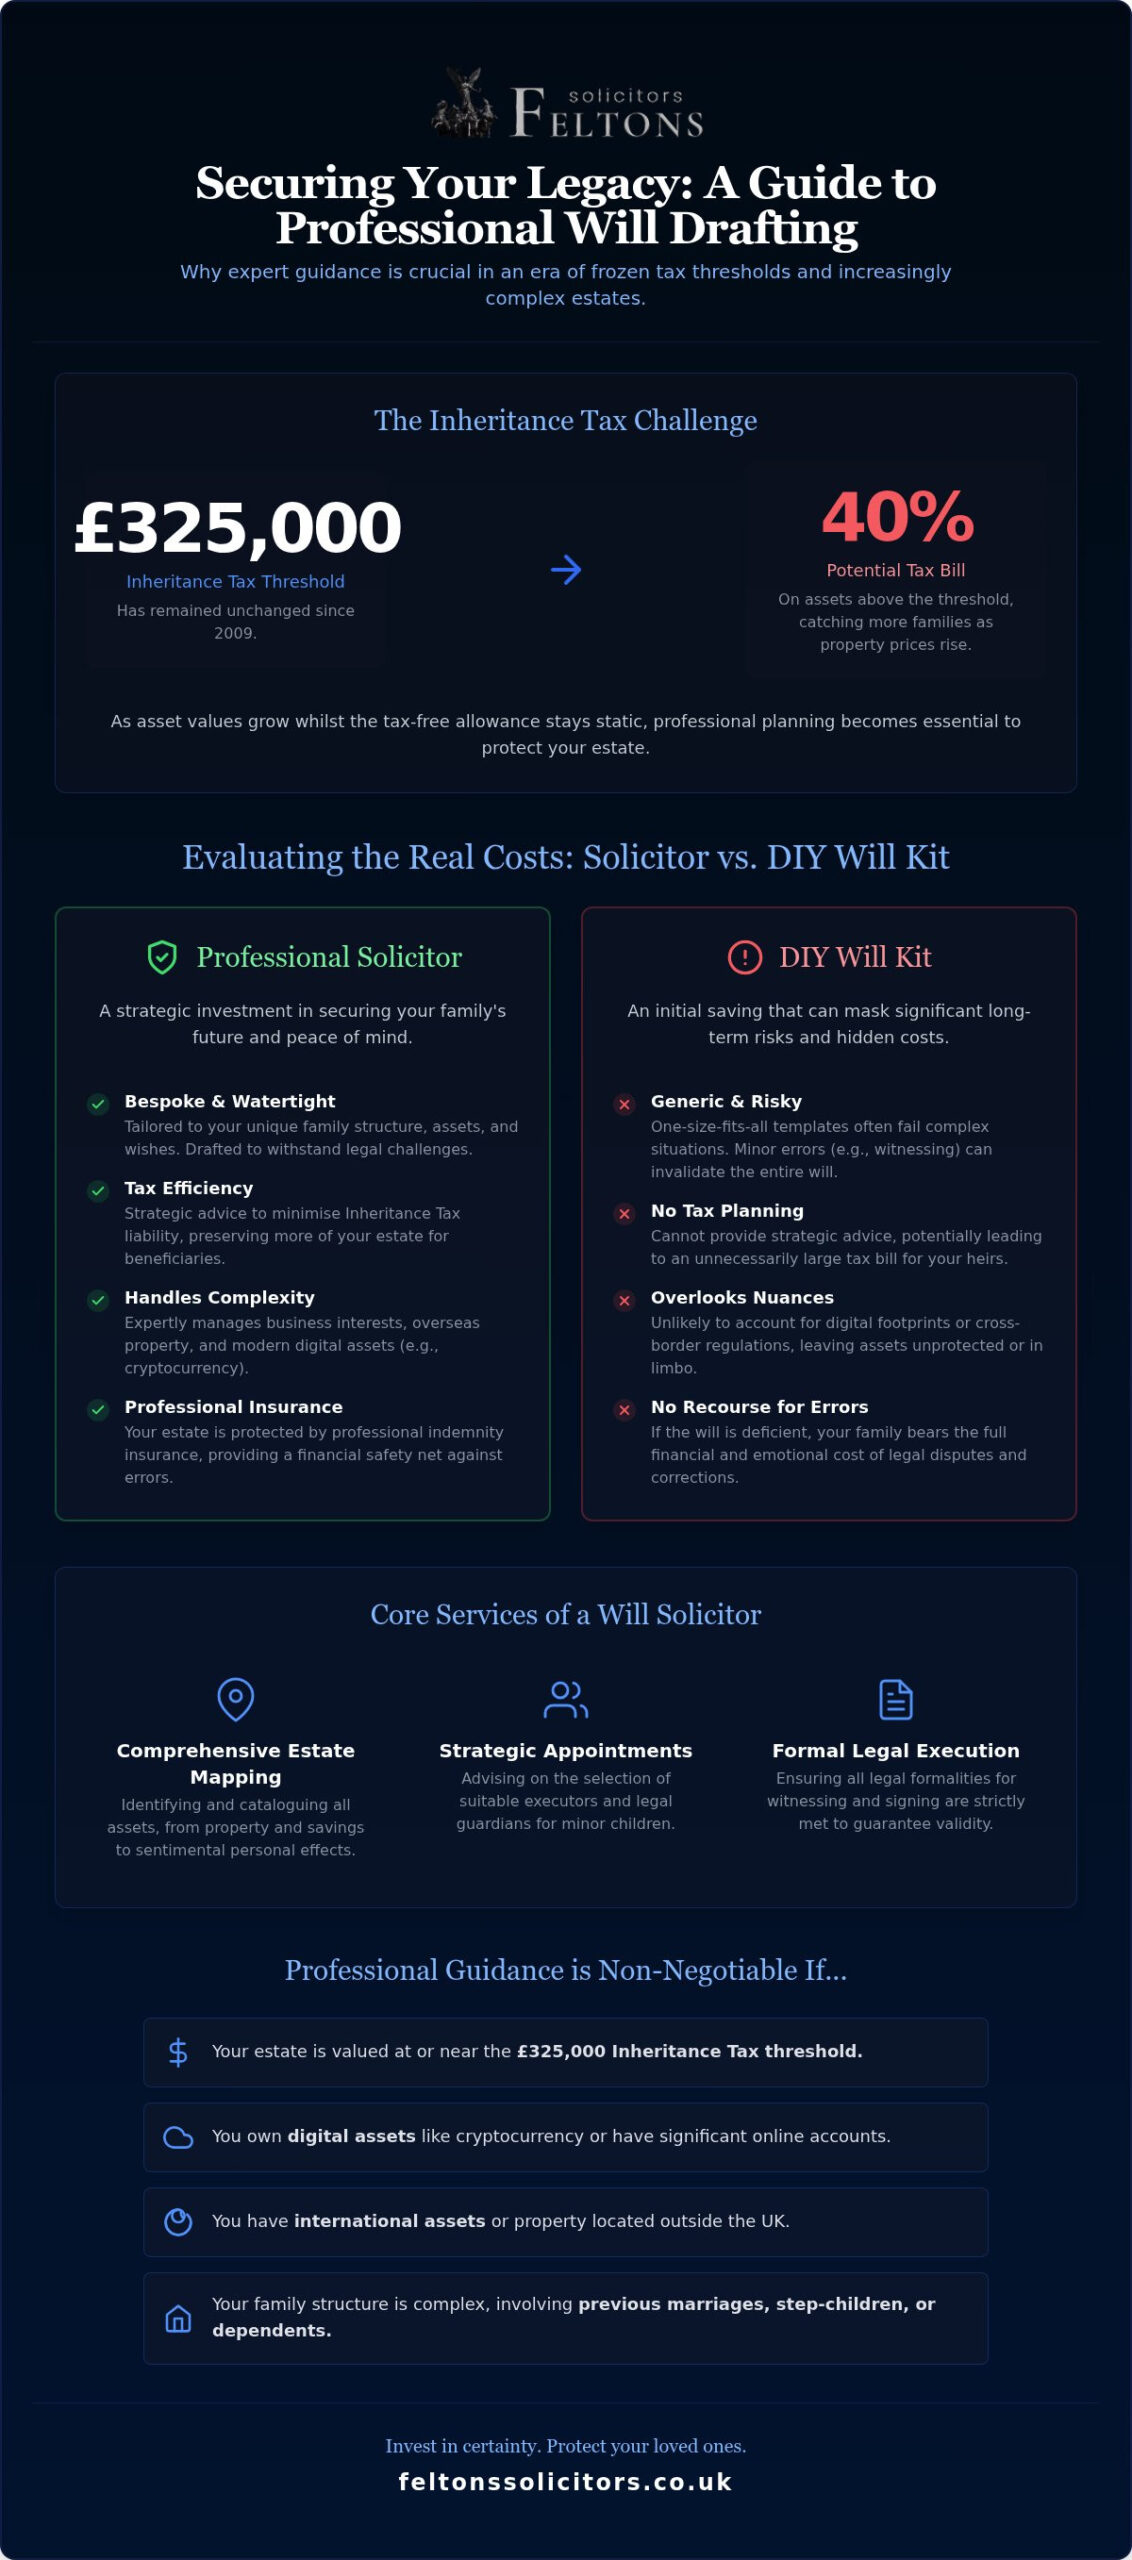
The £325,000 Inheritance Tax threshold has remained frozen since 2009. This means that as property prices continue to climb in 2026, more families find themselves unexpectedly liable for a 40% tax bill. It’s understandable to feel a sense of unease regarding the rules of intestacy or the potential invalidity of a DIY document, which is why many now seek out expert will solicitors to secure their legacy. You deserve the certainty that your life’s work will benefit the people you love most, rather than being lost to administrative errors or avoidable taxes.

Professional guidance allows you to transform a simple document into a strategic shield for your family’s future. This guide demonstrates how expert advice can help you navigate complex thresholds, protect modern digital assets, and ensure your final wishes are entirely watertight. We’ll explore the practical steps you can take today to secure your estate, provide lasting peace of mind for your beneficiaries, and establish a clear, professional plan for asset protection.

Key Takeaways

  • Understand how expert will solicitors provide more than just a document by offering strategic advice on asset distribution and legal compliance to protect your legacy.
  • Learn why the immediate savings of a DIY kit often lead to significant risks. Professional drafting ensures your estate remains tax-efficient and legally watertight.
  • Discover how to incorporate complex modern interests, such as digital assets and overseas property, into a legally binding UK framework.
  • Gain a clear roadmap of the professional consultation process, from identifying your core objectives to creating a comprehensive map of your financial world.
  • Explore how integrating your will with Lasting Powers of Attorney ensures total protection for both your assets and your personal welfare during your lifetime.

What Do Will Solicitors Do and Why Are They Essential?

Will solicitors are legal professionals who specialise in the precision-led drafting, witnessing, and execution of testamentary documents. Whilst it’s possible to write a basic expression of your wishes on a piece of paper, a solicitor ensures that those wishes are translated into a legally binding framework. They provide strategic oversight, ensuring that every asset is accounted for and that your distribution plan complies with current UK law. This professional guidance is about more than just paperwork; it’s about providing a steady presence during a complex life stage.

If you die without a valid will, your estate is subject to the rules of intestacy. This rigid legal process dictates who inherits your assets based on a strict hierarchy, often excluding unmarried partners, step-children, or close friends. By engaging a professional, you prevent the state from making these deeply personal decisions on your behalf. Expert involvement also creates a robust defence against future legal challenges. They ensure your document is resilient against claims of undue influence or lack of testamentary capacity, which are common grounds for contesting a will in the UK courts.

The Core Responsibilities of Your Legal Advisor

A trusted advisor takes a methodical approach to your affairs, ensuring no detail is overlooked. Their core responsibilities include:

  • Estate Mapping: Identifying the full scope of your estate, including property, savings, and sentimental personal effects.
  • Strategic Appointments: Advising on the selection of suitable executors and, crucially, legal guardians for minor children to ensure they’re cared for by people you trust.
  • Formal Execution: Ensuring that all legal formalities for witnessing and signing are strictly met. Even a minor technical error can render a will invalid, leading to significant distress for your loved ones.

When Professional Intervention is Non-Negotiable

Certain circumstances demand a higher level of technical expertise that a DIY kit simply cannot provide. If your family structure involves complex dynamics, such as children from previous relationships or multiple marriages, standard templates often fail to provide adequate protection for all parties. Professional intervention is equally vital for estates exceeding the £325,000 Inheritance Tax threshold. In these cases, strategic planning can significantly reduce the tax burden on your heirs. For those with business interests or international assets, will solicitors ensure that your UK will works in harmony with overseas regulations, providing a seamless transition of wealth across borders.

Solicitors vs. DIY Will Kits: Evaluating the Real Costs

The appeal of a DIY will kit is obvious: it’s inexpensive and can be completed in an afternoon. However, the immediate saving often masks a significant long-term risk. Unlike a static template, will solicitors provide a strategic shield that accounts for the nuances of your specific life circumstances. Shop-bought kits are designed for the “average” person, but few lives are truly average. When you opt for professional drafting, you’re investing in a document that is built to withstand scrutiny.

One of the most critical differences is the protection of professional indemnity insurance. If a solicitor drafts a document that is later found to be deficient, your estate has legal recourse. With a DIY document, your family is left to bear the financial burden of any errors alone. This financial safety net is a cornerstone of professional practice, providing a level of security that a simple form cannot replicate. It’s the difference between a generic product and a bespoke legal service.

The True Price of a ‘Cheap’ Will

A ‘cheap’ will often becomes an expensive legacy. Vague language, such as failing to define “personal effects” or “residuary estate” clearly, frequently leads to bitter litigation amongst beneficiaries. If the document is declared invalid due to a witnessing error, your estate falls under the rules of intestacy. Investing in professional fees now often saves your heirs tens of thousands of pounds in future legal costs. It also prevents the emotional toll of family disputes during an already difficult time.

Why Empathy and Expertise Matter

A sophisticated guide does more than fill in blanks. They act as a trusted advisor, identifying risks you might not have considered. For instance, the Property (Digital Assets etc) Act 2025 now requires specific consideration for cryptocurrency and online accounts. A template won’t ask about your digital footprint, but a specialist will.

At Feltons, we pride ourselves on delivering pragmatic, plain-English advice that prioritises your family’s unique dynamics. We understand that discussing your final wishes requires a delicate balance of technical precision and human empathy. If you’re ready to move beyond templates, you can explore our estate planning services to discuss a tailored approach to your estate. Our goal is to ensure your legacy is handled with the quiet confidence it deserves.

Managing Complex Assets: Digital Legacies and Overseas Interests

The modern estate has evolved significantly beyond physical property and traditional bank accounts. Today, your legacy likely includes a vast array of intangible assets, from cryptocurrency portfolios to professional social media presence and intellectual property. Expert will solicitors now play a vital role in ensuring these modern interests are not lost or locked away forever. Without specific provisions, your executors may find themselves legally barred from accessing essential online accounts, leading to the permanent loss of both financial value and sentimental memories.

The Rise of the Digital Estate

Digital assets encompass everything from online banking and investment platforms to digital creative works and loyalty points. To manage these effectively, your will must grant executors explicit legal authority to interact with service providers. This prevents a “digital dark age” where your online footprint becomes an inaccessible burden for your family. Under 2026 legal standards, a digital legacy is defined as the collective body of a person’s online data, digital property, and social presence that persists after their death.

Strategic planning involves more than just listing passwords; it requires a structured approach to asset discovery. We advise clients to maintain a secure, offline inventory of their digital holdings, which can be referenced in the will without compromising security. This ensures that assets like Bitcoin or NFTs, which are now formally recognised under the Property (Digital Assets etc) Act 2025, are identified and transferred according to your wishes rather than being forgotten in the depths of the blockchain.

International Assets and Overseas Entities

Owning property abroad introduces a layer of complexity that a standard UK will may not fully address. Different jurisdictions have varying rules on “forced heirship,” which can override your stated intentions if not managed correctly. Coordinating your UK arrangements with foreign legal requirements is essential to prevent conflicting instructions and protracted probate disputes. Professional drafting ensures that your global footprint is managed as a single, cohesive strategy.

For individuals with assets or interests in the United States, The Village Law Firm provides the specialised estate planning and administration expertise necessary to ensure your legacy is protected across different legal jurisdictions.

The landscape of property ownership has also been reshaped by transparency requirements. Understanding how overseas entity beneficial owner registration impacts your estate is crucial for those holding UK property through foreign structures. Failure to maintain these registrations can lead to significant delays in the transfer of property to your beneficiaries. By addressing these cross-border issues proactively, will solicitors help you mitigate the risk of international assets becoming a legal or financial liability for your heirs. We provide the discreet, worldly experience necessary to handle these intricate matters with precision.

Will Solicitors: A Comprehensive Guide to Protecting Your Estate in 2026

The Step-by-Step Process of Working with Will Solicitors

Engaging with will solicitors isn’t a mere transaction; it’s a methodical journey toward total peace of mind. The process begins with an initial consultation designed to establish trust and clarity. We don’t just ask about your assets; we seek to understand your primary objectives and the specific people you wish to protect. This isn’t a high-volume processing exercise. It’s a boutique experience where your personal connection to your legacy is prioritised from the very first meeting.

Following the consultation, we move into the vital phase of asset discovery. This is where we create a comprehensive map of your financial and personal world. We look beyond the obvious, examining property, savings, and those complex digital assets that define modern life. This methodical approach ensures that every facet of your estate is accounted for, leaving no room for ambiguity or future dispute. It’s about building a foundation that is both legally robust and personally meaningful.

Preparing for Your Consultation

To make the most of your time, it helps to gather key documents before we meet. Think about your pensions, property deeds, and life insurance policies. Consider your legacy in broader terms too. Are there charitable donations you’d like to make? Do you have specific bequests for sentimental items? Feltons’ methodical flow ensures that even the smallest detail is captured, reflecting our commitment to traditional professional integrity and modern efficiency.

Refining Your Wishes

Drafting is an iterative process. You’ll review the document with your solicitor to ensure it reflects your exact wishes with absolute precision. We’ll refine the language to ensure it’s legally watertight whilst remaining respectful to your beneficiaries. This stage also involves adjusting for tax efficiency. With the Inheritance Tax nil-rate band frozen at £325,000 until 2031, strategic drafting is essential to protect your heirs from unnecessary fiscal drag. We ensure the tone of the document remains clear, avoiding dense legalese in favour of plain English.

The final, critical step is the formal execution. The signing and witnessing ceremony must strictly adhere to legal formalities to ensure the will’s validity. Once complete, secure storage is paramount. We’ll advise on where to keep the original document and how to notify your executors of its location. A will is only effective if it can be found and verified when it’s needed most. If you’re ready to begin this methodical journey, you can contact our team of will solicitors today to discuss your requirements. We’re here to provide the calm, steady presence you need to secure your family’s future.

Beyond the Will: Integrated Asset Protection and Probate

A will shouldn’t exist in a vacuum. To achieve total protection, your testamentary wishes must be woven into a broader framework of estate planning. This integrated approach ensures that your assets are managed efficiently both during your lifetime and after you’ve passed. Whilst a will handles the distribution of your legacy, Lasting Powers of Attorney (LPA) safeguard your interests whilst you’re still alive. These documents allow you to appoint trusted individuals to make decisions about your health and finances if you ever lose the capacity to do so yourself.

Major life changes also necessitate a fresh look at your legal arrangements. If you’re navigating the end of a relationship, consulting a divorce and financial arrangements lawyer is vital. Marriage usually revokes an existing will; divorce can leave significant gaps in your estate’s protection. Expert will solicitors ensure that your updated documents reflect your new financial reality, preventing assets from inadvertently passing to an ex-partner.

Wills and Property Law

There is a powerful synergy between residential property law and the distribution of your estate. Your home is likely your most significant asset, so handling its transfer requires precision. We provide guidance on complex matters like leasehold extensions and enfranchisement, ensuring these property rights are maximised before they pass to your heirs. By using clever trust structures, we can help you protect the family home from being depleted by long-term care costs or unnecessary tax liabilities.

Probate and Estate Administration

When the time comes, the transition to probate should be as seamless as possible. Our role involves applying for a Grant of Probate, which gives executors the legal authority to manage your affairs. We handle the heavy lifting: settling outstanding debts, paying the correct amount of Inheritance Tax, and ensuring assets are distributed exactly as you intended. This methodical process provides a sense of security during a difficult time.

The practical side of estate administration often involves managing physical assets and property contents. In such cases, families may find that Clear This Ltd House Clearance Services offers a sensitive and professional way to handle house clearance throughout the Lancashire area.

Feltons’ “people-first” philosophy is particularly crucial during this stage. We act as a calm, steady presence for your family, handling the technical complexities so they can focus on their own well-being. By choosing experienced will solicitors, you ensure that the same high standard of care you received during the drafting process continues long after you’re gone. We remain your family’s discreet partner, protecting your legacy with traditional integrity and modern efficiency.

Securing Your Legacy for the Next Generation

Protecting your life’s work requires more than a simple document; it demands a strategic vision that accounts for both traditional property and modern digital assets. By moving beyond the limitations of DIY templates, you ensure your estate is resilient against legal challenges and tax inefficiencies. Expert will solicitors provide the steady, professional guidance needed to navigate these complexities with quiet confidence. Our boutique service combines national-level expertise with pragmatic, plain-English advice tailored specifically to your family’s unique dynamics.

Whether you’re managing a global asset portfolio or simply wish to provide peace of mind for your loved ones, a methodical approach is the most reliable way to safeguard your final wishes. We specialise in complex and international estate matters, ensuring that every detail is handled with discretion and integrity. It’s never too early to establish a clear plan for the future. You can book a confidential consultation with our specialist will solicitors to begin securing your legacy today. Taking this proactive step provides the certainty and security that you and your family deserve.

Frequently Asked Questions

How much do will solicitors typically charge in 2026?

Fees vary based on the complexity of your estate and the specific requirements of your family structure. A straightforward single document is generally more cost-effective than mirror wills for couples or complex arrangements involving trusts and overseas assets. We recommend discussing your needs during a consultation to receive a transparent estimate tailored to your circumstances. Investing in professional expertise ensures your document is robust, legally binding, and built to withstand future scrutiny.

Can I change my will after it has been signed and witnessed?

You can change your will at any time as long as you have the mental capacity to do so. For minor adjustments, a legal document called a codicil can be added to the existing will. However, if you wish to make significant changes, it’s usually better to draft a completely new document to avoid confusion or potential conflict. Your solicitor will ensure any updates are executed with the same formal rigour as the original.

What is the difference between an executor and a beneficiary?

An executor is the person responsible for managing your estate and carrying out the instructions in your will, whereas a beneficiary is someone who receives assets or property from the estate. It’s common for a person to be both an executor and a beneficiary, such as a spouse or adult child. Selecting an executor requires careful thought, as the role involves significant legal and financial responsibilities during the probate process.

How often should I review my will with a solicitor?

It’s advisable to review your will every three to five years to ensure it still reflects your wishes and financial situation. Certain life events make an immediate review essential, including marriage, divorce, the birth of children, or a significant change in your asset portfolio. Regular consultations with will solicitors allow you to adjust for legislative changes, such as updated tax thresholds or new regulations regarding digital property and overseas interests.

Do I need a separate will for property I own abroad?

Whether you need a separate will depends on the country where your property is located and its specific inheritance laws. Some jurisdictions have forced heirship rules that may conflict with your UK will. In many cases, having a local will in that country is the most efficient way to handle the property. Your UK solicitor will work to ensure your various testamentary documents are coordinated and don’t contain contradictory instructions.

What happens if my will is lost or destroyed?

If a will cannot be found after your death, the law may presume that you destroyed it with the intention of revoking it, which could lead to your estate being distributed under the rules of intestacy. This is why secure storage is so important. Whilst a copy may sometimes be accepted by the probate registry, the process is complex and requires significant evidence. Storing your original document with a professional firm provides a vital safety net.

Can a will be challenged in court after I die?

Yes, a will can be challenged in the UK courts on several grounds, including claims that the document was not properly executed or that the testator lacked mental capacity. Challenges can also arise under the Inheritance (Provision for Family and Dependants) Act 1975 if a close relative feels they haven’t been adequately provided for. Will solicitors use their expertise to draft robust documents that minimise the risk of these stressful and costly legal disputes.

Is a will made in 2026 valid if I move house or get married?

Moving house doesn’t invalidate your will, but getting married or entering a civil partnership usually revokes any existing document entirely unless it was made in expectation of that specific marriage. Conversely, divorce doesn’t revoke a will, but it treats your former spouse as if they had died before you, which can create unintended gaps in your distribution plan. You should always seek legal advice following these major life changes to ensure total protection.