Buy to Let Conveyancing Solicitor UK: A 2026 Buying Guide

Buy to Let Conveyancing Solicitor UK: A 2026 Buying Guide

A buy-to-let purchase is ready to proceed when the property’s legal position, its letting terms and any mortgage conditions have been considered together. A flat may look ideal as an investment, but a lease restriction or title condition could affect your plans to let it. A residential mortgage may also have terms that do not fit your intended use. A buy to let conveyancing solicitor UK investors appoint can help identify these issues before you become contractually committed.

Although the process has similarities to buying a home, a rental purchase brings extra questions. You need to understand whether the property documents raise issues for letting and whether the lender’s requirements reflect your plans. Addressing those points before exchange gives you a clearer basis for deciding how to proceed.

This guide explains the solicitor’s role, the title, lease and mortgage matters that may affect a buy-to-let purchase, and how conveyancing fits into the wider process. It also sets out what information to prepare and which decisions to consider before exchange.

Key Takeaways

  • A buy to let conveyancing solicitor UK buyers appoint reviews the contract, title and relevant enquiries in light of the property’s intended rental use.
  • Before exchange, consider whether title conditions, lease terms or other property-specific matters could affect your plans to let.
  • If you are using a mortgage, consider the lender’s requirements alongside the property’s legal position and your intended use.
  • Prepare the transaction details, property information and lender correspondence, then review the legal advice before deciding whether to exchange.
  • Feltons Solicitors LLP provides tailored residential and commercial conveyancing, with pragmatic guidance shaped around the circumstances of your purchase.

Role of a buy-to-let solicitor in a UK property purchase

Buy-to-let conveyancing is the legal work involved in transferring a property to a buyer who intends to rent it out. A solicitor reviews the contract and transaction documents, investigates the legal title and raises relevant enquiries. This helps you understand what you are buying and identify legal matters that could affect your plans.

Buy-to-let conveyancing examines the legal position of the property and purchase in light of the buyer’s intended use. The work depends on the property, its tenure, the transaction and the jurisdiction. It does not predict rental income or guarantee that a property will be suitable as an investment.

How does buy-to-let conveyancing differ from a home purchase?

The core process is still a property transaction, but your intended use affects which questions need particular attention. For example, the solicitor may consider whether title conditions or lease terms affect letting, and whether the mortgage arrangements reflect your plans. There is no identical checklist for every rental purchase: enquiries should respond to the documents and circumstances of the specific property. Conveyancing procedures also vary across England and Wales, Scotland and Northern Ireland.

What can a solicitor help you understand before exchange?

Before exchange, your solicitor reviews the contract and title, considers relevant search results and replies to enquiries, and explains legal issues that arise. If a document appears to restrict letting, for example, you can understand what it says and why it may matter before deciding how to proceed. This legal due diligence informs your decision, but does not assess likely rent, investment returns or future property values.

For a purchase with mortgage funding, the conveyancer also deals with the lender’s legal requirements as part of the transaction. The lender assesses the borrowing under its own criteria, while the solicitor handles the legal work and reports relevant matters in line with the transaction requirements. These responsibilities are connected but distinct. If the property’s legal position or your intended use raises a question, clear advice can help you consider it before exchanging contracts.

It is useful to separate three kinds of decision:

  • Legal due diligence: What do the title, contract, searches and relevant replies tell you about the property and purchase?
  • Tax planning: What tax may apply to your circumstances? Legal explanations about the transaction do not replace tailored tax advice.

A buy to let conveyancing solicitor UK buyers instruct can explain the legal documents and flag issues relevant to the proposed purchase. Feltons provides residential and commercial conveyancing, with pragmatic guidance tailored to the details of the transaction. The focus is on helping you understand the legal issues, not promising rental performance or a particular outcome.

For a landlord buyer, the title and contract checks establish what rights come with the property and what obligations or restrictions may shape its use. The relevant enquiries depend on the property and your plans. A buy to let conveyancing solicitor UK buyers instruct can focus the legal review on those circumstances, rather than applying the same checklist to every purchase.

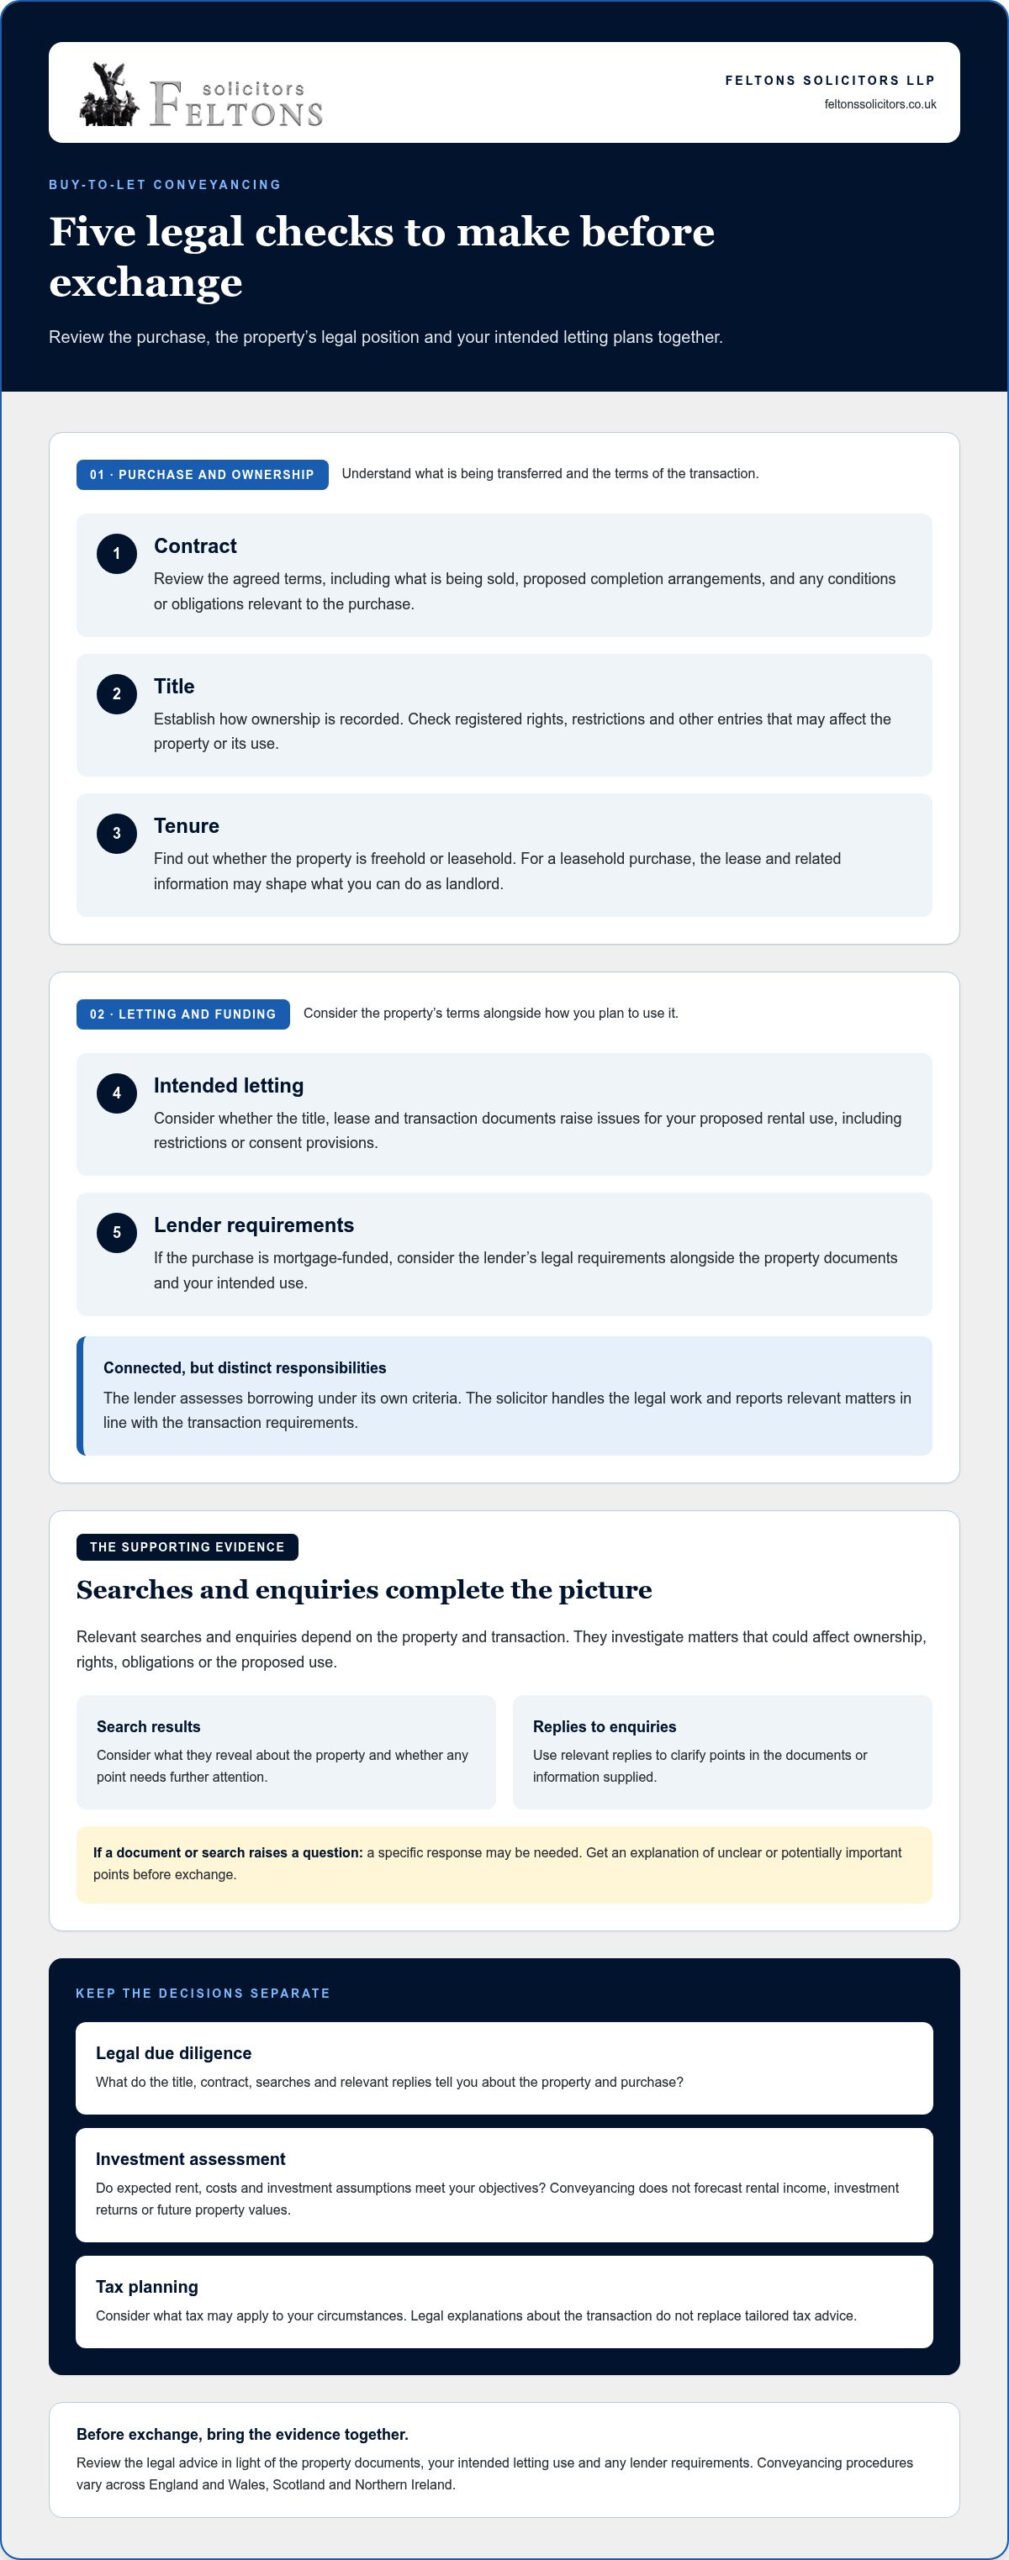
Before exchange, consider these connected parts of the transaction:

  • Contract: Review the agreed terms, including what is being sold, the proposed completion arrangements and any conditions or obligations relevant to the purchase.
  • Title: Establish how ownership is recorded and identify registered rights, restrictions or other entries that may affect the property or its use.
  • Tenure: Understand whether the property is freehold or leasehold. For a leasehold purchase, the lease and related information may shape what you can do as landlord.
  • Intended letting: Consider whether the title, lease and transaction documents raise issues for the proposed rental use, including relevant restrictions or consent provisions.
  • Lender requirements: If the purchase is mortgage-funded, consider the lender’s legal requirements alongside the property documents and your intended use.

Searches and enquiries add to the picture. Which are relevant depends on the property and transaction; they investigate matters that could affect ownership, rights, obligations or the proposed use. If a search or document raises a question, a specific response may be needed before you decide whether to proceed.

What should the title and contract review cover?

The title review helps explain who owns the property, what rights are recorded in connection with it and whether any entries appear to limit or qualify its use. The contract sets out the terms on which the seller proposes to transfer the property. Enquiries can clarify points in the documents or information supplied. Since the documents differ from one purchase to another, the review should respond to what they reveal.

If something is unclear or potentially important, get an explanation before exchange. You can then weigh the legal information against your plans and make an informed decision about proceeding.

How can letting restrictions affect the purchase?

A title entry or lease term may affect whether, or on what terms, a property can be rented out. A lease might contain covenants about occupation or letting, or set out a process for seeking consent. The wording and context matter: consent is not automatically required in every case, and different restrictions can have different effects. Your conveyancer can explain the relevant provision and any issue it raises for your proposed use.

Where legal checks prompt questions, tailored residential conveyancing guidance can help you understand the documents and consider next steps before exchange. Resolve the legal picture as far as possible before committing. Do not assume a restriction is harmless or that it automatically prevents letting.

Tenure and funding raise different legal questions, so a standard residential checklist may not cover every concern relevant to a rental purchase. Freehold and leasehold describe the property interest being bought; mortgage-funded describes how the purchase is financed. Consider all three together, while keeping property permissions separate from the lender’s conditions.

Purchase type Legal focus Question for a landlord buyer
Freehold Review the title, registered rights, restrictions and contract terms affecting the property. Could any right or restriction recorded against the title affect the intended letting or use?
Leasehold Consider the lease, including relevant covenants, consent provisions and obligations attached to the property. Do the lease terms affect whether or how the property may be rented out?
Mortgage-funded Consider the lender’s legal requirements and the terms of the proposed borrowing. Do the lending terms reflect the plan to let, as well as the transaction being carried out?

The property documents and lending conditions answer different questions. A title or lease may affect your rights in relation to the property; mortgage terms govern your relationship with the lender. Satisfying one does not automatically resolve the other. A buy to let conveyancing solicitor UK buyers instruct considers the legal details of the transaction in context, while mortgage suitability and investment decisions remain separate considerations.

What changes between a freehold and leasehold buy-to-let?

With a freehold purchase, the title review focuses on ownership and registered rights or restrictions. A leasehold review also considers the lease’s wording and obligations, including provisions that may relate to letting. If the terms raise questions, you can understand their significance before exchange. A lease variation or leasehold enfranchisement is a distinct legal matter, not an automatic step in buying a leasehold property.

Why must the mortgage match the intended use?

Tax is another separate consideration, and terminology differs across the UK. Buyers may encounter Stamp Duty Land Tax in England and Northern Ireland, Land and Buildings Transaction Tax in Scotland, or Land Transaction Tax in Wales. The applicable treatment depends on the jurisdiction and the buyer’s circumstances, so do not assume one nation’s terminology or rates apply elsewhere. Keep tax planning distinct from title, lease and mortgage checks, and consider the rules that apply where the property is located.

Compare the transaction on its own facts: identify the tenure, understand any letting-related provisions and consider the lender’s requirements against your intended use. This joined-up view can help reveal questions to address before exchange without treating every freehold, leasehold or mortgage-funded purchase as legally identical.
Buy to Let Conveyancing Solicitor UK: A 2026 Buying Guide

How can you prepare for buy-to-let conveyancing before exchange?

Good preparation gives your conveyancer a clearer picture of the purchase and what you intend to do with the property. Share the relevant details early, including your letting plans and any concerns already raised by the seller or agent. A buy to let conveyancing solicitor UK buyers instruct can then consider the transaction in light of the proposed use and follow up on points that need attention.

Use this sequence to organise your preparation:

  1. Clarify your intended use. Set out whether you plan to let the whole property or only part of it, and describe the expected occupancy arrangement as clearly as you can.
  2. Gather the property information. Collect the property particulars, sale details, available title or lease documents, and information about the property’s current use or tenure.
  3. Share purchase and lender details. Provide the agreed transaction information and relevant mortgage correspondence or lender requirements if the purchase is mortgage-funded.
  4. Flag concerns promptly. Tell your solicitor about known title or lease terms, proposed alterations, occupancy plans or anything you have been told could affect letting.
  5. Review the legal advice before exchange. Make sure you understand material enquiries, outstanding points and their implications before deciding whether to proceed.

What information should you have ready?

Bring together documents you already hold rather than trying to obtain every record yourself. Useful items may include the sale memorandum or other purchase details, property particulars, available title information and the lease if the property is leasehold. Add mortgage correspondence relating to the proposed borrowing. A concise note of your intended letting arrangement and any known concerns about use or permissions can help your solicitor focus enquiries on the transaction.

Which decisions should you make before exchange?

Before exchange, consider whether you understand the answers to important enquiries and any unresolved issue that could affect your intended use. If a permission or lender condition is unclear, raise it with your conveyancer and ask them to explain its legal significance. Broader residential property law guidance can help put the purchase process in context, while advice on your transaction should address its specific documents and circumstances.

Preparation does not mean deciding every investment question through conveyancing. It means giving your solicitor accurate information, reading the advice carefully and considering the legal position before becoming committed. If an answer changes your plans, discuss the implications before exchange rather than relying on assumptions about the property or lender requirements.

Feltons provides tailored residential and commercial conveyancing, with pragmatic guidance shaped around the details of each transaction. Discuss your conveyancing requirements with Feltons as you prepare for a buy-to-let purchase.

How Feltons supports buy-to-let conveyancing across the UK

Buying a rental property involves decisions specific to the property, its legal documents and your intended use. Feltons provides residential and commercial conveyancing with pragmatic, tailored guidance to help you understand the legal work involved. The firm serves national and international clients and takes a bespoke approach that keeps the circumstances of each purchase in view.

A buy to let conveyancing solicitor UK buyers work with should make the legal position understandable, especially when documents or enquiries raise questions. Feltons combines modern delivery with traditional values, offering discreet support as you consider the legal implications of your purchase. The focus is on the transaction and relevant legal advice, not on predicting rental returns or promising a particular result.

What can a tailored conveyancing approach offer?

A tailored approach considers the property and transaction on their own facts. A leasehold flat, for example, may raise different document questions from a freehold house, while the proposed letting use can influence which enquiries are relevant. Clear explanations help you understand what an issue means legally and which decisions may need your attention before exchange.

Practical guidance can also help you distinguish a legal concern from a wider investment or management decision. Feltons’ bespoke service model addresses the specific circumstances of your purchase, with advice delivered in a considered, approachable way. This supports informed discussion without implying that every transaction follows the same route.

What is the next step for your property purchase?

To begin a focused discussion, outline the property, whether it is freehold or leasehold, and how you intend to let it. Mention whether you are buying with mortgage funding and share any known concerns about the title, lease or proposed use. These details help frame the conversation around the legal support relevant to your transaction.

Feltons can discuss your conveyancing requirements and explain how the firm can support the purchase. Home visits are available at clients’ convenience, offering another way to discuss your matter. Discuss your buy-to-let conveyancing matter with Feltons and outline the property and your plans for it.

Take your next step with clarity

Before your purchase moves forward, prepare a clear brief: what you want to buy, how you intend to let it and which points still need a legal answer. This gives your conveyancer a practical starting point and helps you focus on decisions that matter to the transaction. A buy to let conveyancing solicitor UK buyers appoint can help clarify the legal position so you can decide how to proceed with a better understanding of the issues.

You do not need to have every answer before beginning. Raise the questions you do have, particularly any uncertainty about the property’s terms, permissions or the relationship between your intended use and the purchase arrangements. Addressing these carefully can help you approach the next stage with a clearer view.

Feltons offers a bespoke approach to conveyancing, with guidance shaped around your circumstances. Discuss your buy-to-let conveyancing with Feltons and take a considered step towards your property purchase.

Frequently Asked Questions

What does a buy-to-let conveyancing solicitor do?

A buy-to-let conveyancing solicitor handles the legal work for transferring a rental property to you. They review the purchase documents, check ownership information and deal with relevant enquiries, including matters raised by your proposed letting use. For example, they can explain a title entry or lease clause in plain English. Their role is to clarify the legal position, not forecast rent or assess whether the investment meets your financial goals.

Do I need a buy-to-let conveyancing solicitor to purchase a rental property?

Whether you must instruct a solicitor depends on the jurisdiction and purchase arrangements, including any lender requirements. A mortgage lender may require a conveyancer to act on the legal transaction, and the process can differ across the UK. Even if you are considering handling matters yourself, conveyancing involves formal documents and legal obligations. Establish early what representation your purchase requires, particularly if you are borrowing or buying in a jurisdiction with distinct conveyancing procedures.

Can a leasehold property be used as a buy-to-let?

Potentially, but the lease terms matter. A lease may contain provisions about subletting, occupancy, use of the property or obtaining consent, and their effect depends on the wording and circumstances. For example, permission to let a whole flat may not answer whether a different occupancy arrangement is allowed. Have the relevant clauses explained before committing, and distinguish lease requirements from separate rules or practical obligations that apply to landlords.

Can I rent out a property with a residential mortgage?

Do not assume a residential mortgage permits you to let the property. The terms depend on your lender and borrowing, and letting without any required agreement could create problems under the mortgage contract. If your plans change after purchase, review the loan terms and obtain the lender’s decision before granting a tenancy. A conveyancer can explain the legal documents involved in the purchase, but mortgage suitability and permission are matters to address with the lender.

How much does a buy-to-let conveyancing solicitor cost in the UK?

There is no single fee that applies to every purchase. The legal work can vary depending on factors such as whether the property is leasehold, the complexity of its title and the enquiries needed. When reviewing a proposed legal fee, consider what work it covers and whether separate transaction expenses apply. The requirements can differ from one transaction to another.

Does buy-to-let conveyancing work the same way across the UK?

No. The core aim is to complete a legal property transfer, but conveyancing procedures and property-law terminology vary between England and Wales, Scotland and Northern Ireland. For instance, the point at which a buyer becomes contractually committed is not described identically in every jurisdiction. If you are purchasing outside the jurisdiction where you normally live, identify where the property is situated and make sure the advice addresses the rules and process that apply there.

What should I check before exchanging contracts on a buy-to-let?

Before exchange, make sure you understand any outstanding legal enquiry, the effect of relevant title or lease provisions and whether the transaction documents reflect the agreed purchase. If the seller has said a letting issue will be resolved, establish what evidence or explanation is available and what it means for your decision. Also make sure your intended use has been considered alongside any lender conditions. Raise uncertainty with your conveyancer before becoming contractually committed.
Leasehold Extension for Overseas Landlords: A Guide to Protecting UK Assets in 2026

Leasehold Extension for Overseas Landlords: A Guide to Protecting UK Assets in 2026

What if the most significant threat to your UK investment isn’t the property market itself, but a ticking clock you can’t see from thousands of miles away? Managing a leasehold extension for overseas landlords often feels like a delicate balancing act between complex legal reforms and the strict requirements of the Register of Overseas Entities. It’s natural to feel a sense of urgency as your asset approaches the 80-year mark, especially whilst navigating different time zones and evolving UK legislation. We understand that your priority is a seamless process that protects your capital without requiring your constant, physical presence in the UK.

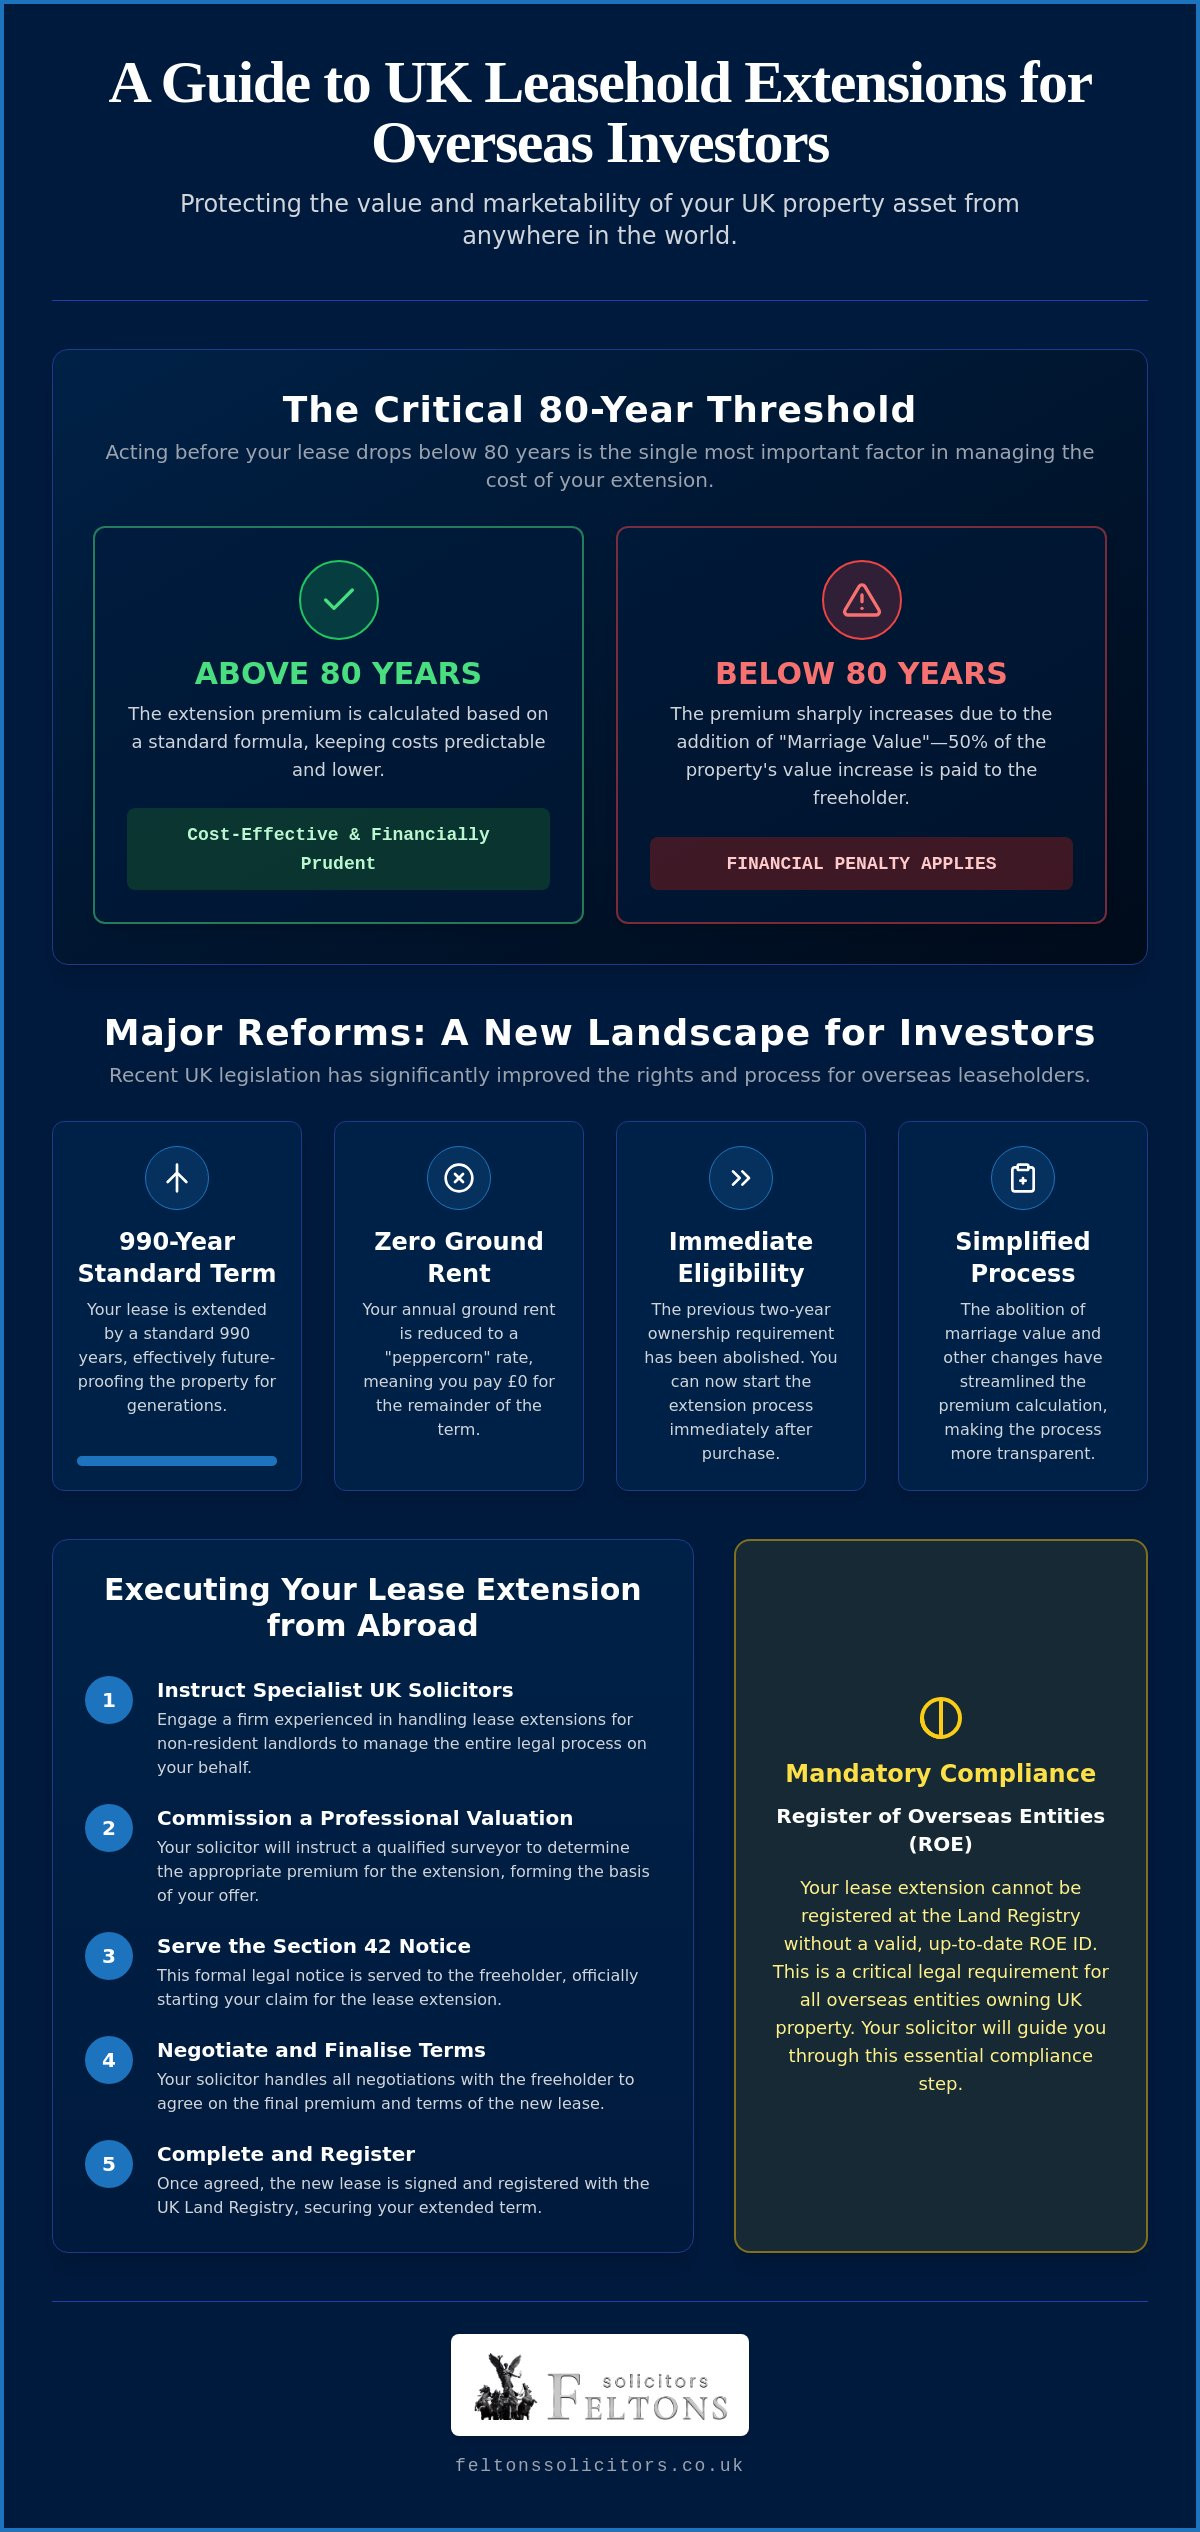
This guide will show you how to secure a valid lease extension that restores your property’s marketability whilst ensuring full compliance with Land Registry and ROE standards. You will discover how the 2024 reforms have simplified the landscape, including the abolition of marriage value and the introduction of the 990-year standard term. We will provide a clear, methodical preview of the steps required to manage these changes, allowing you to maintain your portfolio with the quiet confidence that your interests are fully protected and your legal obligations are met.

Key Takeaways

  • Understand why the 80-year “Marriage Value” threshold remains a critical financial deadline for protecting your property’s long-term market value.
  • Discover how a leasehold extension for overseas landlords now provides a standardised 990-year term and reduced ground rents under the 2024 reforms.
  • Identify the mandatory compliance steps required to synchronise your lease extension with the Register of Overseas Entities (ROE).
  • Learn how the abolition of the two-year ownership rule enables new international investors to initiate the extension process immediately upon purchase.
  • Explore the methodical process of instructing specialist UK solicitors to manage professional valuations and legal filings whilst you are based abroad.

Protecting Asset Value: Why Overseas Landlords Must Prioritise Lease Extensions

A leasehold extension is a vital legal mechanism that allows you to add a significant number of years to your existing UK property lease whilst simultaneously reducing your ground rent to a “peppercorn” or zero rate. For any investor managing a portfolio from afar, a leasehold extension for overseas landlords isn’t merely a paperwork exercise; it’s a strategic move to safeguard the capital value of your asset. The foundation for these rights was established through legislation like the Leasehold Reform Act 1967, which first empowered leaseholders to secure their long-term interests against the freeholder’s interest.

The 80-year mark is often described as a “cliff” because of its dramatic financial consequences. Once a lease drops below this threshold, the cost of extending it rises sharply due to the introduction of marriage value. For landlords living abroad who may not be tracking their lease documents on a weekly basis, missing this date can result in a bill that is tens of thousands of pounds higher than it would’ve been just a few months prior. Acting early is the most effective way to keep your premium predictable and your investment profitable.

Marketability is another pressing factor that demands attention. Most UK high-street lenders are hesitant to offer mortgages on properties with fewer than 85 years remaining on the lease. If you decide to sell or refinance your investment, a short lease significantly shrinks your pool of potential buyers to cash-only investors. This lack of competition inevitably drives down the sale price, making your asset far less liquid than it should be.

As we move through 2026, the UK property market is defined by increased transparency and stricter regulatory scrutiny. A long lease acts as a defensive shield against market volatility, ensuring your property remains a “clean” asset in the eyes of lenders and buyers alike. By securing a 990-year extension now, you effectively future-proof the property for generations, removing the need for any further legal intervention during your lifetime.

The Financial Risk of Diminishing Leases

The price you pay for an extension, known as the premium, is dictated largely by the unexpired term of your lease. The fewer years remaining, the higher the cost you’ll face. Marriage value is the increase in property value following an extension, 50% of which is owed to the landlord. By initiating the process before the lease hits that 80-year mark, you bypass this specific charge entirely, ensuring the extension remains a cost-effective management task rather than a financial burden.

Marketability and Global Portfolios

Maintaining a “clean” asset is vital for those managing a global portfolio where UK property serves as key collateral. International banks are becoming increasingly forensic when reviewing leasehold interests, and they’ve shown a clear preference for assets with long-term stability. A leasehold extension for overseas landlords ensures that the property remains a robust piece of collateral, capable of supporting further investment or providing a secure exit strategy when you choose to sell. It’s about maintaining the same high standard for your UK assets that you expect from your investments elsewhere in the world, which includes ensuring that commercial premises are managed by specialists like DLT Cleaning Services Ltd to meet modern hygiene and compliance benchmarks.

The Leasehold Reform, Housing and Urban Development Act 1993 remains the foundation for leasehold extension for overseas landlords, though its provisions have been significantly enhanced by the Leasehold and Freehold Reform Act 2024. While the 1993 Act established the right to a 90-year extension, the standard term has now been increased to a substantial 990 years. Perhaps the most significant hurdle removed for international investors is the two-year ownership rule. Since February 2025, you can initiate an extension immediately upon purchasing a property, ensuring your capital is protected from day one.

The formal process begins with a Section 42 Notice. This document serves as the “starting gun” for your legal claim, setting out your proposed premium and the terms of the new lease. It’s a precise legal instrument that requires expert handling to avoid being declared invalid by the freeholder. According to official government guidance on lease extensions, the statutory route also ensures your ground rent is reduced to a “peppercorn” rate. This essentially means your ground rent becomes zero for the duration of the new lease, removing a recurring expense that can otherwise complicate property management from abroad.

Qualifying as an Overseas Tenant

To qualify, your property must be held under a “long lease,” which is defined as a lease originally granted for more than 21 years. If you hold your UK assets through an offshore Special Purpose Vehicle (SPV), you are still eligible to exercise these rights, provided the entity is correctly registered with Companies House. For investors managing these types of complex international structures, Brown Hamilton Partners offers the accounting expertise necessary to ensure your global financial reporting remains seamless. Certain exceptions apply, such as properties owned by the National Trust or specific charitable housings. Ensuring your entity is compliant with the latest UK standards is a prerequisite for a smooth claim.

Statutory vs. Informal Extensions

You may find freeholders offering “informal” or private deals. These can seem attractive because they often appear faster or cheaper initially. However, they lack the legal safeguards of the statutory route. Private deals frequently include hidden clauses, such as future ground rent hikes or shorter extension terms that don’t solve the long-term value issue. The statutory route offers the highest level of security for landlords who aren’t physically present in the UK to monitor their freeholder’s behaviour.

In 2026, the timeline for a statutory extension typically spans six to twelve months. While this requires patience, the result is a legally robust asset that meets all modern lending criteria. If you’re unsure which route best suits your portfolio, seeking professional leasehold extension advice can provide the clarity needed to make an informed decision.

The Register of Overseas Entities (ROE): A Crucial Hurdle for Leasehold Extensions

The Economic Crime (Transparency and Enforcement) Act 2022 introduced a significant layer of administration that fundamentally changed how a leasehold extension for overseas landlords is executed. By 2026, the Register of Overseas Entities (ROE) has become a central pillar of UK property law. Any foreign company or entity owning land in the UK must register with Companies House to obtain a unique Overseas Entity ID. Without this ID, your property is effectively frozen. You cannot sell, lease, or, crucially, complete a statutory lease extension. The registration acts as a digital passport for your asset, and without it, the legal doors to the Land Registry remain firmly shut.

The Land Registry acts as the gatekeeper in this process. When your solicitor submits the new lease for registration, the Land Registry cross-references the application with the ROE. If your entity is not registered, or if your annual update is overdue, the application will be rejected. This “Land Registry block” is a common point of failure for many international investors who assume their property rights are independent of corporate filings. To understand the specifics of these filings, you can refer to Overseas Entity Beneficial Owner Registration for a detailed look at the 2026 requirements.

The Link Between ROE and the Land Registry

The registration of a lease extension is technically a “disposition” of land. Under the rules detailed in HM Land Registry Practice Guide 28, the Registrar is prohibited from registering most dealings by an overseas entity unless that entity is compliant with its ROE obligations. If you serve a Section 42 notice whilst your entity is non-compliant, you risk the entire transaction being deemed void. This doesn’t just delay the process; it can lead to significant financial loss if you miss a critical valuation window or a leasehold deadline.

Common Pitfalls in Overseas Registration

Discrepancies in entity names are a frequent cause of rejection. If the name on your original lease differs even slightly from the name registered on the ROE, the Land Registry will likely raise a requisition. Additionally, all information submitted to the ROE must be verified by a UK-regulated agent. This verification is not a one-time task. It must be refreshed annually to keep the entity “active.” For those managing a leasehold extension for overseas landlords, ensuring this compliance is up to date is the first and most vital step in any 2026 property strategy. It’s the foundation upon which your legal claim is built, ensuring your investment remains liquid and secure.

Leasehold Extension for Overseas Landlords: A Guide to Protecting UK Assets in 2026

Step-by-Step Guide: Executing a Lease Extension from Abroad

Executing a leasehold extension for overseas landlords requires a methodical approach that accounts for the physical distance between you and your asset. The process is inherently procedural, but when managed correctly, it can be completed with minimal disruption to your daily life. Your first priority is instructing a specialist UK solicitor who possesses deep experience in international property law and the specific nuances of the 2026 regulatory environment. This legal partner acts as your anchor in the UK, managing the flow of documents and ensuring all statutory deadlines are met with precision.

Once your legal representative is in place, the next step involves a professional valuation. A specialist surveyor will assess your property to determine the “premium,” which is the capital sum you will pay the freeholder to secure the extension. With this figure established, your solicitor will serve the Section 42 Tenant’s Notice. This formal document triggers the legal process and protects your right to the extension from the moment it’s served. The freeholder then has a two-month window to respond with a Counter-Notice, after which your surveyors will negotiate the final premium and lease terms.

The final stages involve the drafting and approval of the new lease, followed by the completion of a deed of substitution. This ensures any existing mortgage is correctly transferred to the new, longer lease. Finally, your solicitor will update the Land Registry records. This step is where your prior compliance with the Register of Overseas Entities becomes critical, as the Land Registry will not finalise the update without a valid Overseas Entity ID.

Remote Identity Verification and AML

Modern legal practice has evolved to support international clients through secure digital ID platforms. These tools allow you to satisfy stringent Anti-Money Laundering (AML) checks from your smartphone, removing the need for international travel. In some instances, you may still require a Notary Public in your home jurisdiction to witness specific signatures on physical documents. A forward-thinking solicitor will coordinate this process, providing clear instructions to ensure your local notary meets UK Land Registry standards.

Managing the Financial Transaction

Handling the transfer of the premium and associated legal costs is managed through secure solicitor client accounts, providing a transparent audit trail for your records. You must also account for any Stamp Duty Land Tax (SDLT) implications, though many extensions fall below the payment threshold. To ensure you aren’t paying more than necessary, it is vital to work with a leasehold enfranchisement expert who can accurately challenge any inflated figures proposed by the freeholder. If a freeholder becomes uncooperative or disputes the premium, engaging experienced dispute resolution solicitors can help you resolve the conflict efficiently without the cost and stress of protracted court proceedings. If you are ready to begin this process, we invite you to contact our team for a professional consultation to discuss your specific property requirements.

At Feltons Solicitors LLP, we’ve built our reputation on providing a sophisticated, boutique service that prioritises the individual needs of international clients. Managing a leasehold extension for overseas landlords requires more than just technical proficiency; it demands a partner who understands the logistical and emotional weight of international asset management. We act as your steady, professional presence in the UK, ensuring that every detail of your property interests is handled with the discreet care you expect. Our philosophy is people-first, which means we focus on managing your stress and providing clarity whilst we handle the complex legal paperwork behind the scenes.

Our expertise is specifically tailored to bridge the gap between traditional leasehold law and the modern requirements of the Economic Crime (Transparency and Enforcement) Act 2022. We understand that your property doesn’t exist in a vacuum. It’s part of a wider financial picture that includes corporate registrations and international compliance. By synchronising these elements, Feltons Solicitors LLP prevents the administrative delays that often plague standard property transactions. You can rely on us to be your eyes and ears on the ground, providing regular, concise updates that respect your time and your privacy.

Why a Specialist Property Law Firm Matters

Precise drafting is the cornerstone of a secure lease. A poorly constructed document can lead to future disputes or difficulties during a sale, especially if the freeholder attempts to insert restrictive clauses. As a dedicated Residential Property Law Firm, we have the experience necessary to identify these risks early. If a freeholder becomes uncooperative or contentious, our litigation and dispute resolution team at Feltons Solicitors LLP is ready to defend your interests, ensuring the statutory process remains on track. We provide the following benefits to our international clients:

  • Direct access to senior solicitors with experience in high-value UK property portfolios.
  • Comprehensive management of both the lease extension and the Register of Overseas Entities (ROE) filings.
  • Transparent communication and secure digital platforms for remote document handling.
  • A methodical approach to valuation negotiations to protect your capital.

Begin Your Lease Extension Today

The year 2026 represents a critical window for action. With the full implementation of the 2024 reforms now in effect, including the abolition of marriage value and the move to 990-year terms, there’s never been a more advantageous time to secure your UK assets. Waiting for further market shifts or legislative tweaks only risks the unexpired term of your lease dropping further. Feltons Solicitors LLP offers bespoke estimates that reflect the specific nuances of your property and corporate structure, providing you with a clear roadmap for the months ahead. To protect your investment and ensure full compliance, contact Feltons Solicitors LLP for expert guidance on your overseas leasehold extension.

Future-Proofing Your UK Property Portfolio for 2026 and Beyond

Securing your UK investment involves more than just monitoring market prices; it requires a proactive approach to the legal health of your assets. As we’ve explored, a leasehold extension for overseas landlords is the most effective way to eliminate ground rent and restore long-term value whilst staying ahead of the 80-year threshold. By aligning your property rights with the latest Register of Overseas Entities requirements, you transform a potentially depreciating asset into a secure, liquid component of your global portfolio.

Feltons Solicitors LLP provides the calm, authoritative guidance necessary to manage these processes from anywhere in the world. Our specialist focus on ROE verification and leasehold enfranchisement ensures that your extension is legally robust and fully compliant with current Land Registry standards. We act as your trusted partner on the ground, offering the discreet, boutique service that complex international matters demand. Secure your UK property value with Feltons Solicitors LLP today. Taking action now provides the certainty that your investment remains protected and your legal obligations are met with professional precision.

Frequently Asked Questions

Can I extend my UK lease if I live in another country?

Yes, you have the same statutory rights to a leasehold extension for overseas landlords as a resident of the UK. Your physical location doesn’t impact your eligibility, provided you hold a “long lease” originally granted for a term of more than 21 years. The process is designed to be handled by your UK legal representative, allowing you to exercise your rights from any jurisdiction.

Do I need to visit the UK to sign the lease extension documents?

No, you don’t need to travel to the UK at any stage of the process. Modern law firms use secure digital ID verification platforms to satisfy Anti-Money Laundering requirements remotely. For documents that require a physical signature, you can use a Notary Public in your home country to witness the signing, after which the papers are couriered to your solicitor in the UK.

How does the Register of Overseas Entities affect my lease extension?

The Register of Overseas Entities (ROE) acts as a mandatory compliance gatekeeper for your transaction. If your property is held in the name of an overseas company, the Land Registry will not register your new lease unless that entity has a valid Overseas Entity ID from Companies House. You must ensure your entity is not only registered but that your annual verification statements are fully up to date before serving your notice.

Is the two-year ownership rule still in effect for overseas landlords in 2026?

No, the requirement to have owned the property for two years was abolished in February 2025. This means you can initiate a leasehold extension for overseas landlords immediately after completing your property purchase. This reform is particularly beneficial for international investors who wish to modernise their lease terms and remove ground rent obligations from the very start of their ownership.

What happens if my UK lease has less than 80 years remaining?

If your lease drops below 80 years, you should prioritise an extension to protect the property’s marketability and mortgageability. Whilst the 2024 reforms abolished “marriage value” fees that previously made short-lease extensions much more expensive, a lease with fewer than 80 years still presents a significant hurdle for UK lenders. Extending your lease ensures the asset remains liquid and maintains its full capital value in a competitive market.

Can my overseas company extend the lease on a commercial property?

Yes, overseas companies can extend leases on commercial properties, although the statutory framework differs from that of residential flats. Commercial extensions are often handled via a negotiated “non-statutory” route. Regardless of the property type, your company must be correctly registered on the ROE to ensure the Land Registry can legally process and record the new lease variation.

How much does a solicitor charge for an overseas leasehold extension?

Legal fees for an international extension depend on the complexity of your corporate structure and whether the freeholder disputes the premium. Costs typically cover the drafting of the new lease, the service of formal notices, and the necessary identity and ROE compliance checks. We recommend requesting a bespoke estimate that accounts for your specific entity type and the number of properties involved in your claim.

What is a Section 42 notice and who serves it?

A Section 42 notice is the formal legal document that officially triggers your statutory claim for a lease extension. It is served by your UK solicitor to the freeholder and sets out your proposed premium and the terms of the new lease. Serving this notice is a critical step because it “fixes” the valuation date, ensuring that any subsequent changes in the property market don’t affect the price you pay for the extension.