Financial Settlement in UK Divorce: A Comprehensive Guide to Protecting Your Assets (2026)

Financial Settlement in UK Divorce: A Comprehensive Guide to Protecting Your Assets (2026)

Is a standard 50/50 split actually the fairest way to divide your life’s work, or is it simply a convenient starting point that overlooks your specific future needs? You’ve spent years building your assets, and the prospect of losing the family home or seeing a hard-earned pension fund diminished is understandably daunting. It’s entirely natural to feel a sense of anxiety regarding your financial independence whilst navigating the legal system. We understand that you seek a resolution that is both discreet and efficient, prioritising stability over conflict.

This guide provides the expert insight required to secure a favourable financial settlement divorce uk, ensuring your interests remain protected through meticulous disclosure and bespoke negotiation. By moving beyond generic templates, we focus on tailored strategies that reflect the true value of your matrimonial estate. You’ll learn how to achieve a definitive clean break, understand the 2026 court fee updates, and discover how to safeguard your wealth for the years ahead. We offer the steady, professional guidance you need to move forward with absolute confidence and peace of mind.

Key Takeaways

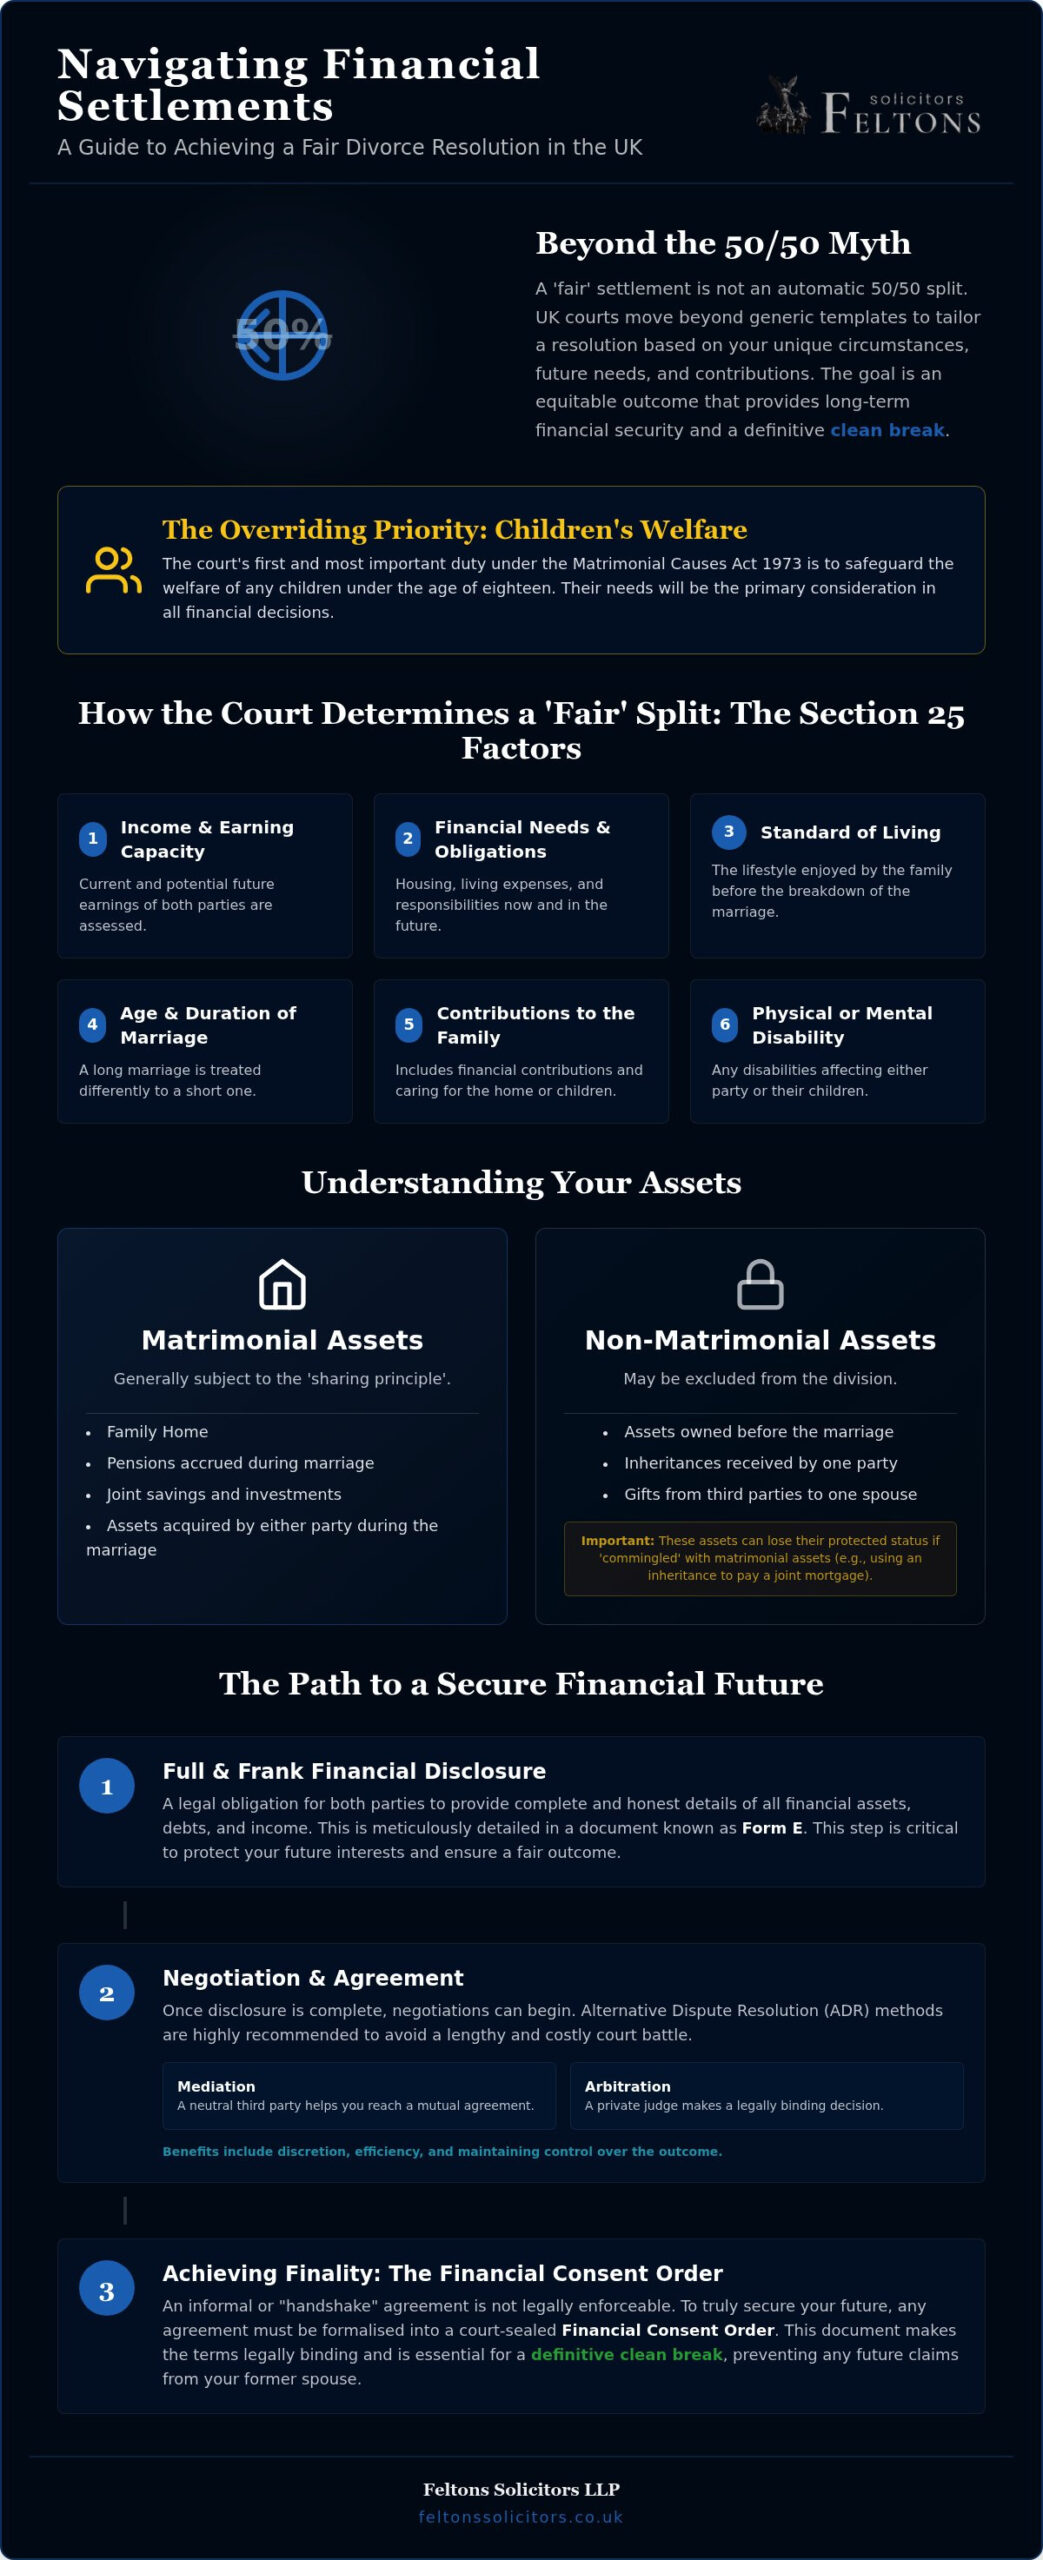
  • Learn how courts apply Section 25 factors to determine a fair financial settlement divorce uk, moving beyond the common misconception of an automatic 50/50 split.
  • Understand your legal obligation for full and frank financial disclosure and how the meticulous completion of Form E protects your future interests.
  • Explore the benefits of alternative dispute resolution methods, such as mediation and arbitration, to reach a discreet agreement whilst avoiding a bitter court battle.
  • Discover why a financial consent order is essential to achieving a definitive clean break and preventing future claims from your former spouse.
  • Gain insight into managing complex or international assets with a calm, steady approach that prioritises your long-term financial security and peace of mind.

Understanding Financial Settlements in UK Divorce Law

A financial settlement in UK divorce is a legally binding agreement that details how assets, property, and income are divided between separating parties. It is a common misconception that the divorce process itself automatically addresses these financial matters. The divorce petition merely ends the legal contract of marriage. In contrast, a financial order provides the finality needed to secure your future. Without a court-sealed order, your former spouse could potentially make a claim against your assets years, or even decades, after the decree is absolute.

Achieving a “clean break” is often the primary objective for those seeking a discreet and efficient resolution. A Clean Break Order dismisses future financial claims, ensuring that any wealth you build post-divorce remains yours alone. Relying on an informal “handshake” agreement is a significant risk. These arrangements lack legal enforceability and offer no protection if circumstances change or relationships sour. Only a court-approved order provides the peace of mind that your financial obligations are truly concluded.

The Legal Framework: Matrimonial Causes Act 1973

The Matrimonial Causes Act 1973 remains the primary authority for a financial settlement divorce uk. When reviewing an application, the court’s first priority is always the welfare of any children under eighteen. Beyond this, judges exercise broad discretion to achieve a result that is “fair”. Modern interpretations have shifted away from rigid formulas towards a pragmatic assessment of each party’s future needs, earning capacity, and contributions to the family. This ensures that the settlement is tailored to the specific realities of your household rather than a generic template.

Matrimonial vs Non-Matrimonial Assets

Distinguishing between asset types is essential for a precise and equitable division. Matrimonial assets generally include everything acquired during the marriage, such as the family home, joint savings, and pensions. These are typically subject to the sharing principle. Non-matrimonial assets often include property owned before the wedding or specific inheritances and gifts received during the relationship.

However, the treatment of non-matrimonial assets is rarely straightforward. If these assets have been “commingled”, for instance by using an inheritance to pay off a joint mortgage, they may lose their protected status. The court evaluates how long the marriage lasted and whether these assets are required to meet the other party’s basic needs. Expert legal insight is vital here to ensure your pre-marital wealth is appropriately ring-fenced wherever possible, maintaining your financial independence post-divorce.

How the Court Determines a ‘Fair’ Financial Split

The concept of “fairness” in a financial settlement divorce uk is often misunderstood as a simple mathematical exercise. Whilst a 50/50 division is frequently used as a starting point for long marriages, it’s by no means an automatic rule in English and Welsh law. The court’s primary objective is to reach an equitable outcome that reflects the unique circumstances of the family. This involves balancing various factors, including the standard of living enjoyed during the marriage. Judges rarely consider personal “conduct” or “blame” for the breakdown of the relationship unless it’s exceptionally egregious and has a direct, significant impact on the financial position. Instead, the focus remains on practical needs and future security.

The Section 25 Criteria Explained

Judges derive their authority from a specific set of criteria known as the Section 25 factors. These rules require a thorough, methodical assessment of each party’s position. The court will examine your income and earning capacity, looking not just at what you earn now, but what you could potentially earn in the future. They’ll also consider your current and future financial needs, obligations, and responsibilities. The age of each party and the duration of the marriage play a significant role; a twenty-year marriage is treated very differently from a two-year union. Additionally, the court weighs contributions to the welfare of the family, ensuring that a spouse who sacrificed their career to manage the home is not financially penalised. This discretionary approach allows for a tailored resolution that accounts for the nuances of your specific household.

Prioritising the Needs of Children

The court has a statutory duty to place the welfare of any children under eighteen at the forefront of its decision-making. This priority often dictates the division of the family home. If one parent remains the primary caregiver, the court may prioritise their housing needs to ensure the children have a stable and secure environment. This might result in an unequal split of capital to facilitate a property purchase or a deferred sale of the matrimonial home. The goal is to minimise disruption to the children’s lives, even if it means a less-than-equal division of the current assets. Understanding how these factors apply to your situation is essential for long-term planning. If you require a bespoke assessment of your matrimonial assets, our team provides the steady, professional guidance needed to navigate these complexities with confidence.

The Critical Role of Full and Frank Financial Disclosure

Full and frank disclosure is the cornerstone of any robust financial settlement divorce uk. It requires both parties to provide a comprehensive and honest overview of their global financial position, ensuring that negotiations are based on fact rather than assumption. This process is primarily facilitated through “Form E”, a detailed document that organises your financial evidence, including bank statements, property valuations, and income details. Providing a complete picture from the outset isn’t merely a procedural requirement; it’s a strict legal obligation. If one party is found to have hidden assets or provided misleading information, the court has the power to set aside the final order, potentially reopening the litigation years later at significant expense.

The strategic completion of Form E ensures that the negotiation starts from a position of absolute clarity. We often engage professional valuers to assess complex assets, such as private collections or property portfolios, to prevent disputes over their true worth. This methodical approach ensures that the matrimonial “pot” is accurately defined before any division begins, providing the firm foundation necessary for a fair and lasting agreement.

Dealing with Pensions and Business Assets

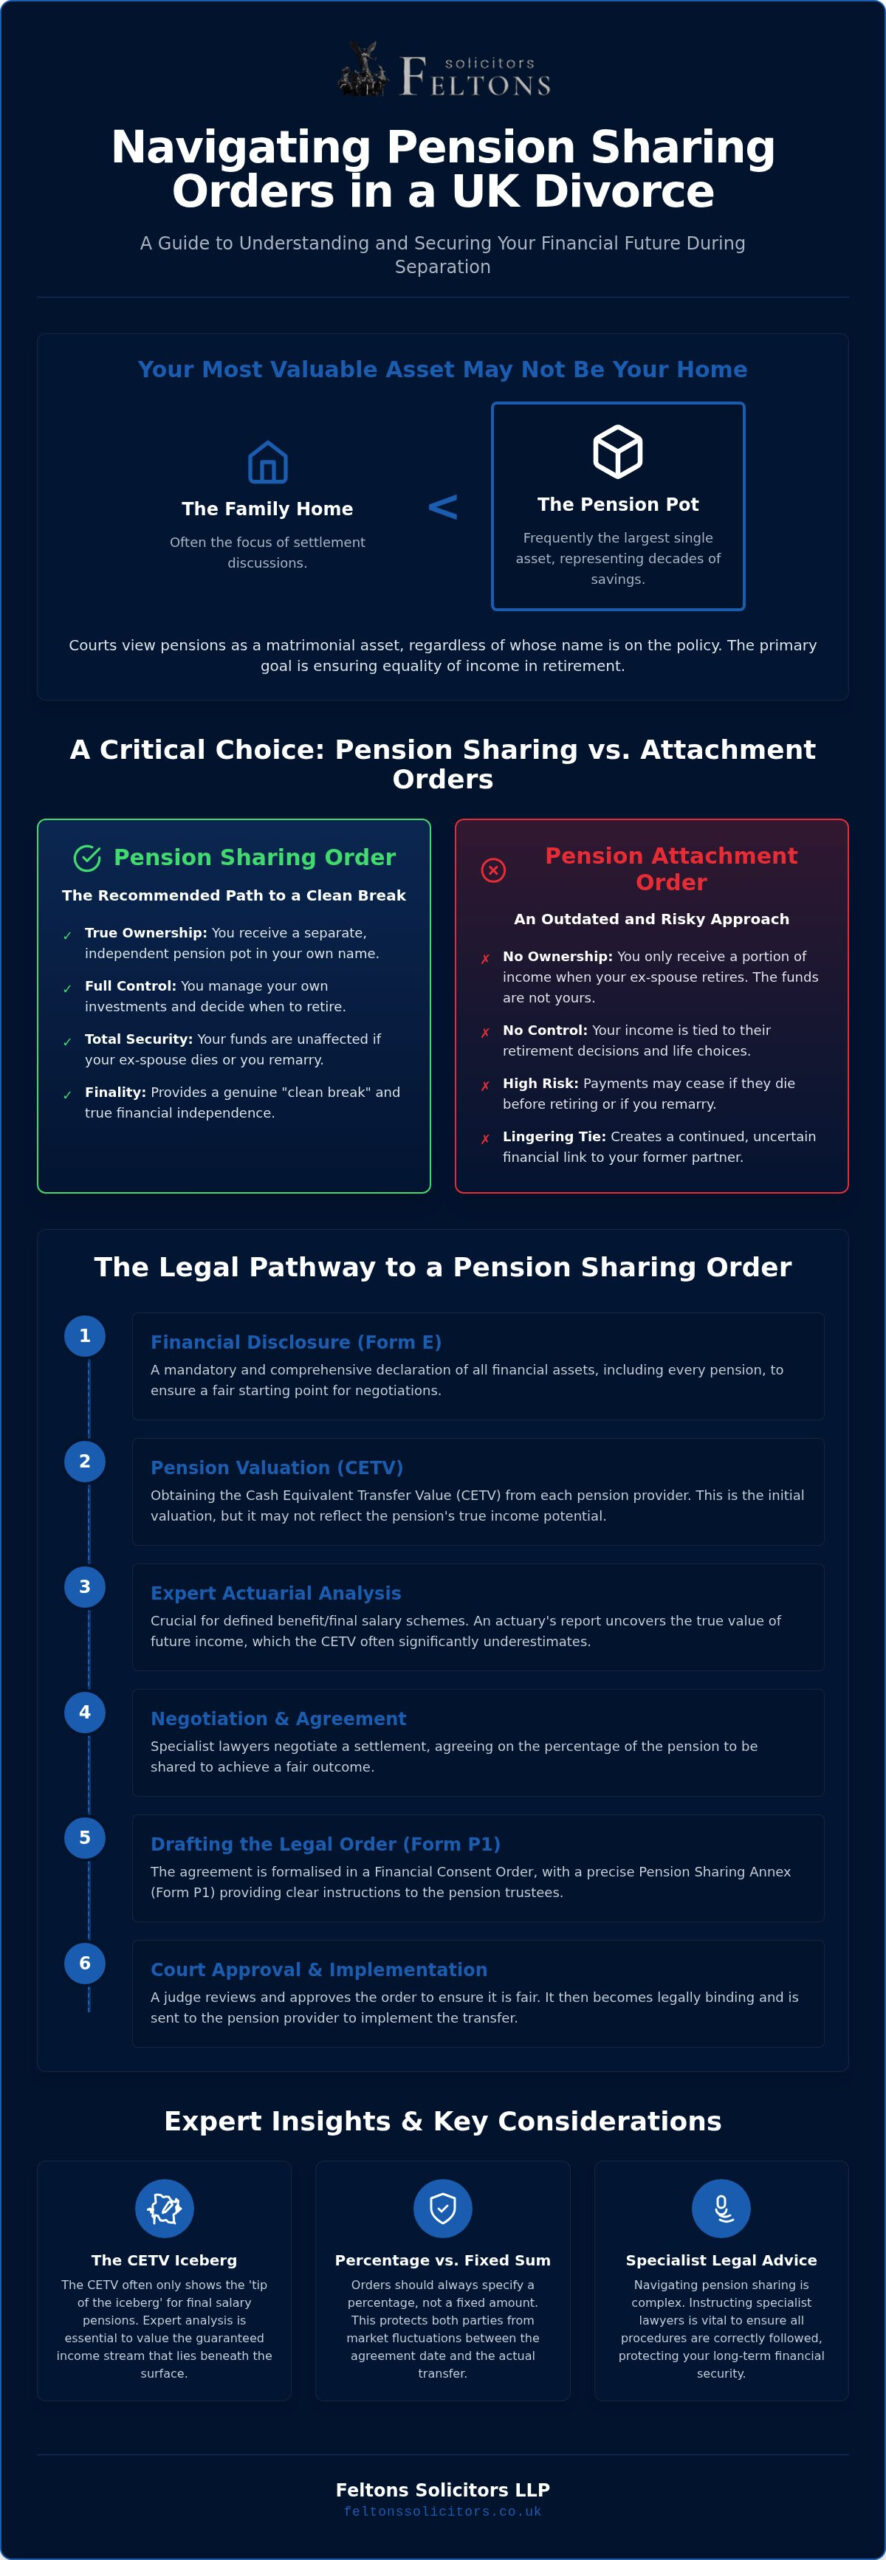
Pensions are frequently the most significant asset after the family home, yet they remain one of the most misunderstood areas of asset division. A Pension Sharing Order provides a definitive clean break by transferring a percentage of one party’s pension credit to the other. In contrast, a Pension Attachment Order acts more like maintenance, where payments are made only once the pension holder retires. It is vital to note that whilst many private schemes can be split, the new state pension (for those reaching state pension age from April 2016) cannot be shared. For high-value pots, we often recommend actuarial reports to determine the true value of the income stream. Similarly, valuing a family business requires a nuanced look at liquidity and future earnings to ensure the settlement remains sustainable for both parties.

International Assets and Overseas Entities

Identifying and valuing investments held abroad adds another layer of complexity to the disclosure process. Modern divorce proceedings frequently involve overseas entity beneficial owner registration, which provides essential transparency for UK property held by foreign organisations. Our expertise in cross-border financial arrangements allows us to navigate these international nuances with calm, steady precision. We ensure that every offshore interest is correctly accounted for, protecting your interests regardless of where the assets are located. This level of meticulous detail is essential for securing a settlement that is both comprehensive and legally sound.
Financial Settlement in UK Divorce: A Comprehensive Guide to Protecting Your Assets (2026)

Reaching an agreement outside the courtroom is increasingly the preferred route for those seeking a discreet and efficient resolution. Alternative Dispute Resolution (ADR) offers a more controlled environment for resolving a financial settlement divorce uk, prioritising cooperation over conflict. Mediation is a primary pillar of this approach. It allows both parties to discuss their needs with a neutral third party, often reducing the overall cost of proceedings whilst fostering a more amicable atmosphere. This is particularly beneficial when children are involved, as it sets a cooperative tone for future co-parenting and reduces the emotional strain on the family unit.

For complex cases that require a definitive decision but seek to avoid the delays of the public court system, arbitration is a sophisticated alternative. In this process, a private judge, known as an arbitrator, reviews the evidence and makes a binding decision. It’s significantly faster than the traditional court route and offers a level of privacy that high-net-worth individuals often prioritise. This ensures that sensitive financial details and business interests remain confidential, away from the public record.

The Process of Securing a Consent Order

Once an agreement is reached through negotiation or mediation, it must be formalised into a Consent Order to become legally binding. This document is meticulously drafted by solicitors to reflect the agreed terms with absolute precision, covering everything from property transfers to pension sharing. A judge then reviews the order to ensure it’s “fair” and meets the statutory requirements of the Matrimonial Causes Act. Without this judicial seal, your agreement remains informal and lacks the power to prevent future claims. For a deeper look at strategic asset division, see our guide to protecting your assets.

When Negotiation Fails: The Path to Court

If an agreement cannot be reached through ADR, the court process provides a structured path to a resolution. This typically involves three distinct stages: the First Appointment (FDA), the Financial Dispute Resolution (FDR) hearing, and the Final Hearing. The FDR is a pivotal moment in the litigation. It’s a “without prejudice” hearing where a judge gives a non-binding indication of the likely outcome if the case were to proceed to a trial. This insight often encourages a settlement, as both parties can see the risks and costs of continuing to a Final Hearing. Expert litigation support is essential during these stages to ensure your position is presented with clarity and authority. If you find yourself facing a contested split, we recommend seeking a professional consultation on divorce and financial arrangements to protect your long-term interests.

Securing Your Future with Feltons Solicitors

Feltons Solicitors LLP offers a boutique experience that prioritises the individual behind the legal case. We understand that navigating a financial settlement divorce uk is one of the most significant transitions you’ll ever face. Our approach is defined by a sophisticated blend of professional authority and empathetic reassurance. We position ourselves as a calm, steady presence during what is often a high-pressure period. By focusing on a personal connection rather than high-volume processing, we ensure that every client receives the discreet, high-standard service they deserve.

We specialise in handling complex, international-scale matters with the worldly experience required for high-net-worth asset division. Whether your estate involves overseas entities or intricate business structures, our team provides the pragmatic, sound judgment needed to secure your financial independence. We value modern efficiency, but we never compromise on the traditional professional integrity that has defined our firm since Paula Felton established it in 2010. This combination of heritage and forward-thinking methodology ensures your financial settlement divorce uk is handled with absolute precision.

A People-First Philosophy to Legal Service

Our “people-first” philosophy means that we never forget the human impact of the technical legal work we perform. We prioritise personal rapport and privacy, acting as your discreet partner throughout the entire process. We guide you through every step of the financial settlement process, from the initial disclosure to the final court-sealed order. Our goal is to provide a sense of security and comprehensive care, ensuring you feel supported and in capable hands. We offer tailored strategies that reflect your specific goals, whether you seek a clean break or the long-term protection of children’s assets.

Next Steps: Contacting Our Trusted Advisors

Taking the first step towards a resolution is often the hardest part. We invite you to arrange an initial consultation with our expert family law team to discuss your specific needs in a confidential setting. To make the most of this meeting, it’s helpful to gather a preliminary list of your assets, including property values, pension statements, and any business interests. This allows us to provide more targeted, practical advice from the very beginning.

Our communication rhythm is steady and deliberate. We respect your time and opt for a methodical flow that guides you through information without the frantic energy of high-pressure sales. If you’re ready to secure your financial future with a partner who values your peace of mind as much as your legal success, we’re here to help. Contact our trusted advisors today to begin your journey toward a discreet and efficient resolution.

Securing Your Financial Independence for the Years Ahead

Transitioning into a new chapter of life requires more than just legal paperwork; it requires a strategy that protects your hard-earned assets and provides long-term security. We’ve explored how the court balances Section 25 factors and why a court-sealed Consent Order is the only way to achieve a definitive clean break. A successful financial settlement divorce uk relies on meticulous disclosure and the ability to navigate complex arrangements, such as pensions and international property, with absolute precision.

Feltons Solicitors has provided boutique, personalised legal service since 2010. We offer the calm, steady presence needed to handle complex international-scale matters whilst prioritising your privacy and peace of mind. Our team is dedicated to helping you achieve a resolution that is both efficient and fair. If you’re ready to move forward with confidence, please contact Feltons Solicitors for a discreet consultation. You deserve a trusted advisor who understands the human impact of your legal journey and works tirelessly to secure your financial future.

Frequently Asked Questions

How long does a financial settlement take in the UK?

A financial settlement typically takes between six and twelve months to conclude if an agreement is reached through negotiation or mediation. If the matter proceeds to a contested court hearing, the timeline can extend significantly beyond a year. It’s important to understand that the financial process runs parallel to the divorce petition but remains a distinct legal matter. Seeking a prompt resolution helps provide the certainty needed to plan for your post-divorce future.

Can I claim my husband or wife’s pension after divorce?

Pensions are often the most significant asset in a marriage and are almost always included in a financial settlement divorce uk. You may be entitled to a portion of your spouse’s pension through a sharing order or an attachment order. However, the new state pension, for those reaching retirement age after April 2016, cannot be shared. We often use actuarial reports to ensure these complex funds are valued accurately before any division is agreed.

What happens to the family home in a financial settlement?

The treatment of the family home depends on the specific needs of each party, with the court prioritising the welfare of any children involved. Common outcomes include selling the property and dividing the proceeds or one party buying out the other’s share to remain in the home. In some cases, a deferred sale order is used to ensure children have a stable environment until they reach adulthood. Every situation requires a bespoke approach to achieve fairness.

Is a financial settlement always 50/50 in the UK?

No, there is no automatic 50/50 split in English and Welsh law. Whilst an equal division is a frequent starting point for long marriages, the court exercises broad discretion under Section 25 of the Matrimonial Causes Act. Factors such as the length of the marriage, each party’s earning capacity, and their future financial needs can lead to an unequal split. The primary goal is to reach an outcome that is equitable and sustainable for both individuals.

Do I need a solicitor for a financial settlement?

You are not legally required to instruct a solicitor for negotiations, but professional representation is essential for drafting a legally binding Consent Order. A solicitor ensures the document accurately reflects your agreement and provides the necessary protection against future claims. Without a court-sealed order, your financial ties remain open, leaving you vulnerable to claims years after the divorce. Expert guidance also helps you navigate complex asset valuations and ensures your long-term interests are fully protected.

What is a Clean Break Order and do I need one?

A Clean Break Order is a court-sealed document that ends the financial relationship between you and your former spouse. It prevents either party from making any future claims against the other’s income, assets, or inheritance. Most individuals require this order to achieve true financial independence and peace of mind. Without it, your former partner could potentially apply for a share of your wealth many years later if your financial circumstances improve significantly or you receive a windfall.

Can a financial settlement be changed after the divorce is finalised?

A financial settlement is usually final once a court has issued a sealed order, particularly if it includes a clean break clause. However, an order can be challenged or set aside in exceptional circumstances, such as a failure to provide full and frank disclosure or evidence of fraud. Additionally, a “Barder event”, which is a significant and unforeseen change occurring shortly after the order, may allow for a review. These cases are rare and require sophisticated legal expertise.

How much does a financial settlement cost in legal fees?

The total cost of a financial settlement divorce uk depends on the complexity of your assets and whether the division is agreed amicably. Court filing fees for 2026 are fixed at £62 for a consent order and £321 for a contested financial order. Professional fees vary based on the level of negotiation or litigation support required. Investing in expert advice early often reduces overall costs by avoiding a protracted court battle and ensuring a more efficient resolution.
Divorce Asset Division Lawyers: Navigating Complex Financial Settlements in 2026

Divorce Asset Division Lawyers: Navigating Complex Financial Settlements in 2026

The assumption that a UK court will always default to a rigid 50/50 split is one of the most persistent myths in family law. It’s entirely natural to feel anxious about the future of a business you built before your marriage or an inheritance you intended to pass down. You likely want a resolution that respects your hard work and provides security without the process becoming an adversarial battle. This guide offers a comprehensive look at how professional divorce asset division lawyers manage the complexities of financial settlements in 2026 to protect your specific interests.

We’ll examine the distinction between matrimonial and non-marital wealth, the necessity of full and frank disclosure via Form E, and how to achieve a pragmatic settlement that prioritises your long-term stability. By understanding the latest judicial approaches to the sharing principle following recent Supreme Court clarifications, you can move forward with the quiet confidence that your financial legacy remains intact. We’ll provide the clarity you need to approach these sensitive negotiations with a steady hand and a clear strategy for your future.

Key Takeaways

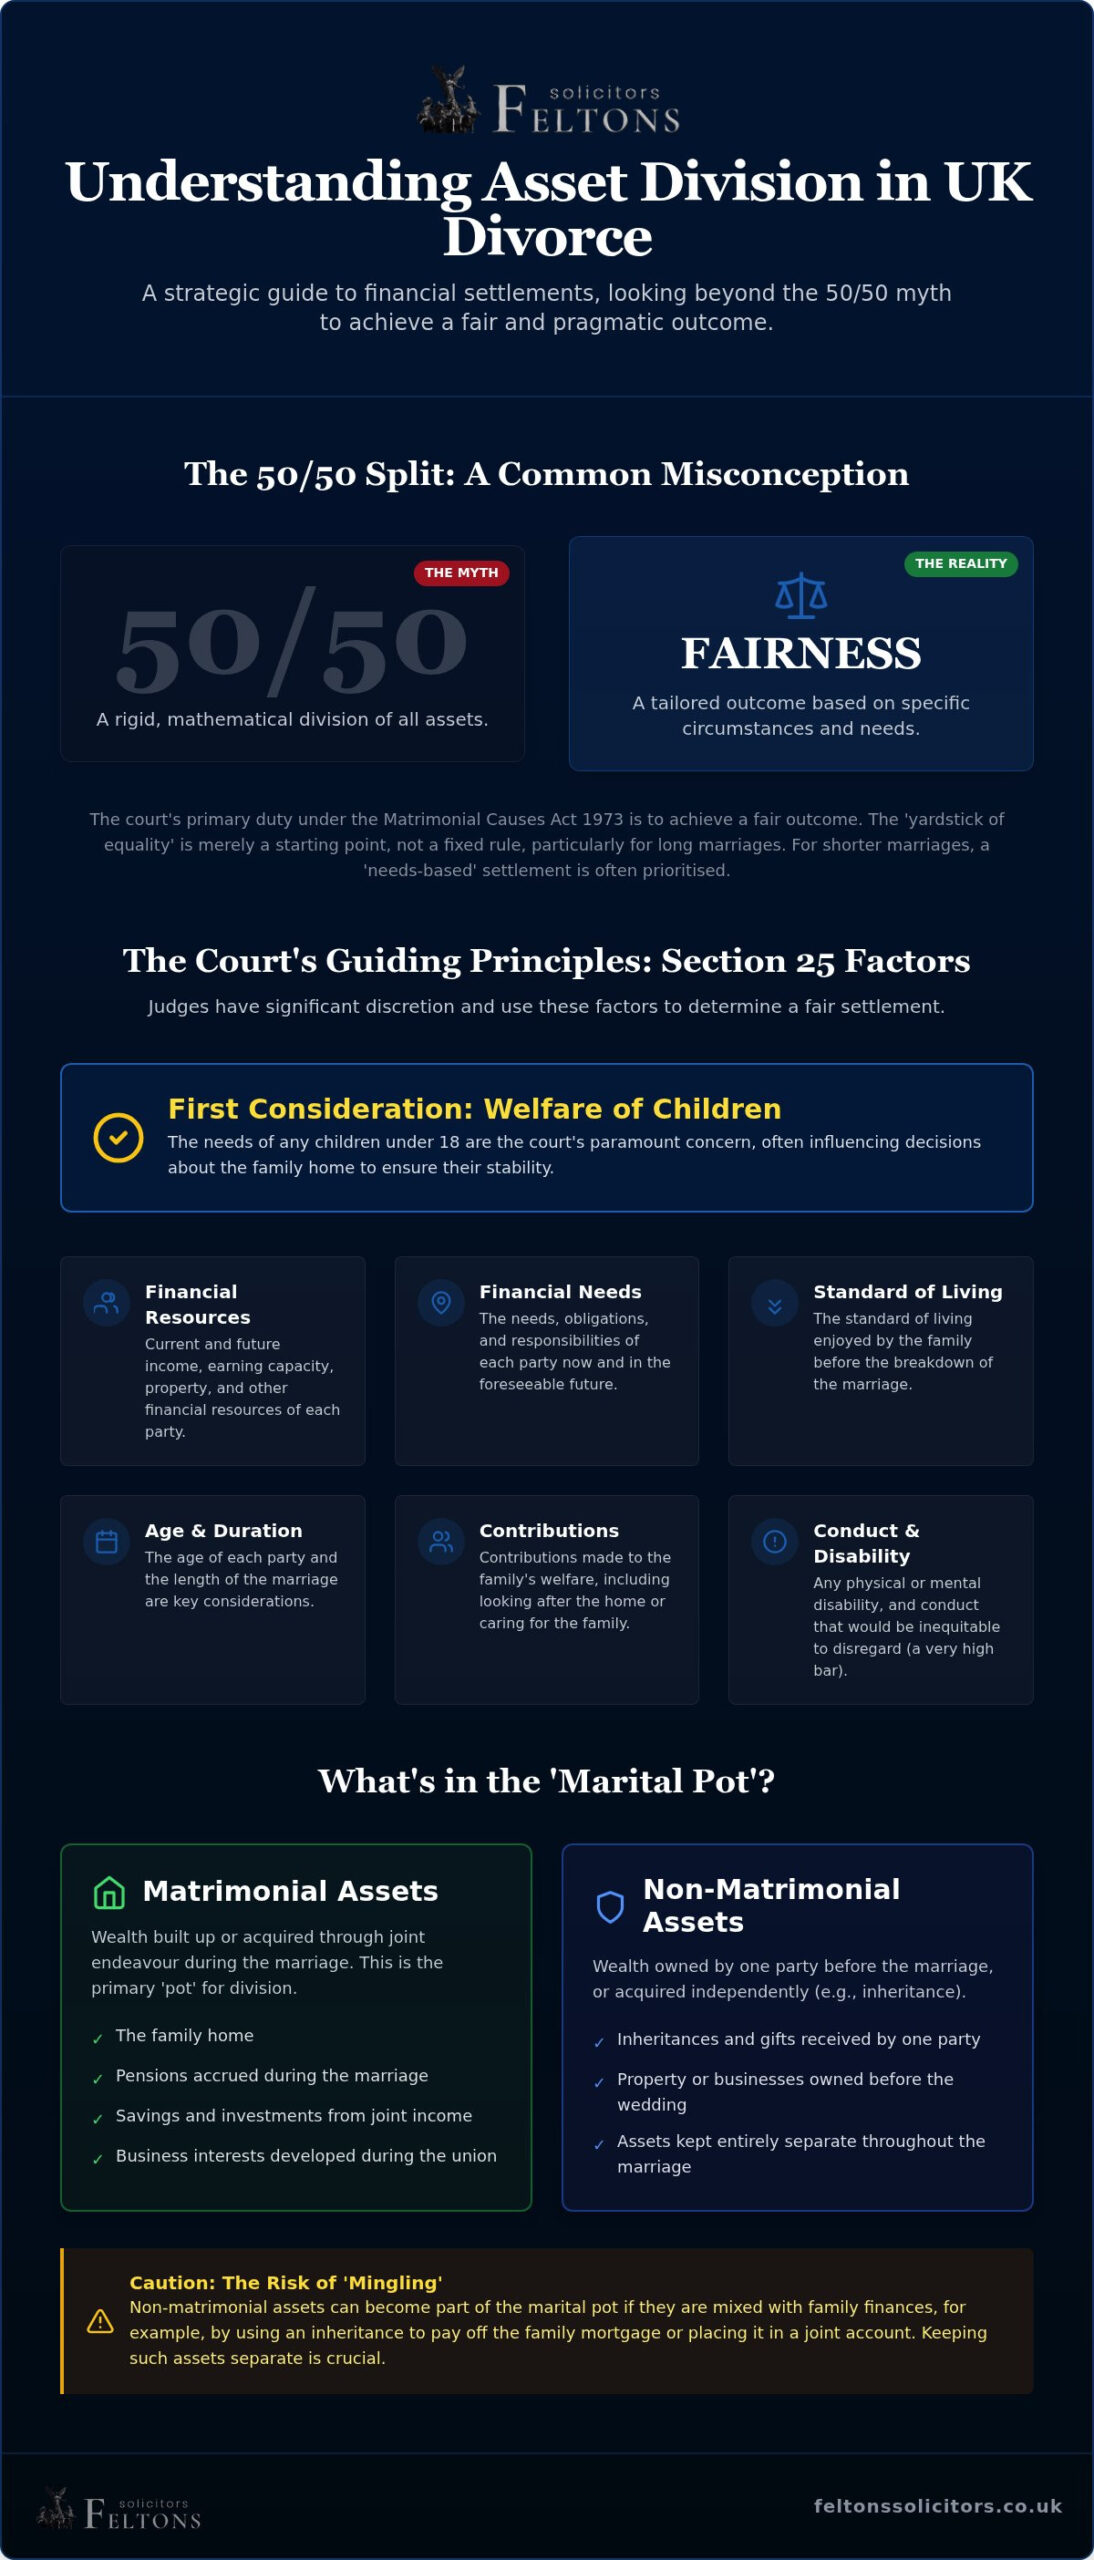
  • Understand why the “50/50” rule is merely a starting point and how Section 25 factors allow courts to prioritise fairness and the welfare of children.
  • Learn the vital distinction between matrimonial assets built through joint endeavour and non-matrimonial wealth, such as inheritances or property acquired before marriage.
  • Discover how experienced divorce asset division lawyers navigate complex financial structures, including investment portfolios and the registration of overseas entities.
  • Recognise the legal necessity of “full and frank disclosure” to ensure your settlement is robust, final, and protected from future challenges.
  • Gain insight into why a discreet, tailored legal strategy is paramount for managing sensitive financial data and securing a pragmatic outcome.

The legal framework for divorce in England and Wales is primarily rooted in the Matrimonial Causes Act 1973. This legislation doesn’t provide a rigid mathematical formula for splitting wealth; instead, it grants judges significant discretion to ensure an outcome that’s fair rather than just mathematically equal. When you consult with divorce asset division lawyers, the first step is often understanding how these broad legal principles apply to your specific financial circumstances.

The court evaluates what are known as Section 25 factors to determine this fairness. These include the income, earning capacity, property, and other financial resources each spouse has or is likely to have in the foreseeable future. The court also considers the financial needs, obligations, and responsibilities that each party has or is likely to have. Crucially, the welfare of any children under eighteen is the court’s first consideration, often dictating how the family home is handled to ensure their stability and continued care.

The Principle of Fairness vs Equality

In long marriages, the yardstick of equality is the standard starting point. This implies that assets built up during the union through joint endeavour should be shared equally. However, equality isn’t always the same as fairness. For shorter marriages, the court often leans towards a needs-based settlement. This approach focuses on ensuring both parties can transition to independent lives and have their housing needs met, rather than simply splitting everything down the middle. If one spouse entered the marriage with significant wealth and the union lasted only a few years, a 50/50 split is unlikely as the court seeks to avoid an unjustified windfall for the other party.

The Court’s Discretionary Power

Judges hold vast discretionary power to adjust settlements based on the standard of living enjoyed during the marriage. Whilst many clients worry about conduct or fault, the court rarely considers behaviour unless it’s financially or physically extreme. Instead, they focus on practicalities like age and future earning capacity. If one partner sacrificed their career to raise children, the court may award a larger share of the capital or ongoing maintenance to balance their reduced ability to earn in the future. Skilled divorce asset division lawyers help frame these arguments to ensure the transition to post-divorce life is as stable as possible, prioritising long-term financial security over short-term gains. This bespoke approach ensures that the final order is tailored to the unique economic reality of the family unit.

Distinguishing Between Matrimonial and Non-Matrimonial Assets

Identifying which assets are actually “on the table” is a critical task for divorce asset division lawyers. The Supreme Court ruling in Standish v Standish UKSC 26 recently clarified that wealth brought into a marriage doesn’t automatically become shared matrimonial property. Instead, the sharing principle primarily applies to assets built through joint endeavour during the union. This distinction is vital for protecting wealth that wasn’t created by the partnership itself.

Matrimonial assets typically include the family home, pensions accrued during the marriage, and savings generated from salaries. Non-matrimonial assets are those acquired before the wedding, inheritances, or gifts received by one party. However, these categories aren’t always fixed. If you use an inheritance to pay off the family mortgage, you mingle that asset, potentially making it matrimonial. In high-net-worth cases, a stellar contribution argument might be raised where one party’s exceptional business success significantly outstrips the other’s contribution, though this remains an exceptionally high bar to meet in court.

Protecting Inherited Wealth and Pre-Marital Property

Ring-fencing non-matrimonial wealth requires a proactive approach. Keeping inherited funds in a sole bank account rather than a joint one helps prevent matrimonialisation. Whilst pre-nuptial and post-nuptial agreements aren’t strictly binding in the UK, courts give them significant weight if they were entered into freely and fairly. These documents serve as a clear record of intent, helping to protect your financial legacy from being subsumed into the marital pot during a settlement.

Valuing Business Interests and Professional Practices

Valuing a private limited company involves more than looking at a balance sheet. Courts must consider liquidity; a business might be worth millions on paper, but if that wealth is tied up in machinery or stock, it can’t easily be paid out as a lump sum. Judges often distinguish between the capital value of the business and the income it generates for maintenance purposes. For complex portfolios, seeking a pragmatic financial arrangement ensures that the business remains viable whilst the other spouse receives a fair settlement. Expert divorce asset division lawyers work with forensic accountants to ensure these valuations are accurate and reflect the true economic reality of the practice.

Evaluating Complex Portfolios: Property and Pensions

Managing a portfolio that spans multiple jurisdictions or includes diverse asset classes requires a high degree of technical precision. Whilst the family home is often the most emotionally charged asset, investment property portfolios present distinct challenges regarding tax liabilities and liquidity. In 2026, the transparency requirements for overseas entity beneficial owner registration have become a pivotal factor in financial settlements. Divorce asset division lawyers must verify that all foreign-held property is correctly registered to avoid legal complications or delays in transferring ownership. Beyond property, modern portfolios frequently include digital assets like cryptocurrency or high-value collectibles such as art and jewellery. These require specialist valuation to ensure they aren’t undervalued or overlooked during the disclosure process.

The Family Home and Housing Needs

The court’s primary objective is to ensure both parties have adequate housing, especially when children are involved. You might consider a direct sale and split of proceeds, or one party may buy out the other’s interest. In cases where immediate sale isn’t viable, a Mesher order can postpone the sale until a specific event, such as a child reaching adulthood. This balances the “right to reside” with the eventual goal of a clean break. If the property is in negative equity or has a complex mortgage structure, your legal team will need to coordinate with lenders to find a pragmatic path forward.

Pensions: The Often Overlooked Asset

Pensions are frequently the second largest asset after the family home, yet they’re often misunderstood. Relying solely on the Cash Equivalent Value (CEV) can be a mistake, as it rarely reflects the true income the pension will provide in retirement. Following the Pension Advisory Group’s second-edition report (PAG2) in 2023, there’s a stronger focus on achieving equality of income rather than just capital value. Divorce asset division lawyers often use pension sharing orders to transfer a percentage of one party’s pension to the other. Alternatively, pension offsetting allows one spouse to retain a larger share of other assets, like the house, in exchange for waiving their rights to the other’s pension. This strategy provides immediate security but requires careful calculation to ensure the trade-off is genuinely fair.

Divorce Asset Division Lawyers: Navigating Complex Financial Settlements in 2026

The Process of Securing a Financial Settlement

The journey towards a final financial order is built upon absolute transparency. Both parties are under a strict legal obligation to provide “full and frank financial disclosure” of their worldwide assets. This isn’t a suggestion; it’s a fundamental requirement. Attempting to hide assets or providing misleading information can lead to the court setting aside an agreement years later, alongside potential cost orders or even criminal penalties. Experienced divorce asset division lawyers guide you through this process to ensure your disclosure is robust and beyond reproach.

Whilst many couples reach an agreement through voluntary negotiations or mediation, others require the structure of court-led financial remedy proceedings. Regardless of the route taken, the objective is to secure a Consent Order. This document transforms your private agreement into a legally binding court order, providing the finality needed to prevent either party from making future claims against the other’s wealth years after the decree absolute.

Navigating Form E and Financial Disclosure

The court’s preferred outcome is a “clean break” agreement. This order severs the financial ties between you and your former spouse entirely, ensuring that neither party can return to court for more money in the future. It’s the ultimate form of financial closure. In some cases, particularly where there’s a significant disparity in earning capacity or long-term care needs, a clean break may not be immediately possible. In these instances, spousal maintenance may be required for a set period. Turning a private agreement into a binding order is a technical task that requires the steady hand of divorce and financial arrangement experts to ensure your future is legally protected.

Choosing a legal partner for a high-value divorce isn’t merely about technical skill; it’s about finding a discreet partner who values privacy and personal rapport. Many national firms operate on high-volume, paralegal-led processing models that can feel impersonal and lack the strategic depth required for complex wealth. As divorce asset division lawyers, we operate on a “trusted advisor” model. This approach ensures you have a single, senior point of contact who understands the nuances of your financial history and the human impact of the settlement. In cases involving sensitive financial data or public-facing reputations, this boutique level of care provides a layer of security that larger practices often struggle to replicate.

Our “people-first” philosophy means we prioritise your long-term stability over aggressive litigation. We understand that a pragmatic financial settlement is often more valuable than a protracted battle that erodes the very assets you’re trying to protect. By maintaining a calm, steady presence, we guide you through the complexities of the legal system with quiet confidence, ensuring your interests are represented with professional integrity and sophisticated authority.

A Tailored Approach to Complex Litigation

Litigation involving international assets or intricate trust structures requires a bespoke strategy rather than a standard checklist. We specialise in handling disputes where wealth is spread across multiple jurisdictions, requiring a methodical and orderly mindset to untangle. Our role is to provide pragmatic advice that avoids unnecessary court costs whilst ensuring your non-matrimonial wealth remains ring-fenced. By fostering a close personal rapport between the client and the lead solicitor, we ensure that every decision is aligned with your specific objectives. This individualized attention is particularly vital when navigating the 74-week average wait times currently seen in the family courts, as it allows for a more efficient and focused path to resolution.

Integrating Property Expertise into Family Law

What distinguishes Feltons Solicitors is our deep-rooted expertise in both family law and complex property matters. Marital splits involving large portfolios often trigger technical issues such as leasehold extensions or enfranchisement requirements. Because our firm also specialises in residential and commercial conveyancing, our divorce and financial arrangements lawyers can coordinate the transfer of equity or the sale of investment properties seamlessly. This internal synergy eliminates the need for external consultants, reducing friction and ensuring that property-related settlement terms are executed accurately. Whether you’re dealing with the registration of overseas entities or managing the division of a commercial practice, our integrated methodology provides a comprehensive shield for your financial future.

Securing Your Financial Legacy with Confidence

Navigating the end of a marriage is undoubtedly challenging, but understanding the legal framework of asset division provides the foundation for a more stable future. We’ve explored how the distinction between matrimonial and non-marital wealth, combined with full financial disclosure, ensures a settlement that’s both fair and robust. By prioritising the welfare of children and addressing the technicalities of property portfolios and pensions, you can achieve a pragmatic resolution that protects your hard-earned assets.

Success in these complex matters often depends on the quality of your partnership with your legal team. Our divorce asset division lawyers provide boutique, people-first advice with direct access to senior solicitors. We combine traditional professional integrity with modern expertise in international structures and complex property law to guide you through every stage of the process. If you require a trusted advisor to handle your settlement with the utmost privacy and skill, contact Feltons Solicitors today for a discreet consultation on your financial arrangements. You don’t have to manage these intricacies alone; we’re here to help you move forward with quiet confidence and financial security.

Frequently Asked Questions

Is asset division always 50/50 in the UK?

No. Whilst an equal split is the starting point for matrimonial assets in long marriages, the court’s ultimate goal is fairness based on Section 25 factors. This includes considering housing needs, earning capacity, and the welfare of children. In shorter marriages or cases involving significant non-matrimonial wealth, the split may be adjusted significantly. Your divorce asset division lawyers will help determine how these factors apply to your specific financial circumstances.

Can I protect assets I owned before I got married?

Yes, pre-marital assets can often be ring-fenced if they haven’t been “matrimonialised” or mingled with joint finances. Recent rulings reinforce that the sharing principle primarily applies to wealth built during the marriage. However, if these assets are needed to meet the other party’s basic housing or financial needs, the court may still include them in the settlement pot to achieve a fair outcome for both parties.

What happens to my business if I get a divorce?

A business is considered a financial asset and must be disclosed, but it’s rarely sold or split down the middle. Instead, its value is often “offset” against other assets. For example, you might retain the company while your spouse receives a larger share of the family home or pension. Valuation is complex, focusing on liquidity and income-generating potential rather than just the balance sheet book value.

Do I have to share my pension with my ex-spouse?

Pensions are significant matrimonial assets and are frequently shared, particularly in long marriages. Under current guidance, courts now prioritise equality of retirement income rather than just equalising capital value. You might use a Pension Sharing Order to transfer a percentage of your fund, or an “offsetting” arrangement where you keep your pension in exchange for giving up other marital property, such as equity in a house.

What is full and frank financial disclosure?

This is the legal duty for both parties to reveal all worldwide assets, income, and liabilities. This process usually involves completing a Form E, supported by twelve months of bank statements and other evidence. Hiding wealth is a serious offence that can lead to court orders being overturned or financial penalties. Experienced divorce asset division lawyers ensure this process is transparent, protecting the final settlement from future legal challenges.

How long does it take to get a financial settlement?

The timeline varies depending on the complexity of the assets and the level of cooperation. Voluntary agreements can be finalised in a few months, but contested court proceedings often take much longer. In early 2025, the average wait from application to a final order reached 74 weeks. Using private dispute resolution or arbitration can sometimes expedite this process if both parties are willing to engage in a more efficient route.

Can my spouse claim against an inheritance I received during the marriage?

Inheritances are generally classified as non-matrimonial assets, but they aren’t automatically excluded from a claim. If the inheritance has been kept separate in a sole account, it’s easier to protect. However, if it was used to buy a joint home or if the marital pot is too small to meet both parties’ needs, the court may “dip into” the inheritance to ensure a fair settlement for both spouses.

What is a Consent Order and why do I need one?

A Consent Order is a legally binding document approved by the court that sets out your financial agreement. Even if you reach an amicable private deal, you need this order to make it final. Without it, your ex-spouse could potentially make a financial claim against you many years into the future, even after your divorce is finalised. It provides the essential “clean break” required for true financial independence and peace of mind.

Pension Sharing Order Lawyers: Securing Your Financial Future After Divorce

Pension Sharing Order Lawyers: Securing Your Financial Future After Divorce

What if the family home is not actually your most valuable asset during a divorce? Whilst many couples focus on property, a pension often represents decades of dedicated saving and is frequently the largest single element of the matrimonial pot. It is entirely understandable to feel a sense of trepidation when faced with complex Cash Equivalent Transfer Value (CETV) figures or the intricate differences between final salary and defined contribution schemes. You deserve a settlement that provides both clarity and long-term security.

By instructing specialist pension sharing order lawyers, you can ensure that your retirement assets are professionally appraised and fairly divided. Our expertise allows us to secure a legally enforceable Pension Sharing Order that provides a genuine clean break and a stable financial future. In this guide, we will examine how to navigate the latest 2026 pension allowances, the reality of implementation fees, and the essential steps to achieving an equitable outcome that protects your standard of living in later life.

Key Takeaways

  • Understand how a Pension Sharing Order facilitates a permanent financial “clean break” by creating a separate, independent pension pot for the recipient.
  • Gain clarity on the essential legal steps, from the initial financial disclosure using Form E to finalising a legally binding court order.
  • Compare the long-term benefits of pension sharing against offsetting strategies to ensure you don’t sacrifice future income for short-term capital gains.
  • Learn why pension sharing order lawyers often recommend expert actuarial reports to uncover the true value of complex final salary schemes.
  • Discover how a tailored, people-first legal approach can simplify pension jargon and provide the reassurance needed during financial remedy proceedings.

Understanding Pension Sharing Orders in UK Financial Settlements

A Pension Sharing Order (PSO) is a formal court instruction that legally transfers a specific percentage of one party’s pension fund to the other. It’s often the most effective way to manage retirement assets during a separation. Unlike other methods of division, a PSO facilitates a “clean break” financial settlement. This means the recipient receives their own independent pension pot, entirely separate from their former spouse. Most private and occupational pensions are eligible for this process, as is the Additional State Pension. It’s why pension sharing order lawyers increasingly recommend this route to ensure long-term financial independence and security.

The Legal Basis: Matrimonial Causes Act 1973

The primary legislation governing these orders includes the Matrimonial Causes Act 1973 and the Welfare Reform and Pensions Act 1999. Under established UK divorce law, the court views pensions as matrimonial assets. It doesn’t matter whose name is on the policy. If the value was accrued during the marriage, it’s part of the shared pot. We’ve seen a distinct shift in judicial behaviour over recent years. Courts now prioritise ensuring equality of income in retirement rather than just a simple split of capital. Whilst the length of the marriage can influence the percentage shared, especially in shorter unions, the primary goal is a fair and sustainable outcome for both parties.

Pension Sharing vs. Pension Attachment Orders

You might hear about Pension Attachment Orders, which were formerly known as “earmarking.” These are rarely recommended by experienced pension sharing order lawyers today because of the inherent risks they carry. With an attachment order, you don’t own the funds. You simply receive a portion of the pension when your ex-spouse starts to draw it. This creates a lingering financial tie. If they die before retiring or if you remarry, those benefits could vanish instantly.

Pension sharing eliminates this uncertainty. It provides immediate ownership and total control over the funds. Once the transfer is complete, the money is yours to manage. You can choose your own investment strategy and decide exactly when you wish to retire. This autonomy is vital. It ensures that your financial future isn’t dependent on the choices or circumstances of your former partner. By securing a separate pot, you gain the peace of mind that comes with true financial independence.

Securing a fair financial settlement requires a methodical approach to legal procedure. The journey begins with full financial disclosure, typically documented in Form E. This stage is non-negotiable; every pension asset, regardless of its size or when it was accrued, must be declared. Once disclosure is complete, pension sharing order lawyers work to negotiate a settlement that reflects your future needs, whether through direct discussion or mediation. If an agreement is reached, it is formalised in a Financial Consent Order. This document is then scrutinised by a judge to ensure the division is fair and reasonable for both parties.

Step 1: Obtaining the CETV Valuation

The Cash Equivalent Transfer Value (CETV) is the starting point for any pension division. It represents the lump sum value the pension provider would pay to move your benefits elsewhere. It’s vital to request these valuations as early as possible. Some schemes, particularly public sector ones, can take several months to provide this data. As detailed in this guide to pensions on divorce, the process requires patience and precision. It’s also a common misconception that the CETV represents the true value of the fund. For defined benefit or final salary schemes, the CETV often significantly undervalues the actual income the pension will produce in retirement.

Step 2: Drafting the Pension Sharing Annex

Precision is paramount when drafting the Pension Sharing Annex, also known as Form P1. This technical document accompanies the main court order and provides the pension trustees with the specific instructions they need. Most pension sharing order lawyers will specify a percentage of the fund to be transferred rather than a fixed monetary amount. This protects you against fluctuations in the fund’s value during the legal process. Before the order is sent to court, it’s standard practice to liaise with the pension trustees to confirm the order is implementable. This avoids costly administrative rejections later.

The procedure doesn’t conclude the moment the judge signs the order. Implementation is a distinct phase that begins after the Final Order is granted. Pension providers have a statutory period of four months to implement the share once they have received the sealed court order and the required implementation fee. These fees vary significantly; for instance, NHS schemes may charge between £2,200 and £3,000. Navigating these timelines requires a steady hand and professional oversight. If you’re concerned about the complexity of your retirement assets, seeking discreet legal support for financial arrangements can provide the clarity and reassurance you need.

Pension Sharing vs. Offsetting: Navigating Your Financial Options

Deciding how to divide matrimonial assets often involves a choice between immediate stability and future security. Offsetting is a common strategy where one party retains their full pension whilst the other receives a larger share of non-pension assets, such as the family home. This section provides a framework to help you navigate these options, ensuring your decision aligns with both your current lifestyle and your long-term goals. Whilst the house may feel like the most important asset today, its value must be weighed against the guaranteed income a pension provides in later life.

There is often a significant psychological weight attached to the family home. For many, staying in a familiar environment provides a sense of continuity that is hard to quantify. However, professional pension sharing order lawyers will always advise you to look beyond the emotional value of property to the cold reality of retirement income. High-net-worth individuals often find that a bespoke mix of both offsetting and sharing provides the most balanced outcome, allowing for a comfortable home today and a secure income tomorrow.

The Pros and Cons of Offsetting

The primary advantage of offsetting is its relative simplicity. It avoids the administrative fees charged by pension providers, which in 2026 can range from £500 to over £3,500 depending on the specific scheme. It also prevents the four-month implementation delay that follows a court order. However, offsetting presents a significant “apples versus oranges” problem. You are essentially trading liquid, tax-free capital, such as house equity, for a future, taxable income stream. Without careful calculation, you may inadvertently fall into a “tax trap” where the nominal value of the assets seems equal, but the actual spending power is vastly different. Feltons Solicitors maintains a cautious approach to offsetting in high-value cases, ensuring that any trade-off is mathematically sound and truly fair.

When is a Pension Sharing Order the Better Choice?

A Pension Sharing Order is frequently the superior option when the pension is the primary matrimonial asset. If there isn’t enough equity in the home or other savings to “buy out” a spouse’s share of the pension, a formal split is the only way to achieve a just result. It is also the preferred route when both parties require an independent income stream to fund their favourite retirement activities. This is particularly vital for a spouse who may have sacrificed career progression or their own pension contributions to focus on family life. By securing their own independent pot, they gain parity and financial autonomy. Expert pension sharing order lawyers ensure that this mechanism is used to create a permanent, legally enforceable separation of finances that allows both parties to move forward with total confidence.

Pension Sharing Order Lawyers: Securing Your Financial Future After Divorce

Valuing Pension Assets: The Critical Role of Actuaries

Relying purely on the Cash Equivalent Transfer Value (CETV) is a frequent mistake in financial remedy proceedings. Experienced pension sharing order lawyers understand that this figure is merely the pension provider’s estimate of what it would cost to buy out the benefits today. It rarely reflects the true utility or the actual cost of replacing that income on the open market. To achieve a truly equitable split, we often instruct a Pension On Divorce Expert (PODE). These specialists look beyond the capital value to calculate the “true value” of a fund, focusing on the income it will generate throughout your retirement.

This actuarial data is vital when arguing for an unequal percentage split. If there’s a significant age gap between spouses or differences in life expectancy, a simple 50/50 division of capital will not result in equal retirement income. An actuary provides the mathematical evidence needed to justify a split that ensures both parties enjoy a similar standard of living. Whilst an expert report carries an additional cost, the investment is highly pragmatic. A small percentage adjustment in a high-value pension can equate to tens of thousands of pounds over a lifetime. It’s a small price for long-term certainty.

Defined Benefit vs. Defined Contribution Schemes

The distinction between scheme types is fundamental to a fair settlement. Defined benefit schemes, particularly public sector pensions for the NHS, Teachers, or Armed Forces, carry significant hidden value that a standard valuation misses. Similarly, older private pensions may contain “guaranteed annuity rates” that are worth a fortune compared to current market offerings. You need a legal partner who understands these nuances. Without expert oversight, you risk accepting a settlement based on an incomplete financial picture. If you have concerns about the valuation of your retirement funds, you should contact our specialist divorce and financial arrangement lawyers for an initial consultation.

Tax Implications and Lifetime Allowance Considerations

The tax position of the recipient (pension credit) and the provider (pension debit) must be carefully balanced to avoid eroding the value of the settlement. Following the full abolition of the Lifetime Allowance on 6 April 2024, pension sharing now requires careful navigation of the new Lump Sum Allowance (LSA) and Lump Sum and Death Benefit Allowance (LSDBA) thresholds to avoid unforeseen tax charges in the 2026 tax year. The standard LSA is currently £268,275, whilst the LSDBA is capped at £1,073,100. Effective pension sharing order lawyers will coordinate with financial advisors to ensure your share doesn’t inadvertently trigger a tax liability that diminishes your future security.

Expert Pension Sharing Order Lawyers: How Feltons Solicitors Protects Your Future

Feltons Solicitors LLP understands that your retirement assets represent years of hard work and sacrifice. We combine modern efficiency with traditional professional integrity to handle these sensitive matters with the care they deserve. Choosing the right pension sharing order lawyers is about more than just technical skill; it’s about finding a partner who values your privacy and personal rapport. Our people-first philosophy ensures you feel supported through every stage of the financial remedy process. By providing pragmatic and discreet advice, we help high-net-worth individuals navigate the most complex settlements. Our extensive experience in divorce and financial arrangements ensures that no asset, however small or complex, is overlooked.

A Tailored Approach to Financial Remedy

We deliberately avoid the high-volume processing found in larger firms. Instead, we prioritise a bespoke personal connection with every client. This boutique level of care is essential when coordinating with the actuaries and financial advisors mentioned earlier to build a comprehensive strategy. We don’t stop once the court order is signed. Our team actively manages the implementation phase. We liaise with pension trustees to ensure the order is executed correctly and that the transfer of funds is completed within the statutory four-month window. This steady oversight prevents administrative delays and provides the reassurance you need during a period of transition.

Securing Your Clean Break

Achieving finality is our primary commitment. We want you to move forward with total confidence in your financial independence. A pension share shouldn’t be viewed in isolation. It is often beneficial to integrate your settlement into a wider estate planning strategy to protect your legacy for future generations. This holistic approach ensures that your new pension pot is correctly nominated and aligned with your overall wishes. Our pension sharing order lawyers are dedicated to securing a permanent resolution that allows you to plan for the future with certainty. If you are ready to secure your retirement assets, we invite you to organise a discreet consultation with our specialist team. We are here to provide the calm, expert guidance you need to move forward.

Securing Your Financial Independence in Retirement

Navigating the complexities of retirement assets requires more than just a surface-level understanding of valuations. You’ve seen how expert actuarial reports and the precise drafting of a Pension Sharing Annex are vital to achieving a truly equitable outcome. A Pension Sharing Order remains the most robust mechanism for ensuring a permanent financial clean break; it transforms a shared past into two independent, secure futures. This process provides the autonomy you need to manage your own funds and retire on your own terms.

Established in 2010 by Paula Felton, our firm specialises in high-net-worth financial arrangements through a pragmatic and empathetic boutique service. We understand that behind every CETV and implementation fee is an individual seeking clarity and security. Our pension sharing order lawyers are here to guide you through the process with discreet, high-standard care that prioritises your long-term wellbeing. Please contact Feltons Solicitors for a discreet consultation on your financial settlement to begin the next chapter of your life with confidence.

Frequently Asked Questions

Can I get a Pension Sharing Order after the divorce is finalised?

Yes, provided a final financial order has not already dismissed your pension claims. However, it is far more complex and costly to reopen financial matters after a divorce is finalised. Most pension sharing order lawyers advise securing the order before the Final Order (formerly Decree Absolute) is granted. This ensures your retirement assets are protected as part of a comprehensive and permanent clean break settlement.

How long does it take for a Pension Sharing Order to be implemented?

Implementation typically takes around four months once the pension provider receives the sealed court order. This is a statutory period. Delays can occur if the provider requires further information or if the implementation fee is not paid promptly. Experienced pension sharing order lawyers monitor this phase closely. We ensure that trustees adhere to the legal timeline so your new pension pot is established without unnecessary friction.

What happens to my State Pension during a divorce?

The basic State Pension cannot be shared. However, you may be able to share the Additional State Pension (accrued before 2016) or the “protected payment” element of the new State Pension. Whilst the rules are complex, a spouse with a lower contribution record might be able to use their ex-partner’s record to increase their own basic State Pension. This occurs without reducing the other person’s actual payment.

Does a Pension Sharing Order apply to a civil partnership dissolution?

Yes, the legal framework for sharing pensions upon the dissolution of a civil partnership is identical to that of a divorce. The court has the same powers to redistribute retirement assets to ensure a fair settlement. This includes private, occupational, and certain state pension elements. The goal is to achieve financial parity regardless of whether the relationship was a marriage or a civil partnership.

Can my ex-partner claim my pension if we were never married?

No, cohabiting couples who were never married or in a civil partnership have no automatic legal claim over each other’s pensions in England and Wales. Pension sharing is a remedy only available through the court during formal divorce or dissolution proceedings. Without a legal union, assets are generally retained by the person whose name is on the policy. This remains true regardless of the length of the relationship.

How much does a Pension Sharing Order cost in legal and actuary fees?

Costs vary depending on the complexity of the schemes. You must factor in the court fee for the consent order, which is £62 as of July 2026. Pension providers also charge their own implementation fees. These vary significantly between schemes; they often range from £500 to over £3,500 and usually attract VAT. We provide a clear breakdown of these third party costs at the start of your instruction.

What is a “Pension Credit” and how is it different from a “Pension Debit”?

These terms describe the two sides of a pension share. A “pension debit” is the specific amount or percentage deducted from the original member’s fund. A “pension credit” is the resulting amount received by the former spouse. Once the transfer is complete, the recipient holds the pension credit as their own independent asset. It is no longer linked to the original member’s scheme or future circumstances.

Is a Pension Sharing Order final, or can it be changed later?

A Pension Sharing Order is final once it has been implemented and the statutory appeal period has passed. Unlike maintenance payments, which can be varied if incomes change, a PSO is designed to provide a permanent clean break. It cannot be reversed or adjusted later. This is true even if the financial situation of either party changes significantly after the divorce is finalised.