Trust creation and asset protection solicitors for property

Trust creation and asset protection solicitors for property

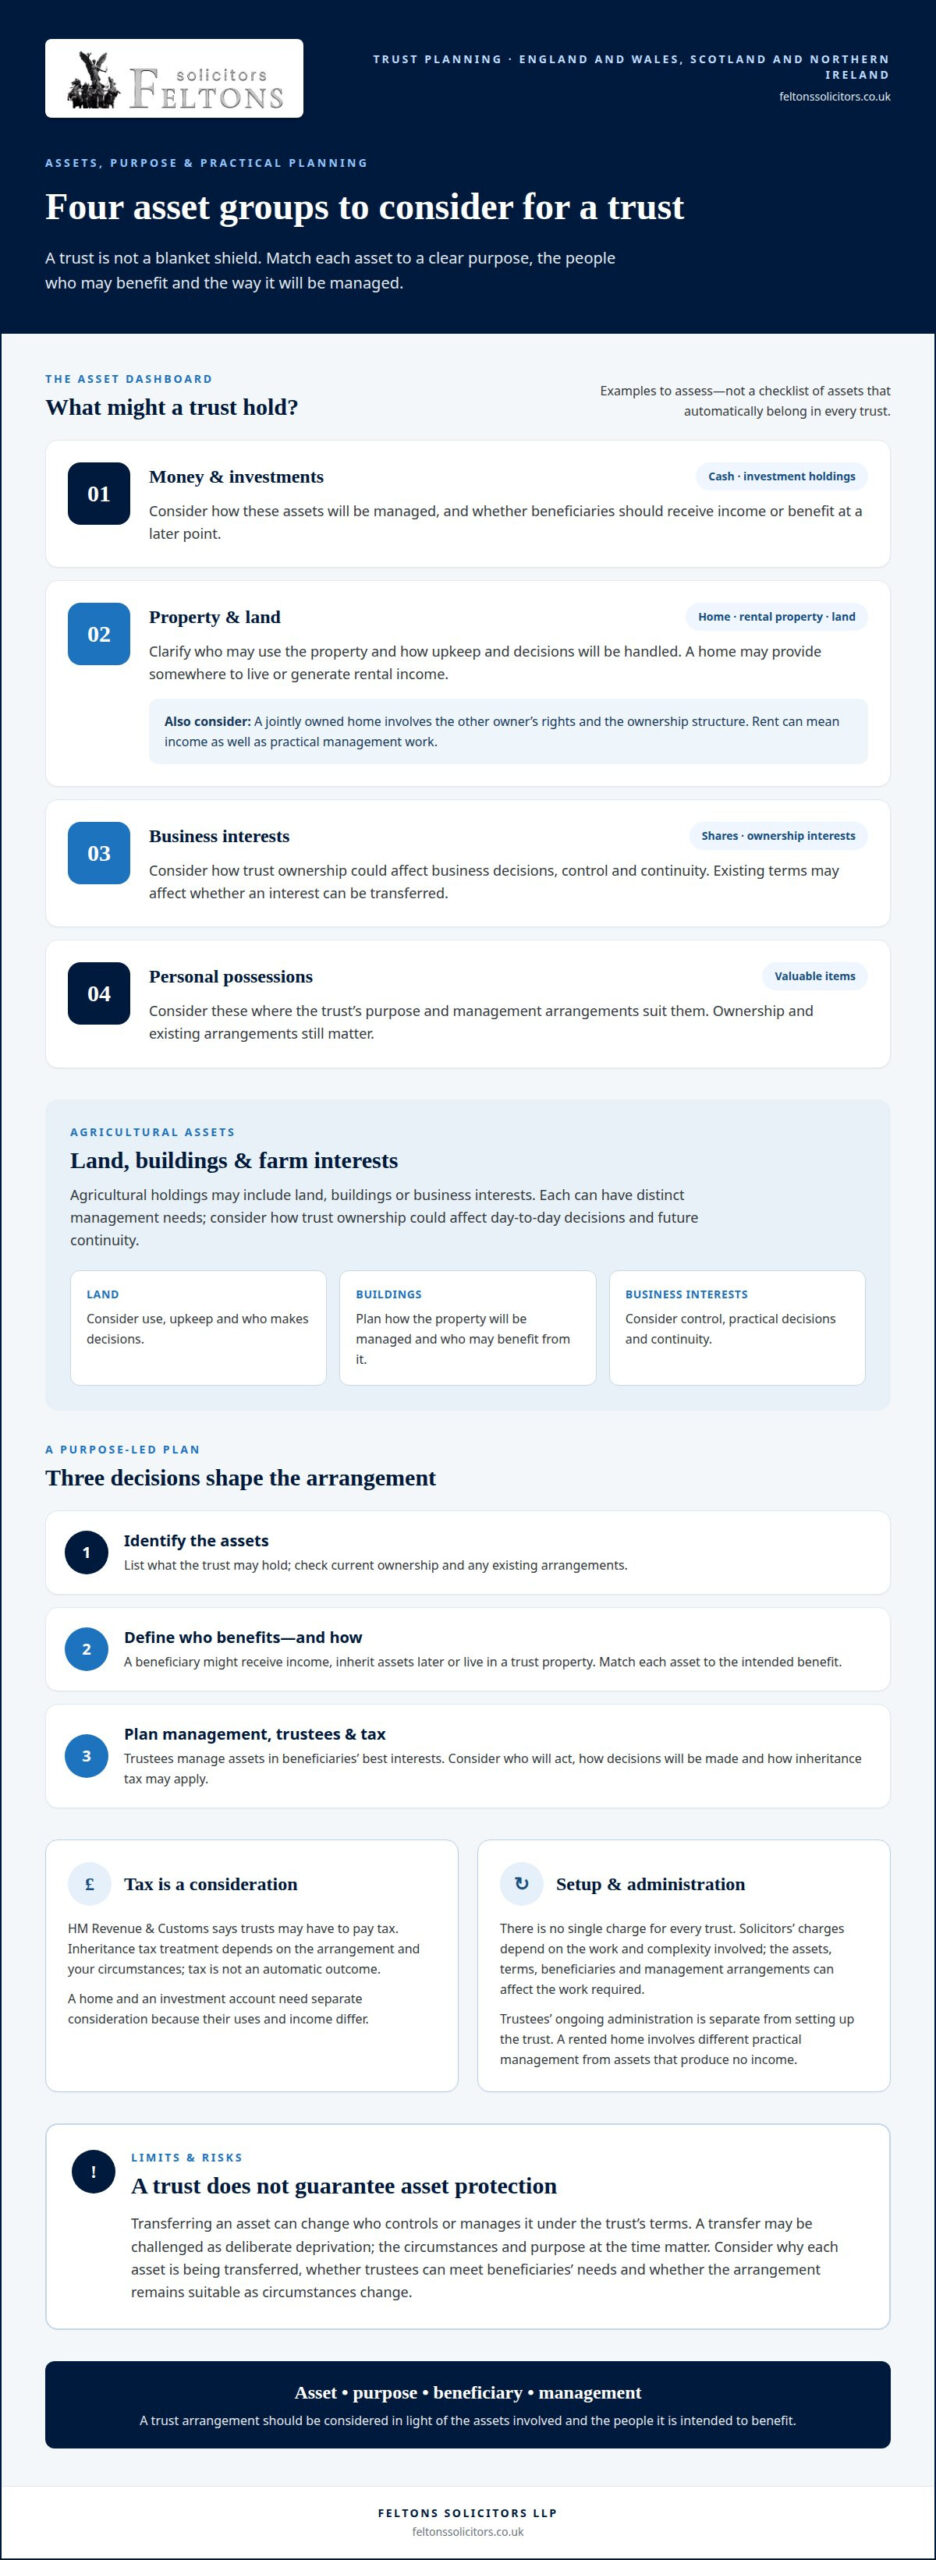
A trust is not a blanket shield for every asset. Trust creation and asset protection solicitors can explain how a trust may hold property, business interests or agricultural assets, and the practical and tax considerations involved. The right structure depends on what you own, who should benefit and how much control you want to retain.

It is understandable to want to protect assets while planning clearly for the people who may inherit or benefit from them. A trust can organise how assets are managed and passed on, but it needs careful consideration rather than being treated as a one-size-fits-all solution.

This article explains which assets may be placed in a trust, how trusts can relate to property, business and agricultural holdings, and what to consider about inheritance tax. It also outlines common trust arrangements and trustees’ roles, helping you approach the decisions with a clearer understanding of what may suit your circumstances.

Key Takeaways

  • Start by matching the assets you want to place in trust with the people who should benefit and the way they should benefit.
  • Factor in trustee responsibilities and the possibility of tax, including inheritance tax considerations, before settling on an arrangement.
  • Consider how property, business interests and agricultural assets are managed, and whether they may generate income within the trust.
  • Compare the purpose of discretionary, income-entitlement, Will, lifetime and disability trusts when considering which structure may fit your plans.

Trusts and inheritance tax considerations

Trust planning involves identifying assets, intended beneficiaries and tax considerations. Inheritance tax treatment depends on the arrangement and your circumstances.

Inheritance tax considerations

HM Revenue & Customs says trusts may have to pay tax. Tax is therefore a planning consideration, not an automatic outcome. Consider which assets would enter the trust, who could benefit and how trustees would manage them. For example, a home and an investment account need separate consideration because their uses and income differ.

Trustees manage trust assets in beneficiaries’ best interests. Before creating a trust, define its purpose and intended beneficiaries, then consider how its terms will affect asset management and future benefits. A beneficiary might receive income, inherit assets later or live in a trust property. These decisions help shape questions about inheritance tax.

Trust set-up and administration costs

There is no single charge that applies to every trust. Solicitors’ charges depend on the work and complexity involved, with a fee provided after a quote request. The trust’s assets, terms, beneficiaries and management arrangements can all affect the work required to prepare its documentation.

Administration is separate from setting up a trust. Trustees must manage its assets and act in beneficiaries’ best interests. A trust holding a rented home, for example, involves different practical management from one holding assets that produce no income. Consider the set-up and ongoing work separately.

Start by reviewing the assets and purpose. List what the trust may hold, who should benefit, and whether they need income, a future inheritance or use of a property. Then consider who will act as trustee and how decisions will be managed. The person establishing a trust may appoint themselves as trustee, while naming a successor can clarify who takes over if they die.

Finally, review the trust document against the intended arrangements. It records how a lifetime trust is to be managed. Clarifying responsibilities, beneficiaries’ needs and tax considerations before creation gives the arrangement a defined purpose. This helps frame a practical discussion about whether a trust suits your estate planning.

Trusts for property, business and agricultural assets

A trust can hold different assets, but each requires practical planning. Consider how ownership, management and beneficiaries’ needs fit together.

To compare solicitors near you, look for clear advice on the assets involved, trustee duties and trust terms. Ask how the proposed arrangement would address your aims, including ongoing management and tax considerations.

For property, consider who can use it and how it will be managed. A home held in trust might provide a place for a beneficiary to live or generate rental income. A business interest may require decisions about control and continuity. Agricultural assets may include land, buildings or business interests, each with distinct management needs.

Challenges to asset transfers

Yes, transferring assets into a trust can be challenged as deliberate deprivation. The circumstances and purpose of the transfer matter, including what was intended at the time. A trust should not be treated as a guaranteed way to prevent assets being considered in other decisions. Consider the reason for transferring each asset and record how the arrangement supports your wider plans.

Limits and risks of asset protection trusts

A trust does not remove every risk or guarantee that assets will be protected. Transferring an asset can also change who controls or manages it under the trust’s terms. Consider whether trustees can meet beneficiaries’ needs, how property or business interests will be handled, and whether the arrangement remains suitable as circumstances change.

According to the UK Government, assets held in a trust can generate income, such as rent from a home. That income and the practical work of managing the property should form part of the planning. For a business or farm, consider how trust ownership could affect day-to-day decisions and future continuity.

For property-related planning, Wills, Probate, and Estate Planning can help shape decisions about assets and beneficiaries.
Trust creation and asset protection solicitors for property

Assets that can be placed in a trust

A trust can hold money or other assets for beneficiaries. Suitable assets depend on ownership, intended use and the trust’s terms. Trust creation and asset protection solicitors can help assess how each proposed asset fits your aims. Start by identifying what the trust may hold and what benefit it should provide. A cash fund, investment holding and family home each raise different management questions.

Examples of assets to consider include:

  • Money and investments: cash or investment holdings can form part of a trust. Consider how they will be managed and whether beneficiaries should receive income or benefit later.
  • Property and land: a home, rental property or land may be considered. Clarify who can use it and how decisions about its upkeep will be handled.
  • Business interests: shares or an ownership interest may be relevant. Consider how trust arrangements fit with business decisions and continuity.
  • Personal possessions: valuable items can be considered where the trust’s purpose and management arrangements suit them.

These examples are not a checklist of assets that automatically belong in every trust. Current ownership and existing arrangements matter. For a jointly owned home, for example, the other owner’s rights and the ownership structure need consideration. Business interests may also have existing terms that affect how they can be transferred.

Next, match each asset to a clear purpose. Decide whether the trust should provide income, preserve an asset for a future inheritance or allow a beneficiary to use it. Then consider who will manage it and what decisions they may need to make. This helps distinguish assets that support the trust’s purpose from those that complicate administration.

Set out the proposed assets and beneficiaries together. A home intended for a beneficiary’s use needs different management planning from cash intended to provide income. A business interest may require attention to decision-making, while land may need ongoing oversight. Trust creation and asset protection solicitors can help clarify how the proposed terms should reflect these practical responsibilities.

Finally, consider how each proposed transfer affects your wider estate plan. Reviewing an asset, its ownership and its intended role together gives you a clearer basis for deciding what to include.

What types of trusts are available in England and Wales, Scotland and Northern Ireland?

Trust options include discretionary, income-entitlement, Will, lifetime and disability trusts. For plans involving England and Wales, Scotland or Northern Ireland, establish the relevant jurisdiction before settling on a structure.

A discretionary trust gives trustees discretion over how beneficiaries benefit. This can suit plans where trustees need to consider beneficiaries’ differing needs over time. The trust document should clearly set out its purpose and management arrangements.

A trust with income entitlements gives a beneficiary an entitlement to income from trust assets. Consider who receives that income and how the underlying assets are managed. For example, both rental income and the property generating it need clear oversight.

A Will trust is created through a will and takes effect as part of estate planning. A lifetime trust is established during the settlor’s lifetime, using a trust document that records how it should be managed. Their timing and purpose distinguish these options. Consider whether the arrangement should form part of a will or begin during your lifetime.

A trust for a person with disabilities is designed around the beneficiary’s circumstances. Consider the person’s needs, the assets intended to support them and how trustees will manage those assets. The terms should connect the trust’s purpose with the support it is intended to provide.

Compare options by asking what beneficiaries need, who should make decisions and when benefits should be available. Then consider the assets involved and how trustees will manage them. A property intended for someone’s use may need different terms from investments intended to provide income. The structure should reflect the practical purpose, not rely on a trust label alone.

Since England and Wales, Scotland and Northern Ireland each form part of the UK’s trust-planning context, identify where the relevant assets and people are based. That helps frame advice on the appropriate structure and its terms. To discuss how trust choices fit your estate plans, arrange a conversation about your estate planning.

Feltons Solicitors LLP

Feltons Solicitors LLP can help you consider trust decisions within your wider estate and property plans. If you’re weighing how assets should benefit family members, its Wills, Probate, and Estate Planning service can support related planning discussions. Where property ownership forms part of your plans, Residential and Commercial Conveyancing may also be relevant.

Bring together the assets you are considering, your intended beneficiaries and the outcome you hope to achieve. This provides a clearer starting point for discussing how trust planning connects with your will, estate and property arrangements. A focused conversation about your circumstances and priorities is a practical next step.

Contact Feltons Solicitors LLP to discuss your estate planning questions.

Make your next planning decision with clarity

Before taking action, set out what you want the trust to achieve and how it fits your wider plans. Consider who should benefit, what role you want trustees to have, and whether your property or family circumstances may change. A clear outline of these priorities can make your next discussion more focused.

Trust creation and asset protection solicitors can help you consider how these decisions connect with your estate and property arrangements. Feltons Solicitors LLP’s work in Wills, Probate, and Estate Planning, Residential and Commercial Conveyancing, and Divorce and Financial Arrangements may be relevant where those matters intersect.

Bring your questions and the decisions you are weighing to a conversation. You can contact Feltons Solicitors LLP about trusts to discuss a practical next step. Thoughtful planning can help you move forward with greater confidence.

Frequently Asked Questions

Need help with a Trust?

Yes, a solicitor can help assess whether a trust fits your aims and circumstances. Prepare a brief outline of the assets involved, who you want to benefit and what you want them to receive. For example, a family home intended for a child’s future use raises different practical questions from investments intended to support someone now.

How do I set up a lifetime trust?

Begin by defining the trust’s purpose, intended beneficiaries and assets. Decide who should act as trustees, then establish how they should manage the trust and make decisions. A lifetime trust is created using a trust document that records its management arrangements. Consider how the terms will work in practice, including how trustees should respond if beneficiaries’ needs change.

What are settlors, trustees, and beneficiaries?

The settlor is the person who creates the trust and places assets into it. Trustees manage those assets under the trust’s terms, while beneficiaries receive the intended benefit. For example, a parent could establish a trust for a child, appoint trustees to manage its assets and set out how the child may benefit.

What can a family trust and asset protection solicitor do?

A solicitor can help a family understand trust options, clarify what the arrangement should achieve and consider how it fits with estate planning. They can also identify practical questions about beneficiaries, trustee roles and asset management. For instance, a family planning for a relative’s future support may need to consider who makes decisions and how those decisions are guided.

What does a trust and asset protection solicitor do in the UK?

A solicitor can explain trust structures, help consider suitable terms and discuss how a proposed arrangement fits your wider plans. This may involve considering asset ownership, beneficiaries, trustee responsibilities and tax implications. Feltons Solicitors LLP offers Wills, Probate, Trusts and Estate Planning, which can be relevant when considering how trust questions connect with your estate arrangements.

How can trusts protect assets from care fees, creditors or divorce in the UK?

A trust does not automatically protect assets from care-fee assessments, creditors or divorce-related claims. The purpose and timing of a transfer, the settlor’s control and the trust’s terms may all matter. Treat a trust as an estate-planning arrangement, not a guaranteed shield. Get advice on your circumstances before transferring assets or relying on a trust for protection.
Equity Release Legal Advice: How to Choose a Solicitor

Equity Release Legal Advice: How to Choose a Solicitor

What if the person checking your equity release paperwork isn’t the person advising whether the plan is financially right for you? If you’re comparing equity release legal advice solicitors, it’s understandable to want clear answers about long-term costs, your partner’s position and what may remain in your estate.

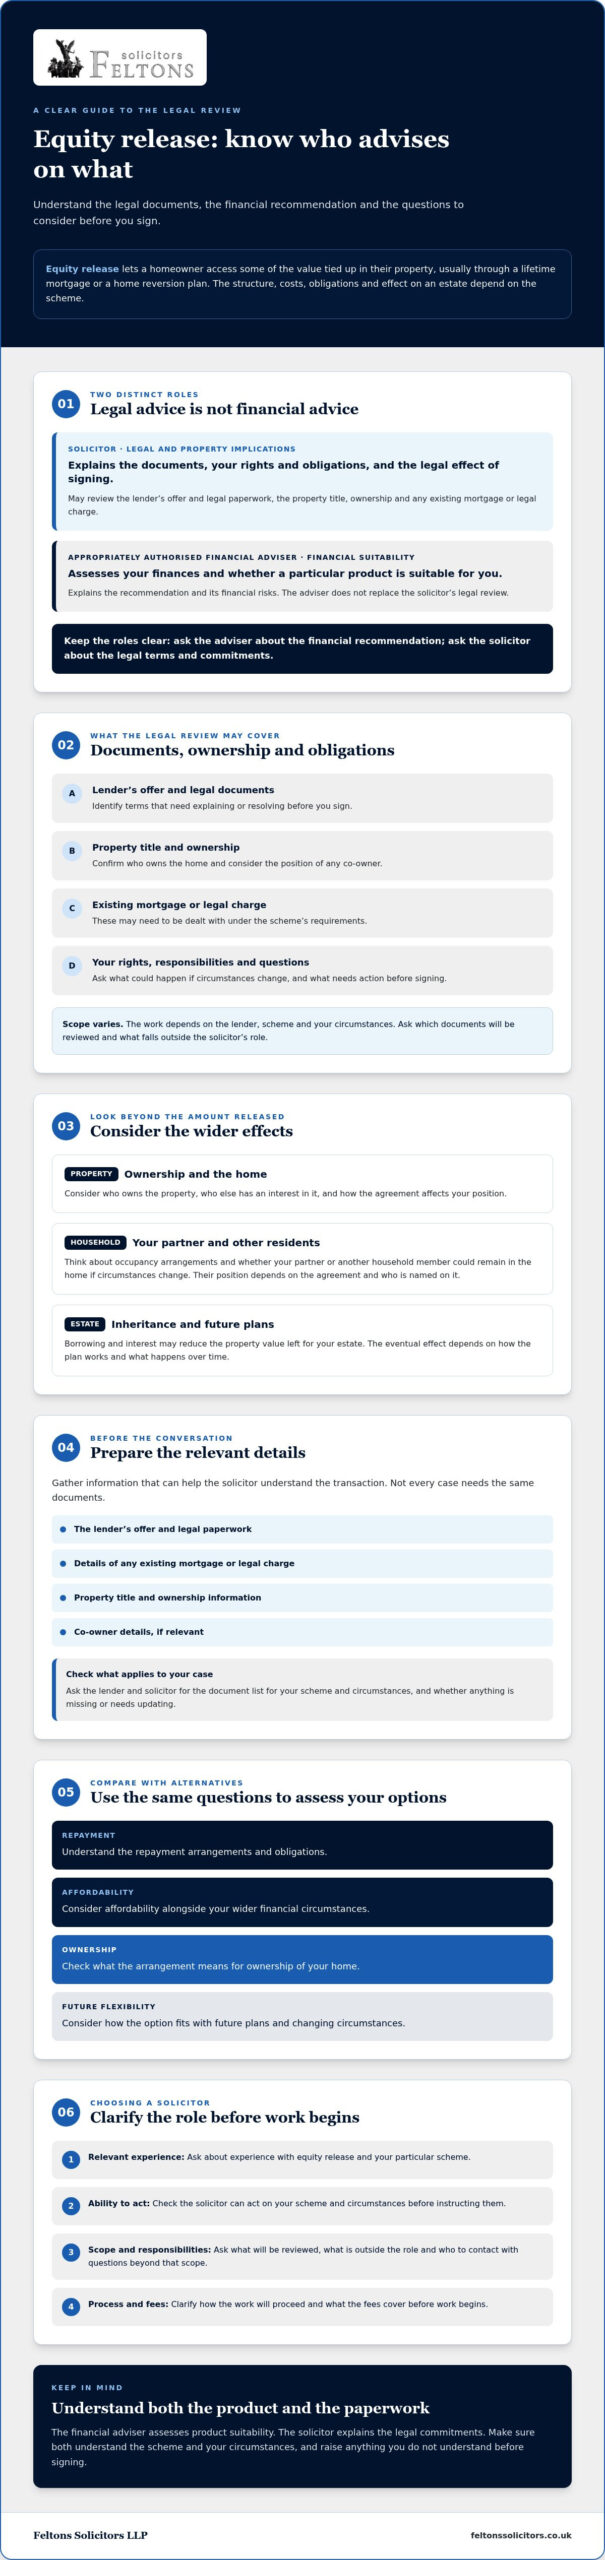
Legal advice and regulated financial advice have different purposes. A solicitor can explain the legal documents and property implications, while an appropriately authorised financial adviser assesses the financial product and its suitability for you. Understanding the distinction can help you make a considered decision and know who to ask when questions arise.

This guide explains what a solicitor may review, what to ask and which details to prepare before a conversation. It also considers how equity release could affect family members and estate plans. Feltons Solicitors LLP provides property and estate-planning legal services. An enquiry can help establish whether the firm is able to assist with your circumstances.

Key Takeaways

  • Equity release legal advice solicitors review a plan’s legal and property implications, but don’t recommend which financial product is right for you.
  • Ask how the agreement could affect ownership, your partner and your estate. The details depend on your circumstances and the scheme terms.
  • Compare equity release with alternatives by considering repayment, affordability, ownership and future flexibility.
  • Prepare information about your property and proposed scheme, then clarify the solicitor’s role, process, responsibilities and fees before work begins.
  • Check that the solicitor has relevant experience and can act on your particular scheme and circumstances before instructing them.

Equity release lets a homeowner access some of the value tied up in their property, usually through a product such as a lifetime mortgage or a home reversion plan. The structure, costs, obligations and effect on your estate depend on the scheme. The Equity release overview offers background on different forms and risks, but your own documents need to be considered in context.

In brief: a solicitor explains the legal effect of the documents and your obligations. A regulated financial adviser assesses and recommends a suitable financial product. Keeping these roles distinct helps you understand both what you’re agreeing to and why the proposed plan may or may not fit your financial circumstances.

What does an equity release solicitor check?

A solicitor’s review may cover the lender’s offer and legal documents, the property title and who owns the home. They can identify terms or details that need explaining or resolving before you sign. For example, an existing mortgage or legal charge may need to be dealt with under the scheme’s requirements. If someone else owns the property with you, their interest and position may also need consideration.

The work depends on the lender, the scheme and your circumstances. Ask which documents the solicitor will review, what is outside their scope and what happens if something needs clarification. Their role is to help you understand the legal commitments, not to tell you which product to choose.

How legal advice differs from financial advice

Legal advice and financial advice answer different questions. An appropriately authorised financial adviser considers your finances and whether a particular product is suitable, then explains the recommendation and its financial risks. The solicitor focuses on the legal documents, your rights and obligations, and whether you understand the legal effect of signing.

An independent legal review matters because lender documents may create binding commitments. Before signing, raise anything you don’t understand, including what could happen if your circumstances change, how the arrangement affects a co-owner and what it may mean for your estate. Don’t assume one professional’s advice covers the other’s role.

  • Ask the adviser to explain the financial recommendation and its risks.
  • Ask the solicitor to explain the legal terms, obligations and any points requiring action.
  • Check that both professionals understand the scheme and your circumstances. Ask who to contact with questions outside their remit.

Choosing between equity release legal advice solicitors is about more than finding someone to process paperwork. Look for a clear explanation of scope and responsibilities, and confirm the solicitor can act on your specific scheme before instructing them.

Financial advice doesn’t replace an independent legal review. The adviser considers the financial product and its suitability; the solicitor examines the legal documents and explains the obligations they create. The role of an equity release solicitor includes helping you understand the legal commitment before you sign. The work and possible consequences depend on the contract, scheme terms and your household circumstances.

Read the documents with your own plans in mind, not just the amount you could release. Borrowing and interest may reduce the property value left for your estate, but the eventual effect depends on how the plan works and what happens over time. If you share your home, consider whether your partner or another household member could remain there if circumstances change. Their position depends on the agreement and who is named on it, so ask the solicitor to explain the relevant terms.

Which documents and details may the solicitor need?

To help the solicitor understand the transaction, gather the lender’s offer and legal paperwork, details of any existing mortgage or legal charge, and information about property ownership. Title details and co-owner information may also be relevant. Not every case needs the same documents. Ask the lender and solicitor for the list that applies to your scheme and circumstances, and check whether anything is missing or needs updating.

Consider your partner, estate and future plans

Think through your occupancy arrangements, inheritance wishes and the needs of anyone who lives with you. Ask what the contract says if you move home or your living arrangements change, and whether your partner’s position is affected. Equity release legal advice solicitors can explain the legal effect of the documents, but they don’t determine whether the financial arrangement is suitable for you.

Before signing, understand exactly what events trigger repayment. The timing and consequences depend on the agreement. Ask the solicitor to explain relevant triggers in plain English, including what happens if the home is sold or the borrower’s circumstances change, where those situations are covered by the contract.

Tax, means-tested benefits and care-fee treatment depend on individual circumstances and current rules. Don’t rely on general information to predict the result; seek appropriate specialist advice before making a decision. If your decision raises wider property or estate-planning questions, you can enquire about property and estate-planning legal services and confirm whether the firm can assist with your circumstances.

Compare equity release with alternatives before choosing a solicitor

Equity release is one way to access money tied up in your home, but it isn’t the only option to explore. Downsizing, another type of loan, using savings or investments, or receiving family support may raise different questions about ownership, repayment, affordability and future plans. None is suitable for everyone. What’s available and appropriate depends on your circumstances and current product terms.

Discuss financial suitability and affordability with an appropriately authorised financial adviser. A solicitor can explain the legal implications of a proposed arrangement, including how it affects the property and the people connected to it. Comparing options first can help you identify the right questions for both professionals.

Compare the questions each option raises

Option Questions to consider
Equity release How does interest build, when is repayment due, and what do the terms say about moving home or changes in circumstances?
Downsizing Would selling and buying a different property suit your housing needs, and what would happen to ownership and the proceeds?
Other borrowing Can repayments remain affordable, what security is required, and how flexible are the repayment and early repayment terms?
Savings, investments or family support What assets could be used without undermining other plans? If a relative helps, is the arrangement a gift or a loan, and should it be recorded clearly?

This is a starting point, not a recommendation. Discuss family support openly with everyone involved and consider recording any agreed terms. The right approach depends on individual finances, property needs and family relationships.

Questions to resolve before deciding

Ask the adviser to explain how interest, repayments and any early repayment charges work under the specific offer. Ask the solicitor to clarify the legal terms and any obligations that could affect your plans. Check what the contract says if you move, your circumstances change or a borrower enters long-term care. Don’t assume the same outcome applies across all schemes.

Write down unanswered questions and take them to the relevant professional. Keep financial suitability questions for your adviser and legal-document questions for your solicitor. Ask each to clarify where their role ends. Comparing options before selecting equity release legal advice solicitors can help you focus on the expertise you need, rather than treating the choice of solicitor as a decision about which financial route to take.

Equity Release Legal Advice: How to Choose a Solicitor

How to prepare for an equity release solicitor consultation

A little preparation can make your first conversation more focused. You don’t need every document ready, but a clear picture of the proposed plan, your property and your priorities can help the solicitor identify what needs checking. Be open about relevant household and estate-planning circumstances, including details that may feel personal. They can affect which questions need to be considered.

Gather information and agree the next steps

  • 1. Collect the paperwork. Bring any proposed plan documents or lender correspondence, property ownership and title information, and details of an existing mortgage or other charge, if applicable. Ask the lender and solicitor which documents they need for your case.
  • 2. Note your circumstances and questions. Record who lives in the property, whether there are co-owners or dependants, and any concerns about a partner’s housing position or your inheritance intentions. Consider possible future changes, such as moving home.
  • 3. Bring relevant estate-planning papers. If you have a will or other documents that may relate to your plans, ask whether they would help the solicitor understand your concerns. Don’t assume they’ll all be required.
  • 4. Clarify the retainer before instructing. Ask what legal work is included, what falls outside the scope, who will handle the matter, how you’ll receive updates and what the next steps are.
  • 5. Confirm fees and process. Request clear information about fees and how any additional work would be discussed. Check your understanding before agreeing to proceed.

Questions to ask your solicitor

Use the conversation to establish practical expectations, not just whether the firm can review documents. Ask: “Which parts of the proposed arrangement will you examine?”, “What issues might require further information?” and “Who should I contact if I have a question about financial suitability?” A solicitor should explain the boundaries of their role, the process they propose and how they’ll raise matters that need your decision.

Timing and required steps vary according to the lender, transaction and your circumstances. Ask what sequence to expect and whether anything is needed from you before the review can progress. Don’t instruct a firm before you understand its scope and fees. If you’re considering equity release legal advice solicitors and have wider property or estate-planning questions, you can enquire with Feltons Solicitors LLP to establish whether the firm can assist with your circumstances.

A suitable solicitor should make the legal process clear, explain what they will review and give you space to raise concerns. Before instructing anyone, confirm they can act on the lender’s scheme and your particular circumstances. Experience with property and private client matters can be relevant, but ask specifically about the documents and requirements involved in your proposed transaction.

How to assess a solicitor’s suitability

Use your first conversation to check the fit rather than assuming a general property background covers every equity release arrangement. Ask whether the solicitor has experience with the relevant lender, scheme documents and transaction requirements, and what they would do if the paperwork raises an issue. Their role should be independent of the financial product recommendation. Ask how they’ll explain the legal obligations and check your understanding.

  • Relevant experience: Can they act on this scheme and explain the legal review it requires?
  • Clear scope: Which documents and issues are included, and what falls outside the work?
  • Communication: Who will handle your matter, how will updates be provided, and how can you raise questions?
  • Transparent fees: What will you be charged, and how will any additional work be discussed?
  • Your circumstances: Will the review take account of ownership, co-owners, household arrangements and your stated concerns?

Equity release legal advice solicitors should explain the legal position in language you understand, without presenting their review as a recommendation about financial suitability. If anything remains unclear, ask for an explanation before you sign or agree to proceed.

What to expect when you contact Feltons Solicitors LLP

Feltons Solicitors LLP provides private client and property legal services, including wills, probate, estate planning and residential conveyancing. The firm’s information does not confirm a specialist equity release service. An enquiry is a practical way to establish whether the firm currently accepts this type of matter, can act on your scheme and circumstances, and what the scope of any advice could be.

If your questions connect with wider inheritance planning, you may find the estate planning guide helpful. For questions about property ownership and transactions, see the residential property law guide. These resources provide background, but they don’t replace advice on your specific documents and circumstances.

To establish whether the firm can assist and discuss an appropriate next step, contact Feltons Solicitors LLP to discuss your circumstances. You can ask about availability, the applicable jurisdiction, the proposed scope of work and fees before deciding whether to instruct.

Take a considered next step

Choosing equity release legal advice solicitors means checking that the legal review is distinct from financial product advice, that the solicitor can act on your particular scheme, and that the documents and obligations are explained in language you understand. Weigh alternatives and consider how the decision may affect your household and estate plans before committing.

Feltons Solicitors LLP provides property law and conveyancing services alongside private client services, including wills and estate planning. The firm’s information doesn’t confirm whether it currently accepts equity release matters, so check availability, scope and whether it can assist with your circumstances before instructing.

Contact Feltons Solicitors to ask whether the firm can assist with your circumstances.

Frequently Asked Questions

What does an equity release solicitor do?

An equity release solicitor reviews the transaction’s legal paperwork and explains the obligations, risks and steps relevant to your case. They may check title ownership, co-owners, any existing mortgage and whether lender requirements appear to have been met. Their role isn’t to recommend a financial product. Ask which documents they’ll review, what falls outside their agreed scope and whether they can act on your particular scheme.

Do I need a solicitor for equity release?

Equity release transactions commonly involve legal work, but the process and requirements depend on the lender, product and your circumstances. A solicitor can explain the documents and commitments so you can understand them before signing. Ask the lender and solicitor to confirm the steps required for your case. Legal advice doesn’t replace regulated financial advice about whether a product is suitable for you.

Can an equity release solicitor give financial advice?

A solicitor’s legal advice is separate from a regulated recommendation about whether an equity release product suits you. Within the agreed scope, the solicitor can explain legal documents, obligations and relevant transaction steps. For product recommendations and financial suitability, speak to an appropriately authorised financial adviser. If you’re unsure who should answer a particular question, ask both professionals to explain their responsibilities before you proceed.

What should I ask an equity release solicitor before instructing them?

Ask whether they can act on your specific scheme, what the legal work includes and who will handle your matter. Clarify the expected steps, how updates will be given, the fees and how additional work would be discussed. You can also ask how the review will address property ownership, your partner’s position and estate-planning concerns. Request clear answers before deciding whether to instruct the firm.

Will equity release affect my inheritance or my family?

It may reduce the property value remaining for your estate after borrowing and interest are repaid, though the eventual effect depends on the agreement and future circumstances. Consider how the arrangement could relate to your partner’s housing position, other household members and inheritance wishes. Ask your financial adviser about the financial implications and your solicitor about the legal terms. You may also wish to review your will or wider estate plans.

Can I compare equity release with other options before signing?

Yes. You can discuss alternatives such as downsizing, other borrowing or using other assets with an appropriately authorised financial adviser. Compare each route by considering ownership, repayment, affordability and flexibility, rather than relying on one feature alone. Availability and suitability depend on your circumstances and current terms. If you’re considering equity release, a solicitor can explain the legal documents and identify points that need clarification before you sign.

What documents should I take to an equity release solicitor?

Useful starting points may include the proposed plan documents, property ownership or title information, and details of any existing mortgage. A will or other estate-planning papers may help if they relate to your concerns. Prepare questions about your household and future plans, too. Requirements vary, so ask the solicitor for their document list before your meeting. Only send sensitive paperwork through a channel you’ve verified with the firm.

International Probate Solicitors UK: Navigating Cross-Border Estates in 2026

International Probate Solicitors UK: Navigating Cross-Border Estates in 2026

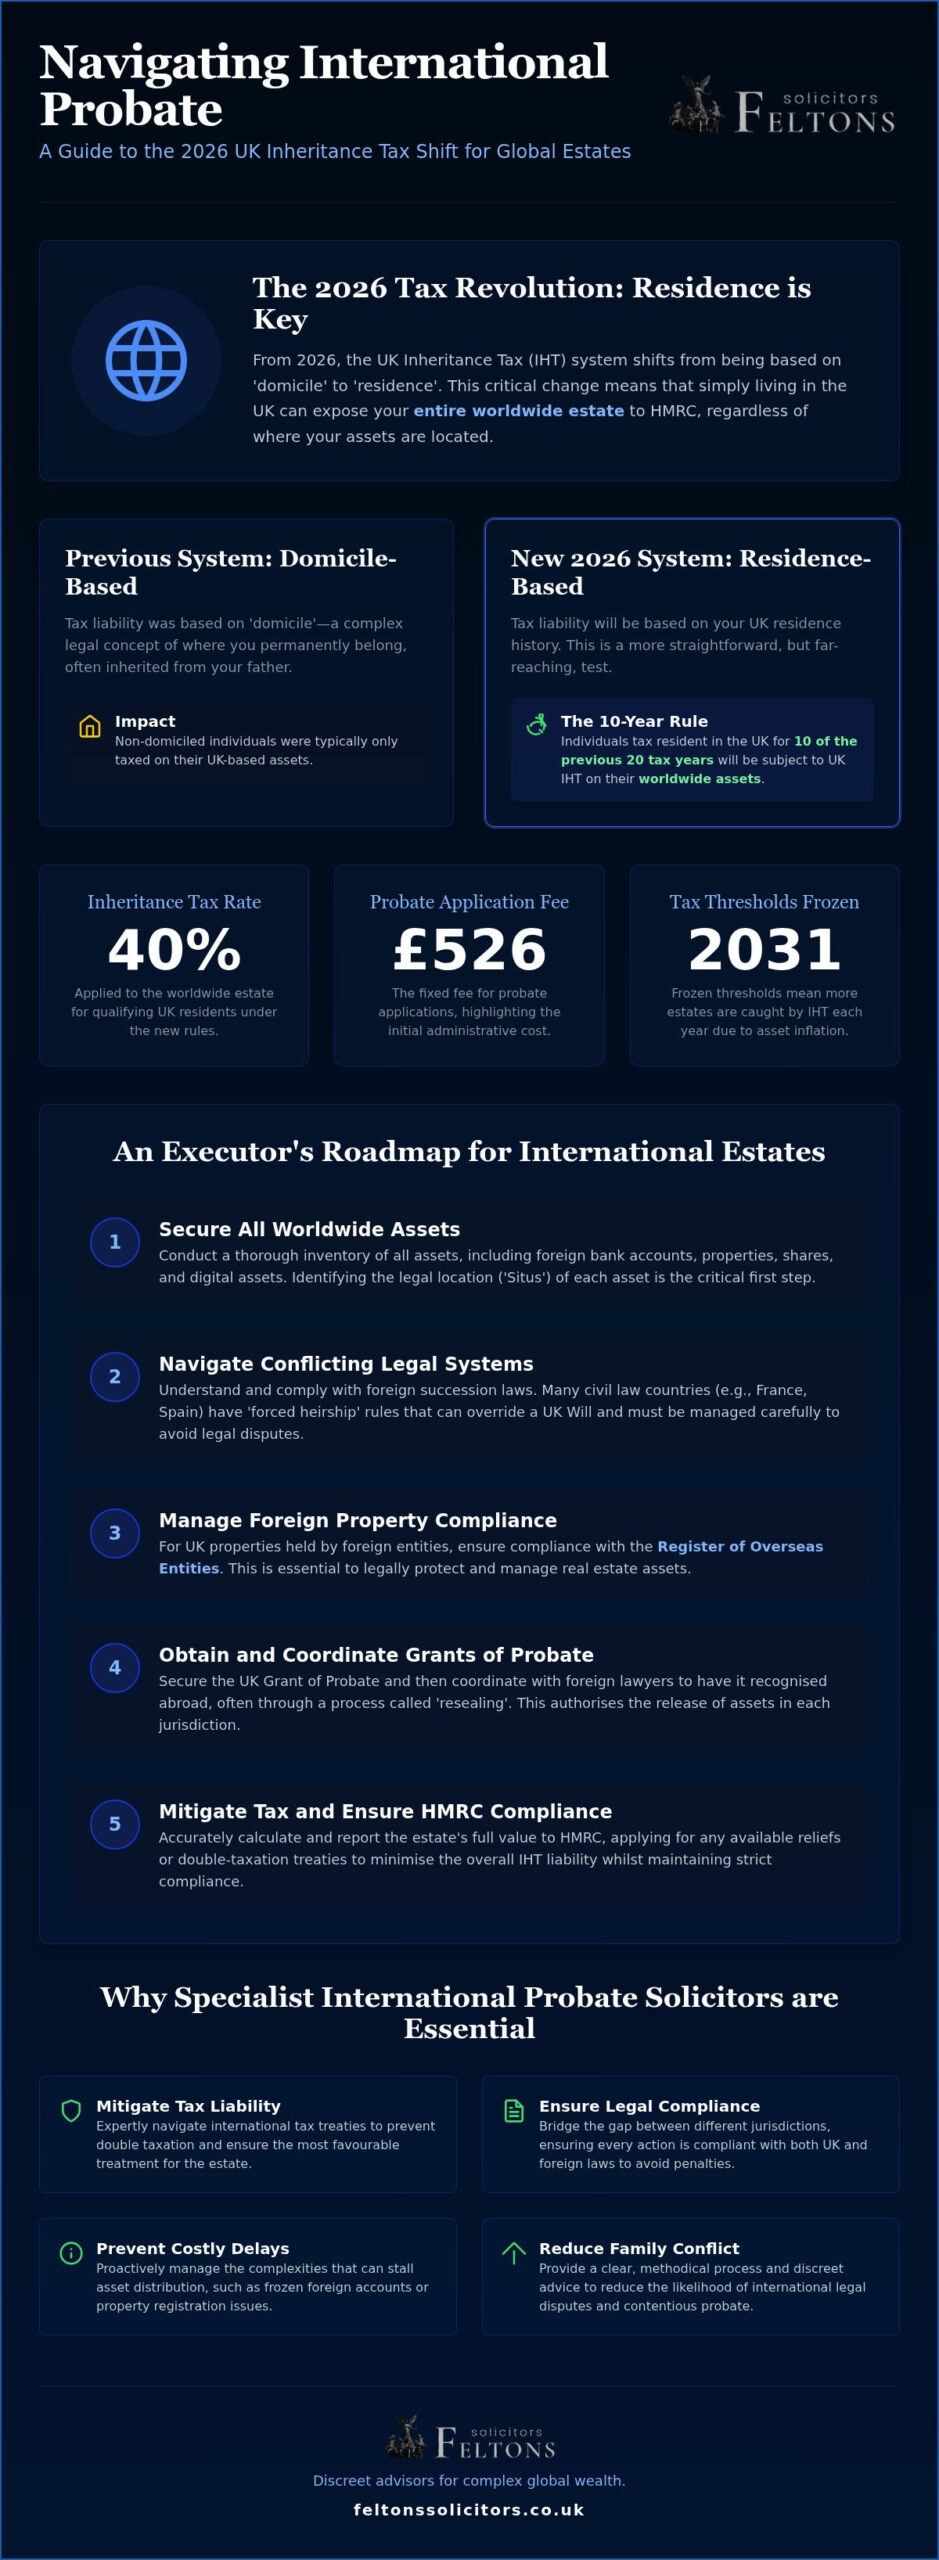
Could your global legacy be dismantled by the very borders you crossed to build it? In 2026, the transition to a residence-based Inheritance Tax system means that simply living in the UK can now expose your worldwide assets to HMRC, regardless of where they’re physically located. Managing these complexities requires the steady hand of experienced international probate solicitors uk. The intersection of foreign succession laws and British tax requirements has never been more intricate, making professional oversight essential for protecting family wealth and ensuring your intentions are honoured.

It’s natural to feel overwhelmed by the conflicting demands of different legal systems or the fear that significant delays will stall the distribution of assets to your beneficiaries. With probate application fees now at £526 and tax thresholds frozen until 2031, the margin for error has vanished. This guide provides a clear, comprehensive roadmap for managing complex cross-border estates, ensuring every foreign asset is legally secured whilst maintaining strict compliance with current 2026 regulations. We’ll examine how to navigate the new residence-based tax landscape, mitigate your total tax liability through expert planning, and streamline the probate process across multiple jurisdictions to provide your family with much-needed stability.

Key Takeaways

  • Grasp how the 2026 shift to a residence-based tax system impacts your global estate and the specific reporting obligations now required by HMRC.
  • Navigate the complexities of foreign property ownership, including the essential steps for the Registration of Overseas Entities to protect your real estate assets.
  • Benefit from the bespoke guidance of international probate solicitors uk to manage the nuances of cross-border administration and ensure seamless asset distribution.
  • Utilise a methodical executor roadmap to accurately secure worldwide assets while identifying the most favourable tax treatments available under current laws.
  • Reduce the likelihood of international legal disputes and contentious probate through discreet, forward-thinking estate management strategies.

What is International Probate? Understanding Cross-Border Estate Administration

International probate is the legal procedure required to manage and distribute an estate when the deceased held assets in more than one country. Unlike a standard domestic probate, which follows a single set of rules, cross-border administration involves a complex conflict of laws between different legal systems. This often occurs in two primary scenarios: a UK resident dies leaving property or bank accounts abroad, or a foreign national passes away leaving assets within the UK. In either case, the process requires international probate solicitors uk to act as a central coordinator, managing various legal threads to ensure a cohesive distribution of the estate.

The role of the UK solicitor is to bridge the gap between jurisdictions. They don’t just handle the UK side; they liaise with foreign legal professionals to ensure that the grant of probate is recognised and that assets are released without unnecessary friction. This coordination is what prevents a cross-border estate from becoming a decades-long administrative burden for the family.

The Legal Complexity of Multiple Jurisdictions

The primary challenge in these cases is the concept of “Situs,” which refers to the legal location of an asset. For example, immovable property like a holiday home is governed by the laws of the country where it stands, whilst movable assets like shares or cash might follow the laws of the deceased’s last residence. Identifying every jurisdiction early is vital. Failing to account for a single foreign bank account can stall the entire process. Experienced international probate solicitors uk must navigate different definitions of “ownership” and “validity” across borders, which significantly increases the administrative burden compared to a UK-only estate.

Why Specialist Expertise is Essential for Cross-Border Estates

Many civil law countries, such as France or Spain, operate under “forced heirship” rules. These regulations dictate that a specific portion of an estate must go to certain relatives, potentially overriding the instructions in a UK Will. Without specialist guidance, executors risk foreign assets being frozen or facing unexpected legal challenges from disgruntled heirs abroad. A dedicated solicitor ensures that the estate remains compliant with international treaties and local requirements, preventing costly delays. At Feltons Solicitors LLP, we provide that boutique level of care, acting as a discreet, trusted advisor to navigate these global complexities whilst protecting the integrity of the deceased’s final wishes.

The distinction between domicile and residence is often the most significant hurdle in cross-border estate administration. Whilst residence describes where you live, domicile is a deeper legal concept reflecting where you truly belong or intend to remain permanently. Since April 2025, the UK has moved to a residence-based system for Inheritance Tax. This means individuals who’ve been UK tax residents for at least 10 out of the previous 20 tax years are now subject to UK IHT on their worldwide assets. For executors, this shift makes the guidance of international probate solicitors uk essential to avoid double taxation or compliance failures with HMRC.

Determining Domicile and Its Impact on Probate

HMRC’s assessment of domicile remains the foundation of any international probate strategy. You typically have a domicile of origin, which is usually the country of your father’s domicile at your birth. However, you can acquire a domicile of choice by moving to a new country with the clear intention of living there permanently. Even if you’ve lived abroad for years, HMRC may still consider you “deemed domiciled” in the UK for tax purposes if you haven’t sufficiently severed those legal ties. This determination dictates whether the 40% Inheritance Tax rate applies only to your UK assets or your entire global estate. Our team at Feltons Solicitors LLP acts as a discreet advisor for complex wealth, ensuring these technical legal frameworks are navigated with precision.

Resealing a Grant vs. Applying for a New Grant

A common point of confusion for foreign executors is whether they need to start the probate process from scratch in the UK. If the deceased was from a country covered by the Colonial Probates Act 1892, the existing foreign grant can often be “resealed”. This process is available for several jurisdictions, including Australia, Canada, New Zealand, and Hong Kong. Resealing is a streamlined administrative procedure where the UK court places its own seal on the foreign document, giving it full legal force here. It’s significantly faster and more cost-effective than a fresh application.

However, for countries not covered by this Act, such as the USA or most of mainland Europe, a full UK Grant of Representation is required. This involves a more rigorous application process, including a detailed account of UK-based assets and liabilities. Experienced international probate solicitors uk can determine which path is necessary, preventing the freezing of assets and reducing distribution delays. Whether your situation requires a simple reseal or a complex new application, a methodical approach ensures that the estate is administered whilst maintaining strict compliance with international treaties.

Managing Foreign Property and the Register of Overseas Entities

Real estate often forms the cornerstone of a cross-border estate, yet it presents unique challenges that differ from liquid assets like cash or shares. When a property is involved, executors must navigate the specific Residential Property Law of the country where the land is situated. This is particularly complex when UK land is held by a foreign company or trust. In such cases, the mandatory Registration of Overseas Entities becomes a critical compliance hurdle. If the deceased was a beneficial owner of an overseas entity that owns UK property, the executor has a legal duty to update the register at Companies House. Failure to do so can freeze the property’s title, preventing any sale or transfer to beneficiaries.

Compliance with the Economic Crime Act

Under the Economic Crime (Transparency and Enforcement) Act 2022, any foreign entity owning UK land must identify its beneficial owners. Probate acts as a trigger for these requirements. Executors must verify the identity of the new beneficial owners or confirm that the deceased’s interest has ceased. This isn’t a task for the layperson. It requires a UK-regulated verification agent to submit the data to Companies House. Professional international probate solicitors uk provide this essential service, ensuring that the estate doesn’t face daily fines or criminal prosecution for non-compliance. These regulations are designed to prevent money laundering, but for an executor, they represent a significant administrative trap that can stall asset distribution for months.

Valuing and Transferring Foreign Real Estate

Securing an accurate valuation of foreign property is the first step in determining the estate’s total value for HMRC. You can’t simply rely on local estate agent estimates. HMRC requires professional valuations that meet their specific criteria, which often means coordinating with surveyors in the country where the property is located. Beyond the valuation, executors must account for local transfer taxes and potential Capital Gains Tax. Each jurisdiction has its own rules for how property passes to heirs. Some countries require a local notary to oversee the transfer, whilst others may have specific “exit taxes” for non-resident beneficiaries. By engaging international probate solicitors uk, you gain a partner who can manage these local professionals, ensuring that the property is either sold or transferred efficiently whilst minimising the tax impact on the final inheritance.

International Probate Solicitors UK: Navigating Cross-Border Estates in 2026

An Executor Roadmap: Steps for Handling International Assets

Managing an estate with global reach requires a disciplined, step-by-step approach to avoid administrative gridlock. While the legal process is complex, the journey often begins with the support of dedicated funeral services like Ashley Edwards to help families through the immediate practicalities of loss. Once these initial arrangements are settled, the first priority for the estate is to conduct a thorough search for all worldwide assets and liabilities. This isn’t always straightforward, as digital accounts, offshore holdings, and foreign life policies can be easily overlooked. Once the inventory is complete, you must determine the deceased’s domicile and the applicable tax regime. This step is critical; it dictates whether HMRC expects a slice of the global pie or just the UK-based assets. Working with international probate solicitors uk ensures this assessment is accurate, preventing costly overpayments or future investigations.

The paperwork for cross-border estates is significantly more demanding than domestic probate. You’ll often need multiple copies of the death certificate, each verified with an Apostille to prove its authenticity to foreign banks and land registries. If the deceased left a Will in a foreign language, it must be translated by a certified professional before the UK Probate Registry will accept it. Organising a comprehensive inventory of global shareholdings is equally vital. Each jurisdiction has its own requirements for transferring securities; missing a single document can stall the distribution process for months. A methodical approach to documentation is the only way to maintain the momentum of the estate administration.

Navigating International Inheritance Tax

Tax is often the greatest source of anxiety for executors. Fortunately, the UK has established Double Taxation Treaties with many countries to ensure you don’t pay tax twice on the same asset. However, claiming this relief isn’t automatic. You must report all foreign assets on the IHT400 form and provide evidence of any tax already paid abroad. This is where professional Estate Planning advice becomes invaluable. It helps you understand the nuances of these treaties and ensures the estate remains compliant whilst protecting the maximum amount of wealth for the beneficiaries. If you’re struggling to manage the complexities of a multi-jurisdictional estate, our team of international probate solicitors uk can provide the steady, expert guidance you need. For tailored support with your cross-border legal matters, contact Feltons Solicitors LLP today.

Why Specialist International Probate Solicitors are Essential

Cross-border estates aren’t just legal puzzles; they’re human stories spanning continents. Managing these requires more than a standard probate application. By engaging international probate solicitors uk, you secure a single point of contact who understands the friction between different legal systems. This central coordination is vital for preventing the misunderstandings that lead to Contentious Probate. When beneficiaries are spread across jurisdictions, the risk of disputes over asset valuation or distribution increases. A specialist firm mitigates this by providing clear, authoritative guidance that respects the laws of every country involved.

Feltons Solicitors LLP brings a unique advantage to this process. We specialise in both Private Client and Property Law, a combination that’s essential when an estate includes high-value UK real estate or complex overseas entities. Many firms treat probate and property as separate silos. We integrate them, ensuring that the registration of overseas entities or the transfer of leasehold property happens alongside the probate application. This prevents the administrative gaps that often cause significant delays for executors.

Discreet Handling of High-Value Estates

Privacy is paramount when dealing with high-value international wealth. Our boutique approach prioritises personal connection over high-volume processing. We understand the sensitive family dynamics that arise when assets are distributed amongst relatives in different tax regimes. By acting as a discreet, trusted advisor, we protect the privacy of your beneficiaries. We ensure that the technical legal work remains invisible to the family, allowing them to focus on their own transition whilst we handle the global complexities with quiet confidence.

Pragmatic Advice for Global Clients

Efficiency is the hallmark of our service. We focus on pragmatic outcomes that avoid protracted legal battles. During what is often a stressful period, we provide a calm, steady presence, guiding you through every HMRC requirement and foreign legal hurdle. Our goal is to secure your assets and distribute them with minimal tax liability. If you’re ready to secure your global legacy, you can instruct us for a comprehensive Probate and Estate Planning review. This ensures your current estate is handled correctly whilst preparing your own affairs for the future. As experienced international probate solicitors uk, we’re here to provide the sophisticated oversight your estate deserves.

Securing Your Global Legacy with Confidence

Managing a cross-border estate in 2026 requires a meticulous balance of legal precision and strategic foresight. As the UK moves towards a residence-based tax system, the importance of accurately determining domicile whilst ensuring compliance with the Registration of Overseas Entities cannot be overstated. These complexities often feel overwhelming. They don’t have to be. By understanding the intersection of private client law and international property requirements, you can protect family wealth and ensure a seamless transition of assets across jurisdictions.

The guidance of international probate solicitors uk provides the steady, professional oversight needed to navigate these global challenges. Feltons Solicitors LLP offers a sophisticated boutique service tailored to the needs of complex global wealth. Our expertise in multi-jurisdictional property and probate ensures that every detail, from foreign tax clearances to beneficial owner registrations, is handled with the utmost discretion and care. We’re here to act as your trusted advisor, providing pragmatic solutions that respect both the law and your family’s privacy. Contact Feltons Solicitors LLP for expert international probate advice today and take the first step towards securing your legacy with peace of mind.

Frequently Asked Questions

Do I need a UK solicitor if the deceased lived abroad but had UK assets?

Yes, if the deceased owned UK property, bank accounts, or shares, you’ll generally need a UK Grant of Probate to release them. UK financial institutions won’t accept foreign grants without a local seal or a fresh application. Engaging international probate solicitors uk ensures that these assets are identified and secured whilst maintaining compliance with local inheritance tax requirements. It’s the most efficient way to prevent assets from being frozen indefinitely.

How long does international probate typically take to complete?

International probate usually takes between 6 and 18 months, depending on the complexity of the jurisdictions involved. Whilst a domestic estate might be settled faster, cross-border cases require coordination with foreign legal professionals and tax authorities. Delays often occur during the valuation of foreign property or when waiting for tax clearances from multiple countries. A methodical approach and early documentation gathering help to keep the process within a predictable and manageable timeframe for the family.

Can I reseal a Grant of Probate from any country in the UK?

No, you can only reseal a Grant of Probate if it was issued in a country covered by the Colonial Probates Act 1892. This includes many Commonwealth jurisdictions such as Australia, New Zealand, Canada, and South Africa. If the deceased lived in a country outside this list, such as the USA or France, you must apply for a fresh UK Grant of Representation. For those managing estates with a US connection, you might check out Coastal Legacy Law to learn more about Florida trusts and elder law. This technical distinction is vital for planning your administrative timeline and overall estate budget.

Having multiple wills is a common strategy to handle assets in different jurisdictions, provided they’re drafted correctly. The primary challenge is ensuring that a newer will doesn’t accidentally revoke an older one in another country. Solicitors must carefully review the revocation clauses in each document. If conflicts arise, legal experts must determine which law takes precedence, often based on the deceased’s domicile or the location of the specific assets being distributed amongst the heirs.

Will I have to pay inheritance tax in both the UK and the foreign country?

You might be liable for tax in both countries, but Double Taxation Treaties usually prevent you from paying twice on the same asset. These treaties allow you to offset tax paid in one jurisdiction against the liability in another. Since the UK moved to a residence-based system in 2025, your worldwide assets may be subject to HMRC’s 40% rate if the deceased met the 10-out-of-20-year residency rule. Professional planning is essential to manage these complex liabilities.

What is an Apostille and why is it needed for international probate?

An Apostille is a certificate that authenticates the signature or seal on a public document, such as a death certificate or a power of attorney. It’s a requirement under the Hague Convention to ensure that documents from one country are legally recognised in another. Without this verification, foreign banks and land registries often won’t accept your UK legal papers. This causes significant administrative hurdles and can indefinitely stall the distribution of the estate to its beneficiaries.

How does the Register of Overseas Entities affect inheriting UK property?

If you’re inheriting UK property held through a foreign company, you must comply with the Register of Overseas Entities. Executors are required to update Companies House regarding any changes in beneficial ownership. Failure to maintain this registration can result in daily fines and prevent the property from being sold or transferred. Specialist international probate solicitors uk can act as verification agents to ensure the estate remains compliant with the Economic Crime Act whilst protecting the property’s legal title.

Can an executor be held personally liable for international tax errors?

Yes, executors carry a heavy burden of personal liability for the accuracy of tax returns submitted to HMRC and foreign authorities. If you fail to report worldwide assets or miscalculate the tax due, you could be held responsible for penalties or unpaid interest out of your own pocket. This financial risk is why many executors seek professional guidance from a boutique firm like Feltons Solicitors LLP to ensure every valuation and tax claim is precise and fully compliant.