Cohabitation Property Dispute Lawyers UK: Your Rights and Next Steps in 2026

Cohabitation Property Dispute Lawyers UK: Your Rights and Next Steps in 2026

What if the property is registered in your former partner’s name, but you paid towards the deposit, mortgage or renovations? The title deeds matter, but they may not tell the whole story. Cohabitation property dispute lawyers UK can help you assess the ownership evidence and understand the options available.

If you’re unsure whether bank transfers, messages or an informal understanding support your position, you’re not alone. Unmarried partners don’t acquire the same rights as married couples simply by living together, and there is no “common law marriage” in England and Wales. A dispute is usually assessed under property and trust law, where the details of your contributions and any agreements may matter.

This guide explains the legal rules that may apply, the documents and other evidence to gather, and how a solicitor can help you consider negotiation, settlement or a court decision. It also covers the 2026 reform consultation. As of October 2026, the law has not changed, so understanding your position under the current rules remains essential.

Key Takeaways

  • Separate legal ownership shown on the title from any claimed beneficial interest, then identify exactly what is in dispute.
  • Gather title records, bank statements and messages. Distinguish evidence of payments from evidence of what both partners intended.
  • Consider negotiation or mediation as possible ways to resolve the disagreement before deciding whether formal proceedings are appropriate.
  • Cohabitation property dispute lawyers UK can assess the ownership evidence, potential claims and practical options for your circumstances.
  • A solicitor can help you understand the strengths and risks of your position, but the outcome depends on the facts and applicable law.

Unmarried partner rights in UK property disputes

A breakup can be difficult enough without uncertainty over who owns the home, who should keep paying the mortgage or whether a deposit should be repaid. A cohabitation property dispute arises when former partners disagree about their legal or beneficial interests in a property, including who owns it or how its value should be shared.

In England and Wales, living together doesn’t make a couple legally married, however long they have been together. Unmarried partners don’t automatically gain the same financial claims on separation as spouses. That doesn’t mean a non-owning partner can never have an interest in a home. A claim may depend on the property arrangements, contributions and evidence of what the parties intended. The applicable rules also depend on where the property is and which jurisdiction’s law applies.

Does living together create ownership rights in a home?

The title register identifies the legal owner or owners. A separate beneficial interest may also be claimed, even where the legal title is in one partner’s name, but living together alone doesn’t establish that interest. In England and Wales, disputes about interests in land may involve the Trusts of Land and Appointment of Trustees Act 1996 (TOLATA). The legal route and evidence needed depend on the circumstances.

Paying household bills, such as utilities or groceries, doesn’t necessarily prove a share of the property. Mortgage payments, a deposit or substantial renovation costs may be relevant, but no single payment automatically decides ownership. The key question is what the evidence shows about the parties’ intentions and the arrangement they made.

Which jurisdiction’s rules apply to a cohabitation dispute?

“UK law” isn’t one set of rules for every property dispute. England and Wales, Scotland and Northern Ireland have distinct legal systems, so the legal tests and procedures can differ. This article’s references to TOLATA and the absence of “common law marriage” relate to England and Wales. They shouldn’t be treated as a UK-wide statement of procedure or rights.

Start by establishing where the property is, then get advice based on the relevant jurisdiction before deciding how to proceed. The phrase cohabitation property dispute lawyers UK may describe the search, but a useful assessment must account for the specific legal system and facts.

In many property disputes, ownership evidence, not relationship status alone, shapes the claim. A solicitor can help distinguish what the title establishes from any beneficial interest being asserted, and assess how the available evidence may affect your options.

How courts assess ownership and interests in shared homes

In England and Wales, the property title is usually the starting point for working out legal ownership. A dispute may also concern beneficial ownership: the interests in the property that determine who is entitled to its value. Legal title shows who owns the property in law; beneficial ownership concerns who is entitled to its value, and in what shares.

The court will consider relevant documents and the parties’ intentions, which may be recorded expressly in a declaration of trust or other written agreement. Where there’s no clear agreement, intention may sometimes be inferred from conduct and the wider circumstances. The legal approach depends on whether the property is registered in one or both partners’ names, and the law differs across the UK.

Two leading England and Wales decisions illustrate how a court may consider shared ownership. In Stack v Dowden [2007] UKHL 17, the House of Lords considered how the beneficial shares of a home registered in joint names could differ from equal shares, taking account of the parties’ whole course of dealings. In Jones v Kernott [2011] UKSC 53, the Supreme Court considered how shares in a jointly owned home could be assessed when the parties’ intentions changed over time. These cases don’t create a simple formula for every dispute. Their application depends on the facts and legal context.

What if only one partner is named on the title deeds?

Sole legal ownership is a significant starting point, but it may not settle whether the other partner has a beneficial interest. A person asserting such an interest needs to establish it through the relevant facts and evidence. The court may consider what was agreed or understood, alongside conduct connected with acquiring or dealing with the home. The length of the relationship alone doesn’t transfer ownership, and no particular contribution guarantees a share.

Can mortgage payments, deposits or renovations affect a claim?

They can be relevant evidence, but they don’t automatically determine whether an interest exists or calculate its size. A deposit transfer may show who provided funds, for example, but context matters: was it intended as a contribution to ownership, a loan or something else? Mortgage statements, renovation invoices and payment histories may help build that picture, as can discussions, written agreements and later conduct.

Keep records together and note what each payment was for, rather than assuming that spending on the home speaks for itself. A careful review can help distinguish evidence of contribution from evidence of shared intention. Advice on property and dispute resolution can help clarify how those issues may apply to your circumstances.

What evidence can strengthen or weaken a cohabitation property claim?

Useful evidence helps show two different things: what each person paid, and what those payments or arrangements were understood to mean. A bank transfer may confirm that money changed hands, for example, but it may not establish whether it was intended as a contribution to ownership, a loan or an ordinary shared expense. The relevance and weight of evidence depend on the facts and the law of the applicable jurisdiction.

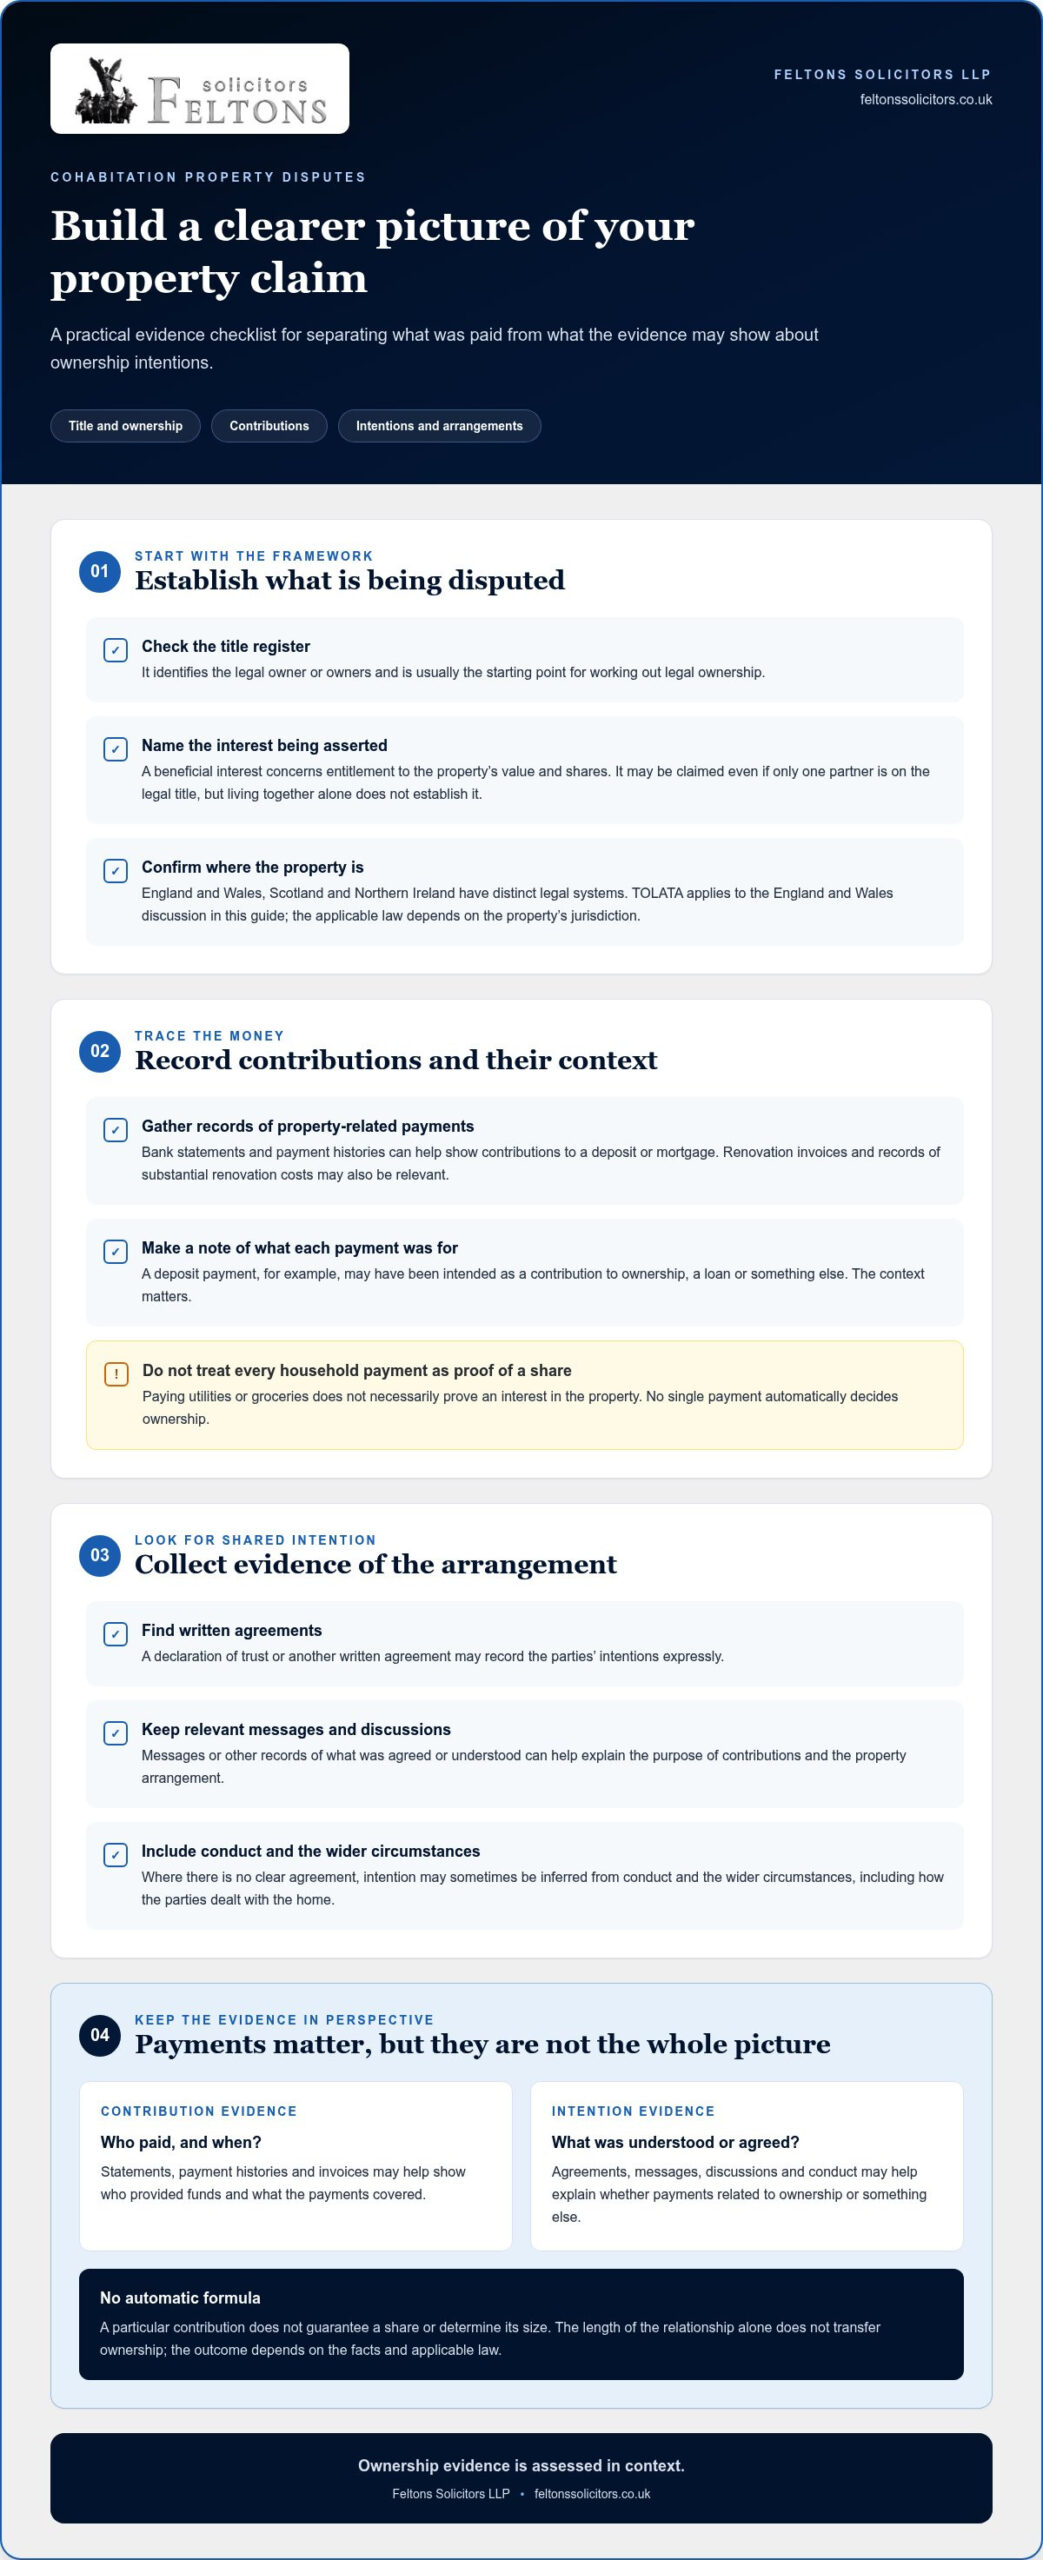
Before seeking advice, keep complete copies of relevant records and prepare a dated chronology. Note key payments, conversations and changes to the property as accurately as you can. Preserve original messages and documents. Don’t alter records or select only the parts that appear helpful. Missing paperwork doesn’t automatically defeat a claim, but it may make it harder to establish what was agreed or intended.

Which documents should you gather before seeking advice?

Start with records showing ownership, funding and the history of the home. Depending on the dispute, these may include:

  • Title documents and conveyancing correspondence, including records of how the property was purchased.
  • Mortgage statements, deposit records and bank statements showing transfers or payments.
  • Renovation invoices, receipts and related payment records.
  • Emails, text messages and other communications about ownership, contributions, repayments or plans for the property.
  • Any written agreement, such as a declaration of trust, alongside records of later discussions or changes in the arrangement.

For your chronology, record dates, amounts, the purpose of each payment and any relevant changes to the property. Add a short note of who was present for significant conversations and what you remember being said. Mark clearly where a date or detail is uncertain rather than filling gaps with assumptions.

How should you handle disputed contributions and informal promises?

Separate direct payments towards a deposit or mortgage from renovation spending, unpaid work, household bills and general living costs. These may provide different kinds of evidence, and none automatically proves a particular share. For instance, a transfer towards the mortgage shows a payment, while a message discussing whether that payment would give someone an interest may help explain its intended meaning.

Keep messages in their original context, including the surrounding conversation and date, rather than relying on isolated quotations or screenshots without context. Record informal promises as accurately as possible, but don’t assume a promise has one guaranteed legal effect. Cohabitation property dispute lawyers UK can review the documents and chronology together, assess what they may establish and identify gaps or conflicting accounts that need careful consideration.
Cohabitation Property Dispute Lawyers UK: Your Rights and Next Steps in 2026

What happens when cohabiting partners cannot agree about the property?

A disagreement doesn’t have to move straight to court. A measured approach can help you understand the issues, preserve options and avoid escalating matters before you know what each person is asking for. The right route depends on the property, the evidence, the jurisdiction and whether constructive discussion is possible.

A practical sequence is to:

  • Clarify the dispute: identify whether it concerns ownership shares, a proposed sale, occupation or the handling of mortgage payments.
  • Organise the evidence: bring together title documents, financial records and communications relevant to the disagreement.
  • Explore resolution: consider whether direct negotiation or mediation could help narrow the issues or reach agreed terms.
  • Assess formal options: take tailored advice on the available legal route and its risks before deciding whether to apply to court.

This staged approach can make discussions more focused. It also helps each person understand what remains unresolved, rather than treating every issue as one indivisible dispute.

Can negotiation or mediation resolve a property dispute?

Structured discussion may help former partners agree practical arrangements, such as a proposed sale or how to address a disputed payment. Mediation can provide a setting to explore those issues, but it isn’t suitable in every case or a guaranteed solution. Safety, each person’s willingness to participate and the nature of the disagreement all matter. Nobody should assume mediation is appropriate in every circumstance.

If you reach an agreement, make the terms clear and record them in writing. Consider legal review before relying on them, particularly where ownership interests, a sale or ongoing financial obligations are involved. For a broader view of alternatives and formal routes, read about dispute resolution options.

When might a court application under TOLATA be considered?

In England and Wales, the Trusts of Land and Appointment of Trustees Act 1996, commonly called TOLATA, may provide a route to ask the court to determine questions about interests in land. Depending on the circumstances and the application, the court may be asked to address matters such as the parties’ interests, sale of the property or occupation. The available orders depend on the facts and legal basis of the claim, so no particular result can be assumed.

A court application is a formal step. Before taking it, consider the evidence needed, the likely costs and procedural consequences, as well as whether another resolution route remains practical. TOLATA applies in England and Wales; Scotland and Northern Ireland have different legal systems. Cohabitation property dispute lawyers UK can assess which jurisdiction applies and help you weigh proportionate options without promising an outcome.

How UK cohabitation property lawyers can help you

A solicitor can bring structure to a dispute by reviewing the registered title, available documents and each partner’s account of what was agreed. They can assess possible claims, identify evidence gaps and explain the risks and practical implications of different routes, from further discussion to formal proceedings. The aim is to help you make informed decisions, not to promise a particular result before the facts have been examined.

Advice should be tailored to the property’s jurisdiction and your circumstances. A solicitor can help clarify the ownership position, consider how evidence may support or weaken a claim, and compare realistic resolution options. That assessment can also help you focus on the outcome you need, whether it involves discussing a sale, occupation or a disputed interest.

What should you prepare before speaking to a solicitor?

A concise summary makes it easier to identify the key questions. Gather what you can, even if some records are incomplete:

  • Title information, mortgage documents and conveyancing paperwork.
  • Deposit and payment records, including bank statements and mortgage contributions.
  • Any cohabitation agreement, declaration of trust or other written arrangement.
  • A brief timeline of the relationship, purchase and ownership arrangements, significant payments and changes to the property.

Also note the outcome you’re seeking and any immediate concerns, such as a proposed sale, transfer or alteration to the property. Bring the key questions you want answered. You don’t need to resolve every detail before seeking advice. Flag uncertainties clearly rather than making assumptions.

What should tailored legal advice help you understand?

After reviewing the information, advice should help you identify which jurisdiction’s rules apply, what the title establishes and whether further evidence may be needed. It should also set out possible routes to resolution and their practical implications, so you can consider what is proportionate for your objectives. The available options depend on the facts, and no outcome can be guaranteed in advance.

If you’d like more context on title and ownership concepts, consult the firm’s residential property law guide. For advice on a cohabitation property dispute, speak with Feltons Solicitors LLP. The firm’s family law, property and dispute resolution experience can help you assess your position and consider sensible next steps. Cohabitation property dispute lawyers UK should offer clear, practical guidance grounded in the evidence and your circumstances.

Take a clear next step with your property dispute

A cohabitation property dispute is assessed under the applicable law and on the evidence, not simply on how long you were together. The title is an important starting point, but documents, payments and what you both intended may also matter. Keep relevant records together and note where the facts or your former partner’s account differ.

Negotiation or mediation may help resolve some disagreements, while formal options may need consideration if agreement isn’t possible. The right route depends on your circumstances and the jurisdiction involved. Advice can clarify your position and practical choices, but no outcome can be guaranteed before the facts are reviewed.

If you’re looking for cohabitation property dispute lawyers UK, Feltons Solicitors can bring family law, property and dispute resolution experience to a tailored, pragmatic assessment of your situation. Discuss your property dispute with Feltons Solicitors and take an informed step towards resolving the issues. You don’t have to work through your options alone.

Frequently Asked Questions

Does living together for years give me rights to my partner’s house?

No. The length of time you’ve lived together doesn’t automatically give you ownership of your partner’s home. The registered title identifies the legal owner, but you may be able to assert a beneficial interest, depending on the facts, evidence and jurisdiction. Contributions to the purchase or mortgage, and evidence of shared intentions, may be relevant, but don’t guarantee a particular share. Seek tailored legal advice before making decisions about the property.

Can I claim a share of a house if my name is not on the deeds?

Possibly. Sole registered ownership is an important starting point, but it doesn’t necessarily resolve whether another person has a beneficial interest. Relevant evidence may include an agreement, payments towards the property and the parties’ conduct. No single contribution automatically creates an entitlement to a share. The legal framework differs across the UK, so advice should reflect where the property is and the circumstances of your claim.

What evidence do I need for a cohabitation property dispute?

Gather the title documents, mortgage statements, deposit records, bank transfers, renovation invoices and relevant correspondence. Messages or written agreements may help show what you and your former partner intended, not just who paid. Keep original records and prepare a dated chronology of key payments, discussions and property changes. Evidence is assessed as a whole, and which documents matter most depends on the dispute’s facts and the applicable jurisdiction.

Can I force the sale of a home after separating from my partner?

A sale may be agreed between the owners or, in some circumstances, sought through a court process. Whether that is possible depends on the legal ownership, any beneficial interests, the circumstances and the relevant jurisdiction. In England and Wales, an application under the Trusts of Land and Appointment of Trustees Act 1996 may be relevant. A court won’t necessarily order a sale, so obtain individual legal advice before taking formal steps.

Does the UK have common-law marriage?

Living together doesn’t generally give unmarried partners the same legal status as spouses simply because time has passed. In England and Wales, there’s no “common-law marriage”. That doesn’t mean a partner can never claim an interest in a home: property rights may arise through legal ownership or beneficial-interest principles, depending on the facts and jurisdiction. The rules aren’t identical across the UK, so consider advice specific to your circumstances.

How can a solicitor help with a cohabitation property dispute?

A solicitor can review the title, documents and each partner’s account, identify relevant legal issues, and explain possible evidence gaps. They can also discuss proportionate options, which may include negotiation, mediation or formal proceedings. Advice helps you understand your position and choices; it can’t guarantee a particular result. Feltons provides family law, property and dispute resolution services, with pragmatic advice tailored to individual circumstances.

Are cohabitation property laws the same across the UK?

No. There isn’t one uniform property dispute procedure for every UK jurisdiction. England and Wales, Scotland and Northern Ireland have distinct legal systems, and the applicable framework may depend on where the property is located. Avoid relying on a rule described as UK-wide without checking how it applies to your circumstances. Jurisdiction-specific legal advice can help clarify your position before you negotiate, make decisions about the property or take formal action.
Post-Nuptial Agreement Drafting Solicitors: 2026 Guide

Post-Nuptial Agreement Drafting Solicitors: 2026 Guide

Could putting financial decisions in writing bring clarity without deciding the future of your marriage? For couples considering a post-nuptial agreement, that balance matters. Discussions about money can feel sensitive or one-sided, and it’s natural to ask whether an agreement will carry legal weight. In England and Wales, post-nuptial agreements aren’t automatically binding. A court may give one significant weight if it is fair and both parties entered into it freely, with full financial disclosure and independent legal advice. Experienced post nuptial agreement drafting solicitors can help you approach the process carefully and with realistic expectations.

A considered agreement is a financial plan tailored to your circumstances, not a guarantee of a particular court outcome. This 2026 guide explains what an agreement can cover, from property and savings to pensions, business interests and debts. It also sets out what information to prepare, how solicitor-led advice can support clear decisions and what to consider before signing.

Key Takeaways

  • Changes such as an inheritance, growing business interests or a shift in finances may prompt you to revisit financial plans after marriage.
  • Understand how the court’s discretion and the principles in Radmacher v Granatino affect the weight an agreement may carry.
  • See where generic templates can fall short, particularly when assets, family circumstances or future plans are more complex.
  • Prepare a clear picture of your objectives, income, assets, pensions, liabilities and relevant supporting records before drafting begins.
  • Learn what to expect from post nuptial agreement drafting solicitors, from initial discussions and financial disclosure to review and signing.

When are post-nuptial agreement drafting solicitors useful after marriage?

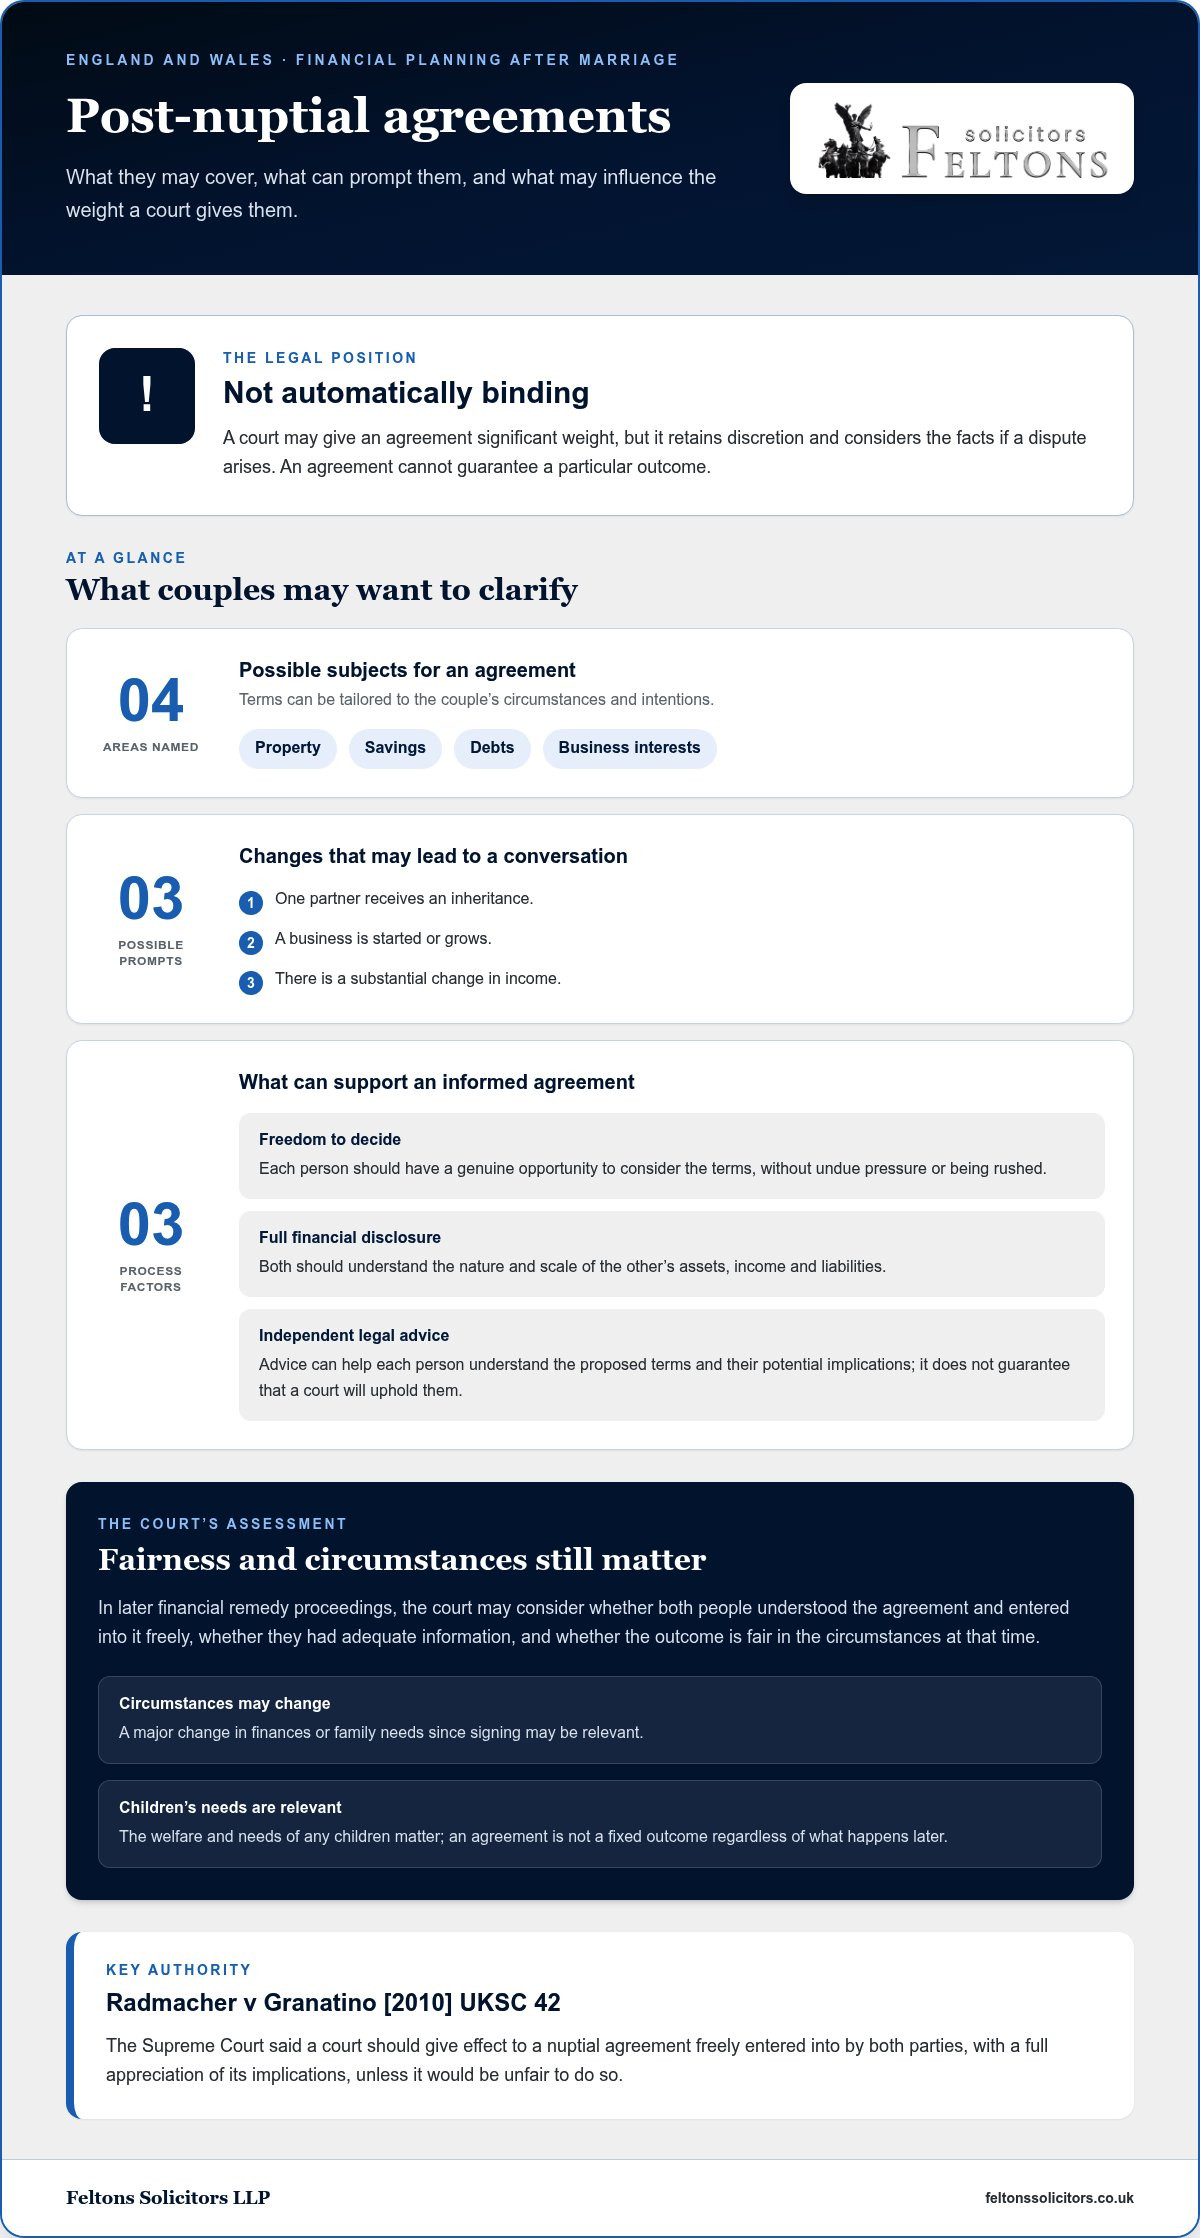
A post-nuptial agreement is a written agreement made after a couple marries or enters a civil partnership. It can set out how they intend to approach their finances if they separate or divorce, including matters such as property, savings, debts or business interests. The Postnuptial agreement overview offers a general introduction, but it isn’t a guide to the law in every jurisdiction. In England and Wales, an agreement can record a couple’s intentions; it can’t guarantee how a court would decide a future financial case.

Post nuptial agreement drafting solicitors can help couples work through their intentions in light of their financial circumstances. Considering an agreement doesn’t mean separation is expected. For some couples, it’s practical planning after a change in circumstances. For others, it creates an opportunity to clarify financial expectations and discuss them openly.

What can prompt a couple to consider an agreement?

A change in finances may lead a couple to revisit arrangements made earlier in their relationship. One partner might receive an inheritance, start or grow a business, or experience a substantial change in income. They may want to record how particular assets or responsibilities should be treated if the relationship later ends.

These are possible reasons to explore an agreement, not a checklist for every couple. Start by identifying what has changed, what each partner wants to clarify and whether both feel able to discuss the subject freely. A focused conversation can help separate shared priorities from assumptions that need further thought.

How is a post-nuptial agreement different from a prenup?

The difference is timing: a prenuptial agreement is made before marriage, while a post-nuptial agreement is made after a marriage or civil partnership has taken place. Either may form part of financial planning, but neither guarantees a particular outcome if the couple separates or divorces.

In both cases, the terms should reflect the couple’s actual circumstances and agreed intentions, rather than generic assumptions. For broader context on the financial issues that can arise if a relationship ends, read this guidance on divorce and financial arrangements.

Family law differs across the UK, so this guide focuses on England and Wales. If your circumstances involve another part of the UK, the applicable law may differ. A solicitor can explain the relevant context and how an agreement may fit into your wider financial planning.

Can a post-nuptial agreement be upheld in England and Wales?

A post-nuptial agreement isn’t automatically legally binding in England and Wales. However, a court may give it significant weight when deciding financial remedy proceedings. The key authority is Radmacher v Granatino [2010] UKSC 42. The Supreme Court said a court should give effect to a nuptial agreement freely entered into by both parties, with a full appreciation of its implications, unless it would be unfair to do so. The Law Commission report on nuptial agreements provides further context on their legal status.

This principle doesn’t promise that a particular agreement or term will be upheld. A court retains discretion and considers the facts when a dispute arises, including whether the agreement was fair at that time and whether circumstances have changed. The needs and welfare of any children are also relevant, so an agreement can’t be treated as a fixed outcome regardless of what happens later.

What factors may influence the weight given to an agreement?

The circumstances in which the agreement was made can matter as much as its wording. Each person should have a genuine opportunity to consider the terms, without undue pressure or being rushed into signing. Full and frank financial disclosure helps both parties understand what they are agreeing to, including the nature and scale of each other’s assets, income and liabilities.

Independent legal advice is an important safeguard. It helps each person understand the proposed terms and their potential implications, but it doesn’t guarantee that a court will uphold the agreement. Post nuptial agreement drafting solicitors can help clarify the issues, record the parties’ intentions and identify points that need careful consideration. The aim is an informed process, not a guaranteed legal result.

Why can’t a solicitor promise a particular result?

If financial remedy proceedings later arise, the court makes its own assessment. It may consider whether each person understood the agreement, entered into it freely and had adequate information, alongside whether the outcome is fair in the circumstances at that time. A major change in finances or family needs since signing may also be relevant.

Careful drafting can support clarity and informed decision-making, but it doesn’t make an agreement automatically binding or remove the court’s discretion. For tailored guidance on how an agreement fits your financial circumstances, explore family law advice on financial arrangements.

Solicitor-drafted agreement or template: what is the difference?

A generic template can provide a starting structure, but it can’t account for how your finances are arranged or what you intend each clause to achieve. Advice-led drafting starts with your circumstances and priorities, then shapes the wording around them. Neither approach guarantees how a court would treat an agreement, and not every couple needs the same provisions.

Consideration Generic template Advice-led drafting
Fit Uses standard wording that may not reflect particular assets, ownership or family circumstances. Considers the couple’s circumstances and identifies where specific terms or further discussion may be needed.
Financial information May provide limited prompts, leaving assumptions about assets, income or liabilities unstated. Uses the financial picture to inform the terms and highlight areas requiring clarity.
Review May not explain how to assess whether the wording reflects both parties’ intentions. Allows the draft to be considered in context, with each person’s position and questions addressed.

Where can a generic template fall short?

Broad wording can blur important differences. For example, a clause referring to “property” may not distinguish a jointly owned home from a property owned by one person, or explain how a mortgage or other liability should be considered. A template may also leave assumptions about a business, shares, inherited assets or changing family circumstances unstated.

This doesn’t mean every template is invalid or unsuitable. The risk is relying on standard language without checking whether it accurately describes the couple’s finances and intentions. If key context is missing, the document may leave room for different interpretations.

What does tailored legal advice add?

Advice can help each person identify their priorities, understand the proposed terms and raise questions before the wording is settled. Since each partner’s circumstances and interests may differ, both should have the opportunity to consider the agreement from their own perspective and receive separate advice. Post nuptial agreement drafting solicitors can help translate agreed intentions into clearer terms and draw attention to unresolved issues rather than obscuring them with general wording.

Inheritance planning may also connect with decisions about how assets are treated in an agreement. For related considerations, see this estate planning guidance. The Law Commission’s report on nuptial agreements provides further background on the legal context. A tailored document isn’t a promise of a particular court outcome; its value lies in recording considered intentions clearly.

Post-Nuptial Agreement Drafting Solicitors: 2026 Guide

What information should you prepare before drafting a post-nuptial agreement?

Good preparation helps turn broad intentions into terms that reflect your finances and priorities. You don’t need to decide every detail alone before seeking advice. Start by gathering a clear picture of your circumstances and noting where you and your spouse agree or need a fuller discussion.

Which financial details and documents may be relevant?

The information needed depends on your circumstances. Records might include property details, bank and investment statements, income information, pension records, details of debts and documents relating to a business or its ownership. Where relevant, note whether an asset is jointly or individually owned and how it was acquired. The aim is an accurate overview, not a standard paperwork list for every couple.

A practical preparation sequence can help:

  1. Set out your objectives. Note what you want the agreement to clarify and which questions remain open.
  2. Gather financial information. List assets, income, pensions, liabilities and business interests, with supporting records where available.
  3. Explain ownership and context. Record how significant assets are held and, where relevant, the source of funds used to acquire them.
  4. Consider day-to-day and future needs. Think about housing, ongoing financial responsibilities and possible changes, such as a new business venture or inheritance.
  5. Review the proposed terms. Read the draft carefully, raise uncertainties and take advice before deciding whether to sign.

How should couples approach terms and future review?

Each person can consider their own priorities and practical needs before discussing how to address them together. For example, think through how housing costs would be managed or what should happen if one partner’s income changes. Listing agreed points separately from unresolved questions can make a sensitive conversation more focused.

You may also wish to discuss whether the agreement should be reviewed after a particular life change or at an agreed point in the future. A review clause can prompt the couple to revisit the terms, but it won’t update them automatically. Any change needs to be considered and properly recorded, with advice tailored to the circumstances at that time.

Post nuptial agreement drafting solicitors can help organise the information, explain issues in plain English and tailor advice and drafting to your circumstances. To discuss your financial arrangements, speak with Feltons about your financial arrangements.

Post-Nuptial Agreements: Instruction to Final Document

A clear, measured process gives both people space to explain their priorities, understand the financial picture and consider the wording before deciding whether to sign. The steps depend on the couple’s circumstances, but the process commonly moves from setting objectives and sharing financial information to advice, drafting, review and completion.

  1. Set out your objectives. Identify what you hope to clarify and which issues need discussion.
  2. Share financial information. Bring together relevant details of assets, income, pensions, liabilities and other interests.
  3. Consider advice. Each person should have the opportunity to understand the proposed terms and their potential implications.
  4. Prepare and review a draft. Instructions and financial information inform the wording. Both parties should read it carefully and raise questions where needed.
  5. Complete the agreement. Before signing, check the final terms and the applicable execution formalities in light of current law and your circumstances.

What happens during the drafting and review stages?

The first draft should reflect the objectives discussed and the financial context provided. During review, check that the language says what you intend, that relevant issues haven’t been overlooked and that unclear or disputed points are addressed. Take time to ask questions. Each person should understand the proposed terms and obtain appropriate advice before completion.

Discussions about money can feel personal. Clear, sensitive communication and appropriate privacy can help keep the focus on practical decisions rather than assumptions about the relationship. Post nuptial agreement drafting solicitors can explain the issues in plain English and tailor advice to the couple’s circumstances, while keeping expectations realistic about the agreement’s potential legal effect.

When should you seek advice about a post-nuptial agreement?

Start early enough to gather financial information, consider the terms and allow each person to obtain independent guidance. A rushed process or pressure to sign can leave one or both parties without a proper opportunity to reflect, undermining confidence in the agreement and how it was reached. If a point remains unresolved, address it before signing rather than treating completion as a formality.

For advice shaped around your objectives and financial circumstances, speak to Feltons about post-nuptial agreement drafting. A solicitor can help you understand the process and prepare carefully, without promising how a court would decide a future dispute.

Take a considered next step with your financial plans

A post-nuptial agreement can set out shared intentions after a change in circumstances, but it can’t guarantee a particular court outcome. Its potential value depends on careful preparation, clear financial information and terms that reflect both parties’ circumstances. Taking time to understand the process and review the draft can help you approach sensitive decisions thoughtfully.

Post nuptial agreement drafting solicitors can help you consider your objectives and the practical issues an agreement may need to address. Feltons advises on divorce and financial arrangements, with pragmatic advice tailored to individual needs. The firm can help you explore your options and take a measured approach.

Discuss post-nuptial agreement drafting with Feltons and take an informed first step towards greater financial clarity.

Frequently Asked Questions

Are post-nuptial agreements legally binding in England and Wales?

No, post-nuptial agreements aren’t automatically legally binding in England and Wales. A court may give an agreement significant weight, particularly where both people entered into it freely, understood its implications and made full financial disclosure. The court retains discretion and may consider fairness, later changes in circumstances and the needs of any children. Careful drafting and independent legal advice can support the process, but neither guarantees that every term will be upheld.

Do both spouses need separate solicitors for a post-nuptial agreement?

Each spouse should have the opportunity to obtain independent legal advice so they can understand the proposed terms and consider their own interests. The same solicitor can’t advise both people on their individual positions. Separate advice can help identify concerns and support informed, voluntary decisions. Post nuptial agreement drafting solicitors can guide each client through the implications of the terms, but independent advice can’t guarantee a particular court outcome.

What should a post-nuptial agreement include?

An agreement may set out how a couple intends to deal with relevant finances if they separate or divorce. Depending on their circumstances, this could include property, savings, pensions, income, debts, business interests and inheritance. It should reflect the couple’s objectives and the financial information available, rather than rely on standard terms that may not fit. Advice can help clarify ownership, responsibilities and points that need further discussion before signing.

Can a post-nuptial agreement protect an inheritance or business?

An agreement can record how a couple intends an inheritance or business interest to be treated if they separate, but it can’t guarantee that a court will follow that intention. The details matter, including ownership, financial disclosure, each person’s needs and later changes in circumstances. For example, a business may change in value or provide income relied on by the family. Tailored advice can help address these factors clearly without promising a legal result.

Can we make a post-nuptial agreement without a solicitor?

You can prepare an agreement without a solicitor, but a generic document may not reflect your finances or make your intentions clear. Independent legal advice can help each person understand the terms, while careful drafting can identify assumptions or unresolved issues. Full financial disclosure and voluntary decision-making are also important considerations. Solicitor involvement may strengthen the preparation, but it doesn’t make an agreement automatically binding or guarantee how a court will treat it.

Can a post-nuptial agreement be changed after it is signed?

Yes, you and your spouse can agree to change the terms, but don’t assume a verbal conversation or informal note updates the agreement. Any variation should be properly documented and considered in light of your current financial circumstances and applicable legal requirements. Independent advice can help each person understand the proposed changes. If circumstances shift, such as a change in income or family responsibilities, review the agreement rather than relying on outdated terms.

Does a post-nuptial agreement cover arrangements for children?

A post-nuptial agreement can record the parents’ intentions about family finances, but it can’t conclusively decide future arrangements for children or bind a court on those matters. If parents separate, decisions concerning a child are assessed in light of the child’s welfare and circumstances at that time. The agreement may include relevant financial intentions, but a court’s consideration of children’s needs remains important. Take advice before including provisions that affect children or family support.

Freezing Orders in Divorce: Protecting Assets in 2026

Freezing Orders in Divorce: Protecting Assets in 2026

Could a court order stop your spouse from moving or selling assets before your financial arrangements are settled, and when is urgent action justified? It’s understandable to want to protect what may form part of a future settlement, particularly if you’re worried that money or property could disappear. A search for “freezing injunctions divorce property assets” often starts with that concern. However, a freezing injunction is an exceptional safeguard for a specific risk of assets being dissipated, not a shortcut to securing a divorce settlement.

This guide explains what a freezing injunction may protect, what it can’t do, and the evidence and legal considerations a court may weigh. It also explains why urgency, proportionality and the possible consequences of an unsuccessful application matter when deciding what to do next. The rules and procedures differ across the UK, so the relevant legal route depends on where your case is being heard. Advice on divorce and financial arrangements can help you assess the facts and consider practical options without escalating matters unnecessarily.

Key Takeaways

  • A freezing injunction may restrict dealings with specified assets to preserve them, but it doesn’t decide ownership or determine the final financial settlement.
  • Concern alone may not be enough. The court considers the particular facts and evidence, including warning signs of possible asset dissipation.
  • Freezing injunctions, disclosure, negotiation and agreed undertakings serve different purposes. The right approach depends on what you need to achieve.
  • Prepare for legal advice by organising relevant records and setting out a clear timeline. Applications without notice carry demanding duties of candour.
  • Where assets may be at risk, consider prompt, tailored advice and weigh whether an urgent protective step or broader financial arrangements advice is the priority.

What is a freezing injunction in divorce, and which assets might it affect?

A freezing injunction is a court order that restricts specified dealings with assets, subject to the wording and limits of the order. In a divorce, its purpose is preservation: it may help prevent assets being moved or dealt with in a way that could undermine the financial process. It doesn’t decide who owns an asset or award either spouse a final financial settlement. For a general overview of the purpose of a freezing order, see this background explanation.

The order does not automatically freeze everything a spouse owns or controls. Its reach depends on the terms made by the court, the assets identified and the legal route available in the relevant jurisdiction. The phrase “freezing injunctions divorce property assets” can describe different concerns, each of which needs careful assessment. There is no standard order that applies in every case.

What does a freezing injunction actually prevent?

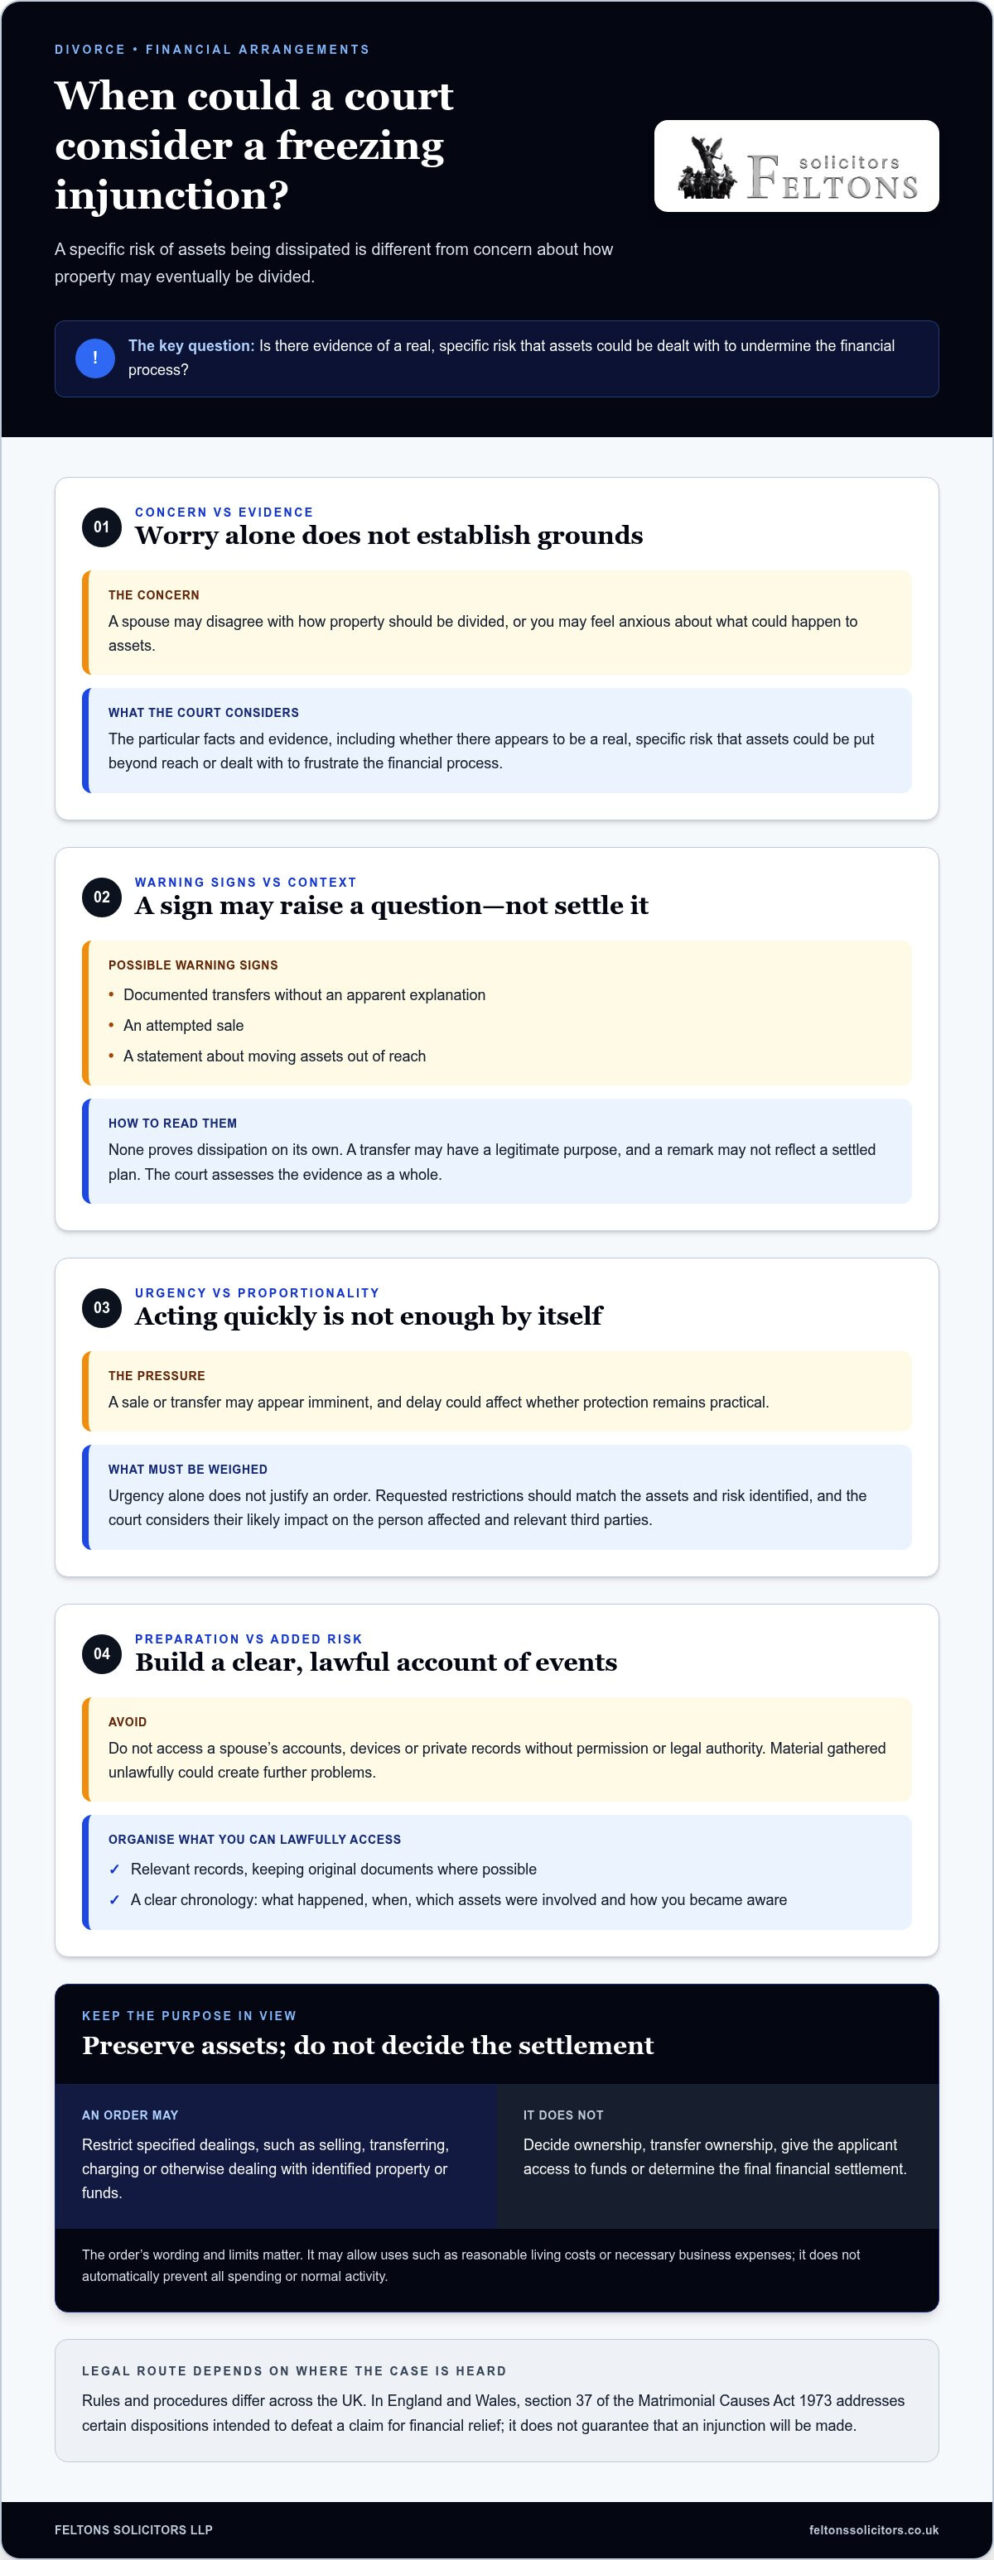
Restrictions are tailored to the order. They may prohibit selling, transferring, charging or otherwise dealing with specified property or funds. The order may also set out permitted uses, such as reasonable living costs or necessary business expenses, so preservation does not automatically prevent all spending or normal activity. Check the exact wording: an asset or transaction not covered by the order may fall outside its restrictions.

A disagreement about who should ultimately receive a home or investment is not, by itself, the same as a risk that assets will be dissipated. The question is whether there is a sufficiently evidenced risk that assets may be put beyond reach or dealt with to frustrate the financial process. Disputes over fairness or ownership are generally addressed through the wider financial arrangements, not by treating a freezing order as a shortcut to deciding the outcome.

Which property and financial assets could be relevant?

Depending on the circumstances, relevant assets might include a family home, an investment property, money in bank accounts or an interest in a business. The court’s ability to make an effective order can depend on who legally owns or controls an asset, where it is located, and whether another person or organisation has rights in it. An asset held jointly or involving a third party may raise different issues from one controlled solely by a spouse.

A freezing injunction doesn’t transfer ownership, give the applicant access to funds or determine how property will be divided. It is a protective measure, not a final resolution. Advice on divorce and financial arrangements can help assess the evidence, the assets at issue and whether an injunction is a proportionate option in the circumstances.

When might a divorce court consider freezing property or other assets?

A freezing injunction isn’t a routine feature of divorce, and anxiety about what a spouse might do does not, by itself, establish grounds for one. The court considers the particular facts and evidence, including whether there appears to be a real, specific risk that assets could be dealt with to undermine a financial claim. The relevant legal framework and procedure depend on where proceedings are taking place. In England and Wales, Section 37 of the Matrimonial Causes Act 1973 addresses certain dispositions intended to defeat a claim for financial relief. It does not guarantee that an injunction will be made.

A specific risk of assets being dissipated is different from the ordinary concern that a spouse may disagree with how property should eventually be divided. The latter is part of resolving financial arrangements. An injunction is an exceptional protective measure, not a way to gain leverage or secure a preferred share of the assets.

What evidence could support concern about asset dissipation?

Relevant warning signs might include documented transfers without an apparent explanation, an attempted sale, or a statement about moving assets out of reach. None proves dissipation on its own. Context matters: a transfer could have a legitimate purpose, and a remark may not reflect a settled plan. The court assesses the evidence as a whole rather than treating any one sign as automatic entitlement to an order.

To prepare for a legal assessment, organise records you can lawfully access and set out a clear chronology: what happened, when, which assets were involved and how you became aware of it. Keep original documents where possible. Don’t access your spouse’s accounts, devices or private records without permission or legal authority. Material gathered unlawfully could create further problems.

How do urgency and proportionality shape the decision?

Timing may matter if, for example, a sale or transfer appears imminent. A delay could affect whether protection remains practical, but urgency alone doesn’t establish that an order is justified. The restrictions requested should relate to the assets and risk identified, rather than going further than the circumstances warrant.

The court considers the evidence and the likely impact of restrictions on the person affected, as well as relevant interests of third parties. The limits of an order may matter if it could disrupt ordinary financial commitments or business activity. A focused review of the evidence and wider financial arrangements can help identify proportionate options. If you’re concerned about a specific transaction, read about divorce and financial arrangements advice.

Freezing injunctions versus other ways to protect divorce assets

A freezing injunction is one possible protective step, but it serves a different purpose from identifying assets or reaching agreement on how they should be divided. The right route depends on the facts, the level of urgency, the available evidence and the practical effect of the proposed step. An overview of freezing injunctions explains the remedy’s general scope, but individual circumstances need careful assessment.

Approach Main purpose Practical distinction
Freezing injunction Restrict specified dealings with assets where urgent protection may be justified. A court order with terms and effects shaped by the circumstances.
Financial disclosure Build a clearer picture of assets, liabilities and relevant transactions. Provides information; it doesn’t itself prevent someone dealing with an asset.
Negotiation Explore agreed arrangements for assets and financial needs. Depends on meaningful engagement and agreement between the parties.
Undertaking Record a formal promise to act, or not act, in a specified way. It is a promise, not the same thing as a court-imposed freeze.

When might disclosure or an undertaking be considered instead?

Financial disclosure can help establish which property, accounts, business interests, liabilities and transactions need to be considered. It may clarify an incomplete picture and support informed discussions, but it isn’t an asset-freezing measure. For more on that process, read about financial disclosure in divorce.

Where appropriate, an undertaking may provide a formal commitment about particular conduct. Its suitability depends on the circumstances and the wording proposed. Neither disclosure nor an undertaking should be treated as a substitute for urgent legal assessment if there is evidence that an asset may soon be transferred or sold. Equally, a suspected risk does not automatically mean an injunction is the right response.

How does an injunction fit into financial arrangements?

Interim protection and the final financial settlement do different jobs. An injunction may address a specific risk while proceedings continue; the broader process considers the parties’ overall financial position and how arrangements should be resolved. It doesn’t determine the final division or guarantee a particular settlement. The phrase freezing injunctions divorce property assets therefore describes only one part of a wider financial picture.

Consider the wider divorce and financial arrangements process alongside any immediate asset concern. A considered approach weighs the evidence and practical impact of each option rather than treating a court application as the default response.

Freezing Orders in Divorce: Protecting Assets in 2026

How to prepare for advice about a freezing injunction

A clear, organised account of your concern helps a solicitor assess whether urgent protection may be appropriate. Identify the action you fear, gather records you can lawfully access, set out key events in date order, and then obtain legal advice. Freezing injunctions divorce property assets is a complex issue, so distinguish what you know from what you suspect rather than presenting concerns as established facts.

What information should you organise before taking advice?

Bring together information that may help identify the asset, the risk and its timing. This could include:

  • Details of the property, accounts, business interests or other assets involved, including known ownership or control.
  • Relevant transaction records, correspondence, sale particulars or other documents you can lawfully access.
  • A chronology of key dates, such as when you learned of a proposed transfer or sale and any stated deadline.
  • A short explanation of the specific action you fear and why you believe it may happen soon.

Label first-hand evidence separately from assumptions or information relayed by someone else. This helps keep the legal assessment accurate and balanced.

What risks and responsibilities should an applicant understand?

An application made without notice to the other party may be considered where giving notice could undermine its purpose. It carries demanding duties of candour: the applicant must give the court a fair and complete account, including relevant points that may weigh against the order. In an urgent application, balanced disclosure matters because the court may initially hear only one party’s account. The applicable procedure and current requirements should be assessed for the court and jurisdiction involved.

Inaccurate or incomplete evidence can seriously affect the application and may have consequences for the applicant. Depending on the circumstances, the court may require a cross-undertaking in damages, a promise to compensate for losses if the order is later found to have been wrongly made. An unsuccessful application may also carry costs consequences. Neither result is automatic, but both should be considered before proceeding.

The wording of an order determines what is restricted and which exceptions apply. Read and follow it carefully: assumptions about what is permitted can create further difficulty. A tailored assessment of the evidence, urgency and possible impact can help you understand the available options. For background, see advice on divorce asset protection.

Choosing the next step when divorce property assets may be at risk

The right response depends on what appears to be happening, how soon it may happen and what the available evidence shows. If a sale or transfer seems imminent, prompt legal assessment can help establish whether urgent protection should be considered and what other options may be proportionate. If there’s no specific sign of assets being moved or dissipated, broader advice on disclosure and the overall financial arrangements may be the more useful priority.

Freezing injunctions divorce property assets concerns are fact-sensitive. An injunction may restrict dealings with specified assets, but it doesn’t decide ownership or guarantee a particular final settlement. The applicable procedure also depends on where the case is being heard, as the law and court processes differ across the UK. Advice should be specific to the relevant jurisdiction.

What should you do if a sale or transfer seems imminent?

Set out the facts as clearly as you can and seek a prompt legal assessment. Record relevant communications and events with their dates, keep copies of documents you can lawfully access, and note any known deadline or proposed transaction. A concise chronology can help distinguish a concrete, time-sensitive concern from uncertainty or assumption.

Avoid confronting your spouse in a way that could intensify the dispute or taking matters into your own hands, such as attempting to access private accounts or interfere with a transaction. Those steps may create further problems without providing reliable protection. Legal advice can help assess the evidence and available options calmly.

How can legal advice put the asset concern in context?

A solicitor can consider the specific concern alongside available disclosure, ownership information and the wider financial arrangements. This helps place any urgent risk within the full picture, rather than treating an injunction as the answer to every disagreement about property. For related guidance, read Protecting Your Assets During a Divorce Settlement.

Feltons Solicitors LLP advises on divorce and financial arrangements, including assessing the facts, evidence and proportionate options where assets may be at risk. A focused discussion can help clarify whether the priority is urgent protective advice, a fuller understanding of the finances, or both.

Discuss your divorce and financial arrangements

Take a considered next step to protect your financial position

A freezing injunction may help address a specific, evidenced risk, but it isn’t a routine part of divorce or a guarantee of a particular settlement. The right response depends on the facts, timing and impact of any proposed restrictions. Organising relevant records and getting advice can help clarify whether urgent protection or broader financial arrangements should take priority.

Concerns about freezing injunctions divorce property assets are best considered in the context of the full financial picture. Feltons Solicitors LLP advises on divorce and financial arrangements and handles complex litigation and dispute resolution, with attention to the evidence and proportionate options available.

If you’re concerned about assets or need to understand your next steps, discuss your divorce and financial arrangements. A clear, informed approach can help you move forward with greater confidence.

Frequently Asked Questions

Can I get a freezing injunction against my spouse during divorce?

Possibly, but a court order isn’t automatic just because you’re divorcing or worried about your spouse’s plans. The court considers the evidence, the specific risk to assets and whether the proposed restrictions are appropriate. The legal route depends on where proceedings are taking place, as the rules differ across the UK. Tailored legal advice can help assess the facts and whether an injunction or another step merits consideration.

What evidence is needed for a freezing injunction in divorce?

There’s no single checklist that guarantees an order. Relevant material may include records of transfers, evidence of an attempted sale, or communications suggesting assets may be moved, considered in their full context. Organise documents you can lawfully access and make a dated chronology, separating what you witnessed from assumptions or information received from others. For searches such as “freezing injunctions divorce property assets”, the key point is that evidence must support the specific concern.

Can a freezing injunction stop my spouse selling the family home?

It may restrict a sale if the order specifically covers the home and the court considers that protection appropriate. The order’s wording determines which dealings are restricted, and ownership, other parties’ rights and the relevant legal process may affect the position. It doesn’t automatically apply to every property or give you control of the home. If a sale appears imminent, organise the relevant records promptly and seek legal advice about the evidence and options.

Does a freezing injunction mean I will receive the frozen assets?

No. A freezing injunction is intended to preserve specified assets, not transfer them to the applicant or decide who owns them. It doesn’t determine the final financial settlement or guarantee that you’ll receive any particular asset or share. Those questions are addressed through the wider divorce financial arrangements process. The order’s precise terms matter, and a court may set out permitted dealings or exceptions, so don’t assume that frozen funds are available for your use.

How quickly can a court make a freezing injunction?

There’s no fixed timeframe that applies in every case. Timing can depend on the urgency, the evidence, the court’s procedures and whether the application is made with or without notice to the other party. An application without notice may carry demanding duties to give the court a fair and complete account. If a transaction seems imminent, organise the key dates and records and seek prompt legal advice. The applicable procedure varies across the UK.

What happens if someone breaches a freezing injunction?

A breach can have serious consequences, but the response depends on the order’s wording and the circumstances. A court may be asked to address non-compliance, and breach of an injunction can raise contempt of court issues. Keep a dated record of what you believe happened and preserve relevant information you can lawfully access. Don’t try to enforce the order yourself or assume conduct is a breach without checking the terms and obtaining legal advice.

Is a freezing injunction the same as a financial settlement order?

No. A freezing injunction is a protective measure that may restrict dealings with specified assets while the case continues. A financial settlement order deals with how financial arrangements are resolved, rather than simply preserving assets. One doesn’t automatically produce the other: a freezing order doesn’t decide the final division, and a settlement addresses the wider financial picture. The appropriate legal process depends on the facts and jurisdiction, so consider urgent asset concerns alongside broader divorce advice.