Unregistered Land Conveyancing: Selling and Registration Explained

Unregistered Land Conveyancing: Selling and Registration Explained

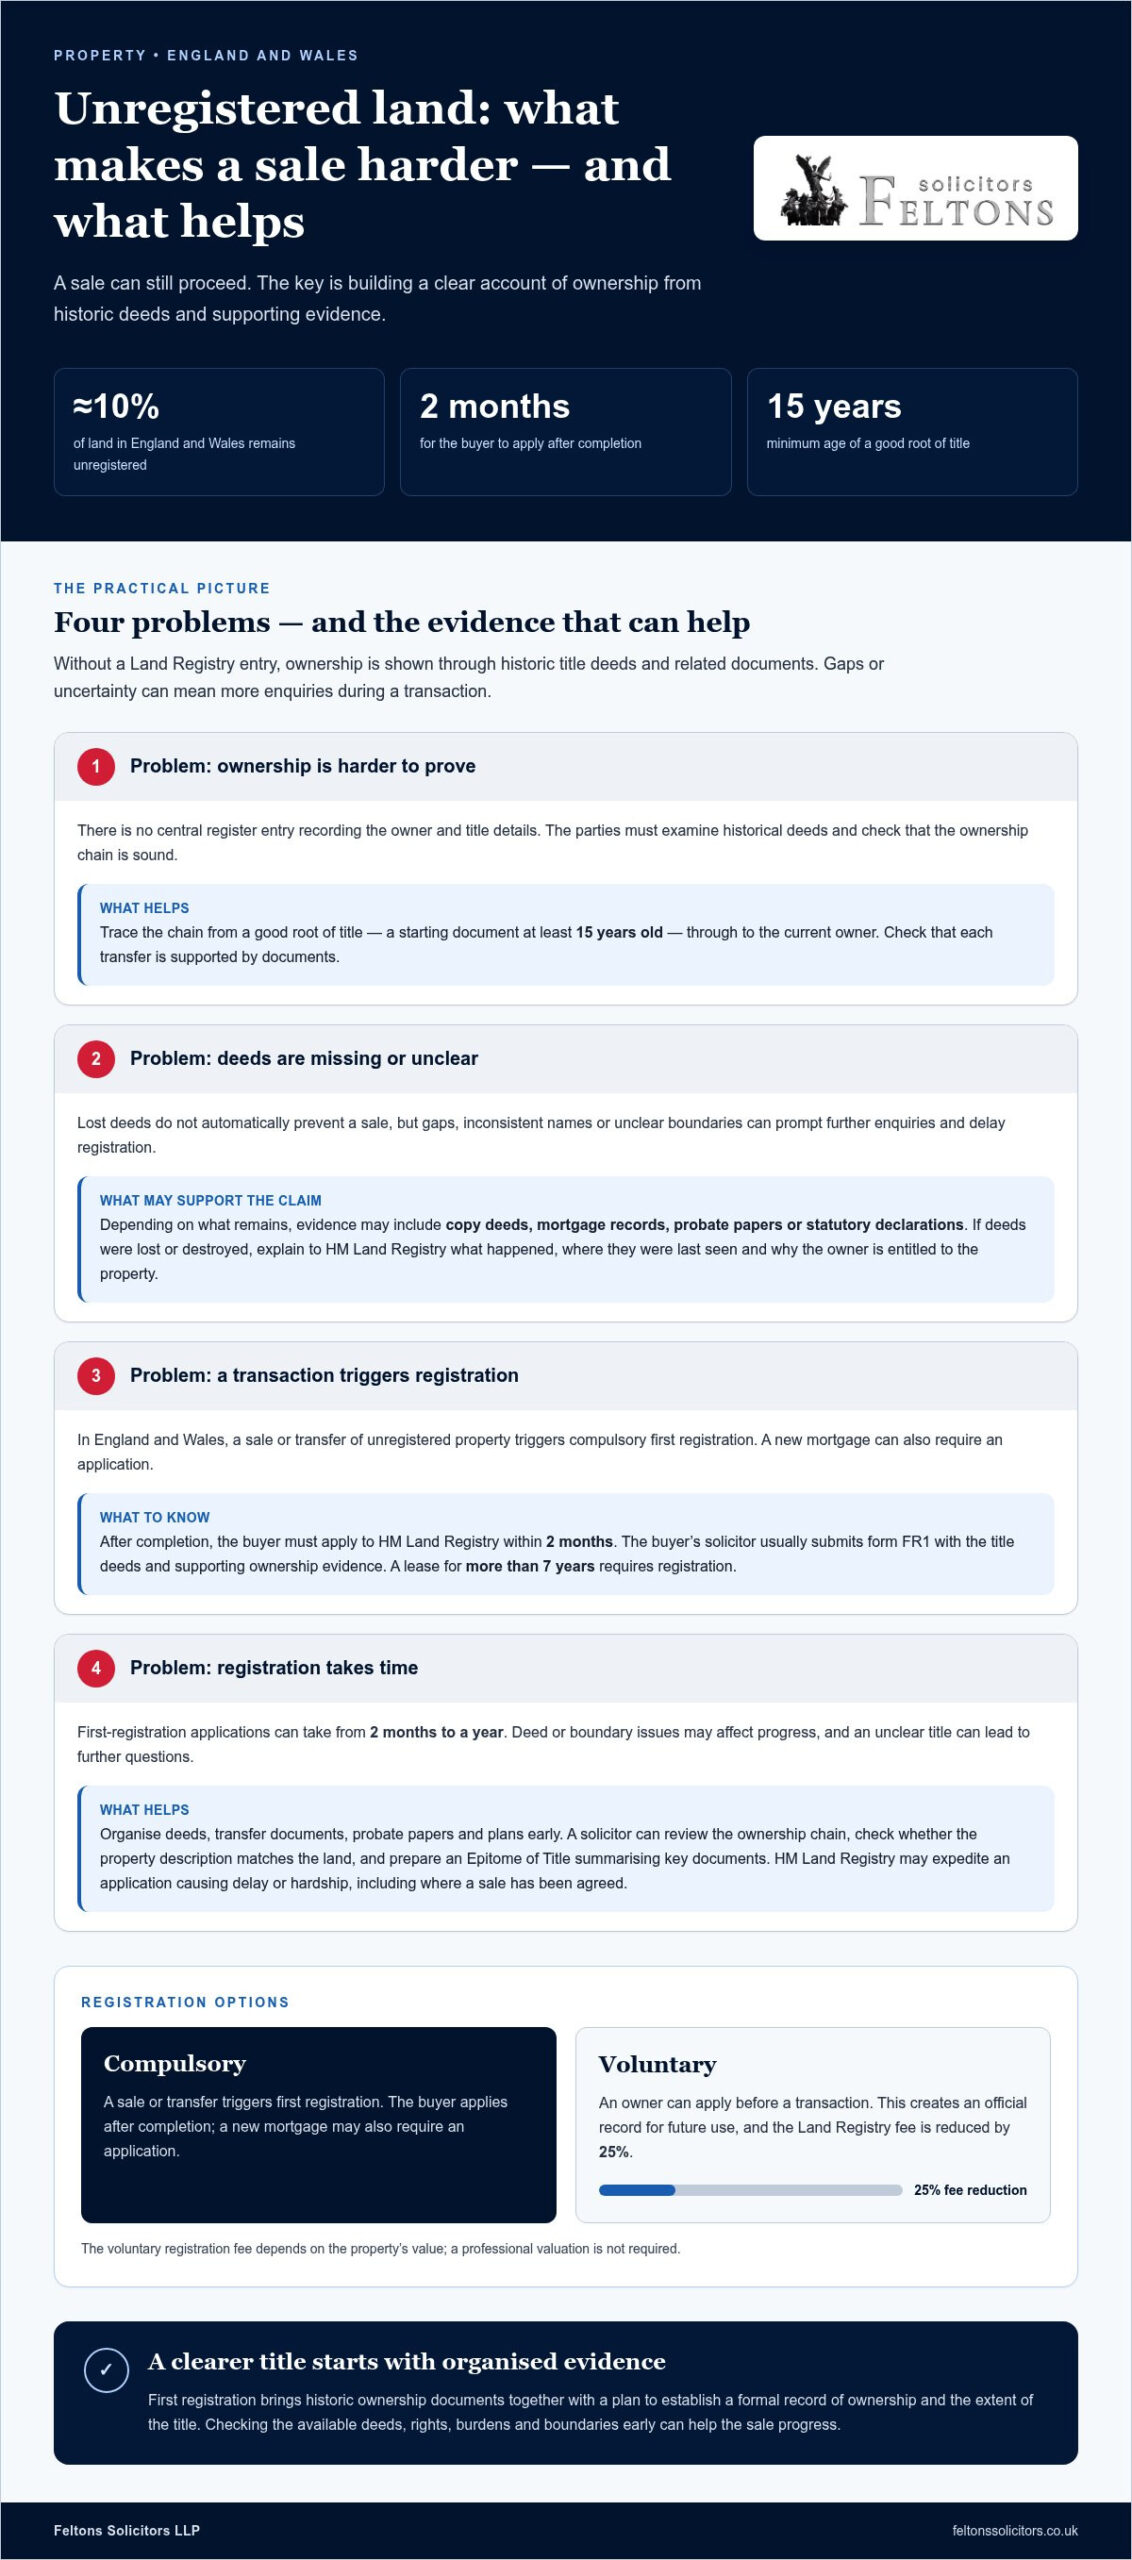
Approximately 10% of land in England and Wales remains unregistered, but a sale or transfer triggers compulsory first registration. After completion, the buyer must apply to HM Land Registry within two months. Unregistered land conveyancing solicitors assess the title deeds and ownership history that support the application.

It’s understandable to wonder whether an unregistered title makes a property harder to sell, or whether registration can wait. The answer depends on whether a sale, transfer or other registrable event has triggered the requirement, and on the evidence available to establish ownership.

This article explains when first registration is compulsory, the practical risks of leaving a title unregistered and how a sale can proceed. It also covers why some land remains unregistered, what to do when deeds are missing and how first registration turns historic ownership documents into a registered title.

Key Takeaways

  • A sale or other registrable transaction can trigger first registration; after buying unregistered property, the buyer must apply within two months of completion.
  • Historic deeds and ownership records help establish the chain of title, so organising the available documents can support a smoother sale.
  • An unregistered property can still be sold, but missing or unclear title evidence may complicate the transaction and delay registration.
  • Some land remains unregistered because no transaction requiring registration has occurred; voluntary registration can help make ownership easier to evidence in future.
  • First registration brings the property onto the register for the first time, creating a formal record of ownership and the extent of the title.

Is it compulsory to register land?

In England and Wales, registration becomes compulsory when unregistered property is sold or transferred. The buyer generally applies for first registration after completion, although an owner can register voluntarily before a transaction.

The Land Registration Act 1925 introduced compulsory registration, initially for specified transactions, including the grant of a new lease of 21 years or more, according to UK legislation. Today, a sale or transfer of unregistered property triggers registration, and a new mortgage can also require an application. HM Land Registry says granting a lease for more than seven years requires registration.

Checking the Registration Status

To check registration status, find out whether HM Land Registry holds an official record for the property. This matters before a sale, transfer or mortgage because the title information determines which documents and registration steps are needed. Anyone can request an official copy of the register for registered land. Check the registered owner, property details, rights and restrictions rather than relying only on old deeds.

First Registration Applications

First registration is the process of creating a Land Registry record for a property that has never been registered. After a purchase, the buyer’s solicitor submits the application, usually using form FR1, with the title deeds and supporting ownership evidence. The application brings earlier conveyances and dealings together with a plan to establish the registered title. A clear, complete application helps address questions about the property boundaries, ownership and rights.

An owner can also apply voluntarily when no transaction has triggered compulsory registration. This can establish an official record before a future sale or mortgage, giving the parties a registered title to work from. A reduced fee applies to voluntary first registration, with the Land Registry fee reduced by 25 per cent. The fee depends on the property’s value, and a professional valuation is not required.

Timing matters if a transaction is under way. The buyer must apply within two months of completion after purchasing unregistered land. First-registration applications can take from 2 months to a year, so unresolved deed or boundary issues may affect progress. HM Land Registry may expedite an application where it is causing delay or hardship, including when a sale has been agreed.

Solicitors’ charges depend on the work involved, such as reviewing historic deeds, resolving title issues and preparing a registration application. The price depends on the case and is given after a quote request.

To find a solicitor experienced in unregistered land conveyancing near you, look for someone who handles first registration, examines historic ownership evidence and can explain the steps for your transaction. A local search for unregistered land conveyancing solicitors can help identify firms offering this specialist conveyancing work.

What are the consequences of not registering an unregistered title?

Without a Land Registry entry, ownership must be established through historical title deeds and related documents. This can make selling, buying or mortgaging more involved, because the parties need to examine the evidence and confirm that the ownership chain is sound. In England and Wales, a good root of title should be at least 15 years old. If that starting document is missing or later transfers are unclear, the investigation may take longer.

The buyer’s solicitor reviews original deeds and conveyances to trace ownership from the good root of title to the current owner. They check that each transfer is supported by documents and that the property described matches the land being sold. The solicitor may also prepare an Epitome of Title, a summary of the ownership chain and the key documents supporting it. Gaps, inconsistent names or unclear boundaries can lead to further enquiries and delays.

Missing deeds don’t automatically prevent a sale, but alternative evidence may be needed to support the ownership claim. Depending on what remains, this could include copy deeds, mortgage records, probate papers or statutory declarations. If deeds have been lost or destroyed, the owner may need to explain to HM Land Registry what happened, where the documents were last seen and why they are entitled to the property. A specialist review can identify gaps before they become obstacles during a transaction.

Leaving a title unregistered means there is no central register entry recording the owner and title details. This can make ownership harder to prove and increase the potential for disputes. It may also complicate a sale or mortgage, as the buyer or lender relies on the deeds and ownership investigation rather than an official register. Registration can help protect an owner’s interests against fraudulent dealings by someone falsely claiming to own the property, and guard against adverse possession claims.

For an unregistered purchase, the solicitor’s investigation does more than collect paperwork. It checks whether the documents form a coherent account of ownership and whether the evidence shows relevant rights or burdens. A land charges search against previous owners can help identify interests affecting the property. If the chain has a gap, the next step is to locate supporting records or assemble other evidence before the application proceeds.

Early document review can reduce avoidable questions once a sale is agreed. Keep deeds, transfer documents, probate papers and plans together, and note any known loss or damage. For support with a property transaction involving historic title documents, residential and commercial conveyancing can provide a relevant next step.

How do I sell an Unregistered Property?

You can sell an unregistered property using its title deeds as evidence of ownership. The seller prepares the deeds and property information, the buyer investigates the title and, after completion, applies for first registration within two months.

Confirming the Seller’s Right to Transfer

To confirm the seller’s right to transfer the property, ownership is traced through the title deeds and supporting documents. The buyer needs evidence that the seller can pass on the title. A conveyancer reviews the chain of transfers, checks names and dates, and identifies gaps that need explanation. The seller’s solicitor can start gathering and organising these documents before a buyer is found, helping to identify issues early.

Property Details, Boundaries and Restrictions

The sale documents must describe the property accurately, including its boundaries and relevant rights or restrictions. Compare the deeds and plans with the land being sold, particularly where the plot includes shared access, a field or an extension. A mismatch can prompt enquiries or complicate the registration application. The buyer’s conveyancer examines the documents to understand which land and rights pass with the transfer.

Conveyancing Timescales

Unregistered title evidence can affect the pace of conveyancing because historic documents need examination before the buyer can be satisfied. First registration can take from 2 months to a year, while creating a new registered title usually takes between 6 and 9 months. These periods concern registration, not the entire sale. Missing deeds, unclear boundaries or incomplete ownership evidence can require further investigation and cause delays.

Steps in an Unregistered Conveyancing Transaction

The transaction usually moves from collecting title deeds, to checking the ownership chain, answering the buyer’s enquiries, completing the sale and applying for first registration. The seller’s solicitor prepares title evidence and can start before marketing. After completion, the buyer’s solicitor submits the application to HM Land Registry, normally using form FR1 with supporting documents. This order matters because the buyer needs evidence to register the transferred title.

Some properties remain unregistered because no sale or other registrable transfer has triggered first registration. Approximately 10% of land in England and Wales remains unregistered. An owner may choose voluntary first registration before selling, but can also proceed with a sale using the deeds. The right approach depends on the available documents, any title concerns and the transaction’s timing.

For practical support with the title investigation and transfer, conveyancing for property transactions can help organise the work involved in an unregistered sale.
Unregistered Land Conveyancing: Selling and Registration Explained

Land that remains unregistered

Land can remain unregistered because no sale or other registrable dealing has triggered first registration. This does not, by itself, mean the owner lacks legal title. In England and Wales, title may still be evidenced by deeds and earlier conveyances. The practical difference is that buyers and lenders must rely on those documents rather than a current Land Registry record.

For an unregistered residential property, the deeds may show how ownership passed between successive owners. A conveyancer examines the documents and checks that the property description, boundaries and ownership chain fit together. This investigation matters before a sale or mortgage because gaps or conflicting details can lead to enquiries, disputes or delays. A straightforward application depends on coherent evidence, not simply the age of the property.

Some registrable dealings make registration compulsory. For example, taking out a mortgage on unregistered commercial property triggers registration as part of the mortgage process. A sale or transfer can also trigger first registration. Owners without an immediate transaction can choose voluntary registration, creating an official record before buyers or lenders need to rely on historic deeds.

Before an application, searches help identify interests that may affect the land. A land charges search should cover previous owners since 1925, and form K15 is used to apply for that search. The search is made against owner names, so accurate details from the title documents matter. An index map search can also help establish whether the land, or part of it, is already recorded on the register.

Where someone occupies land without the owner’s consent and claims it as their own, adverse possession may become relevant. The stated period for a claim involving unregistered land is 12 years. An application may be appropriate where land has been occupied and used as one’s own for the prescribed period, but clear ownership evidence is lacking. Occupation alone does not settle who owns the land; the history and supporting evidence matter.

Leaving land unregistered can make ownership harder to demonstrate and a later sale more document-heavy. Missing deeds may require secondary evidence, such as copy deeds, mortgage records or probate papers. If boundaries are unclear, plans and historical documents can help explain which land the title covers. A solicitor can review the available evidence, arrange relevant searches and prepare an application for first registration where appropriate.

Some owners choose to register before a sale or mortgage, while others wait until a transaction triggers the requirement. The decision depends on the quality of the title evidence, the intended transaction and whether a clear record would assist future buyers. Voluntary first registration can establish the title in advance.

What is unregistered land in England and Wales

Unregistered land is property without a title entry at HM Land Registry. Ownership is evidenced by deeds and documents recording earlier dealings, rather than a current register. The absence of a register entry does not, by itself, mean the land has no owner. It means the title must be understood through its documentary history.

That distinction reflects how registration developed. The Land Registration Act 1925 introduced compulsory registration for specified transactions, and registration became compulsory nationwide for most land transactions in England and Wales in 1990. The Land Registration Act 2002 replaced the 1925 Act. Land that has not undergone a registrable dealing may therefore remain outside the register.

For an unregistered title, conveyancers examine the deeds to establish how ownership passed from one person to another. A conveyance may describe the property, record a transfer and refer to rights affecting access or use. Historical plans can help identify boundaries, while mortgages, probate papers and other documents may explain later changes. Each item contributes evidence, and the chain must make sense as a whole.

Registered ownership works differently. HM Land Registry records the owner and title details, including relevant rights and restrictions, under a unique title number. An official copy of the register can be requested for registered land. For unregistered land, there is no equivalent title entry to inspect, so the buyer’s investigation depends on the documents available and whether they establish a consistent chain.

First registration creates a Land Registry title for land that has never been registered. The application brings together evidence from earlier conveyances and dealings, along with a plan showing the property outline. This turns a documentary history into an official record that can be inspected in future transactions. Registration does not remove the need to understand the property’s boundaries or recorded rights.

Unregistered status can also matter when ownership changes through inheritance. A personal representative dealing with property may need to establish the deceased’s title from the deeds before the transfer can be registered. Keeping property documents with estate records can help make that investigation more manageable. Where property forms part of a wider succession plan, discuss your estate planning needs and how ownership should be documented.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP provides residential and commercial conveyancing for property transactions, including matters involving unregistered titles. If you’re preparing to sell or buy unregistered property, the firm can assess the title documents, trace the ownership chain and manage the conveyancing process. This can be particularly useful where deeds are incomplete, boundaries need clarifying or first registration follows a transfer.

The firm also assists with wills, probate and estate planning where property ownership forms part of a wider family or estate matter. The right support depends on the legal issue: a property sale calls for conveyancing, while questions about distributing property after death may involve estate planning or probate.

Contact Feltons Solicitors LLP to discuss your property matter.

Prepare your next property decision with confidence

Before taking your next step, gather the available deeds, plans and correspondence. A clear set of documents makes it easier to identify what needs attention and raise the right questions about a proposed sale, purchase or registration. Note any missing deeds or boundary descriptions that are difficult to interpret. These details give a conveyancer a practical starting point.

The right unregistered land conveyancing solicitors can explain the work involved in your transaction and how historic title evidence fits into it. Feltons Solicitors LLP handles residential and commercial conveyancing, including property matters that need careful title review. Taking advice before agreeing a transaction can help you plan around the documents and decisions ahead.

If you’re ready to discuss your property matter, contact Feltons Solicitors LLP. A considered next step can make a complex title easier to approach, and help you move forward with greater clarity.

Frequently Asked Questions

Who should register the property?

After buying unregistered property, the buyer is responsible for applying for first registration. The buyer’s conveyancer usually prepares and submits the application as part of the post-completion work. A seller may register voluntarily before a sale, giving the buyer an established title to work from. For example, an owner preparing to market a property can consider registration before finding a buyer.

Should You Consider Voluntary First Registration?

Voluntary first registration may suit an owner who wants to establish a registered title before a sale, transfer or mortgage requires an application. Consider the condition of the deeds, whether the property description is clear and whether a transaction is planned. The Land Registry fee depends on the property’s value, and a professional valuation is not required. The timing can depend on whether the title evidence is ready.

What are the risks of buying and selling unregistered land?

The main risks include difficulty evidencing ownership, extra title enquiries and possible delays if the deeds don’t clearly match the land being transferred. For instance, a deed plan might not show clearly whether a garage or access strip forms part of the property. Buyers may also need to understand rights affecting the land before proceeding. Sellers can reduce uncertainty by gathering relevant deeds and plans early.

What details should be included in the application for first registration?

An application should identify the property’s address and boundaries, the current owner, and relevant rights or restrictions. Form FR1 is used for first registration. Supporting evidence includes the title deeds and documents showing ownership history. Include a scale drawing if the deeds don’t contain a suitable plan. Accurate information helps the application describe the land and title being registered, rather than leaving key details unclear.

When is first registration of unregistered land compulsory?

In England and Wales, a purchase or transfer of unregistered property triggers compulsory first registration. A new mortgage on unregistered property can also trigger it. Certain other dealings matter too: gifts of land and assents by personal representatives require a change of ownership to be registered, and granting a lease for more than seven years requires registration. Following a purchase, the buyer must apply within two months of completion.

What documents are needed to convey unregistered land?

Gather the original title deeds, earlier conveyances and transfer documents that evidence the ownership chain. Plans help identify the land, while probate papers may explain how an owner inherited it. The conveyancer can prepare an Epitome of Title summarising the relevant ownership documents. Searches can also form part of the investigation, including land charges and an index map search. If original deeds are missing, secondary evidence may help support the title.

How long does unregistered land conveyancing take compared with registered land?

Unregistered transactions can take longer because the conveyancer must investigate historical deeds and establish the ownership chain. First registration may take from 2 months to a year, and creating a new registered title usually takes between 6 and 9 months. These are registration timeframes, not a guaranteed completion date for the sale. The work required depends on the title evidence, searches and any questions raised about the property.

How do solicitors investigate title to unregistered land?

Solicitors examine the deeds to trace ownership from a good root of title to the current owner. In England and Wales, a good root should be at least 15 years old. They compare names, dates, property descriptions and plans, then investigate gaps using supporting material such as probate records or copy deeds. Searches against previous owners can identify land charges, while an index map search helps check the land’s registration position.
Cohabitation Property Dispute Lawyers UK: Your Rights and Next Steps in 2026

Cohabitation Property Dispute Lawyers UK: Your Rights and Next Steps in 2026

What if the property is registered in your former partner’s name, but you paid towards the deposit, mortgage or renovations? The title deeds matter, but they may not tell the whole story. Cohabitation property dispute lawyers UK can help you assess the ownership evidence and understand the options available.

If you’re unsure whether bank transfers, messages or an informal understanding support your position, you’re not alone. Unmarried partners don’t acquire the same rights as married couples simply by living together, and there is no “common law marriage” in England and Wales. A dispute is usually assessed under property and trust law, where the details of your contributions and any agreements may matter.

This guide explains the legal rules that may apply, the documents and other evidence to gather, and how a solicitor can help you consider negotiation, settlement or a court decision. It also covers the 2026 reform consultation. As of October 2026, the law has not changed, so understanding your position under the current rules remains essential.

Key Takeaways

  • Separate legal ownership shown on the title from any claimed beneficial interest, then identify exactly what is in dispute.
  • Gather title records, bank statements and messages. Distinguish evidence of payments from evidence of what both partners intended.
  • Consider negotiation or mediation as possible ways to resolve the disagreement before deciding whether formal proceedings are appropriate.
  • Cohabitation property dispute lawyers UK can assess the ownership evidence, potential claims and practical options for your circumstances.
  • A solicitor can help you understand the strengths and risks of your position, but the outcome depends on the facts and applicable law.

Unmarried partner rights in UK property disputes

A breakup can be difficult enough without uncertainty over who owns the home, who should keep paying the mortgage or whether a deposit should be repaid. A cohabitation property dispute arises when former partners disagree about their legal or beneficial interests in a property, including who owns it or how its value should be shared.

In England and Wales, living together doesn’t make a couple legally married, however long they have been together. Unmarried partners don’t automatically gain the same financial claims on separation as spouses. That doesn’t mean a non-owning partner can never have an interest in a home. A claim may depend on the property arrangements, contributions and evidence of what the parties intended. The applicable rules also depend on where the property is and which jurisdiction’s law applies.

Does living together create ownership rights in a home?

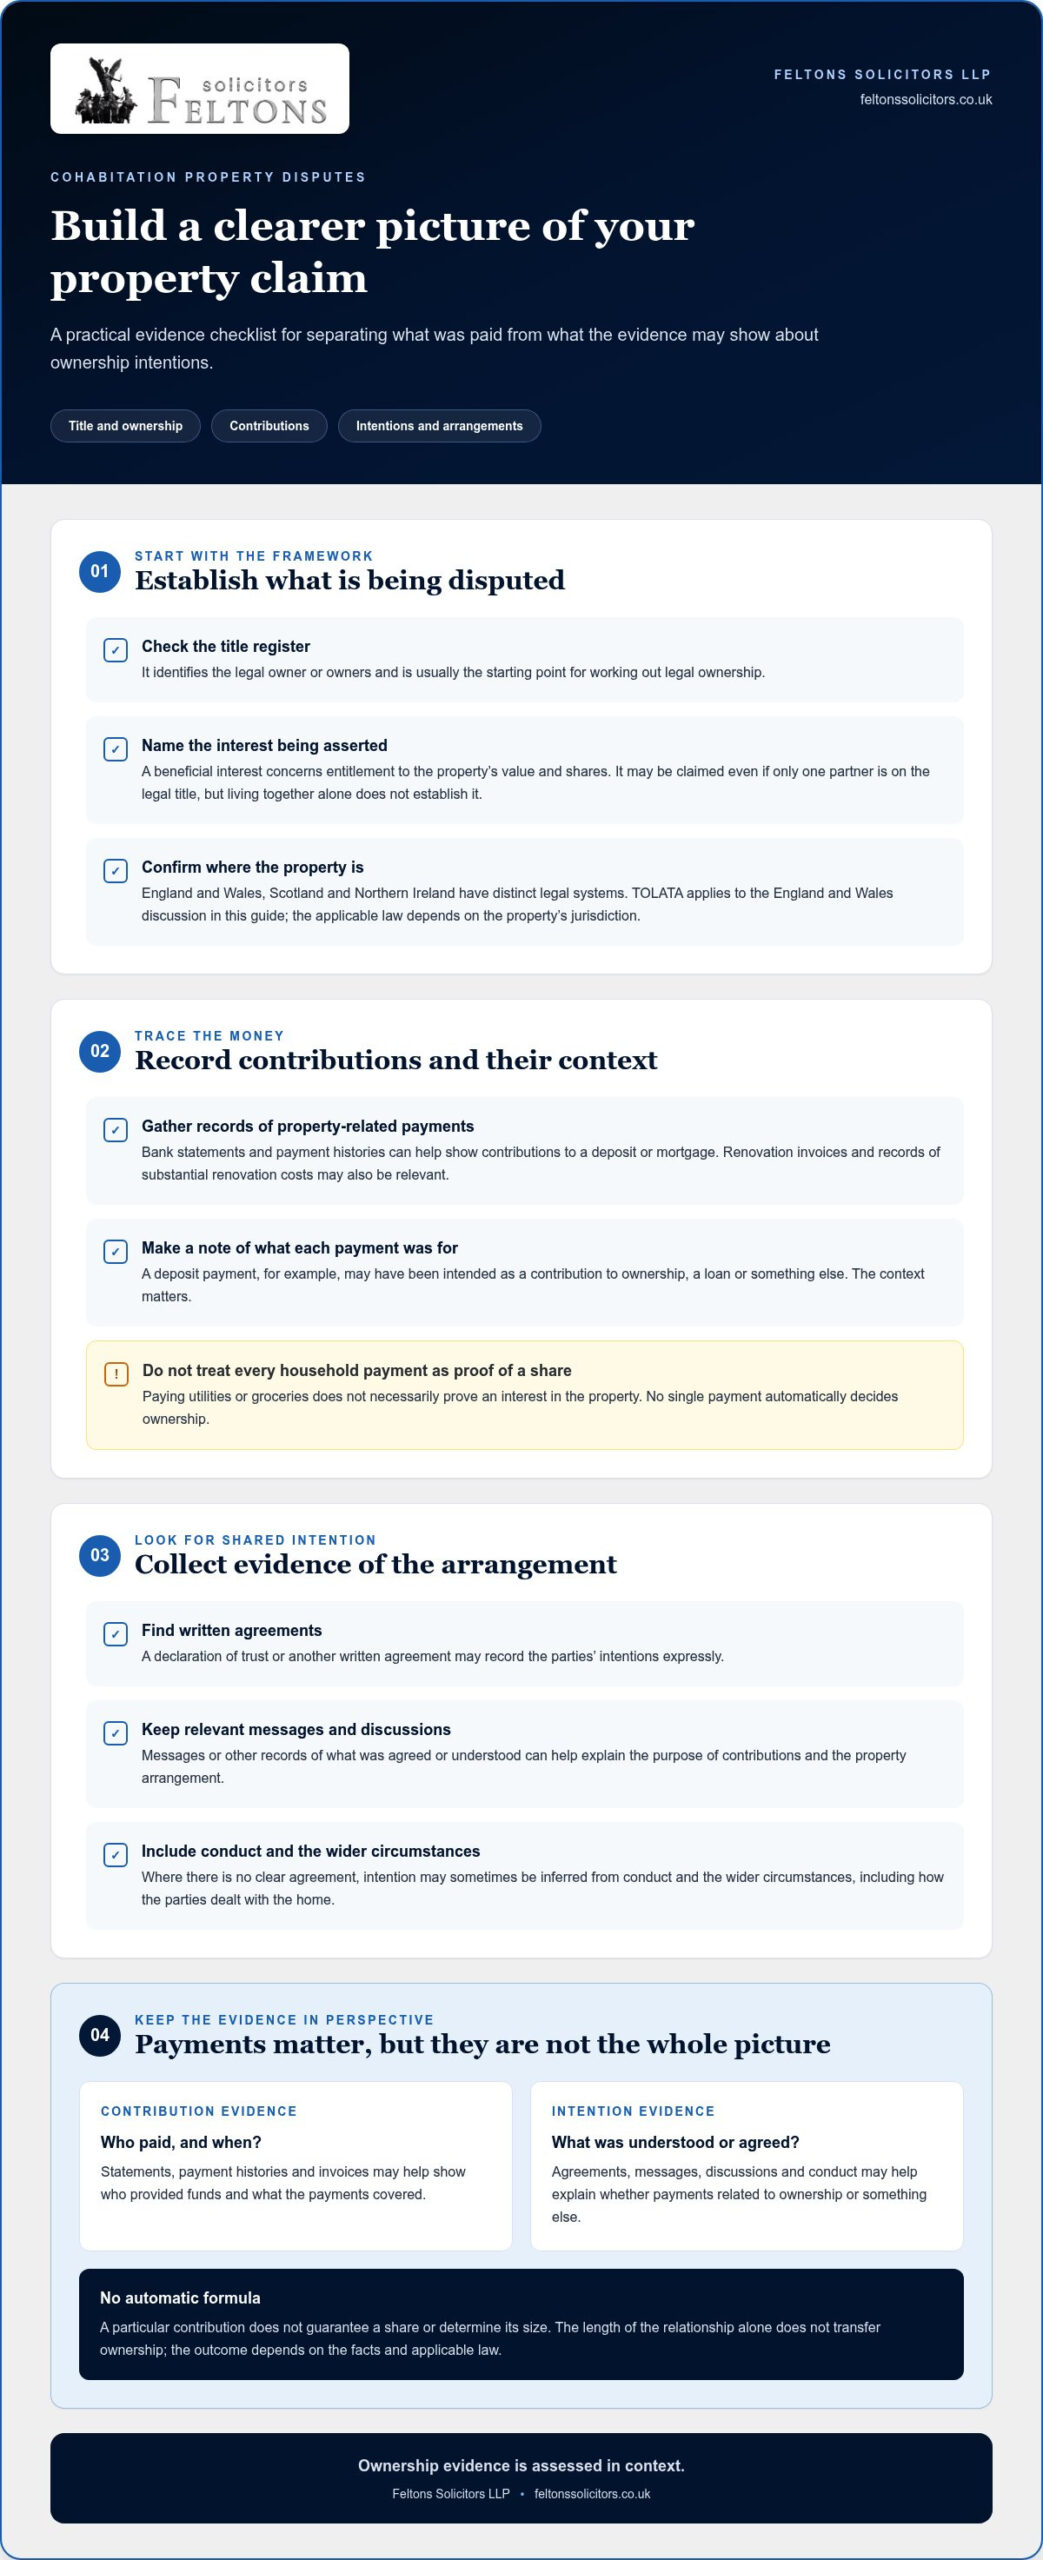
The title register identifies the legal owner or owners. A separate beneficial interest may also be claimed, even where the legal title is in one partner’s name, but living together alone doesn’t establish that interest. In England and Wales, disputes about interests in land may involve the Trusts of Land and Appointment of Trustees Act 1996 (TOLATA). The legal route and evidence needed depend on the circumstances.

Paying household bills, such as utilities or groceries, doesn’t necessarily prove a share of the property. Mortgage payments, a deposit or substantial renovation costs may be relevant, but no single payment automatically decides ownership. The key question is what the evidence shows about the parties’ intentions and the arrangement they made.

Which jurisdiction’s rules apply to a cohabitation dispute?

“UK law” isn’t one set of rules for every property dispute. England and Wales, Scotland and Northern Ireland have distinct legal systems, so the legal tests and procedures can differ. This article’s references to TOLATA and the absence of “common law marriage” relate to England and Wales. They shouldn’t be treated as a UK-wide statement of procedure or rights.

Start by establishing where the property is, then get advice based on the relevant jurisdiction before deciding how to proceed. The phrase cohabitation property dispute lawyers UK may describe the search, but a useful assessment must account for the specific legal system and facts.

In many property disputes, ownership evidence, not relationship status alone, shapes the claim. A solicitor can help distinguish what the title establishes from any beneficial interest being asserted, and assess how the available evidence may affect your options.

How courts assess ownership and interests in shared homes

In England and Wales, the property title is usually the starting point for working out legal ownership. A dispute may also concern beneficial ownership: the interests in the property that determine who is entitled to its value. Legal title shows who owns the property in law; beneficial ownership concerns who is entitled to its value, and in what shares.

The court will consider relevant documents and the parties’ intentions, which may be recorded expressly in a declaration of trust or other written agreement. Where there’s no clear agreement, intention may sometimes be inferred from conduct and the wider circumstances. The legal approach depends on whether the property is registered in one or both partners’ names, and the law differs across the UK.

Two leading England and Wales decisions illustrate how a court may consider shared ownership. In Stack v Dowden [2007] UKHL 17, the House of Lords considered how the beneficial shares of a home registered in joint names could differ from equal shares, taking account of the parties’ whole course of dealings. In Jones v Kernott [2011] UKSC 53, the Supreme Court considered how shares in a jointly owned home could be assessed when the parties’ intentions changed over time. These cases don’t create a simple formula for every dispute. Their application depends on the facts and legal context.

What if only one partner is named on the title deeds?

Sole legal ownership is a significant starting point, but it may not settle whether the other partner has a beneficial interest. A person asserting such an interest needs to establish it through the relevant facts and evidence. The court may consider what was agreed or understood, alongside conduct connected with acquiring or dealing with the home. The length of the relationship alone doesn’t transfer ownership, and no particular contribution guarantees a share.

Can mortgage payments, deposits or renovations affect a claim?

They can be relevant evidence, but they don’t automatically determine whether an interest exists or calculate its size. A deposit transfer may show who provided funds, for example, but context matters: was it intended as a contribution to ownership, a loan or something else? Mortgage statements, renovation invoices and payment histories may help build that picture, as can discussions, written agreements and later conduct.

Keep records together and note what each payment was for, rather than assuming that spending on the home speaks for itself. A careful review can help distinguish evidence of contribution from evidence of shared intention. Advice on property and dispute resolution can help clarify how those issues may apply to your circumstances.

What evidence can strengthen or weaken a cohabitation property claim?

Useful evidence helps show two different things: what each person paid, and what those payments or arrangements were understood to mean. A bank transfer may confirm that money changed hands, for example, but it may not establish whether it was intended as a contribution to ownership, a loan or an ordinary shared expense. The relevance and weight of evidence depend on the facts and the law of the applicable jurisdiction.

Before seeking advice, keep complete copies of relevant records and prepare a dated chronology. Note key payments, conversations and changes to the property as accurately as you can. Preserve original messages and documents. Don’t alter records or select only the parts that appear helpful. Missing paperwork doesn’t automatically defeat a claim, but it may make it harder to establish what was agreed or intended.

Which documents should you gather before seeking advice?

Start with records showing ownership, funding and the history of the home. Depending on the dispute, these may include:

  • Title documents and conveyancing correspondence, including records of how the property was purchased.
  • Mortgage statements, deposit records and bank statements showing transfers or payments.
  • Renovation invoices, receipts and related payment records.
  • Emails, text messages and other communications about ownership, contributions, repayments or plans for the property.
  • Any written agreement, such as a declaration of trust, alongside records of later discussions or changes in the arrangement.

For your chronology, record dates, amounts, the purpose of each payment and any relevant changes to the property. Add a short note of who was present for significant conversations and what you remember being said. Mark clearly where a date or detail is uncertain rather than filling gaps with assumptions.

How should you handle disputed contributions and informal promises?

Separate direct payments towards a deposit or mortgage from renovation spending, unpaid work, household bills and general living costs. These may provide different kinds of evidence, and none automatically proves a particular share. For instance, a transfer towards the mortgage shows a payment, while a message discussing whether that payment would give someone an interest may help explain its intended meaning.

Keep messages in their original context, including the surrounding conversation and date, rather than relying on isolated quotations or screenshots without context. Record informal promises as accurately as possible, but don’t assume a promise has one guaranteed legal effect. Cohabitation property dispute lawyers UK can review the documents and chronology together, assess what they may establish and identify gaps or conflicting accounts that need careful consideration.

Cohabitation Property Dispute Lawyers UK: Your Rights and Next Steps in 2026

What happens when cohabiting partners cannot agree about the property?

A disagreement doesn’t have to move straight to court. A measured approach can help you understand the issues, preserve options and avoid escalating matters before you know what each person is asking for. The right route depends on the property, the evidence, the jurisdiction and whether constructive discussion is possible.

A practical sequence is to:

  • Clarify the dispute: identify whether it concerns ownership shares, a proposed sale, occupation or the handling of mortgage payments.
  • Organise the evidence: bring together title documents, financial records and communications relevant to the disagreement.
  • Explore resolution: consider whether direct negotiation or mediation could help narrow the issues or reach agreed terms.
  • Assess formal options: take tailored advice on the available legal route and its risks before deciding whether to apply to court.

This staged approach can make discussions more focused. It also helps each person understand what remains unresolved, rather than treating every issue as one indivisible dispute.

Can negotiation or mediation resolve a property dispute?

Structured discussion may help former partners agree practical arrangements, such as a proposed sale or how to address a disputed payment. Mediation can provide a setting to explore those issues, but it isn’t suitable in every case or a guaranteed solution. Safety, each person’s willingness to participate and the nature of the disagreement all matter. Nobody should assume mediation is appropriate in every circumstance.

If you reach an agreement, make the terms clear and record them in writing. Consider legal review before relying on them, particularly where ownership interests, a sale or ongoing financial obligations are involved. For a broader view of alternatives and formal routes, read about dispute resolution options.

When might a court application under TOLATA be considered?

In England and Wales, the Trusts of Land and Appointment of Trustees Act 1996, commonly called TOLATA, may provide a route to ask the court to determine questions about interests in land. Depending on the circumstances and the application, the court may be asked to address matters such as the parties’ interests, sale of the property or occupation. The available orders depend on the facts and legal basis of the claim, so no particular result can be assumed.

A court application is a formal step. Before taking it, consider the evidence needed, the likely costs and procedural consequences, as well as whether another resolution route remains practical. TOLATA applies in England and Wales; Scotland and Northern Ireland have different legal systems. Cohabitation property dispute lawyers UK can assess which jurisdiction applies and help you weigh proportionate options without promising an outcome.

How UK cohabitation property lawyers can help you

A solicitor can bring structure to a dispute by reviewing the registered title, available documents and each partner’s account of what was agreed. They can assess possible claims, identify evidence gaps and explain the risks and practical implications of different routes, from further discussion to formal proceedings. The aim is to help you make informed decisions, not to promise a particular result before the facts have been examined.

Advice should be tailored to the property’s jurisdiction and your circumstances. A solicitor can help clarify the ownership position, consider how evidence may support or weaken a claim, and compare realistic resolution options. That assessment can also help you focus on the outcome you need, whether it involves discussing a sale, occupation or a disputed interest.

What should you prepare before speaking to a solicitor?

A concise summary makes it easier to identify the key questions. Gather what you can, even if some records are incomplete:

  • Title information, mortgage documents and conveyancing paperwork.
  • Deposit and payment records, including bank statements and mortgage contributions.
  • Any cohabitation agreement, declaration of trust or other written arrangement.
  • A brief timeline of the relationship, purchase and ownership arrangements, significant payments and changes to the property.

Also note the outcome you’re seeking and any immediate concerns, such as a proposed sale, transfer or alteration to the property. Bring the key questions you want answered. You don’t need to resolve every detail before seeking advice. Flag uncertainties clearly rather than making assumptions.

What should tailored legal advice help you understand?

After reviewing the information, advice should help you identify which jurisdiction’s rules apply, what the title establishes and whether further evidence may be needed. It should also set out possible routes to resolution and their practical implications, so you can consider what is proportionate for your objectives. The available options depend on the facts, and no outcome can be guaranteed in advance.

If you’d like more context on title and ownership concepts, consult the firm’s residential property law guide. For advice on a cohabitation property dispute, speak with Feltons Solicitors LLP. The firm’s family law, property and dispute resolution experience can help you assess your position and consider sensible next steps. Cohabitation property dispute lawyers UK should offer clear, practical guidance grounded in the evidence and your circumstances.

Take a clear next step with your property dispute

A cohabitation property dispute is assessed under the applicable law and on the evidence, not simply on how long you were together. The title is an important starting point, but documents, payments and what you both intended may also matter. Keep relevant records together and note where the facts or your former partner’s account differ.

Negotiation or mediation may help resolve some disagreements, while formal options may need consideration if agreement isn’t possible. The right route depends on your circumstances and the jurisdiction involved. Advice can clarify your position and practical choices, but no outcome can be guaranteed before the facts are reviewed.

If you’re looking for cohabitation property dispute lawyers UK, Feltons Solicitors can bring family law, property and dispute resolution experience to a tailored, pragmatic assessment of your situation. Discuss your property dispute with Feltons Solicitors and take an informed step towards resolving the issues. You don’t have to work through your options alone.

Frequently Asked Questions

Does living together for years give me rights to my partner’s house?

No. The length of time you’ve lived together doesn’t automatically give you ownership of your partner’s home. The registered title identifies the legal owner, but you may be able to assert a beneficial interest, depending on the facts, evidence and jurisdiction. Contributions to the purchase or mortgage, and evidence of shared intentions, may be relevant, but don’t guarantee a particular share. Seek tailored legal advice before making decisions about the property.

Can I claim a share of a house if my name is not on the deeds?

Possibly. Sole registered ownership is an important starting point, but it doesn’t necessarily resolve whether another person has a beneficial interest. Relevant evidence may include an agreement, payments towards the property and the parties’ conduct. No single contribution automatically creates an entitlement to a share. The legal framework differs across the UK, so advice should reflect where the property is and the circumstances of your claim.

What evidence do I need for a cohabitation property dispute?

Gather the title documents, mortgage statements, deposit records, bank transfers, renovation invoices and relevant correspondence. Messages or written agreements may help show what you and your former partner intended, not just who paid. Keep original records and prepare a dated chronology of key payments, discussions and property changes. Evidence is assessed as a whole, and which documents matter most depends on the dispute’s facts and the applicable jurisdiction.

Can I force the sale of a home after separating from my partner?

A sale may be agreed between the owners or, in some circumstances, sought through a court process. Whether that is possible depends on the legal ownership, any beneficial interests, the circumstances and the relevant jurisdiction. In England and Wales, an application under the Trusts of Land and Appointment of Trustees Act 1996 may be relevant. A court won’t necessarily order a sale, so obtain individual legal advice before taking formal steps.

Does the UK have common-law marriage?

Living together doesn’t generally give unmarried partners the same legal status as spouses simply because time has passed. In England and Wales, there’s no “common-law marriage”. That doesn’t mean a partner can never claim an interest in a home: property rights may arise through legal ownership or beneficial-interest principles, depending on the facts and jurisdiction. The rules aren’t identical across the UK, so consider advice specific to your circumstances.

How can a solicitor help with a cohabitation property dispute?

A solicitor can review the title, documents and each partner’s account, identify relevant legal issues, and explain possible evidence gaps. They can also discuss proportionate options, which may include negotiation, mediation or formal proceedings. Advice helps you understand your position and choices; it can’t guarantee a particular result. Feltons provides family law, property and dispute resolution services, with pragmatic advice tailored to individual circumstances.

Are cohabitation property laws the same across the UK?

No. There isn’t one uniform property dispute procedure for every UK jurisdiction. England and Wales, Scotland and Northern Ireland have distinct legal systems, and the applicable framework may depend on where the property is located. Avoid relying on a rule described as UK-wide without checking how it applies to your circumstances. Jurisdiction-specific legal advice can help clarify your position before you negotiate, make decisions about the property or take formal action.

Buying UK Commercial Property: Overseas Entity Guide 2026

Buying UK Commercial Property: Overseas Entity Guide 2026

In 2026, the Register of Overseas Entities is no longer a hurdle; it is the foundation of the UK commercial conveyancing process. You likely recognise that the landscape for a commercial property purchase by overseas entity uk has shifted, placing transparency at the heart of every transaction. It’s natural to feel a sense of unease regarding the stringent disclosure of beneficial ownership or the threat of severe penalties for administrative oversights. These concerns are valid, as a single delay in verification can stall a high-value acquisition indefinitely.

We’re here to provide a steady hand through this process, offering the expert legal guidance you need to secure your investment with confidence. This guide provides a clear roadmap for your acquisition, ensuring you meet every requirement of the Register of Overseas Entities. We’ll walk you through the latest reporting standards, the annual update statement cycle, and the practical steps required to achieve a completion that is entirely free from regulatory friction. You’ll gain the clarity necessary to manage your international portfolio whilst maintaining total compliance with Companies House.

Key Takeaways

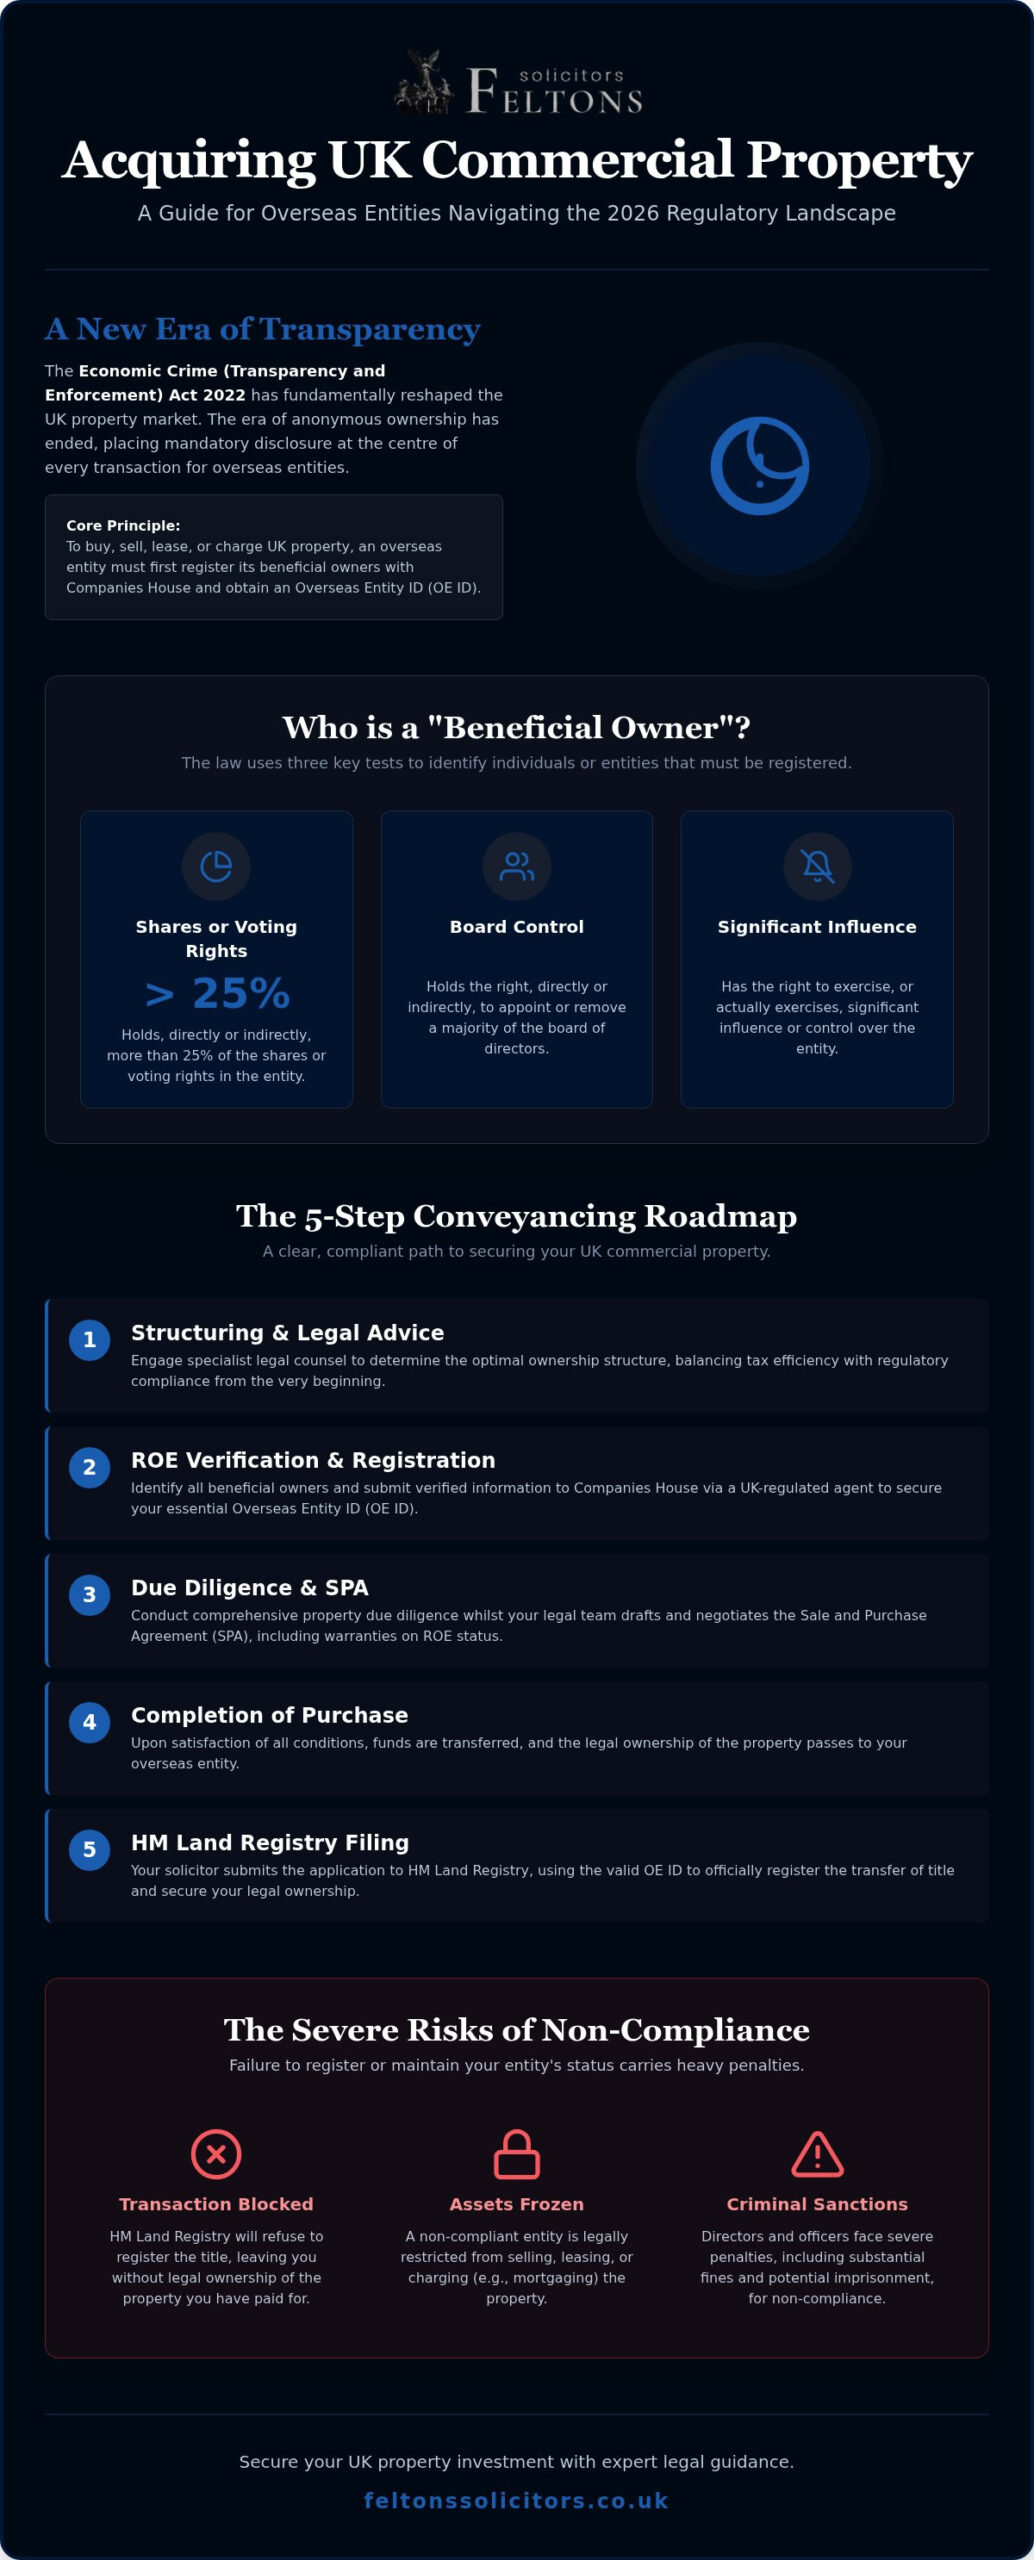
  • Understand how the Economic Crime (Transparency and Enforcement) Act 2022 has made transparency the central pillar of the UK property market.
  • Gain clarity on the 25% control tests used to define beneficial owners, ensuring your entity meets all mandatory disclosure requirements without delay.
  • Discover how to structure your commercial property purchase by overseas entity uk to balance tax efficiency with regulatory ease.
  • Follow a methodical five-step roadmap for conveyancing that integrates Register of Overseas Entities verification into the heart of the legal process.
  • Recognise the value of bespoke legal support in avoiding the administrative friction and heavy penalties associated with non-compliance.

The Regulatory Landscape: Buying UK Commercial Property in 2026

The introduction of the Economic Crime (Transparency and Enforcement) Act 2022 fundamentally altered how international investors approach the UK market. By 2026, the era of anonymous property ownership has effectively ended. Every commercial property purchase by overseas entity uk now begins with a rigorous compliance check, as the legislation serves as a robust gatekeeper for the nation’s real estate assets. HM Land Registry acts as the final enforcement point. They’ll simply refuse to register the transfer of title if the purchasing entity hasn’t secured a valid Overseas Entity ID before completion.

The Shift Towards Transparency

The UK has meticulously organised its property laws to prioritise transparency and deter illicit finance. This shift means that corporate structures once favoured for their privacy are now subject to intense scrutiny. To participate in the market, overseas entities must disclose their “Beneficial Owners” to Companies House. This isn’t a mere administrative formality; it’s a mandatory requirement to ensure that the ultimate individuals in control are identifiable. Investors who embrace this “clean” approach often find that their transactions proceed with greater efficiency, whilst those who ignore the requirements face immediate roadblocks. Lenders and sellers are increasingly wary of opaque ownership chains that might trigger money laundering concerns.

Consequences of Non-Compliance

Failing to adhere to these regulations carries risks that extend far beyond simple transaction delays. Without a verified registration, an entity cannot legally register its ownership at HM Land Registry. This leaves the buyer in a precarious position where they’ve paid for a property but don’t hold the legal title. For any commercial property purchase by overseas entity uk, the lack of an OE ID is a terminal flaw in the conveyancing process. Additionally, the legal framework imposes strict restrictions on future dealings. A non-compliant entity will find it impossible to lease, charge, or sell the asset. Perhaps most significantly, directors and officers of the entity may face criminal sanctions, including heavy fines or even imprisonment, if they knowingly provide false information or fail to update the register annually.

Given these complexities, seeking specialist legal advice before signing a Sale and Purchase Agreement (SPA) is essential. A well-drafted SPA should include specific warranties regarding the entity’s status on the Register of Overseas Entities to protect your interests from the outset. Early preparation ensures that the path to completion remains clear and that your investment is protected by a solid legal foundation.

The Register of Overseas Entities (ROE): A Mandatory First Step

The Register of Overseas Entities is a public register managed by Companies House that records the details of foreign-domiciled owners of UK land. It’s a non-negotiable part of any commercial property purchase by overseas entity uk. An Overseas Entity ID (OE ID) is the unique 10-digit code required for all Land Registry filings to prove the entity is compliant. Without this identifier, your transaction cannot legally proceed to completion. The register ensures that the true owners behind corporate veils are identifiable, creating a more transparent environment for high-value investments.

Identifying a “Beneficial Owner” is the core of the registration process. Usually, this refers to any individual or legal entity that holds more than 25% of the shares or voting rights in the overseas company. However, the law also applies control tests. If an individual has the power to appoint or remove a majority of the board of directors, or otherwise exercises significant influence, they’re a beneficial owner regardless of their shareholding percentage. Identifying these individuals accurately is the first step in building a compliant acquisition structure.

The Verification Process Explained

Accuracy is paramount when submitting data to the register. A UK-regulated agent, such as a solicitor, must verify the information before it’s formally submitted. This involves a methodical review of international corporate documents, which often requires certified translations or apostilles to meet UK standards. When dealing with trusts or complex layering in offshore structures, the verification becomes significantly more intricate. We examine the entire chain of ownership to ensure every registrable person is correctly identified, providing a sense of security for our clients whilst satisfying the stringent requirements of the Economic Crime Act.

Maintaining Your OE ID

Registration isn’t a one-off event. You must file an update statement every 12 months, even if your beneficial ownership remains unchanged. This 12-month update cycle is critical for ongoing property management. A lapsed OE ID can freeze your ability to deal with the asset, preventing you from selling or charging the property. If a change in ownership occurs whilst a transaction is mid-flight, the register must be updated within 14 days of the anniversary of the initial registration to avoid administrative friction.

Managing these statutory requirements requires a professional and methodical approach. Feltons Solicitors LLP provides dedicated support for overseas entity beneficial owner registration, ensuring your filings are precise and timely. If you’re concerned about meeting these deadlines or navigating the verification process, our team can act as your trusted legal partner to maintain your entity’s standing and protect your investment.

Structuring Your UK Commercial Property Acquisition

Choosing the right vehicle for a commercial property purchase by overseas entity uk is a decision that balances tax efficiency against administrative ease. Whilst offshore structures in jurisdictions like the British Virgin Islands (BVI) or Jersey remain common, the regulatory tide is turning. Your choice of entity doesn’t just affect your tax profile; it dictates your ability to secure UK debt finance. Many domestic lenders prefer the familiarity of a UK-incorporated subsidiary. It simplifies their own due diligence and security requirements, often leading to more favourable lending terms.

Offshore Entities vs UK SPVs

Using an offshore entity from a jurisdiction like the Isle of Man can offer specific tax advantages, yet it comes with a heavier administrative burden. You’ll often need formal legal opinions from counsel in that jurisdiction to satisfy UK lenders or HM Land Registry. This adds cost and time to the transaction. Conversely, a UK-resident Special Purpose Vehicle (SPV) is often more straightforward to manage. Foreign directors should also consider their legal liability. Whilst a corporate veil exists, UK law can occasionally look through it in cases of environmental breach or health and safety failures. A UK subsidiary can act as a useful buffer for international parents.

Stamp Duty Land Tax (SDLT) and VAT Considerations

The tax landscape for international investors is nuanced. Whilst the 2% non-resident SDLT surcharge primarily targets residential assets, it can impact mixed-use properties or commercial-residential hybrids. You must also account for the Annual Tax on Enveloped Dwellings (ATED) if your commercial acquisition includes high-value residential elements. VAT is another critical factor. If a seller has “opted to tax” the property, the purchase price effectively increases by 20% upfront. Whilst you can often recover this, it creates a significant cash flow requirement that must be managed during the commercial property purchase by overseas entity uk.

Deciding on the right structure requires a methodical look at your long-term goals. We often advise clients to weigh the merits of commercial property law: buying vs leasing before committing to a specific corporate vehicle. A bespoke approach ensures that your structure remains robust against future regulatory shifts. It provides the security and flexibility needed for sophisticated international portfolio management.

Buying UK Commercial Property: Overseas Entity Guide 2026

The 5-Step Conveyancing Journey for Overseas Entities

Successfully managing a commercial property purchase by overseas entity uk requires more than just capital; it demands a synchronised legal strategy. By 2026, the Register of Overseas Entities (ROE) isn’t a separate administrative task but a core component of the conveyancing timeline. If these steps aren’t perfectly aligned, you risk significant transaction delays or, in the worst cases, a total collapse of the deal. We guide our clients through a methodical five-step process to ensure a smooth transition from offer to ownership.

  • Step 1: Pre-contract due diligence and ROE verification. Before any formal commitment, we verify your entity’s status and ensure your OE ID is active and updated.
  • Step 2: Drafting the contract and negotiating the Sale and Purchase Agreement (SPA). We negotiate specific clauses that protect international buyers, particularly regarding warranties for ROE compliance.
  • Step 3: Exchange of contracts and payment of the deposit. This is the point of no return. We manage the secure transfer of the 10% deposit, ensuring funds are held safely in a client account.
  • Step 4: Pre-completion checks. We perform final anti-money laundering (AML) updates and ensure the seller’s ROE status is also valid, preventing any blocks at the Land Registry.
  • Step 5: Completion and registration. Funds are transferred, and we submit the application to HM Land Registry using your unique 10-digit OE ID.

Enhanced Due Diligence and AML

Overseas entities are subject to “Enhanced Due Diligence” under UK law. This means your legal team must go beyond simple identity checks. You’ll need to provide clear documentation regarding your Source of Wealth (SoW) and Source of Funds (SoF). These protocols are designed to confirm that the capital used for the commercial property purchase by overseas entity uk is legitimate and transparent. In 2026, “Know Your Customer” (KYC) requirements are more rigorous than ever, often requiring detailed histories of corporate earnings or investment returns. Preparing this documentation early prevents the “compliance bottleneck” that often stalls international transactions.

Navigating the Completion Process

The final stages of a cross-border transaction involve unique logistical challenges. Coordinating international bank transfers requires precision to account for currency fluctuations and varying time zones. Furthermore, the execution of legal deeds whilst overseas remains a point of detail; whilst digital signatures are increasingly accepted, some documents still require “wet-ink” signatures witnessed by a notary. It’s often beneficial to work with a residential property law firm with deep commercial expertise to handle these nuances. They can bridge the gap between high-standard international service and the practical realities of UK property law.

If you’re planning an acquisition, our specialist commercial conveyancing team is ready to provide the discreet, high-standard support your transaction deserves. Contact us to ensure your next investment is handled with the poise and technical precision it requires.

In 2026, the complexity of a commercial property purchase by overseas entity uk means that standard legal support is often insufficient. International investors require a partner who understands the high stakes of cross-border acquisitions and the rigorous demands of the Economic Crime Act. At Feltons Solicitors LLP, we position ourselves as a calm, steady presence in the face of these stresses. We recognise that whilst the technical legal work is paramount, the human impact of these transactions is never forgotten. Our approach is designed to provide you with high-end reliability and the quiet confidence that your investment is secure.

Mitigating the risk of transaction collapse is our primary objective. A single administrative oversight in beneficial ownership disclosure or a lapsed OE ID can lead to immediate blocks at HM Land Registry. These errors don’t just delay completions; they can lead to heavy financial penalties and reputational damage. By choosing a specialist firm, you ensure that every detail is scrutinised by experts who handle these complex verification services daily. We manage the intricate due diligence required for international corporate documents, ensuring your path to completion remains clear of regulatory friction.

Discreet and Tailored Service

We believe that high-standard international service should feel personal. As a boutique firm, we prioritise personal connection over high-volume processing, acting as a sophisticated guide through the UK legal market. This allows us to provide pragmatic advice that is tailored to your specific portfolio goals. Whether you are a first-time investor or managing a large commercial estate, we offer the same level of discreet, high-standard care. This commitment to excellence extends across our firm, from our conveyancing team to our leasehold enfranchisement experts, ensuring your property rights are always protected.

Contact Feltons Solicitors LLP for International Acquisitions

Beginning your verification and conveyancing process early is the most effective way to ensure a successful acquisition. We’re ready to assist with your initial registration on the Register of Overseas Entities and manage the entire conveyancing journey on your behalf. Our team bridges traditional professional integrity with modern efficiency to deliver results that respect your time and your capital. To take the first step towards a frictionless completion, secure your UK commercial investment with Feltons Solicitors LLP today. Let us act as your trusted advisor in the UK property market.

Securing Your UK Investment with Confidence

The shift towards total transparency in the UK property market represents a significant evolution, yet it should not deter sophisticated international capital. As we’ve discussed, the key to a successful commercial property purchase by overseas entity uk lies in the early alignment of corporate structuring and ROE verification. By addressing the nuances of beneficial ownership and the specifics of the five-step conveyancing journey, investors can avoid the pitfalls of transaction delays and regulatory penalties. The goal is to transform these statutory requirements from a hurdle into a standard, efficient part of your portfolio management.

At Feltons Solicitors LLP, we provide the calm, steady guidance necessary to handle these high-value matters with precision. Our firm operates as a discreet partner, bridging modern efficiency with a deep respect for professional integrity and personal rapport. We invite you to speak with our specialist commercial conveyancing team today to ensure your next acquisition is managed with the boutique-level care it deserves. Together, we can secure your position in the UK market with absolute confidence.

Frequently Asked Questions

Can an overseas company still buy property in the UK after the 2022 Act?

Yes, overseas companies can continue to invest in the UK market. The Economic Crime (Transparency and Enforcement) Act 2022 didn’t ban foreign ownership; it simply introduced a mandatory registration requirement. To complete a commercial property purchase by overseas entity uk, the buyer must obtain a valid Overseas Entity ID from Companies House. This identifier proves the entity has disclosed its beneficial owners, allowing the Land Registry to process the transfer of title without legal obstruction.

How long does it take to register an overseas entity with Companies House?

Registration typically takes a few working days once Companies House receives the application. However, the pre-submission phase often takes longer. A UK-regulated agent must first verify all beneficial ownership details, which involves reviewing international corporate documents and identity records. Depending on the complexity of your offshore structure and the speed of document retrieval, the entire process from initial instruction to receiving your OE ID usually spans several weeks. Early preparation is essential for maintaining transaction timelines.

What happens if an overseas entity fails to update its beneficial owner information?

Failing to file an annual update statement has severe consequences for your investment. Your Overseas Entity ID will become invalid, which effectively freezes your ability to deal with the property. You won’t be able to sell, lease, or charge the asset until the register is corrected. Additionally, the entity and its officers may face daily fines. For any commercial property purchase by overseas entity uk, maintaining an active registration is a critical ongoing compliance duty.

Do I need a UK bank account to buy commercial property as a foreign entity?

You aren’t legally required to hold a UK bank account to buy commercial property, but it’s practically indispensable. Whilst you can often transfer purchase funds from abroad, you’ll need a domestic account to manage rental income, pay UK taxes, and handle utility bills or service charges. Many international investors find that setting up a UK-resident Special Purpose Vehicle (SPV) makes opening a domestic account significantly easier than doing so for a foreign-domiciled company.

Is the Register of Overseas Entities information available to the public?

Yes, most information on the Register of Overseas Entities is accessible to the public. Anyone can search Companies House to view the names of beneficial owners and the entity’s registration details. Certain sensitive information, such as home addresses or full dates of birth, remains protected from public view. This transparency is a central pillar of the 2022 Act, designed to ensure that the ultimate individuals in control of UK land are identifiable to the public.

How much does the ROE verification process cost for a foreign company?

The cost of the verification process varies based on the complexity of your corporate structure. Companies House charges a fixed registration fee of £100 and an annual update fee of £120. Beyond these government charges, you’ll also incur professional fees for the mandatory verification services provided by a UK-regulated agent. These fees reflect the rigorous due diligence required to examine international deeds, trust documents, and shareholder registers to ensure total accuracy before submission.

Can I use an overseas entity to buy residential property as well as commercial?

Overseas entities can buy both commercial and residential property in the UK. However, the tax regimes differ significantly. Residential acquisitions trigger a 2% non-resident SDLT surcharge, which does not apply to non-residential commercial assets. You may also face the Annual Tax on Enveloped Dwellings (ATED) for high-value homes. Regardless of the property type, the requirement to register with Companies House remains mandatory for any foreign-domiciled legal entity owning UK land.

What are the penalties for providing false information to the Register of Overseas Entities?

Providing false or misleading information to the register is a serious criminal offence. If an individual or entity knowingly submits incorrect data, they face significant penalties under the Economic Crime Act. This includes potential unlimited fines and criminal prosecution for both the entity and its officers. The UK government uses these stringent measures to maintain the integrity of the register, ensuring that all disclosures regarding beneficial ownership are both honest and verifiable.