Executor Not Following a Will: What Beneficiaries Can Do

Probate solicitor oversees beneficiaries receiving estate heirlooms from a reluctant executor in a London home

An executor cannot replace the instructions in a will with personal preferences. If an executor doesn’t follow the will, beneficiaries can raise their concerns, request information about the estate and, if the problem persists, seek a court order requiring the executor to act or asking the court to remove them. Court intervention is generally a last resort.

It is understandable to expect an executor to manage the estate fairly and keep beneficiaries informed, particularly when money or family relationships are involved. This article explains what beneficiaries can do if an executor withholds money, fails to carry out their duties or mishandles estate assets. It also explains when delays may be legitimate, which records can clarify the situation and how court orders may address persistent problems in England and Wales.

Key Takeaways

  • An executor who is also a beneficiary must still act impartially; a personal interest can create a conflict that deserves careful scrutiny.
  • Keep a clear record of concerns, correspondence and any apparent effect on the estate if you may need to show how the executor has acted.
  • In England and Wales, the Non-Contentious Probate Rules 1987 may be used to deal with problem-executor matters at the Probate Registry, according to the UK legislation register.
  • If informal efforts do not resolve the issue, beneficiaries may be able to seek an order requiring the executor to provide accounts or carry out their duties.

Can an executor withhold money from beneficiaries?

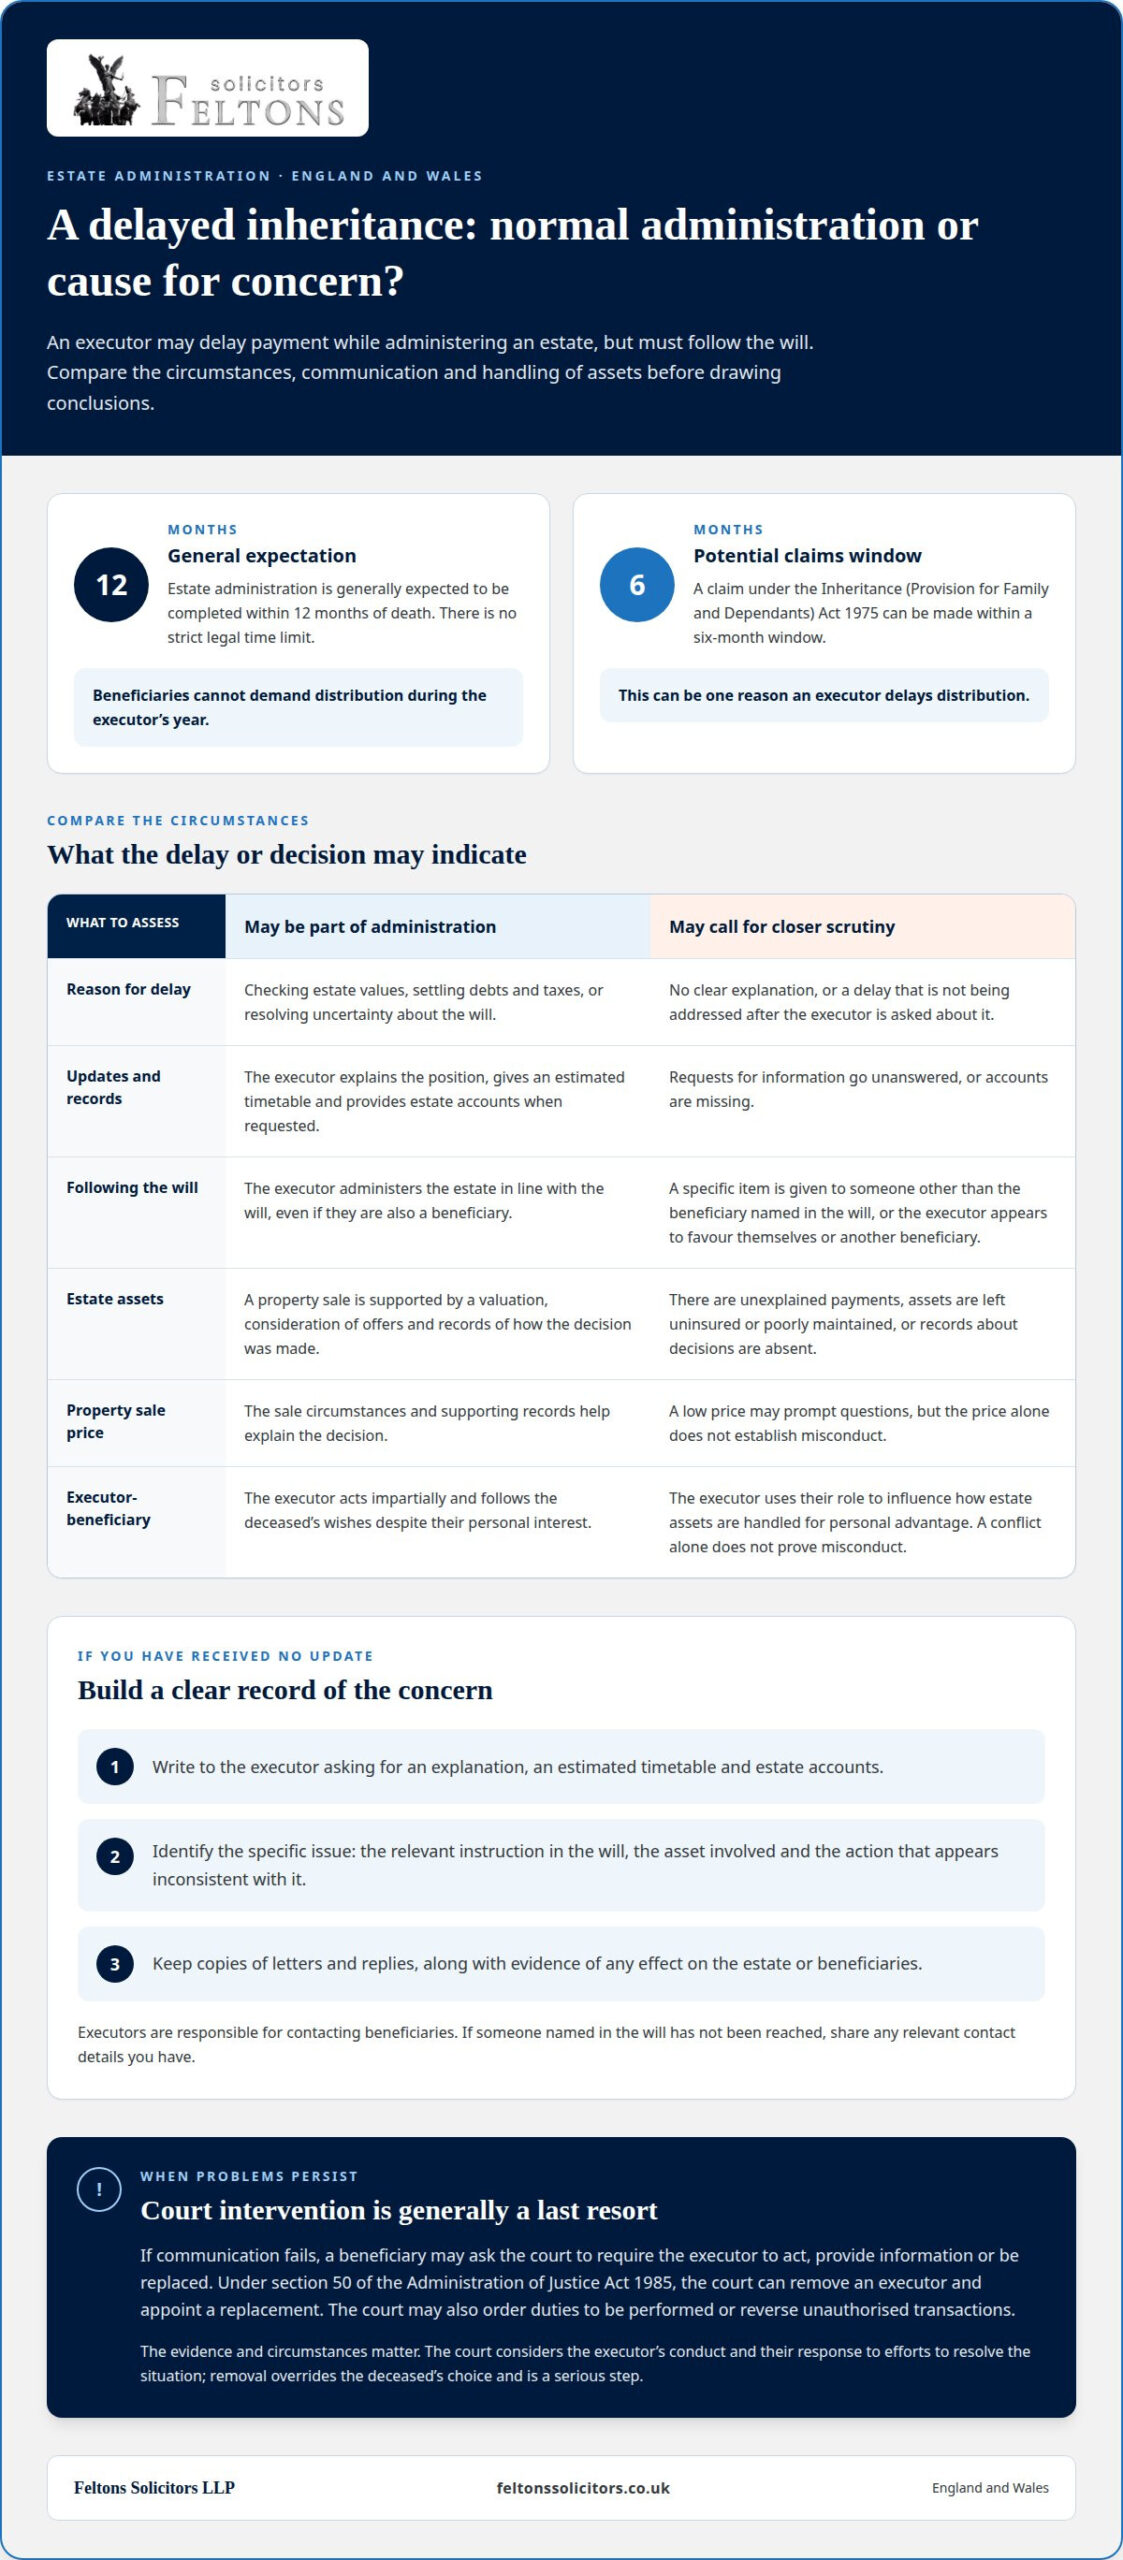
An executor may delay payment while administering the estate, but must distribute it according to the will. If you’re concerned about what happens if an executor doesn’t follow the will, ask for an explanation before treating a delay as misconduct.

Conflicts involving executor-beneficiaries

A conflict can arise when an executor is also entitled to inherit, because their personal interests may differ from those of the beneficiaries as a whole. They must still act impartially and follow the deceased’s wishes, rather than favouring themselves or another beneficiary. For example, an executor-beneficiary should not use their role to influence how estate assets are handled for personal advantage. A conflict alone does not prove misconduct, but the executor’s decisions and explanations matter.

Delays to beneficiary distributions

An executor may sometimes delay distribution while checking estate values, settling debts and taxes, or resolving uncertainty about the will. In England and Wales, administration is generally expected to be completed within 12 months of the death, though there is no strict legal time limit. Beneficiaries cannot demand distribution during the executor’s year. An executor may also delay while potential claims under the Inheritance (Provision for Family and Dependants) Act 1975 can be made within a six-month window, according to the UK legislation register.

If you have received no update, write to the executor asking for an explanation, an estimated timetable and estate accounts. Executors should keep accurate records and provide accounts when beneficiaries request them. They are also responsible for contacting beneficiaries, so share any relevant contact details you have if someone named in the will has not been reached. Keep copies of letters and replies. A dated record can clarify whether the delay is being addressed.

There is no single deadline for every challenge or estate claim. In England and Wales, a breach-of-duty claim may be brought up to 12 years from when the right to receive the estate accrued; a claim under the 1975 Act has a six-month window. What happens if an executor doesn’t follow the will may depend on the conduct and the evidence available.

An executor cannot change the will because they consider it unfair, and cannot prevent beneficiaries from contesting it. A challenge to the will is separate from a complaint about the executor’s conduct: the first disputes the will’s validity or effect, while the second concerns estate administration. Set out the specific issue in writing so the executor can respond and the appropriate action can be considered.

What Happens if the Executor Does Not Follow the Will?

Where an executor’s conduct threatens estate administration, beneficiaries can seek court intervention. Removal is a serious step, so the evidence and circumstances matter.

Court applications to remove an executor

A beneficiary can ask the court to remove an executor who is failing to perform their role. The application should set out specific actions, supporting evidence and the effect on the estate or beneficiaries. For example, include unanswered written requests or records of assets handled contrary to the will. Under section 50 of the Administration of Justice Act 1985, a court can remove an executor and appoint a replacement.

Court orders and executor replacement

The court can order an executor to perform duties, such as applying for probate or distributing assets, and may reverse unauthorised transactions. Removal is generally a last resort, particularly because it overrides the deceased’s choice. The court considers the executor’s conduct and their response to efforts to resolve the situation. If one executor is clearly responsible, the court may appoint a replacement. Persistent disagreement between executors can also make independent administration necessary.

Challenging an executor’s conduct

To challenge decisions, beneficiaries can first raise concerns in writing and explain which part of the will or administration is at issue. Keep copies of correspondence and evidence showing any effect on the estate. If communication fails, a beneficiary may petition the probate court and ask for an order compelling the executor to act, provide information or be replaced. In England and Wales, the Non-Contentious Probate Rules 1987 may be used to deal with problem-executor matters at the Probate Registry, according to the UK legislation register.

The court process depends partly on whether a Grant of Probate has already been issued. Applications may follow different procedures and timescales depending on that situation. The cost of applying or pursuing recovery depends on the case, the work involved and the procedure; costs are given after a quote request.

This section covers England and Wales. Probate procedures differ in Scotland and Northern Ireland, so beneficiaries there need to follow the process that applies to the estate’s jurisdiction. Likewise, where estates involve cross-border assets or family members overseas, consulting specialist succession practices such as rgs-law.com can help clarify relevant local inheritance rules.
Executor Not Following a Will: What Beneficiaries Can Do

Examples and signs of executor misconduct

Misconduct may involve ignoring the will, mishandling assets or failing to carry out estate duties. A clear example is giving a specific item to someone other than the beneficiary named in the will. An executor must preserve estate property and manage it prudently. If you spot a concern, identify the asset, the relevant instruction in the will and the action that appears inconsistent with it.

Property sales can also raise questions. A low sale price alone does not establish misconduct, but the circumstances matter, including whether the executor obtained a valuation, considered offers and kept records. A solicitor assessing the issue may examine sale documents and correspondence to understand how the decision was made.

Other warning signs include unexplained payments from estate funds, missing accounts, assets left uninsured or poorly maintained, and one beneficiary receiving preferential treatment. An executor-beneficiary’s personal interest can make decisions particularly important to scrutinise. Compare the will’s instructions with estate accounts and transaction records. A mistake may still lead to a claim, although a court can relieve an executor from liability for an honest and reasonable mistake under section 61 of the Trustee Act 1925.

Separate evidence from suspicion before deciding whether to make an application. Record dates, amounts, property details and the executor’s explanation, then keep copies of relevant documents. For example, a delayed response does not itself prove that inheritance is being withheld improperly. An unanswered request combined with unexplained withdrawals may warrant closer examination. Executors should keep accurate estate records and provide accounts when beneficiaries request them. A written record helps show what happened and whether the executor addressed the concern.

Orders requiring an executor to provide accounts or perform duties

An executor should value the deceased’s estate, record each beneficiary’s share and account for financial dealings. If an executor gives no clear reason for withholding accounts, request them in writing before considering a court application. This creates a record of the dispute and gives the executor an opportunity to respond.

In England and Wales, beneficiaries can seek a court order requiring an executor to provide an inventory and account of the estate’s financial dealings under section 25 of the Administration of Estates Act 1925. The inventory identifies estate assets, while the account explains receipts, payments and distributions. These records can help beneficiaries understand how money was handled and identify transactions needing explanation. For example, an account may clarify whether estate funds paid a debt or were transferred without a proper estate reason.

A court application may also ask an executor to carry out a specific responsibility, such as applying for probate or distributing assets under the will. Identify the outstanding duty, the relevant provision in the will and any attempts to resolve the matter. Dated letters, unanswered requests and estate documents can show what remains undone. The court can consider the executor’s response and the practical effect of further delay when deciding what order may help the administration.

Keep the request focused: specify which accounts or action you seek, why they are needed and a reasonable date for a response. If the executor disputes the request, their explanation and supporting records can help narrow the issue. A court order can require information or action, but it does not automatically remove the executor; that is a separate remedy. For support with an executor dispute, seek advice on estate administration.

Feltons Solicitors LLP: Wills, Probate, and Estate Planning

Feltons Solicitors LLP assists with wills, probate and estate planning, including matters where a beneficiary is concerned about an executor’s conduct. Legal support can help clarify the executor’s responsibilities, assess estate information and consider suitable next steps, such as seeking accounts or asking the court to require action. It may be appropriate to seek advice when communication has stalled, estate records raise questions or an executor appears not to be following the will. The right approach depends on the circumstances and evidence. Clear guidance can help you understand your options before deciding how to proceed.

For advice about an executor or estate administration, contact Feltons Solicitors LLP.

Choose a clear next step

Understanding what happens if an executor doesn’t follow the will can help you define the issue, but your next step should focus on the outcome you need. Decide whether you want clarity about a particular decision, completion of an outstanding responsibility or protection of an estate asset. A clear objective makes it easier to explain what needs attention and what resolution would address it.

Family relationships can make estate disagreements difficult to raise, especially when the executor is close to other beneficiaries. Keep communication measured and focused on the estate, rather than personal blame. If discussion has become unproductive, legal advice can help you assess the available options and choose a proportionate way forward.

Discuss your estate concerns with Feltons Solicitors LLP. A considered next step can help you move forward with greater confidence.

Frequently Asked Questions

Can I Claim Against an Executor if They Do Not Follow the Will?

Yes, you may be able to claim if an executor’s breach causes loss to the estate or beneficiaries. A claim may still be considered if the executor’s conduct was a mistake, but evidence matters: identify the decision, its effect and the loss you say followed. For example, records of an unauthorised payment may help explain the concern. The court may consider whether the executor acted honestly and reasonably.

Can I Remove an Executor From a Will?

A court can remove an executor and appoint a replacement where the evidence supports intervention. Relevant circumstances may include misconduct, incapacity or persistent disagreement that obstructs estate administration. Removal is not a way to change the deceased’s choice simply because beneficiaries disagree with it. Explain the executor’s conduct, its effect on the estate and why replacing them would help the administration continue.

Can an executor be held personally liable?

Yes. An executor may be personally liable for losses caused to the estate or beneficiaries by failing to meet their responsibilities. Liability is not automatic merely because a beneficiary is unhappy with a decision; the circumstances and resulting loss matter. Even a mistake may lead to a claim. Under section 61 of the Trustee Act 1925, the court may relieve an executor from liability for an honest and reasonable mistake.

How can I deal with an unresponsive executor of a will?

Send a clear written message identifying the estate, your relationship to it and the specific information or action you need. For example, ask whether a particular asset has been valued or a payment has been made. Keep a copy and note when you sent it. If the executor remains unresponsive, this record can help show the court what you requested and how communication broke down.

How do you force an executor to act?

You can ask the court to order an executor to carry out a specific duty, such as applying for probate or distributing estate assets. State precisely what remains undone and support your request with the will, relevant estate records and correspondence. A focused application helps distinguish a genuine failure to act from a disagreement about how the estate should be administered. The court can then consider an order suited to the issue.

What Isn’t an Executor Allowed to Do?

An executor must not rewrite the will, substitute personal preferences for its instructions or unfairly favour one beneficiary. For example, they cannot redirect a gift to themselves simply because they consider the named distribution unfair. They must also preserve estate assets and manage them prudently. An executor’s authority is to administer the estate after death, not to carry out the will while its maker is alive.
Complex Probate Solicitors: Navigating Intricate Estate Administration in 2026

Complex Probate Solicitors: Navigating Intricate Estate Administration in 2026

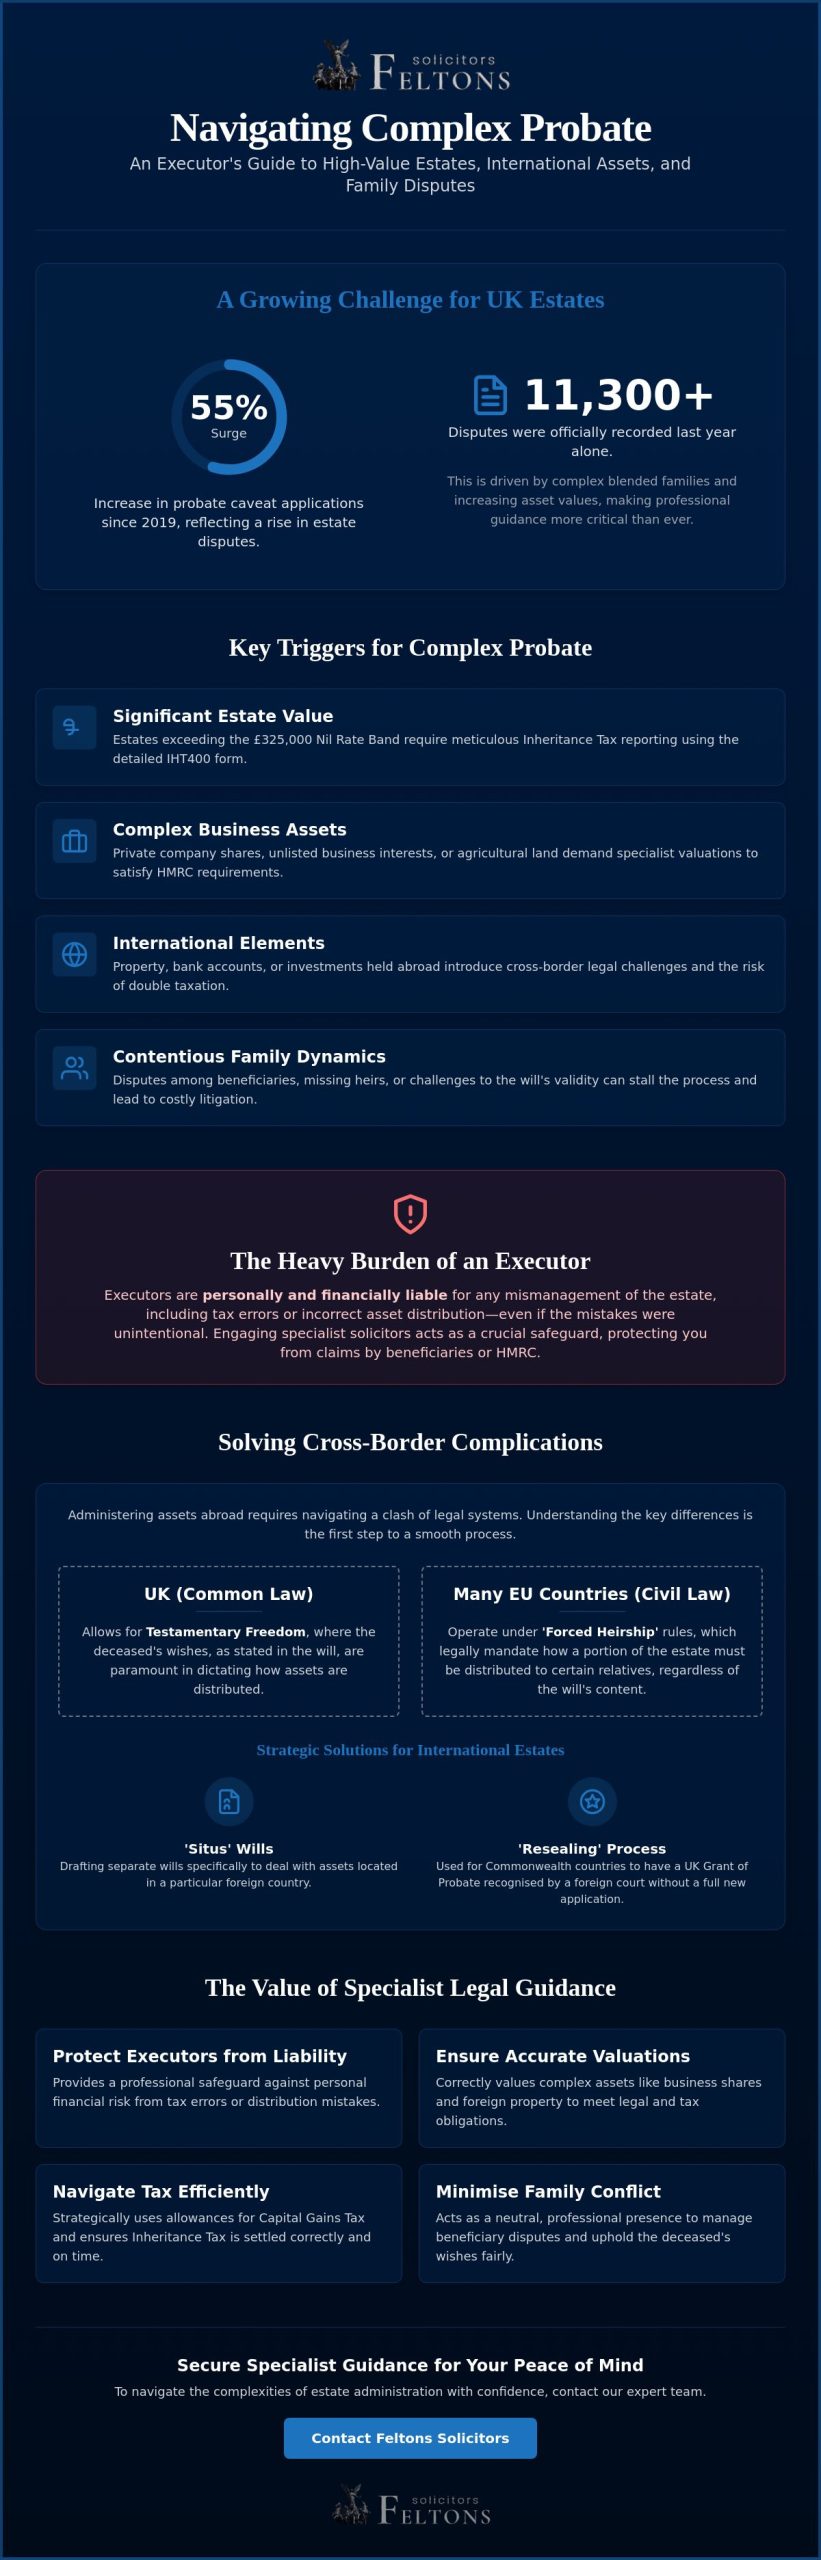
Did you know that probate caveat applications have surged by 55% since 2019, with over 11,300 disputes recorded last year? This sharp rise reflects a modern landscape where blended families and rising asset values make estate administration increasingly contentious. When you’re managing an estate that spans international borders or involves significant business interests, the margin for error is slim and the pressure is immense.

It’s natural to feel concerned about the personal liability that comes with potential tax errors or the emotional strain of family disagreements. You want to ensure that every asset is accounted for and every beneficiary is treated fairly, yet the technical hurdles can feel insurmountable. Specialist complex probate solicitors act as a steady, professional presence, taking the weight of these intricate responsibilities off your shoulders whilst providing much-needed clarity.

In this article, you’ll discover how expert legal guidance manages high-value assets and foreign jurisdictions to ensure a seamless probate process. We’ll outline the steps taken to protect you from liability, facilitate efficient asset distribution, and maintain clear communication during what can often be a long and challenging journey.

Key Takeaways

  • Identify the specific triggers that move an estate from standard administration into a complex legal landscape, including technical financial intricacies and multi-jurisdictional assets.
  • Explore the specialised processes required for valuing private business shares and managing the legalities of property held in foreign jurisdictions.
  • Understand how to handle modern family dynamics and potential disputes amongst beneficiaries, ensuring the deceased’s wishes are upheld whilst minimising conflict.
  • Master the financial nuances of the administration period, including the strategic use of Capital Gains Tax allowances and the timely settlement of Inheritance Tax.
  • Discover why engaging complex probate solicitors provides the discreet, high-standard guidance necessary to protect executors from personal liability and ensure a smooth distribution.

Probate is often viewed as a procedural necessity. For many families, however, the Probate process in the UK evolves into a multi-layered legal undertaking. Complexity isn’t merely about the volume of paperwork; it arises when the estate’s composition involves technical, financial, or legal intricacies that exceed the scope of a standard Grant of Representation. Whilst administrative difficulty refers to the time taken to gather assets, complex probate involves navigating conflicting laws, high-stakes valuations, and nuanced tax obligations.

Engaging complex probate solicitors is often the difference between a stalled application and a successful distribution. Standard DIY approaches frequently falter when executors encounter HMRC ‘long-form’ accounts, known as the IHT400. These forms require a level of forensic detail that goes far beyond simple bank balances. They demand precise reporting of lifetime gifts, trust interests, and foreign holdings. Without specialist oversight, the risk of professional negligence or significant tax penalties increases.

Common Triggers for Complex Estate Administration

Several factors can elevate a case into the complex category. Estates exceeding the Nil Rate Band threshold of £325,000, which is currently frozen until April 2031, require meticulous Inheritance Tax reporting. Complexity also spikes when the deceased held unlisted business interests, agricultural land, or private company shares. These assets require specialist valuations to satisfy HMRC requirements. Additionally, the presence of multiple beneficiaries spread across different countries or missing heirs adds a layer of cross-border legal coordination that few executors are equipped to handle alone.

The Legal Responsibility of the Executor

Executors carry a heavy burden. They are personally and financially liable for any mismanagement of the estate, including tax errors or incorrect distributions. This liability remains even if the mistake was unintentional. Professional guidance from complex probate solicitors acts as a safeguard. It protects you from potential claims brought by disgruntled beneficiaries or HMRC. Securing a Grant of Probate is the key to unlocking sophisticated asset classes, yet doing so correctly requires a methodical approach that prioritises legal integrity over speed. Proactive estate planning, including working with a lasting power of attorney solicitor London residents trust, can help reduce the administrative burden placed on executors before probate even begins.

While many associate estate disputes with family disagreements, technical complexity often stems from the nature of the assets themselves. High-value estates frequently involve intricate financial structures, such as Lloyd’s of London memberships or sophisticated trust arrangements, that require a methodical legal approach. Managing these requires more than just administrative diligence; it demands a deep understanding of how different asset classes interact with current Inheritance Tax rules. Expert complex probate solicitors provide the necessary oversight to ensure that valuations are accurate and that all available reliefs are fully utilised.

International Assets and Cross-Border Probate

Modern estates are rarely confined to a single country. When a deceased person held property, bank accounts, or investments abroad, the administration process must account for the clash between different legal systems. Common Law jurisdictions, like the UK, generally allow for testamentary freedom, whereas many Civil Law countries in Europe operate under ‘forced heirship’ rules. These rules can dictate exactly how assets must be distributed, regardless of what the will says.

Coordinating this requires a strategy involving ‘Situs’ wills, which are documents drafted specifically to deal with assets in a particular jurisdiction. For assets held within the Commonwealth, we often use the ‘resealing’ process, which allows a UK Grant of Probate to be recognised by a foreign court without a full new application. Working alongside international legal counsel is vital to avoid the pitfalls of double taxation and to ensure that foreign grants of probate are obtained efficiently. If you are managing a portfolio with multi-jurisdictional reach, our team offers the specialised probate and estate planning support required to navigate these global requirements.

Business Interests and Agricultural Property Relief

For business owners and landowners, the stakes are particularly high. The valuation of private company shares, intellectual property rights, and agricultural land is a forensic exercise that HMRC scrutinises closely. A significant change occurring in 2026 is the new cap on Business Property Relief (BPR) and Agricultural Property Relief (APR). From 6 April 2026, the 100% relief is capped at a combined £2.5 million per person; any value above this threshold will only attract 50% relief. This makes the role of complex probate solicitors even more critical in ensuring business continuity whilst the estate is being settled.

Business Property Relief can potentially reduce Inheritance Tax by 50% or 100% depending on the asset type. Identifying which assets qualify and ensuring they meet the strict ‘trading’ criteria is essential for protecting the estate’s value. We focus on providing pragmatic advice that keeps the business operational, preventing the forced sale of assets to cover tax liabilities that could have been mitigated through careful administration.

For executors managing Australian-based entities, integrating small business advisory services Perth into the broader strategy helps maintain profitability and personal freedom for the new owners during the transition.

Addressing Contentious Probate and Modern Family Dynamics

Estate administration is rarely just a matter of calculating figures and filing forms. The human element often presents the greatest challenge. Modern family structures, including cohabitees, step-children, and multiple marriages, frequently result in competing claims that a standard probate process cannot resolve. Under the Inheritance (Provision for Family and Dependants) Act 1975, certain individuals can claim they haven’t been left reasonable financial provision. Managing these sensitivities requires complex probate solicitors who act as both technical experts and calm, steady mediators.

Our approach prioritises pragmatism. We understand that behind every legal dispute is a family seeking closure and fairness, and for those with interests spanning multiple regions, it is often helpful to explore family law with specialists such as Israel Cross Border Law Firm. By addressing potential conflicts early, we help executors navigate the emotional weight of their role whilst ensuring the estate remains protected from the high costs of prolonged litigation.

Contesting the Validity of a Will

Challenges to a will’s validity usually arise from three specific areas: lack of testamentary capacity, undue influence, or improper execution. Proving or defending these claims requires forensic evidence gathering, including medical records and witness statements. A critical first step in this process is finding a will that represents the deceased’s final, uncoerced intentions. Complex probate solicitors provide a sophisticated guide through this evidence, ensuring that the deceased’s true wishes are upheld and that the estate is not depleted by meritless challenges.

Resolving Conflict Amongst Executors and Beneficiaries

Friction isn’t always between beneficiaries; it often occurs amongst the executors themselves. If an executor fails in their duties or acts in their own interest, the law provides a path for their removal through a court application. However, we believe that transparency is the most effective defence against suspicion. By providing meticulous estate accounts and clear communication, executors can demonstrate they are acting fairly and in accordance with their legal obligations.

When disputes delay the sale of assets, such as a family home, the financial implications can be significant. Delays can impact the eventual Capital Gains Tax on inherited property, as the market value may shift between the date of death and the date of sale. We utilise mediation as a discreet tool for family reconciliation, aiming to reach a settlement that avoids the public nature and stress of a full court hearing. This methodical flow ensures that the distribution of assets remains as efficient and harmonious as possible.

Complex Probate Solicitors: Navigating Intricate Estate Administration in 2026

Managing the Financial Burden: Inheritance Tax and Capital Gains

The financial aspects of estate administration often present the most significant pressure for executors. One of the most challenging requirements is the necessity to pay at least a portion of the Inheritance Tax (IHT) bill before the Grant of Probate is even issued. This creates a liquidity challenge, as many assets remain frozen until the grant is secured. Expert complex probate solicitors play a vital role here, helping executors identify sources of funding, such as the Direct Payment Scheme, to settle tax liabilities without personal financial strain.

HMRC maintains rigorous compliance checks for high-value estates, often scrutinising valuations and lifetime gifting history. Accuracy is paramount. During the period of administration, executors must also manage Capital Gains Tax (CGT) on any assets that increase in value between the date of death and the date of sale. Utilising the estate’s specific CGT allowance requires a methodical approach to timing and asset disposal to ensure the maximum value remains for the beneficiaries.

Inheritance Tax (IHT) Efficiency Strategies

Strategic tax planning doesn’t necessarily end when a person passes away. We focus on applying for all available reliefs, including transferable Nil Rate Bands and Residence Nil Rate Bands, which can collectively shield up to £1 million for a married couple. Lifetime gifts made within seven years of death must be meticulously accounted for, as they can significantly impact the tax threshold through ‘taper relief’. A Deed of Variation can be used post-death to improve tax efficiency for beneficiaries by effectively rewriting the will to redirect assets in a more tax-advantageous manner. These sophisticated tools require precise legal drafting to satisfy HMRC’s strict criteria.

Trust Administration and Asset Protection

The role of family trusts is central to many complex estates. Often, these structures ‘crystallise’ upon the death of the settlor, requiring immediate and expert management to protect the legacy for future generations. There is a profound interaction between long-term estate planning and the eventual probate outcome; a well-structured trust can simplify the process, but only if the trustees understand their ongoing legal obligations.

We often see a clear distinction between the effectiveness of professional trustees versus lay trustees. Whilst a family member may have the best intentions, they may lack the technical knowledge to manage complex long-term obligations, such as tax filings and investment oversight. Complex probate solicitors provide the steady guidance needed to ensure trusts remain compliant and continue to serve their intended purpose. If you are concerned about the tax implications or trust management of a high-value estate, our team provides the professional tax and probate support necessary to safeguard your interests.

Why Choose Feltons Solicitors for Complex Probate?

Choosing the right legal partner for an intricate estate is a decision that impacts both the financial outcome and your personal peace of mind. Unlike high-volume firms where cases are often processed as mere numbers, our boutique approach ensures that your matter receives the focused attention of senior legal experts. We believe that professional authority and empathetic reassurance are not mutually exclusive. As complex probate solicitors, we provide a sophisticated level of care that prioritises your specific needs whilst maintaining the highest standards of technical precision. Our ‘people-first’ philosophy means we never lose sight of the human impact behind the legal administration, offering a steady hand when family dynamics or financial pressures feel overwhelming.

We pride ourselves on delivering pragmatic, plain-English advice. In a world of dense legalese, we choose clarity. This commitment to transparent communication allows us to handle both national and international matters with discreet professional integrity, ensuring that executors feel empowered rather than confused. Whether you’re managing multi-jurisdictional assets or navigating the new 2026 tax caps, our team provides the worldly experience necessary to protect your interests.

A Tailored Approach to Estate Administration

Every estate we manage is unique, requiring a strategy that is as individualised as the legacy it represents. We organise a bespoke plan for each client, ensuring that the nuances of business assets, agricultural land, or foreign property are handled with sound judgment. During high-stress legal periods, we act as a calm, steady presence. Our focus isn’t solely on the technicalities; we remain mindful of the human impact of our work, ensuring that every beneficiary feels supported and informed throughout the process. By acting as your complex probate solicitors, we bridge the gap between established heritage and forward-thinking methodology.

Moving Forward with Confidence

The first step in resolving a complex administration is a comprehensive estate review. During an initial consultation, we’ll discuss the technical hurdles you’re facing and provide a clear outline of the necessary steps. You can expect transparent communication regarding timelines and the frequency of updates, ensuring you’re never left in the dark. We understand that executors often feel the weight of personal liability, which is why our methodical flow is designed to provide security and comprehensive care. Contact us today for a discreet discussion about your probate needs and discover how our expertise can provide the protection and efficiency you require.

Securing Your Legacy with Professional Integrity

Managing an intricate estate involves more than just administrative diligence; it requires a sophisticated understanding of cross-border laws and evolving tax thresholds. You’ve seen how technical hurdles, such as valuing private business shares or resolving modern family disputes, can quickly complicate the probate process. By addressing these challenges with a methodical and proactive strategy, you can protect the estate’s value and ensure a harmonious distribution for all beneficiaries.

Since 2010, Feltons Solicitors has provided the discreet, senior-level attention that high-value estates demand. Our boutique approach means you’ll always have direct access to experienced advisors who prioritise personal connection over volume. As complex probate solicitors, we’re dedicated to delivering pragmatic, plain-English advice that simplifies the most daunting legal landscapes. We invite you to speak with our complex probate experts at Feltons Solicitors for a tailored review of your circumstances. You don’t have to carry the burden of executor liability alone. With the right guidance, even the most intricate administration can be managed with quiet confidence and success.

Frequently Asked Questions

How long does complex probate usually take in the UK?

Complex probate typically takes between 12 and 18 months to conclude. Whilst a standard estate might be settled much sooner, the presence of foreign property or unlisted business interests requires additional time for forensic valuations and international tax clearances. Each jurisdiction involved adds its own procedural layer, and if the estate is particularly intricate, the process can extend beyond two years to ensure every asset is correctly accounted for.

Can an executor be held personally liable for mistakes in a complex estate?

Executors carry full personal financial liability for any mismanagement of the estate. This liability remains even if the error was unintentional, such as a miscalculation of Inheritance Tax or an overlooked beneficiary. Engaging complex probate solicitors provides a layer of protection, as professional oversight ensures that all legal and fiscal obligations are met, significantly reducing the risk of personal claims being brought against you.

What makes a probate case ‘contentious’ rather than just ‘complex’?

A case is defined as ‘complex’ when it involves technical or financial hurdles, whereas ‘contentious’ probate refers to active legal disputes amongst parties. Complexity often stems from multi-jurisdictional assets or sophisticated tax structures that require specialist handling. Contentiousness arises when the validity of a will is challenged or when beneficiaries disagree on the distribution. It’s common for high-value estates to be both complex and contentious simultaneously.

How much do complex probate solicitors charge for their services?

The fees for administering an intricate estate are determined by the specific nature of the assets and the time required to resolve technical hurdles. Most complex probate solicitors provide a tailored estimate following an initial review of the estate’s composition. This ensures that the fee reflects the level of specialist expertise required, whether that involves negotiating with foreign tax authorities or managing private company valuations during the administration period.

What happens if there are assets located in multiple countries?

Assets located in multiple countries usually require a coordinated approach across several legal systems. For property held in Commonwealth countries, the UK Grant of Probate can often be ‘resealed’ by the local court to gain recognition. In other jurisdictions, you may need to obtain a separate grant of probate entirely. We coordinate with local legal counsel to manage these requirements and prevent the estate from being taxed twice on the same assets.

Can I change solicitors if my current probate process is stalled or becoming too difficult?

You have the legal right to transfer your file to a different firm at any stage of the probate process. If you feel that your current solicitors lack the specialist knowledge required for intricate financial matters, or if communication has become infrequent, you can request a transfer. A fresh perspective from a boutique firm often provides the necessary momentum to resolve long-standing technical issues and bring the administration to a close.

What is a Deed of Variation and when should it be used in complex probate?

A Deed of Variation is a legal instrument used to alter the distribution of an estate after someone has died. It must be executed within two years of the death and requires the consent of all affected beneficiaries. This tool is frequently utilised in complex administration to improve tax efficiency or to move assets into a trust, ensuring the long-term protection of the family legacy for future generations.

How do business assets affect the timeline for receiving a Grant of Probate?

Business assets often extend the timeline for securing a Grant of Probate because they require forensic valuation to satisfy HMRC. Specialist valuers must assess the company’s worth and determine eligibility for Business Property Relief (BPR) before the tax accounts are submitted. This detailed valuation process can add several months to the initial stages of administration, particularly if the business structure is sophisticated or involves intellectual property rights. Ensuring that legal arrangements such as a lasting power of attorney solicitor London professionals recommend are in place before death can help streamline the handover of business management responsibilities during this period.