Divorce Financial Settlements: The Definitive Guide to Protecting Your Assets in 2026

Divorce Financial Settlements: The Definitive Guide to Protecting Your Assets in 2026

Finalising your divorce dissolves your legal marriage, but it does not extinguish your financial liabilities. Without a sealed court order, an ex-spouse can pursue claims against your property, pension wealth, or business equity years into the future. When speaking with Feltons Solicitors LLP or specialist family practitioners, people often share the same justified anxiety: the fear of losing assets they spent a lifetime building, alongside confusion over why a divorce decree alone leaves them unprotected.

You deserve clarity and certainty as you plan your next chapter. This guide explains how courts assess fairness under English law, how matrimonial property is divided, and how to achieve an enforceable clean break settlement that permanently safeguards your personal wealth. From the division of substantial pension pots to the practical benefits of resolving disputes outside a contentious courtroom, here is how you can resolve your financial arrangements calmly, pragmatically, and decisively.

Key Takeaways

  • Securing a court-approved consent order is the only method to achieve a true clean break and permanently terminate your ex-spouse’s financial claims.
  • Judges evaluate the division of matrimonial property using statutory Section 25 criteria, prioritising the housing needs of minor children above equal sharing.
  • Accurately dividing complex holdings like private company shares, high-value pensions, and property portfolios requires specialist valuation methods to prevent post-separation tax penalties.
  • Partnering with experienced divorce financial settlement solicitors london ensures full financial disclosure via Form E, protecting personal wealth from future claims without unnecessary court conflict.
  • Proactive negotiation and alternative dispute resolution offer a discreet, cost-effective pathway to resolve finances while preserving long-term estate planning integrity.

The Fundamentals of a Financial Settlement: Securing a Clean Break

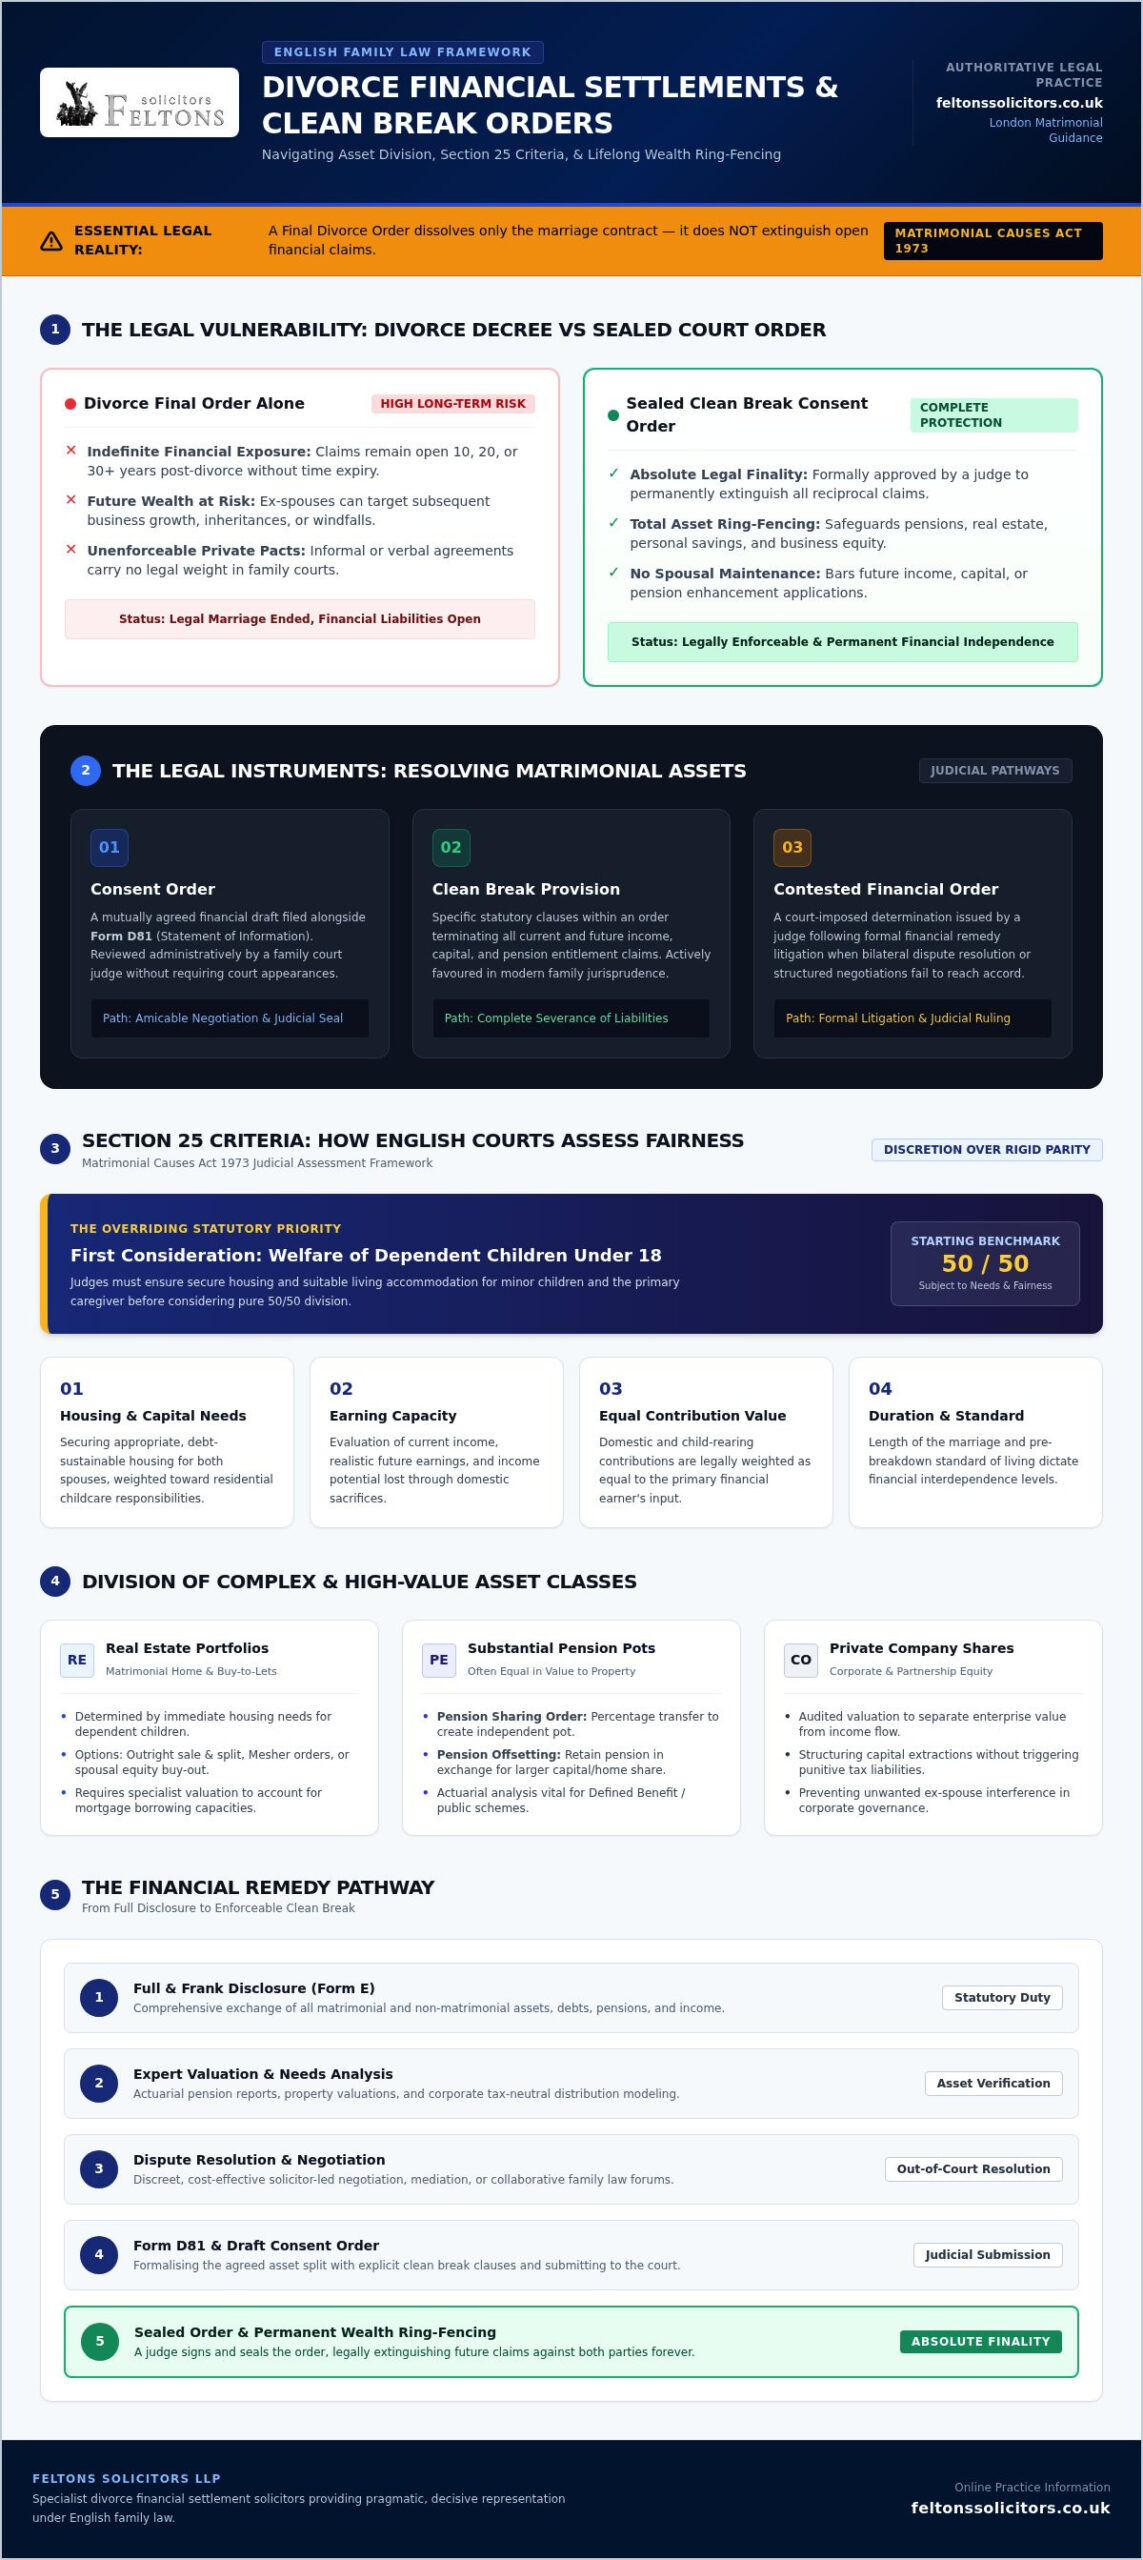
A matrimonial financial settlement legally resolves the division of capital, real estate, pension entitlements, and ongoing income following the breakdown of a marriage. Many individuals mistakenly assume that obtaining a final divorce order concludes their financial ties. In reality, ending the legal marriage leaves every financial claim open between former spouses. A financial remedy order approved by the court provides absolute legal finality.

Informal arrangements or verbal pacts offer no lawful protection. Even if you draft a private written contract, it remains unenforceable within family law jurisdiction without judicial endorsement. Under the Matrimonial Causes Act 1973, the family court retains overarching supervisory power over marital property. Judges must review every proposed split to confirm it is fair, reasonable, and capable of satisfying both parties’ independent housing and living needs.

Why Finalising Your Divorce Does Not End Financial Claims

A conditional order and subsequent final order dissolve only the marriage contract. They do not dismiss statutory financial rights. Without an explicit, legally binding dismissal order, your former spouse can lodge claims against your wealth ten, twenty, or thirty years later. This exposure applies to future inheritances, lottery windfalls, and post-divorce business equity. Securing a sealed court order remains the only way to achieve authentic, permanent independence.

Consent Orders Versus Financial Remedy Orders: Understanding the Instruments

Choosing the correct legal mechanism depends entirely on whether you and your spouse can reach an agreement. Working with specialist divorce financial settlement solicitors london allows you to pursue an amicable resolution first, converting negotiations into a watertight judicial order.

  • Consent Orders: A mutually agreed draft order submitted alongside Form D81, detailing current and proposed asset distributions. A judge reviews this paperwork administratively without requiring either party to attend court.
  • Contested Financial Remedy Orders: Court-imposed determinations issued by a judge following formal litigation when private negotiations fail.
  • Clean Break Provisions: Clauses within an order that permanently terminate all capital, income, and pension claims, ensuring neither party can request spousal maintenance in the future.

While ongoing spousal maintenance suits situations with significant income disparities or young children, modern family jurisprudence actively favours clean break outcomes wherever capital resources suffice. Experienced divorce financial settlement solicitors london construct these arrangements to balance immediate liquidity with comprehensive long-term asset ring-fencing.

Section 25 Criteria: How Family Courts Assess Fair Asset Division

When determining financial settlements under the Matrimonial Causes Act 1973, English courts operate from an initial benchmark of equal division. However, this equal starting point frequently yields to ensure equitable living outcomes for both individuals. As set out in the GOV.UK guidance on dividing money and property, the primary duty of the court is the welfare of any dependent child under eighteen. Section 25 gives judges broad discretion to achieve substantive fairness over mathematical parity.

To establish what is truly fair, judges examine each family’s unique economic fabric rather than applying a rigid numerical formula. Instructing experienced divorce financial settlement solicitors london helps ensure your position is framed persuasively against every statutory consideration.

Assessing Needs, Earning Capacity, and Standards of Living

The court evaluates each party’s capital, current income, and realistic future earning capacity. Where one spouse paused a lucrative career to handle domestic care or child-rearing duties, the law recognises that contribution as equal to that of the primary financial earner. Factors that directly shape court awards include:

  • Housing and Capital Requirements: Securing suitable, secure accommodation for children and the primary residential parent.
  • Duration of Marriage and Age: Longer marriages naturally foster deeper financial interdependence, whereas shorter unions without children often justify a swift return to pre-marital status.
  • Standard of Living: The lifestyle enjoyed during the marriage serves as a guiding guidepost, tempered by the economic reality of funding two separate households from a single pool of wealth.

Matrimonial Versus Non-Matrimonial Property

Family law draws a sharp distinction between matrimonial assets generated through joint efforts and non-matrimonial holdings brought into the union. Matrimonial assets typically include the family residence, joint savings, business equity created during the partnership, and pensions built during the cohabitation period. These are subject to the sharing principle.

Conversely, non-matrimonial property encompasses pre-owned assets, inheritances received independently, and gifts from external family members. Following landmark Supreme Court precedent, non-matrimonial wealth is generally insulated from sharing unless required to meet the other party’s basic reasonable needs. If you need bespoke guidance on structuring your holdings or navigating property adjustments, consulting specialists at Feltons Solicitors LLP provides the clarity needed to protect your legitimate entitlements.

Division of Complex Wealth: Real Estate, Pensions, and Private Businesses

High-value matrimonial estates present unique structural hurdles. When marital wealth spans substantial real estate portfolios, defined benefit pension funds, and private commercial enterprises, applying a clean division requires deep technical precision. Rather than treating all capital uniformly, courts and instructing divorce financial settlement solicitors london must evaluate the distinct liquidity, taxation, and long-term utility of each holding.

The Matrimonial Home: Mesher Orders, Buyouts, and Immediate Sale

The matrimonial residence carries intense personal sentiment alongside substantial equity. Couples generally face three practical routes to resolve ownership:

  • Immediate Open-Market Sale: Realising total net proceeds to fund the independent rehousing of both individuals.
  • Equity Buyout: One spouse refinances the property to purchase the other’s legal share and secure a release from mortgage covenants.
  • Mesher Orders: Postponing the sale of the family home until a triggering event occurs, such as the youngest child completing secondary education or reaching age eighteen.

Executing an equity transfer or property sale demands meticulous legal implementation. Coordinating your family settlement alongside an experienced residential property law firm guarantees that deeds, Land Registry charges, and conveyancing processes align with the court order.

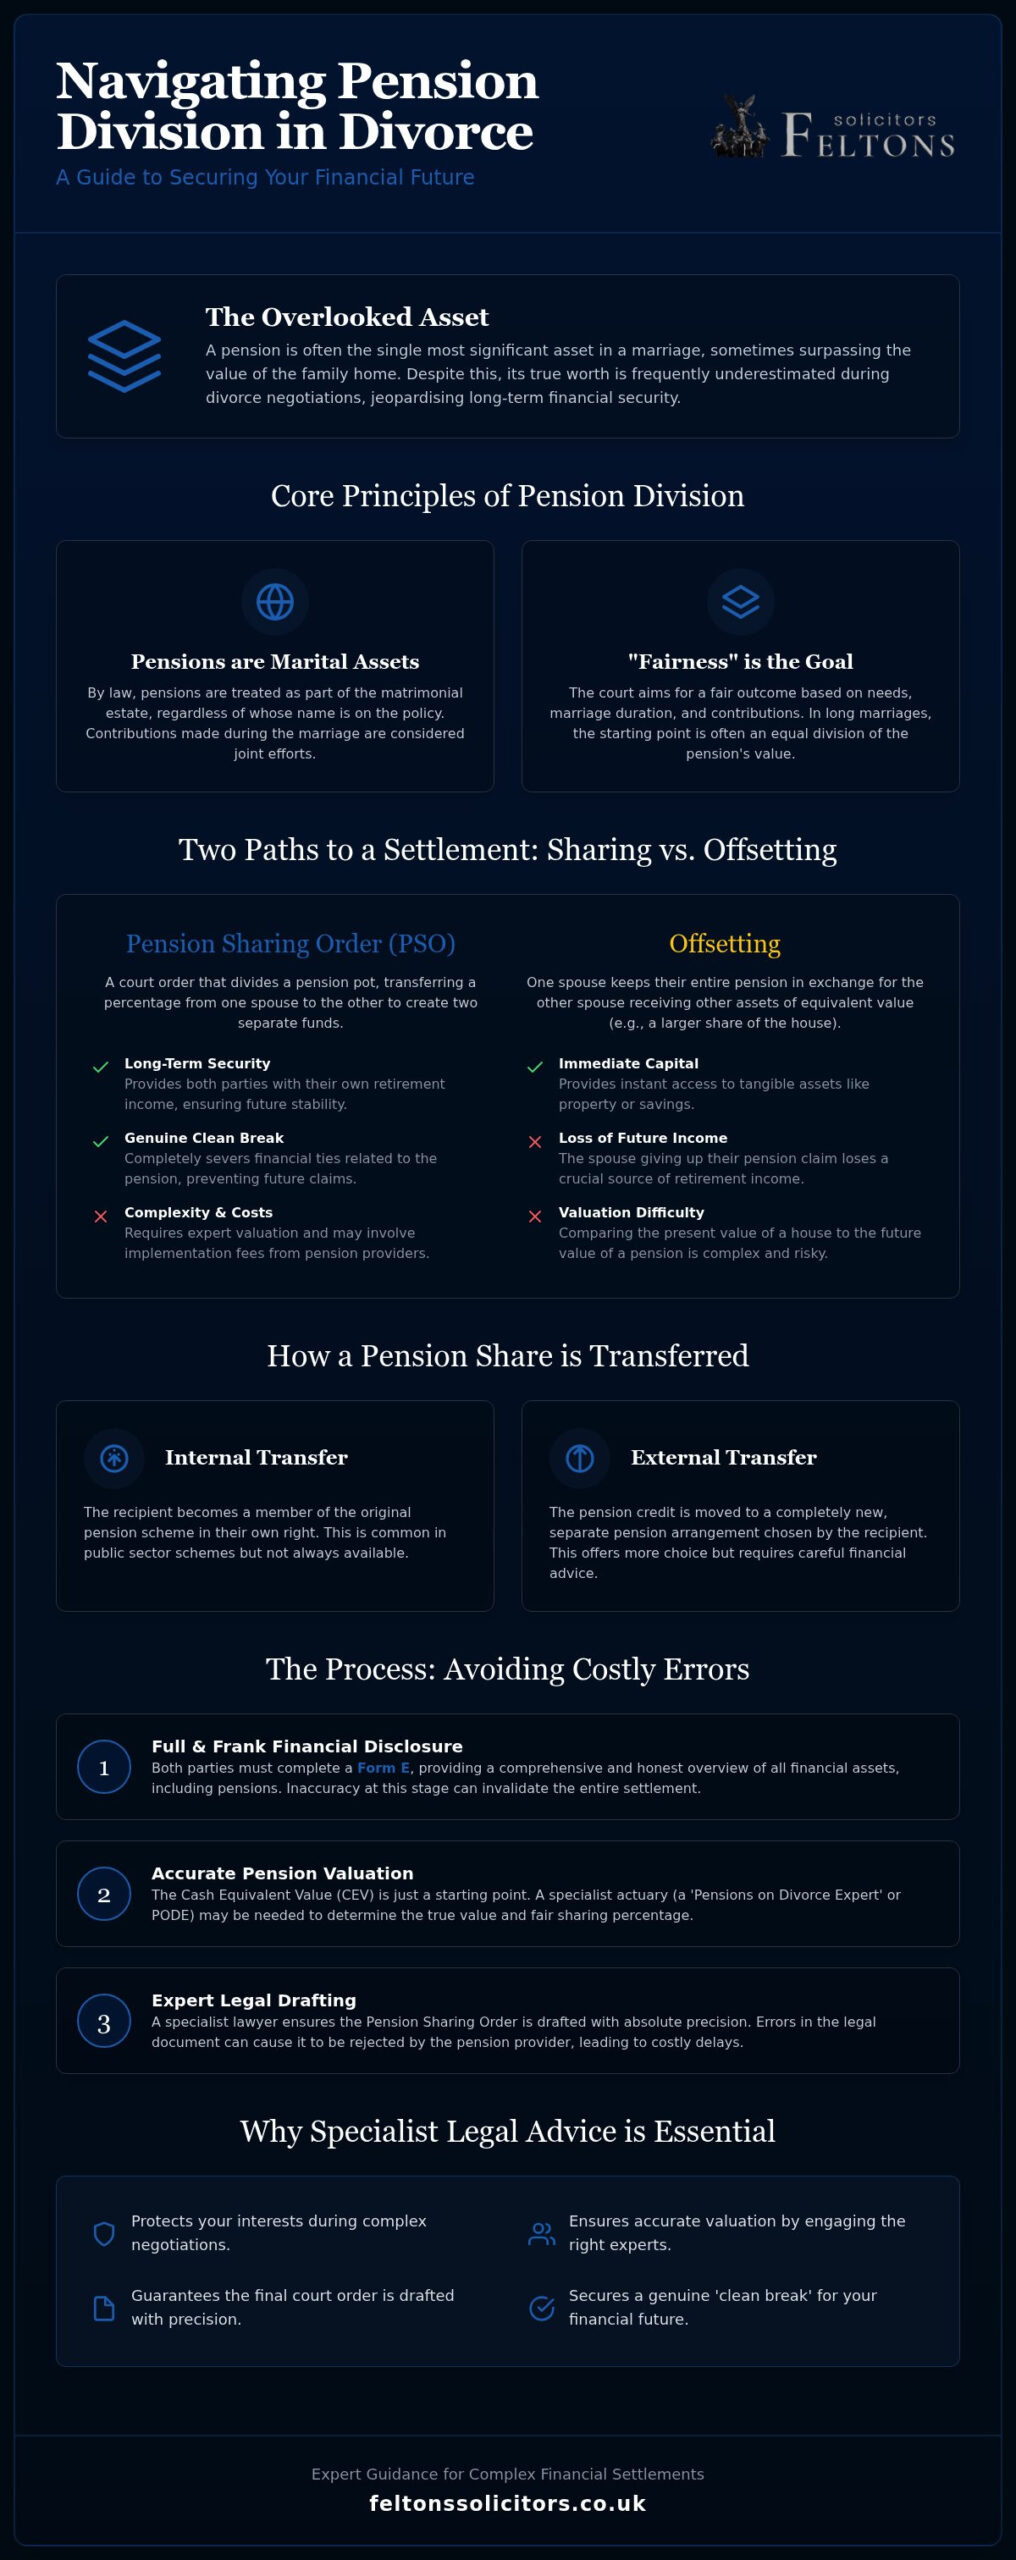
Pensions on Divorce: Sharing Orders Versus Capital Offsetting

Pension funds frequently equal or eclipse the capital tied up in real estate. Despite this, they remain widely overlooked during direct negotiations. Under current Pension Advisory Group guidelines, standard Cash Equivalent Transfer Values (CETVs) often fail to reflect the true value of defined benefit or public sector schemes. Specialist actuarial reports are vital to achieve genuine parity of retirement income.

Parties typically divide retirement assets through Pension Sharing Orders, which carve out an exact percentage of a fund into a new, independent plan for the receiving spouse. Alternatively, pension offsetting permits one spouse to retain greater real estate equity or liquid savings in exchange for waiving rights to the other’s pension pot. As highlighted in the GOV.UK guide to dividing money and property on divorce, older Pension Attachment Orders have fallen out of common practice because they tie your financial future to your former spouse’s eventual retirement date.

Valuing and Protecting Private Business Interests and Company Shares

Private company shareholdings demand forensic evaluation. Judges avoid dismantling viable commercial ventures to satisfy personal capital divisions. Jointly instructed forensic accountants evaluate sustainable earnings, net asset values, and latent corporation or capital gains tax liabilities. Settlement structures must protect commercial cash flow, using staged lump sums, dividend extractions, or structured share buybacks rather than forcing an immediate operational sale.
Divorce Financial Settlements: The Definitive Guide to Protecting Your Assets in 2026

Securing an enforceable financial settlement demands a structured, transparent legal procedure. Whether resolving arrangements privately or through judicial intervention, the process follows a predictable sequence. Completing these formal stages protects your capital while eliminating the risk of future legal challenges.

  1. Exchange Formal Disclosure: Both spouses complete Form E, setting out their worldwide capital, liabilities, business assets, and pensions with documentary proof.
  2. Instruct Joint Experts: Appoint independent specialists to value shared real estate, unquoted business shares, and complex defined benefit pensions.
  3. Conduct Structured Negotiations: Explore constructive proposals through solicitor correspondence, mediation, or private dispute resolution sessions.
  4. Ratify the Agreement: Draft a formal consent order and submit it to the court alongside Form D81 for final judicial sealing.

The Importance of Full and Frank Financial Disclosure

Every matrimonial settlement rests upon absolute financial honesty. You must disclose every domestic bank balance, offshore holding, share option, and trust benefit. Attempting to conceal wealth or understate company valuations carries severe legal consequences. Under long-standing precedent, the court will readily overturn sealed orders where a spouse committed fraudulent or deliberate non-disclosure. Judges also impose punitive adverse costs orders against deceptive parties. Engaging a qualified divorce and financial arrangements lawyer ensures your financial statement is meticulously prepared, defending you against unfair scrutiny while actively uncovering any hidden spousal wealth.

Out-of-Court Resolutions: Mediation, Collaborative Law, and Private FDRs

Resolving your finances does not require an acrimonious courtroom battle. Before issuing proceedings, parties must ordinarily attend a Mediation Information and Assessment Meeting (MIAM) to explore constructive dialogue. For complex or high-value estates, Private Financial Dispute Resolution (Private FDR) hearings have become the preferred option. A hired specialist barrister or retired judge evaluates the evidence and delivers an evaluative settlement recommendation in complete privacy. This private forum avoids the lengthy delays and public disclosure associated with open family courts.

Navigating Court Proceedings: First Directions and Final Hearings

When alternative methods cannot resolve entrenched disputes, the court timetable governs proceedings:

  • First Directions Appointment (FDA): The preliminary procedural hearing where a judge reviews disclosure, orders questionnaire answers, and authorises expert valuations.
  • Financial Dispute Resolution (FDR): The core negotiation hearing where the presiding judge offers an informal view on the likely outcome, strongly urging parties to settle without trial.
  • Final Contested Hearing: A formal trial where witnesses undergo cross-examination and the judge imposes a legally binding financial order.

If you face complex negotiations or wish to initiate an orderly asset split, instruct reputable divorce financial settlement solicitors london to protect your wealth. Reach out directly to Feltons Solicitors to discuss your circumstances with our discreet private client team.

Resolving complex marital assets requires steady judgment alongside technical mastery. Retaining specialist legal counsel ensures your financial position remains robustly insulated without escalating interpersonal tension. A comprehensively drafted financial agreement does far more than resolve present-day division; it protects your future wealth, insulates commercial enterprise, and preserves inheritance for children across generations.

Decisive advice taken early in the separation process brings profound relief. It clarifies enforceable statutory rights, establishes realistic expectations, and replaces emotional panic with orderly strategy. Instructing top-tier divorce financial settlement solicitors london ensures that every settlement term is framed to deliver complete, permanent security.

Aligning Property, Wills, and Estate Planning After Separation

A financial separation cannot occur in an administrative vacuum. Comprehensive wealth protection demands synchronising your family law arrangements with property ownership changes and succession plans. Key legal steps to undertake alongside your financial agreement include:

  • Severing the Joint Tenancy: Converting joint ownership of the matrimonial property into a tenancy in common prevents your share from passing automatically to your estranged spouse under survivorship rules if you die before the divorce finalises.
  • Executing an Immediate Will Update: Separation alone does not alter the provisions of an existing will. Until a final divorce order is sealed, an estranged spouse retains their legal status as a primary beneficiary unless you rewrite your testamentary documents.
  • Revising Beneficiary Nominations: Updating death-in-service benefits and pension expression-of-wish forms ensures accumulated funds flow directly to your intended recipients.

Coordinating with our private client team on your broader estate planning needs guarantees that newly negotiated capital distributions remain fully protected against future tax burdens or inheritance disputes.

Choosing a Pragmatic and Authoritative Legal Advocate

The solicitor you choose fundamentally shapes the tone and efficiency of your separation. While high-volume practices often adopt aggressive stances that inflate costs and prolong disputes, a boutique law firm prioritises tailored personal attention, strict discretion, and pragmatic dispute resolution. You need an advisor who pairs unflinching resolve to protect your balance sheet with a commitment to resolving disagreements outside contentious courtrooms whenever feasible.

Early consultation with dedicated divorce financial settlement solicitors london gives you the strategic foundation required to negotiate with quiet confidence. Taking control of your assets today ensures your post-divorce future begins on solid, independent ground.

Taking Confident Steps Towards Lasting Financial Independence

Achieving a fair matrimonial settlement is fundamentally about protecting your future autonomy. While a final divorce order dissolves the marriage, only a court-sealed consent order provides absolute finality through an enforceable clean break. Whether unravelling complex real estate holdings, valuing private company shares, or dividing pensions, precision and transparent financial disclosure remain paramount. Engaging reputable divorce financial settlement solicitors london ensures that your hard-earned assets receive the meticulous protection they require.

Founded in 2010, Feltons Solicitors combines proven expertise in high-stakes financial remedies with cross-practice capabilities in property conveyancing and estate planning. Our boutique practice prioritises discreet negotiation and constructive dispute resolution outside contentious court settings, providing tailored personal care at every stage. Arrange a confidential consultation with Feltons Solicitors today to safeguard your wealth and step forward into your next chapter with complete clarity.

Frequently Asked Questions

Can my spouse claim money or assets acquired after we separated?

Yes, your former spouse can make a financial claim against assets you acquire after separating, provided you have not obtained a sealed clean break order. While judges distinguish between joint marital wealth and post-separation accrual, non-matrimonial gains remain vulnerable if your ex-spouse has unmet housing or maintenance needs. Obtaining formal advice from divorce financial settlement solicitors london ensures your post-separation income and newly acquired property remain protected against delayed claims.

Is a divorce financial settlement automatically fifty-fifty in England and Wales?

No, a financial settlement is not automatically split fifty-fifty. While English law treats equality as an initial starting point, judges depart from an even division to achieve genuine fairness. The primary concern is always meeting the reasonable housing and income needs of dependent children and their primary caregiver. Disparities in earning capacity, marriage length, and health frequently justify an unequal asset distribution in favour of the financially weaker party.

What happens if my former partner refuses to disclose all their financial assets?

Both parties have an absolute legal duty to provide full and frank financial disclosure. If your partner hides accounts, conceals business interests, or refuses to complete Form E, the court can issue penal orders compelling disclosure. Judges often draw adverse inferences against uncooperative spouses, assuming they hold the suspected wealth. The court may also order them to pay your legal costs or overturn any fraudulent agreement reached without transparency.

Do I need a financial consent order if we already agree on asset division?

Yes, an informal agreement holds no binding legal power in family court. Even if you divide property and savings amicably, either spouse can resurrect financial claims decades later without a court-approved order. Drafting a formal consent order and submitting it alongside Form D81 turns your mutual arrangement into a legally enforceable clean break. Instructing divorce financial settlement solicitors london ensures the document is watertight and properly sealed by a judge.

How are pensions divided during a divorce settlement?

Pensions are typically divided using Pension Sharing Orders, which transfer a designated percentage of one spouse’s pension fund into a separate scheme for the other. Alternatively, pension offsetting allows one party to retain more home equity or savings instead of claiming retirement funds. Courts follow Pension Advisory Group guidance, instructing independent actuaries on complex defined benefit schemes to ensure the settlement achieves genuine equality of future retirement income.

Can a finalised financial consent order ever be overturned or reopened?

A finalised financial consent order is rarely overturned because the court prioritises legal certainty. However, a judge can set an order aside if one party concealed material wealth, committed fraud, or exerted undue coercion. Orders may also be reopened under very narrow circumstances if an unforeseen event occurs shortly after the order that undermines the entire basis of the settlement, such as a sudden death or substantial unexpected windfall.

How long does it typically take to obtain a financial consent order?

If both spouses agree on terms, obtaining a financial consent order usually takes between two and four months. This timeframe covers drafting the agreement, compiling the Form D81 statement, and awaiting judicial review. The paperwork can only be lodged after the court pronounces the conditional divorce order. If negotiations break down and formal court proceedings become necessary, resolving the financial remedy through a full trial can take twelve to eighteen months.
Financial Settlement in UK Divorce: A Comprehensive Guide to Protecting Your Assets (2026)

Financial Settlement in UK Divorce: A Comprehensive Guide to Protecting Your Assets (2026)

Is a standard 50/50 split actually the fairest way to divide your life’s work, or is it simply a convenient starting point that overlooks your specific future needs? You’ve spent years building your assets, and the prospect of losing the family home or seeing a hard-earned pension fund diminished is understandably daunting. It’s entirely natural to feel a sense of anxiety regarding your financial independence whilst navigating the legal system. We understand that you seek a resolution that is both discreet and efficient, prioritising stability over conflict.

This guide provides the expert insight required to secure a favourable financial settlement divorce uk, ensuring your interests remain protected through meticulous disclosure and bespoke negotiation. By moving beyond generic templates, we focus on tailored strategies that reflect the true value of your matrimonial estate. You’ll learn how to achieve a definitive clean break, understand the 2026 court fee updates, and discover how to safeguard your wealth for the years ahead. We offer the steady, professional guidance you need to move forward with absolute confidence and peace of mind.

Key Takeaways

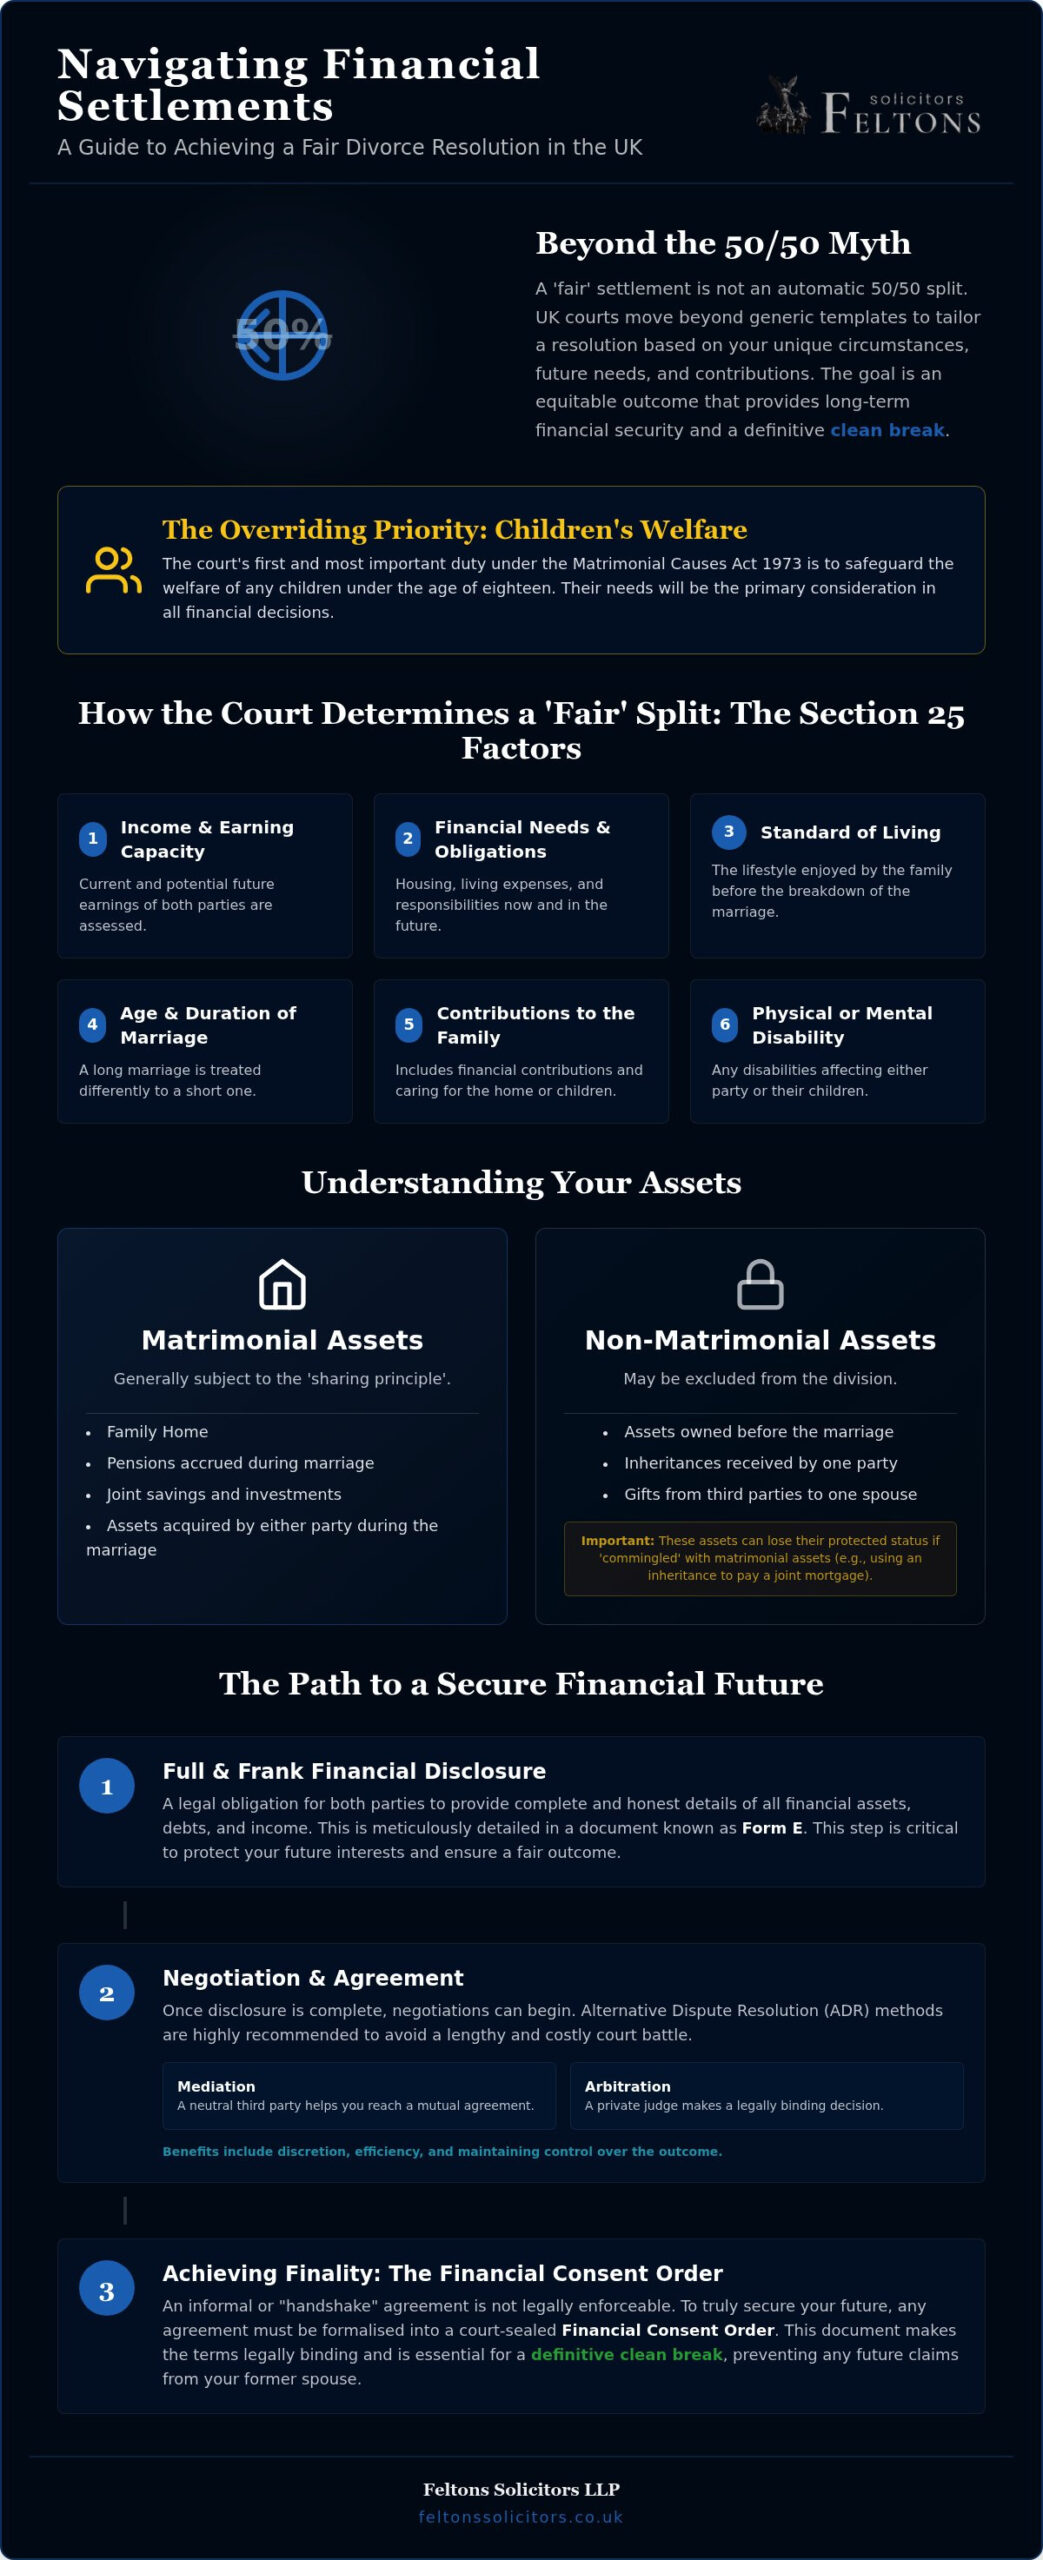
  • Learn how courts apply Section 25 factors to determine a fair financial settlement divorce uk, moving beyond the common misconception of an automatic 50/50 split.
  • Understand your legal obligation for full and frank financial disclosure and how the meticulous completion of Form E protects your future interests.
  • Explore the benefits of alternative dispute resolution methods, such as mediation and arbitration, to reach a discreet agreement whilst avoiding a bitter court battle.
  • Discover why a financial consent order is essential to achieving a definitive clean break and preventing future claims from your former spouse.
  • Gain insight into managing complex or international assets with a calm, steady approach that prioritises your long-term financial security and peace of mind.

Understanding Financial Settlements in UK Divorce Law

A financial settlement in UK divorce is a legally binding agreement that details how assets, property, and income are divided between separating parties. It is a common misconception that the divorce process itself automatically addresses these financial matters. The divorce petition merely ends the legal contract of marriage. In contrast, a financial order provides the finality needed to secure your future. Without a court-sealed order, your former spouse could potentially make a claim against your assets years, or even decades, after the decree is absolute.

Achieving a “clean break” is often the primary objective for those seeking a discreet and efficient resolution. A Clean Break Order dismisses future financial claims, ensuring that any wealth you build post-divorce remains yours alone. Relying on an informal “handshake” agreement is a significant risk. These arrangements lack legal enforceability and offer no protection if circumstances change or relationships sour. Only a court-approved order provides the peace of mind that your financial obligations are truly concluded.

The Legal Framework: Matrimonial Causes Act 1973

The Matrimonial Causes Act 1973 remains the primary authority for a financial settlement divorce uk. When reviewing an application, the court’s first priority is always the welfare of any children under eighteen. Beyond this, judges exercise broad discretion to achieve a result that is “fair”. Modern interpretations have shifted away from rigid formulas towards a pragmatic assessment of each party’s future needs, earning capacity, and contributions to the family. This ensures that the settlement is tailored to the specific realities of your household rather than a generic template.

Matrimonial vs Non-Matrimonial Assets

Distinguishing between asset types is essential for a precise and equitable division. Matrimonial assets generally include everything acquired during the marriage, such as the family home, joint savings, and pensions. These are typically subject to the sharing principle. Non-matrimonial assets often include property owned before the wedding or specific inheritances and gifts received during the relationship.

However, the treatment of non-matrimonial assets is rarely straightforward. If these assets have been “commingled”, for instance by using an inheritance to pay off a joint mortgage, they may lose their protected status. The court evaluates how long the marriage lasted and whether these assets are required to meet the other party’s basic needs. Expert legal insight is vital here to ensure your pre-marital wealth is appropriately ring-fenced wherever possible, maintaining your financial independence post-divorce.

How the Court Determines a ‘Fair’ Financial Split

The concept of “fairness” in a financial settlement divorce uk is often misunderstood as a simple mathematical exercise. Whilst a 50/50 division is frequently used as a starting point for long marriages, it’s by no means an automatic rule in English and Welsh law. The court’s primary objective is to reach an equitable outcome that reflects the unique circumstances of the family. This involves balancing various factors, including the standard of living enjoyed during the marriage. Judges rarely consider personal “conduct” or “blame” for the breakdown of the relationship unless it’s exceptionally egregious and has a direct, significant impact on the financial position. Instead, the focus remains on practical needs and future security.

The Section 25 Criteria Explained

Judges derive their authority from a specific set of criteria known as the Section 25 factors. These rules require a thorough, methodical assessment of each party’s position. The court will examine your income and earning capacity, looking not just at what you earn now, but what you could potentially earn in the future. They’ll also consider your current and future financial needs, obligations, and responsibilities. The age of each party and the duration of the marriage play a significant role; a twenty-year marriage is treated very differently from a two-year union. Additionally, the court weighs contributions to the welfare of the family, ensuring that a spouse who sacrificed their career to manage the home is not financially penalised. This discretionary approach allows for a tailored resolution that accounts for the nuances of your specific household.

Prioritising the Needs of Children

The court has a statutory duty to place the welfare of any children under eighteen at the forefront of its decision-making. This priority often dictates the division of the family home. If one parent remains the primary caregiver, the court may prioritise their housing needs to ensure the children have a stable and secure environment. This might result in an unequal split of capital to facilitate a property purchase or a deferred sale of the matrimonial home. The goal is to minimise disruption to the children’s lives, even if it means a less-than-equal division of the current assets. Understanding how these factors apply to your situation is essential for long-term planning. If you require a bespoke assessment of your matrimonial assets, our team provides the steady, professional guidance needed to navigate these complexities with confidence.

The Critical Role of Full and Frank Financial Disclosure

Full and frank disclosure is the cornerstone of any robust financial settlement divorce uk. It requires both parties to provide a comprehensive and honest overview of their global financial position, ensuring that negotiations are based on fact rather than assumption. This process is primarily facilitated through “Form E”, a detailed document that organises your financial evidence, including bank statements, property valuations, and income details. Providing a complete picture from the outset isn’t merely a procedural requirement; it’s a strict legal obligation. If one party is found to have hidden assets or provided misleading information, the court has the power to set aside the final order, potentially reopening the litigation years later at significant expense.

The strategic completion of Form E ensures that the negotiation starts from a position of absolute clarity. We often engage professional valuers to assess complex assets, such as private collections or property portfolios, to prevent disputes over their true worth. This methodical approach ensures that the matrimonial “pot” is accurately defined before any division begins, providing the firm foundation necessary for a fair and lasting agreement.

Dealing with Pensions and Business Assets

Pensions are frequently the most significant asset after the family home, yet they remain one of the most misunderstood areas of asset division. A Pension Sharing Order provides a definitive clean break by transferring a percentage of one party’s pension credit to the other. In contrast, a Pension Attachment Order acts more like maintenance, where payments are made only once the pension holder retires. It is vital to note that whilst many private schemes can be split, the new state pension (for those reaching state pension age from April 2016) cannot be shared. For high-value pots, we often recommend actuarial reports to determine the true value of the income stream. Similarly, valuing a family business requires a nuanced look at liquidity and future earnings to ensure the settlement remains sustainable for both parties.

International Assets and Overseas Entities

Identifying and valuing investments held abroad adds another layer of complexity to the disclosure process. Modern divorce proceedings frequently involve overseas entity beneficial owner registration, which provides essential transparency for UK property held by foreign organisations. Our expertise in cross-border financial arrangements allows us to navigate these international nuances with calm, steady precision. We ensure that every offshore interest is correctly accounted for, protecting your interests regardless of where the assets are located. This level of meticulous detail is essential for securing a settlement that is both comprehensive and legally sound.

Financial Settlement in UK Divorce: A Comprehensive Guide to Protecting Your Assets (2026)

Reaching an agreement outside the courtroom is increasingly the preferred route for those seeking a discreet and efficient resolution. Alternative Dispute Resolution (ADR) offers a more controlled environment for resolving a financial settlement divorce uk, prioritising cooperation over conflict. Mediation is a primary pillar of this approach. It allows both parties to discuss their needs with a neutral third party, often reducing the overall cost of proceedings whilst fostering a more amicable atmosphere. This is particularly beneficial when children are involved, as it sets a cooperative tone for future co-parenting and reduces the emotional strain on the family unit.

For complex cases that require a definitive decision but seek to avoid the delays of the public court system, arbitration is a sophisticated alternative. In this process, a private judge, known as an arbitrator, reviews the evidence and makes a binding decision. It’s significantly faster than the traditional court route and offers a level of privacy that high-net-worth individuals often prioritise. This ensures that sensitive financial details and business interests remain confidential, away from the public record.

The Process of Securing a Consent Order

Once an agreement is reached through negotiation or mediation, it must be formalised into a Consent Order to become legally binding. This document is meticulously drafted by solicitors to reflect the agreed terms with absolute precision, covering everything from property transfers to pension sharing. A judge then reviews the order to ensure it’s “fair” and meets the statutory requirements of the Matrimonial Causes Act. Without this judicial seal, your agreement remains informal and lacks the power to prevent future claims. For a deeper look at strategic asset division, see our guide to protecting your assets.

When Negotiation Fails: The Path to Court

If an agreement cannot be reached through ADR, the court process provides a structured path to a resolution. This typically involves three distinct stages: the First Appointment (FDA), the Financial Dispute Resolution (FDR) hearing, and the Final Hearing. The FDR is a pivotal moment in the litigation. It’s a “without prejudice” hearing where a judge gives a non-binding indication of the likely outcome if the case were to proceed to a trial. This insight often encourages a settlement, as both parties can see the risks and costs of continuing to a Final Hearing. Expert litigation support is essential during these stages to ensure your position is presented with clarity and authority. If you find yourself facing a contested split, we recommend seeking a professional consultation on divorce and financial arrangements to protect your long-term interests.

Securing Your Future with Feltons Solicitors

Feltons Solicitors LLP offers a boutique experience that prioritises the individual behind the legal case. We understand that navigating a financial settlement divorce uk is one of the most significant transitions you’ll ever face. Our approach is defined by a sophisticated blend of professional authority and empathetic reassurance. We position ourselves as a calm, steady presence during what is often a high-pressure period. By focusing on a personal connection rather than high-volume processing, we ensure that every client receives the discreet, high-standard service they deserve.

We specialise in handling complex, international-scale matters with the worldly experience required for high-net-worth asset division. Whether your estate involves overseas entities or intricate business structures, our team provides the pragmatic, sound judgment needed to secure your financial independence. We value modern efficiency, but we never compromise on the traditional professional integrity that has defined our firm since Paula Felton established it in 2010. This combination of heritage and forward-thinking methodology ensures your financial settlement divorce uk is handled with absolute precision.

A People-First Philosophy to Legal Service

Our “people-first” philosophy means that we never forget the human impact of the technical legal work we perform. We prioritise personal rapport and privacy, acting as your discreet partner throughout the entire process. We guide you through every step of the financial settlement process, from the initial disclosure to the final court-sealed order. Our goal is to provide a sense of security and comprehensive care, ensuring you feel supported and in capable hands. We offer tailored strategies that reflect your specific goals, whether you seek a clean break or the long-term protection of children’s assets.

Next Steps: Contacting Our Trusted Advisors

Taking the first step towards a resolution is often the hardest part. We invite you to arrange an initial consultation with our expert family law team to discuss your specific needs in a confidential setting. To make the most of this meeting, it’s helpful to gather a preliminary list of your assets, including property values, pension statements, and any business interests. This allows us to provide more targeted, practical advice from the very beginning.

Our communication rhythm is steady and deliberate. We respect your time and opt for a methodical flow that guides you through information without the frantic energy of high-pressure sales. If you’re ready to secure your financial future with a partner who values your peace of mind as much as your legal success, we’re here to help. Contact our trusted advisors today to begin your journey toward a discreet and efficient resolution.

Securing Your Financial Independence for the Years Ahead

Transitioning into a new chapter of life requires more than just legal paperwork; it requires a strategy that protects your hard-earned assets and provides long-term security. We’ve explored how the court balances Section 25 factors and why a court-sealed Consent Order is the only way to achieve a definitive clean break. A successful financial settlement divorce uk relies on meticulous disclosure and the ability to navigate complex arrangements, such as pensions and international property, with absolute precision.

Feltons Solicitors has provided boutique, personalised legal service since 2010. We offer the calm, steady presence needed to handle complex international-scale matters whilst prioritising your privacy and peace of mind. Our team is dedicated to helping you achieve a resolution that is both efficient and fair. If you’re ready to move forward with confidence, please contact Feltons Solicitors for a discreet consultation. You deserve a trusted advisor who understands the human impact of your legal journey and works tirelessly to secure your financial future.

Frequently Asked Questions

How long does a financial settlement take in the UK?

A financial settlement typically takes between six and twelve months to conclude if an agreement is reached through negotiation or mediation. If the matter proceeds to a contested court hearing, the timeline can extend significantly beyond a year. It’s important to understand that the financial process runs parallel to the divorce petition but remains a distinct legal matter. Seeking a prompt resolution helps provide the certainty needed to plan for your post-divorce future.

Can I claim my husband or wife’s pension after divorce?

Pensions are often the most significant asset in a marriage and are almost always included in a financial settlement divorce uk. You may be entitled to a portion of your spouse’s pension through a sharing order or an attachment order. However, the new state pension, for those reaching retirement age after April 2016, cannot be shared. We often use actuarial reports to ensure these complex funds are valued accurately before any division is agreed.

What happens to the family home in a financial settlement?

The treatment of the family home depends on the specific needs of each party, with the court prioritising the welfare of any children involved. Common outcomes include selling the property and dividing the proceeds or one party buying out the other’s share to remain in the home. In some cases, a deferred sale order is used to ensure children have a stable environment until they reach adulthood. Every situation requires a bespoke approach to achieve fairness.

Is a financial settlement always 50/50 in the UK?

No, there is no automatic 50/50 split in English and Welsh law. Whilst an equal division is a frequent starting point for long marriages, the court exercises broad discretion under Section 25 of the Matrimonial Causes Act. Factors such as the length of the marriage, each party’s earning capacity, and their future financial needs can lead to an unequal split. The primary goal is to reach an outcome that is equitable and sustainable for both individuals.

Do I need a solicitor for a financial settlement?

You are not legally required to instruct a solicitor for negotiations, but professional representation is essential for drafting a legally binding Consent Order. A solicitor ensures the document accurately reflects your agreement and provides the necessary protection against future claims. Without a court-sealed order, your financial ties remain open, leaving you vulnerable to claims years after the divorce. Expert guidance also helps you navigate complex asset valuations and ensures your long-term interests are fully protected.

What is a Clean Break Order and do I need one?

A Clean Break Order is a court-sealed document that ends the financial relationship between you and your former spouse. It prevents either party from making any future claims against the other’s income, assets, or inheritance. Most individuals require this order to achieve true financial independence and peace of mind. Without it, your former partner could potentially apply for a share of your wealth many years later if your financial circumstances improve significantly or you receive a windfall.

Can a financial settlement be changed after the divorce is finalised?

A financial settlement is usually final once a court has issued a sealed order, particularly if it includes a clean break clause. However, an order can be challenged or set aside in exceptional circumstances, such as a failure to provide full and frank disclosure or evidence of fraud. Additionally, a “Barder event”, which is a significant and unforeseen change occurring shortly after the order, may allow for a review. These cases are rare and require sophisticated legal expertise.

How much does a financial settlement cost in legal fees?

The total cost of a financial settlement divorce uk depends on the complexity of your assets and whether the division is agreed amicably. Court filing fees for 2026 are fixed at £62 for a consent order and £321 for a contested financial order. Professional fees vary based on the level of negotiation or litigation support required. Investing in expert advice early often reduces overall costs by avoiding a protracted court battle and ensuring a more efficient resolution.

Pension Sharing Order Lawyers: Strategic Guidance for Your Financial Future

Pension Sharing Order Lawyers: Strategic Guidance for Your Financial Future

A pension is often the single most significant asset in a marriage, yet it remains the most frequently undervalued during a divorce. While property and savings are easily quantified, the true worth of a retirement fund is often hidden beneath layers of complex actuarial data and shifting legislation. Engaging specialised pension sharing order lawyers is not merely a procedural step; it is a strategic necessity to ensure your future remains secure. You likely feel a profound sense of anxiety regarding your standard of living in later life, especially whilst facing the pressure of acrimonious financial negotiations.

We understand that you want more than just a settlement; you want the peace of mind that comes with a genuine clean break. This guide will provide the clarity you need to manage the intricacies of pension division, from understanding implementation fees to the impact of the rising Normal Minimum Pension Age. We will outline how a legally binding Pension Sharing Order can provide the foundation for your long-term stability. By the end of this article, you will have a clear overview of how professional expertise can protect your interests and help you move forward with confidence.

Key Takeaways

  • Recognise why pensions are treated as essential marital assets and how their value is assessed alongside the family home.
  • Understand the technical differences between internal and external transfers to facilitate a genuine clean break financial settlement.
  • Evaluate the long-term benefits of pension sharing against the immediate appeal of offsetting to protect your retirement income.
  • Engage specialised pension sharing order lawyers to manage complex valuations and ensure your final court order is drafted with absolute precision.
  • Discover how full and frank financial disclosure through Form E prevents costly errors and secures your financial future.

Understanding Pensions as Essential Marital Assets

Pensions are frequently the most significant asset in a matrimonial estate, occasionally even surpassing the value of the family home. Despite this, they’re often overlooked or undervalued during initial discussions. It’s a fundamental legal principle that pensions are marital assets. This remains true regardless of whose name is on the policy or which party made the contributions. Because these funds represent future security rather than immediate cash, they require a methodical approach to valuation. Experienced pension sharing order lawyers ensure that these complex financial vehicles are correctly identified and appraised from the outset of the proceedings.

Distinguishing between different types of retirement provision is vital. Whilst the basic State Pension generally cannot be shared, certain “protected payments” or older entitlement structures might be subject to specific rules. In contrast, private and occupational schemes, including final salary and money purchase arrangements, are fully eligible for division. Achieving a genuine clean break financial settlement usually necessitates a formal Pension Sharing Order. Without this legally binding document, one party may retain a claim against the other’s future income, preventing the finality that most couples seek when they separate.

The Legal Framework for Pension Division in the UK

The legal framework for divorce in England and Wales is primarily governed by the Matrimonial Causes Act 1973. This legislation grants the court broad discretion to redistribute assets to achieve a “fair” outcome. Fairness doesn’t always mean an equal split. The court prioritises the financial needs of both parties and any children involved. They’ll consider the duration of the marriage and the contributions each person made, whether financial or through caring for the family. In long marriages, the starting point is often an equal division of the pension’s value to ensure both parties can maintain a comparable standard of living in retirement.

Why “Ring-fencing” Pre-marital Contributions is Complex

There’s a common misconception that any pension growth occurring before the wedding is automatically excluded from the settlement. This isn’t always the case. Courts often view the total pension pot as matrimonial property if it’s required to meet the basic needs of the lower-earning spouse. Ring-fencing requires precise actuarial evidence to prove which portions of the fund should be treated as non-matrimonial. This is where pension sharing order lawyers provide essential value. We help you navigate these arguments, ensuring that your contributions are protected where possible, or conversely, that you aren’t unfairly deprived of a share in a fund that was built up over many years of partnership.

The Mechanics of a Pension Sharing Order (PSO)

A Pension Sharing Order (PSO) is the legal mechanism that facilitates the transfer of a specified percentage of one party’s pension pot to the other. It’s a precise instrument; the court doesn’t award a fixed sum of money, but rather a “pension credit” calculated as a percentage of the fund’s value at the time of transfer. This process can only begin once the Final Order in the divorce has been granted. Navigating this timeline requires steady oversight from pension sharing order lawyers to ensure the paperwork is served correctly and within the strict legal windows. Whilst many focus on private funds, it is also useful to consult government guidance on State Pension sharing to see if any additional “protected payments” apply to your situation.

Internal vs External Pension Transfers

When a PSO is granted, the recipient must decide where the pension credit will be held. An internal transfer allows the recipient to become a member of the original pension scheme in their own right. This is often common in public sector schemes, though it isn’t always an option. Conversely, an external transfer involves moving the credit into a completely different pension arrangement. Some schemes mandate an external transfer, forcing the recipient to find a suitable provider. This choice has significant long-term implications for your retirement income. Our team at Feltons Solicitors LLP works alongside financial advisors to ensure you understand the specific benefits and risks associated with each path.

The Implementation Period and Provider Fees

Once the pension provider receives the court order and the Final Order, a statutory four-month implementation period begins. During this window, the provider must execute the transfer. It’s a critical phase; any errors in the original drafting of the order can lead to the provider rejecting the document, causing significant delays and additional costs.

You should also be aware of the administrative costs. In 2026, implementation fees typically range from £300 to over £3,500, depending on the complexity of the scheme. These fees are usually shared between the parties or paid by the person receiving the credit. pension sharing order lawyers play a vital role here, ensuring the order is drafted with absolute precision to meet the scheme’s specific requirements. This methodical approach prevents the anxiety of a rejected application and ensures your financial future is secured without unnecessary friction.

Pension Sharing vs. Offsetting: Strategic Considerations

Deciding between a pension sharing order and offsetting is one of the most consequential choices you’ll face during financial proceedings. Offsetting involves one party retaining a larger share of non-pension assets, typically the family home, in exchange for waiving their rights to the other’s retirement fund. Whilst this provides immediate stability and housing security, it inherently sacrifices long-term income. This trade-off requires a sophisticated analysis of your current needs versus your future requirements. Strategic pension sharing order lawyers help you weigh these competing interests to ensure you don’t trade a valuable lifetime income for a short-term asset that may carry high maintenance costs.

You should also be aware of Pension Attachment Orders, formerly known as earmarking, though they are now increasingly rare. These orders don’t provide a genuine clean break; the recipient only receives payments when the pension holder chooses to retire. Furthermore, these payments usually cease if the recipient remarries. Because of these limitations, most modern settlements favour the finality of a sharing order or the pragmatism of offsetting.

When Offsetting is the Pragmatic Choice

For younger couples or those with dependent children, offsetting often emerges as the most practical route. It prioritises the immediate need for a stable home environment and avoids the administrative complexities of transferring pension credits. Calculating a fair offset isn’t a simple pound-for-pound exchange. It involves assessing the “utility” of the money; cash today is often considered more valuable than a pension you can’t access for decades. To achieve a fair result, we often use actuarial calculations to determine how much cash is required to “buy out” a specific percentage of a pension, ensuring the settlement remains equitable for both parties.

The Dangers of Misvaluing Pension Assets

A significant risk in divorce negotiations is assuming that the Cash Equivalent Value (CEV) provided by a pension scheme represents its true worth. This is rarely accurate, especially with defined benefit or “final salary” schemes. A £100,000 cash sum in a bank account is not equal to a £100,000 defined benefit pension pot. The cash is liquid and taxable only upon spending, whereas the pension represents a guaranteed, inflation-linked income for life that is subject to different tax treatments. A Pension on Divorce Expert (PODE) is a neutral specialist actuary or financial professional instructed to provide a comprehensive report on the true value and fair division of pension assets. Expert pension sharing order lawyers identify these valuation gaps early, preventing you from agreeing to a settlement that looks fair on paper but leaves you financially disadvantaged in the years to come.

Pension Sharing Order Lawyers: Strategic Guidance for Your Financial Future

The Valuation and Disclosure Process: Avoiding Costly Errors

Full and frank financial disclosure is a mandatory requirement in any divorce proceeding, typically facilitated through the completion of Form E. This document demands absolute honesty regarding all financial interests, including every pension scheme you’ve ever contributed to. Failing to disclose these assets is a grave error that can lead to the court reopening your case years later or even imposing penalties for contempt. Experienced pension sharing order lawyers ensure that every stone is unturned, protecting you from the risks of non-disclosure and ensuring the final settlement is based on a complete financial picture.

The starting point for any valuation is the Cash Equivalent Value (CEV) provided by the pension scheme administrator. Whilst the CEV gives a snapshot of the fund’s current worth, it’s rarely the final word in a fair negotiation. It represents the amount the scheme would pay to transfer your benefits elsewhere, not necessarily the value of the benefits you’d receive if you stayed. For many, relying solely on this figure leads to a settlement that significantly undervalues their future security.

The Role of the Pension On Divorce Expert (PODE)

In cases involving complex or high-value schemes, a standard CEV is almost always insufficient. A Pension On Divorce Expert (PODE) is a neutral actuary or specialist financial professional instructed to provide a comprehensive report. In 2026, a PODE report typically costs between £750 and £3,000, but this investment is often vital. The report provides a more accurate picture of future income, accounting for inflation-linked benefits and tax implications that a simple CEV ignores. We help you conduct a cost-benefit analysis to determine if commissioning an expert report is the right strategic move for your specific circumstances.

Managing Defined Benefit vs. Defined Contribution Schemes

Public sector pensions, such as those for the NHS, Police, or Armed Forces, are “Defined Benefit” schemes and are notoriously difficult to value. These schemes focus on “income equality” in retirement rather than “capital equality.” Simply splitting the capital value of an NHS pension 50/50 might result in one party receiving a much lower monthly income than the other due to different retirement ages or tax brackets. Conversely, Defined Contribution schemes like SIPPs or SSASs are more straightforward but require careful management to ensure the underlying investments aren’t liquidated at a loss during the transfer. If you are concerned about the accuracy of your pension valuations, contact our team at Feltons Solicitors LLP for a discreet consultation to protect your financial interests.

How Specialist Pension Sharing Order Lawyers Protect Your Interests

The final stage of securing your financial future is the translation of complex actuarial data into a robust, enforceable legal document. Specialist pension sharing order lawyers provide the bespoke drafting necessary to ensure that your intentions are accurately reflected in the final court order. A minor clerical error or an ambiguous clause can lead to a pension provider rejecting the order during the implementation period, causing months of delay and additional costs. By meticulously managing the transition from financial disclosure to a final Consent Order, we ensure that your settlement is not just fair in principle, but functional in practice.

A legally binding Consent Order is the only way to achieve a genuine clean break financial settlement. This document effectively closes the door on future claims, providing the certainty you need to rebuild your life. Our role involves more than just filling in forms; we act as a strategic shield, ensuring that the percentage of the pension being shared is calculated to your maximum advantage. We oversee every interaction with the pension scheme administrators, removing the burden of technical correspondence from your shoulders during an already stressful period.

The Boutique Advantage: Tailored Legal Architecture

High-volume law firms often treat pension division as a secondary administrative task. This approach can overlook the nuanced structures of modern retirement funds and the profound human impact of these decisions. At Feltons Solicitors LLP, we offer a boutique alternative that prioritises personal rapport and privacy. We organise your financial disclosure to project clarity and strength, ensuring that your position is articulated with quiet confidence during negotiations. This tailored approach allows us to handle complex matters whilst maintaining the supportive, discreet presence you require during a sensitive life transition.

Securing Your Future with Feltons Solicitors LLP

Our firm was established in 2010 by Paula Felton with a clear mission: to combine modern efficiency with traditional professional integrity. We provide a calm, steady hand in the face of acrimonious negotiations, focusing on pragmatic solutions that avoid unnecessary litigation where possible. However, should your case require robust representation, our expertise in high-net-worth matters ensures your interests are protected with absolute diligence.

Early legal intervention is the most effective way to prevent costly valuation errors and secure a genuine clean break. To understand how we can safeguard your broader portfolio, you may wish to consult our expert divorce and financial arrangements lawyer services. We act as your trusted advisor, ensuring that your technical legal needs are met without losing sight of the human impact of our work. Our goal is to move you from the uncertainty of initial disclosure to the security of a final settlement that protects your lifestyle in retirement.

Securing Your Retirement with Expert Precision

Securing your retirement requires more than a simple division of assets; it demands a methodical strategy that accounts for the nuances of your specific pension schemes. We’ve explored why standard valuations often fall short and how the choice between sharing and offsetting can dictate your financial comfort for decades. By prioritising a genuine clean break, you can step into your future without the lingering anxiety of unresolved financial ties. You deserve a settlement that reflects the true value of your contributions and provides a stable foundation for the years ahead.

Engaging specialised pension sharing order lawyers is the most effective way to manage these complexities whilst protecting your long-term interests. Feltons Solicitors LLP provides a boutique service characterised by high-end reliability and a people-first philosophy. We’re committed to delivering pragmatic, expert advice in even the most complex financial litigation. If you’re ready to secure your financial architecture with a trusted advisor, please contact Feltons Solicitors LLP for a discreet consultation on your financial arrangements. You don’t have to face these negotiations alone; we’re here to provide the calm, steady presence you need to move forward with absolute confidence.

Frequently Asked Questions

What is a Pension Sharing Order (PSO)?

A Pension Sharing Order is a formal court instruction that transfers a specific percentage of one party’s pension pot to their former spouse or civil partner. It’s designed to facilitate a genuine clean break financial settlement by creating a separate pension credit for the recipient. This credit is held in either the original scheme or a new arrangement. Unlike other methods, it provides immediate clarity and independence for both parties’ future retirement planning.

Can I get a Pension Sharing Order after my divorce is finalised?

You can apply for a Pension Sharing Order after your divorce is finalised, provided you haven’t remarried and a court hasn’t already dismissed your financial claims. However, it’s significantly more complex to negotiate these arrangements once the Final Order is granted. Delaying this process can leave your future financial security at risk. It’s always advisable to resolve pension division alongside the divorce proceedings to ensure a comprehensive and legally binding settlement is achieved.

How much does a pension sharing order cost in the UK?

The total cost of a pension sharing order varies based on complexity. As of April 2026, the court fee for a financial consent order is £53. You must also account for pension scheme implementation fees, which typically range from £300 to over £3,500 depending on the provider. If your situation involves complex defined benefit schemes, an expert actuary report may cost between £750 and £3,000. These figures exclude the professional fees for legal drafting and advice.

Are all pensions included in a divorce settlement?

Most pension assets are considered marital property, regardless of whether they were started before the marriage. This includes private pensions, occupational schemes, and Self-Invested Personal Pensions (SIPPs). Whilst the court has the discretion to ring-fence pre-marital contributions, they often include the entire fund if it’s necessary to meet the lower-earning party’s needs. Every scheme must be disclosed during the valuation process to ensure the final settlement is based on accurate data.

What happens if my ex-spouse refuses to disclose their pension value?

If an ex-spouse refuses to disclose their pension value, the court can intervene to enforce full and frank disclosure. Both parties must complete a Form E, which carries a duty of honesty to the court. Failure to comply can result in the court drawing adverse inferences about their wealth or issuing costs orders against them. Experienced pension sharing order lawyers can also apply for a court order to obtain the necessary information directly from the pension provider.

How long does it take for a Pension Sharing Order to be implemented?

Once a pension provider receives the sealed court order and the Final Order, they have a statutory four-month period to implement the transfer. However, the entire process usually takes longer. You must first obtain valuations, negotiate the percentage, and wait for court approval. If the paperwork contains errors, the provider may reject it, restarting the timeline. Methodical legal oversight is vital to ensure the documentation is correct the first time to avoid these delays.

Do I need a lawyer for a Pension Sharing Order?

Whilst you aren’t legally required to use a solicitor, the technical nature of pension division makes professional guidance essential. Pension sharing order lawyers ensure that the order is drafted with the specific wording required by scheme administrators. They also help identify if a Cash Equivalent Value (CEV) accurately reflects the fund’s true worth. Without this expertise, you risk accepting a settlement that leaves you significantly disadvantaged or failing to secure a legally enforceable clean break.

Can I share my State Pension with my ex-partner?

The rules for sharing a State Pension depend on when you reached retirement age. For those reaching pension age after April 2016, the New State Pension generally cannot be shared. The main exception is a protected payment, which represents an entitlement above the full rate. If you reached retirement age before this date, different rules regarding the Additional State Pension may apply. It’s important to check your specific entitlement with the Department for Work and Pensions.