Commercial Property Acquisition by an Overseas Company: UK Legal Guide

Commercial Property Acquisition by an Overseas Company: UK Legal Guide

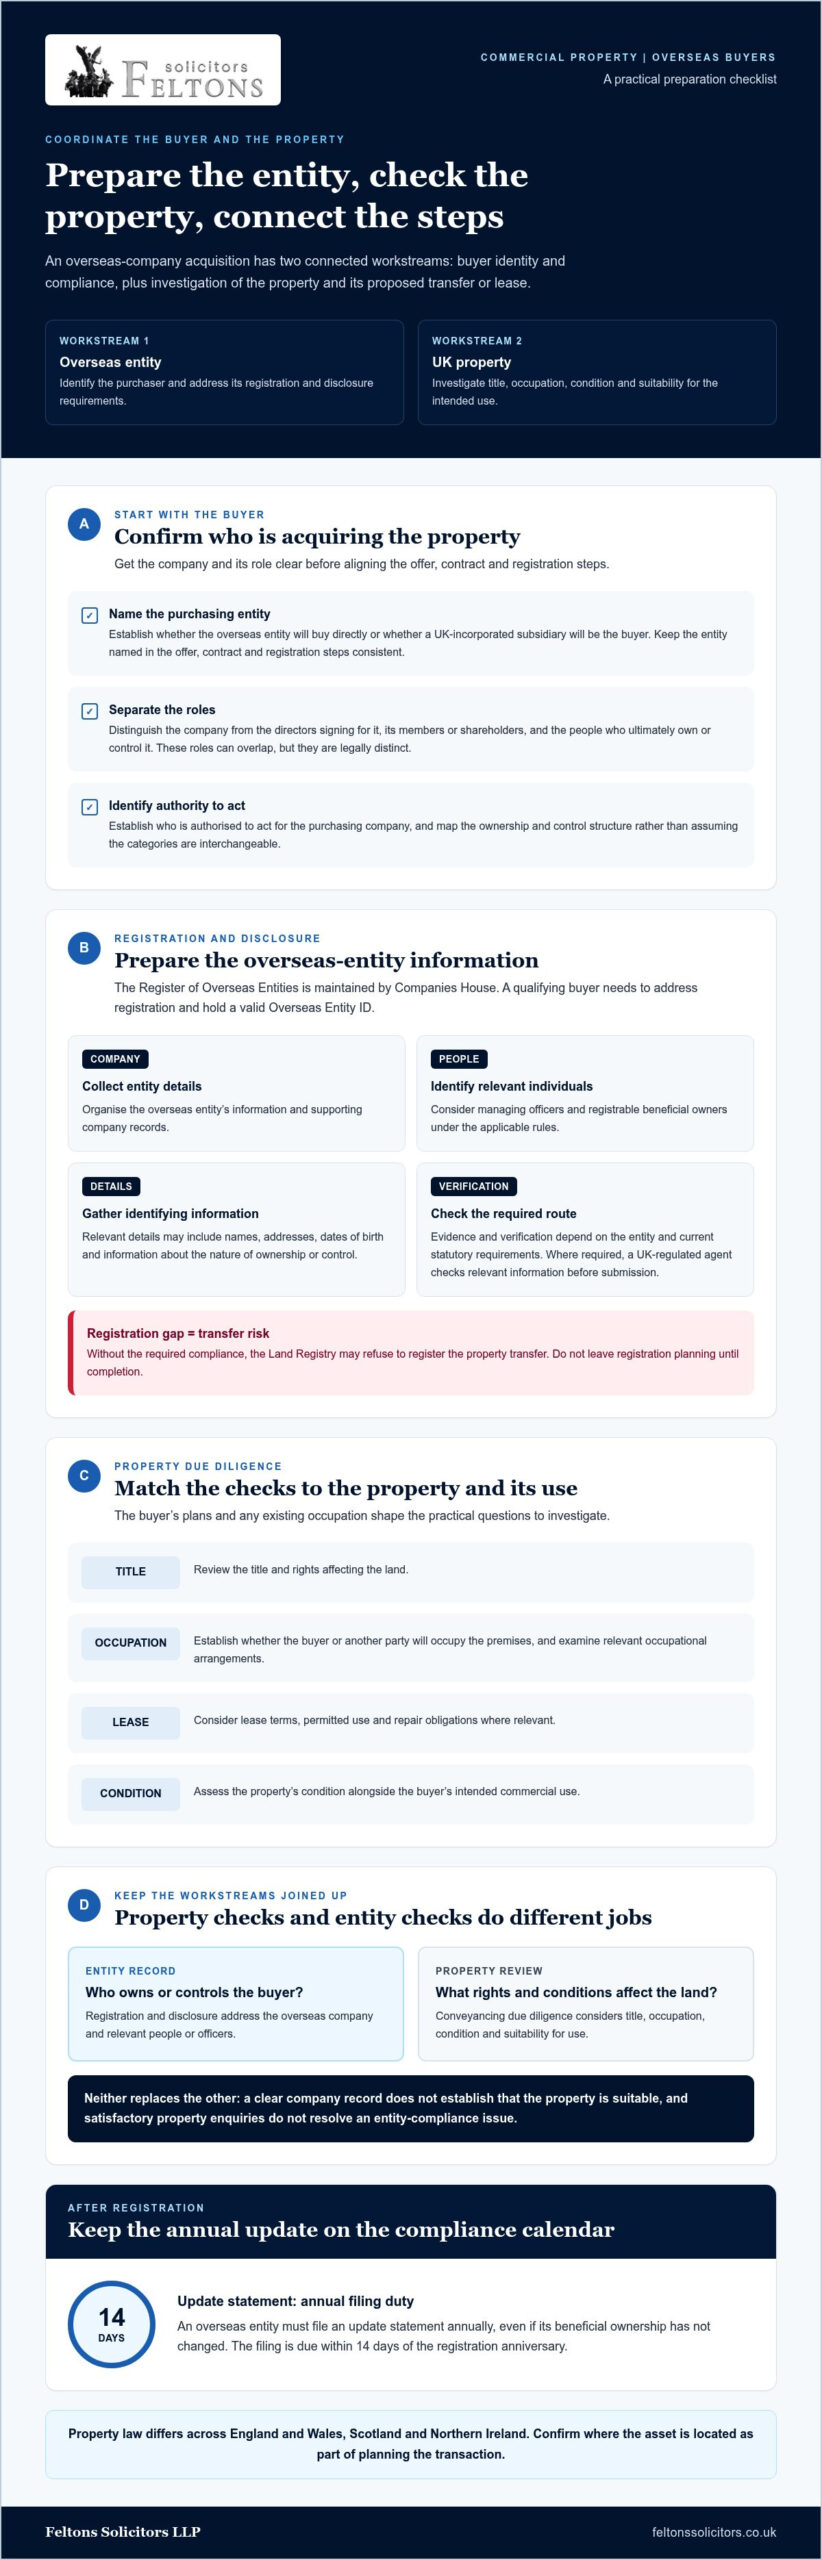
Could an overseas company agree terms for a UK commercial property, only to find that a registration gap prevents the transfer being registered? It’s a practical risk: an overseas entity generally needs to be registered with Companies House and hold a valid Overseas Entity ID, or the Land Registry may refuse to register the property transfer. A commercial property acquisition overseas company buyers plan therefore needs the legal and compliance steps considered together from the outset.

Registration, company records and property due diligence can all affect the transaction. Preparing early helps you identify the information needed and deal with key requirements before they become obstacles. This guide covers the main stages, including overseas-entity registration, due diligence, conveyancing and the filing duties that follow registration.

Feltons Solicitors LLP advises on commercial conveyancing and registration of overseas entities, helping national and international clients coordinate these connected matters. This guide explains what to prepare, when each step arises and how tailored legal advice can help you move the transaction forward.

Key Takeaways

  • Clarify which UK jurisdiction the property is in and whether the buyer is an overseas entity, as this shapes the legal steps involved.
  • Prepare beneficial-owner and managing-officer information early to address registration and disclosure requirements.
  • Tailor due diligence to the property’s title, occupational arrangements, condition and intended commercial use.
  • Plan the commercial property acquisition overseas company process as a connected sequence, coordinating entity checks, property enquiries and conveyancing from the outset.
  • Joined-up legal advice can help organise company information, assess contractual issues and progress registration and conveyancing together.

Commercial property acquisition by an overseas company: what the transaction involves

An overseas-company acquisition is a transaction in which an entity formed outside the UK buys or holds UK commercial land. The purchaser is the company, not the directors who sign documents on its behalf, its members or shareholders, or the people who ultimately own or control it. These roles can overlap, but they are legally distinct and may call for different information and checks.

This guide focuses on UK property. Land and property law differs across England and Wales, Scotland and Northern Ireland, so the location of the asset matters. For general background on the UK market, see the UK Real Estate Market Overview. A “commercial property acquisition overseas company” transaction involves two connected workstreams: checking the overseas buyer’s identity and compliance, and investigating the property while negotiating its transfer or lease.

Which overseas-company structure is buying the property?

An overseas entity may buy property directly in its own name. Alternatively, a group might use a UK-incorporated subsidiary as the buyer, creating a separate UK legal entity within the wider corporate structure. The choice can affect how ownership is organised and may have corporate, tax and financing consequences that depend on the buyer’s circumstances. There is no single structure that suits every purchaser. Identify the intended buyer early so the entity named in the offer, contract and registration steps is consistent.

What makes a commercial acquisition different?

Commercial due diligence depends on what the buyer plans to do with the premises and whether anyone already occupies them. An office bought for the buyer’s own business raises different practical questions from a warehouse acquired with an existing tenant, for example. The title, lease terms, permitted use, repair obligations and condition can all affect the buyer’s assessment of the property and the terms needed in the contract.

Keep these property questions separate from ownership disclosure. The property review concerns rights affecting the land, occupational arrangements and suitability for the intended use. Entity checks concern the overseas company and the people or officers relevant to its ownership and control. Neither replaces the other: a clear company record does not establish that the property is suitable, and satisfactory property enquiries do not resolve an entity-compliance issue.

  • Purchasing entity: establish which company will enter into the transaction and who is authorised to act for it.
  • Ownership and control: distinguish the company’s directors and members from the people who ultimately own or control it.
  • Property purpose: identify the planned use and whether the premises will be occupied by the buyer or another party.

Resolve these points together to give the transaction a clearer foundation. This helps align company information, property enquiries and contract arrangements before the buyer commits to a structure or timetable.

Overseas-entity registration and disclosure: the compliance questions to resolve

The Register of Overseas Entities (ROE), maintained by Companies House, records information about overseas entities that own or seek to acquire qualifying UK land. The regime was introduced by the Economic Crime (Transparency and Enforcement) Act 2022. For a qualifying buyer, registration and a valid Overseas Entity ID are important parts of the acquisition. Without compliance, the Land Registry may refuse to register the property transfer.

Registration is not a formality to leave until completion. The buyer needs to establish which overseas entity is acquiring the property, identify the people and officers whose details must be disclosed, and organise verification in line with the rules that apply to its ownership structure. These checks sit alongside, rather than replace, conveyancing due diligence. An entity’s registration record does not establish that the property title, lease arrangements or condition are satisfactory.

What information and verification may be required?

The application generally involves information about the overseas entity, its managing officers and any registrable beneficial owners. A beneficial owner is an individual or relevant legal entity that meets the statutory tests for owning or controlling the overseas entity. A managing officer is a person who manages the entity where the rules require their details. Directors, shareholders and beneficial owners are not automatically interchangeable categories, so examine the ownership structure rather than assume they are the same.

Relevant details may include names, addresses, dates of birth or other identifying information, as well as information about the nature of ownership or control. The evidence and verification route depend on the entity and the current statutory requirements. Where verification by a UK-regulated agent is required, that agent checks the relevant information before it is submitted. Different structures can involve several lines of ownership and control, so map the group structure and collect supporting company records early.

How can registration affect the acquisition timetable?

Check registration status as soon as the proposed buyer and transaction are identified. If the entity still needs to register, gathering information across a group with several ownership layers or overseas officers may require coordination. Running this work alongside offer negotiations and property enquiries can help avoid leaving a key compliance step until the parties are preparing to complete.

The practical link is clear: an overseas entity that must comply with the ROE needs the required registration status for the Land Registry to register the relevant property transaction. The precise restriction and how it applies depend on the circumstances and current rules, so review the buyer’s status and title requirements as part of the conveyancing process.

For a commercial property acquisition overseas company, aligning registration work with conveyancing helps keep entity information, verification and title registration on the same transaction plan. Feltons advises on overseas-entity registration and commercial conveyancing, coordinating these related steps and addressing the details of the ownership structure.

Commercial property due diligence for an overseas-company buyer

Property due diligence helps you understand what is being acquired, how it can be used and which obligations may continue after completion. Shape enquiries around the buyer’s plans: a property intended for its own operations may raise different priorities from an investment property with existing tenants. Keep this review separate from checks on the purchasing entity. Company registration does not establish that the property is suitable or that its title and occupation arrangements are acceptable.

Organise the work by linking each enquiry area to the decision it informs:

Enquiry area What to examine Decision it informs
Title and rights Ownership, title entries, access, restrictions and third-party interests Whether the buyer can obtain the rights and control it needs
Occupation Lease terms, rent position, tenant obligations and who occupies the premises Whether income, possession and continuing responsibilities fit the plan
Condition and environment Available building information and appropriate technical investigations Whether further assessment or contractual protection is needed
Intended use Planning history, permitted use and relevant building documents Whether the proposed activity appears compatible with the property information

Title, rights and occupational arrangements

Title review identifies the registered owner and the rights or restrictions recorded against the land. An access route, for example, may depend on rights benefiting the property, while a title restriction may affect how it can be dealt with. Third-party interests can also shape the buyer’s practical control. Conveyancing enquiries clarify what those entries mean for the proposed transaction and whether further information or contractual provisions should be considered.

If the property is let, examine the lease rather than relying only on a summary of the rental position. Relevant points include the term, rent, review provisions, repair and insurance obligations, permitted occupation and arrangements affecting the tenant’s use. The findings may inform negotiations, contractual protections or, if a concern cannot be resolved, a decision not to proceed.

Use, condition and transaction-specific risks

Start with the intended activity. A buyer planning to operate a particular business from the premises needs enquiries into whether the recorded planning position, permitted use and available building documents align with that plan. The precise enquiries depend on the site and proposed use. Legal review can identify issues in the available documents, but cannot replace specialist technical conclusions.

Condition and environmental investigations serve a different purpose from legal due diligence. Appropriate surveys and assessments can reveal matters that need specialist evaluation. A valuation considers the asset’s value for its purpose, while tax advice addresses the buyer’s particular structure and transaction. These workstreams should inform one another without being confused.

VAT also deserves early attention. If the seller has opted to tax the property, VAT may affect the purchase price and the SDLT calculation. The position depends on the transaction, so include it in tailored tax advice before finalising the commercial assumptions. A coordinated commercial property acquisition overseas company review connects title findings, occupation, intended use and tax questions to the buyer’s decision, rather than treating each enquiry in isolation.
Commercial Property Acquisition by an Overseas Company: UK Legal Guide

From offer to completion: a practical acquisition sequence

A clear sequence keeps company checks, property enquiries and contract decisions moving together. The steps below are a useful framework, not a fixed timetable. The transaction’s pace depends on the property, the buyer’s company information, the registration position and what due diligence reveals.

Before exchange: establish the buyer and investigate the asset

Before committing, confirm the exact entity that will buy the property and gather its constitutional documents, authority to act and relevant ownership information. At the same time, review the title and contract papers, arrange appropriate searches and consider the property’s commercial arrangements. Record issues that need negotiation, further investigation or specialist input so they can inform the decision to proceed.

  1. Identify the proposed buyer. Confirm the overseas entity’s legal name, place of incorporation and the people authorised to act for it. Make sure the proposed purchaser is consistent across the offer, company records and transaction documents.
  2. Review registration requirements early. Establish whether the entity needs to register with Companies House and whether it has the required Overseas Entity ID. If registration or verification is needed, coordinate that work with conveyancing rather than leaving it until the parties are ready to complete.
  3. Agree offer terms and obtain the papers. Clarify the proposed price, what is included in the sale, any occupation arrangements and the intended use. Request the contract pack and available property information so legal review can begin promptly.
  4. Investigate the property and the transaction. Review the title, searches, leases and other relevant documents, and arrange appropriate specialist enquiries. Compare the findings with the buyer’s plans, noting matters that may affect value, use, obligations or contract terms.
  5. Resolve key issues before exchange. Decide whether further information, contract changes or other protections are needed. Exchange is the point at which the parties enter into a binding contract on its terms, so address material concerns before making that commitment.

Exchange, completion and registration

Completion is when the transaction is carried out in accordance with the contract, including payment of the balance and transfer of the property. The conveyancer then deals with applicable post-completion filings and applies to register the transfer with the relevant land registry. Requirements depend on the property’s jurisdiction and the transaction. The sequence is straightforward in principle, but the supporting documents and compliance position must be in order.

  1. Prepare for completion. Confirm that contractual requirements, funds and documents are ready, and that the buyer’s registration position supports the intended transaction.
  2. Complete and register the transfer. Carry out the agreed completion steps, then submit the required application and supporting documents to the relevant land registry.

For more detail on ownership disclosures, the guide to overseas entity beneficial owner registration explains the information involved. Feltons coordinates registration and commercial conveyancing as part of a commercial property acquisition overseas company transaction. Speak to Feltons about your acquisition for tailored legal support with company information, property enquiries and contractual steps.

How Feltons can support an overseas-company commercial acquisition

A commercial purchase by an overseas entity brings together company information, property documents and contractual decisions. Feltons Solicitors LLP advises on commercial conveyancing and registration of overseas entities, including complex property transactions for national and international clients. Tailored legal advice can help you understand how these strands relate, identify the information to gather and focus on issues that may affect the proposed transaction.

The legal work can include considering the buyer’s entity details and registration position alongside the property papers, reviewing the contract and raising relevant conveyancing enquiries. This joined-up approach helps show where one issue may affect another. For example, proposed occupation arrangements may influence contract terms, while the identity of the purchasing entity informs registration work. The aim is pragmatic advice shaped around the transaction, not a promise of a particular outcome.

Coordinating registration and conveyancing advice

Clear responsibilities and organised documents can make a complex purchase easier to manage. The buyer’s team can identify who will provide company and ownership records, who can approve decisions, and how property enquiries and registration information will be gathered. Timely communication matters, particularly where information must come from people in different roles or jurisdictions.

The legal team can connect the entity review with the title, contract and occupational arrangements while keeping each workstream distinct. If the commercial decision involves weighing ownership against occupation under a lease, Feltons’ guide to commercial property law: buying versus leasing may help frame the issues for discussion. Tax, financing and technical questions may need input from the relevant specialists. Legal advice can identify where those questions intersect with the conveyancing process.

Preparing for an initial legal discussion

A focused first discussion is easier when the key facts are to hand. You do not need to resolve every issue in advance. A useful starting pack may include:

  • Entity details: the proposed buyer’s legal name, place of incorporation and available constitutional documents.
  • Ownership and authority information: a group structure or ownership chart, details of relevant officers and information about who can authorise the purchase.
  • Property particulars: the address, title information if available, sales particulars, draft contract papers and details of any existing lease or occupation.
  • Commercial objectives: the intended use, whether the buyer or a tenant will occupy the premises, and the key points the buyer wants the transaction to achieve.

These details help shape advice around the actual buyer and asset. They also make it easier to identify missing information, clarify priorities and organise next steps without assuming every acquisition follows the same route.

If you’re considering a commercial property acquisition overseas company structure, Feltons can advise on the proposed purchase. A discussion of the company, property and commercial objectives can help establish the appropriate conveyancing and overseas-entity registration work for your circumstances. Discuss your commercial property acquisition with Feltons.

Plan your next step with confidence

Turn your commercial objective into a clear legal plan. Consider what the property needs to achieve for your business or investment, which decisions are time-sensitive and who within your organisation can provide the required information. For a commercial property acquisition overseas company buyers pursue, this early alignment helps connect legal questions to the purpose of the purchase.

Feltons Solicitors LLP advises national and international clients on complex property matters, bringing commercial conveyancing and overseas-entity registration support together where the transaction calls for both. Advice can be tailored to the proposed buyer, property and contractual issues, while tax, finance or technical questions can be considered with the relevant specialists.

You do not need every detail resolved before seeking legal guidance. A discussion can help clarify priorities, identify useful documents and establish appropriate next steps for your circumstances. Discuss your commercial property acquisition with Feltons to understand the legal work involved.

Frequently Asked Questions

Can an overseas company obtain a UK commercial mortgage?

Does buying UK commercial property through an overseas company create UK tax obligations?

It can. The acquisition may involve property transaction taxes, and VAT can affect the price and tax calculation if the seller has opted to tax the property. Tax obligations can also arise during ownership or on disposal; non-resident companies pay UK Corporation Tax on gains from disposing of UK commercial property. The treatment depends on the transaction, structure and property location, so obtain tailored tax advice before relying on projected costs or returns.

Is beneficial ownership information on the Register of Overseas Entities publicly available?

Yes, the Register of Overseas Entities is publicly searchable and provides information about overseas entities and registrable beneficial owners. Not every personal detail is necessarily displayed: some information, such as residential addresses and full dates of birth, is treated differently from public-facing details, and protection arrangements may apply in defined circumstances. Buyers should distinguish the information that must be supplied to Companies House from what the public can view.

How often must an overseas entity update its information?

An overseas entity must file an update statement with Companies House annually, even if its beneficial ownership information has not changed. The filing is due within 14 days of the anniversary of its registration. The statement confirms or updates the relevant information for the entity. Keep a record of the registration anniversary and review ownership and officer details in good time so changes can be accurately reported through the applicable process.

Can an overseas company buy UK property through a UK subsidiary instead?

Yes. A group may choose to have a UK-incorporated subsidiary purchase the property rather than having the overseas parent acquire it directly. The subsidiary is a separate legal entity, so its authority, funding and contractual position need to be considered in their own right. Using a UK company does not automatically remove other disclosure or compliance obligations. The right structure depends on the group’s commercial, tax and financing circumstances.

Does an overseas company need a UK bank account to buy commercial property?

A UK bank account is not necessarily a legal prerequisite to owning commercial property, but the buyer needs a workable arrangement for paying the purchase funds and meeting any lender or transaction requirements. The conveyancer will need to understand the source and movement of funds as part of the transaction checks. If funds will arrive from an overseas account, agree the practical transfer arrangements early, particularly where currency conversion or several group entities are involved.

What happens if an overseas company’s ownership changes after it acquires property?

A change in ownership or control may affect the information the company must disclose to Companies House. The entity should assess whether the change makes someone a registrable beneficial owner or alters details already on the Register, then report it through the applicable update process. Keep supporting records and review the effect promptly rather than waiting for a future sale or refinancing. Changes can also have separate corporate, financing or tax implications.
Overseas Corporate Property Compliance: UK Guide 2026

Overseas Corporate Property Compliance: UK Guide 2026

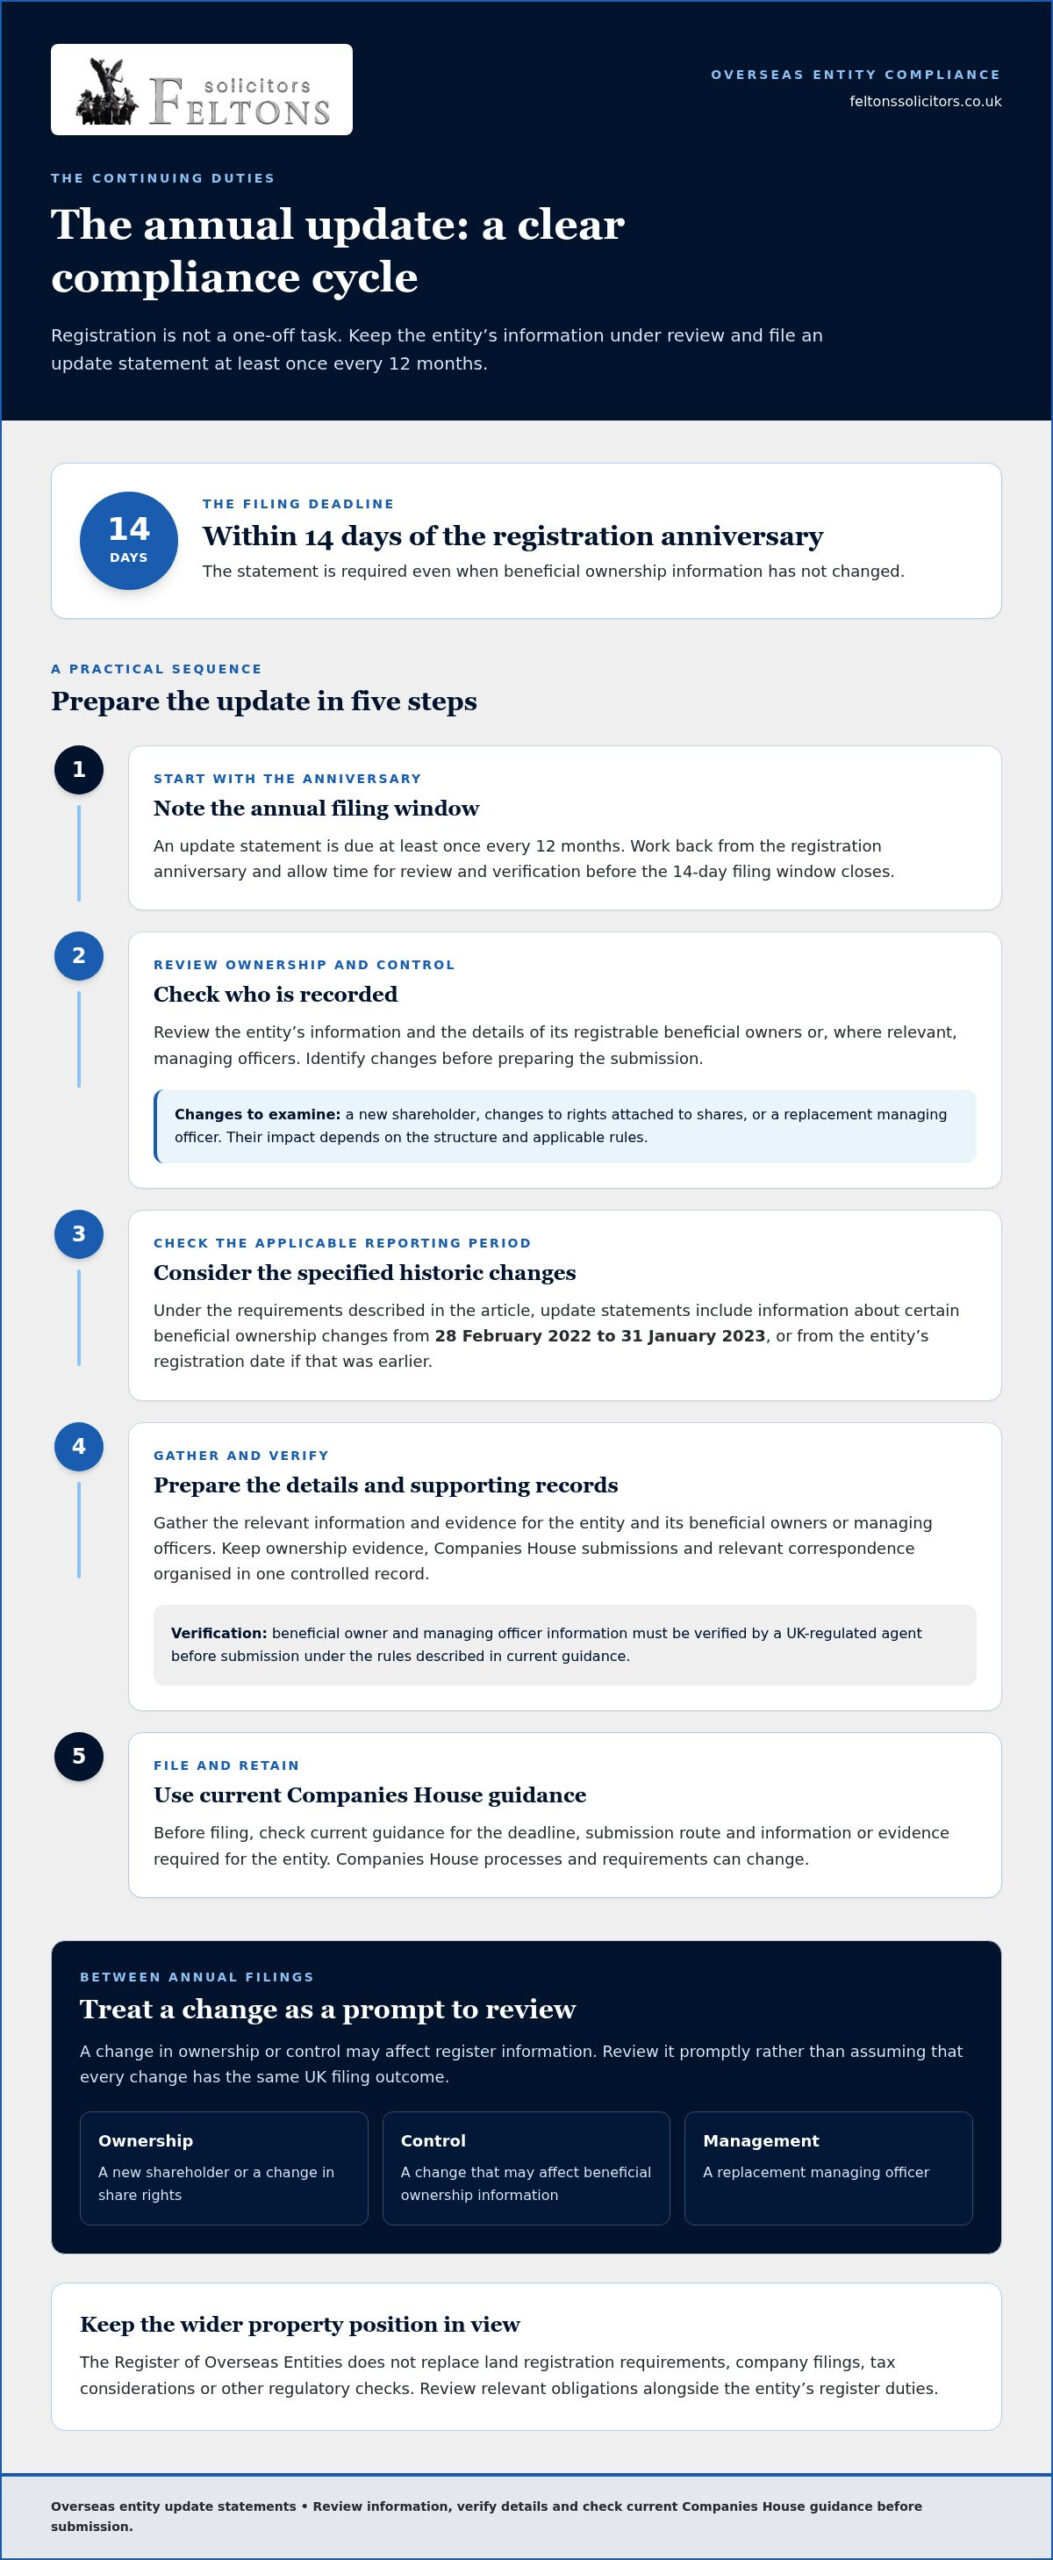
What if registering an overseas entity is only the start of its UK property compliance duties? For organisations that own UK land, overseas corporate property ownership compliance is an ongoing process. A registered entity must file an update statement with Companies House at least once every 12 months, even if its beneficial ownership hasn’t changed. The filing is due within 14 days of the registration anniversary.

It can be difficult to know which changes to report, what records to keep current and how the Register of Overseas Entities fits alongside other obligations. These duties are connected: a change in ownership or company information may require a prompt review.

This guide explains the continuing duties linked to overseas entity registration and the events that may need attention. It distinguishes register requirements from land, company, tax and sanctions considerations, and compares a structured self-managed process with tailored legal support. Feltons Solicitors LLP advises on registration of overseas entities and property matters, helping owners assess how the requirements apply to their particular structure.

Key Takeaways

  • Treat overseas corporate property ownership compliance as an ongoing process, not a one-off registration task.
  • Review changes to beneficial ownership, registrable beneficial owners or managing officers promptly to assess whether reporting action is needed.
  • Use the property’s status, planned transaction and ownership structure as prompts for a focused compliance review.
  • Keep ownership evidence, Companies House submissions and relevant correspondence organised in one controlled record.
  • Compare self-managed administration with tailored legal support to decide how best to coordinate register duties with property transactions.

Overseas corporate property ownership compliance: why registration is only the starting point

Overseas corporate property ownership compliance covers the continuing legal and administrative responsibilities that may apply when an overseas entity owns or seeks to acquire relevant UK land. Registration with Companies House is a key part of the process, but it doesn’t keep the entity’s information accurate by itself or satisfy every obligation connected with its company, property or wider regulatory position. Beyond entity filings, managing UK real estate also requires meeting statutory physical building and safety requirements, where organisations like Oxford Environmental Consultants (OEC) assist with multi-disciplinary property compliance.

Start by identifying the legal owner, the property and the relevant UK jurisdiction. An entity may have registered correctly when it acquired a property, but later changes to its ownership or management could mean its register information needs attention. The position may also depend on when the land was acquired and what type of interest is held. Treating registration as a one-off task risks overlooking these continuing responsibilities.

What does the Register of Overseas Entities do?

Companies House maintains the Register of Overseas Entities under the Economic Crime (Transparency and Enforcement) Act 2022. Its purpose is to make information available about overseas entities that own or seek to acquire qualifying UK land, including details of registrable beneficial owners or, where relevant, managing officers. The register helps show who stands behind an entity, but it doesn’t replace checks on the entity’s wider obligations.

For the registration regime, qualifying land interests include freehold ownership and certain leasehold interests. A non-UK legal entity may need to register before it can complete a relevant property transaction. The position should be assessed against the property’s location, legal interest and transaction history. Companies House registration doesn’t replace land registration requirements, company filings, tax considerations or other regulatory checks—cross-border owners managing international real estate portfolios, for example, often engage accounting firms such as Tax Partners to address jurisdiction-specific tax liabilities and deductible financing costs alongside corporate transparency filings.

Which overseas property owners should review their position?

Overseas legal entities should review their position if they already hold relevant UK land, plan to acquire it or are preparing to dispose of it. This means checking the entity’s ownership chain and the information recorded about its beneficial owners or managing officers. A sale or other transaction can bring register status into focus, so assess it as part of property planning rather than waiting until completion is imminent.

Individual overseas buyers shouldn’t assume that the Register of Overseas Entities applies to them in the same way simply because they live outside the UK. The regime is directed at overseas legal entities. The correct analysis depends on who legally owns the property and how that ownership is structured.

Historic holdings also need careful review. The registration rules have retrospective application for certain properties acquired on or after 1 January 1999 in England and Wales, and 8 December 2014 in Scotland. Transitional circumstances and jurisdiction-specific land rules can affect the analysis, including where a property has changed hands or the ownership structure has been reorganised. Check current Companies House guidance and assess the facts before drawing a conclusion.

  • Identify the registered owner: distinguish the overseas entity from individuals or other entities in its ownership chain.
  • Establish the property history: record where the land is, the interest held and when it was acquired.
  • Review the wider position: consider register duties alongside relevant land, company and regulatory requirements.

The continuing compliance duties overseas entities need to understand

For an overseas entity on the Register of Overseas Entities, compliance means keeping its recorded information current, not simply retaining a registration number. The annual update statement is the recurring Companies House filing used to confirm or update information about the entity and its beneficial owners or managing officers. It’s required at least once every 12 months, even if nothing has changed.

Annual updates and keeping information accurate

The filing deadline is 14 days after the anniversary of the entity’s registration. Before preparing a submission, review the ownership and control information, identify any changes and gather the relevant details. The review should also account for applicable reporting rules: under current requirements, update statements include information about certain beneficial ownership changes from 28 February 2022 to 31 January 2023, or the entity’s registration date if earlier.

Companies House processes and requirements can change. Before filing, check its current guidance for the deadline, submission route and information or evidence required for the entity. Beneficial owner and managing officer information must be verified by a UK-regulated agent before submission under the rules described in current guidance. Allow time for review and verification rather than leaving these steps until the deadline.

Changes, verification and supporting records

A change in ownership or control should trigger a compliance review. A new shareholder, a change in the rights attached to shares or a replacement managing officer could affect information relevant to the register. The impact depends on the structure and applicable rules, so don’t assume that a change in the overseas entity’s home jurisdiction has the same UK filing outcome in every case.

Keep a clear record of the change, the assessment, supporting documents and any submission or correspondence. The evidence and verification steps depend on the filing and current requirements. Companies House identity-verification reforms are separate from verification of Register of Overseas Entities information. As implementation can depend on role and timing, check current Companies House guidance before deciding who must verify their identity or when.

Register duties are only one part of the picture. Tax reporting, filings required in the entity’s place of incorporation and registration of the land itself are separate matters, each with its own rules and processes. For land registration context, HM Land Registry Practice Guide 78 is an official reference. Requirements can vary according to the property’s UK jurisdiction and the transaction.

A disciplined process makes overseas corporate property ownership compliance easier to manage: assign responsibility for monitoring changes, maintain an organised evidence file and diarise the annual review. Where the ownership chain or a property transaction raises questions, tailored advice on overseas entity registration can help connect register information with the particular structure and property circumstances.

How compliance considerations differ by ownership structure and property situation

Begin the review with the event under consideration: a purchase, continued ownership or a proposed disposal. Each raises different questions about the entity’s registration position, ownership information and the property transaction. The correct compliance steps depend on the entity’s structure and the property’s history.

Acquiring, holding or disposing of UK property

Use the comparison below to organise an initial review. It helps identify issues, but it doesn’t determine whether a particular filing or restriction applies. The answer depends on the facts, current rules and the property’s jurisdiction.

Situation Questions to investigate
Proposed acquisition Is the buyer a legal entity incorporated outside the UK? What type of land interest is being acquired, and what registration and transaction steps apply before completion?
Existing holding When and where was the property acquired? Has the ownership or control structure changed since acquisition, and is the recorded information consistent with the current position?
Proposed disposal What is the entity’s current register status? Do the title, entity details and ownership records align, and are any additional steps needed for the planned transaction?

Land transaction work and Register of Overseas Entities duties are related, but they are not interchangeable. A purchase or sale involves property-specific conveyancing and land registration considerations as well as a review of the entity’s register obligations. The steps can vary across England and Wales, Scotland and Northern Ireland. Don’t assume registration alone resolves every transaction requirement, or that the same restriction applies in every case. Companies House guidance on the Register of Overseas Entities provides an official overview of the regime.

Ownership chains, beneficial owners and managing officers

Direct ownership may make it easier to identify the entity that holds the property, but the underlying ownership and control still need review. With layered ownership, trace the chain through each organisation and consider who ultimately owns or controls the overseas entity. A change at an upper level can prompt a fresh assessment of the information relevant to the register, even if the entity named on the property title hasn’t changed.

In plain English, a beneficial owner is a person or entity identified under the applicable rules as owning or exercising relevant control. A managing officer is someone who manages the overseas entity where the rules require that information to be reported. These roles are distinct, and a person’s involvement in day-to-day decisions doesn’t by itself settle how they should be classified. Review the facts against current guidance.

Trusts, nominees and arrangements involving several connected entities need particular care. The legal documents, actual control and reporting requirements may all matter. As part of overseas corporate property ownership compliance, record the structure clearly and assess changes before a property transaction advances. Coordinated advice on overseas entity registration and property matters can help bring these considerations together without treating a general framework as a determination of a specific case.

Overseas Corporate Property Compliance: UK Guide 2026

A practical overseas corporate property compliance checklist

A repeatable process helps identify filing or information issues before they become urgent. For overseas corporate property ownership compliance, assign responsibility, maintain a reliable record trail and treat changes in ownership or property plans as prompts for review. Use the checklist below as a practical sequence, adapting it to the entity’s structure and circumstances.

  1. Identify the legal owner. Record the overseas entity’s full name and jurisdiction of incorporation, along with the UK property it owns or plans to acquire. Check that the entity name matches the relevant corporate and property records.
  2. Map the ownership and control structure. Set out each organisation in the ownership chain and identify the individuals or entities whose ownership or control may be relevant. Note any layers, trusts, nominees or management arrangements that need closer analysis.
  3. Confirm the registration position. Review whether the entity is registered and whether the information held is consistent with its current structure. For practical background on identifying reportable individuals, see this guide to overseas entity beneficial owner registration. For an overview of the registration process connected with UK property, consult the guide to registering an overseas entity for UK property.
  4. Monitor changes and transactions. Treat ownership restructuring, changes to beneficial owners or managing officers, acquisitions and proposed disposals as review triggers. A trigger calls for assessment; it doesn’t automatically mean register information or a filing must change.
  5. Diarise recurring reviews. Assign a named person or team to monitor relevant filing dates and review the ownership information at planned intervals. Include a handover process so responsibility doesn’t disappear when staff or advisers change.

Build a repeatable review and record-keeping process

Keep a controlled file containing ownership charts, source documents used to assess control, submitted forms, confirmation records and relevant correspondence. A dated record of who reviewed the information and what action followed can help the organisation respond consistently if questions arise. Restrict access appropriately and keep the file organised instead of relying on scattered email threads or one person’s notes.

Set retention and access practices with reference to the requirements for each record type. Don’t assume one retention period suits every document. The aim is a usable audit trail that can be updated as the entity, its ownership or its property position changes.

Recognise when a change needs legal assessment

Flag changes early, particularly when a transaction is being planned alongside a restructure or change in control. A review can establish whether the event affects reported information, requires supporting evidence or raises a separate property registration question. Feltons Solicitors LLP advises on overseas entity registration and property matters. Explore legal support for overseas entity registration for a tailored assessment of the next steps.

Some entities manage routine administration internally, using a clear ownership record and a reliable system for monitoring filing dates. This keeps the process close to the people who understand the organisation’s structure. It also requires someone with the time and knowledge to recognise when a change may affect the register or a planned property transaction.

Tailored legal support can help where ownership is layered, the property has a complex history, or an acquisition or disposal is approaching. A legal review can connect Companies House information with the entity’s ownership structure and relevant property-law questions. Neither approach suits every owner. The right level of support depends on the facts, internal resources and confidence in assessing the requirements.

What tailored legal support can help coordinate

Advice can clarify how registration and ownership information relate to the entity’s particular structure, and identify property-law questions arising from its holdings or planned transactions. This can be especially useful when a change in control occurs alongside a restructure or proposed sale, and it isn’t clear which records or obligations need review.

Feltons Solicitors LLP advises on registration of overseas entities and property matters, including conveyancing. This combined perspective helps organise a review around the entity’s circumstances rather than treating register information and property activity as unrelated tasks. Legal advice can guide the process, but the entity remains responsible for the accuracy and completeness of information it provides for its filings.

Prepare for a focused conversation about compliance

A focused discussion is easier when the relevant material is ready. Consider gathering:

  • the overseas entity’s name, jurisdiction of incorporation and registration details
  • property details, including location, ownership history and any planned transaction
  • ownership charts, relevant company records and information about beneficial owners or managing officers
  • previous Register of Overseas Entities submissions and related correspondence

Note known changes, such as a transfer of ownership interests, a new managing officer or a proposed acquisition or disposal. This gives the review a practical starting point and helps distinguish changes that need investigation from routine updates. Keep source documents organised, but don’t assume every event automatically requires a filing: its effect depends on the facts and current requirements.

For tailored guidance on overseas corporate property ownership compliance, discuss overseas entity and property compliance with Feltons Solicitors LLP. A conversation can clarify how the register, ownership structure and property plans fit together, so the next steps can be considered in context.

Make your next compliance decision with clarity

Build overseas corporate property ownership compliance into the organisation’s forward planning rather than treating it as an isolated filing task. Before an ownership change or property decision moves ahead, identify unanswered questions about the entity’s structure, register information and legal steps connected with the property. A considered review helps the organisation decide what needs attention and who should take responsibility.

Where a matter involves both register duties and a property transaction, joined-up advice can bring those considerations into one discussion. Feltons Solicitors advises on overseas entity registration and residential and commercial conveyancing, so relevant points can be considered in the context of the organisation’s property plans.

If you’d value a clear assessment of your circumstances, discuss your overseas entity and property compliance matter with Feltons Solicitors. A considered next step can make a complex issue more manageable and help you plan with confidence.

Frequently Asked Questions

Does an overseas company have to register to own property in the UK?

An overseas legal entity may need to register if it owns or intends to acquire qualifying UK land, such as a freehold or a lease exceeding seven years. The requirement depends on the entity and the property interest, so “overseas company” alone doesn’t settle the question. An individual buying in their own name shouldn’t assume the entity rules apply to them. Review the ownership documents and relevant jurisdiction before proceeding.

Is overseas entity registration a one-off requirement?

No. Registration establishes the entity’s entry on the Register of Overseas Entities, but the entity must continue to review and report its information under the applicable rules. For example, a change in who owns or controls the entity may need assessment even if the property title remains unchanged. Registration also doesn’t remove separate company, tax or land-registration responsibilities, which should be managed separately.

What changes must an overseas entity report to Companies House?

Changes to beneficial ownership, registrable beneficial owners or managing officers should prompt a review of the entity’s register information. The entity should also consider whether other recorded details have changed and what the current filing rules require. For instance, a new parent company may alter the ownership chain even though the registered property-owning entity stays the same. Assess the change against current Companies House guidance before preparing a submission.

How often must an overseas entity update its information?

An overseas entity must file an update statement at least once every 12 months, including when there’s been no change to its beneficial owners. The filing deadline is 14 days after the anniversary of its registration. Keep the anniversary and submission deadline in a central calendar, allowing time to review the information and complete any required verification. Check current Companies House filing guidance before submitting, as processes can change.

Can an overseas entity sell UK property if its register information is out of date?

It may face a restriction that prevents a property transaction from proceeding. A restriction on the title can affect an entity’s ability to sell, lease or charge the property while it remains non-compliant. The practical effect depends on the title, the property’s jurisdiction and the entity’s circumstances. If a sale is planned, review the register position early alongside the conveyancing work rather than assuming an update can wait until completion.

What is the difference between an overseas entity and a beneficial owner?

An overseas entity is the non-UK legal body that may own or acquire qualifying UK land. A beneficial owner is a person or entity identified under the applicable rules as owning or exercising relevant control over that body. For example, a property title may name an overseas company, while another organisation or individual further up its ownership chain may be relevant to beneficial ownership reporting.

Do the same overseas property ownership rules apply across the UK?

No. The Register of Overseas Entities is UK-wide, but land registration systems and property processes differ between England and Wales, Scotland, and Northern Ireland. The property’s location and acquisition history can therefore affect the review. For example, retrospective registration dates differ for some holdings in England and Wales and in Scotland. Don’t assume that a conclusion about a property in one jurisdiction applies to another.

Can a solicitor help manage overseas corporate property compliance?

Yes. A solicitor can help assess how the entity’s ownership structure, register information and property plans fit together, and advise on relevant registration and conveyancing questions. This can be particularly useful before a proposed transaction or after a change in control. Legal support can help organise the review, but the entity remains responsible for ensuring the information it provides is accurate. Feltons Solicitors LLP advises on overseas entity registration and property matters.

Land Registry Overseas Entity ID Requirements: A 2026 Checklist

Land Registry Overseas Entity ID Requirements: A 2026 Checklist

An Overseas Entity ID is a registration reference, not a green light for a UK property transaction. The land registry overseas entity ID requirements involve registering the entity with Companies House and checking that its details support the Land Registry application. An ID alone does not resolve inconsistencies or fill gaps in the information needed for a transaction.

To assess whether the rules apply, look at the entity’s legal status, its UK land interests and the activity proposed. Companies House registration and a Land Registry application are separate steps, so check that the relevant details align before documents are prepared. Doing this early can help identify issues before they affect an application.

This 2026 checklist explains when an Overseas Entity ID may be needed, what information to prepare and what to review before an application is made. It also covers how to check registration details and where legal support can help. Feltons Solicitors LLP advises on overseas entity registration and complex property transactions, helping clients coordinate registration information and conveyancing documents.

Key Takeaways

  • Start by reviewing the entity’s UK land interests and proposed transaction to establish which requirements may apply.
  • Use the land registry overseas entity ID requirements checklist to organise the registration and transaction details before applying.
  • Compare the entity’s legal name, form and identifying information across Companies House records and transaction documents.
  • Check that registration details are current, then review the property title restriction and transaction type before preparing the Land Registry application.
  • A solicitor can help coordinate ownership information, entity records and conveyancing documents when the transaction or ownership structure is complex.

What does a Land Registry overseas entity ID prove?

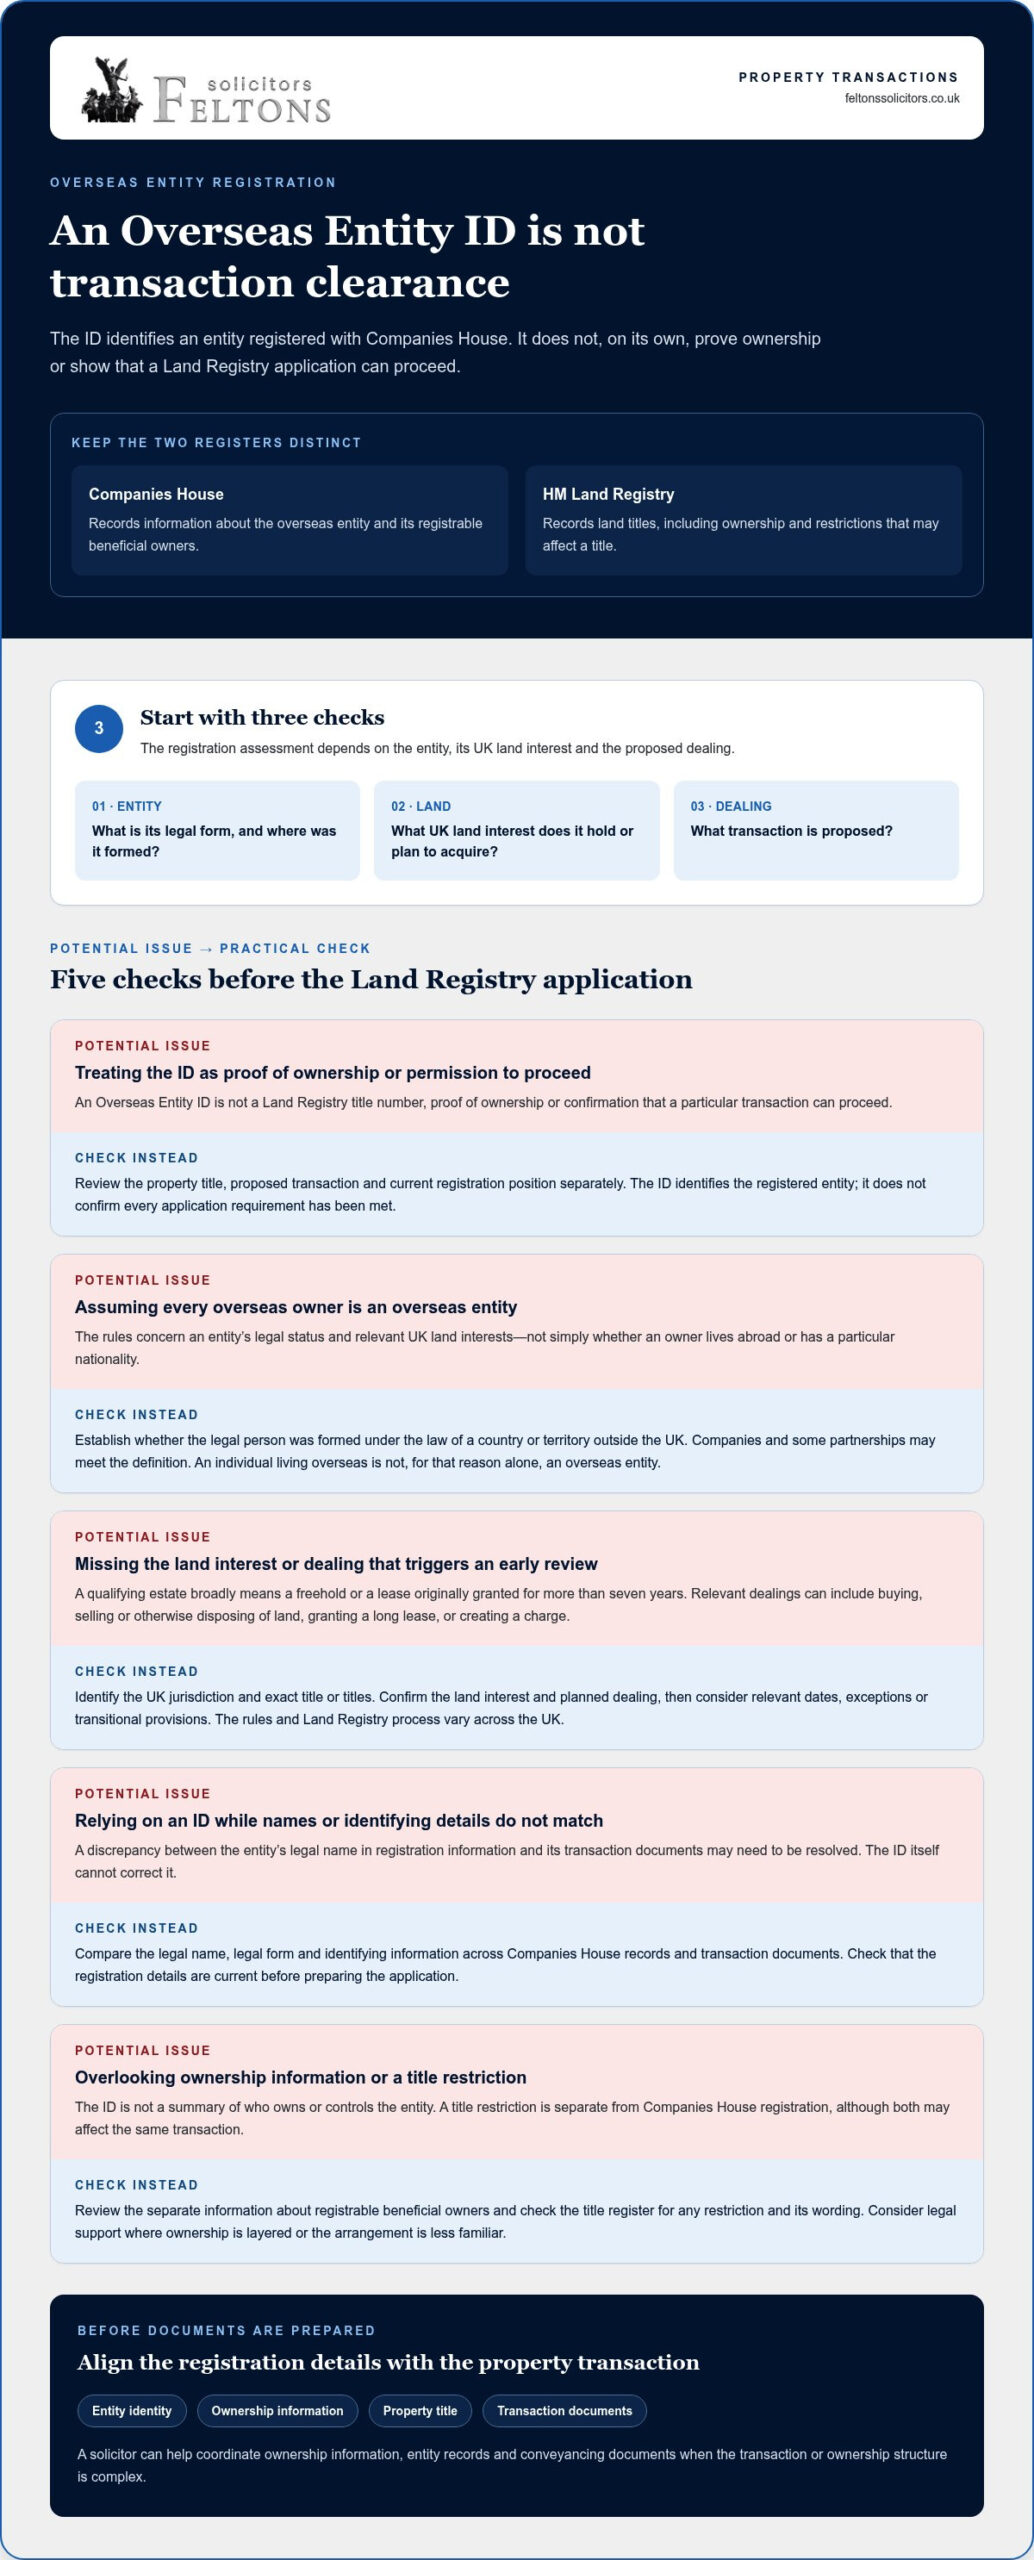
An Overseas Entity ID is the reference issued by Companies House when an overseas entity is entered on the Register of Overseas Entities. It identifies the registered entity. It is not a Land Registry title number, proof of ownership or confirmation that a particular property transaction can proceed.

The two registers serve different purposes. Companies House records information about the overseas entity and its registrable beneficial owners. HM Land Registry records land titles, including ownership and restrictions that may affect a title. An ID may be necessary for a property transaction, but it does not show that every registration or application requirement has been met. Check the title, proposed transaction and current registration position separately.

Which overseas entities are within the registration rules?

An overseas entity is a legal person formed under the law of a country or territory outside the UK. Companies and some partnerships may meet this definition. The rules concern the entity’s legal status and relevant UK land interests, not simply whether an owner lives abroad or has a particular nationality.

An individual who lives overseas is not, for that reason alone, an overseas entity. However, an individual may be a beneficial owner of an entity, which is a separate part of the registration analysis. The entity’s legal form and the law under which it was formed can affect whether the rules apply. Less familiar arrangements and layered ownership structures may need case-specific legal analysis before a transaction proceeds.

What is the difference between an entity ID and an owner’s details?

The ID is a reference for the registered entity. It is not a summary of the people who own or control it, and it does not replace the information required about registrable beneficial owners. Those details are assessed separately as part of the registration process.

Beneficial ownership analysis looks at relevant information about people or legal entities that own or exercise control over the overseas entity. The assessment depends on the structure and applicable rules. An ID alone does not establish that ownership information is complete, current or suitable for the transaction.

  • Entity identity: the overseas entity’s legal name and form.
  • Entity reference: the Overseas Entity ID issued after registration.
  • Ownership and control: the separate information required about registrable beneficial owners.

When checking the land registry overseas entity ID requirements, keep these elements distinct. A mismatch between the entity’s legal name in registration information and its transaction documents may need to be resolved. The ID itself cannot correct that discrepancy. Feltons Solicitors advises on overseas entity registration and complex property transactions, helping clients align ownership information with conveyancing documents.

Who needs an overseas entity ID for a UK property transaction?

Start with three questions: what kind of entity is involved, what interest in UK land does it hold or plan to acquire, and what transaction is proposed? Under the overseas entities regime, a legal entity governed by the law of a country or territory outside the UK may need to register if it owns or seeks to acquire a qualifying estate. Broadly, this means a freehold or a lease originally granted for more than seven years. The rules and Land Registry process vary across the UK, so identify the relevant jurisdiction before assessing the transaction.

This is a starting point, not a universal answer. The land registry overseas entity ID requirements can depend on the property interest, transaction date, title and applicable exemptions or transitional provisions. The regime also covers certain earlier acquisitions, with relevant dates varying across the UK. Review the transaction and title rather than relying on a general summary.

Which property dealings should prompt an early eligibility check?

Check the position early if an overseas entity is buying a qualifying estate, selling or otherwise disposing of relevant land, granting a long lease, or creating a charge over it. The effect of the rules depends on the dealing and circumstances. Having an ID does not automatically satisfy every Land Registry requirement.

Review the property title alongside the Companies House registration. A restriction on a title is a Land Registry entry that can limit registration of specified dispositions unless its stated condition is met. It is separate from registration on the Register of Overseas Entities, although both may affect the same transaction.

  • Identify the relevant UK jurisdiction and exact title or titles.
  • Confirm whether the entity owns or proposes to acquire a freehold or qualifying lease.
  • Describe the planned dealing, such as a transfer, lease or charge.
  • Review the title register for a restriction and note its wording.
  • Check relevant dates and whether an exception or transitional provision may apply.

How can ownership structures change the assessment?

Look beyond the name shown on the title. An overseas entity may be owned through several companies, or control may be exercised through arrangements that are not obvious from a simple ownership chart. Registration analysis must identify any registrable beneficial owners under the applicable tests. Shareholders and directors are not automatically decisive in every case.

Trust arrangements need particular care. Depending on the facts and rules, trustees and other people connected with a trust may be relevant to the ownership or control assessment. The treatment differs between structures. Record the chain of ownership and control, and flag trusts, intermediate entities or disputed control for legal analysis before preparing documents.

Where the structure or title raises questions, overseas entity registration and conveyancing support can help align the ownership analysis with the proposed property dealing and its Land Registry requirements.

What information should you check before relying on an overseas entity ID?

Review the details before relying on the ID in a property transaction. A valid-looking reference could be linked to the wrong entity, or the records may no longer reflect its legal name or ownership structure. The land registry overseas entity ID requirements are one part of the check: compare the Companies House record with the title and transaction documents.

Consistent records make it easier to show that the registered entity, property title and application documents refer to the same legal person. Differences in spelling, legal form or identifying details may need an explanation or correction. Deal with discrepancies early rather than waiting until the application is being prepared.

How should the entity’s registration details be checked?

Start with the Companies House Register of Overseas Entities. Find the entity and compare its record with the proposed transfer, lease or charge. Check the exact legal name and form, then confirm that the Overseas Entity ID belongs to that entity, not another group company with a similar name. Review the registration details for changes since the ID was issued.

Check the entity’s current position as well as its original registration. Overseas entities must file an annual update statement within 14 days of each registration anniversary, even if there have been no changes. Review the Companies House record for the latest filing and the next update date. Confirm the evidence and checking process required for the particular application against current Companies House and HM Land Registry guidance.

What owner and control information may need attention?

Compare the ownership and control information on the register with the entity’s current structure. Trace intermediate companies and consider whether changes in ownership, control or relevant personal details have been reflected in the required filings. Investigate missing or inconsistent entries rather than assuming they are immaterial. Trust arrangements may also require careful analysis. The people and information relevant to the disclosure depend on the circumstances and applicable rules.

  1. Match the entity: compare the exact legal name, legal form and identifying details across the Companies House record and transaction documents.
  2. Check the ID: confirm it is recorded against the entity that will be party to the transaction.
  3. Review current status: check registration details, the latest update statement and its next due date.
  4. Compare ownership: review beneficial owner and control information against the current structure, noting changes or uncertainties.
  5. Check the property records: examine the relevant HM Land Registry title information and ensure the application documents address any restriction.
  6. Organise supporting material: keep relevant records together and submit sensitive information only through the appropriate official process.

For complex structures, a solicitor can help reconcile entity records, beneficial ownership information and conveyancing documents before an application is lodged. This review can identify inconsistencies early and clarify which points need further attention under the current rules. In addition, individuals managing cross-border assets should keep abreast of broader statutory obligations, taking note of any recent hmrc tax warning regarding financial compliance and reporting.

Land Registry Overseas Entity ID Requirements: A 2026 Checklist

How do overseas entity ID requirements affect a Land Registry application?

Companies House registration and a Land Registry application are separate steps. Companies House records the overseas entity and issues its Overseas Entity ID. HM Land Registry deals with the property title and applications to register transactions. Having an ID does not, by itself, establish that an application meets the requirements for the title or the particular dealing.

The land registry overseas entity ID requirements need to be considered alongside the title register, transaction and supporting documents. A restriction on the title may specify conditions that must be satisfied before a disposition can be registered. Its wording matters. Do not assume that the same evidence or process applies to every sale, lease, charge or other dealing.

What should be checked on the title and application?

Begin with the current title information and identify any restriction referring to an overseas entity. Compare the registered proprietor and transaction parties with the Companies House details. A group may have several overseas companies with similar names, so confirm that the ID belongs to the legal entity named in the transaction and title records.

Next, establish which Land Registry application and evidence are appropriate for the transaction. Requirements can depend on the title, restriction and nature of the disposition. Check the current HM Land Registry guidance, forms and evidence standards rather than reusing documents from a different matter. The September 2026 version of Practice Guide 78 may require evidence that an overseas entity has existed continuously since it was first registered as proprietor. Assess whether that point is relevant to the title and application.

  • Read the restriction on the title and note the condition it sets.
  • Match the entity named on the title and in transaction documents to its Companies House record and ID.
  • Identify the transaction type and the application being made.
  • Check current Land Registry guidance for the applicable evidence and filing requirements.

What can happen if the ID or application details do not match?

An inconsistency may prompt HM Land Registry to raise questions or requisitions, or delay consideration of the application. The outcome depends on the issue and relevant rules. An administrative difference is not necessarily the same as a substantive eligibility or compliance problem, but it should be explained or corrected through the appropriate process.

For example, if a transfer names “Northstar Holdings Ltd” but the title or Companies House record uses a different legal name, the application may need clarification or supporting evidence. The mismatch could be a naming discrepancy, or it could indicate that the ID for a different entity has been supplied. These situations require different responses, so investigate the cause rather than making assumptions.

Where a restriction, ownership structure or supporting evidence raises questions, get legal support with your Land Registry application to coordinate registration details and conveyancing documents before submission.

A checklist helps organise the facts, but it cannot replace advice on the specific entity, title and transaction. The land registry overseas entity ID requirements involve separate Companies House and Land Registry processes. A solicitor can bring the records together, identify gaps in ownership information and assess how a title restriction applies to the proposed dealing.

Coordination is especially useful when registration details and conveyancing documents were prepared at different times or by different parties. For example, a change to an entity’s legal name or control structure may need to be reflected in relevant records and considered alongside the transaction documents. Legal review can identify what needs attention and which steps apply, without assuming a particular outcome or timetable.

When is tailored legal advice particularly useful?

Consider transaction-specific advice if ownership runs through several entities, a trust is involved, the entity’s details have changed, or the transaction is time-sensitive. These circumstances can raise questions that a general checklist cannot resolve by itself.

A solicitor can review the entity and ownership information alongside the title restriction and planned dealing. This joined-up assessment can help distinguish a record discrepancy from a wider eligibility or compliance issue, and clarify what to address before an application is prepared. Feltons Solicitors advises on overseas entity registration and complex property transactions, bringing registration and conveyancing considerations into the same discussion.

What should you have ready for an initial discussion?

You do not need to resolve every issue before seeking advice. A concise set of core details helps focus the discussion and identify what further information may be needed.

  • Entity details: the exact legal name, legal form and jurisdiction in which the entity is formed.
  • Registration reference: the Companies House Overseas Entity ID, if one has been issued, and any known update or record changes.
  • Property information: the relevant title number or title details, together with a copy of the title register if available.
  • Transaction outline: a short description of the proposed purchase, sale, lease, charge or other dealing, including any key dates.
  • Ownership and control: a simple outline of the ownership chain, any trusts, changes in control and unresolved questions.

Keep supporting documents organised, but avoid sending sensitive ownership material through informal or insecure channels. Appropriate handling depends on the information and why it is being provided.

For broader background on identifying the people connected with an overseas entity, the Overseas Entity Beneficial Owner Registration guide can help explain the ownership side of the checklist. For a UK property transaction, Feltons Solicitors can discuss how the registration position, title details and conveyancing documents fit together.

Put the next property step on a clear footing

Before the transaction moves further, turn your checklist into a working file. Record unanswered questions, identify who can provide the missing information and keep relevant documents together. This gives everyone involved a clearer basis for addressing registration and application issues as they arise.

The land registry overseas entity ID requirements can intersect with ownership structures and conveyancing documents in ways that call for a transaction-specific review. That assessment can help you identify what needs attention next, rather than relying on assumptions about how a previous matter was handled.

Feltons assists with overseas entity registration, residential and commercial conveyancing, and complex property transactions. Discuss your overseas entity and property registration requirements with Feltons to consider the appropriate next steps for your matter.

With the relevant details organised and issues identified, you can move forward with greater clarity about the registration and application requirements.

Frequently Asked Questions

What is a Land Registry overseas entity ID?

It is the reference Companies House issues after registering an overseas entity on its Register of Overseas Entities. The ID identifies the entity in that register. It is not a property title number or confirmation that every requirement for a particular transaction has been met. For example, an entity’s ID does not explain whether a restriction on a title affects a proposed transfer. Check the current rules and application requirements for the specific property and transaction.

Does an overseas entity need an ID to buy UK property?

An overseas entity may need to register and obtain an ID before a relevant property transaction can proceed, depending on its circumstances and the applicable rules. The land registry overseas entity ID requirements are not a single test that applies identically to every buyer. Establish the entity’s legal status, the property interest being acquired and whether an exception may be relevant. The title and current Companies House guidance can help identify the checks needed.

Can an overseas entity sell UK property without an ID?

That depends on the title, proposed sale and rules that apply to the entity. A restriction on the title may affect whether HM Land Registry can register a disposition, but its wording and any relevant exception need to be considered in context. Review the title register and current Land Registry guidance before progressing. A conveyancing solicitor can assess whether the entity’s registration position and sale documents address the relevant requirements.

What information is needed to apply for an overseas entity ID?

Registration generally requires information about the overseas entity and, where applicable, its registrable beneficial owners or managing officers. The details depend on the entity’s legal form and ownership arrangements. For example, a structure involving intermediate companies may require tracing ownership and control rather than considering only the immediate shareholder. Check the latest Companies House guidance before preparing the application, particularly if trusts or unusual control arrangements are involved.

Is an overseas entity ID the same as a Companies House number?

No. An Overseas Entity ID relates specifically to registration on the Register of Overseas Entities. It is distinct from other Companies House identifiers and from a Land Registry title number, which relates to a property title. For a transaction, use the precise reference requested and compare it with the entity’s official register entry. Similar names or numbers within a corporate group make this check particularly important. Do not assume one identifier can replace another.

What happens if the overseas entity ID is incorrect on a Land Registry application?

An incorrect or inconsistent ID may lead HM Land Registry to ask for clarification or raise a requisition, and could delay registration depending on the circumstances. Compare the application against the entity’s Companies House record to establish whether the error is a typing mistake or relates to a different entity. If the application has already been submitted, establish the appropriate correction process promptly. Where completion arrangements are time-sensitive, seek advice on the specific application.

Do beneficial owners need their own overseas entity ID?

No. The Overseas Entity ID identifies the registered entity, not each beneficial owner. However, registration may require information about registrable beneficial owners and other relevant people, depending on the ownership structure and applicable tests. For example, an individual who controls an entity through another organisation may need to be considered as part of the ownership analysis. Keep the entity’s reference separate from disclosure information and review complex arrangements carefully.

How long does it take to get an overseas entity ID?

There is no fixed timeframe that applies to every application. Processing can vary, and the completeness of the submission, verification requirements and complexity of the ownership structure may affect progress. Check current Companies House service information when planning, and allow time to address questions or correct information before a property transaction reaches a critical stage. If timing could affect contractual or completion arrangements, seek advice based on the transaction’s circumstances.