Did you know that competing valuation experts in UK matrimonial cases often produce figures that differ by as much as 50% for the same company? You’ve spent years, perhaps decades, building your enterprise from the ground up, so it’s entirely natural to feel a sense of dread that a legal process might dismantle your life’s work. The prospect of business assets valuation in divorce often brings more questions than answers, particularly when technical terms like “personal goodwill” and “earnings normalisation” enter the conversation.
We understand that you need more than just a spreadsheet; you require a strategy that respects the reality of your operations. This guide provides the clarity you need to protect your commercial interests whilst ensuring a settlement that is both fair and legally robust. We’ll explore the latest 2026 valuation methodologies, the critical role of forensic accountants, and the practical steps you can take to ensure your business continues to trade successfully long after your financial arrangements are finalised.
Key Takeaways
- Understand why the court classifies your company as a matrimonial asset and how it balances current capital value against future income potential.
- Navigate the role of the Single Joint Expert to ensure the business assets valuation in divorce is conducted with the forensic precision required for a fair settlement.
- Compare earnings-based and asset-based methodologies to anticipate which calculation best reflects your firm’s commercial reality and industry standing.
- Identify critical valuation challenges, such as minority shareholding discounts and the risk of “double dipping” into your income stream.
- Explore pragmatic settlement options like asset offsetting and structured payments that allow you to protect your business’s continuity whilst meeting your legal obligations.
Why Business Assets Are Central to Divorce Financial Settlements
In England and Wales, the court treats a business as much more than a career; it’s a significant matrimonial asset. Whether you are a majority shareholder or a silent partner, your interest in a company is a tangible piece of the matrimonial pot. The court’s primary objective is to achieve a fair outcome, which often starts with an equal split of assets accrued during the marriage. This is known as the sharing principle. It assumes that both parties contributed equally to the family’s wealth, even if one spouse was the sole driver of the business whilst the other managed the household.
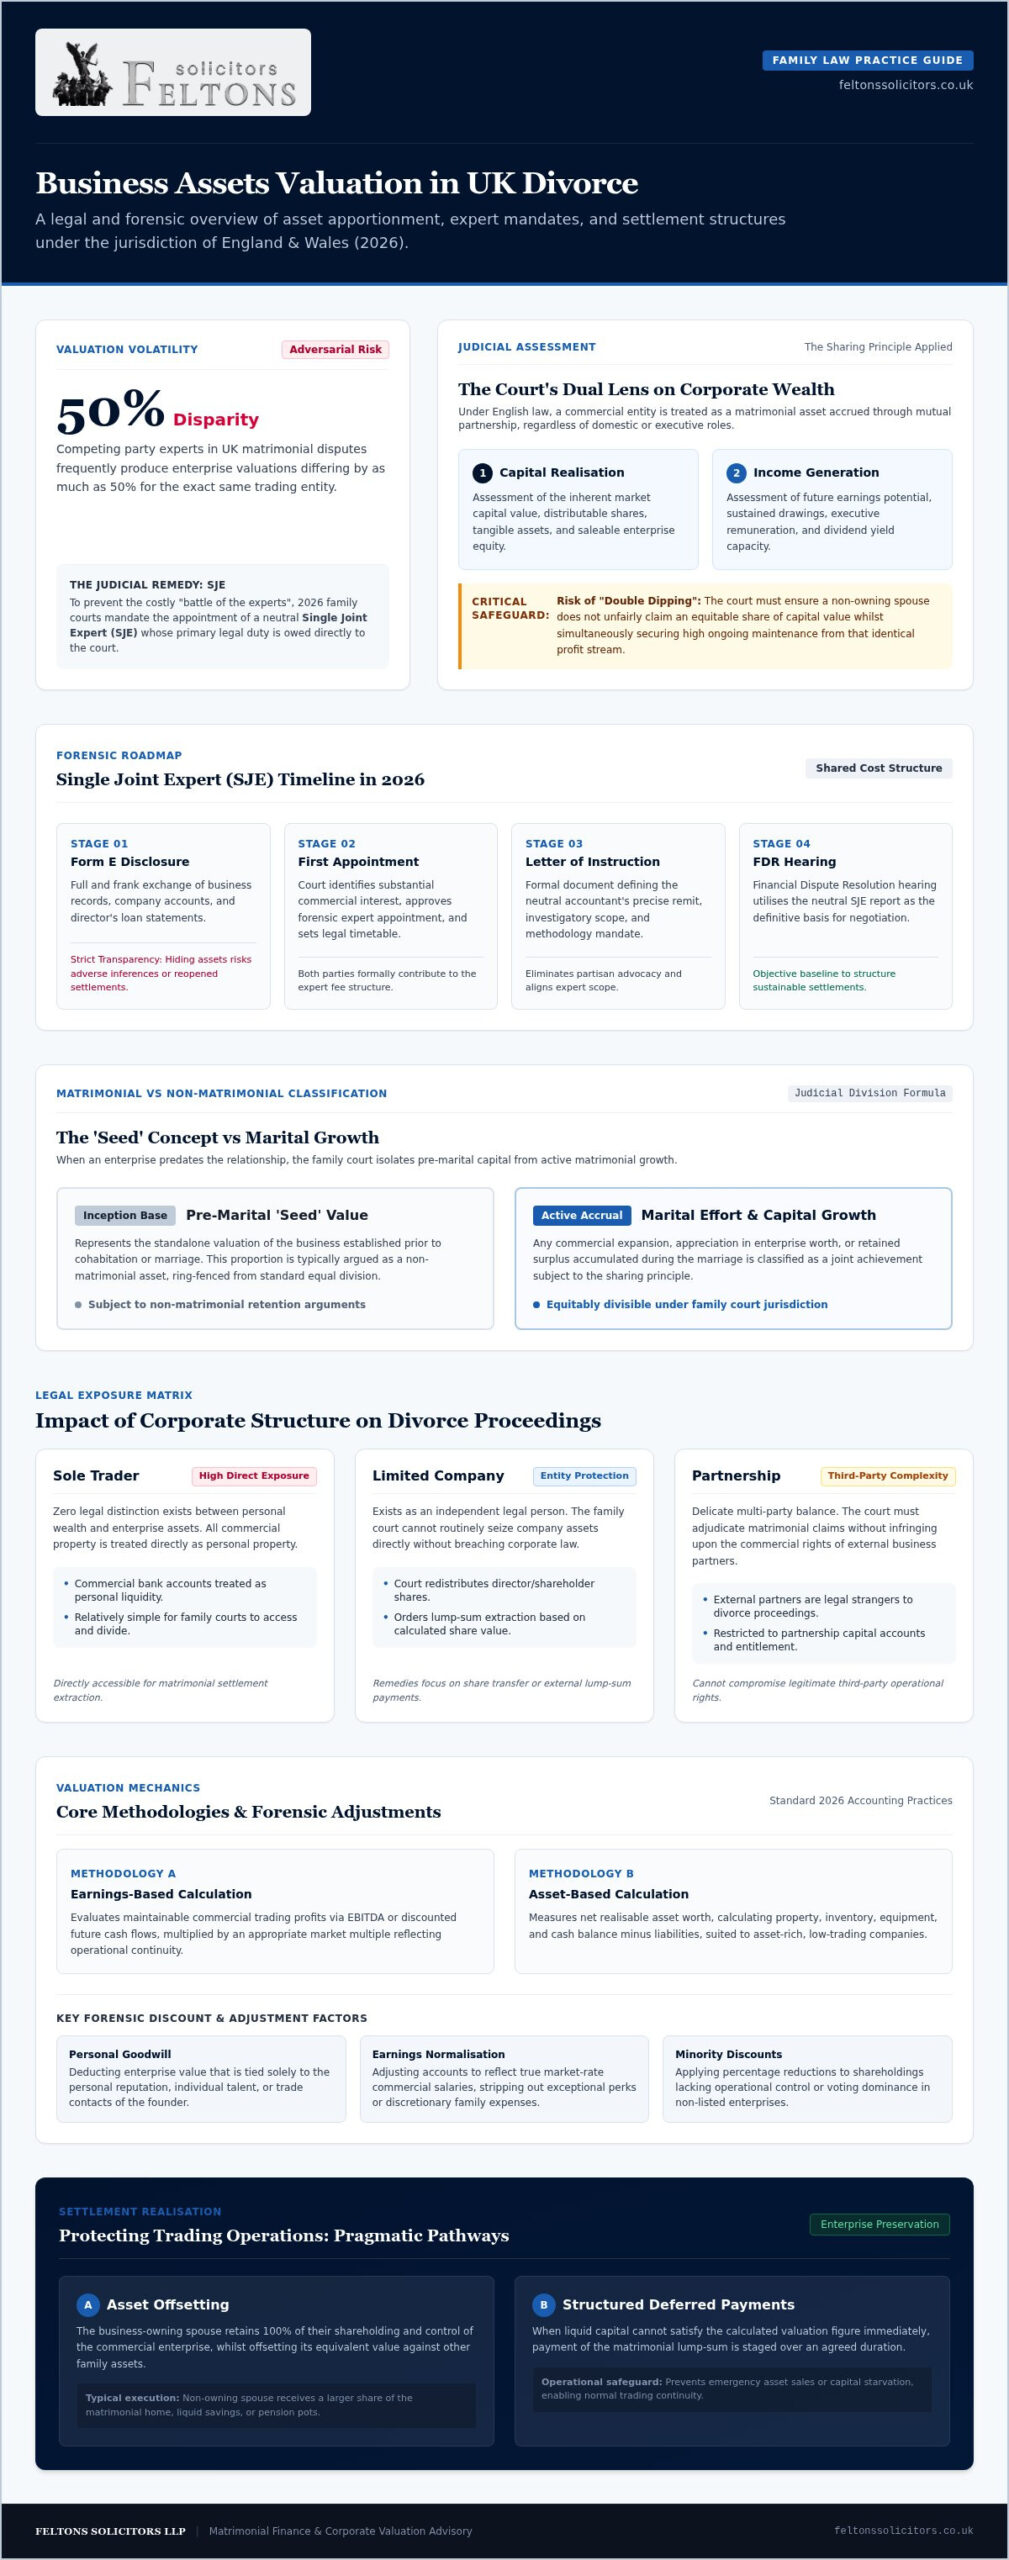
Understanding business valuation principles is vital because the court views your company through two distinct lenses. It sees a capital asset with an inherent market value and a reliable source of future income. This dual nature often complicates the business assets valuation in divorce, as the court must ensure that one spouse doesn’t receive an unfair advantage by claiming both a share of the capital and high maintenance payments based on the same profit stream.
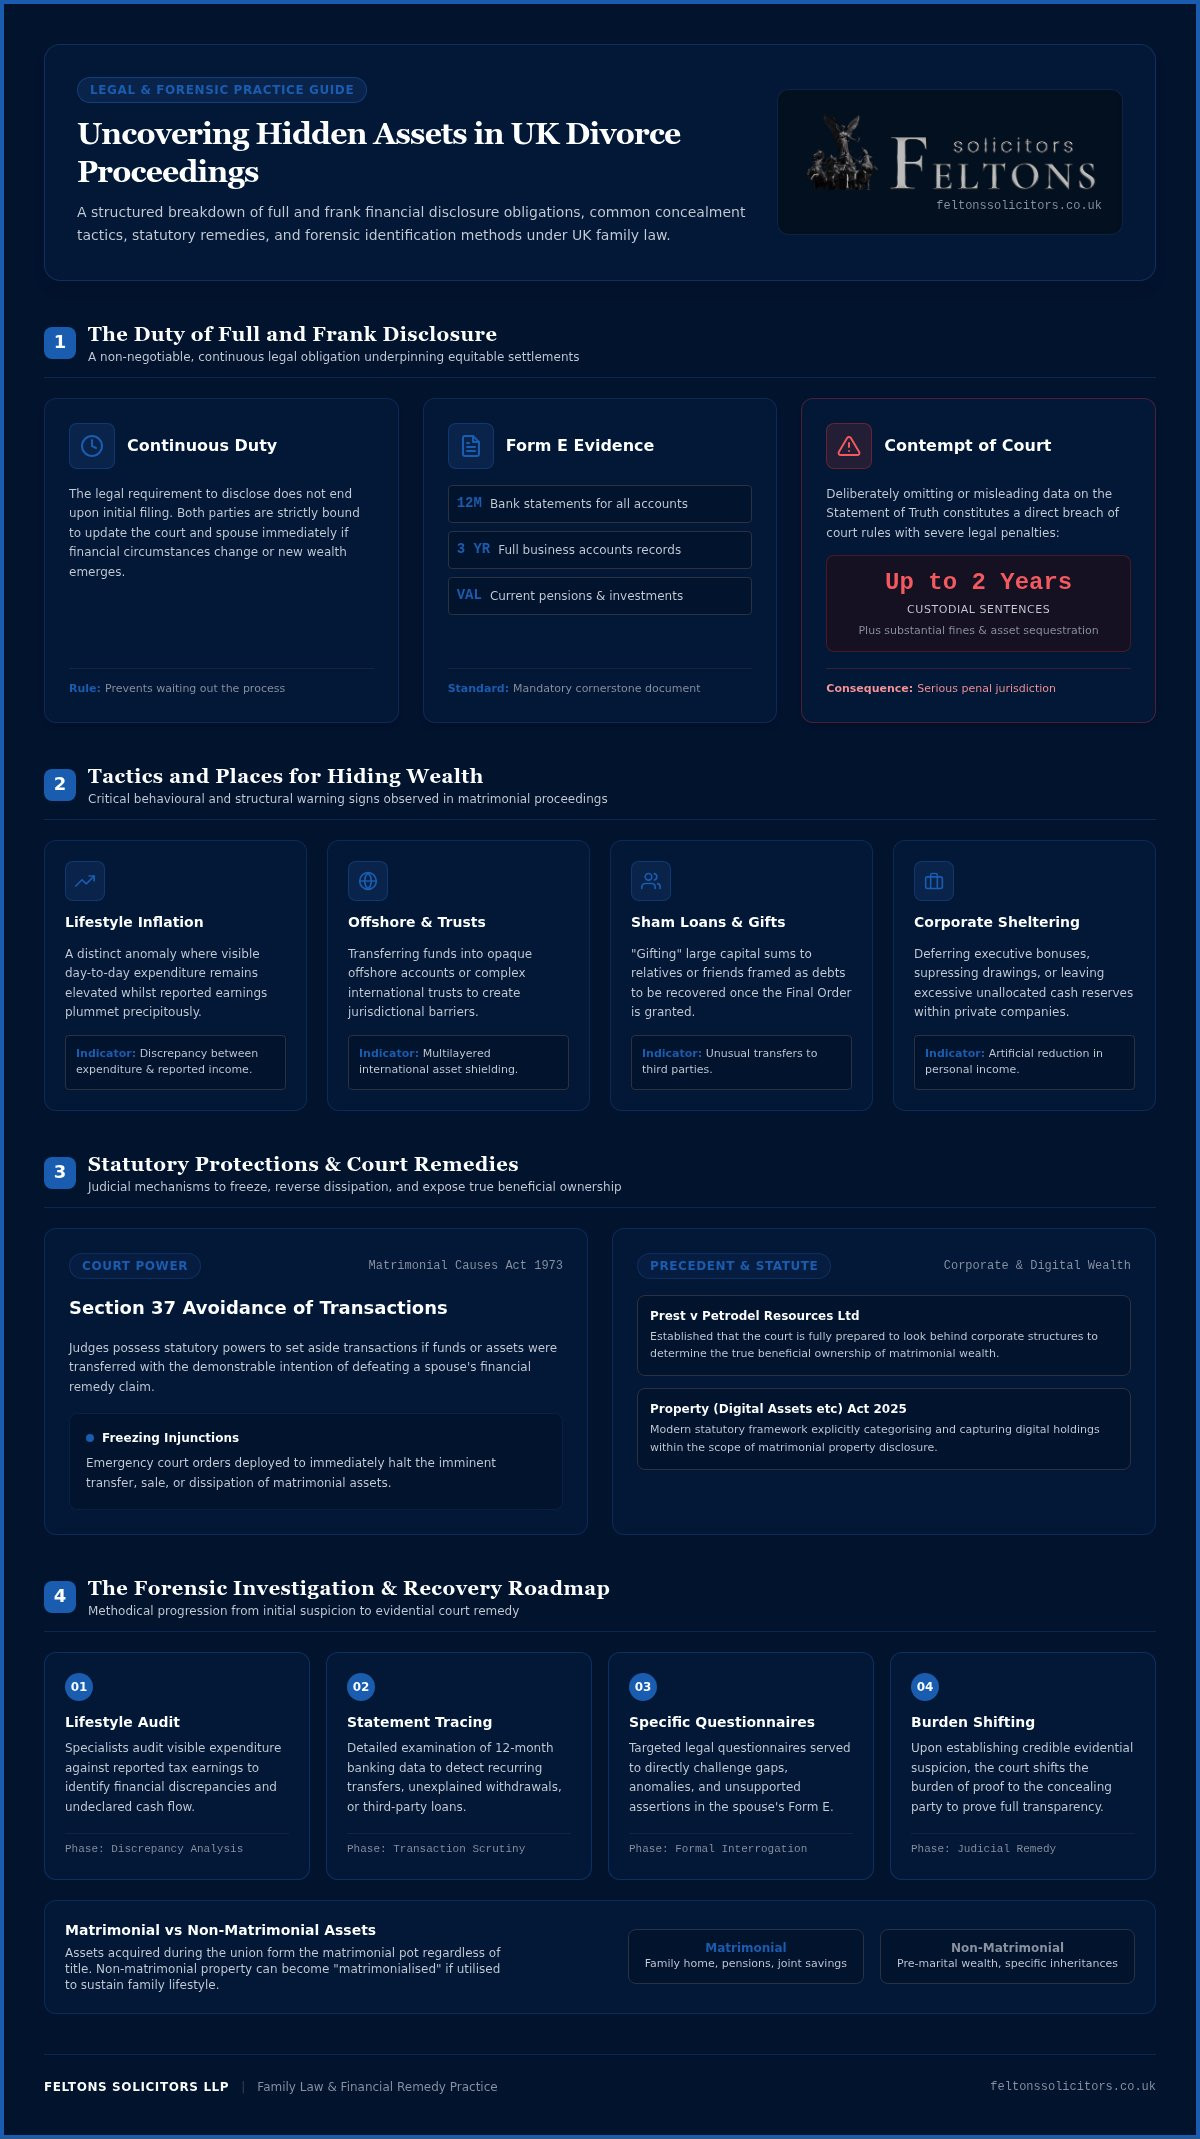
Transparency is the foundation of this process. Every party must provide full and frank financial disclosure via Form E. This document requires you to list all business interests, including recent accounts and director’s loan statements. Attempting to obscure the true value of a company doesn’t just damage trust. It can lead to the court drawing adverse inferences or even reopening settlements years later if they discover assets were hidden.
Matrimonial vs Non-Matrimonial Business Assets
Distinguishing between assets built during the marriage and those established before the wedding is a complex task. If you started your company before you met your spouse, you might argue it’s a non-matrimonial asset. However, if the business grew significantly during your years together, the court often views that active growth as a joint achievement. The ‘seed’ of a business represents its pre-marital inception value, whereas the current valuation reflects the total marital effort and capital growth subject to court division.
The Impact of Business Structure on Divorce
Your company’s legal structure dictates how the court approaches the valuation and eventual settlement. Different entities offer different levels of protection and complexity:
- Sole traders: There is no legal distinction between your personal finances and your business. The court treats all business assets as your personal property, making them relatively easy to access during a settlement.
- Limited companies: The business is a separate legal entity. Whilst the court cannot usually seize company assets directly, it can redistribute your shares or order you to pay a lump sum based on their value.
- Partnerships: These are particularly delicate. The court must balance your spouse’s claims against the legal rights of your business partners, who are considered strangers to the divorce proceedings.
The Process of Valuing a Business: How It Works in 2026
Securing an accurate valuation is rarely a matter of simple arithmetic. In the UK court system, the preferred method for establishing the worth of a company is the appointment of a Single Joint Expert (SJE). This individual is a neutral forensic accountant who owes a primary duty to the court rather than to either spouse. By 2026, the courts have become increasingly strict about the use of SJEs to prevent the “battle of the experts” that previously inflated legal costs and extended litigation timelines. This impartial approach ensures that the business assets valuation in divorce remains grounded in objective data rather than partisan advocacy.
The timeline for this process usually begins after the first exchange of financial disclosure (Form E). Once the court identifies that a business interest exists, it will set a deadline for the expert’s report, typically falling between the First Appointment and the Financial Dispute Resolution (FDR) hearing. Whilst the fees for a high-calibre forensic accountant represent a significant investment, instructing a single expert allows both parties to share the cost. It also provides a stable foundation for negotiations. If you’re concerned about how an expert might interpret your company’s books, seeking expert guidance on divorce and financial arrangements early can help you prepare for the disclosure phase.
Instructing the Single Joint Expert (SJE)
The success of a valuation depends heavily on the “Letter of Instruction.” This document defines the expert’s remit, including which valuation methods they should use and which specific assets they must investigate. Both legal teams must agree on this letter to ensure the expert has full access to the necessary financial records. If you believe the final report contains factual errors or flawed assumptions, your solicitor can submit written questions to the SJE under Part 25 of the Family Procedure Rules. However, successfully challenging an SJE’s conclusion usually requires proving a significant oversight or a departure from established business valuation principles.
Information the Valuer Will Require
A forensic accountant doesn’t just look at a single tax return. They typically require at least three to five years of statutory accounts to identify trends, along with current management accounts and future order books to assess the company’s trajectory. They will also look for “add-backs,” such as personal expenses run through the business, to determine the true maintainable earnings. A mere snapshot of today’s balance sheet is insufficient for a 2026 divorce settlement because it fails to account for the long-term sustainability of the company’s earnings or the impact of shifting market conditions on future cash flow.
Common Methodologies for Business Asset Valuation
Selecting the appropriate methodology is often the most contentious phase of the financial remedy process. In the Family Court of England and Wales, the standard applied is typically “Fair Value” rather than “Open Market Value.” Whilst market value reflects what a third party might pay in a hypothetical sale, fair value accounts for the ongoing benefit the business provides to the owner as a going concern. This distinction is vital; it ensures the valuation reflects the reality of the business’s worth to the family unit, even if there’s no immediate intention to sell.
For most trading companies, an earnings-based approach is the gold standard. This involves calculating the company’s maintainable earnings, often expressed as EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortisation), and applying a specialised “multiple” based on industry benchmarks. In contrast, for property investment firms or businesses with significant tangible holdings, an asset-based valuation is more appropriate. This focuses on the Net Asset Value (NAV), adjusting the balance sheet to reflect the current market value of all holdings minus liabilities. If you hold a minority stake, the valuer might use a dividend-based approach, focusing on the actual income stream you receive rather than the total value of a company you cannot control.
The complexity of these calculations is why business assets valuation in divorce requires such a methodical approach. It’s not just about the numbers on the page; it’s about how those numbers translate into a sustainable settlement.
Understanding Goodwill: Personal vs Corporate
Goodwill represents the value of a business beyond its tangible assets. However, the court makes a sharp distinction between corporate goodwill, which is tied to the brand and systems, and personal goodwill, which is tied to your individual reputation. If the business cannot function or be sold without your specific skills, that personal goodwill is often excluded from the divisible capital pot. A high level of personal goodwill can significantly lower the final capital valuation, as it suggests the business has limited transferable value to a third party.
Liquidity and the Ability to Pay
A high “paper value” doesn’t always translate to cash in the bank. The court is acutely aware that stripping a business of its working capital to fund a divorce settlement could cripple its future. Valuers will assess the company’s liquidity and its capacity to borrow against its assets to facilitate a buyout. Balancing these competing needs is a core part of our Guide to Divorce and Financial Arrangements, which helps business owners navigate the tension between asset division and commercial survival.
Challenges and Objections in Business Valuations
Even with the appointment of a Single Joint Expert, the path to a final financial order is often blocked by complex legal objections. A report provides a figure, but it doesn’t always provide a solution that feels equitable to both parties. One of the most significant pitfalls in business assets valuation in divorce is the “double dip.” This occurs when a spouse claims a share of the business’s capital value, which is calculated based on future earnings, and then requests spousal maintenance from those same earnings. Courts in 2026 are increasingly vigilant about this, as it effectively forces the business owner to pay out on the same profit stream twice. Successfully navigating this requires a legal team that can distinguish between capitalised income and maintainable dividends.
Beyond the double-dipping trap, the argument of “special contribution” remains a frequent but rarely successful tactic. Unless the business owner can prove they possess a “genius” quality that generated exceptional wealth, the court almost always adheres to the sharing principle. Similarly, the treatment of director’s loan accounts can create friction. If you have borrowed money from your company, that debt is an asset of the business but a liability for you personally. Forensic accountants will scrutinise these accounts to ensure they aren’t being used to artificially deflate the value of the matrimonial pot.
The Minority Shareholder Discount
A common point of confusion is why a 10% shareholding isn’t simply worth 10% of the company’s total value. In the world of private companies, a minority stake lacks “control” and “marketability,” meaning the shareholder cannot force a sale or dictate dividend policy. Forensic accountants often apply a discount, which can range from 25% to over 50% depending on the level of influence the shares provide. However, an exception often exists for “quasi-partnerships.” These are small companies that function like partnerships despite their corporate structure, where the court may decide that no discount should be applied because the parties always intended to share equally.
Addressing Allegations of Financial Non-Disclosure
Attempting to hide assets or run personal “lifestyle” expenses through the company books is a high-risk strategy that usually backfires. Forensic accountants are trained to spot anomalies, such as family holidays or school fees categorised as business expenses, and they will “add back” these sums to the company’s profit. If the court finds that you have been less than transparent, it has the power to draw “adverse inferences.” This means the judge can assume your business is worth significantly more than you claim. To ensure your disclosure is handled with the necessary precision and discretion, you should instruct a specialist solicitor for your financial arrangements at the earliest opportunity.
Protecting Your Business and Negotiating the Settlement
Once the business assets valuation in divorce is finalised, the focus shifts from calculation to implementation. The court generally follows the “Golden Egg” principle. It prefers not to kill the goose that lays the golden eggs. If a business provides the income necessary to support both parties and their children, judges are often reluctant to order a sale that would destroy that income stream. Instead, they look for creative ways to satisfy the non-owning spouse’s claims whilst ensuring the company remains a viable trading entity.
One of the most effective tools is offsetting. This involves the business owner “trading” their share of other matrimonial assets, such as the family home or liquid savings, in exchange for retaining full ownership of the company. If there isn’t enough equity elsewhere to achieve a clean break, a structured settlement may be negotiated. This allows for a lump sum to be paid in instalments over several years, protecting the company’s cash flow whilst providing the other spouse with their fair share over time. These arrangements require careful drafting to ensure they are legally binding and enforceable.
Alternatives to Selling the Business
Pension offsetting is another sophisticated route, where one party keeps their pension intact whilst the other retains the business interests. Whilst transferring shares to a spouse is technically possible, it’s often fraught with commercial risk. Becoming “accidental” business partners after a divorce can lead to operational deadlock and further litigation. For future protection, a well-drafted shareholders’ agreement or a pre-nuptial agreement can define exactly how a business should be valued and divided. This forward-thinking approach is a key part of A Complete Guide to Estate Planning, which ensures your commercial legacy remains secure.
Why Expert Legal Representation is Essential
Feltons Solicitors LLP acts as your sophisticated guide through these high-stakes negotiations. We provide the calm, steady presence needed when personal emotions collide with complex commercial interests. Our team prioritises a people-first philosophy, ensuring that whilst the technical aspects of the business assets valuation in divorce are precise, the human impact of the settlement is never forgotten.
To begin the process with professional support, your next step should be a discreet consultation to review your business structure and disclosure requirements. We’ll help you navigate the complexities of asset protection with the quiet confidence that comes from years of expertise in complex financial litigation. Protecting what you’ve built requires more than just a lawyer; it requires a partner who values your privacy and understands the nuances of your industry.
Securing Your Commercial Legacy
The complexities of business assets valuation in divorce require a balance of forensic accuracy and strategic foresight. Navigating the transition from identifying matrimonial assets to finalising a settlement involves understanding the nuances of the Single Joint Expert process and the “Golden Egg” principle. By prioritising transparency and selecting the correct valuation methodology, you can ensure your company remains a viable entity whilst meeting your legal obligations. This approach protects your life’s work from unnecessary disruption and provides a stable foundation for the future.
Feltons Solicitors provides a boutique level of care combined with national expertise in complex financial arrangements. Our specialists offer the discreet and professional legal guidance necessary to resolve high-stakes disputes with quiet confidence. We act as your sophisticated guide through every stage of the negotiation, ensuring the human impact of our work is never forgotten. Secure your business’s future with Feltons Solicitors and move forward with a resolution that respects your commercial achievements. You don’t have to navigate these complexities alone; your interests are in capable hands.
Frequently Asked Questions
Will I have to sell my business to pay my ex-spouse in a divorce?
It is rare for a court to order the sale of a business if it provides the primary income for the family. Judges prefer to keep the “golden egg” intact to ensure ongoing maintenance and financial stability. Instead, you might offset the business value against other assets like the family home or arrange a structured payout over several years. This allows the business to continue trading whilst satisfying the legal requirements of the settlement.
How long does a forensic valuation of a business usually take?
A forensic valuation typically takes between four and twelve weeks to complete once the expert has all the necessary data. This timeline depends on the complexity of your company structure and the speed at which you provide financial records. Delays often occur if there are gaps in the statutory or management accounts. It is vital to start this process early in the financial remedy proceedings to avoid pushing back your court dates.
What happens if my business is currently making a loss?
A loss-making business still has a value for divorce purposes, though it may be calculated differently. If the company is not profitable, the valuer might use an asset-based approach, focusing on the Net Asset Value (NAV) of its equipment, property, or stock. In some cases, a business might have “hope value” if it possesses unique intellectual property or a market position that suggests a return to profitability in the near future.
Can I use my own accountant to value the business for the court?
The court usually requires a Single Joint Expert (SJE) to ensure an impartial valuation that both parties can trust. Whilst your own accountant understands your books, they are not considered independent by the court. However, working with an established firm of chartered accountants like Stewart Accounting Services can help you prepare your disclosure and review the SJE’s findings. Ultimately, the formal business assets valuation in divorce must be conducted by a neutral forensic specialist appointed under a joint letter of instruction.
Is the value of my business based on what I started with or what it is worth now?
The court considers the current value of the business, but it also looks at what the business was worth at the date of marriage. Any growth that occurred during the years you were together is typically seen as a matrimonial asset. If the business was established long before the wedding, you may be able to argue that the initial “seed” value should be excluded from the pot, though this depends on the length of the marriage.
How much does a forensic business valuation cost in 2026?
Fees for a forensic accountant vary significantly based on the size and complexity of the enterprise. For a standard small-to-medium enterprise, costs generally start in the thousands and are typically shared between both parties as a joint disbursement. More complex cases involving international assets or multiple subsidiaries will naturally attract higher fees. You should discuss these costs with your solicitor early on to ensure they are proportionate to the overall value of the matrimonial estate.
What is ‘double dipping’ and how can it be avoided in my settlement?
Double dipping is a common error where the same income stream is used twice in a settlement. This happens when a business is valued based on its future earnings to create a capital lump sum, and those same earnings are then used to calculate spousal maintenance. To avoid this, your legal team must ensure that the valuation and the maintenance calculations are adjusted so the business owner isn’t paying out on the same profit twice.
Can my spouse claim a share of a business I inherited?
Inherited businesses are often viewed as non-matrimonial assets, but they aren’t automatically protected. If the business was used to fund the family’s lifestyle or if your spouse’s financial needs cannot be met by other assets, the court may choose to include it in the settlement. The longer the marriage and the more the business was integrated into your joint finances, the more likely it is that your spouse will have a valid claim.