Statutory declarations in property law for right of way evidence

Statutory declarations in property law for right of way evidence

A declaration is only as useful as the facts it records. In England and Wales, making a statutory declaration in property law can support a claimed right of way where access has been used openly, without interruption or permission for at least 20 years, according to the UK legislation register. It records evidence of that use; the details and accuracy of the account matter.

If you’re trying to establish or explain access to land, you may want to know what to include in a statutory declaration in property law and how much weight it can carry. This article explains how a declaration can support right-of-way evidence, what to include in a factual account, and why a false statement can have serious consequences.

You’ll also learn how a declaration differs from other evidence used in property matters, and when legal support may help if access rights or land documents are disputed.

Key Takeaways

  • A statutory declaration can set out personal knowledge of how a route has been used and help support evidence about access to land.
  • Clear details about the route, the pattern of use and whether permission was given help make the account easier to understand.
  • HM Land Registry can accept a statement of truth as an alternative form of evidence in relevant cases, with formal requirements for how it is made.
  • Accuracy matters: a knowingly false statement can have serious legal consequences, so distinguish what you witnessed from what you have been told.
  • Understanding the legal basis and purpose of a declaration can help you decide what evidence is relevant to a property access issue.

What is a Statutory Declaration for a Right of Way?

A statutory declaration records facts that a person declares to be true, including their own experience of using a route. It can help explain the history of access where no right has been granted.

Signing and witnessing the declaration

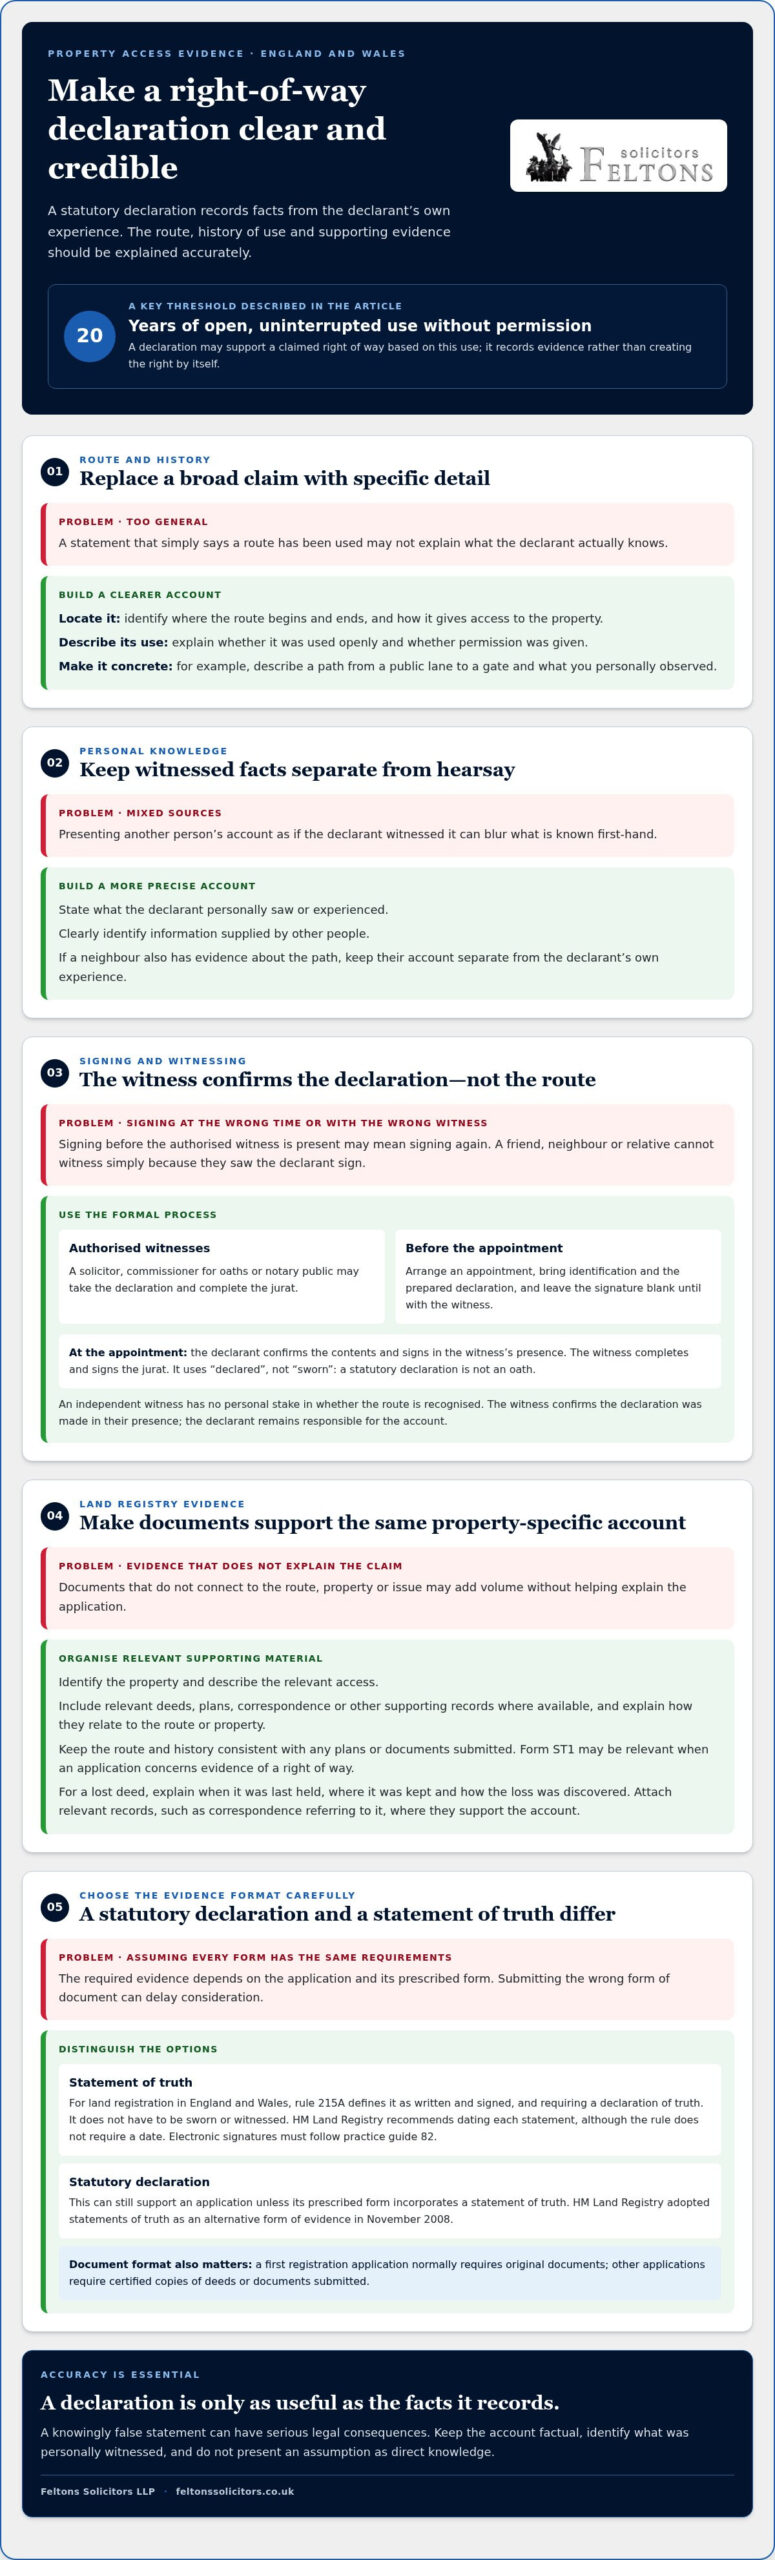
The declarant signs the document in front of an authorised witness, confirms its contents and makes the declaration using the required wording. The witness then completes and signs the jurat, the section recording that the declaration was made before them.

Signing in the witness’s presence matters. If you sign beforehand, you may need to sign again. The usual process includes the declarant confirming the contents after the solicitor or other authorised witness. The jurat uses “declared” rather than “sworn”, because this is a declaration, not an oath.

Who can witness a declaration

A statutory declaration may be witnessed by a solicitor, commissioner for oaths or notary public. These authorised witnesses can take the declaration and complete the jurat. A friend, neighbour or relative cannot witness it simply because they saw the declarant sign.

Choose an authorised witness before signing, and arrange an appointment with the solicitor or commissioner. Bring identification and the prepared declaration, but leave the signature blank until you are with the witness. Their details and signature form part of the completed document.

Choosing an independent witness

An independent witness has no personal stake in whether the route is recognised. For example, a solicitor who is not involved in the dispute can witness the declaration, provided they are authorised to do so.

Independence helps distinguish the witness’s formal role from the evidence itself. The declarant is responsible for the account, while the witness confirms the declaration was made in their presence. If a neighbour also has evidence about the path, keep their account separate from the declarant’s own experience.

In England and Wales, a statutory declaration may support a claimed right of way based on open, uninterrupted use without permission for at least 20 years, according to the UK legislation register. The declaration should explain the declarant’s own knowledge of the route and its use, rather than make broad claims without personal detail.

Useful context can include where the route begins and ends, how the declarant accessed the property, and whether the route was used openly or with permission. For example, describe a path from a public lane to a gate and explain what the declarant personally observed. Separate direct observations from information supplied by others.

Bring the exact fee in cash, along with identification and a copy of the declaration completed in advance where required. Arrange an appointment before attending, as the witness must be present when the declaration is made.

Using a statutory declaration for HM Land Registry evidence

A statutory declaration can support a land registration application, including by explaining how deeds were lost or destroyed. The account should identify the property, describe the relevant access and distinguish personal knowledge from information provided by others. What evidence should accompany a property statutory declaration? Include relevant deeds, plans, correspondence or other supporting records where available, and explain how they relate to the route or property.

For land registration purposes in England and Wales, rule 215A of the Land Registration Rules 2003 defines a statement of truth and requires it to be made in writing, signed, and to contain a declaration of truth, according to the UK legislation register. HM Land Registry adopted statements of truth as an alternative form of evidence in November 2008. A statutory declaration can still support an application unless its prescribed form incorporates a statement of truth.

Statements of truth and supporting documents

A statement of truth is written and signed, but it does not have to be sworn or witnessed. HM Land Registry recommends dating each statement to help avoid requisitions, although rule 215A does not require a date. Electronic signatures must follow the process in practice guide 82.

For example, if an original deed has been misplaced, a declaration can explain when it was last held, where it was kept and how the loss was discovered. Attach relevant records, such as correspondence referring to the deed, if they support the account. Do not present an assumption as something the declarant witnessed.

Form ST1 and other requirements

Form ST1 may be relevant when an application concerns evidence of a right of way. Use the form to give a clear, property-specific account, keeping the route and history consistent with any plans or documents submitted. Each piece of evidence should help explain the claim rather than merely add volume.

HM Land Registry requirements depend on the application and its prescribed form. A first registration application normally requires original documents; other applications require certified copies of deeds or documents submitted. Check which category applies before assembling the registration papers, because submitting the wrong form of document can delay consideration.

A mortgage company may also have evidence requirements relating to the property or lending decision. Keep its request separate from HM Land Registry’s application requirements, and make sure the declaration addresses the specific issue raised. For instance, evidence about a route may not answer a separate question about a missing title deed.

Solicitors can help organise property documents and explain how they relate to a registration application. Where land is held through an overseas entity, overseas entity registration may also be relevant to the ownership context.

Fraud consequences for false statements

A statutory declaration is a formal statement, so review every sentence before signing. In the United Kingdom, making a false statement in a statutory declaration is a criminal offence under the Perjury Act 1911. The risk is not limited to a property dispute: the declaration may be relied on as evidence by HM Land Registry or another decision-maker.

Fraud is a separate offence. According to the UK legislation register, the maximum penalty for fraud under section 1 of the Fraud Act 2006 is 10 years’ imprisonment, an unlimited fine, or both. That is the maximum penalty for fraud, not an automatic sentence for every error or disagreement in a declaration.

The distinction matters when an account of a right of way includes uncertainty. Someone might remember using a track but not know whether a gate was locked during a particular period. They should describe what they recall accurately, rather than state an uncertain detail as fact. Clearly separating personal knowledge from assumption helps prevent a misleading account.

Check each detail against available records before making the declaration. For example, compare the route description with a property plan and review correspondence about access. If a document gives a different account, address the discrepancy honestly. Do not change a date or omit relevant context to make the evidence appear stronger.

The declarant is responsible for the contents, even if a solicitor prepared the wording. A solicitor or commissioner witnesses the declaration in their presence, but that formal role does not make an inaccurate account true. Read the completed document carefully and raise any wording that does not reflect your knowledge before signing.

If you discover a mistake before signing, pause and have the wording corrected before making the declaration. For instance, if the draft says you used a route every day but you only remember using it regularly, that difference should be addressed. Do not sign a statement because someone expects a stronger or more definite version.

A disputed right of way can affect neighbouring owners, property access and later dealings with land. An unsupported claim may therefore have consequences beyond the registration application itself. Keep a copy of the signed declaration and the documents used to prepare it, so the account can be considered alongside its supporting evidence.

HM Land Registry may consider a declaration as part of a wider application, alongside plans, deeds or other relevant records. Consistency matters: a route described as running beside a boundary in the declaration should match the submitted plan. If the accounts differ, explain why rather than leaving the conflict unresolved.

Before signing, confirm that the declaration states only what you can honestly stand behind, including its description of the route, the nature of its use and any permission given. Accurate wording protects the value of genuine evidence. A statement made for property purposes must not turn a belief, assumption or another person’s account into a claimed personal fact.
Statutory declarations in property law for right of way evidence

Information to include in a declaration

A useful declaration gives a clear, first-hand account of the route and the circumstances of its use. For a property access claim, organise the facts so another person can understand where the route runs, who used it and what the declarant personally observed.

Begin with your full name, address and connection to the property. Identify the land precisely, using its postal address and a plan or title reference where available. If the route crosses a neighbouring field before reaching a home, describe those points rather than relying on a general phrase such as “the back path”.

Set out the route in practical terms. Describe its starting point, direction, destination, surface and any gates or landmarks that help identify it. Explain how you know the route, such as by living at the property or regularly walking it. A sketch plan can help, but the written account should still make sense without unexplained markings.

  • Pattern of use: explain who used the route, for what purpose and how regularly, using specific memories or events where possible.
  • Permission: state whether permission was requested or given, and describe any conversation you personally remember.
  • Changes or interruption: record an observed barrier, closure or alteration, and explain how it affected access.
  • Supporting material: identify photographs, correspondence, plans or other documents, and say what each one helps to show.

Include details based on personal knowledge, not assumptions. For example, say you saw a neighbour pass through a gate only if you witnessed it; don’t present the neighbour’s account as your own observation. If a date is uncertain, explain the event that helps place it in time instead of inventing precision. Distinguish what you remember from what a document or another person tells you.

Keep the account focused on the reason for the declaration. If it supports a right-of-way claim, explain the history of access rather than adding unrelated details about ownership or a separate boundary disagreement. A formal statement is easier to assess when each paragraph relates to the route, the property or the evidence being explained.

Before attending to sign, read the complete document and compare its route description with any attached plan. Check names, addresses and dates, then mark any wording that does not match your recollection. A commissioner for oaths witnesses the declaration but cannot supply missing facts or correct the declarant’s personal account. Organising these details beforehand helps the witness understand which document is being declared.

Finish with a concise statement confirming that the contents are true to the best of your knowledge and belief. Keep a copy of the signed declaration with any referenced documents. That record can help explain the evidence later if HM Land Registry or another party asks how a detail was established.

A statutory declaration is a formal statement of fact made by a person who declares its contents to be true. The framework described here applies across the United Kingdom, but the discussion of rights of way and HM Land Registry concerns England and Wales. Property procedures are not necessarily identical in Scotland or Northern Ireland.

Meaning of statutory declarations

A declarant sets out facts they believe to be true, based on personal knowledge. For example, someone describing a path may state when they first used it, where it runs and what they observed. This differs from offering a general opinion about who owns the route or what access should be allowed.

The declaration creates a formal record that can support an application or explain a matter where documentary evidence is limited. Its value depends on the detail and source of each fact. A declarant who personally saw a gate being opened can say so; a neighbour’s account should be identified as information from another person.

For someone making a statutory declaration in property law, this distinction clarifies what the evidence can establish. The declarant should separate what they remember from what they infer, and ensure the wording reflects the difference. An account of access, for instance, should not claim uninterrupted use if the declarant knows only about occasional visits.

Legal basis and regional rules

Statutory declarations in the United Kingdom are governed by the Statutory Declaration Act 1835, according to the UK legislation register. The Act is also cited in connection with the standard form of a declaration. That form gives the statement a recognised legal structure, while the declarant supplies the facts relevant to their particular application.

The statutory wording does not replace a complete account. A declaration about a right of way needs facts about the route and its use; one explaining a missing deed needs facts about the document and its loss. Making a statutory declaration in property law therefore involves both the formal declaration and a relevant, accurate account.

Schedule 1 of the Interpretation Act 1978 provides that an affidavit includes a declaration and that “sworn” means “declare”. This helps explain why statutory declarations use declaration wording rather than treating the declarant as taking an oath. A solicitor, commissioner for oaths or notary public can witness a declaration in the appropriate formal process.

For a property application, identify the relevant jurisdiction before relying on a form or procedure. The rules discussed here relate to England and Wales, including HM Land Registry evidence. If your land is in Scotland or Northern Ireland, the applicable property and registration framework needs separate consideration; do not assume that an England and Wales process applies.

Where a property issue also involves estate administration, discuss your legal options before preparing a declaration, so the statement fits the wider matter.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP assists with residential and commercial conveyancing when a right-of-way question affects a property transaction. Understanding the access evidence may be important when considering the property and its documents. If a property issue also forms part of a divorce or separation, Feltons Solicitors LLP can advise on divorce and financial arrangements in that context.

Consider legal support if the route is disputed, the declaration conflicts with other property records, or access concerns arise during a sale or purchase. Advice can help you understand how the property issue fits the wider matter and what information may be relevant to discuss.

To discuss your circumstances, contact Feltons Solicitors LLP.

Take the next step with confidence

Before relying on a declaration, consider how the access issue fits the property’s wider circumstances. A route may affect a sale, shared ownership or decisions about an estate, so the evidence should be understood in context. Making a statutory declaration in property law is one part of addressing the issue, not a substitute for considering its effect on the property and the people connected to it.

Feltons Solicitors LLP offers residential and commercial conveyancing, as well as wills, probate and estate planning. If a property matter also intersects with separation, the firm handles divorce and financial arrangements. The right legal support depends on the issue you need to resolve and how it connects with your wider plans.

For guidance on your circumstances, contact Feltons Solicitors LLP. A considered next step can help you move forward with greater clarity.

Frequently Asked Questions

When is this needed?

A statutory declaration may be useful when a property matter needs a formal account of facts that documents alone cannot establish. For example, it can explain how deeds were lost or provide evidence about access to a route. In England and Wales, a claimed right of way may rely on open, uninterrupted use without permission for at least 20 years, according to the UK legislation register.

Where do I swear the declaration?

Arrange to make the declaration before a solicitor, commissioner for oaths or notary public. The witness must be authorised and present when you sign. Contact the solicitor’s office to arrange an appointment, then take identification and the prepared document. Do not sign beforehand. The witness completes the jurat, recording that you made the declaration in their presence.

What is a statutory declaration in UK property law?

It is a formal written statement in which a person declares facts to be true to the best of their knowledge. In a property matter, it might explain a route’s history or the circumstances in which a deed disappeared. The declaration records the maker’s evidence; it does not, by itself, create a right of way or settle a disagreement about ownership.

When is a statutory declaration used in a property transaction?

It may be required to address a particular issue affecting a property transaction, such as missing title documents or a proposed commercial lease exclusion. For a lease contracted out of the Landlord and Tenant Act 1954, a tenant must make a statutory declaration before an independent solicitor if fewer than 14 days separate the warning notice and lease entry.

Who can make and witness a property statutory declaration in England and Wales?

The person making it should have personal knowledge of the facts they declare. For instance, someone who regularly used a path can describe their own experience, but should identify a neighbour’s account as information from that neighbour. A solicitor, commissioner for oaths or notary public may witness the declaration. The declarant gives the evidence; the witness formally takes the declaration.

What wording and information must a property statutory declaration contain?

Use the appropriate formal declaration wording and identify the person making it and the property concerned. For a route, describe its start, destination, location and the declarant’s experience of using it. A useful account separates remembered events from assumptions and refers clearly to any attached plan or document. The wording should match the facts the declarant is prepared to affirm.

How do you make and sign a statutory declaration for a property matter?

Prepare the statement and supporting documents, then arrange an appointment with an authorised witness. Take identification and leave the signature blank until you attend. Read the final wording and raise any errors, then sign in the witness’s presence and make the declaration as directed. The witness also signs and completes the jurat, recording the place and date.

What are the legal requirements for witnessing a statutory declaration in the UK?

The declaration must be made before an authorised witness, such as a solicitor, commissioner for oaths or notary public. The declarant signs in that person’s presence, and both sign the document. The jurat records the act of declaration, using “declared” instead of “sworn”. For solicitors and commissioners, the place and date must also be stated.
What Happens to a Business in Divorce and Who Keeps It

What Happens to a Business in Divorce and Who Keeps It

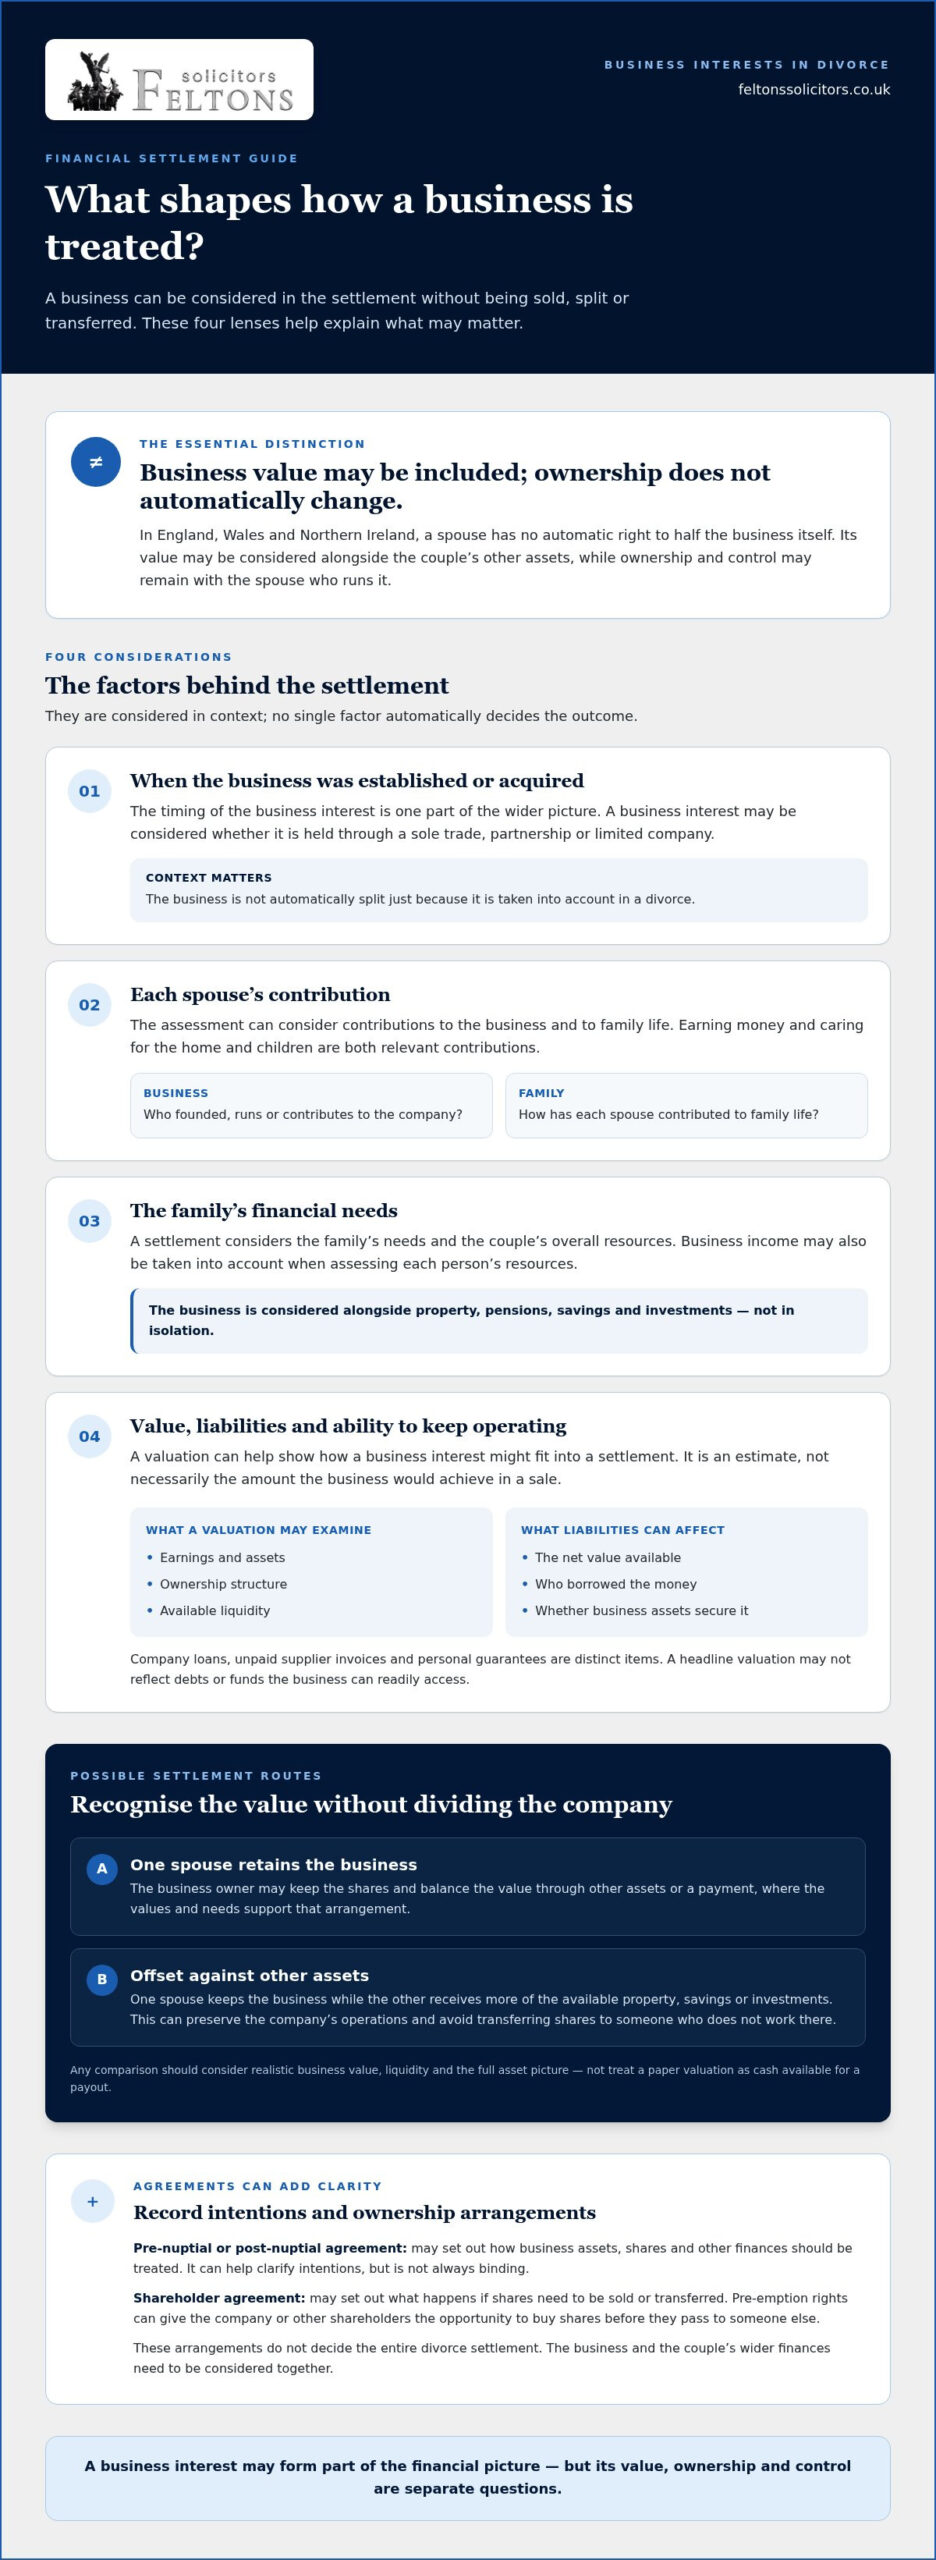
A divorce doesn’t automatically mean a business must be sold or divided. What happens to a business when a couple divorces depends on factors such as when it was established, each spouse’s contribution and the family’s financial needs. The business’s value may be considered in the settlement, while ownership and control may remain with the spouse who runs it.

It’s understandable to worry that a financial claim could disrupt the business you’ve built. Including a business in the settlement doesn’t necessarily mean your spouse will receive shares or take over the company. Depending on the circumstances, its value may instead be balanced against other assets.

This article explains when a business is taken into account, how its value and ownership may be treated, and what can help protect control. It also covers practical ways to address business interests in financial arrangements, so you can understand the issues before deciding what to do next.

Key Takeaways

  • A pre-nuptial or post-nuptial agreement can set out how business assets should be treated, but it isn’t always binding.
  • A spouse isn’t automatically entitled to half of the business; the settlement can reflect its value alongside other assets.
  • When a business is assessed, factors can include when it was established, each spouse’s contributions, the family’s needs and the business’s ability to keep operating.
  • Valuation helps clarify the options, which can include one spouse retaining the business and balancing its value through other assets or a payment.
  • Clear financial records and suitable business agreements can help protect ownership and control if a relationship breaks down.

Can I ringfence my business in a prenuptial agreement?

A nuptial agreement can record how a couple intends to treat business interests if they separate. It may help protect ownership, but it doesn’t guarantee that a court will follow every term.

Nuptial agreements and business protection

A pre-nuptial agreement is made before marriage; a post-nuptial agreement is made during the marriage. Either can set out how business assets, shares and other finances should be divided if the relationship ends.

For example, an agreement could record that one spouse founded and runs a company, then explain how its value should be considered alongside other assets. A nuptial agreement made before separation can help clarify intentions, but it isn’t always binding. Legal advice can help both spouses understand the terms and disclose their finances.

After separation, spouses may need to work through how to divide their finances, including property, pensions, savings and investments. Seeking guidance from independent wealth specialists like Her Financial Planning can help individuals evaluate the broader financial and retirement picture, ensuring a written agreement addresses the business as part of that wider settlement, rather than treating it in isolation.

Shareholder agreements and pre-emption rights

A shareholder agreement sets out arrangements between a company’s shareholders, including what happens if someone needs to sell or transfer shares. It may give the company or other shareholders pre-emption rights, allowing them the opportunity to buy shares before they pass to someone else.

For example, a family company’s agreement could specify how shares are offered if an owner needs to transfer them following a divorce. These terms can help manage ownership disputes and reduce uncertainty for other shareholders. They don’t decide the entire divorce settlement, so the agreement and the couple’s wider finances need to be considered together.

Business valuation and solicitor costs

A business valuation estimates the value of an interest for financial discussions and helps show how it might fit into a settlement. How much does a business valuation or divorce solicitor cost in the UK? The price depends on the case and is given after a quote request; factors include the work required, the quality of financial records and the complexity of the valuation.

A valuation may examine earnings, assets, ownership structure and available liquidity. It is an estimate, not necessarily the amount the business would achieve in a sale. Specialist accounting work may be needed, particularly when company finances, other shareholders or several ownership interests require analysis.

Business debts and liabilities

Business debts and liabilities affect the net value available for a financial settlement. Start by identifying each obligation, its balance, who borrowed the money and whether business assets secure it.

For example, a company loan, an unpaid supplier invoice and an owner’s personal guarantee are distinct items to record. Current accounts, loan documents and guarantee terms help show how each liability relates to the business or an individual. A clear picture matters because a headline valuation may not reflect the business’s debts or the funds it can readily access.

Is my spouse entitled to half of my business?

No. In England, Wales and Northern Ireland, a spouse has no automatic right to half the business itself. Business interests and their value may be considered alongside the couple’s other assets when working out a financial settlement.

Business interests as matrimonial assets

A business interest may form part of the assets considered in a divorce, whether held through a sole trade, partnership or limited company. That doesn’t mean the company must be split: the court considers the circumstances, including when it was acquired, each spouse’s contributions and the family’s needs.

In White v White in 2000, the House of Lords rejected discrimination between earning money and caring for the home and children. Miller v Miller and McFarlane v McFarlane in 2006 addressed needs, compensation in some cases and sharing wealth built during marriage. Those principles help explain why a business owner’s work is considered alongside their spouse’s contribution to family life.

Freezing orders and business assets

A freezing order can prevent a spouse from dealing with assets when there’s a risk of disposal or devaluation that could undermine a fair financial settlement. For example, transferring company funds or selling valuable equipment could affect the assets available for division.

A freezing order is a protective measure, not a way to decide who owns the business. In England and Wales, the court must be satisfied that the risk could prejudice the applicant’s ability to obtain a fair share. If assets are being moved or depleted, prompt legal action matters because prevention can be more effective than seeking a remedy afterwards.

Offsetting business interests against other assets

Offsetting means one spouse retains the business while the other receives more of the available property, savings or investments. For example, a business owner might keep their shares while the other spouse receives a larger share of a jointly owned property, if the values and needs support that arrangement.

This approach can preserve the company’s operations and avoid transferring shares to someone who doesn’t work there. The comparison should account for realistic business value, liquidity and the full asset picture, rather than treating a paper valuation as cash available for a payout. A settlement may also take business income into account when assessing each person’s resources.

Tax considerations when dividing business assets

Selling or transferring business assets during a divorce can have tax consequences. Capital gains tax may arise when assets are sold or transferred, while stamp duty may be payable on a property transfer. These potential liabilities can change the net value each spouse receives.

For example, comparing a share transfer with a sale requires attention to the asset involved, its ownership and the proposed settlement structure. A valuation can help identify the options and their tax implications before terms are finalised. A settlement should compare what each person receives after relevant liabilities, not just the stated value of the business or property.

A business is only one part of the financial picture: pensions, property, savings and investments also matter. Financial arrangements in a divorce place business interests alongside those wider assets when considering a settlement.

Will my business be taken into account in a divorce?

Yes. A business may be included when the couple’s finances are considered, but it isn’t automatically sold or divided. The settlement looks at the business alongside other assets, income and family needs.

Accounting for a business in a settlement

A financial settlement considers the business interest as part of the couple’s wider finances. How it is treated depends on its value, income, ownership structure and the needs of each spouse and any children.

For example, a director who runs a company may keep operating it, while the settlement accounts for its value through other assets or income. The family court can consider the business’s earning capacity, underlying assets and available liquidity. These factors help distinguish a valuable but cash-poor company from one that can readily provide funds.

In England and Wales, the needs of minor children receive first priority in a financial settlement. The court also considers housing and income needs, including future earning capacity and retirement. The business is assessed in context, rather than in isolation from the family’s circumstances.

Separating business and household finances

Keeping company accounts separate from household and jointly held finances creates a clearer record of what belongs to the business. Separate bank accounts and properly recorded drawings, for example, can help distinguish company expenditure from personal spending.

Good records also help explain income, liabilities and transactions during financial disclosure. Both spouses must provide full financial information, including details of any business sale and its proceeds. If a company account has paid household costs, recording those transactions helps show how they should be treated in the settlement.

Current governance documents matter too. Keeping shareholder records, company accounts and ownership documents organised makes the business structure clearer during discussions. Clear separation doesn’t determine the settlement, but it helps each person understand the business assets and income being considered.

Financial claims after separation or divorce

Separation does not by itself resolve financial claims between spouses. In England and Wales, there is no time limit for a husband or wife to make a financial claim following separation or divorce, so an informal arrangement may leave finances unresolved.

A consent order records agreed terms and can bring greater finality to the division of assets. Without an order, a couple may have agreed who keeps the business but not legally concluded their financial claims. Mediation can help address outstanding matters, such as business income, pensions or property, before an application for a financial order.

If spouses cannot agree, they can ask the court to make a financial order. The court considers the available assets, each person’s needs and the business’s ability to continue functioning. For a family with children, housing and income needs are particularly important.

What Happens to a Business in Divorce and Who Keeps It

Keeping business ownership with the operating spouse

A spouse who established and runs a business will usually be considered to retain it where possible. A court is unlikely to order a sale if that would harm the company or its shareholders, though a Scottish court may order a sale to fund an equalising payment when other assets cannot offset its value.

Lump-sum settlements instead of ownership

A lump-sum settlement can compensate one spouse for the business’s value without giving them ownership or control. This can allow the operating spouse to keep running the company while the other receives a payment or a greater share of other assets.

For example, if a business owner has sufficient personal funds or other assets, a payment may settle the other spouse’s financial interest. The figures must reflect the business’s value and the wider settlement, including each person’s needs. If the business has limited liquidity, extracting capital could affect its ability to trade, so the payment structure matters.

A spouse may also receive a share of business income rather than part of its ownership. That can provide financial support while leaving daily decisions with the person who operates the company. The settlement needs to distinguish income from capital value, since they affect the business and each spouse differently.

Ownership structures and minority shareholdings

The legal structure affects what can be transferred. A sole trader owns the business personally, while a partnership or limited company has different ownership arrangements. In a limited company, the divorcing spouse’s shares are relevant, but transferring them can affect other shareholders and directors.

A minority shareholding in a company owned by a wider group is assessed by considering the value of that particular interest, not the whole company. A spouse holding a minority stake, for instance, doesn’t own the other shareholders’ shares. Any proposed transfer must also account for the company’s governing documents and the practical effect on its operation.

Keeping the business with one spouse doesn’t require the other to receive shares. A court can consider the business’s value alongside other assets, or the spouses may agree on a financial arrangement that avoids shared ownership.

Former spouses can sometimes continue to co-own a business, but that means their decisions and financial interests remain connected after divorce. If they jointly own a company, they need to address how each person participates, makes decisions and receives income. Separating roles may be harder if both previously worked in the business than if only one spouse operated it.

Keeping control of the business after divorce

Ownership and control are related, but they are not identical. One spouse may retain a business while the settlement recognises its value through other assets or payments. For a family business, the practical question is also who makes decisions, manages staff and maintains trading relationships after the marriage ends.

Before agreeing to transfer shares, consider the effect on other directors, shareholders and employees. A spouse receiving shares, for example, may become a shareholder without experience running the company. A transfer could also affect voting arrangements or the working relationship between existing owners. Reviewing the company’s governance documents helps identify restrictions and existing rights that may shape a workable outcome.

A shareholder agreement can set out what happens if an owner must sell or transfer shares. It may give the company or another shareholder pre-emption rights, so they have the opportunity to buy shares before they pass to someone else. In a divorce, those provisions can help manage a proposed transfer and reduce disruption for the remaining owners. They don’t determine the whole financial settlement, so the share arrangements and family finances need to be considered together.

A trust may help keep a family business within the family after divorce. Its purpose and structure need careful consideration alongside the settlement, the people involved and the business’s future needs. Insurance can also protect a business if an owner dies or becomes disabled, events that may affect its value and ownership. These measures address different risks, so neither should replace clear ownership records or suitable governance arrangements.

For businesses in Scotland, courts are unlikely to force a spouse to sell or take action that harms the business, its value or its workforce. This highlights why continuity matters when considering control after separation. In other parts of the UK, the settlement also needs to account for the company’s operation and shareholders’ interests, rather than treating shares as cash that can simply be divided.

The parties can consider who will hold shares, who will make operational decisions and how future disagreements will be managed. A family company, for example, could document decision-making responsibilities and the process for a future share sale. Clear terms can help separate the spouses’ personal financial arrangements from the company’s day-to-day management.

Discuss business control in divorce to consider how ownership, financial arrangements and the company’s ongoing operation fit together.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP provides Divorce and Financial Arrangements for people working through separation and business-related financial decisions. The service can help when you need to understand how business interests, property, pensions and other assets may fit into a settlement, or how to formalise agreed arrangements.

Advice can help you consider practical outcomes, such as retaining control of a company, addressing a shareholding or balancing business value against other assets. If separation also means reviewing your will or longer-term estate plans, Wills, Probate, and Estate Planning may be relevant.

For guidance on your circumstances, contact Feltons Solicitors LLP or visit feltonssolicitors.co.uk.

Prepare for a clear next step

Understanding what happens to a business when a couple divorces is useful when it helps you plan for your financial position and your company’s future. Before discussions begin, gather current accounts, ownership records, shareholder or partnership agreements, loan documents and any nuptial agreement. Note who runs key operations, which decisions require approval, and how a transfer could affect employees or co-owners. These details can focus discussions on practical options.

Feltons Solicitors LLP offers Divorce and Financial Arrangements for financial issues arising from separation. If the settlement also affects your estate plans or property, the firm offers Wills, Probate, and Estate Planning and Residential and Commercial Conveyancing. Considering these connected arrangements together can help you plan beyond the immediate ownership question.

Arrange a discussion with Feltons Solicitors LLP about your financial arrangements and business decisions. With clear records and considered advice, you can move towards a workable plan for the next chapter.

Frequently Asked Questions

What happens to the family business upon divorce?

What happens to a business when a couple divorces depends on its ownership, finances and the family’s circumstances. The business interest and its value may be considered within the wider financial arrangements, but that doesn’t automatically mean a sale. One spouse, for example, may continue running the company while the settlement addresses the other spouse’s financial position through other resources.

How is the business divided?

A business isn’t necessarily divided by transferring half its shares. The settlement may account for its value through other assets, a payment or arrangements involving business income. One spouse might, for example, retain the company while the other receives a greater share of property or savings. The practical options depend on the business structure, available liquidity and the parties’ financial needs.

Is a limited company protected from divorce?

No. A limited company’s separate legal identity doesn’t automatically exclude a spouse’s shareholding or the company’s value from divorce financial arrangements. The court may consider the owner’s shares, income, assets and ability to generate income. The company itself isn’t automatically divided or sold. Its articles and any shareholder agreement may affect share transfers, but they don’t determine the entire financial settlement.

Who conducts the business valuation for a divorce?

An independent accountant is commonly appointed to value a business, often jointly by both spouses. A specialist may review financial statements, earnings, assets, market conditions and the company’s ownership structure. The valuation may also consider liquidity and whether capital can be extracted or borrowed against business assets. It provides an estimate for settlement discussions, not necessarily the price achievable in an actual sale.

Can a business be considered a marital asset even if only one spouse owns it?

Yes. Sole legal ownership doesn’t automatically prevent a business interest from being considered in divorce proceedings. Relevant factors include when it was acquired, whether it grew during the marriage, each spouse’s contributions and the family’s needs. A spouse’s contribution to family life, for instance, may matter to the wider financial picture even without a formal role or shareholding in the company.

Can my wife take half my business in divorce?

There’s no automatic rule that a wife receives half the business or its shares. The financial settlement considers the business alongside other assets, income and needs. The spouse operating the company may retain it while the other spouse’s financial position is addressed separately. The outcome depends on the circumstances, including the marriage, each person’s contributions, children’s needs and available resources.

Divorce with a business involved, how does it work in the UK?

Understanding what happens to a business when a couple divorces in the UK starts with financial disclosure, including business interests, income, assets and liabilities. In England and Wales, spouses can negotiate or use mediation, then seek a consent order to make agreed terms legally binding. Scotland has different rules, and Northern Ireland has its own court process, so the relevant jurisdiction matters.

How is a business valued during divorce in the UK?

A valuation considers the business’s financial position and how it operates, rather than relying on turnover alone. An accountant may assess earnings, profits, underlying assets, income-generating capacity, liquidity and ownership interests. A profitable company with limited available cash, for example, may not readily fund an immediate payment. The estimate helps compare settlement options, but doesn’t necessarily represent the price the business would fetch if sold.

Unregistered Land Conveyancing: Selling and Registration Explained

Unregistered Land Conveyancing: Selling and Registration Explained

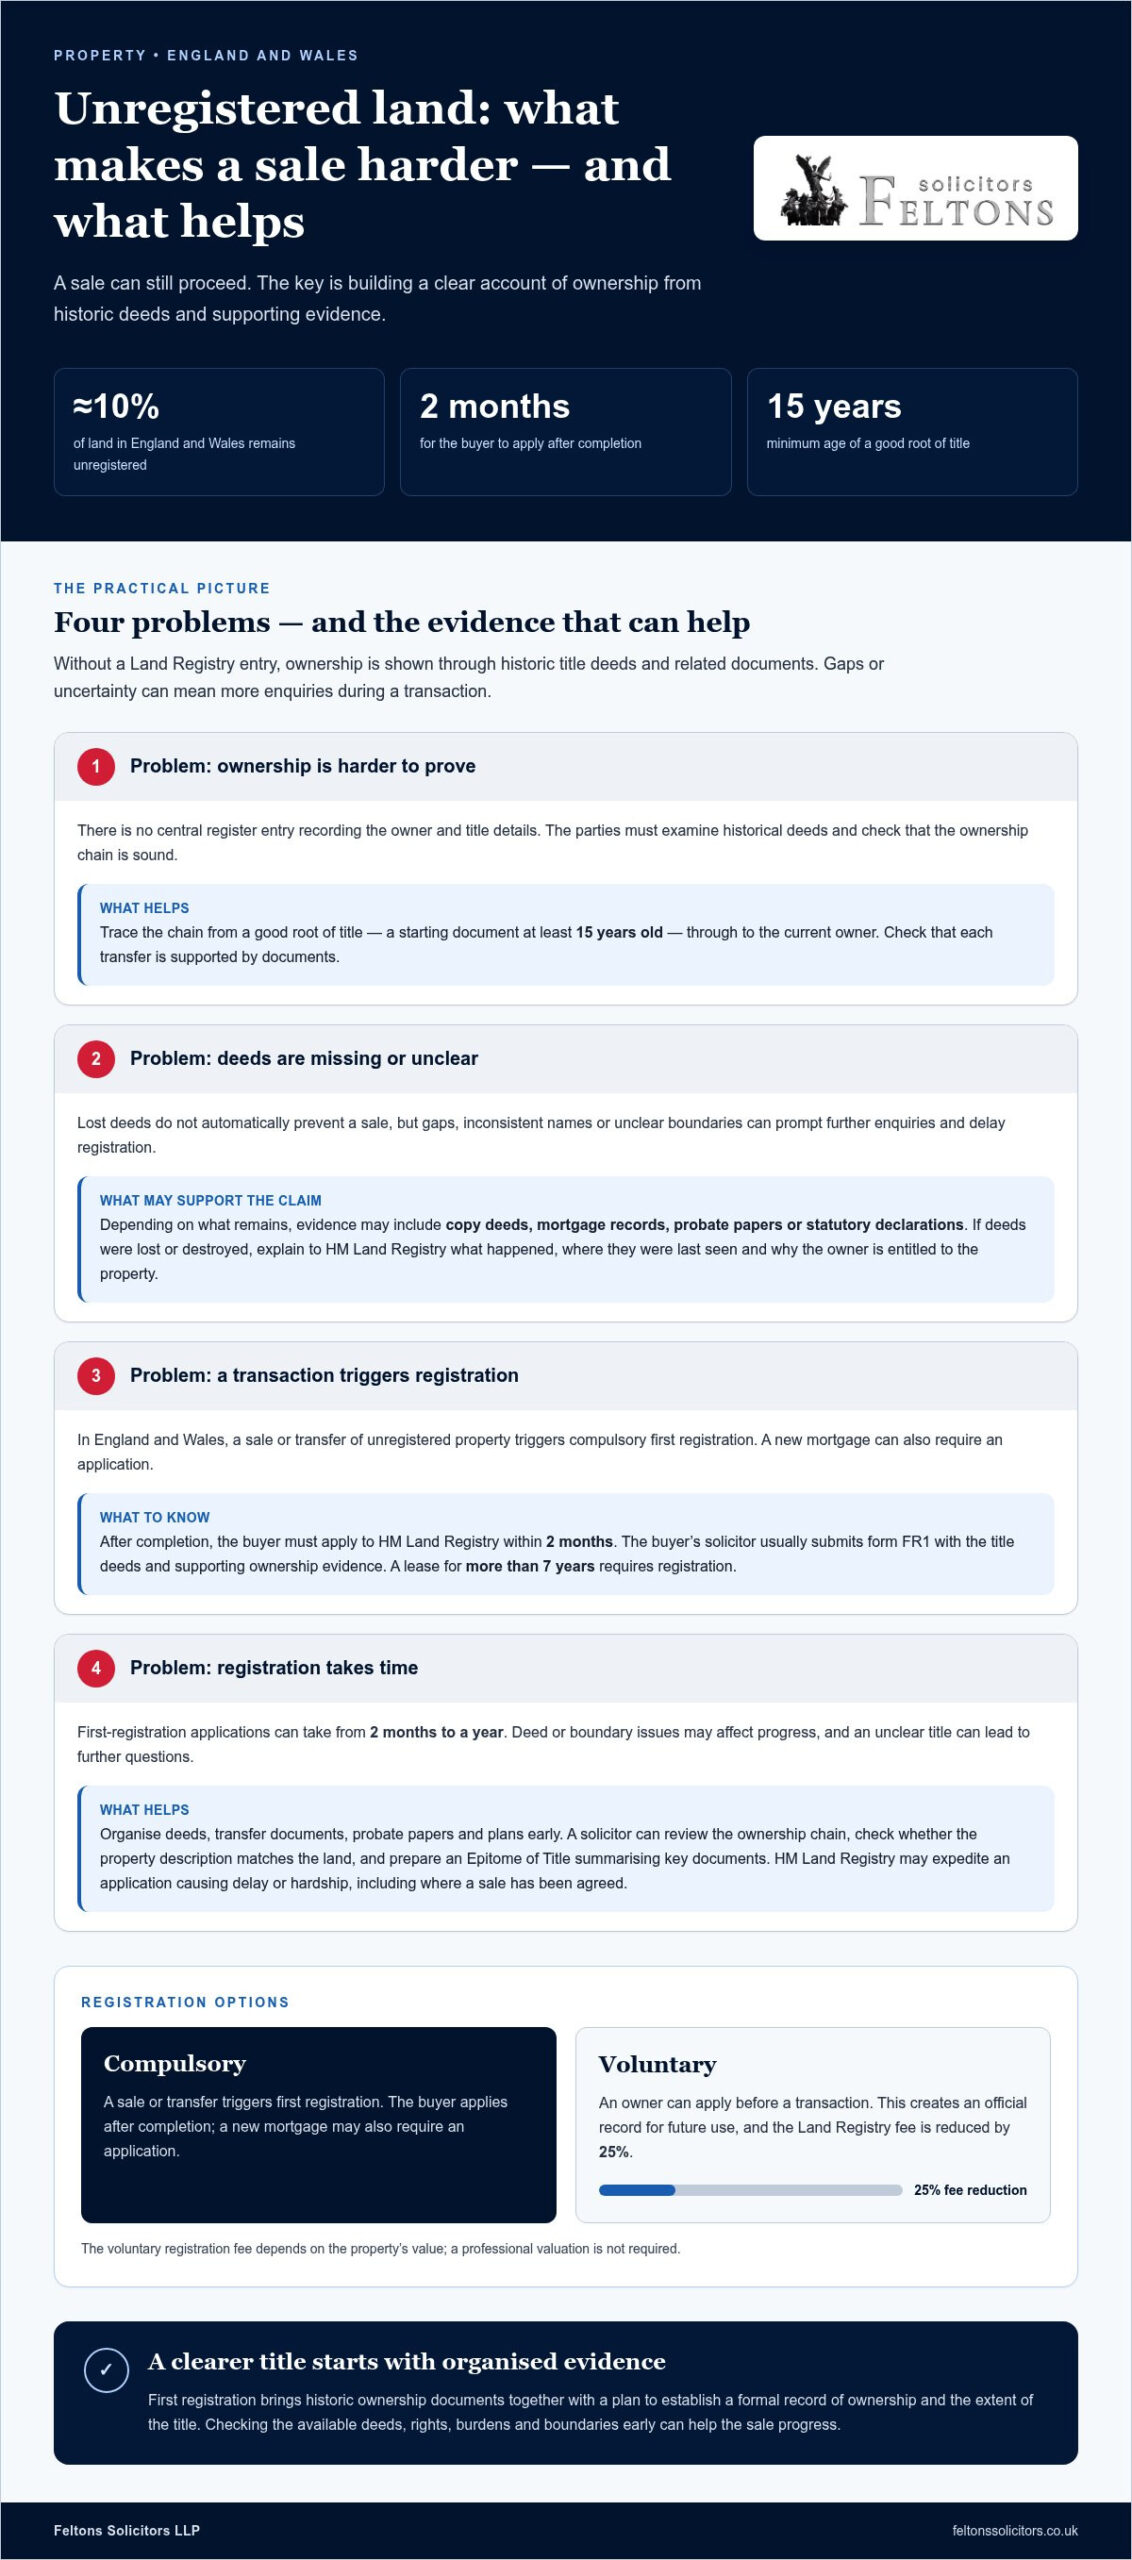
Approximately 10% of land in England and Wales remains unregistered, but a sale or transfer triggers compulsory first registration. After completion, the buyer must apply to HM Land Registry within two months. Unregistered land conveyancing solicitors assess the title deeds and ownership history that support the application.

It’s understandable to wonder whether an unregistered title makes a property harder to sell, or whether registration can wait. The answer depends on whether a sale, transfer or other registrable event has triggered the requirement, and on the evidence available to establish ownership.

This article explains when first registration is compulsory, the practical risks of leaving a title unregistered and how a sale can proceed. It also covers why some land remains unregistered, what to do when deeds are missing and how first registration turns historic ownership documents into a registered title.

Key Takeaways

  • A sale or other registrable transaction can trigger first registration; after buying unregistered property, the buyer must apply within two months of completion.
  • Historic deeds and ownership records help establish the chain of title, so organising the available documents can support a smoother sale.
  • An unregistered property can still be sold, but missing or unclear title evidence may complicate the transaction and delay registration.
  • Some land remains unregistered because no transaction requiring registration has occurred; voluntary registration can help make ownership easier to evidence in future.
  • First registration brings the property onto the register for the first time, creating a formal record of ownership and the extent of the title.

Is it compulsory to register land?

In England and Wales, registration becomes compulsory when unregistered property is sold or transferred. The buyer generally applies for first registration after completion, although an owner can register voluntarily before a transaction.

The Land Registration Act 1925 introduced compulsory registration, initially for specified transactions, including the grant of a new lease of 21 years or more, according to UK legislation. Today, a sale or transfer of unregistered property triggers registration, and a new mortgage can also require an application. HM Land Registry says granting a lease for more than seven years requires registration.

Checking the Registration Status

To check registration status, find out whether HM Land Registry holds an official record for the property. This matters before a sale, transfer or mortgage because the title information determines which documents and registration steps are needed. Anyone can request an official copy of the register for registered land. Check the registered owner, property details, rights and restrictions rather than relying only on old deeds.

First Registration Applications

First registration is the process of creating a Land Registry record for a property that has never been registered. After a purchase, the buyer’s solicitor submits the application, usually using form FR1, with the title deeds and supporting ownership evidence. The application brings earlier conveyances and dealings together with a plan to establish the registered title. A clear, complete application helps address questions about the property boundaries, ownership and rights.

An owner can also apply voluntarily when no transaction has triggered compulsory registration. This can establish an official record before a future sale or mortgage, giving the parties a registered title to work from. A reduced fee applies to voluntary first registration, with the Land Registry fee reduced by 25 per cent. The fee depends on the property’s value, and a professional valuation is not required.

Timing matters if a transaction is under way. The buyer must apply within two months of completion after purchasing unregistered land. First-registration applications can take from 2 months to a year, so unresolved deed or boundary issues may affect progress. HM Land Registry may expedite an application where it is causing delay or hardship, including when a sale has been agreed.

Solicitors’ charges depend on the work involved, such as reviewing historic deeds, resolving title issues and preparing a registration application. The price depends on the case and is given after a quote request.

To find a solicitor experienced in unregistered land conveyancing near you, look for someone who handles first registration, examines historic ownership evidence and can explain the steps for your transaction. A local search for unregistered land conveyancing solicitors can help identify firms offering this specialist conveyancing work.

What are the consequences of not registering an unregistered title?

Without a Land Registry entry, ownership must be established through historical title deeds and related documents. This can make selling, buying or mortgaging more involved, because the parties need to examine the evidence and confirm that the ownership chain is sound. In England and Wales, a good root of title should be at least 15 years old. If that starting document is missing or later transfers are unclear, the investigation may take longer.

The buyer’s solicitor reviews original deeds and conveyances to trace ownership from the good root of title to the current owner. They check that each transfer is supported by documents and that the property described matches the land being sold. The solicitor may also prepare an Epitome of Title, a summary of the ownership chain and the key documents supporting it. Gaps, inconsistent names or unclear boundaries can lead to further enquiries and delays.

Missing deeds don’t automatically prevent a sale, but alternative evidence may be needed to support the ownership claim. Depending on what remains, this could include copy deeds, mortgage records, probate papers or statutory declarations. If deeds have been lost or destroyed, the owner may need to explain to HM Land Registry what happened, where the documents were last seen and why they are entitled to the property. A specialist review can identify gaps before they become obstacles during a transaction.

Leaving a title unregistered means there is no central register entry recording the owner and title details. This can make ownership harder to prove and increase the potential for disputes. It may also complicate a sale or mortgage, as the buyer or lender relies on the deeds and ownership investigation rather than an official register. Registration can help protect an owner’s interests against fraudulent dealings by someone falsely claiming to own the property, and guard against adverse possession claims.

For an unregistered purchase, the solicitor’s investigation does more than collect paperwork. It checks whether the documents form a coherent account of ownership and whether the evidence shows relevant rights or burdens. A land charges search against previous owners can help identify interests affecting the property. If the chain has a gap, the next step is to locate supporting records or assemble other evidence before the application proceeds.

Early document review can reduce avoidable questions once a sale is agreed. Keep deeds, transfer documents, probate papers and plans together, and note any known loss or damage. For support with a property transaction involving historic title documents, residential and commercial conveyancing can provide a relevant next step.

How do I sell an Unregistered Property?

You can sell an unregistered property using its title deeds as evidence of ownership. The seller prepares the deeds and property information, the buyer investigates the title and, after completion, applies for first registration within two months.

Confirming the Seller’s Right to Transfer

To confirm the seller’s right to transfer the property, ownership is traced through the title deeds and supporting documents. The buyer needs evidence that the seller can pass on the title. A conveyancer reviews the chain of transfers, checks names and dates, and identifies gaps that need explanation. The seller’s solicitor can start gathering and organising these documents before a buyer is found, helping to identify issues early.

Property Details, Boundaries and Restrictions

The sale documents must describe the property accurately, including its boundaries and relevant rights or restrictions. Compare the deeds and plans with the land being sold, particularly where the plot includes shared access, a field or an extension. A mismatch can prompt enquiries or complicate the registration application. The buyer’s conveyancer examines the documents to understand which land and rights pass with the transfer.

Conveyancing Timescales

Unregistered title evidence can affect the pace of conveyancing because historic documents need examination before the buyer can be satisfied. First registration can take from 2 months to a year, while creating a new registered title usually takes between 6 and 9 months. These periods concern registration, not the entire sale. Missing deeds, unclear boundaries or incomplete ownership evidence can require further investigation and cause delays.

Steps in an Unregistered Conveyancing Transaction

The transaction usually moves from collecting title deeds, to checking the ownership chain, answering the buyer’s enquiries, completing the sale and applying for first registration. The seller’s solicitor prepares title evidence and can start before marketing. After completion, the buyer’s solicitor submits the application to HM Land Registry, normally using form FR1 with supporting documents. This order matters because the buyer needs evidence to register the transferred title.

Some properties remain unregistered because no sale or other registrable transfer has triggered first registration. Approximately 10% of land in England and Wales remains unregistered. An owner may choose voluntary first registration before selling, but can also proceed with a sale using the deeds. The right approach depends on the available documents, any title concerns and the transaction’s timing.

For practical support with the title investigation and transfer, conveyancing for property transactions can help organise the work involved in an unregistered sale.

Unregistered Land Conveyancing: Selling and Registration Explained

Land that remains unregistered

Land can remain unregistered because no sale or other registrable dealing has triggered first registration. This does not, by itself, mean the owner lacks legal title. In England and Wales, title may still be evidenced by deeds and earlier conveyances. The practical difference is that buyers and lenders must rely on those documents rather than a current Land Registry record.

For an unregistered residential property, the deeds may show how ownership passed between successive owners. A conveyancer examines the documents and checks that the property description, boundaries and ownership chain fit together. This investigation matters before a sale or mortgage because gaps or conflicting details can lead to enquiries, disputes or delays. A straightforward application depends on coherent evidence, not simply the age of the property.

Some registrable dealings make registration compulsory. For example, taking out a mortgage on unregistered commercial property triggers registration as part of the mortgage process. A sale or transfer can also trigger first registration. Owners without an immediate transaction can choose voluntary registration, creating an official record before buyers or lenders need to rely on historic deeds.

Before an application, searches help identify interests that may affect the land. A land charges search should cover previous owners since 1925, and form K15 is used to apply for that search. The search is made against owner names, so accurate details from the title documents matter. An index map search can also help establish whether the land, or part of it, is already recorded on the register.

Where someone occupies land without the owner’s consent and claims it as their own, adverse possession may become relevant. The stated period for a claim involving unregistered land is 12 years. An application may be appropriate where land has been occupied and used as one’s own for the prescribed period, but clear ownership evidence is lacking. Occupation alone does not settle who owns the land; the history and supporting evidence matter.

Leaving land unregistered can make ownership harder to demonstrate and a later sale more document-heavy. Missing deeds may require secondary evidence, such as copy deeds, mortgage records or probate papers. If boundaries are unclear, plans and historical documents can help explain which land the title covers. A solicitor can review the available evidence, arrange relevant searches and prepare an application for first registration where appropriate.

Some owners choose to register before a sale or mortgage, while others wait until a transaction triggers the requirement. The decision depends on the quality of the title evidence, the intended transaction and whether a clear record would assist future buyers. Voluntary first registration can establish the title in advance.

What is unregistered land in England and Wales

Unregistered land is property without a title entry at HM Land Registry. Ownership is evidenced by deeds and documents recording earlier dealings, rather than a current register. The absence of a register entry does not, by itself, mean the land has no owner. It means the title must be understood through its documentary history.

That distinction reflects how registration developed. The Land Registration Act 1925 introduced compulsory registration for specified transactions, and registration became compulsory nationwide for most land transactions in England and Wales in 1990. The Land Registration Act 2002 replaced the 1925 Act. Land that has not undergone a registrable dealing may therefore remain outside the register.

For an unregistered title, conveyancers examine the deeds to establish how ownership passed from one person to another. A conveyance may describe the property, record a transfer and refer to rights affecting access or use. Historical plans can help identify boundaries, while mortgages, probate papers and other documents may explain later changes. Each item contributes evidence, and the chain must make sense as a whole.

Registered ownership works differently. HM Land Registry records the owner and title details, including relevant rights and restrictions, under a unique title number. An official copy of the register can be requested for registered land. For unregistered land, there is no equivalent title entry to inspect, so the buyer’s investigation depends on the documents available and whether they establish a consistent chain.

First registration creates a Land Registry title for land that has never been registered. The application brings together evidence from earlier conveyances and dealings, along with a plan showing the property outline. This turns a documentary history into an official record that can be inspected in future transactions. Registration does not remove the need to understand the property’s boundaries or recorded rights.

Unregistered status can also matter when ownership changes through inheritance. A personal representative dealing with property may need to establish the deceased’s title from the deeds before the transfer can be registered. Keeping property documents with estate records can help make that investigation more manageable. Where property forms part of a wider succession plan, discuss your estate planning needs and how ownership should be documented.

Feltons Solicitors LLP: Divorce and Financial Arrangements

Feltons Solicitors LLP provides residential and commercial conveyancing for property transactions, including matters involving unregistered titles. If you’re preparing to sell or buy unregistered property, the firm can assess the title documents, trace the ownership chain and manage the conveyancing process. This can be particularly useful where deeds are incomplete, boundaries need clarifying or first registration follows a transfer.

The firm also assists with wills, probate and estate planning where property ownership forms part of a wider family or estate matter. The right support depends on the legal issue: a property sale calls for conveyancing, while questions about distributing property after death may involve estate planning or probate.

Contact Feltons Solicitors LLP to discuss your property matter.

Prepare your next property decision with confidence

Before taking your next step, gather the available deeds, plans and correspondence. A clear set of documents makes it easier to identify what needs attention and raise the right questions about a proposed sale, purchase or registration. Note any missing deeds or boundary descriptions that are difficult to interpret. These details give a conveyancer a practical starting point.

The right unregistered land conveyancing solicitors can explain the work involved in your transaction and how historic title evidence fits into it. Feltons Solicitors LLP handles residential and commercial conveyancing, including property matters that need careful title review. Taking advice before agreeing a transaction can help you plan around the documents and decisions ahead.

If you’re ready to discuss your property matter, contact Feltons Solicitors LLP. A considered next step can make a complex title easier to approach, and help you move forward with greater clarity.

Frequently Asked Questions

Who should register the property?

After buying unregistered property, the buyer is responsible for applying for first registration. The buyer’s conveyancer usually prepares and submits the application as part of the post-completion work. A seller may register voluntarily before a sale, giving the buyer an established title to work from. For example, an owner preparing to market a property can consider registration before finding a buyer.

Should You Consider Voluntary First Registration?

Voluntary first registration may suit an owner who wants to establish a registered title before a sale, transfer or mortgage requires an application. Consider the condition of the deeds, whether the property description is clear and whether a transaction is planned. The Land Registry fee depends on the property’s value, and a professional valuation is not required. The timing can depend on whether the title evidence is ready.

What are the risks of buying and selling unregistered land?

The main risks include difficulty evidencing ownership, extra title enquiries and possible delays if the deeds don’t clearly match the land being transferred. For instance, a deed plan might not show clearly whether a garage or access strip forms part of the property. Buyers may also need to understand rights affecting the land before proceeding. Sellers can reduce uncertainty by gathering relevant deeds and plans early.

What details should be included in the application for first registration?

An application should identify the property’s address and boundaries, the current owner, and relevant rights or restrictions. Form FR1 is used for first registration. Supporting evidence includes the title deeds and documents showing ownership history. Include a scale drawing if the deeds don’t contain a suitable plan. Accurate information helps the application describe the land and title being registered, rather than leaving key details unclear.

When is first registration of unregistered land compulsory?

In England and Wales, a purchase or transfer of unregistered property triggers compulsory first registration. A new mortgage on unregistered property can also trigger it. Certain other dealings matter too: gifts of land and assents by personal representatives require a change of ownership to be registered, and granting a lease for more than seven years requires registration. Following a purchase, the buyer must apply within two months of completion.

What documents are needed to convey unregistered land?

Gather the original title deeds, earlier conveyances and transfer documents that evidence the ownership chain. Plans help identify the land, while probate papers may explain how an owner inherited it. The conveyancer can prepare an Epitome of Title summarising the relevant ownership documents. Searches can also form part of the investigation, including land charges and an index map search. If original deeds are missing, secondary evidence may help support the title.

How long does unregistered land conveyancing take compared with registered land?

Unregistered transactions can take longer because the conveyancer must investigate historical deeds and establish the ownership chain. First registration may take from 2 months to a year, and creating a new registered title usually takes between 6 and 9 months. These are registration timeframes, not a guaranteed completion date for the sale. The work required depends on the title evidence, searches and any questions raised about the property.

How do solicitors investigate title to unregistered land?

Solicitors examine the deeds to trace ownership from a good root of title to the current owner. In England and Wales, a good root should be at least 15 years old. They compare names, dates, property descriptions and plans, then investigate gaps using supporting material such as probate records or copy deeds. Searches against previous owners can identify land charges, while an index map search helps check the land’s registration position.