Post-Nuptial Agreement Drafting Solicitors: 2026 Guide

Post-Nuptial Agreement Drafting Solicitors: 2026 Guide

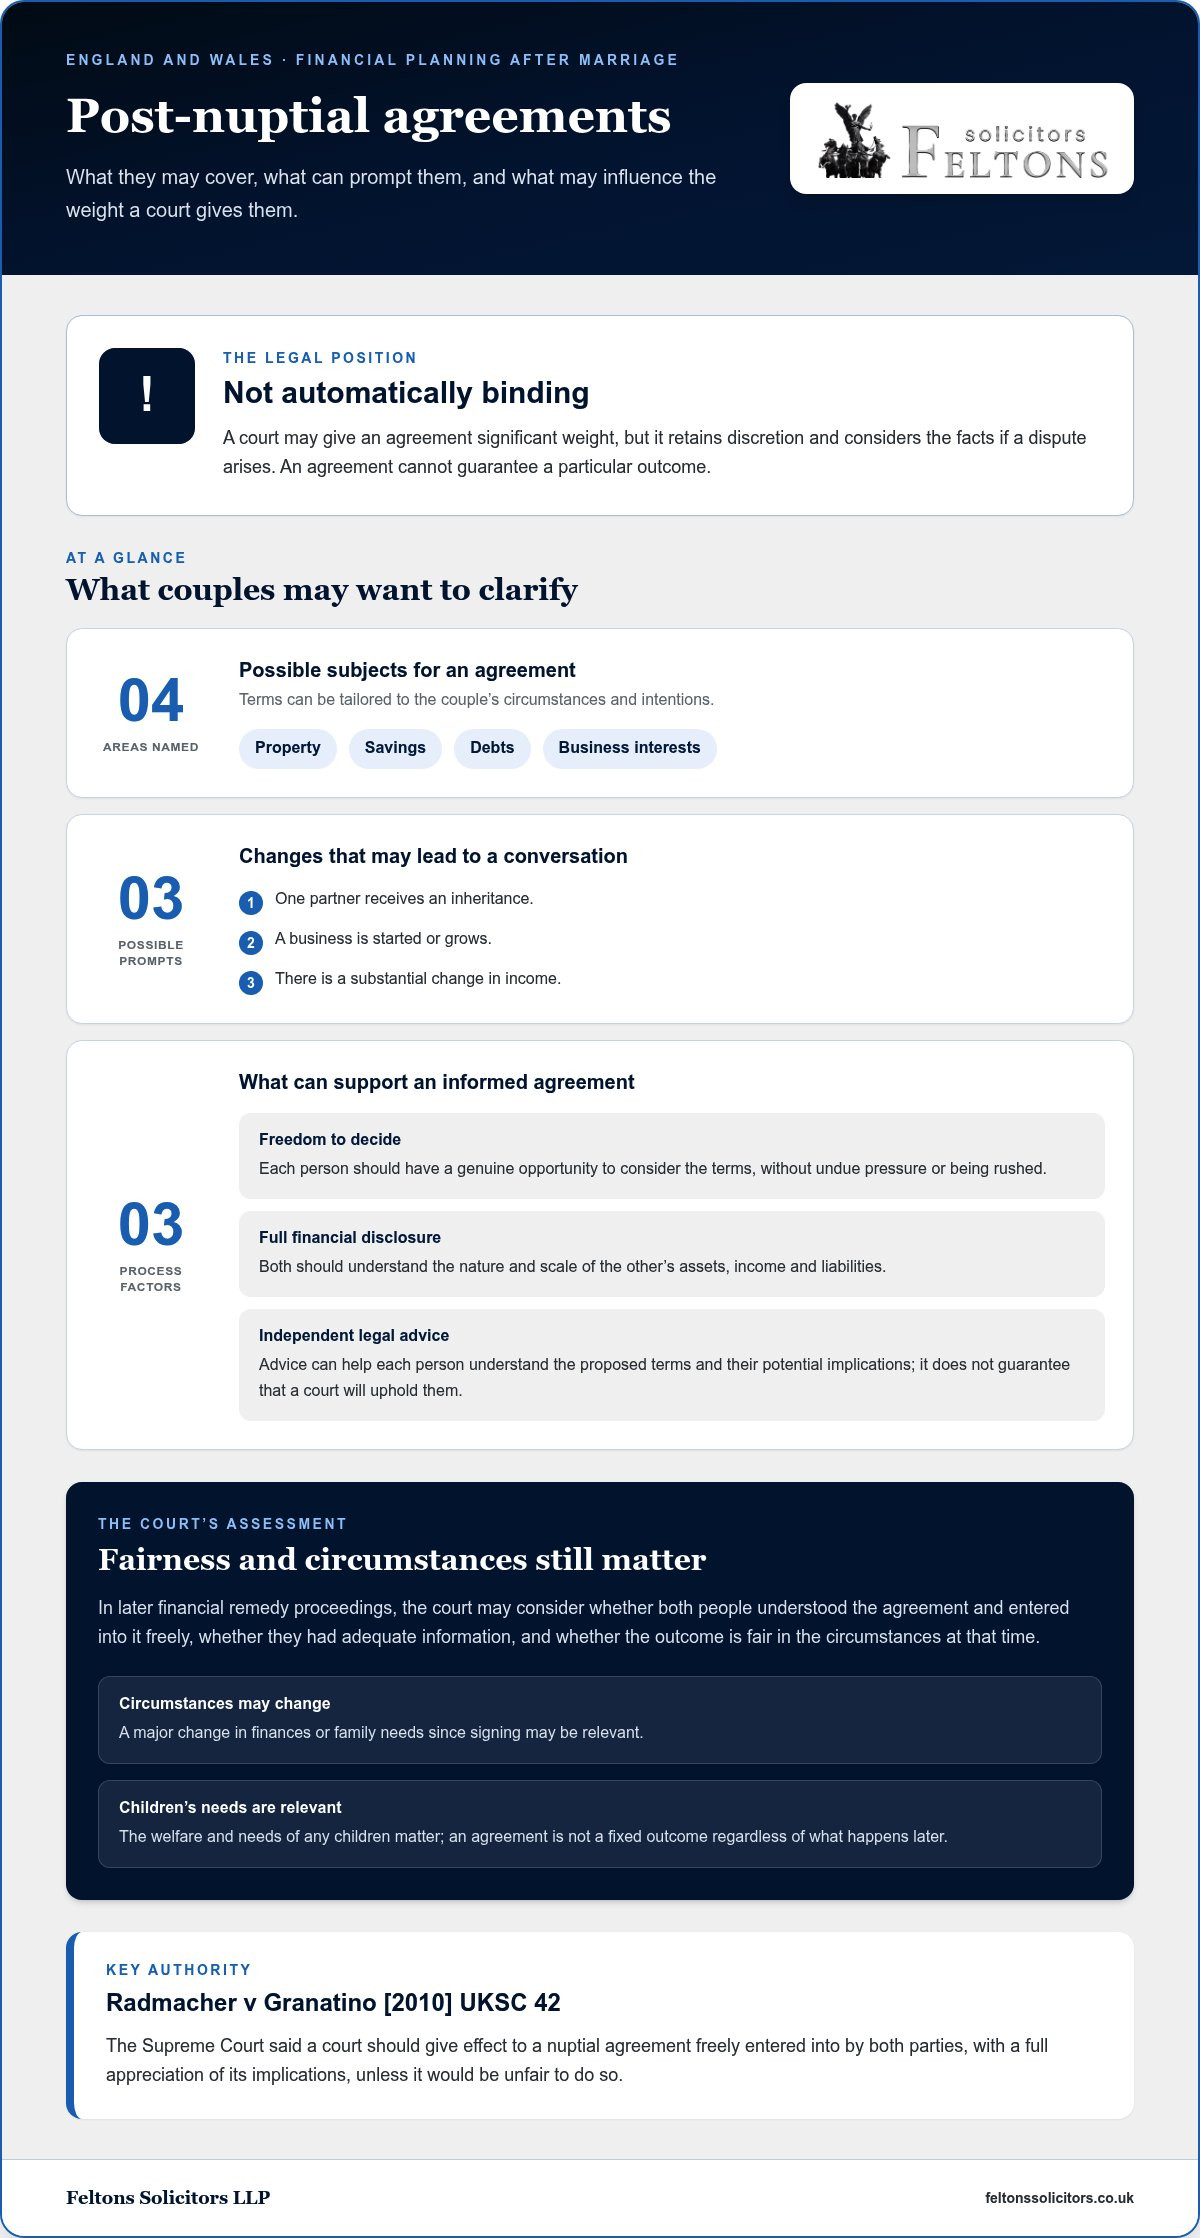
Could putting financial decisions in writing bring clarity without deciding the future of your marriage? For couples considering a post-nuptial agreement, that balance matters. Discussions about money can feel sensitive or one-sided, and it’s natural to ask whether an agreement will carry legal weight. In England and Wales, post-nuptial agreements aren’t automatically binding. A court may give one significant weight if it is fair and both parties entered into it freely, with full financial disclosure and independent legal advice. Experienced post nuptial agreement drafting solicitors can help you approach the process carefully and with realistic expectations.

A considered agreement is a financial plan tailored to your circumstances, not a guarantee of a particular court outcome. This 2026 guide explains what an agreement can cover, from property and savings to pensions, business interests and debts. It also sets out what information to prepare, how solicitor-led advice can support clear decisions and what to consider before signing.

Key Takeaways

  • Changes such as an inheritance, growing business interests or a shift in finances may prompt you to revisit financial plans after marriage.
  • Understand how the court’s discretion and the principles in Radmacher v Granatino affect the weight an agreement may carry.
  • See where generic templates can fall short, particularly when assets, family circumstances or future plans are more complex.
  • Prepare a clear picture of your objectives, income, assets, pensions, liabilities and relevant supporting records before drafting begins.
  • Learn what to expect from post nuptial agreement drafting solicitors, from initial discussions and financial disclosure to review and signing.

When are post-nuptial agreement drafting solicitors useful after marriage?

A post-nuptial agreement is a written agreement made after a couple marries or enters a civil partnership. It can set out how they intend to approach their finances if they separate or divorce, including matters such as property, savings, debts or business interests. The Postnuptial agreement overview offers a general introduction, but it isn’t a guide to the law in every jurisdiction. In England and Wales, an agreement can record a couple’s intentions; it can’t guarantee how a court would decide a future financial case.

Post nuptial agreement drafting solicitors can help couples work through their intentions in light of their financial circumstances. Considering an agreement doesn’t mean separation is expected. For some couples, it’s practical planning after a change in circumstances. For others, it creates an opportunity to clarify financial expectations and discuss them openly.

What can prompt a couple to consider an agreement?

A change in finances may lead a couple to revisit arrangements made earlier in their relationship. One partner might receive an inheritance, start or grow a business, or experience a substantial change in income. They may want to record how particular assets or responsibilities should be treated if the relationship later ends.

These are possible reasons to explore an agreement, not a checklist for every couple. Start by identifying what has changed, what each partner wants to clarify and whether both feel able to discuss the subject freely. A focused conversation can help separate shared priorities from assumptions that need further thought.

How is a post-nuptial agreement different from a prenup?

The difference is timing: a prenuptial agreement is made before marriage, while a post-nuptial agreement is made after a marriage or civil partnership has taken place. Either may form part of financial planning, but neither guarantees a particular outcome if the couple separates or divorces.

In both cases, the terms should reflect the couple’s actual circumstances and agreed intentions, rather than generic assumptions. For broader context on the financial issues that can arise if a relationship ends, read this guidance on divorce and financial arrangements.

Family law differs across the UK, so this guide focuses on England and Wales. If your circumstances involve another part of the UK, the applicable law may differ. A solicitor can explain the relevant context and how an agreement may fit into your wider financial planning.

Can a post-nuptial agreement be upheld in England and Wales?

A post-nuptial agreement isn’t automatically legally binding in England and Wales. However, a court may give it significant weight when deciding financial remedy proceedings. The key authority is Radmacher v Granatino [2010] UKSC 42. The Supreme Court said a court should give effect to a nuptial agreement freely entered into by both parties, with a full appreciation of its implications, unless it would be unfair to do so. The Law Commission report on nuptial agreements provides further context on their legal status.

This principle doesn’t promise that a particular agreement or term will be upheld. A court retains discretion and considers the facts when a dispute arises, including whether the agreement was fair at that time and whether circumstances have changed. The needs and welfare of any children are also relevant, so an agreement can’t be treated as a fixed outcome regardless of what happens later.

What factors may influence the weight given to an agreement?

The circumstances in which the agreement was made can matter as much as its wording. Each person should have a genuine opportunity to consider the terms, without undue pressure or being rushed into signing. Full and frank financial disclosure helps both parties understand what they are agreeing to, including the nature and scale of each other’s assets, income and liabilities.

Independent legal advice is an important safeguard. It helps each person understand the proposed terms and their potential implications, but it doesn’t guarantee that a court will uphold the agreement. Post nuptial agreement drafting solicitors can help clarify the issues, record the parties’ intentions and identify points that need careful consideration. The aim is an informed process, not a guaranteed legal result.

Why can’t a solicitor promise a particular result?

If financial remedy proceedings later arise, the court makes its own assessment. It may consider whether each person understood the agreement, entered into it freely and had adequate information, alongside whether the outcome is fair in the circumstances at that time. A major change in finances or family needs since signing may also be relevant.

Careful drafting can support clarity and informed decision-making, but it doesn’t make an agreement automatically binding or remove the court’s discretion. For tailored guidance on how an agreement fits your financial circumstances, explore family law advice on financial arrangements.

Solicitor-drafted agreement or template: what is the difference?

A generic template can provide a starting structure, but it can’t account for how your finances are arranged or what you intend each clause to achieve. Advice-led drafting starts with your circumstances and priorities, then shapes the wording around them. Neither approach guarantees how a court would treat an agreement, and not every couple needs the same provisions.

Consideration Generic template Advice-led drafting
Fit Uses standard wording that may not reflect particular assets, ownership or family circumstances. Considers the couple’s circumstances and identifies where specific terms or further discussion may be needed.
Financial information May provide limited prompts, leaving assumptions about assets, income or liabilities unstated. Uses the financial picture to inform the terms and highlight areas requiring clarity.
Review May not explain how to assess whether the wording reflects both parties’ intentions. Allows the draft to be considered in context, with each person’s position and questions addressed.

Where can a generic template fall short?

Broad wording can blur important differences. For example, a clause referring to “property” may not distinguish a jointly owned home from a property owned by one person, or explain how a mortgage or other liability should be considered. A template may also leave assumptions about a business, shares, inherited assets or changing family circumstances unstated.

This doesn’t mean every template is invalid or unsuitable. The risk is relying on standard language without checking whether it accurately describes the couple’s finances and intentions. If key context is missing, the document may leave room for different interpretations.

What does tailored legal advice add?

Advice can help each person identify their priorities, understand the proposed terms and raise questions before the wording is settled. Since each partner’s circumstances and interests may differ, both should have the opportunity to consider the agreement from their own perspective and receive separate advice. Post nuptial agreement drafting solicitors can help translate agreed intentions into clearer terms and draw attention to unresolved issues rather than obscuring them with general wording.

Inheritance planning may also connect with decisions about how assets are treated in an agreement. For related considerations, see this estate planning guidance. The Law Commission’s report on nuptial agreements provides further background on the legal context. A tailored document isn’t a promise of a particular court outcome; its value lies in recording considered intentions clearly.
Post-Nuptial Agreement Drafting Solicitors: 2026 Guide

What information should you prepare before drafting a post-nuptial agreement?

Good preparation helps turn broad intentions into terms that reflect your finances and priorities. You don’t need to decide every detail alone before seeking advice. Start by gathering a clear picture of your circumstances and noting where you and your spouse agree or need a fuller discussion.

Which financial details and documents may be relevant?

The information needed depends on your circumstances. Records might include property details, bank and investment statements, income information, pension records, details of debts and documents relating to a business or its ownership. Where relevant, note whether an asset is jointly or individually owned and how it was acquired. The aim is an accurate overview, not a standard paperwork list for every couple.

A practical preparation sequence can help:

  1. Set out your objectives. Note what you want the agreement to clarify and which questions remain open.
  2. Gather financial information. List assets, income, pensions, liabilities and business interests, with supporting records where available.
  3. Explain ownership and context. Record how significant assets are held and, where relevant, the source of funds used to acquire them.
  4. Consider day-to-day and future needs. Think about housing, ongoing financial responsibilities and possible changes, such as a new business venture or inheritance.
  5. Review the proposed terms. Read the draft carefully, raise uncertainties and take advice before deciding whether to sign.

How should couples approach terms and future review?

Each person can consider their own priorities and practical needs before discussing how to address them together. For example, think through how housing costs would be managed or what should happen if one partner’s income changes. Listing agreed points separately from unresolved questions can make a sensitive conversation more focused.

You may also wish to discuss whether the agreement should be reviewed after a particular life change or at an agreed point in the future. A review clause can prompt the couple to revisit the terms, but it won’t update them automatically. Any change needs to be considered and properly recorded, with advice tailored to the circumstances at that time.

Post nuptial agreement drafting solicitors can help organise the information, explain issues in plain English and tailor advice and drafting to your circumstances. To discuss your financial arrangements, speak with Feltons about your financial arrangements.

Post-Nuptial Agreements: Instruction to Final Document

A clear, measured process gives both people space to explain their priorities, understand the financial picture and consider the wording before deciding whether to sign. The steps depend on the couple’s circumstances, but the process commonly moves from setting objectives and sharing financial information to advice, drafting, review and completion.

  1. Set out your objectives. Identify what you hope to clarify and which issues need discussion.
  2. Share financial information. Bring together relevant details of assets, income, pensions, liabilities and other interests.
  3. Consider advice. Each person should have the opportunity to understand the proposed terms and their potential implications.
  4. Prepare and review a draft. Instructions and financial information inform the wording. Both parties should read it carefully and raise questions where needed.
  5. Complete the agreement. Before signing, check the final terms and the applicable execution formalities in light of current law and your circumstances.

What happens during the drafting and review stages?

The first draft should reflect the objectives discussed and the financial context provided. During review, check that the language says what you intend, that relevant issues haven’t been overlooked and that unclear or disputed points are addressed. Take time to ask questions. Each person should understand the proposed terms and obtain appropriate advice before completion.

Discussions about money can feel personal. Clear, sensitive communication and appropriate privacy can help keep the focus on practical decisions rather than assumptions about the relationship. Post nuptial agreement drafting solicitors can explain the issues in plain English and tailor advice to the couple’s circumstances, while keeping expectations realistic about the agreement’s potential legal effect.

When should you seek advice about a post-nuptial agreement?

Start early enough to gather financial information, consider the terms and allow each person to obtain independent guidance. A rushed process or pressure to sign can leave one or both parties without a proper opportunity to reflect, undermining confidence in the agreement and how it was reached. If a point remains unresolved, address it before signing rather than treating completion as a formality.

For advice shaped around your objectives and financial circumstances, speak to Feltons about post-nuptial agreement drafting. A solicitor can help you understand the process and prepare carefully, without promising how a court would decide a future dispute.

Take a considered next step with your financial plans

A post-nuptial agreement can set out shared intentions after a change in circumstances, but it can’t guarantee a particular court outcome. Its potential value depends on careful preparation, clear financial information and terms that reflect both parties’ circumstances. Taking time to understand the process and review the draft can help you approach sensitive decisions thoughtfully.

Post nuptial agreement drafting solicitors can help you consider your objectives and the practical issues an agreement may need to address. Feltons advises on divorce and financial arrangements, with pragmatic advice tailored to individual needs. The firm can help you explore your options and take a measured approach.

Discuss post-nuptial agreement drafting with Feltons and take an informed first step towards greater financial clarity.

Frequently Asked Questions

Are post-nuptial agreements legally binding in England and Wales?

No, post-nuptial agreements aren’t automatically legally binding in England and Wales. A court may give an agreement significant weight, particularly where both people entered into it freely, understood its implications and made full financial disclosure. The court retains discretion and may consider fairness, later changes in circumstances and the needs of any children. Careful drafting and independent legal advice can support the process, but neither guarantees that every term will be upheld.

Do both spouses need separate solicitors for a post-nuptial agreement?

Each spouse should have the opportunity to obtain independent legal advice so they can understand the proposed terms and consider their own interests. The same solicitor can’t advise both people on their individual positions. Separate advice can help identify concerns and support informed, voluntary decisions. Post nuptial agreement drafting solicitors can guide each client through the implications of the terms, but independent advice can’t guarantee a particular court outcome.

What should a post-nuptial agreement include?

An agreement may set out how a couple intends to deal with relevant finances if they separate or divorce. Depending on their circumstances, this could include property, savings, pensions, income, debts, business interests and inheritance. It should reflect the couple’s objectives and the financial information available, rather than rely on standard terms that may not fit. Advice can help clarify ownership, responsibilities and points that need further discussion before signing.

Can a post-nuptial agreement protect an inheritance or business?

An agreement can record how a couple intends an inheritance or business interest to be treated if they separate, but it can’t guarantee that a court will follow that intention. The details matter, including ownership, financial disclosure, each person’s needs and later changes in circumstances. For example, a business may change in value or provide income relied on by the family. Tailored advice can help address these factors clearly without promising a legal result.

Can we make a post-nuptial agreement without a solicitor?

You can prepare an agreement without a solicitor, but a generic document may not reflect your finances or make your intentions clear. Independent legal advice can help each person understand the terms, while careful drafting can identify assumptions or unresolved issues. Full financial disclosure and voluntary decision-making are also important considerations. Solicitor involvement may strengthen the preparation, but it doesn’t make an agreement automatically binding or guarantee how a court will treat it.

Can a post-nuptial agreement be changed after it is signed?

Yes, you and your spouse can agree to change the terms, but don’t assume a verbal conversation or informal note updates the agreement. Any variation should be properly documented and considered in light of your current financial circumstances and applicable legal requirements. Independent advice can help each person understand the proposed changes. If circumstances shift, such as a change in income or family responsibilities, review the agreement rather than relying on outdated terms.

Does a post-nuptial agreement cover arrangements for children?

A post-nuptial agreement can record the parents’ intentions about family finances, but it can’t conclusively decide future arrangements for children or bind a court on those matters. If parents separate, decisions concerning a child are assessed in light of the child’s welfare and circumstances at that time. The agreement may include relevant financial intentions, but a court’s consideration of children’s needs remains important. Take advice before including provisions that affect children or family support.
Freezing Orders in Divorce: Protecting Assets in 2026

Freezing Orders in Divorce: Protecting Assets in 2026

Could a court order stop your spouse from moving or selling assets before your financial arrangements are settled, and when is urgent action justified? It’s understandable to want to protect what may form part of a future settlement, particularly if you’re worried that money or property could disappear. A search for “freezing injunctions divorce property assets” often starts with that concern. However, a freezing injunction is an exceptional safeguard for a specific risk of assets being dissipated, not a shortcut to securing a divorce settlement.

This guide explains what a freezing injunction may protect, what it can’t do, and the evidence and legal considerations a court may weigh. It also explains why urgency, proportionality and the possible consequences of an unsuccessful application matter when deciding what to do next. The rules and procedures differ across the UK, so the relevant legal route depends on where your case is being heard. Advice on divorce and financial arrangements can help you assess the facts and consider practical options without escalating matters unnecessarily.

Key Takeaways

  • A freezing injunction may restrict dealings with specified assets to preserve them, but it doesn’t decide ownership or determine the final financial settlement.
  • Concern alone may not be enough. The court considers the particular facts and evidence, including warning signs of possible asset dissipation.
  • Freezing injunctions, disclosure, negotiation and agreed undertakings serve different purposes. The right approach depends on what you need to achieve.
  • Prepare for legal advice by organising relevant records and setting out a clear timeline. Applications without notice carry demanding duties of candour.
  • Where assets may be at risk, consider prompt, tailored advice and weigh whether an urgent protective step or broader financial arrangements advice is the priority.

What is a freezing injunction in divorce, and which assets might it affect?

A freezing injunction is a court order that restricts specified dealings with assets, subject to the wording and limits of the order. In a divorce, its purpose is preservation: it may help prevent assets being moved or dealt with in a way that could undermine the financial process. It doesn’t decide who owns an asset or award either spouse a final financial settlement. For a general overview of the purpose of a freezing order, see this background explanation.

The order does not automatically freeze everything a spouse owns or controls. Its reach depends on the terms made by the court, the assets identified and the legal route available in the relevant jurisdiction. The phrase “freezing injunctions divorce property assets” can describe different concerns, each of which needs careful assessment. There is no standard order that applies in every case.

What does a freezing injunction actually prevent?

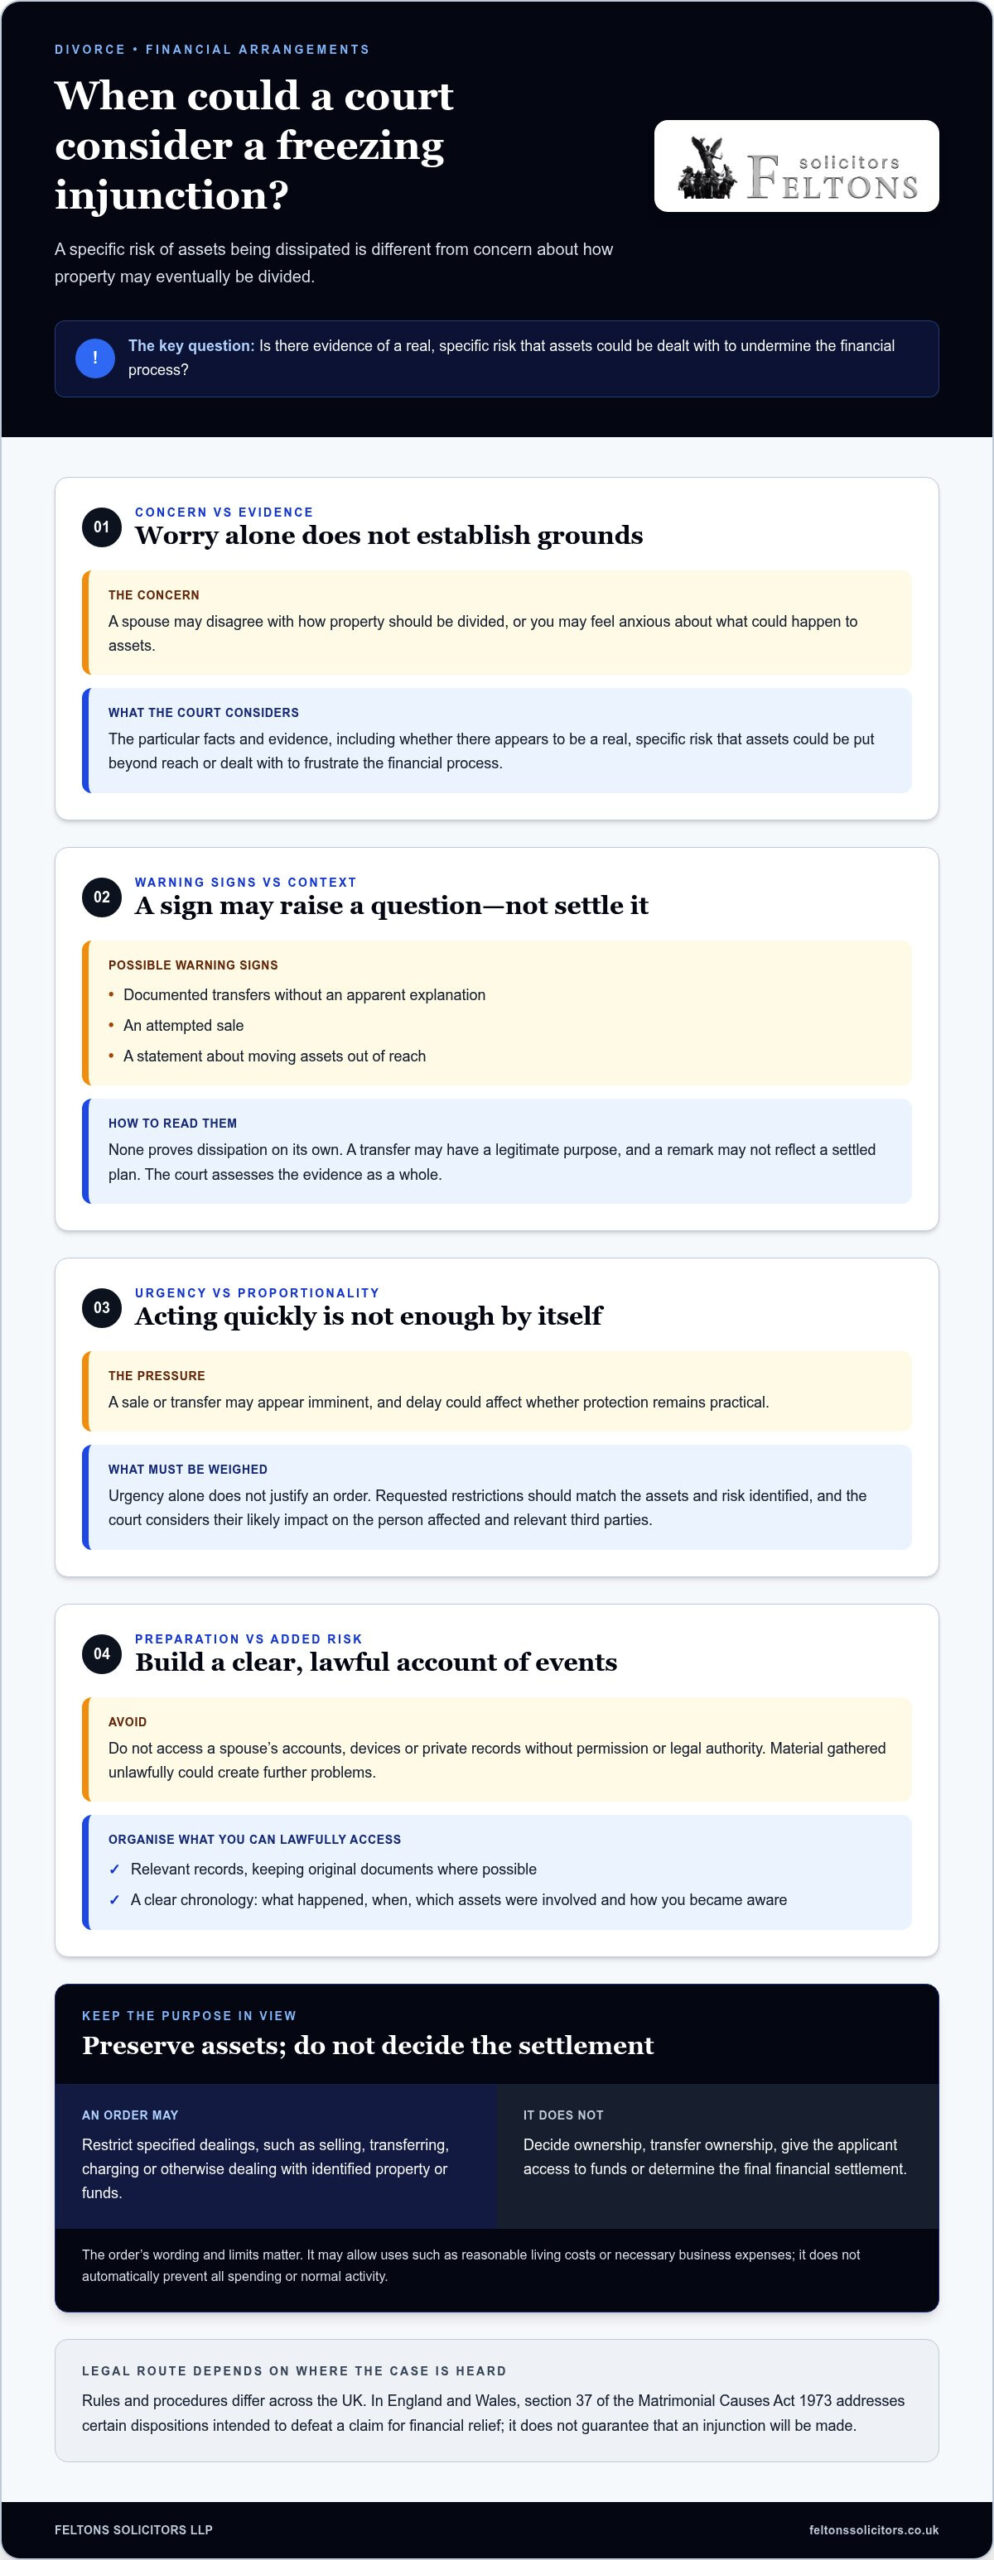
Restrictions are tailored to the order. They may prohibit selling, transferring, charging or otherwise dealing with specified property or funds. The order may also set out permitted uses, such as reasonable living costs or necessary business expenses, so preservation does not automatically prevent all spending or normal activity. Check the exact wording: an asset or transaction not covered by the order may fall outside its restrictions.

A disagreement about who should ultimately receive a home or investment is not, by itself, the same as a risk that assets will be dissipated. The question is whether there is a sufficiently evidenced risk that assets may be put beyond reach or dealt with to frustrate the financial process. Disputes over fairness or ownership are generally addressed through the wider financial arrangements, not by treating a freezing order as a shortcut to deciding the outcome.

Which property and financial assets could be relevant?

Depending on the circumstances, relevant assets might include a family home, an investment property, money in bank accounts or an interest in a business. The court’s ability to make an effective order can depend on who legally owns or controls an asset, where it is located, and whether another person or organisation has rights in it. An asset held jointly or involving a third party may raise different issues from one controlled solely by a spouse.

A freezing injunction doesn’t transfer ownership, give the applicant access to funds or determine how property will be divided. It is a protective measure, not a final resolution. Advice on divorce and financial arrangements can help assess the evidence, the assets at issue and whether an injunction is a proportionate option in the circumstances.

When might a divorce court consider freezing property or other assets?

A freezing injunction isn’t a routine feature of divorce, and anxiety about what a spouse might do does not, by itself, establish grounds for one. The court considers the particular facts and evidence, including whether there appears to be a real, specific risk that assets could be dealt with to undermine a financial claim. The relevant legal framework and procedure depend on where proceedings are taking place. In England and Wales, Section 37 of the Matrimonial Causes Act 1973 addresses certain dispositions intended to defeat a claim for financial relief. It does not guarantee that an injunction will be made.

A specific risk of assets being dissipated is different from the ordinary concern that a spouse may disagree with how property should eventually be divided. The latter is part of resolving financial arrangements. An injunction is an exceptional protective measure, not a way to gain leverage or secure a preferred share of the assets.

What evidence could support concern about asset dissipation?

Relevant warning signs might include documented transfers without an apparent explanation, an attempted sale, or a statement about moving assets out of reach. None proves dissipation on its own. Context matters: a transfer could have a legitimate purpose, and a remark may not reflect a settled plan. The court assesses the evidence as a whole rather than treating any one sign as automatic entitlement to an order.

To prepare for a legal assessment, organise records you can lawfully access and set out a clear chronology: what happened, when, which assets were involved and how you became aware of it. Keep original documents where possible. Don’t access your spouse’s accounts, devices or private records without permission or legal authority. Material gathered unlawfully could create further problems.

How do urgency and proportionality shape the decision?

Timing may matter if, for example, a sale or transfer appears imminent. A delay could affect whether protection remains practical, but urgency alone doesn’t establish that an order is justified. The restrictions requested should relate to the assets and risk identified, rather than going further than the circumstances warrant.

The court considers the evidence and the likely impact of restrictions on the person affected, as well as relevant interests of third parties. The limits of an order may matter if it could disrupt ordinary financial commitments or business activity. A focused review of the evidence and wider financial arrangements can help identify proportionate options. If you’re concerned about a specific transaction, read about divorce and financial arrangements advice.

Freezing injunctions versus other ways to protect divorce assets

A freezing injunction is one possible protective step, but it serves a different purpose from identifying assets or reaching agreement on how they should be divided. The right route depends on the facts, the level of urgency, the available evidence and the practical effect of the proposed step. An overview of freezing injunctions explains the remedy’s general scope, but individual circumstances need careful assessment.

Approach Main purpose Practical distinction
Freezing injunction Restrict specified dealings with assets where urgent protection may be justified. A court order with terms and effects shaped by the circumstances.
Financial disclosure Build a clearer picture of assets, liabilities and relevant transactions. Provides information; it doesn’t itself prevent someone dealing with an asset.
Negotiation Explore agreed arrangements for assets and financial needs. Depends on meaningful engagement and agreement between the parties.
Undertaking Record a formal promise to act, or not act, in a specified way. It is a promise, not the same thing as a court-imposed freeze.

When might disclosure or an undertaking be considered instead?

Financial disclosure can help establish which property, accounts, business interests, liabilities and transactions need to be considered. It may clarify an incomplete picture and support informed discussions, but it isn’t an asset-freezing measure. For more on that process, read about financial disclosure in divorce.

Where appropriate, an undertaking may provide a formal commitment about particular conduct. Its suitability depends on the circumstances and the wording proposed. Neither disclosure nor an undertaking should be treated as a substitute for urgent legal assessment if there is evidence that an asset may soon be transferred or sold. Equally, a suspected risk does not automatically mean an injunction is the right response.

How does an injunction fit into financial arrangements?

Interim protection and the final financial settlement do different jobs. An injunction may address a specific risk while proceedings continue; the broader process considers the parties’ overall financial position and how arrangements should be resolved. It doesn’t determine the final division or guarantee a particular settlement. The phrase freezing injunctions divorce property assets therefore describes only one part of a wider financial picture.

Consider the wider divorce and financial arrangements process alongside any immediate asset concern. A considered approach weighs the evidence and practical impact of each option rather than treating a court application as the default response.

Freezing Orders in Divorce: Protecting Assets in 2026

How to prepare for advice about a freezing injunction

A clear, organised account of your concern helps a solicitor assess whether urgent protection may be appropriate. Identify the action you fear, gather records you can lawfully access, set out key events in date order, and then obtain legal advice. Freezing injunctions divorce property assets is a complex issue, so distinguish what you know from what you suspect rather than presenting concerns as established facts.

What information should you organise before taking advice?

Bring together information that may help identify the asset, the risk and its timing. This could include:

  • Details of the property, accounts, business interests or other assets involved, including known ownership or control.
  • Relevant transaction records, correspondence, sale particulars or other documents you can lawfully access.
  • A chronology of key dates, such as when you learned of a proposed transfer or sale and any stated deadline.
  • A short explanation of the specific action you fear and why you believe it may happen soon.

Label first-hand evidence separately from assumptions or information relayed by someone else. This helps keep the legal assessment accurate and balanced.

What risks and responsibilities should an applicant understand?

An application made without notice to the other party may be considered where giving notice could undermine its purpose. It carries demanding duties of candour: the applicant must give the court a fair and complete account, including relevant points that may weigh against the order. In an urgent application, balanced disclosure matters because the court may initially hear only one party’s account. The applicable procedure and current requirements should be assessed for the court and jurisdiction involved.

Inaccurate or incomplete evidence can seriously affect the application and may have consequences for the applicant. Depending on the circumstances, the court may require a cross-undertaking in damages, a promise to compensate for losses if the order is later found to have been wrongly made. An unsuccessful application may also carry costs consequences. Neither result is automatic, but both should be considered before proceeding.

The wording of an order determines what is restricted and which exceptions apply. Read and follow it carefully: assumptions about what is permitted can create further difficulty. A tailored assessment of the evidence, urgency and possible impact can help you understand the available options. For background, see advice on divorce asset protection.

Choosing the next step when divorce property assets may be at risk

The right response depends on what appears to be happening, how soon it may happen and what the available evidence shows. If a sale or transfer seems imminent, prompt legal assessment can help establish whether urgent protection should be considered and what other options may be proportionate. If there’s no specific sign of assets being moved or dissipated, broader advice on disclosure and the overall financial arrangements may be the more useful priority.

Freezing injunctions divorce property assets concerns are fact-sensitive. An injunction may restrict dealings with specified assets, but it doesn’t decide ownership or guarantee a particular final settlement. The applicable procedure also depends on where the case is being heard, as the law and court processes differ across the UK. Advice should be specific to the relevant jurisdiction.

What should you do if a sale or transfer seems imminent?

Set out the facts as clearly as you can and seek a prompt legal assessment. Record relevant communications and events with their dates, keep copies of documents you can lawfully access, and note any known deadline or proposed transaction. A concise chronology can help distinguish a concrete, time-sensitive concern from uncertainty or assumption.

Avoid confronting your spouse in a way that could intensify the dispute or taking matters into your own hands, such as attempting to access private accounts or interfere with a transaction. Those steps may create further problems without providing reliable protection. Legal advice can help assess the evidence and available options calmly.

How can legal advice put the asset concern in context?

A solicitor can consider the specific concern alongside available disclosure, ownership information and the wider financial arrangements. This helps place any urgent risk within the full picture, rather than treating an injunction as the answer to every disagreement about property. For related guidance, read Protecting Your Assets During a Divorce Settlement.

Feltons Solicitors LLP advises on divorce and financial arrangements, including assessing the facts, evidence and proportionate options where assets may be at risk. A focused discussion can help clarify whether the priority is urgent protective advice, a fuller understanding of the finances, or both.

Discuss your divorce and financial arrangements

Take a considered next step to protect your financial position

A freezing injunction may help address a specific, evidenced risk, but it isn’t a routine part of divorce or a guarantee of a particular settlement. The right response depends on the facts, timing and impact of any proposed restrictions. Organising relevant records and getting advice can help clarify whether urgent protection or broader financial arrangements should take priority.

Concerns about freezing injunctions divorce property assets are best considered in the context of the full financial picture. Feltons Solicitors LLP advises on divorce and financial arrangements and handles complex litigation and dispute resolution, with attention to the evidence and proportionate options available.

If you’re concerned about assets or need to understand your next steps, discuss your divorce and financial arrangements. A clear, informed approach can help you move forward with greater confidence.

Frequently Asked Questions

Can I get a freezing injunction against my spouse during divorce?

Possibly, but a court order isn’t automatic just because you’re divorcing or worried about your spouse’s plans. The court considers the evidence, the specific risk to assets and whether the proposed restrictions are appropriate. The legal route depends on where proceedings are taking place, as the rules differ across the UK. Tailored legal advice can help assess the facts and whether an injunction or another step merits consideration.

What evidence is needed for a freezing injunction in divorce?

There’s no single checklist that guarantees an order. Relevant material may include records of transfers, evidence of an attempted sale, or communications suggesting assets may be moved, considered in their full context. Organise documents you can lawfully access and make a dated chronology, separating what you witnessed from assumptions or information received from others. For searches such as “freezing injunctions divorce property assets”, the key point is that evidence must support the specific concern.

Can a freezing injunction stop my spouse selling the family home?

It may restrict a sale if the order specifically covers the home and the court considers that protection appropriate. The order’s wording determines which dealings are restricted, and ownership, other parties’ rights and the relevant legal process may affect the position. It doesn’t automatically apply to every property or give you control of the home. If a sale appears imminent, organise the relevant records promptly and seek legal advice about the evidence and options.

Does a freezing injunction mean I will receive the frozen assets?

No. A freezing injunction is intended to preserve specified assets, not transfer them to the applicant or decide who owns them. It doesn’t determine the final financial settlement or guarantee that you’ll receive any particular asset or share. Those questions are addressed through the wider divorce financial arrangements process. The order’s precise terms matter, and a court may set out permitted dealings or exceptions, so don’t assume that frozen funds are available for your use.

How quickly can a court make a freezing injunction?

There’s no fixed timeframe that applies in every case. Timing can depend on the urgency, the evidence, the court’s procedures and whether the application is made with or without notice to the other party. An application without notice may carry demanding duties to give the court a fair and complete account. If a transaction seems imminent, organise the key dates and records and seek prompt legal advice. The applicable procedure varies across the UK.

What happens if someone breaches a freezing injunction?

A breach can have serious consequences, but the response depends on the order’s wording and the circumstances. A court may be asked to address non-compliance, and breach of an injunction can raise contempt of court issues. Keep a dated record of what you believe happened and preserve relevant information you can lawfully access. Don’t try to enforce the order yourself or assume conduct is a breach without checking the terms and obtaining legal advice.

Is a freezing injunction the same as a financial settlement order?

No. A freezing injunction is a protective measure that may restrict dealings with specified assets while the case continues. A financial settlement order deals with how financial arrangements are resolved, rather than simply preserving assets. One doesn’t automatically produce the other: a freezing order doesn’t decide the final division, and a settlement addresses the wider financial picture. The appropriate legal process depends on the facts and jurisdiction, so consider urgent asset concerns alongside broader divorce advice.

Maintenance Pending Suit UK: Practical Guide 2026

Maintenance Pending Suit UK: Practical Guide 2026

Could temporary financial support help you meet essential living costs while divorce or dissolution proceedings continue? For people considering maintenance pending suit applications UK, the key is to show how immediate, reasonable needs relate to the other party’s ability to pay. An application doesn’t guarantee an order. Uncertainty about evidence, eligibility or the effect on an already difficult relationship can make the next step feel daunting.

It’s understandable to want clarity before taking formal action. Maintenance pending suit is temporary support during financial proceedings, not a final settlement or a way to fund legal fees. The court considers the circumstances, including each party’s needs and financial position, and the process differs across the UK.

This practical guide explains when an application may be relevant, what financial information and supporting evidence can help present your position, and what to expect from the process. It also explains how to prepare proportionately and why tailored legal advice can help you assess your options before deciding whether to apply.

Key Takeaways

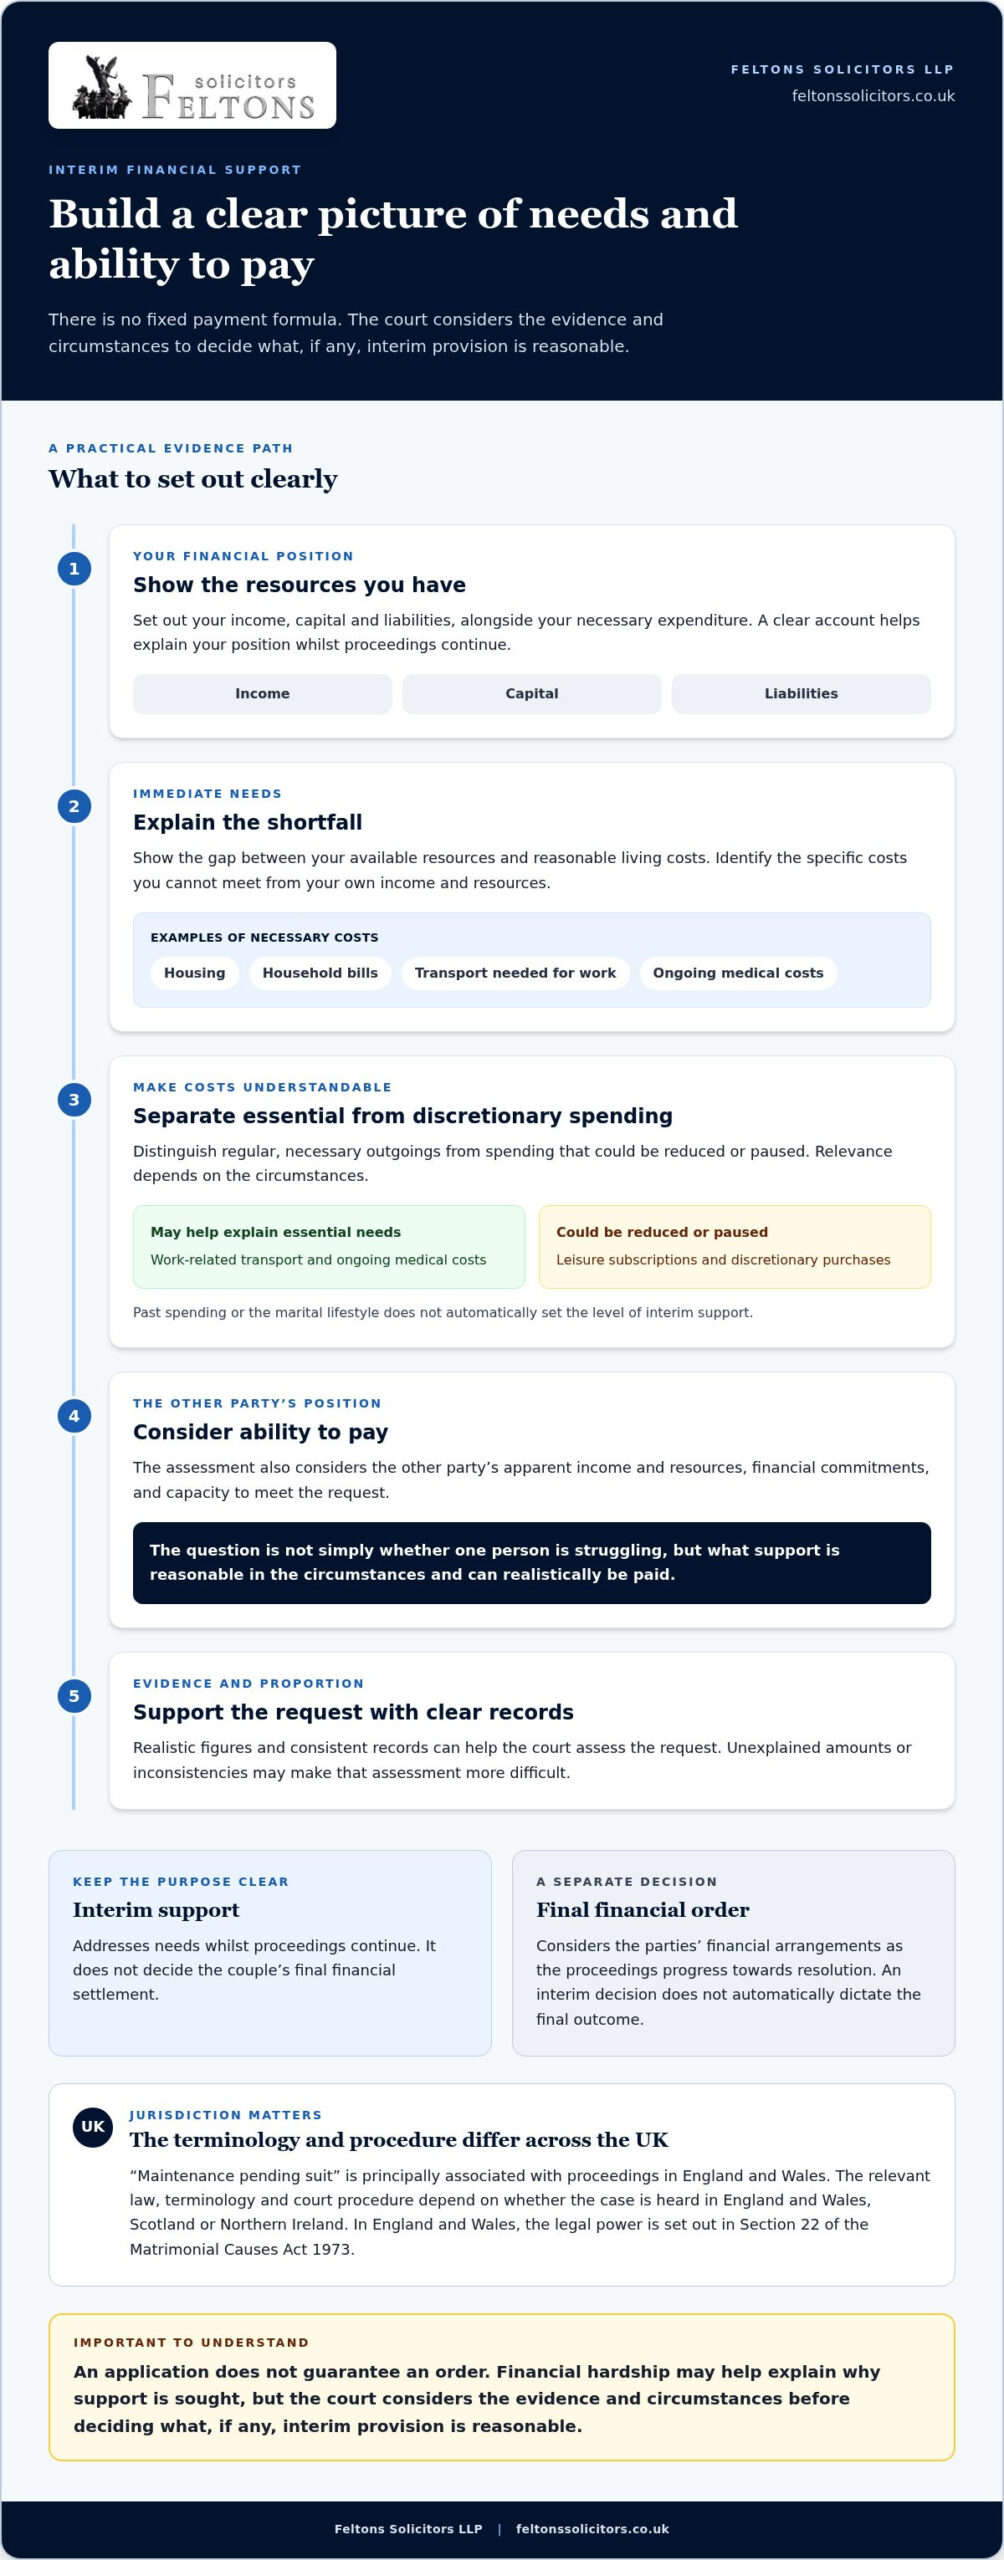
  • Maintenance pending suit is interim support during matrimonial proceedings. The terminology and procedure vary across the UK.
  • Maintenance pending suit applications UK are assessed on the evidence and circumstances, not a fixed payment formula.
  • Set out your income, capital, liabilities and essential expenditure clearly to explain your immediate needs.
  • Distinguish interim support from final financial orders and child maintenance, as each serves a different purpose.
  • Before taking action, consider affordability and jurisdiction, then get tailored advice on how an application fits the wider financial proceedings.

What are maintenance pending suit applications in the UK?

Maintenance pending suit is temporary financial support that a spouse may ask the court to order whilst certain matrimonial proceedings are under way. In England and Wales, the term is principally used for an application made during divorce, nullity or judicial separation proceedings. A corresponding provision applies to civil partners. The remedy is intended to address financial needs during the case, rather than decide the couple’s final financial settlement.

The phrase describes support during proceedings and is sometimes also called interim maintenance. For general background on spousal support and the term, see Maintenance Pending Suit. The legal test and process depend on the relevant jurisdiction and the facts of the case.

An application isn’t automatic. The court considers the evidence and circumstances, including the applicant’s reasonable needs and the other party’s ability to meet them. Financial hardship may help explain why support is being sought, but it doesn’t guarantee an order. Any interim decision is distinct from a final financial remedy order, which addresses the parties’ financial arrangements as the proceedings progress towards resolution.

When might someone consider applying for interim maintenance?

It may be relevant where a person cannot meet reasonable living expenses from their own income and resources whilst the case is ongoing. For example, there may be a shortfall in the money available for housing, household bills and other necessary costs. The court will need a clear picture of those needs, alongside information about the other party’s apparent income and resources. The question is not simply whether one person is struggling, but what support is reasonable in the circumstances and can realistically be paid.

Does maintenance pending suit work the same way across the UK?

No. Family law procedure differs between England and Wales, Scotland, and Northern Ireland. “Maintenance pending suit” is terminology principally associated with proceedings in England and Wales, so it shouldn’t be assumed to describe the same remedy or application process everywhere in the UK. The relevant law, terminology and court procedure depend on the jurisdiction where the case is being heard. Specialist advice can help identify the correct route before an application is prepared.

How does the court assess a maintenance pending suit application?

There is no fixed payment formula. The court looks at the evidence and the parties’ circumstances to decide what, if any, interim provision is reasonable. In England and Wales, the legal power is set out in Section 22 of the Matrimonial Causes Act 1973. The assessment focuses on the applicant’s reasonable needs and the respondent’s ability to meet them, rather than applying a standard figure to every case.

Interim maintenance is assessed against demonstrated needs and available means. A clear, supported account of the shortfall is more useful than an estimate without context. The court may consider the applicant’s income, capital, liabilities and necessary expenditure, as well as the respondent’s income, resources, financial commitments and capacity to pay.

How are needs and affordability considered?

Separate essential and regular costs from spending that could be reduced or paused. For instance, transport needed to get to work or ongoing medical costs may be presented differently from leisure subscriptions or discretionary purchases. This is not a fixed court checklist. Relevance depends on the circumstances, and past spending or the marital lifestyle does not automatically set the level of interim support.

Both financial positions matter. Explain your actual resources and the gap between those resources and reasonable outgoings. The respondent’s position also needs to be understood, including commitments that affect what they can afford. Clear records and realistic figures help the court assess the request fairly. Unexplained or inconsistent amounts may make that assessment more difficult.

What is the difference between interim maintenance and a final settlement?

Interim support is intended to address needs while proceedings continue. It does not resolve all financial claims or determine how assets and other resources should ultimately be divided. A final financial order may take a broader view of the parties’ finances and the issues raised in the case. The court’s interim decision does not automatically dictate the final outcome, although the parties’ circumstances and evidence may continue to develop during proceedings.

For anyone considering maintenance pending suit applications UK, keeping the immediate request proportionate and supported can help clarify the issue for both parties and the court. Tailored advice on divorce and financial arrangements can help organise the relevant financial information and consider an application alongside the wider proceedings.

Maintenance pending suit or another financial option: what should you consider?

The right route depends on what needs to be addressed: immediate support for a spouse, a lasting financial arrangement after separation, or financial provision for a child. These options serve different purposes and may be governed by different rules. Their terminology and availability also depend on the proceedings and jurisdiction. Practical Law guidance on Section 22 provides further context on the maintenance pending suit framework in England and Wales.

Option Main purpose Question it addresses
Maintenance pending suit Interim support for a spouse during relevant proceedings. Is financial help needed whilst the case is ongoing, and what may be reasonable?
Final financial orders Resolve financial claims as part of the longer-term arrangements. How should the parties’ wider financial position be settled?
Child maintenance Make financial provision for a child. What arrangements apply to the child’s support?

The table is a starting point, not a substitute for advice on the applicable law. Maintenance pending suit is not a final settlement, and seeking interim support does not determine the eventual financial outcome.

How does maintenance pending suit differ from child maintenance?

Maintenance pending suit concerns support between spouses during proceedings. Child maintenance concerns a child’s financial support, so it is not simply another name for a spouse’s interim application. The routes, decision-making and relevant rules may differ. Don’t assume that a child maintenance arrangement will meet a spouse’s personal living costs, or that the same eligibility and calculation rules apply throughout the UK.

When might a legal services payment order be relevant?

A legal services payment order raises a separate question: how one party may fund legal representation, rather than how to meet ordinary living expenses. It should not be treated as part of a maintenance request or as a guaranteed source of funding. Whether this type of order is available, and which statutory provisions and procedural test apply, depend on the jurisdiction. A family law solicitor can help distinguish these issues and consider how they fit alongside the wider financial proceedings.

When weighing up maintenance pending suit applications UK, first identify whose needs the application is intended to address and whether the concern is interim living costs, longer-term financial claims, child support or legal representation. Advice on the relevant jurisdiction can help ensure the issue is considered through the appropriate route.

Maintenance Pending Suit UK: Practical Guide 2026

How to prepare for a maintenance pending suit application

Preparation starts with a clear account of what support is needed, why it’s needed now and what resources are available to each party. The correct application procedure depends on the jurisdiction and stage of the proceedings. A well-organised summary can help keep the request focused and make legal advice more useful.

  1. Confirm the jurisdiction and proceedings. Establish where the case is being heard, what proceedings are under way and which procedure applies. The terminology, forms and court rules aren’t uniform across the UK.
  2. Set out your immediate needs. Prepare a realistic monthly budget, separating regular essentials from discretionary spending. Note any payment due soon and explain the consequences if it can’t be met.
  3. Collect current financial evidence. Bring together information about income, bank accounts, savings, regular expenses, debts and other available resources. Support the figures with documents such as payslips, bank statements, bills, loan statements and evidence of other income where relevant.
  4. Prepare a concise chronology. Record key dates in the proceedings, material changes in either party’s finances and urgent payment needs. Brief context can explain why a particular bill or shortfall needs attention now.
  5. Check the application before it is made. Compare the figures with the documents, identify missing information and confirm the required form, supporting material and service process for the jurisdiction.

What financial evidence should you organise?

Group evidence by income, expenditure, debts and available resources. Make sure the amounts in your budget correspond with the records, and explain any differences, unusual one-off costs or changes in income. If a bill is urgent, show its amount, due date and relevance to your immediate needs without overstating its impact or leaving out important context. Accurate records are more persuasive than a long, unexplained bundle of paperwork.

What happens after an application is prepared?

Broadly, an application is filed, the other party is notified in accordance with the applicable rules, they may respond, and the court considers the evidence. The court may ask for further information or give directions about how the case should proceed. The precise steps and timing vary, so don’t assume a particular hearing date or outcome. The procedure depends on the relevant jurisdiction.

Interim support also sits within wider financial proceedings. For an overview of that context, read this guide to divorce and financial arrangements. Tailored advice can help organise the evidence and consider whether the proposed application is proportionate. If you’re considering maintenance pending suit applications UK, get advice on your interim maintenance options as part of the wider financial picture.

Getting tailored advice on maintenance pending suit applications

Deciding whether to seek interim support involves more than identifying a shortfall. Consider your immediate and reasonable needs, the evidence available, the other party’s apparent ability to pay and the jurisdiction in which proceedings are taking place. A family law solicitor can assess these factors alongside the wider financial case, so an interim step is considered in context rather than in isolation.

What should tailored legal advice help you clarify?

Advice should help you understand whether an interim application addresses the financial problem you’re facing, or whether another route may be more appropriate. It can also help identify relevant documents, procedural requirements and practical considerations. The outcome can’t be guaranteed: the court’s decision depends on the facts, evidence and applicable law.

Consider asking for guidance on:

  • How to explain your immediate expenses and any urgent payment shortfall clearly.
  • Which records best support your account of income, resources, liabilities and regular spending.
  • How the application may interact with the financial remedy proceedings and longer-term settlement objectives.
  • Which terminology and procedure apply in the relevant part of the UK.

This joined-up view matters. An interim request focuses on needs during proceedings, while the wider case may involve financial issues that require separate consideration. Tailored advice on divorce and financial arrangements can help keep those objectives distinct and put the information prepared for one step in the context of the other.

How can you approach the next steps calmly?

Before an initial discussion, organise the key documents you already have and note the questions you most need answered. A short summary can be enough to begin:

  • Your essential household expenses and any bills at risk of going unpaid.
  • Your current income, accessible funds, debts and other relevant resources.
  • Important dates, changes in financial circumstances and the stage of the proceedings.
  • The outcome you need in the short term, kept separate from what you hope to resolve in the final settlement.

You don’t need to have every document perfectly arranged before seeking guidance. If essential expenses are at risk, prompt, proportionate advice may help you understand the available options and prepare carefully, without assuming that an application is the only answer. Feltons Solicitors LLP advises on divorce and financial arrangements, with a tailored approach to the issues in each case.

For guidance on your circumstances, discuss your financial arrangements with Feltons.

Take a considered next step

Deciding whether to seek interim support starts with a practical assessment: what essential costs need to be met now, what evidence supports those needs, and what resources may be available? The court considers the circumstances rather than applying a fixed formula, and the correct procedure depends on where the proceedings are taking place. Clear, proportionate preparation can help you understand whether maintenance pending suit applications UK may be relevant to your situation.

Interim maintenance is only one part of a wider financial case. It doesn’t settle all financial claims or guarantee a particular outcome. Tailored legal advice can help you weigh immediate needs against affordability, organise the relevant information and consider the application alongside the wider proceedings. Feltons advises on divorce and financial arrangements, and handles complex litigation and dispute resolution.

If you’re considering your options, discuss your financial arrangements with Feltons. A measured, informed approach can help you move forward with greater clarity.

Frequently Asked Questions

What is maintenance pending suit in the UK?

Maintenance pending suit is interim financial support sought during certain matrimonial proceedings, principally in England and Wales. It is intended to help address a spouse’s needs whilst the case is ongoing, rather than settle all financial claims. The term and legal route aren’t uniform across the UK. Identify the jurisdiction where proceedings are taking place and the rules that apply there before considering an application.

Who can apply for maintenance pending suit?

Eligibility depends on the proceedings and the law that applies in the relevant jurisdiction. In England and Wales, maintenance pending suit is associated with specified matrimonial proceedings, not a general application available to every separated couple. Relationship status, the type and stage of proceedings, and the financial circumstances may all be relevant. A solicitor can help assess whether this interim option fits the facts of your case.

How does a court decide whether to award maintenance pending suit?

The court considers the evidence and circumstances of the case, rather than applying a guaranteed payment formula. Relevant matters may include the applicant’s reasonable needs, income, resources and liabilities, alongside the respondent’s financial position and ability to pay. A clear account of the shortfall, supported by accurate records, can help explain the request. An application doesn’t guarantee an order or a particular amount.

What evidence is needed for a maintenance pending suit application?

Useful evidence may include current income records, bank statements, regular household expenses, debts and documents supporting urgent financial needs. For example, a bill with a due date can help explain why a payment matters now. Keep figures accurate and consistent with the documents, and explain unusual costs or changes. Required forms or further disclosure depend on the proceedings and jurisdiction.

How long does a maintenance pending suit application take?

There isn’t one timetable for every maintenance pending suit application. Timing may depend on the court, procedural route, urgency of the circumstances, completeness of the evidence and whether further information is requested. A general estimate shouldn’t be treated as a promise of a hearing date or decision. The specific circumstances of your case and the applicable procedure will affect expectations.

Is maintenance pending suit the same as child maintenance?

No. Maintenance pending suit generally concerns interim financial support between spouses during certain proceedings, whilst child maintenance is a separate matter with different rules and possible routes for assessment or agreement. A family’s circumstances may involve both, but one shouldn’t be assumed to replace the other. Consider each need separately and establish which process applies to the child’s support and which, if relevant, addresses a spouse’s interim needs.

Can maintenance pending suit be changed or end before the final settlement?

Interim arrangements may be affected by changed circumstances, further court decisions, or the progress and conclusion of proceedings. The effect depends on the wording of any order, the applicable rules and the facts. Don’t assume an arrangement will continue unchanged or determine the final settlement. Before changing payments or relying on an informal variation, get advice on the order and the proper steps in the relevant jurisdiction.